Striving to Make India the Best Version of Itself
Many East Asian economies in the last three decades have prospered because of large allocations using massive State subsidies to chosen sectors and respective industries via affordable credit while keeping interest rates at bare minimums. Wages were and remain suppressed to make industrialization possible through a transfer of savings from households to businesses – to help manufacturing thrive.
This has helped China and other East Asian Tiger nations to compete head to head with Western economies with fortified industries. Globalization also extended this phenomenon. Western economies offshored a lot manufacturing to countries that produced competitive goods to keep their corporate costs low – including wages, this while the majority of Western nations also shifted towards service sectors and consumption to generate solid performing GDPs.
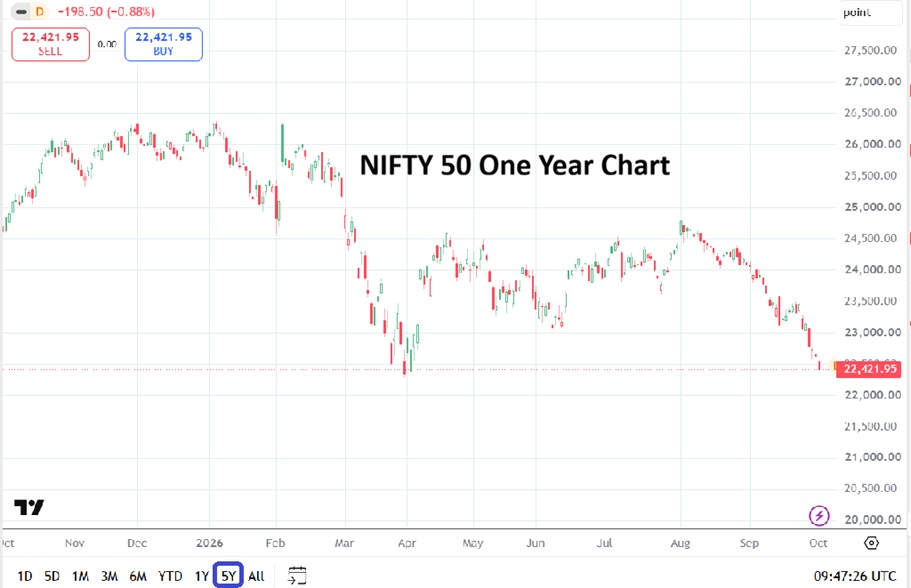
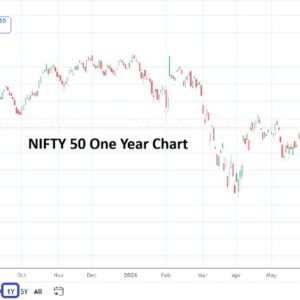
Nifty 50 One Year Chart as of 4th October 2026
This system ran extraordinarily well the last two decades, until trade deficits in the Western economies ignited agitation amongst citizens and inside the government offices of policymakers from Brussels to Washington. In order to create jobs for their own people and protect their legacy industries from losses, countries are increasingly discussing protectionism, illegal immigration, and restricting access on critical technologies.
Irrespective of the tranquility and results in the past, this after the Latin American and Asian financial crises caused by the abrupt policy shifts. Changes to the free flow of capital and trade have shown they can disrupt exporting based economies faster than many governments could handle the challenging circumstances appropriately.
India is one of the nations’ standing at this new crossroad. It has favorable trade relations with many partners. Though India runs a trade surplus of good with the United States and Europe, its trade with China and Russia is clearly unilateral – Beijing and Moscow holds advantages.
To compete with external trade partners like Vietnam, China and Korea, India wants to allocate expertise into high tech manufacturing like semi-conductors, electronics, and other preferred sectors. Problematically, because every State in India follows a different industrial policy according to their own political aspirations and needs, it’s difficult for New Delhi to dictate policies that align with central government objectives cohesively.
Changing the Playing Field to Accommodate Growth
The experience of industrial bases like Germany, Japan and the East Asian economies show that manufacturing growth requires coordinated policy. Ironically in India, after the 1991 economic reforms, no structured national manufacturing gameplan existed until 2011.
Industrial strategy should provide better support for land acquisition by the government with generous terms to landowners for agricultural lands, rather than merely leaving it to private corporate interests. Less bureaucratic labor law reforms would help too.
The 1991 industrial policy statement reduced the barriers to entry for private industry, deregulating, abolishing the monopolies and restrictive trade practices act of 1969, and significantly reduced import duties. This remained a focused policy pillar over two decades. However, there remained a number of gaps that still need to be improved.
The “new economy narrative” discussed by the Indian government needs a realistic perspective. For example, policy makers in the government argue that PLI (Performance Linked Incentive) which started in 2021 is an answer for reviving sector specific manufacturing. But not everyone is convinced. PLI is based on subsidies that provide incentives to generate output in fourteen highly import dependent sectors (especially for imports to China) that are extremely capital intensive in character. This has happened at a time when India needs to create more quality jobs in manufacturing, but faces hurdles.
The PLI has issues because the system requires many firms apply for the incentive subsidy to increase production in their chosen sectors, and the government will be in charge of picking winning firms (rather than sectors). This is the opposite of the practiced industrial policy of the East Asian Tiger miracle economies and what underlaid their success in export oriented manufacturing growth. The East Asian nations only selected industries to support, they did not ‘pre-pick’ winning firms.
The Soviet Example: Agriculture as a Competitive Lever?
During the Brezhnev era in the Soviet Union, most everyone in the top government positions of the now disbanded nation knew something was wrong economically. The Soviet Union was a giant bureaucracy that wanted to manage all production according to misguided yearly targets – the failure was only a matter of time as the utopian economic system imploded upon itself with malfeasance.
In the 1970s within the Soviet Union the immense influx of hard currency achieved from energy exports masked severe domestic failures, particularly in agriculture. Instead of investing the trade surplus into modernizing domestic infrastructure, the Kremlin was forced to use its Petrodollars to import vast quantities of Eastern grain and agricultural products to compensate for chronic harvest failures and feed its population.
By the early 1980s, the Soviet Union’s trade profile resembled that of a developing nation: exporting raw unrefined materials to purchase food and finished goods. When global oil prices crashed in the mid-1980s, the Soviet Union trade balance plunged into severe deficit and never recovered. Stripping the state of the hard currency it needed to survive.
Likewise, despite being an agriculturally important nation, India is forced to import massive quantities of specific agricultural goods due to low domestic yields. For instance, researchers had long predicted a rise in prices of Tamil Nadu State agricultural commodities due to a shortage of agrarian areas and stagnant growth in irrigation. Farmers are turning away from paddy cultivation because the returns fail to cover costs. Increased farm wages, machinery rentals, irrigation costs, fertilizer and pesticide prices have steeply driven up the costs of crops in Tamil Nadu. Consequently, paddy farmers are trapped in a cycle of debt and economic distress.
Although agriculture employs nearly half of India’s workforce, it contributes only about 15-18% of GDP. Outputs per workers are low. Tiny landholdings, low yields, dependence on the monsoon, and depleted groundwater limit productivity, this while subsidies and procurement favor rice and wheat over diversification. Poor storage, weak credit access for small scale farming, low investment opportunities add to problems and limited non-farm jobs keep surplus labor stuck on farms. India remains a net agricultural exporter achieving about $51.9 billion USD in 2024-25, but despite this higher valued Agri-export composition is not sufficient.
Policy Decisions and Competitive Companies
India’s services exports and remittances have created a persistent source of Forex earnings. The resulting accumulation of foreign exchange reserves provides an external capacity to import vital capital goods, technology and other productive tools to create benefits. The challenge is to convert this external surplus into better domestic productive capacity. This can be done by investing in infrastructure including logistics, energy, worker skillsets, technology development, improved ports and warehousing – and other foundations required for manufacturing and developing superior values in agriculture.
Improving the infrastructure for success is crucial, but importantly the Indian government should not attempt to pre-ordain winners through the PLI. Choosing winners can become a doomed strategy when the State tries to determine in advance which firms, technologies or industries will ultimately become globally competitive as capitalism plays out and companies ascend or fail sometimes.
The East Asian experience suggests that industrial policy can support selected sectors, but competitiveness ultimately has to be tested through productivity and export markets. The role of the State should therefore create conditions in which winners can emerge through competition within the marketplace, as they manage finance, technology and their workforces – which will help the companies strive to become the best versions of themselves.
Copy and paste the text from AMT that you want to share
Like this? Get the next one in your inbox.
Independent commentary on global markets, geopolitics, and the forces shaping capital flows. Two to three articles per week.
Related posts:
 India Insider: Growth without Prosperity, Thoughts and Comparisons
 India Insider: Leveraged FCNR Deposits Reliance and Remittances Masks Structural Vulnerabilities
 India Insider: Systematic Investment Plan Boom
 India Insider: Foreign Investors and Their Selective Choices
 India Insider: A Giant Bureaucracy Needs an Urgent Reset