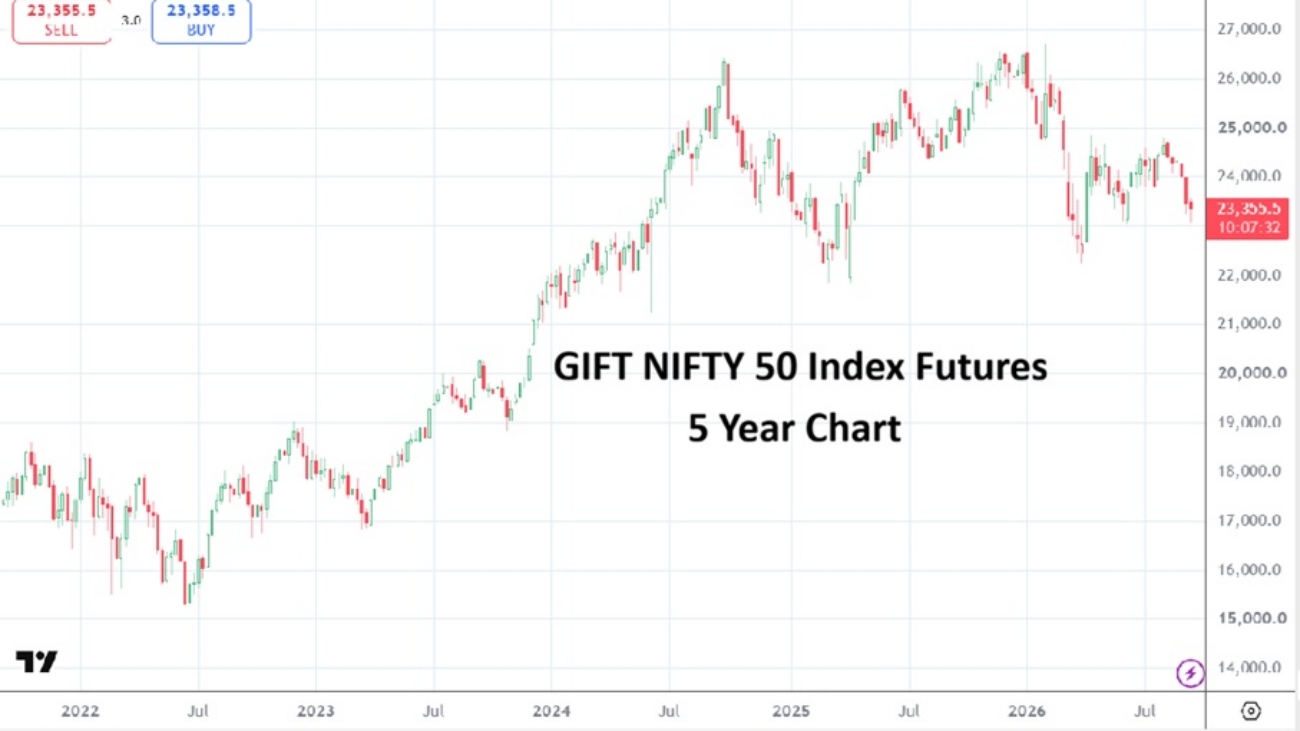
GIFT NIFTY 50 20260918

India Insider: NSE IPO Coming While Local Macro Conditions Not Accommodative

India's National Stock Exchange Magic Act Needs to Diversify

The National Stock Exchange (NSE) of India has been planning for an IPO quite a while. The total valuation of NSE is estimated at 5 trillion Rupees ($53 billion USD).  The issue size is 22,569 crore ($2.4 billion USD) while shares are priced at 1700 to 1785 per equity share. Share value of 65% are blocked for institutions and 35% for the retail segment. The IPO is open from September 17th to the 21st. The sales is an offer by existing shareholders, not a fresh issue of equity shares.

The rise of stock trading apps in India has made applying for primary offers easier, especially after 2020. The NSE’s value has soared over the past decade as India’s capital markets have expanded and retail participation has been surging. NSE’s unlisted shares were bought by wealthy individuals and NRIs (Non-Resident Indians) over the last few years in order to capitalize from the new trading boom.

The NSE IPO is priced at 42 times its earnings, a steep valuation compared to its global peers. NSE investment bankers were advising the stock exchange to issue 148.9 million shares at a higher valuation, but upon sensing less market depth and cautious appetite, bankers have reduced the number of shares offered to 126.44 million.
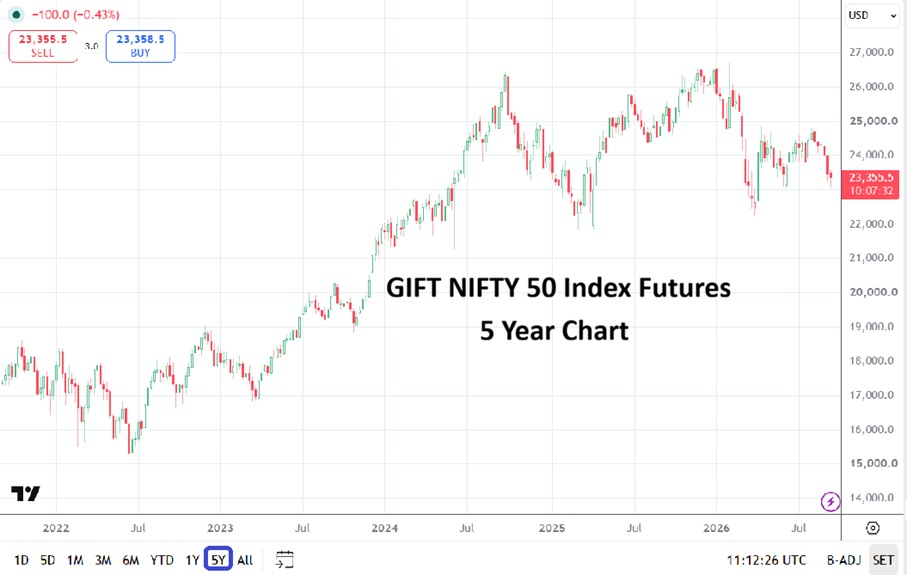
GIFT NIFTY 50 Index Futures Five Year Chart as of 18th September 2026

Reports from the last few days say anxious brokers have been calling individual investors and trying to entice them to invest in NSE. As an example, the Life Insurance Corporation (LIC) IPO in 2022 did not demonstrate as strong a marketing push from brokers compared to this NSE event. 

What’s the reason for the NSE IPO is being rushed to the marketplace when internal macro conditions are not accommodative? Various India state owned enterprises own stakes in the exchange including the State Bank of India and its subsidiary SBI Capital Markets entities – they and others likely want to be part of a ‘win’.

The NSE IPO comes at a time when the regulatory barrier on brokering and trading has intensified in recent years. Options activity propelled a gigantic boom in retail activity and helped strengthen NSE’s capital position. But it could not have happened without the regulator, the Securities and Exchange Board of India, providing a relaxed attitude regarding influencers who sugar coated facts and were partnering with brokers to attract millions of uneducated and struggling youth to bet on India’s index derivatives market.

As someone who worked in a private full service broker, I have seen countless numbers of people lose money while options betting. College students, retired people, small shop owners opened trading accounts in mass with a number of digital brokers and began to bet on weekly option wagers where the odds of winning were stacked against them.

The Indian government by igniting this machine has so far collected 90,000 crore ($9.37 billion USD) between Financial years 2021 and 2026. The flip side is the mounting losses incurred by retail traders. From FY 2021 to 2025 the losses are estimated to be around 287,000 crore ($30 billion USD) per SEBI’s data. Individual traders lost money in this casino like atmosphere around 91% of the time.  The numbers are staggering because option sellers, hedge funds, prop and other wealthy traders made money at the expense of retail losses.

The government has collected income taxes on these capital gains from profits generated by the option sellers. While retail traders who had borrowed money via personal loans to wager in these dangerous trading instruments are now suffering severe financial liabilities, paying 40-60% interest rates on their loans. Many youngsters have lost serious money. This is a severe situation because the average annual income for a person is around 15,000-20,000 Rupees ($208 USD) per month.

The NSE meanwhile has made revenues of around 35,000 crore ($3.65 billion USD) between FYs 2021-2025 for facilitating this disastrous betting landscape. In other words, the National Stock Exchange has seen profits rise by more than three times in these last four years due to the retail boom. Brokerage offices have collected handsome rewards too.

After the regulator begun to scrutinize losses incurred by retail traders in 2023 and 2024, they increased the minimum margin requirements for option traders to participate on particular contracts by a multiple of 3. This means those who were wagering with 500 Rupees now have to spend 1500 Rupees for pursuing the same contracts, assuming the premium per unit of the contract is unchanged. The regulator also limited numerous other option contracts on various indices to streamline the segment, i.e. allowing weekly expiry options for NSE and for the BSE (Bombay Stock Exchange). The chief aim of these measures was to discourage people from rapid, speculative bets on options that expired within days and it worked. Within a few weeks the high frequency retail trading frenzy had deflated sharply.

The biggest loser to this action is the NSE, which is getting around 60% of revenues from derivatives trading volumes. As retail traders activity cooled, exchanges like NSE shifted towards attracting patient long term capital from institutions for listings and rely heavily on traditional cash markets for generating revenues.

Despite pundits arguing that India has deepened the capital market inclusion, the reality is it has made very few changes in the existing system. For instance, the Reserve Bank of India ordered the closure of the exchange traded currency derivatives market in 2024, which helped small scale exporters and importers to hedge their risks efficiently. The country also has made little in-roads trying to expand the corporate bond market, and 75% of financing is still done by corporations through bank credit lines. India despite making numerous changes in regulations has failed to foster the development of financial institutions with bonds.

Short selling of shares remains banned, meaning a buyer of shares has two variables whenever he or she is purchasing, profit or loss. They can’t hedge. There is also no major marketable securities avenue for government or corporate bonds. Government bonds are still fix-rated like bank deposits. In the last decade many who people who ‘invested’ and funded instruments in shadow banking firms lost huge amounts of money, and so have individuals who invested in non-convertible debentures (NCDs) via Yes Bank and Dewan Housing Finance Limited.

If the National Stock Exchange wants retail investors to participate in its IPO shares it should diversify avenues for making money and issue a lower valuation to be attractive. The NSE cash machine has stumbled. Profits in the India financial markets industry have slowed as wealthy high net worth individuals and prop traders have shifted bases to UAE and Singapore. The NSE should not expect retail traders and small investors to subscribe to its IPO when people are struggling to pay their monthly bills. The NSE minted a huge amount of money from retail traders via a casino like binge and helped institutions and governments earn superlative profits. Now the NSE wants to replicate this cash magic act with its IPO.
Copy and paste the text from AMT that you want to share

Share:
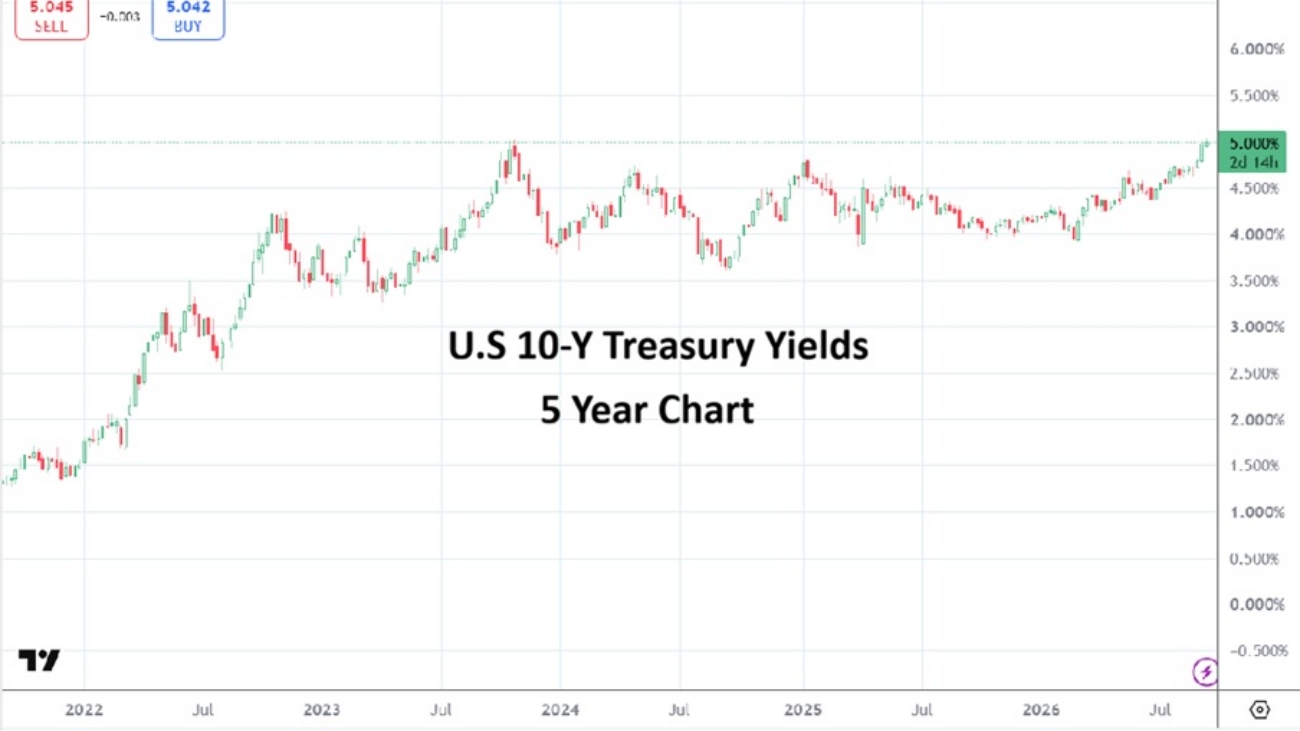
10Y Treasury Yields 20260916

Fed Decision: Two Sides of a Dangerous Coin

The Fed Should Not Raise Rates But It Will

What and who you believe will play an important part in today’s market for speculators. While investors who are looking at long-term prisms can comfortably wait on the decision from the Fed’s FOMC regarding interest rates later today, retail traders who are trying to profit on near-term wagers via momentum and are seeking to gain an advantage by knowing which way the wind is blowing have a difficult task ahead. Via results in the Forex market it appears many financial institutions have braced already for an interest rate hike of a quarter basis point.

However, what if the financial institutions and many analysts are wrong? What if Fed Chair Kevin Warsh and other FOMC voting members believe the White House and think that inflation will erode as price pressures ease when there is a remedy to the Iranian conflict. That would mean that they could debate with other Fed officials for no interest rate hike. Because if the Fed were to raise interest rates later today, thus making borrowing costlier for businesses and consumers – and potentially putting more strain on the U.S debt payments because of increasing Treasury yields, it would still not solve the higher costs of energy. (There is an argument below which negates this possible yield problem and one that is likely to be heard from some economists).

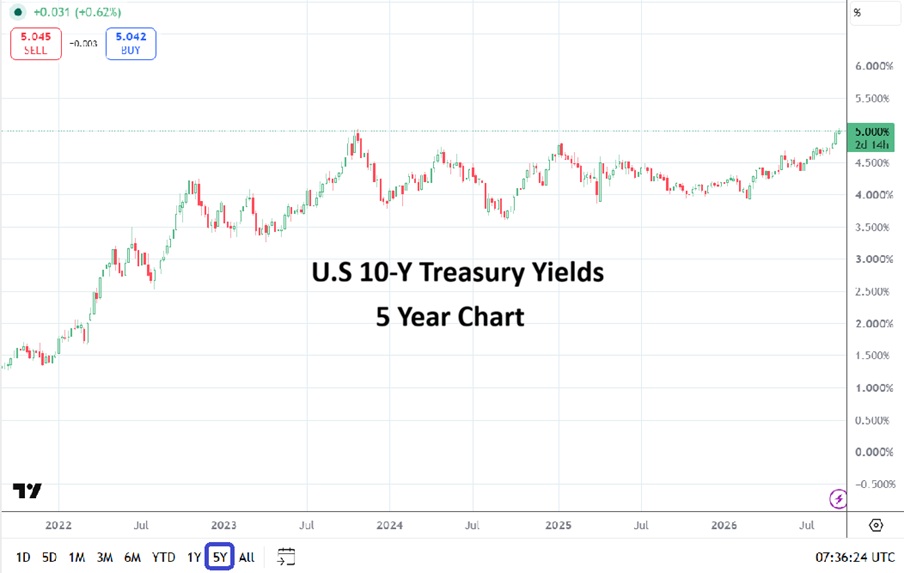
U.S 10-Y Treasury Yields Five Year Chart as of 16th September 2026

Yes, there is demand for fuel globally, but the demand for energy is not going to decrease because the U.S Federal Reserve may raise interest rates. In fact, it could make costs more expensive for businesses who are likely burning money via increased credit lines already created, this to transact their currently higher costs to guarantee effective supply of fuel to fund their logistics and manufacturing which they had not planned for while making their initial 2026 budget estimates prior to the Iranian war. In other words, a higher Federal Funds Rate will equate into higher costs for businesses.

$100.00+ WTI Crude Oil is Not A Friend

Per the other side of the coin, WTI Crude Oil has turned more expensive and volatile since March of this year. For a moment it looked like relief would be delivered via the supposed MoU between Iran and the U.S. WTI Crude Oil went below $80.00 periodically when optimism was peaked by White House rhetoric and calm waters in the Hormuz Strait were reported. Hopes for a return to WTI Crude Oil below $70.00 were viewed as legitimate.

However, the tranquility sought has vanished in the past couple of weeks and has grown more anxious as Saudi Arabia has become an important actor in the Middle East conflict as the Houthis and Iraqi militias cause havoc for the Saudi Arabian government. The price of WTI Crude Oil is now stubbornly above $100.00 and rumors about how Saudi Arabia is dealing with its own military confrontation and the way it is able to supply its own Crude Oil are confounding.

Which brings us back to the initial question regarding the Federal Reserve and Kevin Warsh, who will the Fed Chair listen to? Does he and other voting members of the FOMC believe there will be a quick fix to what has become stubbornly higher costs for WTI Crude Oil which is creating inflation? Or do they now have to objectively consider what may have been perceived as a temporary blip of elevated expenditures for the U.S economy as a potentially long-term problem? If Warsh and his cohorts believe the Iranian situation is going to find a remedy within the next four to five months, they should NOT raise interest rates today.

Again, while higher fuels costs are problematic, raising interest rates is not going to lower demand for WTI Crude Oil which is the chief instigator of higher inflation globally. It is not a question of who believes President Trump’s tantrums, it is a question concerning viability of a real end game to the Iranian situation. Plenty of Crude Oil exists, its production capabilities are strong, it is Middle East supply to Asia, Europe and Africa that is causing a problem and the higher cash and futures pricing for WTI Crude Oil. Thus, the lynchpin remains Iran. If their government capitulates and bends a knee, opening up the Hormuz Strait and stops plying its influence on the Houthis of Yemen and other militia groups in Iraq that are now causing problems for Saudi Arabia the price of WTI Crude Oil will drop dramatically.

If the situation is not rectified and the price of WTI Crude Oil remains elevated and Saudi Arabia doesn’t handle their confrontation which is turning increasingly militaristic, then it will not solve a higher interest rate initiative from the U.S Federal Reserve – unless the Fed is merely looking to decrease Treasury yields by increasing global demand for the bonds – thus hoping to increase their desirability.

Old School vs. New School 

Today’s decision from the Fed comes down to old text books and failed central bank policies versus new economic considerations. An interest rate hike from the Fed may actually make circumstance more difficult for governments around the world trying to balance their own books. 

For instance, higher yields on U.S debt are causing problems in India where some investors are shedding Indian Rupee assets and seeking the high yielding U.S Treasuries not only because of a ‘guaranteed’ bond yield, but the fact that their assets are stored in USD which is likely going to remain stronger than the INR over the next few years if a historical track record is looked upon. This is a saga that will play out in other emerging market nations too as financial institutions chase ‘secure’ profits.

5 is a Dangerous Number

So not only does the Fed face a problem regarding an interest rate hike that will not solve inflation problems caused by a war that is effecting prices because there is a fear of supply logistics, but there could be a knock-on effect regarding debt. U.S 10-Y Treasury yields near and above 5% is a clear warning side that investors are uncomfortable, this no mere speculative gain achieved by bond vigilantes. 

Another point, if the Fed were to raise interest rates today, it could in theory cause greater demand for U.S Treasuries from abroad and thus lower the Treasury yields for the moment – thus making the argument for a higher interest rate more dignified for those who want to raise rates. However, if the Fed were to say no to interest rate increases for now and point to a belief the U.S conflict with Iran is going to conclude sooner rather than later and said the U.S economy faces distress because of the higher fuels costs alone, this could also solve confidence problems.

U.S debt stands above 40 USD trillion, lower yields are a desire, but lower borrowing costs for businesses and consumers are wanted too. So what will the Fed do today………..drumroll please…………the Fed will raise interest rates – making a mistake. And will show it fears a long-term risk scenario between Iran and the U.S and problems for Saudi Arabia. The USD will see plenty of volatility. Confidence will not be shown by the Federal Reserve today and this will be problematic.

Stage presence from Fed Chair Kevin Warsh is going to be extremely important today. He has failed in his previous two FOMC Press Conferences to look confident while speaking and answering questions. His speech at Jackson Hole in late August also proved lackluster.

And this is where is gets more dangerous for Warsh and the U.S White House, because of President Trump’s ability to change his tactics quickly – there is a lack of confidence among investors who are trying to gauge their outlooks for the mid-term and beyond.

Kevin Warsh will find it difficult to pull a rabbit out of a hat. Many folks will walk away disgruntled if an interest rate is introduced and no clear guideline is mentioned regarding what is next regarding other potential rate hikes – or a plan to actually lower the Federal Funds Rate. The U.S economy while strong could easily be sent into a recession with an interest rate hike and sustained higher WTI Crude Oil costs. 

Behavioral sentiment is going to remain on a toxic tightrope unless confidence is delivered. While individual perceptions about what should be done are important, understanding the mindset of the U.S Federal Reserve is crucial. Eliminating our own personal beliefs and bias from trading decisions and acting on what realities may be demonstrated are vital to profit. 

Copy and paste the text from AMT that you want to share

Share:
Iran Last Stand or 20260915

Iran’s Last Stand or a Humbled Saudi Arabia?

Either bin-Salman or the Islamic Republic will Survive

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 15th of September via The Angry Demagogue.

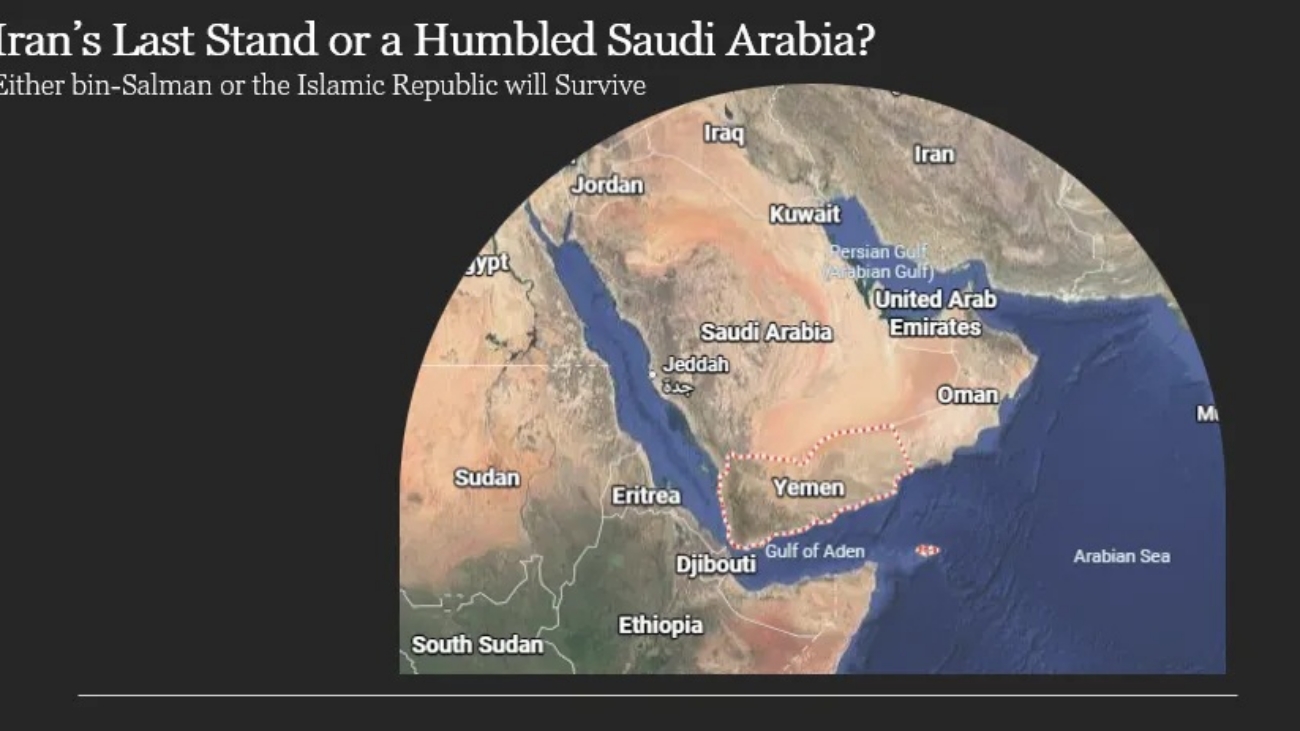
The Houthis have not only pushed back and regained ground lost in the Saudi offensive against them in Yemen, they have taken Saudi backed ground and are moving forward. They seem to be moving at will and are now in total control of the Bab al Mandab Straits and are looking to surround and then capture the port of Aden. According to Or ben Yehezkel of the Telegram site 301 Ha’Olam Ha’aravi, which consists of a group who are fluent in Arabic and Farsi, the Houthis are moving quickly and if they take the port of Aden, the main port of Saudi backed Yemen, they will organize, along with the Shiite militia’s in Iraq to invade Saudi Arabia.

Although they don’t have an air force, the Houthis have managed to gain ground against an air force with over 220 advanced fighters, 8 AWACS for air coordination and over 20 refueling aircraft. With their missiles and drones, the Houthis have managed to cause severe damage to Saudi Air Force bases and have all but neutralized Saudi air superiority.

Iran’s Last Stand or a Humbled Saudi Arabia?

It seems that the Islamic Republic has given up on getting Israel out of Lebanon and saving Hezbollah and instead is concentrating on Saudi Arabia and the Gulf States with the goal of forcing the U.S out of the region. If they do in fact take Aden, the Houthis can go up the coast to Mecca and Madinah and meet Iraqi-Shiite militias there as they attack across northern Saudi Arabia. This will force the Saudis to defend what is as important for them, reputation-wise, as oil – and that is the holy cities of Mecca and Madinah. For the Houthis the coastal route is do-able. From Iraq it is a 20 hour drive from Iraq to Mecca (a bit shorter to Madinah) through harsh dessert terrain – although there are paved roads. Alternatively, the Iraqi militias could attack in the Gulf area (either going through or avoiding Kuwait) while the Houthis rush to Mecca, forcing the Saudis to split forces.

For the U.S, ground attacks in Saudi Arabia proper, putting American bases and troops at risk, will force them to intervene so as to save U.S bases as well as Saudi honor. It is not that the Iranian Islamists think they can take over Saudi Arabia, only that they can embarrass it into submission. In the Arab and Moslem world, pride is more important than fact and a near defeat might embarrass the ibn-Saud kingdom enough to rattle its self confidence. The Mecca Accords between Turkey, Pakistan and Saudi Arabia have shown their impotence as neither the Turkish nor the Pakistani Air Forces have been seen over the Saudi desert (although it seems that bin-Salman asked CENTCOM to ask Israel to help them).

However, the real goal of the Houthi-Iranian offensive is to force the United States out of the Gulf. No matter what people are saying the blockade and other economic measures are having a strong effect on Iran and its regime. This does not mean it is close to falling, but they obviously feel a need to change the conversation and to use outside pressure to bring some relief to the country and eventually to remove the American “menace”.

An article in The Free Press (whose headline is more optimistic than the article itself) correctly states that the Houthis are trying to lessen their dependence on Iran, but that does not mean that most of the orders are not still coming from Iran. It is not the Houthi’s themselves that are a threat but the Houthis as an Iranian proxy that is the danger. A Houthi semi-state in western Yemen is a thorn in the side of the world, but it is very different than an Iranian controlled western Yemen. Currently, there is no reason to believe that Iran is not controlling events in Yemen just like they controlled events in Lebanon. Israel’s “ceasefire offensive” against Hezbollah, taking their major command centers and all but pushing them out of their strongholds in southern Lebanese Shiite villages has shaken the Iranian leadership and weakened their hold on events in the Middle East. They only have Yemen, the Persian Gulf itself (the Straits of Hormuz) and some Iraqi militias left to take the pressure off them.

Alternatively, if the Houthis attack fails, could this be Iran’s last stand? A defeat at the hands of the Saudis, coming right after the Hezbollah defeat at the hands of Israel will leave Iran with only one pressure point – one that the U.S Navy has blocked. While they are causing some discomfort in the West via rising oil prices, they are causing more discomfort in their ally China and even more in their own country.

Last week we indicated that there are four things that need to happen in order to put in place the possibility, let’s upgrade that to the probability of regime change. The Islamic Republic understands this better than the Western press. The first is nearly complete and that is the destruction of Hezbollah. The second is the American blockade and economic D-day which are in full force but need time to work. The third is the defeat of the Houthis and the last one is an intensive U.S (or U.S and Israeli) bombing campaign combined, possibly, with the taking of Persian Gulf islands.

If the Saudi’s lose, this will endanger the entire U.S plan and may even bring down the bin-Salman rule in Saudi Arabia as he can be replaced by more conservative Princes if his plans fail and he embarrasses the Kingdom in front of the Moslem world. This is a best-case scenario for the suffocating Islamic Republic and could lead to their resurgence in the region.

Iran knows this well and the Houthi-Saudi war will either lead to the downfall of the Islamic Republic or a very humbled and maybe changed Saudi kingdom. A fight to a standstill with the Houthis remaining an Iranian proxy means that the other three legs of the plan – the destruction of Hezbollah, economic D-day and U.S bombing effort will need to be pursued quickly and violently. As Israel has painfully learned, fighting to a standstill just gives your terrorist enemies time to regroup. Without a Houthi defeat we will be where we are today and the U.S goal of ridding the region of the Islamic Republic of Iran will be much more difficult. Much more is at stake in the Houthi-Saudi war than people believe.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

Follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

Share:
India GDP Savings 20260911

India Insider: Leveraged FCNR Deposits Reliance and Remittances Masks Structural Vulnerabilities

Forging True External Strength Without Relying on the Crutch of Foreign Deposits

For the last few weeks, financial publications have applauded the news that India received around $127 billion USD via leveraged foreign NRI deposits (FCNR). Banks swapped these dollars for Rupees with the Reserve Bank of India (RBI), securing cheap funding while ostensibly strengthening India’s external position. Analysts have calculated that while the hedging cost for the RBI is around $16.3 billion USD, the investment income generated by parking those funds in U.S Treasuries could reach $22.4 billion USD. On a net basis, this implies a $6.1 billion USD gain for the RBI over the next five years. However, while this may look like a tactical victory on a balance sheet, it ignores a fundamental macroeconomic contradiction: if the Indian economy is growing robustly, why isn’t its external position strengthening organically?

The Remittance Paradox

Indian rural towns and villages have long sent workers abroad to Singapore, Malaysia, the Gulf States and beyond. This migration has created a flush of dollar remittances, making India the world’s largest recipient in absolute terms. For instance, India has attracted around $135 billion USD in 2025, a figure that has been rising steadily. Yet, despite this massive nominal volume, remittances represent only about 3.6% of total GDP. 

This capital undeniably boosts domestic consumption, but it also exposes a structural gap between wages inside India and abroad. The fundamental characteristics of current account deficit countries is that they demonstrate low domestic savings, high investment needs, and persistent reliance on foreign capital to finance their deficits.

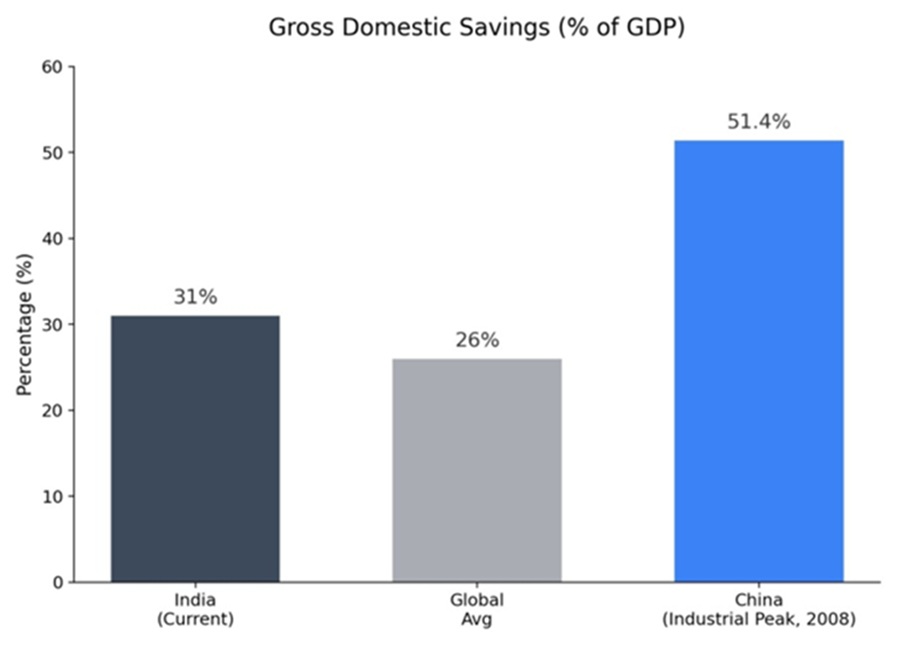
World Bank/CEIC for India and Global Average, and Wiemer EAI Brief for China’s 2008 Peak

In India’s case if the economy were truly expanding from within as said, domestic incomes would have risen proportionally with national growth, expanding the pool of internal capital. Instead with a vastly informal economy, India remains heavily dependent on its diaspora to fund its current account deficit.

The Domestic Savings Deficit

According to periodic labor force surveys, India is projected to have a working age population of around 900 million by 2030. To effectively employ this massive demographic dividend, the country urgently needs to raise its domestic savings rate. Currently clinging to roughly 31% of GDP, India lags far behind industrial powerhouses like China, which leveraged a domestic savings rate of around 45% to fuel its manufacturing ascent.

Policymakers should not rejoice over a capital account surplus funded by NRIs, especially when that surplus is leveraged over 7 to 10 times. It is this exact diaspora sending USD home that fuels India’s consumption, creating an illusion of self sustaining economic liftoff.

The “Dutch Disease” in Local Economies

The heavy reliance on remittances creates severe geographical distortions. Many towns possess high savings but they are incredibly unevenly distributed. These high savings are attributed to external capital rather than domestic productivity, while local employment remains trapped in informal service sectors or low productivity agriculture. Towns with high foreign remittances naturally develop immense asset bubbles in real estate and experience soaring rent and consumption costs. Because these economies do not export goods or services to other states or countries via production or services, they rely entirely on external capital inflows to generate internal demand. This reflects a localized variant of the “Dutch Disease”.

The labor market is extremely tight in these areas. Due to the high cost of living and limited wage growth, workers tend to migrate to other regions or overseas in search of better opportunities. This tight market further contributes to cost inflation in labor, food, and overall living expenses and increasing the cost structure for both households and businesses. This vicious cycle is primarily due to weak policy decisions from the government’s end, such as inadequate industrial infrastructure, poor urban planning, weak skills development, limited MSME financing, also insufficient connectivity.

A Structural Transformation is Required

This economic pattern is not unique to India, it also mirrors provincial towns in the Philippines, regions in Mexico and parts of the Balkans. While remittances support consumption and keep real estate elevated, they fail to translate into productive investment due to weak industrial bases and limited economic linkages. The result is seen vividly in the balance of payments clearly as India’s importing needs keep increasing, but the inability of Indian goods to compete globally results in persistent gaps in export volumes. 

With protectionist rhetoric vibrating in Washington and anti immigration protests rising from the U.S to Australia, this model is highly vulnerable. The Indian government must urgently pivot toward policies that empower Indian nationals to work in small and medium scale businesses (SMEs) domestically. By focusing on small scale manufacturing with high economic linkages and wage growth potential, domestic savings will naturally rise, eventually forging true external strength without relying on the crutch of foreign deposits.

Copy and paste the text from AMT that you want to share

Share:
AMT Top 10

AMT Top Ten Miscellaneous Post-Labor Day Notes and Tantrums

Higher Hopes and False Victories Welcome Nervous Investors Back After the Holiday

10. We Thought You Won – Part One: Apologies to Western Michigan University who had a victory stolen from them on Saturday in Ann Arbor. The Big Ten should not only be embarrassed, but they should be investigated. Big time college football suffered a black eye this past weekend. Folks wondering why WMU is not making a bigger stink regarding the added time and decision to repeat the last play of the game which ultimately cost WMU the contest against the Wolverines, should understand they will not. Because WMU needs to play against the University of Michigan to receive big pay days, which often are hard to find. WMU received 1.5 million USD for the game on Saturday and are scheduled to play against Big Blue again on the 1st of September, 2029.

9. Not Dead Yet: Bitcoin is trading near $78,800. After flirting with lows around the $58,100 vicinity in late June, BTC/USD has created momentum upwards. However, the elevator still can go down. Strategy via MSTR is near $142.00 per share. Michael Saylor survives and influencers are boisterous and breathing a bit easier – for now.

AMT Top 10 Miscellaneous Post-Labor Day Notes and Tantrums, 8th of Sept. 2026

8. Bad Brains: Tucker Carlson forayed into another absurd path when his recent guest, Jess Elofson, declared that Algebra is not needed and those who use it are ‘good little goy-slaves’. Carlson averages almost 57 million views to his podcast and social media outlets on a weekly basis.

7. NVDA: Nvidia is priced near $230.00 and the Nasdaq 100 finished Friday’s trading around 29,544. The Nasdaq 100 traded above 30,700 on the 3rd of June. Nvidia’s high touched the $236.00 level in the middle of May. Summer saw choppy reversals in the Nasdaq and S&P and values while elevated have run into cautious headwinds. Now that Labor Day is complete and summer ambivalence will be dusted off, where will the stock markets go? Iran lingers, inflation via higher energy costs looks problematic, mid-term election worries, AI infrastructure expenditures are concerning and bond yields all weigh on investment mindsets. Additional risk events are coming quickly down the road, Consumer Price Index data will be released this Friday and the Fed’s FOMC interest rate decision is next Wednesday on the 16th.

6. Reversal City: The USD/JPY is traversing below the 154.000 mark currently. The Bank of Japan and the U.S Treasury/Fed interaction regarding intervention and rhetoric about protecting the Yen’s value has apparently scared off buyers of the currency pair for the moment. Will bullish speculators now stay away from the USD/JPY for good? Doubtful.

5. Rhetoric Alone: Fed Chairman Kevin Warsh has found it difficult to convince the investment community that his lack of interest rate guidance is a good idea. Instead, the lack of clarity delivered from the Fed has led to higher Treasury yields. While Scott Bessent tried to fight the higher yields a couple of weeks ago, Treasuries are still smoldering and threaten to become a more dangerous fire. Investors and traders want more tangible proof that interest rate and monetary policies are structurally solid.

4. September 11th: This Friday will mark the 25th anniversary of terrorists attacks on the World Trade Center, Pentagon, and plane crash near Shanksville, Pennsylvania. 

3. Upwards: WTI Crude Oil price have shown plenty of nervous behavioral sentiment higher this past week. WTI Crude Oil is now over $94.00 in the cash market. Reports indicate that shipping via the Hormuz Strait has decreased again, this as military escalation appears ready to potentially increase as a reportedly desperate IRGC led Iran and frustrated U.S White House collide.

2. Post-Summer Guillotine: Danger lurks over the global marketplace, this as risk analysts, traders and investors appear to be converging into the same cautious direction. Forex, stock markets, bond yields, and key commodities are flashing bright yellow waring slow signals. Contrarian investors and speculators may be enjoying the current financial landscape. Value plays and volatile trading opportunities may feel appealing, but risk management is going to prove useful.

1. We Thought You Won – Part Two: After saying over the past handful of months that Iran had lost the war and just hadn’t surrendered yet, via Truth Social yesterday President Trump wrote that “when we WIN the war with Iran” that gasoline prices in the U.S would plummet. While observers are used to President Trump’s seemingly infinite capability to utter contradictory statements, yesterday’s appraisal of the current situation in the Middle East may be realistic, but it can also be observed as disquieting. There appears to be more trouble down the road.

Copy and paste the text from AMT that you want to share

Share:
Power of Intelligence 20260906

The Great Compression Part 4: Sovereignty Franchise

The Power of Intelligence

The most valuable piece of real estate in the world is a fab complex on the western edge of the Pacific, a short flight from the coast of a huge country that claims the ground it sits on. Taiwan Semiconductor Manufacturing Company, aka TSMC, prints the chips that every frontier AI model on earth depends on – and nearly all of them are currently made on that shore in Taiwan. This is simply a given; geography, unlike software, doesn’t scale, doesn’t copy, and doesn’t move.

For a decade the industry treated intelligence as something borderless, a global utility that would flow to wherever demand called for it. That framing is way past obsolete in a world that is split, lost along with the old dream of an uncensored Internet and free information exchange. Now, the crack is widening along a new axis. Forty years ago, the division ran through Berlin, and it was drawn by ideology. Today it runs through a supply chain, and it is drawn by who can make, buy, and run the machines that think. The AI chips are only the part of the split you can see and touch.

The Great Compression Part 4: Sovereignty Franchise

The Independence Chokepoint

Compute has already left the free market and entered the permitted layer of the economy. Advanced NVIDIA processors are no longer something a buyer simply purchases; they are something a government allows a buyer to receive. Export licenses now stand between the most capable silicon and any customer headquartered on the wrong side of the line. Washington has spent three years building this wall chip by chip – and the reshoring push, the fabs rising in Arizona, the equipment and materials supply chains being pulled back onto home turf, is the same impulse cast in concrete: move the chokepoint onto ground you control.

The scale of the gap explains the urgency. The U.S. holds a lead in AI compute capacity measured not in percentages but in multiples. China’s domestic production of the highest-end accelerators runs at a small fraction of American-equivalent scale. Its most advanced labs still lean on Western silicon to train their best models, whether the chips arrive through smuggling networks or through the gray route of renting restricted hardware inside third-country data centers.

Even when it’s leaking, the chokehold does its work. The controls slow every Chinese frontier effort, force it onto inferior domestic silicon, and keep it a step behind the labs it is chasing. But compute is only the first roadblock to independence: the next ones – on the intelligence itself – are only going up now.

The Gate to Intelligence

A wall around compute would be contained if compute were the end of the story, but it isn’t. The same logic that gates the chip is now reaching for what runs on it.

In June 2026, the U.S. Commerce Department required an export license for any foreign national to access a frontier AI model made by Anthropic – including the developer’s own non-citizen staff. Unable to verify the nationality of its users, the company withdrew the model entirely, and for the first time in this cycle a publicly available AI capability moved backward by government order. The controls were contested, the legal basis was unsettled, and access was restored within weeks. But the precedent was set: the authority to license the export of chips had been stretched to license access to an intelligence provider, and the mechanism worked before anyone had settled whether it lawfully could.

Beijing read the same lesson and moved to mirror it, drafting a regime to fence its own leading model weights behind national-security law rather than let them diffuse into the world. Two capitals, the same month, reaching the same conclusion from opposite sides: an AI model is not a product to be sold freely but a strategic asset released on terms. Intelligence has crossed into the permitted layer, and it crossed at both ends of the divide at once.

The Chained Brains

All of that is behind us; the interesting part is ahead.

Every ally now starting up its own sovereign AI is building it on a stack it doesn’t own – because the models, the chips, and the cloud beneath them are all American. What the ally holds is the building, the flag over the door, and the electricity bill. But the intelligence itself answers to another country’s export regime. This is sovereignty in name and franchise in fact.

The precedent for this arrangement already flies. Allied air forces buy the F-35 – the most expensive piece of weaponry in history – but they don’t thereby own it. The U.S. controls the source code and the mission-data files, and the aircraft’s full capability remains under American authority no matter how large the check. The buyer flies a plane whose brain is licensed, not sold, because withholding the core is the entire instrument of leverage. You can’t buy your way to control over a capability whose value to the seller depends on never fully handing it over.

While the F-35’s licensed brain governs a single platform, a national AI stack governs the layer through which a modern state thinks: its analysis, its logistics, its intelligence fusion, its administration. The fighter is a product on a leash, while the intelligence layer is the nervous system on a leash.

The Thinking Franchise

And the company installing that nervous system is already doing it. Palantir’s value was never the model but the trust above it and the data structure beneath it – the ontology layer that ingests a government’s data and turns it into decisions. In mid-2026 it began offering sovereign customers what they most wanted to have: full ownership of their model weights, retrainable, air-gapped, sealed behind their own walls. Still, the weights are the airframe that a buyer can own – but they will still have to run on NVIDIA silicon, inside an operating layer a U.S. company builds and controls, under the same export regime that pulled a frontier model offline in June.

Canada shows how thin the sovereignty can wear. Ottawa named itself the anchor customer of its own national AI strategy in mid-2026 while already running tens of millions of dollars in undisclosed Palantir contracts inside its defense and policing systems. The strategy announced sovereignty, but the procurement had already outsourced it. And by late summer, the two were trading tariffs and hard words, the closest alliance on the continent gone frosty, with the most sensitive systems of one side still running on the other’s stack. Nobody had to threaten anything. The dependency simply sat there, the way it was always going to.

Right in front of our eyes, the forward base of the last century gives way to the forward stack of this one. Instead of a U.S. army base near a European capital, a data-orchestration system running on NVIDIA chips, wired into the host government’s own operations, doing quietly what the garrison once did loudly. Land, power, and data can belong to Berlin or Paris, on paper – but the intelligence stack that holds the dependency will be American. It’s a cheaper umbrella, a deeper one, and a far harder one to ask to leave.

The End of Sovereignty

The immovable object was supposed to be the safe end of this story. Land, power, fabs, the heavy and hard-to-replicate assets that no software cycle can compress, the bedrock beneath the cloud. All of that still holds. But immovable is not the same as owned – and anyway, even the owner isn’t sovereign, because sovereignty itself is what’s being compressed at the top of the stack.

Every chokepoint described above rests on a fact that holds only for now: advanced compute is scarce, and what it produces can be walled. Practical quantum advantage dissolves both, and it is a contest between the same two powers that have run through every layer of this story. Perhaps one arrives first. Perhaps, if less likely, two arrive together. It changes little for everyone else. The machine owner reads what others hide and shields what it keeps. The only defense is a new cryptography built to withstand it, and it takes the same frontier compute and talent that only those two powers command. Even the lock is provisioned by the vendor.

It doesn’t matter who owns the oil or holds the warheads if the secrets around them can be opened at will and the means to reseal them belongs to someone else. The world is already two powers and their satellites, although most of them still speak as though sovereignty were something they possessed. The quantum edge is the point where the pretense ends.

Copy and paste the text from AMT that you want to share

India Employment 20260904

India Insider: An Unfinished Economic Transformation

Improving India's Education Strategy to Help Prosperity

Indian government officials, policy makers and journalists have all applauded the GDP April-June quarter data that came in 7.8%, compared to last year’s 6.9% growth. Although, the growth metrics are essential for understanding the results achieved in the broad economy, improved metrics should be applied towards the quality and conditions of life for citizens throughout India while comparing prosperity inequality.

Reading economic statistics without political or sociological factors becomes irrelevant. International trade agreements are often examined between capital and trade statistics, but in reality they are dominated by corporate lobbying and geopolitical powers behind the scenes calling into question results and assumptions.

Economists frequently discuss marginal propensity and disposable income elasticity, but in reality labour laws, union suppression and offshore workforce capabilities determine the wages paid to local employees. India like other Western countries, judges economic growth via headline statistics, without explaining the qualitative factors that determine a nation’s prosperity.

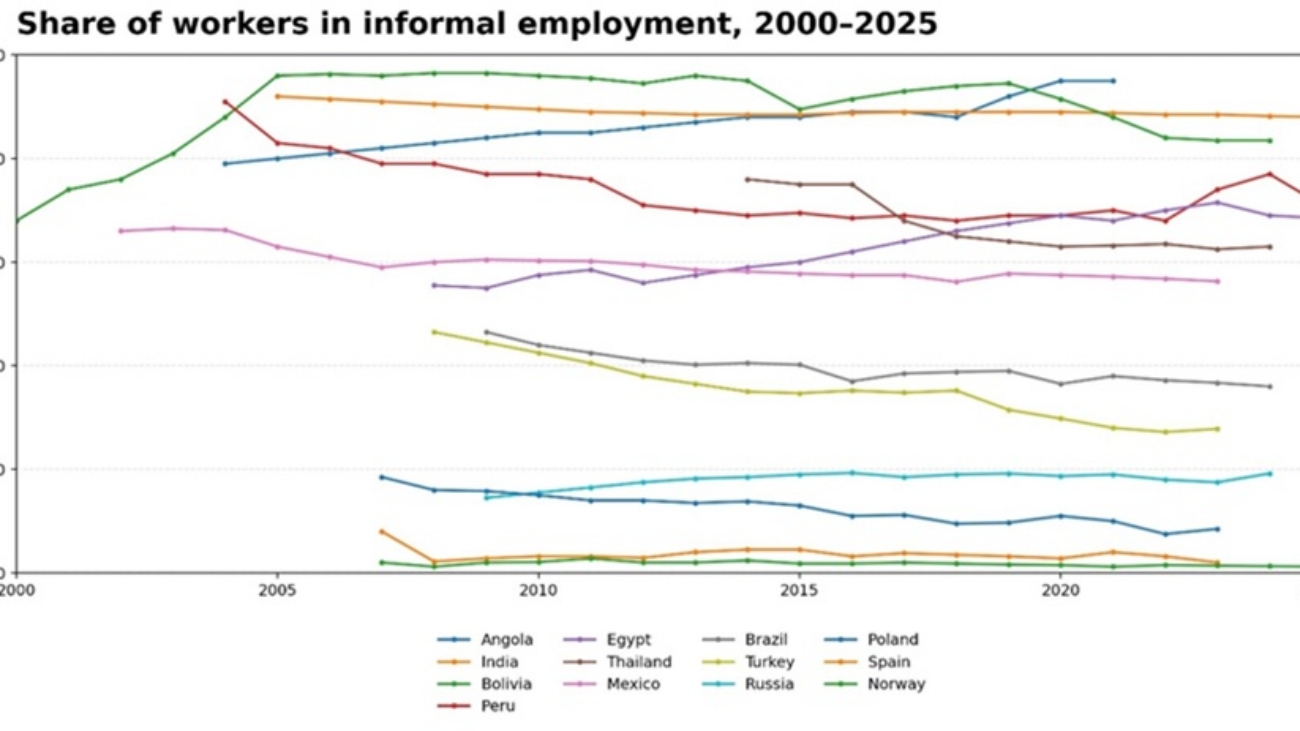
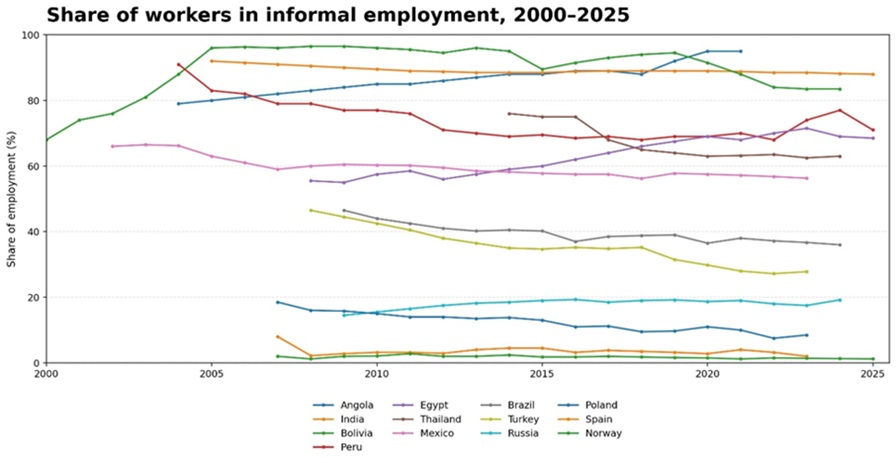
Share of Informal Employment Comparison 2005 – 2025

Human development concerns via good housing, better roads, access to quality education for every child, and secure hospitalization in government run facilities are not covered in GDP data. India calculates GDP data with a production and expenditure approach. Meaning the production of goods and services in a given time must match the underlying expenditures of the overall economy. Since the Indian statistical office calculates expenditures from with a limited number of household surveys and proxies, it’s not prudent to conclude that all GDP data is correct.

Some analysts prefer to look at Gross Value Added, GVA, to determine the overall value created by the nation’s producers. However, this data observes the organized sector via corporate filings, GST (Good and Services Tax) data, industrial production indices, but leaves the contribution of India’s vast unorganized employment sector in the dark.

Informality in the Job Sector

Over the last few years, non-farm jobs which are crucial for diversifying the economy and providing stability are not growing as needed. The formal job sector which offers security, benefits and fair wages is also stagnant. This lack of job creation is pushing more people into unpaid or informal work (the latter constitutes around 90% of the work force) where people struggle to make ends meet.

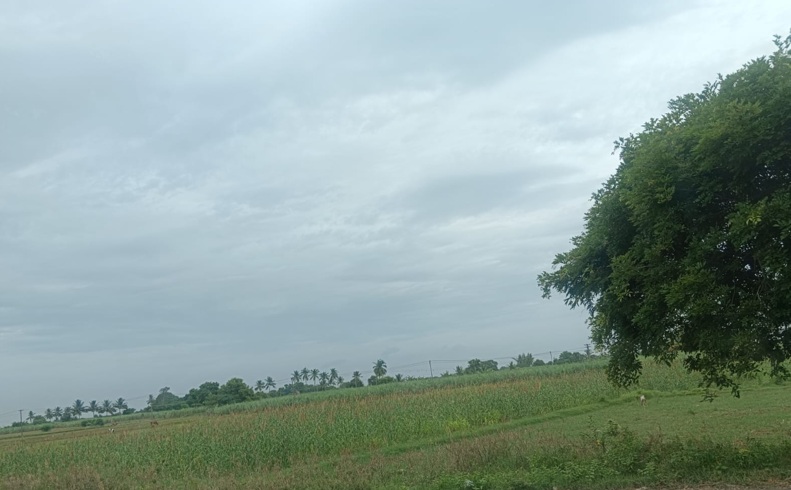
Kallakurichi District in Tamil Nadu State

The National Statistical Office ( NSO) under the Ministry of Statistics and Programme Implementation (MoSPI), performs periodic labour force studies, including household consumption and annual questionnaires of the unorganized sector, but they are sample based surveys and taken only as a proxy due to a lack of available data.

However, these sample based household surveys allow observations of the unorganized sector via snap shots. The agricultural sector traditionally seen as a last resort for employment in rural areas, witnessed a resurgence after the Covid-19 pandemic. Unbelievably, about 80 million people rejoined this sector (including women in rural areas who had exited agriculture jobs after 2004, as a periodic labour force quarterly survey shows) between mid 2020 and mid 2024. This increase in employment continued into 2025, not because of farm growth and modernization, but due to stagnation in the industrial and services sectors.

India’s major challenge in the coming decade is to create enough adequate non-farm jobs in order to accommodate new entrants and for those who are want to leave agricultural employment. Meanwhile, India has one of the lowest rates of work participation of women in the world. Yet, some studies argue that there is a close link between the female labour force participation rate and manufacturing employment. To help GDP growth rates move qualitatively upwards, India must absorb more women from farm work and into manufacturing.

Population size matters and because of India’s large numbers if rising labour productivity is accomplished the nation will not only continue to become one of the largest economies, but will have the the capacity to influence the world’s GDP growth rate positively. The impact of one policy (for instance to promote economic growth) on another (i.e: income poverty reduction) crucially depends on the level of a third variable like the improvement of human capital via better skills, knowledge and health. In other words, growth will be more successful in reducing income poverty if economic value is well developed and more equitably distributed for individuals.

Increasing the capabilities for those who want to be employed and form the base of a country would facilitate the creation of improved formal jobs, labour productivity and real wages. However, the reality is complex. During the Covid-19 pandemic and in its aftermath workers who had earlier left agriculture for better earnings in the first half of the noughties shifted back to agriculture instead of moving to more productive or formal jobs in non-farm activities. In other words, India has seen an odd reversal of structured change that normally characterizes economic development.

Education for the Entire Population

The only upward mobility for Indians predominately is to educate their children, so that they can get comfortable jobs and lift their families out of poverty. For decades especially after the post independence period, India’s higher education remained an elusive dream for millions of historically marginalized people from Schedule Tribes, Schedule Castes and many struggling communities. 

Unfortunately, the gates of universities and colleges were mainly opened to only privileged students belonging to the upper caste elites. Young ST or Dalit students in remote villages faced layers of disadvantages regarding poor schooling – including financial strains, social stigmas, etc. This is in contrast to students from the privileged social groups who often inherited aspirations and the access to higher quality education that comes with an expensive price tag.

While the door for higher education opportunities has been opened for all, it was much wider for those privileged groups, and it remained relatively narrower for the marginalized communities. As the data suggests, In 2023-2024, only about 6.8% of STs and 8.6% of SCs aged 24 and above had attained education up to the graduation level and above, while 12.5% from the OBCs and a striking 23% “others category attained the same”. This hierarchy pattern suggests that STs are the most disadvantaged, followed by SCs, and then OBCs with others at the top, suggesting structural barriers based on caste and historical exclusion.

Aspirations and Sustainable Quality Growth

With a large segment of population stuck in informal or low skilled work, their purchasing power remains soft, weakening aggregate demand. India doesn’t value GDP using an income based approach, because of the same informality. Therefore the failure to ensure equitable access to higher education does not simply reflect social injustice, it also directly weakens India’s growth aspirations, inclusiveness and sustainability. 

Inequality in classrooms today becomes inequality in income tomorrow and eventually a drag on the nation’s economic growth. Instead of rejoicing over the quarter to quarter GDP growth comparing to last year, India must sincerely look into real problems that need to be solved and use its demographic dividend to create better results for all. A sociological and political lens is important to devise policies and strategies for next decade’s growth.

Copy and paste the text from AMT that you want to share

Share:
Wars Against America 20260903a

The Wars Against America

Kicking the Can Down the Road is a Public Policy Alternative

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 2nd of September via The Angry Demagogue.

We recently met a young Russian citizen and when asked when the war with Ukraine will end, the response was “Ukraine is just a place, the war is against America”. This Russian citizen was from a city in Siberia, a “regular” Russian with no official contacts that we know of but who, it seems is a proud Russian who “understands” that her leader, Vladimir Putin, is at war with America, who wants to harm and destroy Russia and Russian religion and culture. This war of the West, now the United States, against Russia goes back centuries in the Russian mind.

The Wars Against America: Kicking the Can Down the Road is a Public Policy Alternative

For nearly five decades the Islamic Republic of Iran has planned and prepared to fight the Great Satan, the United States, with the Little Satan, Israel, just a place, a small one bomb country to destroy en-route to the greater, the greatest enemy. This is not speculation but is written into the DNA of the Islamic Republic of Iran in all their announcements and policies over the last, nearly, 50 years.

Way back in my college years in the late 1970’s in one of my first political science courses we learned of China’s desire for “hegemony” in their neighborhood. It was the first time I heard the word hegemony and have always associated it with the Chinese Communist Party and their desire to control the land masses and sea lanes that are near it – what we now call the Indo-Pacific. China to this day not only claims Taiwan as part of its rightful territory but of course Tibet, border areas with India and the entirety of the South China Sea including major U.S allies like Philippines. The CCP has also never given up its desire for revenge against Japanese atrocities of WWII and control of the Korean peninsula – or eastern Russia, for that matter.

And yet, irrespective of all the evidence gathered over the centuries and especially over the last decades since the cold war ended, there are still those in the American establishment, left and right, who feel that the United States can avoid what are naively called “foreign entanglements”. However, if America does not go “there”, the world will come to its shores. Even the Monroe Doctrine at its height did not keep non-Western hemisphere militaries away from the United States.

With the advent of drone warfare, hypersonic missiles, hacking of infrastructure and the battle over AI, there is no avoiding American involvement in global affairs unless it wants to be a nation subservient to China, Russia and Iran – and even then, subservient states rarely live in peace. Another lesson we learned in Political Science 101 was that “power abhors a vacuum”. An American retrenchment will not mean a world at peace. Much as Israel learned it cannot just “separate” from the Gazans, America will learn it can’t just ignore the world around it.

American governments have decided on a “kick the can down the road” organizing principle for nearly all domestic and foreign policy. There seems to be an assumption amongst American politicians and policy makers that American ingenuity can always solve the problem, no matter how late it gets. Social Security is in trouble, the deficit has reached a point where just the interest is $1 trillion, North Korea has multiple nuclear weapons, Iran is as close as it could get, Russia is waging (indirect) war in western Europe and the United States (see: Russian hacking), China is waging a propaganda campaign against American AI that AI executives seem overeager to support by their sci-fi fear mongering and there is no sense of urgency amongst American politicians.

The Vice President wonders aloud about the “harm” to America that the US Dollar as the reserve currency recieves, not thinking beyond the simplistic price of exports. The lower cost of energy and minerals due to their being priced in Dollars does not seem to be a net gain for the US in his eyes. The Democratic Socialists of America (DSA) of course wants to bankrupt America and the Democratic party does not have the will to oppose them. The Michigan AG wants Jews to sacrifice themselves because otherwise the planet will be uninhabitable and the State of California can’t seem to build houses anymore.

The Vance-Kushner-Qatar cabal control American policy in the Persian Gulf up to the point where President Trump gets too annoyed at Iranian duplicity and he sicks American airpower on them. Then it returns as the deals that this group want to do with Qatar (and Turkey) are too much for them to resist as they lead American deeper into subservient status. They don’t seem to realize that the Qatari-Turkish attempt to break the American-Israeli relationship is being done to weaken the American presence in the Middle East by making it dependent upon Qatar. 

Syria’s Islamist leader is still building his Islamist army while Turkey presents him to the world as the moderate who just wants to build a nice country. What is happening though, is that Qatar and Turkey are having America sponsor the Moslem Brotherhood. It is not the American war against Iran that has caused strategic overreach but the potential deals that have left the world’s greatest free power at the behest of a dessert kingdom with no people but lots of ready cash. Deals for pipelines and railways through the Middle Eastern desert are apparently more important for American success than the technology coming out of Israel.

America cannot avoid the world since the world will not avoid America. America is the main target of all revisionist States, whether it likes it or not.

Everyone is waiting until after the mid-terms for something to happen, but then the 2028 presidential campaign starts. The waiting needs to stop regarding Iran, Russia, China, defense manufacturing and the fiscal situation. As Yogi Berra brilliantly stated – “it gets late early out there”.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

Follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

Share:
WTI CrudeOila 20260902

Bad Timing for President Trump May Equal Good Trading Opportunities

You Don't Have to be a Buyer in the Current Marketplace in Order to Profit

There are moments when the markets are calm and then there are these times. It is beginning to look like increasingly bad timing for President Trump and his administration’s hope to keep WTI Crude Oil prices in check and silence the chatter about inflation. 

Instead of a de-escalation based on tranquil conditions in the Middle East, investors were smacked in the face again last night. However, while this may be a bad time to be an investor unless they are looking for value plays, traders may actually have more opportunities in the current market circumstances as long as they manage their risks appropriately.

WTI Crude Oil jumped higher last night and while the commodity has outdone itself since late February regarding price velocity, last night’s performance likely felt volatile even for experienced large players who have solid intel on the ground regarding Middle East shipping and supplies. The energy sector has been more akin to the soft commodities regarding reversals the past handful of months, Coffee, Cocoa and Crude Oil have offered colorful price ranges. But that is not how WTI Crude Oil is supposed to work.

WTI Crude Oil 1 Year Chart as of 2 September 2026

Inflation concerns will not go away quietly as long as WTI Crude Oil remains highly valued. Fed Chairman Kevin Warsh may in fact be putting on a show for the public – that he is his own man and can express his concerns regarding inflation no matter what President Trump thinks – when in fact he may simply be laying a framework to work in tandem with Treasury Secretary Scott Bessent and lower interest rates in order to create less pressure on Treasury yields. However, this planned (or conspiratorial) thinking may be hard to actually produce in reality on the 16th of September when the Fed’s FOMC has to show its cards once again. As long as WTI Crude Oil remains above $90.00, “Houston we have a problem,” murmurs may be heard loud and clear.

If Treasury yields remain tilted upwards because investors are refusing to buy them at cheaper rates, it will start to infect the Nasdaq 100, S&P 500 and the Dow 30 more and create cautionary skirmishes which may produce deeper downsides in stock markets.

Iran wouldn’t want to cause President Trump problems, correct? Why would Iran want higher Crude Oil prices to ensnarl President Trump into a morass of political battles in the U.S and make life difficult for the Republicans during the mid-term elections? Does the IRGC have folks who understand the dynamics of U.S politics? Yes they do and it is a 100% certainty they would like to be a pain in President’s Trump’s aspirations.

We are left to deal with the ever-changing events that seem to be quite good at repeating themselves. Financial institutions are not only nervous about their mid-term outlooks, they are wary about the near-term too. Forex, commodities, bond yields, Wall Street and other global stock markets will struggle to make solid gains until clarity develops.

What will clarity look like? It will be optimistic banter in which rhetoric from different mouths and geographies is actually believed by the adoring crowds. Results do not have to be good, but outcomes need to be able to be forecasted and planned, allowing investors to seek their cash preservation and fortunes in a variety of assets (and show their overseers that they used adequate risk management in case things go wrong). 

Gold has done well recently, although it seems to have hit some resistance lately. However, if inflation tranquility is not achieved and if President Trump’s circumstances grow more dire, the precious metal will continue to offer speculative plays upwards. 

Investors are restless. Making 6 to 8% profits a year looks rather boring after plenty of solid years of upwards traction. Folks aren’t used to powerful financial storms and they forget about lingering troubled periods in which simple profits can prove comforting as broad markets struggle. 

Day trading is dangerous. However, those with solid risk taking tactics and those who aren’t married to the notion that markets only go up, but are willing to bet that markets (assets of many classes) can go lower too – now have an opportunity to test their technical perspectives and understanding of behavioral sentiment. 

Realistic targets using take profits and making sure stop loss protection still allows for a trade to move until goals are met is important when volatility is ripping price realms to shreds. Forex instability appears to be increasing as USD centric attitudes remain convoluted. Does Fed Chair Kevin Warsh have enough power to fight against an interest rate hike on the 16th of September, will the price of WTI Crude Oil cooperate, will President Trump’s wishful thinking about Iran come true? Results may not match what is wanted by the guardians of the marketplace. Contrarians may see the current market and global political situation as a time to seek value and help inflate markets, but they might be spitting into the wind. 

Maybe the AI concerns about infrastructure costs and corporate cash needs are baseless. Perhaps the deficit being created by the U.S and many other nations is simply idle chatter by risk analysts who are too nervous. Maybe there is a secret pill for all of us to become optimistic about all things.

It is a good time for traders to remain realistic and target exaggerated price movements in assets that offer opportunities in distressed offerings. You do not have to buy the marketplace to profit ladies and gentlemen.

Copy and paste the text from AMT that you want to share

Share:
Contraries 20260831

Why Some Traders Go Bust: What Medieval Logic Knew That Your Backtest Doesn’t

Aristotle's Square of Opposition and Why Traders Still Walk Off Cliffs

Somewhere in a 9th century Carolingian monastery a logician diagrammed four sentences into a square to help him distinguish whether a statement was universally true, or only partially so. A thousand years later and that square can explain why a trader with a positive-expectancy strategy and a spotless backtest can still walk off a cliff. The tool is Aristotle’s Square of Opposition. The victim is anyone who has confused what happens on average across many trades with what happens to one trader using the same strategy over time.

The Square

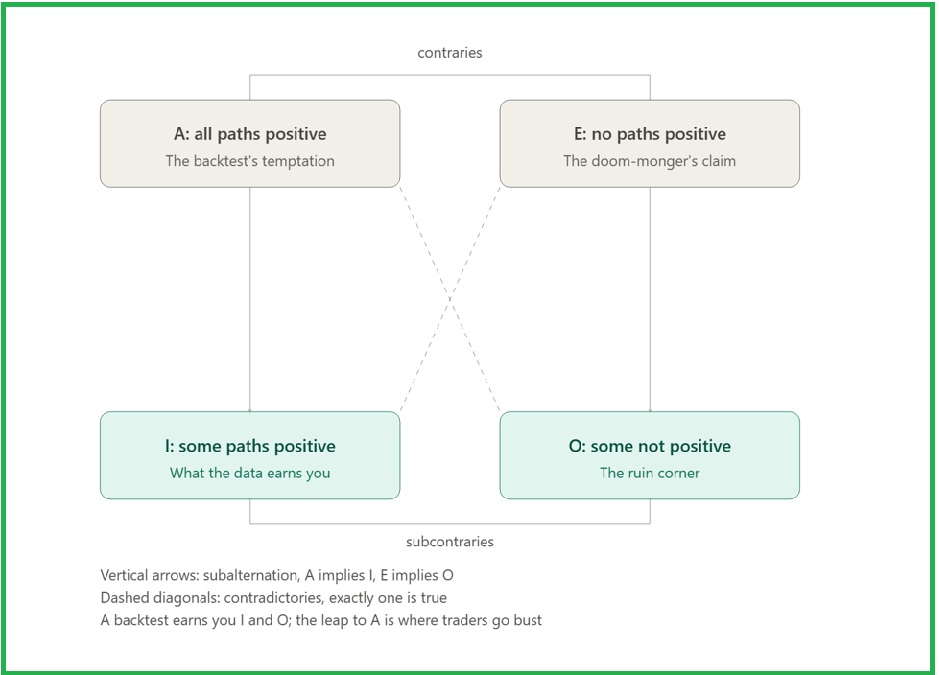
Aristotle’s Square of Opposition sorts any claim about “all,” “none,” “some,” and “some not” into four corners: A (universal affirmative — “all X are Y”), E (universal negative — “no X are Y”), I (particular affirmative — “some X are Y”), and O (particular negative — “some X are not Y”). The corners have relationships: A and E can’t both be true, but can both be false. I and O can’t both be false, but can both be true. And crucially, A and O are direct contradictories — exactly one of them holds. Medieval scholars used this to catch people smuggling a universal claim into an argument that had only earned them a particular one. It turns out finance does this constantly.

Why Some Traders Go Bust: What Medieval Logic Knew That Your Backtest Doesn’t 

The Deception: Ensemble vs. Time

Imagine a bet: 50% chance of +50%, 50% chance of -40%. Average that across a thousand parallel traders taking the bet once, and the ensemble average is comfortably positive. Looks like a great trade. But average it across one trader taking that bet a thousand times in a row, and the time average growth rate is negative. Same bet, opposite verdict, because compounding is multiplicative, not additive. This is the ergodicity problem: the ensemble average and the time average only coincide if the process is ergodic, and most wealth processes — especially leveraged, compounding ones — are not.

Nassim Taleb gave us the gut feeling for this in Fooled by Randomness. As an Options trader he was intimately familiar with the notion of skewed distributions and how these can impact wealth in terminal ways. In FX (my world) the carry strategy buying high yielding currencies and selling them against low yielding currencies has an asymmetric payoff, similar to picking up pennies on the tracks in front of an oncoming train. The formal model of ergodicity as applied to economics was developed later by physicist Ole Peters in a great paper “The Ergodicity Problem in Economics”( 2019) building explicitly on the Kelly criterion. He demonstrates why time averages diverge from ensemble averages in multiplicative systems, and showed the divergence isn’t a glitch,  it is structural.

Putting a Strategy on the Square

It is tempting when reviewing  a backtest with a fat positive Sharpe ratio, to leap straight to A: “this strategy is profitable” — full stop, universal, works everywhere, always. Let’s gear it up. But probably the more honest claim your data has actually earned is closer to I: “some paths through this strategy are profitable” — a particular, not a universal. The Square’s discipline is to check category before you trust quantity. Before asking “how profitable?” ask “profitable for whom, under what — the ensemble of possible paths, or the one path you’ll actually live through?” A strategy can be I-true (some simulated paths win handsomely) while quietly also being O-true (some paths,  including, possibly, yours; go to zero). I and O aren’t contradictions; they’re subcontraries, and they can both hold simultaneously. That’s precisely the shape of a fat-tailed strategy: mostly fine, occasionally ruinous.

Why Expectancy Lies by Omission

Expectancy (“average win × win rate minus average loss × loss rate”) isn’t itself a universal claim. The mistake comes when we quietly promote an ensemble average into one by letting  an I-shaped number pretend to answer an A-shaped question. Positive expectancy tells you the average across scenarios is favourable; it says nothing about whether your single compounding sequence survives long enough to enjoy it. One of the questions that expectancy cannot answer, but survival requires us to ask, is the probability of ruin. Given position sizing and volatility, what fraction of paths hit zero before they hit target? Monte Carlo simulation offers one way to estimate this but it should be used with extreme caution. Feed a Monte Carlo engine the wrong return distribution such as  thin tails in place of  real world fat ones and it will confidently hand you a beautifully wrong answer. A mis-specified Monte Carlo is just a very fast way to fool yourself with more decimal places.

The Habit Worth Keeping

The practical takeaway isn’t a formula, it’s a reflex. Before trusting any metric — a Sharpe ratio, an expectancy figure, a backtested drawdown — ask the medieval logician’s question: is this claim universal, or is it merely particular? Most of what a backtest can honestly give you lives at I and O, not A. The traders who go bust aren’t usually wrong about the arithmetic. They’re wrong about the quantifier — mistaking “true for the ensemble” for “true for me, through time.” Aristotle can’t size your position for you. But he can stop you asking the wrong question about it.

The deeper point of the monastery image we opened with echoes a point Jeremy Naydler makes “In the Shadow of the Machine – a pre history of the computer”.  The instruments we reason with don’t just extend the mind, they reshape it: what counts as thinkable changes with what’s sitting on the desk. The Square of Opposition is one of the earliest such instruments, a piece of technology built to discipline inference. The backtest, the Sharpe ratio, the Monte Carlo engine are its modern descendants — and like any tool, they don’t just answer questions, they quietly decide which questions get asked at all. The trader who never learns to ask “universal or particular?” isn’t missing a fact. He’s missing a habit of mind his tools may not have taught him to have. A framework is most powerful not when it gives us the wrong answer, but when it prevents us from noticing that we have asked the wrong question.

Copy and paste the text from AMT that you want to share

Share:
Indian Rupee 20260826

India Insider: Rupee’s Prolonged Weakness Remains Unresolved

Better Streamlined Government Policy Needed for the Rupee

In July of this year Reserve Bank of India Governor Sanjay Malhotra talked to Business Line magazine and argued that recent Rupee depreciation does not reflect any weakness in the country’s economic fundamentals. According to him, pressure on the currency has largely stemmed from geopolitical tensions, USD strength  and broader volatility across emerging markets.

However, the USD which strengthened during the outset of the US-Iran war has been losing value in large chunks in the broad Forex market the past month. The U.S Federal Reserve remains neutral regarding its interest rate guidance and U.S labor market data has emerged weaker. On top of that, the U.S Treasury’s decision to intervene in U.S long-term bonds via buybacks in order to cool yields has hastened another USD path lower, while igniting buying in many other currencies and gold.

USD/INR Five Year Chart as of 26 August 2026

Despite the Foreign Currency Non-Resident (Bank) deposits coming from overseas investors increasing, which are leveraged products structured by banks and helped to attract more than $50 Billion USD since June, the Rupee’s reaction to this set of recent inflows has been muted. The Indian Rupee is traversing near 95.55 levels as of this writing, notably as other Asian currencies like Korean Won and Singapore Dollar are trading at stronger levels.

India’s Forex reserves climbed to $716.9 billion boosted by these inflows, along with USD related external borrowings by corporate and commercial banks. Nevertheless, the fundamental problems for the Rupee’s prolonged weakness remains unresolved.

Reasons for Rupee’s Weakness Structurally

The Indian Rupee has depreciated around 28% against USD since 2022. Irrespective of this, the merchandise tradable exports have been stagnant, rising a mere 5.7% – from $417 billion to $441.8 billion USD. While on the other hand, merchandise imports have risen 26% from $610 billion to $774.80 billion USD in the period between 2021-2025.

However, India’s balance of payments is not at immediate risk, because even as higher importing needs (especially with Crude Oil and LNG) and lower tradable exports, the total merchandise deficit of around $350 billion USD as of 2025 is being offset by healthy IT exports and foreign remittances.

The fundamental question is why hasn’t the Indian Rupee depreciation expanded merchandise exports in the last few years? As Carlos Dias Alejandro depicts in his seminal work Exchange-rates Devaluations in a Semi-industrialized Country: The Experience of Argentina 1955-1961, throughout Argentina’s history rural producers who supplied most of the exported commodities traditionally advocated a policy of devaluation.

Argentine exporters expected Peso prices for their outputs to rise faster than the Peso prices for their imports, including the wages that they paid for their employees in current prices. In other words, exporters stand to gain from a currency devaluation because it can make their products more competitive in global markets and encourage resources to move towards export production.

Argentina’s experience after Juan Peron who was overthrown in 1955 provides an important context to this argument. The economic policies pursued during the Peron years had already left Argentina with serious inflation , weak agricultural incentives, low investment and balance of payments pressures. The devaluation and stabilization policies that followed were therefore part of a broader attempt to correct the distortions that had built up during the previous period.

Interestingly, the Rupee depreciation has so far not shifted resources from producing goods for foreign products as it is apparently clear via merchandise trade data. The IT sector has been one of the few sectors that has been able to use this shift positively.

It is also important to understand that devaluation does not produce only positive outcomes. A devaluation that increases the overall level of prices can cause a redistribution of income among different social groups, in much the same way as inflation does in a closed economy. Unwieldy redistribution becomes inevitable when the prices of outputs and inputs do not change proportionally.

For instance, wages are central to this process. If prices of food, fuel and other essential goods rise quickly after a devaluation, but nominal wages adjust slowly, workers experience a decline in real wages and purchasing power. Their incomes may remain unchanged in Rupee terms, yet they can afford fewer goods and services. This effectively transfers income from wage earners to firms and producers whose prices or profits adjust more rapidly.

The impact can also differ across workers. Employees in organized sectors may negotiate higher wages or receive inflation linked adjustments, while informal workers, agricultural laborers and those dependent on fixed incomes often have less bargaining power and face a sharper fall in real earnings. At the same time, exporters may benefit if the prices of their products rise faster than their wage and other input costs.

However, if workers eventually demand compensation for the higher cost of living, wage increases can raise production costs and reduce part of the initial competitiveness gained through devaluation. Thus the effect of devaluation depends not only on the exchange rate, bit also on how quickly wages, prices and productivity respond.

In that sense, Argentina’s experience in the 1950s offers a warning for semi industrialized countries like India. A devaluation of the Rupee can make some exports competitive, but it cannot create more productive capacity on its own. Without addressing deeper structural problems, a weaker currency can instead push up prices and reduce households real purchasing power.

Rupee Effects Absorbed and Felt by Those Who Earn Low Wages

Prices of goods and services have increased in the last few years due to the depreciation of the Rupee, especially for imported goods. Since India not only imports oil and gas for consumption, but also imports machinery and intermediate goods for production it has forced households to spend a higher share of their income on the consumption of needed goods.

When households do not earn they need to borrow or hope that their wages increase. In India real wages don’t always go up with inflation. This is due to India having a higher supply of available labor which makes negotiating for higher wages difficult for workers. If employers can find another worker relatively easily as a replacement, the employed worker has limited power.

The ILO (International Labor Organization) notes that India remains characterized by extensive informality and low pay employment, it also estimates that 62 million workers earn below the minimum wage. India’s workers are not necessarily competing in the global market. Manufacturing as a percent of GDP has stayed around 15% over a decade. And irrespective of the fact that India is a major agricultural producer and exporting nation and over 46% of its labor force engages in the sector, total Agri-Exports stayed within a band of $48-$53 billion for the last few years.

The government says that India is growing because services as a percent of GDP is 55%, but the nation employs around one-third of the labor force in the informal economy. While IT employees earn higher wages comparatively because their wages are connected with global demand and have an advantage because they are export services, those who work in construction, domestic help, shops, agriculture and the service sector are earning substantially less. The wages of these people won’t go up until changes are made. 

The vast numbers and informality of employment within a significant amount of India’s labor force prevents low wage costs from translating into solid competitiveness, particularly as inflation is seen and depreciation of the INR continues. Economies like China, Vietnam and Korea have created industrial strength by transferring household savings through lower costs for goods and subsidizing businesses.

India’s decade long reluctance to invest in necessary infrastructure, not preventing or fixing regulatory problems, a lack of commitment to invest in skill based education, and not creating conditions for businesses to compete with overseas markets have created conditions that result in low consumption and low wages. The devaluation of the INR hits households who are acting as shock absorbers in the absence of streamlined government policy.

Copy and paste the text from AMT that you want to share

Share:
30Y Treausry Yields 20260826

How Warsh Can Solve the US Debt Crisis With Just a Few Words at Jackson Hole!

A Roadmap for Fed Chairman Kevin Warsh to Rescue U.S Debt

Many think the market decides interest rates.

Wrong!

The Fed – and only the Fed – has full control over interest rates, all over the curve!

We just need to have the right person on board.

During the European crisis in 2011, speculators all around the world were betting that the Eurozone would explode and that the EUR would collapse under the weight of government debt that had started with Greece and spread to other countries that were shamelessly labelled “PIGS,” adding insult to the speculative attack.

Trichet, at that time chair of the ECB, seemed totally clueless, afraid to take any “unconventional” step, even at the risk of seeing the entire European financial system go bust.

The crisis seemed unstoppable… until Mario Draghi stepped in, replacing Trichet.

With just one magical statement (“the ECB will do whatever it takes to save the Euro. And believe me, it will be enough”) Draghi implied that he was ready to buy government bonds from European countries, even though such action was considered at the time to be “against the ECB’s statutes” and outside its mandate.

By going against the prevailing market narrative, and knowing very well the economic strength of the Eurozone, Draghi forced the market to follow him.

The speculation against the Eurozone stopped almost instantly, and European government bond prices recovered without the ECB even being forced to intervene!

U.S 30-Year Treasury Yields Chart From 1988 until 26 August 2026

Today, the U.S is in exactly the same position!

A massive speculative attack is being waged against U.S debt (probably led in part by the crypto industry in an attempt to justify the “value” of its virtual tokens), with “inflation” suddenly becoming the ultimate beast.

Like Trichet at the time, the weak Powell got driven into the trap of raising rates abruptly on his own government, forcing it to pay more than $1 trillion in yearly interest, a massive and unnecessary injection of liquidity that is itself… inflationary!

In today’s world, driven by massive debt, raising interest rates on governments is INFLATIONARY!

Now that Powell is almost gone, all hopes lie on Warsh’s shoulders.

He can save the U.S from the current debt crisis with just a few words, exactly as Draghi did for Europe.

Warsh completely missed his first intervention a month ago. Instead of showing the market who’s boss, he showed total febrility.

Fearing being labelled a “Trump puppet,” he insisted on the 2% inflation target – an absurd threshold that nobody really knows where it came from – and claimed that “the economy is robust”… while we all know it is not!

Then he totally capitulated to the market by saying that he would “listen to the market” to determine where rates should go. The worst thing any Governor could ever say!

That’s how long-term yields exploded to levels not seen since 2007, and forcing Bessent to intervene to limit the damage.

We are now just one day away from the Jackson Hole Symposium.

Warsh can now either save the U.S or send it into Armageddon!

Every word he says could change the entire picture.

He simply has to focus on the right narrative:

  • Current inflation is geopolitical and driven by supply shocks. Raising interest rates has zero impact on such inflation.
  • The 2% inflation target is NOT an absolute figure. A 3% inflation rate should be acceptable when the economy is at risk.
  • Signs of recession are looming, with the labor market under pressure, rising bankruptcies, and record rates of defaults on credit cards and car loans.
  • Forcing the government to inject more than $1 trillion through interest payments is itself inflationary. Raising interest rates to fight inflation is counterproductive at such a high level of government debt.

If Warsh is capable of highlighting these arguments, yields will drop instantly without any intervention from Bessent.

Then the Fed can start decreasing interest rates gradually, with the market accepting whatever rate it sets.

What if Warsh deliberately gave a disastrous speech a month ago, taking a tough position against what Trump appointed him to do and allowing the market to drive rates to extreme levels… only to radically change his position following the recommendations of the task force he appointed?

This way, he would have absolved himself from being labelled Trump’s puppet while executing exactly the plan of reducing interest rates.

We can therefore suspect that he will take the opportunity at Jackson Hole to present the first findings of this task force, which could include, among other things:

  • A questioning of the 2% inflation threshold, especially when the economy is at risk of entering a deep recession.
  • Stressing that inflation comes mainly from geopolitical issues and supply shock. Fighting such inflation with high interest rates is totally inefficient.
  • A highlight of the absurdity of raising interest rates on the U.S government and forcing it to inject $1 trillion in interest payments – an unnecessary injection of liquidity that is itself inflationary.
  • The necessity of coordinating with the Treasury Department to fight inflation where it hurts the most, through subsidies, tax relief, and other targeted measures, while primarily fighting “greedflation” through higher profit taxes on specific industries.
  • A warning about the increasing risk of recession, with record numbers of corporate bankruptcies, credit-card defaults, and a deteriorating job market.

Warsh has a unique chance to prove that he is the right person for the job by rescuing the U.S from the massive speculation against its debt, exactly like “Super Mario” did when he saved Europe from collapse in 2012.

Copy and paste the text from AMT that you want to share

Share: