WTI Crude Oil 20261104

AMT Commodities Corner: Can Blue Wave Change Momentum of Black Gold?

President Trump's Reaction to Election Defeat Matters for WTI Crude Oil

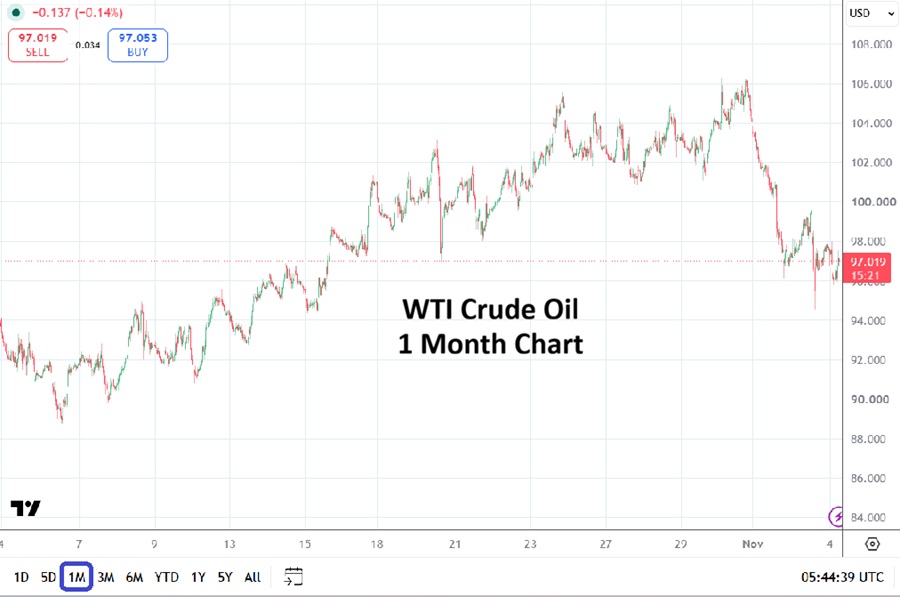
A blue Democratic Party wave has hit the U.S in the past day and early this morning as votes are still being counted and clearly show a definitive victory for the Democrats. The manner in which President Trump reacts to the election defeat will influence the price of WTI Crude Oil greatly, because his handling of the Iranian situation will now be confronted by new political obstacles. The current price of WTI Crude Oil cash is near $97.00 as of this writing.

In the past few days WTI Crude has come off of fearful highs which challenged values above $106.00 last Friday on the 30th of October. In early trading this morning the price of WTI Crude Oil cash has lowered slightly, but has begun to show slight signs of consolidation again. Some speculators may be eyeing a renewed testing ground around the $96.00 ratio with some lower momentum being seen. However, before speculators rush into a wave of additional selling they should note that WTI Crude Oil remains within a cautiously priced realm as large players clearly remain worried about potential impacts if the Iranian situation worsens.

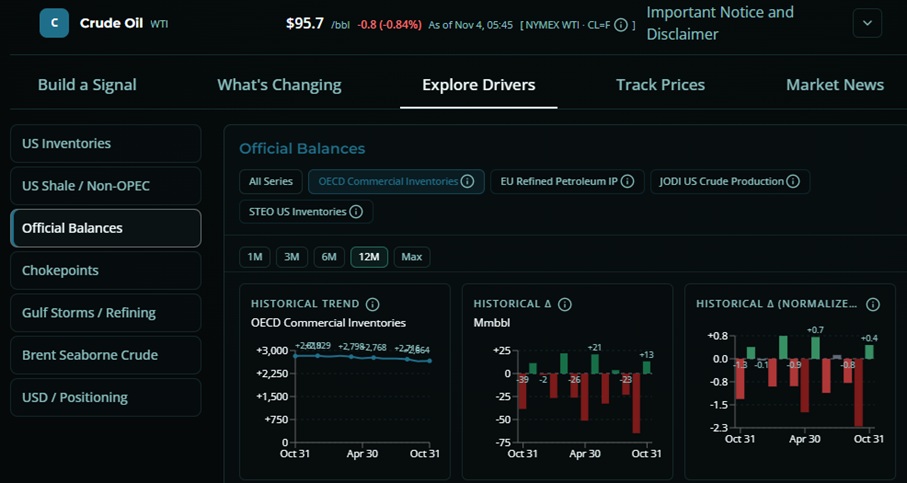
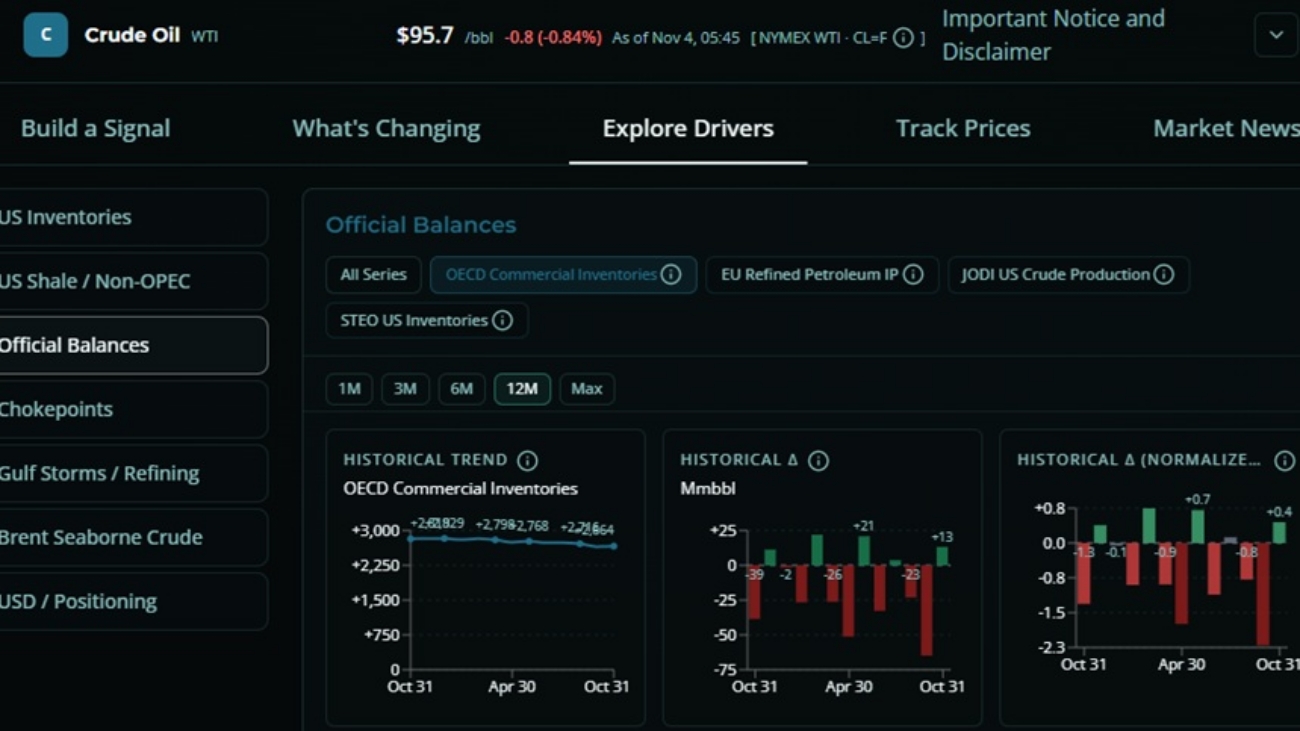
WTI Crude Oil Price and OECD Commercial Inventories via Viridian Commodity Intelligence on the 4th November 2026

And here is where things will get tricky in the near-term for retail traders as they try to weigh their perceptions and anticipate the reaction of the bigger forces in the energy market that will move values. The outcome of the U.S mid-term elections last night may cause some large players in WTI Crude Oil to feel more optimistic about a possibly quicker conclusion to the Iranian war which has been staunchly in the headlines since late February. 

However, key factors remain unanswered regarding consequences, and short-term notions must be compared to mid-term timetables. What will President Trump’s immediate reaction rhetorically be regarding ‘his’ election defeat and what he now views as viable as he presses forth against Iran? How will energy demand and inventories be influenced in the coming weeks? For instance the OECD (Organization for Economic Co-operation and Development) commercial inventories reporting via Viridian Commodities Intelligence shows supply remains low among member nations. Meaning that a perceived escalation to come in Iran could create more headwinds and sustain negative outlooks. Suggesting fears which still exist about the Iranian situation may be priced into WTI Crude Oil because supply for the OECD nations remains vulnerable.  

WTI Crude Oil One Month Chart as of 4th November 2026

Prices today and tomorrow should be watched carefully. A psychological test for large players in WTI Crude Oil will be factored by President Trump’s reactions to the strong Republican loss of power in the U.S House of Representatives and Senate. President Trump is still the Commander in Chief of the U.S military and his loss of Congressional backing may not stop him from escalating military conflict with Iran near-term. 

Will President Trump sound more pragmatic and put his ego to the side and offer the Democrats an olive branch? Or will the President use the time between now and the 3rd of January – when the new Congress will be sworn in constitutionally to take advantage of his lame-duck window which will start to be felt in an increasingly harsh manner. Note that the 3rd of January 2027 falls on a Sunday, so the official swearing in date for Congress may be changed by a few days depending on what agreements are made.

President Trump is on the clock and in essence the Iranian war is too. The price of WTI Crude Oil which has been a swift speculative playground since February of this year is set for more dynamic price action. Short and near-term traders who want to ride the momentum of larger players in WTI Crude Oil should expect plenty of velocity the remainder of this week. 

Copy and paste the text from AMT that you want to share

Share:
Brazilian Real 20261023

USD/BRL: Anticipating Brazilian Election Results and a Liberal Party Victory

Flavio Bolsonaro Appears Set to Become the Next President of Brazil

Brazil will conduct the second round of its elections this coming Sunday on the 25th of October. Flavio Bolsonaro is predicted to win the election handily. No second place presidential candidate has ever comeback after the initial vote and beaten the first place finisher in the 2nd round of the direct elections which was implemented in 1989. 

Financial institutions appear to favor a Liberal Party victory over Lula da Silva’s Workers’ Party. If Flavio Bolsonaro wins the vote as expected on Sunday he will have strong coalition powers in the National Congress as a whole, including the upper house Federal Senate with conservative members that is expected to include 45 to 50 approval votes depending on the issue out of 81 collective seats. The USD/BRL closed yesterday’s trading near the 5.0525 vicinity.

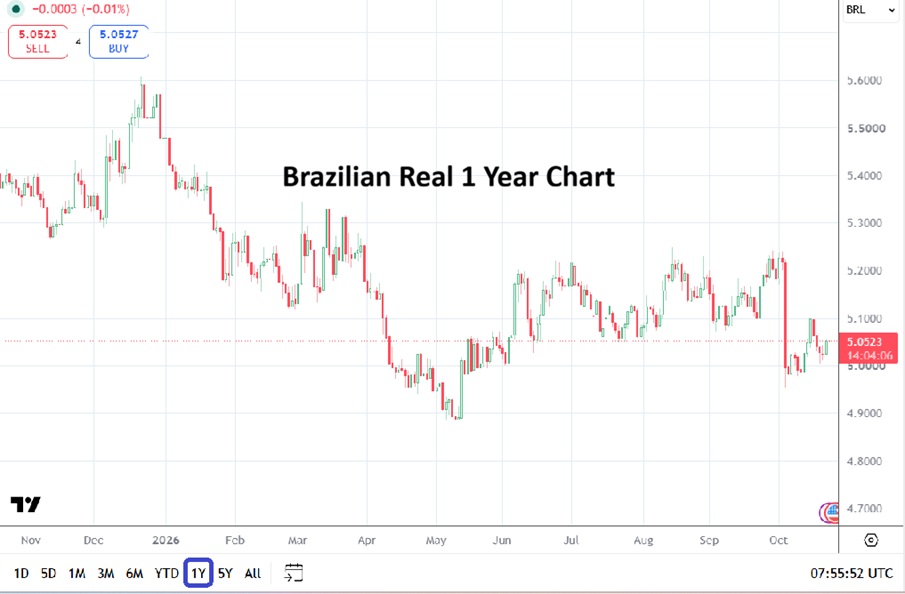
USD/BRL One Year Chart as of 23 October 2026

Brazilian Real’s Performance Has Been Solid Since December 2024

The USD/BRL is traversing lower ratios that were challenged momentarily in early August, late July and saw sustained lower action in May of this year with depths touching the 4.9000 area briefly. The Central Bank of Brazil has leadership via Lula da Silva’s choice of Gabriel Galipolo as the Governor who will serve until the 31st of December 2028.

Financial institutions have shown faith in the Brazilian Central Bank as it maintained interest rates and did not succumb to the wishes of many from the Workers Party who had lobbied for a lowering of borrowing costs as inflation ran high. The USD/BRL has performed well since touching highs around 6.2500 in December of 2024. While the USD/BRL has been correlating with the broad Forex market to a degree, reaching the 5.2500 realm on the 1st of October, the Brazilian Real has shown more fortitude than the EUR, GBP and has done better that the South African Rand against the USD the past handful of weeks.

Geo-Political Implications of a Flavio Bolsonaro Victory

Optimism in Brazilian financial institutions regarding a government victory by Flavio Bolsonaro who is seen as pro-business (and certainly is not a socialist) is viewed as a positive by global investors too. The geo-political relationship between Brazil and other nations will be captivating if Bolsonaro wins Sunday’s presidential race. Brazil maintains an enormous trading relationship with China and its membership in BRICS is considered very important. These political relationships should be watched closely.

Brazil’s relationship with South Africa may also be tested quickly as Flavio Bolsonaro imposes a more conservative approach regarding his worldview. Bolsonaro is certainly an ally of President Trump. Brazil’s relationship with the majority of conservative leadership in South America will be dynamic and worth giving attention as it improves. The USD/BRL via behavioral sentiment could find itself testing additional lower values in the coming months. A free enterprise surge from Brazil will create a more vibrant economic landscape in South America, provided corruption is fought and transparency is delivered.

Cautious Global Markets as Optimism Engulfs Brazil

Cautious global investment certainly continues to create problems in equity markets. However, the Ibovespa Index of Brazil has performed exceptionally well the past year, even though it suffered a slight downturn yesterday it remains within sight of all-time highs. The results on the Ibovespa and the USD/BRL considering the predicted election outcome this Sunday will be important for retail traders to monitor.

Speculators need to keep in mind a Liberal Party victory has been factored into the value of both trading assets already, meaning some profit taking could transpire early until additional positive waves of enthusiasm engulf the marketplace…….and then eventually sees euphoria erode back into realistic outlooks and correlations with global mechanisms again.

Paying For Celebrations Via Profit Taking

Traders of the USD/BRL may want to pursue the currency pair in a speculative manner today and early next week, but they need to remain tactical and not allow overly ambitious targets guide their wishful thinking. Bias needs to be eliminated and USD/BRL traders should not indulge in leveraged positions which could get out of hand quickly if sudden sentiment shifts strike via larger players and financial institutions, particularly if they cash out winning positions (this to pay for some victory celebrations should the mood strike). The USD/BRL appears to be in a solid position to continue move lower via positive outlooks for business enterprise in Brazil, but traders should remain realistic and not step out ahead of the parade unless they have deep pockets and can demonstrate patience.

A Gap Higher Amidst Over-Exuberant Retail Trader Ambitions

Early Tuesday’s price action in the USD/BRL did see the 5.0000 realm come into sight, but an upwards wave developed and Thursday’s opening did produce a gap higher which tested values near 5.0575 momentarily. Yes, conditions appear ripe for exuberance to help the Brazilian Real become stronger against the USD, but retail traders need to practice risk management at all times.

Copy and paste the text from AMT that you want to share

Share:
SPCX 20261020

The Markets: Not to be Funny but Many are Confused

Mid-Term Ambivalence Reigns as Major Risk Events Unfold and Await for All Traders

In an effort to lighten the mood of the room let me assure you that most financial analysts feel they are in the dark. Talks with a wide range of investors and large speculators nowadays (at least within my circles) leads to the conclusion that a lack of clarity is becoming a known landscape. 

The Federal Reserve will hold conduct its FOMC meetings and rate decision next week. The price of WTI Crude Oil is raging near high water marks. SpaceX is traversing its initial IPO values again. There are major elections on the horizon in Brazil, Israel, the U.S and South Africa which will effect world views starting this weekend and into early November. Some parts of Europe are burning. And the Middle East conflict appears to be on pause, but folks are bracing for a resumption of military noise. 

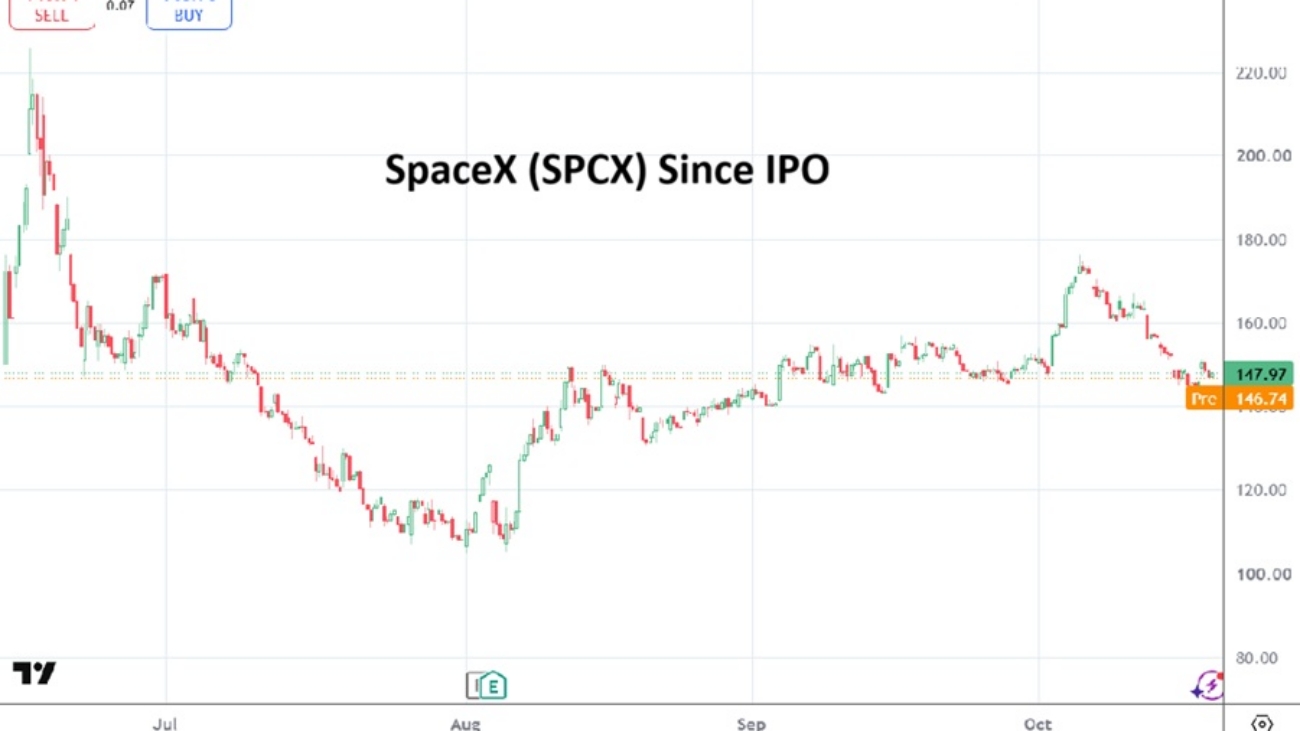
SpaceX (SPCX) Value Since IPO Chart as of 20th October 2026

Add to the above a U.S President who appears able to change his stance in a moment’s notice without showing any outward signs of remorse is also a feature – one that often leaves other leaders perplexed. Except, that the White House seems primed on trying to keep chaos from entering the economic picture by trying to talk the public (voters and the world) into a stated belief that all will be OK, it will be tremendous, magnificent, better than ever before………and Crude Oil will be valued below $65.00 a barrel when everything is figured out, the U.S economy will remain uniquely strong and Wall Street will be a lovefest. The White House is correct to take a positive approach, but others are free to doubt.

And therein lies the problems, when will all be paradise? Clarity over the mid-term is important for investors who crave the basic necessity of being able to have some type of predictive grasp for the coming six months. Where will interest rates be? What will the price of oil be doing? Will the Iranian situation be cleared up? Will Tesla’s flying roadsters crash back to earth or land right side up? (Tesla announces its 3rd quarter results when Wall Street closes tomorrow btw).

USD centric strength continues to fluster Forex positions. U.S Treasury yields have come off their highs but are still elevated. The hidden costs of infrastructure builds for data centers remains an open nasty secret as revenue concerns are discussed. The Nasdaq 100 lurks near record highs, but at the same time creates fear that not enough momentum is being shown upwards – possibly translating into massive losses to come via some technical mindsets. Some are openly predicting a Wall Street crash. We have seen this show before folks, but it is unclear what path is going to develop. The Cassandras’ of the world do get boring as they proclaim a known script.

Yet we stand at a precipice and better know how to scale the cliff. Inflation via Crude Oil prices that are currently gushing past $100.00 are problematic. But should Fed Chair Kevin Warsh raise interest rates next week to try and fight inflation being caused by a geo-political storm that he has no power over? Saudi Arabia, the Houthis, Iran, the UAE, Israel and many others are seemingly waiting for the mid-term elections in the U.S to take place if you pay attention to the media, but is that what really is going on? Doubtful. There are plans being made outside of our known scopes and we are not allowed to look beyond the curtain.

The Federal Reserve should not raise the Federal Funds Rate next week because of oil price fears and even if its inflation remains sticky for the time being. ‘Should not’ being the key words. The USD should return to a slightly weaker stance, but will this happen as financial institutions brace the potential of cumbersome near-term dramas over the next two weeks? Let’s point out that the price of WTI Crude Oil was slightly lower on the 16th of September, during the last FOMC meeting and decision.

No, I am sorry, I do not have a whirlwind of advice for speculators except to say be careful for the moment. As a trader I knew in the past once told me, reading today’s news means you are reacting to something someone knew a few days beforehand – there is a source, a discussion with a journalist, and then the writing and publication of the article roadmap which we must consider when trying to act on news we are reading for the first time. In other words, someone has already traded on the news you are consuming. 

Social media and influencers are terrific, but they tend to be a day late. Current trading dynamics offer a slightly different problem for the moment, because large institutional investors have likely positioned themselves ahead of the news flow that the public is consuming as they try to venture forth via their own predictions. However, because confusion reigns for the moment, there is a good chance the financial institutions are wrong. Meaning speculators should use their own perceptions and experience to judge the potential dangerous currents flowing. Hoping for the best will not be enough, being prepared for challenging circumstances near-term will help.

Copy and paste the text from AMT that you want to share

Share:
SP500 20261002

All Quiet on the Trump Front?

Biased Information Extends to Economic Reporting as Much as It Does To Global Affairs

Nearly one month from now, on the 3rd of November, the U.S mid-term elections will be held. Today the Non-Farm Employment Change date will be published. But will these economic numbers matter? The coverage of the Trump presidency remains problematic no matter what your political beliefs are because it is difficult to know the truth regarding details being reported, particularly as the vote approaches and folks want to influence your decisions.

Depending on which media source you are paying attention to and what the outcome is you are certain to be spoon-fed a large amount of bias. The problem for voters in one month, and for investors today is that a lot of the information and opinions being consumed cannot and should not be trusted. Everyone has bias, to not admit this is not honest. AngryMetaTraders tries to give a solid centrist reasoning of the speculative and investing world based on – truth must win out. However, certainly I and our other writers within AMT have insights that are based on our unique perspectives. 

Reality is important: A case in point is the Fly Dubai terror incident which occurred two days ago. Media outlets are depicting the events in a myriad of ways. Clearly the co-pilot tried to kill the 1st pilot, this so the plane could be be crashed into the ground over the Middle East on its way to Tel Aviv – or possibly be flown into a building. The nosedive of the plane which equated into roughly 5,000 meters in about one minute’s time was only stopped because of the heroic actions by the Indian 1st pilot, and by an Israeli passenger who grabbed the control wheel and leveled off the plane during the confrontation in the cockpit as others also intervened to avert a tragic disaster.

What does this have to do with economics and the markets? Many media sources did not report the events transparently, nor did they provide details on the actual attack. In other words they showed bias.

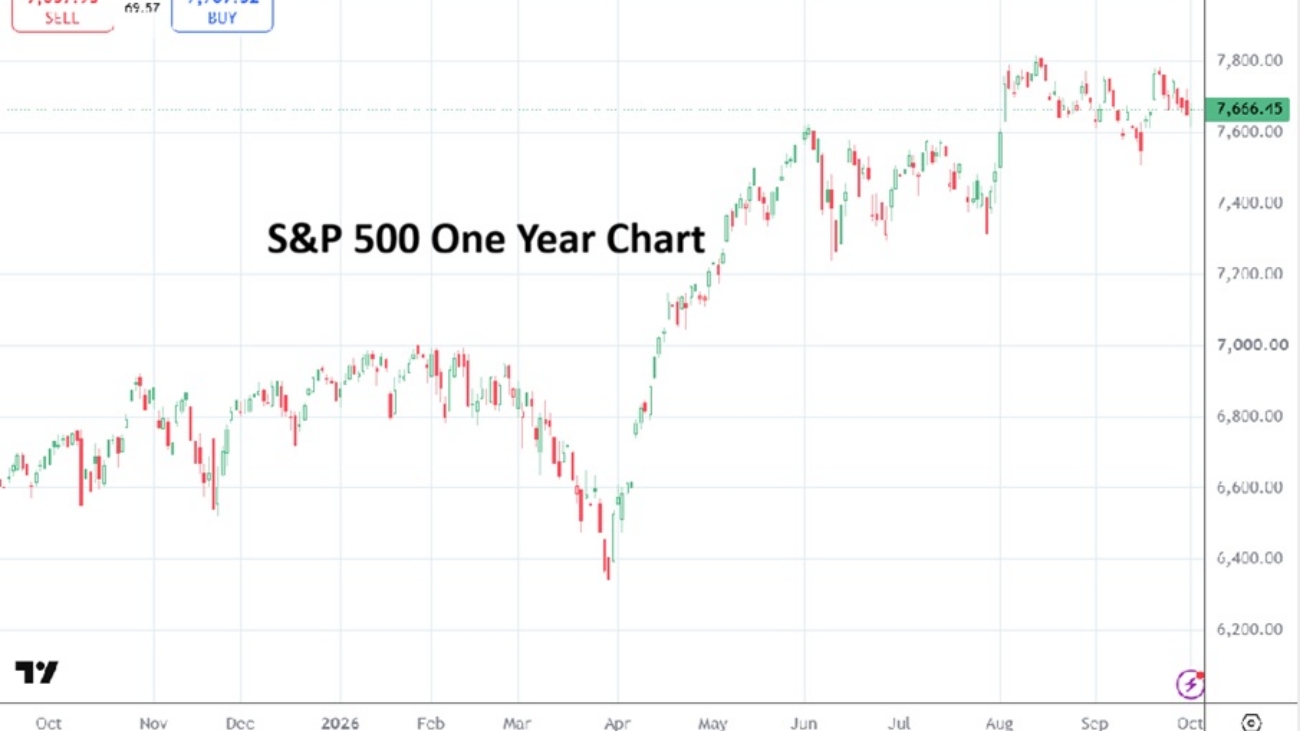
S&P 500 One Year Chart as of 2nd October 2026

The reason this is important is because like the incident in the Middle East in which a plane flying from the United Arab Emirates to Israel received a variety of different reporting, economic news receives the same type of bias. How can you trust a media source that doesn’t want to be transparent about outcomes? Now while it may be simply a lack of known details and an attempt to get a story reported on quickly to beat competitors, it would be foolhardy to say bias wasn’t a culprit in many instances.

As a consumer of news, speculators and investors need to be aware they are looking at information that often is being presented with details that the source wants to convey, while possible omitting facts. Unfortunately, global markets are being confronted by a complex amount of circumstances which include interpretation by the media which is reporting and this can lead to bad trading decisions. 

The war (conflict) with Iran continues to traverse a fragile  and unresolved path. Higher energy costs remain. WTI Crude Oil as of this moment is trading near $92.00. Gold is around $4,180.00. President Trump seemingly is attempting to practice relative calm – within his frequently loud characteristics – and not escalate the Middle East saga until the mid-term elections are complete. Perhaps that is merely my own bias as an observer.

Today Non-Farm Employment Change numbers will be published. And getting back to the original paragraph and its question, will the data matter and how will it be presented. Bias is apparent in most publications that cover the economy, to deny this would be a mistake by investors and speculators. 

While it is likely the jobs numbers are not going to have a significant impact on the voting decisions, nor the trading choices by market participants, what matters is the fact that the presentation is being geared towards an audience depending on bias of the source. The Wall Street Journal, Bloomberg, CNBC all have reporters who certainly have their own perceptions and beliefs. There is nothing wrong with this, but as a consumer of news and as a market participant you must understand that you are being influenced intentionally by media sources. 

The results from Wall Street the past handful of months have seen plenty of trading opportunities. Yet, there is a loud debate on what the near and mid-term will produce. Plenty of risk analysts are nervous about their forecasts. Yet, even soothsayers need to be aware and remind themselves they are being influenced (including myself) by the news they are consuming.

There are facts. Market results are a truth. Higher U.S Treasury yields are a reality, the stronger USD in recent weeks is happening. Sideways results – via a handful amount of months – in the SP 500, Nasdaq 100 and Dow 30 are facts – but importantly too is they remain within sight of apex highs. But the market results and their storylines are determined by media depending on how they would like you to interpret the results.

As an investor or speculator you must know your own timeframes and what your ambitions are regarding targets. Is there an AI bubble, can AI make enough revenues to cover existing valuations? Market results are delivering real values, but they still need to be interpreted and with open and flexible perspectives to determine what might happen near and mid-term.

Be careful folks. Understand what you are looking at is in fact meant to make you feel a certain way, you must digest the information and manner it is being conveyed the same way you treat a meal depending on what you have eaten. Some of the information you are taking in is junk food. You need to be able to decide on your own – hopefully with reliable insights and information – on what trading and investment paths you want to pursue.

Copy and paste the text from AMT that you want to share

AMT Top 10

AMT Top Ten Miscellaneous Insights, Mischief and Concerns for the 22nd of September

Trump's Saga, Market Conditions, Saudi Arabia, Investor Outlooks and More

10. Naima: John Coltrane’s classic composition from the late 1950’s should be listened to intently with eyes closed as his harmony and provocative ability to create a devotional hymn enchants. What do you hear? Instead of playing music for mere mortals, it sounds as if Coltrane is orchestrating for gods – take a moment to listen.

9. Upwards: Bitcoin, cough, cough is again making some look foolish as it traverses higher. As of this moment, BTC/USD is at $86,000 and making doubters – among them some AMT staff – shake their heads in disbelief (disdain). Michael Saylor’s Strategy/MicroStrategy entities have MSTR share prices around $168.00 per yesterday’s close. This is occurring as AI concerns because of its ability to challenge cybersecurity and coding of crypto remains relevant. Additionally, higher energy costs are causing miners to wince, running out of folks who are willing to speculate in the domain remains a danger (because of Ponzi suspicions), notions about government supervision getting stronger instead of becoming more lax, quantum technology, and known rogue nations keeping Bitcoin and other cryptos vibrant to hide illicit money shadow. But this is nothing to worry about it appears for Bitcoin believers and influencers.

AMT Top 10 Miscellaneous Insights, Mischief and Concerns for the 22nd of September

8. Unheralded Victories: While many were looking away purposely and likely do not want to give President Trump applause, Denmark extended the U.S administration not only an olive branch regarding Greenland, but perhaps a signal that they have acquiesced by expanding U.S security jurisdiction. From a foreign policy perspective the Trump administration has changed the Venezuela leadership, secured greater military capabilities in Greenland, and remains focused on bringing Cuba’s leadership to their knees as the island nation suffers from extended electrical outages.

7. Berkshire Hathaway: Warren Buffet stepped away from his job as Chairman on the 18th of September and named his son as successor. Share values via BRK.A were above $800,000 in April and March of 2025. This August BRK was again over $800,000. Yesterday’s close was near $752,000. Warren Buffet’s brand and era is coming to a close and the new leadership will be hard pressed to fill the confidence void. Berkshire Hathaway investors however, are some of the most loyal constituents in the marketplace. They will want to see a steady ship run by Howard Buffet and CEO Greg Abel.

6. New School: What will the Fed do now that they have raised the Federal Funds Rate by a quarter of a basis point on the 16th of September? Kevin Warsh has proven he is not exactly in the coat pocket of President Trump. After the Fed’s unanimous vote last week to raise rates, what happens on the 28th of October? Via Forex it appears financial institutions have braced their outlooks for another hike sometime later this year, but are they correct? Old theories via central banking to attack inflation with higher interest rates is a standard practice, but the escalating costs via higher energy prices has nothing to do with a sudden emergence of pent up demand, it is a supply shock that has caused more expensive WTI Crude Oil – not one driven by an increase in desire. Will Warsh prove he is new-school and proactively fight for lower interest rates sooner rather than later? Higher interest rates will not stop the Middle East saga from remaining an economic influence and spectacle.

5. Bank of Japan: Like the Fed the BoJ is not in a particularly safe space. After following in the footsteps of the Federal Reserve last week, the interest rate hike of 0.25% by the BoJ was viewed as a rather lackluster move from financial institutions and Forex players who seemingly wanted an increase of at least 0.50%. The USD/JPY remains a volatile speculative wager and is above 156.850 – give or take the tantrums and punishment inflicted from the FX market. The Bank of Japan has only had 3+ decades of questionable policy, here’s to another decade worth of doubts and consistent critical observations from outsiders.

4. Hear No Trump: The U.S President is entering a dangerous political phase for his legacy and risks losing his grip on power. Mid-term elections are rapidly drawing closer and the White House could lose its Republican led majority of the House. The President is starting to be viewed as a lame-duck by some observers. Trump who is known for his ability to change his rhetorical stances and policies quickly is still at the epi-center of global affairs. The question is if other policy makers and nations are listening. The Republican party is entering a dangerous phase and its leadership is likely going to endure a rather loud fight for control as factions take sides. The Vance and Rubio camps are likely to grow louder and divergent.

3. Saudi Arabia: Ask a friend to point to Yemen on a map, can they do this correctly? The Houthis of Yemen and Saudi Arabia may feel like a world away from known geographies, but what is happening in the wake of attacks on port areas and islands in the Red Sea (and even Riyadh) is significant. Crude Oil production and shipping problems suffered because of pipeline vulnerability is a vital concern for energy supply to Europe and Asia. While large investors may feel like they have digested the dangers, Iran and its proxies – including the Houthis may have additional theater to present. WTI Crude Oil has come down in price since yesterday but remains volatile and is around $93.00. Will optimistic banter continue?

2. FOMO: The Nasdaq 100, S&P 500, Dow 30 and their global counterparts are within their higher apexes as traders and financial institutions keep placing their money into these known asset spheres. The bond market is still producing high yields and folks are seemingly letting their casino like bets ride on a wheel they hope propels solid momentum for as long as possible. But alas, number 1, should make people pause:

1. Bandages: Perhaps our circle of contacts is too small, but behavioral sentiment is not exactly robust regarding positive market outlooks via mid-term queries. Concerns about equity indices, bond yields, inflation (because of sticky energy costs) and the general malaise that is hovering over the broad markets is not appealing. It feels as if sutures are keeping wounds from becoming infected in a haphazard manner. Investors are cautious and appear ready for the Band-Aid to be ripped off. The late ’90s and early 2000s dot.com bubble bursting, the 2006 bank and housing whispers and rumors flotilla which turned into the catastrophe of 2007-08 feel oddly similar. Perhaps it is a good time for accumulation if nothing seriously bad takes place in the markets. Circumstances feel as if a wave of blind market powers may harm those who seek never ending profits with a tsunami of losses. Perhaps it is a good time to be a speculator.

Copy and paste the text from AMT that you want to share

Share:
GIFT NIFTY 50 20260918

India Insider: NSE IPO Coming While Local Macro Conditions Not Accommodative

India's National Stock Exchange Magic Act Needs to Diversify

The National Stock Exchange (NSE) of India has been planning for an IPO quite a while. The total valuation of NSE is estimated at 5 trillion Rupees ($53 billion USD).  The issue size is 22,569 crore ($2.4 billion USD) while shares are priced at 1700 to 1785 per equity share. Share value of 65% are blocked for institutions and 35% for the retail segment. The IPO is open from September 17th to the 21st. The sales is an offer by existing shareholders, not a fresh issue of equity shares.

The rise of stock trading apps in India has made applying for primary offers easier, especially after 2020. The NSE’s value has soared over the past decade as India’s capital markets have expanded and retail participation has been surging. NSE’s unlisted shares were bought by wealthy individuals and NRIs (Non-Resident Indians) over the last few years in order to capitalize from the new trading boom.

The NSE IPO is priced at 42 times its earnings, a steep valuation compared to its global peers. NSE investment bankers were advising the stock exchange to issue 148.9 million shares at a higher valuation, but upon sensing less market depth and cautious appetite, bankers have reduced the number of shares offered to 126.44 million.

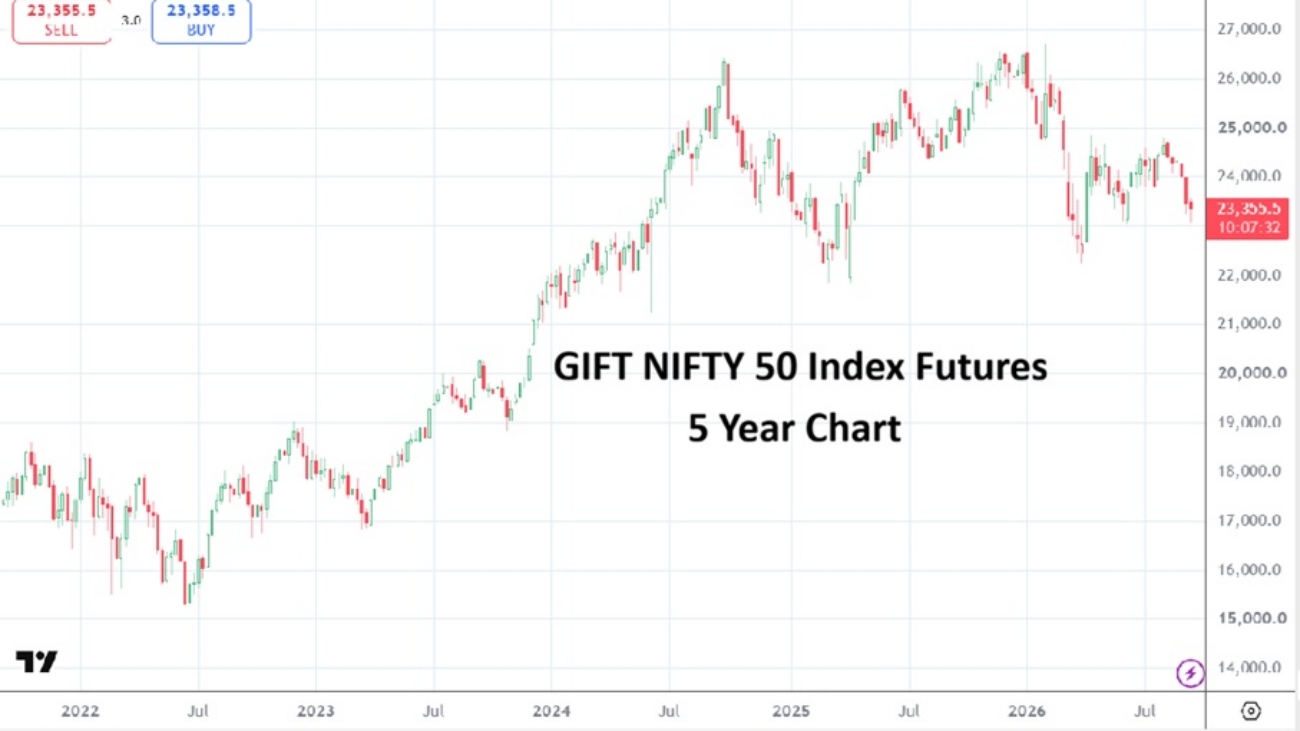
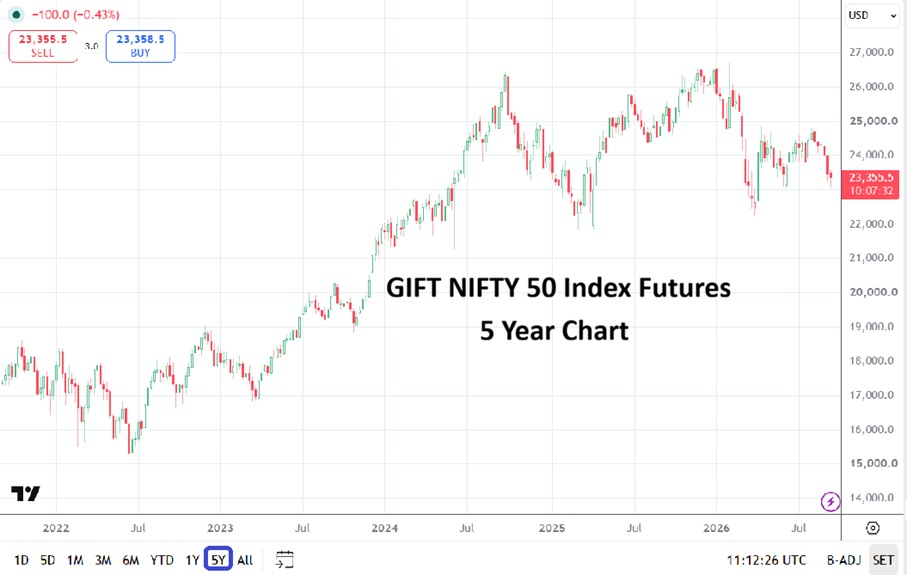
GIFT NIFTY 50 Index Futures Five Year Chart as of 18th September 2026

Reports from the last few days say anxious brokers have been calling individual investors and trying to entice them to invest in NSE. As an example, the Life Insurance Corporation (LIC) IPO in 2022 did not demonstrate as strong a marketing push from brokers compared to this NSE event. 

What’s the reason for the NSE IPO is being rushed to the marketplace when internal macro conditions are not accommodative? Various India state owned enterprises own stakes in the exchange including the State Bank of India and its subsidiary SBI Capital Markets entities – they and others likely want to be part of a ‘win’.

The NSE IPO comes at a time when the regulatory barrier on brokering and trading has intensified in recent years. Options activity propelled a gigantic boom in retail activity and helped strengthen NSE’s capital position. But it could not have happened without the regulator, the Securities and Exchange Board of India, providing a relaxed attitude regarding influencers who sugar coated facts and were partnering with brokers to attract millions of uneducated and struggling youth to bet on India’s index derivatives market.

As someone who worked in a private full service broker, I have seen countless numbers of people lose money while options betting. College students, retired people, small shop owners opened trading accounts in mass with a number of digital brokers and began to bet on weekly option wagers where the odds of winning were stacked against them.

The Indian government by igniting this machine has so far collected 90,000 crore ($9.37 billion USD) between Financial years 2021 and 2026. The flip side is the mounting losses incurred by retail traders. From FY 2021 to 2025 the losses are estimated to be around 287,000 crore ($30 billion USD) per SEBI’s data. Individual traders lost money in this casino like atmosphere around 91% of the time.  The numbers are staggering because option sellers, hedge funds, prop and other wealthy traders made money at the expense of retail losses.

The government has collected income taxes on these capital gains from profits generated by the option sellers. While retail traders who had borrowed money via personal loans to wager in these dangerous trading instruments are now suffering severe financial liabilities, paying 40-60% interest rates on their loans. Many youngsters have lost serious money. This is a severe situation because the average annual income for a person is around 15,000-20,000 Rupees ($208 USD) per month.

The NSE meanwhile has made revenues of around 35,000 crore ($3.65 billion USD) between FYs 2021-2025 for facilitating this disastrous betting landscape. In other words, the National Stock Exchange has seen profits rise by more than three times in these last four years due to the retail boom. Brokerage offices have collected handsome rewards too.

After the regulator begun to scrutinize losses incurred by retail traders in 2023 and 2024, they increased the minimum margin requirements for option traders to participate on particular contracts by a multiple of 3. This means those who were wagering with 500 Rupees now have to spend 1500 Rupees for pursuing the same contracts, assuming the premium per unit of the contract is unchanged. The regulator also limited numerous other option contracts on various indices to streamline the segment, i.e. allowing weekly expiry options for NSE and for the BSE (Bombay Stock Exchange). The chief aim of these measures was to discourage people from rapid, speculative bets on options that expired within days and it worked. Within a few weeks the high frequency retail trading frenzy had deflated sharply.

The biggest loser to this action is the NSE, which is getting around 60% of revenues from derivatives trading volumes. As retail traders activity cooled, exchanges like NSE shifted towards attracting patient long term capital from institutions for listings and rely heavily on traditional cash markets for generating revenues.

Despite pundits arguing that India has deepened the capital market inclusion, the reality is it has made very few changes in the existing system. For instance, the Reserve Bank of India ordered the closure of the exchange traded currency derivatives market in 2024, which helped small scale exporters and importers to hedge their risks efficiently. The country also has made little in-roads trying to expand the corporate bond market, and 75% of financing is still done by corporations through bank credit lines. India despite making numerous changes in regulations has failed to foster the development of financial institutions with bonds.

Short selling of shares remains banned, meaning a buyer of shares has two variables whenever he or she is purchasing, profit or loss. They can’t hedge. There is also no major marketable securities avenue for government or corporate bonds. Government bonds are still fix-rated like bank deposits. In the last decade many who people who ‘invested’ and funded instruments in shadow banking firms lost huge amounts of money, and so have individuals who invested in non-convertible debentures (NCDs) via Yes Bank and Dewan Housing Finance Limited.

If the National Stock Exchange wants retail investors to participate in its IPO shares it should diversify avenues for making money and issue a lower valuation to be attractive. The NSE cash machine has stumbled. Profits in the India financial markets industry have slowed as wealthy high net worth individuals and prop traders have shifted bases to UAE and Singapore. The NSE should not expect retail traders and small investors to subscribe to its IPO when people are struggling to pay their monthly bills. The NSE minted a huge amount of money from retail traders via a casino like binge and helped institutions and governments earn superlative profits. Now the NSE wants to replicate this cash magic act with its IPO.

Copy and paste the text from AMT that you want to share

Share:
10Y Treasury Yields 20260916

Fed Decision: Two Sides of a Dangerous Coin

The Fed Should Not Raise Rates But It Will

What and who you believe will play an important part in today’s market for speculators. While investors who are looking at long-term prisms can comfortably wait on the decision from the Fed’s FOMC regarding interest rates later today, retail traders who are trying to profit on near-term wagers via momentum and are seeking to gain an advantage by knowing which way the wind is blowing have a difficult task ahead. Via results in the Forex market it appears many financial institutions have braced already for an interest rate hike of a quarter basis point.

However, what if the financial institutions and many analysts are wrong? What if Fed Chair Kevin Warsh and other FOMC voting members believe the White House and think that inflation will erode as price pressures ease when there is a remedy to the Iranian conflict. That would mean that they could debate with other Fed officials for no interest rate hike. Because if the Fed were to raise interest rates later today, thus making borrowing costlier for businesses and consumers – and potentially putting more strain on the U.S debt payments because of increasing Treasury yields, it would still not solve the higher costs of energy. (There is an argument below which negates this possible yield problem and one that is likely to be heard from some economists).

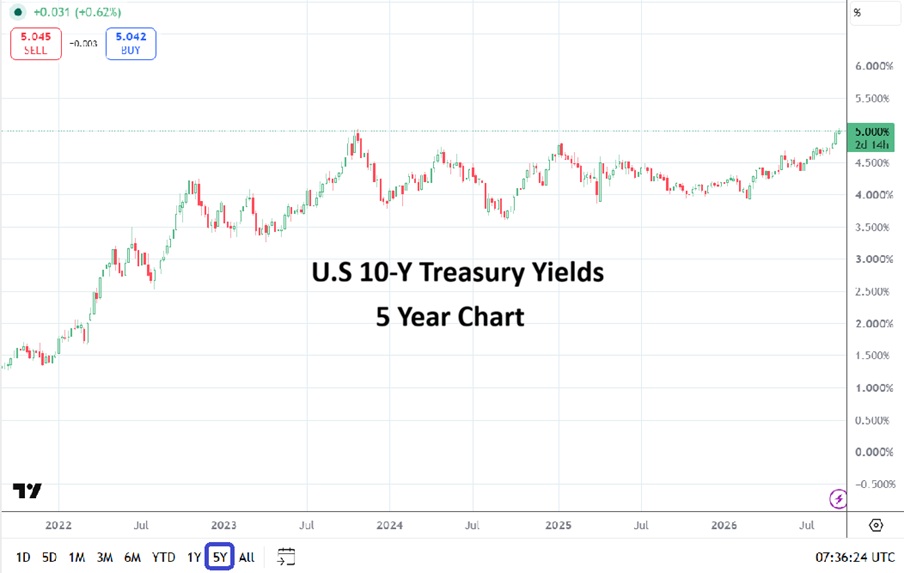
U.S 10-Y Treasury Yields Five Year Chart as of 16th September 2026

Yes, there is demand for fuel globally, but the demand for energy is not going to decrease because the U.S Federal Reserve may raise interest rates. In fact, it could make costs more expensive for businesses who are likely burning money via increased credit lines already created, this to transact their currently higher costs to guarantee effective supply of fuel to fund their logistics and manufacturing which they had not planned for while making their initial 2026 budget estimates prior to the Iranian war. In other words, a higher Federal Funds Rate will equate into higher costs for businesses.

$100.00+ WTI Crude Oil is Not A Friend

Per the other side of the coin, WTI Crude Oil has turned more expensive and volatile since March of this year. For a moment it looked like relief would be delivered via the supposed MoU between Iran and the U.S. WTI Crude Oil went below $80.00 periodically when optimism was peaked by White House rhetoric and calm waters in the Hormuz Strait were reported. Hopes for a return to WTI Crude Oil below $70.00 were viewed as legitimate.

However, the tranquility sought has vanished in the past couple of weeks and has grown more anxious as Saudi Arabia has become an important actor in the Middle East conflict as the Houthis and Iraqi militias cause havoc for the Saudi Arabian government. The price of WTI Crude Oil is now stubbornly above $100.00 and rumors about how Saudi Arabia is dealing with its own military confrontation and the way it is able to supply its own Crude Oil are confounding.

Which brings us back to the initial question regarding the Federal Reserve and Kevin Warsh, who will the Fed Chair listen to? Does he and other voting members of the FOMC believe there will be a quick fix to what has become stubbornly higher costs for WTI Crude Oil which is creating inflation? Or do they now have to objectively consider what may have been perceived as a temporary blip of elevated expenditures for the U.S economy as a potentially long-term problem? If Warsh and his cohorts believe the Iranian situation is going to find a remedy within the next four to five months, they should NOT raise interest rates today.

Again, while higher fuels costs are problematic, raising interest rates is not going to lower demand for WTI Crude Oil which is the chief instigator of higher inflation globally. It is not a question of who believes President Trump’s tantrums, it is a question concerning viability of a real end game to the Iranian situation. Plenty of Crude Oil exists, its production capabilities are strong, it is Middle East supply to Asia, Europe and Africa that is causing a problem and the higher cash and futures pricing for WTI Crude Oil. Thus, the lynchpin remains Iran. If their government capitulates and bends a knee, opening up the Hormuz Strait and stops plying its influence on the Houthis of Yemen and other militia groups in Iraq that are now causing problems for Saudi Arabia the price of WTI Crude Oil will drop dramatically.

If the situation is not rectified and the price of WTI Crude Oil remains elevated and Saudi Arabia doesn’t handle their confrontation which is turning increasingly militaristic, then it will not solve a higher interest rate initiative from the U.S Federal Reserve – unless the Fed is merely looking to decrease Treasury yields by increasing global demand for the bonds – thus hoping to increase their desirability.

Old School vs. New School 

Today’s decision from the Fed comes down to old text books and failed central bank policies versus new economic considerations. An interest rate hike from the Fed may actually make circumstance more difficult for governments around the world trying to balance their own books. 

For instance, higher yields on U.S debt are causing problems in India where some investors are shedding Indian Rupee assets and seeking the high yielding U.S Treasuries not only because of a ‘guaranteed’ bond yield, but the fact that their assets are stored in USD which is likely going to remain stronger than the INR over the next few years if a historical track record is looked upon. This is a saga that will play out in other emerging market nations too as financial institutions chase ‘secure’ profits.

5 is a Dangerous Number

So not only does the Fed face a problem regarding an interest rate hike that will not solve inflation problems caused by a war that is effecting prices because there is a fear of supply logistics, but there could be a knock-on effect regarding debt. U.S 10-Y Treasury yields near and above 5% is a clear warning side that investors are uncomfortable, this no mere speculative gain achieved by bond vigilantes. 

Another point, if the Fed were to raise interest rates today, it could in theory cause greater demand for U.S Treasuries from abroad and thus lower the Treasury yields for the moment – thus making the argument for a higher interest rate more dignified for those who want to raise rates. However, if the Fed were to say no to interest rate increases for now and point to a belief the U.S conflict with Iran is going to conclude sooner rather than later and said the U.S economy faces distress because of the higher fuels costs alone, this could also solve confidence problems.

U.S debt stands above 40 USD trillion, lower yields are a desire, but lower borrowing costs for businesses and consumers are wanted too. So what will the Fed do today………..drumroll please…………the Fed will raise interest rates – making a mistake. And will show it fears a long-term risk scenario between Iran and the U.S and problems for Saudi Arabia. The USD will see plenty of volatility. Confidence will not be shown by the Federal Reserve today and this will be problematic.

Stage presence from Fed Chair Kevin Warsh is going to be extremely important today. He has failed in his previous two FOMC Press Conferences to look confident while speaking and answering questions. His speech at Jackson Hole in late August also proved lackluster.

And this is where is gets more dangerous for Warsh and the U.S White House, because of President Trump’s ability to change his tactics quickly – there is a lack of confidence among investors who are trying to gauge their outlooks for the mid-term and beyond.

Kevin Warsh will find it difficult to pull a rabbit out of a hat. Many folks will walk away disgruntled if an interest rate is introduced and no clear guideline is mentioned regarding what is next regarding other potential rate hikes – or a plan to actually lower the Federal Funds Rate. The U.S economy while strong could easily be sent into a recession with an interest rate hike and sustained higher WTI Crude Oil costs. 

Behavioral sentiment is going to remain on a toxic tightrope unless confidence is delivered. While individual perceptions about what should be done are important, understanding the mindset of the U.S Federal Reserve is crucial. Eliminating our own personal beliefs and bias from trading decisions and acting on what realities may be demonstrated are vital to profit. 

Copy and paste the text from AMT that you want to share

Share:
Singapore Dollar 20260911

Conflicted Trading: Singapore Dollar and Federal Reserve Considerations

USD/SGD: Conflicting Desires From the Federal Reserve and Financial Institutions

The world of Forex is about to grow murkier in the coming days as shadows loom over financial institutions regarding their near-term decisions as they try to gain clarity regarding what appears to be confused and concerning mid-term outlooks for speculators and investors.

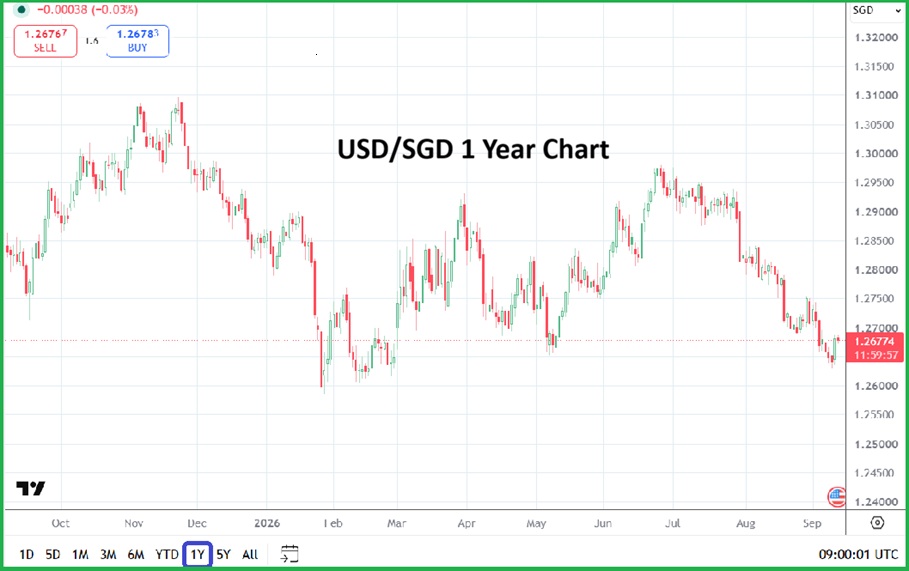
The USD/SGD is traversing near the 1.26776 vicinity as of this writing. The currency pair is trading within a long-term historical lower realm in which the 1.26000 level was challenged from mid-January until the first week of this year. This past Wednesday the USD/SGD traded near the 1.26280 mark. Previous to the current ratios and lows seen in early 2026, the Singapore Dollar traded around the 1.24475 level in June of 2014. The USD/SGD challenged 1.20000 level in early August of 2011 – yes, 25 years ago.

USD/SGD One Year Chart as of 11th September 2026

Here Come The Risk Events: Inflation, BRICS, Iranian War and the U.S Fed

Now that we have alerted technical traders about the long-term depths of the USD/SGD being flirted upon once again, it needs to be pointed out that a parade of risk events are standing in front of global Forex today and next week. First up today is the U.S Consumer Price Index inflation data. This weekend the 18th BRICS Summit will be conducted in New Delhi, India as geopolitics and trade talks will get plenty of attention. Next Wednesday the U.S Federal Reserve will issue its FOMC Statement and Federal Funds Rate decision – which may produce a climax for theatrical trading in the coming week.

While it feels almost needless to say, the Iranian War has not relented. The price of WTI Crude Oil is around $100.65 per the cash market. The sustained highs achieved in the past couple of days do not show many signs of suddenly relenting. WTI Crude Oil was around $86.50 around the 1st of September, the USD/SGD was near 1.27200. To create a bit more alarm regarding the risk horizon going into this weekend the U.S 10-Y Treasury yields lurk around 4.945%, the 30-Y Bond yields are close to 5.355% – none of this sits well with the U.S White House, nor Treasury. In the midst of this investment noise, the price of Gold is close to $4,345.00, which still looks cheap considering current circumstances.

Crude Oil supplies remain anxious globally and inflation is certainly causing angst for citizens and a variety of government policies. Singapore will report August inflation data on the 23rd of September, July’s inflation data came in around 2%, with energy costs being the culprit for higher prices in many cases. The USD/SGD was near 1.29500 around the 14th of July. Prices for energy have not gone lower and the likelihood of them turning cheaper soon remains unlikely.

USD/SGD Correlations and Current Sentiment

USD centric action since the first week of July has showed weakness against many major currencies including the Singapore Dollar. Let’s put the USD/JPY to the side because of the intervention via the Bank of Japan and input of the U.S Treasury and Federal Reserve collectively. The USD/SGD is correlating to the broad market. Risk averse decisions have been prevalent in stock markets. The U.S major indices while remaining near higher altitudes are showing cautious behavioral sentiment.

The USD/SGD certainly went lower in January and early February of this year, but this occurred as doses of optimism were filling the air and in the absence of the Iranian war. Yet, the downturn in the USD/SGD has been formidable since highs around 1.29900 were seen on the 24th of June. In late November of 2025 the currency pair flirted with the 1.31000 level. 

Federal Reserve and Treasury Battle with Reality

The U.S Treasury and Federal Reserve will not tell the U.S public that the USD loss of value is an invisible tax. Nor does President Trump want Crude Oil prices to remain high because Americans are certain to get angry about more expensive gasoline prices, particularly if they remain elevated after being promised costs will come down. Reality may prove painful for all parties in the coming months.

Which leaves us with the Federal Reserve’s interest rate decision this coming Wednesday and how it decides to decode the current anxious inflation concerns. Will the Fed try to explain that they still believe – due to the U.S intended Iranian war policy and its belief they will win in the coming months – that the Federal Funds Rate remains situated properly at around 3.50-3.75%? Delivering the important question regarding what exactly has been traded into the USD/SGD. Have financial institutions traded an interest rate increase into the currency pair already?

It certainly feels like long-term investors who believe the Federal Reserve will have to raise interest rates to fight against stubborn inflation have refused to buy Treasuries cheaply and thus forced yields upwards the past months. So what does the Federal Reserve do as an ‘independent’ institution knowing that U.S White House and Treasury desires may not match policy coordination? It is the 40+ trillion USD debt question.

Will Fed Chair Kevin Warsh actually dare to raise the current borrowing rates and say that it is quite possible the rate can be lowered again in the mid-term? Or does he admit that as feared by many financial institutions that two to three interest rate hikes will be needed per old school economic thoughts, which may actually make the current circumstances of average Americans much worse with higher borrowing costs created across the board as a side effect?

Fed Chairman Kevin Warsh has not exactly proven efficient while addressing journalists and Fed watchers quite yet. His speech this coming Wednesday on the 16th will be crucial for the broad markets. The USD/SGD is trading within its lower realm, but durable support technically does lurk. Jittery Forex trading awaits for all.

Will the Federal Reserve be bold enough to actually NOT increase the current Federal Funds Rate and talk about the risks to the U.S economy because of potential recession concerns; this as the mid-term elections lurk in November and President Trump watches and doesn’t want talk about a slowdown in the U.S economy heard from what he considers his administration. However, the Fed is independent and can do as it wants in theory.

At this point the Federal Reserve and Treasury should make sure the drama is coordinated because many eyes will be focused on the coming show. And the end result over the near-term will be volatile Forex and a USD/SGD that reacts with price velocity depending on the immediate reactions from financial institutions as they judge the path ahead which will likely remain unclear. 

Copy and paste the text from AMT that you want to share

Share:
AMT Top 10

AMT Top Ten Miscellaneous Post-Labor Day Notes and Tantrums

Higher Hopes and False Victories Welcome Nervous Investors Back After the Holiday

10. We Thought You Won – Part One: Apologies to Western Michigan University who had a victory stolen from them on Saturday in Ann Arbor. The Big Ten should not only be embarrassed, but they should be investigated. Big time college football suffered a black eye this past weekend. Folks wondering why WMU is not making a bigger stink regarding the added time and decision to repeat the last play of the game which ultimately cost WMU the contest against the Wolverines, should understand they will not. Because WMU needs to play against the University of Michigan to receive big pay days, which often are hard to find. WMU received 1.5 million USD for the game on Saturday and are scheduled to play against Big Blue again on the 1st of September, 2029.

9. Not Dead Yet: Bitcoin is trading near $78,800. After flirting with lows around the $58,100 vicinity in late June, BTC/USD has created momentum upwards. However, the elevator still can go down. Strategy via MSTR is near $142.00 per share. Michael Saylor survives and influencers are boisterous and breathing a bit easier – for now.

AMT Top 10 Miscellaneous Post-Labor Day Notes and Tantrums, 8th of Sept. 2026

8. Bad Brains: Tucker Carlson forayed into another absurd path when his recent guest, Jess Elofson, declared that Algebra is not needed and those who use it are ‘good little goy-slaves’. Carlson averages almost 57 million views to his podcast and social media outlets on a weekly basis.

7. NVDA: Nvidia is priced near $230.00 and the Nasdaq 100 finished Friday’s trading around 29,544. The Nasdaq 100 traded above 30,700 on the 3rd of June. Nvidia’s high touched the $236.00 level in the middle of May. Summer saw choppy reversals in the Nasdaq and S&P and values while elevated have run into cautious headwinds. Now that Labor Day is complete and summer ambivalence will be dusted off, where will the stock markets go? Iran lingers, inflation via higher energy costs looks problematic, mid-term election worries, AI infrastructure expenditures are concerning and bond yields all weigh on investment mindsets. Additional risk events are coming quickly down the road, Consumer Price Index data will be released this Friday and the Fed’s FOMC interest rate decision is next Wednesday on the 16th.

6. Reversal City: The USD/JPY is traversing below the 154.000 mark currently. The Bank of Japan and the U.S Treasury/Fed interaction regarding intervention and rhetoric about protecting the Yen’s value has apparently scared off buyers of the currency pair for the moment. Will bullish speculators now stay away from the USD/JPY for good? Doubtful.

5. Rhetoric Alone: Fed Chairman Kevin Warsh has found it difficult to convince the investment community that his lack of interest rate guidance is a good idea. Instead, the lack of clarity delivered from the Fed has led to higher Treasury yields. While Scott Bessent tried to fight the higher yields a couple of weeks ago, Treasuries are still smoldering and threaten to become a more dangerous fire. Investors and traders want more tangible proof that interest rate and monetary policies are structurally solid.

4. September 11th: This Friday will mark the 25th anniversary of terrorists attacks on the World Trade Center, Pentagon, and plane crash near Shanksville, Pennsylvania. 

3. Upwards: WTI Crude Oil price have shown plenty of nervous behavioral sentiment higher this past week. WTI Crude Oil is now over $94.00 in the cash market. Reports indicate that shipping via the Hormuz Strait has decreased again, this as military escalation appears ready to potentially increase as a reportedly desperate IRGC led Iran and frustrated U.S White House collide.

2. Post-Summer Guillotine: Danger lurks over the global marketplace, this as risk analysts, traders and investors appear to be converging into the same cautious direction. Forex, stock markets, bond yields, and key commodities are flashing bright yellow waring slow signals. Contrarian investors and speculators may be enjoying the current financial landscape. Value plays and volatile trading opportunities may feel appealing, but risk management is going to prove useful.

1. We Thought You Won – Part Two: After saying over the past handful of months that Iran had lost the war and just hadn’t surrendered yet, via Truth Social yesterday President Trump wrote that “when we WIN the war with Iran” that gasoline prices in the U.S would plummet. While observers are used to President Trump’s seemingly infinite capability to utter contradictory statements, yesterday’s appraisal of the current situation in the Middle East may be realistic, but it can also be observed as disquieting. There appears to be more trouble down the road.

Copy and paste the text from AMT that you want to share

Share:
Power of Intelligence 20260906

The Great Compression Part 4: Sovereignty Franchise

The Power of Intelligence

The most valuable piece of real estate in the world is a fab complex on the western edge of the Pacific, a short flight from the coast of a huge country that claims the ground it sits on. Taiwan Semiconductor Manufacturing Company, aka TSMC, prints the chips that every frontier AI model on earth depends on – and nearly all of them are currently made on that shore in Taiwan. This is simply a given; geography, unlike software, doesn’t scale, doesn’t copy, and doesn’t move.

For a decade the industry treated intelligence as something borderless, a global utility that would flow to wherever demand called for it. That framing is way past obsolete in a world that is split, lost along with the old dream of an uncensored Internet and free information exchange. Now, the crack is widening along a new axis. Forty years ago, the division ran through Berlin, and it was drawn by ideology. Today it runs through a supply chain, and it is drawn by who can make, buy, and run the machines that think. The AI chips are only the part of the split you can see and touch.

The Great Compression Part 4: Sovereignty Franchise

The Independence Chokepoint

Compute has already left the free market and entered the permitted layer of the economy. Advanced NVIDIA processors are no longer something a buyer simply purchases; they are something a government allows a buyer to receive. Export licenses now stand between the most capable silicon and any customer headquartered on the wrong side of the line. Washington has spent three years building this wall chip by chip – and the reshoring push, the fabs rising in Arizona, the equipment and materials supply chains being pulled back onto home turf, is the same impulse cast in concrete: move the chokepoint onto ground you control.

The scale of the gap explains the urgency. The U.S. holds a lead in AI compute capacity measured not in percentages but in multiples. China’s domestic production of the highest-end accelerators runs at a small fraction of American-equivalent scale. Its most advanced labs still lean on Western silicon to train their best models, whether the chips arrive through smuggling networks or through the gray route of renting restricted hardware inside third-country data centers.

Even when it’s leaking, the chokehold does its work. The controls slow every Chinese frontier effort, force it onto inferior domestic silicon, and keep it a step behind the labs it is chasing. But compute is only the first roadblock to independence: the next ones – on the intelligence itself – are only going up now.

The Gate to Intelligence

A wall around compute would be contained if compute were the end of the story, but it isn’t. The same logic that gates the chip is now reaching for what runs on it.

In June 2026, the U.S. Commerce Department required an export license for any foreign national to access a frontier AI model made by Anthropic – including the developer’s own non-citizen staff. Unable to verify the nationality of its users, the company withdrew the model entirely, and for the first time in this cycle a publicly available AI capability moved backward by government order. The controls were contested, the legal basis was unsettled, and access was restored within weeks. But the precedent was set: the authority to license the export of chips had been stretched to license access to an intelligence provider, and the mechanism worked before anyone had settled whether it lawfully could.

Beijing read the same lesson and moved to mirror it, drafting a regime to fence its own leading model weights behind national-security law rather than let them diffuse into the world. Two capitals, the same month, reaching the same conclusion from opposite sides: an AI model is not a product to be sold freely but a strategic asset released on terms. Intelligence has crossed into the permitted layer, and it crossed at both ends of the divide at once.

The Chained Brains

All of that is behind us; the interesting part is ahead.

Every ally now starting up its own sovereign AI is building it on a stack it doesn’t own – because the models, the chips, and the cloud beneath them are all American. What the ally holds is the building, the flag over the door, and the electricity bill. But the intelligence itself answers to another country’s export regime. This is sovereignty in name and franchise in fact.

The precedent for this arrangement already flies. Allied air forces buy the F-35 – the most expensive piece of weaponry in history – but they don’t thereby own it. The U.S. controls the source code and the mission-data files, and the aircraft’s full capability remains under American authority no matter how large the check. The buyer flies a plane whose brain is licensed, not sold, because withholding the core is the entire instrument of leverage. You can’t buy your way to control over a capability whose value to the seller depends on never fully handing it over.

While the F-35’s licensed brain governs a single platform, a national AI stack governs the layer through which a modern state thinks: its analysis, its logistics, its intelligence fusion, its administration. The fighter is a product on a leash, while the intelligence layer is the nervous system on a leash.

The Thinking Franchise

And the company installing that nervous system is already doing it. Palantir’s value was never the model but the trust above it and the data structure beneath it – the ontology layer that ingests a government’s data and turns it into decisions. In mid-2026 it began offering sovereign customers what they most wanted to have: full ownership of their model weights, retrainable, air-gapped, sealed behind their own walls. Still, the weights are the airframe that a buyer can own – but they will still have to run on NVIDIA silicon, inside an operating layer a U.S. company builds and controls, under the same export regime that pulled a frontier model offline in June.

Canada shows how thin the sovereignty can wear. Ottawa named itself the anchor customer of its own national AI strategy in mid-2026 while already running tens of millions of dollars in undisclosed Palantir contracts inside its defense and policing systems. The strategy announced sovereignty, but the procurement had already outsourced it. And by late summer, the two were trading tariffs and hard words, the closest alliance on the continent gone frosty, with the most sensitive systems of one side still running on the other’s stack. Nobody had to threaten anything. The dependency simply sat there, the way it was always going to.

Right in front of our eyes, the forward base of the last century gives way to the forward stack of this one. Instead of a U.S. army base near a European capital, a data-orchestration system running on NVIDIA chips, wired into the host government’s own operations, doing quietly what the garrison once did loudly. Land, power, and data can belong to Berlin or Paris, on paper – but the intelligence stack that holds the dependency will be American. It’s a cheaper umbrella, a deeper one, and a far harder one to ask to leave.

The End of Sovereignty

The immovable object was supposed to be the safe end of this story. Land, power, fabs, the heavy and hard-to-replicate assets that no software cycle can compress, the bedrock beneath the cloud. All of that still holds. But immovable is not the same as owned – and anyway, even the owner isn’t sovereign, because sovereignty itself is what’s being compressed at the top of the stack.

Every chokepoint described above rests on a fact that holds only for now: advanced compute is scarce, and what it produces can be walled. Practical quantum advantage dissolves both, and it is a contest between the same two powers that have run through every layer of this story. Perhaps one arrives first. Perhaps, if less likely, two arrive together. It changes little for everyone else. The machine owner reads what others hide and shields what it keeps. The only defense is a new cryptography built to withstand it, and it takes the same frontier compute and talent that only those two powers command. Even the lock is provisioned by the vendor.

It doesn’t matter who owns the oil or holds the warheads if the secrets around them can be opened at will and the means to reseal them belongs to someone else. The world is already two powers and their satellites, although most of them still speak as though sovereignty were something they possessed. The quantum edge is the point where the pretense ends.

Copy and paste the text from AMT that you want to share

WTI CrudeOila 20260902

Bad Timing for President Trump May Equal Good Trading Opportunities

You Don't Have to be a Buyer in the Current Marketplace in Order to Profit

There are moments when the markets are calm and then there are these times. It is beginning to look like increasingly bad timing for President Trump and his administration’s hope to keep WTI Crude Oil prices in check and silence the chatter about inflation. 

Instead of a de-escalation based on tranquil conditions in the Middle East, investors were smacked in the face again last night. However, while this may be a bad time to be an investor unless they are looking for value plays, traders may actually have more opportunities in the current market circumstances as long as they manage their risks appropriately.

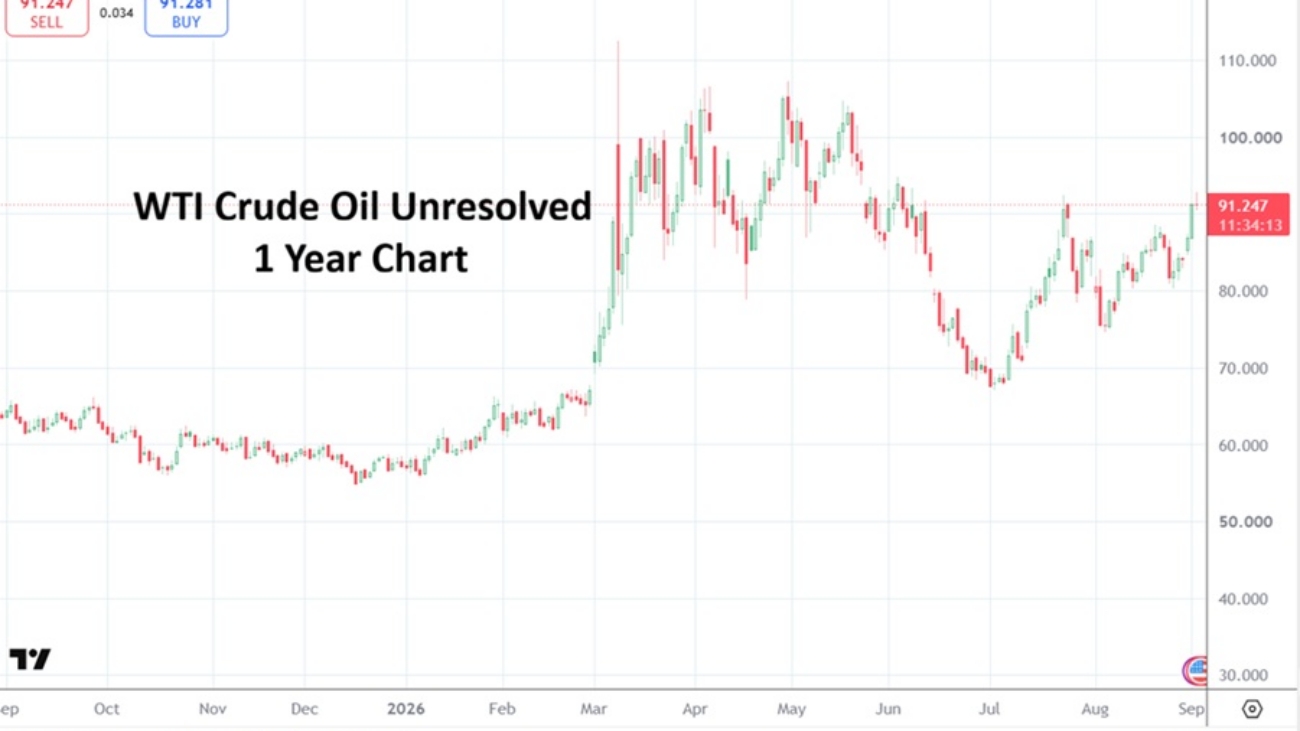
WTI Crude Oil jumped higher last night and while the commodity has outdone itself since late February regarding price velocity, last night’s performance likely felt volatile even for experienced large players who have solid intel on the ground regarding Middle East shipping and supplies. The energy sector has been more akin to the soft commodities regarding reversals the past handful of months, Coffee, Cocoa and Crude Oil have offered colorful price ranges. But that is not how WTI Crude Oil is supposed to work.

WTI Crude Oil 1 Year Chart as of 2 September 2026

Inflation concerns will not go away quietly as long as WTI Crude Oil remains highly valued. Fed Chairman Kevin Warsh may in fact be putting on a show for the public – that he is his own man and can express his concerns regarding inflation no matter what President Trump thinks – when in fact he may simply be laying a framework to work in tandem with Treasury Secretary Scott Bessent and lower interest rates in order to create less pressure on Treasury yields. However, this planned (or conspiratorial) thinking may be hard to actually produce in reality on the 16th of September when the Fed’s FOMC has to show its cards once again. As long as WTI Crude Oil remains above $90.00, “Houston we have a problem,” murmurs may be heard loud and clear.

If Treasury yields remain tilted upwards because investors are refusing to buy them at cheaper rates, it will start to infect the Nasdaq 100, S&P 500 and the Dow 30 more and create cautionary skirmishes which may produce deeper downsides in stock markets.

Iran wouldn’t want to cause President Trump problems, correct? Why would Iran want higher Crude Oil prices to ensnarl President Trump into a morass of political battles in the U.S and make life difficult for the Republicans during the mid-term elections? Does the IRGC have folks who understand the dynamics of U.S politics? Yes they do and it is a 100% certainty they would like to be a pain in President’s Trump’s aspirations.

We are left to deal with the ever-changing events that seem to be quite good at repeating themselves. Financial institutions are not only nervous about their mid-term outlooks, they are wary about the near-term too. Forex, commodities, bond yields, Wall Street and other global stock markets will struggle to make solid gains until clarity develops.

What will clarity look like? It will be optimistic banter in which rhetoric from different mouths and geographies is actually believed by the adoring crowds. Results do not have to be good, but outcomes need to be able to be forecasted and planned, allowing investors to seek their cash preservation and fortunes in a variety of assets (and show their overseers that they used adequate risk management in case things go wrong). 

Gold has done well recently, although it seems to have hit some resistance lately. However, if inflation tranquility is not achieved and if President Trump’s circumstances grow more dire, the precious metal will continue to offer speculative plays upwards. 

Investors are restless. Making 6 to 8% profits a year looks rather boring after plenty of solid years of upwards traction. Folks aren’t used to powerful financial storms and they forget about lingering troubled periods in which simple profits can prove comforting as broad markets struggle. 

Day trading is dangerous. However, those with solid risk taking tactics and those who aren’t married to the notion that markets only go up, but are willing to bet that markets (assets of many classes) can go lower too – now have an opportunity to test their technical perspectives and understanding of behavioral sentiment. 

Realistic targets using take profits and making sure stop loss protection still allows for a trade to move until goals are met is important when volatility is ripping price realms to shreds. Forex instability appears to be increasing as USD centric attitudes remain convoluted. Does Fed Chair Kevin Warsh have enough power to fight against an interest rate hike on the 16th of September, will the price of WTI Crude Oil cooperate, will President Trump’s wishful thinking about Iran come true? Results may not match what is wanted by the guardians of the marketplace. Contrarians may see the current market and global political situation as a time to seek value and help inflate markets, but they might be spitting into the wind. 

Maybe the AI concerns about infrastructure costs and corporate cash needs are baseless. Perhaps the deficit being created by the U.S and many other nations is simply idle chatter by risk analysts who are too nervous. Maybe there is a secret pill for all of us to become optimistic about all things.

It is a good time for traders to remain realistic and target exaggerated price movements in assets that offer opportunities in distressed offerings. You do not have to buy the marketplace to profit ladies and gentlemen.

Copy and paste the text from AMT that you want to share

Share:
30Y Treausry Yields 20260826

How Warsh Can Solve the US Debt Crisis With Just a Few Words at Jackson Hole!

A Roadmap for Fed Chairman Kevin Warsh to Rescue U.S Debt

Many think the market decides interest rates.

Wrong!

The Fed – and only the Fed – has full control over interest rates, all over the curve!

We just need to have the right person on board.

During the European crisis in 2011, speculators all around the world were betting that the Eurozone would explode and that the EUR would collapse under the weight of government debt that had started with Greece and spread to other countries that were shamelessly labelled “PIGS,” adding insult to the speculative attack.

Trichet, at that time chair of the ECB, seemed totally clueless, afraid to take any “unconventional” step, even at the risk of seeing the entire European financial system go bust.

The crisis seemed unstoppable… until Mario Draghi stepped in, replacing Trichet.

With just one magical statement (“the ECB will do whatever it takes to save the Euro. And believe me, it will be enough”) Draghi implied that he was ready to buy government bonds from European countries, even though such action was considered at the time to be “against the ECB’s statutes” and outside its mandate.

By going against the prevailing market narrative, and knowing very well the economic strength of the Eurozone, Draghi forced the market to follow him.

The speculation against the Eurozone stopped almost instantly, and European government bond prices recovered without the ECB even being forced to intervene!

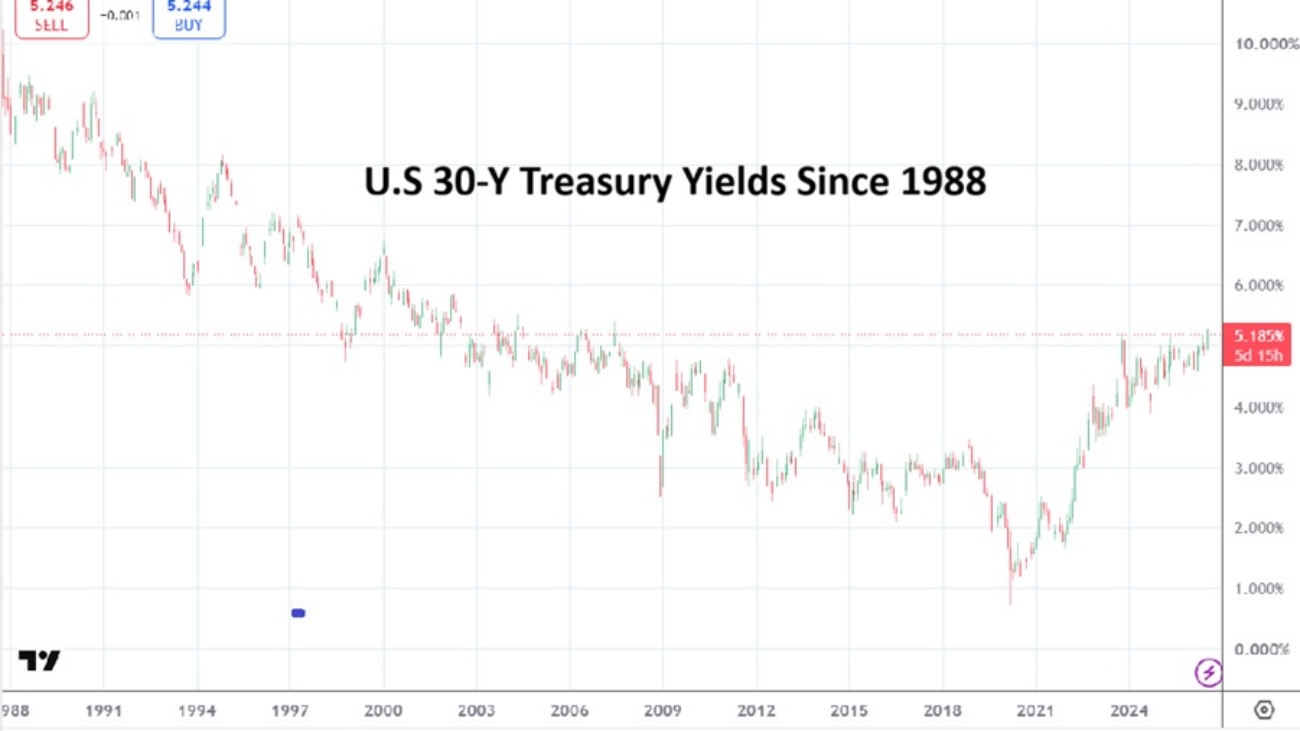
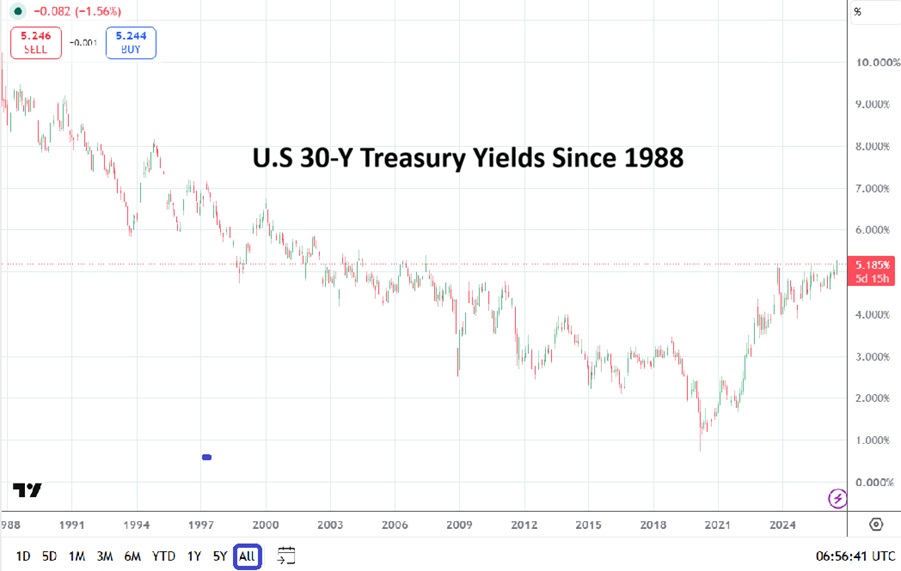
U.S 30-Year Treasury Yields Chart From 1988 until 26 August 2026

Today, the U.S is in exactly the same position!

A massive speculative attack is being waged against U.S debt (probably led in part by the crypto industry in an attempt to justify the “value” of its virtual tokens), with “inflation” suddenly becoming the ultimate beast.

Like Trichet at the time, the weak Powell got driven into the trap of raising rates abruptly on his own government, forcing it to pay more than $1 trillion in yearly interest, a massive and unnecessary injection of liquidity that is itself… inflationary!

In today’s world, driven by massive debt, raising interest rates on governments is INFLATIONARY!

Now that Powell is almost gone, all hopes lie on Warsh’s shoulders.

He can save the U.S from the current debt crisis with just a few words, exactly as Draghi did for Europe.

Warsh completely missed his first intervention a month ago. Instead of showing the market who’s boss, he showed total febrility.

Fearing being labelled a “Trump puppet,” he insisted on the 2% inflation target – an absurd threshold that nobody really knows where it came from – and claimed that “the economy is robust”… while we all know it is not!

Then he totally capitulated to the market by saying that he would “listen to the market” to determine where rates should go. The worst thing any Governor could ever say!

That’s how long-term yields exploded to levels not seen since 2007, and forcing Bessent to intervene to limit the damage.

We are now just one day away from the Jackson Hole Symposium.

Warsh can now either save the U.S or send it into Armageddon!

Every word he says could change the entire picture.

He simply has to focus on the right narrative:

  • Current inflation is geopolitical and driven by supply shocks. Raising interest rates has zero impact on such inflation.
  • The 2% inflation target is NOT an absolute figure. A 3% inflation rate should be acceptable when the economy is at risk.
  • Signs of recession are looming, with the labor market under pressure, rising bankruptcies, and record rates of defaults on credit cards and car loans.
  • Forcing the government to inject more than $1 trillion through interest payments is itself inflationary. Raising interest rates to fight inflation is counterproductive at such a high level of government debt.

If Warsh is capable of highlighting these arguments, yields will drop instantly without any intervention from Bessent.

Then the Fed can start decreasing interest rates gradually, with the market accepting whatever rate it sets.

What if Warsh deliberately gave a disastrous speech a month ago, taking a tough position against what Trump appointed him to do and allowing the market to drive rates to extreme levels… only to radically change his position following the recommendations of the task force he appointed?

This way, he would have absolved himself from being labelled Trump’s puppet while executing exactly the plan of reducing interest rates.

We can therefore suspect that he will take the opportunity at Jackson Hole to present the first findings of this task force, which could include, among other things:

  • A questioning of the 2% inflation threshold, especially when the economy is at risk of entering a deep recession.
  • Stressing that inflation comes mainly from geopolitical issues and supply shock. Fighting such inflation with high interest rates is totally inefficient.
  • A highlight of the absurdity of raising interest rates on the U.S government and forcing it to inject $1 trillion in interest payments – an unnecessary injection of liquidity that is itself inflationary.
  • The necessity of coordinating with the Treasury Department to fight inflation where it hurts the most, through subsidies, tax relief, and other targeted measures, while primarily fighting “greedflation” through higher profit taxes on specific industries.
  • A warning about the increasing risk of recession, with record numbers of corporate bankruptcies, credit-card defaults, and a deteriorating job market.

Warsh has a unique chance to prove that he is the right person for the job by rescuing the U.S from the massive speculation against its debt, exactly like “Super Mario” did when he saved Europe from collapse in 2012.

Copy and paste the text from AMT that you want to share

Share: