Indian Rupee 20261026

India Insider: RBI Considers Higher Interest Rates as Rupee’s Direction Remains Vulnerable

Structural Financial Solutions Needed to Create INR Resilience

The Indian Rupee has appreciated in the last week, amid escalating tensions in the Middle East and capital outflows from stocks and bonds. The Rupee has gained from 97.00 in early October to a close around 95.20 levels this past Friday. 

The Rupee’s strength also came on the foreign interest delivered from the $3.2 billion USD valued Jio Platforms Ltd. initial public offering. Still, analysts say that any appreciation should be expected to be short lived. The RBI has not used interest rates to manage the Rupee, instead it attracted inflows from Non-Resident Indians (albeit leveraged flows) to manage its balance of payments.
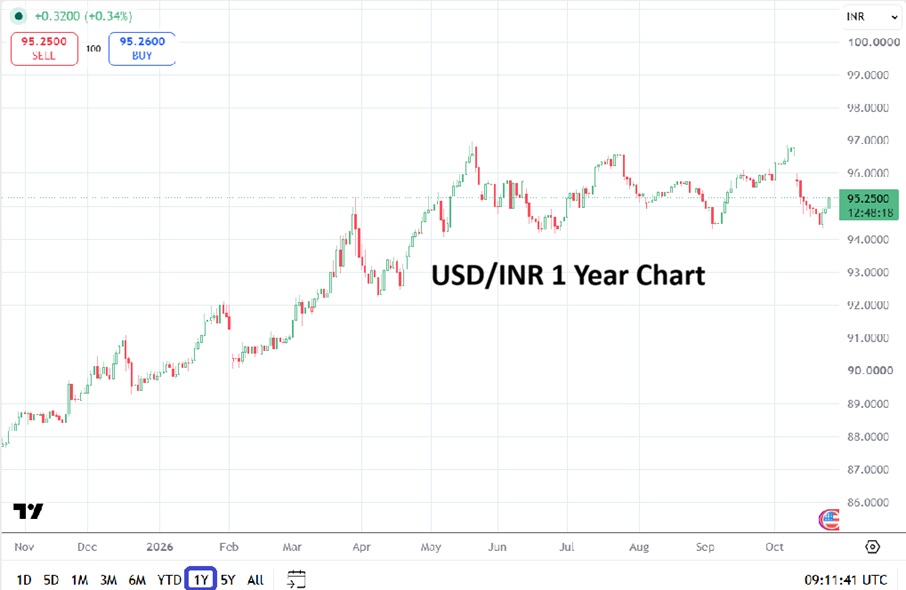
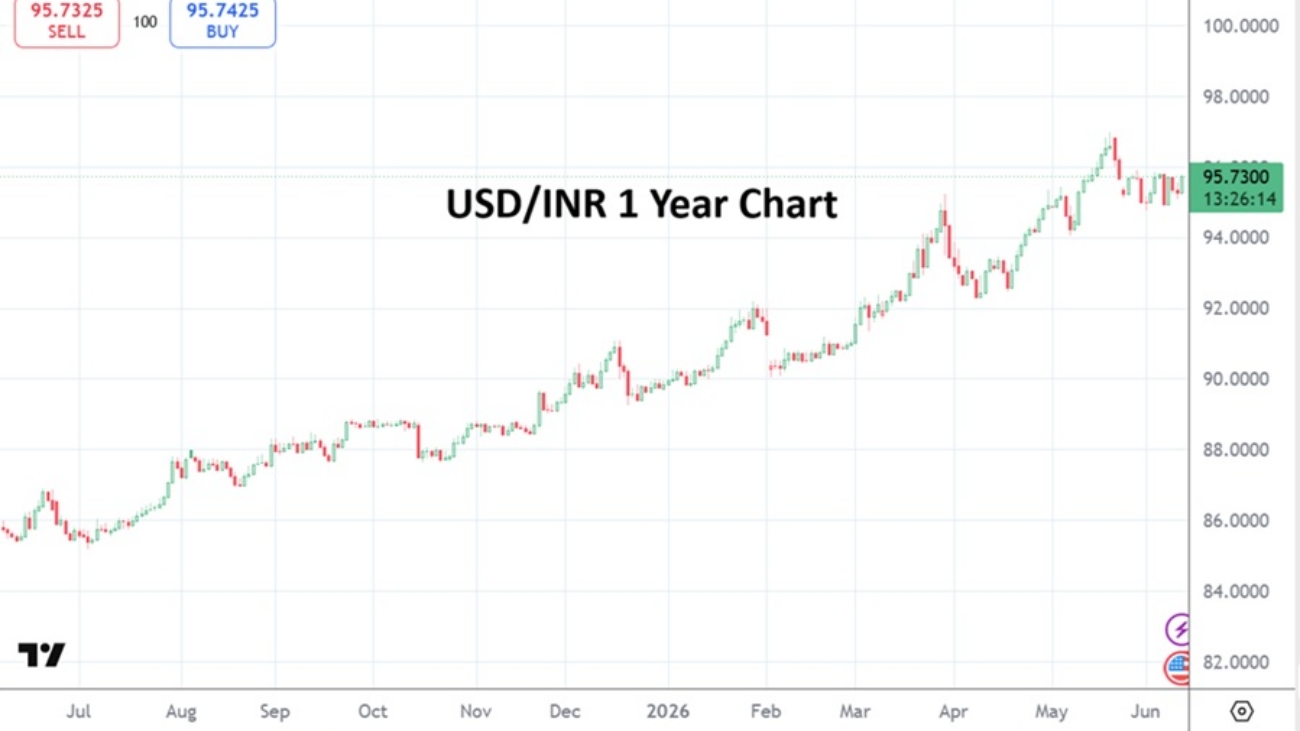
USD/INR One Year Chart as of 26th October 2026

This is despite the fact that Asian and African central banks have used interest rates to manage their currencies. The Philippines has raised rates by 50 bps this past week, and Uganda’s Central Bank hiked by 225 basis points, from 9.75 to 12%, surpassing their 50 basis point jump in 2024 and the 100bp rise in 2022.

The fact is current account deficit countries need foreign capital to finance deficits via international balance of payments, and rising oil prices and volatile capital flows have exacerbated the problem. Recently, the Reserve Bank of India has rolled out measures to curb Dollar demand, including a special window to supply foreign currency to State run oil refiners.

The spot Forex market is where currencies are bought and sold at prevailing exchange rates. The Indian Oil Corp., Bharat Petroleum Ltd. and Hindustan Petroleum Ltd. buy large amounts of USD through banks in the foreign exchange market to pay for Crude Oil imports. Large Dollar purchases can increase demand for USD and put pressure on the Rupee, particularly when Crude Oil prices are high and import payments rise. But with elevated oil prices and foreign outflows persisting, traders are betting the RBI will need to rely more on rate hikes, which tend to push bond prices down and yield higher.

Global central banks are using interest rates as ammunition to fight against USD centric strength as the rising value of the USD via a perceived hawkish Federal Reserve, along with mounting geopolitical tensions like the escalation between Saudi Arabia and Yemeni Houthis cause angst. Brent Crude Oil is now near $110.00 per barrel. This is an alarming consequence for India and other nations that rely upon oil imports. Requirements for India’s Crude Oil supply is around a 88 to 90% dependency.

India’s import bill rose by 47% in September compared to last year, rising from $10.5 billion to 15.4, obviously straining & draining foreign exchange reserves. Yes, spot level prices are inflicting less pain, but USD demand is real.

Angry Meta Traders has written in the past about the challenges of using FCNR (Foreign Currency Non-Resident) deposits, which the Reserve Bank of India has attracted around $135 billion. However, the RBI is being confronted by a mounting and increasingly costly need to defend the Rupee. Deploying tens of billions of dollars and resorting to extraordinary market interventions to protect a currency (the INR) is a costly endeavor.

India’s central bank is reportedly tightening scrutiny of large overseas investments by domestic companies as it seeks to contain capital outflows amid pressure on the Rupee. Many analysts point out that a bad outlook exists as the nation struggles to attract capital, and the risk sentiment remains elevated. As Chris Kay wrote in the Financial Times recently, “ the central bank since June has already used about $90bn of what it raised from India’s diaspora to prop up the Rupee, including through sales to the spot market and currency swaps to absorb surplus liquidity.”

The interest rate hike debate comes as the inflation backdrop is worsening. Consumer price growth accelerated to an almost two year high in September, nearing the top of the RBI’s 2 to 6% tolerance band. A weak monsoon threatens to keep food prices elevated, while the Rupee’s decline could further stoke inflation by making imports more expensive.

India’s 10 Year Bond yields have risen by 26 basis points from 7.21 to 7.47%. Investors are concerned about higher and tightening rates by the Reserve Bank of India, in which the repo rate stands at 5.5% as stubborn inflation and falling real wages also spark concerns.

In the Emerging Markets bond investment space, some financial institutions are picking perceived winners in places like Brazil, Colombia, Malaysia, Thailand, China, Pakistan and Peru. They consider Indonesia, India, Philippines, Turkey, Mexico as losers due to the prevailing global macro sentiment.

What is the RBI is Going to do Short-Term?

Will India attempt a jumbo hike like other nations? This could reduce capital outflows and supposedly reduce depreciation of the Rupee. Or will it try to restrict Indian capital going abroad which would likely choke off growth? Economists from major investment banks argue that India’s primary problem is not weak exports but capital flows.

Per their viewpoints, a drop in Net Foreign Direct Investment has left the Indian Rupee more dependent on volatile portfolio flows as global markets have turned fragile and geopolitical tensions remain legitimate and people and companies seek safety. Ultimately, for pressures on the Rupee to ease, India requires changes in underlying fundamental flows financially which exert tangible structural solutions that are not short-term fixes.
Copy and paste the text from AMT that you want to share

Share:
Indian Rupee 20261014

India Insider: RBI’s Rate Hike Cannot Mask Persistent Issues

Supply Chain and Balance of Payment Concerns Remain for the Indian Rupee

The Reserve Bank of India hiked interest rates by 25 basis points recently as inflation has shown signs of becoming entrenched due to higher Crude Oil prices and El Nino effects, and inducing supply side pressures especially in Agri-commodities. The headline inflation rate in India rose to 5.54% in September 2026 from 4.83% in the previous month, the highest reading since October 2024. 

Food costs have been 7.74% higher year-on-year with onion prices jumping 108%, while upwards costs for ginger of 62.9% and garlic at 54.6% have been significantly sharp. Meanwhile, higher Crude Oil prices and a weakening Rupee drove transportation inflation to a 5.01% increase. Surging prices have hit restaurants, accommodations by nearly 9.36%, personal care, and social protection costs by around 13.75%. Month-on-month the Indian CPI rose by 0.69%.

Crude Oil prices remain elevated due to the conflict in the Middle East. India’s position as a net energy importer makes it particularly vulnerable to rising import costs. On top of this, the USD has strengthened partly due to a Federal Reserve rate hike and safe haven (risk averse) flows, contributing also to the depreciation of the Indian Rupee. The Indian energy sector having to spend more USD to purchase resources has exacerbated Rupee depreciation as costs for imports have soared and show an ability to remain stubborn.

Global conditions remain unhelpful and the Middle East conflict shows little chance for immediate solutions. Indian officials within the Reserve Bank of India seemingly have felt they had no other choice to fight inflation and falling exchange values via the USD/INR, except by raising interest rates like other global central banks.

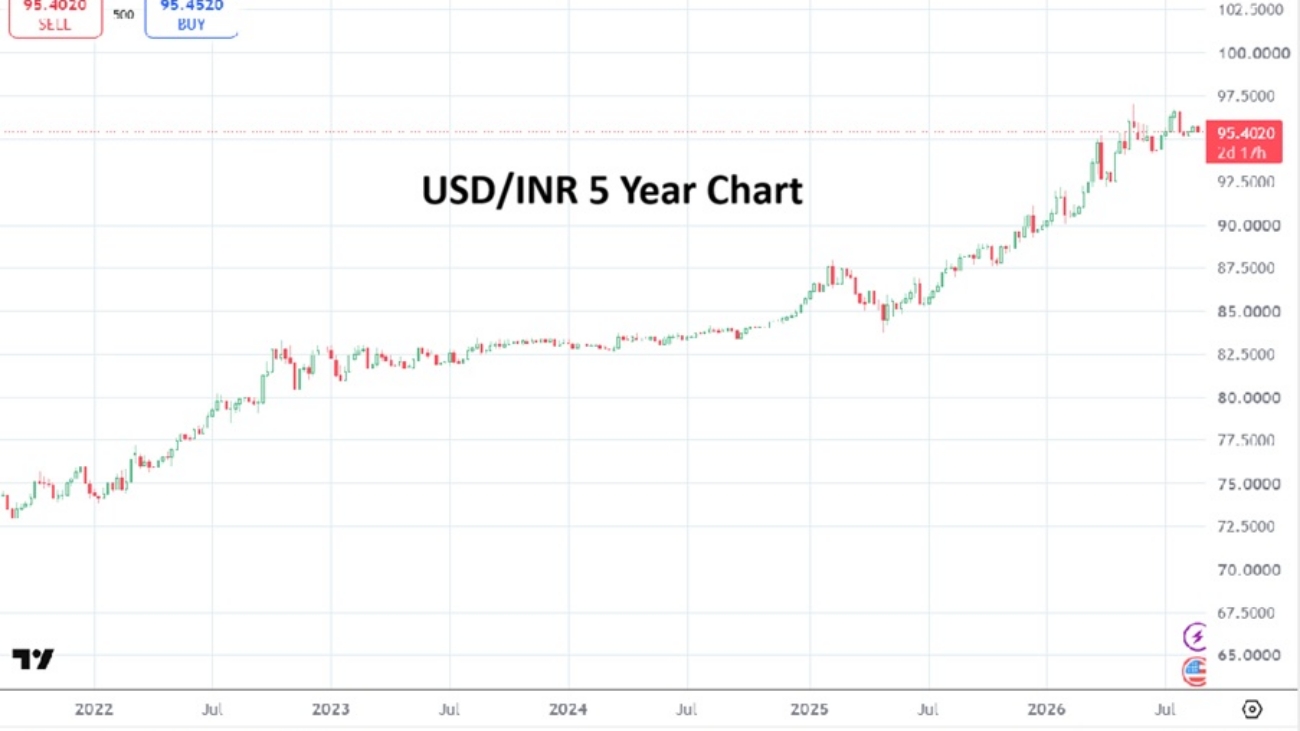
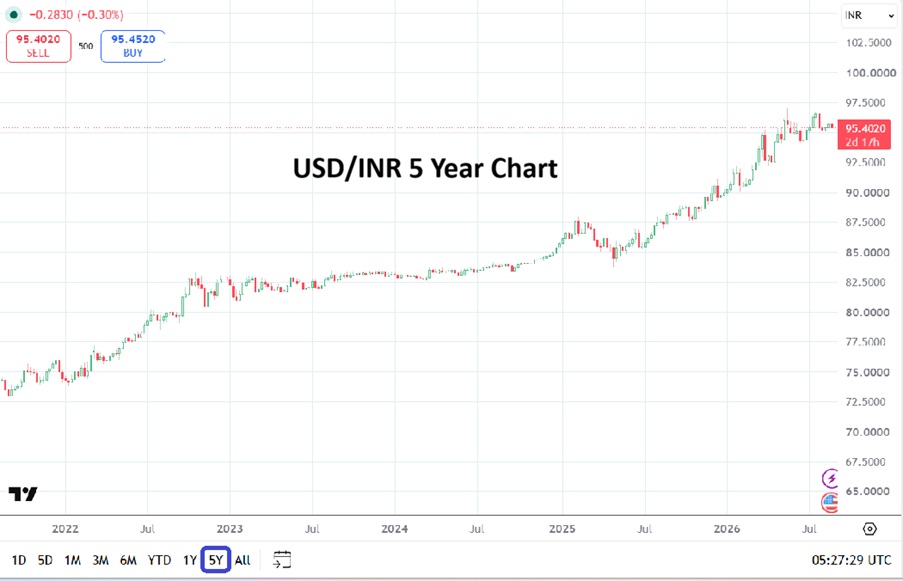
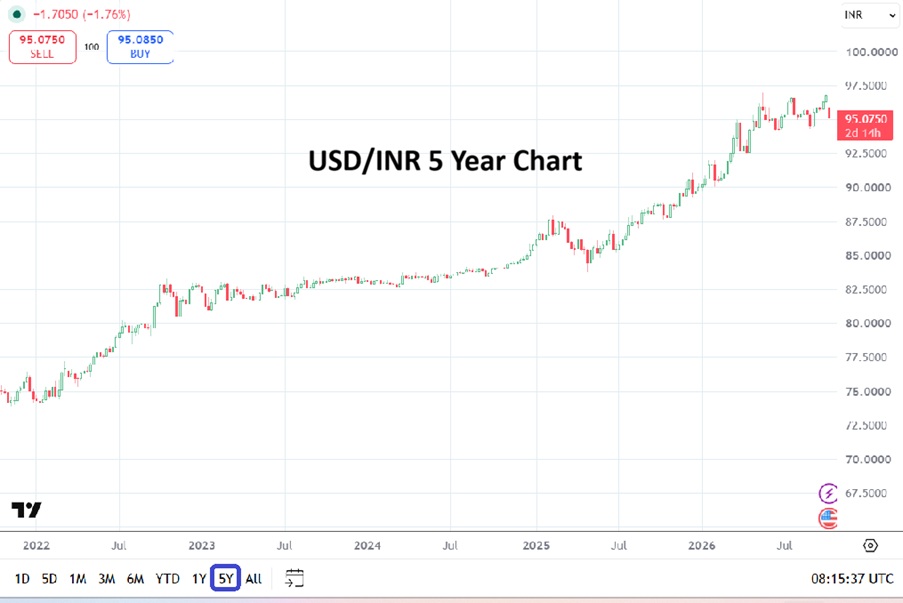
USD/INR Five Year Chart as of 14th October 2026

Robert Petrucci, an astute observer and writer on the Indian Rupee, argues that an interest rate hike to deal with the problem of higher energy costs will not fix the inflation problem caused by the Middle East conflict. In Petrucci’s opinion, even if a central bank has raised interest rates by full basis point of 1%, it would have little effect on the demand of energy as long as prices remain a geo-politically influenced circumstance. 

Robert Petrucci has also said that the decline in value of the Indian Rupee could also stimulate India’s exports of tradable goods making them cheaper for foreign importers. Evidence shows the cumulative value of India’s merchandise exports between April and August of 2026 reached USD 215.91 billion. This is a 17.85% increase compared to the same five month period in 2025, when exports were USD 183.21 billion.

Even as prices for commodities also rise due to El Nino weather effects, this storyline cannot be entirely blamed. Professor Narayana Moorthy wrote recently that in the State of Tamil Nadu the rise in prices of Agri-commodities can also be attributed to shrinking cultivation areas and stagnant irrigation improvement. Tamil Nadu’s inflation rate in May 2026 reached 5.11% against the national average of 3.93% comparatively. Crop prices cannot be controlled simply by raising interest rates, as Robert Petrucci alludes, without boosting domestic agricultural production capabilities.

Balance of Payments Highlights Another Influence

Despite generating higher GDP growth and claims of economic strength India’s balance of payments remains severely weakened by massive capital flight. By the end of June 2026 a staggering 543.9 billion USD combined had left India, comprised of 316.1 billion in direct investment outflows, 23.4 billion into portfolio funding, and 204.4 billion into other outward stakes. As Professors Jayati Ghosh and C.P. Chandrasekar have written in a recent BusinessLine article, “for a lower middle income country, with most of its development projects incomplete and greatly in need for additional investments, the extent of capital outflows is quite large. It significantly reduces the net inflows that economies in India’s position require for development.”

Economist Michal Kalecki observed in Poland in early twentieth century, capitalists invest only in when they accumulate profits, no matter whether it stimulates wages or reduces unemployment. In that sense, according to Kalecki, the changes in the prices of goods or wages or household demand would not entice a capitalist other than making a profit. They are there to make profits and want to see accumulated retained earnings on balance sheets. If mass consumption is not sufficient enough for their goods and services, investments would channel or divert into other premium products or markets that command higher profits.

Investments, as Kalecki observed via his practical business experience, are not decided by household demand but by businesses decisions that ultimately influence employment and national income. In that sense Kalecki never argued that investment is independent of demand, his thesis is that the capitalists as a class are protected even in a slump, as they would invest in resources that maximize their profits. According to him, investment was not simply a function of interest rates or consumer expectations. It was connected to profitability, income distribution and the contradictions of accumulation. It literally means, any rise in prices of goods and services due to a depreciating currency or supply chain induced inflation would be passed to consumers as we have seen in the last few years, even as real wages are not growing and become unbearable for households.

What India needs is patient capital that funds infrastructure and development, creates jobs, along with some government allocated capital expenditures, rather than capital that solely chases returns or deviates quickly once returns are achieved. By showing the government can provide long-term commitment allowing low return assets that stimulate household demand, this could make private investments profitable in future rounds.

In planned economies like the failed former Soviet Union, authorities frequently forced investments rates up without genuine profitability or consumption orientation. Capital was often misallocated, funds were dispersed via corruption and outright theft. Accountability was certainly not transparent.

Kalecki reminds us that economic stability cannot be separated from the question of whose interests it serves. A key component is ultimately developing increasingly sophisticated techniques for stabilizing capitalism and understanding why capitalism requires continuous stabilization.

A rise in interest rates may help reduce consumer demand in some areas, but money naturally chases allocations which earn ‘best’ returns. This is highlighted by businesses and financial markets where capital outflows seek profits and do not protect the Indian Rupee. Support for the INR provided by Non-Resident Indians inflows that has helped build the FX Reserves recently cannot be relied upon alone to fix the weakened Indian Rupee problem alone, nor can ‘simple’ fixes like the recent quarter of a point interest rate hike by the Reserve Bank of India. A coordinated and tactical policy is needed.

Copy and paste the text from AMT that you want to share

Share:
Nifty 50 20261004

India Insider: From Farms to Factories An Unfinished Productivity Transition

Striving to Make India the Best Version of Itself

Many East Asian economies in the last three decades have prospered because of large allocations using massive State subsidies to chosen sectors and respective industries via affordable credit while keeping interest rates at bare minimums. Wages were and remain suppressed to make industrialization possible through a transfer of savings from households to businesses – to help manufacturing thrive.

This has helped China and other East Asian Tiger nations to compete head to head with Western economies with fortified industries. Globalization also extended this phenomenon. Western economies offshored a lot manufacturing to countries that produced competitive goods to keep their corporate costs low – including wages, this while the majority of Western nations also shifted towards service sectors and consumption to generate solid performing GDPs.

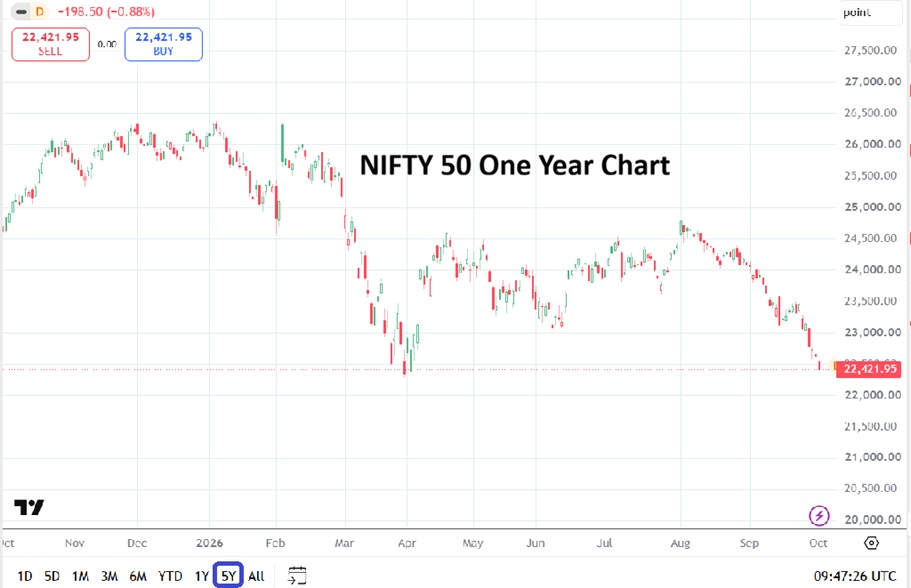
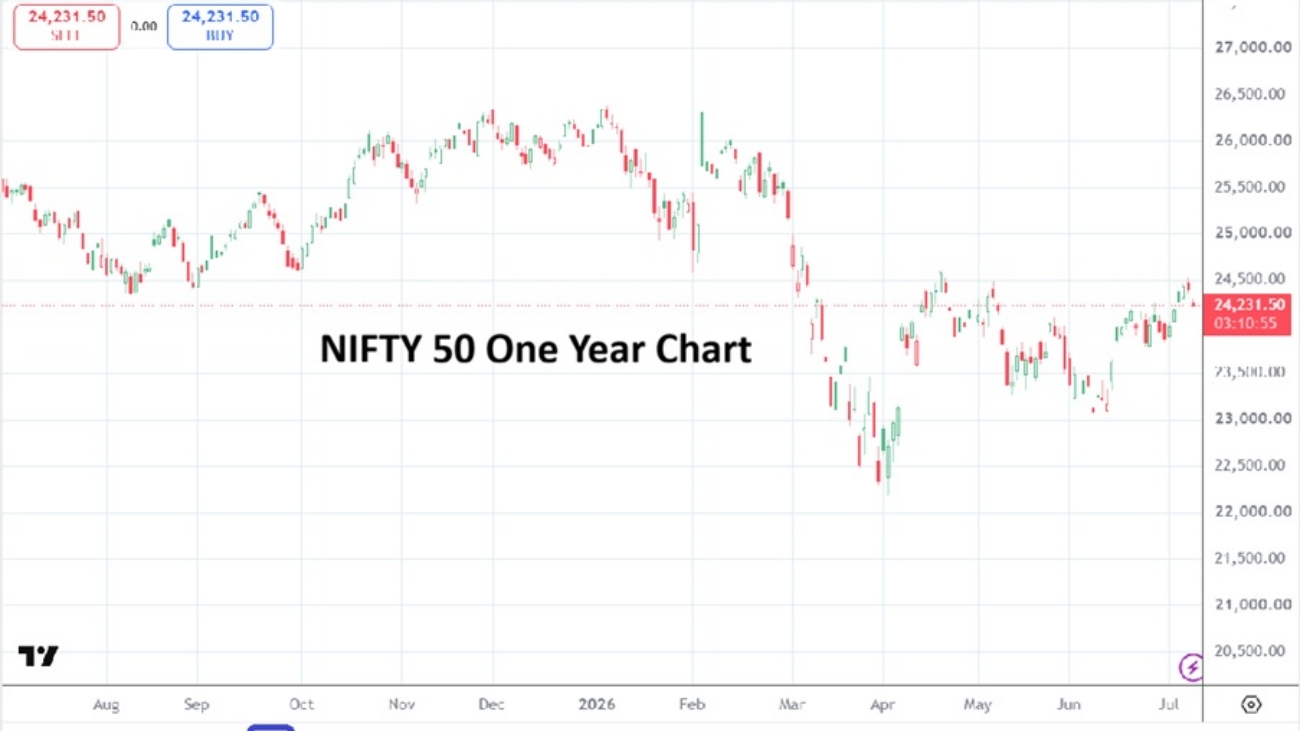
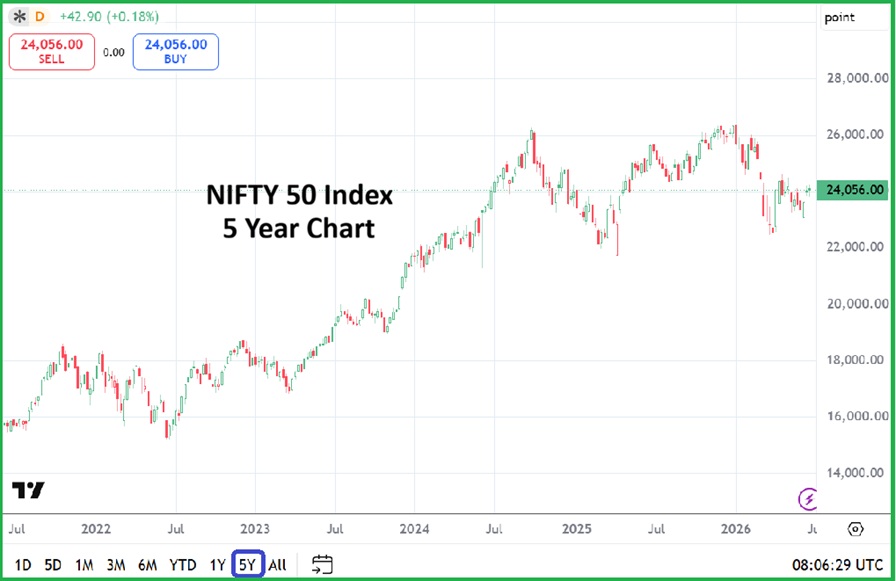
Nifty 50 One Year Chart as of 4th October 2026

This system ran extraordinarily well the last two decades, until trade deficits in the Western economies ignited agitation amongst citizens and inside the government offices of policymakers from Brussels to Washington. In order to create jobs for their own people and protect their legacy industries from losses, countries are increasingly discussing protectionism, illegal immigration, and restricting access on critical technologies.

Irrespective of the tranquility and results in the past, this after the Latin American and Asian financial crises caused by the abrupt policy shifts. Changes to the free flow of capital and trade have shown they can disrupt exporting based economies faster than many governments could handle the challenging circumstances appropriately.

India is one of the nations’ standing at this new crossroad. It has favorable trade relations with many partners. Though India runs a trade surplus of good with the United States and Europe, its trade with China and Russia is clearly unilateral – Beijing and Moscow holds advantages.

To compete with external trade partners like Vietnam, China and Korea, India wants to allocate expertise into high tech manufacturing like semi-conductors, electronics, and other preferred sectors. Problematically, because every State in India follows a different industrial policy according to their own political aspirations and needs, it’s difficult for New Delhi to dictate policies that align with central government objectives cohesively.

Changing the Playing Field to Accommodate Growth

The experience of industrial bases like Germany, Japan and the East Asian economies show that manufacturing growth requires coordinated policy. Ironically in India, after the 1991 economic reforms, no structured national manufacturing gameplan existed until 2011.

Industrial strategy should provide better support for land acquisition by the government with generous terms to landowners for agricultural lands, rather than merely leaving it to private corporate interests. Less bureaucratic labor law reforms would help too.

The 1991 industrial policy statement reduced the barriers to entry for private industry, deregulating, abolishing the monopolies and restrictive trade practices act of 1969, and significantly reduced import duties. This remained a focused policy pillar over two decades. However, there remained a number of gaps that still need to be improved.

The “new economy narrative” discussed by the Indian government needs a realistic perspective. For example, policy makers in the government argue that PLI (Performance Linked Incentive) which started in 2021 is an answer for reviving sector specific manufacturing. But not everyone is convinced. PLI is based on subsidies that provide incentives to generate output in fourteen highly import dependent sectors (especially for imports to China) that are extremely capital intensive in character. This has happened at a time when India needs to create more quality jobs in manufacturing, but faces hurdles.

The PLI has issues because the system requires many firms apply for the incentive subsidy to increase production in their chosen sectors, and the government will be in charge of picking winning firms (rather than sectors). This is the opposite of the practiced industrial policy of the East Asian Tiger miracle economies and what underlaid their success in export oriented manufacturing growth. The East Asian nations only selected industries to support, they did not ‘pre-pick’ winning firms.

The Soviet Example: Agriculture as a Competitive Lever?

During the Brezhnev era in the Soviet Union, most everyone in the top government positions of the now disbanded nation knew something was wrong economically. The Soviet Union was a giant bureaucracy that wanted to manage all production according to misguided yearly targets – the failure was only a matter of time as the utopian economic system imploded upon itself with malfeasance.

In the 1970s within the Soviet Union the immense influx of hard currency achieved from energy exports masked severe domestic failures, particularly in agriculture. Instead of investing the trade surplus into modernizing domestic infrastructure, the Kremlin was forced to use its Petrodollars to import vast quantities of Eastern grain and agricultural products to compensate for chronic harvest failures and feed its population.

By the early 1980s, the Soviet Union’s trade profile resembled that of a developing nation: exporting raw unrefined materials to purchase food and finished goods. When global oil prices crashed in the mid-1980s, the Soviet Union trade balance plunged into severe deficit and never recovered. Stripping the state of the hard currency it needed to survive.

Likewise, despite being an agriculturally important nation, India is forced to import massive quantities of specific agricultural goods due to low domestic yields. For instance, researchers had long predicted a rise in prices of Tamil Nadu State agricultural commodities due to a shortage of agrarian areas and stagnant growth in irrigation. Farmers are turning away from paddy cultivation because the returns fail to cover costs. Increased farm wages, machinery rentals, irrigation costs, fertilizer and pesticide prices have steeply driven up the costs of crops in Tamil Nadu. Consequently, paddy farmers are trapped in a cycle of debt and economic distress.

Although agriculture employs nearly half of India’s workforce, it contributes only about 15-18% of GDP. Outputs per workers are low. Tiny landholdings, low yields, dependence on the monsoon, and depleted groundwater limit productivity, this while subsidies and procurement favor rice and wheat over diversification. Poor storage, weak credit access for small scale farming, low investment opportunities add to problems and limited non-farm jobs keep surplus labor stuck on farms. India remains a net agricultural exporter achieving about $51.9 billion USD in 2024-25, but despite this higher valued Agri-export composition is not sufficient.

Policy Decisions and Competitive Companies

India’s services exports and remittances have created a persistent source of Forex earnings. The resulting accumulation of foreign exchange reserves provides an external capacity to import vital capital goods, technology and other productive tools to create benefits. The challenge is to convert this external surplus into better domestic productive capacity. This can be done by investing in infrastructure including logistics, energy, worker skillsets, technology development, improved ports and warehousing – and other foundations required for manufacturing and developing superior values in agriculture.

Improving the infrastructure for success is crucial, but importantly the Indian government should not attempt to pre-ordain winners through the PLI. Choosing winners can become a doomed strategy when the State tries to determine in advance which firms, technologies or industries will ultimately become globally competitive as capitalism plays out and companies ascend or fail sometimes.

The East Asian experience suggests that industrial policy can support selected sectors, but competitiveness ultimately has to be tested through productivity and export markets. The role of the State should therefore create conditions in which winners can emerge through competition within the marketplace, as they manage finance, technology and their workforces – which will help the companies strive to become the best versions of themselves.

Copy and paste the text from AMT that you want to share

Share:
GIFT NIFTY 50 20260918

India Insider: NSE IPO Coming While Local Macro Conditions Not Accommodative

India's National Stock Exchange Magic Act Needs to Diversify

The National Stock Exchange (NSE) of India has been planning for an IPO quite a while. The total valuation of NSE is estimated at 5 trillion Rupees ($53 billion USD).  The issue size is 22,569 crore ($2.4 billion USD) while shares are priced at 1700 to 1785 per equity share. Share value of 65% are blocked for institutions and 35% for the retail segment. The IPO is open from September 17th to the 21st. The sales is an offer by existing shareholders, not a fresh issue of equity shares.

The rise of stock trading apps in India has made applying for primary offers easier, especially after 2020. The NSE’s value has soared over the past decade as India’s capital markets have expanded and retail participation has been surging. NSE’s unlisted shares were bought by wealthy individuals and NRIs (Non-Resident Indians) over the last few years in order to capitalize from the new trading boom.

The NSE IPO is priced at 42 times its earnings, a steep valuation compared to its global peers. NSE investment bankers were advising the stock exchange to issue 148.9 million shares at a higher valuation, but upon sensing less market depth and cautious appetite, bankers have reduced the number of shares offered to 126.44 million.

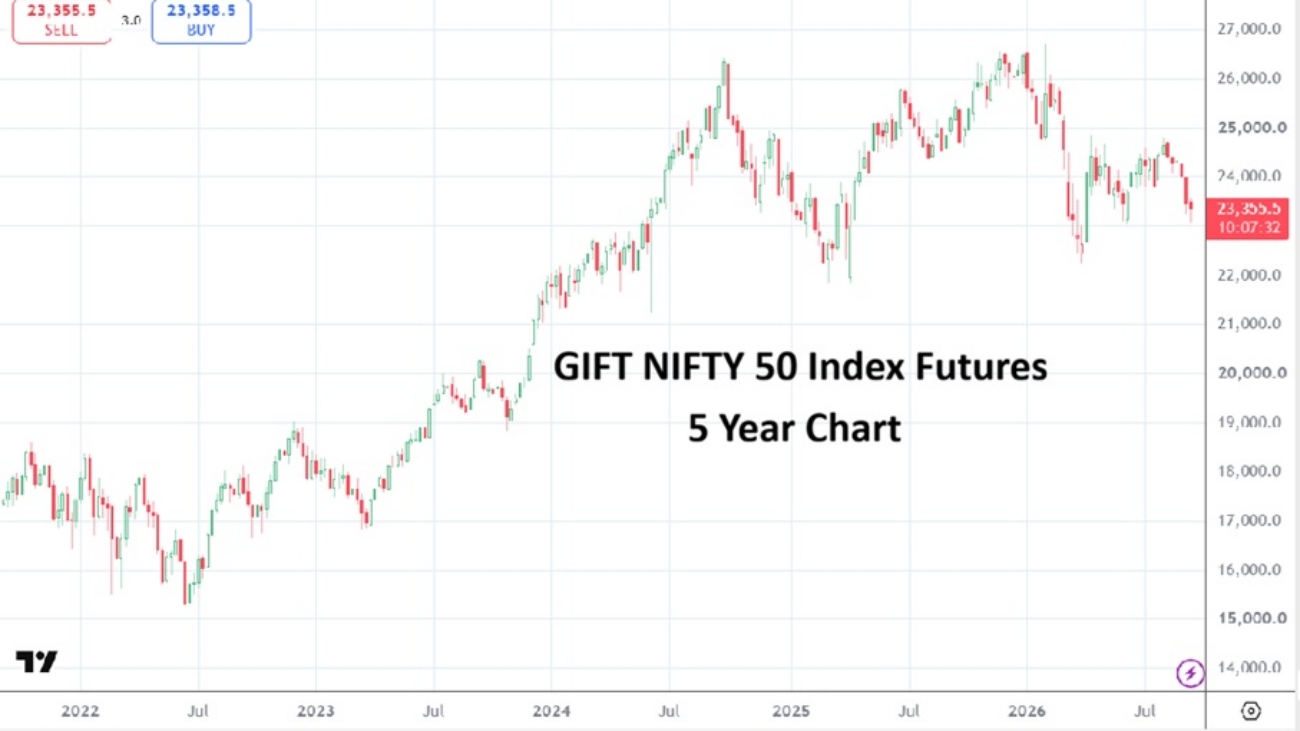
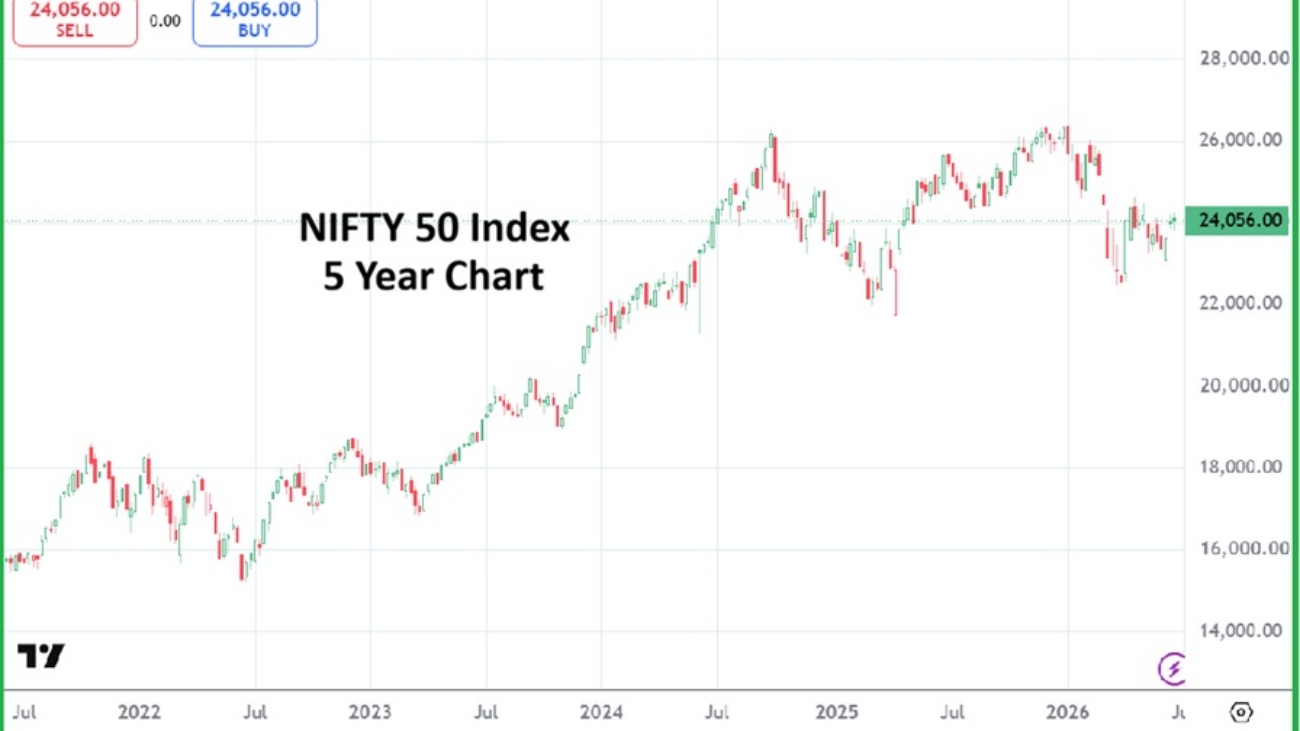
GIFT NIFTY 50 Index Futures Five Year Chart as of 18th September 2026

Reports from the last few days say anxious brokers have been calling individual investors and trying to entice them to invest in NSE. As an example, the Life Insurance Corporation (LIC) IPO in 2022 did not demonstrate as strong a marketing push from brokers compared to this NSE event. 

What’s the reason for the NSE IPO is being rushed to the marketplace when internal macro conditions are not accommodative? Various India state owned enterprises own stakes in the exchange including the State Bank of India and its subsidiary SBI Capital Markets entities – they and others likely want to be part of a ‘win’.

The NSE IPO comes at a time when the regulatory barrier on brokering and trading has intensified in recent years. Options activity propelled a gigantic boom in retail activity and helped strengthen NSE’s capital position. But it could not have happened without the regulator, the Securities and Exchange Board of India, providing a relaxed attitude regarding influencers who sugar coated facts and were partnering with brokers to attract millions of uneducated and struggling youth to bet on India’s index derivatives market.

As someone who worked in a private full service broker, I have seen countless numbers of people lose money while options betting. College students, retired people, small shop owners opened trading accounts in mass with a number of digital brokers and began to bet on weekly option wagers where the odds of winning were stacked against them.

The Indian government by igniting this machine has so far collected 90,000 crore ($9.37 billion USD) between Financial years 2021 and 2026. The flip side is the mounting losses incurred by retail traders. From FY 2021 to 2025 the losses are estimated to be around 287,000 crore ($30 billion USD) per SEBI’s data. Individual traders lost money in this casino like atmosphere around 91% of the time.  The numbers are staggering because option sellers, hedge funds, prop and other wealthy traders made money at the expense of retail losses.

The government has collected income taxes on these capital gains from profits generated by the option sellers. While retail traders who had borrowed money via personal loans to wager in these dangerous trading instruments are now suffering severe financial liabilities, paying 40-60% interest rates on their loans. Many youngsters have lost serious money. This is a severe situation because the average annual income for a person is around 15,000-20,000 Rupees ($208 USD) per month.

The NSE meanwhile has made revenues of around 35,000 crore ($3.65 billion USD) between FYs 2021-2025 for facilitating this disastrous betting landscape. In other words, the National Stock Exchange has seen profits rise by more than three times in these last four years due to the retail boom. Brokerage offices have collected handsome rewards too.

After the regulator begun to scrutinize losses incurred by retail traders in 2023 and 2024, they increased the minimum margin requirements for option traders to participate on particular contracts by a multiple of 3. This means those who were wagering with 500 Rupees now have to spend 1500 Rupees for pursuing the same contracts, assuming the premium per unit of the contract is unchanged. The regulator also limited numerous other option contracts on various indices to streamline the segment, i.e. allowing weekly expiry options for NSE and for the BSE (Bombay Stock Exchange). The chief aim of these measures was to discourage people from rapid, speculative bets on options that expired within days and it worked. Within a few weeks the high frequency retail trading frenzy had deflated sharply.

The biggest loser to this action is the NSE, which is getting around 60% of revenues from derivatives trading volumes. As retail traders activity cooled, exchanges like NSE shifted towards attracting patient long term capital from institutions for listings and rely heavily on traditional cash markets for generating revenues.

Despite pundits arguing that India has deepened the capital market inclusion, the reality is it has made very few changes in the existing system. For instance, the Reserve Bank of India ordered the closure of the exchange traded currency derivatives market in 2024, which helped small scale exporters and importers to hedge their risks efficiently. The country also has made little in-roads trying to expand the corporate bond market, and 75% of financing is still done by corporations through bank credit lines. India despite making numerous changes in regulations has failed to foster the development of financial institutions with bonds.

Short selling of shares remains banned, meaning a buyer of shares has two variables whenever he or she is purchasing, profit or loss. They can’t hedge. There is also no major marketable securities avenue for government or corporate bonds. Government bonds are still fix-rated like bank deposits. In the last decade many who people who ‘invested’ and funded instruments in shadow banking firms lost huge amounts of money, and so have individuals who invested in non-convertible debentures (NCDs) via Yes Bank and Dewan Housing Finance Limited.

If the National Stock Exchange wants retail investors to participate in its IPO shares it should diversify avenues for making money and issue a lower valuation to be attractive. The NSE cash machine has stumbled. Profits in the India financial markets industry have slowed as wealthy high net worth individuals and prop traders have shifted bases to UAE and Singapore. The NSE should not expect retail traders and small investors to subscribe to its IPO when people are struggling to pay their monthly bills. The NSE minted a huge amount of money from retail traders via a casino like binge and helped institutions and governments earn superlative profits. Now the NSE wants to replicate this cash magic act with its IPO.

Copy and paste the text from AMT that you want to share

Share:
India GDP Savings 20260911

India Insider: Leveraged FCNR Deposits Reliance and Remittances Masks Structural Vulnerabilities

Forging True External Strength Without Relying on the Crutch of Foreign Deposits

For the last few weeks, financial publications have applauded the news that India received around $127 billion USD via leveraged foreign NRI deposits (FCNR). Banks swapped these dollars for Rupees with the Reserve Bank of India (RBI), securing cheap funding while ostensibly strengthening India’s external position. Analysts have calculated that while the hedging cost for the RBI is around $16.3 billion USD, the investment income generated by parking those funds in U.S Treasuries could reach $22.4 billion USD. On a net basis, this implies a $6.1 billion USD gain for the RBI over the next five years. However, while this may look like a tactical victory on a balance sheet, it ignores a fundamental macroeconomic contradiction: if the Indian economy is growing robustly, why isn’t its external position strengthening organically?

The Remittance Paradox

Indian rural towns and villages have long sent workers abroad to Singapore, Malaysia, the Gulf States and beyond. This migration has created a flush of dollar remittances, making India the world’s largest recipient in absolute terms. For instance, India has attracted around $135 billion USD in 2025, a figure that has been rising steadily. Yet, despite this massive nominal volume, remittances represent only about 3.6% of total GDP. 

This capital undeniably boosts domestic consumption, but it also exposes a structural gap between wages inside India and abroad. The fundamental characteristics of current account deficit countries is that they demonstrate low domestic savings, high investment needs, and persistent reliance on foreign capital to finance their deficits.

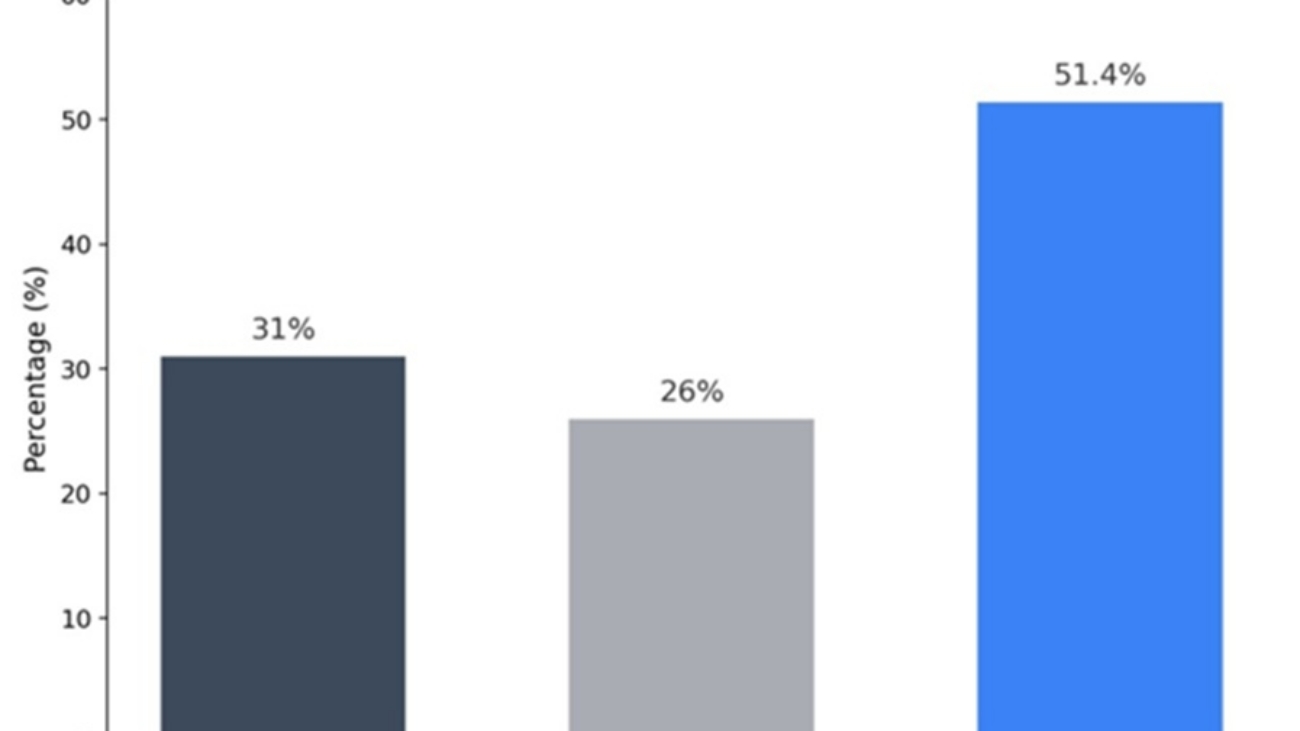
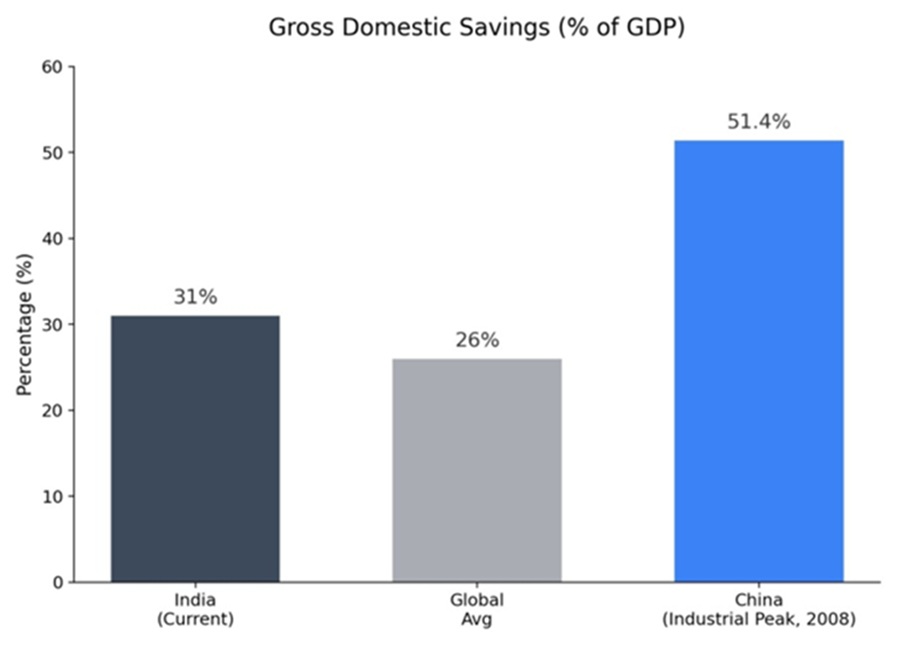
World Bank/CEIC for India and Global Average, and Wiemer EAI Brief for China’s 2008 Peak

In India’s case if the economy were truly expanding from within as said, domestic incomes would have risen proportionally with national growth, expanding the pool of internal capital. Instead with a vastly informal economy, India remains heavily dependent on its diaspora to fund its current account deficit.

The Domestic Savings Deficit

According to periodic labor force surveys, India is projected to have a working age population of around 900 million by 2030. To effectively employ this massive demographic dividend, the country urgently needs to raise its domestic savings rate. Currently clinging to roughly 31% of GDP, India lags far behind industrial powerhouses like China, which leveraged a domestic savings rate of around 45% to fuel its manufacturing ascent.

Policymakers should not rejoice over a capital account surplus funded by NRIs, especially when that surplus is leveraged over 7 to 10 times. It is this exact diaspora sending USD home that fuels India’s consumption, creating an illusion of self sustaining economic liftoff.

The “Dutch Disease” in Local Economies

The heavy reliance on remittances creates severe geographical distortions. Many towns possess high savings but they are incredibly unevenly distributed. These high savings are attributed to external capital rather than domestic productivity, while local employment remains trapped in informal service sectors or low productivity agriculture. Towns with high foreign remittances naturally develop immense asset bubbles in real estate and experience soaring rent and consumption costs. Because these economies do not export goods or services to other states or countries via production or services, they rely entirely on external capital inflows to generate internal demand. This reflects a localized variant of the “Dutch Disease”.

The labor market is extremely tight in these areas. Due to the high cost of living and limited wage growth, workers tend to migrate to other regions or overseas in search of better opportunities. This tight market further contributes to cost inflation in labor, food, and overall living expenses and increasing the cost structure for both households and businesses. This vicious cycle is primarily due to weak policy decisions from the government’s end, such as inadequate industrial infrastructure, poor urban planning, weak skills development, limited MSME financing, also insufficient connectivity.

A Structural Transformation is Required

This economic pattern is not unique to India, it also mirrors provincial towns in the Philippines, regions in Mexico and parts of the Balkans. While remittances support consumption and keep real estate elevated, they fail to translate into productive investment due to weak industrial bases and limited economic linkages. The result is seen vividly in the balance of payments clearly as India’s importing needs keep increasing, but the inability of Indian goods to compete globally results in persistent gaps in export volumes. 

With protectionist rhetoric vibrating in Washington and anti immigration protests rising from the U.S to Australia, this model is highly vulnerable. The Indian government must urgently pivot toward policies that empower Indian nationals to work in small and medium scale businesses (SMEs) domestically. By focusing on small scale manufacturing with high economic linkages and wage growth potential, domestic savings will naturally rise, eventually forging true external strength without relying on the crutch of foreign deposits.

Copy and paste the text from AMT that you want to share

Share:
India Employment 20260904

India Insider: An Unfinished Economic Transformation

Improving India's Education Strategy to Help Prosperity

Indian government officials, policy makers and journalists have all applauded the GDP April-June quarter data that came in 7.8%, compared to last year’s 6.9% growth. Although, the growth metrics are essential for understanding the results achieved in the broad economy, improved metrics should be applied towards the quality and conditions of life for citizens throughout India while comparing prosperity inequality.

Reading economic statistics without political or sociological factors becomes irrelevant. International trade agreements are often examined between capital and trade statistics, but in reality they are dominated by corporate lobbying and geopolitical powers behind the scenes calling into question results and assumptions.

Economists frequently discuss marginal propensity and disposable income elasticity, but in reality labour laws, union suppression and offshore workforce capabilities determine the wages paid to local employees. India like other Western countries, judges economic growth via headline statistics, without explaining the qualitative factors that determine a nation’s prosperity.

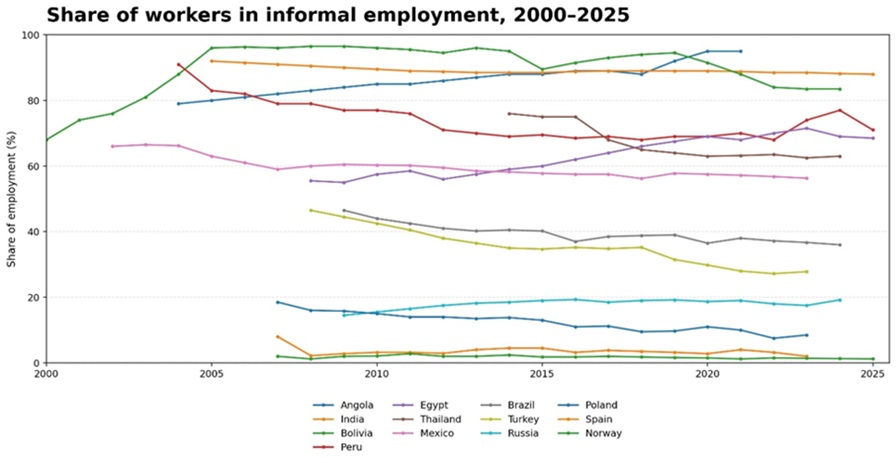
Share of Informal Employment Comparison 2005 – 2025

Human development concerns via good housing, better roads, access to quality education for every child, and secure hospitalization in government run facilities are not covered in GDP data. India calculates GDP data with a production and expenditure approach. Meaning the production of goods and services in a given time must match the underlying expenditures of the overall economy. Since the Indian statistical office calculates expenditures from with a limited number of household surveys and proxies, it’s not prudent to conclude that all GDP data is correct.

Some analysts prefer to look at Gross Value Added, GVA, to determine the overall value created by the nation’s producers. However, this data observes the organized sector via corporate filings, GST (Good and Services Tax) data, industrial production indices, but leaves the contribution of India’s vast unorganized employment sector in the dark.

Informality in the Job Sector

Over the last few years, non-farm jobs which are crucial for diversifying the economy and providing stability are not growing as needed. The formal job sector which offers security, benefits and fair wages is also stagnant. This lack of job creation is pushing more people into unpaid or informal work (the latter constitutes around 90% of the work force) where people struggle to make ends meet.

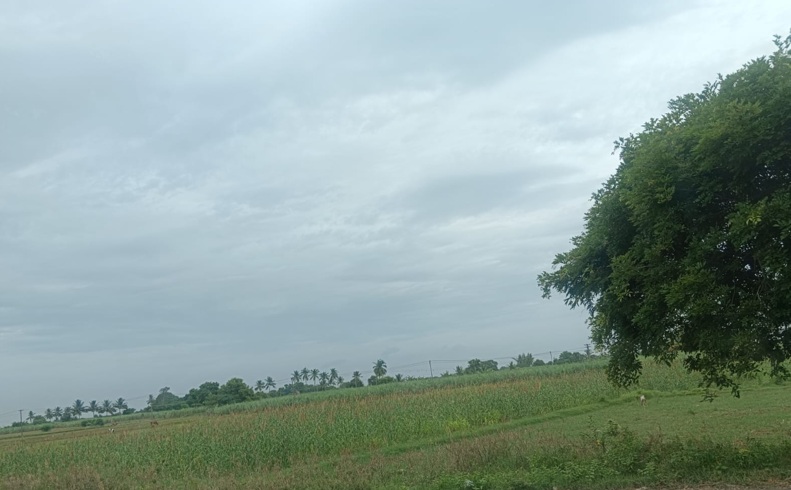
Kallakurichi District in Tamil Nadu State

The National Statistical Office ( NSO) under the Ministry of Statistics and Programme Implementation (MoSPI), performs periodic labour force studies, including household consumption and annual questionnaires of the unorganized sector, but they are sample based surveys and taken only as a proxy due to a lack of available data.

However, these sample based household surveys allow observations of the unorganized sector via snap shots. The agricultural sector traditionally seen as a last resort for employment in rural areas, witnessed a resurgence after the Covid-19 pandemic. Unbelievably, about 80 million people rejoined this sector (including women in rural areas who had exited agriculture jobs after 2004, as a periodic labour force quarterly survey shows) between mid 2020 and mid 2024. This increase in employment continued into 2025, not because of farm growth and modernization, but due to stagnation in the industrial and services sectors.

India’s major challenge in the coming decade is to create enough adequate non-farm jobs in order to accommodate new entrants and for those who are want to leave agricultural employment. Meanwhile, India has one of the lowest rates of work participation of women in the world. Yet, some studies argue that there is a close link between the female labour force participation rate and manufacturing employment. To help GDP growth rates move qualitatively upwards, India must absorb more women from farm work and into manufacturing.

Population size matters and because of India’s large numbers if rising labour productivity is accomplished the nation will not only continue to become one of the largest economies, but will have the the capacity to influence the world’s GDP growth rate positively. The impact of one policy (for instance to promote economic growth) on another (i.e: income poverty reduction) crucially depends on the level of a third variable like the improvement of human capital via better skills, knowledge and health. In other words, growth will be more successful in reducing income poverty if economic value is well developed and more equitably distributed for individuals.

Increasing the capabilities for those who want to be employed and form the base of a country would facilitate the creation of improved formal jobs, labour productivity and real wages. However, the reality is complex. During the Covid-19 pandemic and in its aftermath workers who had earlier left agriculture for better earnings in the first half of the noughties shifted back to agriculture instead of moving to more productive or formal jobs in non-farm activities. In other words, India has seen an odd reversal of structured change that normally characterizes economic development.

Education for the Entire Population

The only upward mobility for Indians predominately is to educate their children, so that they can get comfortable jobs and lift their families out of poverty. For decades especially after the post independence period, India’s higher education remained an elusive dream for millions of historically marginalized people from Schedule Tribes, Schedule Castes and many struggling communities. 

Unfortunately, the gates of universities and colleges were mainly opened to only privileged students belonging to the upper caste elites. Young ST or Dalit students in remote villages faced layers of disadvantages regarding poor schooling – including financial strains, social stigmas, etc. This is in contrast to students from the privileged social groups who often inherited aspirations and the access to higher quality education that comes with an expensive price tag.

While the door for higher education opportunities has been opened for all, it was much wider for those privileged groups, and it remained relatively narrower for the marginalized communities. As the data suggests, In 2023-2024, only about 6.8% of STs and 8.6% of SCs aged 24 and above had attained education up to the graduation level and above, while 12.5% from the OBCs and a striking 23% “others category attained the same”. This hierarchy pattern suggests that STs are the most disadvantaged, followed by SCs, and then OBCs with others at the top, suggesting structural barriers based on caste and historical exclusion.

Aspirations and Sustainable Quality Growth

With a large segment of population stuck in informal or low skilled work, their purchasing power remains soft, weakening aggregate demand. India doesn’t value GDP using an income based approach, because of the same informality. Therefore the failure to ensure equitable access to higher education does not simply reflect social injustice, it also directly weakens India’s growth aspirations, inclusiveness and sustainability. 

Inequality in classrooms today becomes inequality in income tomorrow and eventually a drag on the nation’s economic growth. Instead of rejoicing over the quarter to quarter GDP growth comparing to last year, India must sincerely look into real problems that need to be solved and use its demographic dividend to create better results for all. A sociological and political lens is important to devise policies and strategies for next decade’s growth.

Copy and paste the text from AMT that you want to share

Share:
Indian Rupee 20260826

India Insider: Rupee’s Prolonged Weakness Remains Unresolved

Better Streamlined Government Policy Needed for the Rupee

In July of this year Reserve Bank of India Governor Sanjay Malhotra talked to Business Line magazine and argued that recent Rupee depreciation does not reflect any weakness in the country’s economic fundamentals. According to him, pressure on the currency has largely stemmed from geopolitical tensions, USD strength  and broader volatility across emerging markets.

However, the USD which strengthened during the outset of the US-Iran war has been losing value in large chunks in the broad Forex market the past month. The U.S Federal Reserve remains neutral regarding its interest rate guidance and U.S labor market data has emerged weaker. On top of that, the U.S Treasury’s decision to intervene in U.S long-term bonds via buybacks in order to cool yields has hastened another USD path lower, while igniting buying in many other currencies and gold.

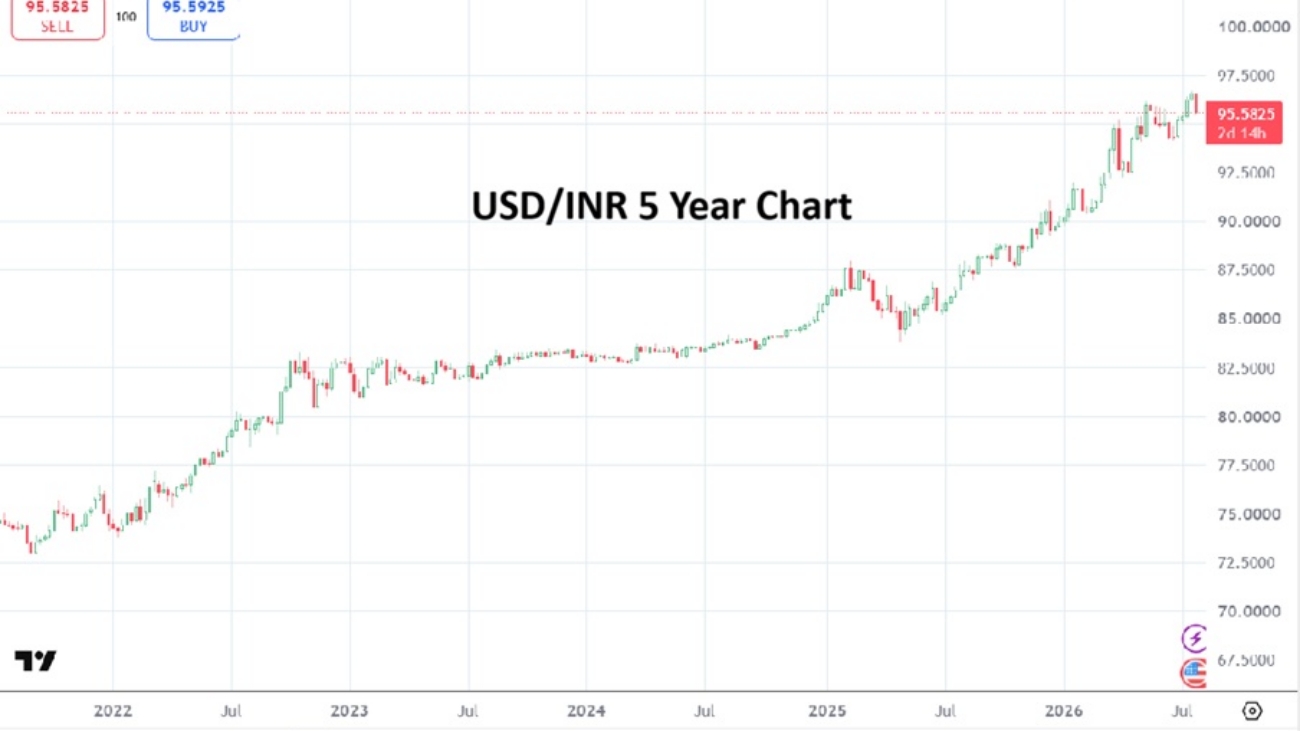
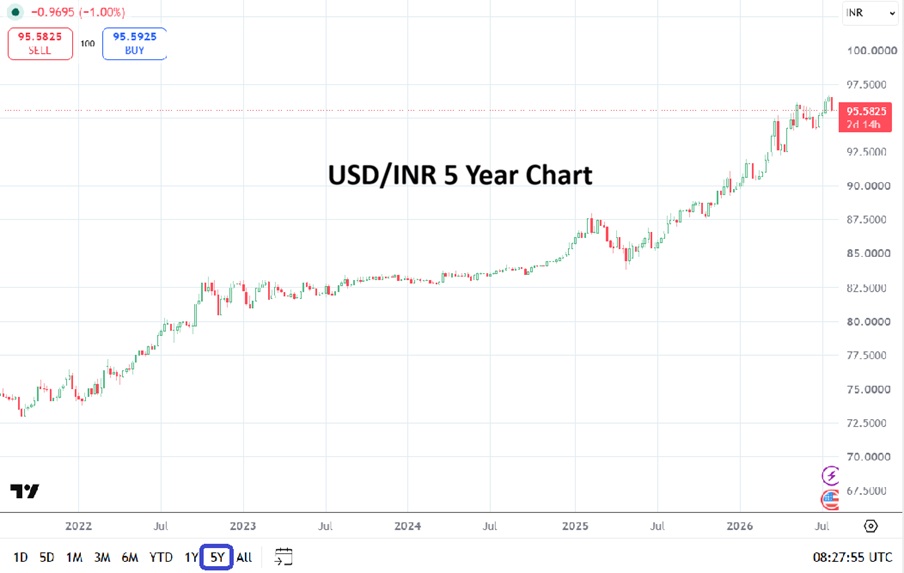
USD/INR Five Year Chart as of 26 August 2026

Despite the Foreign Currency Non-Resident (Bank) deposits coming from overseas investors increasing, which are leveraged products structured by banks and helped to attract more than $50 Billion USD since June, the Rupee’s reaction to this set of recent inflows has been muted. The Indian Rupee is traversing near 95.55 levels as of this writing, notably as other Asian currencies like Korean Won and Singapore Dollar are trading at stronger levels.

India’s Forex reserves climbed to $716.9 billion boosted by these inflows, along with USD related external borrowings by corporate and commercial banks. Nevertheless, the fundamental problems for the Rupee’s prolonged weakness remains unresolved.

Reasons for Rupee’s Weakness Structurally

The Indian Rupee has depreciated around 28% against USD since 2022. Irrespective of this, the merchandise tradable exports have been stagnant, rising a mere 5.7% – from $417 billion to $441.8 billion USD. While on the other hand, merchandise imports have risen 26% from $610 billion to $774.80 billion USD in the period between 2021-2025.

However, India’s balance of payments is not at immediate risk, because even as higher importing needs (especially with Crude Oil and LNG) and lower tradable exports, the total merchandise deficit of around $350 billion USD as of 2025 is being offset by healthy IT exports and foreign remittances.

The fundamental question is why hasn’t the Indian Rupee depreciation expanded merchandise exports in the last few years? As Carlos Dias Alejandro depicts in his seminal work Exchange-rates Devaluations in a Semi-industrialized Country: The Experience of Argentina 1955-1961, throughout Argentina’s history rural producers who supplied most of the exported commodities traditionally advocated a policy of devaluation.

Argentine exporters expected Peso prices for their outputs to rise faster than the Peso prices for their imports, including the wages that they paid for their employees in current prices. In other words, exporters stand to gain from a currency devaluation because it can make their products more competitive in global markets and encourage resources to move towards export production.

Argentina’s experience after Juan Peron who was overthrown in 1955 provides an important context to this argument. The economic policies pursued during the Peron years had already left Argentina with serious inflation , weak agricultural incentives, low investment and balance of payments pressures. The devaluation and stabilization policies that followed were therefore part of a broader attempt to correct the distortions that had built up during the previous period.

Interestingly, the Rupee depreciation has so far not shifted resources from producing goods for foreign products as it is apparently clear via merchandise trade data. The IT sector has been one of the few sectors that has been able to use this shift positively.

It is also important to understand that devaluation does not produce only positive outcomes. A devaluation that increases the overall level of prices can cause a redistribution of income among different social groups, in much the same way as inflation does in a closed economy. Unwieldy redistribution becomes inevitable when the prices of outputs and inputs do not change proportionally.

For instance, wages are central to this process. If prices of food, fuel and other essential goods rise quickly after a devaluation, but nominal wages adjust slowly, workers experience a decline in real wages and purchasing power. Their incomes may remain unchanged in Rupee terms, yet they can afford fewer goods and services. This effectively transfers income from wage earners to firms and producers whose prices or profits adjust more rapidly.

The impact can also differ across workers. Employees in organized sectors may negotiate higher wages or receive inflation linked adjustments, while informal workers, agricultural laborers and those dependent on fixed incomes often have less bargaining power and face a sharper fall in real earnings. At the same time, exporters may benefit if the prices of their products rise faster than their wage and other input costs.

However, if workers eventually demand compensation for the higher cost of living, wage increases can raise production costs and reduce part of the initial competitiveness gained through devaluation. Thus the effect of devaluation depends not only on the exchange rate, bit also on how quickly wages, prices and productivity respond.

In that sense, Argentina’s experience in the 1950s offers a warning for semi industrialized countries like India. A devaluation of the Rupee can make some exports competitive, but it cannot create more productive capacity on its own. Without addressing deeper structural problems, a weaker currency can instead push up prices and reduce households real purchasing power.

Rupee Effects Absorbed and Felt by Those Who Earn Low Wages

Prices of goods and services have increased in the last few years due to the depreciation of the Rupee, especially for imported goods. Since India not only imports oil and gas for consumption, but also imports machinery and intermediate goods for production it has forced households to spend a higher share of their income on the consumption of needed goods.

When households do not earn they need to borrow or hope that their wages increase. In India real wages don’t always go up with inflation. This is due to India having a higher supply of available labor which makes negotiating for higher wages difficult for workers. If employers can find another worker relatively easily as a replacement, the employed worker has limited power.

The ILO (International Labor Organization) notes that India remains characterized by extensive informality and low pay employment, it also estimates that 62 million workers earn below the minimum wage. India’s workers are not necessarily competing in the global market. Manufacturing as a percent of GDP has stayed around 15% over a decade. And irrespective of the fact that India is a major agricultural producer and exporting nation and over 46% of its labor force engages in the sector, total Agri-Exports stayed within a band of $48-$53 billion for the last few years.

The government says that India is growing because services as a percent of GDP is 55%, but the nation employs around one-third of the labor force in the informal economy. While IT employees earn higher wages comparatively because their wages are connected with global demand and have an advantage because they are export services, those who work in construction, domestic help, shops, agriculture and the service sector are earning substantially less. The wages of these people won’t go up until changes are made. 

The vast numbers and informality of employment within a significant amount of India’s labor force prevents low wage costs from translating into solid competitiveness, particularly as inflation is seen and depreciation of the INR continues. Economies like China, Vietnam and Korea have created industrial strength by transferring household savings through lower costs for goods and subsidizing businesses.

India’s decade long reluctance to invest in necessary infrastructure, not preventing or fixing regulatory problems, a lack of commitment to invest in skill based education, and not creating conditions for businesses to compete with overseas markets have created conditions that result in low consumption and low wages. The devaluation of the INR hits households who are acting as shock absorbers in the absence of streamlined government policy.

Copy and paste the text from AMT that you want to share

Share:
Indian Rupee 20260729

India Insider: Real Story Behind the Rupee’s Weakness

Change of Policy Could Create a Stronger INR

RBI Governor Sanjay Malhotra says, Rupee depreciation doesn’t reflect weaknesses in the underlying economy. He says that the external factors due to geopolitical tensions induced by oil prices rising has created a Dollar demand and created Rupee weakness. 

While it’s true the Rupee has depreciated because of foreign capital fleeing and oil importers’ persistent demand for USD when buying oil and gas, this doesn’t answer the entire issue regarding INR vulnerability.

Questions surrounding the Rupee’s weakness should also focus on fundamental causes for depreciation. For instance, the Rupee has largely depreciated the past 5 years from 2021 – from 74.50 per Dollar – and into 2026, where its trading around 95.72 per the USD/INR now. Why?

USD/INR Five Year Chart as of 29 July 2026

Nominal depreciation has been 28%, and this is despite service exports growing healthier, and remittances flows that have been good in the last few years. Can the RBI governor say anything related to it?

Why Does the Rupee Remain Weak?

Economists point to the widening gap between India’s foreign inflows and outflows as a structural flaw that’s weighed on the Rupee and growth. A reason for this is India’s struggle to attract long-term capital through Foreign Direct Investment. Net FDI has declined from $28 billion in 2022-23 year to just $7.7 billion in the financial year that ended in March.

Foreign multinationals, venture capitalists and private equity titans have been taking advantage of high valuations to cash out. Despite recent pro-business reforms by Narendra Modi’s government, India’s shabby infrastructure and a bureaucracy that reduces Byzantium schemes to shame, puts off new arrivals. This is also a reason why tradable exports are not growing compared to India’s vast import needs. India’s exchange rate remains relatively overvalued, even though in purchasing power parity (PPP) terms, Indian products are inexpensive compared with those of the United States.

India could have allowed the Rupee to reflect it’s underlying market fundamentals in order to make it’s exports more competitive and restore external balance. Given the high supply of skilled India’s labor force and opportunities in small and medium scale businesses, especially in agricultural value added products where India holds competitive advantages, it’s not impossible to improve tradable export volumes. Instead, the Reserve Bank of India went in the opposite direction by managing the Rupee at 83/USD and made it overvalued, especially when Shaktikanda Das was the Governor of RBI.

If the RBI truly believes in India’s economic fundamentals story, then why did it intervene aggressively during the 2023-2024 period? Critics argued these known interventions may also have had the effect of supporting India’s GDP when measured in USD, although the RBI maintains that its objective was to reduce excessive volatility and preserve financial stability.

Even with respect to headline GDP growth numbers, many economists in India and around the world still believe that Indian statistical numbers overstate the actual strength of the underlying economy. To generate better growth data in India, the government has expanded it capital expenditures to compensate against relatively weak private investment. However, creating jobs and opportunities for linkages – opportunities in sector related industries, and enhancing India’s trade competitiveness via high value exports are important and urgent, rather than depending on foreign capital flows. In this regard, private capital expenditures still need to increase substantially.

Relying on short term capital flows for managing the current account deficit is a difficult strategy. Even if the RBI believes a de-escalation in the US and Iran War will occur, and believes that global liquidity conditions will allow the RBI to accumulate higher Forex reserves, risks remain skewed negatively to the upside without meaningful changes to improve long-term net Foreign Direct Investment.

David Lubin of Chatham House argues that countries should not rely only on high Forex reserves to protect themselves from volatile capital flows. The best strategy in his view is to reduce the potential problems at its source by discouraging unstable, short term inflows, and ensuring banks do not accumulate excessive foreign currency risks.

However, this is exactly what India is doing by mobilizing leveraged foreign currency deposits from non-resident Indian’s and offering hedging for these inflows until September 2026. Reserve Bank of India Governor Malhotra has stated that the RBI has attracted around $32 billion worth of USD inflows via this route.

Arguably, another side of the equation should be examined. If central banks were to accumulate FX reserves for the sake of paying for their imports, without meaningful reforms in their own economy and not creating conditions for capital to be deposited long-term, no capital controls can ably solve the underlying deficits or surplus nature for those respective economies.

In India capital account surplus has created deficits because the net Foreign Direct Investment has been weak resulting in funding costs for transactions in current accounts to increase. Apparently, this dilemma goes beyond the RBI balance sheet capabilities and exposes flaws in the fundamental reality of economic internal policies. The ensuing crisis hits the Rupee faster as capital leaves and damages the exchange rate.

Copy and paste the text from AMT that you want to share

Share:
Troll

India Insider: A Giant Bureaucracy Needs an Urgent Reset

Paperwork Cyclones and Slow Pace Confront Indian Citizens and Corporate Investment

Almost every single day Indians are confronted by massive bureaucratic problems when they have to approach the government for basic services. When this will change?

For example if you apply for an Aadhaar card (which is used for proof of identity and address in India), birth certificate or ration card (used primarily for getting subsidized groceries in government run stores), or want an electricity connection or passport, you have to move through a myriad of unnecessary bureaucracy in many government offices.

Recently, I went to renew my passport which was authorized and overseen in a regional passport office in Tiruchirappalli of the Tamil Nadu State. To my astonishment, there were no single chairs or any other type of sitting amenities for visitors carrying their applications. Visitors had to sit down on the floor outside the passport office.

India Insider: A Giant Bureaucracy Needs an Urgent Reset

Also applicants inside the premises had no access to office drinking water or restroom facilities. And the waiting hours were too long. The authorities there treat people like teachers treating students, making normal people wonder why they have to apply for their  passports by undergoing this giant bureaucracy as if it were a psychology test of some sort. Many people pour their anger and frustrations onto online forums complaining about the mistreatment.

Some of these people likely wondered how India despite showcasing it can send satellites to space and the Chandrayaan to the moon, doesn’t seem to have a stable, nor easier services for the day to day needs of the people regarding government affairs.

The government may argue that due to large numbers of people constantly applying for various forms and certificates, and a lack of adequate staff, things are more than a little complex in many overburdened government departments. But the fact the government seems to miss and a critical point people are driven to anger about, is that the nation collect taxes from its citizens to insure adequate services which are not fulfilled comfortably in most cases.

Indian citizens are not applying empty handed for a passport and expecting charity or miracles from the government, rather they pay an accepted fee to the passport office. Thus, it’s the duty of the government bureaucracies to be held accountable.

In government run local panchayats (rural government assemblies), there is always rampant corruption. An example can be given regarding the simple renewing of a business license. Corruption is a common thing. Vishalini (name changed) told me that she had to pay a 5000 Rupees fee ($51 USD) in 2019 in order to bribe a local panchayat to get her father’s death certificate

Imagine what would happen if some officers from the government or its employees, went to a restaurant and they were treated badly and charged $20 instead of $2 for a Dosa or Vada Pav. Would they silently pay the bill with cash not resisting, or would they fight back and ask questions?

As a former Forex broker working in the Indian financial markets and servicing retail clients, I have witnessed how this bureaucracy has worked. In April 2024, the authorities simply banned the exchange traded currency derivatives market that allowed retail speculators, small scale exporters and importers to hedge their exposure, wagering on the direction of the Rupee against 4 currencies – the EUR, GBP, Yen and USD. Many clients lost money, because they couldn’t sell at the available market price and some of the trades were liquidated by brokers’ risk management systems when the directive was put into force. The authorities neither compensated, nor took responsibility for these actions. The government action was decisive and swift.

Almost everyone in India knows that we have ‘missed the boat’ by making small manufacturing detrimentally hard due to red tape, poor infrastructure and giant bureaucracy. Free enterprise and entrepreneurship create innovation, less government intervention and greater economic freedom could allow small scale manufacturing to flourish.

Not Only Indian Citizens Suffer, So Do Investors

India has huge gaps to fill, but even if someone injects capital for an infrastructure project, makes money, and is creating jobs, there are still many things to be done about the burden of bureaucracy. The results of government inefficiency and corruption also creates hurdles and disadvantages for investors who would like to participate in India’s growth story with much needed foreign money.

India’s enormous bureaucracy needs urgent improvement and progress in order to facilitate and revitalize its approval system to receive Aadhaar cards, marriage certificates and even death certificate in a more timely manner. Everything can and should be digitized, so people don’t have to wait in long cues to verify or get new documents.  

A lack of effective and transparent services in government offices have to be dealt with effectively. Standards need to be created, upheld and checked on regularly, a host of problems need to be eradicated. Indian citizens would benefit.

India is a current account deficit country and it needs foreign direct capital to help finance its deficit. Investment opportunities need to be made easier for financial institutions abroad to facilitate capital inflows into India so it is less reliant on its own domestic borrowing and savings. Weak frameworks and institutional voids create problems. For India to reverse the weakened foreign direct investment being demonstrated and attract meaningful capital, fundamental changes need to take place, we cannot rely on mere hope for more favorable diversification cycles from abroad. With better policies implemented by the government, India can attract global investment funds easier and help foster improvements for all.

Copy and paste the text from AMT that you want to share

Nifty 50 20260708

India Insider: Foreign Investors and Their Selective Choices

Return of Global Investors into the Indian Marketplace

Global investors are gradually returning to Indian assets after months of persistent outflows as risk appetite sentiment has been ignited by an extended ceasefire between the U.S and Iran. Energy prices have moved in India’s favor, sparking favorable conditions. 

Despite recent flare ups in the Strait of Hormuz, Brent Crude has dropped about 30% in the past quarter, easing India’s fuel concerns as the world’s third largest Crude Oil buyer. AI trade rotation is gathering pace in Asia also, this as investors pull money from chipmakers that powered this year’s rally and hunt for cheaper ways to deploy their cash.

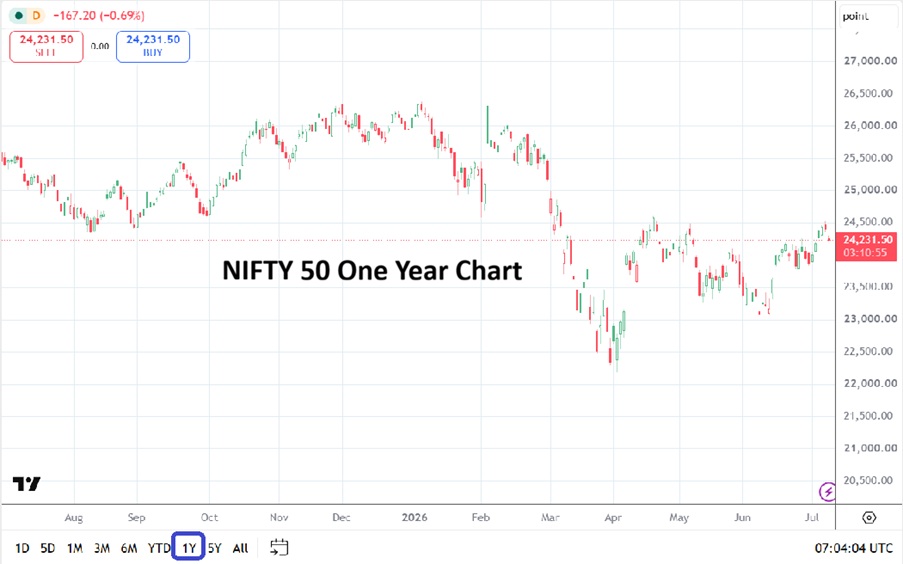
NIFTY 50 One Year Chart as of 8th of July 2026

Indian equities beat its emerging markets peers in June by its biggest margin in seven months. The Reserve Bank of India’s measures to attract foreign currency deposits and overseas capital have eased funding concerns for lenders, record foreign inflows into government bonds have helped stabilize the Rupee and improve liquidity conditions. According to Bloomberg, “Goldman Sachs favors 30-Year government bonds as lower oil prices allay inflation and fiscal risks”. 

Combined with resilient credit growth and improving asset quality, India’s banking sector is once again attracting global investors, this after trading at meaningful discounts to historical valuations for quite a while.

Second Opportunity May Be Information Technology

Indian IT companies have undergone a sharp valuation correction over the past two years. Unlike the post pandemic period, when large Indian technology firms traded at substantial premiums to global peers such as Accenture. These premiums have now narrowed considerably after earnings growth slowed, and enthusiasm surrounding Artificial Intelligence shifted investor attention towards US technology companies.

As highlighted in Business Line magazine, the sector is undergoing a healthy valuation reset, with investors increasingly questioning whether premium valuations remain justified without a corresponding acceleration in earnings growth.

However, the discussion extends beyond valuations. Artificial Intelligence is fundamentally reshaping the enterprise software industry. For decades, Software as a Service (SaaS) companies dominated enterprise technology by offering standardized cloud based solutions that were cheaper and easier than developing software in-house. That advantage is now beginning to erode.

Large AI companies such as OpenAI and Anthropic are building AI agents capable of operating across multiple enterprise applications through a single conversational interface. Rather than competing within individual software categories, these horizontal AI platforms could reduce the importance of stand alone enterprise applications by seamlessly connecting them. At the same time, AI native startups are targeting specialized business functions, while advances in generative AI are encouraging enterprises to revisit the traditional ‘build versus buy’ decision as they develop customized software internally at significantly lower costs.

For Indian IT services companies, this represents both a disruption and a new opportunity. Routine application development and maintenance may become increasingly automated, placing pressure on traditional outsourcing revenues. Yet demand for AI integration, cloud migration, cybersecurity, enterprise transformation, and customised AI deployment is likely to create an entirely new investment cycle. The winners will be firms that evolve from conventional software service providers into strategic AI implementation partners.

Risks ahead for Indian Markets

The near term outlook is not without risks for India. A weak monsoon could push food inflation higher. Elevated Crude Oil prices may widen India’s external balances. And a stronger USD with elevated U.S interest rate yields could moderate foreign capital inflows. The technology sector also faces a structural challenge as Artificial Intelligence reshapes the traditional software business model, requiring companies to adapt more quickly than in previous technology cycles.

Even so, the broader macro backdrop appears to be improving. Policy measures have eased liquidity conditions, corporate balance sheets remain healthy, and valuations across several sectors have become considerably more attractive after an extended correction. Rather than chasing expensive momentum trades elsewhere in emerging markets, global investors may increasingly look toward Indian sectors where fundamentals are strengthening while expectations remain relatively subdued.

Copy and paste the text from AMT that you want to share

Nifty 50 20260626

India Insider: Systematic Investment Plan Boom

Liquidity, Valuations and the Limits of Domestic Capital

India’s equity market has surprised many investors over the past two years. Despite persistent foreign institutional investor selling, weak net foreign direct investment (FDI), subdued private capital expenditures and a depreciating Rupee, the broader markets have not fallen and proven remarkably resilient. But risks abound.

Many observers point to the rapid growth of Systematic Investment Plans (SIPs), which millions of retail investors invest regularly via mutual funds in India. Monthly SIP inflows into the Indian equity market has reached record highs at the tune of 32,087 Crore Rupees ($3.38 billion USD) in March, 2026 per AMFI (Association of Mutual Funds India) data. 

Nifty 50 Five Year Chart as of 26th June 2026

Before COVID-19, the stock market industry in India was a boring business. Accounts were opened via paperwork, and demat (the account in which the digital shares were held) in a bureaucratic manner with multiple paperwork requirements. Clients who liked to participate in the Initial Public Offerings (IPOs) had to go to their broker or issue a cheque to participate in the bidding process. As of 2019, the total demat accounts in India stood at 40 million. Sophisticated retail investors would go to their local branches of associated brokers and trade stocks, derivatives or commodities. They sometimes would use telephone or online orders.

All this changed during the Covid-19 pandemic, when equity market valuations became depressed and people were forced to stay at home. This ushered a wave of new retail traders who had time to master the game and wanted to capitalize on the falling valuations of many companies and take advantage of opportunities they believed in. Astonishingly, demat accounts opened between 2020-2026 totaled around 180 million, almost quadrupling pre-Covid levels. Due to digital penetration and the rise of discount brokers, young retail traders were able to quickly allocate substantial portions of their monthly income into SIPs.

SIPS have strengthened the financial market resilience of India, compared to the previous decade when it was the domestic institutional investors who helped market stability. Yet concerns are now arising whether domestic household savings are supporting fundamentally stronger companies, or are creating systematic inflows which help tenuous companies to have higher valuations?

For instance, a famous financial markets journalist recently argued that India’s SIP boom has fueled expensive stocks. Thus, enabling insiders and institutions to exit at favorable prices, reduced future return potential, has weakened the Rupee, and exposed the limitations of crowd-driven investing.

As the AMT India Insider columnist, I decided to investigate these considerations and talked with some people in the financial markets who offered different perspectives regarding the issue.

Mr. Mahalingam, an IIM alumnus noted, “it is difficult to generalize like that. Total SIP inflows should be viewed relative to the total market capitalization of listed companies, not in absolute terms. If the Nifty delivers around 12% returns, it roughly doubles every six years. SIP inflows must also increase over time, simply to purchase the same proportion of shares.”

Arguably, the SIP flows into the Nifty Index some 15 years back are not comparable to today. Considering the higher capitalization of Nifty listed companies (which means greater share values), and given the Nifty index has delivered 12% returns in the last few years, and that it took 6 years for it to double at this rate, it’s important that investors look at higher share prices values arising out of company earnings while considering their investment decisions.

Mr. Prasath, who taught economics and finance to students during his tenure at a private educational institution, argues, “I think there are many dimensions. In stock markets, everything comes down to valuations, the continuous SIP flows may diminish future returns if the earnings don’t grow. But comparing SIP flow with 2005 numbers exaggerates the issue. The Indian economy has grown bigger since 2005 and naturally inflows will also grow accordingly. India has one of the lowest public participation in the capital markets, even with current SIP numbers.”

Mr. Prasath continued, “currently the world is going through turbulent times with the Russia-Ukraine war, the Trump Presidency including tariff actions, the Iran situation and energy crisis, and supply chain disruptions, etc., which are effecting economic growth. The Indian government is also not taking some required steps. Indian companies also have low R&D and failed to participate in emerging themes like AI and semiconductor development. These turbulent times will continue for awhile and Indian markets will underperform its peers. So we have to wait for better times or for world leaders to come to their senses. I think we have to remain both optimistic/realistic and plan our investments accordingly”

If India grows at 7.7% during the 2025-2026 annual year, and foreign capital (especially foreign portfolio investment) is leaving, while private capital expenditures are weak and government capital expenditures are increasing, then what’s the point of higher stock prices for many of these companies? Is it due to steady retail SIP inflows? Does it really help institutions and insiders to cash out, and make retail investors vulnerable?  Foreign investors have sold $29 billion USD worth of equities so far this year, and the Rupee has taken a hit, yet we have not see drastic changes in companies’ share or indices values.

In 2022, when the U.S Federal Reserve was raising interest rates, the Nifty 50 Index lost around 3000 points, but this did not happen in 2026. The SIP retail crowd and domestic institutional investors have absorbed the foreign investors’ outflows and provided a cushion for share prices.

Even if some people in the financial markets argue that the foreign investors’ selloff off did not result in poor corporate performance or themes becoming weak, given that the growing market capitalization and the past earnings has justified the higher share prices, it’s significant to note that the Net FDI remains weak. Indian and foreign corporations are repatriating cash at a faster pace, and capital is flowing out of India. That’s ironically what hit the Rupee this year, along with higher oil prices due to the Iran war. In my opinion, private capital expenditures of listed corporations has to grow to justify higher earnings multiples.

Kotak Mahindra Bank director Paritosh Kashyap, while talking to Business Line said that private capital expenditures in India has been subdued for the last 10 years. Higher interest rates, expensive oil and lower equity valuations has dampened sentiment. India’s government Capex (capital expenditure strategy) remains the primary driver.

To summarize and conclude, weak foreign direct investment, subdued private investment, and inflated valuations of Indian assets along with a lack of AI related development is a large underlying issue and concern. For foreign investors to return with greater force again into Indian equities, either the Rupee has to depreciate or equity prices have to decline to generate investor confidence and create an appealing landscape. Retail investors may soon have to face drawdowns in their portfolios as returns dwindle and headwinds move against them.0

Copy and paste the text from AMT that you want to share

Indian Rupee 20260611

India Insider: Should the RBI Raise Interest Rates?

A Case for Higher Interest Rates In India

As the Rupee remains under pressure and oil prices continue to rise amid tensions in the Middle East, the debate has shifted towards what the Reserve Bank of India (RBI) should do next.

Economist Janak Raj has argued that raising interest rates to defend the Rupee comes with significant costs. Higher rates increase the cost of capital for businesses, reduce investment activity, and compress equity valuations. In theory, this could even accelerate foreign outflows from equities rather than attract fresh capital. Yet the RBI may soon find itself with limited options.

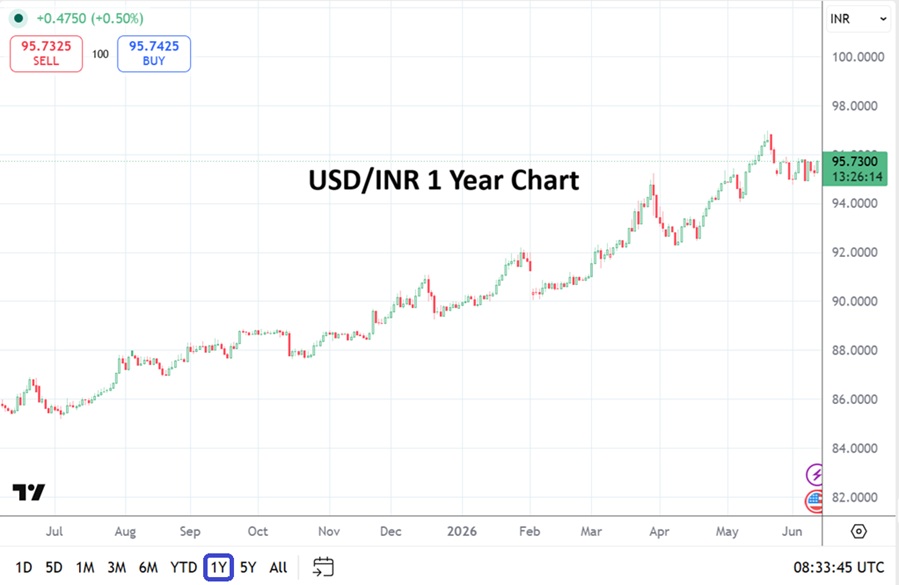
USD/INR One Year Chart as of 11th of June 2026

Foreign Portfolio Investors (FPIs) were net buyers of Indian equities for most of the period between 2004 and 2024, with only a few exceptions such as 2011, 2018 and 2022. However, the trend has changed. FPIs sold approximately $19 billion USD worth of Indian equities in 2025 and another $24 billion USD so far in 2026.

Question: Why are Foreign Investors Selling

One reason is that global investors today have alternatives. The growth of Artificial Intelligence related companies in the United States has created significant investment opportunities. At the same time, U.S Treasury yields hovering around 4.6% offer attractive risk-free returns in a strengthening dollar environment.

For many global investors, earning high returns in Dollar assets is preferable to taking exposure in emerging markets that face current account pressures from rising  Crude Oil prices and other energy costs.

Taxation is another factor. India taxes foreign investors at 20% on short-term capital gains and 12.5% on long-term gains. Meanwhile, competing financial centres such as Singapore, Hong Kong, Malaysia and Thailand generally do not tax foreign investors’ capital gains.

Some global funds have argued that India should move closer to international norms, where capital gains are usually taxed in the investor’s home jurisdiction rather than the country where the investment is made. Higher post-tax returns would undoubtedly make Indian assets more attractive.

A stable Rupee would also reduce hedging costs, lower currency-risk premiums and improve the overall risk-reward profile for overseas investors. However, tax cuts alone cannot solve India’s problem.

The Real Issue is Balance of Payments

As Business Line columnist Lokeshwari Mam has pointed out, a significant portion of equity outflows consists of short-term speculative capital. Long-term capital tends to remain invested. This is why the decline in net Foreign Direct Investment (FDI) should concern policymakers more than short-term fluctuations in portfolio flows.

Net FDI has fallen sharply from $28 billion in FY 2022-23 to just $7.7 billion in the year ended March 2026. This is a worrying trend because FDI is the most stable source of external financing. Unlike portfolio flows, it creates factories, jobs, exports and long-term productive capacity.

India therefore needs more than tax incentives. A genuine single window clearance system, reduced bureaucracy, easier business regulations and reforms in manufacturing remain essential. Attracting long-term capital should be a national priority.

The recent foreign buying of Indian bonds after tax cuts is encouraging. But relative to India’s current account financing requirements, it remains a small drop in the ocean.

For example, in FY 2025, the current account deficit was 0.6% of GDP. And in Q4, the current account became a surplus. Is it really that difficult to finance it’s small current account deficit?

India’s external vulnerability is determined not merely by a current account deficit, but by whether the capital account can be comfortably financed. A modest current account deficit still creates currency pressure if foreign capital inflows weaken (which we are seeing), while a larger deficit may be sustainable when capital inflows remain strong. The risk of sustained higher oil prices could widen the deficit, increasing India’s dependence on foreign capital at a time when global liquidity is tightening and U.S Treasury yields are rising.

Furthermore, hedging costs continue to erode much of the yield advantage that Indian bonds offer over U.S Treasuries. In that sense, active global money is likely to prefer Dollar assets over emerging-market debt or equities

India’s repo rate currently stands at 5.25%. The RBI’s decision to raise its inflation forecast to 5.1%, while lowering its GDP growth projection to 6.6% reveals where the shock from the Iran conflict is likely to be felt via higher inflation and weaker growth. For an economy that remains heavily dependent on imported oil, a depreciating Rupee only compounds the problem by increasing the cost of energy imports. 

In such an environment, the Monetary Policy Committee is unlikely to focus solely on growth. Currency stability, inflation expectations and the availability of foreign capital to finance India’s external requirements could become increasingly important considerations. If these pressures persist, the RBI should raise the repo rate, in the same manner other Asian central banks have done in recent weeks.

Copy and paste the text from AMT that you want to share