US Dollar Index 20261103

Elections and Nervous Global Markets

U.S Mid-Term Elections, Anxious Investors, Risks and Potential Collisions

U.S mid-term elections will be held today. Wall Street has turned in anxious results recently and USD centric price action remains relatively strong. South Africa holds municipal elections tomorrow on the 4th of November with implications for the USD/ZAR.

The VIX index (Volatility S&P 500 Options) results have nudged upwards incrementally in recent trading. Still far below the March and early April highs, the index nevertheless has shown increased nervousness among investors. 

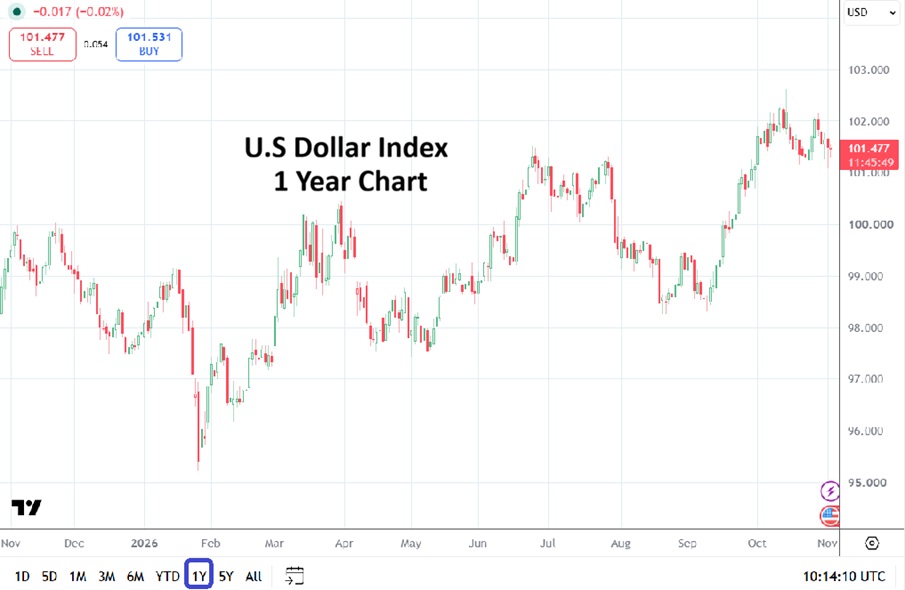
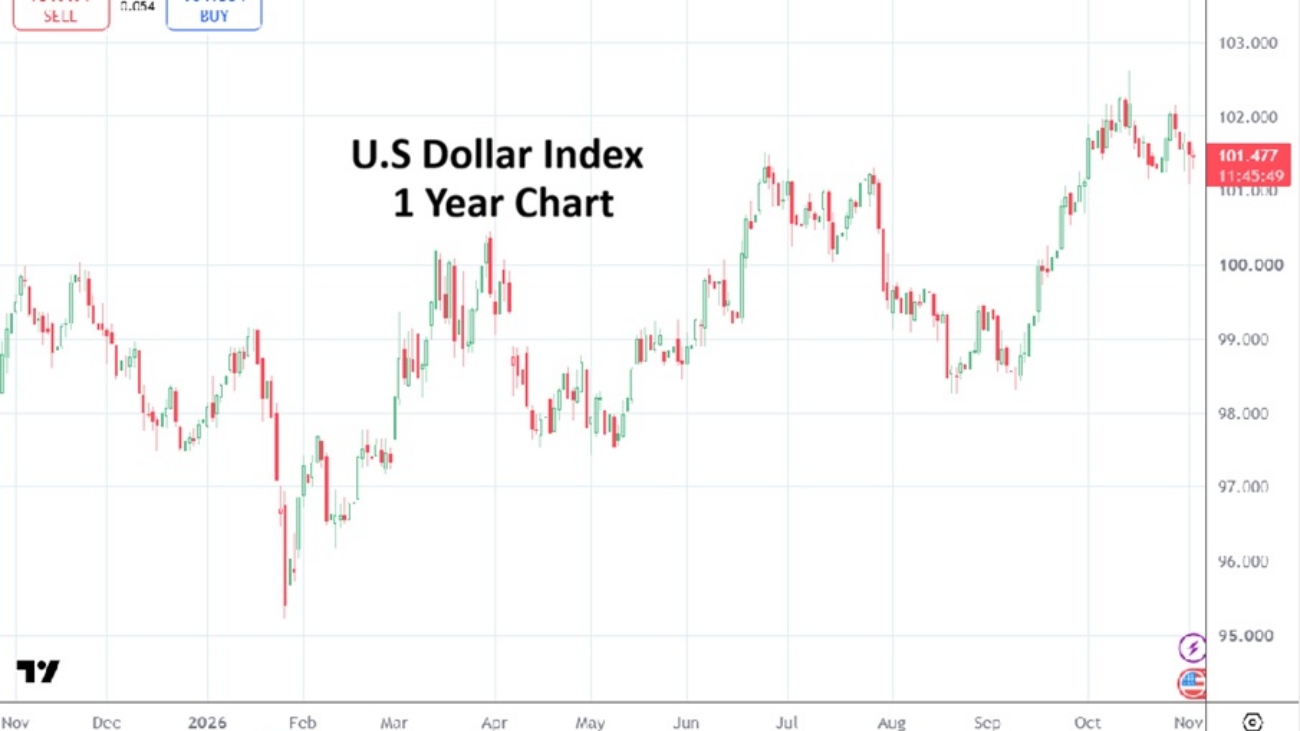
U.S Dollar Index One Year Chart as of 3rd of November 2026

Prevailing sentiment regarding the U.S elections appears to indicate the Congress may become divided per its leadership. A potential Democratic party win of the House of Representatives and a slim majority held by the Republican in the U.S Senate would not be a surprising outcome. A divided Congress could set the table for a rise in angry rhetorical political stances from the U.S and a confrontational White House led by President Trump.

No matter the outcome presenting itself tomorrow, Wall Street should be watched for reactions. Global investors will continue to be also largely swayed by Middle East storylines and supply of energy and its effect on inflation. The U.S Federal Reserve remains in the thoughts of all investors regarding its interest rate policy. A general lack of clarity still persists, along with worries about over-inflated equity values shadowing companies with exposure to AI and the costs of infrastructure via analysts narrative.

In South Africa, municipal elections will be held on Wednesday. The outcome of the Johannesburg mayoral race should be watched by investors who have interest in the nation. Since the national elections held on the 29th of May 2024, which produced a government coalition led by the ANC sharing some power with the Democratic Alliance and other parties – the South African Rand has performed better – gaining strength against the USD. 

If tomorrow’s Johannesburg voting results produce an optimistic result showing that political power is still shifting towards more transparency and shared power this could inject another dose of positive force into the ZAR. However, until the municipal voting results our known sometime on Thursday, the USD/ZAR should be treated cautiously by day traders. And speculators should note South African banks will be largely shuttered on Wednesday limiting USD/ZAR volume.

Other important features for traders coming up will be the Bank of England’s Monetary Policy Summary on Thursday and expected hike of 0.25 basis points to the Official Bank Rate. The GBP/USD is near 1.34100 as of this writing.

On Friday the U.S will release its Non-Farm Employment Change numbers, but this data may not have a gigantic effect on sentiment taking into consideration that today’s Congressional Elections will amplify existing sentiment the remainder of this week depending on the outcomes.

Copy and paste the text from AMT that you want to share

Share:
Gold forecast 20261028

AMT Commodities Corner: The Fed, Energy Inflation, Forex, Gold, Politics and Coffee

The Need for Confident Sounding Policy From Fed Chair Kevin Warsh

Forgive me please if the following appears to be a vacuum trying to suck a complex web of risk events and their effects on the speculative nature of commodities and Forex. Yet, the state of the world means that technical and fundamentals are clashing significantly and it would be foolish to make believe influences do not exists. Today the Federal Reserve will deliver its FOMC Statement (and the word statement is emphasized because no interest rate hike is expected). 

However, considering the surprise delivered from Brazil via its election results on Sunday and reactions in the Ibovespa and USD/BRL afterwards, it might be wise too brace for the potential of additional dynamics. But I do not want to digress, because price action and velocity are natural parts of the financial world and in fact act as a barometer regarding how economic and political outlooks are converging.

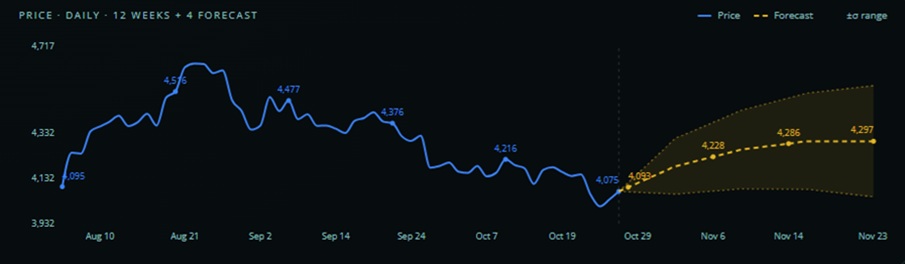
Gold Price as of 28th October and Viridian Commodity Forecast

Fed Chairman Kevin Warsh remains under a bright light. He didn’t exactly take the helm of the U.S central bank in the most tranquil of times. Thus, it is difficult to blame him quite yet for the mess and quandary the Federal Reserve finds itself trying to navigate. Energy costs remain high and will so for the foreseeable future. The Iran war looks a long way from being solved in the coming month (‘months’ may be the more appropriate word choice), although saber-rattling and outright military escalation may in fact be coming sooner rather than later. This depending on President Trump and his loud threats and ability to follow up on his rhetoric and negotiation methods, and or the ability of the Iranian and all other factions converging on a compromise (which doesn’t looking forthcoming). 

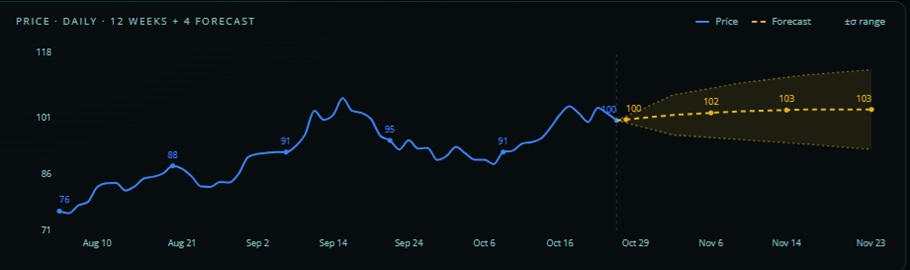
Meaning if WTI Crude Oil remains at its current price levels over $100.00 consistently, this as war drums bang it will not be a surprise. According to Viridian Commodity Intelligence based on shipping and supply and other logical predictions which factor in higher prices as as caution reigns, support levels in the Crude Oil sector will likely remain durable until an end game is reached with results large players feel comfortable within – including nations – and good luck trying to achieve this type of solution folks. Which brings us back to Fed Chairman Kevin Warsh and other FOMC officials who understand inflation is being caused by geo-political upheavals creating higher energy costs. There is little the Fed can do to fight expensive fuel costs and the effect on logistics, manufacturing and agriculture remains a losing game until a conclusion of the Iranian quagmire is attained. 

WTI Crude Oil Price as of 28th October and Viridian Forecast

Thus, even as the Fed has shown no signs of raising interest rates today, the next FOMC decision on the 9th of December will remain under the same storm clouds. The energy situation is not likely to have been fixed by then. Warsh must deliver a determined policy stance and tell the public (and investors) that he remains confident in the U.S economy as it faces inflation caused by energy prices; the economy may be challenged in the mid-term but no additional interest rate hikes are planned. Except for the problem, Kevin Warsh has not expressed this viewpoint forcefully yet – creating USD centric strength in the meantime.

Gold Recovery Coming Or Wishful Biased Thoughts?

A bold Federal Reserve stance would potentially help ease U.S Treasury yields too. The prevailing fragility in equity indices may also press more investors into U.S bonds which would supposedly help yields come down a bit too. And this brings up the specter of gold which is producing a battle for value near the $4,050.00 mark as of this writing and has gone below $4,000.00 recently. Even in the wake of global risk events the price of the precious metal has looked strained (nixing notions of a safe haven momentarily). USD centric price action has created headwinds against gold, along with the elevated U.S Treasury yields. However, support levels have looked reasonably stable near $4000,00 and the price of the commodity appears undervalued from my (possibly gold bug) eyes. 

USD/JPY Implications and Gameplan

Forex will remain tricky short and near-term, particularly for the USD/JPY, as the the Fed makes its rhetoric stance today and the Bank of Japan speaks on Friday. Japanese Yen traders may have taken advantage of oversold conditions which appeared late last week, but retail traders should note that volatility will remain a steady diet as large players speculate and seek additional momentum waves over the next two and half days.

The higher realms of the USD/JPY are not likely to disappear anytime soon. However, retail traders need to be wary of actual interventions from the Bank of Japan in order to counter blind buying of the currency pair by large players and financial houses based on their poor outlooks for the Japanese Yen based on their lack of confidence in BoJ policy.

Coffee Trading and the USD/BRL

From the commodity standpoint both WTI Crude Oil and gold have definite causation and in some sense their trading realms feel as if they are known for speculators who have the ability to tackle risk taking with solid tactics. The same cannot be said exactly for Coffee, which could face complications and shock waves potentially in the coming days and weeks as growers and producers, wholesalers and their large buyers have to deal with the potential of a weakened Brazilian Real. 

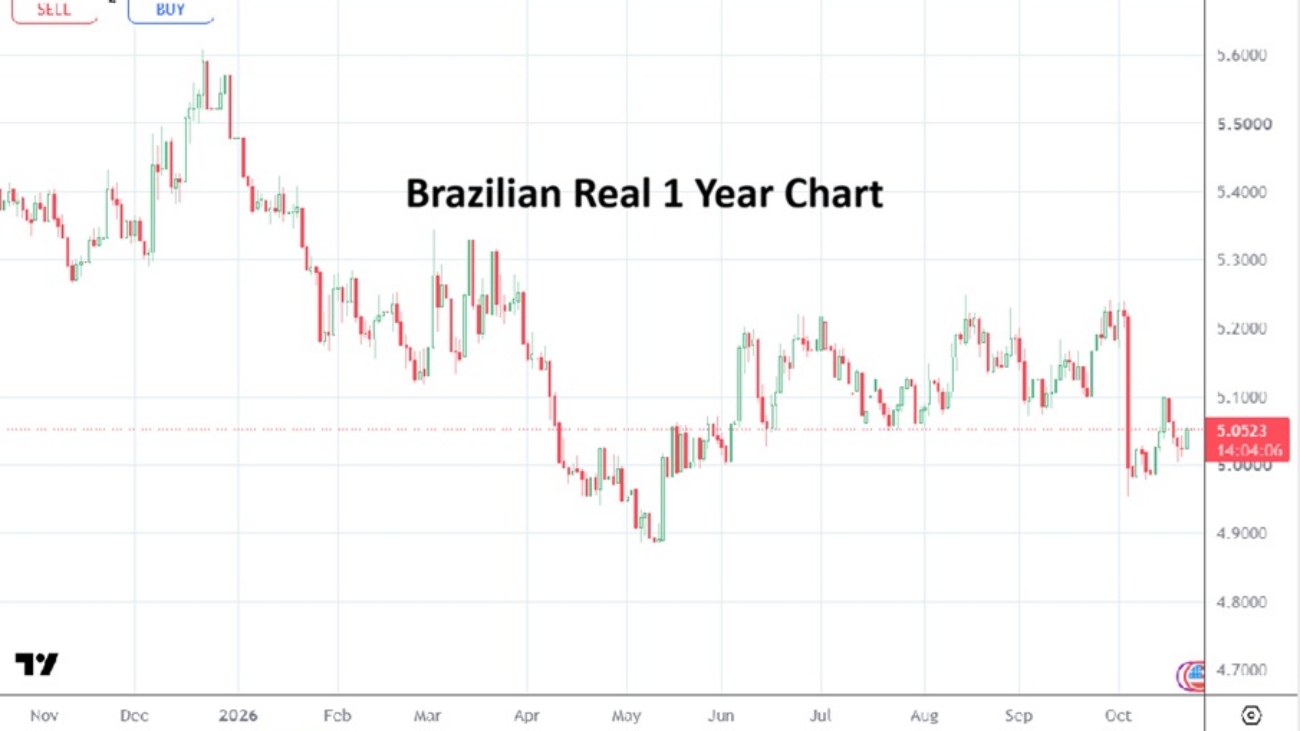
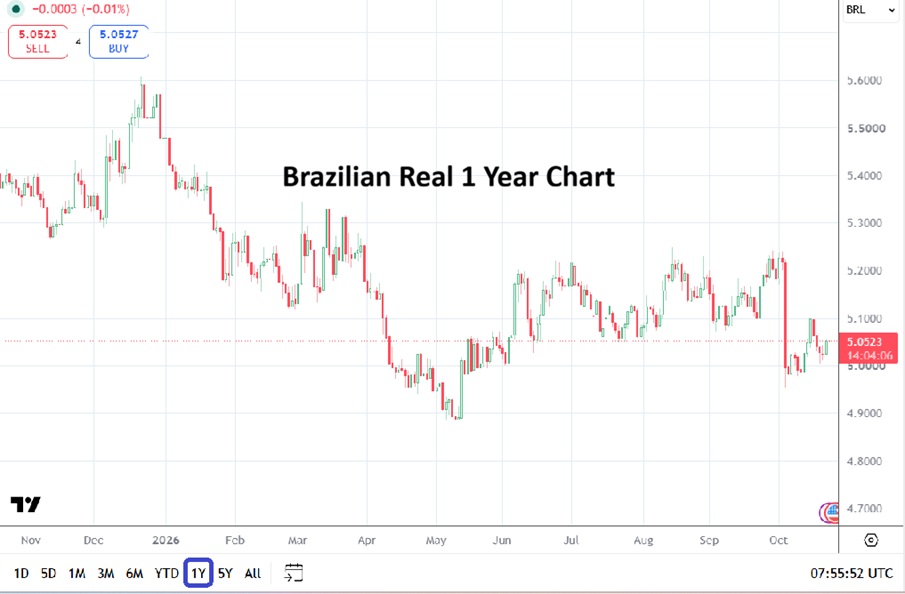
The BRL was trading near 5.0500 in a relatively calm and bearish trend within the USD/BRL into last Friday and all seemed like it would remain tranquil after the weekend. And then came the early Monday surprise (for many – including myself) via results from the Brazilian election in which Lula da Silva won another term as President. The USD/BRL before Forex trading begins today is near 5.3500. Coffee traders may be bracing for some shockwaves if the value of the currency pair doesn’t recover to lower ground in the coming days and week. No Brazil is not the sole producer of Robusta (and Conilon) and Arabica Coffee, but its influence in markets remains important – even if solid supply is known to exists in other global locales.

Copy and paste the text from AMT that you want to share

Share:
Indian Rupee 20261026

India Insider: RBI Considers Higher Interest Rates as Rupee’s Direction Remains Vulnerable

Structural Financial Solutions Needed to Create INR Resilience

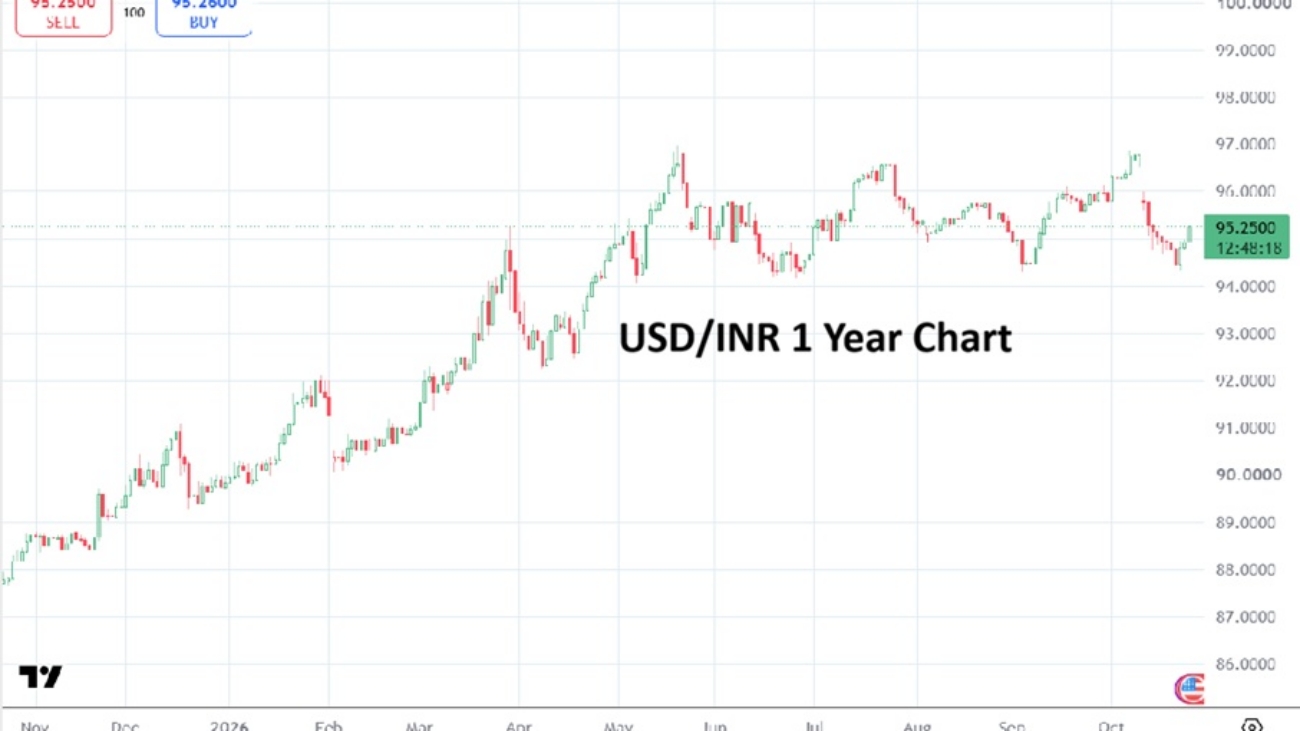
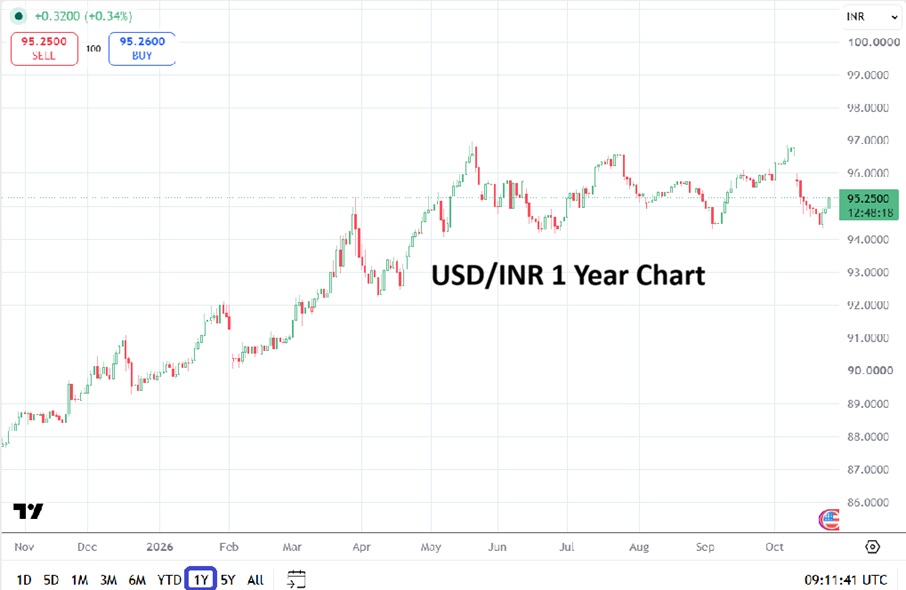
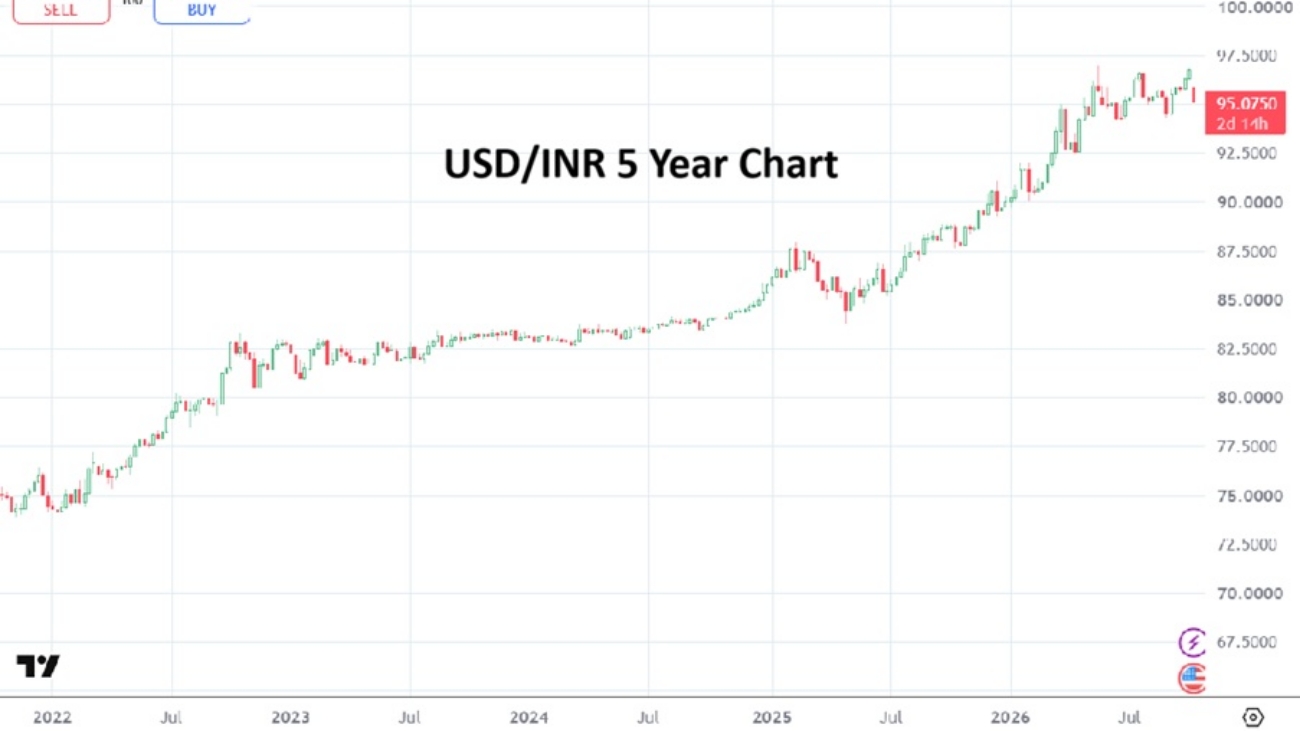
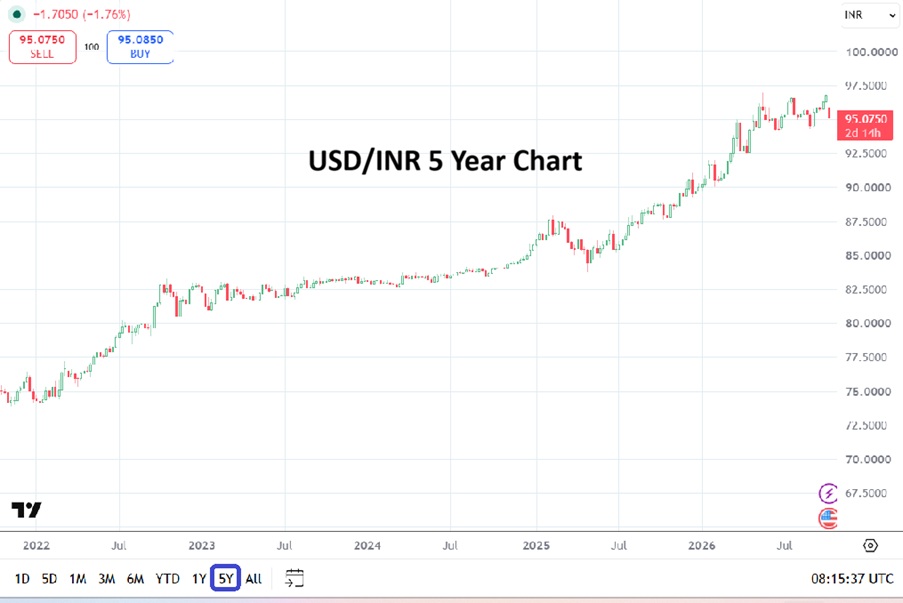
The Indian Rupee has appreciated in the last week, amid escalating tensions in the Middle East and capital outflows from stocks and bonds. The Rupee has gained from 97.00 in early October to a close around 95.20 levels this past Friday. 

The Rupee’s strength also came on the foreign interest delivered from the $3.2 billion USD valued Jio Platforms Ltd. initial public offering. Still, analysts say that any appreciation should be expected to be short lived. The RBI has not used interest rates to manage the Rupee, instead it attracted inflows from Non-Resident Indians (albeit leveraged flows) to manage its balance of payments.

USD/INR One Year Chart as of 26th October 2026

This is despite the fact that Asian and African central banks have used interest rates to manage their currencies. The Philippines has raised rates by 50 bps this past week, and Uganda’s Central Bank hiked by 225 basis points, from 9.75 to 12%, surpassing their 50 basis point jump in 2024 and the 100bp rise in 2022.

The fact is current account deficit countries need foreign capital to finance deficits via international balance of payments, and rising oil prices and volatile capital flows have exacerbated the problem. Recently, the Reserve Bank of India has rolled out measures to curb Dollar demand, including a special window to supply foreign currency to State run oil refiners.

The spot Forex market is where currencies are bought and sold at prevailing exchange rates. The Indian Oil Corp., Bharat Petroleum Ltd. and Hindustan Petroleum Ltd. buy large amounts of USD through banks in the foreign exchange market to pay for Crude Oil imports. Large Dollar purchases can increase demand for USD and put pressure on the Rupee, particularly when Crude Oil prices are high and import payments rise. But with elevated oil prices and foreign outflows persisting, traders are betting the RBI will need to rely more on rate hikes, which tend to push bond prices down and yield higher.

Global central banks are using interest rates as ammunition to fight against USD centric strength as the rising value of the USD via a perceived hawkish Federal Reserve, along with mounting geopolitical tensions like the escalation between Saudi Arabia and Yemeni Houthis cause angst. Brent Crude Oil is now near $110.00 per barrel. This is an alarming consequence for India and other nations that rely upon oil imports. Requirements for India’s Crude Oil supply is around a 88 to 90% dependency.

India’s import bill rose by 47% in September compared to last year, rising from $10.5 billion to 15.4, obviously straining & draining foreign exchange reserves. Yes, spot level prices are inflicting less pain, but USD demand is real.

Angry Meta Traders has written in the past about the challenges of using FCNR (Foreign Currency Non-Resident) deposits, which the Reserve Bank of India has attracted around $135 billion. However, the RBI is being confronted by a mounting and increasingly costly need to defend the Rupee. Deploying tens of billions of dollars and resorting to extraordinary market interventions to protect a currency (the INR) is a costly endeavor.

India’s central bank is reportedly tightening scrutiny of large overseas investments by domestic companies as it seeks to contain capital outflows amid pressure on the Rupee. Many analysts point out that a bad outlook exists as the nation struggles to attract capital, and the risk sentiment remains elevated. As Chris Kay wrote in the Financial Times recently, “ the central bank since June has already used about $90bn of what it raised from India’s diaspora to prop up the Rupee, including through sales to the spot market and currency swaps to absorb surplus liquidity.”

The interest rate hike debate comes as the inflation backdrop is worsening. Consumer price growth accelerated to an almost two year high in September, nearing the top of the RBI’s 2 to 6% tolerance band. A weak monsoon threatens to keep food prices elevated, while the Rupee’s decline could further stoke inflation by making imports more expensive.

India’s 10 Year Bond yields have risen by 26 basis points from 7.21 to 7.47%. Investors are concerned about higher and tightening rates by the Reserve Bank of India, in which the repo rate stands at 5.5% as stubborn inflation and falling real wages also spark concerns.

In the Emerging Markets bond investment space, some financial institutions are picking perceived winners in places like Brazil, Colombia, Malaysia, Thailand, China, Pakistan and Peru. They consider Indonesia, India, Philippines, Turkey, Mexico as losers due to the prevailing global macro sentiment.

What is the RBI is Going to do Short-Term?

Will India attempt a jumbo hike like other nations? This could reduce capital outflows and supposedly reduce depreciation of the Rupee. Or will it try to restrict Indian capital going abroad which would likely choke off growth? Economists from major investment banks argue that India’s primary problem is not weak exports but capital flows.

Per their viewpoints, a drop in Net Foreign Direct Investment has left the Indian Rupee more dependent on volatile portfolio flows as global markets have turned fragile and geopolitical tensions remain legitimate and people and companies seek safety. Ultimately, for pressures on the Rupee to ease, India requires changes in underlying fundamental flows financially which exert tangible structural solutions that are not short-term fixes.

Copy and paste the text from AMT that you want to share

Share:
Israeli Elections 20261025

The Israeli Elections: A Cynic’s View

A Not So Clear Guide For The Perplexed

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 25th of October via The Angry Demagogue.

We have taken a break from writing for a while due to technical reasons combined with way too much work, but it is a good thing our analysis of the Israeli election has waited until everyone has reverted to his natural attacks. As the only right of center reporter in the establishment and the only reporter in the country with a sense of humor, Amit Segel has stated – I paraphrase – that after months of thoughtful campaign planning the two camps have decided that what they have done for the past two decades is what they will continue to do: Anyone But Bibi on one side and Bibi or Palestine on the other.

The Israeli Elections: A Cynic’s View 

The Bibi camp has at least had success with their cliché while the anti-Bibi camp seems to think what didn’t work the previous dozen times will certainly work this time.

We would love to say this is left vs right, but since almost no one has stated what their policies will be that is difficult to do. The Likud is trying to scare us into voting for them because everyone else is “pro-Palestine” while the opposition candidates want change for the sake of change.

Gadi Eisenkot, the alleged leading opposition candidate has two main campaign billboards that tell us nothing and give us no reason to vote for him. The first is “This time – Eisenkot”, emphasizing that the last time it was Gantz, the time before that Lapid and the time before that Herzog, etc, etc. Why, “this time – Eisenkot” we are not told. The other big billboard is “Eisenkot – for change”. Now the opposition has emphasized one thing – we are not them and we need to change. The problem is that they have not said what they want to change besides personalities.

Naftali Bennett and Avigdor Leiberman, the two other pretenders to the throne on the opposition are, in their past votes at least, more right wing than the Likud. Bennett was an up and coming challenger to Netanyahu from the right until he made the political error of joining the “anyone but Bibi” camp. Lieberman even resigned as Defense Minister years ago after his scraps with Netanyahu as well as his fight with then IDF Chief of Staff Gadi Eisenkot (yes, the current challenger) accusing him of being the representative of “Peace Now”.

On the government side, Netanyahu is doubling down on his opposition, not to the left but to a right of center party that has promised to support him in the coming Knesset – that is the party called “Amcha Yisrael” (your people, Israel) led by ex-brigadier general Ofer Winter). His number two is an Israeli Christian Arab, Yousef Haddad who is one of the most successful defenders of Israel in the foreign press. Ostensibly, the reason Netanyahu (and his poodle, Smotrich) are giving for their fierce campaign against him is that if he does not pass the minimum amount of votes needed (around 3.25% or 4 seats) then these right wing votes will have gone to waste. However, polls are split – giving Winter anywhere from 3-6 seats so logic would tell you that Netanyahu would encourage those last few to vote for him and get him an extra 4 or more seats in the Knesset.

But those who claim the above don’t really understand Netanyahu the politician (as opposed to Netanyahu the statesman). Netanyahu has three goals in this election and the one you would think is most important is not. A clear victory is his goal, but only on the condition that the other two goals are met. The first of these is that there not be anyone else on the right who is Prime Minister material and the second is that he will be able to continue with the ultra-orthodox Haredi parties and give them what they want regarding the draft (with minor changes). As for the first of these two, Netanyahu has managed to eliminate all those who could replace him as PM on the right and they include, Nir Barkat, Yuli Edelstein, Ayelet Shaked, Gilad Erdan and has sent Bennett to the opposition. Now there are two newcomers. Ofer Winter and Amir Avivi. The latter is the founder of the Israel Defense and Security Forum (IDSF or Bitchonistim in Hebrew) and he was promised a top spot in the Likud Knesset list. He is knowledgeable, serious and has connections abroad making him a possible successor to Netanyahu. Instead of being given a place on the Likud list though, he was promised to be a minister in the next government. Fair enough until you realize that only Members of the Knesset can become Prime Minister, and Netanyahu always fears that the Likud itself will get rid of him and replace him with someone else.

Winter is new to politics, but has been popular on the right since he was a colonel leading his brigade (Givati) in the Tzuk Eitan (Gaza) war in 2014. He then became persona-non-grata on the left for two reasons – he was tactically superior to and more aggressive than the other brigade commanders, and when he spoke to his troops before they went into Gaza in 2014 he mentioned the “God of Israel”. While generals and other commanders have mentioned God to their soldiers for 3,000 years or more, it was taboo in the Israeli general staff which doubles as the country’s defender of progressive values. So Winter is a clear possible successor to Netanyahu (not now – but after a few years of political experience) and Netanyahu is convinced that he will lead for foreseeable future.

It seems that Netanyahu does not fear Eisenkot, Lieberman and Bennet per se, and as none of these three have gone beyond slogans and cliché there is really not much to argue against besides the Eisenkot promise that he will form a minority government with outside support of the Arab parties. That has become the center of the Netanyahu campaign and it is a strong argument which is why the other two opposition party leaders with PM ambitions – Avigdor Lieberman and Naftali Bennett have promised not to support that effort.

On the far left and far right we have opposite sides of the same coin. Itamar Ben-Gvir, who, after four years as head of the police and failing to stop crime stemming from Arab cities and villages is still campaigning to stop crime stemming from Arab cities and villages. Failure does not seem to bother voters as long as he “says the right thing”. The Ben-Gvir of the left, Yair Golan seems to be adopting the global woke left’s agenda by threatening to censor right wing news sites and stations while not having met an anti-Jewish cause he does not support. He runs, as the woke always do as the last defender of “our democracy”. Without endorsing anyone, we will say that a government with neither of these two would be a welcome one.

When all the votes are cast and the quest for power begins in earnest, we will know who is really controlling the candidates. Bennett seems to be more independent than his rivals as he does not come from the security establishment and is independently wealthy. The fear about Eisenkot is that he is a puppet controlled by the Israeli security establishment that has not given up its ideas of appeasement as the way to the “good life” (See anything by Tamir Heyman of the INSS). Leiberman on the other hand has been rumored to be under the thumb of the prosecution – explaining how this man who was considered as right wing as Ben-Gvir is so virulently anti-Netanyahu.

So, what will be?

Only fools can predict an Israeli election. Since we qualify, we will say that no one will know who will be the next prime minister until 4-8 weeks after the election due to all the horse trading and egos. There is no consensus in the opposition as to who is “the one” – in spite of the security establishments efforts to crown Eisenkot so, short of a rout by Eisenkot, the others will not easily give in.

When all is said and done, we feel that Winter and the other new party headed by Yoaz Hendel, a right of center ex-academic and politician who is in the anti-Bibi camp but not a fan of the left at all, will both get in, giving 8-10 seats to those who are against any appeasement of the enemy, who support a more equal draft and who were not involved in October 7 at all. Amit Segel wrote last week that this might be the last election for this generation of “leaders”. If both get in – that might be beginning of the end for the septuagenarians and octogenarians.

Therefore, we predict that after many weeks of back and forth, (55 year old) Naftali Bennett will be the next Prime Minister of Israel.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

Follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

Share:
Brazilian Real 20261023

USD/BRL: Anticipating Brazilian Election Results and a Liberal Party Victory

Flavio Bolsonaro Appears Set to Become the Next President of Brazil

Brazil will conduct the second round of its elections this coming Sunday on the 25th of October. Flavio Bolsonaro is predicted to win the election handily. No second place presidential candidate has ever comeback after the initial vote and beaten the first place finisher in the 2nd round of the direct elections which was implemented in 1989. 

Financial institutions appear to favor a Liberal Party victory over Lula da Silva’s Workers’ Party. If Flavio Bolsonaro wins the vote as expected on Sunday he will have strong coalition powers in the National Congress as a whole, including the upper house Federal Senate with conservative members that is expected to include 45 to 50 approval votes depending on the issue out of 81 collective seats. The USD/BRL closed yesterday’s trading near the 5.0525 vicinity.

USD/BRL One Year Chart as of 23 October 2026

Brazilian Real’s Performance Has Been Solid Since December 2024

The USD/BRL is traversing lower ratios that were challenged momentarily in early August, late July and saw sustained lower action in May of this year with depths touching the 4.9000 area briefly. The Central Bank of Brazil has leadership via Lula da Silva’s choice of Gabriel Galipolo as the Governor who will serve until the 31st of December 2028.

Financial institutions have shown faith in the Brazilian Central Bank as it maintained interest rates and did not succumb to the wishes of many from the Workers Party who had lobbied for a lowering of borrowing costs as inflation ran high. The USD/BRL has performed well since touching highs around 6.2500 in December of 2024. While the USD/BRL has been correlating with the broad Forex market to a degree, reaching the 5.2500 realm on the 1st of October, the Brazilian Real has shown more fortitude than the EUR, GBP and has done better that the South African Rand against the USD the past handful of weeks.

Geo-Political Implications of a Flavio Bolsonaro Victory

Optimism in Brazilian financial institutions regarding a government victory by Flavio Bolsonaro who is seen as pro-business (and certainly is not a socialist) is viewed as a positive by global investors too. The geo-political relationship between Brazil and other nations will be captivating if Bolsonaro wins Sunday’s presidential race. Brazil maintains an enormous trading relationship with China and its membership in BRICS is considered very important. These political relationships should be watched closely.

Brazil’s relationship with South Africa may also be tested quickly as Flavio Bolsonaro imposes a more conservative approach regarding his worldview. Bolsonaro is certainly an ally of President Trump. Brazil’s relationship with the majority of conservative leadership in South America will be dynamic and worth giving attention as it improves. The USD/BRL via behavioral sentiment could find itself testing additional lower values in the coming months. A free enterprise surge from Brazil will create a more vibrant economic landscape in South America, provided corruption is fought and transparency is delivered.

Cautious Global Markets as Optimism Engulfs Brazil

Cautious global investment certainly continues to create problems in equity markets. However, the Ibovespa Index of Brazil has performed exceptionally well the past year, even though it suffered a slight downturn yesterday it remains within sight of all-time highs. The results on the Ibovespa and the USD/BRL considering the predicted election outcome this Sunday will be important for retail traders to monitor.

Speculators need to keep in mind a Liberal Party victory has been factored into the value of both trading assets already, meaning some profit taking could transpire early until additional positive waves of enthusiasm engulf the marketplace…….and then eventually sees euphoria erode back into realistic outlooks and correlations with global mechanisms again.

Paying For Celebrations Via Profit Taking

Traders of the USD/BRL may want to pursue the currency pair in a speculative manner today and early next week, but they need to remain tactical and not allow overly ambitious targets guide their wishful thinking. Bias needs to be eliminated and USD/BRL traders should not indulge in leveraged positions which could get out of hand quickly if sudden sentiment shifts strike via larger players and financial institutions, particularly if they cash out winning positions (this to pay for some victory celebrations should the mood strike). The USD/BRL appears to be in a solid position to continue move lower via positive outlooks for business enterprise in Brazil, but traders should remain realistic and not step out ahead of the parade unless they have deep pockets and can demonstrate patience.

A Gap Higher Amidst Over-Exuberant Retail Trader Ambitions

Early Tuesday’s price action in the USD/BRL did see the 5.0000 realm come into sight, but an upwards wave developed and Thursday’s opening did produce a gap higher which tested values near 5.0575 momentarily. Yes, conditions appear ripe for exuberance to help the Brazilian Real become stronger against the USD, but retail traders need to practice risk management at all times.

Copy and paste the text from AMT that you want to share

Share:
CrudeOil 20261021

AMT Commodities Corner: WTI Crude Oil’s $100.00 Cautious Price Realm

Large Players and Retail Traders Awaiting More Noise in WTI Crude Oil

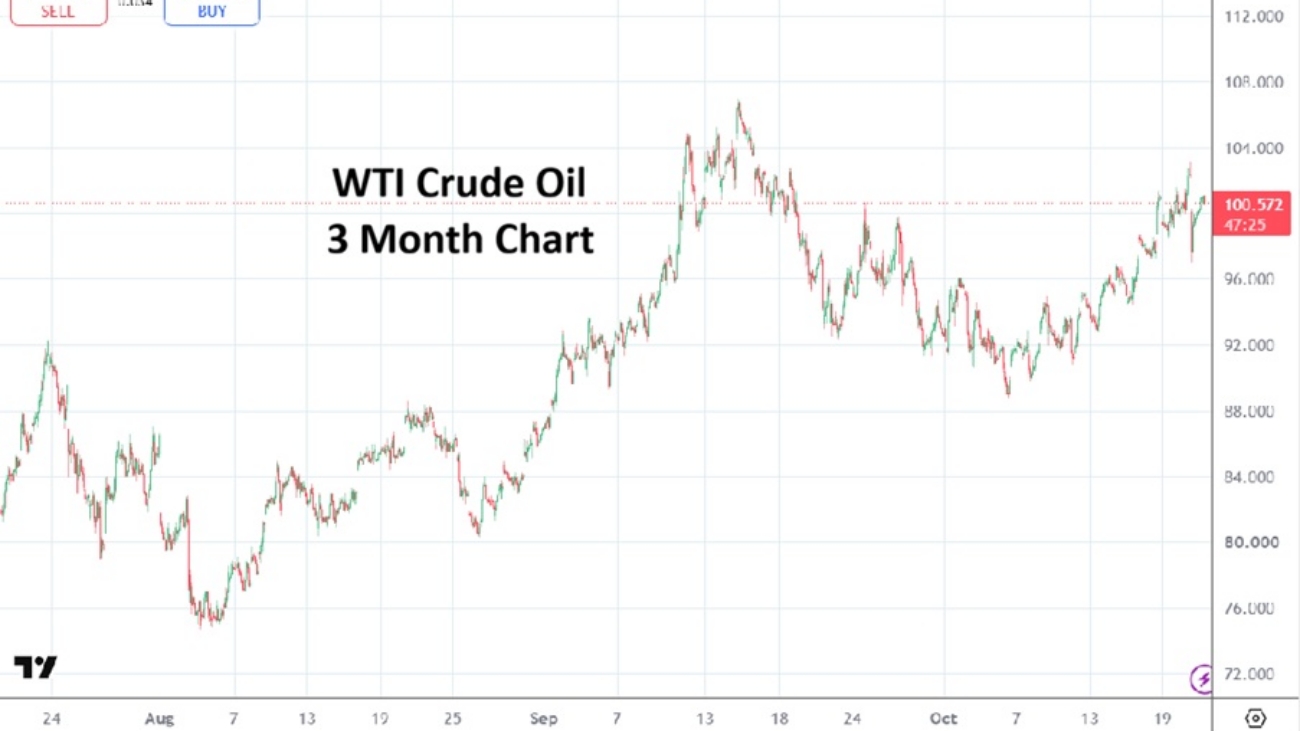
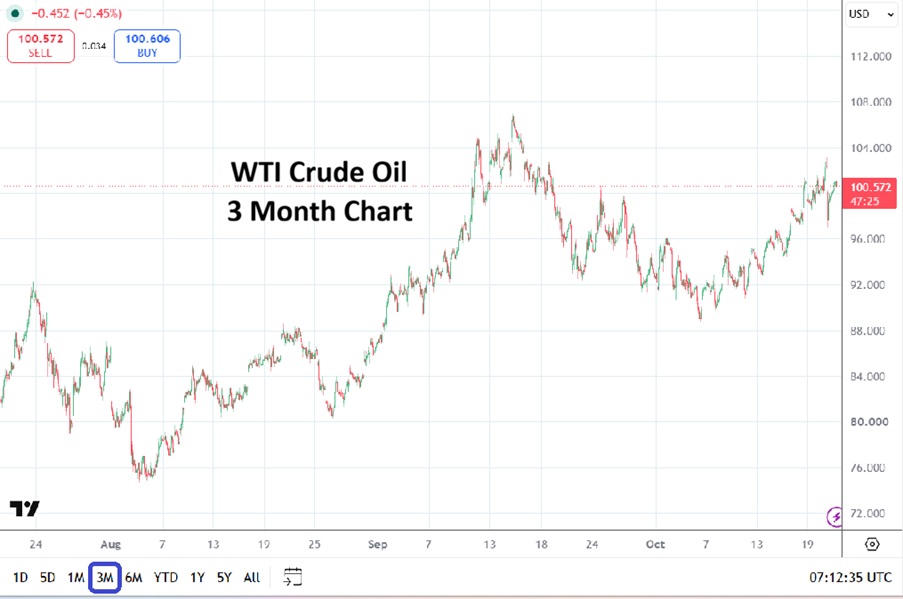
WTI Crude Oil continues to float around the $100.00 mark via cash as a plethora of information and rumors converge into noise that large players and retail traders must distinguish between. The price of the commodity remains seemingly frozen in a higher range that has become almost tight. An air of cautiousness surrounds WTI Crude Oil as nearly all participants brace for additional impetus which will shake value. Near-term wagering considerations appear to be leaning into the potential of negative developments which could ignite more upwards trajectory.

WTI Crude Oil Three Month Chart as of 21st October

Inventory and Transits Confronted by Potential of Military Resumption

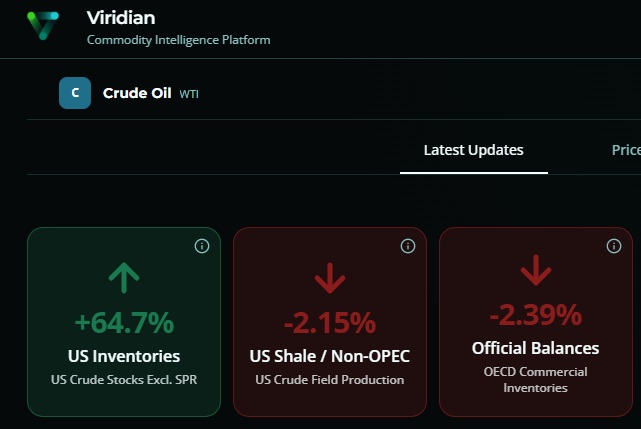
While there is evidence of solid supply coming out of the Hormuz Strait, nervousness surrounding the almost promise like rhetoric of additional military action in the Middle East has the WTI Crude Oil market on a nervous edge. U.S supply of WTI Crude Oil is showing better inventory numbers, however the OECD Commercial Inventory numbers appear to be faltering via information gathered from Viridian Commodities Intelligence.

OECD Commercial Inventories Data via the Viridian Commodity Intelligence on the 21st October

This highlights the assumption that logistics remain challenging to Europe and Asia and are creating higher energy costs globally as ordering remains concerned about delivery. Besides the inventory worries being felt, the anxiousness from the overwhelming shadow being cast over the Middle East regarding a resumption of intense military conflict is certainly supporting durable higher prices. However, the rather well-traversed $100.00 ratio in WTI Crude Oil remains difficult to pursue regarding short-term momentum technically for speculators who are simply trying to profit on a chosen direction.

What If Scenarios and Rhetoric and Threats From the U.S White House

Intraday pricing remains dynamic and retail traders are vulnerable to actions being generated by the constant whirlwinds of behavioral sentiment ambushing WTI Crude Oil. The current price in the cash market near the $100.550 realm must be given respect. While some traders may look at the current price and believe resistance will kick in and push values lower, rhetoric coming from the U.S White House continues to threaten that more military action is being planned for against Iran. Whether this is a negotiating tactic of President Trump to try and make the Iranian leadership capitulate can be debated until we are all blue in the face.

Furthermore, the emergence of Saudi Arabia as a hotspot in the Middle Eastern conflict has grown significantly. The military attacks from the Houthis of Yemen towards and into Saudi Arabia has certainly added to the upwards price in WTI Crude Oil as supply nervousness has turned from thoughts about a potential hazard into an actual realization regarding the consequences of escalation. As WTI traverses its higher values, traders need to understand the sticky inflated realm is factoring a ‘what if’ scenario.

Programed Algo Trading Versus Sentiment Shifts in WTI Crude Oil

With WTI Crude Oil traversing above $100.000 steadily, retail traders who have the ability to react quickly via their ordering skills could take advantage of quick swings in prices technically as support and resistance levels are tested. Yet, the danger of using a stop loss order in WTI Crude Oil has to be thought out wisely, because even as sentiment drives the market it is still being traded by algo systems geared towards values that coders target as saturated levels where they believe orders are congested.

In other words, algo systems will aim for targets until their programed coding has been achieved per momentum shifts. Yesterday’s high above $103.000 was met by a swift reversal lower which took WTI Crude Oil close to $97.000 before kickstarting upwards again. The lower prices were met by a wave of influencers it should be pointed out that exclaimed good news had overtaken the nervous sentiment which has been dominating the energy sector. However, sustained optimism has been and remains in short supply. The positive sounding influencers’ social media posts quickly disappeared.

Coming Elections and Lack of Optimistic Sunshine

Peace could come in our time. Yes, things could go quiet and get serene. However, betting on the emergence of optimistic sunshine shining brightly on the WTI Crude Oil market in the near-term is a far-flung bet. The U.S mid-term elections are on the 3rd of November. 

There should be little doubt in speculators mindsets that rhetoric towards Iran via the U.S White House is going to continue the next week and a half. Threats about the possibility of sudden military action taking place now remains part of the mix too, but because of the U.S election (and Israel’s vote on the 27th of October) it seems unlikely there will be an escalation near-term unless Iran strikes first.

Ultra-Cautious Highs and Fast Moving Price Differentials

Wagering on WTI Crude Oil in the short and near-term should be done with solid emotional fortitude. The commodity continues to move quickly. Price differentials of 5.00 USD in a single day have become almost regular and this means leverage needs to remain conservative, particularly by traders who do not want to use nearby stop losses so they are not kicked out of positions before magic strikes. WTI Crude Oil is going to remain volatile and likely going to sustain its known higher price realm which is ultra-cautious.

Copy and paste the text from AMT that you want to share

Share:
SPCX 20261020

The Markets: Not to be Funny but Many are Confused

Mid-Term Ambivalence Reigns as Major Risk Events Unfold and Await for All Traders

In an effort to lighten the mood of the room let me assure you that most financial analysts feel they are in the dark. Talks with a wide range of investors and large speculators nowadays (at least within my circles) leads to the conclusion that a lack of clarity is becoming a known landscape. 

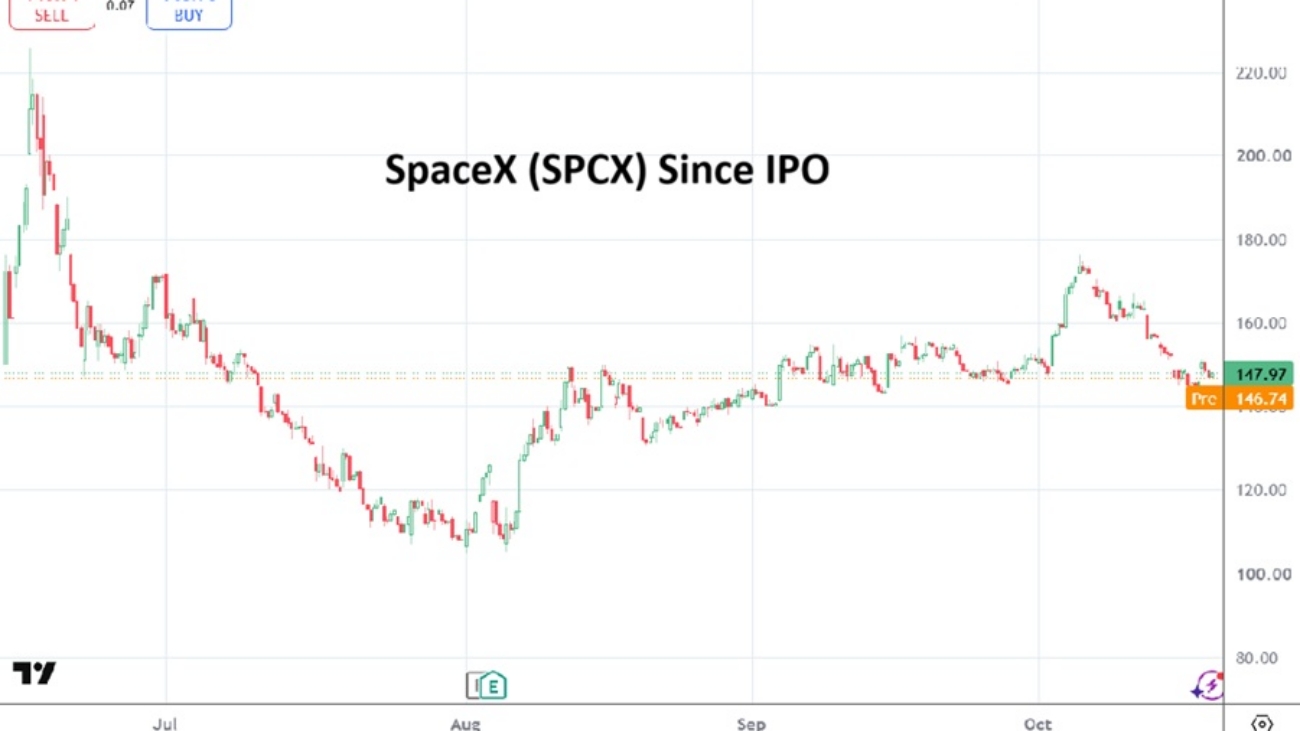
The Federal Reserve will hold conduct its FOMC meetings and rate decision next week. The price of WTI Crude Oil is raging near high water marks. SpaceX is traversing its initial IPO values again. There are major elections on the horizon in Brazil, Israel, the U.S and South Africa which will effect world views starting this weekend and into early November. Some parts of Europe are burning. And the Middle East conflict appears to be on pause, but folks are bracing for a resumption of military noise. 

SpaceX (SPCX) Value Since IPO Chart as of 20th October 2026

Add to the above a U.S President who appears able to change his stance in a moment’s notice without showing any outward signs of remorse is also a feature – one that often leaves other leaders perplexed. Except, that the White House seems primed on trying to keep chaos from entering the economic picture by trying to talk the public (voters and the world) into a stated belief that all will be OK, it will be tremendous, magnificent, better than ever before………and Crude Oil will be valued below $65.00 a barrel when everything is figured out, the U.S economy will remain uniquely strong and Wall Street will be a lovefest. The White House is correct to take a positive approach, but others are free to doubt.

And therein lies the problems, when will all be paradise? Clarity over the mid-term is important for investors who crave the basic necessity of being able to have some type of predictive grasp for the coming six months. Where will interest rates be? What will the price of oil be doing? Will the Iranian situation be cleared up? Will Tesla’s flying roadsters crash back to earth or land right side up? (Tesla announces its 3rd quarter results when Wall Street closes tomorrow btw).

USD centric strength continues to fluster Forex positions. U.S Treasury yields have come off their highs but are still elevated. The hidden costs of infrastructure builds for data centers remains an open nasty secret as revenue concerns are discussed. The Nasdaq 100 lurks near record highs, but at the same time creates fear that not enough momentum is being shown upwards – possibly translating into massive losses to come via some technical mindsets. Some are openly predicting a Wall Street crash. We have seen this show before folks, but it is unclear what path is going to develop. The Cassandras’ of the world do get boring as they proclaim a known script.

Yet we stand at a precipice and better know how to scale the cliff. Inflation via Crude Oil prices that are currently gushing past $100.00 are problematic. But should Fed Chair Kevin Warsh raise interest rates next week to try and fight inflation being caused by a geo-political storm that he has no power over? Saudi Arabia, the Houthis, Iran, the UAE, Israel and many others are seemingly waiting for the mid-term elections in the U.S to take place if you pay attention to the media, but is that what really is going on? Doubtful. There are plans being made outside of our known scopes and we are not allowed to look beyond the curtain.

The Federal Reserve should not raise the Federal Funds Rate next week because of oil price fears and even if its inflation remains sticky for the time being. ‘Should not’ being the key words. The USD should return to a slightly weaker stance, but will this happen as financial institutions brace the potential of cumbersome near-term dramas over the next two weeks? Let’s point out that the price of WTI Crude Oil was slightly lower on the 16th of September, during the last FOMC meeting and decision.

No, I am sorry, I do not have a whirlwind of advice for speculators except to say be careful for the moment. As a trader I knew in the past once told me, reading today’s news means you are reacting to something someone knew a few days beforehand – there is a source, a discussion with a journalist, and then the writing and publication of the article roadmap which we must consider when trying to act on news we are reading for the first time. In other words, someone has already traded on the news you are consuming. 

Social media and influencers are terrific, but they tend to be a day late. Current trading dynamics offer a slightly different problem for the moment, because large institutional investors have likely positioned themselves ahead of the news flow that the public is consuming as they try to venture forth via their own predictions. However, because confusion reigns for the moment, there is a good chance the financial institutions are wrong. Meaning speculators should use their own perceptions and experience to judge the potential dangerous currents flowing. Hoping for the best will not be enough, being prepared for challenging circumstances near-term will help.

Copy and paste the text from AMT that you want to share

Share:
Indian Rupee 20261014

India Insider: RBI’s Rate Hike Cannot Mask Persistent Issues

Supply Chain and Balance of Payment Concerns Remain for the Indian Rupee

The Reserve Bank of India hiked interest rates by 25 basis points recently as inflation has shown signs of becoming entrenched due to higher Crude Oil prices and El Nino effects, and inducing supply side pressures especially in Agri-commodities. The headline inflation rate in India rose to 5.54% in September 2026 from 4.83% in the previous month, the highest reading since October 2024. 

Food costs have been 7.74% higher year-on-year with onion prices jumping 108%, while upwards costs for ginger of 62.9% and garlic at 54.6% have been significantly sharp. Meanwhile, higher Crude Oil prices and a weakening Rupee drove transportation inflation to a 5.01% increase. Surging prices have hit restaurants, accommodations by nearly 9.36%, personal care, and social protection costs by around 13.75%. Month-on-month the Indian CPI rose by 0.69%.

Crude Oil prices remain elevated due to the conflict in the Middle East. India’s position as a net energy importer makes it particularly vulnerable to rising import costs. On top of this, the USD has strengthened partly due to a Federal Reserve rate hike and safe haven (risk averse) flows, contributing also to the depreciation of the Indian Rupee. The Indian energy sector having to spend more USD to purchase resources has exacerbated Rupee depreciation as costs for imports have soared and show an ability to remain stubborn.

Global conditions remain unhelpful and the Middle East conflict shows little chance for immediate solutions. Indian officials within the Reserve Bank of India seemingly have felt they had no other choice to fight inflation and falling exchange values via the USD/INR, except by raising interest rates like other global central banks.

USD/INR Five Year Chart as of 14th October 2026

Robert Petrucci, an astute observer and writer on the Indian Rupee, argues that an interest rate hike to deal with the problem of higher energy costs will not fix the inflation problem caused by the Middle East conflict. In Petrucci’s opinion, even if a central bank has raised interest rates by full basis point of 1%, it would have little effect on the demand of energy as long as prices remain a geo-politically influenced circumstance. 

Robert Petrucci has also said that the decline in value of the Indian Rupee could also stimulate India’s exports of tradable goods making them cheaper for foreign importers. Evidence shows the cumulative value of India’s merchandise exports between April and August of 2026 reached USD 215.91 billion. This is a 17.85% increase compared to the same five month period in 2025, when exports were USD 183.21 billion.

Even as prices for commodities also rise due to El Nino weather effects, this storyline cannot be entirely blamed. Professor Narayana Moorthy wrote recently that in the State of Tamil Nadu the rise in prices of Agri-commodities can also be attributed to shrinking cultivation areas and stagnant irrigation improvement. Tamil Nadu’s inflation rate in May 2026 reached 5.11% against the national average of 3.93% comparatively. Crop prices cannot be controlled simply by raising interest rates, as Robert Petrucci alludes, without boosting domestic agricultural production capabilities.

Balance of Payments Highlights Another Influence

Despite generating higher GDP growth and claims of economic strength India’s balance of payments remains severely weakened by massive capital flight. By the end of June 2026 a staggering 543.9 billion USD combined had left India, comprised of 316.1 billion in direct investment outflows, 23.4 billion into portfolio funding, and 204.4 billion into other outward stakes. As Professors Jayati Ghosh and C.P. Chandrasekar have written in a recent BusinessLine article, “for a lower middle income country, with most of its development projects incomplete and greatly in need for additional investments, the extent of capital outflows is quite large. It significantly reduces the net inflows that economies in India’s position require for development.”

Economist Michal Kalecki observed in Poland in early twentieth century, capitalists invest only in when they accumulate profits, no matter whether it stimulates wages or reduces unemployment. In that sense, according to Kalecki, the changes in the prices of goods or wages or household demand would not entice a capitalist other than making a profit. They are there to make profits and want to see accumulated retained earnings on balance sheets. If mass consumption is not sufficient enough for their goods and services, investments would channel or divert into other premium products or markets that command higher profits.

Investments, as Kalecki observed via his practical business experience, are not decided by household demand but by businesses decisions that ultimately influence employment and national income. In that sense Kalecki never argued that investment is independent of demand, his thesis is that the capitalists as a class are protected even in a slump, as they would invest in resources that maximize their profits. According to him, investment was not simply a function of interest rates or consumer expectations. It was connected to profitability, income distribution and the contradictions of accumulation. It literally means, any rise in prices of goods and services due to a depreciating currency or supply chain induced inflation would be passed to consumers as we have seen in the last few years, even as real wages are not growing and become unbearable for households.

What India needs is patient capital that funds infrastructure and development, creates jobs, along with some government allocated capital expenditures, rather than capital that solely chases returns or deviates quickly once returns are achieved. By showing the government can provide long-term commitment allowing low return assets that stimulate household demand, this could make private investments profitable in future rounds.

In planned economies like the failed former Soviet Union, authorities frequently forced investments rates up without genuine profitability or consumption orientation. Capital was often misallocated, funds were dispersed via corruption and outright theft. Accountability was certainly not transparent.

Kalecki reminds us that economic stability cannot be separated from the question of whose interests it serves. A key component is ultimately developing increasingly sophisticated techniques for stabilizing capitalism and understanding why capitalism requires continuous stabilization.

A rise in interest rates may help reduce consumer demand in some areas, but money naturally chases allocations which earn ‘best’ returns. This is highlighted by businesses and financial markets where capital outflows seek profits and do not protect the Indian Rupee. Support for the INR provided by Non-Resident Indians inflows that has helped build the FX Reserves recently cannot be relied upon alone to fix the weakened Indian Rupee problem alone, nor can ‘simple’ fixes like the recent quarter of a point interest rate hike by the Reserve Bank of India. A coordinated and tactical policy is needed.

Copy and paste the text from AMT that you want to share

Share:
Nifty 50 20261004

India Insider: From Farms to Factories An Unfinished Productivity Transition

Striving to Make India the Best Version of Itself

Many East Asian economies in the last three decades have prospered because of large allocations using massive State subsidies to chosen sectors and respective industries via affordable credit while keeping interest rates at bare minimums. Wages were and remain suppressed to make industrialization possible through a transfer of savings from households to businesses – to help manufacturing thrive.

This has helped China and other East Asian Tiger nations to compete head to head with Western economies with fortified industries. Globalization also extended this phenomenon. Western economies offshored a lot manufacturing to countries that produced competitive goods to keep their corporate costs low – including wages, this while the majority of Western nations also shifted towards service sectors and consumption to generate solid performing GDPs.

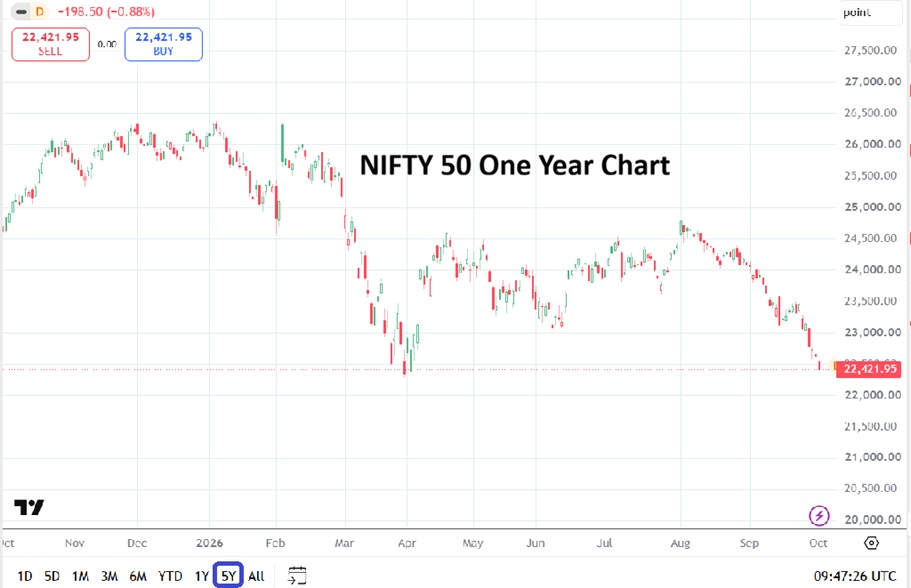
Nifty 50 One Year Chart as of 4th October 2026

This system ran extraordinarily well the last two decades, until trade deficits in the Western economies ignited agitation amongst citizens and inside the government offices of policymakers from Brussels to Washington. In order to create jobs for their own people and protect their legacy industries from losses, countries are increasingly discussing protectionism, illegal immigration, and restricting access on critical technologies.

Irrespective of the tranquility and results in the past, this after the Latin American and Asian financial crises caused by the abrupt policy shifts. Changes to the free flow of capital and trade have shown they can disrupt exporting based economies faster than many governments could handle the challenging circumstances appropriately.

India is one of the nations’ standing at this new crossroad. It has favorable trade relations with many partners. Though India runs a trade surplus of good with the United States and Europe, its trade with China and Russia is clearly unilateral – Beijing and Moscow holds advantages.

To compete with external trade partners like Vietnam, China and Korea, India wants to allocate expertise into high tech manufacturing like semi-conductors, electronics, and other preferred sectors. Problematically, because every State in India follows a different industrial policy according to their own political aspirations and needs, it’s difficult for New Delhi to dictate policies that align with central government objectives cohesively.

Changing the Playing Field to Accommodate Growth

The experience of industrial bases like Germany, Japan and the East Asian economies show that manufacturing growth requires coordinated policy. Ironically in India, after the 1991 economic reforms, no structured national manufacturing gameplan existed until 2011.

Industrial strategy should provide better support for land acquisition by the government with generous terms to landowners for agricultural lands, rather than merely leaving it to private corporate interests. Less bureaucratic labor law reforms would help too.

The 1991 industrial policy statement reduced the barriers to entry for private industry, deregulating, abolishing the monopolies and restrictive trade practices act of 1969, and significantly reduced import duties. This remained a focused policy pillar over two decades. However, there remained a number of gaps that still need to be improved.

The “new economy narrative” discussed by the Indian government needs a realistic perspective. For example, policy makers in the government argue that PLI (Performance Linked Incentive) which started in 2021 is an answer for reviving sector specific manufacturing. But not everyone is convinced. PLI is based on subsidies that provide incentives to generate output in fourteen highly import dependent sectors (especially for imports to China) that are extremely capital intensive in character. This has happened at a time when India needs to create more quality jobs in manufacturing, but faces hurdles.

The PLI has issues because the system requires many firms apply for the incentive subsidy to increase production in their chosen sectors, and the government will be in charge of picking winning firms (rather than sectors). This is the opposite of the practiced industrial policy of the East Asian Tiger miracle economies and what underlaid their success in export oriented manufacturing growth. The East Asian nations only selected industries to support, they did not ‘pre-pick’ winning firms.

The Soviet Example: Agriculture as a Competitive Lever?

During the Brezhnev era in the Soviet Union, most everyone in the top government positions of the now disbanded nation knew something was wrong economically. The Soviet Union was a giant bureaucracy that wanted to manage all production according to misguided yearly targets – the failure was only a matter of time as the utopian economic system imploded upon itself with malfeasance.

In the 1970s within the Soviet Union the immense influx of hard currency achieved from energy exports masked severe domestic failures, particularly in agriculture. Instead of investing the trade surplus into modernizing domestic infrastructure, the Kremlin was forced to use its Petrodollars to import vast quantities of Eastern grain and agricultural products to compensate for chronic harvest failures and feed its population.

By the early 1980s, the Soviet Union’s trade profile resembled that of a developing nation: exporting raw unrefined materials to purchase food and finished goods. When global oil prices crashed in the mid-1980s, the Soviet Union trade balance plunged into severe deficit and never recovered. Stripping the state of the hard currency it needed to survive.

Likewise, despite being an agriculturally important nation, India is forced to import massive quantities of specific agricultural goods due to low domestic yields. For instance, researchers had long predicted a rise in prices of Tamil Nadu State agricultural commodities due to a shortage of agrarian areas and stagnant growth in irrigation. Farmers are turning away from paddy cultivation because the returns fail to cover costs. Increased farm wages, machinery rentals, irrigation costs, fertilizer and pesticide prices have steeply driven up the costs of crops in Tamil Nadu. Consequently, paddy farmers are trapped in a cycle of debt and economic distress.

Although agriculture employs nearly half of India’s workforce, it contributes only about 15-18% of GDP. Outputs per workers are low. Tiny landholdings, low yields, dependence on the monsoon, and depleted groundwater limit productivity, this while subsidies and procurement favor rice and wheat over diversification. Poor storage, weak credit access for small scale farming, low investment opportunities add to problems and limited non-farm jobs keep surplus labor stuck on farms. India remains a net agricultural exporter achieving about $51.9 billion USD in 2024-25, but despite this higher valued Agri-export composition is not sufficient.

Policy Decisions and Competitive Companies

India’s services exports and remittances have created a persistent source of Forex earnings. The resulting accumulation of foreign exchange reserves provides an external capacity to import vital capital goods, technology and other productive tools to create benefits. The challenge is to convert this external surplus into better domestic productive capacity. This can be done by investing in infrastructure including logistics, energy, worker skillsets, technology development, improved ports and warehousing – and other foundations required for manufacturing and developing superior values in agriculture.

Improving the infrastructure for success is crucial, but importantly the Indian government should not attempt to pre-ordain winners through the PLI. Choosing winners can become a doomed strategy when the State tries to determine in advance which firms, technologies or industries will ultimately become globally competitive as capitalism plays out and companies ascend or fail sometimes.

The East Asian experience suggests that industrial policy can support selected sectors, but competitiveness ultimately has to be tested through productivity and export markets. The role of the State should therefore create conditions in which winners can emerge through competition within the marketplace, as they manage finance, technology and their workforces – which will help the companies strive to become the best versions of themselves.

Copy and paste the text from AMT that you want to share

Share:
SP500 20261002

All Quiet on the Trump Front?

Biased Information Extends to Economic Reporting as Much as It Does To Global Affairs

Nearly one month from now, on the 3rd of November, the U.S mid-term elections will be held. Today the Non-Farm Employment Change date will be published. But will these economic numbers matter? The coverage of the Trump presidency remains problematic no matter what your political beliefs are because it is difficult to know the truth regarding details being reported, particularly as the vote approaches and folks want to influence your decisions.

Depending on which media source you are paying attention to and what the outcome is you are certain to be spoon-fed a large amount of bias. The problem for voters in one month, and for investors today is that a lot of the information and opinions being consumed cannot and should not be trusted. Everyone has bias, to not admit this is not honest. AngryMetaTraders tries to give a solid centrist reasoning of the speculative and investing world based on – truth must win out. However, certainly I and our other writers within AMT have insights that are based on our unique perspectives. 

Reality is important: A case in point is the Fly Dubai terror incident which occurred two days ago. Media outlets are depicting the events in a myriad of ways. Clearly the co-pilot tried to kill the 1st pilot, this so the plane could be be crashed into the ground over the Middle East on its way to Tel Aviv – or possibly be flown into a building. The nosedive of the plane which equated into roughly 5,000 meters in about one minute’s time was only stopped because of the heroic actions by the Indian 1st pilot, and by an Israeli passenger who grabbed the control wheel and leveled off the plane during the confrontation in the cockpit as others also intervened to avert a tragic disaster.

What does this have to do with economics and the markets? Many media sources did not report the events transparently, nor did they provide details on the actual attack. In other words they showed bias.

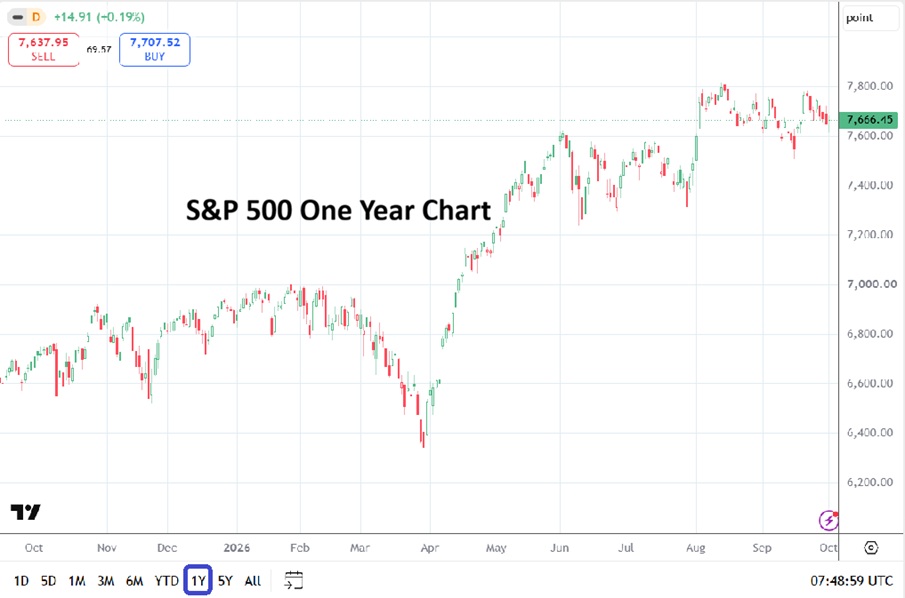
S&P 500 One Year Chart as of 2nd October 2026

The reason this is important is because like the incident in the Middle East in which a plane flying from the United Arab Emirates to Israel received a variety of different reporting, economic news receives the same type of bias. How can you trust a media source that doesn’t want to be transparent about outcomes? Now while it may be simply a lack of known details and an attempt to get a story reported on quickly to beat competitors, it would be foolhardy to say bias wasn’t a culprit in many instances.

As a consumer of news, speculators and investors need to be aware they are looking at information that often is being presented with details that the source wants to convey, while possible omitting facts. Unfortunately, global markets are being confronted by a complex amount of circumstances which include interpretation by the media which is reporting and this can lead to bad trading decisions. 

The war (conflict) with Iran continues to traverse a fragile  and unresolved path. Higher energy costs remain. WTI Crude Oil as of this moment is trading near $92.00. Gold is around $4,180.00. President Trump seemingly is attempting to practice relative calm – within his frequently loud characteristics – and not escalate the Middle East saga until the mid-term elections are complete. Perhaps that is merely my own bias as an observer.

Today Non-Farm Employment Change numbers will be published. And getting back to the original paragraph and its question, will the data matter and how will it be presented. Bias is apparent in most publications that cover the economy, to deny this would be a mistake by investors and speculators. 

While it is likely the jobs numbers are not going to have a significant impact on the voting decisions, nor the trading choices by market participants, what matters is the fact that the presentation is being geared towards an audience depending on bias of the source. The Wall Street Journal, Bloomberg, CNBC all have reporters who certainly have their own perceptions and beliefs. There is nothing wrong with this, but as a consumer of news and as a market participant you must understand that you are being influenced intentionally by media sources. 

The results from Wall Street the past handful of months have seen plenty of trading opportunities. Yet, there is a loud debate on what the near and mid-term will produce. Plenty of risk analysts are nervous about their forecasts. Yet, even soothsayers need to be aware and remind themselves they are being influenced (including myself) by the news they are consuming.

There are facts. Market results are a truth. Higher U.S Treasury yields are a reality, the stronger USD in recent weeks is happening. Sideways results – via a handful amount of months – in the SP 500, Nasdaq 100 and Dow 30 are facts – but importantly too is they remain within sight of apex highs. But the market results and their storylines are determined by media depending on how they would like you to interpret the results.

As an investor or speculator you must know your own timeframes and what your ambitions are regarding targets. Is there an AI bubble, can AI make enough revenues to cover existing valuations? Market results are delivering real values, but they still need to be interpreted and with open and flexible perspectives to determine what might happen near and mid-term.

Be careful folks. Understand what you are looking at is in fact meant to make you feel a certain way, you must digest the information and manner it is being conveyed the same way you treat a meal depending on what you have eaten. Some of the information you are taking in is junk food. You need to be able to decide on your own – hopefully with reliable insights and information – on what trading and investment paths you want to pursue.

Copy and paste the text from AMT that you want to share

AMT Top 10

AMT Top Ten Miscellaneous Insights, Mischief and Concerns for the 22nd of September

Trump's Saga, Market Conditions, Saudi Arabia, Investor Outlooks and More

10. Naima: John Coltrane’s classic composition from the late 1950’s should be listened to intently with eyes closed as his harmony and provocative ability to create a devotional hymn enchants. What do you hear? Instead of playing music for mere mortals, it sounds as if Coltrane is orchestrating for gods – take a moment to listen.

9. Upwards: Bitcoin, cough, cough is again making some look foolish as it traverses higher. As of this moment, BTC/USD is at $86,000 and making doubters – among them some AMT staff – shake their heads in disbelief (disdain). Michael Saylor’s Strategy/MicroStrategy entities have MSTR share prices around $168.00 per yesterday’s close. This is occurring as AI concerns because of its ability to challenge cybersecurity and coding of crypto remains relevant. Additionally, higher energy costs are causing miners to wince, running out of folks who are willing to speculate in the domain remains a danger (because of Ponzi suspicions), notions about government supervision getting stronger instead of becoming more lax, quantum technology, and known rogue nations keeping Bitcoin and other cryptos vibrant to hide illicit money shadow. But this is nothing to worry about it appears for Bitcoin believers and influencers.

AMT Top 10 Miscellaneous Insights, Mischief and Concerns for the 22nd of September

8. Unheralded Victories: While many were looking away purposely and likely do not want to give President Trump applause, Denmark extended the U.S administration not only an olive branch regarding Greenland, but perhaps a signal that they have acquiesced by expanding U.S security jurisdiction. From a foreign policy perspective the Trump administration has changed the Venezuela leadership, secured greater military capabilities in Greenland, and remains focused on bringing Cuba’s leadership to their knees as the island nation suffers from extended electrical outages.

7. Berkshire Hathaway: Warren Buffet stepped away from his job as Chairman on the 18th of September and named his son as successor. Share values via BRK.A were above $800,000 in April and March of 2025. This August BRK was again over $800,000. Yesterday’s close was near $752,000. Warren Buffet’s brand and era is coming to a close and the new leadership will be hard pressed to fill the confidence void. Berkshire Hathaway investors however, are some of the most loyal constituents in the marketplace. They will want to see a steady ship run by Howard Buffet and CEO Greg Abel.

6. New School: What will the Fed do now that they have raised the Federal Funds Rate by a quarter of a basis point on the 16th of September? Kevin Warsh has proven he is not exactly in the coat pocket of President Trump. After the Fed’s unanimous vote last week to raise rates, what happens on the 28th of October? Via Forex it appears financial institutions have braced their outlooks for another hike sometime later this year, but are they correct? Old theories via central banking to attack inflation with higher interest rates is a standard practice, but the escalating costs via higher energy prices has nothing to do with a sudden emergence of pent up demand, it is a supply shock that has caused more expensive WTI Crude Oil – not one driven by an increase in desire. Will Warsh prove he is new-school and proactively fight for lower interest rates sooner rather than later? Higher interest rates will not stop the Middle East saga from remaining an economic influence and spectacle.

5. Bank of Japan: Like the Fed the BoJ is not in a particularly safe space. After following in the footsteps of the Federal Reserve last week, the interest rate hike of 0.25% by the BoJ was viewed as a rather lackluster move from financial institutions and Forex players who seemingly wanted an increase of at least 0.50%. The USD/JPY remains a volatile speculative wager and is above 156.850 – give or take the tantrums and punishment inflicted from the FX market. The Bank of Japan has only had 3+ decades of questionable policy, here’s to another decade worth of doubts and consistent critical observations from outsiders.

4. Hear No Trump: The U.S President is entering a dangerous political phase for his legacy and risks losing his grip on power. Mid-term elections are rapidly drawing closer and the White House could lose its Republican led majority of the House. The President is starting to be viewed as a lame-duck by some observers. Trump who is known for his ability to change his rhetorical stances and policies quickly is still at the epi-center of global affairs. The question is if other policy makers and nations are listening. The Republican party is entering a dangerous phase and its leadership is likely going to endure a rather loud fight for control as factions take sides. The Vance and Rubio camps are likely to grow louder and divergent.

3. Saudi Arabia: Ask a friend to point to Yemen on a map, can they do this correctly? The Houthis of Yemen and Saudi Arabia may feel like a world away from known geographies, but what is happening in the wake of attacks on port areas and islands in the Red Sea (and even Riyadh) is significant. Crude Oil production and shipping problems suffered because of pipeline vulnerability is a vital concern for energy supply to Europe and Asia. While large investors may feel like they have digested the dangers, Iran and its proxies – including the Houthis may have additional theater to present. WTI Crude Oil has come down in price since yesterday but remains volatile and is around $93.00. Will optimistic banter continue?

2. FOMO: The Nasdaq 100, S&P 500, Dow 30 and their global counterparts are within their higher apexes as traders and financial institutions keep placing their money into these known asset spheres. The bond market is still producing high yields and folks are seemingly letting their casino like bets ride on a wheel they hope propels solid momentum for as long as possible. But alas, number 1, should make people pause:

1. Bandages: Perhaps our circle of contacts is too small, but behavioral sentiment is not exactly robust regarding positive market outlooks via mid-term queries. Concerns about equity indices, bond yields, inflation (because of sticky energy costs) and the general malaise that is hovering over the broad markets is not appealing. It feels as if sutures are keeping wounds from becoming infected in a haphazard manner. Investors are cautious and appear ready for the Band-Aid to be ripped off. The late ’90s and early 2000s dot.com bubble bursting, the 2006 bank and housing whispers and rumors flotilla which turned into the catastrophe of 2007-08 feel oddly similar. Perhaps it is a good time for accumulation if nothing seriously bad takes place in the markets. Circumstances feel as if a wave of blind market powers may harm those who seek never ending profits with a tsunami of losses. Perhaps it is a good time to be a speculator.

Copy and paste the text from AMT that you want to share

Share:
GIFT NIFTY 50 20260918

India Insider: NSE IPO Coming While Local Macro Conditions Not Accommodative

India's National Stock Exchange Magic Act Needs to Diversify

The National Stock Exchange (NSE) of India has been planning for an IPO quite a while. The total valuation of NSE is estimated at 5 trillion Rupees ($53 billion USD).  The issue size is 22,569 crore ($2.4 billion USD) while shares are priced at 1700 to 1785 per equity share. Share value of 65% are blocked for institutions and 35% for the retail segment. The IPO is open from September 17th to the 21st. The sales is an offer by existing shareholders, not a fresh issue of equity shares.

The rise of stock trading apps in India has made applying for primary offers easier, especially after 2020. The NSE’s value has soared over the past decade as India’s capital markets have expanded and retail participation has been surging. NSE’s unlisted shares were bought by wealthy individuals and NRIs (Non-Resident Indians) over the last few years in order to capitalize from the new trading boom.

The NSE IPO is priced at 42 times its earnings, a steep valuation compared to its global peers. NSE investment bankers were advising the stock exchange to issue 148.9 million shares at a higher valuation, but upon sensing less market depth and cautious appetite, bankers have reduced the number of shares offered to 126.44 million.

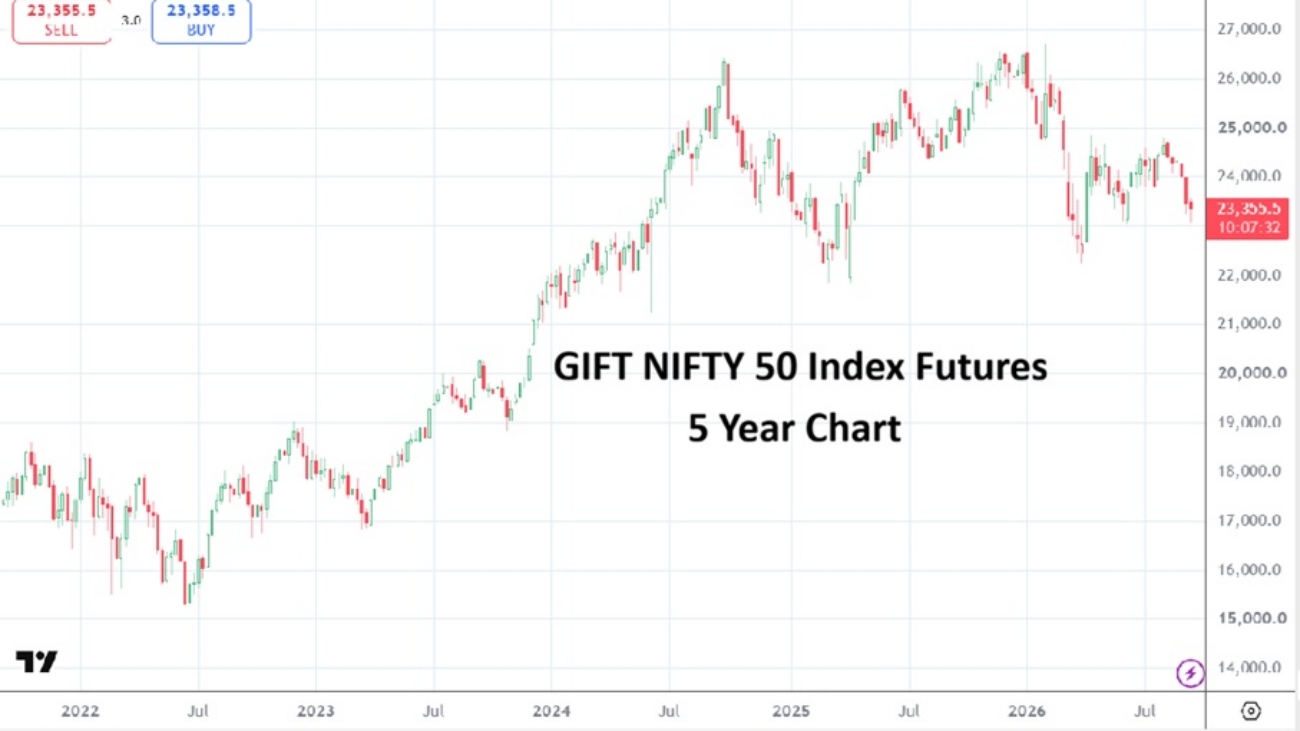
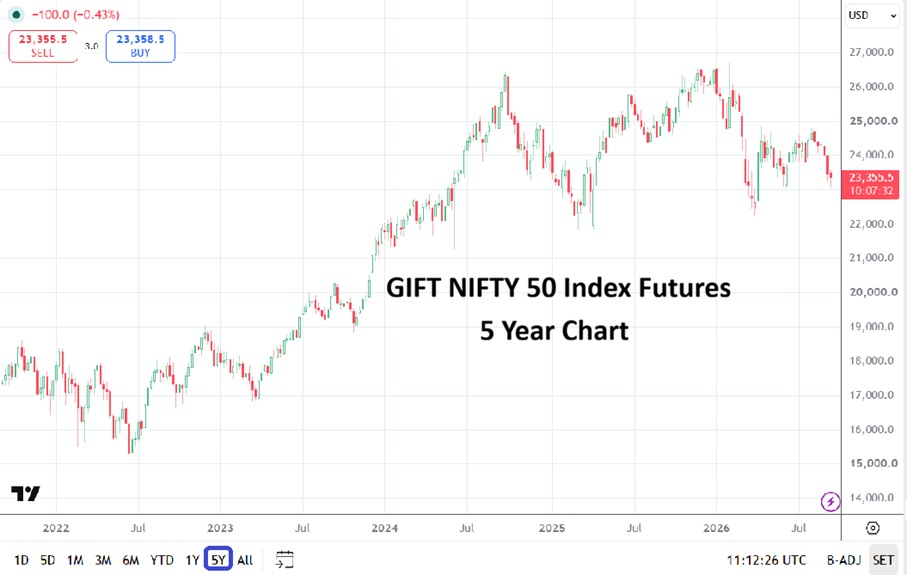
GIFT NIFTY 50 Index Futures Five Year Chart as of 18th September 2026

Reports from the last few days say anxious brokers have been calling individual investors and trying to entice them to invest in NSE. As an example, the Life Insurance Corporation (LIC) IPO in 2022 did not demonstrate as strong a marketing push from brokers compared to this NSE event. 

What’s the reason for the NSE IPO is being rushed to the marketplace when internal macro conditions are not accommodative? Various India state owned enterprises own stakes in the exchange including the State Bank of India and its subsidiary SBI Capital Markets entities – they and others likely want to be part of a ‘win’.

The NSE IPO comes at a time when the regulatory barrier on brokering and trading has intensified in recent years. Options activity propelled a gigantic boom in retail activity and helped strengthen NSE’s capital position. But it could not have happened without the regulator, the Securities and Exchange Board of India, providing a relaxed attitude regarding influencers who sugar coated facts and were partnering with brokers to attract millions of uneducated and struggling youth to bet on India’s index derivatives market.

As someone who worked in a private full service broker, I have seen countless numbers of people lose money while options betting. College students, retired people, small shop owners opened trading accounts in mass with a number of digital brokers and began to bet on weekly option wagers where the odds of winning were stacked against them.

The Indian government by igniting this machine has so far collected 90,000 crore ($9.37 billion USD) between Financial years 2021 and 2026. The flip side is the mounting losses incurred by retail traders. From FY 2021 to 2025 the losses are estimated to be around 287,000 crore ($30 billion USD) per SEBI’s data. Individual traders lost money in this casino like atmosphere around 91% of the time.  The numbers are staggering because option sellers, hedge funds, prop and other wealthy traders made money at the expense of retail losses.

The government has collected income taxes on these capital gains from profits generated by the option sellers. While retail traders who had borrowed money via personal loans to wager in these dangerous trading instruments are now suffering severe financial liabilities, paying 40-60% interest rates on their loans. Many youngsters have lost serious money. This is a severe situation because the average annual income for a person is around 15,000-20,000 Rupees ($208 USD) per month.

The NSE meanwhile has made revenues of around 35,000 crore ($3.65 billion USD) between FYs 2021-2025 for facilitating this disastrous betting landscape. In other words, the National Stock Exchange has seen profits rise by more than three times in these last four years due to the retail boom. Brokerage offices have collected handsome rewards too.

After the regulator begun to scrutinize losses incurred by retail traders in 2023 and 2024, they increased the minimum margin requirements for option traders to participate on particular contracts by a multiple of 3. This means those who were wagering with 500 Rupees now have to spend 1500 Rupees for pursuing the same contracts, assuming the premium per unit of the contract is unchanged. The regulator also limited numerous other option contracts on various indices to streamline the segment, i.e. allowing weekly expiry options for NSE and for the BSE (Bombay Stock Exchange). The chief aim of these measures was to discourage people from rapid, speculative bets on options that expired within days and it worked. Within a few weeks the high frequency retail trading frenzy had deflated sharply.

The biggest loser to this action is the NSE, which is getting around 60% of revenues from derivatives trading volumes. As retail traders activity cooled, exchanges like NSE shifted towards attracting patient long term capital from institutions for listings and rely heavily on traditional cash markets for generating revenues.

Despite pundits arguing that India has deepened the capital market inclusion, the reality is it has made very few changes in the existing system. For instance, the Reserve Bank of India ordered the closure of the exchange traded currency derivatives market in 2024, which helped small scale exporters and importers to hedge their risks efficiently. The country also has made little in-roads trying to expand the corporate bond market, and 75% of financing is still done by corporations through bank credit lines. India despite making numerous changes in regulations has failed to foster the development of financial institutions with bonds.

Short selling of shares remains banned, meaning a buyer of shares has two variables whenever he or she is purchasing, profit or loss. They can’t hedge. There is also no major marketable securities avenue for government or corporate bonds. Government bonds are still fix-rated like bank deposits. In the last decade many who people who ‘invested’ and funded instruments in shadow banking firms lost huge amounts of money, and so have individuals who invested in non-convertible debentures (NCDs) via Yes Bank and Dewan Housing Finance Limited.

If the National Stock Exchange wants retail investors to participate in its IPO shares it should diversify avenues for making money and issue a lower valuation to be attractive. The NSE cash machine has stumbled. Profits in the India financial markets industry have slowed as wealthy high net worth individuals and prop traders have shifted bases to UAE and Singapore. The NSE should not expect retail traders and small investors to subscribe to its IPO when people are struggling to pay their monthly bills. The NSE minted a huge amount of money from retail traders via a casino like binge and helped institutions and governments earn superlative profits. Now the NSE wants to replicate this cash magic act with its IPO.

Copy and paste the text from AMT that you want to share

Share: