Gemini3 20270711

The Great Compression Part 3: The Immovable Object

The Landlord Beneath the Cloud

There is an old paradox: what happens when an unstoppable force meets an immovable object? The AI buildout is the unstoppable force – the largest concentrated wave of capital spending in history. The immovable object is the physical world it is colliding with. Land, power, and water are the tangible bedrock that no balance sheet can conjure into existence. The paradox has a resolution the classical philosophers never thought of: the immovable object collects the rent.

Consider the scale of the force first. The four hyperscalers – Amazon, Alphabet, Meta, and Microsoft – plan to spend roughly $725 billion on capital expenditures in 2026, up nearly 80% from the year before. Add Oracle, the neoclouds, sovereign funds, and the rest of the AI heavy spenders – and total compute capex crosses $1 trillion in a single year, the first trillion-dollar year of its kind. Much of that money flows to the visible beneficiaries the market already knows by heart: NVIDIA for the GPUs, Micron for the memory, Dell for the servers, Cisco for the networking. Silicon, racks, interconnects.
The Great Compression Part 3: The Immovable Object 

But every one of those chips has to be housed somewhere. It has to be powered. It has to be cooled. And this is where the unstoppable force runs into something it cannot simply outspend.

The constraint is no longer capital, and it is increasingly no longer silicon. It is the physical world. The bottleneck has shifted to power generation and grid interconnection, which take years to permit and build, and to the land and water that data centers consume at industrial scale. The richest corporations that have ever existed are discovering that a signed check does not produce a megawatt or a water right. The immovable object has begun to set the terms.

Nowhere is this clearer than in a deal signed on June 23rd. Texas Pacific Land Corporation, aka TPL, agreed to provide the surface acreage and brackish water for Project Kilby, a large-scale power generation facility Chevron is building to supply a Microsoft data center cluster in Reeves County, Texas. When the announcement crossed the wires, Chevron’s name led every headline – and TPL was a footnote.

Meanwhile, the framing should be exactly backwards. Chevron, for all its scale, is the replaceable party in that transaction. Exxon, Occidental, or any of a dozen major energy companies could have built that power plant. What none of them could have supplied is the specific land and the specific water rights in that specific corner of the Permian Basin – because those belong to TPL, and there is no substitute for them at any price. The company that got the headlines is interchangeable. The company that got the footnote is the immovable object.

TPL is the purest expression of the scarcity trade beneath the AI buildout. It owns roughly a million acres of West Texas and produces almost nothing itself. It does not drill. It does not manufacture. It collects royalties, easements, and water fees from everyone who needs to operate on its ground. It is a toll booth on the physical world, and the AI buildout has just become one of its largest new customers. For years the market valued it as an oil-and-gas royalty play. It is quietly becoming an infrastructure landlord for compute – and almost nobody has ever heard of it.

The same logic radiates outward through the entire physical layer. Power is the genuine bottleneck, and the companies that generate it are being repriced accordingly. Constellation Energy, the largest operator of nuclear plants in the U.S., has become an unlikely AI stock as hyperscalers sign long-term deals for the one thing they cannot build fast enough: reliable, always-on baseload power. The grid that carries it has its own set of indispensable names – Quanta, which builds and maintains transmission infrastructure; GE Vernova, which supplies the turbines and grid equipment; Eaton, whose electrical systems distribute power inside the data center itself. And as chip density rises, the heat has to go somewhere, which has turned Vertiv, a maker of cooling and thermal management systems, into a core holding of the buildout.

What is striking is that this category does not merely sit still and collect. Some of its members are actively repositioning to attack. Ford, unable to win the electric-vehicle war against Tesla and nursing a $19.5 billion writedown on its EV investments, has taken the same physical assets – its plants, its battery capacity, a century of manufacturing expertise – and redirected them. In May it launched Ford Energy, a subsidiary building grid-scale battery storage systems, with data centers named explicitly as the demand driver. The immovable object, it turns out, can also choose its targets.

This is the HALO trade: Heavy Assets, Low Obsolescence. Companies whose value rests on tangible, physical assets and established operations that are expensive, time-consuming, or regulated – and therefore very hard to replicate. Land. Power. Grid. Water. Steel and concrete and copper. The unglamorous inputs that no model can commoditize because they cannot be reduced to software, and no amount of capital can summon into existence overnight.

None of this is permanently fixed, and it would be dishonest to pretend otherwise. Innovation erodes scarcity: small modular reactors, advanced geothermal, and better transmission technology will, in time, loosen some of the constraints that look absolute today. But two things blunt that threat. The first is Jevons paradox – when a resource becomes cheaper to use, consumption rises to swallow the savings, which means more efficient power generation is likely to expand the buildout, not shrink the edge of the providers. The second is that not all heavy assets are equal. The manufacturers and equipment makers face real competitive pressure over time. The owners of irreplaceable location – the specific acre, the specific water right – do not. You can build a better reactor, but you cannot build another Permian Basin.

The value that fled the human middlemen, that commoditized in the model layer, that migrated up the stack toward proprietary data and orchestration – also flows downward, and at the bottom it stops. It settles into the ground, into the wires, into the water table. But the ground is not neutral territory: land is permitted, power is regulated, water is allocated, and the fabs that print the silicon sit inside country borders. The unstoppable force keeps accelerating; the immovable object keeps collecting. And the moment we ask who owns the immovable object, the scarcity trade stops being a matter of markets and becomes a matter of sovereignty.
Copy and paste the text from AMT that you want to share

postN9

India’s Speculative Real Estate Bubble and Values: Part One

India’s Speculative Real Estate Bubble and Values: Part One

India’s Real Estate Sector is a Well Known Affair to its own Citizens and to Global Asset Management Companies

India’s major cities like Mumbai, the financial capital of India, Gurgaon, Delhi, Bengaluru and Hyderabad, the tech hub of the nation, serve as major attractions for local players and international corporate giants who want to participate in the real estate sector. While transparency still remains a challenge that needs to be addressed in Tier 2 and Tier 3 cities of India, underlying demand continues to expand throughout the nation. The Real Estate Regulatory Authority, passed a bill known as the RERA Act, by the serving government in March of 2016, to create transparency and fairness between buyers and sellers in the residential real estate market, however these measures do not always help circumstances as hoped.

Well known companies like Blackstone which is based in New York, and Brookfield Asset Management of Toronto have vast operations in the commercial real estate sector of India. Their estimated investments are significant. Amounts spent are believed respectively to be nearly 50 billion USD by Blackstone, and the Brookfield figure is likely around 22 billion USD. The companies concentrate money for real estate, and infrastructure like telecommunications, roads and other spheres crucial to create value.

The reason why private equity giants allocate massive investments into India commercial real estate is due to the remarkable advantages of the locations available for property, and the capability to turn a profit. The land purchased and developed is usually situated close to burgeoning information technology companies. It is easily understood these IT companies have expansive needs to function properly which include plenty of area for employees to work. This is relevant in the north of India where Brookfield has invested in places like Mumbai and Gurgaon. Apart from the commercial demand for property, the employees who work in these type of companies also drive residential apartment sales in these cities.

The real estate market in Gurgaon has seen remarkable growth in the recent years where prices have experienced double digit appreciation. Readers need to understand that Gurgaon, is a city near India’s capital of New Delhi in northern

India. It’s known as a financial and technology hub. The rise of e-commerce players like Amazon and the Walmart owned Flipkart are important. Walmart spent around 16 USD billion to buy about 77% of Flipkart in 2018 and their vast operations also have sparked demand for huge amounts of property, including warehouses. This activity has certainly attracted the attention and desire of global players to invest in commercial real estate operations.

The residential real estate market has grown fast, and continues to achieve huge growth even after the coronavirus pandemic. An extremely rapid pace is fueled because low interest rates have appealed to new home buyers to initiate purchases of apartments and condominiums in metropolitan cities like Chennai, Mumbai, Hyderabad, and Bengaluru. Many affluent families in India from these major cities continue to own and rent residential homes in the areas, taking advantage of demand. According to a survey conducted by the global property consultancy firm Savills, now 70% of families in the metropolitan cities mentioned previously from the north and south of India have answered positively when asked if they would like to buy a second home in the next couple of years.

Residential real estate sales have been rising after the pandemic, especially for double bedroom apartments averaging 1200 square feet of housing, usually within a category that is priced in a range above 5,000,000 Rupees (around 60,000 USD). India’s benchmark mortgage rate is in the 8.7% to 9.7% range as of this writing, this is higher than it was one year ago. But Indian home buyers haven’t yet stepped back from buying, this because interest rates in India have not increased too much in percentage terms. The average time to pay a loan for residential mortgages ranges from 10 to 20 years in India. This allowable time frame makes it affordable for employees to pay via Monthly EMI, Equated Monthly Installments. The mortgages come with a floating rate meaning the buyers can reset their rates when the local interest rate falls. Yes, floating rates certainly do contain dangers if interest rates climb too high.

A Speculative Roulette Game: The Least Known and Unequal Affair

But there is another reality and a very different story in certain areas of India where data misses critical elements of the real estate business. Speculative participation in property is done by the most affluent who are the dominant buyers and sellers; speculative buying and selling is too expensive for most citizens. Real estate has frequently been used as a tool to hide wealth and avoid taxes by many within certain segments of India. The real estate speculative bubble creates vast distortions in the costs of rents, and affects employment opportunities for the masses. Government offices may sometimes turn a blind eye to these circumstances, because as long as cities and regions can collect money from the speculative frenzy there is little reason to turn off the revenue streams.

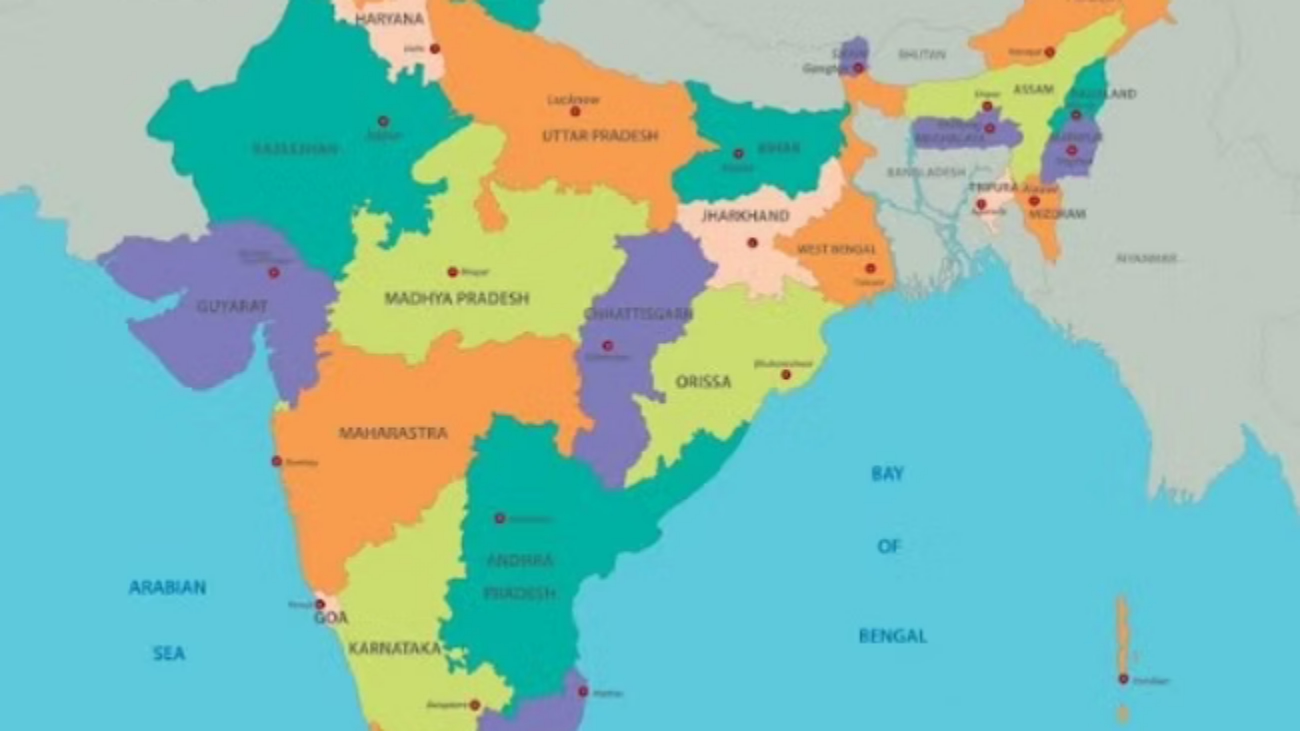
Frequently there is someone who is capable of bidding higher for lands in most of the Tier 2 and Tier 3 cities discussed, compared to those who actually need the property to live there and function properly. It is important to mention Tier 2 and Tier 3 cities and what is taking place in these areas, because these locations frequently lack substantial income generation opportunities for people and don’t have massive infrastructure or enough office space to employ people where wages have stagnated for many years. Take for example the Tamil Nadu, a state in southern India where I live, the average price of a double bedroom 1200 sq’ft residential apartment in the capital city of Chennai is around 6,000,000 Rupees (around $73,000 USD).

Readers need to note that the Indian ‘middle class’ prefers to have 2 bedroom 1200 sq’ft residential houses and apartments on average, thus builders construct houses and units based on land availability. Market prices for the property equals the costs of building materials and labor along with the speculative factors worked into the total value.

A look at the town of Madurai where the same apartment is available at a comparable price tag like Chennai is important to critique. Because wages in Madurai are a quarter, and sometimes less than half of what one could earn in Chennai, the disparities in the income distribution and the property prices in India become evident and need to be recognized.

In some rural towns where wages have not grown more than 5% per year,

India has seen real estate prices doubling every 4 years. For example, the rural town called Ponnamaravathy near to Madurai, which is my hometown, speculation in the real estate sector has seen frenzied pricing in an unprecedented manner for land and newly built houses. There is a great divergence between real per capita income versus the escalating real estate prices and rents in the interiors of India in towns such as Ponnamaravathy.

According to real estate analysts, most land parcels and their inventory of projects within metropolitan cities that are under construction has been bought by speculators. When units in new projects are sold to speculators, these generally change hands multiple times during the construction period, which generally lasts three to four years. Such heavy ‘churning’ means fast price increases. Also, the builders who market their own projects as investments raise list prices frequently to keep existing investors happy with notional gains, so they can point to the ‘attractiveness’ of potential speculation.

While it may not matter to some citizens in the larger cities, the problem of speculative influences do matter in the small towns where community wages have not grown properly. Inflation and speculative investments in these towns do not create sufficient job growth either. Surplus cash profits earned by many businesses, and foreign remittances, which were close to 108 billion USD in 2022, goes back into real estate speculation causing higher rents and forcing lower income households to struggle.

Rural Wages Haven’t Grown but Prices are Increasing for Homes

According to economists data, Average Nominal Wages in rural India is approximately 15,000 Rupees per month for men and 8,000 Rupees per month for women.There is an ample real estate supply in the rural market, but speculative demand has created steep pricing, typically initiated by large ‘investors’ willing to pay top money for any asset irrespective of its location, affordability or current market price based on the assumption values will continue to increase.

The difference between rural wages and costs for homes creates heavy disparities and inequalities for households living within the lower thresholds of society. For example, a double bedroom 1200 sq’ft residential apartment in Ponnamaravathy can be selling at a whopping 7,000,000 Rupees (approximately 85,365 USD). This is 20% more than what we have seen before on average in Chennai, and Madurai, a Tier 2 city, in Tamil Nadu state. The wages in the rural town of Ponnamaravathy are just 10% compared to what one could earn in Chennai annually, making the purchase of a residence priced at these higher values difficult for most residents and making many people renters for life.