postN61.1

Nervous Results Next: Forex and Equities Wait for Jobs Data

Nervous Results Next: Forex and Equities Wait for Jobs Data

Tomorrow’s jobs numbers from the U.S will get plenty of media coverage. Typically the Non-Farm Employment Change data is used as a selling tool by brokers to get their traders motivated and speculating on Forex and stocks via CFDs with the promise of swift price action. Many times the jobs numbers prove to have limited value, serving mostly as entertainment for back office risk managers at Forex houses as the whipsaw value changes wipe out speculators across the board. However, tomorrow may prove different.

Friday’s Non-Farm Employment Change and the Average Hourly Earnings statistics may produce dynamics worthy of their news coverage. Financial institutions are actually quite interested in tomorrow’s coming reports as the U.S Federal Reserve lingers in the shadows having spoken boldly about raising the Federal Funds Rate in November. It would take a weaker hiring result from the Non-Farm Employment Change data, and lower inflation numbers from the Average Hourly Earnings outcome to change financial institution outlooks regarding the U.S central bank.

EUR/USD One Month Chart as of 5th Oct. 2023

The trend of the EUR, GBP and JPY clearly demonstrate the value that has been lost against the USD over the past three months. While many financial institutions and speculators believe the USD will begin to lose strength eventually, timing the moment this is going to start happening in earnest is difficult. U.S Treasuries have come off of highs in recent trading, but nervousness remains abundant and recent heights remain in sight. Tomorrow’s U.S jobs number could reignite fear and spark behavioral sentiment which is reactionary.

As a side note, while U.S indices turned in some gains on Wednesday, the moves higher were not exactly momentous which sets up the U.S stock markets to produce a sudden reversal lower if widespread nervousness is produced today and tomorrow.

Importantly, hiring is believed to be weakening in the U.S by some analysts, but there is plenty of talk about a lack of qualified workers to fill important jobs still. So while the Non-Farm Employment Change number may come in below estimates and could spark hope among financial institutions the U.S Fed will be given a reason to sit on their hands, it is the Average Hourly Earnings inflation numbers which should be watched even more closely. If the costs of paying wages is more expensive than the previous month, this would spark concerns about price pressures remaining problematic.

Analysts have also continued to speak about concerns regarding revisions being made by the U.S government to past jobs reports, which means financial institutions are wary of positioning themselves fully based on the current month’s reporting. Accurate reporting from the U.S government has become problematic, and is causing nervous and conspiracy minded chatter in some trading corners.

WTI Crude Oil One Month Chart as of 5th Oct. 2023

Another factor which day traders may want to consider is the price of Crude Oil which has sunk below 84.00 USD per barrel in the footsteps of a one week decline. If the price of the commodity can remain muted and show a solid trend downwards this would help reduce hawkish rhetoric from the Federal Reserve.

As we go into tomorrow’s jobs numbers from the U.S, the broad markets do continue to exhibit nervousness which appears justified. The results of the Non-Farm Employment Change and Average Hourly Earnings may produce results which cause a reaction which shakes the outlooks of financial institutions and carries strong implications for day traders that matter.

postN56

Wednesday Federal Reserve Prediction and Central Bank Unity

Wednesday Federal Reserve Prediction and Central Bank Unity

Later today the Federal Reserve will release its Federal Funds Rate and FOMC Statement. Jerome Powell will also field questions. My prediction regarding the Fed today is that the Federal Reserve will hold (pause). It will say inflation remains problematic and stubborn, and the Fed continues to monitor economic conditions it finds complex. The high costs of energy (Crude Oil) will be presented as part of the problem.

The Fed will say they will strongly consider an interest rate hike next month, thus bracing the markets for what financial institutions have already traded into the system. This because trading houses have listened to the Fed already and believed that a pause would be seen for a few months, but cracks in sentiment quickly appeared in mid-July because of the Fed’s cloudy rhetoric as it spoke out of both sides of its mouth. Ratings downgrades and worries began, the USD sprung to significant values, higher U.S Treasury yields have flourished and increased fears for the long-term investment world. All the noise has certainly helped doomsayers.

The problem for the Fed and they should be aware of this, is that their interest rate hike threats have little direct affect on the price of Crude Oil. The rise in oil prices is directly due to Saudi Arabia cutting back on production. The U.S has much less influence on Saudi Arabia then it would like to believe it does. The Saudi Arabia government is interested in sustaining a profitable price for the commodity. At 90.00 USD per barrel, Saudi Arabia is making significant profit, but under 80.00 USD per barrel they grow concerned. After all someone has to pay for the ‘Line’ project of Neom.

Getting back on point, if the Fed is so intent on raising rates they should do so now. Not next month. But as the Federal Reserve and other major central banks often demonstrate, they are reactive – not proactive. Meaning if the Fed has no direct influence on the high price of energy that they should go ahead now and influence the marketplace instead of rattling a sword which only creates nervous global behavioral sentiment.

And yes, a hike of the Federal Funds Rate would be problematic for credit and cash reserves of consumers and businesses, which face more expensive obligations regarding loans and bonds. However, if you are merely going to threaten to do something, why not do it now and say without a doubt – like the ECB did last week – this will be our last hike for the foreseeable future. But the Fed is likely to prove they have limited desire to act swiftly and try to remain painfully polite, very much like when they refused to acknowledge inflation was a real threat when it started in earnest over two years ago.

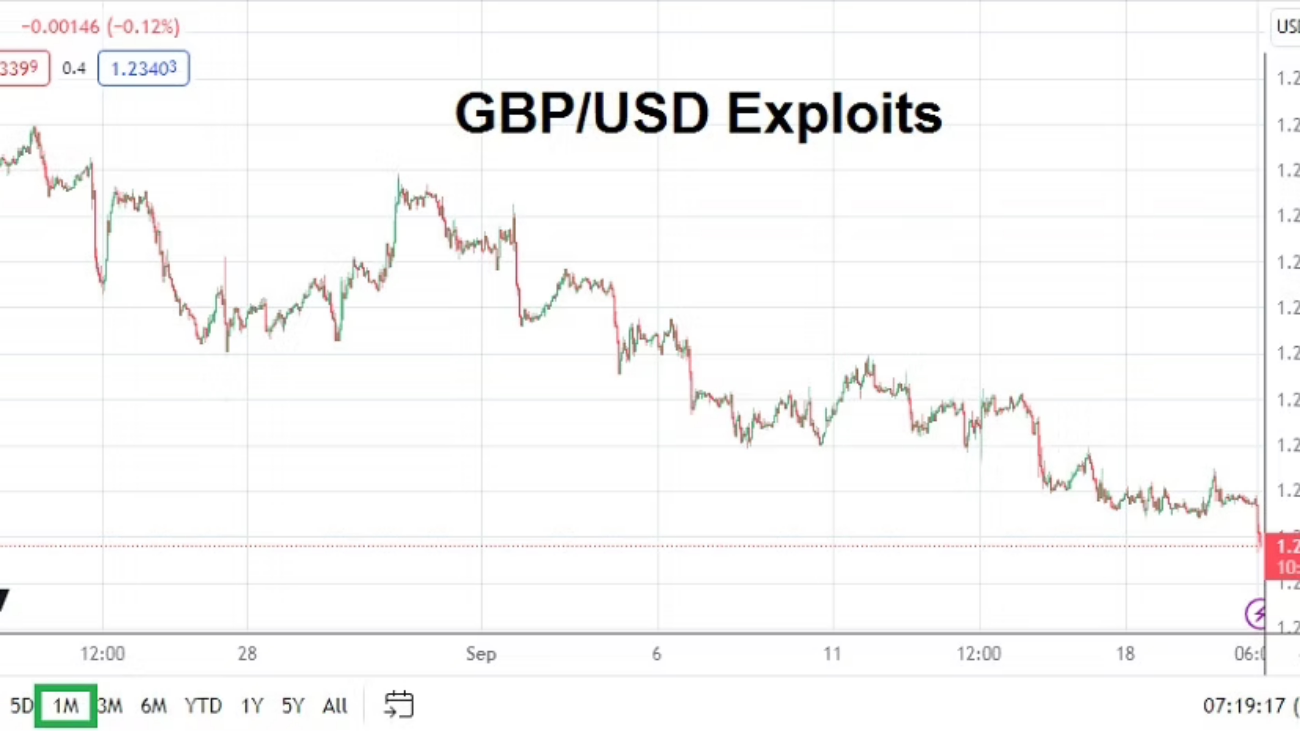
GBP/USD One Month Chart as of 20th Sept. 2023

Lastly, the Bank of England will make their pronouncements tomorrow, and some are suggesting the BoE because of today’s ‘weaker’ inflation results will not raise the Official Bank Rate. However, I disagree, inflation is still high in the U.K and the Bank of England may also feel it has to protect GBP value.

Last week’s interest rate hike from the European Central Bank, which I didn’t believe would happen and was wrong about, suggests the BoE and ECB may have privy knowledge regarding the Fed’s inner thinking. It is quite possible the European’s raised rates last week not only to fight inflation, but because they had been warned by the Federal Reserve that the U.S central bank wants to ‘sound’ aggressive. There is reason to believe if the Fed doesn’t raise tonight, but groans on about a complex economy and stubborn inflation and the need to consider raising rates next month, the BoE will feel very compelled to still hike the Official Bank Rate by a quarter of a point tomorrow.

Nothing quite like coordinated banter between the major central banks which have already demonstrated a rather stark level of mistakes over the past two years. Why not add onto the shenanigans today and tomorrow? Good luck to us all.

postN17

Fed Caught Again in Reactive Stance waiting for ‘Good’ News

Fed Caught Again in Reactive Stance waiting for 'Good' News

Let’s recall that about two and a half years ago the U.S Federal Reserve was still calling inflation transitory and claiming that price pressures would subside quickly as the onslaught of coronavirus decreased. Nearly all financial institutions could see the Fed was merely being stubborn, and that is a polite way of putting it, instead of being realistic.

It would be nice to give the Fed the benefit of the doubt now, and say the Fed have better information and know how to quantify the outlook of the U.S economy in a more dynamic fashion. However, being skeptical of the U.S Federal Reserve and its ability to miss signs plainly in front of them is a full time job for many analysts and it pays well.

As said by many before, many members of the U.S Federal Reserve have the profound disadvantage of not having the experience of ‘skin in the game’. Many Fed officials have worked as paid bureaucrats their entire lives and have literally ‘studied’ their way to the top of the central banking world, without having firsthand knowledge regarding the daily chore of running businesses. Most Fed officials have no dirt under their fingernails.

The Fed is clamoring now to return the U.S inflation level to 2.0%, and there is a large amount of disagreement about how this number is interpreted via different economic gauges. The Federal Reserve has a poor track record as stated above for being able to know what is actually ahead. They have been very aggressive regarding raising interest rates the past year and a half, and now they are finding it difficult to say they are done. This tough talk could be an attempt by the Fed to create headwinds for those considering proclaiming the U.S central bank should become ‘dovish’ by speaking tough about potential pitfalls to come, this even though the Fed plainly missed dangerous road signs a few years ago which helped agitate the problems being dealt with at this moment.

What could go wrong you ask? A credit crunch for banks and consumers.

However, business people know all about potential crisis if they have enough experience. Paying employees wages, finding additional good employees, landing a space that charges a reasonable amount for rent, hoping taxes remain sane, and hoping your shop is not shoplifted into poverty are some obstacles business owners face nowadays in the U.S. The rising costs of wholesale prices has not completely disappeared, but things may be getting better via economic data. Maybe this will be proven wishful thinking, but outlook is important and should be considered.

The rising costs of doing business is then passed along to consumers. The Federal Reserve seemingly doesn’t understand that it has made it more expensive to accomplish positive business results for small owners of enterprise in the U.S, and the Fed seems to forget that over 44% of the American economy is powered by what can be called family owned companies. The Fed certainly doesn’t mention that it is hard enough for small U.S business to survive over the long haul, with a number of nearly 65% becoming failures after ten years statistically.

So while the Federal Reserve talks a great game about managing interest rates via their monetary policy and the Federal Funds Rate, they often forget about the problem small business owners face. Having said that, the higher interest rates the Fed has sparked because of its slow reaction to what they perceived as transitory inflation two years ago – is having a bad effect on bigger businesses too. This because big corporations no longer enjoy ‘free money’ from their banks. Money has become harder to attain.

Once again it has been proven that everyone looks like a genius when the U.S economy is sailing smoothly, but when obstacles develop and people have to quantify solutions to real problems, suddenly it is harder to produce profitable results. The U.S government has created massive deficits by using huge amounts of cash stimulus to protect economic growth in the U.S over the past five years. In fact because of the quantitative easing after the financial crisis of 2007, it can be argued the U.S has used stimulus for more than 15 years to make sure the U.S economy is ‘stable’. Politicians like to keep their jobs because there is little else they can do in the real world.

The Federal Reserve by increasing the Federal Funds Rate has made U.S Treasuries a feeding frenzy and yields have increased substantially. The higher rates of interest the U.S government will have to pay down the road on existing U.S Treasuries is not a small problem mathematically. However, for the time being the Federal Reserve and U.S government seem to be less concerned about what they are potentially putting on the shoulders of future generations of U.S citizens, and trying to keep the U.S population tranquil. Luckily for many American homeowners, U.S mortgages are still mostly being paid out via the lower interest rate amounts agreed upon a couple of years ago and beyond. New home sales and existing home sales are sputtering in the U.S, because many people do not want to pay the higher interest rates that now need to be signed upon for mortgages and paid.

What the U.S Federal Reserve needs to do is to state publicly that it is not going to raise interest rates over the mid-term, and that it is going to allow the free market to work itself out via enterprise with supply and demand ratios taking center stage and being allowed to work. And lastly, that if inflation conditions as expected continue to improve by decreasing, that the Federal Reserve will consider lowering interest rates in the first part of 2024.

However, the Federal Reserve is worried that if it does sound too positive, businesses will start to gamble on a better outlook and this will raise existing inflation which has been stubborn. But again, the Federal Reserve often doesn’t understand how smaller U.S businesses work. To get out of the current economic mess the U.S Federal Reserve needs to be pro-active and not reactive. Also, the ‘ruling’ U.S government has to cut back on stimulus programs with promises of a ‘free lunch’ for all and return to looking at numbers realistically. Fiscal responsibility is an idea that can actually be practiced.

postN34

USD/INR: Consolidation Might Come to an Abrupt Conclusion

USD/INR: Consolidation Might Come to an Abrupt Conclusion

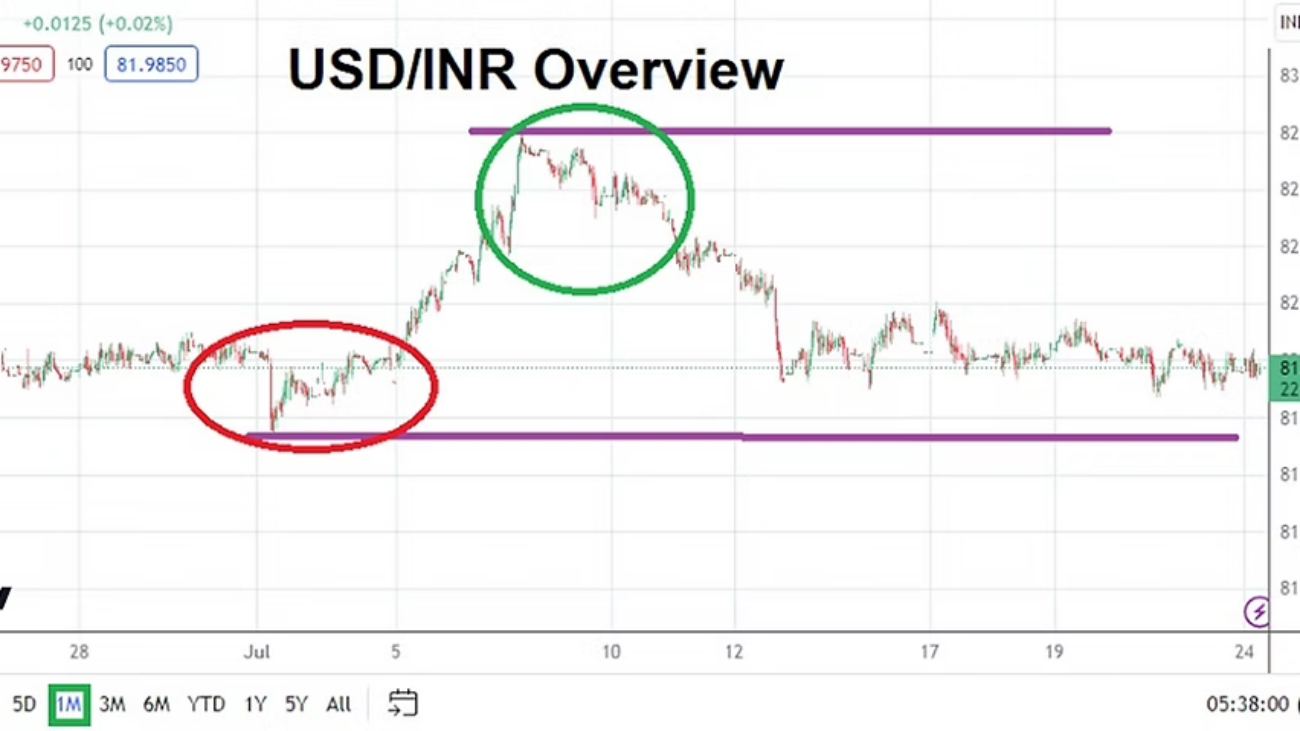
The USD/INR is trading near the 81.9750 ratio as of this writing and its price action since the 13th of July has produced a tight price range. On the 12th of July the USD/INR was trading around the 82.3000 region, this after being able to incrementally decline when a high of nearly 82.7900 was reached on the 6th of July.

Prior to the apex value of July, the USD/INR had traded in a rather consolidated mode from the middle of June until the first few days of July, essentially within a price realm the currency pair now lingers. Speculators must constantly fight the slightest of reversals if they are using too much leverage, but the USD/INR over the mid-term has produced interesting behavioral sentiment and this can be seen on technical charts.

While day traders may believe the current price ratios will hold and the potential interest rate hike from the U.S Federal Reserve has been digested into the USD/INR for this coming Wednesday, they might want to reconsider their thinking. No, the world is not coming to an end, Forex has dealt with U.S central bank decisions before and experienced traders understand the sudden potential of the USD/INR changing direction. The rather tight price range of the USD/INR could vanish in the coming days if the Federal Reserve begins to change their tone within the FOMC Statements.

USD/INR One Month Chart as of 24th July 2023

U.S Federal Reserve is Likely to Raise the Federal Funds Rate but Perhaps Shouldn’t

The USD/INR may not get hit too hard when the U.S Federal Reserve delivers the anticipated 0.25% addition to the Federal Funds Rate. However, the FOMC Statement which talks about the Fed’s outlook might cause a change to what have been calm seas recently in the USD/INR. Recent U.S economic data has been rather troubling, but inflation does actually seem to be creeping lower. The Fed has been pretty adamant in their recent ‘whispering’ about raising interest rates in July, and the potential of raising again later this year.

Time for the U.S Federal Reserve to Start Sounding Dovish

Yet, recent data suggests the Fed should likely not even raise rates on the 26th of July and continue its pause. But having expressed plenty of verbiage on the subject, the Fed may not want to surprise financial institutions and may have to raise, even if they do not really have to this week. And here is where it gets interesting – the FOMC Statement may have to express this notion of becoming more dovish. Think of this potential hike to the Federal Funds Rate this week as the last dose of medicine for a patient who already feels better, the doctor (the Fed) is insisting that to make sure the ‘sick’ is cured another teaspoon consisting of an interest rate hike is necessary.

If the FOMC Statement sounds more dovish than expected the USD/INR might start to see selling ignite and a downturn generate. There are no guarantees and certainly the Fed’s actions this coming Wednesday are not known. Yet, if the Fed hints that it will not raise interest rates over the mid-term and wants to see if inflation continues to lower that it may consider the potential of no more hikes, the USD will start to get weaker across the board. In other words, this last dose of medicine from the Fed may give them the feeling to tell the patient (U.S economy) that they no longer need to visit the doctor’s office for a while.

Other central banks are watching too. Inflation in Europe and elsewhere remains high. The complications of weaker domestic currencies against the USD have hit many economies including India where inflation has been rather strong. If the Fed can now start to become less aggressive, the effect will be quick and start helping the USD/INR trade lower if healthy economic mechanics allow this to happen.

Support levels for the USD/INR near 81.8000 to 81.7500 should be watched, if these levels begin to see challenges and sustained prices remain nearby, the USD/INR may be signaling that another downturn is about to happen. If the U.S Fed delivers a cautious, but more optimistic FOMC Statement this coming Wednesday, the USD/INR may deliver a new cycle of selling.

postN30.1

Summertime Behavioral Sentiment Game: Who Do You Trust?

Summertime Behavioral Sentiment Game: Who Do You Trust?

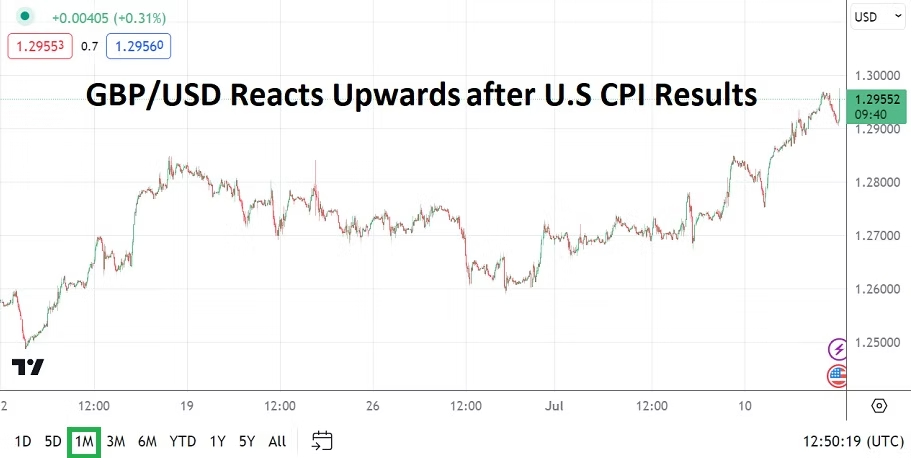
Have we started to reach a polite equilibrium within Forex, gold, equities and bonds for a moment? U.S CPI data just came in below expectations, the decrease of inflation pressures in the U.S will be welcomed. Price ranges are starting to show signs of polite trends in Forex and equities – there seems to be a recognition of basic ideas which are perhaps serving as factors that are ‘accepted’ in the broad markets. Please do not close your eyes for long, because conditions can change in a moments notice, but for the moment the USD is weaker.

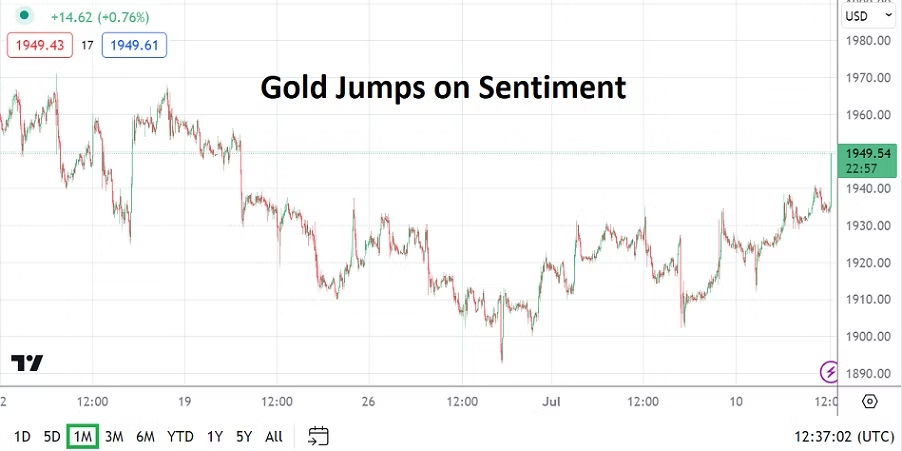
Gold One Month Chart as of 12th July 2023

The Federal Reserve could still raise its Federal Funds Rate at the end of July, though today’s CPI data outcome will create headwinds against that notion. There has been a wide voice given by folks who say the Fed shouldn’t raise rates again, and that real inflation will start to come down and that it is doing so now. The CPI has shown a decrease in U.S inflation – a larger drop than anticipated, which will certainly spur on USD weakness today. This confirms – momentarily – many analysts inflation outlooks who work in financial institutions not related to the U.S Federal Reserve and have been saying price pressures will recede. Yet, inflation is not dead yet and may still be heard. Stagflation is a genuine concern.

Tomorrow’s U.S Producer Price Index will be another opportunity to stir sentiment. Remember folks, outlooks are often adjusted according to facts. But what are facts? Can we really trust them. What are leading indicators, what is data that looks forward instead of backwards – numbers are often offered as evidence but randomness often rules interpretations of data. How do acceptable outlooks really develop when data management and outlooks can change within split seconds depending on the team looking over the quantified math. Humans are naturally optimistic, even when the data is negative, this can lead to bias.

We are in an age when trading software is doing a majority of the large volume transactions, and has been coded by algos processed by quant teams in financial institutions. Do retail traders even have a chance in this type of environment? Yes, retail traders can still manage to find opportunities, but they need to combine technical perceptions with fundamental knowledge of data, and combine the two into a behavioral sentiment outlook depending on their time horizons.

Market dynamics and situations change a lot in the broad markets. Assets move depending on the bias of incoming data. Preconceived notions being acted on and then changing according to need can be done in microseconds because of existing trading technology that financial institutions use. Larger players have an advantage and they are not about to give this up. Timeframes are also different for big trading houses compared to small speculators. It is also important to stress institutional traders could care less about day traders in Forex.

GBP/USD One Month Chart as of 12th July 2023

We have finished nearly a month of summer trading and seem to be confronted by a question of who do we trust? Do we trust the U.S Federal Reserve and its decisions and outlooks? In my opinion, you shouldn’t. But you should also remember the old adage, do not fight the Fed. The U.S central bank is bigger than you and I.

Central banks work together and often coordinate their combined outlooks, while shadows cast from the ‘oversight’ of political leaders rhetoric are frequently given consideration by the Fed, BoE, ECB and BoJ officials even if they claim they are not listening. Inflation is not welcomed by central banks, but because they are largely reactive and not proactive the Fed and others sometimes look uncaring and like fools, while the public sometimes suffer.

Thus we sit and wait for central bank pronouncements, but for the moment we seem to have a good grasp regarding what they will say. And perhaps – for the moment, maybe that is why Forex, gold and equities are trading rather politely. We seem to think we know what is going to be said moving forward for the next few weeks and remainder of the summer – more of the same warnings and interest rate correlations sprinkled in via central bank diatribes.

postN28

Week Ahead: Inflation will be the Crucial Word for Investors

Week Ahead: Inflation will be the Crucial Word for Investors

Last week finished with another reminder that inflation cannot be easily scoffed at by investors who continue to believe higher prices will eventually slowdown. Average Hourly Earnings last Friday came in above the expectation and this was enough to rattle Wall Street again, which saw the major equity indices decline and bond yields incrementally rise. Inflation ‘talk’ will remain important this week because of coming U.S data.

Real Estate including REITS becoming a Topic of Discussion as Mortgages Rise

Market watchers should also pay attention to news regarding mortgages on residential homes, and listen for troubles from the commercial real estate market, as these sectors deal with rising interest rates in the U.S and U.K. Increased nervousness within these markets could have an affect on behavioral sentiment. Let’s remember the catalyst for the financial crisis of 2007 was the real estate sector.

Which brings us back to inflation and the growing acceptance among investors the U.S Federal Reserve may be ‘forced’ to hike the Federal Funds Rate on the 26th of July, if price data continues to come in ‘hot’. Some investors will likely be heard saying an increase of 0.25% has already been factored into marketplace, but the prospect of another hike in late 2023 could be problematic. Forex, gold and bonds dynamics will tell us a lot when this week concludes regarding outlooks.

BNB/USD Price Should be Monitored as Binance Trembles

An outside source of financial and speculative news is likely to come from cryptocurrency. If you are gambling on this asset class (or should we say commodity based on hot air) and like the adventure of wagering, please continue to pay attention to Binance which is showing signs of duress. If the Binance cryptocurrency exchange shows additional signs of pressure on its BNB (Binance Coin), trading waters within the world of crypto could trigger additional drowning victims. If you thought the Sam Bankman-Fried story made interesting news last year regarding fraud and other criminal activity, the FTX saga could prove to be only the tip of the iceberg.

Data Events Ahead to Watch

Monday, 10th of July, China CPI and PPI – the inflation data could prove important for investors who correlate economic statistics from China into their global forecasts. Traders within India should pay attention to these Chinese price reports, because global investors are starting to shift their assets into the Nifty 50 and other NSE equities because of risk and reward equations.

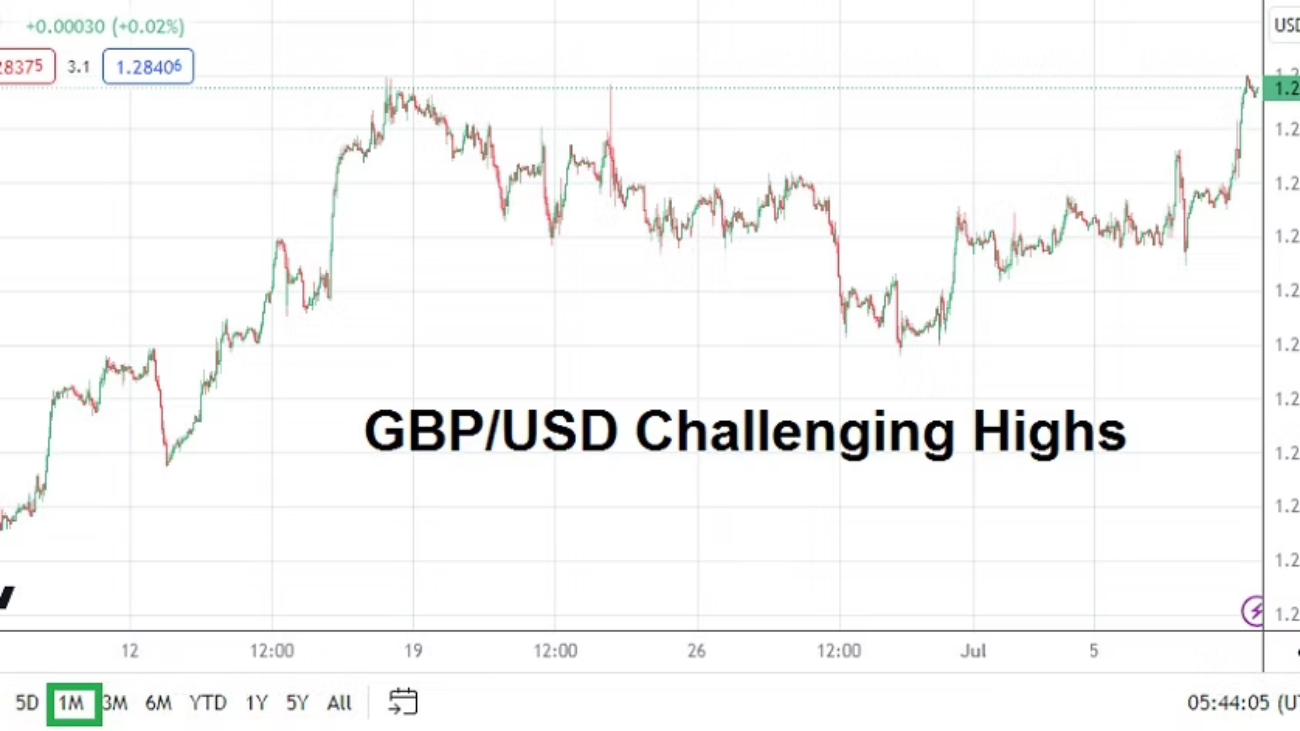
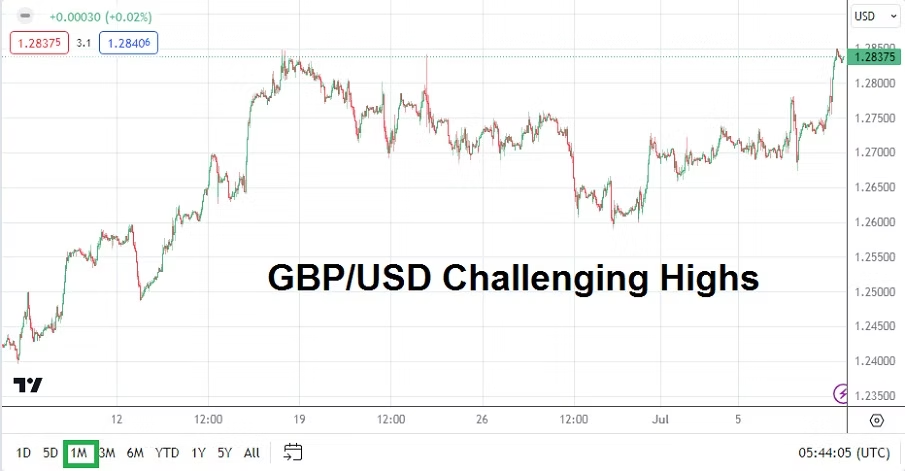
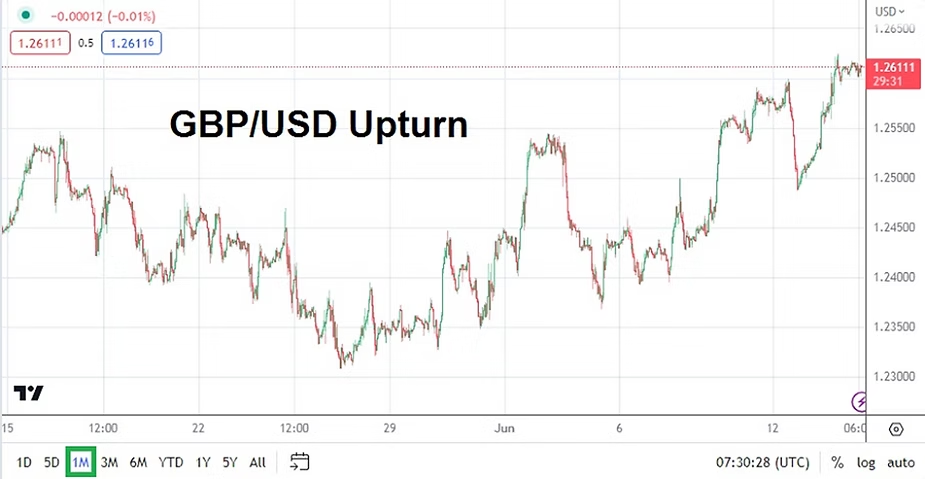
GBP/USD One Month Chart as of 9th July 2023

Tuesday, 11th of July, U.K Claimant Count Change and Average Earnings Index – the numbers need to be watched by GBP/USD speculators. The results from the U.K will be intriguing because of employment results, but more importantly for inflation concerns and the knock-on effects. Bank of England Governor Andrew Bailey is speaking a few times this week, and this includes Wednesday the 12th of July, when he will talk about the Financial Stability Report. The GBP/USD has moved towards monthly highs recently.

Wednesday, 12th of July, New Zealand RBNZ Official Bank Rate – NZD/USD day traders will want to pay attention to the central bank’s Rate Statement. While no increase of interest rates is predicted, the Reserve Bank of New Zealand at a minimum will likely have to admit inflation remains a concern.

Wednesday, 12th of July, U.S Consumer Price Index – the inflation reports from the States will have all eyes on the outcomes of the monthly and annual comparisons, including the Core numbers. The results from these inflation statistics will certainly cause momentary volatility within Forex with the USD as the focal point.

Wednesday, 12th of July, Canada BoC Overnight Rate – the Bank of Canada is expected to hike its interest rate by 0.25% to the 5.00% mark. USD/CAD will react to the BoC Rate Statement based on its outlook.

Thursday, 13th of July, U.K Gross Domestic Product – the ‘growth’ numbers are not expected to be positive. A drop of minus -0.3% is the expectation. Talk of recessionary pressures in Great Britain will be heard. Unfortunately, the discussion about a struggling economy, mixed with stubborn higher prices for consumers and mortgage rates that are rising will not make for calm stomachs. U.K equity results via the FTSE 100 Index should be monitored.

Thursday, 13th of July, U.S PPI – the Producer Price Index figures will be the last cog within the important inflation data for the week. Stubborn prices for wholesale goods are a concern, because the costs to consumers becomes more expensive when there are higher price pressures.

Friday, 14th of July, U.S Consumer Sentiment via the University of Michigan – if the Consumer Sentiment readings from the UofM report improves, and the U.S inflation data which was released earlier this week has proven stubborn, this could become a source of pain for investors who may be forced to consider the Fed will not only raise the Federal Funds Rate late July, but later in 2023 also. Short-term traders should monitor this report accordingly.

postN26.1

USD/INR: Bounce Higher Ignites a Return to High Water Values

USD/INR: Bounce Higher Ignites a Return to High Water Values

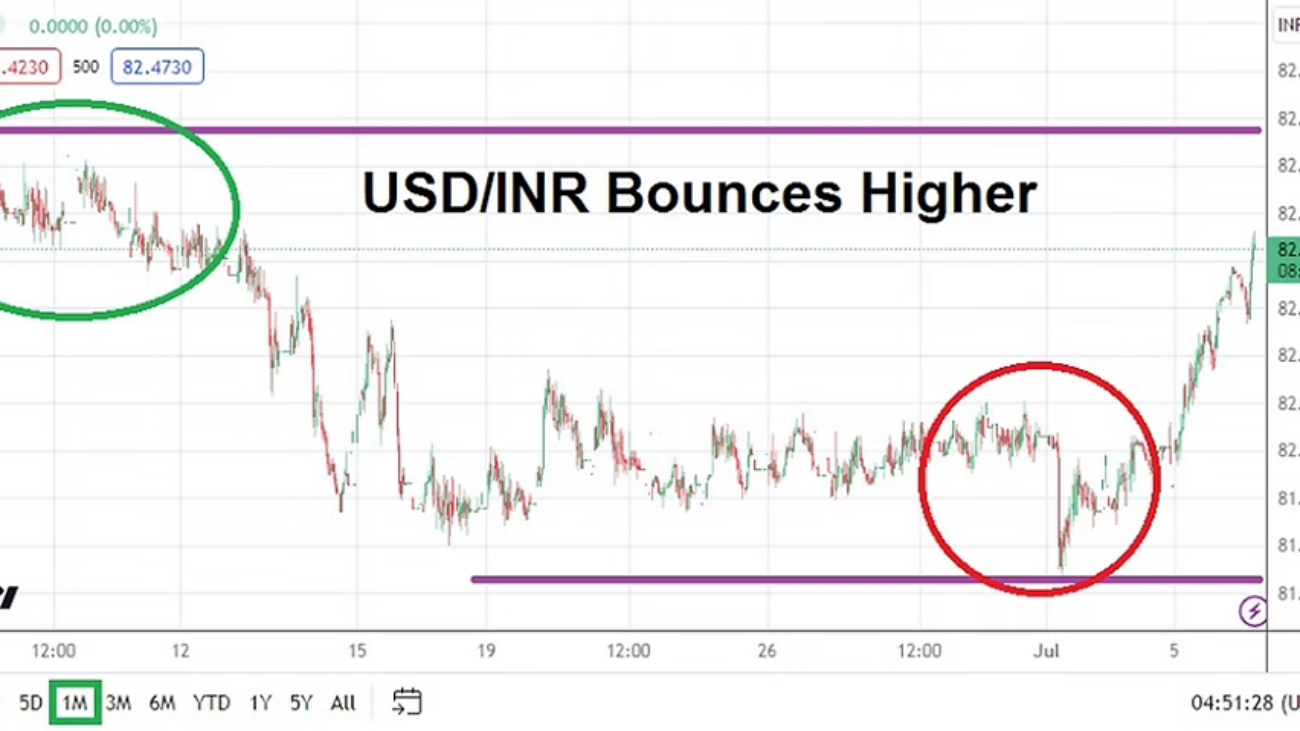
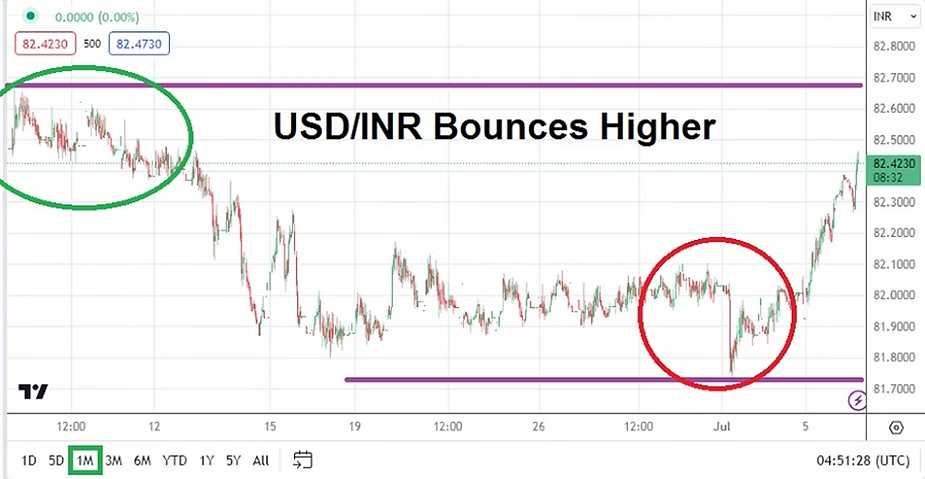
The USD/INR is trading near 82.4350 as of this writing, which is a value the currency pair has not touched since the second week of June. While some analysts may say the move to higher ground yesterday and early this morning is based on the U.S FOMC Meeting Minutes, Wednesday’s report from the Federal Reserve likely only reinforced the bullish momentum which started earlier this week. The world of Forex can feel fickle, particularly when so many of the internal dynamics are hidden from a large segment of people who are trying to speculate on the results.

If the mechanics of the move higher which started on Monday are examined a couple of points should be considered closely, the low of the USD/INR was around 81.7300 on the 3rd of July. This low took place as most U.S financial institutions were on holiday in preparation for Tuesday’s 4th of July celebrations.

Fears of U.S Economic Prospects: Behavioral Sentiment and Stagflation Potential

The reversal higher since the 3rd of July has been pronounced, but before going into last weekend the USD/INR was largely trading within a consolidated manner near the 82.0000 level with a test of this mark having been displayed forcefully since the middle of June. A range of nearly 81.8500 to about 82.1500 largely has played out the past three weeks of Forex trading.

USD/INR One Month Chart as of 6th July 2023

Monday’s dip in value to lows around 81.7300 took place when there was very little volume in the USD/INR market. The depths challenged marks not seen since the first week of May.

The reversal higher the past few days is certainly part of more transactional volume starting to be pumped into the USD/INR as U.S financial institutions have returned, but they are also likely being caused by an underlying nervousness within the Forex markets which may be factoring in the notion the U.S Federal Reserve seems to be on a path which will increase the Federal Funds Rate on the 26th of July.

The behavioral sentiment being generated regarding a Federal Reserve which stays in an aggressive stance started before yesterday’s release of the FOMC Meeting Minutes. Nervous conditions have been on the surface of the broad markets because U.S inflation remains rather resilient – but also importantly because last week’s Gross Domestic Product numbers published on the 29th of June, came in stronger than anticipated. From a troubling perspective some analysts could point to the moderately improved growth and combination of stubborn inflation as a sign stagflation is starting to shadow the U.S, which would certainly be a troubling predicament.

USD/INR Move to New Highs this Morning could Ignite more Nervous Reactions

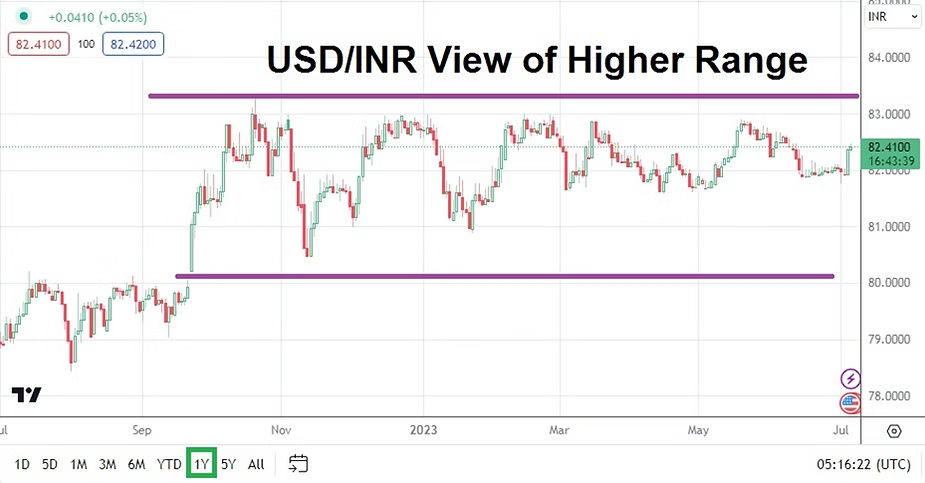
USD/INR speculators may believe the move higher in the currency pair is overdone and that values need to be lower. However, the current price of the USD/INR is one that has been experienced quite a bit since October of 2022. A look at a one year chart shows the USD/INR has returned to higher ratios of its price range which it has experienced since breaking upwards in the middle of September 2022. And to make things more interesting for technical traders, the USD/INR has actually produced a rather stable range between 81.6000 and 82.9000 since February of this year.

USD/INR One Year Chart as of 6th July 2023

While traders are certainly trying to anticipate what will happen next in the USD/INR to gain an advantage, they should remember the currency markets are almost impossible to time on a daily basis, but a look at mid-term prices does offer plenty of insights. If the USD/INR climbs too high, perhaps to the 82.5000 level the Reserve Bank of India could get a bit nervous and consider some type of intervention which it supposedly has done a few times over the past handful of months – but perhaps at higher price ratios.

USD/INR Mid-Term Considerations and the Current Price Range

However it is more cost efficient and reputably less damaging for central banks to not intervene if they do not have to, and simply let market dynamics effectively create a price for the USD/INR based on supply and demand. Meaning the current prices of the USD/INR look to be rather high, but taking into consideration the range of the Forex pair the past five months the values are not new. The prices in fact have been rather established, meaning the USD/INR may trade slightly higher, but then a lower wave of downward momentum could be anticipated.

Day traders who are gamblers may be tempted to sell the USD/INR if the currency pair finds more upwards mobility in the near-term. Trading volumes should be back to normal now that U.S financial institutions have returned from their holidays, and traders should be ready for the potential of fast price velocity developing. Risk management on wagers regarding the USD/INR are essential as always.

postN24

Interest Rates, Fireworks, OPEC, Fed Minutes, and Jobs Data

Interest Rates, Fireworks, OPEC, Fed Minutes, and Jobs Data

Global day traders will certainly be able to work early this week, but they should note the 4th of July holiday in the U.S will deliver rather light volumes Monday and Tuesday. Markets in the U.S will be open on the 3rd, but speculators need to understand that price action may be flat and then experience sudden bursts of energy. Financial institutions in the U.S could be rather quiet until Wednesday.

Monday, the 3rd of July, European Manufacturing PMI – data will come from across Europe and is expected to show the sector remains rather lackluster. France, Germany, the U.K and others will issue reports.

Monday, the 3rd of July, U.S Manufacturing PMI via the ISM – the Purchasing Managers Index numbers are expected to produce a slight rise, but remain under the level of 50. However, any increase compared to last month’s outcome will be an additional sign the U.S economy is battling on and would give the U.S Federal Reserve another reason to lean towards an interest rate hike later this month.

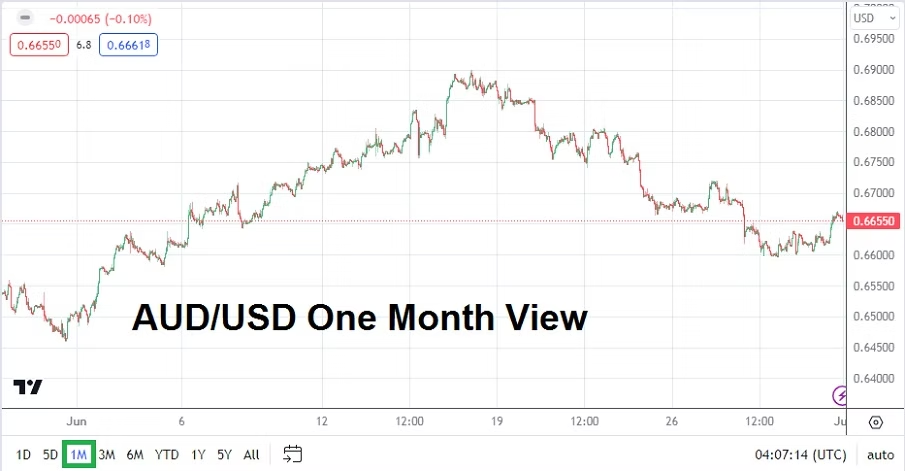
AUD/USD One Month Chart as of 2nd July 2023

Tuesday, the 4th of July, Australia RBA Cash Rate and Statement – while some analysts assume no interest rate hike will be delivered in July because the CPI has shown a slight downturn, there seems to be rather large whispers another hike of 0.25% could be added from the Reserve Bank of Australia. AUD/USD traders certainly need to pay attention, and folks with limited funds should stay on the sidelines until the decision is released.

Tuesday, the 4th of July, U.S Independence Day – banking holiday.

Wednesday, the 5th of July, China Caixin Services PMI – economic data from China has certainly shown signs of downward pressure. A slight decrease is the expected result.

Wednesday, 5th of July, OPEC Meetings – the energy cartel will be conducting its official get together in Vienna, Austria and oil traders should be on alert for any news and decisions made public that could affect the energy sector.

Wednesday, 5th of July, U.S FOMC Meeting Minutes – the publication will provide insights into the Federal Reserve’s decision to ‘pause’ interest rate hikes last month, but could also add fuel to the notion the U.S central bank remains within an aggressive stance regarding inflation. Forex markets will react to the report.

Thursday, 6th of July, U.S Services PMI via ISM – the statistics will be monitored closely due to the rather positive outcome from the GDP report last week, which showed the U.S economy remains rather resilient. A positive outcome in the Services numbers will add further evidence for the Federal Reserve to remain hawkish.

Friday, 7th of July, U.S Jobs Numbers – the employment data will culminate as the week comes to an end with the Non-Farm Employment Change and Average Hourly Earnings figures. Yes, on the day before, Thursday, traders will also see the JOLTS numbers and weekly Unemployment Claims. However, it is the Non-Farm and wages data that financial institutions will largely react upon depending on the outcomes. Because it is a ‘holiday’ week in the U.S, the reports may find a muted response, but financial institutions will use the information to gauge their mid-term outlooks and position their assets including Forex and bonds.

postN23

Fed Spits into the Wind as Day Traders React to Volatility

Fed Spits into the Wind as Day Traders React to Volatility

Broad market analysts continue to spit up an eternal fountain of opinions and data to show why yesterdays moves happened and why tomorrows are going to have bright sunshine and positive outcomes. However, day traders know this is not the reality for them and understand the gyrations and volatility of the marketplace is actually quite dangerous in the short-term.

Day traders may even know market correlations looking backwards are also tales of fiction sometimes. Random results from various fronts are often viewed and assembled by analysts and data providers to give credence as to why ‘John Doe’ lost all of his money, because he was not paying attention to the storm that was ‘obviously’ developing in front of his face. Thus, wiping away any stains of responsibility the analysts and data providers may have for their clients loss of money.

Gold Five Year Chart as of 28th June 2023

Traders seemingly want to know what the U.S Federal Reserve is going to do every minute. If they could, short-term speculators would probably buy information on the amount of coffee breaks FOMC members take, and monitor what Fed officials daily meals are to understand their moods.

However, we should also understand that a lot of the day to day mechanics in the financial markets are tasks that have been done thousands of times before, in other words we know the history and results of many financial institutions. The U.S Federal Reserve is doing nothing new and their actions in July, August and onward really do not amount to much. The monthly decisions and annual manifestations of governments that spend too much cash and their officials trying to balance the value of their national currencies are well documented historically.

Markets in reality think long-term and this is where nearly all of the large money is invested. Day traders need to understand what they are doing is almost considered a ‘hobby’ by investment professionals who do not take the ‘hobby’ of the small speculators very seriously. This because the amount of money most day traders are using doesn’t affect market price very much, unless they form a ‘team’ like the Wall Street Bets ‘crew’ or act in unison via other social media groups influenced by people they mostly do not know personally, and should be wary of regarding motives. Let’s point out for a moment though, that long-term investors can lose money too based on faulty outlooks.

Long-term money is invested with perspectives that stretch often for periods of two to three years and beyond. Outcomes are projected not on data that cause daily momentary values to change, but rather on sophisticated insights which take a perspective the value of equities and certain indices, and other assorted assets tend to rise. Long-term investors mix their outlooks on economic road signs which will be affected by the investing landscape over a period of years. Meaning knowledge of geopolitics, interest rates, social stability and economic transparency are vital. History is a guide post for established financial institutions as they work. But sometimes these factors do not work, and employees at long-term thinking financial institutions find they need new jobs.

U.S Federal Reserve officials, after yesterday’s Core Durable Goods Orders and the CB Consumer Confidence reports which showed strength were published, might have raised their eyebrows. FOMC members likely acknowledged the long-term exuberance and nature of the U.S economy and thought ‘we need to raise interest rates again in July’ because growth data is too resilient. However, they have already said this via their FOMC Statement in June which warned about inflation and why it continues to be a concern, but the ‘words’ thus far have not been taken too seriously.

Yesterday’s reaction in the broad markets was not overly volatile because of the U.S data outcomes. Yes, short-term Forex traders were likely hurt or rewarded depending on the what lucky side of the coin they were betting. However, for the most part many long-term investors have already placed their positions and continue to do so, which they may not alter for the next two to three years depending on the amount of cash reserves they have in their arsenal. This ammunition of large capital, allows long-term players to remain in the game until a result can be quantified – good or bad.

Day traders and long-term investors are playing a different game. Their mode of operations work in different manners. Again, it must be stressed long-term investors do not take into consideration the outcome of most short-term traders, nor for that matter do global central banks. In fact most global central banks and the governments behind them, would rather see day traders simply give their money to investment ‘experts’ who put the ‘little peoples’ money into long-term savings and investment programs.

Speculative cash in the markets does exists, but the amounts of money being used by day traders and large ‘players’s looking for short-term results are quite different. It should also be pointed out that many day traders are using CFD’s – which largely means their positions are being wagered virtually – and are not really being deposited into the ‘cash markets’. In other words day traders can go broke much faster than their long-term counterparts who are investing in positions that have the power of time duration on their side. The virtual positions of CFD wagers are not going into the real cash market, thus not causing a reaction in the actual assets being traded.

Many day traders participating in the daily results of Forex, and equities and indices are merely trading on casino like platforms built for wagering on the results of what is happening elsewhere in the real cash markets of assets. It in a sense, it quite a bit like sports gamblers betting on the outcome of game they are not participating.

Tomorrow the GDP numbers will come from the U.S and the growth numbers will certainly be watched. The results will be consumed differently by day traders compared to long-term speculators. The Final Gross Domestic Product numbers from the States on Thursday are expected to show a slight rise. An outcome of 1.3% was seen last month, tomorrow’s anticipated number is a 1.4% gain.

If the growth number is stronger than expected, this would put the U.S Federal Reserve in a position in which it would almost certainly have to acknowledge another hike to the Federal Funds Rate is ‘needed’ in July. The Fed has learned the hard way that incremental rises in the costs of borrowing (Federal Funds Rate) are not curtailing the spending of U.S consumers. If the U.S doesn’t start to show recessionary like economic signs in the mid-term, the Fed may feel like it has been spitting into the wind. Day traders will find tomorrow’s GDP report causes volatility, but long-term investors will likely view this as just another day with a momentary price reaction.

postN18

USD/INR: Correlation to Broad Forex Market Intriguing Signal

USD/INR: Correlation to Broad Forex Market Intriguing Signal

The USD/INR is near the 82.1200 price as of this writing. On Friday the USD/INR hit a low near the 81.8000 ratio. The ability to touch depths in the USD/INR before going into the weekend correlated well with the broad Forex markets, as the USD was showing signs of weakness globally. Yesterday’s trading volumes were weak because of a U.S banking holiday being observed and only in the next handful of hours will U.S financial institutions return from their long weekend, meaning an increase in volatility could arise.

The lows seen in the USD/INR on Friday challenged values not seen since the 10th and 11th of May. Interestingly support seems to have held technically, and the USD/INR was not able to test lower values seen in the middle of April and the first week of May. However, the trading conditions in the USD/INR appear to be healthy and performing in a manner that can be compared to the broad currency markets, and that is important because it may be a sign that interventions have not been necessary from the Reserve Bank of India the past few weeks.

USD/INR One Month Chart as of 20th of June

Was the Federal Reserve Decision a Pause or a Skip Regarding Interest Rates?

While the U.S Federal Reserve behaved as anticipated last Wednesday and did not raise its Federal Funds Rate, the central bank is still rattling its ‘inflation’ sword and has let it be known it can raise interest rates in July. The decision to not hike borrowing rates in June has been described widely as a pause by U.S Federal Reserve watchers, but if the Fed were to raise interest rates in July the pause would then have to be described as mere ‘skip’.

However, if broad Forex market price action is being interpreted correctly, it does appear many financial institutions are seemingly betting on a less aggressive Federal Reserve over the long-term. The question is if this is the correct outlook. Inflation remains problematic and until consistently solid drops in the costs of goods takes place, the Federal Reserve will remain rather unclear regarding its rhetoric and will likely bang on its higher interest rates ‘drum’ as a warning.

Here Comes More U.S Federal Reserve Rhetoric: Today and Tomorrow

Something USD/INR traders should pay attention to later today and tomorrow are the spoken words and gestures from Federal Reserve officials. New York Fed President John William will be speaking later today and he will certainly be asked about his outlook regarding interest rates. Because he is in charge of the New York Federal Reserve Bank, Williams remarks are watched carefully by the financial markets and his comments will certainly affect Forex and equity indices.

And then leaning into the microphone tomorrow will be Federal Reserve Chairman Jerome Powell. He will present his viewpoints and be asked questions regarding monetary policy in the House of Representatives by the Financial Services Committee on Wednesday. On Thursday, Powell will remain in Washington and perform the same show for the Senate Banking Committee. The Fed Chairman is a trained D.C insider and he will try not to inflame the financial markets with any surprises.

Outlook for the USD/INR is Choppy in the Near-Term

A reversal higher in the USD/INR early this morning has also correlated to the broad Forex market. It is likely the USD has been viewed as potentially oversold in the short-term. However, the slight moves higher might also be a natural cautious reaction to the coming rhetoric from John Williams and Jerome Powell. Because of this USD/INR traders should expect rather choppy conditions to flourish near-term.

Friday’s trading for the USD/INR will get important U.S economic data via the Flash Manufacturing and Services PMI reports. If the USD/INR remains below resistance levels of 82.1500 and 82.2000 consistently over the next few days leading into Friday’s trading, this could mean the broad Forex market remains bearish regarding its outlook for the USD. Speculators should be careful over the next 24 hours. It should also be mentioned that if Jerome Powell doesn’t surprise the marketplace tomorrow, he will not be likely to offer any new information the following day in Washington, meaning tomorrow’s comments from the Fed Chairman are the words likely to cause volatility if this happens.

postN14.1

Anticipated Federal Reserve Shop Talk to be Delivered Today

Anticipated Federal Reserve Shop Talk to be Delivered Today

For what it’s worth, here is my prediction regarding what the Federal Reserve will do today. The Federal Funds Rate will remain unchanged in my opinion. The FOMC Statement may show that the vote actually was debated and not unanimous. The statement is likely to warn that inflation remains stubborn and potentially problematic, meaning the Federal Reserve continues to believe it may have to raise the Federal Funds Rate over the mid-term and again before the end of 2023.

The Forex market has seen the USD get weaker against many major currencies since late May. While financial institutions have seemingly positioned for no increase from the Federal Reserve today, this move has also likely been priced into Forex. Day traders need to understand institutional traders will not be betting on what took place the last three weeks, but are trying to anticipate what will happen into early July and beyond regarding their Forex positions.

GBP/USD One Month Chart as of the 14th June 2023

Many financial institutions may still be betting the Fed will remain more dovish than the U.S central bank wants to admit, but this is a dangerous perception and could prove costly. Financial institutions are concerned about the Fed because they know the central bank has painted itself into a corner it may not be able to maneuver freely within. The battle to conquer inflation while trying to fuel economic growth is not an easy one. Mixed sentiment abounds regarding the U.S economy depending on who is asked.

Talk of a soft landing and a small recession continues to be heard, this while some analysts warn about a hard drop and darker days ahead. Folks, it is all about timelines and their interpretations, experts warning about brighter or darker days ahead have a tendency to be vague regarding exact moments in time. Everyone has an opinion, and people often have more than one.

In my opinion – my one opinion, the Fed is likely to say that it is not going to raise rates today, but may have to do so in the mid-term. If these were normal times and economic conditions were not suffering from huge spending running amok in Washington and the corporate banking sector wasn’t fragile, the Fed may actually have raised the Federal Funds Rate today to continue to battle inflation deliberately. However, a pause for the moment seems like the logical choice, this while ‘hoping’ inflation continues to diminish. And hope is a key word here. Everyone seems to be hoping. The question financial houses and traders need to decide after the FOMC Statement takes place today is how seriously do they consider the Fed’s remarks.

If they believe the Fed will have to continue to remain neutral regarding its mid and long-term interest rate policy, the USD may soften and incremental selling might be demonstrated. Human instinct tends to be optimistic, which means financial institutions and maybe even the Fed wants to believe inflation will ebb lower. If this happens the USD would weaken further. However, the Fed may have to sound more aggressive than people want, but that would damper the mood of financial institutions – so look for optimistic interpretations to abound with rose colored glasses, even if they are wrong in the long-term.

Gold One Month Chart as of the 14th June 2023

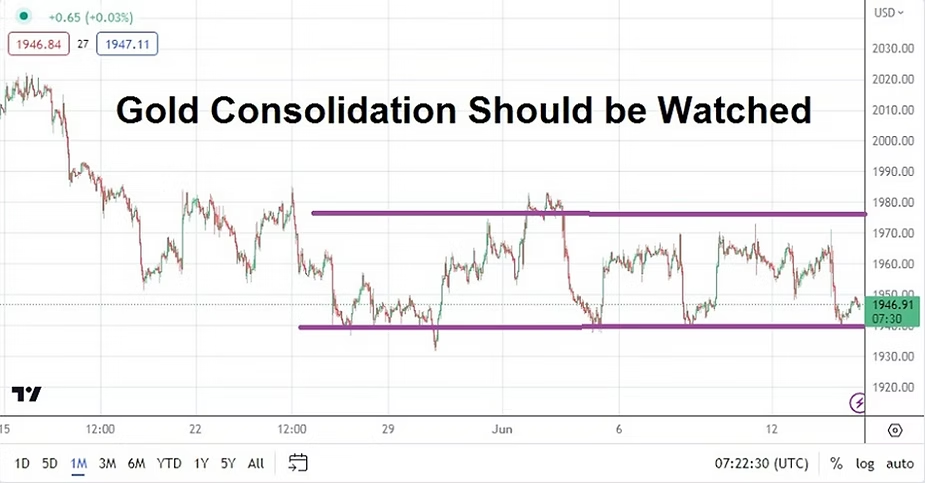
For evidence of outside barometers, traders may want to look at Gold which has essentially traded between 1940.00 and 1975.00 with a few outliers since the last week in May. The price of Gold has seemingly situated within a consolidated framework the past few weeks. The precious metal may produce a strong move if the Fed shows more dovish behavior today, particularly if financial institutions show more optimism via behavioral sentiment in Forex – meaning if a weaker USD trend continues momentarily Gold could traverse higher.

My prediction and $1.00 USD may get you on a bus. As always caution will be needed if you are trading immediately before and after the U.S Federal Reserve’s rate decision. I advise using a seat belt today consisting of entry price, stop loss and take profit orders via solid risk management, but then again these cautious attitudes should always be practiced by day traders.

postN11.1

Week Ahead: Inflation Followed by the U.S Federal Reserve

Week Ahead: Inflation Followed by the U.S Federal Reserve

Monday, 12th of June, U.S Federal Budget Balance – hold down the laughter and snickers please as you wonder why you should care, this as the report shows monthly income versus spending from the month before. Yes, the U.S ‘Debt Ceiling’ bill was passed recently. Very few people are going to pay attention to Budget Balance report, except economists and traders who have ‘skin in the game’ via hedge funds as an example – that make long-term bets, and U.S politicians who want to hoot and holler…….while nothing really gets done to limit wasteful spending in Washington D.C.

Tuesday, 13th of June, U.S Consumer Price Index reports – yes, this inflation data will be important per the monthly numbers showing what consumers are spending. A slight uptick is expected with an outcome of plus 0.2% via the broad statistics – last month’s number showed a gain of 0.4%. The outcome of the broad and core CPI statistics will give the Federal Reserve a sounding board for what will take place on Wednesday via the Federal Funds Rate announcement. Stronger than expected inflation numbers could cause a rupture and nervousness. A weaker result would calm Forex and perhaps make the USD slightly weaker.

EUR/USD One Month Chart as of 11th June 2023

Wednesday, 14th of June, U.S Producer Price Index – these numbers will be released early in the day and will be followed by the Federal Reserve five and half hours later. The inflation outcome via the PPI if stronger than anticipated would cause some caution before the Federal Reserve takes the stage.

Wednesday, 14th of June, U.S Federal Funds Rate, FOMC Statement and FOMC Press Conference – while many analysts seem convinced the Fed will not hike the interest rate this week, there are obviously no guarantees. The FOMC Statement will indicate the U.S central bank’s outlook. Traders who are intent on trading before the official interest rate announcement and statement are playing with fire. Speculators should keep in mind that other central banks have surprised folks with increases recently including Canada and Australia. A hike from the U.S Federal Reserve would surprise a lot of people and financial institutions, but stranger things have happened.

Thursday, 15th of June, New Zealand Gross Domestic Product – the growth numbers which will come out a handful of hours after the U.S Fed leaves the stage will be intriguing and provide NZD/USD traders more impetus into what will likely already be a volatile trading session taking place.

Thursday, 15th of June, China Industrial Production and Retail Sales – these two reports from the economic giant will be watched closely. China’s economy is struggling a bit, and weakness in the housing sector via values are starting to cause a reaction in domestic spending. Industrial Production numbers will give some insights regarding global demand. Economic problems in Europe and North America are certainly not helping matters in China because demand for goods are restrained and hurting the manufacturing sector.

Thursday, 15th of June, U.S Retail Sales – consumers in the U.S have been expected to start producing negative numbers via these statistics, will they begin to do it? A stronger number would be of interest to some, but after Wednesdays’ FOMC Statement and news that will be generated, it is questionable who will give full attention to this report and what affect it could have.

Thursday, 15th of June, E.U ECB Press Conference – this question and answer session could prove to be interesting depending on what the U.S Fed does the day before. Certainly the European Central Bank will give their opinions on monetary policy and economic circumstances in the European Union and abroad. The EUR/USD could be affected.

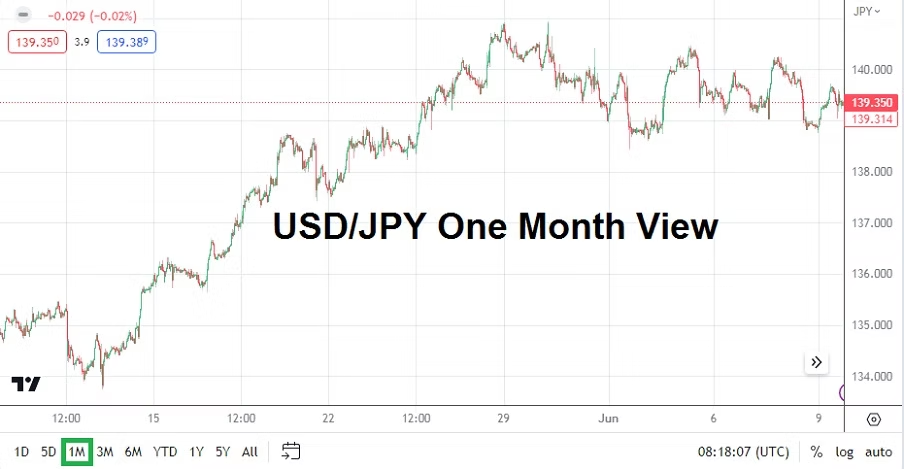
USD/JPY One Month Chart as of 11th June 2023

Friday, 16th of June, Japan BoJ Policy Rate and Monetary Policy Statement – no major changes are expected from the Bank of Japan. This is the one central bank unwilling to change its attitude regarding monetary policy because of the whims of others. Perhaps if the U.S Federal Reserve surprised everyone on Wednesday with a hike, this could change the quiet rhetoric from the BoJ – but even that is doubtful. USD/JPY traders should pay attention to the BoJ Press Conference just in case.