post219

MicroStrategy and Bitcoin: Will They Turn into Smithereens?

MicroStrategy and Bitcoin: Will They Turn into Smithereens?

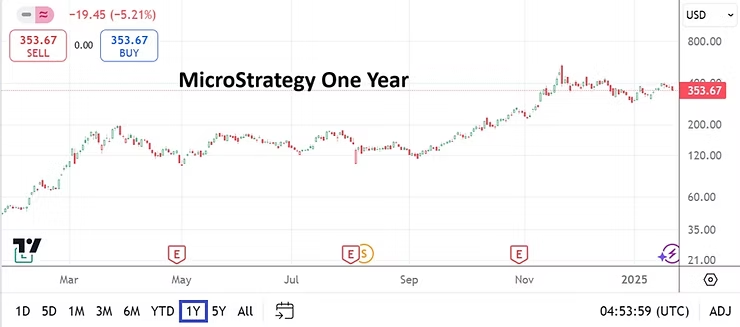
MicroStrategy One Year Chart as of 25th January 2025

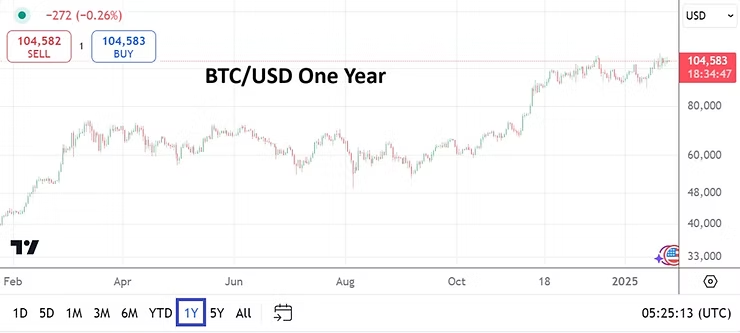
MicroStrategy near 353.67 per yesterday’s close. Bitcoin around $104,625 this morning. Will the balloons keep inflating or become smithereens? The combo of MSTR and BTC/USD are combustible.

MarketWatch has published an excellent article on the borrowing via bonds that MicroStrategy is undertaking with investors. https://www.marketwatch.com/story/why-investors-are-lending-microstrategy-billions-of-dollars-at-0-interest-so-it-can-buy-bitcoin-03f7cacf The article highlights the red hot glow that some investors are pursuing via bets on MicroStrategy and Bitcoin.

MSTR has turned from a data driven company that produces revenue into a proxy bet on Bitcoin. Not everyone is a fan. As of late November 2024 Citron Capital has been reported to be ‘shorting’ MicroStrategy.

Students intrigued by the art of speculation, finance and business outlook have an active case study via MicroStrategy. This is a saga which will continue to grow in stature as investors and speculators seek profits. While the potential for disaster remains high, Michael Saylor of MicroStrategy and his cult like leadership capabilities has led his flock of believers into a golden land for now, but what storms await?

BTC/USD One Year Chart as of 25th January 2025

Naysayers of MicroStrategy’s foray into Bitcoin have thus far been proven wrong. Michael Saylor and his legions will continue singing praises about Bitcoin and its ability to turn into the modern version of gold, but perhaps it will turn into a digital asset nightmare. However, there is no denying the strength of the trend which has manifested the past year in both MSTR and BTC/USD. With the advent of President Trump and his seemingly pro digital asset stance being taken; and the growing desire by some crowds to turn fiat currencies which have been paper based into Central Bank Digital Currencies (CBDC) there are likely years left in this saga to unfold.

There has been a growing clamor for central banks to start holding some of their reserves in Bitcoin instead of gold, but for the moment this seems like too wild a thought and a purely speculative notion. Wagering on the confidence generated by digital hype with little intrinsic value, except the ability to create hot air via rhetoric and lofty visions of grandeur still appears to a step too far for most central bankers. Speculating on MicroStrategy and Bitcoin is one of the ultimate bets looking to take advantage of behavioral sentiment in the digital asset realm. MSTR and BTC/USD are highly volatile and have certainly created profits, but the combination could also turn into a horror if things go wrong.

post217

USD/JPY: Bank of Japan Actually Does its Job: Raises Rate

USD/JPY: Bank of Japan Actually Does its Job: Raises Rate

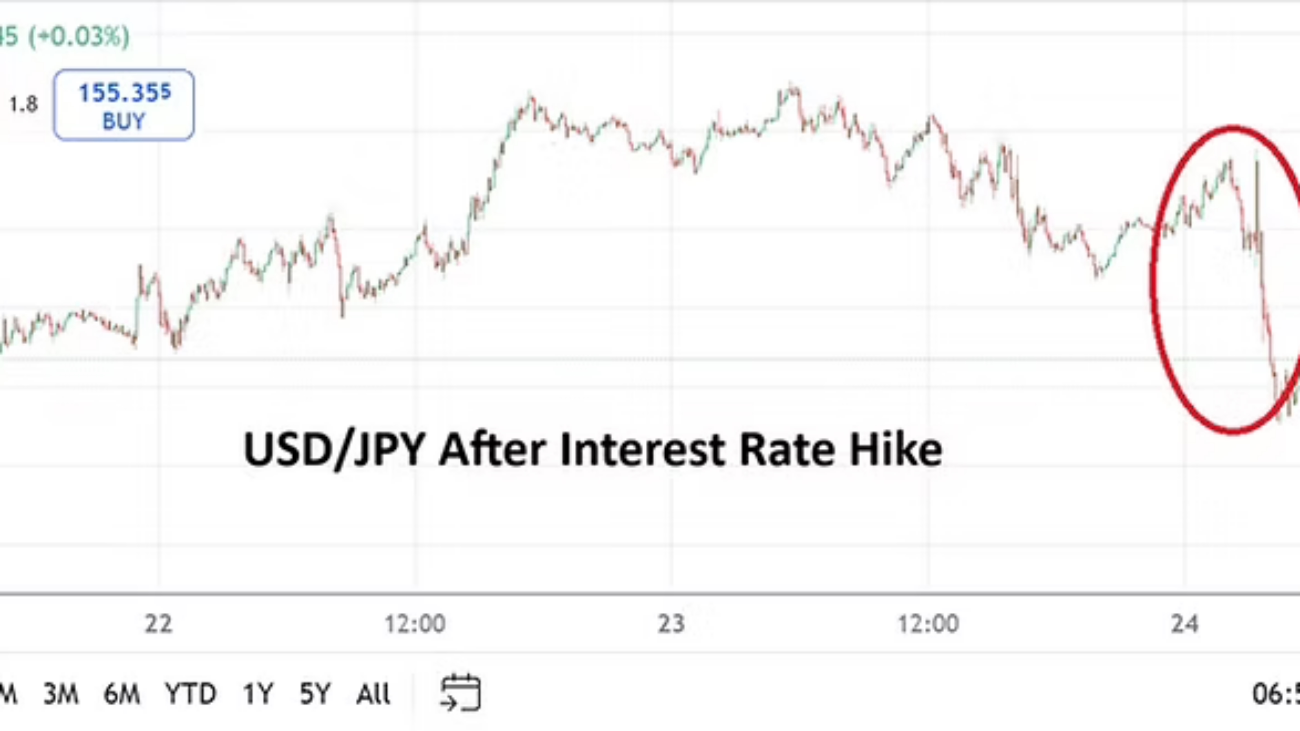
USD/JPY Five Day Chart as of 24th January 2025

The Bank of Japan actually raised its Policy Rate by 0.25 to 0.50% this morning. The move was done while the central bank stated the Japan economy is improving. The Bank of Japan also noted that the implications of U.S tariff policy are not completely known, thus it is acting on existing facts. The action by the BoJ created selling in the USD/JPY and is a healthy sign.

While the U.S Federal Reserve has taken on a cautious tone, President Trump has started to signal via rhetoric that he would like to see U.S interest rates lowered. The Fed and President Trump may find that they are in disagreement regarding mid-term policy and Forex traders shouldn’t be surprised if the debate escalates. The USD/JPY is trading near the 155.500 vicinity with fast price action at this moment. The ability to sustain values below the 156.000 level will be important technically if maintained. A fall below the 155.000 ratio may indicate more selling should be expected.

While financial institutions globally remain nervous about U.S economic policy regarding trade negotiations, Japan for the moment is out of the spotlight regarding tariff implications. The USD/JPY was trading near the 153.000 area on the 17th of December and it will be intriguing to see if large players use this level as a target in the coming days.

Retail traders should practice solid risk taking tactics and conservative leverage. The ability of the Bank of Japan to increase its interest rate, while the U.S Fed is in the midst of considering no changes to the Federal Funds Rate is a potentially solid sign for USD/JPY bearish attitudes.

Global Forex conditions remain choppy, but there has been some buying of the EUR/USD and GBP/USD produced recently. Next week talk of tariffs against China, Canada and Mexico will heighten, but traders need to understand the tough sounding talk from Trump is part of his negotiation tactics. While he certainly seems intent on carrying out his mandate, he will also be open to finding a way to create agreements.

Behavioral sentiment is in charge of Forex for the moment. Outlooks remain unclear, but USD centric strength may be traversing within the apex of its highs in many cases.

post216

Trump Bounce Potentially Coming This Week in Equity Indices

Trump Bounce Potentially Coming This Week in Equity Indices

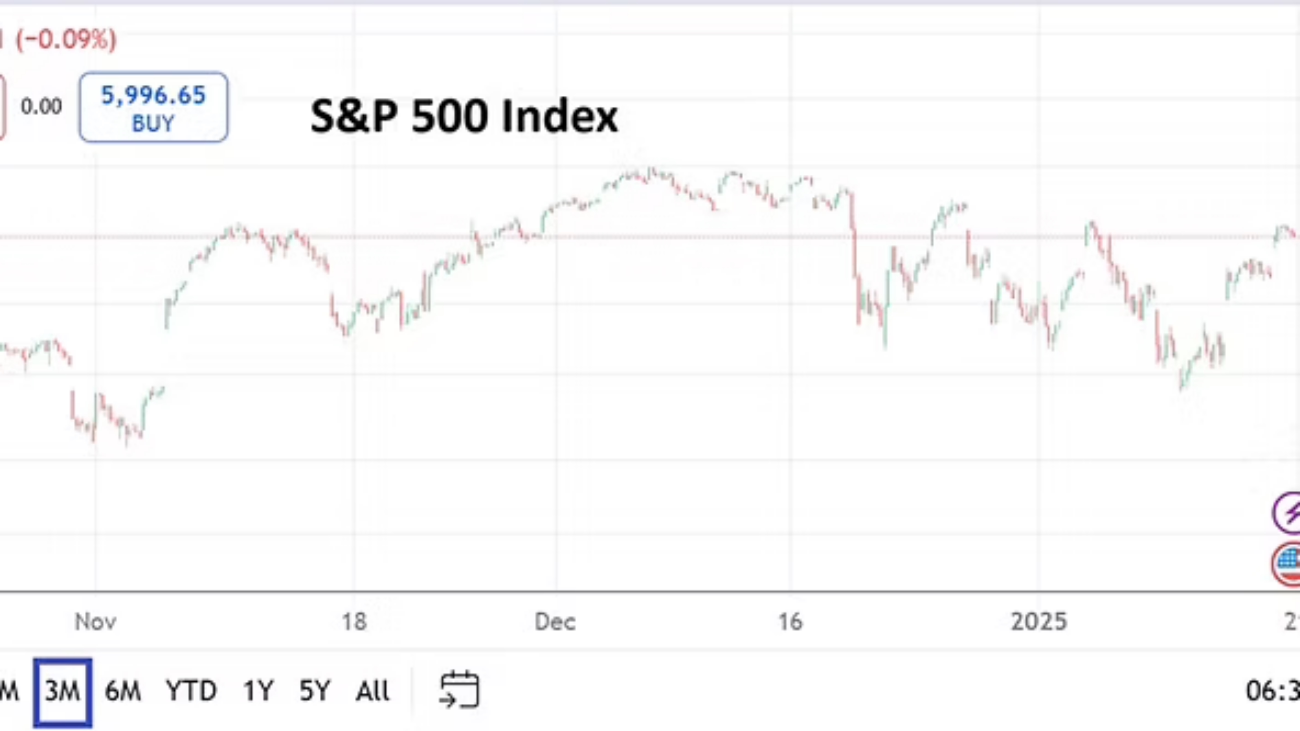
S&P 500 Three Month Chart as of 19th January 2025

Trump: U.S equity markets will be closed Monday for MLK Day. Upwards momentum developing this week as Trump White House takes power would not be surprising.

Retail traders need to know that U.S equity markets will be shuttered on the 20th of January because of the Martin Luther King Jr. holiday. Importantly tomorrow is also the United States Presidential Inauguration. Donald Trump will retake power of the Executive Branch of the U.S government at noon in Washington D.C as he is sworn in as the 47th President. U.S stock markets have produced choppy results the past few months but still remain in sight of highs. It would not be a shock to see optimistic momentum develop on Tuesday in the U.S stock markets near-term.

Yes, financial institutions have known Trump will be taking the White House for two and a half months and have had plenty of time to already react regarding their outlooks. However, from a behavioral sentiment standpoint it is easy to deduce that Trump’s coming inauguration speech tomorrow will deliver a confirmation of his economic policy intentions. Financial institutions near-term may produce optimistic upwards trajectory and they may have psychological targets which take into account late November and early December 2024 highs in the S&P 500.

The coming week will also be light on U.S economic data, except for the weekly Unemployment Claims on Thursday, Flash Manufacturing PMI and Existing Home Sales on Friday. Meaning the week will be driven largely on sentiment generated via President’s Trump’s actions in the coming days. Trump is expected to deliver a series of Executive Orders which will affect outlooks and likely be reflective of his campaign rhetoric spoken the past year.

Retail traders should not bet blindly on upside via CFDs for the S&P 500, Nasdaq and Dow 30. Near-term prices are not guaranteed to move higher, but there is reason to suspect buying might prove positive. An interesting barometer for price action will certainly be seen via future contracts early on Tuesday morning as financial institutions return to full volume and get set to return after a long holiday weekend. Risk taking tactics should include price targets that are realistic and not be leveraged wildly.

Forex conditions may prove volatile this week, and traders need to remain cautious about betting against the strength of the USD which has been ferocious the past three months. U.S Federal Reserve outlook remains murky and cautious, and nervousness regarding Trump’s intended foreign policy changes including trade negotiations still have to be fully demonstrated. USD centric risk bullishness likely still has ammunition which will be displayed in the coming days.

post215

New Year’s Thought on AUD/USD Potential Intervention by RBA

New Year's Thought on AUD/USD Potential Intervention by RBA

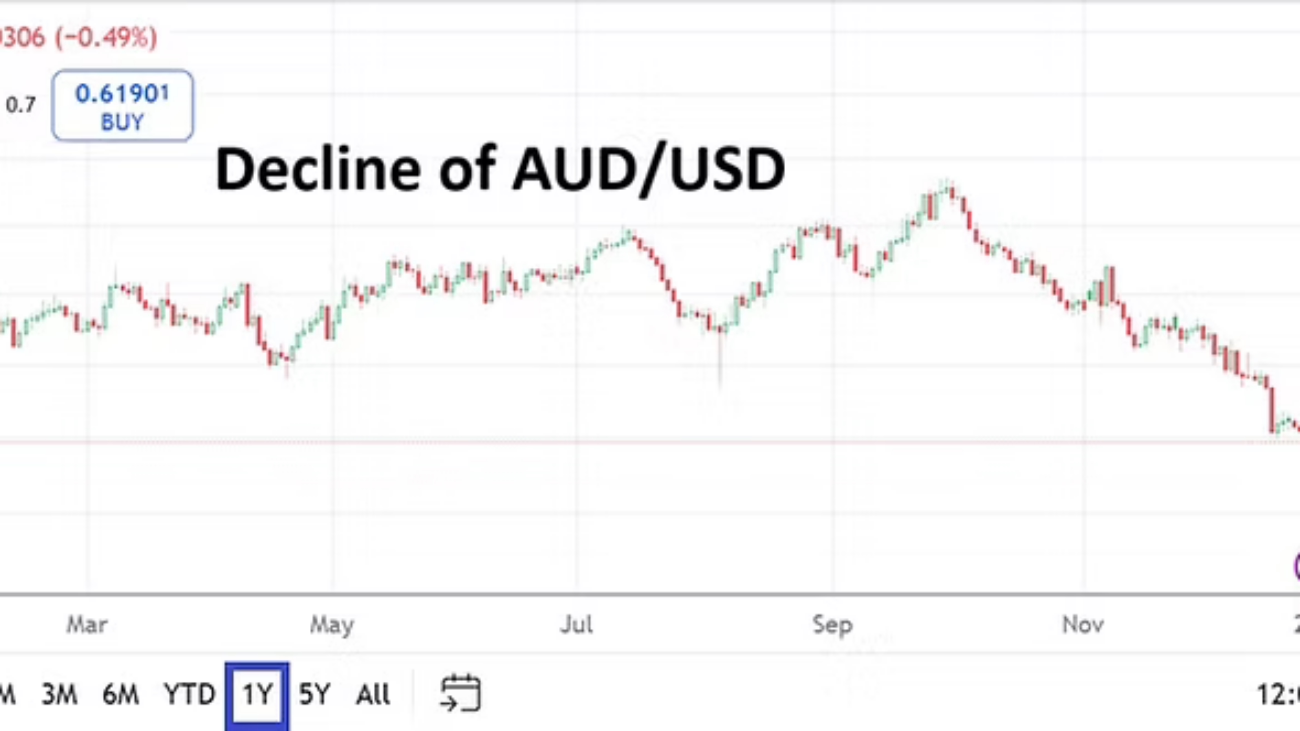
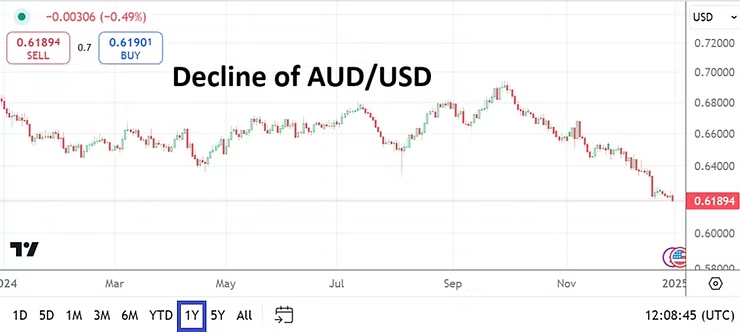
AUD/USD One Year Chart as of 1st January 2025

1 year chart of AUDUSD showing decline and lows as rumors swirl about the Reserve Bank of Australia contemplating intervention due to weak Australian Dollar.

AUD/USD and AMT thoughts: Australia’s govt is led by the Labor party which is socialist based, so it would be no surprise if they and the Reserve Bank of Australia believe (wrongly) they can intervene to help the strength of the AUD, when actually they should work on improving the fundamentals of their economy with solid fiscal policy. But being socialists they don’t know how to do that. Labor is going to lose big in the next Australian federal government election.

post214

Central Banks Noise: Holiday Trading Put on Hold For a Bit

Central Banks Noise: Holiday Trading Put on Hold For a Bit

As suspected the Federal Reserve sounded more cautious than many analysts expected yesterday. While the Fed did cut the Federal Funds Rate by 0.25 to 4.50%, they essentially opened the door to allowing the current borrowing rate to simmer over the mid-term. Yes, they did suggest they would like to lower interest rates, but it sounded more like wishful thinking. In response to the more aggressive rhetoric (hawkish) from the Federal Reserve financial markets became volatile in equities, Forex and bonds.

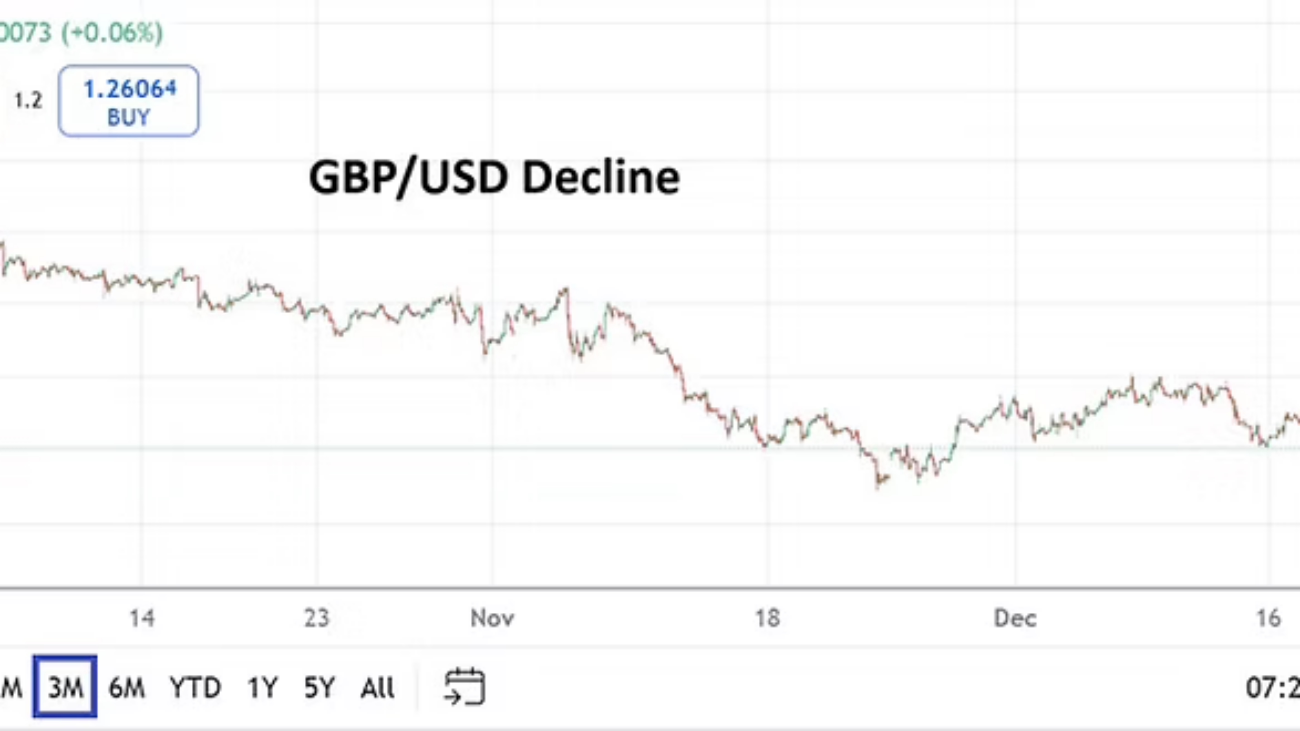
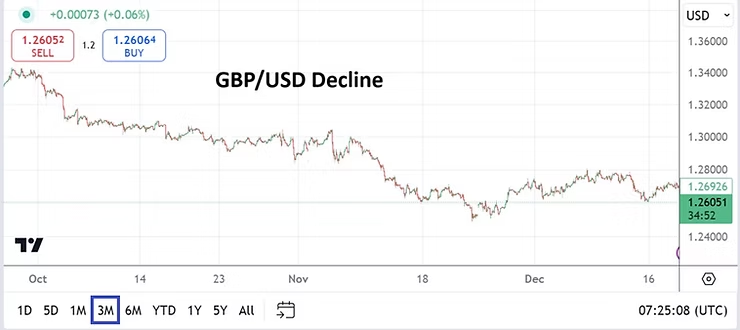
GBP/USD Three Month Chart as of 19th December 2024

The show is not over yet ladies and gentlemen, this morning the Bank of Japan repeated their typical historic stance of proving cautious, and later today the Bank of England will step onto centerstage with their Monetary Policy Summary and Official Bank Rate. And here is where things may get more odd, the BoE in many circles is not expected to cut its interest rate even though the U.K economy has been struggling and continues to publish lackluster statistics. The current borrowing rate via the Bank of England stands at 4.75%. Though the BoE should consider a rate cut of 0.25 certainly, and may even have enough reasons to decrease by 0.50, they may do absolutely nothing and that would be a mistake.

If the BoE decides to remain overtly guarded this will cause some bedlam with the GBP/USD. Large commercial players may choose to punish the GBP/USD as they consider their cash forward positions. Retail traders should be extremely careful if they choose to speculate on the British Pound in the coming hours. Not to say the GBP/USD is going to have a Liz Truss like moment from September 2022 today, but Forex traders have been selling the currency pair based on nervous outlooks over the past three months. If the Bank of England looks at the incoming headlights via the GBP/USD bearish trend and does not move, they might get run over by the truck.

Big and small traders certainly have the approaching holiday season on their minds and they might be getting things in order to take a break for the next couple of weeks, but financial markets because of the central banks actions yesterday and today will not allow for comfortable thoughts. And this is important, because some financial institutions are shuttering for the long holiday starting this Friday, they may be more prone to being quite cautious going into a period where trading volumes will light and assets will be exposed to the potential of sudden gyrations caused by large positions being placed in unbalanced markets. In other words, equities, Forex and bonds will be dangerous today and tomorrow. Behavioral sentiment will be the power.

post212

Cocoa Surges Past 11,500 per Ton, Coffee Flying High Too

Cocoa Surges Past 11,500 per Ton, Coffee Flying High Too

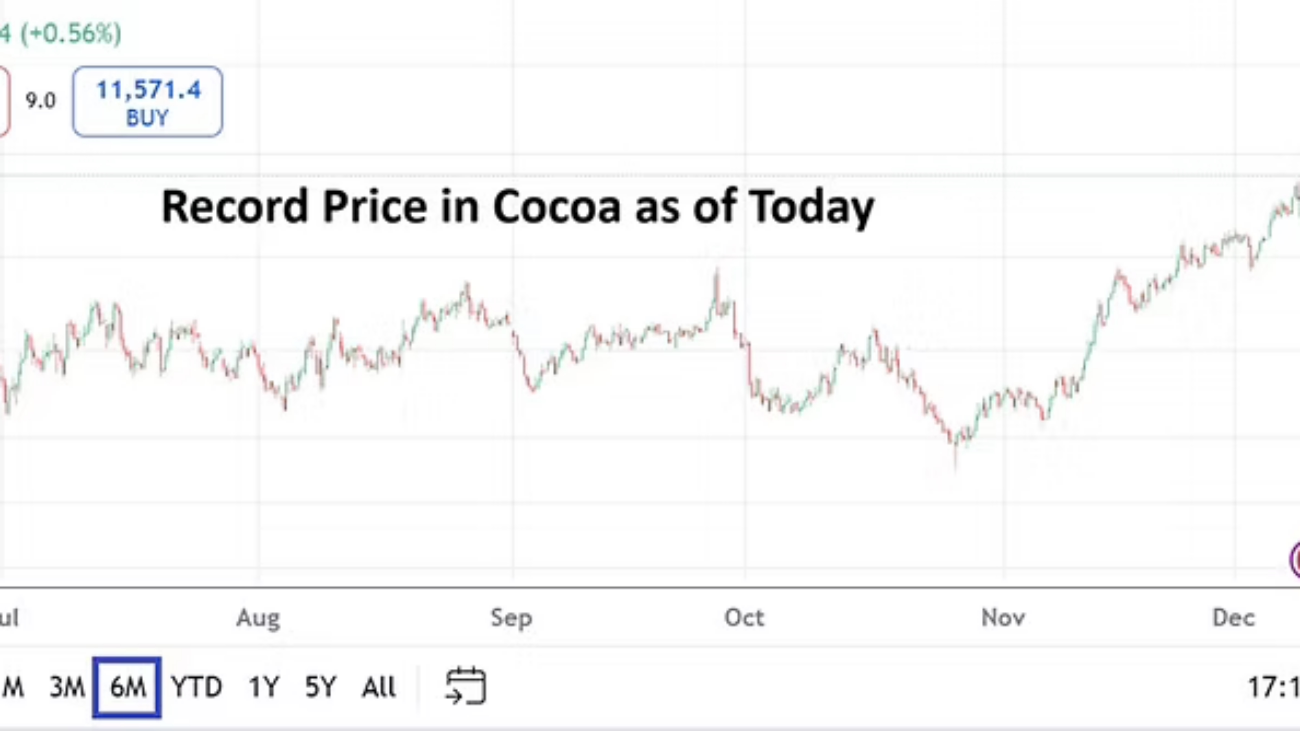
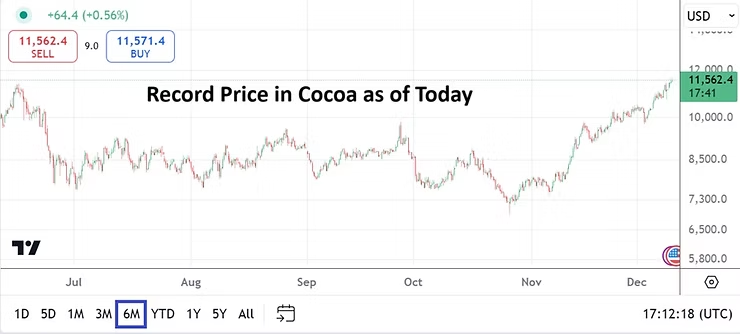
Cocoa above 11,500 per ton as of 10th December 2024

Holiday chocolate about to get more expensive? Cocoa and Coffee futures are hitting highs again. Someone, somewhere is making a lot of money off of the surges.

If you are a day trader trying to pursue these commodities you need deep pockets and conservative leverage (if at all). The reversals higher in Cocoa and Coffee futures since November have been fast and dangerous, even for the large players. The notion the market is overbought is logical, but it has also been fatal for short sellers.

post206

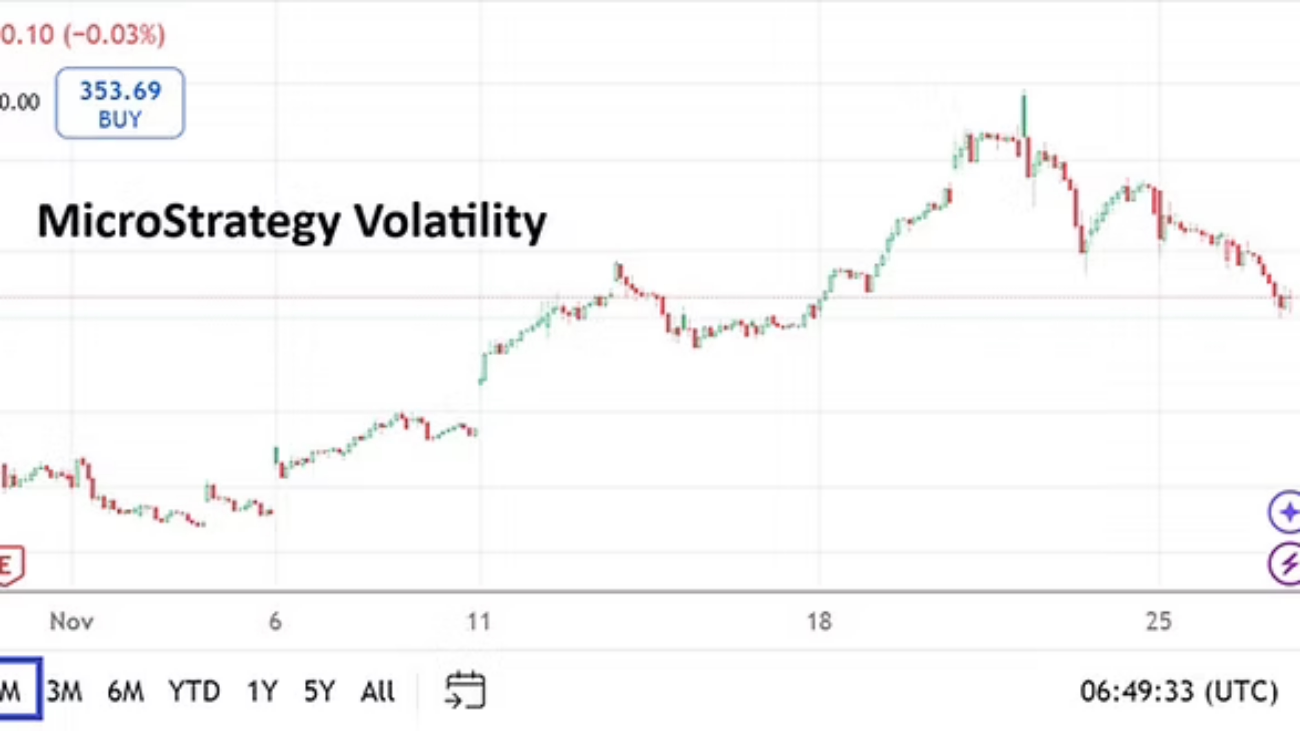
MSTR fell from 400.00 USD yesterday to the 350.00 level.

MSTR fell from 400.00 USD yesterday to the 350.00 level.

MicroStrategy One Month Chart as of 27th November 2024

MicroStrategy went from above 400.00 USD yesterday to the 350.00 level. MSTR is a Bitcoin proxy and speculative. Michael Saylor, the Chairman of MSTR, takes many risks as its leader and appears to have a lot of decision making power when it comes to the company’s corporate treasury purse strings.

MicroStrategy if pursued by retail traders as a CFD or held as a equity in a portfolio needs to be treated as a speculative asset that is highly volatile. Technically MicroStrategy has seen its value correlate to Bitcoin in a well defined manner over the past handful of years. Per current accounting MSTR holds over 386,000 Bitcoin, this per MicroStrategy’s own reporting and publication of a Form 8-K via the SEC.

Its corporate governance has essentially allowed MSTR to become a company that while listed as a data provider including business intelligence, mobile software and cloud based services for users is for all intensive purposes now ‘married’ to Bitcoin as a main driver for its value. MSTR is traded on Nasdaq and the Russell 1000. The company is based in Virginia, USA.

postR198

CPI Meets Expectations but Caution Remains as USD Stays Strong

CPI Meets Expectations but Caution Remains as USD Stays Strong

EUR/USD One Day Chart on 13th November 2024

Initial jump in EURUSD, but caution returned after U.S CPI data met expectations. This was a tame outcome for inflation and Fed doves, but financial institutions in Forex remain risk adverse and USD centric. When will tide turn to bullish perspectives vs. USD? PPI tmrw.

postR194.1

Forex: Dangerous Triggers Abound for Inexperienced Speculators

Forex: Dangerous Triggers Abound for Inexperienced Speculators

While the U.S jobs reports via the Non-Farm Employment Change and Average Hourly Earnings will grab attention today, and the Advance GDP this Wednesday and inflation numbers yesterday were important. Institutional trading focus in many respects will be elsewhere, behavioral sentiment and the potential reactions that lurk after the results from the U.S election are known are the biggest risk threat.

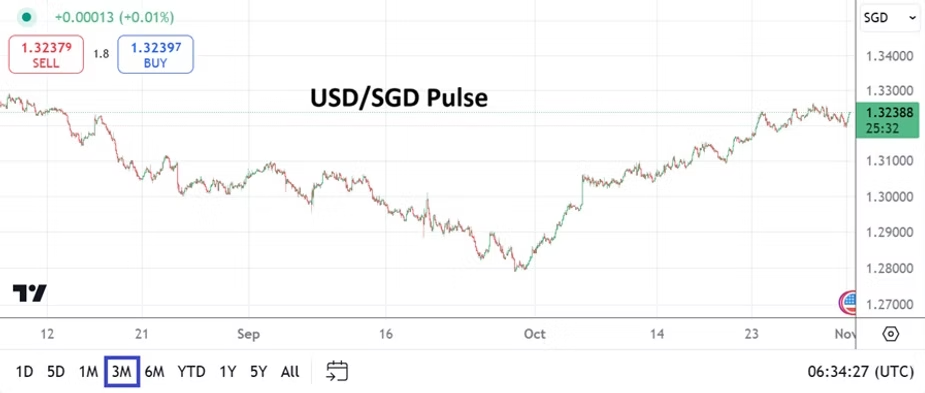
USD/SGD Three Month Chart as of 1st November 2024

Yesterday’s weaker than expected Employment Cost Index will help the U.S Federal Reserve to clip another 0.25% off of the Federal Funds Rate on the 7th of November. However, the winner of the U.S Presidency will be a talking point in the coming FOMC meeting, and also the halls of the U.S Treasury, influencing potential policies. Weaker than expected jobs numbers would fuel dovish perspectives from financial institutions today, but because of the coming U.S election on Tuesday results will fall on ears possibly tuned into other frequencies. And let’s remember last month’s job numbers were stronger than expected, and revisions downward in the back months remains a problem causing mixed sentiment.

Major currencies versus the USD continue to thread within cautious weaker values. USD centric strength has been persistent since the last week of September. If this had been a normal week of trading, the USD would have likely gotten weaker after the Advance GDP results came in slightly less than anticipated. Fuel might have been added to USD selling on yesterday’s lower than expected labor costs too, but this did not happen in many cases. This needs to be a consideration for day traders who are trying to interpret U.S economic data as the U.S election looms. Simply put, behavioral sentiment in the near-term is being more influenced by the race for the White House.

If a trader wants to bet on who they think the winner of the U.S vote will be they need to be careful too, not only because they could be wrong, but if their ‘winner’ takes the presidency, reactions may be more tumultuous than planned. Speculators need to understand that financial institutions too have likely been positioning their cash forward transactions based on who they think is going to win the U.S vote. Meaning wicked reversals and take profit orders could be triggered when the U.S election outcome is known. Forex trading volumes next week should be immense.

Gold Three Month Chart as of 1st November 2024

It is a dangerous time for inexperienced traders to participate in Forex. Brokers will certainly sell this alluring show and point out that there is a lot of opportunity to make money in the coming days, but the opposite is true too. Because if you can make a lot of money from volatility, you can also lose a lot of money. Folks without deep pockets who are using leverage will be vulnerable to price velocity.

Retail traders need to understand the risks that confront them are dangerous because their Forex positions cannot be held over a long-term because of too much carrying costs, too much volatility and frequently too much leverage. Large financial institutions who are the shakers in Forex play by a completely different set of rules. It may help a day trader immensely to understand they can really only feast on profits when they have been able to ride the technical momentum caused by the influence of financial institutions.

The cyclical nature of Forex has been on full display the past three months. Trading within the USD/SGD the past three months is a solid example of a major currency teamed against the USD and sustaining a strong bearish cycle on the expectation the U.S Fed would become dovish, and then the reversal higher since late September as financial institutions started to become risk adverse. While some analysts may argue this point, the coming results in the weeks ahead will tell us a lot as large players react to clarity via a new U.S President and the Federal Reserve’s monetary policy outlook. Traders large and small over the next five days in Forex will be treated to quite a carnival like experience.

postR189.1

Hurricanes, Wars, U.S Election and Inflation Reports Noise

Hurricanes, Wars, U.S Election and Inflation Reports Noise

Between hurricanes, wars, the coming U.S election what could possibly go wrong for day traders? Oh wait, the U.S will also issue their Consumer Price Index reports today to throw some fuel onto the Federal Reserve outlooks of financial institutions. As the loud headlines get attention and try to scare us, it should be noted that markets have actually behaved rather calmly this week. Perhaps volatility was already traded heavily into assets the past week and a half, and tranquility is returning. However, there is the possibility that experienced smart money has simply positioned investments and speculative endeavors, and now await outcomes via objectives in order to react.

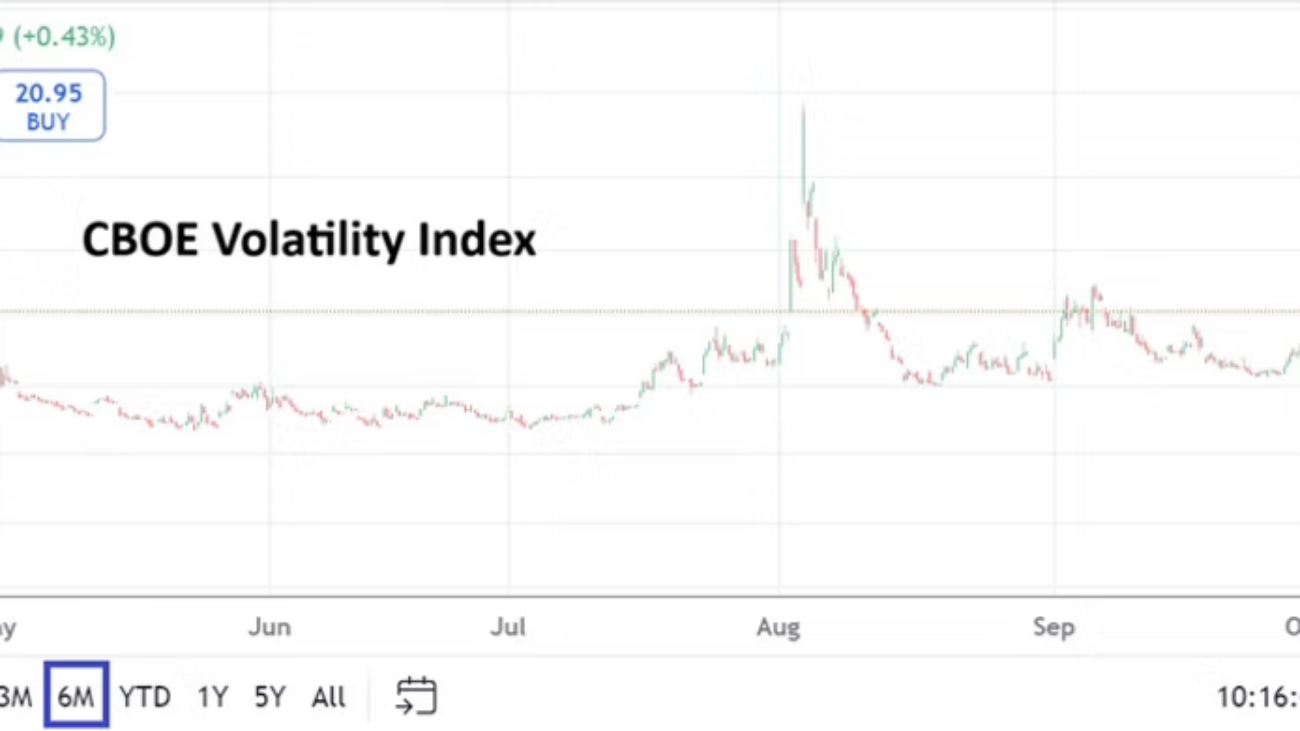
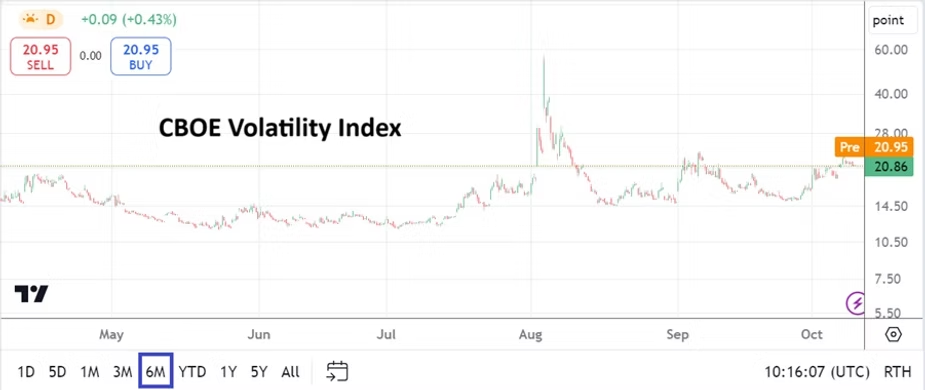
CBOE Volatility Index Six Month Chart on the 10th of October 2024

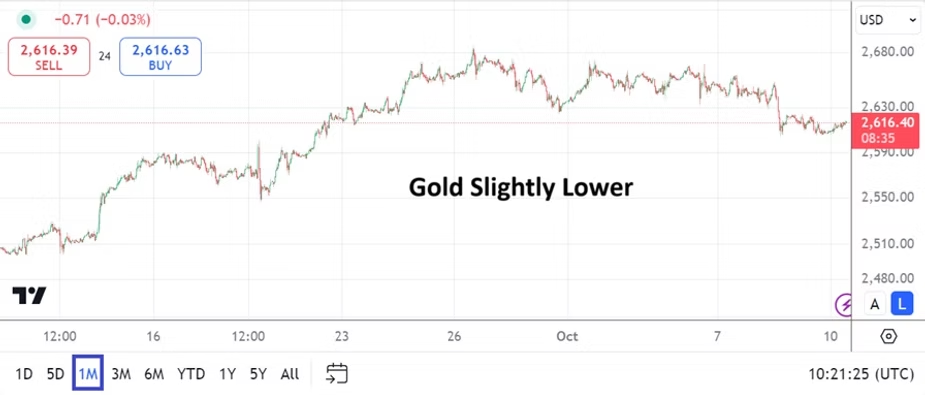
The Chicago Board Options Exchange’s Volatility Index (VIX) has risen since the last week of September, but remains within known realms. Gold while definitely within the higher levels of its long-term price range has ebbed lower during the same timeframes. And WTI Crude Oil while flirting with short-term highs today, actually remains within the known realms of its six month range. In other words while short-term day traders potentially get caught up in fearmongering rants and tremble, financial institutions continue to trade with an outlook that remains rather tame mid-term.

Gold One Month Chart on the 10th of October 2024

Financial institutions were dealt a perplexing blow last Friday when the U.S Non-Farm Employment Change hiring numbers came in stronger than anticipated. However, what is not getting enough attention is another revision downwards to the previous month’s totals did happen. Today’s Consumer Price Index statistics and tomorrow’s U.S Producer Price Index results are expected to show that inflation remains under control. If the coming data meets estimates or can show a slight decrease this could ease the fear of some financial institutions regarding what’s coming next from the Federal Reserve. If higher inflation numbers are displayed this would spark more volatility.

WTI Crude Oil Six Month Chart on the 10th of October 2024

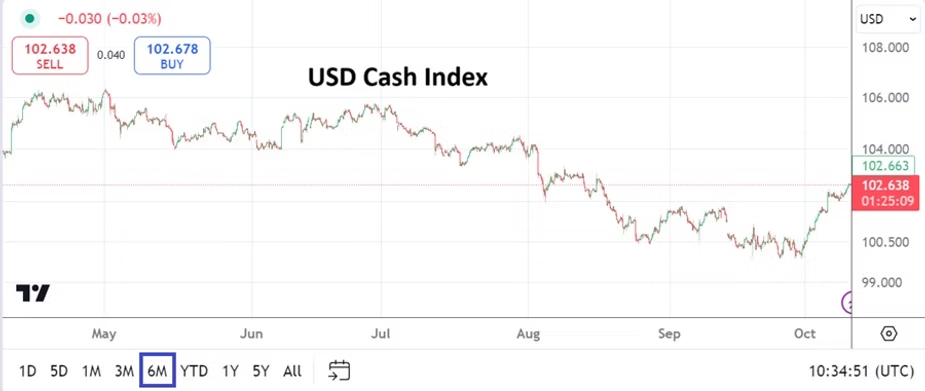
Certainly, USD selling got ahead of itself by the end of September. Day traders need to understand there are seldom one way avenues in Forex. Intraday reversals aside, when equilibrium and outlooks do not mesh via the insights of financial institutions, volatility occurs. The buying of the USD since September’s end has been noteworthy, but it was not entirely unexpected. The CPI and PPI reports from the U.S on the calendar will provide impetus. Let’s see if the markets remain calm as a swirl of other risk events linger in the air. Risk adverse tendencies have caused caution in the broad markets.

USD Cash Index Six Month Chart on the 10th of October 2024

Traders need to know there will be one more jobs report from the U.S on the 1st of November. There are some people around us that no doubt believe the U.S government is showing better than expected jobs numbers to try and ramp up support for certain political candidates. However, if analysts do their jobs well enough and point to the revisions downwards that have been consistently seen, this could help alleviate fear of conspiracies.

The Fed is still in a position to cut the Federal Funds Rate by another 0.25 on the 7th of November. Yes, the FOMC Statement is coming only two days after the U.S election, so the Fed’s decision which will be garnered during meetings on the 6th and 7th will carry some significance depending on who has been elected U.S President. While U.S economic data has been mixed via a combination of jobs numbers which had been faltering until last week, and consumers suddenly showing greater confidence and manufacturing sentiment in important sectors with improved optimism, interest rates are still high. The Federal Reserve has a dilemma and likely will want to try continuing to incrementally cut borrowing costs when they have the opportunity.

Day traders should not be too concerned with what will happen a few weeks away, particularly when they are interested in the results of trades consisting of a few minutes, half hour, and other limited durations. But they should always understand their positions in Forex, equity indices, commodities, and elsewhere have little to no effect on the real marketplace. Day traders need to be able to catch onto the technical trends and behavioral sentiment being created by larger players and financial institutions.

postR196

AMT Top Ten Miscellaneous Concerns for the 6th of October

AMT Top Ten Miscellaneous Concerns for the 6th of October

10. Ya Gotta Believe: The New York Mets are finding ways to score in the late innings. Having won with last minute runs against the Atlanta Braves in the 8th and 9th innings early last week to save their season, hitting a home run to take the lead against the Brewers in the deciding game of the Wild Card in the 9th, and last night’s 5 runs in the 8th to take the lead in Game One against the Phillies in the Division Series has been rather remarkable. Game two between the Mets and Philadelphia will be played later today.

9. Information Technology: OpenAI’s value is now estimated around 157 billion USD, this after their latest round of investments garnered that includes both Nvidia and Microsoft funding. The search engine arms race will continue to get tougher and more competitive, but recent data released by Statcounter shows that Google still has over 90% of the U.S search engine traffic. While it has lost some ground in the search engine battles to upstarts statistically, Google remains dominant. Microsoft has made inroads with Bing, and Yahoo has also gained, but Google’s stranglehold via browser usage remains strong.

8. Helene Meets Milton: A pair of hurricanes – this if Milton fulfills forecasts and becomes a major storm – are not helping create easy days in the U.S Southeast, nor for the Biden administration. Criticism regarding a lack of government help has been heard in the aftermath of Helene and with another potential punch about to be delivered by Milton, U.S relief agencies like FEMA will certainly be pushed to the limit organizationally.

7. Oil Alerts: WTI Crude Oil went into the weekend close to 75.00 USD per barrel as nervousness increased about the potential of an attack on Iranian oil infrastructure. While many nations in the West do not purchase Iranian Crude Oil openly, the Iranian commodity is sold to China at nearly an 89% ratio. This allows oil from other suppliers like Saudi Arabia, the U.S and Mexico to sell elsewhere and the price of Crude Oil to remain relatively tame. However, if the supply of Iranian Crude Oil were suddenly to be crippled for any length of time, the price of the commodity from the other major suppliers would certainly go higher if expanded demand needs to be met. Speculators should pay attention to strike prices in the energy sectors via options trading in the future markets to understand potential vulnerabilities that large players may be anticipating.

6. Precious Metal: Gold prices remain within sight of record values, but below the apex values seen on the 26th of September. Risk sentiment, speculative forces and long-term investors are seemingly creating resilient support levels. Gold went into this weekend near the 2,653.00 USD ratio. Silver remains near 32.00 USD per ounce, which is where its price was traversing in May. Speculators intent on betting that silver will rise because nervous market conditions will create more demand need to be careful. A vast supply of silver exists in known mines globally, and producers simply need to extract more of the commodity to garner profits which is relatively easy. In other words, gold and silver do not correlate as much as some people believe.

5. Forex Chaos: Day traders of USDJPY, NZDUSD, EURUSD and a slew of other major currency pairs were taken on a wild ride last week as USD centric strength surged and fragile conditions in global markets grew. The coming days will remain difficult for FX retail traders as they face a whirlwind of threats. Technical and fundamental traders are being hit by shifting winds generating via a myriad of worries. Speculators without deep pockets are advised to remain cautious in the coming days because trading dynamics are not likely to ease. Yes, there will be price velocity which allows for quick profits, but those who are willing to bet on the prospects of fantastic gains must also accept the dangerous proposition that wildly expensive losses if they are on the wrong side of a trade are equally possible. Brokers will certainly welcome their clients with open arms this coming week because the volatility may entice many with the potential of getting rich. However, brokers will not tell you about the poor house on the other side of the street.

4. Unscripted: There are a little more than four weeks before the 2024 U.S elections on the 5th of November. Trump appears to be gaining momentum in polls, but certainly remains vulnerable per his ability to speak without a script and create verbal firestorms. Kamala Harris ran into problems recently with a suspected malfunctioning teleprompter and her inability to escape repeating the words ’32 days’. While the two candidates battle for voter supremacy, questions persists about the current leadership from the White House and who exactly is running the show.

3. Noisy Data: The Federal Reserve and economic data remain concerns. This Thursday the Consumer Price Index data will be released. If the inflation statistics can come in below expectations this may soothe financial institutions who have leaned into the notion the Fed needs to remain aggressive in November. Another interest rate has been expected, but some are nervous the Fed may not be able to cut as fully as wished. However, day traders need to also understand politics are playing a role in the bombastic soundbites being generated by the media, this as they try to deliver messaging which reflect their viewpoints. If inflation numbers remain under control the mid-term outlook continues to point towards more interest rate cuts. While the U.S jobs numbers on Friday were better than expected it should be noted revisions downward were seen again. There is one more Non-Farm Employment Change report before the election, by then it will probably not have an impact on potential voters, but its affect on the Fed will certainly be felt.

2. End Game: As the Iranian and Israel conflict escalates and threatens to become a dark spiral, some are still hoping for an avenue which will allow normality to return. That appears to be wishful thinking for the moment. Reports, perhaps paranoid, regarding an earthquake in Iran yesterday with a magnitude 4.5 seismic rating which was 48 kilometers from Semnan was noted by the USGS. The reason why it is potentially scary notion is because some are questioning if this was a nuclear test being conducted by Iran.

1. Risk Adverse: A trifecta of nervous behavioral sentiment is shadowing the financial markets via Fed outlook, Middle East tensions, and the approaching U.S election. Unfortunately none of these components are likely to disappear soon and in fact may grow in stature as outlooks potentially create more anxiousness. Safe havens in the USD, gold and U.S Treasuries may find they deliver some calm for those that are nervous. However, it must be noted that U.S equity indices gained nicely late last week after gains on Friday. The Dow 30 and S&P 500 remain near apexes and the Nasdaq Composite is within sight of highs. In other words, for all the talk about dark days, financial markets and investors are still active.