30 Year Govt Bonds 20260820

Bond Yields: The Wheel Has Not Been Rediscovered

Unintended Consequences: USD and Gold will now get their turn in the casino because of Scott Bessent's QA

Treasury Secretary Scott Bessent’s decision to begin injecting money into U.S Treasuries needs to be looked at by Forex traders. There is reason to suspect USD centric weakness may prevail moving forward. 

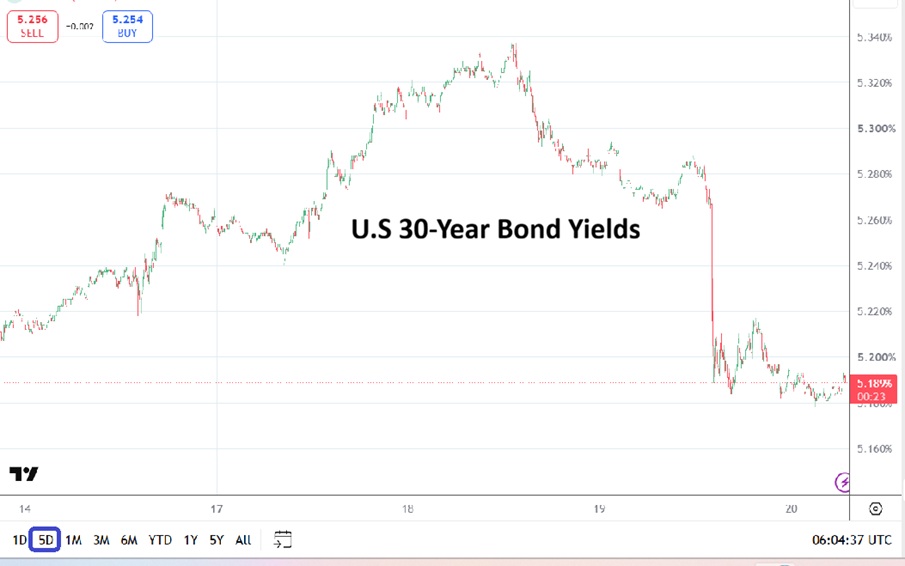
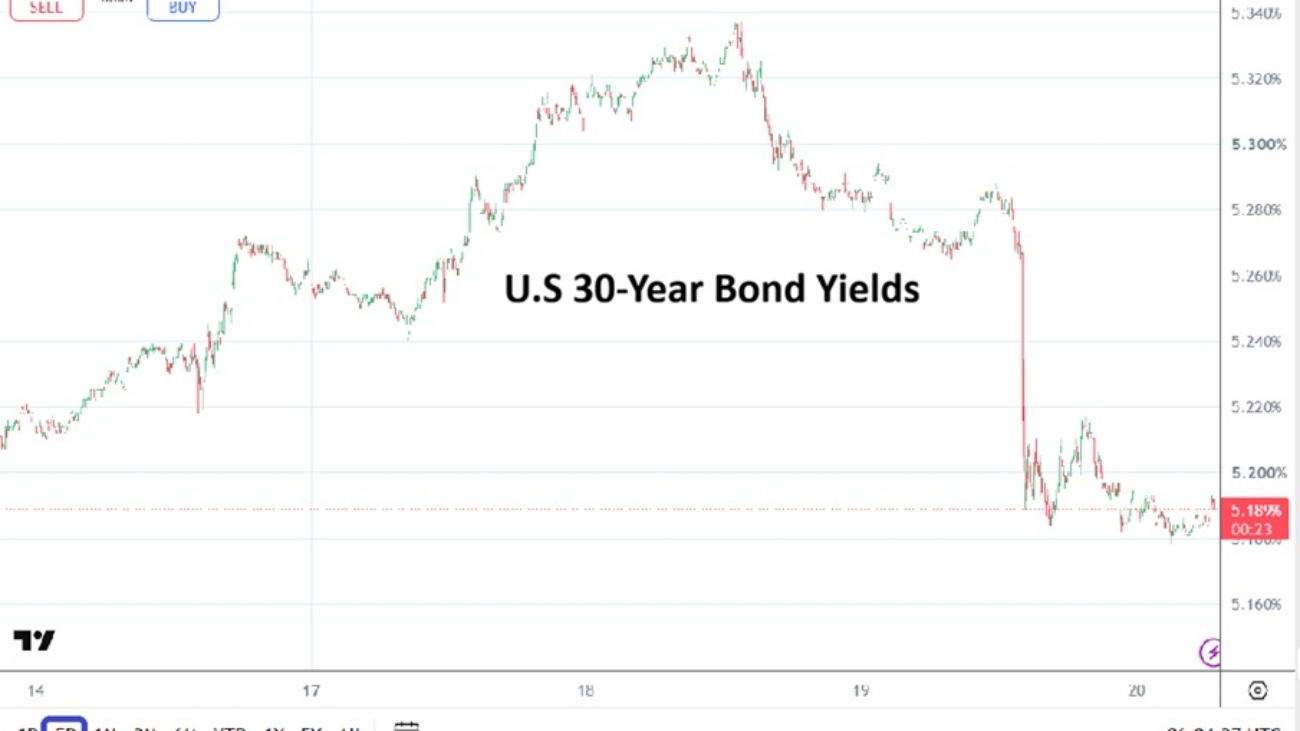
Yesterday’s bond news regarding Bessent’s actions to fight the higher yields in U.S 30-Year Bonds has brought rates down from almost 5.28% to nearly 5.18% as of this morning. 

U.S 30-Year Bond Yields 5 Day Chart as of 20 August 2026

Perhaps market results and dynamics can be quantified as math within a game, but at the end of the day it is behavioral sentiment that drives market forces and the way financial institutions react. Psychology can be looked at as the reaction via the marketing/influence of policy positions and presentation.

We have been down this road before. The decision to announce a round of quantitative easing yesterday via Treasury/Fed intervention should be compared to what the same team did a couple of weeks ago regarding its powerplay with the Bank of Japan in order to make the JPY stronger. We are now in a definite cycle in which government institutions are battling investors to stop momentum in certain assets when policies have gone bad.

The wheel has not been reinvented. It may seem like an unfair advantage to traders betting against government policies that are interpreted (correctly) as being misguided or unwise, but these are the rules of the game. Large players who have been betting on U.S Treasury yields to increase were likely not happy yesterday, but they should have known the U.S government would not sit idly and simply allow an implosion of the financial system to occur.

Having said the above, now we can look towards the realm of unintended consequences. The U.S Dollar Index dove yesterday with USD centric weakness and gold soared. And as long as folks refuse to buy U.S long-term Treasuries on the cheap and demand higher interest rates to protect their investments the potential of further unintended consequences will occur. 

Scott Bessent handled the situation perhaps correctly yesterday, but he is dealing with symptoms and not the cause of the virus. A lack of clarity clouds global central banks and monetary policies connected to their interest rates. Inflation concerns persists and so does the debate regarding how to battle this illness.

The U.S Fed and Chair Kevin Warsh have a major task ahead regarding interest rate policy.  And government’s – particularly the U.S – have to decide if they can actually stop the bleeding. For the moment this appears to be a tall order because by injecting digital money into U.S long-term bonds the U.S is spending money that it really doesn’t have, except to say that this is a game of chicken in some respects and financial institutions could be faced with the dilemma of cutting off their nose to spite their face. Where are Friedrich Hayek and Milton Friedman when you need them?

Copy and paste the text from AMT that you want to share

Share:
Singapore Dollar 20260818

Forex: Compressed Tight Realms Signaling Nervous Reactions

Sentiment Storms as Financial Institutions Remain Unsure about Outlooks

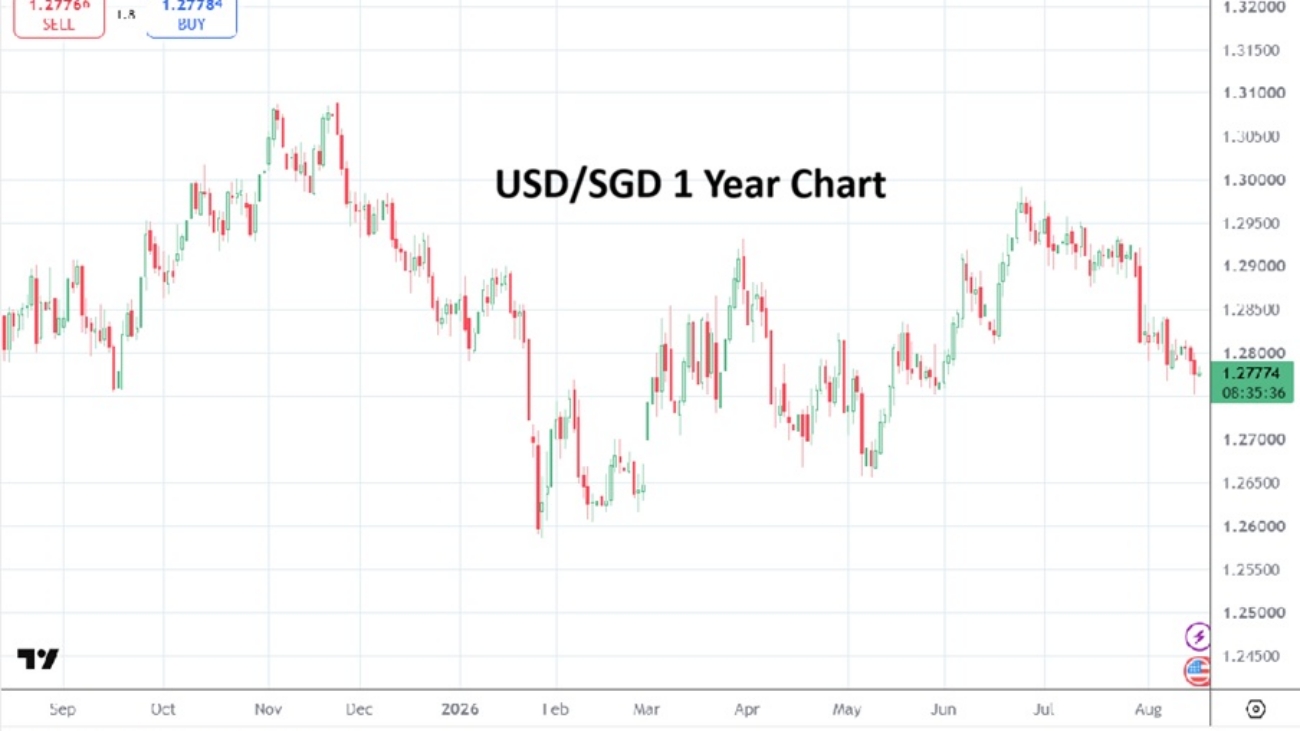
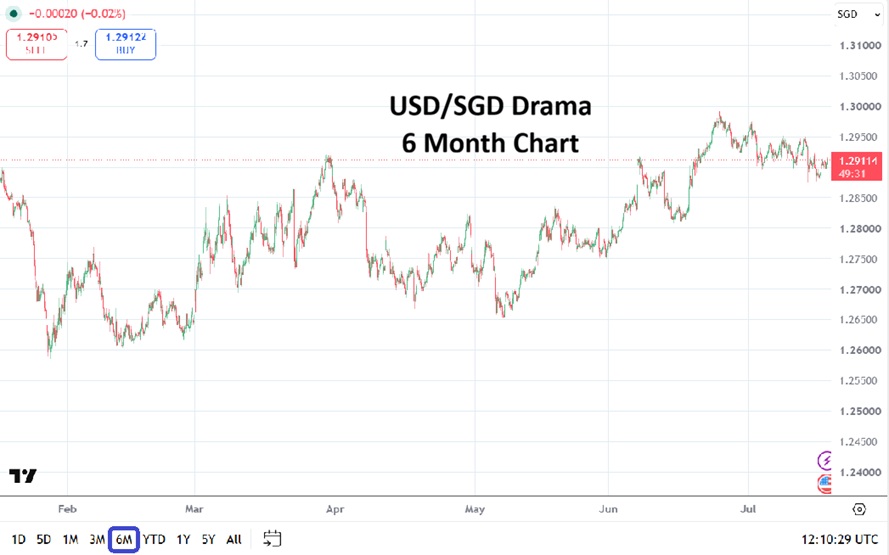
Price action in the USD/SGD has continued to demonstrate a rather significant turn downwards since the last week of June. The price of the currency pair is near 1.27800 as of this writing and is traversing near values seen the 1st of June and towards the end of the first week of March. Importantly, the USD/SGD has also seen recent lower depths and was below 1.27000 in the second week of May.

The USD/SGD traversed deeper ratios in late January when the 1.26000 vicinity was challenged and these levels were sustained until the middle of February. On the 26th of February the USD/SGD was near the 1.26500 mark. Now that the above numbers have been established, let’s discuss why this is potentially important for Forex traders as developing trends surface.

The past few years of trading have seen a compression of Forex deviations, in other words the FX market has grown more tame. However, the Bank of International Settlements (BIS) now reports that over 9.6 trillion USD in value is traded daily. This is a stark increase compared to 2022 when Forex saw an average daily market around 7.5 trillion – meaning there has been a 28% increase over the past four years.

USD/SGD One Year Chart as of 18 August 2026

The scope of volume is presented not to cause fear, but to show Forex traders what is at stake and the size of the marketplace and its potential for sudden jolts of volatility if it is established. 

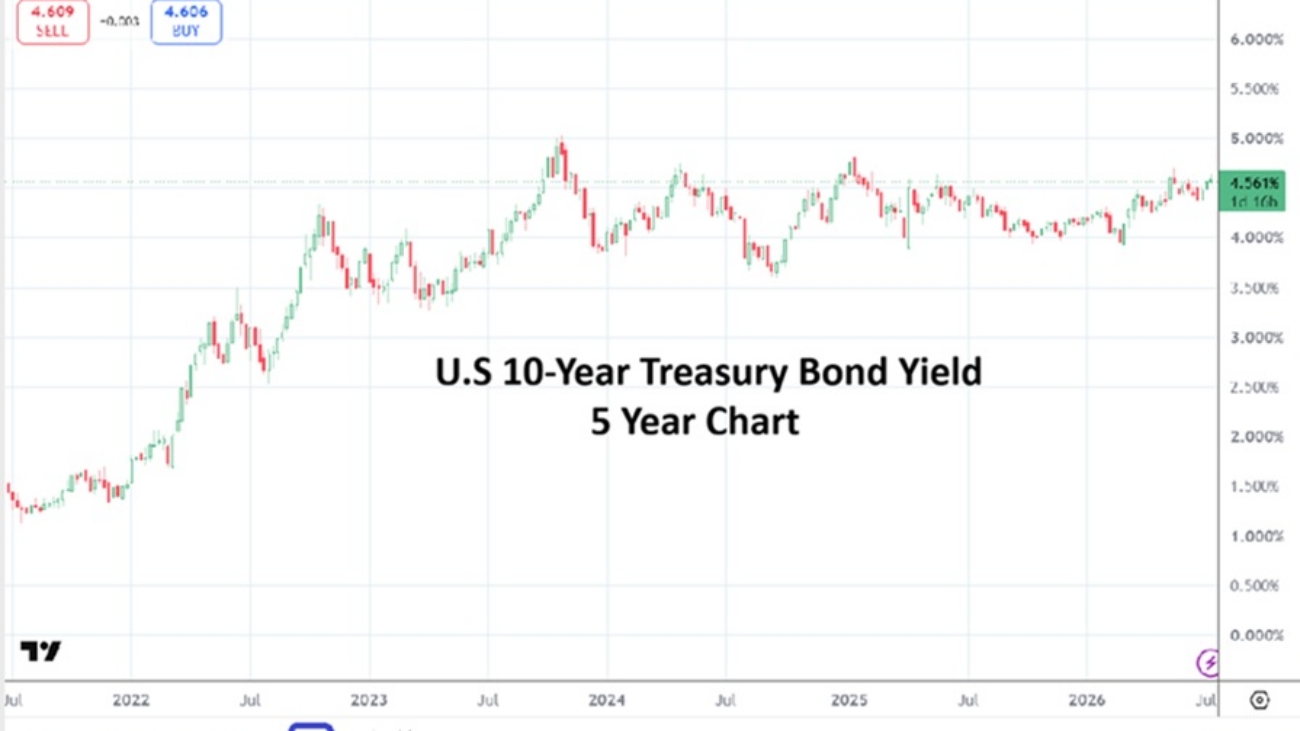
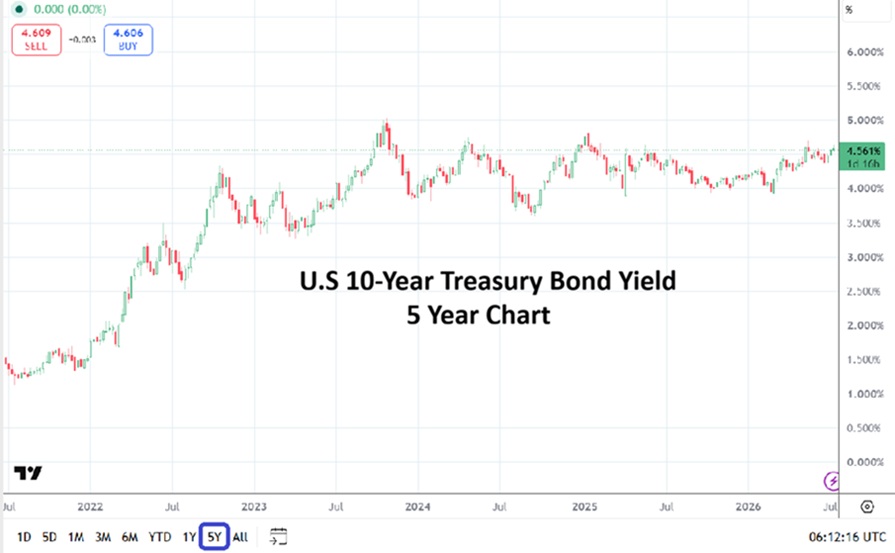
Turning our attention to the new Fed Chairman Kevin Warsh and his preference to not give concrete forward guidance is important. U.S Treasury yields are dangerously high (the 30-Y yield is near 5.31%), and the military conflict between Iran and the U.S  continues to fester. Threats remain on the horizon which need observation, insights that prove correct regarding how these bits of information will influence the Fed Chair and the impact on the USD could prove significant for financial institutions.

Large players have reasons to be critical about a lack of clarity and this might spark more choppiness in Forex – even though value realms are said to be in a compressed state. This opens the door for technical traders who may have a better gauge on existing behavioral sentiment of the Forex markets compared to fundamental traders who have too many tea leaves to interpret which are moving rapidly as the cup gets shifted. Technical traders may have a good sense of where algo trading is directing its velocity per current Forex sentiment. 

While some analysts make a case for an increase to the Federal Funds Rate because of inflation concerns, what happens if they are wrong? And what if large players are now discounting their initial fears regarding higher interest rates and are actually starting to position themselves for the Fed Funds Rate to remain the same or be lowered in the mid-term? Is this one of the reasons why the USD has become weaker recently?

What if the new Fed Chairman Kevin Warsh proves stronger than people believe and has the ability to talk lower interest rates into reality? The U.S Treasury faces a huge and expensive task trying to pay off the yields of the high flying 10-Year and 30-Year bonds. What if Treasury Secretary Scott Bessent who has a solid relationship with Fed Chair Warsh proves influential? Read AMT’s Charles Najjar’s article on his thoughts about why the Fed should aim for a 2% Fund Rate: https://www.angrymetatraders.com/why-the-us-fed-should-lower-interest-rates-to-2/

Yes, the Middle East situation remains troubling from a mid-term economic viewpoint regarding the implications on WTI Crude Oil prices and ancillary energy costs globally. Inflation must be battled, but is raising the Federal Funds Rate going to help decrease the cost of energy or lessen its demand? Mostly likely no.

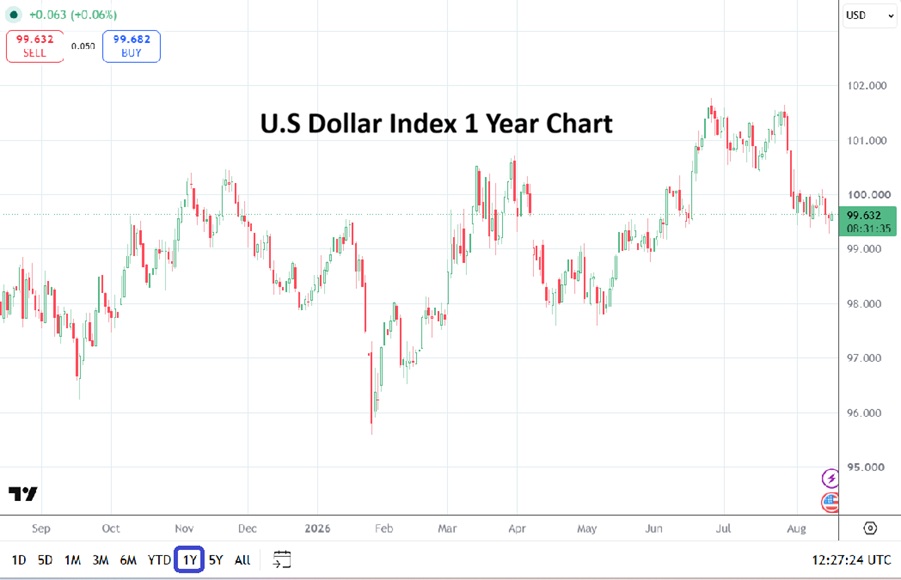
U.S Dollar Index One Year Chart as of 18 August 2026

The gold market has started to show signs of price velocity the past couple of weeks. The precious metal is trading near $4,395.00 as of this writing. Investors with a long-term window and troubled perspectives about the health of the USD have plenty of reasons to be more comfortable holding gold compared to staying in cash. 

U.S equities have been doing well via indices, but nervous shadows are hovering (maybe they always are). And this is why diversification is always important via long-term investment. Equities, bonds, gold and a small proportion for speculative purposes – this for those who want to try and increase their wealth while maintaining a status quo regarding preservation of wealth.

However, from a speculative standpoint, the Forex market is starting to show signs of alarming behavior, some may even call it a lack of correlation caused by storms forming. Yes, we know the USD/JPY is within its own environment as the BoJ and U.S Treasury/Fed play tag team trying to scare folks away from buying the currency pair. However, putting the JPY to the side for the moment, USD centric weaker positions are showing ability to sustain trends. 

The USD/SGD is a prime example of this momentum. The Fed’s Jackson Hole Symposium begins on the 27th of August and ends on the 29th  and all the major central banks will be attendance. Financial institutions will be keen to hear discussions about U.S bond yields, U.S and Japan currency interventions, but importantly will also want to monitor what Kevin Warsh and his cast of FOMC officers have to say about U.S interest rates. And it has to be known given the past two months from the new Fed Chair, he may remain rather quiet regarding outlook. 

And that might be good for the Forex market and spark some opportunities for traders to find an advantage. Because if nothing new or convincing comes out of the Jackson Hole meetings that financial institutions can decipher regarding their mid-term outlooks, perhaps the near-term will produce more volatility.  The next Federal Reserve FOMC meeting decision will be on the 16th of September. Do not expect interest rates to be raised.

Copy and paste the text from AMT that you want to share

Share:
USDJPY 20260813

Sentiment Matters: Speculative Narrative and the False Promise of Data

Do Retail Traders Understand They Are Being Misled?

As day traders ponder what they should do next via their speculative wagers in the broad marketplace, now is a good time to remind small speculators stepping into the casino of global assets that a lot of the production value they are offered is part of a show. Entertainment is literally being produced to entice people to trade. A large amount of retail traders are constantly being misled. Your adrenaline high is being counted upon to keep you a participant. The thrill you get when you are trading should not be more important than the outcome of your trade.

Large money machines like the Nasdaq 100, S&P 500, U.S Treasury yields, Forex, commodities and even the cryptocurrencies have plenty of descriptive words and definitions trying to interpret and predict values, trends and outlook, but quite frankly a lot of the words are nonsense created to entice and fool. Making retail traders willing participants in the circus is important because it keeps a lot of the the entertainers employed. 

It should be remembered that a lot of the folks on the institutional side of financial markets do not care about day traders except as an example of what not to do. They use day traders as a touchstone to point to failures and convince you why you are out of your element, while hoping you will stick around to create volumes that are often needed in some speculative assets. Are you being taken advantage of as a small speculator? 

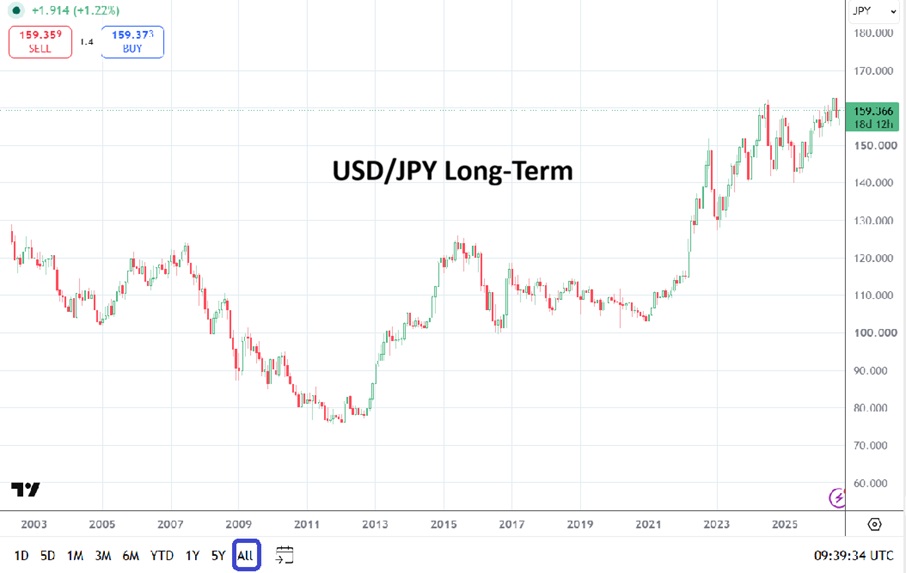
USD/JPY Long-Term Charts as of 13 August 2026

It is Much Better to be the Bank

A lot of people in the institutional financial industry know one thing for certain, while some make money investing by themselves or produce outstanding results for funds, many do not. There is an old saying among veterans in the arena, “it is much better to be the bank”. Transactional costs from commissions, carrying charges, exchange fees and taxes make money for the institutions and government regulators.

Many folks are involved in the financial markets because it provides a solid pay check, it remains a good career path for those who want the comforts of modern society. However, being a day trader while working another job as a blue collar employee, or business owner, or while being a professional in another endeavor and dreaming about wealth creation via speculation is alluring, but it frequently does not produce steady profits like it does for the people working in financial institutions collecting a paycheck. 

Confirmation Bias and Investment Outcomes

Economists for instance are relied upon to decipher inflation and decode data for devoted audiences. The believers are told why certain assets are reacting and what might happen in the future by the influencers. But this also can manifest into self-fulfilling prophesy that may not actually be connected to real economic outcomes, except that outlooks get fulfilled because of emerging behavioral sentiment.

For instance when yesterday’s U.S Core CPI was released and hit its expectation, what did markets do exactly, what were investors reacting to? The markets reacted to what the perception of mid-term outlooks will now do, based on how they think the Federal Reserve will act in September and the coming months. Reactions to anticipated results are a key factor in market dynamics. Large positions are shifted by financial institutions which have the ability to to absorb short and near-term losses of capital while they wait for their mid-term outlooks to be confirmed. Confirmation bias remains important in the marketplace as results get generated via intraday results as big players thrash violently with massive piles of cash causing technical perspectives to drive algo trading.

Inflation is Not a Joke

Btw, why did god create economists? To make weathermen look good. While that may fray the feelings of economists, the joke holds water. Because observable data and printed results often do not correlate. Just ask global consumers in various nations what they think about their government’s stated inflation data compared to what they are spending on a monthly basis and rising costs. People on the street often feel their national currencies feel like they are losing money no matter what central banks are proclaiming.

Inflation is an important measurement for consumers and investors. But real inflation is often not a desirable talking point for many governments. Often excluded data includes products like food, energy, and mandated medical and pension costs via payments to government social programs. Increasing rent or mortgages via rising interest rates inside of certain government inflation reports are frequently avoided too and would look atrocious. Central banks are supposed to fight inflation, but which inflation exactly? I am digressing I know, this may have nothing to do supposedly with everyday speculating in the marketplace, but actually it does.

Because the Forex market, gold, equity indices are reacting to sentiment generated by the second based on what outlooks will be in vogue in a few months and inflation effects. Our age of social media and fast communication makes the markets vulnerable to fear and optimism equally. Speed matters even if it sometimes causes pain for day traders via lightning quick results in the marketplace as outlooks change constantly.

Make no mistake, market forces are always in play as investors look for value. Sentiment caused by folks like central banks and their policies play consistently important and volatile roles as large players and financial institutions react to tea leaves being read. The USD/JPY is a case in point, the Japanese Yen has been dramatically weak and losing value long-term. 

The intervention by the BoJ and U.S Treasury which was coordinated a couple of weeks ago didn’t fix the problem that Japan has poor monetary and fiscal policy. What it did was serve as a warning to day traders and large players (including banks) not to bet too strongly against the JPY too consistently even if their perceptions tell them otherwise, because the Japanese and U.S government can wreck havoc and create unforgiving momentum which can kill the infectious trend upwards when they desire. 

The BoJ and U.S Treasury definitively put on a show for traders to watch and contemplate before they consider stepping into the casino again. Sometimes it is better to watch the entertainment instead of being an actor within the drama.

Thrill of Risks and Solid Tactical Strategy 

Why do speculators insists on chasing markets without having proper guidance? Why don’t these same smaller traders just let professionals manage their assets and put some money away when they can and accept the returns? Maybe because many speculators are skeptical about the real returns and know they are being made to endure a magic show of sorts. 

Day traders should only risk what they can afford to lose via a speculative allotment of cash. Fund managers for financial institutions, pension funds for example, are often mandated to put 2 to 3% of holdings into speculative assets in order to seek bolder returns. This is one of the reasons why hedge funds and speculative assets flourish in a cyclical manner. Large financial institutions allow for wagering on asset classes they know are dangerous in an extremely limited manner, but with a huge amount of money. Can you say Bitcoin? And it is widely accepted that these speculative positions can be wiped out and destroy capital. Institutions often do not mind losing on limited speculative positions, the same cannot be said for retail traders.

Smaller retail traders should not view themselves engaged in a battle against financial institutions which are filled to the rim with employees who are often unsympathetic about the outcomes produced. The world of speculative betting by retail traders is not about to change. Day traders should study momentum and behavioral sentiment.

Traders need to understand how to manage risks and emotions. While speculators can dream about making illustrious profits to impress friends and partners, if they do not take into the consideration the costs of the risks they are likely going to fall into a deep hole. Strategic tactics are necessary. Retail trading doesn’t have to be a game if it is conducted wisely.

Copy and paste the text from AMT that you want to share

Gold 20260805

Gold Looks Oversold in What Appears to be a Vulnerable Global Market

Quick Thoughts on Why Gold Should Remain a Friend

Did you stop paying attention to Gold after it stumbled from its record highs in late January? Was it no longer interesting because it wasn’t churning like an invincible machine upwards? Is Gold boring because it has produced sluggish results the past half year that doesn’t deliver the daily excitement craved to get you to wager in the marketplace? No, Gold isn’t WTI Crude Oil which has seen increased volume since late February due to the Iranian war and it might be a while before the precious metal regains a full fanbase.

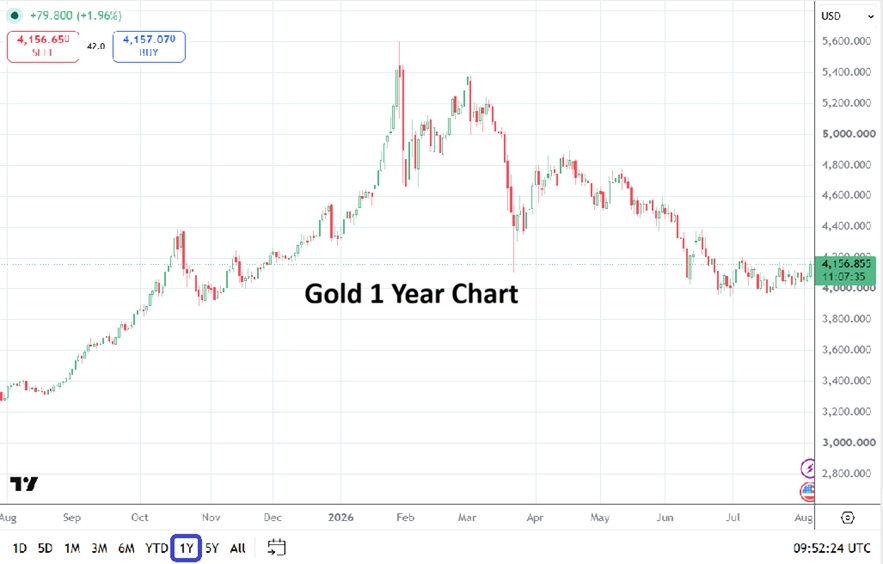
However, Gold still looks to be in oversold territory. Yes, Gold is near $4,150.00 as of this writing and in the middle of July was below $4,000.00. However, given the fragile behavioral sentiment that is being displayed in the global markets, there is a case for Gold being valued higher. Is the momentum produced upwards the past couple of days a signal that large players are starting to eye the commodity again?

Gold touched a high of nearly $5,610.00 on the 29th of January this year. Speculative fever was certainly ripe. Silver was near $120.00 too. Silver is now priced slightly above $61.00. I am not going to make a case for Silver here, so if you are looking for optimistic or speculative guidelines for ‘Argent’ you will not find it here. If you want to see a positive outlook for Gold please read on, and if you decide this means Silver may find another dose of increased pursuit that is your choice. 

Gold One Year Chart as of 5 August 2026

Via a one year chart Gold has lost plenty of value the past six months, but conditions may be turning favorable for the precious metal. Vulnerable sentiment in bonds, equity indices and Forex has grown loud and it might not vanish soon. 

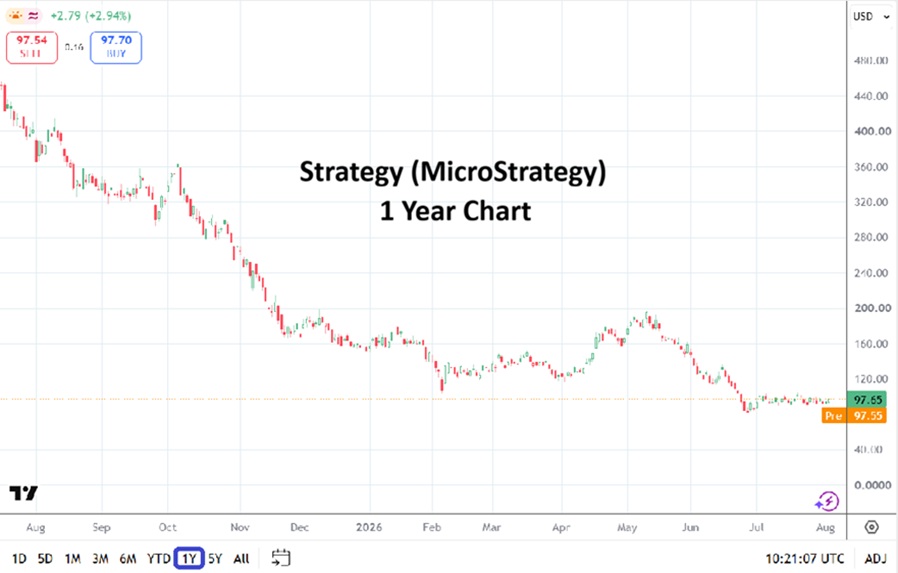
Yes, the Nasdaq 100 is once again back in its higher elements near 29,733.00, and has the 30,000 target lighting up again, but how long will it be before questions about the high cost of data centers, worries about AI revenues come back into vogue? What if interest rate worries continue to cause financial institutions to fear an increase in borrowing costs? What is going to happen if Bitcoin and Strategy (MSTR) implode completely? 

Allow me to say I am not saying Gold will go higher just because BTC/USD and MSTR are imploding, but it will not hurt the case for the precious metal either. Gold looks good because the over all health and sentiment of the marketplace doesn’t look particularly bright. 

If the price of WTI Crude Oil remains within sight of $74.00 and below that will be a positive development regarding inflation concerns, but will it be enough to generate a positive global economy? How will investors react if the Trump administration loses control in the House of Representatives in early November via the mid-term elections?

Strategy (MicroStrategy) One Year Chart as of 5 August 2026

The Case for Gold

Over the past year Gold has turned in a rather remarkable run from a speculative point of view and investment framework. One things stands out, Gold is not going anywhere. It will not disappear suddenly, meaning within the next 100 years and it will still be seen as a store of value. Gold remains a steady unit of secured capital for long-term investors having established a track record the past 3,500 years. Speculators who pursued the run higher, including hedge funds and large players likely lost money as values decreased the past six months, but let’s also note Gold has found rather tight support around its current price point since the middle of June.

Yes, gold lost value after the speculative storm subsided and people turned their wagering attention elsewhere, but the commodities loss of value in the past six months was froth being wiped away from a speculative market in which bulls ran wild.

The Fed may find itself in an increasingly difficult spot with the U.S Treasury reminding the U.S central bank about higher yield provisions. Japan is likely to continue to find it difficult to extricate doubts within financial institutions regarding the JPY. And if investment wheels struggle to produce gains steadily in the asset machines of the stock markets, some folks will turn their mid-term outlooks elsewhere for stability and potential profits.

Gold will continue to shine as it has always done. Fools Gold attracts the ignorant, real Gold attracts those looking to sustain value. I am not saying Gold needs to be $5,000, but Gold looks to be oversold in what feels like an increasingly nervous global market. 

Perhaps that is the risk manager in me taking on the psychological sentiment of nervous investors who do not feel comfortable with the higher yields being seen in U.S Treasuries, the weakness in the USD because of a Fed that many feel lacks clarity or proper policy guidelines, shadows from the Middle East which are unlikely to suddenly disappear even if there is a formal agreement achieved in the near-term…and yes even as Gold has gained the past few days in the midst of the sudden USD slump.

Gold back to the $4,500.00 mark might seem like a farflung wager perhaps, but from a mid-term outlook, one that I wouldn’t be surprised with if it occurs. From a perspective of where things will be within 3 to 6 months I would venture to say Gold should not be lower than it is now. I would be genuinely surprised if it was below $4,000 in November of this year, but would not be surprised if it is touching $4,500 or higher.

Copy and paste the text from AMT that you want to share

Share:
US Dollar Index 20260804

Apologia: Confronting Market Opinions and Pointing Out Wrongs

The Markets Can and Will Harm You, Can You Survive?

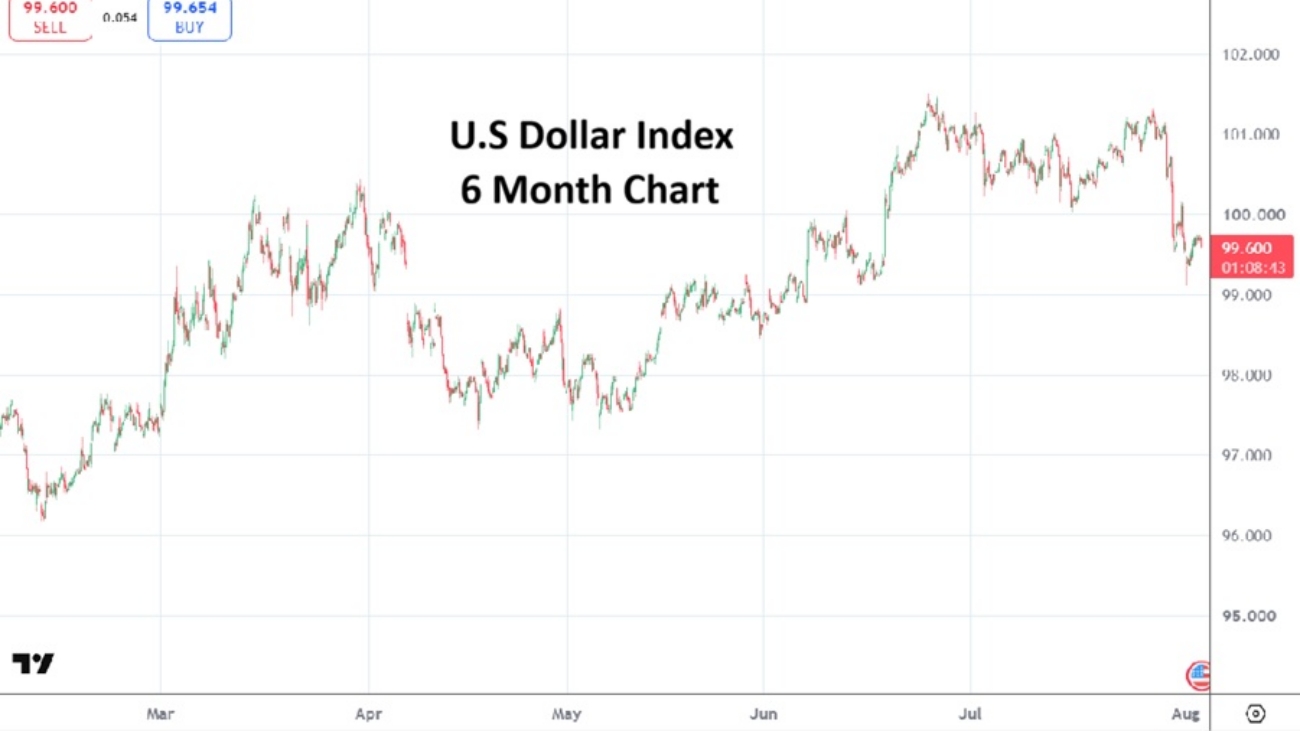
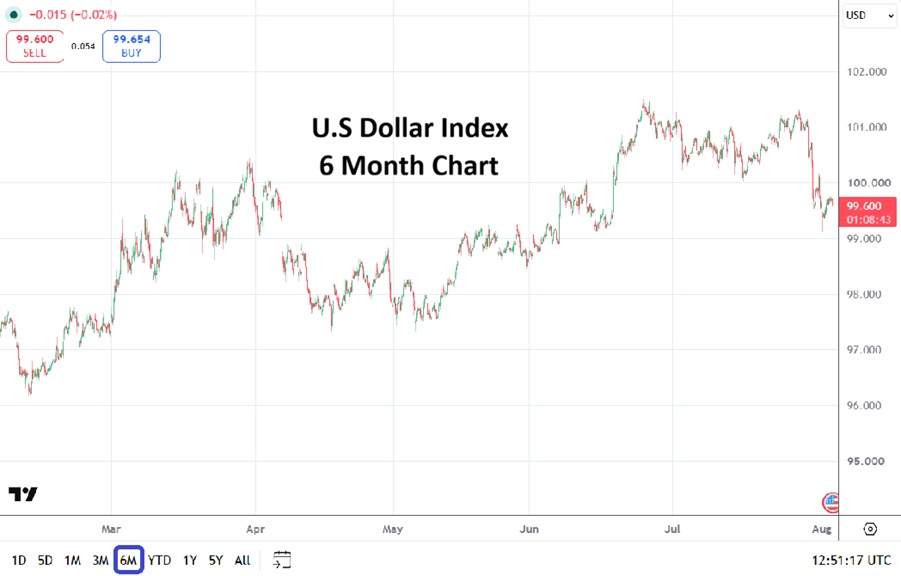
The U.S Dollar Index is back to where it was trading on Friday the 13th of March. (Yes, a Friday the 13th). Literally a week and half after the Iranian war started from a trading perspective. We are almost half a year into the war and many are still acting surprised by surges which churn on a daily basis in WTI Crude Oil and a host of other assets including bonds, equities – indices, and Forex. 

A large group of people are acting as if the USD selloff sparked across the Forex board on Friday was doomsday and had evil intentions. But what if the Trump administration actually wants a weaker USD? What if all they need to do is to get Wall Street to kick into gear and create higher values to change behavioral sentiment in Treasury yields? It is not so easy to fool professionals is it?

The narrative that the N.Y Fed via orders from the U.S Treasury was selling USD to strengthen the JPY became a conspiracy masterclass in over-reaction. Particularly because the BoJ had intervened twice already this year prior to Friday’s action – why is nobody pointing to that? It doesn’t mean, by the way, that the BoJ suddenly knows what they are doing, but it doesn’t mean that the financial end of the world is near. We need to get over our own fears.

Fed Chairman Kevin Warsh may be new on the job, he may be nervous, but he is not a schoolboy, and likely has a plan of action. I agree it sometimes is not easy to discern what Warsh wants exactly, but the USD is now weaker and maybe Scott Bessent and Donald Trump do not mind. I didn’t call Bessent and Trump the Fed Chair’s boss please note – he is independent after all. Cough, cough.

Everyone Has An Opinion, Many of Them Are Wrong

I have a good friend who constantly tells me to make sure I give an opinion, he will know who he is when I say he has proven to be the worst trader I have ever known. Hello there, Mr. Bad Trader if you are reading. Part of the reason he is so bad at trading is because he has never understood who he is as an individual participant in the marketplace.

U.S Dollar Index Six Month Chart as of 4 August 2026

His ego will not let him admit to himself he is wrong. This is not an easy thing to do for anyone. When is the last time you were able to admit you were wrong about a market position and turn around on a dime and be willing to take a loss? 

My friend doesn’t seem capable of understanding he is not an investor, he is a trader. While his outlooks about the market often prove correct, his timeframes constantly complicate matters. He has never had the temprament to be an investor, he is too impatient. He always used too much exposure via leverage and he remained unwilling to change his sails even when the winds clearly told him he was about to get wrecked. My friend no longer trades.

I am certain he would be willing to trade someone else’s money, but he has no funds to risk on his own. And I kid you not when I say he has attempted to prove the marketplace wrong more times then can be counted and still thinks he will eventually be proven correct. 

So when was the last time you were able to change your mind about an opinion you held? When was the last time you said to yourself and aloud, “I am wrong and I misunderstood the circumstances.” And do you know why you were wrong?

We listen to analysts tell us why the marketplace is going to sink, we also pay attention when they say an asset is going to the moon. Analysts are never held accountable because they are able to say things like past results do not guarantee future results. They also get to point to risk disclaimers, have a look at ours angrymetatraders.com/risk-disclaimer, protecting their opinions about the markets put forth. So why should you pay attention to someone who has no skin in your game? Because it is important to get other viewpoints, once in a while you may actually be able to allow yourself to admit that your perspective is only one of many.

The broad markets have been unkind the last six months in many ways to retail speculators. Investors have gotten hurt, but they will likely survive or at least find a job elsewhere if they cannot improve their results in the coming months to hide their failures at their current firms. This is not a polite game you are playing as a retail trader. Your brokers’ no doubt love you and talk to you about the markets and your participation like it is a sporting event. ‘Even the great ones fail once in while,” have you heard this one? 

Yesterday I stumbled upon someone’s post on LinkedIn discussing a theory and ability to only aim for a half a percent of gain everyday as if that small target somehow made it achievable – all the time. Like compound interest they subtly suggested, half a percent gained everyday would show the level of control you would have in the marketplace and allow you to make millions of dollars within a few years. Good news, isn’t it?

However, many of us know, it just isn’t that easy. While it is a great notion to remain focused and not be too ambitious while trading, buying someone else’s system for a lot of money or being charged their management fee is a little like being chewed on slowly by a vulture. 

Where is the optimism? Where is the golden secret that will allow you to become a better trader? I don’t have any, except to say diligence, determination and knowing when you are wrong and need to get out of a position is vital. We all want to find the big wave and ride momentum in order to profit. 

Sometimes the markets look like they offer riches for the brave, but sometimes they turn into a pile of ashes. No matter how hard influencers want to praise certain assets they cannot shine a turd into gold. Sometimes the turds are merely garbage and need to be treated like fertilizer, allowing for something else to grow its in its place. Maybe that is replacement theory. Maybe it is meaningless. But this is a game with hard rules, risk management and knowing when you are wrong are among some of the more important early lessons that should be sustained.

A lot of smaller players are angry at larger players in the marketplace, the reason for this has a lot to do with survivability. Small traders like my friend are no longer able to speculate, big players who are frequently part of larger financial institutions simply go home and wait for another day. Those are my opinions, take them or leave them. Tomorrow is a new day and may offer more clarity, for the moment I suggest being careful in the broad markets.

Copy and paste the text from AMT that you want to share

Share:
AMT Top 10

AMT Top Ten Miscellaneous Interjections on the 3rd of August

Narrative Storms, Complaints and Observations

10. Mo’ Money: The Los Angeles Dodgers surprised nobody when they acquired Detroit Tiger’s pitcher Tarik Skubol in an effort to solidify their chances of a World Series three-peat. Don’t blame the LA Dodgers for playing by the rules, even if many don’t like the results. Expect a MLB strike in the coming year when owners try to change the salary structure in baseball.

9. Staggered: SpaceX is below $110.00 as trading gets set to begin today. Financial institutions are likely bracing for the open window that begins the 6th of August via a large amount of unblocked initial equity from pre-IPO shareholding that will soon be given freedom to sell. 

AMT Top 10 Miscellaneous Interjections on the 3rd of August 2026

8. Fidel Castro: Mayor Mamdani and a gang of other U.S utopian (and sometimes bigoted) politicians continue to make headway. Authoritarian failures like Venezuela and Cuba are prime examples of the paradise offered to U.S voters who lean left for the coming mid-term elections.

7. Takeover: Citadel’s takeover of Situational Awareness – which seems to have proven it had none – this past week in the wake of multi-billion dollars of losses has put Leopold Aschenbrenner’s smirk on hold for the moment. Have no fear fans, Aschenbrenner is likely to land on his feet and extol his methods once again to those who love leveraged speculative ventures while embracing unproven hedge fund saints.

6. Fragile: The VIX Index appears asleep as it remains a hair under 16 as it measures the volatility of  the S&P 500 Index’s options. 10-Year U.S Treasury yields are around 4.68% and within sight of apex highs. The Nasdaq 100 futures are higher as of this writing as the cash market and a full week of trading awaits, having finished Friday’s session at 28,274. 

5. Anthony Fauci: Takes the Fifth and now hopes his pardon covers contempt.

4. Bitcoin: BTC/USD is near $62,850 in the wake of confirmed cold storage hacks via a generated random prediction onslaught using AI against Coldcard hardware. In other bad news Strategy’s MSTR value is around $93.35. And, yes, Michael Saylor has reportedly whispered he is thinking about buying more BTC soon. The ship appears to be sinking folks.

3. $80.00: WTI Crude Oil has shown price velocity lower today again, this after another flip-flop in behavioral sentiment was sparked by the announcement this weekend of a ‘rough framework’ agreed upon by Iran and the U.S. The Strait of Hormuz is seemingly quiet for the moment. At this point WTI Crude Oil price reversals are beginning to look like a well practiced dance routine. What will the next steps look like?

2. Forex Freakout: USD/JPY traders are listening to a myriad of narratives regarding the BoJ’s intervention. All experienced large players in the USD/JPY had to know an intervention was coming. While folks are pointing to the N.Y Fed and U.S Treasury selling of positions to bolster the JPY last week, they apparently need to be reminded the Treasury had the N.Y Fed start preparing the groundwork for such maneuvers earlier this year with steps including the ability to check on and counter USD/JPY Forex rates in January. 

While folks are accusing the Fed/Treasury of hurting the USD, they should note the move is to counter weaker JPY which Treasury Secretary Scott Bessent likely had been pressed by ‘higher ups’ to manage in order to make sure Japanese products didn’t become too cheap in the States. There had been at least two other interventions in the past handful of months from the BoJ, as of this writing the USD/JPY is near 156.600.

1. Unilateral: President Trump’s decision making has become bewildering entertainment as he practices a comedic like opera trying to convince people about his opinions which he seems to change relentlessly. President Trump should learn the Art of Sparse Talking. Will the Republicans harness the President after the mid-term elections?

Copy and paste the text from AMT that you want to share

Share:
Bitcoin 20260730

Debunking Bitcoin Lies

The Paradox, Absurdity, Lies and Myths of Bitcoin

They say it’s an “asset”… but it has zero assets.

They say it’s decentralized… but the large majority of all transactions go through trading platforms.

They say it’s digital gold… but it has none of the physical attributes gold derives its value.

They say it’s immune to censorship… but countries like the US and China manage to be the largest holders without buying any Bitcoin.

They say it’s scarce… but there are 2.1 quadrillion Satoshi units that act exactly like a Bitcoin unit.

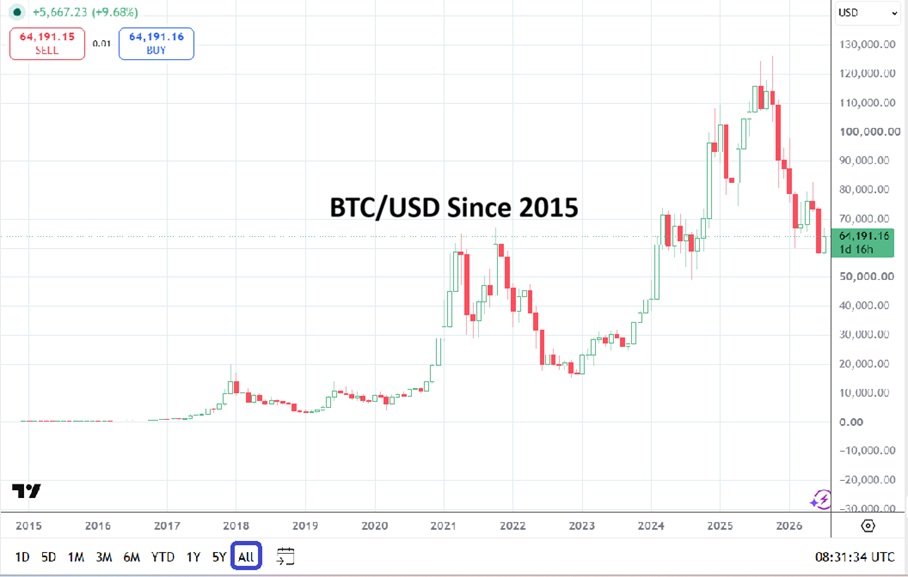
They say it’s a store of value… but it has witnessed several -50% to -80% drawdowns in its short history.

They say it derives its value from energy… but energy is a massive cost that someone has to pay!

BTC/USD Chart Since 2015 as of 30 July 2026

The Bitcoin protocol was introduced as a new monetary system: decentralized, censorship-resistant, scarce, transparent, secure, and independent of governments and financial intermediaries. It promised to eliminate the need for trusted third parties and replace institutional trust with a code.

However, more than fifteen years later, Bitcoin has failed on all those fake promises…

Today, the Bitcoin ecosystem is increasingly dependent on centralized exchanges, custodians, mining companies, stablecoin issuers, institutional investors, and financial intermediaries. The supposedly revolutionary monetary asset has become deeply intertwined with the very financial infrastructure it was designed to bypass.

And beneath everything lies an uncomfortable economic reality: the Bitcoin mining industry must continuously spend real resources (electricity, capital, land, labor, and massive equipment that becomes obsolete very quickly) to generate a virtual token that is distributed randomly… with the reward being halved by design every four years! What business model can survive such a flawed system where revenues are distributed randomly and halved every four years while costs increase constantly with adoption? It is the exact opposite of an economy of scale. The more successful your product is, the deeper your losses are! Even Fried Thiel, MARA’s CEO, ended up admitting that Bitcoin mining is a “zero sum game”! With miners doomed to fail economically, Bitcoin’s network security is destined to failure.

1. The Decentralization Paradox

The word “decentralized” is perhaps the most important word in the Bitcoin vocabulary.

In practice, it is far from being the case. Most Bitcoin transactions go through exchanges, custodians, brokers, or institutional funds (ETFs). Even miners store their mined bitcoins with custodians like Coinbase.

Today, the entire ecosystem relies on the solvency of companies like Coinbase, Binance, Tether, Strategy… all of which are in a critical financial situation. Should any of them collapse, the whole house of cards will fall down.

The irony is striking. Bitcoin was designed to eliminate the need for trusted intermediaries. Yet Bitcoin users increasingly trust intermediaries to hold their Bitcoins. Even miners do! How absurd is that?

2. The 21 Million Fake Limit

The most used argument for Bitcoin is that there will only ever be 21 million bitcoins.

But the statement requires closer examination too. A bitcoin is divisible into 100 million Satoshis. Each Satoshi has exactly the same “shape,” the same function, and the same attributes as a Bitcoin! Dividing something into exact copies of itself acts like a multiplier! That means the real supply is 2.1 quadrillion units (call them Satoshis or Bitcoins, it doesn’t matter).

The immediate response from Bitcoin supporters is that this is no different from saying that one dollar consists of 100 cents… but the dollar was never designed to have an absolute monetary cap.

The question then becomes whether the 21 million cap creates meaningful economic scarcity or simply a narrative of scarcity for marketing purposes. Anyway, the scarcity of something useless doesn’t make it useful…

The “21 million limit” becomes even more absurd when we consider the enormous number of other cryptocurrencies and tokens that exist. If scarcity itself is the central source of value, why should Bitcoin’s scarcity be uniquely valuable? The crypto ecosystem has demonstrated that creating a new digital asset is technically easy. Anyone can create a token with a fixed supply. If we create another digital token with a 10 million limit, much lower than Bitcoin’s 21 million limit, would it be worth more than Bitcoin because it would be considered scarcer? How can something be considered scarce if it can be replicated indefinitely with exactly the same “unique” attributes?

3. The “Digital Gold” Absurdity

They say Bitcoin is digital gold. Yet gold has physical properties that have made it valuable for thousands of years: durability, divisibility, portability, resistance to corrosion, and usefulness in jewelry and industry. Bitcoin has none of those unique physical attributes. Take away those physical attributes from gold, and it loses all its value. Since Bitcoin is gold without its physical attributes, it is therefore worth nothing! It’s as if we created a virtual token and called it “digital water,” pretending it’s “liquid” and “essential to life.” Still, if we can’t drink it or wash with it, what value would it have? Not only does Bitcoin have no intrinsic value, but it also requires continued investment in heavy infrastructure and massive electricity consumption to stay alive. It is like having a car parked in a garage, continuously consuming gas to remain “alive,” while you pretend it has value because it is unique! Once gold is mined, it costs nothing to continue existing. When Bitcoin is mined, the network needs to keep running on heavy electricity consumption for the Bitcoin to remain “alive.”

4. The “Censorship Proof” Lie

Governments around the world have acquired Bitcoin through seizures, confiscations, enforcement actions, bankruptcies, and other means. That’s how a digital coin created as a challenge to government monetary authority ended up in government-controlled wallets.

Governments do not need to control the blockchain to influence the market. They can shut down crypto platforms and seize their assets. What happened to the promise of monetary freedom?

5. The Myth of Low-Cost Bitcoin

Bitcoin is sometimes described as a cheap way to transfer money. The comparison can be attractive. There is no need for a traditional bank to approve a transaction. The network operates continuously.

But the cost of the system is not simply the transaction fee paid by the user. There is also the cost of maintaining the infrastructure. Bitcoin mining consumes enormous amounts of electricity and requires heavy equipment that becomes rapidly obsolete. The economic cost of maintaining the network is simply unsustainable. All listed miners show constant negative cash flow with massive dilution of shareholders and collapsing stock prices. It is not a coincidence. It is simply a sign that Bitcoin mining is economically unsustainable. It is a fundamentally losing business that is doomed to fail. When most miners inevitably capitulate, they will sell their Bitcoin reserves and provoke a massive collapse in the price. With less than 5% remaining to be mined over the next 100 years, there will be zero incentive for miners to start all over again. Bitcoin is doomed to fail from within.

If Bitcoin were truly revolutionary, all large technology companies, like Apple, Google, Microsoft, and Meta, would have jumped in to get their market share (as they did for AI)… instead we have empty shells with no business model, like Strategy, Nakamoto Inc, and Metaplanet, turning into “Bitcoin treasury” companies while incurring heavy losses and permanent negative cash flow.

Bitcoin was designed as an alternative to financial intermediaries. Now collapsing “treasury companies” and unsecured crypto platforms control the ecosystem. We shifted the risk from banks like JPMorgan, Citi, or Morgan Stanley, supported by the US central bank, to entities like Coinbase, Tether, and Binance… some of which aren’t even audited! And all without any support from a central authority.

The user may distrust banks, but he is asked to trust an exchange. The user may distrust central banks, but he is asked to trust a stablecoin issuer. The system has not eliminated trust. It has redistributed it to a much weaker ecosystem!

Bitcoin will be remembered as the greatest bubble of all time and the largest misallocation of capital and resources in human history.

Copy and paste the text from AMT that you want to share

Share:
10Y Treasury Yields 20260728

Thoughts on Kevin Warsh, the Fed and USD, Energy, Nasdaq 100, USD/JPY and Bitcoin

Fed’s Rate Announcement Tomorrow and Underlying Market Conditions as Folks Talk

Tomorrow’s FOMC rate decision from the Federal Reserve continues to cause some angst in the investment community as folks try to decipher Fed Chairman Kevin Warsh’s disdain for tea leaf reading. What is being missed by seemingly a lot of the crowd is the open signal from Warsh that he prefers to keep his outlooks rather muted, this because he appears to be focused on the mid and long-term economic picture.

Simply put, I do not think the Federal Reserve is going to raise interest rates tomorrow, nor will the Fed Chair give too much indication about his thoughts for mid-September. It might be stated in the Fed Press Conference afterwards that the costs of energy is being watched, but that is too obvious. Count on it being recorded that the Federal Reserve will watch data and react accordingly. In the meantime, financial institutions may demonstrate volatile overplayed USD centric positions which look overbought looking into the mid-term, as they still worry about the near-term.

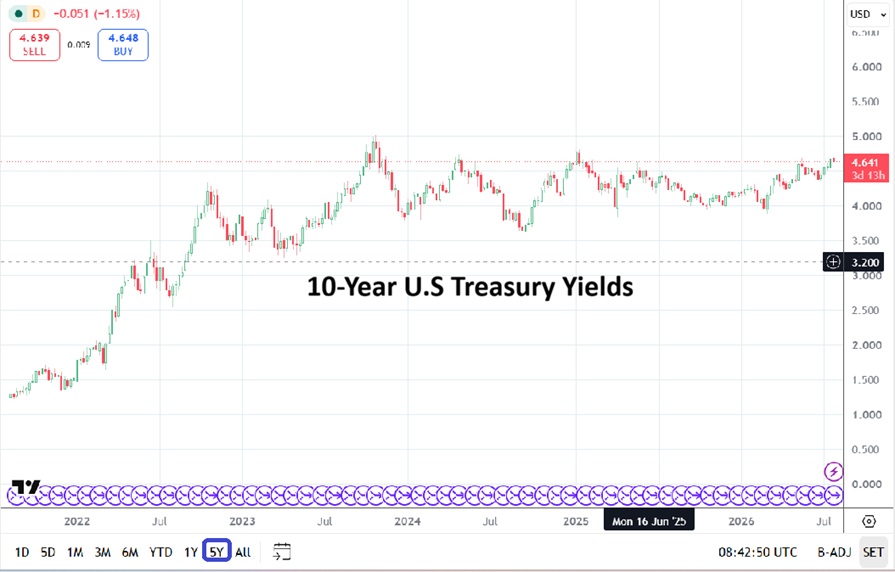
10-Year U.S Treasury Yields Five Year Chart as of 28 July 2026

Political Questions and the Cost of Energy as the Fed Reacts

Let’s for a moment dive into politics. Does anyone think that Kevin Warsh doesn’t speak to Treasury Secretary Scott Bessent who has been a long-time associate? And does anyone think Bessent doesn’t have the constant voice of President Donald Trump in his ear? 

The mid-term elections are nearing ladies and gentlemen. The de-escalation in the Iranian situation certainly has something to do with nations expressing wishes for less military action to the White House. Israel, the UAE, Kuwait, Bahrain, Iraq, Qatar, Saudi Arabia, Pakistan and Turkey are trying to influence positions as President Trump considers his next moves regarding alliances and resources. However, the situation may have something to do with the price of WTI Crude Oil too and its effect on U.S manufacturing and surprise, surprise the Federal Reserve. 

Does anyone else remember that the last de-escalation also started just before the Federal Reserve’s last FOMC meeting in June? I am not being a conspiracy fanatic, just pointing out that lower WTI Crude Oil prices do help the case for a Fed outlook which looks at the costs of energy in a pro-active manner, one which might include the U.S economy and internal White House discussions with politicians who represent voters who have the power of creating a backlash. Lower interest rates equate into lower borrowing costs for consumers.

The Fed’s Impact on Equities and Forex (and the USD/JPY)

So if the Fed does not raise tomorrow, nor gives an indication of what it will do in September and offers a stance of ‘we are vigilant and will watch the economy’ will that help sentiment on the Nasdaq 100 which is starting to have the look of a patient with a bad cold who can’t quite seem to get rid of a cough? Microsoft and Meta step into the limelight tomorrow with earnings reports, Amazon and Apple follow on Thursday.  The combination of the Fed and important quarterly earnings will impact Nasdaq sentiment and other equity indices.

It appears analysts of financial institutions are starting to discuss CAPEX – capital and expenditures – openly. And this is creating shadows as investors weigh the costs of energy and infrastructure against stated profit projections. However, let’s not throw the baby out with the bath water, the Nasdaq 100 has a gain of 20%+ over the past year (July to July), and since March the index has still gained 12%+. The war in Iran (excuse me, conflict) has not had a meaningful impact it appears on the outcome of the Nasdaq 100 via sentiment generated. But the shadow of expenditures, debt and revenue is getting louder bandwidth and speculators need to remain cautious in the indices.

Back to the Fed and Forex, the USD has been strong, you are allowed to say extremely strong if you have been betting on downside incorrectly. The USD/JPY is almost in nosebleed terrain, currently 163.830. The Bank of Japan will announce their interest rate policy very early Friday (for those of us not in Asia) and let’s see if the ‘independent’ Bank of Japan is taking a cue from their government which is clearly interested in continuing to build stronger export ratios. Has the Bank of Japan given up the so-called stated fight to keep the JPY within a solid stance? This is doubtful externally, and Japan is certainly not going to allow the USD/JPY to traverse wildly higher, but it may not consider the 165.000 mark as the end of the world. Beware of saber-rattling from the BoJ in the coming days.

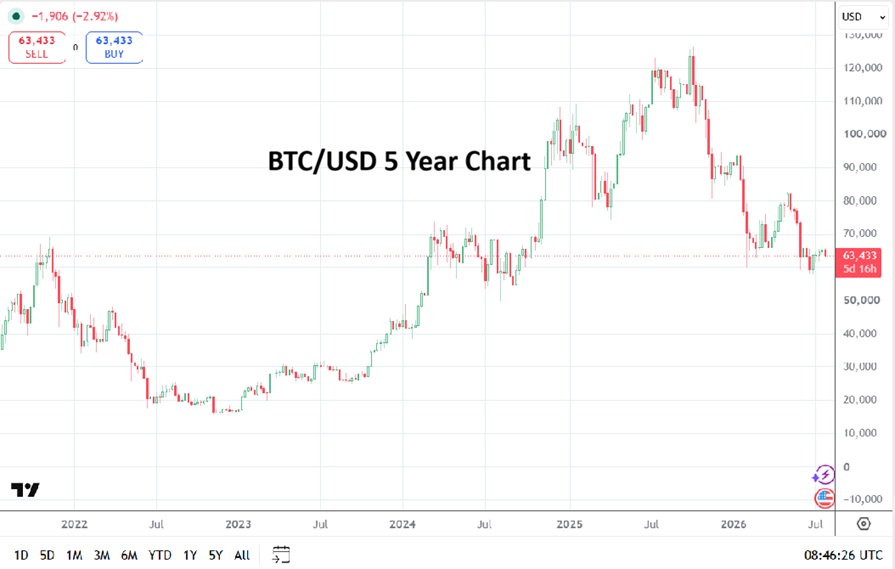
Bitcoin Five Year Chart as of 28 July 2026

Doubts and Remarks Regarding Bitcoin Below $64K

On a last note, the world of cryptocurrency remains interesting and stormy. It appears from watching the awkward statements from influencers and crypto (including Bitcoin) media outlets the past couple of months, as they attempt to explain their pain and convince others that everyone should buy at these lower values that more troubles are coming. 

What are the influencers, crypto media’s and importantly financial institutions’ actual skin in the game relative to those who have lost interest in Bitcoin and the digital market worth? Are influencers and large institutions like BlackRock hoping to pawn off their suffering ‘asset’ holdings to the public, while trying to convince us that today’s cheap prices represent buying opportunities? Is the wave of slanted influence and panic-like banner waving a hope to save themselves in order to cash out of a sinking market, this while hoping someone else takes their place in lifeboats that face a difficult voyage to safe harbors? 

BTC/USD is near $63,4000 now. Yes, we know, we have been told plenty of times before that all the Bitcoin winters eventually turn into summer again. Blossoms will create the sweet scent of profit we are assured, but what if the winter becomes an ice age? What if Michael Saylor and his ability to produce complex financial statements and instruments for MicroStrategy and Strategy equity shares continue to make little mathematical sense? What if all the investors into Bitcoin and cryptocurrencies are left holding the bag and find themselves covered by permafrost? The tundra currently looks harsh. Will the Bitcoin crowd who has been so adamant about being free of regulatory controls and mismanaged central banks cry openly for bailouts from the U.S Treasury with USD? Now that would be entertaining.

Copy and paste the text from AMT that you want to share

Alphabet 20260724

The Not So Coincidental World of Google and WTI Crude Oil

Energy and Commodities in a World Where Legacy and Infrastructure Collide

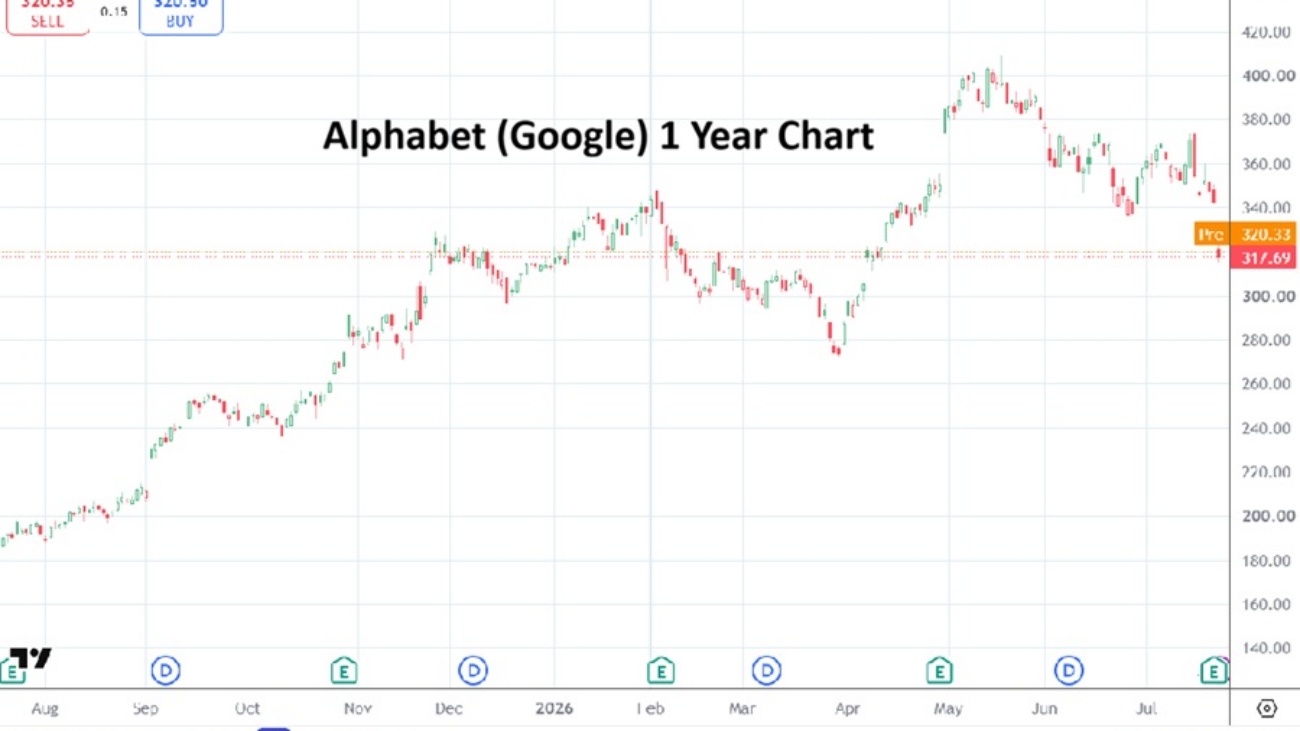
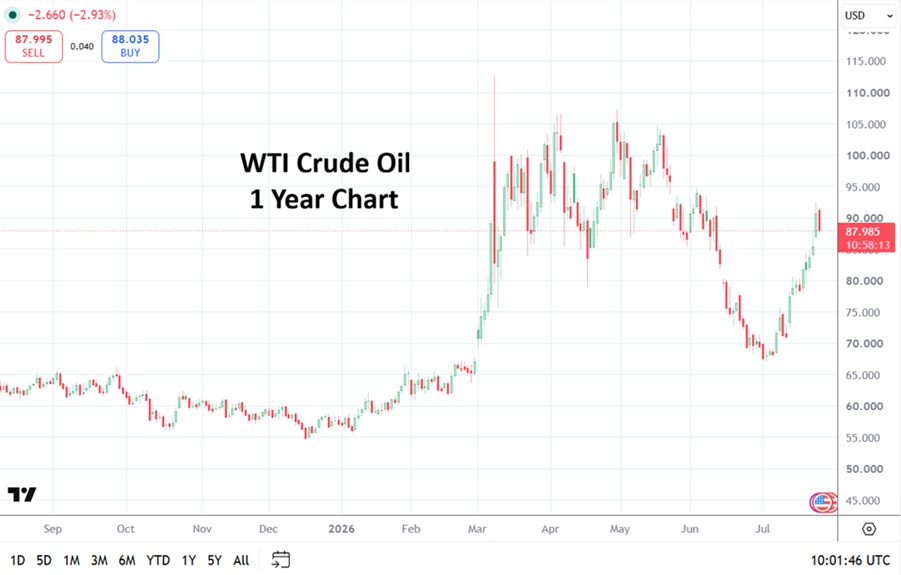
Google (Alphabet) finished yesterday’s trading near $ 317.69, as of this moment WTI Crude Oil is around $88.50. It might seem rather odd to pair the two into the same paragraph, but this is not a coincidence. Both are now relevant regarding energy costs for consumers and produce an abundance of legacy products the world over. And oddly enough their one year charts almost look as if they are dancing in step.

Google is facing headwinds in recent trading as questions surround its capability to produce revenues because of its push into Artificial Intelligence and always growing need for more data center power. AI which has been an abundant source of bullishness in the Nasdaq 100 and had a knock-on effect into the S&P 500 the past couple of years has become shadowed by concerns of turning into a commodity. 

Alphabet (Google) One Year Chart as of 24 July 2026

As competition in the AI sector increases this is creating pressure on prices in order to allure customers away from competing brands. China is also stepping into the world of Artificial Intelligence and it will certainly use its ability to produce less expensive products moving forward. Profit margins are being fought over by competing companies

Google is not a poor company, but there are growing doubts about its debt and revenue ratios. The costs to power its worldwide data ability for its users and its investment into AI via Gemini and its DeepMind technology does not have a particularly easy solution. Estimates from a variety of sources claim that Google has reduced its staff between 1,500 to 3,000 through employee reductions and reorganization, this as the company needs to pile more cash into infrastructure.

The onslaught of other companies able to produce AI which is seen as more robust and capable have also caused a marketing headache for Google, which has an effect on behavioral sentiment. GOOGL was trading at apex levels only two months ago when it was traversing above the $400.00 mark. The downturn thus far has been bad, but not catastrophic. 

WTI Crude Oil One Year Chart as of 24 July 2026

While nervous sentiment can be blamed on the situation in the Middle East the past handful of months, the downturn which has occurred for Google and other important companies on the Nasdaq 100 involved or seen as having an ancillary association with AI needs to be considered a legitimate reaction because of worries surfacing regarding the ability to simply pay for all of the research and infrastructure. 

In order to power AI it is becoming clear that energy costs are part of investing frameworks. Concerns about an AI bubble started to gather an audience last fall and the rumblings have grown louder, yet it can be said the ability of Google and many other companies to gain the past year in value still outweighs this current downturn experienced the past couple of months.

The Iranian war which is ongoing, appears to be entering a phase in which financial institutions are having to succumb to the notion of higher prices not only for WTI Crude Oil but other energy resources with a mid-term viewpoint. While there is abundant supply of Crude Oil worldwide, the current problems surrounding navigation and logistics are causing pandemonium in a consistent manner via WTI’s price as Middle East nations try to ship to their clients. This is causing many Asian nations to look elsewhere for their energy, Brazil has seen an increase in orders. And because of the upwards trend in fuel costs again, the Federal Reserve will have to look hard at inflation data and play a game of interest rate mania, which investors will have to calculate into their outlooks regarding debt ratios.

What does this have to do with Google and AI?

People like nations will search for the easiest and most cost efficient pathway to access their needs. Anthropic, OpenAI, Kimi K3, Microsoft Copilot, DeepBlue Technology, Meta, Sakana AI, IBM, Nvidia are only some of the companies involved in sourcing software and providing hardware to users. Many nations are involved in this AI chase and understand the importance of cybersecurity, data sharing and the problems surrounding the costs to power all of these machines.

Many of these companies above including Google are searching for a holy grail via energy supply and discussing the financing and building of energy infrastructure including nuclear capabilities. But as Google and other companies search for more energy to fuel their dependence on powering their systems for clients, they continue to be confronted by a growing wave which will eventually drown some of the companies in debt that they will not be able to recover from.

I am not forecasting an apocalypse, but I am suggesting not all of these companies which we think of as part of our everyday lives will survive this fight. Legacy companies eventually parish, just like many start ups. The realization that many companies are merely providing what the public is starting to see as necessity is a simple competitive evolution. BlackBerry, Nokia and Motorola are examples of giants falling.

It appears many investors are starting to ask hard questions about costs compared to future earnings in AI. The allure of the next big thing, which AI has been part of the past couple of years, is running into well-practiced investment cycle as froth erodes and financial institutions start to look at the accounting of the companies they are being asked to consider as long-term endeavors. Not all that glitters is gold will certainly start to create a patina on many of the so-called AI companies as they are forced to prove their worth as suppliers of a commodity.

The AI world has run into the time honored financial realization that many exotic tastes soon turn into another form of vanilla. The next big thing is always being anticipated and hoping to attract the deep pockets of investors. Certainly many of the big companies including Google are going to survive the current headwinds. but real profits could become harder to attain. Investors and speculators should not be surprised that reality has a tendency to reduce momentum.  Entropy is part of the investment world, investors and speculators always have to be ready for new disruptions and systems to emerge.

Copy and paste the text from AMT that you want to share

Challenge Part 1 20260721

The Challenge of October 7: Part 1 – Introduction

Cynicism and Wake Up Calls: World War I, Vietnam, October 7th

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 20th of July via The Angry Demagogue.

Europe and the UK had WWI, the United States had Vietnam. Israel had the birth of the post-Zionist left in the wake up call that was the Yom Kippur War, and now (learning that the wake up call did not last) the events of October 7 have demanded that the country face new challenges – intellectually, politically and socially.

The Challenge of October 7: Part 1 – Introduction

World War I and Vietnam gave birth to the cynicism and inferiority complex to Europe and the United States respectively that has reached its nadir in the contemporary West. The utter lack of self-confidence in the traditions, virtues and ideas that moved the West forward from ancient Athens and Jerusalem to the Middle Ages to the enlightenment and on to the computer age. As technology moved forward, the ideas that underpinned it retreated to a nihilistic denial of the monotheistic idea that is the basis of all Western life.

Today’s engineers, physicists, humanists and social scientists miss the historical arc that moves from Plato and Aristotle’s break from paganism and the Jewish intellectual monotheistic heritage from late Biblical and post-Biblical times through the Church Fathers and the medieval Jewish, Christian and Moslem thinkers to our current times. The bits and bytes of the computer age didn’t just happen to be created in this cultural milieu. That is not to say that the monotheistic religions over the past 2,500 years have not held back important thinkers, caused wars and acted (shall we say, pagan-like?) over this time. They have. Each of the monotheistic religions have something to atone for, as do great Eastern religions – Hinduism, Buddhism and Confucianism in their various forms. And no one can deny that in addition to freedom and scientific advances, the Western tradition also created evils such as fascism, Nazism and communism.

Racism, slavery and misogyny existed throughout history in all cultures and while it was the Judeo-Christian tradition that finally ended at least the “acceptance” of these practices, they seem to rear their ugly heads again and again. We see that in the rebound of antisemitism in polite society.

The fundamentalists of all religions and ideologies unable to live with the belief that what they hold dear can be challenged and therefore we have before us various post-modern narratives instead of historical honesty. In my own religion, the fundamentalists go so far as to deny that a great rabbi ever visited a Jewish library and read the stories of a non-religious Jewish writer. The hagiography and insistence that “the greats” never sinned is part and parcel of the fundamentalist narrative and is due at least as much to the same loss of self-confidence that the secular world has endured as it is to blind belief. On the other side, we have “great” historians who create theories that belittle ancient truths with as much scientific proof as the ancient traditions themselves.

In Israel, as we stated before, the Yom Kippur War was the shock that told the elites that maybe they were mistaken in their Zionism and that a new post-Zionist, post-nationalist, European style country is what should replace the pioneering, self-sacrificing, idealistic country that had been built. They looked at Western Europe and saw a peaceful, prosperous continent and wanted to copy it. What they ignored of course was the beginnings of a demographic crisis, the total dependence for their defense on the United States, and most importantly a loss of creativity and energy that comes with the cynicism and exhaustion of a continent that went through two world wars and was free only because outside powers fought their occupiers and tormentors. Half the continent was still under occupation of course in 1945, but that did not affect the post-Zionist worship of the free half then under the nihilistic force of post-modernism.

After the Yom Kippur War, the Israeli establishment and not only the establishment was ready to move on from the Zionism and Judaism that formed the basis of the Jewish and democratic state in order to move it from its pariah-hood in its own neighborhood. The lure of peace and stability and the hope of a comfortable future was put in the hands of those who felt it was Israeli pride and self-respect that was the reason why the country could not live in peace with its neighbors. Shimon Peres, the tactician, par excellence, who was more responsible for building up the IDF than any other single person, decided to turn into a strategist and went so far as to oppose the study of history in schools. Only forward-looking people need apply.

October 7 has brought the country to another crisis of confidence, but the consensus that is being established is neither a return to the post-Six Day War euphoria nor the post Yom Kippur War depression. Over the coming few days we will examine the intellectual, political, military, diplomatic, cultural, social and economic changes that the post-October 7 country is forcing on the old leadership of both the left and right, the religious, fundamentalist and secular. The current election battle is being fought along the old lines, but the country is moving away from them. It could be that the change will come in this October election, but it may take more time until the leadership is changed and the discussion moves from the old battle lines to new, unknown disagreements.

Over the next few days, we will examine the changes that need to happen in order for Israel to deal with the trauma and, dare we say, opportunities that the failure of October 7 has brought.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

Follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

SIngapore Dollar 20260717

Thoughts on the USD/SGD, Cautious Broad Market Sentiment and the Weekend

USD/SGD: Currently a Hope and Prayers Barometer in Global Forex

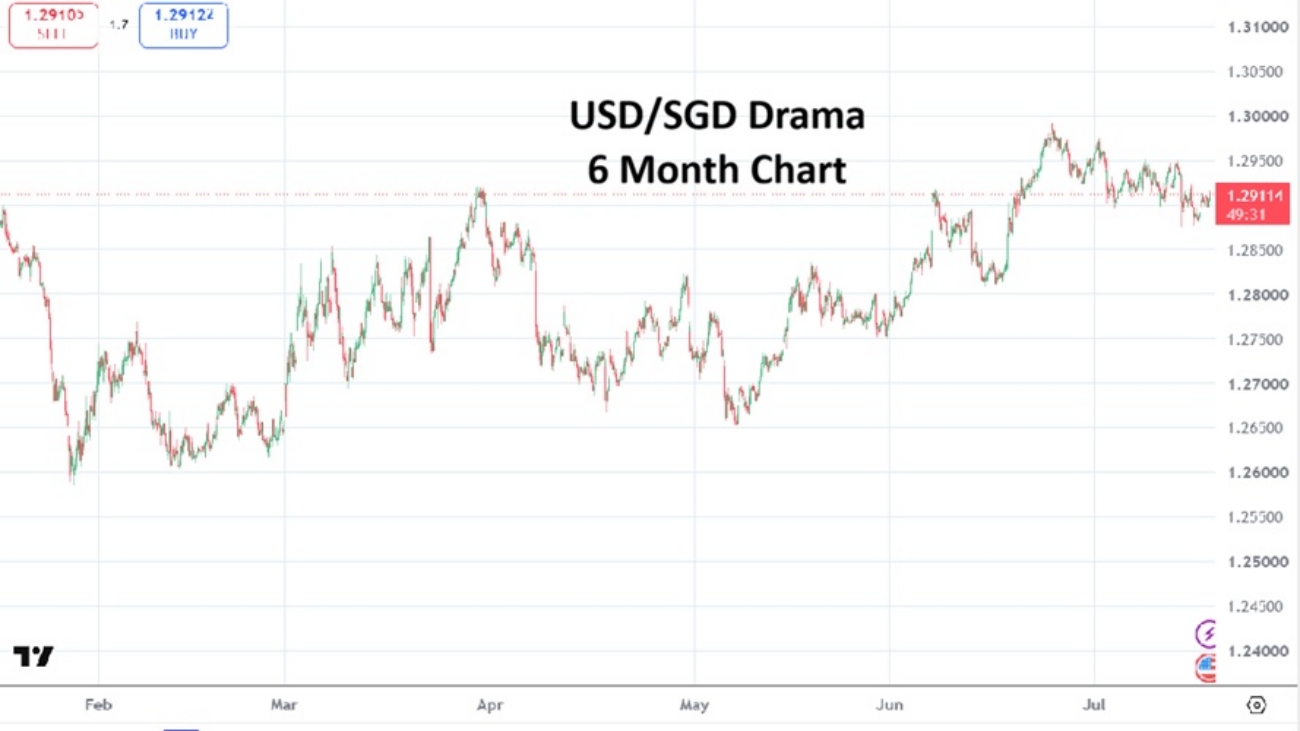
The USD/SGD is near the 1.29110 vicinity as of this writing. Financial institutions apparently have combined their cautious outlooks in the broad Forex market as USD centric strength continues to leak into sentiment, while their instincts technically demonstrate that over the mid-term currencies like the Singapore Dollar should be stronger and the USD/SGD is supposed to show some bearish activity.

For dramatic purposes let’s call this current phase of Forex trading including the USD/SGD as the hope and prayers act. The Singapore Dollar has sustained highs, but it has traversed lower over the past few weeks. On the 24th of June the USD/SGD was near the 1.29940 ratio. Let’s be clear, for small speculative Forex traders broad market wagering on USD direction remains dangerous.

USD/SGD Six Month Chart as of 17th July 2026

Fed Chairman Keven Warsh and His Desire to Introduce New Data

During the recent testimony of Fed Chairman Kevin Warsh in Washington D.C he made it clear he is keen on introducing AI tools into interpretations regarding Federal Reserve policy. However, he also said that AI will not be relied upon alone. From a coding perspective, Warsh essentially said proactive data will become part of the Fed’s thinking with proper supervision: some of you may want to call this a stack developer’s job.

At the same time while refusing to tip his cards regarding his stance on interest rates too much, Forex markets responded by selling the USD in incremental bouts. Intraday trading flared in its usual manner, but started show a core belief that Warsh is demonstrating dovish sentiment regarding interest rates.

USD/SGD as a Forex Barometer and Near-Term Behavioral Sentiment

The USD/SGD serves as a solid barometer of the Forex market. It offers perspectives on Asian sentiment, but also shows how global financial institutions are leaning. The escalation of firepower in the Middle East the past week and into today has caused reactions in the USD/SGD, but somewhat politely.

Having been able to trade below the 1.29000 mark on Tuesday and Thursday of this week, the currency pair is trading near values seen on the 8th of June and 18th. A lack of clarity remains a theme in Forex. The USD/SGD is the 10th biggest Forex pair via transactional averaged volume, so traders should give it attention even if they do not pursue.

Wall Street Remains Nervous and the Tense Weekend to Come

Going into this weekend Forex traders have created downside pressure on the EUR/USD and GBP/USD. The USD/JPY remains stubbornly above the 162.300 ratio. Nervous selling on the Nasdaq 100 via futures trading has been seen today and it looks as if Wall Street will be in for another bumpy ride. The wishful thinking drama in the financial markets is being confronted by the reality of a potentially loud weekend of military conflict between Iran and the U.S, and a seemingly unconvinced marketplace that doesn’t want to demonstrate risk appetite.

WTI Crude Oil prices via futures trading are above $80.00. Having been able to sustain values above the 1.29100 mark in the USD/SGD signals that bearish mid-term perspectives still need additional impetus to create more selling, but this doesn’t appear a wise speculative bet going into the weekend.

A cautious stance over the coming hours should be anticipated as folks wonder what the coming weekend will bring. At least there is the World Cup championship on Sunday (New York time) to take our minds off of concerns. However, Monday will not react to the trophy being raised, but to behavioral sentiment that will takes its cue via today’s finish on Wall Street and noise generated via the Strait of Hormuz this weekend.

Copy and paste the text from AMT that you want to share

10Y US Treasury Yield 20260716

Why the U.S Fed Should Lower Interest Rates Closer to 2%

Fighting Inflation with Higher Interest Rates is Totally Counterproductive

For nearly a century, central banks have relied on one dominant prescription to fight inflation: raise interest rates. The theory is straightforward. Higher borrowing costs discourage spending and investment, reducing demand and eventually slowing price increases.

While this approach may have worked reasonably well in the past, today’s economy is fundamentally different. Applying the same monetary formula developed in the past century by Irving Fisher is obviously creating more problems than it solves. In many cases, raising interest rates has become a counterproductive way to fight inflation.

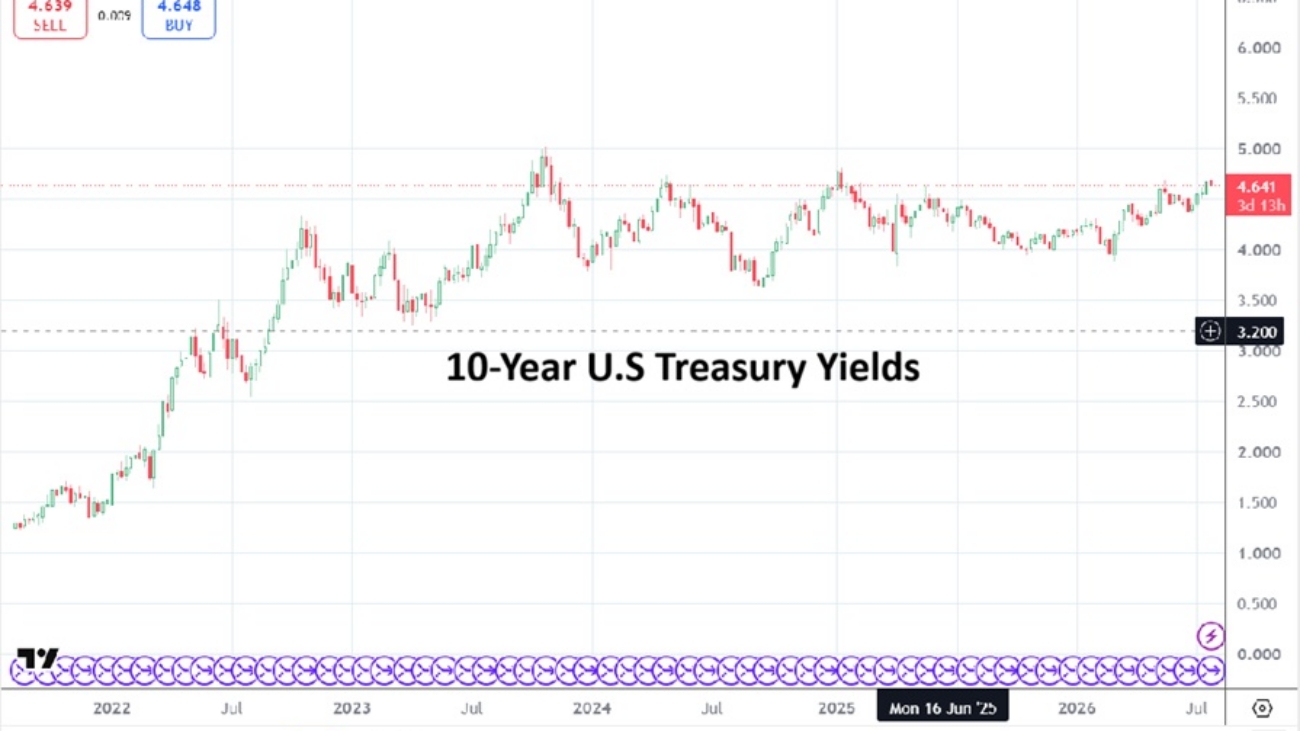
  • The first and most obvious consequence is the impact on government finances. As interest rates rise, the U.S. Treasury must refinance its enormous public debt at increasingly expensive rates. The result is an explosion in annual interest payments, which now exceed $1 trillion. Those payments are in fact a direct injection of additional liquidity into the economy while simultaneously widening the federal deficit.

U.S 10-Y Treasury Yields Five Year Chart as of 16th of July 2026

Ironically, a policy designed to reduce inflation is contributing to larger government spending through higher debt-servicing costs. Instead of easing inflationary pressures, excessively high interest rates may actually reinforce them through this fiscal channel.

  • Consumers also bear a heavy burden. Modern households depend far more on credit than previous generations. Credit cards, auto loans, and consumer financing have become an integral part of everyday life. When the Federal Reserve raises interest rates, millions of Americans see the interest on their credit card balances climb to 20% or more.

Many families attribute their declining purchasing power entirely to inflation, when in reality a significant portion of the financial pressure comes from soaring interest payments.

  • Businesses suffer as well. Higher interest rates increase the cost of financing, while the same capital could be dedicated to investment, expansion, innovation, and research. Every additional dollar spent on interest is a dollar that cannot be invested in productive activity.

A recent example is SpaceX, which issued debt carrying a yield of approximately 6.65%. Given the company’s negative cash flow, investors naturally require a risk premium. However, if the Federal Reserve’s policy rate were closer to 2% rather than current levels, the company’s borrowing costs would be at least half their current level. The extra interest payments would instead be directed toward research, development, hiring, that would strengthen long-term economic growth.

In the current race for AI, that requires heavy investments, the Fed should lower the financing burden on U.S companies. Every additional percentage point of interest represents billions of dollars transferred from productive investment to debt servicing. Money that could finance AI chips, data centers, engineers, research laboratories or new factories instead goes to creditors.

The U.S cannot simultaneously declare China its principal strategic competitor while maintaining a monetary policy that systematically makes capital more expensive for American businesses than for their Chinese rivals, that benefit from much lower rates. The Fed may intend to fight inflation, but it is also making it more costly for American companies to invest in the industries that will determine economic leadership over the decade. The Fed may believe it is fighting inflation, but it is simultaneously increasing the cost of winning the AI race.

Perhaps the greatest weakness of relying on high interest rates is that much of today’s inflation originates from supply-side shocks that monetary policy simply cannot fix.

How does raising interest rates reduce the price of oil when energy prices are driven by geopolitical tensions such as the war with Iran?

How does raising interest rates lower egg prices when shortages stem from productivity issues in the poultry industry?

How does raising interest rates lower the prices of wheat, corn, or cocoa when inflation is due to droughts, floods, or other climate-related events?

How does it reduce insurance premiums that are rising because natural disasters have become more frequent and more costly?

In each of these cases, higher interest rates are totally inefficient to address the underlying cause of inflation. Instead, they merely increase financing costs across the economy while leaving supply constraints largely unchanged.

A more effective strategy would be to fight inflation where it actually originates. Governments possess fiscal tools that can be deployed with much greater precision than broad monetary tightening. Temporary subsidies, targeted tax relief, incentives for increased production, strategic investment in critical industries, and, in exceptional circumstances, carefully designed price controls can address specific inflationary pressures without unnecessarily slowing the entire economy.

For example, if geopolitical tensions cause oil prices to spike, temporarily subsidizing fuel or reducing fuel taxes is likely to be a far more direct and effective response than raising interest rates across the entire economy. Similarly, boosting domestic agricultural production is a better solution to food inflation than making mortgages, business loans, and credit cards more expensive.

The Fed should therefore focus on reducing the financing burden on both the federal government and the private sector. Maintaining interest rates closer to 2% would significantly lower debt-servicing costs, support productive investment, and allow fiscal authorities to intervene more effectively with targeted measures when inflation arises from specific sectors.

The doctrine of fighting inflation through higher interest rates was developed by Irving Fisher nearly a century ago, in an era with very different financial institutions, consumer behavior, and sources of inflation. Credit cards did not exist. Household debt was far lower. Global supply chains, geopolitical energy shocks, and climate-related disruptions were not defining features of inflation.

The modern economy requires modern solutions. Rather than relying almost exclusively on higher interest rates, policymakers should recognize that today’s inflation often demands targeted fiscal responses. Persisting with an outdated monetary framework risks imposing unnecessary costs on governments, businesses, and households while failing to address the real drivers of rising prices.

Supporters of high interest rates often argue that they are unavoidable whenever inflation rises. Yet international experience suggests otherwise.

Switzerland has repeatedly maintained policy interest rates close to 1%, or even below zero in previous years, despite being exposed to many of the same global shocks affecting other economies. Switzerland imports energy, is affected by fluctuations in oil prices, and faces the same geopolitical uncertainties. Yet the Swiss National Bank has generally preferred to tolerate modest inflation rather than impose unnecessarily high financing costs on households, businesses, and the government.

This illustrates an important principle: not every inflation shock requires an aggressive monetary response. When inflation is primarily imported through energy prices or supply-chain disruptions, forcing the entire economy to pay dramatically higher borrowing costs creates more economic damage than the inflation itself.

Copy and paste the text from AMT that you want to share