SP500 20260713

S&P 500: Short-Term Caution and Long-Term Ambitions

Speculative Opportunities Do Not Promise Immediate Profits as Cautious Outlooks Stir

The S&P went into this past weekend with slight gains made on Friday, but essentially finished where last week began. In early morning trading via the futures market the index has seen a slight decline. Retail short-term traders may decide that offers the potential to sit on the sidelines and watch what may be rather choppy conditions, this if they decide not to pursue.

Global markets including stock indices like the Nikkei and broad Forex have shown more discomfort early today. Short-term concerns and mid-term viewpoints are colliding and making momentum hard to sustain. The S&P 500 remains within its elevated realm, but there is a rather unpleasant taste many speculators have had to endure since the end of May, particularly if trading ambitions have been limited to near-term pursuits.
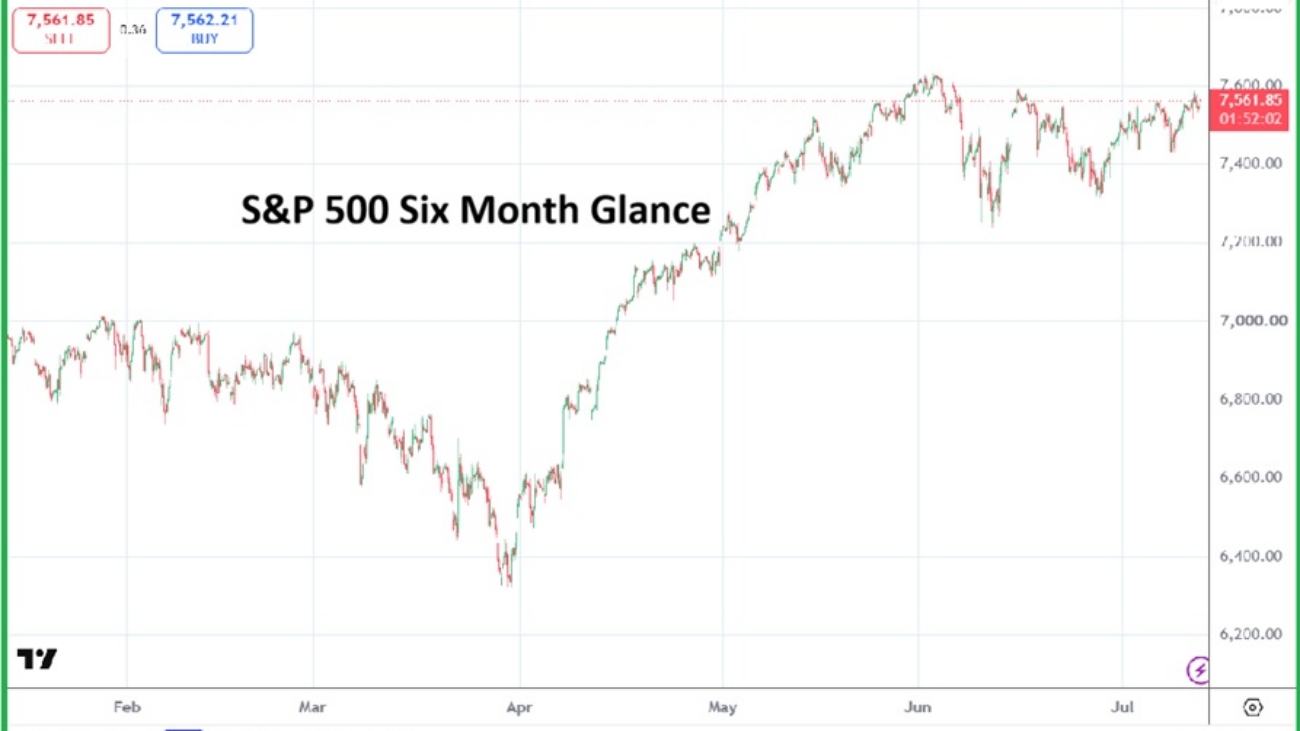
S&P 500 Futures Six Month Chart as of 13th July 2026

There will be a crowd of people at summer parties (or winter outings depending on which side of the equator you are on) discussing the gains made in the S&P 500 (and Nasdaq  100) since the end of March who will be quite keen to brag about their insights. However these same people have likely made their money via pension funds, mutual funds and other long-term endeavors guided by institutions managing their money. Because most short and near-term retail traders have likely been savaged by the results in the marketplace the past handful of months. 

Trading within the current markets conditions for those who have smaller accounts and are relying on leverage to create profits have likely been bled dry of their funds if they have not used proper risk management. It is one thing to want to make a thousand dollars a week in the markets as a retail trader and quite another to actually accomplish the task. 

Indices the past handful of months have been a churning machine in which volumes stir and create attractive chatter, but also deceive folks into believing they can win easily. The only folks winning consistently right now are brokers handling their clients’ retail accounts.

This doesn’t mean you have to stop and give up as a retail trader, but it should serve as a warning that not being overly ambitious and remaining patient are keys when trying to beat the markets. And again, let’s remember the average retail trader has about a 90% chance of failing when trying to speculate.

The S&P 500 did hit a record height in early June around the 7,620.00 vicinity. Its current values are well within sight of those highs too. Yet, headwinds continue to be seen via trading results intraday as financial institutions deal with wavering behavioral sentiment complicated by a myriad of concerns.

Yes, there will always be concerns in the marketplace, risk and reward are often compared to the potential of loss. If you are placing a bet in the markets that you believe can garner a thousand-fold profit, it is likely you are also risking a thousand-fold loss. And unfortunately the marketplace, nor your broker is going to lose sleep over your inability to understand what risks you are undertaking. You will hear that you have learned a tough lesson and the experience will help you become a better trader next time around by your broker, this as they offer you another opportunity to enter the markets on their platforms, but it still doesn’t guarantee you anything. 

The rumblings from the Middle East continues to mitigate sentiment in the global markets. As of this writing WTI Crude Oil is around $73.70. If military conflict between the U.S and Iran continues to incrementally escalate, perhaps experienced players will be able to handle the noise and worries regarding higher energy costs and threats of inflation. 

Equity indices are also running into problems caused by a realization that the costs of investing into companies working in the AI realm are now having to deal with rising costs, this as revenues do not meet expectations, and a lack of adequate physical resources to fuel growth in the sector are raised as concerns. And it is not a stretch to say the AI sector has helped drive more than a handful of equity indices higher. A legitimate fear regarding a downturn in AI related stocks and a possible knock-on effect is a sobering reminder that bullish trends do not last forever. 

And then there is the shadow that is overhangs the Federal Reserve and interest rate calisthenics being worked out by analysts who are trying to convince others (and themselves) that their outlooks are correct.

Yet, we return thankfully to a simple notion and question, one that has very little to do with economics that are taught in university classrooms – are there enough buyers in the marketplace to sustain the upwards trend in the S&P 500? The answer doesn’t have much to do with fundamentals, and often is driven by pure sentiment. Pushing aside day to day travails, wagering on long-term upside remains almost the only wager that can be made. Sure, you can bet on downside; you can short stocks, buy put options that look for lower markets. However, matching negative outlooks with the correct timeframe is just as hard as it is to bet on positive momentum. For the time being it is easy to say the near-term remains murky for day traders. It is harder to predict actual direction
Copy and paste the text from AMT that you want to share

Gemini3 20270711

The Great Compression Part 3: The Immovable Object

The Landlord Beneath the Cloud

There is an old paradox: what happens when an unstoppable force meets an immovable object? The AI buildout is the unstoppable force – the largest concentrated wave of capital spending in history. The immovable object is the physical world it is colliding with. Land, power, and water are the tangible bedrock that no balance sheet can conjure into existence. The paradox has a resolution the classical philosophers never thought of: the immovable object collects the rent.

Consider the scale of the force first. The four hyperscalers – Amazon, Alphabet, Meta, and Microsoft – plan to spend roughly $725 billion on capital expenditures in 2026, up nearly 80% from the year before. Add Oracle, the neoclouds, sovereign funds, and the rest of the AI heavy spenders – and total compute capex crosses $1 trillion in a single year, the first trillion-dollar year of its kind. Much of that money flows to the visible beneficiaries the market already knows by heart: NVIDIA for the GPUs, Micron for the memory, Dell for the servers, Cisco for the networking. Silicon, racks, interconnects.

The Great Compression Part 3: The Immovable Object 

But every one of those chips has to be housed somewhere. It has to be powered. It has to be cooled. And this is where the unstoppable force runs into something it cannot simply outspend.

The constraint is no longer capital, and it is increasingly no longer silicon. It is the physical world. The bottleneck has shifted to power generation and grid interconnection, which take years to permit and build, and to the land and water that data centers consume at industrial scale. The richest corporations that have ever existed are discovering that a signed check does not produce a megawatt or a water right. The immovable object has begun to set the terms.

Nowhere is this clearer than in a deal signed on June 23rd. Texas Pacific Land Corporation, aka TPL, agreed to provide the surface acreage and brackish water for Project Kilby, a large-scale power generation facility Chevron is building to supply a Microsoft data center cluster in Reeves County, Texas. When the announcement crossed the wires, Chevron’s name led every headline – and TPL was a footnote.

Meanwhile, the framing should be exactly backwards. Chevron, for all its scale, is the replaceable party in that transaction. Exxon, Occidental, or any of a dozen major energy companies could have built that power plant. What none of them could have supplied is the specific land and the specific water rights in that specific corner of the Permian Basin – because those belong to TPL, and there is no substitute for them at any price. The company that got the headlines is interchangeable. The company that got the footnote is the immovable object.

TPL is the purest expression of the scarcity trade beneath the AI buildout. It owns roughly a million acres of West Texas and produces almost nothing itself. It does not drill. It does not manufacture. It collects royalties, easements, and water fees from everyone who needs to operate on its ground. It is a toll booth on the physical world, and the AI buildout has just become one of its largest new customers. For years the market valued it as an oil-and-gas royalty play. It is quietly becoming an infrastructure landlord for compute – and almost nobody has ever heard of it.

The same logic radiates outward through the entire physical layer. Power is the genuine bottleneck, and the companies that generate it are being repriced accordingly. Constellation Energy, the largest operator of nuclear plants in the U.S., has become an unlikely AI stock as hyperscalers sign long-term deals for the one thing they cannot build fast enough: reliable, always-on baseload power. The grid that carries it has its own set of indispensable names – Quanta, which builds and maintains transmission infrastructure; GE Vernova, which supplies the turbines and grid equipment; Eaton, whose electrical systems distribute power inside the data center itself. And as chip density rises, the heat has to go somewhere, which has turned Vertiv, a maker of cooling and thermal management systems, into a core holding of the buildout.

What is striking is that this category does not merely sit still and collect. Some of its members are actively repositioning to attack. Ford, unable to win the electric-vehicle war against Tesla and nursing a $19.5 billion writedown on its EV investments, has taken the same physical assets – its plants, its battery capacity, a century of manufacturing expertise – and redirected them. In May it launched Ford Energy, a subsidiary building grid-scale battery storage systems, with data centers named explicitly as the demand driver. The immovable object, it turns out, can also choose its targets.

This is the HALO trade: Heavy Assets, Low Obsolescence. Companies whose value rests on tangible, physical assets and established operations that are expensive, time-consuming, or regulated – and therefore very hard to replicate. Land. Power. Grid. Water. Steel and concrete and copper. The unglamorous inputs that no model can commoditize because they cannot be reduced to software, and no amount of capital can summon into existence overnight.

None of this is permanently fixed, and it would be dishonest to pretend otherwise. Innovation erodes scarcity: small modular reactors, advanced geothermal, and better transmission technology will, in time, loosen some of the constraints that look absolute today. But two things blunt that threat. The first is Jevons paradox – when a resource becomes cheaper to use, consumption rises to swallow the savings, which means more efficient power generation is likely to expand the buildout, not shrink the edge of the providers. The second is that not all heavy assets are equal. The manufacturers and equipment makers face real competitive pressure over time. The owners of irreplaceable location – the specific acre, the specific water right – do not. You can build a better reactor, but you cannot build another Permian Basin.

The value that fled the human middlemen, that commoditized in the model layer, that migrated up the stack toward proprietary data and orchestration – also flows downward, and at the bottom it stops. It settles into the ground, into the wires, into the water table. But the ground is not neutral territory: land is permitted, power is regulated, water is allocated, and the fabs that print the silicon sit inside country borders. The unstoppable force keeps accelerating; the immovable object keeps collecting. And the moment we ask who owns the immovable object, the scarcity trade stops being a matter of markets and becomes a matter of sovereignty.

Copy and paste the text from AMT that you want to share

Nvidia 20260630

Nvidia Suffering From the AI Cold Bothering Investors and Speculators

AI: Exuberance and Threats of Fatigue

Has Nvidia now been oversold? While the Nasdaq 100 produces a casino like experience for day traders and large players, the velocity of value changes in the index should serve as a simple reminder that before stepping into traffic a speculator needs to acknowledge the road. A large collision is taking place before our eyes and it will generate more noise over the coming months. 

Nvidia is a solid indicator of behavioral sentiment being influenced by a mix of optimism and fears by speculators and investors competing, and trying to define terrain as turmoil swirls and a battle for profits rage. Day traders need to remember a lot of hyperbole is amplified to get eyeballs on opinions, hoping that your attention is grabbed. (Please buy me a cup of coffee has become a begging mantra).

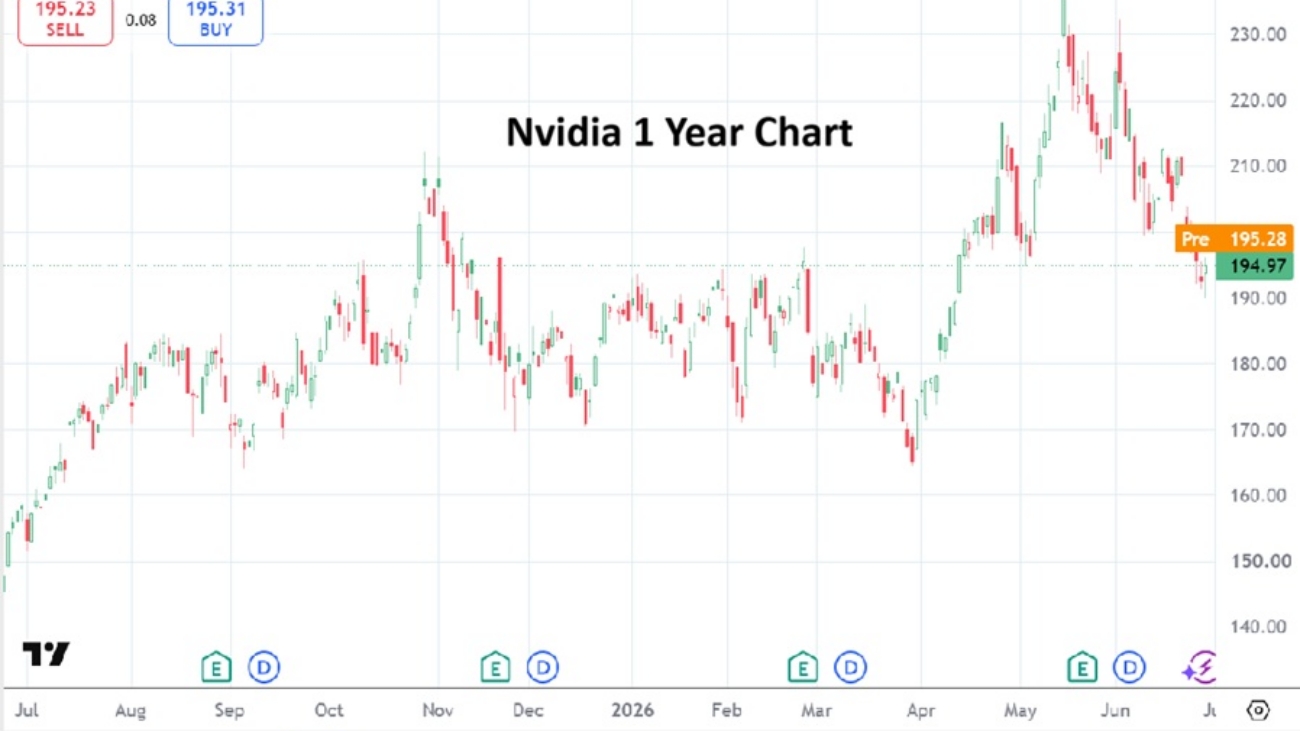
Nvidia One Year Chart as of 30th June 2026

Nvidia finished yesterday’s trading near $195.00, this after touching highs in May around the $238.00 vicinity. The fact that NVDA has lost a large chunk of its value indicates sentiment is not entirely rational. There is a vast difference between speculative hopes compared to long-term investing. 

Results in the stock markets do show symptoms of overbought conditions prevail, but over indulgent fears are taking hold as folks try to interpret every move in a haphazard manner and make correlations which often have no evidence. Nvidia is a solid company which will continue to produce product lines that will be needed long-term. Talk of Nvidia suffering from an AI cold is relevant because it has certainly lost value, but the patient is going to survive.

Others however may not. AI companies and their proclamations about being able to deliver substantial change for users has become tiresome. Supply of software is widespread. While there is demand for use, competitors are abundant and growing daily. Users can now question just how reliable and strong the products they are using are, and if promises meet the results wanted. Costs users are paying for services will also become more critical. If products don’t meet needs, other AI systems can be easily installed nowadays. 

Oversupply is Saturating the Marketplace

Because AI tools are widespread it means users will demand services get cheaper. At some point it is clear that consumers will gravitate to competitive pricing, because at the end of the day there is only a certain amount of time to verify all the products in the marketplace and understand what works best. Branding as always is important, but so is quality. Loyalty in the AI world is only a couple of years old and cannot be counted on, some early companies are already seen as legacies and allegiances will shift. 

Competitors and new ideas continue to be brought forth quickly. A lot of product is being rushed to the market that lacks proper Q&A and actually does not deliver what is promised. Proof of concept is fluid with Artificial Intelligence, along with many claims of superiority. A company can get a product into consumers hands first, but at some point value has to be delivered too.

Investors are growing wary from too many claims. Yes, a revolution has taken place, but a counter-revolution is certainly coming. A lot of AI products are simply poor. Day traders have seen chaotic results on the Nasdaq 100 over the past year. 

President Trump, tariffs, the war in Iran, Federal Reserve and interest rate uncertainty, fear of inflation (all headlines from only the past few weeks) and other complexities can be blamed for volatility as folks wager on values on the Nasdaq 100. However, the prime mover of the index has not only been investing by long-term players, it has come from speculation chasing momentum via the Artificial Intelligence boom. However, a genuine concern that a fear of missing out is turning into fatigue exists.

AI because of its abundance is going to eliminate competing systems which are seen as cumbersome and expensive. Chinese companies appear ready to confront American enterprises with cheaper products that consumers may not mind paying less for even if this means consumers are sharing intellectual property and data with unknown entities. 

Sakana AI from Japan has announced and shown the past couple of weeks that it has software, Sakana Fugu, that is comparable in a favorable manner to Anthropic and Claude services. Sakana testers claim their system is robust and offers a multi-integrated modeling system, meaning a user doesn’t have to toggle in and out of models to deliver efficient information. The data via Sakana’s system is brought together via coordinated agent forces for the user. What will this do to valuation of Anthropic moving forward?

There is also a South Korean company called Furiosa, which is not public yet, that stands in the shadows and makes outstanding AI infrastructure. Furiosa appears ready to become an important player in chips and software innovation. Nvidia is certainly keeping their eyes on Furiosa. Meta offered Furiosa 800 million USD and was rejected in March 2025. 

Investors and speculators should not discount the potential of an AI tech dump from global competitors into the U.S and elsewhere developing over the next year. Mobile phones became a rather boring commodity after their initial entry astonished first time users two decades ago, AI will undergo the same pathway.

Some AI companies will certainly struggle over the next few years, but other enterprises will succeed merrily and profit. There is a big difference between investing and speculating. Even mid-term forays into the stock markets remain only gambles if a person plans on cashing out profits when they have hit a price target, instead of long-term ambitions to own shares in a quality company. 

Nasdaq100 bubble talk which has recently reignited in a loud manner should be given attention but astutely. It is hard to argue that the value of the indices like the Nasdaq 100 and S&P 500 are not in over-inflated territory. Looking at historical p/e ratios seems to have gone out of fashion. Warren Buffet cannot be thrilled and his fundamental strategies should not be ignored. Speculative hype needs to be confronted by investment reality. Folks will continue talking themselves into stances that are comfortable, even if they make little sense. The markets will certainly survive and so will AI.

Copy and paste the text from AMT that you want to share

US Cash Index 20260617

Forex and the Fed Chair: Kevin Warsh in the Spotlight Later Today

New Federal Reserve Chairman will Cause a Reaction in Forex Today

I offer readers a ‘what if’ proposition ahead. These are my opinions and I am simply trying to give my perspective on what may happen in the Forex market in the coming hours.

The Fed Press Conference later today will be must watch television for Forex traders, including retail speculators, large players and financial institutions. Federal Reserve Chairman Kevin Warsh will make his first appearance after a FOMC rate decision. Dynamic conditions in the broad Forex market should be anticipated – that doesn’t tell day traders much I know, keep reading, please. 

U.S inflation has sparked higher this as energy prices have ignited upwards and caused logistics, manufacturing and agriculture to become more expensive. The Bank of Japan raised its interest rate by a quarter of a point yesterday to 1.00%. However, these two bits of evidence doesn’t mean the Federal Reserve will increase its interest rate today. 

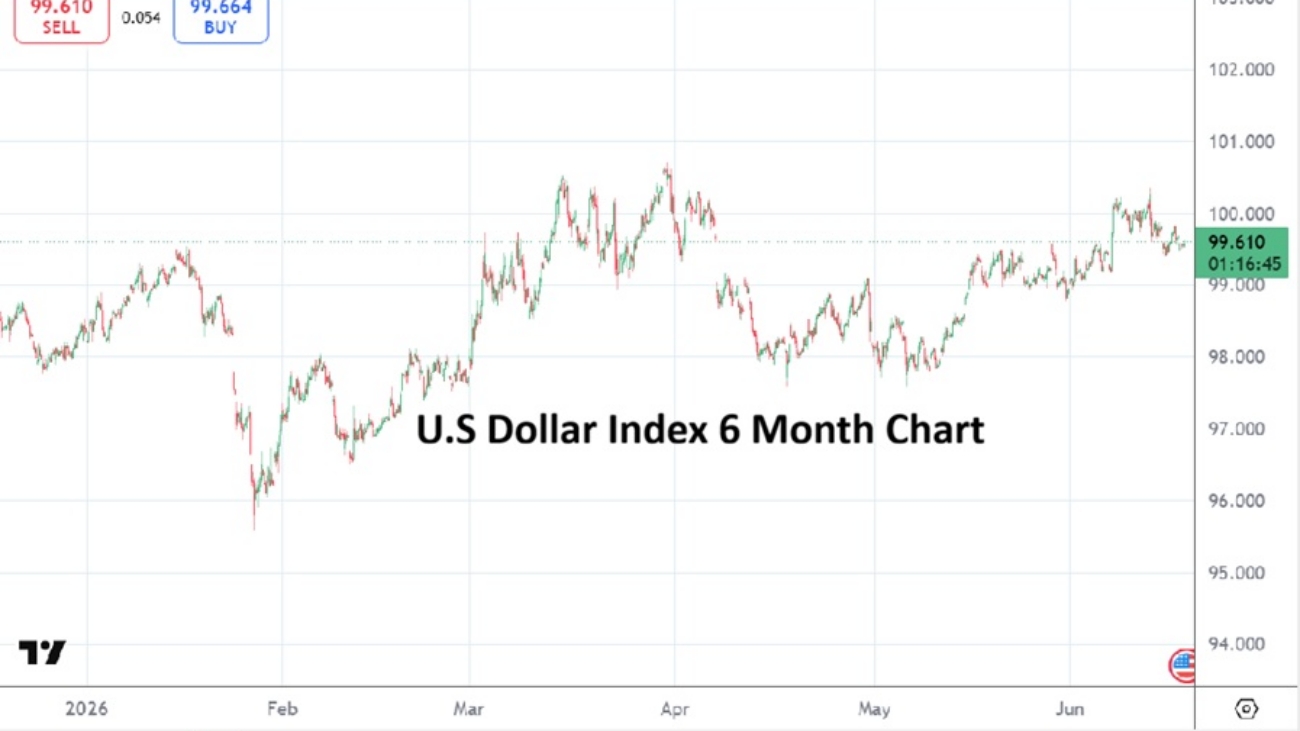
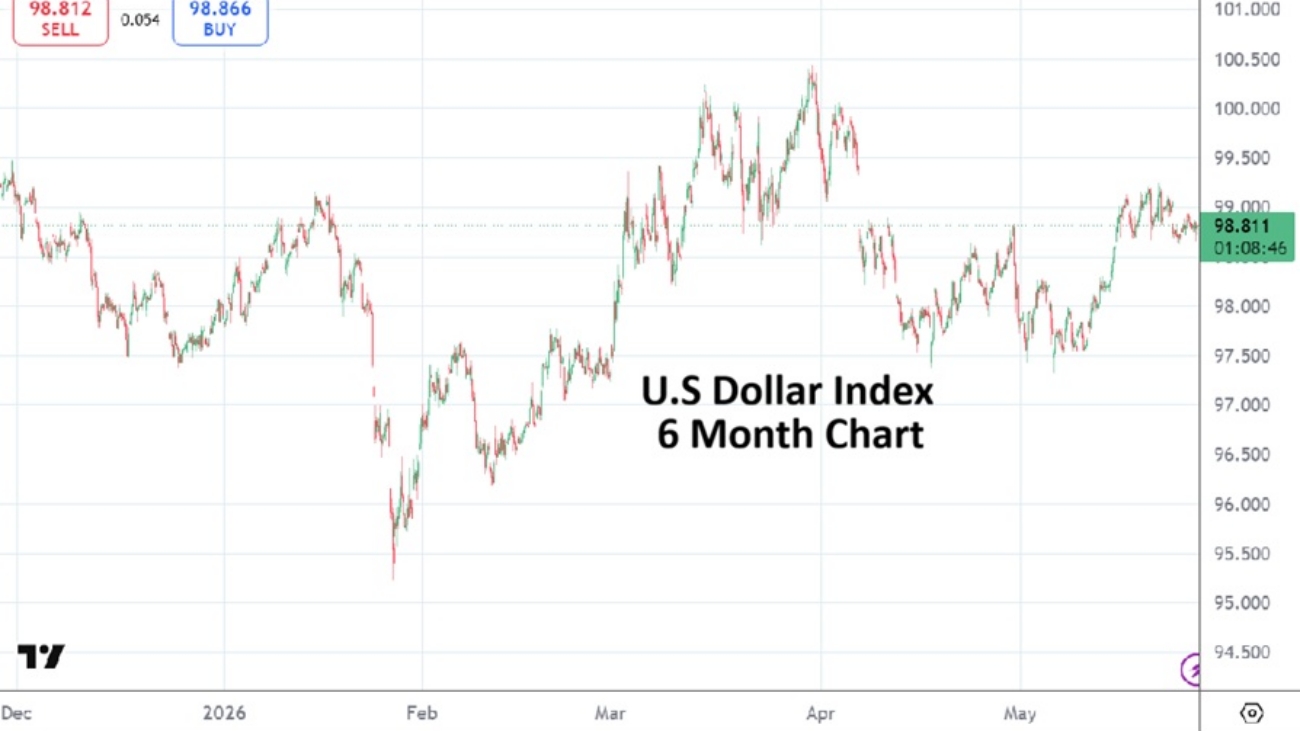
The U.S Dollar Index is trading near relative highs. The broad FX market is certainly cautious, but financial institutions may be leaning into the notion of USD centric weakness. Yes, the USD/JPY remains above 160.000+ for the moment, but the USD/SGD is flirting with its lower range and came within sight of the 1.28000 mark on Monday. So why is this important? Because folks are acting cautious before a potential storm.

U.S Dollar Index Six Month Chart as of 17th of June, 2026

Perhaps this will go down as an infamous egg on the face situation for me personally, but does Fed Chair Kevin Warsh really want to raise interest rates during his first FOMC meeting at the helm? Yes, Jerome Powell is still around as a voting Governor, but Warsh may find he has enough votes (and influence) to get a majority of other FOMC voting members to allow today’s decision to be a test case in favor of patience. 

If the Fed holds the Fed Funds Rate in place and announces it will use the near and mid-term as a trial period regarding their belief inflation will lessen, because it believes energy prices over the mid-term will erode rapidly, that may be enough to cause USD centric selling later today. The Fed will not use the word transitory I suspect, but an argument can certainly be made that now is the time to actually elucidate on the subject of transitory inflation.

Monday’s trading in the broad Forex markets showed that financial institutions bought into the optimism of an anticipated U.S and Iranian agreement and what it could deliver – a glut of Crude Oil, including lower costs for its ancillary products. Financial institutions were also relieved that U.S equity markets survived the launch of the SpaceX IPO certainly. While yesterday’s broad market trading turned cautious and demonstrated sideways action in Forex, many major currencies are traversing near curious values. Equities also went sideways for the most part on Tuesday.

The U.S Dollar Index is swimming within its higher terrain via a six month chart (per a look above), yet financial institutions – if they hear dovish sentiment from the new Fed Chair today could spring into action and sell the USD quickly. Day traders need to understand even if this occurs that it will still be ultra-dangerous to bet ahead of the Fed rate announcement and Press Conference. This because volatility leading up to and following the FOMC Federal Funds Rate decision will create large spreads in Forex and choppiness that small retail accounts cannot handle most of the time – particularly when too much leverage creates wildfires.

While the before and after of the Fed interest rate announcement will garner the headline news, and create a reaction on Wall Street for the S&P 500 and Nasdaq 100 immediately; it will be wise to pay attention to Fed Chairman Kevin Warsh a half hour later when he steps into the spotlight for the first time. There has been chatter that Warsh is not keen on trying to give too many signals regarding the Fed’s thinking regarding every move it is contemplating. 

This coincides with thoughts that Kevin Warsh and Scott Bessent believe in a more high-tech and pro-active approach to interest rate and monetary policy based on forward looking data. The consideration of a more dynamic approach to interest rates has not been widely considered by financial institutions quite yet. If the new Fed Chair surprises reporters and onlookers at the Press Conference today with a new philosophy on the way the Fed will work, this will set the stage for potentially large behavioral sentiment shifts that were not wagered on quite yet. In other words mid-term outlooks regarding U.S interest rate policy may change in a handful of hours more than many people think. 

Maybe I am wrong, maybe I am interpreting the political and financial landscape incorrectly, but these are my thoughts as a risk analyst – one who thinks the U.S White House would not mind seeing a weaker USD, a Fed that likely wants a different approach to interest rates – as they both hope for energy prices to lower (and may get their wishes fulfilled).

Copy and paste the text from AMT that you want to share

AMT Top 10

AMT Top Ten Miscellaneous Meditations for the 16th of June

Memorandum of Misunderstanding, the SPCX Rocket, the Knicks and Brazil as Jazz Plays in the Background

10. Legacy: Sonny Rollins passed away on the 25th of May at the age of 95. Rollins was a master jazz musician and saxophonist who will be listened to forever. His sound, cadence and imaginative ability to create while playing with bands, and often lead via his unique style make him an everlasting legend. If you haven’t listened to Sonny Rollins start out with his song St. Thomas via Saxophone Colossus.

AMT Top 10 Miscellaneous Meditations for the 16th of June, 2026

9. Surreal: The New York Knicks won their first NBA Championship in 53 years. Some Brazilian football fans returning to their hotels after their team’s 1-1 draw versus Morocco in their Group Stage World Cup match in New Jersey had to walk through throngs of Knick fans celebrating on the streets of Manhattan in bizarre looking circumstances as they worried about their national team. Walt Frazier and Pele both wore Puma and met in the 70’s.

8. Strategy: Michael Saylor continues to claim the wet and cold Bitcoin wind blowing back in investors’ faces is a refreshing mist that will invigorate the HODL crowd eventually. In the meantime MSTR is near $131.00 and BTC/USD around $66,300.00. Saylor sees Bitcoin above 1 million eventually and beyond, while some others see headwinds and more losses developing.

7. Bleeding Money: Political mismanagement shadows Chicago which appears ready to lose the Bears football team via a new stadium across state lines in Hammond, Indiana, this as team officials and ill-equipped Illinois leaders argue about property taxes and other business considerations (and maybe kickbacks). NYC is hurting for funds too, this as important companies make plans to place their corporate headquarters and employees elsewhere and avoid Mayor Mamdani’s nonsense. Apollo Global Management is the latest to decide to venture forth into Texas and make its New York presence less important. 

6. Commodities: Gold is near $4,330.00 this morning, Silver around $70.00 and WTI Crude Oil close to $78.00 via futures pricing.

5. Nasdaq 100: The index finished 3.06% higher yesterday and at a value of 30,543.92 per last night’s close. The Nasdaq 100 has been delivering a wild ride for speculators and investors. The index saw all-time highs in early June when it went above the 30,700.00 level. The S&P 500 concluded Monday’s trading at 7,554.28 and up by 1.65%, the index’s high was also in early June when it went above 7,600.00. For all the talk of doom and gloom over the past week and a half with fears about a sustained run downwards in the U.S indices, they are showing upwards momentum for now. 

4. BoJ: The USD/JPY remains within sight of the 160.000+ mark consistently. While other major currencies have gained a bit the past few days against the USD, the Japanese Yen remains sticky near its highs as the Bank of Japan is likely watching speculators wager on the higher realm. FX traders need to remember that the BoJ may act when it feels it has enough clarity regarding the Iran saga and inflation concerns. In other words, a warning shot may come soon threatening an intervention. Buyers beware.

3. SpaceX: Is it a bird or a plane? No, its a 2.1 trillion market cap valuation via a rocket like IPO on the Nasdaq 100. While some may want to bet against Elon Musk early, those type of decisions have proven costly mistakes for some short sellers in the past when dealing with Musk and Tesla. Some may argue for value of $115.00 and less per each SPCX share, but it might prove unwise to step in front of the upward trend for the moment. Case in point, Tesla is near $411.00 per share and causing chagrin within certain crowds as they point to weakening sales, but only see the company do better in value. Oh, and SpaceX ended Monday’s trading at $192.50.

2. Fed: Kevin Warsh leads the FOMC Committee as the Chairman for the first time as the Federal Funds Rate decision awaits this Wednesday. Some think the Fed will increase the interest rate by 0.25%, AMT does not based on the opinion Chairman Warsh likely wants to start off his job on friendly terms with the White House and Treasury, while also counting (hoping) on cheaper energy prices.

1. MoU: The Iran conflict awaits a signed agreement. The terms of the Memorandum of Understanding are being whispered, but transparency has not been delivered and won’t be until Friday supposedly when the U.S and Iran attend a ceremony in Switzerland. While financial institutions and global markets are ready to turn the page and engage in optimistic outlooks, it remains to be seen if negotiations will lead to tangible results as multiple questions and concerns linger. In the meantime a sizeable part of Iran’s population still lives under tyranny. Who won? Did President Trump make a quiet deal with China to guarantee oil flows from the Strait of Hormuz and receive something in return during his visit to Beijing from the 13th to the 15th of May? There appears to be room for plenty of misunderstanding.

Copy and paste the text from AMT that you want to share

Indian Rupee 20260611

India Insider: Should the RBI Raise Interest Rates?

A Case for Higher Interest Rates In India

As the Rupee remains under pressure and oil prices continue to rise amid tensions in the Middle East, the debate has shifted towards what the Reserve Bank of India (RBI) should do next.

Economist Janak Raj has argued that raising interest rates to defend the Rupee comes with significant costs. Higher rates increase the cost of capital for businesses, reduce investment activity, and compress equity valuations. In theory, this could even accelerate foreign outflows from equities rather than attract fresh capital. Yet the RBI may soon find itself with limited options.

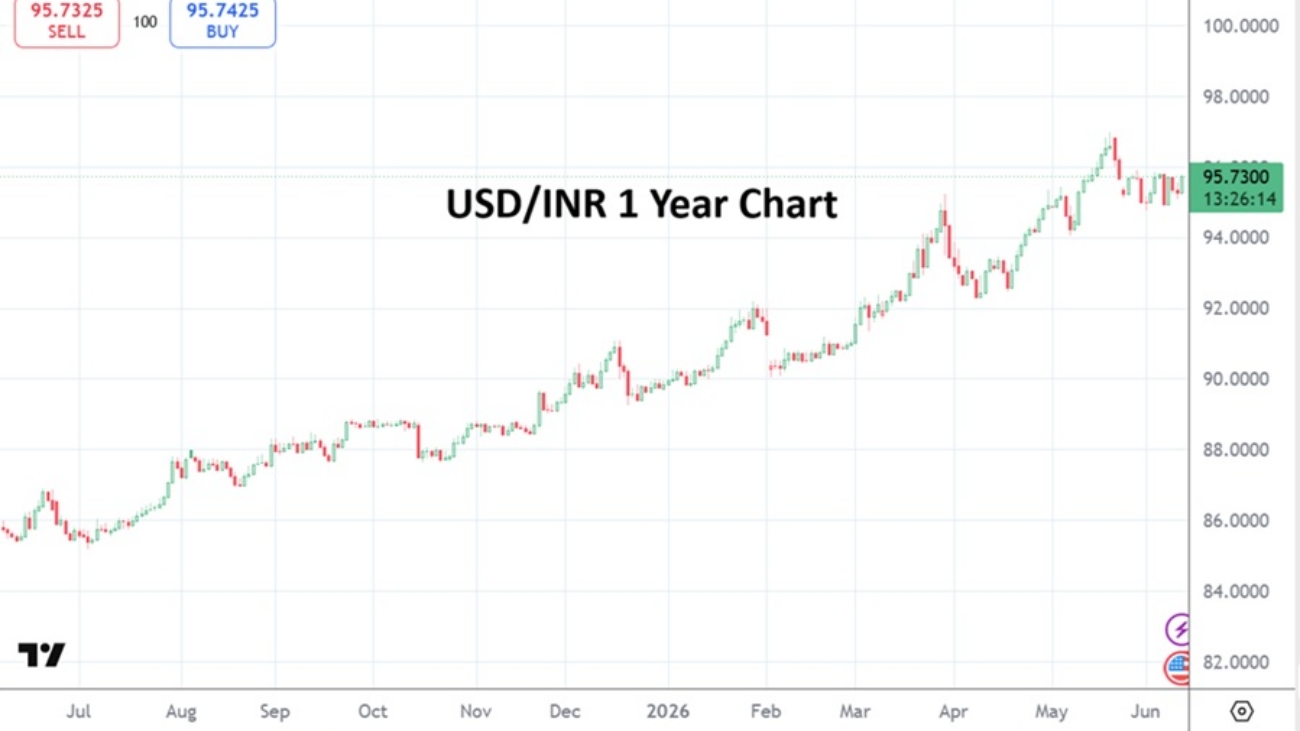
USD/INR One Year Chart as of 11th of June 2026

Foreign Portfolio Investors (FPIs) were net buyers of Indian equities for most of the period between 2004 and 2024, with only a few exceptions such as 2011, 2018 and 2022. However, the trend has changed. FPIs sold approximately $19 billion USD worth of Indian equities in 2025 and another $24 billion USD so far in 2026.

Question: Why are Foreign Investors Selling

One reason is that global investors today have alternatives. The growth of Artificial Intelligence related companies in the United States has created significant investment opportunities. At the same time, U.S Treasury yields hovering around 4.6% offer attractive risk-free returns in a strengthening dollar environment.

For many global investors, earning high returns in Dollar assets is preferable to taking exposure in emerging markets that face current account pressures from rising  Crude Oil prices and other energy costs.

Taxation is another factor. India taxes foreign investors at 20% on short-term capital gains and 12.5% on long-term gains. Meanwhile, competing financial centres such as Singapore, Hong Kong, Malaysia and Thailand generally do not tax foreign investors’ capital gains.

Some global funds have argued that India should move closer to international norms, where capital gains are usually taxed in the investor’s home jurisdiction rather than the country where the investment is made. Higher post-tax returns would undoubtedly make Indian assets more attractive.

A stable Rupee would also reduce hedging costs, lower currency-risk premiums and improve the overall risk-reward profile for overseas investors. However, tax cuts alone cannot solve India’s problem.

The Real Issue is Balance of Payments

As Business Line columnist Lokeshwari Mam has pointed out, a significant portion of equity outflows consists of short-term speculative capital. Long-term capital tends to remain invested. This is why the decline in net Foreign Direct Investment (FDI) should concern policymakers more than short-term fluctuations in portfolio flows.

Net FDI has fallen sharply from $28 billion in FY 2022-23 to just $7.7 billion in the year ended March 2026. This is a worrying trend because FDI is the most stable source of external financing. Unlike portfolio flows, it creates factories, jobs, exports and long-term productive capacity.

India therefore needs more than tax incentives. A genuine single window clearance system, reduced bureaucracy, easier business regulations and reforms in manufacturing remain essential. Attracting long-term capital should be a national priority.

The recent foreign buying of Indian bonds after tax cuts is encouraging. But relative to India’s current account financing requirements, it remains a small drop in the ocean.

For example, in FY 2025, the current account deficit was 0.6% of GDP. And in Q4, the current account became a surplus. Is it really that difficult to finance it’s small current account deficit?

India’s external vulnerability is determined not merely by a current account deficit, but by whether the capital account can be comfortably financed. A modest current account deficit still creates currency pressure if foreign capital inflows weaken (which we are seeing), while a larger deficit may be sustainable when capital inflows remain strong. The risk of sustained higher oil prices could widen the deficit, increasing India’s dependence on foreign capital at a time when global liquidity is tightening and U.S Treasury yields are rising.

Furthermore, hedging costs continue to erode much of the yield advantage that Indian bonds offer over U.S Treasuries. In that sense, active global money is likely to prefer Dollar assets over emerging-market debt or equities

India’s repo rate currently stands at 5.25%. The RBI’s decision to raise its inflation forecast to 5.1%, while lowering its GDP growth projection to 6.6% reveals where the shock from the Iran conflict is likely to be felt via higher inflation and weaker growth. For an economy that remains heavily dependent on imported oil, a depreciating Rupee only compounds the problem by increasing the cost of energy imports. 

In such an environment, the Monetary Policy Committee is unlikely to focus solely on growth. Currency stability, inflation expectations and the availability of foreign capital to finance India’s external requirements could become increasingly important considerations. If these pressures persist, the RBI should raise the repo rate, in the same manner other Asian central banks have done in recent weeks.

Copy and paste the text from AMT that you want to share

Celtics and the Middle East 20260609

Falling into the Middle Eastern Trap

When Talking Becomes an Obsession

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 9th of June via The Angry Demagogue.

The United States is falling into the Middle Eastern trap that Israel fell into thirty years ago. This trap fits nicely with the post cold-war progressive Western way of diplomacy in that its goal is “talking”. Perpetual talking rather than deal making is the key to understanding the Middle Eastern way of things and Israel has become a practitioner in the “way” that led directly to October 7. The idea of perpetual talking is to reach a situation where you can defeat your opponent without making concessions. In the Middle East, they suck you in to a point where just “talking” becomes an obsession. The United States is heading into the same where results are less important than the act of discussion itself.

Falling into the Middle Eastern Trap – When Talking Becomes an Obsession 9th of June 2026

This obsession, this being sucked into something against your best interests reminds me of a wonderful episode of Cheers, the sitcom that takes place in a Boston bar – a bar in which pints of beer plus inane discussions over anything that leads to nowhere is its reason for being. The episode that I am thinking of has Boston Celtics great Kevin McHale as a guest and the two main instigators of irrelevant and purposeless conversation, Norm and Cliff, (not so) innocently ask McHale how may bolts are in the famous parquet floor at the Boston Garden.

The waitress Carla, Boston working class par excellence, begs the basketball star to ignore them, knowing he will become obsessed and sucked into something that clearly will lead to a disaster for him and her beloved Celtics. Sure enough, the episode ends with McHale driving towards the basket with what ought to be the winning shot only to get distracted by trying to figure out how many bolts are in the floor of the Boston Garden.

That is exactly what is happening now in in the Middle East where President Trump is the basketball star being distracted by Iran and their attempt to suck him into endless discussions that are meant to lead to nothing productive. We don’t know if McHale ever figured out the number of bolts, but besides going back to Cheers with the answer, it is a useless endeavor that can only lead to defeat. So too, with the Trump Administration and the sacred talks with Iran where the end game might be something he can bring back to a press conference in DC or a rally in Pennsylvania but will be worth as much as knowing the number of bolts in the Boston Garden floor.

Israel fell into this trap with the Palestinian Authority of Yasser Arafat and when talks ended, the only goal was to start them up again. Just return to talking. The result didn’t matter. This trap picked up again after October 7 when the goal seemed to be to always be talking with Hamas via Qatar or Egypt even if everyone knew it would lead to nowhere. Ironically, it was President Trump who realized this and was able to do his dealmaking magic to free the hostages – but only after the IDF put Hamas in an untenable situation and Qatar wanted a “great deal” with the Trump administration. Talks never led anywhere.

So here we are, the Trump Administration is hell bent on continuing discussions for the sake of discussions no matter how many times Kuwait, UAE, Bahrain, Israel, or even the U.S military get shot at by Iran. When the goal is talking – when the obsession becomes talking – you have fallen into the Middle Eastern trap much as Keven McHale fell into the trap of inane bar talk for the sake of inane bar talk.

While the American President is a deal maker par-excellence, the Middle Eastern leaders, this time Iran’s, are the experts at making you think that talking is always the best outcome – because it is, for them. Eventually, their experience tells them, you will make a mistake. The Administration has allowed Iran to attack allies at will in the Gulf and in Israel, as Iran gains concession after concession due to the trap that is “talks at all costs”. The first concession was linking Lebanon to the talks and the next, done just yesterday was in putting Iran and Israel on the same level.

This is the mistake one would expect from the Obama-Biden crowd where they always believed that talks were the purpose – they didn’t have to fall into any trap as they were there already. However, the Trump Administration understood the fallacy of forever talks which is what makes it so painful to see them fall into the same Middle-Eastern and Western, progressive trap. Obsession to make a deal is good because results oriented; but an obsession that is just to “get back to talking” will lead only to results that you never wanted in the first place.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

Follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

Nasdaq 100 20260608

Nasdaq 100: Terrible Friday Being Confronted by Manic Monday

Fear of the Middle East Not the Main Motivator for the Nasdaq 100

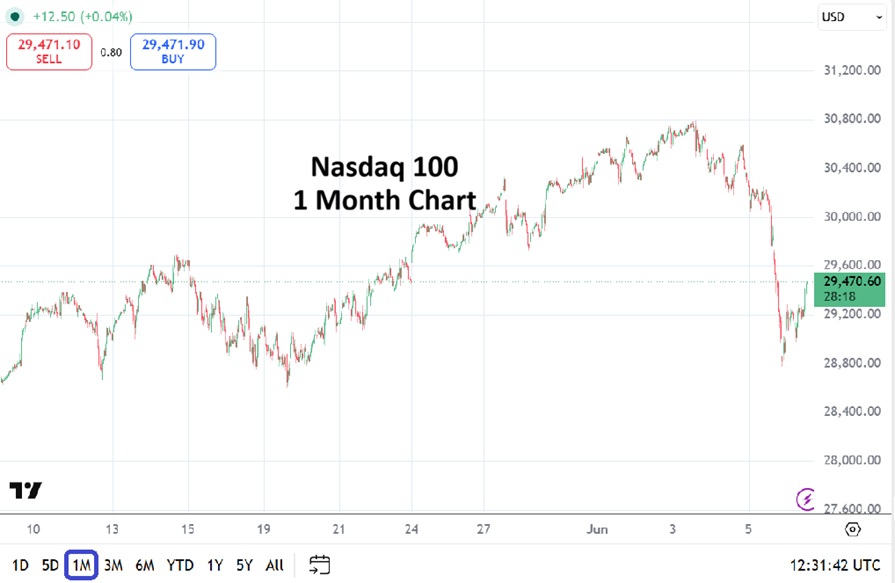
After Friday’s selling surge and a fall of -4.77% with a close of 28,957.60, the Nasdaq 100 futures trading this morning has actually seen an increase and is near the 29,479.00 mark as of this writing before the cash Nasdaq 100 market opens.

Friday’s selling nightmare for traders who found themselves stubbornly locked into what were to be short-term buying positions and saw the Nasdaq 100 plummet -4.77%, probably woke this morning believing ugly conditions may not stop. An escalation in military action via proclaimed retaliatory moves between Israel and Iran started today’s trading with a high degree of more anxiousness. USD centric strength in Forex was demonstrated early.

Nasdaq 100 Futures Value 1 Month Chart as of the 8th of June 2026

However, in the past couple of hours calmer heads have prevailed among financial institutions and USD centric buying in the broad Forex market has run out of steam – at least momentarily. For instance the USD/JPY is near 159.927 currently, opposed to earlier highs seen this morning which challenged the 160.400 vicinity. What does this have to do with the Nasdaq 100 and its current status? 

It appears via futures trading that large players may also have taken a sedative and looked at the index as having been oversold on Friday. The Nasdaq 100 has actually gained early today and signs that a de-escalation of military force between Israel and Iran is being reported. However, that still leaves day traders wondering what will happen as the cash market opens soon and volumes increase.

Let’s Say Quiet Prevails the Remainder of the Day

Not because of a utopian outlook, but a geopolitical perspective, let’s try to image Iran’s stated intentions of no more retaliatory strikes being launched towards Israel as true. The past couple of hours have been more tranquil as a signal in case you are wondering. Then investors and financial institutions will have to digest the Middle East concerns as they have done over the past couple of months in U.S equities, and decide to operate again on the Nasdaq 100 with near and mid-term outlooks.

Friday’s huge selling was blamed by some on the likelihood of a ‘potential’ U.S Federal Reserve interest rate taking place on the 17th of June. This because better than expected jobs numbers showed to some that the U.S economy was running hot once again. 

Additionally expressed fears, which are legitimate, about higher energy costs sparking sticky inflation have been discussed and worried about aloud. Yet, again let’s decide to say even if U.S inflation numbers via the Consumer Price Index come in higher than expected this Wednesday via the coming CPI data, that doesn’t shut the door on the possibility the new Fed Chair Kevin Warsh won’t fight against an interest rate hike during the FOMC meeting next week. In other words it still seems rather unlikely – to me – that the new Federal Reserve Chairman is going to want to initiate higher interest rates the first month on the job. So what if there was another reason for the steep selling on the Nasdaq 100?

Not Paradise but Purgatory

The Nasdaq 100 actually has other questions which have been raised as possible fodder for its large selling this past Friday. Was it spawned because of profit taking by those who took advantage of the index’s fabulous rise knowing that many institutions had been front running the IPO of SpaceX which is scheduled to happen on the 12th of June – this Friday? 

Did large players who rode the wave of frontrunning by financial institutions up in the Nasdaq 100 since late March, decide to cash in profits. There is plenty of nervousness surrounding what will take place with SpaceX in the coming months and long-term via outlooks because of its rather inflated valuation which looks like it will be around 1.7+ Trillion plus at share values of $135.00 per share this coming Friday. 

Questions surrounding SpaceX’s price per sales rhetoric, this instead of price per earnings (because SpaceX is not making a net profit) is just one example. While denying Elon Musk’s genius and ability to create clamor for his companies has proven to be a losing proposition for many, doubters still remain. 

Folks might have cashed out winnings on Friday and decided to now wait on the sidelines to see where behavioral sentiment takes the Nasdaq 100. After two full months of paradise for the Nasdaq 100, a few days of purgatory and seeing which direction U.S indices go may be the right decision by folks who rely on clarity; this as the Middle East gets untangled (or becomes more complicated), the Federal Reserve offers insights on the 17th of June, and large financial institutions lead the way regarding investment decisions.

Copy and paste the text from AMT that you want to share

Perception Over Fact 20260603

Perception Over Fact: Iran as the Savior of Beirut

Trump Policy and The Art of a Middle Eastern Deal: Israel, Iran and Lebanon

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 2nd of June via The Angry Demagogue.

Although it is difficult to see where the negotiations between Iran and the United States are going – if anywhere – over the last 24 hours the United States has made Iran the “savior” of Beirut. Against American policy of creating a civil and unified Lebanon at peace with its neighbors, the Trump Administration has told the Lebanese government and people that Iran still controls what happens in Lebanon.

Perception over Fact: Iran as the Savior of Beirut

Even if this was not the case, in the art of the Middle Eastern deal, perception is more important than fact. Whether the Trump Administration actually twisted Israel’s arm due to Iran’s demands or not, the fact that Israel has agreed not to bomb the Dahiya section of Beirut after announcing that they would gives a message to the Lebanese people and government that Iran still calls the shots in Lebanon and not to rush to support those who wish to disarm or dismantle Hezbollah since you will be on the losing side.

Lebanon has been embroiled in civil wars since its inception. Beirut, the “Paris of the Middle East” has never known quiet times although that did not stop the partying (sort of like Paris itself today) and Iran’s involvement, much like Syria’s and the PLO’s before has not helped. Before the PLO inspired civil war in the mid 1970’s, after King Hussein threw them out of Jordan, the civil wars were about Lebanon itself. The French thought they created a formula for the creation of a semi-western state by dividing up the power centers amongst the religious and ethnic groups – Maronite-Christians got the Presidency, the Sunnis the Prime Minister-ship, the Shiites the speaker of the Parliament. The Druze historically were appointed Chief of the General Staff of the army.

This formula was, as can be imagined, not one for the free exchange of ideas but caused a rush to create power centers and led to conflict, civil and military. But it was all internal. Once the PLO and Yassir Arafat came, Israel became a factor in the civil war since Israel had to cross the border to stop the PLO from its numerous cross border terrorist attacks. After the First Lebanon War and the forced exit of the PLO, Iran created Hezbollah with the sole aim of using it, in the future, to destroy Israel. Therefore, from the late 1970’s until today, the Lebanese state has been embroiled, often against its will, in the Israeli-Palestinian conflict.

The goal of the Trump Administration’s negotiations in Washington between Israel and the Lebanese government is to break Iran’s stranglehold over Lebanese internal and external policy and allow it to either establish diplomatic relations with Israel or at least to put the two countries in the situation they were in before the late 1970’s – and that was a quiet, irrelevant border for both countries.

The real or even perceived notion that Beirut was “saved” from Israeli bombing by Iran’s demands has set back that goal and given Hezbollah and hence Iran, veto power over Lebanese government policy. The correct answer to Iran after their demands were made tying Lebanon to the cease fire was that Lebanon is none of your business and if your proxy decided to join your war then they will have to take responsibility for it. The time for “protecting” Lebanon was when you ordered Hezbollah to come to your aid and attack Israel’s north. The result of that – the administration needs to tell both Iran and the Lebanese government and people, is the loss of Lebanese sovereign territory to Israel and the destruction of Shiite villages in the south of the country. A further price is the destruction of the Beirut neighborhood in which Hezbollah has command and control facilities as well as underground arms depots.

Iran cannot be seen to be the savior of Beirut and Lebanon but the cause of its troubles. No amount of rhetoric to the contrary will prove to the Lebanese government and people what they see on the ground now – only Iran has the power to stop Israel’s bombing of their country. The Administration has set back its goals in Lebanon without aiding its war effort in Iran. The constant Iranian threat to make the war regional is coming true since the Administration is not taking seriously Iranian deal-making methods.

As we wrote two months ago in The Art of the (Middle Eastern) Deal” – “Each ‘concession’ by Iran will have to be paid for twice or three times – once upon agreement and then again before numerous times before implementation”. Iran agreed to open the Straits and then reneged and the US is negotiation for that again – AFTER Iran received the much needed cease fire.

Now, after the administration denied linkage to Lebanon, Iran is again demanding that linkage – not in order to open the Straits, but just to continue negotiations. This pushes both American interests to the back burner – the opening of the Straits of Hormuz and the normalization of Lebanon as a country free from Iranian influence. And the “concession” that Iran is giving for this is just a continuation of the negotiations that have been going on for over two months. In other words, like most negotiations in the middle east that are supposed to lead to “peace” – this too is moving backwards.

President Trump has asked for patience and has insisted that the United States will never accept a bad deal – and I am willing to be patient and believe that. But what if the goal of the Iranian government is not a deal at all but the ability to re-set their genocidal triad or missiles, proxies and nuclear weapons? These negotiations have given them time to dig out their underground missile cities, to keep their enriched uranium hidden and now to revive their flailing major proxy – Hezbollah. In the end, as the President said, it will be good, but by allowing Iran to take the initiative he is making it harder to get to that “good”.

What we have now is a continuation of American-Iranian negotiations where a concession was given to Iran and they are no closer to reaching an agreement. Iran is now perceived as the power to be reckoned with in Lebanon and Israel is put on a level with Hezbollah. Iran and the United States are now equals in this negotiation, something that was not the case when they started. While it might in fact end well, the journey is now a longer and more difficult one. The perception given by the last 24 hours that Iran controls Lebanon, is now the “fact” that the Middle East “knows”.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

Follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

WTI Crude Oil 20260601

Clues and Insults: Forex and Equity Indices During the Iran Saga

Profits: Optimistic Wagers and Preserving Self as the Party Rages

New Federal Reserve Chairman Kevin Warsh certainly doesn’t want to have problems with President Trump. On the 17th of June the FOMC meeting via the Fed will make their interest rate decision known. Who really believes that during the first month on the job at the helm of the U.S central bank that Warsh is not going to fight to keep interest rates in place?

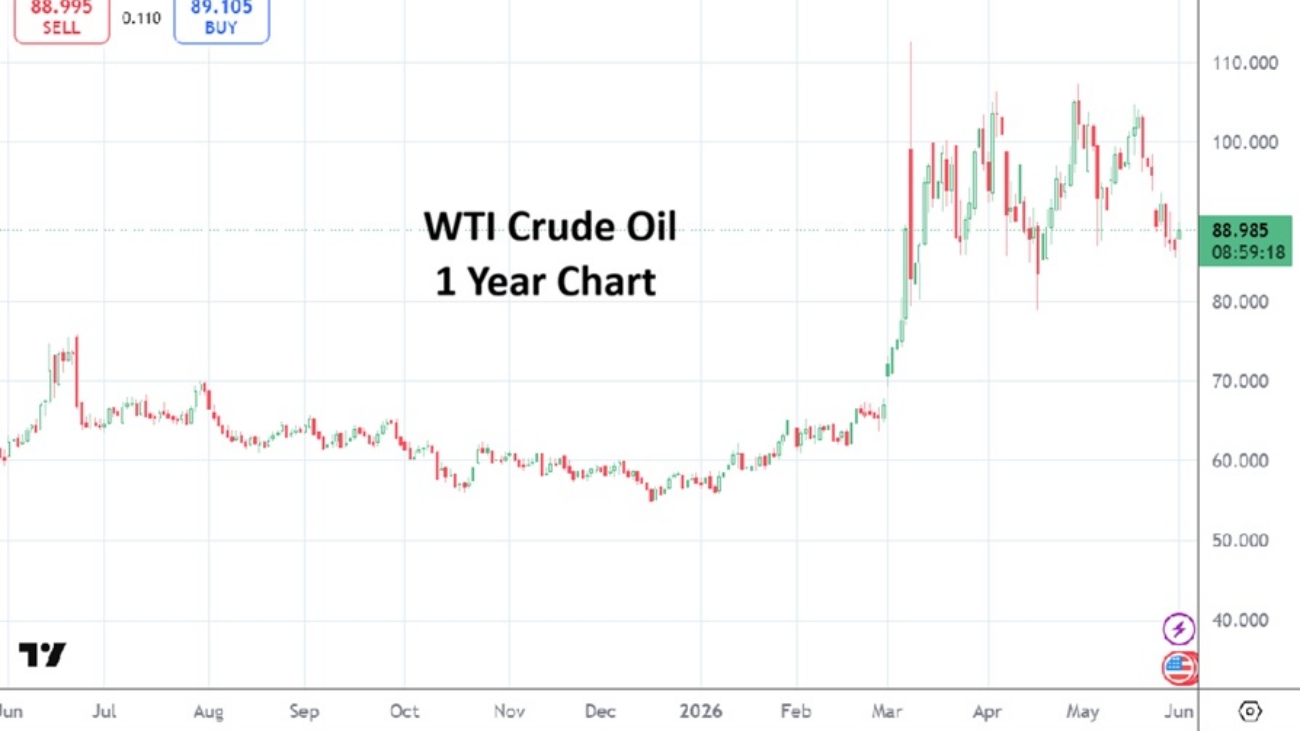
Those who are expecting an interest rate hike in June of a quarter of a point (0.25%) are most likely wrong. Yes, the price of WTI Crude Oil is high and the situation in Iran via narrative varies from one moment to the next per the reported incidents on the Strait of Hormuz.

However, just like the Fed there is a certain amount of reality that must be dealt with regarding human nature and behavioral sentiment regarding Iran and how it is dealt with via market participants. From the department of no news is good news: financial institutions and investors would like the noise to be kept to a minimum so they can continue doing their jobs and not be criticized themselves for potentially wrong outlooks. The art of making sure disclaimers are up to date is important for everyone who wants to stay employed.

WTI Crude Oil 1 Year Chart as of 1st June 2026

USD centric weakness was seen late last week in many currency pairs, but a quick glance at the majors: EUR/USD, GBP/USD and USD/JPY actually show the pairs traversing rather cautious values. The EUR has gained slightly for instance, but at its current levels around 1.16410 some may believe it is a safe equilibrium. (One that may be able to be taken advantage of by those with the ability to bet on mid-term higher trajectories).

Central Banks globally also want to keep the noise down in their various locations. Inflation concerns persists worldwide depending on the amount of knock-on effects that higher energy costs have on national economies.

Also adding additional intrigue to the storyline of wanting to keep quiet while volatility threatens the gates, is that many people with comfortable jobs in various government institutions do not want to step out of line and sacrifice their careers for the sake of being proven right. They would rather be proven wrong, but would like to do this quietly without facing consequences.

The fact that we are now in a situation in which we are afraid to undertake critical thinking aloud is going to cause problems down the road, but for the moment most will simply go on with their various duties and pretend all is well.

U.S equity indices have been having a massive upwards party since the end of March as record heights are attained. Certainly some long-term investors are simply throwing money into indices as a way to get positioned before the SpaceX IPO which is coming soon. There will also be the Anthropic IPO which is reportedly set for late 2026.

The SPCX which seems to be aiming for the 12th of June will create a valuation well above 1 Trillion USD for SpaceX. The perceived value of Anthropic is becoming a loud talking point among analysts in the tech sectors and they are keen to have the company join the 1 Trillion USD party. The cost of admission for bragging rights is getting more expensive.

There was a time when things like PE (price and earnings) ratios mattered on Wall Street. Some brave folks still whisper about such things in meetings and bars late at night, but many do not want to be insulted or possibly worse get marketing folks selling these high priced products angry. The reason for speaking softly about actual earnings regarding SpaceX is because the company is actually working via an earnings loss, and instead price to sales estimates are being offered as some type of guideline. Having said the above, it would be foolhardy to bet against SpaceX and Elon Musk. And it might be equally unwise to bet against Anthropic in a handful of months. And thus, the rush into equity indices because there is a genuine fear of missing out does exist. Afterall, we all want to be part of the party.

And that brings us back to Fed Chairman Kevin Warsh who has the backing of President Trump and Treasury Secretary Scott Bessent, he doesn’t want to insult these men either. Warsh may be quite good at what he does, he might be an expert and have real world business experience, and that might be a real clue for Forex traders who think higher interest rates are coming. Warsh will likely want to keep his first months on the job at the Fed on good terms with the White House and the Treasury. Kevin Warsh might be a free-thinker and know legally he is an independent leader of the Federal Reserve, but he also knows he was hired with a stated mission. There is a pro-business, free enterprise administration in power at the White House. Bessent, Warsh and Trump are on the same team.

So again, while some traders may believe the Fed will raise interest rates in June because of concerns of higher inflation, it most likely will not happen. While the Iranian war continues to make headlines in the financial world and dealt with via sentiment decisions, actual economic U.S data will start being watched in the coming days and weeks and might even influence perspectives. Investors will get bored of the Iranian saga as long as its narrative stays somewhat tepid. Meaning investors will start looking at CPI and PPI numbers coming from the U.S next week and talking about higher interest rates that will likely not be delivered in the upcoming FOMC meeting. 

The price of WTI Crude Oil as boring as it is to say remains a strong sentiment gauge for traders intraday. Large players involved in Forex might believe this will involve higher interest rates, but on the 17th of June it is more likely that Kevin Warsh will say that for the moment the Fed chooses to watch energy sector costs with the belief prices will decline in the coming months. The Fed will not use the term ‘transitory’ which was used infamously during the Covid crisis and turned into a poison pill with inflation that was not effectively fought. What the Fed will likely do is say they want more info to be gathered and more clarity regarding the Iranian situation and its overall effect on oil prices for a little while longer. Some patience will be asked for and it might be granted by investors who want the party to continue via equities.

Day traders should expect cautious markets to prevail in Forex with choppy results as financial institutions weigh their behavioral sentiment and try to make believe they are not too worried about near-term inflation. The CPI and PPI readings next week will prove of interest, but the results may be brushed aside by market pundits.

In the meantime, the celebrations on Wall Street continue as folks march merrily into the frenzy. Retail speculators who want to pursue short or near-term profits on the Nasdaq 100, S&P 500 or Dow 30 indices need to be careful and might want to stay away from daily bets and instead engage in conservative positions that allow for a full week of results. The gains made since the end of March have been outlandish and likely will not be repeated anytime soon, but why try standing in front of a trend that can crush you.

Near-term considerations in these markets should be done carefully. The mid-term may be very different from where we stand today and our current outlooks. One thing that may bother some risk analysts is that it may prove wrong to bet against the current parade of optimists who insists on participating in dangerous conditions and profit, while they (the risks mavens) stand in place.

Copy and paste the text from AMT that you want to share

Fear of Russia 20260529

Fear of Russia in Europe

Time for the Baltic+ Alliance

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 28th of May via The Angry Demagogue.

The Wall Street Journal had a thoughtful piece the other day (Europe is Starting to Think Putin will Expand the War Beyond Ukraine) on Europe fearing that Russia will look to expand their war beyond Ukraine. This has been a fear since Russia’s ill-fated invasion four years ago and is the reason why Europe is supporting Ukraine (not due to any love or respect for the people of Ukraine).

The gist of the article though is America’s possible unwillingness to come to the rescue of Europe and honor their NATO commitments. These fears are not unfounded, but sitting and worrying about American will or overextension will not deter Putin from yet another attempt to divert attention to the deteriorating nature of his country’s military, economy and general health.

Rather than whine and wonder, those front line countries that will be most affected by Russian adventures need to form a new or sub-alignment and make moves that Russia can judge only as threatening to any new venture. Rather than not provoke, this new alliance needs to show Russia that they have the power and more importantly the will to defend the Baltic States and others that border Russia and are most at risk.

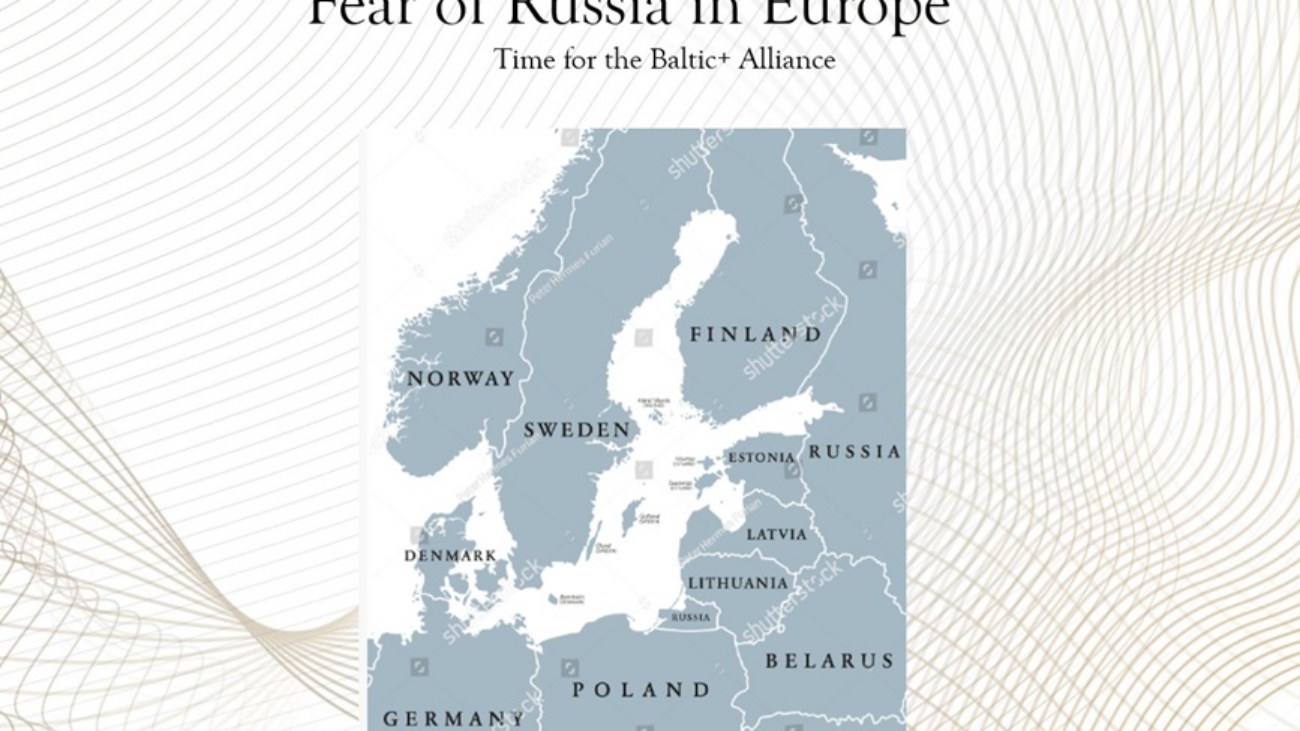
As we have written in the past (National Security Strategy, part 2: Regional Alliances-Europe), only countries with “skin in the game” have the will and the opportunity to successfully fight any Russian invasion. This Baltic+ alliance of Poland, Germany, Sweden, Finland, Norway, Denmark, Latvia, Lithuania and Estonia have a joint population of nearly 160 million people to Russia’s 145 million. Further, these countries have nearly 500 advanced jet fighters and a navy that can control the Baltic Sea. They have around 1,500 battle tanks combined and over 300,000 infantry soldiers.

Neither the United States, nor for that matter the UK, France, Italy or Spain (not to speak of the weak Benelux countries) have the will to defend the Baltic countries but, as they usually do, will offer diplomatic and other “help” in case of crisis. These 9 Baltic+ countries alone have the wherewithal and power to defeat Russia in case of attack. Joint air and naval maneuvers in and near the Baltic countries, naval buildups in the Baltic and the movement of tanks and infantry closer to the border including a “tripwire” in the Baltic countries themselves should be enough to deter and if necessary, defeat Russia in a new Putin venture.

However, this needs to be made operational and not just discussed. They cannot show the cowardice they usually show when facing military challenges like they have done in the Persian Gulf. Diplomatic solutions can work when backed up by superior military force and a clear will to use that force.

While the U.S sending 9,000 troops to Poland is a good thing, Sweden’s increasing its naval and air presence close to the Baltic States, combined with Polish and German tanks and infantry in those states and Finland moving troops close to its border with Russia will be taken by Russia with a sense of seriousness. There should be no fear of “provoking” Russia since Russia responds to perceived weakness and not strength. Russia would love to depend on America’s “overextension” and lack of will but this strong new alliance will compensate for any American hesitation. More than that, it will be taken more seriously than a few American brigades on Polish soil.

The creation of alliances does not need years of study and position papers, but bold moves by leaders that are sworn to protect their countries. If Europe seriously fears a Russian expansion of their war beyond Ukraine, then leadership of a kind Europe has been missing since Adenauer, De Gaulle and Thatcher left the scene, needs to come to the fore. Only then will it make sense for America to use its formidable power.

America does have a deep national interest in containing Russia and protecting Central Europe but, like when it faced its Iranian enemy it needs allies that are willing and able to take a central role in combat and not only half hearted support at the UN.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

You can follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/ 

Copy and paste the text from AMT that you want to share

US Dollar Index 20260627

The USD and The Art of Not Knowing

Being Mature Enough to Know You Don't Know as You Watch the Marketplace

Ask anyone that typically knows how they gauge the state of the global marketplace for the near-term and you are likely to either get a solid, “I have no idea” now. Or a bunch of thoughts on what might happen, which might lead to being more confused. Simply put at this point, it is easier to admit that potential conclusions regarding the world’s current affairs taking place and effecting the global marketplace are out of most peoples’ hands. 

Even those who have duties within the higher paid grades likely are just as confused about the potential unintended consequences not wanted, and results they hope will be achieved. And what am I speaking about exactly, regarding the world and its state of affairs, is that even qualifying the particular topics are difficult to put a finger on. Ramblings certainly include the Iran saga, but Cuba, the Ukraine, the NATO pact, shifting world alliances and future ones are creating a whirlwind. Besides the rather noisy political landscape of the USA. Not to mention China and Russia and other nations with aspirations.

Yet, the global markets continue to trade, albeit within a confused haze it sometimes appears. But do not be despondent day traders, brokers and their platforms will offer you the opportunity to wager on results of the USD in Forex, and CFDs certainly contain opportunities in major equity indices the world over, various big singular companies, commodities and yes cryptocurrencies (apologies to Bitcoin fans – who insist it is called a digital currency).

U.S Dollar Index Six Month Chart as of 27th May 2026

Iran War and Unclear Results

The U.S Dollar Index for the moment is near the 98.880 ratio, which it should be pointed out is near the values it swam upon the April 8th announcement of a ceasefire between Iran and the States, this after dropping from its 99.800 threshold on the 7th when investors were more troubled. The ceasefire is still in effect and now there seems to be a resolution which is being hoped for by the U.S White House – although when pressed about what negotiations between Iran and the U.S will result in delivers a few different versions of ideas. 

Perhaps that is to be expected via the fog of war, but what should not be expected is an easy path to a genuine resolution. And even if there is a pact of some type, what objectives will have been genuinely fulfilled? But alas, that is a question for those in the future, because the facts on the ground do not bode well for ordinary Iranians who have yearned for freedom. 

The Fed Has a Problem

But again, let’s not dwell on things like the individual rights of people, money is at stake…..(that is humor folks, others can call it sarcasm). The price of WTI Crude Oil has dropped this week on the idea that a resolution will actually be accomplished between Iran and the U.S – one at least that allows tankers to navigate the Hormuz Strait. 

The price of WTI via futures at this moment are around the $90.00 mark again, this after moving within sight of 88.00 USD earlier today. At the end of last week the $96.00 mark was in sight for WTI. And the price of energy continues to cast a shadow that is moving over the U.S Federal Reserve and has large implications for the new Fed Chairman Kevin Warsh. 

The mid-term versus the long-term in financial institutions as they judge their interest rate perspectives are likely making for rather entertaining dialogue. And let’s not forget ladies and gentlemen, the U.S mid-term elections are approaching in November of this year and are resulting in primary elections that are punishing Republicans who voiced criticism towards President Trump. The question about who will hold power in the U.S House of Representatives is a big riddle. Even the U.S Senate leadership may be fragile. Why is that important, because if President Trump were to become what is known as a lame-duck President during his last two years in office, this would produce different outlooks among investors. Stay focused on the money people. 

Our Forex Friend: The BoJ

The USD/JPY is now traversing its 159.490 vicinity again, and perhaps that is a bell weather for soothsayers to criticize again. The Bank of Japan is watching the Japanese Yen as its trades within sight of its weakest values, and yes, the BoJ can be expected to issue another warning to speculators once again about being run over by an intervention. The BoJ’s broken record about interventions have produced solid results for folks who are able to trade the USD/JPY with positions that can be held for a few weeks at a time – namely hedge funds, large players and some financial institutions. Retail traders trying to take advantage of the USD/JPY are likely suffering trauma via anxiety if their wagers have gone in the wrong direction.

SpaceX and Scams in the Cryptoworld

And as a bonus, let’s not forget about rumblings regarding SpaceX and another topic within the I do not know category. Elon Musk has set the table for an attempt at a 2 trillion USD market cap after the IPO for the corporation is launched in the second week of June. The value of SpaceX can be and will be argued for the next few years as admirers and critics lineup to be heard and spread sheets are compared regarding revenues against one of the greatest marketing giants of our time. Intriguingly, however, are hints that there has been a lot of cryptocurrency fiddling regarding how the corporation is going to allow investors to participate. Apparently there have been tokens issued in the cryptocurrency world that have promised some type of participation in SpaceX and most are being exposed as scams and have nothing to do with the company or Musk. Buyer beware folks.

Copy and paste the text from AMT that you want to share