postN87

AMT Top Ten Miscellaneous Views for the 15th of December

AMT Top Ten Miscellaneous Views for the 15th of December

10. Book: Doctor Zhivago by Boris Pasternak.

9. Music: Moanin’ – Charles Mingus Big Band 93 Nostalgia in Times Square. Fantastic jazz.

8. Cryptocurrencies: Game of double dare continues as BTC/USD trades near 42,600.00. ETH/USD resides around 2,250.00. USDT remains at 1.00 and BNB/USD (yes, from the much criticized Binance operation) hovers near 250.00. Be careful out there, folks.

7. Argentina: Newly elected President Javier Milei has begun to enact economic reforms as the nation’s citizens and businesses hunger for better days. Will the Argentine Peso begin to stabilize?

6. South Africa: As the nation celebrates a public holiday for its Rugby World Cup victory today, it should be asked if the people are ready to vote for a political change in 2024? Or have things not gotten bad enough yet?

5. Central Banks: Federal Reserve ‘officially’ turned to a neutral/ almost soft monetary policy stance on Wednesday, the BoE and ECB followed Fed’s dance steps yesterday. GBP and EUR have gained and look intent to flirt with July 2023 values.

4. U.S Treasuries: Yields continue to erode and are near values seen half a year ago, with further decreases seemingly ready to occur mid-term.

3. Commodities: Gold is producing near-term speculative upwards muscle. Copper traders appear to be eyeing higher values.

2. JPY: Price velocity has propelled the USD/JPY to fresh lows, this as the currency pair gains speculative interest and behavioral sentiment shifts.

1. All Time Value: Dow Jones Industrials has achieved record heights. Nasdaq Composite and S&P 500 indices at one year highs as investors show risk appetite.

postN51

AMT Top Ten Miscellaneous Nibbles for the 1st of December

AMT Top Ten Miscellaneous Nibbles for the 1st of December

10. Book: Kissinger: 1923 – 1968: The Idealist by Neill Ferguson

9. Music: Clifford Brown and Max Roach Quintet playing Joy Spring.

8. Bitcoin: Curious stubborn trend higher as ETF fever appears to be creating bets on perceived ‘forced’ upwards momentum. BTC/USD now above 38,000.00.

7. Charlie Munger: Passed away earlier this week. Extremely well regarded as a man and helped create the Berskshire Hathaway colossus.

6. Crude Oil: Cash price of WTI Crude Oil remains stable and hovering above mid-term support after OPEC and associates announced voluntary production reductions yesterday.

5. Data: While U.S GDP numbers came in with solid growth statistics on Wednesday, yesterday’s U.S Core Personal Consumption Expenditures results came in below last month’s data showing inflation is eroding.

4. Gold: The precious metal remains above 2000.00 USD in a rather strong fashion, short-term speculation has been vigorous. Caution is advised for day traders.

3. Jerome Powell: The Federal Reserve Chairman will be speaking in Atlanta later today and his comments while participating in a ’roundtable’ discussion could affect behavioral sentiment going into the weekend.

2. USD: Outlooks via tier 1 financial institutions and larger players keeping the ‘greenback’ weaker and near mid-term support against other major currencies, price velocity should be watched.

1. U.S Indices: Dow Jones Industrials touching highs not seen since January 2022. S&P 500 and Nasdaq Composite within sight of July 2023 apex levels, and if penetrated upwards would also bring these indices to heights of late 2021 and early 2022, this as risk appetite demonstrates backbone.

You can find more AMT Top Ten Miscellaneous lists in the AngryMetaTraders archive

postN51

AMT Top Ten Miscellaneous Feast for the 24th of November

AMT Top Ten Miscellaneous Feast for the 24th of November

10. Book: A Thanksgiving Diet – Life as a Glutton by T.M.F Resuscitate.

9. Music: Frank Sinatra singing Somethin’ Stupid.

8. Global Commerce: London Metal Exchange and Baltic Exchange Dry Index prices are higher since September lows.

7. Post Holiday Warning: Trading volumes will be light today, day traders should expect quiet markets and sudden bursts of volatility. Early reactions next week may result in reversals due to perceived lack of price equilibriums having occured via today’s results, this as U.S financial institutions return in full to their offices Monday and Tuesday.

6. Election Surprises: Argentina and the Netherlands point to seismic changes in voting sentiment. India, South Africa and the U.S have major elections coming in 2024.

5. Crytocurrencies: Binance legal problems in the U.S casting shadows of doubt, but BNB/USD has been somewhat stable. Bitcoin – yes, a digital asset – is above 37,000.00 USD as of this writing.

4. Gold: Price of the precious metal remains slightly below 2000.00 USD level.

3. Energy Prices: WTI Crude Oil, Brent, Natural Gas and Gasoline remain within sight of one year lows, but intriguing support levels for speculators with long-term outlooks.

2. U.S Equity Indices: Stocks will trade in shortened sessions today. The major indices are within sight of one year highs. Next week could see positive momentum sustained.

1. Forex: USD within an intriguing near-term price range. GBP, JPY and NZD are some of the major currencies showing signs of potential strength versus the ‘greenback’ as outlooks seemingly shift.

postN51

AMT Top Ten Miscellaneous Thoughts for the 10th of November

AMT Top Ten Miscellaneous Thoughts for the 10th of November

AMT Top Ten Thoughts for 10th of November 2023

10. Book: Art Lover: A Biography of Peggy Guggenheim by Anton Gill.

9. Music: Igor Stravinsky’s The Firebird.

8. Word of Day: Parabolic which highlights Bitcoin’s movement the past month, and may be followed by the word reversal.

7. Centrism: A political wish for our times.

6. Equivocate: Central Banks led by the U.S Federal Reserve continue to protect one another by talking out of both sides of their mouths.

5. Gold: 1950.00 USD per ounce looks to be important support for the precious metal via a three month chart. Will 1950.00 USD remain durable?

4. USD: Stubborn choppy Forex conditions continue to flourish and may remain prevalent in the near-term.

3. Consumer Sentiment: U.S consumers are staying away from home purchases because of high interest rates, today’s data from the University of Michigan will shed light on what they are buying instead.

2. U.S Treasuries: Higher yields are trouble for the Federal Reserve, and should scare U.S citizens who may be penalized with higher taxes to pay off U.S mounting debts.

1: USD/JPY: Japanese Yen trading near values last sustained in 1990 for a significant amount of time.

postN51

AMT Top Ten Miscellaneous Shots for Friday the 3rd of Nov.

AMT Top Ten Miscellaneous Shots for Friday the 3rd of Nov.

10. NBA: Welcome to Victor Wembanyama’s world. VW’s 5th game as a Spur was historic last night.

9. South Africa: The Springboks Rugby World Cup victory is helping unifying the nation and giving all its citizens a hope for better days.

8. Book: The Gulag Archipelago by Aleksandr I. Solzhenitsyn.

7. Crypto: Sam Bankman-Fried found guilty on all counts. Yet, Bitcoin is near 34,600.00 USD per coin.

6. Risks: Signs of appetite as U.S equity indices have moved higher, and U.S Treasury yields have declined.

5. Gold: The precious metal still lingering near 2000.00 USD and may attract bearish speculative positions.

4. Middle East: Global financial institutions appear to have dealt with the noise.

3. U.S Jobs Reports: Non-Farm Employment Change numbers and Average Hourly Earnings inflation data will be published today and shake markets.

2. Federal Reserve: The U.S central bank may have reached the end of it interest rates hikes cycle.

1. USD: The world’s reserve currency remains suspiciously strong and if it is a relatively calm today and this weekend, day traders may begin to embrace selling wagers.

postN62.1

Inflation Data and Fed’s FOMC Meeting Minutes This Week

Inflation Data and Fed's FOMC Meeting Minutes This Week

Last week’s economic data ended with rather tantalizing headline jobs numbers as the U.S showed more hiring than expected, but while this grabbed media soundbites in many circles – the Average Hourly Earnings numbers came in below expectations. The broad Forex market proved dynamic with a stronger USD in many cases, but intriguingly equity markets in the States generated upwards momentum on Friday too. U.S Treasuries were mixed regarding their yields, and the 10-year bond while finishing up for the week was below its highs.

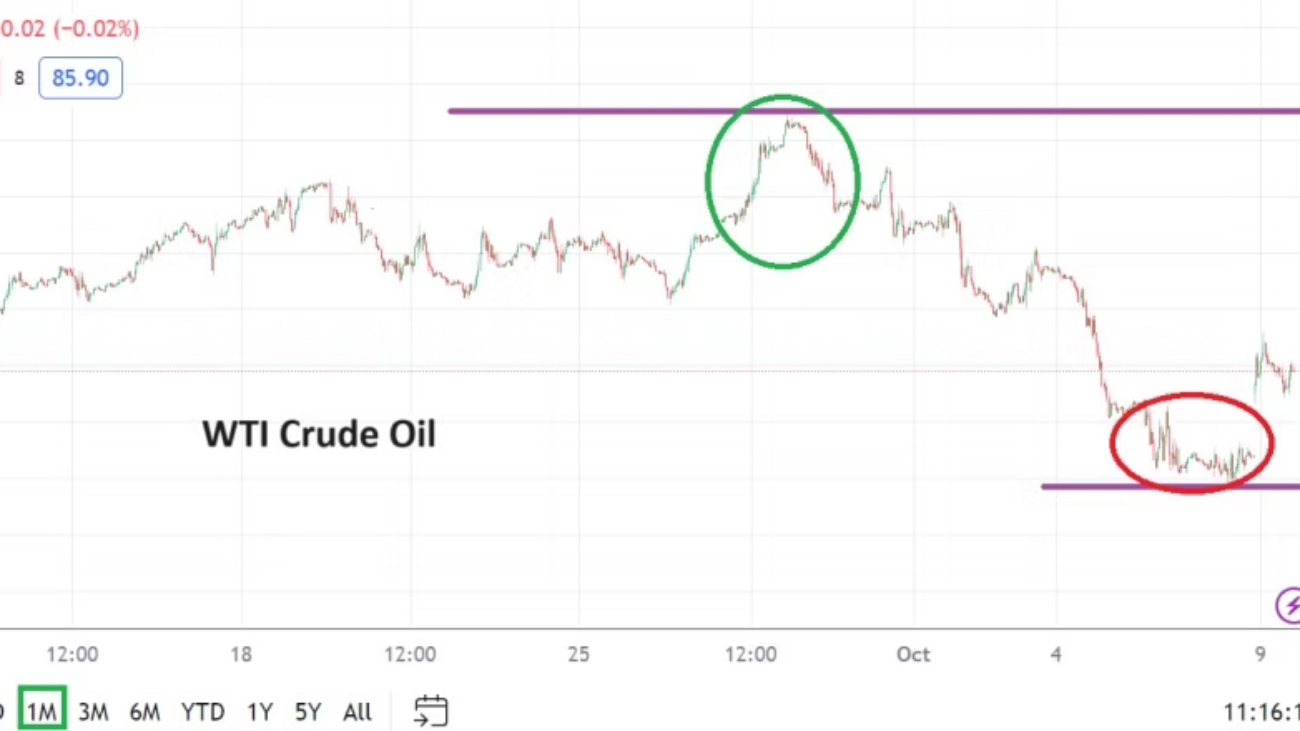
WTI Crude Oil One Month Chart as of 9th of Oct. 2023

The coming week will likely continue to produce nervousness, but outlook will be helped via a couple of U.S inflation reports and the FOMC Meeting Minutes report. Crude Oil prices should be watched as news from the Middle East unfolds. Gold remains under pressure.

Cryptocurrency speculators should keep their eyes on Binance Coin as it battles important lows. Bitcoin has remained relatively stable, but BNB/USD is near crucial support that could signal another wave of pressure is developing within the Binance exchange.

Monday, the 9th of October, International Monetary Fund – week-long meetings get underway and investors who participate in global stock markets and bonds should pay attention to the chatter.

Tuesday, the 10th of October, Central Bank Officials speaking – ECB President Lagarde will be speaking at the IMF conference. Federal Reserve officials will be speaking at meetings in the U.S. While the chatter may cause some nervous reactions briefly in financial institutions, it is unlikely the central bankers will say anything that is surprising.

Wednesday, the 11th of October, U.S Producer Price Index – the broad and core reports should be watched. Last week’s lower Average Hourly Earnings numbers were slightly surprising, but the recent higher energy costs could factor into the PPI results. The broad report is anticipated to show a decline. If the Producer Price Index statistics come in weaker than expected this could help the USD lose some strength.

Wednesday, the 11th of October, U.S FOMC Meeting Minutes – the publication is expected to follow the rhetoric already voiced by the Fed at their last press conference. However, insights regarding dialogue could move the needle in Forex. The U.S central bank is widely expected to raise the Federal Funds Rate in November, but what comes beyond this anticipated move is still in question. Expect the key word in the FOMC report to be ‘inflation’.

Thursday, the 12th of October, U.K Gross Domestic Product – the growth numbers from Great Britain are expected to show a slight rise in GDP. If the gains match expectations or come in better it could help bolster the GBP/USD which has been struggling against the USD for the past three months.

Thursday, the 12th of October, U.S Consumer Price Index – these reports will be crucial and will impact Forex and equities immediately after their release. While the Core CPI number is expected to match last month’s outcome, the broad reports are anticipated to be weaker. If the inflation numbers are stronger than expected the USD could gain strength, if the results are weaker it could help build selling momentum in the USD.

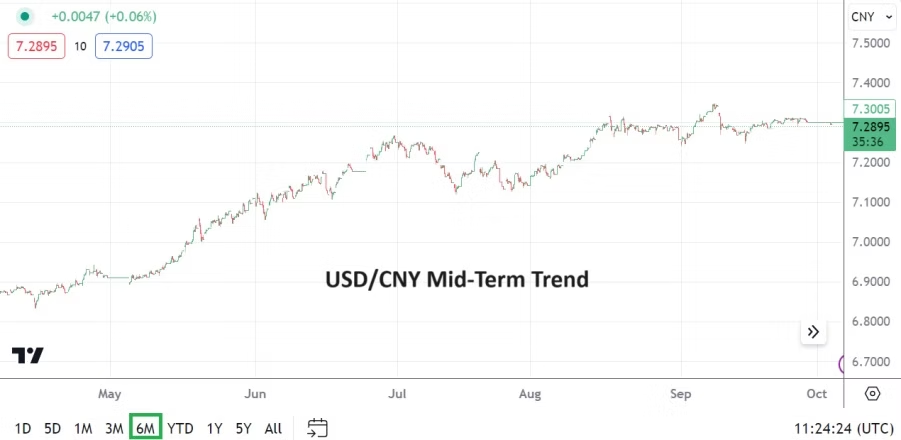
USD/CNY Six Month Chart as of 9th Oct. 2023

Friday, the 13th of October, China Consumer and Producer Price Index – the two releases will be watched carefully by investors. China’s economic data has been weak and financial institutions have become concerned by deflation. The USD/CNY may be impacted upon the publication of the reports.

Friday, the 13th of October, U.S Consumer Sentiment via the University of Michigan – following the CPI numbers from the U.S on Thursday, these numbers will show the attitude of U.S consumers and their spending habits. Financial institutions will monitor these numbers and correlate them to the U.S inflation reports seen earlier.

postN53.1

Anxious Results and Outlooks as Traders Brace for Week Ahead

Anxious Results and Outlooks as Traders Brace for Week Ahead

Speculators with visions of taking advantage of day trading perspectives often look for correlations within asset classes to help gain an outlook on another trading vehicle they may be considering. The problem with this like many things for day traders is that sudden gyrations in asset classes technically are often affected by positioning from large players who do not care what the ‘minnows’ are doing. Institutional trading is frequently done with long-term considerations.

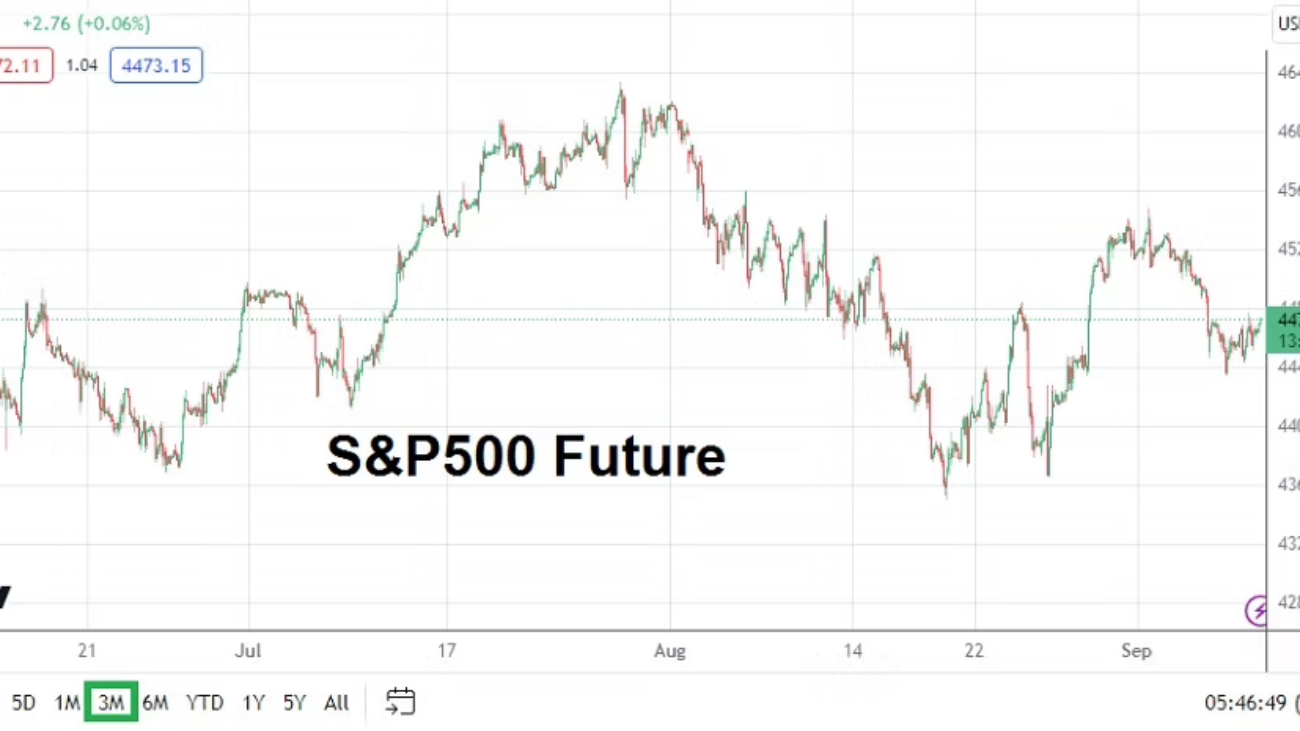
S&P500 Index Future Three Months Chart as of 11th Sept. 2023

The Forex market has seen the USD grow stronger since the middle of July against most major currencies. At the same time charts via U.S Treasuries clearly demonstrate yields increasing. This is not a coincidence. Market behavior remains anxious as financial institutions look to lock in a certain amount of ‘guaranteed’ returns. Recent economic data has been lackluster from the U.S and this week important inflation numbers are certain to influence existing sentiment.

A side note for day traders who like to study economic data, ‘revisions’ via published data is starting to set off concerns among traders. Revisions to previous statistics reported are becoming a talking point among investors who believe the numbers they are looking at from many countries, including the U.S, need to be given a certain degree of skepticism. The Wall Street Journal published an article about this a couple of weeks ago.

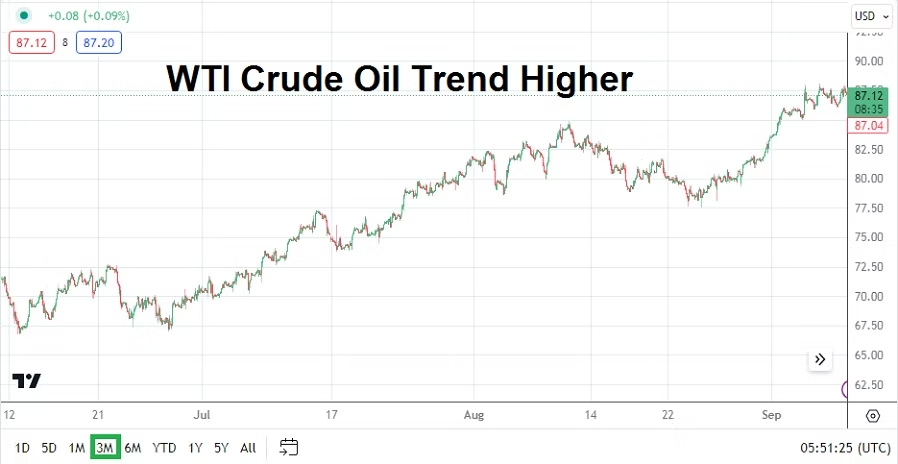
WTI Crude Oil Three Months Chart as 11th Sept. 2023

In the coming days the price of Crude Oil may make headlines as the commodity enters this week near values last seen in November of 2022. The high price of Crude Oil will spark vocal warnings about potential inflation dangers. Speculative elements within the energy sector will be active and hope to take advantage of its trend. A sustained move above 90.00 USD per barrel would be intriguing.

Some analysts might try to correlate higher energy prices to increased demand from global manufacturing sectors, but this could be questionable considering many spheres are suffering from recessionary pressures. But again, the real facts and dynamics behind a potential sustained climb of Crude Oil prices are complex.

Smaller traders need to understand the news they are reading today was known by ‘insiders’ many days before and they have already acted on their knowledge to take advantage of prices.

The cuts in production from Saudi Arabia and other producers has sparked speculative influence, and perhaps the narrative that outlook for more Crude Oil demand could build if the U.S continues to demonstrate a ‘soft landing’. The chatter and explanations for changes to price are almost limitless and day traders need to be aware they will not be privy certain information.

This leaves the door open for day traders to consider trying to understand market behavior within the financial world. The answer for short-term speculators who are wagering on price direction is not a simple interpretation of technical charts, they should also consider fundamental knowledge of the asset mixed with an understanding of current market dynamics as sentiment shifts among institutional players.

In other news to look out for this week, traders who are active in the cryptocurrency space should continue to monitor the support levels that Bitcoin and Binance Coin are traversing. Incremental drops in value continue to be seen and a sustained reversal higher has been difficult to attain.

Monday, 11th of September, China New Loans – the amount of borrowing from businesses and consumers within China will provide insights regarding the strength (or weakness) of the domestic economy.

Tuesday, 12th of September, U.K Claimant Count Change and Average Earnings Index – the jobs numbers from the U.K will provide the GBP/USD with a bit of additional impetus. The U.K economy is in the spotlight and critics have become loud as many point to Brexit problems, which they claim are causing complications. However, within a global economy that is under pressure the fact that conditions in Britain are difficult doesn’t take a lot of time to find other correlations.

Tuesday, 12th of September, Germany Economic Sentiment via ZEW – the reading is expected to show a negative outlook again from the responses of institutional investors based in Germany. A result of minus -15.0 is the forecast. The report could shake the EUR/USD a bit momentarily.

Wednesday, 13th of September, U.K GDP – growth numbers will certainly get plenty of attention for Britain. The anticipated number is minus -0.2%. If the result is worse than the recessionary estimate it could spark more negative sentiment.

Wednesday, 13th of September, U.S Consumer Price Index reports – inflation statistics will be studied carefully and impact Forex immediately if the published results do not meet expectations. The Federal Reserve, institutional investors and the broad financial markets will react to the CPI data.

Thursday, E.U European Central Bank Main Refinancing Rate – the ECB is not expected to make any changes to borrowing rates. The European Central Bank is also anticipated to warn that economic conditions remain challenging and they are monitoring inflation and growth. Anything more than these words via the ECB Monetary Policy Statement and Press Conference could spark some EUR/USD price action.

Thursday, 14th of September, U.S Producer Price Index – like Wednesday’s inflation numbers, the PPI statistics will affect market sentiment regarding outlook and interpretations regarding the potential responses from the Federal Reserve.

Thursday, 14th of September, U.S Retail Sales – this data will give traders insights regarding the spending habits of U.S consumers, which is a key barometer for equity traders regarding consumer driven stocks, and also because an increase would underscore solid economic sentiment from the public.

Friday, 15th of September, China Industrial Production and Retail Sales – these two reports will provide additional insights about the Asian giant. Global investors continue to be concerned about the direction of the Chinese economy. Slight gains are forecast for both publications.

Friday, 15th of September, U.S University of Michigan Consumer Sentiment – the preliminary report is expected to have a reading of 69.2 which would be below the previous reading.

post203

AMT Top Ten Miscellaneous Considerations for this Friday

AMT Top Ten Miscellaneous Considerations for this Friday

AMT Top Ten Miscellaneous Considerations 1st September 2023

10. Travel Alert: Surprise visit to Jeddah, Saudi Arabia for Israeli bound passenger jet.

9. Book: Machiavelli A Biography by Miles J. Unger.

8. Coup d’Etat: Gabon added to the growing African list.

7. Bitcoin: Rollercoaster prices in BTC/USD past 48 hours. Up 2,000.00, down 2,000.00.

6. China: Weakness in Yuan is concerning governments and financial institutions.

5. Market Shifts: U.S Treasury yields have decreased the past week.

4. USD and Gold: Greenback stubborn with slight weakness emerging, Gold steady.

3. U.S Data: Jobs numbers may rattle markets today and expose underlying outlooks.

2. Labor Day: Volumes could be light today with long U.S holiday weekend coming.

1. Trading Tip: Cautious trading likely today, expect volatility to increase next week.

post204

AMT Top Ten Miscellaneous Considerations for this Friday

AMT Top Ten Miscellaneous Considerations for this Friday

AMT Top Ten Miscellaneous Considerations 25th August 2023

10. Behavioral Sentiment: Risk adverse conditions heightened again.

9. Book: Pioneering Portfolio Management by David F. Swenson.

8. Rugby: All Blacks vs. Springboks tonight at Twickenham.

7. Federal Reserve: Jackson Hole Symposium and Speeches.

6. Travel Tips: Stay away from Russian corporate jets with Wagner members flying aboard.

5. South Africa: What’s next after BRICS Summit, an end to loadshedding?

4. Cryptocurrencies: Bitcoin, Binance coin remain under pressure.

3. Germany data: Coming ifo Business Climate and GDP data.

2. U.S data: Yesterday’s mixed Durable Goods numbers.

1. USD: Another burst of strength yesterday.

postN44.1

Dog Days of Summer and a Return of Calm as Storms Threaten

Dog Days of Summer and a Return of Calm as Storms Threaten

With essentially two full weeks of trading until the end of August and the unofficial end of summer in sight, perhaps this week may be a good time for retail traders to be observers if they do not have the stomach for potentially noisy speeches and markets.

However, speculators who can block out media hyperbole and microphone soundbites from folks standing on podiums may find conditions rather attractive. As always outlook depends on perspective, time frames and managing risk. Behavioral sentiment has been rather chaotic the past month and some traders may suspect we are approaching the end of the loud spectacles of nervous drama in the markets.

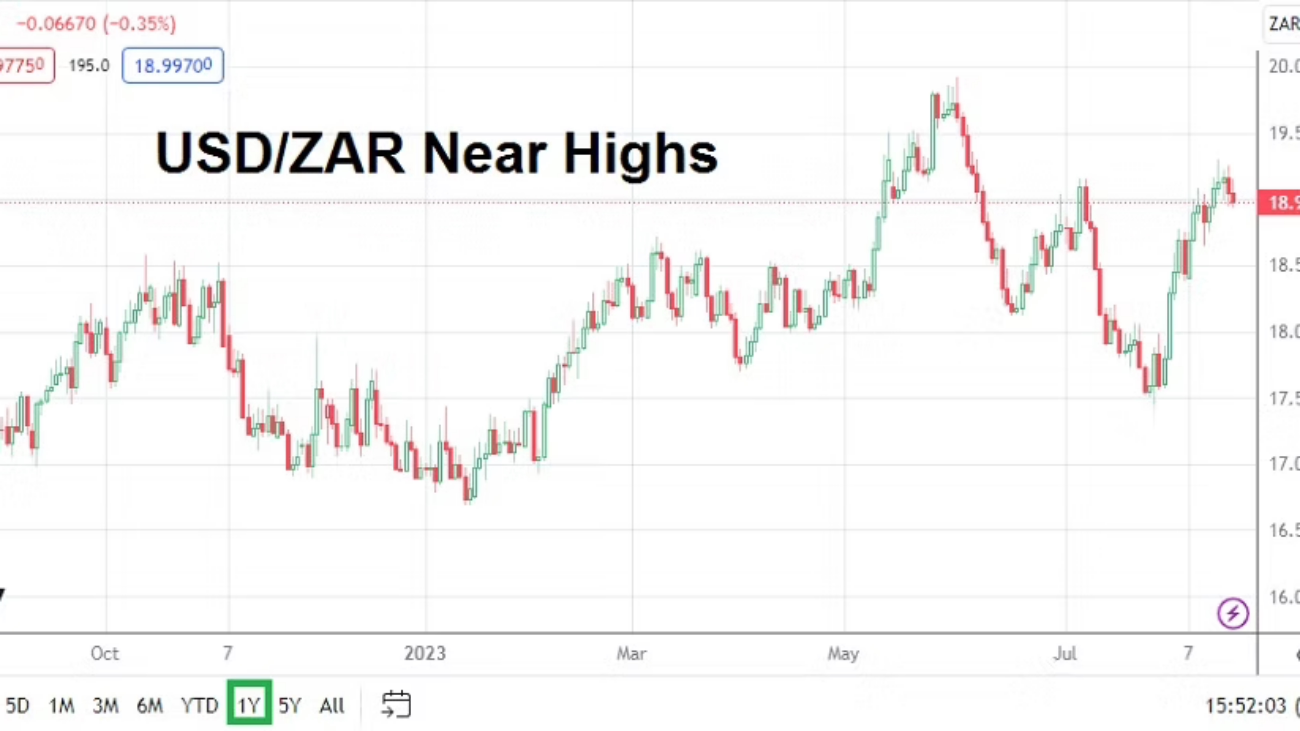
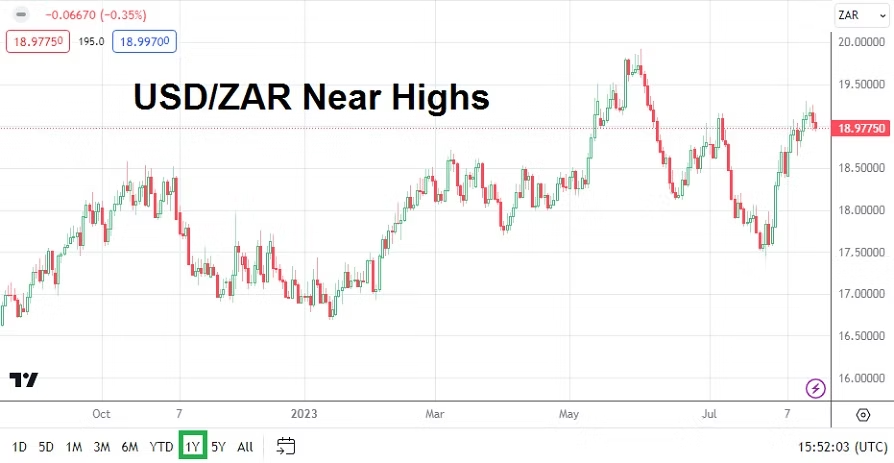
USD/ZAR One Year Chart as of 20th August 2023

The economic data this coming week should prove to be a rather mild schedule, but outside influences will certainly get publicity and get fanfare from talking heads who want 15 minutes of your attention. The BRICS Summit will get underway in Johannesburg, South Africa officially on the 22nd. Another big conference later this week will be the U.S Federal Reserve’s Jackson Hole Symposium. Both events will produce plenty of conversations about inflation, economic stability and a more cohesive global cooperation monetarily. This will also create many raised eyebrows among traders who are skeptical about these type of events.

While leaders of China, Russia, India, Brasil and South Africa get together in Johannesburg, it is likely we will hear talk about potential BRICS expansion and the pursuit of a new unified currency which doesn’t rely upon the USD. However, in the background there is likely to be plenty of distraction because of China’s faltering economic data and Russia’s Ruble which has been impacted severely in the past month. Plenty of large rugs will be needed to hide the dust which threatens to make this BRICS event rather memorable.

Add the ongoing saga of Niger and the absence of a political solution for the world’s fourth largest producer of uranium as a potential flash point standing on the side of the stage waiting to make an appearance regarding Africa news. Perhaps it is too cynical to wonder if coordinated military action within Niger will await the end of the BRICS Summit. This so China and Russia are not given an opportunity on the ‘world stage’ as a united voice to offer their opinions regarding an intervention.

The Jackson Hole get together of global central bankers from the Fed, BoE, ECB, BoJ and others will certainly grab headlines late this week, but the script is mostly known regarding the rhetoric to come from the Federal Reserve’s annual event. Forex may move based on comments from the central bank chiefs as they speak towards the end of this week, but it is unlikely anything surprising is going to be heard. U.S Treasuries will remain a topic because of the ability to lock in a solid return over the mid-term compared to betting on the outcomes of the stock market, but this scenario has been playing out the past month. Investors should prepare for a long line of speeches regarding economic outlooks from central bank officials all week. Day traders should also remember that the chatter starts to be ‘tuned out’ as the speeches grow longer.

Traders looking for other outside influences may want to look at the cryptocurrency market where major assets have shown signs of struggling. Bitcoin and Binance coin could remain in the headlines for all the wrong reasons, if their prices continue to challenge important support levels and become more vulnerable.

Monday, 21st August, China Prime Rates – economic data from the nation has caused concerns that real estate problems are spilling over into the domestic consumer market. The interest rates China lends money to consumers is expected to be lowered to try and spark spending. Recent economic reports from China have been bad, and readers who believe this is merely ‘Western’ bias being reported should be careful to look for other sources to confirm data. Investment within the second biggest economy of the world has become tentative, because there is a fear the ‘official’ China numbers may be worse than those being reported.

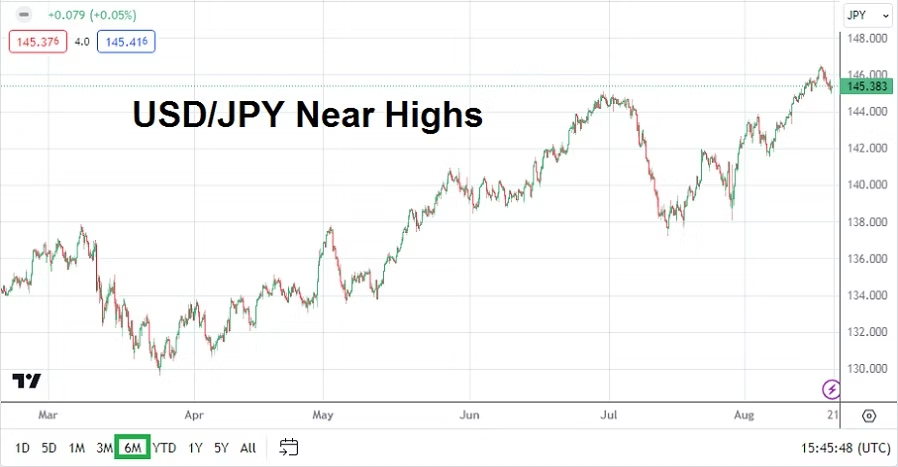
USD/JPY Six Months Chart as of 20th August 2023

Tuesday, 22nd August, Japan Consumer Price Index – the Bank of Japan report is expected to show a slight decline to the inflation numbers. Last month’s outcome of 3.0% is expected to lower and produce a 2.9% result. The USD/JPY could react momentarily to the outcome, the currency pair is near highs it hasn’t touched since November 2022.

Tuesday, 22nd August, U.S Existing Home Sales – the data is expected to show a slight decline of purchases. Mortgage prices continue to climb in the U.S and homeowners are less likely to desire taking on a new higher mortgage, this if they already have a lower mortgage locked in from a few years ago within a dwelling they already live.

Wednesday, 23rd August, Flash European Manufacturing and Services PMI – the reports will come from the E.U and U.K. The German and British outcomes will stir the Forex markets. The manufacturing data from Germany and Britain are forecast to be slightly negative.

Wednesday, 23rd of August, U.S Flash Manufacturing and Services PMI – the U.S reports are expected to show a decline in the manufacturing sector. If a negative result materializes, this could actually spark a selloff of the USD – if the financial markets have returned to calm waters by the middle of this week. Weaker numbers might be interpreted as another reason for the U.S Federal Reserve to remain neutral and why they should consider becoming dovish over the mid-term.

Thursday, 24th of August, U.S Durable Goods Orders – the core and broad numbers are anticipated to show declines. If the Durable Goods Orders numbers are worse than expected this could spark more USD selling, particularly if financial institutions are already calm and feel the data is another step to ‘lowering’ the Fed’s hawkish interest rate rhetoric. However, for the USD to weaken the markets will likely have needed to be tranquil beforehand, without major surprises having happened earlier in the week that may have escalated nervous behavioral sentiment in the broad markets.

Friday, 25th of August, Germany Business Climate and GDP – the ifo Business Climate report comes from a composite of manufacturers, wholesalers, and other enterprises and is expected to be lower than last month’s outcome. The Gross Domestic Product results are anticipated to show no changes, which would mean Germany’s economy remains in the doldrums and is flirting with recessionary pressures.

Friday, 25th of August, U.S University of Michigan Consumer Sentiment – this revised reading is expected to show U.S consumers remain steady without significant changes compared to the previous outcome.

postN43

Alert: Important Support in View for Binance Coin Traders

Alert: Important Support in View for Binance Coin Traders

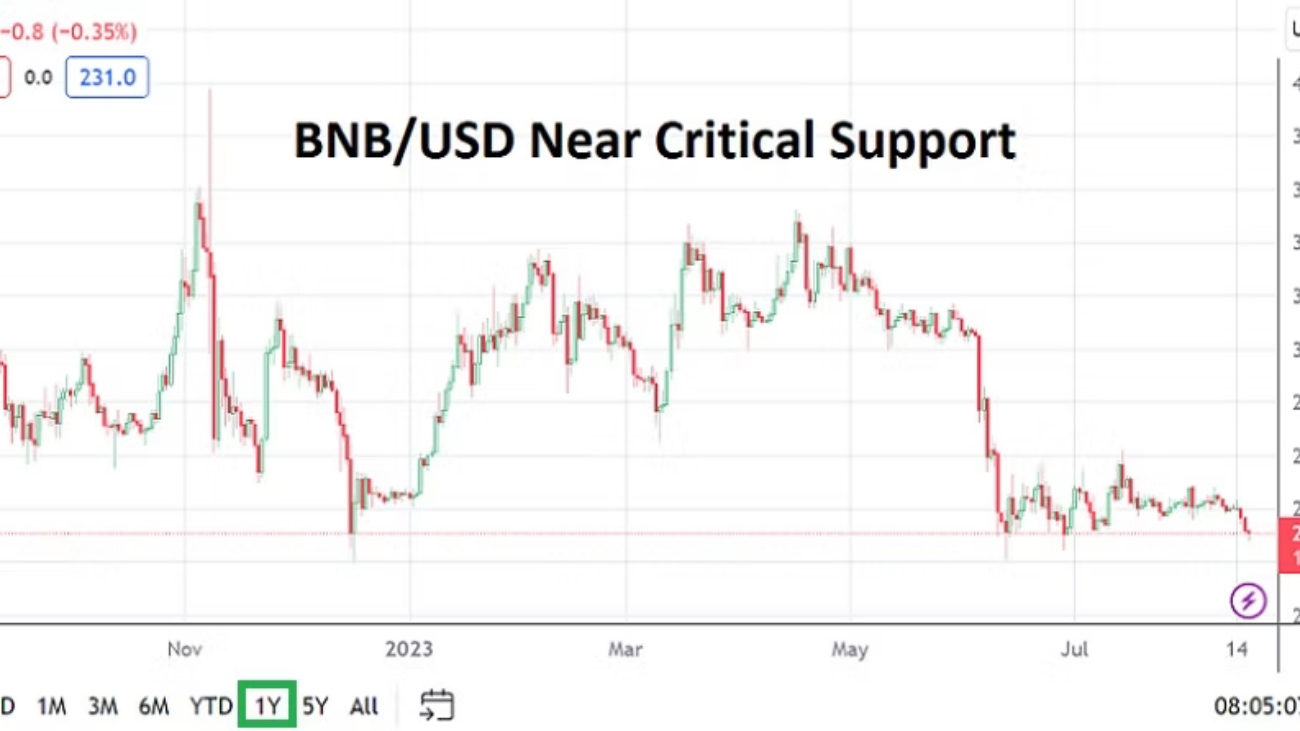
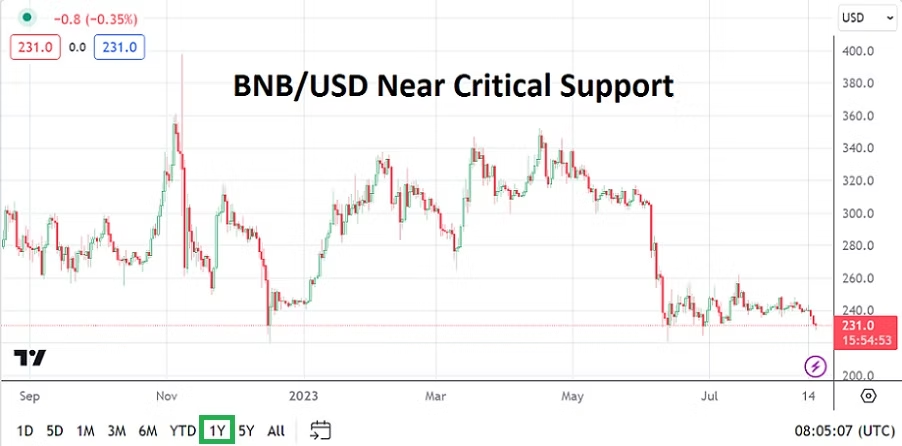
BNB/USD One Year Chart as of 17th August 2023

Important support for BNB/USD is now being battled. The price of Binance coin is near a key inflection value of 230.00 USD. The digital asset world including Bitcoin and other cryptocurrencies has taken on stronger selling recently. Legal issues surrounding Binance have not gone away, nor will they. If Binance starts to show stronger price velocity lower it could spook the broad cryptocurrency market in a large manner. Binance is still the biggest crypto exchange in the world, even as it has come under the investigative pressures of the U.S and some European nations.

Traders should pay attention to ‘stablecoins’ as a barometer of behavioral sentiment in the cryptocurrency landscape. Tether should be watched closely. If USDT sustains value below the 1.00000 USD level for more than a couple of days this would be a negative signal that ‘players’ in the cryptocurrency world are getting more nervous.

Bitcoin is also seeing steady selling early this morning and the price of BTC/USD is near 28,550.00 as of this writing. If BTC/USD were to break below the 28,000.00 this could also add to fear and noise in the cryptocurrency world.

The next seemingly important level for BNB/USD below is around the 225.00 USD mark if tested, if this level proved vulnerable and trading momentum continued downward stronger selling could develop if panic erupts surrounding Binance coin. Traders should be very careful in the cryptocurrency trading environment right now. Legal shadows hovering over Binance have existed for a long-time, and if selling pressure were to mount and values are suddenly tested from June of last year when the 200.00 BNB/USD level was last tested (this as FTX collapsed) this would clearly not be a good signal.

postN27.1

Risk Friday: Fear is a Terrible Thing to Waste

Risk Friday: Fear is a Terrible Thing to Waste

Behavioral sentiment in the broad markets took a turn for the worse yesterday among many major equity indices. This as financial institutions seemingly came to the short-term conclusion the Federal Reserve may actually have to raise interest rates again on the 26th of July, and possibly beyond. Meaning, the Fed might actually back up what it has been saying.

Yes, investors have been warned many times already by some analysts that the handwriting was on the wall regarding additional increases to the Federal Funds Rate, but it seems a fear of losing out has kept many market participants actively running forward with blinders on not cognizant of the Fed’s rhetoric.

Day traders should always be mindful of their emotions. While it is not good to trade based on emotions when involved in an active position, intuition and gut instinct sometimes can save you money when you decide to simply sit on the sidelines and watch the market action instead of participating. In other words, if you are nervous and your instinct is bothering you – do not attempt to enter the trade.

U.S Data Remains Rather Strong even as Inflation Boils

Yesterday’s better than expected jobs report via ADP helped create sparks early regarding U.S economic data continuing to show it is robust, but the ISM Services PMI threw gasoline onto the fire with a much better result of 53.9 compared to the estimated reading of only 51.3. While inflation simmers in the U.S, signs of limited growth abound too making stagflation a real danger.

Investors can now attain a yield around 4.995% on 2-year U.S government Treasuries. A gain of nearly 5% that is almost assured with very little costs regarding commission rates needing to be spent, looks like a solid short-term investment to many. Equity markets have a reason to feel spooked. If the U.S Fed raises the Federal Funds Rate which is now 5.25% to 5.50% at the end of July, and at the same time continues to speak in an aggressive manner about other potential hikes later this year, summer may lose its sense of tranquility for financial institutions.

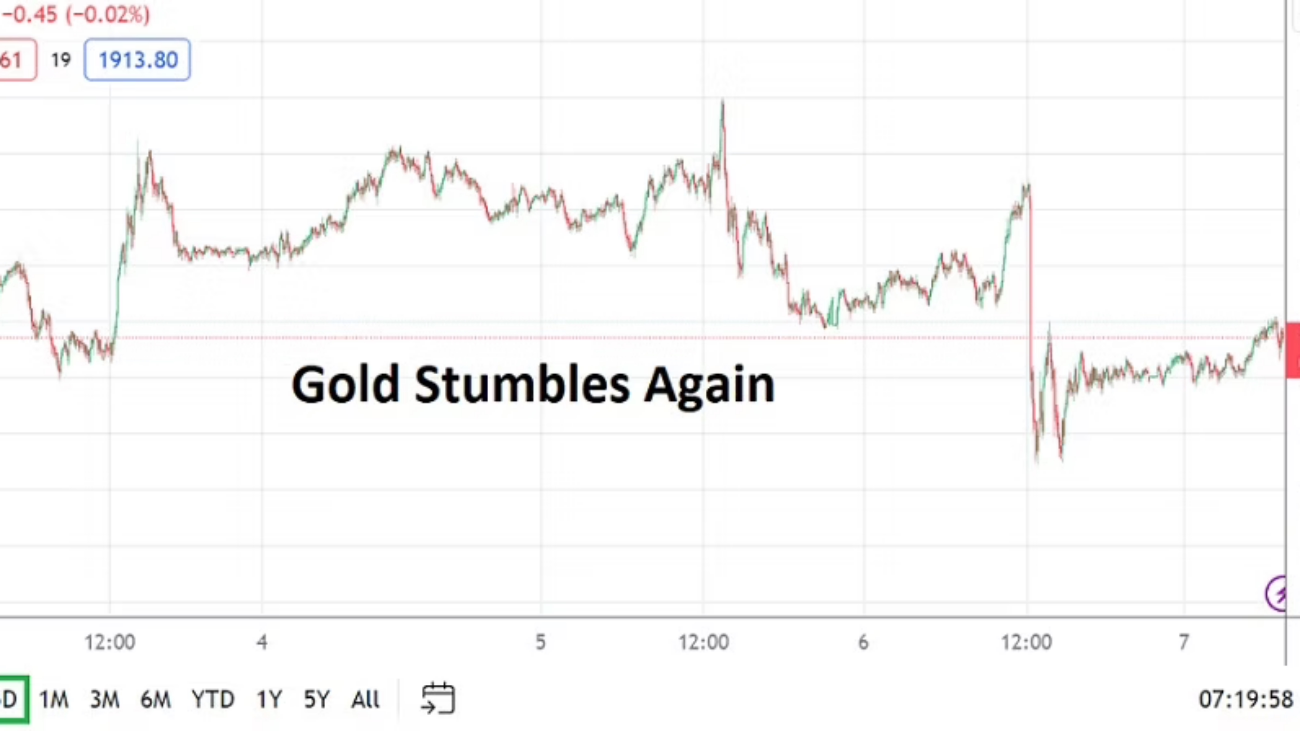
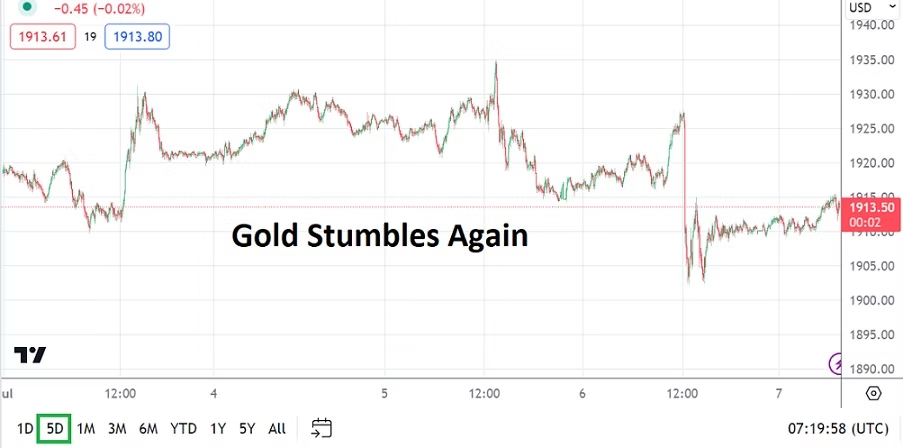
Gold Five Day Chart as of 7th July 2023

Gold which was trading at nearly 1925.00 USD yesterday, suddenly fell to around the 1900.00 briefly in the wake of the better U.S economic data, showing investors are worried the USD has some additional strength to display potentially. Again, the results of intraday gyrations may not mean a lot to mid and long-term investors, but day traders speculating on the outcome of quick hitting results frequently get hurt by the bursts of volatile storms.

U.S Official Jobs Numbers Today and Anticipation

Adding another dose of intrigue to the day are the upcoming official jobs numbers from the U.S, including the Non-Farm Employment Change and the Average Hourly Earnings reports. The inflation data via the earnings statistics are anticipated to show a gain of 0.3%, if for some reason it comes in stronger than expected this could create more fireworks. Having said that, the Wall Street Journal reported yesterday that Americans appear to have stopped quitting their jobs in order to switch to similar competitive positions as much as they had been the past couple of years. Perhaps this signals wages are starting to cool or least will in the near-term.

Let’s also remember that yesterday’s selloff in equities may have been anticipating better Non-Farm Employment Change results today based on the ADP outcome Thursday, and other solid U.S data before like last week’s GDP gains. Day traders betting on quick hitting CFDs via their brokerage platforms should be careful today and listen to news regarding the U.S bonds market. Inexperienced speculators should try to understand the adage – buy the rumor and sell the fact. Meaning ‘smart money’ often acts before others and takes advantage of their outlooks regarding data.

Quick Warning on Binance and Cryptocurrencies for Gamblers

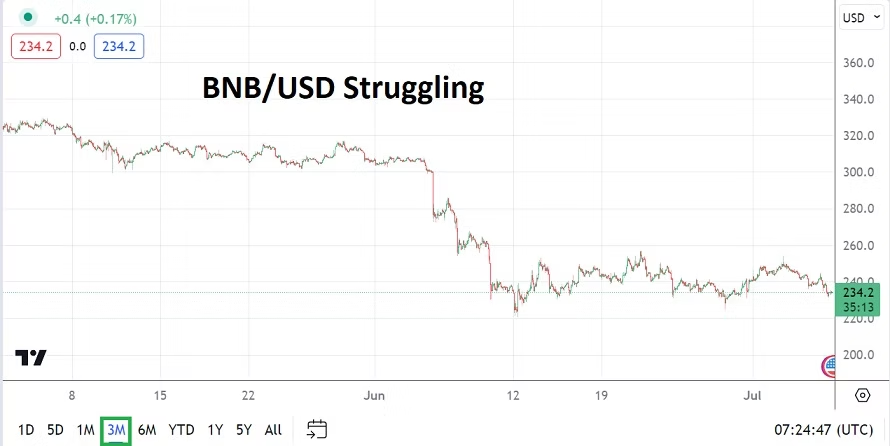
BNB/USD Three Month Chart as of 7th July 202

In a non-related subject, cryptocurrency traders seem to remain rather steady but should be nervous – if anyone is actually really trying to speculate in this endeavor besides Larry Fink of BlackRock currently, news regarding Binance remains troubling on the surface as legal clouds grow. Folks involved with the BNB coin should be careful. As one of the most ‘important’ crypto exchanges Binance’s legal problems moving forward could affect the prices of cryptocurrencies significantly. As of this writing BNB/USD is at nearly 233.00, and it should be noted Tether’s USDT appears to remain rather solid for the moment at 1.00. A look at the current three month chart of BNB/USD highlights its latest value struggles.