post204

AMT Top Ten Miscellaneous Tastings for the 10th of May 2024

AMT Top Ten Miscellaneous Tastings for the 10th of May 2024

10. Word of the day: Ultracrepidarian is a person who speaks assertively about subjects that are beyond their level of knowledge. The world is full of many suspects ladies and gentlemen.

9. Steve Albini: The musician and production sound engineer passed away earlier this week in Chicago. Albini was a pioneer and leader in ‘alternative’ music and battled homogenized corporate music for nearly 40 years. Nirvana, Fugazi, Jimmy Page, the Pixies, P.J Harvey are some of the many that worked with Albini.

8. Bitcoin: BTC/USD continues to hover around the 63,000.00 realm per a three month technical chart perspective. Bitcoin’s higher values via one year results are being maintained. BNB/USD is lurking near 600.00 per a three month glance.

7. Commodities: Cocoa and Coffee prices remain elevated. After touching a low around the 7,250.00 USD mark last week per metric ton, Cocoa is now within sight of 9,000.00 USD again. Retail speculators who like to wager via CFDs on commodities need to remember their bets have no influence on the markets, which are in complete control by the largest players in the commodities sector.

6. Wayve Technologies: A U.K based company specializing in autonomous driving software has announced they have raised more than 1 billion USD in investments recently via the likes of Softbank, Nvidia and Microsoft. The U.K government has highlighted Wayve, proclaiming it shows Britain will be a major force in AI development. Wayve was established in 2017 and is still a privately held company.

5. U.S Foreign Policy: Election concerns appear to be a prime motivator for the U.S executive branch as its attempts to walk a fine line regarding diplomacy and saber-rattling in the Middle East. Polling from a variety of sources indicate Joe Biden is in jeopardy of not being reelected.

4. USD/CNY: China will release its Consumer Price Index and Producer Price Index numbers early on Saturday. The USD/CNY is trading around the 7.2245 mark as of this writing. Some analysts have expressed concerns about the China Yuan weakening via attempts by the Chinese government to boost exports. The USD/CNY certainly remains within the higher elements of its range, but is below marks seen in early September 2023 which were around the 7.3425 ratio.

3. Data Warning: While day traders may be inclined to look at the University of Michigan’s Consumer Sentiment reading today, they should remember to pay attention to the Inflation Expectations statistics. Last month’s inflation report produced a result of 3.2%, which delivered a solid dose of volatility to financial assets.

2. Forex: Behavioral sentiment appears to be leaning towards a weaker outlook for the USD as major currencies like the EUR, GBP (solid GDP numbers also helped this morning in Britain) and others have gained. However, its should be pointed out that the USD/JPY has seen an incremental climb since touching a low of nearly 151.880 last Friday. As of this writing the USD/JPY is around the 155.650 level.

1. Equity Indices: Bullish optimism has been seen in the S&P 500, Dow 30 and Nasdaq as all three major indices are ready to start the day near highs for the week. The burst of upwards momentum which started last Thursday, has ignited the major U.S indices within sight of their apex realms achieved in late March and early April.

post203

AMT Top Ten Miscellaneous Observations for 3rd of May 2024

AMT Top Ten Miscellaneous Observations for 3rd of May 2024

10. Formula One: The Miami Grand Prix race will be held on Sunday. Whispers have been heard that Red Bull driver Max Verstappen has been approached by Mercedes bidding an annual contract over 150 million USD, but that he has not accepted the offer. However, Adrian Newey, engineer and CTO of Red Bull Racing, has confirmed he is leaving the team after 19 years of leadership. F1 certainly needs more competitive racing, a shake up at Red Bull could deliver this for the sport.

9. De-movements: Desire for decolonization, decarbonization, depopulation, turned into delusion and dehydration for Columbia University protestors and the need for a glass of water per the request of a student leader. Perhaps de-escalation is next.

8. Geopolitics: The nation of Georgia is dealing with demonstrations as some citizens show disdain regarding feared political influence from Russia. Georgia has an approximate population of 3.7 million. The East European and West Asian country has seen civil disobedience on the streets of Tbilisi increase this week.

7. Lower Values: Cocoa is near 7,658.00 USD per metric ton as of this morning, on the 19th of April it traded above 12,000.00 briefly. BTC/USD is around 59,250 after having faced headwinds this week.

6. Gold: The precious metal has sold off this week and is hovering near 2,300.00 per ounce as concerns build about USD outlook remaining strong over the mid-term. A low of nearly 2,282.00 was seen on Wednesday. Today’s publication of U.S economic data will push the price of Gold around.

5. Mixed Trading: Equity indices have produced uneven results this week as investors try to find equilibrium. Optimism almost always is the eventual emotion long-term institutional market participants lean towards. The S&P 500, Dow 30, and Nasdaq Composite all gained yesterday, but remain below highs from earlier in the week. Behavioral sentiment appears fragile and many Fed observers are disgruntled.

4. Uncertainty: The Federal Reserve has admitted it is unsure about future economic progress this calendar year. When questioned about the potential of stagflation Fed Chairman Jerome Powell said he see no signs of this – while forgetting to add that politically saying such a thing would likely cost him his job. And lets remember, the Fed claimed they thought inflation was transitory in July of 2021.

3. Bank of Japan: A battle is underway with the USD/JPY as the BoJ has staged two interventions this week. Intent on trying to create economic growth via stronger exports, while allowing import inflation to be seen, the BoJ interest rate policy remains dovish. The USD/JPY is near 153.230 now, but it is unlikely to go into the weekend with this price. An apex on the 29th of April approached the 159.610 ratio. Financial institutions and Japanese Yen traders must remain alert.

2. High Anxiety: Day traders in Forex, equity indices and commodities have certainly seen heightened volatility and the choppiness is going to persist. Retail brokers will welcome speculators with open arms and point to opportunities, but traders need to understand the ‘casino’ often is making money via losses incurred because of leveraged wagers which turn into losing bets when price velocity hits.

1. Jobs Data: Yet another opportunity for inflation to be seen today via the Average Hourly Earnings numbers. A cautionary road sign was seen this Tuesday when the U.S Employment Cost Index came in with a stronger than anticipated quarterly gain of 1.2%. The USD will remain a lynchpin in many financial assets, and Treasury yields should be watched after the employment statistics have been printed.

postN51

AMT Top Ten Miscellaneous Postings for the 5th of April 2024

AMT Top Ten Miscellaneous Postings for the 5th of April 2024

10. Petrichor: The pleasant smell after a rain has fallen following a long dry spell which elicits earth’s fragrance. The Fed is likely hoping for this sensation via ‘weaker’ Non-Farm Employment Change numbers today. In December the Federal Reserve spoke about data signals needed in order to cut interest rates. If jobs statistics are stronger than anticipated, there will be no ‘petrichor’ for the Fed.

9. Underreported: Five engineers from China on their way to work for the Dasu dam project they participated, were killed in a ‘suicide’ terrorist attack in Pakistan on the 26th of March. Terror attacks in Pakistan on Chinese involved with infrastructure ‘Economic Corridor’ work have been increasing.

8. Qubits: Microsoft and Quantinuum recently announced they have made breakthroughs regarding quantum computing research reliability. Results have shown 14,000 ‘test routines’ without errors. The emergence of quantum technology approaches.

7. Intrinsic Value: Cocoa is near 9640.0 USD per metric ton as of this morning and remains speculatively energetic. Bitcoin is slightly below 67,000 USD and continues to ‘beat’ the notion that intrinsic value is important.

6. Precious: Gold prices have ‘fallen’ below 2300.00 USD per ounce, and is near 2289.00 for the moment, but the metal is shining as crowds admire its ability to create a safe haven.

5. WTI Crude Oil: Middle East news is rumbling and hyperbole is resonating, the price of the commodity is over 86.40 USD per this writing. A calm weekend, and peaceful end to Ramadan this coming Tuesday might help calm nerves. Higher oil prices will not help global inflation.

4. Forex: The USD/JPY has started to experience waves of volatility and has recently challenged long-term highs. Bottom line is the notion that large players are positioning for today’s U.S data which will affect all financial assets as USD centric power resounds.

3. Equities: The U.S major stock indices are beginning their day near lows not seen since the 15th of March for the Dow 30, and the 19th of March for the S&P 500 and Nasdaq Composite. Nervous?

2. Bonds Watch: U.S Treasuries need to be monitored as the 5, 7, and 10-Years Notes respond to nervous investors and fears of a new ‘inversion’. Having come off of high yields a couple of days ago, doesn’t mean all is well as values languish near late September 2023 technical realms.

1. Data: Recent chatter from many Fed FOMC members have created anxious investors. Vivid reactions will occur after the Non-Farm Employment Change and Average Hourly Earnings. Bluntly, today’s jobs reports are crucial and the Fed would like the results to be weaker than anticipated in order to consider cutting interest rates. However, if hiring comes in stronger, it would be a sign of a resilient U.S economy and would ignite more USD strength. The first half hour following the jobs numbers may look counter-intuitive regarding price action as financial institutions adjust their trading positions.

postN51

AMT Top Ten Miscellaneous Musings for the 29th of March 2024

AMT Top Ten Miscellaneous Musings for the 29th of March 2024

10. Holidays: We wish everyone a peaceful long weekend. Hopefully the price of your chocolate eggs have not emptied your wallets.

9. Superconductivity: Nuclear fusion and magnets have a future together. Efficient electricity produced via compact generation is being worked on by the Massachusetts Institute of Technology and the Jet Propulsion Laboratory of NASA.

8. TMTG: The Trump Media and Technology Group listed as DJT on Nasdaq ended yesterday’s trading within sight of 62.00 USD. The price is overbought taking into consideration its lack of revenues. However, because of its limited available shares, ‘shorting’ DJT is dangerous and a potentially expensive mistake.

7. Silly Season: U.S elections are growing closer and louder. However, fiscal and foreign policy clarity doesn’t get much airtime. Bread and circus for the masses.

6. Crypto ‘Insanity’: FTX Founder Sam Bankman-Fried was sentenced to 25 years in prison yesterday for his crimes. In the meantime, Bitcoin is over 70,000.00 USD this morning. Binance Coin is valued above 600.00 USD.

5. Frothy: Gold is near 2,230.00 USD per ounce, even as the USD grows in strength. Cocoa closed yesterday around 9,792.00 USD per metric ton, meaning it is more expensive than Copper, and the reason why your chocolate may be getting costly.

4. ‘Quiet’ Data: Core Personal Consumption Expenditures Price Index data will be released today in the U.S, this as the financial markets are largely absent. Yesterday’s GDP and Consumer Sentiment numbers were stronger than expected. The inflation statistics may not get much fanfare today, but paying attention to the results could prove worthwhile for speculators.

3. Risk Warning: The return of large trading volumes next week are likely to cause volatility as financial institutions reopen and are reactive.

2. Bias: Many major currencies are struggling against the USD. Traders who believe their chosen currencies have been oversold should contemplate their perspectives and potential bias. Just because you believe something, doesn’t mean it is true. Forex is expressing nervous behavioral sentiment.

1. Fed Watch: Many analysts are starting to believe the Federal Reserve may not be able to cut interest rates this year, but traders should remember politics will be crucial as the U.S Presidential Election approaches. The Fed may be ‘independent’ but they are not deaf. If inflation remains stubborn, the Fed will need weak jobs numbers. But weekly Unemployment Claims came in below expectations yesterday. Financial institutions understand the U.S central bank is in a difficult place.

post193

Inflation Encore: Forex Traders Gathering Important Evidence

Inflation Encore: Forex Traders Gathering Important Evidence

The USD has been weaker against many major currencies the past week and inflation numbers coming from the U.S will test short-term outlooks. It should be remembered that in February before the CPI numbers were published, some who were leaning towards a weaker USD were traumatized after the stronger than anticipated results. However recent U.S economic data has shown a rather polite and distinct downturn.

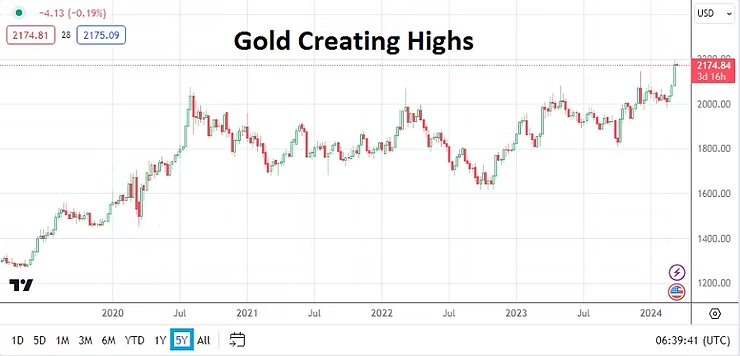
Day traders should brace for drama today and understand that financial institutions will lead the way, either catapulting trends or stopping them in their tracks. As Forex speculators get set, Gold continues to also flirt with highs, as of this writing the precious metal is near 2175.00 USD. Financial assets from equity indices to digital assets (yes, Bitcoin) are experiencing frothy returns as values seemingly attract more capital inflows. In other words, bullish behavioral sentiment is rather strong and traders are reminded to stay realistic with their goals.

Again, there is a difference between quick hitting speculators trying to take advantage of robust trends compared to long-term investing. Day traders still need to do their homework and not bet blindly.

Gold Five Year Chart as of 12th March 2024.

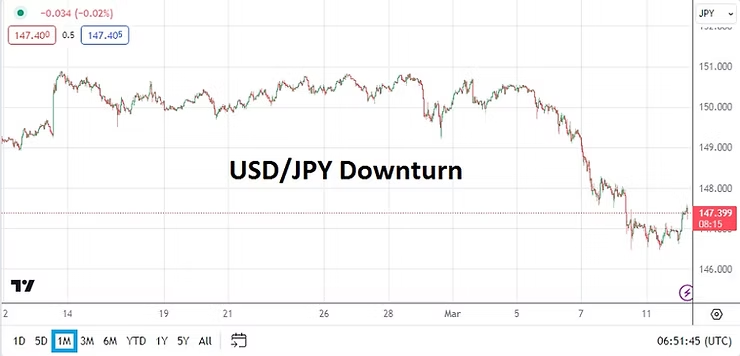
Monday, 11th of March, Japan GDP – Gross Domestic Product numbers yesterday came in with unexpected weaker results showing a gain of only 0.1% compared to an anticipated 0.3% gain. Yes, the USD/JPY held onto it downwards momentum, which it has established since last week. The trading results in the currency pair suggest financial institutions are placing their faith in mid-term outlooks.

USD/JPY One Month Chart as of 12th March 2024

Tuesday, 12th of March, U.S Consumer Price Index – the inflation reports will headline and drive market conditions near-term. Last month’s numbers provoked a strong reaction when prices remained stubborn. The monthly core report is expected to show a slight decline today, but the monthly broad number is actually anticipated to rise slightly. With mixed statistics forecast already, day traders need to be prepared for a lot of noise – which may prove rather misguided. The problem for the markets today will come from the interpretation of the numbers, if the CPI figures can simply come close to their expectations this might keep conditions from getting wild, but choppy trading should certainly be counted upon leading up to and following the publication. This month’s encore of the CPI inflation numbers will hopefully be less dramatic than February’s performance.

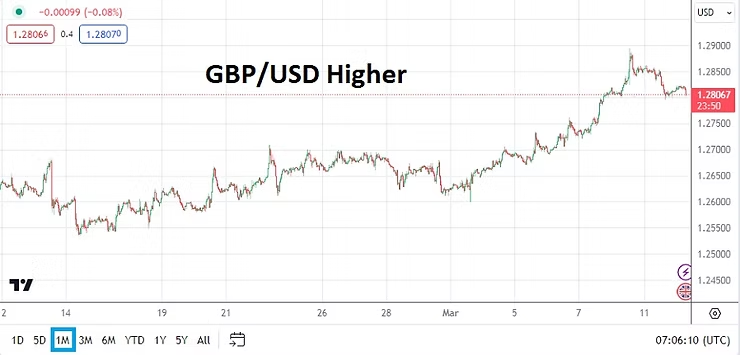
GBP/USD One Month Chart as of 12th March 2024

Wednesday, 13th of March, U.K Gross Domestic Product – a gain of 0.2% is expected via the growth number. Last month’s minus -0.1% outcome should serve as a reminder tough economic conditions remain evident. Yet, last month’s number actually beat a worse expectation. GBP/USD traders who have been patient with their bullish stances have been rewarded recently. A slight gain in the GDP number from the U.K could help bolster additional confidence regarding mid-term outlooks for the GBP/USD. The BoE, like the U.S Federal Reserve, will make their monetary policy pronouncements next week.

Thursday, 14th of March, U.S PPI and Retail Sales – the Producer Price Index and consumer spending numbers may produce the surprise for the week regarding market reactions. The Core PPI results are expected to be weaker, while Retail Spending is anticipated to grow. If the inflation results via the PPI data is weaker than anticipated this could allow for further weakness in the USD to develop.

Friday, 15th of March, China New Home Sales – real estate values in the nation remain a focal point for analysis. Another large decline in prices for homes would not be good news. The economy of China is suffering from deflation which hasn’t shown evidence of diminishing soon. China remains a vital part of the global economy. Industrial Production numbers will come from the nation on Monday.

postN89.1

Forex: Powell, ECB and U.S Jobs Numbers as Gold and Oil Run

Forex: Powell, ECB and U.S Jobs Numbers as Gold and Oil Run

Day traders and investors received a dose of optimistic ‘news’ last week as U.S economic data came in weaker than expected. While Forex certainly proved choppy as anticipated, the USD has shown signs of stability and perhaps has created a durable resistance level up above regarding its potential value looking into the mid-term.

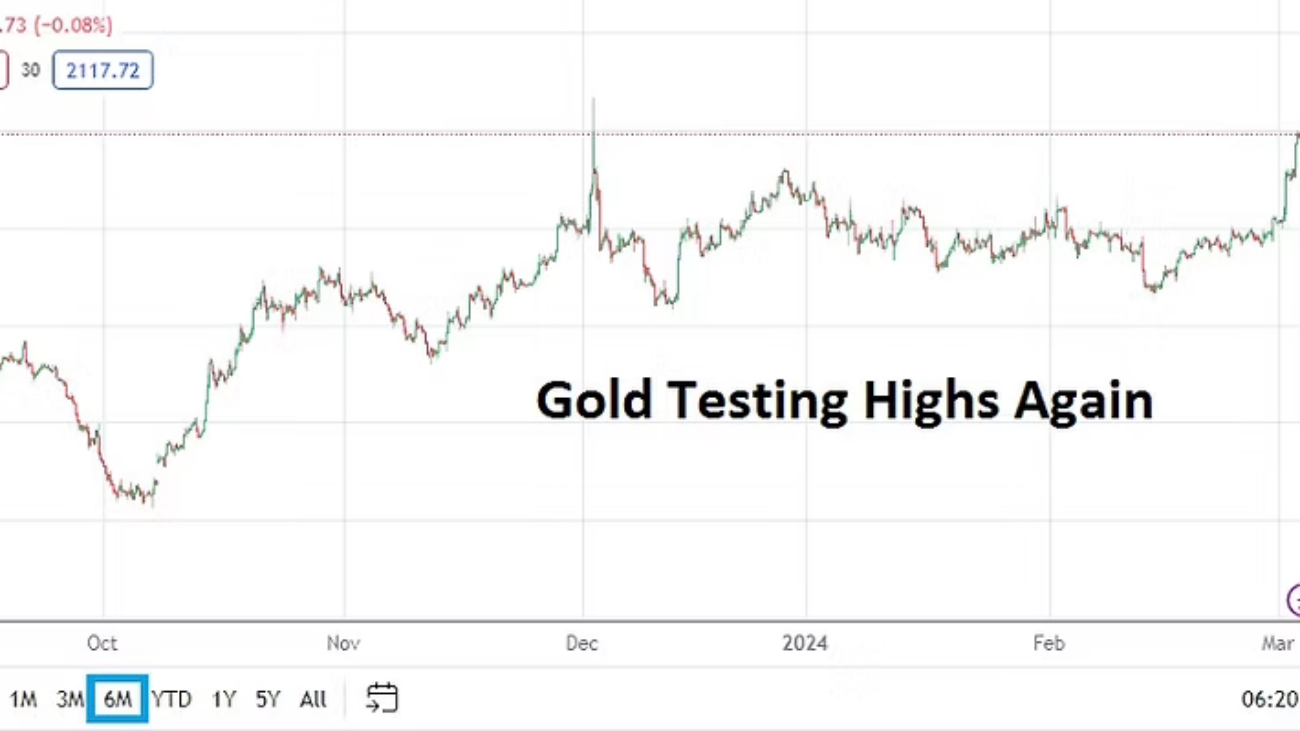
Gold Six Month Chart as of 5th March 2024

A potential telltale sign regarding the USD in Forex is the current price of Gold which is testing highs and as of this writing is near 2115.00 USD. While below the speculative heights of early December, the precious metal is above prices seen in late December when the USD was being sold heavily. The value of Gold is a rather solid barometer regarding outlook for behavioral sentiment in Forex. A weaker USD translates into a higher Gold price in many cases.

U.S Treasury yields have also decreased slightly over the past handful of days. And while U.S equity indices are within sight of record values, traders should monitor developing news regarding U.S regional banks and concerns about New York Community Bancorp (NYBC). For the moment it appears investors have not turned too nervous when considering the bigger picture of stock markets. Perhaps last year’s regional bank crisis has made investors in equity indices feel immune to fears of contagion stemming from bad commercial real estate lending. Or perhaps many folks are marching along merrily and refuse to pay attention for fear of missing out when their associates continue to parade into the indices.

The cryptocurrency market has come out of its deep freeze and sunshine is pervading the mindsets of speculative gamblers in crypto assets. U.S run ETFs are raising a lot of money. Folks have driven the market sky high again in the digital asset Bitcoin and its fellow travelers like Ethereum, Binance Coin, and there have been signs of pure casino like wagering in Dogecoin and Shibu Inu. Be carefu if you are considering dipping your toes into this ‘market’. Volatility and changes of sentiment can happen in the flick of an eye.

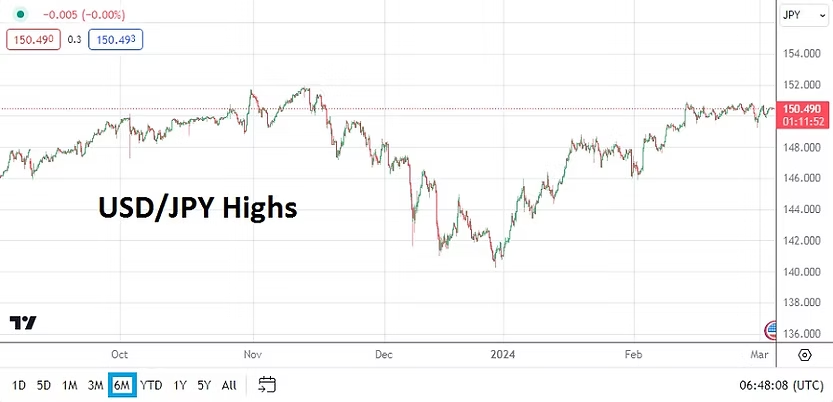
USD/JPY Six Month Chart as of 5th March 2024

Monday, 4th of March, Japan Capital Spending – a huge jump of 16.4% was reported yesterday. This points to better economic sentiment. The Bank of Japan has been getting a lot of attention the past handful of months because some financial institutions expect the BoJ’s monetary policy to begin changing. The USD/JPY remains near important resistance levels, but below the highs of last October and November 2023 values. Mid-term speculators may be leaning towards bearish sentiment in the currency pair, but a trend lower has not been established yet.

Tuesday, 5th of March, U.S Service PMI via ISM – last week’s growth and inflation data from the U.S was less than expected. While the U.S economy has shown rather stubborn growth, the American economy may be showing signs of slowing. Today’s reading is expected to come in below the previous month’s outcome.

Wednesday, 6th of March, U.S Federal Reserve Chairman Powell – the Fed chief will testify before the Senate via the Semi-Annual Monetary Report over a two day span. Because it is an election year a rather aggressive amount of questions will be asked. However, Powell is a skilled speaker and it unlikely he will be rattled by political rhetoric. Of interest will be any comments regarding inflation, this as the Fed Chairman is asked for insights regarding the Federal Funds Rate outlook. While this testimony in Washington D.C is usually a polite get together, the notion that some politicians may try to score points will make this a potentially important calendar event for investors to pay attention regarding financial market gyrations. Powell is expected to remain cautious regarding his answers.

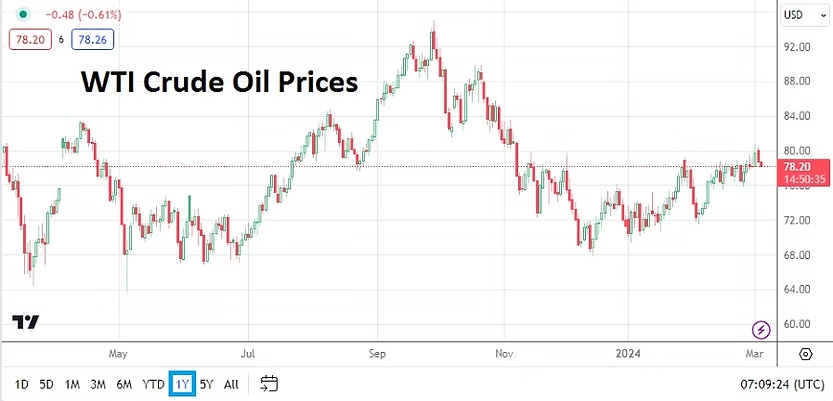
WTI Crude Oil One Year Chart as of 5th March 2024

Wednesday, 6th of March, U.S Crude Oil Inventories – last week’s U.S supply report posted increased results, yet the price of WTI Crude Oil jumped the end of last week. The value of the commodity remains within the lower part of its one year range and should be watched. Recent speculative action has shown some buying momentum. The price of energy is a big component within global inflation and should be watched as the 80.00 USD Crude Oil level is challenged.

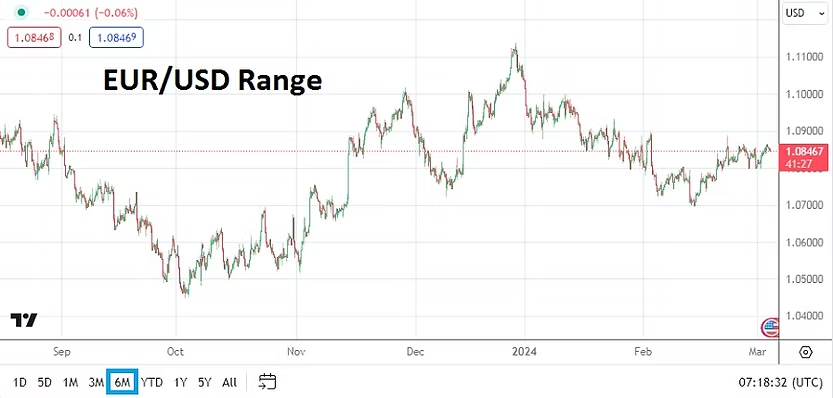
EUR/USD Six Month Chart as of 5th March 2024

Thursday, 7th of March, European Central Bank Main Refinancing Rate – once again the ECB is expected to not act. The question is if financial institutions may try to send the European Central Bank a message because of its ‘inaction’ as inflation remains stubborn in Europe and growth hard to achieve. The EUR/USD has returned to value above the 1.08000 mark again, but visions of a stronger EUR have been hard to attain. The combination of the ECB Monetary Policy Statement and Press Conference, as Fed Chairman Jerome Powell is addressing politicians in Washington D.C could make for an interesting day of volatility in Forex.

Thursday, 7th of March, U.S State of the Union – President Joe Biden will deliver his address to Congress.

Friday, 8th of March, U.S Non-Farm Employment Change and Average Hourly Earnings – weaker jobs numbers and diminishing wage escalation are expected. U.S economic data last week came in below estimates. This report will be a solid barometer for financial institutions. While the work force numbers in the U.S are said to be tight – meaning there is full employment – layoffs have certainly been taking place in some sectors. Also worth paying attention to in the ‘back pages’ of the report, will be the amount of average hours worked by employees which have seen a statistical decline emerge.

postN51

AMT Top Ten Miscellaneous Spiders for the 1st of March 2024

AMT Top Ten Miscellaneous Spiders for the 1st of March 2024

10. Palystes: Huntsman spiders known in South Africa as ‘rain spiders’ are nocturnal and visit indoors, sometimes causing horror for those stumbling through hallways in the middle of the night. But it is better than a baboon entering the house.

9. Victor Wembanyama: Last night’s stat line included 28 points, 13 rebounds, 5 blocks, 5 3pts made, 7 assists, 2 steals in less than 33 minutes played. The rookie is already one of the best NBA players. Btw, the Spurs beat the Thunder also.

8. Tech: Chinese cars are now in the crosshairs of U.S politicians who are worried the ‘smart’ vehicles can collect sensitive data from Americans.

7. Crypto: Bitcoin above 61,000.00 USD, Ethereum over 3,300.00, and Binance Coin testing 400.00 even as the company remains under U.S legal shadows. How much air can the balloons withstand?

6. Putin’s Nuclear Threats: In a world with escalating geo-political tension, the Russian leader remains determined and energetic while playing ‘war poker’ against Europe.

5. U.S Data: Core PCE Index numbers yesterday met expectations, but the previous month’s outcome was revised downwards. Today a Consumer Sentiment reading comes from the University of Michigan. This week’s U.S data has mostly been pleasantly ‘weaker’.

4. Central Banks: Fed ‘watchers’ are likely feeling more comfortable this morning regarding the possibility of a late spring ‘thaw’ in U.S interest rates. Jerome Powell will testify in front of the Senate next Thursday. The ECB will release their Monetary Policy Statement on the 7th of March also. Next FOMC pronouncements will be on the 20th of March.

3. Gold: The precious metal is near 2050.00 USD, this after yesterday’s U.S inflation report, gold could remain volatile today. Some speculators may be looking for additional value to develop.

2. Forex: FX has been a constant battle the past two months, but patient traders with mid-term perspectives may be anticipating their weaker USD targets to trend more steadily.

1. Equities: Many global stock indices are achieving record levels as bullish behavioral sentiment creates upwards momentum. S&P 500, Nasdaq 100 and the Composite, Dow 30, Nikkei 225 and the DAX Index are flirting with higher values.

postN51

AMT Top Ten Miscellaneous Raindrops for 16th of February

AMT Top Ten Miscellaneous Raindrops for 16th of February

10. Bitcoin is trading within sight of 52,000.00 USD, the digital asset was trading near 38,700.00 on the 23rd of January, which is over 34% in less than a month. That’s a lot of air in the balloon folks.

9. Gold: The precious metal has climbed above 2000.00 USD, this after a drop to 1985.00 USD on the 14th of February. Sentiment is uneasy.

8. Not April Fool’s Day: Iran has announced ‘plans’ to build a naval base on Antarctica, after declaring ‘property rights’.

7. WTI Crude Oil: The price of the commodity continues to battle the 77.00 USD level. Higher energy costs will not be looked on favorably by inflation hawks.

6. U.S Treasuries: Yields should be watched today after having provided anxious results this week, U.S equity indices will continue to react to the ‘bonds’ market.

5. Nvidia: After delivering superlative results in 2023, the company has announced the release of Chat with RTX, which allows independent AI chatbot capabilities to interface with your own documents, videos, etc., providing insights from personal queries.

4. Chinese Property: Investments dropped by over 9% in 2023. China’s government faces a clash between socialistic ideology in order to help the market versus practical supply and demand realities.

3. U.K: Gross Domestic Product numbers came in with negative results yesterday for Britain, the combination of recessionary GDP and stubborn inflation is stagflation. Bank of England faces a difficult decision. Will the BoE get proactive and cut interest rates before the Federal Reserve? GBP/USD is below 1.25800 this morning.

2. Data: Stronger than expected U.S CPI statistics caused bedlam on Tuesday, but yesterday’s Retail Sales came in weaker. The ‘disappointing’ consumer spending numbers were likely welcomed by the Federal Reserve and financial institutions. Producer Price Index statistics will be published today, surprise inflation results could jostle financial markets.

1. Forex: Day traders witnessed whipsaw results early this week and should remain cautious going into this weekend. Patience will be needed as USD centric outlooks adjust to nervous shifts in behavioral sentiment.

postN91.1

USD: Hidden Jobs Data Shows Potentially Intriguing Weakness

USD: Hidden Jobs Data Shows Potentially Intriguing Weakness

Forex traders like many market participants react to the ‘noise’ of U.S headline data results. The recent U.S jobs numbers published last Friday is certainly an example. The USD surged in strength on the backbone of more hiring via the Non-Farm Employment Change numbers. Also the Average Hourly Earnings beat expectations showing the cost of labor had become more expensive.

The U.S Federal Reserve stood in place last Wednesday before the jobs report. Pointing towards some troubling inflation, and mentioning the labor market was tight, the Fed refused to give a timetable regarding potential Federal Funds Rate cuts. The U.S central bank is showing more patience about coming interest rate cuts than many hoped on and had wagered.

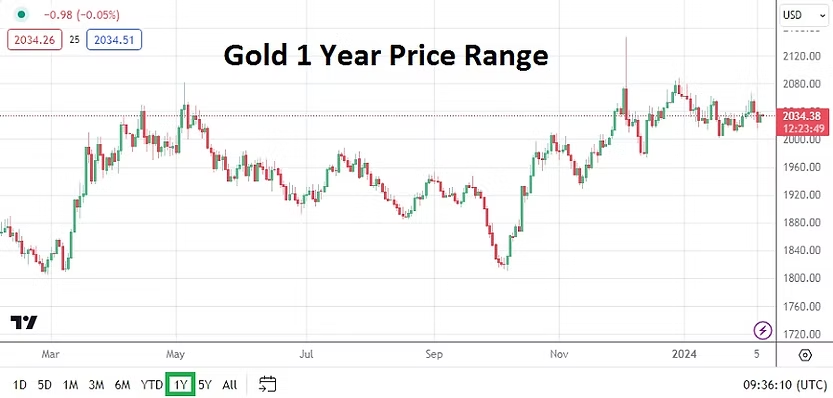
Gold One Year Chart as of 7th February 2024

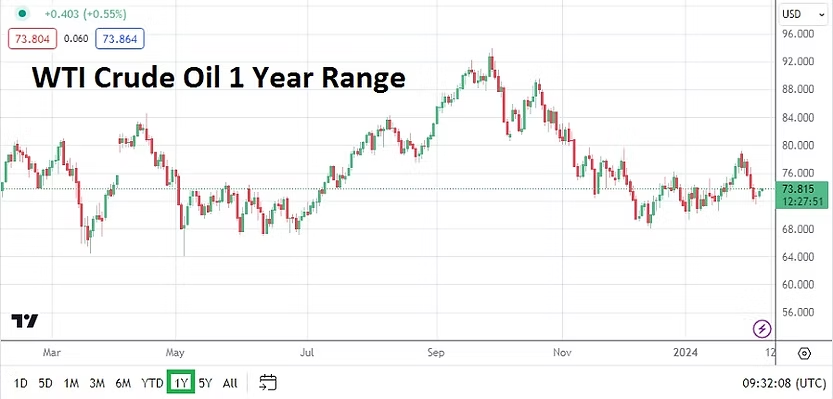
Yet, there continues to be signs of anticipation for a weaker USD in the mid-term. The price of Gold remains within its higher elements, and U.S Treasury yields remain lower (although it must be said the past two weeks have seen an incremental move higher). And as a sign of potential inflation erosion, energy prices continue to be polite, which means the costs of logistics may continue to ease (except to say concerns about Suez Canal availability and chaos in the Red Sea are certainly risks).

WTI Crude Oil One Year Chart as of 7th February 2024

The fact that gold remains solid in value, and energy prices remain relatively low, and that support levels in Forex via the USD continue to drift near realms seen on the 13th and 14th of December is an intriguing behavioral sentiment clue. Perhaps it is a sign large institutional players believe they know something others are not considering regarding the future direction of the USD fundamentally.

There are always risks for day traders. Having solid information which is correct and can affect values in Forex, commodities and even equities is important for speculators, but is also hard to find when there are limited resources regarding market intelligence.

U.S Jobs Numbers Headline may be Misleading

Importantly, while last week’s jobs numbers on the ‘surface’ scared many large players who believed the USD will get weaker, thus causing the significant reactions via reversals in many major currency pairs teamed against the USD; there is some evidence from the U.S jobs statistics that needs consideration which was not widely reported. It is important to read beyond the headlines.

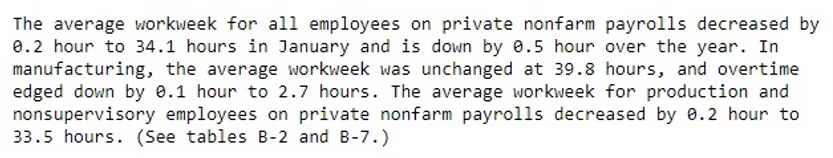
The amount of hours worked in the U.S on a weekly basis has eroded. Added to this consideration is that the stronger hiring numbers may still have been affected from seasonal needs due to the holiday season. This sets the table for the next U.S jobs numbers as a significant report on the 8th of March, and one that will have a big impetus on Federal Reserve’s monetary policy outlook and USD.

The U.S Bureau of Labor Statistics Employment Situation News Release on the 2nd of February (https://www.bls.gov/news.release/archives/empsit_02022024.htm) reported the following:

Perhaps it is conjecture to speculate the average workweek for employees decreasing is a telltale sign of weakening employment numbers to come, but it might prove to be a useful insight. Layoffs via U.S corporations continue to make news as companies seem to be bracing for a downturn in U.S economic health in the coming months. If the layoff theme remains noisy it will create the need for action from the Federal Reserve regarding monetary policy.

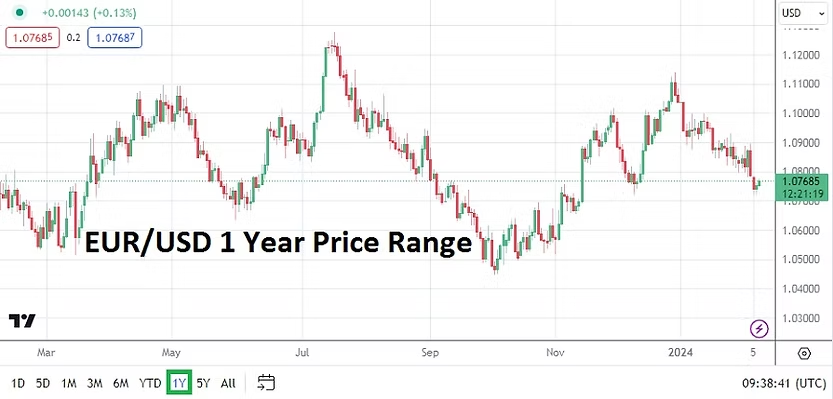
EUR/USD One Year Chart as of 7th February 2024

What does it mean for day traders? There are absolutely no guarantees, but the major currency pairs ability to stay within their mid-December prices is a likely sign that financial institutions have analysts which are looking beyond the headline numbers from the recent U.S jobs report, and have also seen the hourly workweek data. In other words support levels in many of the major currency pairs could prove durable. There is no doubt reversals and outliers will be demonstrated, and choppy Forex conditions will happen, but perhaps the current lows in many major currency pairs will start to exhibit resilience.

Trying to time short-term moves via behavioral sentiment that is generated by statistics found ‘hidden’ away in the jobs numbers is speculative. But if traders want to consider the potential of technical support, it might be worth a consideration to think the U.S employment picture isn’t as strong as the headline ‘noise’ is projecting.

postN87

AMT Top Ten Miscellaneous Clues for the 26th of January

AMT Top Ten Miscellaneous Clues for the 26th of January

10. Sports: Australian Open Tennis Tournament Finals this weekend. And five episodes into Netflix’s Six Nations: Full Contact there has been NO mention of rugby national teams in the Southern Hemisphere. Bias?

9. Money Club: Microsoft has joined Apple with a market cap over 3 trillion USD, the only two companies in the world able to make this boast.

8. Democracy: India elections coming in April and May seem to have a predictable outcome, but the South Africa voting date has not been made official and the ANC is under pressure. U.S citizens appear set for a rematch of Biden and Trump in November.

7. Layoffs: Around 1,900 employees of Activision Blizzard and Xbox, both owned by Microsoft, will have their jobs eliminated. Microsoft spent about 68.7 billion USD to acquire Activision Blizzard – a deal that was finalized in October of 2023.

6. Nervous: Bitcoin still battling the 40,000.00 USD ratio. Binance Coin has fallen below 300.00 USD, BNB/USD traded near 200.00 USD in the middle of October.

5. Behavioral Sentiment: Gold remains near 2020.00 USD, U.S Treasury yields are in sight of three month lows, but energy prices have ticked upwards this week with WTI Crude Oil near 77.00 USD.

4. Forex Caution Sign: Day traders should be braced for price velocity today. Is the USD going to become weaker going into the weekend?

3. U.S Federal Reserve: FOMC Statement will be on the 31st of January. Yesterday’s GDP numbers came in stronger than anticipated, fueled by robust consumer spending. However the GDP Price Index results were well below their expectations. Some folks may be dreaming about a rate cut in March, but there is still plenty of data ahead.

2. Stock Indices: The S&P 500, Dow Jones 30 and Nasdaq 100 are within record heights. Japan’s Nikkei 225 is challenging values not traversed since early 1990. The values of these indices may be dizzying, but the trend has been hard to bet against.

1. Inflation: Core Personal Consumption Expenditures (PCE) Index reading is anticipating a 0.2% gain today. Last month’s outcome was 0.1%. The U.S Federal Reserve monitors this particular report closely. Financial institutions will react and any surprises will become a catalyst in the broad markets.

postN101

Anonymous Kingdom: Bitcoin’s Lack of Transparency is Supreme

Anonymous Kingdom: Bitcoin's Lack of Transparency is Supreme

Bitcoin has fallen below the 40,000.00 USD price level today, and after penetrating the depth of 39,500.00 USD has shown additional velocity lower. Bitcoin is now testing support near the 38,850.00 ratio, a value it last tested on the 2nd of December.

Influencers will likely urge their fanbases to look at six-month charts to understand Bitcoin is still within the upper levels of its price range, this because a look at a three-month chart isn’t as cheerful. The speculative asset remains a dangerous place for day traders to participate who do not have legitimate insights regarding Bitcoin.

BTC/USD Six Month Chart as of 23rd January 2024

The question that some are likely starting to ask is what happened to the bullish rush in Bitcoin that was evangelized as a source of inspiration when the U.S Bitcoin ETFs materialized? FOMO (fear of missing out) again became an ‘advert’ for Bitcoin. True patience is needed when investing in financial assets, but day traders aren’t investing they are speculating and BTC/USD is likely costing them plenty of money.

It has been publicized that BlackRock’s spot Bitcoin ETF now holds over 1 billion USD in funds. However, while BlackRock and other ETFs have added to their assets under management of Bitcoin, what are short positions within the ETFs regarding size? This number is elusive, but the ability to sell ETF ‘share’ value within the new Bitcoin funds being offered is said to exist.

Bitcoin’s open interest numbers within the CME’s future contracts was nearly 26,669 positions on the 11th of January, yesterday’s reporting via the Chicago Mercantile Exchange was 22,250 open positions. While day traders may be speculating on the price of BTC/USD via their brokers’ trading platforms, they have to understand that their wagers are not affecting the real market price. The big players within the Bitcoin market do not operate on brokerage platforms which are merely offering CFD positions. The large traders are using cryptocurrency exchanges, futures and options via the CME, and now ETF positions.

Unless a trader is actively selling Bitcoin on a selected cryptocurrency exchange – and likely being asked to open a margin account – and thus opening the door to leverage and volatility, which it can be argued is designed to knock you out of the positions. You are going to find it difficult to actually sell ‘physical’ Bitcoin via short positions that are ‘manipulating’ the cash/spot market.

Bitcoin is a playground for sophisticated traders with plenty of cash to speculate and will continue to produce a world of extreme price volatility. On the 11th of January the price of Bitcoin jumped towards the 49,000.00 mark before declining. Bitcoin’s high early this morning was around the 40,150.00 ratio before stumbling the past handful of hours. Note, that open interest was at its highest on the 11th of January via CME futures trading information.

If you want to speculate (bet) on the value of Bitcoin as a day trader you should understand that you are participating in a marketplace that still doesn’t have the best of transparency. Yes, in most assets day traders are always competing against complex dynamics in which they have no control. However, speculating on BTC/USD is still being done almost blindfolded because of the lack of insights that is part of Bitcoin’s anonymous allure that many of its proponents love. We are still a distance away from transparency within the world of Bitcoin.

If traders can get access to volumes data – and the size of long and short positions being placed within the crypto exchanges they are using that helps. But because Bitcoin trading is still unregulated, and since there are many crypto exchanges operating you will only be getting small bits of information. The lack of information should worry day traders and serve as a caution sign.

postN87

AMT Top Ten Miscellaneous Notions for 12th of January 2024

AMT Top Ten Miscellaneous Notions for 12th of January 2024

10. Music: School Days by Stanley Clarke. Recorded in 1976, the ‘song’ is one of the best jazz fusion pieces ever played.

9. Coaches: Bill Belichick and Pete Carroll have been ‘politely’ fired, Nick Saban has retired. NFL and college football remain the ‘Kings of Sport’ in the United States.

8: Taiwan: Presidential election will be held tomorrow. Expect noise from China this weekend regarding Taiwan’s sovereignty.

7. Forex: Volatility struck yesterday in USD based currency pairs, whipsawing as financial institutions reacted to the Consumer Price Index reports. More inflation data will come from the U.S today.

6. Gold and Crude Oil: Precious metal value has been ‘almost’ steady, and WTI Crude Oil price remains rather calm.

5. China Deflation: CPI and PPI numbers were lackluster this morning. Export numbers from the nation have also delivered troubling declines.

4. Houthis: U.S and U.K missile strikes in Yemen have been conducted, diatribes from the extremists have been sounded, and may cause some investors concerns and potential risk adverse trading considerations going into weekend.

3. Bitcoin: SEC ETF funds approval has been completed, and launch is set to allow retail traders and ‘investors’ to purchase the digital asset. BTC/USD is near 45,960.00 currently. CFD products from brokers will likely be introduced and flourish soon, which will be based on the ETF notional values and allow day traders to wager on upside and downward momentum.

2. PPI Data: U.S Producer Price Index inflation results today could rattle the broad markets. No changes are forecasted. A surprise increase would worry those betting against the USD. Traders should also keep their eyes open for potential revisions to previous months.

1. Risk Appetite: Dow Jones 30, S&P 500 and Nasdaq 100 continue to flirt with apex values. The Nikkei 225, from Japan, is challenging highs not seen since 1990 as it trades above 35,575.00 for the moment. Equity indices remain optimistic.