postN63.1

Fed Rhetoric, U.S Consumers, and Fresh Concerns about China

Fed Rhetoric, U.S Consumers, and Fresh Concerns about China

U.S inflation data via the Consumer Price Index last Thursday met the anticipated result regarding the core number, and the broad statistics were only fractionally larger than expected. U.S Treasuries yields however jumped via quick reactions about stubborn inflation, then settled down. Equities via the major indices continue to show nervousness.

Day traders continue to get hit by choppiness, which means if they are not on the correct side of a trade initially, they can get knocked out of their positions quickly due to the use of too much leverage.

China produced another round of troublesome Consumer Price Index Producer Price Index reports last Friday, once again highlighting deflation is a legitimate concern for the nation.

The USD began to weaken within many major currency pairs on late Tuesday and early Wednesday, and then began to prove difficult with sideways price action. However, many currencies held onto their slight gains against the USD going into the weekend. But before a massive bearish trend against the USD actually can be sustained, perceptions about the U.S Federal Reserve stands clearly in the way regarding behavioral sentiment.

Inflation numbers last week remained strong enough to suspect the Fed will raise interest rates again on the 1st of November. As a way to keep traders on their toes, U.S Federal Reserve officials will be speaking at many functions over the entirety of this week, offering crumbles of evidence for their less than spectacular rhetoric on the global economy no doubt.

Gold has produced a rather startling climb in the past ten days and its one month charts resemble a rather turbulent roller coaster. Traders who have been pursuing the precious metal during its strong reversals the past handful of weeks have hopefully been using solid risk management while taking a speculative ride.

Gold One Month Chart as of 16th of October

Monday, the 16th of October, U.S Empire State Manufacturing Index – the number has come in slightly better than expected, but has still produced a negative reading of minus -4.6. While many U.S officials will not state it publicly, a decline in the manufacturing index may pave the way towards a more tranquil Federal Reserve. But this may be wishful thinking too, particularly if inflation remains elevated.

Tuesday, the 17th of October, U.S Retail Sales – the data about consumer spending will affect Forex if there are surprises. Both the core and broad reports are anticipated to be weaker than last month’s numbers. Weaker results could create some USD weakness.

Wednesday, the 18th of October, China Industrial Production, Gross Domestic Product and Retail Sales – the Industrial Production results are expected to be slightly weaker than last months, while the GDP outcome is being estimated to show a significant drop. If the growth number comes in at the anticipated 4.5% mark it would be another signal that China is struggling while trying to jump start the economy. USD/CNY traders should be careful around these reports.
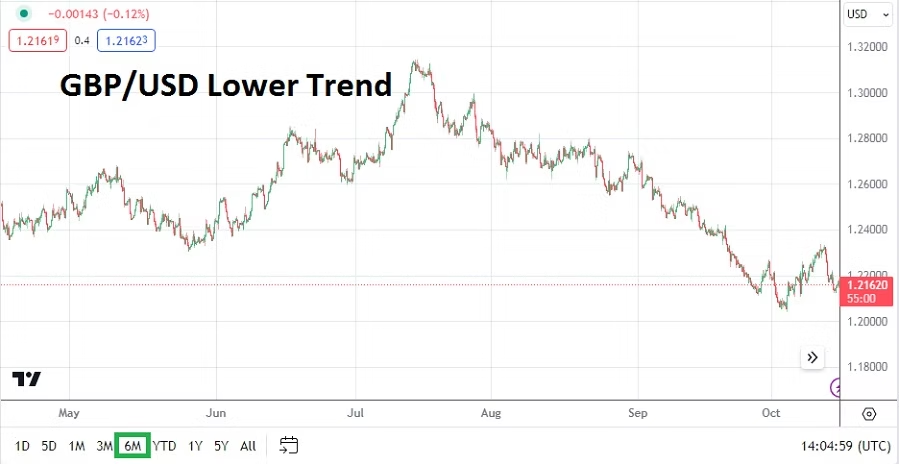
GBP/USD Six Month Chart as of 16th October

Wednesday, the 18th of October, U.K Consumer Price Index – the CPI data from Great Britain is expected to show a slight decline from the previous month. While last week’s GDP numbers met their rather lackluster expectations; Construction, Manufacturing, Trade Balance data came in much worse than anticipated. While no one from the U.K government is going to cheer on the bad economic numbers from last week, these figures will make these CPI inflation results important to monitor. Will the U.K inflation numbers remain stubborn like the U.S? The GBP/USD certainly needs to be watched in the aftermath of this CPI report.

Thursday, the 19th of October, China New Home Prices – the housing bubble within China is a thing of the past. Last month’s outcome produced another negative number and a poor report would not be a surprise this week. Negative housing values hurt the Chinese public which have largely quantified their personal savings via their real estate holdings.

Thursday, the 19th of October, U.S Unemployment Claims – the weekly report will give another small dose of evidence regarding the strength of the U.S economy for financial institutions to consider.

Friday, the 20th of October, U.K Retail Sales – the consumer spending report is expected to produce a decline of minus -0.3%. GBP/USD traders may use this report as another sphere of influence.
postN57.1

Concerns Ahead and a Potentially Noisy Week for Day Traders

Concerns Ahead and a Potentially Noisy Week for Day Traders

In the wake of last week’s central banks follies, day traders have what may appear on the surface a rather comfortable week of economic data to consider as they make their wagers. However, there are outside risk events looming which will likely stir the emotions and positions of financial institutions, and cause knock on tremors that speculators feel caused by a noisy storm of experts and media pundits.

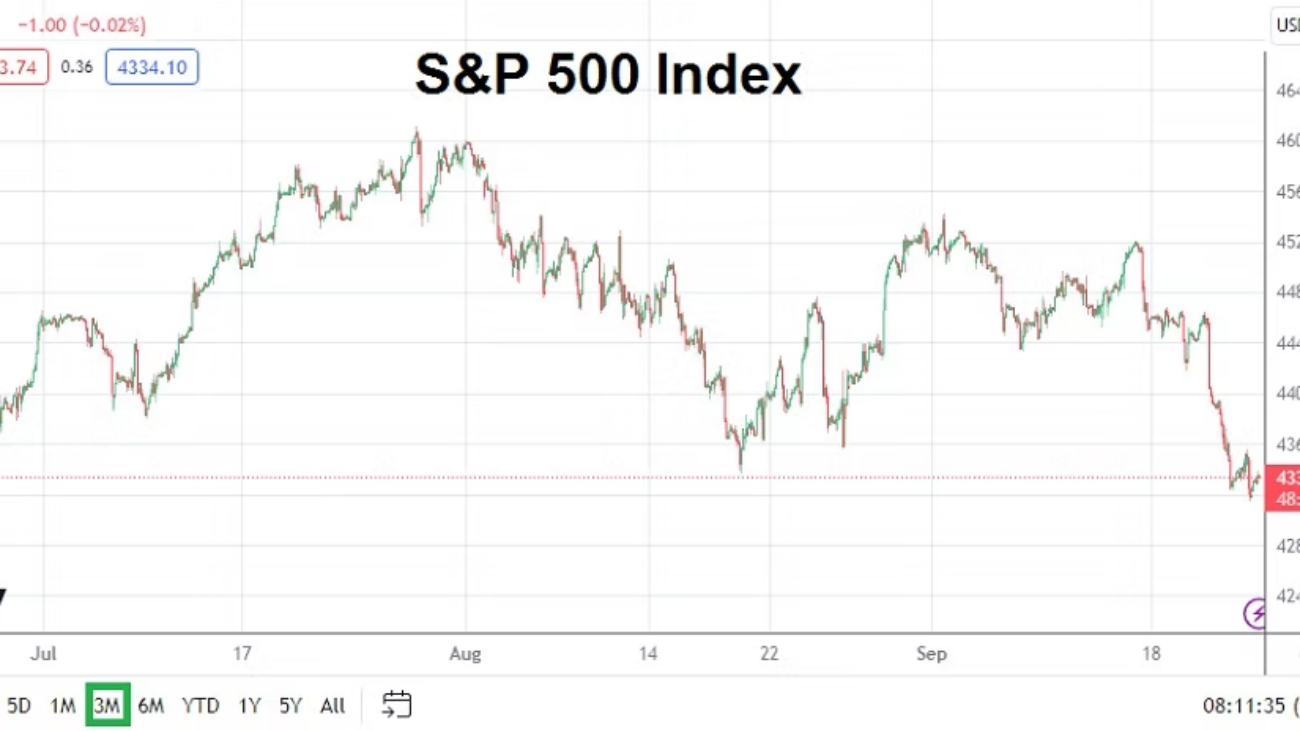
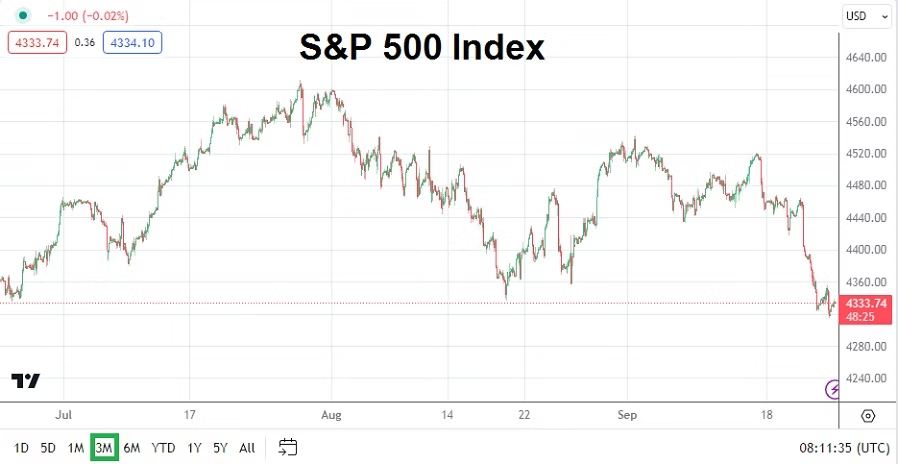
SP 500 Index Three Month Chart as of 25th of Sept. 2023

U.S equity indices have struggled recently and this should be viewed as a barometer of current behavioral sentiment. Concerns regarding higher Crude Oil prices, and talk of a growing U.S political crisis as a government shutdown is threatened (remember next year’s election is shadowing all spectacles in Washington D.C presently) highlight the nervous state of affairs. The USD has been stronger and gold has remained under pressure in recent trading. Risk adverse trading is proving rather flavorful for the moment.

The ongoing strong rhetoric from the U.S Federal Reserve and what appears to be an almost certain interest rate hike in November is causing market sentiment to remain anxious. Financial institutions are not only lining up to buy U.S Treasuries, but money market funds are also being sought too which offer the ability to accumulate returns from higher interest rates. While cash is being parked in ‘sure things’ because financial institutions and large investors are keen on locking in ‘known’ returns (profits), this creates potentially less money supply for buying of U.S and global equities momentarily.

Troubling economic data continues to mire the terrain also for financial institutions, and the heightened fear is causing a reaction which day traders need to deal with as short-term volatility mounts creating dangerous speculative conditions. Consumers face a rather large bag of ‘troubles’ via higher mortgages, debt obligations on credit cards and student loans, and inflation costs. Yet, intriguingly the U.S economy has shown resilience which is almost perplexing.

Current behavioral sentiment appears fragile and ready to crack open into a chaotic storm if too much pressure is exerted. Day traders should be cautious this week because plenty of diatribes and warnings are sure to be heard. Unfortunately the warnings being heard now for this coming week could prove correct.

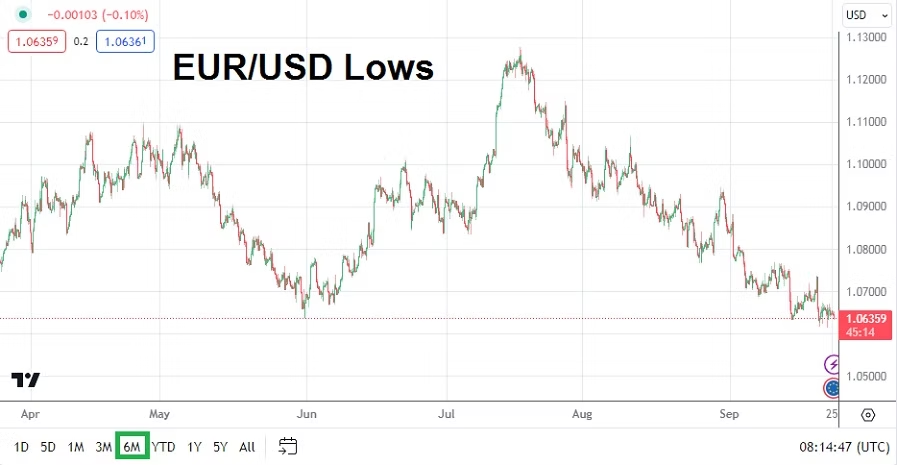
EUR/USD Six Month Chart as of 25th Sept. 2023

Monday, 25th September, Germany Business Climate via Ifo – investors will keep their eyes on the sentiment reading from Germany which is expected to be worse than last month’s results. The EUR/USD is trading at six month lows.

Tuesday, 26th September, U.S CB Consumer Confidence – the result is anticipated to be slightly negative compared to last month’s outcome. U.S consumers have remained strong and financial institutions will want to see if they remain optimistic regarding their outlooks. The outcome could affect the USD, particularly if the number is weaker than expected.

Wednesday, 27th September, U.S Durable Goods Orders – this report could prove noteworthy via the broad and core reports. Durable Goods Orders are a relatively important barometer on U.S big ticket spending and demand. The numbers are likely to cause a rumble in U.S equity markets.

Thursday, 28th September, Germany CPI – the inflation results will be watched carefully by EUR/USD speculators. Higher prices in Germany are not welcome and a larger number than anticipated would be troubling.

Thursday, 28th September, U.S GDP – the Gross Domestic Product data from the States on Thursday will be closely monitored and likely provide impetus for Forex and major indices. If the growth numbers are stronger than expected this will serve as another nail for the U.S Federal Reserve to hit when it makes its case for another interest rate hike. While it is good the U.S economic growth numbers have been relatively strong, better than expected data could play into U.S Treasury yields remaining high and spark additional complex considerations for investors.

Friday, 29th September, Canada GDP – the data from Canada is expecting a negative ‘growth’ result which would have an affect on the USD/CAD.

Friday, 29th September, U.S University of Michigan Consumer Sentiment – the revised numbers will give insights into American spending habits. The previous two months have been more lower than anticipated, this outcome is expected to produce a reading of 67.7.

Saturday, 30th September, China Manufacturing PMI – while the Purchasing Managers Index reports from China are forecast to show slight improvements, analysts remain worried about economic conditions in the nation. Transparency remains a focal point for investors who want to make sure the results they are being given are accurate.

postN56

Wednesday Federal Reserve Prediction and Central Bank Unity

Wednesday Federal Reserve Prediction and Central Bank Unity

Later today the Federal Reserve will release its Federal Funds Rate and FOMC Statement. Jerome Powell will also field questions. My prediction regarding the Fed today is that the Federal Reserve will hold (pause). It will say inflation remains problematic and stubborn, and the Fed continues to monitor economic conditions it finds complex. The high costs of energy (Crude Oil) will be presented as part of the problem.

The Fed will say they will strongly consider an interest rate hike next month, thus bracing the markets for what financial institutions have already traded into the system. This because trading houses have listened to the Fed already and believed that a pause would be seen for a few months, but cracks in sentiment quickly appeared in mid-July because of the Fed’s cloudy rhetoric as it spoke out of both sides of its mouth. Ratings downgrades and worries began, the USD sprung to significant values, higher U.S Treasury yields have flourished and increased fears for the long-term investment world. All the noise has certainly helped doomsayers.

The problem for the Fed and they should be aware of this, is that their interest rate hike threats have little direct affect on the price of Crude Oil. The rise in oil prices is directly due to Saudi Arabia cutting back on production. The U.S has much less influence on Saudi Arabia then it would like to believe it does. The Saudi Arabia government is interested in sustaining a profitable price for the commodity. At 90.00 USD per barrel, Saudi Arabia is making significant profit, but under 80.00 USD per barrel they grow concerned. After all someone has to pay for the ‘Line’ project of Neom.

Getting back on point, if the Fed is so intent on raising rates they should do so now. Not next month. But as the Federal Reserve and other major central banks often demonstrate, they are reactive – not proactive. Meaning if the Fed has no direct influence on the high price of energy that they should go ahead now and influence the marketplace instead of rattling a sword which only creates nervous global behavioral sentiment.

And yes, a hike of the Federal Funds Rate would be problematic for credit and cash reserves of consumers and businesses, which face more expensive obligations regarding loans and bonds. However, if you are merely going to threaten to do something, why not do it now and say without a doubt – like the ECB did last week – this will be our last hike for the foreseeable future. But the Fed is likely to prove they have limited desire to act swiftly and try to remain painfully polite, very much like when they refused to acknowledge inflation was a real threat when it started in earnest over two years ago.

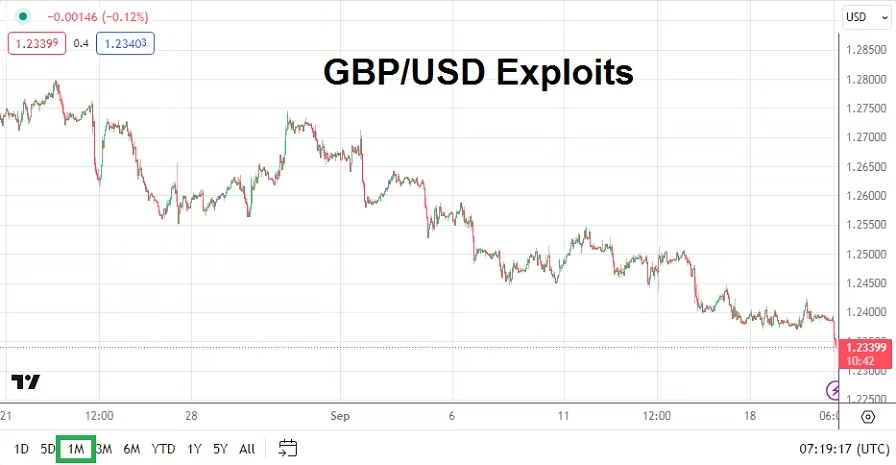
GBP/USD One Month Chart as of 20th Sept. 2023

Lastly, the Bank of England will make their pronouncements tomorrow, and some are suggesting the BoE because of today’s ‘weaker’ inflation results will not raise the Official Bank Rate. However, I disagree, inflation is still high in the U.K and the Bank of England may also feel it has to protect GBP value.

Last week’s interest rate hike from the European Central Bank, which I didn’t believe would happen and was wrong about, suggests the BoE and ECB may have privy knowledge regarding the Fed’s inner thinking. It is quite possible the European’s raised rates last week not only to fight inflation, but because they had been warned by the Federal Reserve that the U.S central bank wants to ‘sound’ aggressive. There is reason to believe if the Fed doesn’t raise tonight, but groans on about a complex economy and stubborn inflation and the need to consider raising rates next month, the BoE will feel very compelled to still hike the Official Bank Rate by a quarter of a point tomorrow.

Nothing quite like coordinated banter between the major central banks which have already demonstrated a rather stark level of mistakes over the past two years. Why not add onto the shenanigans today and tomorrow? Good luck to us all.

postN54.2

Last Week Caught Many by Surprise, as Fed Looms Wednesday

Last Week Caught Many by Surprise, as Fed Looms Wednesday

The ECB obviously decided to highlight how seriously they want to fight inflation last Thursday, when they increased their Main Refinancing Rate by a quarter of a point. The move was not only a surprise to many financial institutions, but displayed a large ‘miss’ by most analysts. While some point out the European Central Bank is powered by Germany who have a historically bad memory regarding inflation, it would also be correct to acknowledge the ECB is trying to protect their own currency against the potential volatility the Federal Reserve could cause with a rather aggressive monetary policy stance this coming Wednesday.

WTI Crude Oil One Month Chart as 18th Sept. 2023

Another broad market influence as this week begins remains the high price of Crude Oil which has now surpassed 90.00 USD per barrel. The higher energy price will certainly not calm inflation anxiousness. Higher energy costs equate into costlier logistics, manufacturing, and agricultural production – this is not a problem central banks wished upon their plates as the final quarter of 2023 gets set to start in a couple of weeks.

Monday, 18th of September, Canada Housing Starts – the housing market in Canada is important to its economy and the nation has enjoyed a housing price bubble for a couple of decades. The past two months have produced higher than expected Housing Starts numbers which is intriguing because Canada is suffering from lackluster growth. The USD/CAD could move slightly on this result, but unless there is a profoundly surprising number from this report, the currency pair will remain focused on ‘other’ things to come.

Tuesday, 19th of September, Canada Consumer Price Index – last week’s CPI and PPI numbers from the U.S came in stronger than anticipated, and Canada’s projected estimates for Tuesday’s results nearly match the nation’s total from last month. Leaving the suspicious notion that inflation could possibly come in stronger in Canada like it did in the U.S last week since these two economies often mirror each other.

Wednesday, 20th of September, China One and Five Year Loan Prime Rates – China continues to be watched closely as investors point out potential dark shadows creating headwinds for the nation economically. The results regarding the loans taken by household and businesses are a solid barometer for outlook if the data is transparent.

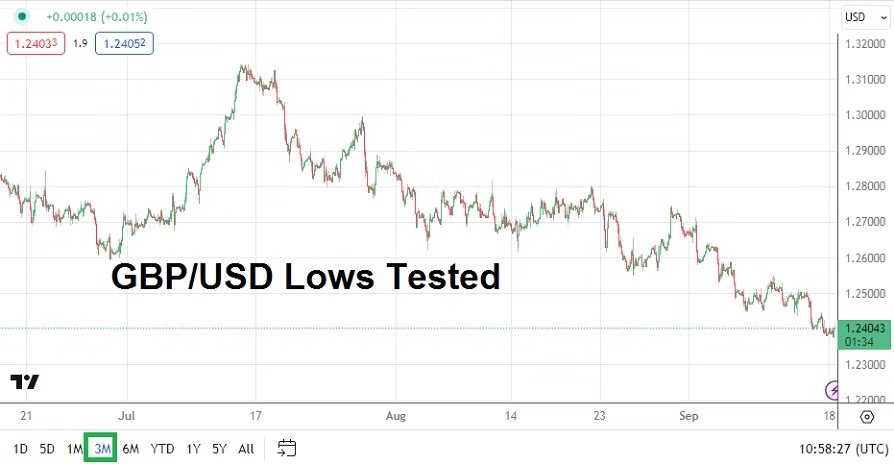
GBP/USD 3 Months Chart as of 18th Sept. 2023

Wednesday, 20th of September, U.K Consumer Price Index – the anticipated numbers expects an inflation result of 7.1%, which would be remarkably high and not treated kindly. The results will create havoc in the GBP/USD because not only is the Fed is waiting literally in the wings after this report, but the BoE is going to respond on Thursday.

Wednesday, 20th of September, U.S Federal Reserve Funds Rate – one week ago this day didn’t look like it would cause that much excitement. This all changed last Thursday when the ECB raised its borrowing costs and put financial institutions into a full state of alarm. Yes, the ECB may have acted on its own, but some suspect they know what the Fed is planning on doing already. The Fed is not expected to raise interest rates, but they will certainly sound aggressive and point out inflation remains a danger. Here’s the thing, the ECB sounded quite confident last Thursday, that it will not raise its interest rates again in the mid-term, essentially saying they were done. Did the ECB base this on knowledge that the Fed could do the same thing? What was perceived as a potentially sleepy and quiet Fed meeting and FOMC Statement has now taken on major importance. Forex, U.S Treasuries and global equities will move based on the Federal Reserve’s action and rhetoric. How will the Fed react to higher inflation data?

Thursday, 21st of September, U.K Bank of England Official Bank Rate – the BoE is widely expected to raise the borrowing rate by a quarter of a point. If the Fed did not raise rates the day before and the BoE acts as expected, this could in theory help the GBP/USD gain. However, it should be pointed out following the ECB’s interest rate hike last week, the EUR/USD traded into this past weekend weaker.

Friday, 22nd of September, E.U, U.K and U.S Services and Manufacturers PMI – Europe, Great Britain and the U.S will all release this data on Friday and all expect rather lackluster results. While this data is important, the broad financial markets will likely still be reacting to the actions of the major central banks and the credit crunch problems they are causing globally for consumers and businesses who are facing cash shortfalls and costlier loan expenditures.

postN44.1

Dog Days of Summer and a Return of Calm as Storms Threaten

Dog Days of Summer and a Return of Calm as Storms Threaten

With essentially two full weeks of trading until the end of August and the unofficial end of summer in sight, perhaps this week may be a good time for retail traders to be observers if they do not have the stomach for potentially noisy speeches and markets.

However, speculators who can block out media hyperbole and microphone soundbites from folks standing on podiums may find conditions rather attractive. As always outlook depends on perspective, time frames and managing risk. Behavioral sentiment has been rather chaotic the past month and some traders may suspect we are approaching the end of the loud spectacles of nervous drama in the markets.

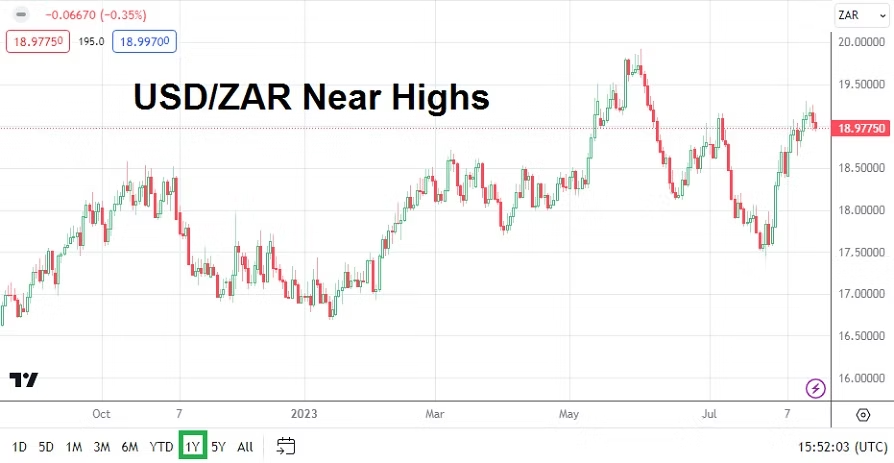
USD/ZAR One Year Chart as of 20th August 2023

The economic data this coming week should prove to be a rather mild schedule, but outside influences will certainly get publicity and get fanfare from talking heads who want 15 minutes of your attention. The BRICS Summit will get underway in Johannesburg, South Africa officially on the 22nd. Another big conference later this week will be the U.S Federal Reserve’s Jackson Hole Symposium. Both events will produce plenty of conversations about inflation, economic stability and a more cohesive global cooperation monetarily. This will also create many raised eyebrows among traders who are skeptical about these type of events.

While leaders of China, Russia, India, Brasil and South Africa get together in Johannesburg, it is likely we will hear talk about potential BRICS expansion and the pursuit of a new unified currency which doesn’t rely upon the USD. However, in the background there is likely to be plenty of distraction because of China’s faltering economic data and Russia’s Ruble which has been impacted severely in the past month. Plenty of large rugs will be needed to hide the dust which threatens to make this BRICS event rather memorable.

Add the ongoing saga of Niger and the absence of a political solution for the world’s fourth largest producer of uranium as a potential flash point standing on the side of the stage waiting to make an appearance regarding Africa news. Perhaps it is too cynical to wonder if coordinated military action within Niger will await the end of the BRICS Summit. This so China and Russia are not given an opportunity on the ‘world stage’ as a united voice to offer their opinions regarding an intervention.

The Jackson Hole get together of global central bankers from the Fed, BoE, ECB, BoJ and others will certainly grab headlines late this week, but the script is mostly known regarding the rhetoric to come from the Federal Reserve’s annual event. Forex may move based on comments from the central bank chiefs as they speak towards the end of this week, but it is unlikely anything surprising is going to be heard. U.S Treasuries will remain a topic because of the ability to lock in a solid return over the mid-term compared to betting on the outcomes of the stock market, but this scenario has been playing out the past month. Investors should prepare for a long line of speeches regarding economic outlooks from central bank officials all week. Day traders should also remember that the chatter starts to be ‘tuned out’ as the speeches grow longer.

Traders looking for other outside influences may want to look at the cryptocurrency market where major assets have shown signs of struggling. Bitcoin and Binance coin could remain in the headlines for all the wrong reasons, if their prices continue to challenge important support levels and become more vulnerable.

Monday, 21st August, China Prime Rates – economic data from the nation has caused concerns that real estate problems are spilling over into the domestic consumer market. The interest rates China lends money to consumers is expected to be lowered to try and spark spending. Recent economic reports from China have been bad, and readers who believe this is merely ‘Western’ bias being reported should be careful to look for other sources to confirm data. Investment within the second biggest economy of the world has become tentative, because there is a fear the ‘official’ China numbers may be worse than those being reported.

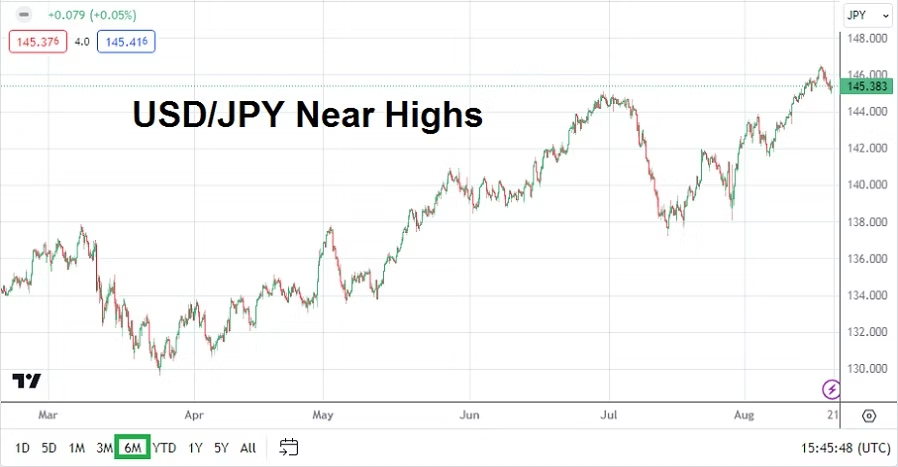
USD/JPY Six Months Chart as of 20th August 2023

Tuesday, 22nd August, Japan Consumer Price Index – the Bank of Japan report is expected to show a slight decline to the inflation numbers. Last month’s outcome of 3.0% is expected to lower and produce a 2.9% result. The USD/JPY could react momentarily to the outcome, the currency pair is near highs it hasn’t touched since November 2022.

Tuesday, 22nd August, U.S Existing Home Sales – the data is expected to show a slight decline of purchases. Mortgage prices continue to climb in the U.S and homeowners are less likely to desire taking on a new higher mortgage, this if they already have a lower mortgage locked in from a few years ago within a dwelling they already live.

Wednesday, 23rd August, Flash European Manufacturing and Services PMI – the reports will come from the E.U and U.K. The German and British outcomes will stir the Forex markets. The manufacturing data from Germany and Britain are forecast to be slightly negative.

Wednesday, 23rd of August, U.S Flash Manufacturing and Services PMI – the U.S reports are expected to show a decline in the manufacturing sector. If a negative result materializes, this could actually spark a selloff of the USD – if the financial markets have returned to calm waters by the middle of this week. Weaker numbers might be interpreted as another reason for the U.S Federal Reserve to remain neutral and why they should consider becoming dovish over the mid-term.

Thursday, 24th of August, U.S Durable Goods Orders – the core and broad numbers are anticipated to show declines. If the Durable Goods Orders numbers are worse than expected this could spark more USD selling, particularly if financial institutions are already calm and feel the data is another step to ‘lowering’ the Fed’s hawkish interest rate rhetoric. However, for the USD to weaken the markets will likely have needed to be tranquil beforehand, without major surprises having happened earlier in the week that may have escalated nervous behavioral sentiment in the broad markets.

Friday, 25th of August, Germany Business Climate and GDP – the ifo Business Climate report comes from a composite of manufacturers, wholesalers, and other enterprises and is expected to be lower than last month’s outcome. The Gross Domestic Product results are anticipated to show no changes, which would mean Germany’s economy remains in the doldrums and is flirting with recessionary pressures.

Friday, 25th of August, U.S University of Michigan Consumer Sentiment – this revised reading is expected to show U.S consumers remain steady without significant changes compared to the previous outcome.

postN34

USD/INR: Consolidation Might Come to an Abrupt Conclusion

USD/INR: Consolidation Might Come to an Abrupt Conclusion

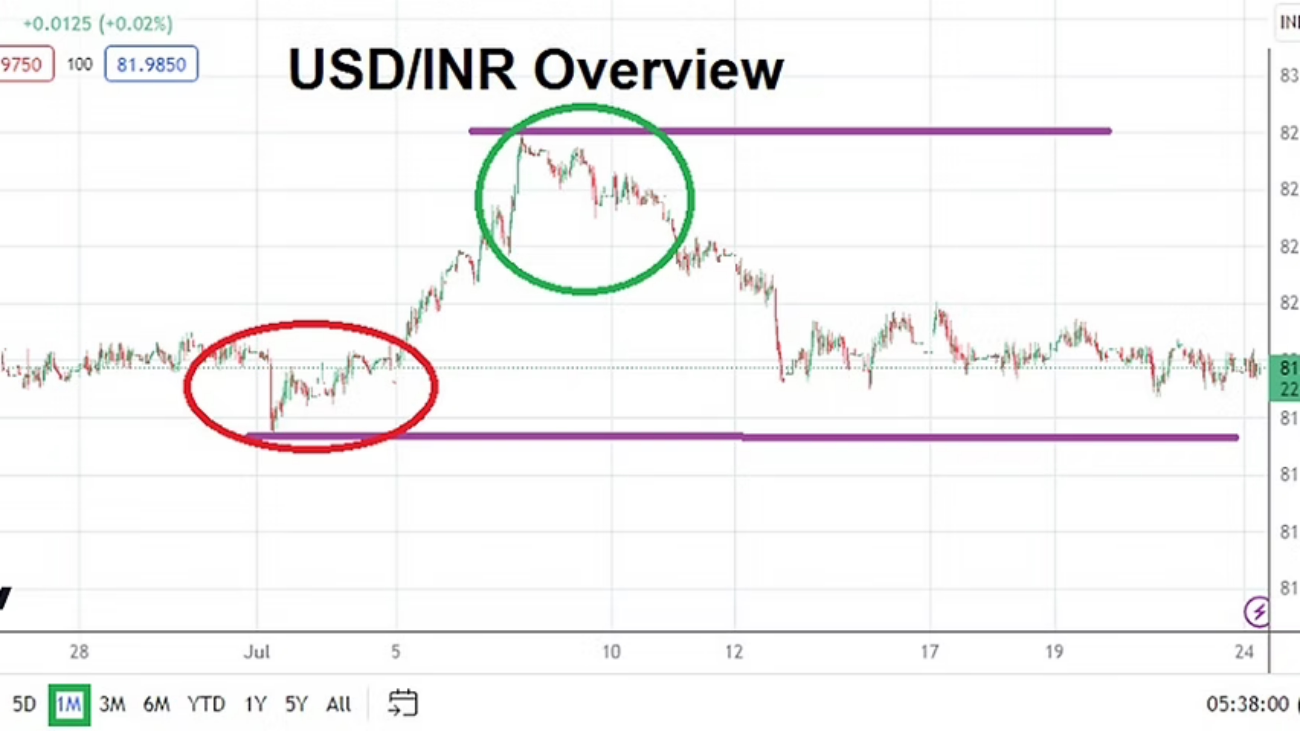
The USD/INR is trading near the 81.9750 ratio as of this writing and its price action since the 13th of July has produced a tight price range. On the 12th of July the USD/INR was trading around the 82.3000 region, this after being able to incrementally decline when a high of nearly 82.7900 was reached on the 6th of July.

Prior to the apex value of July, the USD/INR had traded in a rather consolidated mode from the middle of June until the first few days of July, essentially within a price realm the currency pair now lingers. Speculators must constantly fight the slightest of reversals if they are using too much leverage, but the USD/INR over the mid-term has produced interesting behavioral sentiment and this can be seen on technical charts.

While day traders may believe the current price ratios will hold and the potential interest rate hike from the U.S Federal Reserve has been digested into the USD/INR for this coming Wednesday, they might want to reconsider their thinking. No, the world is not coming to an end, Forex has dealt with U.S central bank decisions before and experienced traders understand the sudden potential of the USD/INR changing direction. The rather tight price range of the USD/INR could vanish in the coming days if the Federal Reserve begins to change their tone within the FOMC Statements.

USD/INR One Month Chart as of 24th July 2023

U.S Federal Reserve is Likely to Raise the Federal Funds Rate but Perhaps Shouldn’t

The USD/INR may not get hit too hard when the U.S Federal Reserve delivers the anticipated 0.25% addition to the Federal Funds Rate. However, the FOMC Statement which talks about the Fed’s outlook might cause a change to what have been calm seas recently in the USD/INR. Recent U.S economic data has been rather troubling, but inflation does actually seem to be creeping lower. The Fed has been pretty adamant in their recent ‘whispering’ about raising interest rates in July, and the potential of raising again later this year.

Time for the U.S Federal Reserve to Start Sounding Dovish

Yet, recent data suggests the Fed should likely not even raise rates on the 26th of July and continue its pause. But having expressed plenty of verbiage on the subject, the Fed may not want to surprise financial institutions and may have to raise, even if they do not really have to this week. And here is where it gets interesting – the FOMC Statement may have to express this notion of becoming more dovish. Think of this potential hike to the Federal Funds Rate this week as the last dose of medicine for a patient who already feels better, the doctor (the Fed) is insisting that to make sure the ‘sick’ is cured another teaspoon consisting of an interest rate hike is necessary.

If the FOMC Statement sounds more dovish than expected the USD/INR might start to see selling ignite and a downturn generate. There are no guarantees and certainly the Fed’s actions this coming Wednesday are not known. Yet, if the Fed hints that it will not raise interest rates over the mid-term and wants to see if inflation continues to lower that it may consider the potential of no more hikes, the USD will start to get weaker across the board. In other words, this last dose of medicine from the Fed may give them the feeling to tell the patient (U.S economy) that they no longer need to visit the doctor’s office for a while.

Other central banks are watching too. Inflation in Europe and elsewhere remains high. The complications of weaker domestic currencies against the USD have hit many economies including India where inflation has been rather strong. If the Fed can now start to become less aggressive, the effect will be quick and start helping the USD/INR trade lower if healthy economic mechanics allow this to happen.

Support levels for the USD/INR near 81.8000 to 81.7500 should be watched, if these levels begin to see challenges and sustained prices remain nearby, the USD/INR may be signaling that another downturn is about to happen. If the U.S Fed delivers a cautious, but more optimistic FOMC Statement this coming Wednesday, the USD/INR may deliver a new cycle of selling.

postN28

Week Ahead: Inflation will be the Crucial Word for Investors

Week Ahead: Inflation will be the Crucial Word for Investors

Last week finished with another reminder that inflation cannot be easily scoffed at by investors who continue to believe higher prices will eventually slowdown. Average Hourly Earnings last Friday came in above the expectation and this was enough to rattle Wall Street again, which saw the major equity indices decline and bond yields incrementally rise. Inflation ‘talk’ will remain important this week because of coming U.S data.

Real Estate including REITS becoming a Topic of Discussion as Mortgages Rise

Market watchers should also pay attention to news regarding mortgages on residential homes, and listen for troubles from the commercial real estate market, as these sectors deal with rising interest rates in the U.S and U.K. Increased nervousness within these markets could have an affect on behavioral sentiment. Let’s remember the catalyst for the financial crisis of 2007 was the real estate sector.

Which brings us back to inflation and the growing acceptance among investors the U.S Federal Reserve may be ‘forced’ to hike the Federal Funds Rate on the 26th of July, if price data continues to come in ‘hot’. Some investors will likely be heard saying an increase of 0.25% has already been factored into marketplace, but the prospect of another hike in late 2023 could be problematic. Forex, gold and bonds dynamics will tell us a lot when this week concludes regarding outlooks.

BNB/USD Price Should be Monitored as Binance Trembles

An outside source of financial and speculative news is likely to come from cryptocurrency. If you are gambling on this asset class (or should we say commodity based on hot air) and like the adventure of wagering, please continue to pay attention to Binance which is showing signs of duress. If the Binance cryptocurrency exchange shows additional signs of pressure on its BNB (Binance Coin), trading waters within the world of crypto could trigger additional drowning victims. If you thought the Sam Bankman-Fried story made interesting news last year regarding fraud and other criminal activity, the FTX saga could prove to be only the tip of the iceberg.

Data Events Ahead to Watch

Monday, 10th of July, China CPI and PPI – the inflation data could prove important for investors who correlate economic statistics from China into their global forecasts. Traders within India should pay attention to these Chinese price reports, because global investors are starting to shift their assets into the Nifty 50 and other NSE equities because of risk and reward equations.

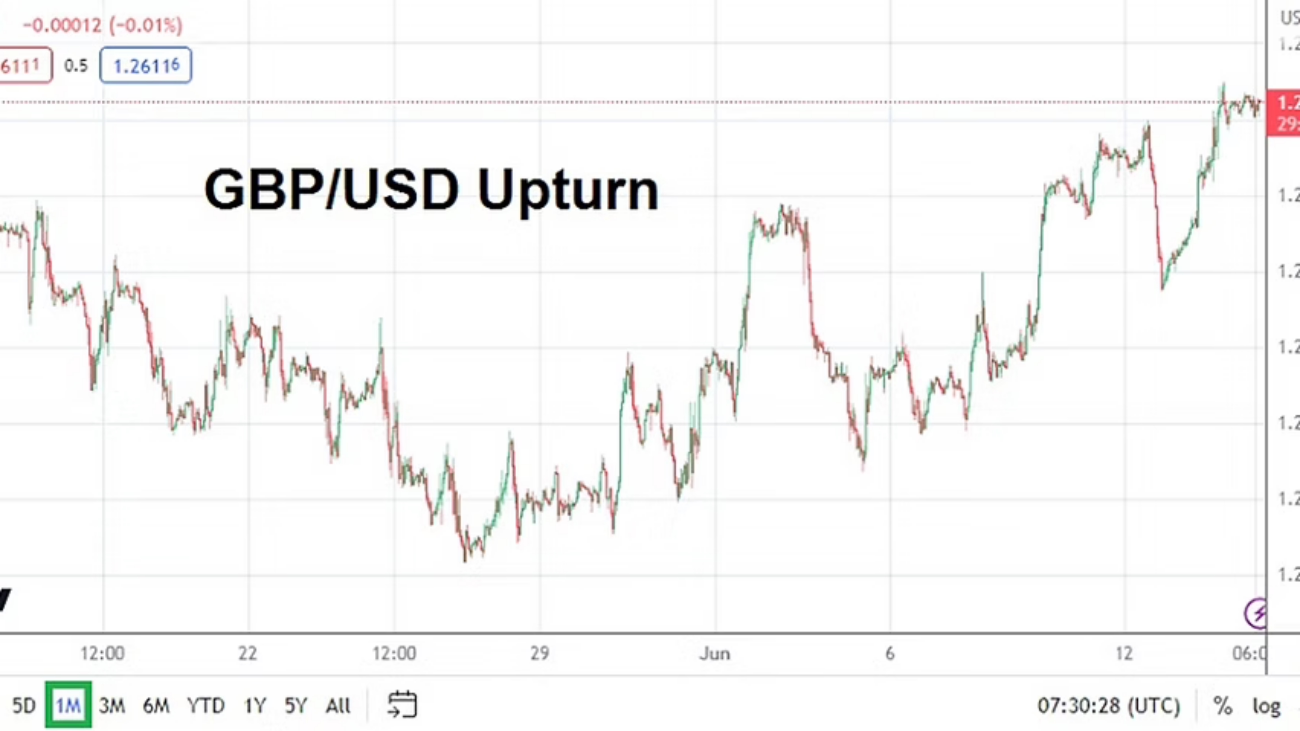
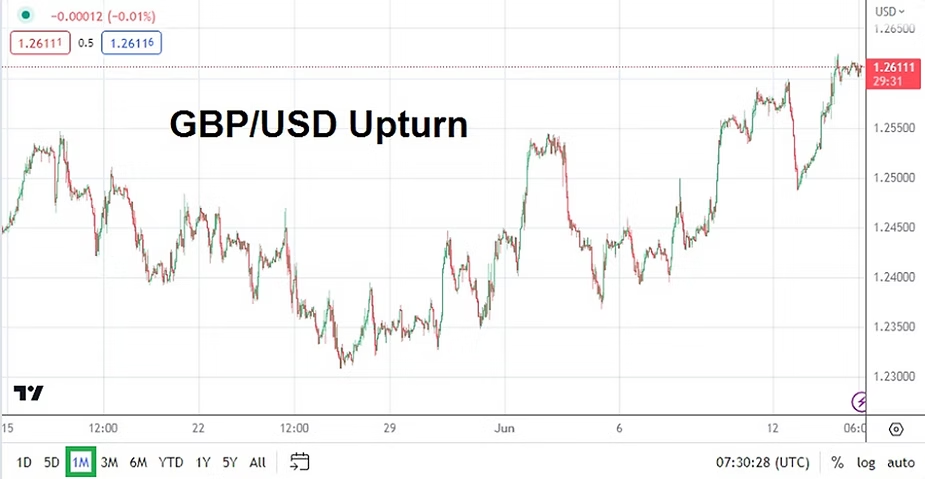
GBP/USD One Month Chart as of 9th July 2023

Tuesday, 11th of July, U.K Claimant Count Change and Average Earnings Index – the numbers need to be watched by GBP/USD speculators. The results from the U.K will be intriguing because of employment results, but more importantly for inflation concerns and the knock-on effects. Bank of England Governor Andrew Bailey is speaking a few times this week, and this includes Wednesday the 12th of July, when he will talk about the Financial Stability Report. The GBP/USD has moved towards monthly highs recently.

Wednesday, 12th of July, New Zealand RBNZ Official Bank Rate – NZD/USD day traders will want to pay attention to the central bank’s Rate Statement. While no increase of interest rates is predicted, the Reserve Bank of New Zealand at a minimum will likely have to admit inflation remains a concern.

Wednesday, 12th of July, U.S Consumer Price Index – the inflation reports from the States will have all eyes on the outcomes of the monthly and annual comparisons, including the Core numbers. The results from these inflation statistics will certainly cause momentary volatility within Forex with the USD as the focal point.

Wednesday, 12th of July, Canada BoC Overnight Rate – the Bank of Canada is expected to hike its interest rate by 0.25% to the 5.00% mark. USD/CAD will react to the BoC Rate Statement based on its outlook.

Thursday, 13th of July, U.K Gross Domestic Product – the ‘growth’ numbers are not expected to be positive. A drop of minus -0.3% is the expectation. Talk of recessionary pressures in Great Britain will be heard. Unfortunately, the discussion about a struggling economy, mixed with stubborn higher prices for consumers and mortgage rates that are rising will not make for calm stomachs. U.K equity results via the FTSE 100 Index should be monitored.

Thursday, 13th of July, U.S PPI – the Producer Price Index figures will be the last cog within the important inflation data for the week. Stubborn prices for wholesale goods are a concern, because the costs to consumers becomes more expensive when there are higher price pressures.

Friday, 14th of July, U.S Consumer Sentiment via the University of Michigan – if the Consumer Sentiment readings from the UofM report improves, and the U.S inflation data which was released earlier this week has proven stubborn, this could become a source of pain for investors who may be forced to consider the Fed will not only raise the Federal Funds Rate late July, but later in 2023 also. Short-term traders should monitor this report accordingly.

postN27.1

Risk Friday: Fear is a Terrible Thing to Waste

Risk Friday: Fear is a Terrible Thing to Waste

Behavioral sentiment in the broad markets took a turn for the worse yesterday among many major equity indices. This as financial institutions seemingly came to the short-term conclusion the Federal Reserve may actually have to raise interest rates again on the 26th of July, and possibly beyond. Meaning, the Fed might actually back up what it has been saying.

Yes, investors have been warned many times already by some analysts that the handwriting was on the wall regarding additional increases to the Federal Funds Rate, but it seems a fear of losing out has kept many market participants actively running forward with blinders on not cognizant of the Fed’s rhetoric.

Day traders should always be mindful of their emotions. While it is not good to trade based on emotions when involved in an active position, intuition and gut instinct sometimes can save you money when you decide to simply sit on the sidelines and watch the market action instead of participating. In other words, if you are nervous and your instinct is bothering you – do not attempt to enter the trade.

U.S Data Remains Rather Strong even as Inflation Boils

Yesterday’s better than expected jobs report via ADP helped create sparks early regarding U.S economic data continuing to show it is robust, but the ISM Services PMI threw gasoline onto the fire with a much better result of 53.9 compared to the estimated reading of only 51.3. While inflation simmers in the U.S, signs of limited growth abound too making stagflation a real danger.

Investors can now attain a yield around 4.995% on 2-year U.S government Treasuries. A gain of nearly 5% that is almost assured with very little costs regarding commission rates needing to be spent, looks like a solid short-term investment to many. Equity markets have a reason to feel spooked. If the U.S Fed raises the Federal Funds Rate which is now 5.25% to 5.50% at the end of July, and at the same time continues to speak in an aggressive manner about other potential hikes later this year, summer may lose its sense of tranquility for financial institutions.

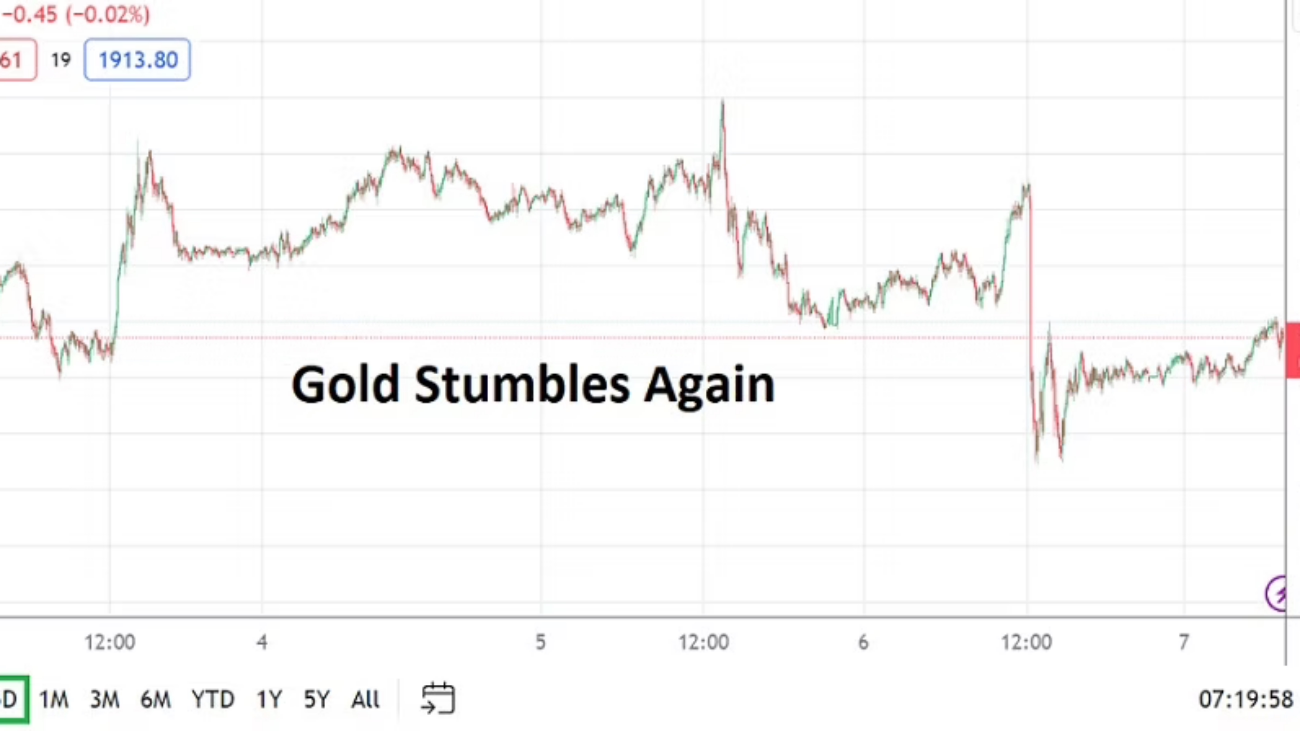
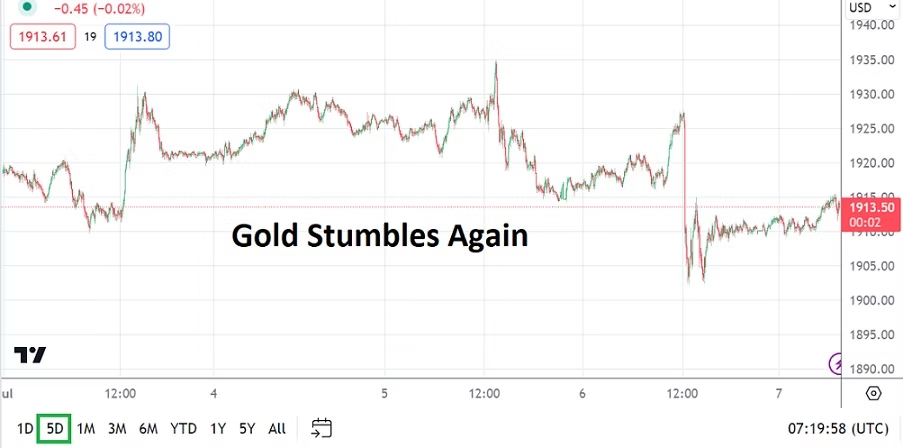
Gold Five Day Chart as of 7th July 2023

Gold which was trading at nearly 1925.00 USD yesterday, suddenly fell to around the 1900.00 briefly in the wake of the better U.S economic data, showing investors are worried the USD has some additional strength to display potentially. Again, the results of intraday gyrations may not mean a lot to mid and long-term investors, but day traders speculating on the outcome of quick hitting results frequently get hurt by the bursts of volatile storms.

U.S Official Jobs Numbers Today and Anticipation

Adding another dose of intrigue to the day are the upcoming official jobs numbers from the U.S, including the Non-Farm Employment Change and the Average Hourly Earnings reports. The inflation data via the earnings statistics are anticipated to show a gain of 0.3%, if for some reason it comes in stronger than expected this could create more fireworks. Having said that, the Wall Street Journal reported yesterday that Americans appear to have stopped quitting their jobs in order to switch to similar competitive positions as much as they had been the past couple of years. Perhaps this signals wages are starting to cool or least will in the near-term.

Let’s also remember that yesterday’s selloff in equities may have been anticipating better Non-Farm Employment Change results today based on the ADP outcome Thursday, and other solid U.S data before like last week’s GDP gains. Day traders betting on quick hitting CFDs via their brokerage platforms should be careful today and listen to news regarding the U.S bonds market. Inexperienced speculators should try to understand the adage – buy the rumor and sell the fact. Meaning ‘smart money’ often acts before others and takes advantage of their outlooks regarding data.

Quick Warning on Binance and Cryptocurrencies for Gamblers

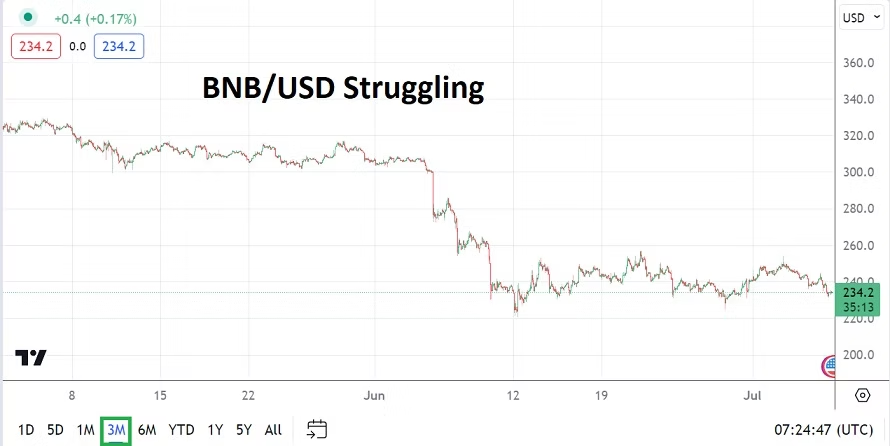
BNB/USD Three Month Chart as of 7th July 202

In a non-related subject, cryptocurrency traders seem to remain rather steady but should be nervous – if anyone is actually really trying to speculate in this endeavor besides Larry Fink of BlackRock currently, news regarding Binance remains troubling on the surface as legal clouds grow. Folks involved with the BNB coin should be careful. As one of the most ‘important’ crypto exchanges Binance’s legal problems moving forward could affect the prices of cryptocurrencies significantly. As of this writing BNB/USD is at nearly 233.00, and it should be noted Tether’s USDT appears to remain rather solid for the moment at 1.00. A look at the current three month chart of BNB/USD highlights its latest value struggles.

postN24

Interest Rates, Fireworks, OPEC, Fed Minutes, and Jobs Data

Interest Rates, Fireworks, OPEC, Fed Minutes, and Jobs Data

Global day traders will certainly be able to work early this week, but they should note the 4th of July holiday in the U.S will deliver rather light volumes Monday and Tuesday. Markets in the U.S will be open on the 3rd, but speculators need to understand that price action may be flat and then experience sudden bursts of energy. Financial institutions in the U.S could be rather quiet until Wednesday.

Monday, the 3rd of July, European Manufacturing PMI – data will come from across Europe and is expected to show the sector remains rather lackluster. France, Germany, the U.K and others will issue reports.

Monday, the 3rd of July, U.S Manufacturing PMI via the ISM – the Purchasing Managers Index numbers are expected to produce a slight rise, but remain under the level of 50. However, any increase compared to last month’s outcome will be an additional sign the U.S economy is battling on and would give the U.S Federal Reserve another reason to lean towards an interest rate hike later this month.

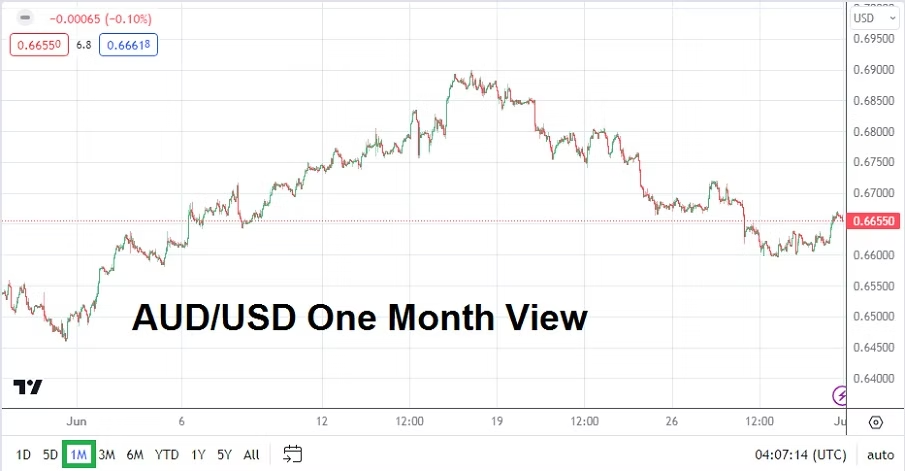
AUD/USD One Month Chart as of 2nd July 2023

Tuesday, the 4th of July, Australia RBA Cash Rate and Statement – while some analysts assume no interest rate hike will be delivered in July because the CPI has shown a slight downturn, there seems to be rather large whispers another hike of 0.25% could be added from the Reserve Bank of Australia. AUD/USD traders certainly need to pay attention, and folks with limited funds should stay on the sidelines until the decision is released.

Tuesday, the 4th of July, U.S Independence Day – banking holiday.

Wednesday, the 5th of July, China Caixin Services PMI – economic data from China has certainly shown signs of downward pressure. A slight decrease is the expected result.

Wednesday, 5th of July, OPEC Meetings – the energy cartel will be conducting its official get together in Vienna, Austria and oil traders should be on alert for any news and decisions made public that could affect the energy sector.

Wednesday, 5th of July, U.S FOMC Meeting Minutes – the publication will provide insights into the Federal Reserve’s decision to ‘pause’ interest rate hikes last month, but could also add fuel to the notion the U.S central bank remains within an aggressive stance regarding inflation. Forex markets will react to the report.

Thursday, 6th of July, U.S Services PMI via ISM – the statistics will be monitored closely due to the rather positive outcome from the GDP report last week, which showed the U.S economy remains rather resilient. A positive outcome in the Services numbers will add further evidence for the Federal Reserve to remain hawkish.

Friday, 7th of July, U.S Jobs Numbers – the employment data will culminate as the week comes to an end with the Non-Farm Employment Change and Average Hourly Earnings figures. Yes, on the day before, Thursday, traders will also see the JOLTS numbers and weekly Unemployment Claims. However, it is the Non-Farm and wages data that financial institutions will largely react upon depending on the outcomes. Because it is a ‘holiday’ week in the U.S, the reports may find a muted response, but financial institutions will use the information to gauge their mid-term outlooks and position their assets including Forex and bonds.

postN20.1

Friday Barometer Regarding the BoE Decision and Gold Prices

Friday Barometer Regarding the BoE Decision and Gold Prices

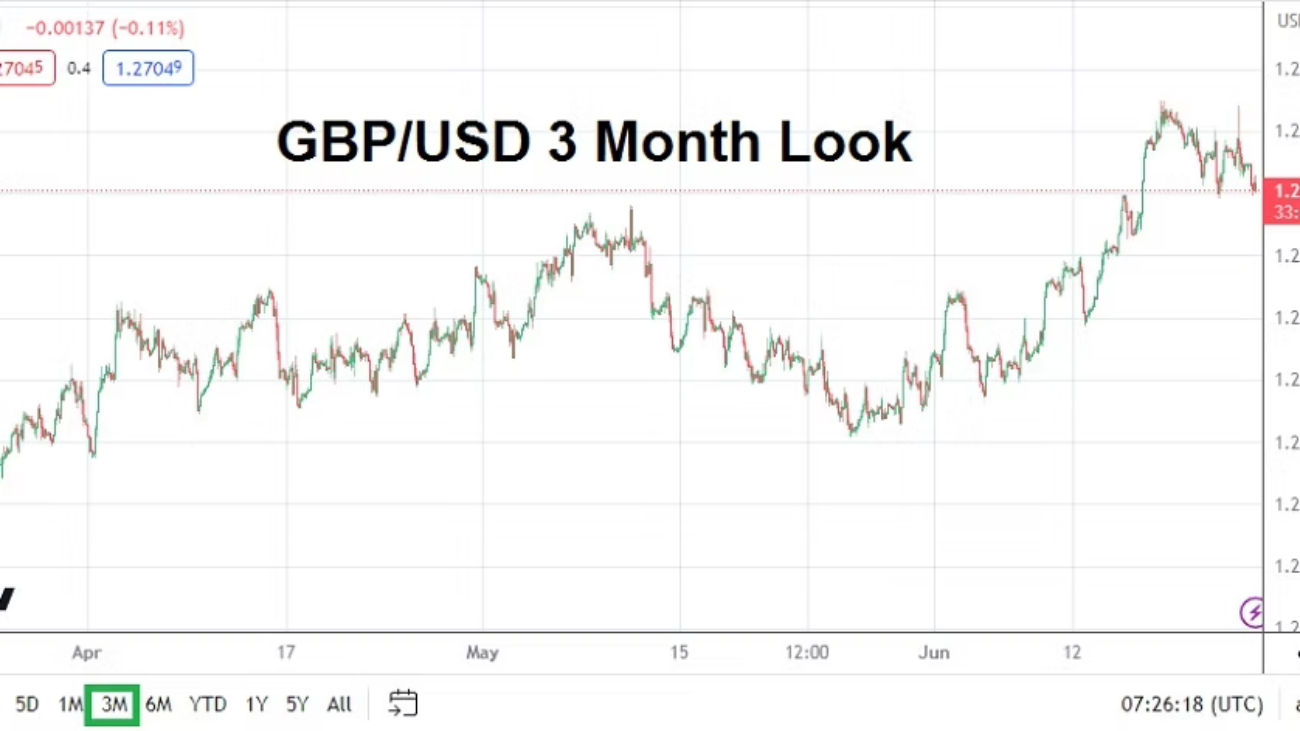
The Bank of England’s rate hike of 0.50% cements the notion that global central banks remain steadfastly locked on inflation, and understand politically the implications on the public regarding higher consumer prices which are being experienced. The Bank of England ‘met’ before its Official Bank Rate announcement with corporate bank executives it was whispered, to discuss their concerns regarding the knock on affects of higher mortgage rates to come. However, this did not stop the BoE from being aggressive.

GBP/USD Three Month Chart as of 23rd June 2023

Is the BoE Move a Sign Regarding the Fed’s Next Decision?

The move by the BoE also is intriguing because the larger than expected hike puts into play the notion the U.S Fed may be raising the Federal Funds Rate in July. The reasoning is based on the idea the Bank of England wants to protect the British Pound from another interest rate hike from the Fed, thus ‘securing’ the value of GBP/USD Forex mechanics.

The U.S Federal Reserve, the BoE and ECB finally seem to have a grasp on import inflation implications. Although higher costs and dynamic pressures on exporting countries like China, India and others that face the gauntlet of these challenges remains critical, because these nations need to raise the costs of manufactured goods internationally when they sell.

Smart Money and the Value of Gold

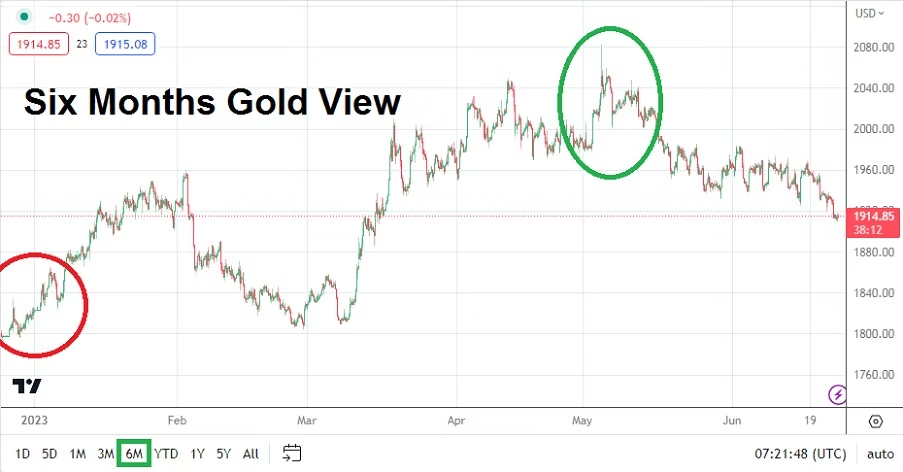
Let’s talk about ‘smart money’ for a moment surrounding Gold – and please try to hold down your laughter – but the price of the precious metal is interesting and should be monitored even by folks who do not trade the commodity. Gold as of this morning is near the 1915.00 USD ratio.

Gold Six Month Chart as of 23rd June 2022

On the 4th of May the price of the precious metal momentarily challenged the 2080.00 level. On the 1st of June the price of the commodity was near 1985.00. Do you see a trend here? Please note, Gold isn’t going to zero.

The point to be made is that the build up in the price of the precious metal from the 22nd of November 2022 when Gold was around the 1625.00 USD per ounce level, until early May anticipated the U.S Federal Reserve was going to become more dovish regarding their interest rate polkicy. For consideration look at the price of the USD during this time too, against many major currencies – the value of the USD also started to come down.

‘Smart money’ is showing signs of nervousness certainly since the start of June that more hikes are feared from the Federal Reserve. However, the price of Gold and the USD are not correlating well at this moment. This is a potential sign that Gold and the USD are both within speculative trading zones in which financial institutions are seeking ‘true’ equilibrium and are not comfortable. Fragility in the financial marketplace is likely to be seen until the Federal Reserve Federal Funds Rate announcement late in July. Expect financial institutions to price in their outlooks respectively depending on their outlooks.

Gold and U.S Treasuries: Inverted Interest Rate Implications

Gold definitely fluctuates within daily trading conditions, it is a speculative commodity, but it is also a solid barometer of risk management among the elite. If financial institutions are in favor of buying items like U.S bonds because of their guaranteed short term interest payments (look at the fact U.S Treasuries are mostly inverted – meaning shorter term bond interest rates are paying higher returns compared to longer term bonds) instead of buying Gold as an investment tool.

The Gold and USD Forex dynamics tells us that investment institutions are still very nervous about the Fed potentially raising interest rates a couple of more times this year. July and late this year appear to be reasonable bets. This Fed consideration and concern remains legitimate while looking forward as long as inflation remains elevated in the U.S. However, the Federal Reserve must also feel comfortable they will not kill mid and small sized banks, which by now should have shifted their business practices allowing for slightly higher interest rates to be delivered.

postN14.1

Anticipated Federal Reserve Shop Talk to be Delivered Today

Anticipated Federal Reserve Shop Talk to be Delivered Today

For what it’s worth, here is my prediction regarding what the Federal Reserve will do today. The Federal Funds Rate will remain unchanged in my opinion. The FOMC Statement may show that the vote actually was debated and not unanimous. The statement is likely to warn that inflation remains stubborn and potentially problematic, meaning the Federal Reserve continues to believe it may have to raise the Federal Funds Rate over the mid-term and again before the end of 2023.

The Forex market has seen the USD get weaker against many major currencies since late May. While financial institutions have seemingly positioned for no increase from the Federal Reserve today, this move has also likely been priced into Forex. Day traders need to understand institutional traders will not be betting on what took place the last three weeks, but are trying to anticipate what will happen into early July and beyond regarding their Forex positions.

GBP/USD One Month Chart as of the 14th June 2023

Many financial institutions may still be betting the Fed will remain more dovish than the U.S central bank wants to admit, but this is a dangerous perception and could prove costly. Financial institutions are concerned about the Fed because they know the central bank has painted itself into a corner it may not be able to maneuver freely within. The battle to conquer inflation while trying to fuel economic growth is not an easy one. Mixed sentiment abounds regarding the U.S economy depending on who is asked.

Talk of a soft landing and a small recession continues to be heard, this while some analysts warn about a hard drop and darker days ahead. Folks, it is all about timelines and their interpretations, experts warning about brighter or darker days ahead have a tendency to be vague regarding exact moments in time. Everyone has an opinion, and people often have more than one.

In my opinion – my one opinion, the Fed is likely to say that it is not going to raise rates today, but may have to do so in the mid-term. If these were normal times and economic conditions were not suffering from huge spending running amok in Washington and the corporate banking sector wasn’t fragile, the Fed may actually have raised the Federal Funds Rate today to continue to battle inflation deliberately. However, a pause for the moment seems like the logical choice, this while ‘hoping’ inflation continues to diminish. And hope is a key word here. Everyone seems to be hoping. The question financial houses and traders need to decide after the FOMC Statement takes place today is how seriously do they consider the Fed’s remarks.

If they believe the Fed will have to continue to remain neutral regarding its mid and long-term interest rate policy, the USD may soften and incremental selling might be demonstrated. Human instinct tends to be optimistic, which means financial institutions and maybe even the Fed wants to believe inflation will ebb lower. If this happens the USD would weaken further. However, the Fed may have to sound more aggressive than people want, but that would damper the mood of financial institutions – so look for optimistic interpretations to abound with rose colored glasses, even if they are wrong in the long-term.

Gold One Month Chart as of the 14th June 2023

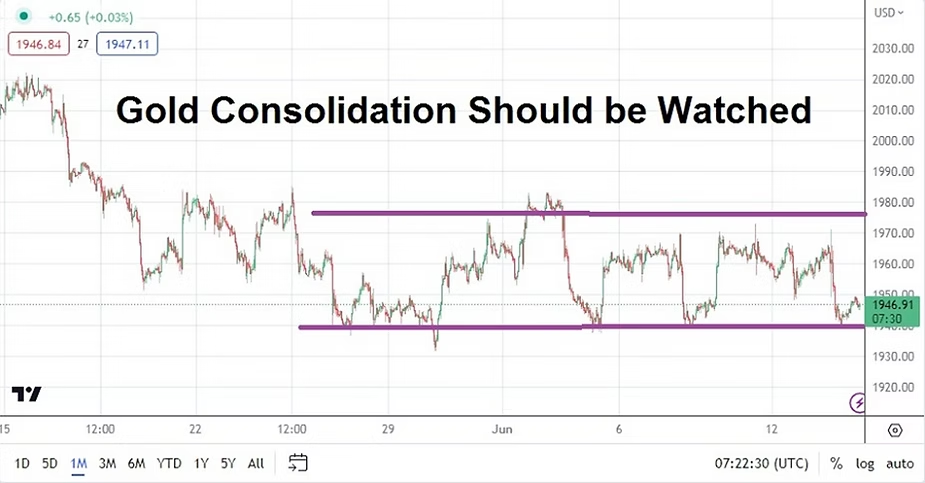
For evidence of outside barometers, traders may want to look at Gold which has essentially traded between 1940.00 and 1975.00 with a few outliers since the last week in May. The price of Gold has seemingly situated within a consolidated framework the past few weeks. The precious metal may produce a strong move if the Fed shows more dovish behavior today, particularly if financial institutions show more optimism via behavioral sentiment in Forex – meaning if a weaker USD trend continues momentarily Gold could traverse higher.

My prediction and $1.00 USD may get you on a bus. As always caution will be needed if you are trading immediately before and after the U.S Federal Reserve’s rate decision. I advise using a seat belt today consisting of entry price, stop loss and take profit orders via solid risk management, but then again these cautious attitudes should always be practiced by day traders.

post38

FOMC Meeting Minutes and Key Growth Data Coming this Week

FOMC Meeting Minutes and Key Growth Data Coming this Week

Monday the 22nd of May, Japan Core Machinery Orders – which will likely have very little impact on the markets – not even the USD/JPY should react too much. Although it should be noted last month’s figure was negative and this month’s result is expecting a better outcome.

Monday the 22nd of May, E.U Consumer Confidence – forecast to produce a negative number, but this statistic doesn’t usually get much of a response in the financial markets unless there is a shocking result.

Tuesday the 23rd of May, E.U French and German Manufacturing and Services PMI, along with the broad E.U results – the manufacturing statistics from France and Germany are expected to come in slightly better than last month’s results but remain in negative territory.

Tuesday the 23rd of May, U.K Manufacturing and Services PMI – traders will watch these results after the bad GDP numbers from Britain almost two weeks ago.

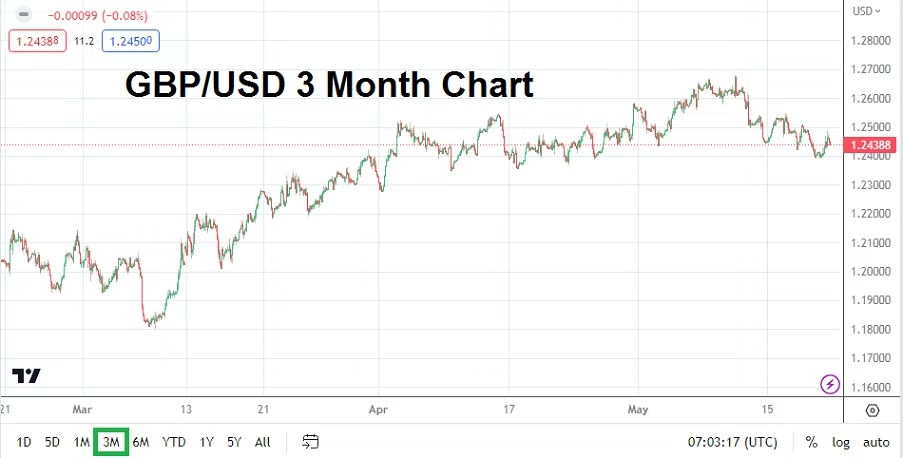
GBP/USD Three Month Chart as of 21st of May 2023

Tuesday the 23rd of May, U.S Flash Manufacturing and Services PMI – the reports could prove of interest and cause a bit of a tremor in the market, but unless there is a big surprise investors will remain cautious as they anticipate the next day’s potentially big risk events.

Wednesday the 24th of May, U.K Bank of England Governor Bailey – will be speaking at two events and could stir the GBP/USD with his comments on the British economy and inflation.

Wednesday the 24th of May, U.S Treasury Secretary Janet Yellen – will be speaking at a Wall Street Journal event, where she will be listened to for any comments on the ‘U.S debt ceiling” crisis. Yellen is a ‘trained’ speaker and she will try not to scare financial institutions who will have some leaders in attendance.

Wednesday the 24th of May, U.S FOMC Meeting Minutes – the report which will outline the U.S Federal Reserve’s thinking regarding its recent interest rate hike and what it might be considering regarding June could impact the marketplace. The report is published late in the day, but financial institutions will certainly wait for the publication and react. While the FOMC paper is sometimes considered ‘noise’, this report will be important because of the nervous sentiment which exists in markets like Forex and equity indices as they deal with a lack of clarity.

Thursday the 25th of May, U.S Preliminary Gross Domestic Product – the growth (or lack of growth) numbers from the States will be watched intently. A muted projected gain of 1.1% is anticipated by some analysts.

Thursday the 25th of May, U.S Preliminary GDP Price Index – this report will deliver insights regarding inflation in the U.S and should be given some attention by traders.

Friday the 26th of May, Core PCE Price Index – the inflation numbers should be watched. Any surprise above the anticipated 0.3% forecast could cause an affect in the financial markets.