Singapore Dollar 20260911

Conflicted Trading: Singapore Dollar and Federal Reserve Considerations

USD/SGD: Conflicting Desires From the Federal Reserve and Financial Institutions

The world of Forex is about to grow murkier in the coming days as shadows loom over financial institutions regarding their near-term decisions as they try to gain clarity regarding what appears to be confused and concerning mid-term outlooks for speculators and investors.

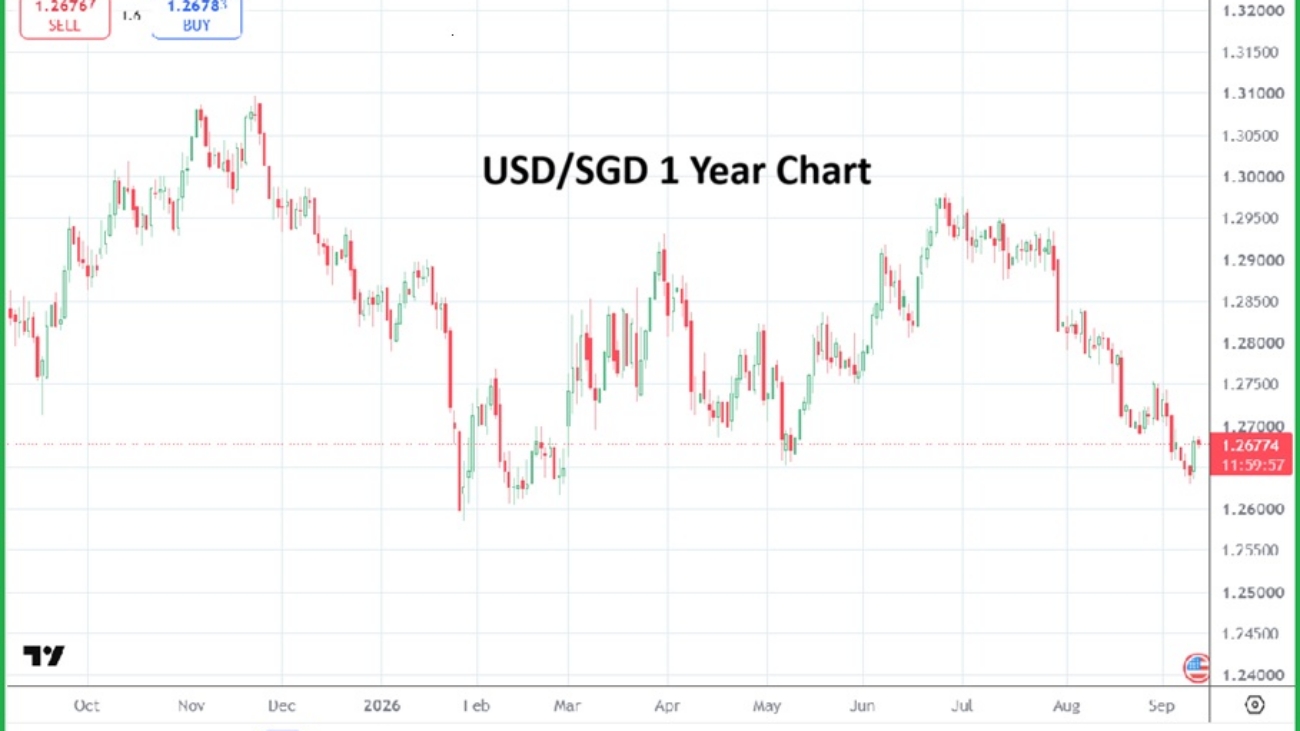
The USD/SGD is traversing near the 1.26776 vicinity as of this writing. The currency pair is trading within a long-term historical lower realm in which the 1.26000 level was challenged from mid-January until the first week of this year. This past Wednesday the USD/SGD traded near the 1.26280 mark. Previous to the current ratios and lows seen in early 2026, the Singapore Dollar traded around the 1.24475 level in June of 2014. The USD/SGD challenged 1.20000 level in early August of 2011 – yes, 25 years ago.
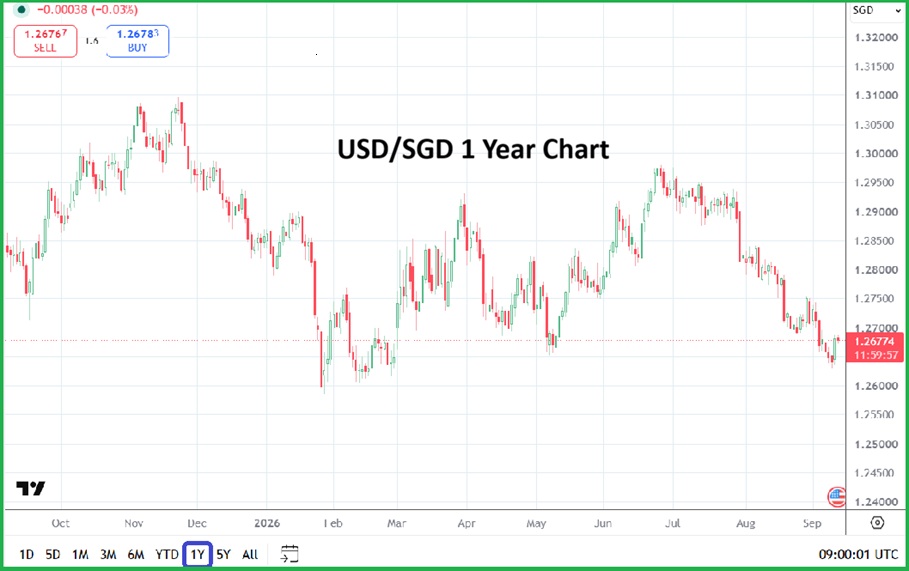
USD/SGD One Year Chart as of 11th September 2026

Here Come The Risk Events: Inflation, BRICS, Iranian War and the U.S Fed

Now that we have alerted technical traders about the long-term depths of the USD/SGD being flirted upon once again, it needs to be pointed out that a parade of risk events are standing in front of global Forex today and next week. First up today is the U.S Consumer Price Index inflation data. This weekend the 18th BRICS Summit will be conducted in New Delhi, India as geopolitics and trade talks will get plenty of attention. Next Wednesday the U.S Federal Reserve will issue its FOMC Statement and Federal Funds Rate decision – which may produce a climax for theatrical trading in the coming week.

While it feels almost needless to say, the Iranian War has not relented. The price of WTI Crude Oil is around $100.65 per the cash market. The sustained highs achieved in the past couple of days do not show many signs of suddenly relenting. WTI Crude Oil was around $86.50 around the 1st of September, the USD/SGD was near 1.27200. To create a bit more alarm regarding the risk horizon going into this weekend the U.S 10-Y Treasury yields lurk around 4.945%, the 30-Y Bond yields are close to 5.355% – none of this sits well with the U.S White House, nor Treasury. In the midst of this investment noise, the price of Gold is close to $4,345.00, which still looks cheap considering current circumstances.

Crude Oil supplies remain anxious globally and inflation is certainly causing angst for citizens and a variety of government policies. Singapore will report August inflation data on the 23rd of September, July’s inflation data came in around 2%, with energy costs being the culprit for higher prices in many cases. The USD/SGD was near 1.29500 around the 14th of July. Prices for energy have not gone lower and the likelihood of them turning cheaper soon remains unlikely.

USD/SGD Correlations and Current Sentiment

USD centric action since the first week of July has showed weakness against many major currencies including the Singapore Dollar. Let’s put the USD/JPY to the side because of the intervention via the Bank of Japan and input of the U.S Treasury and Federal Reserve collectively. The USD/SGD is correlating to the broad market. Risk averse decisions have been prevalent in stock markets. The U.S major indices while remaining near higher altitudes are showing cautious behavioral sentiment.

The USD/SGD certainly went lower in January and early February of this year, but this occurred as doses of optimism were filling the air and in the absence of the Iranian war. Yet, the downturn in the USD/SGD has been formidable since highs around 1.29900 were seen on the 24th of June. In late November of 2025 the currency pair flirted with the 1.31000 level. 

Federal Reserve and Treasury Battle with Reality

The U.S Treasury and Federal Reserve will not tell the U.S public that the USD loss of value is an invisible tax. Nor does President Trump want Crude Oil prices to remain high because Americans are certain to get angry about more expensive gasoline prices, particularly if they remain elevated after being promised costs will come down. Reality may prove painful for all parties in the coming months.

Which leaves us with the Federal Reserve’s interest rate decision this coming Wednesday and how it decides to decode the current anxious inflation concerns. Will the Fed try to explain that they still believe – due to the U.S intended Iranian war policy and its belief they will win in the coming months – that the Federal Funds Rate remains situated properly at around 3.50-3.75%? Delivering the important question regarding what exactly has been traded into the USD/SGD. Have financial institutions traded an interest rate increase into the currency pair already?

It certainly feels like long-term investors who believe the Federal Reserve will have to raise interest rates to fight against stubborn inflation have refused to buy Treasuries cheaply and thus forced yields upwards the past months. So what does the Federal Reserve do as an ‘independent’ institution knowing that U.S White House and Treasury desires may not match policy coordination? It is the 40+ trillion USD debt question.

Will Fed Chair Kevin Warsh actually dare to raise the current borrowing rates and say that it is quite possible the rate can be lowered again in the mid-term? Or does he admit that as feared by many financial institutions that two to three interest rate hikes will be needed per old school economic thoughts, which may actually make the current circumstances of average Americans much worse with higher borrowing costs created across the board as a side effect?

Fed Chairman Kevin Warsh has not exactly proven efficient while addressing journalists and Fed watchers quite yet. His speech this coming Wednesday on the 16th will be crucial for the broad markets. The USD/SGD is trading within its lower realm, but durable support technically does lurk. Jittery Forex trading awaits for all.

Will the Federal Reserve be bold enough to actually NOT increase the current Federal Funds Rate and talk about the risks to the U.S economy because of potential recession concerns; this as the mid-term elections lurk in November and President Trump watches and doesn’t want talk about a slowdown in the U.S economy heard from what he considers his administration. However, the Fed is independent and can do as it wants in theory.

At this point the Federal Reserve and Treasury should make sure the drama is coordinated because many eyes will be focused on the coming show. And the end result over the near-term will be volatile Forex and a USD/SGD that reacts with price velocity depending on the immediate reactions from financial institutions as they judge the path ahead which will likely remain unclear. 
Copy and paste the text from AMT that you want to share

Share:
SIngapore Dollar 20260717

Thoughts on the USD/SGD, Cautious Broad Market Sentiment and the Weekend

USD/SGD: Currently a Hope and Prayers Barometer in Global Forex

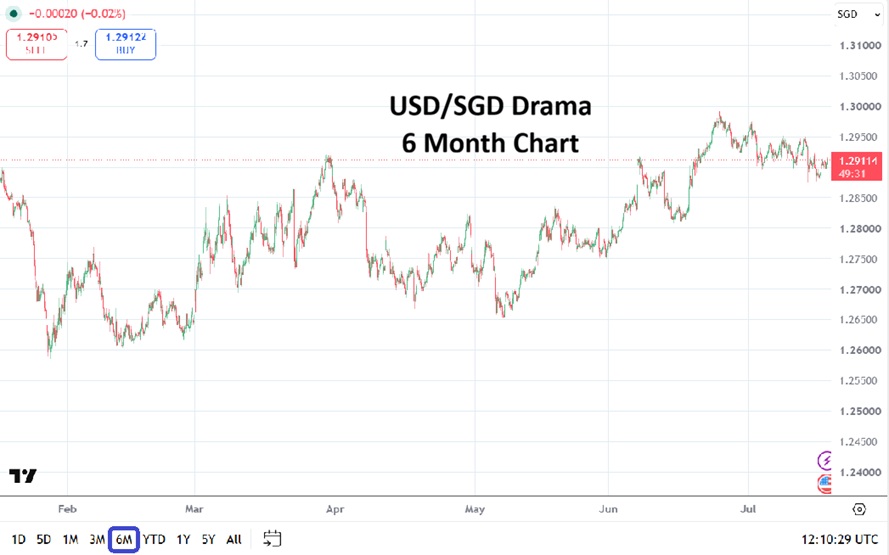
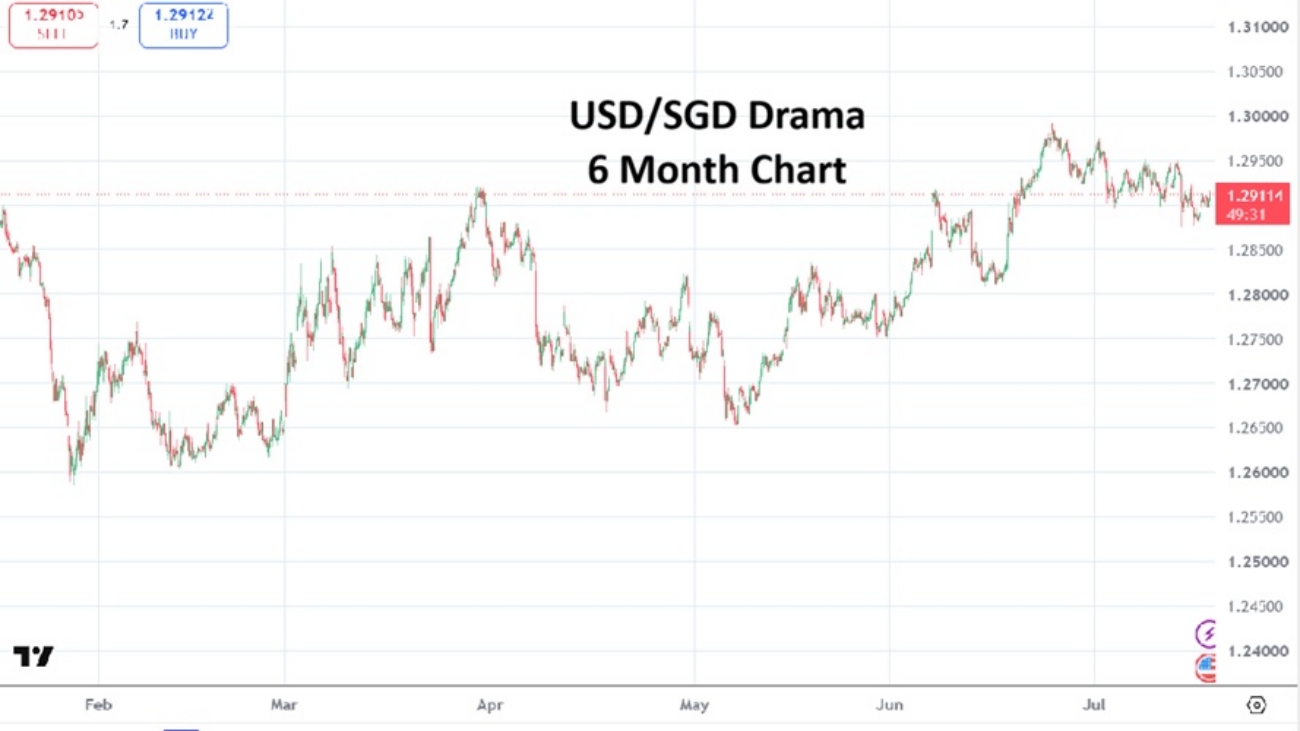
The USD/SGD is near the 1.29110 vicinity as of this writing. Financial institutions apparently have combined their cautious outlooks in the broad Forex market as USD centric strength continues to leak into sentiment, while their instincts technically demonstrate that over the mid-term currencies like the Singapore Dollar should be stronger and the USD/SGD is supposed to show some bearish activity.

For dramatic purposes let’s call this current phase of Forex trading including the USD/SGD as the hope and prayers act. The Singapore Dollar has sustained highs, but it has traversed lower over the past few weeks. On the 24th of June the USD/SGD was near the 1.29940 ratio. Let’s be clear, for small speculative Forex traders broad market wagering on USD direction remains dangerous.

USD/SGD Six Month Chart as of 17th July 2026

Fed Chairman Keven Warsh and His Desire to Introduce New Data

During the recent testimony of Fed Chairman Kevin Warsh in Washington D.C he made it clear he is keen on introducing AI tools into interpretations regarding Federal Reserve policy. However, he also said that AI will not be relied upon alone. From a coding perspective, Warsh essentially said proactive data will become part of the Fed’s thinking with proper supervision: some of you may want to call this a stack developer’s job.

At the same time while refusing to tip his cards regarding his stance on interest rates too much, Forex markets responded by selling the USD in incremental bouts. Intraday trading flared in its usual manner, but started show a core belief that Warsh is demonstrating dovish sentiment regarding interest rates.

USD/SGD as a Forex Barometer and Near-Term Behavioral Sentiment

The USD/SGD serves as a solid barometer of the Forex market. It offers perspectives on Asian sentiment, but also shows how global financial institutions are leaning. The escalation of firepower in the Middle East the past week and into today has caused reactions in the USD/SGD, but somewhat politely.

Having been able to trade below the 1.29000 mark on Tuesday and Thursday of this week, the currency pair is trading near values seen on the 8th of June and 18th. A lack of clarity remains a theme in Forex. The USD/SGD is the 10th biggest Forex pair via transactional averaged volume, so traders should give it attention even if they do not pursue.

Wall Street Remains Nervous and the Tense Weekend to Come

Going into this weekend Forex traders have created downside pressure on the EUR/USD and GBP/USD. The USD/JPY remains stubbornly above the 162.300 ratio. Nervous selling on the Nasdaq 100 via futures trading has been seen today and it looks as if Wall Street will be in for another bumpy ride. The wishful thinking drama in the financial markets is being confronted by the reality of a potentially loud weekend of military conflict between Iran and the U.S, and a seemingly unconvinced marketplace that doesn’t want to demonstrate risk appetite.

WTI Crude Oil prices via futures trading are above $80.00. Having been able to sustain values above the 1.29100 mark in the USD/SGD signals that bearish mid-term perspectives still need additional impetus to create more selling, but this doesn’t appear a wise speculative bet going into the weekend.

A cautious stance over the coming hours should be anticipated as folks wonder what the coming weekend will bring. At least there is the World Cup championship on Sunday (New York time) to take our minds off of concerns. However, Monday will not react to the trophy being raised, but to behavioral sentiment that will takes its cue via today’s finish on Wall Street and noise generated via the Strait of Hormuz this weekend.

Copy and paste the text from AMT that you want to share

postR186.1

Risk Appetite: Forex and Equities and Cautious Optimism

Risk Appetite: Forex and Equities and Cautious Optimism

Day traders can clearly see that risk appetite has taken hold of behavioral sentiment early this week. USD centric price action has created highs for the British Pound, South African Rand, Singapore Dollar and a host of other major currencies paired against the USD. Yesterday’s poor showing via the CB Consumer Confidence reading in the U.S poured additional fire onto the notion the U.S economy is not doing as well as Fed Chairman Jerome Powell expressed last week, which means caution should be used when looking at the broad markets. Speculators who only make short-term wagers cannot let blind optimism be the guiding light.

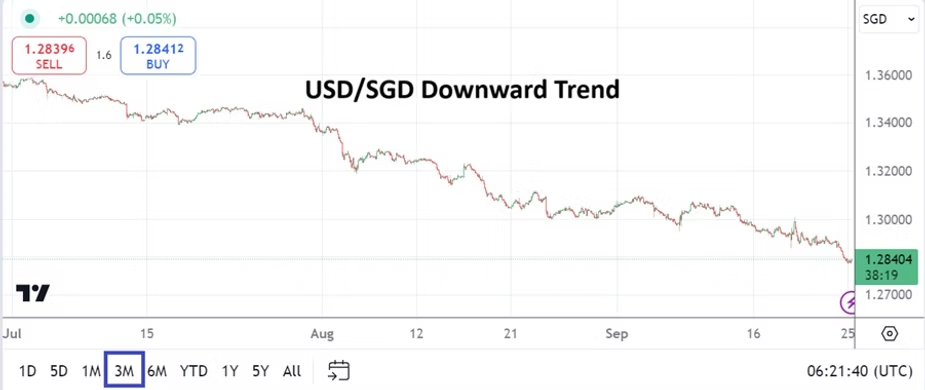
USD/SGD Three Month Chart as of 25th Sept. 2024

While today will be thin with economic data, Thursday’s Gross Domestic Product results could prove to be another ignition switch for market impetus. The quarterly Final GDP result is widely expected by analysts to produce a gain of 3.0%. The Final GDP Price Index statistics are anticipated to show a 2.5% ratio. If the growth and inflation numbers miss their marks this could set off a momentary storm in the markets. A good example of trading that has already been baked into the cake regarding values and mid-term outlook is the USD/JPY, which while maintaining its bearish stance has clearly found a price realm financial institutions are now maneuvering carefully within as equilibrium is battled.

GBP/USD Three Month Chart as of 25th Sept. 2024

Yet, many financial institutions have clearly leaned further into their optimistic stances particularly via the U.S major equity indices and day traders are likely trying to follow the momentum being generated. Yes, New Home Sales will be published in the U.S today, but these numbers carry a lot of complex considerations which analysts tend to dissect in a myriad of ways, meaning that while they will get some attention, the largest players will stay focused on tomorrow’s growth and inflation data coming via the U.S GDP outcomes.

USD/ZAR Three Month Chart as of 25th Sept. 2024

Forex traders should keep an eye on U.S Treasury yields, yesterday’s slight climbs early in they day were mostly met by reversals lower later on. There is also the knowledge that the yields are traversing long-term depths and there is an assumption they don’t appear ready to see a large shift in momentum. The Federal Reserve is widely expected to cut the Federal Funds Rate again in November by another 0.25%. Numbers via reports like tomorrow’s GDP statistics, and Friday’s Core Personal Consumption Expenditures Price Index will shake existing behavioral sentiment and the Fed’s outlook. The Core PCE number has an estimate of 0.2% per its monthly reading, the last three reports have met expectations.

USD/JPY Three Month Chart as of 25th Sept. 2024

Fed Chairman Jerome Powell will speak tomorrow at the U.S Treasury Markets Conference in New York, but his remarks will have been pre-recorded and presented via video. Treasury Secretary Janet Yellen will also speak afterwards at the meeting. However, their thinking is widely known and they are expected to sound rather tame. It also needs to be added that both Powell and Yellen are fully aware the U.S Presidential election is approaching. Neither one of them is going to risk saying something that can be interpreted as economically defiant.

Traders should expect the potential of volatility developing tomorrow as financial institutions and larger market participants position for the GDP reports, but if the numbers are within sight of expectations, it is likely current price equilibriums will continue to reflect current risk appetite dynamics. Proper risk management and the use of conservative leverage should be fully practiced. Retail traders should also begin to start considering that Non-Farm Employment Change data that will come from the U.S on Friday, October the 4th. The jobs numbers next week could pose a significant threat.

The Fed last week made it clear they believe there was reason to lower the Federal Funds Rate (while playing catch up) and there is the potential to enact further dovish actions in the months ahead. However, Jerome Powell also insisted – paraphrasing – the U.S economy is rather strong and added this is being reflected in solid growth statistics and a jobs market which may be weaker but remains stable.

Given the Fed’s propensity for a conservative approach, they have crawled out a rather precarious limb regarding their rather positive attitude. The coming economic data will certainly be noteworthy tomorrow and Friday, and via next week’s job numbers. Will optimistic equilibrium in Forex prevail over the next week? The major currency pairs will certainly be tested.