post219

MicroStrategy and Bitcoin: Will They Turn into Smithereens?

MicroStrategy and Bitcoin: Will They Turn into Smithereens?

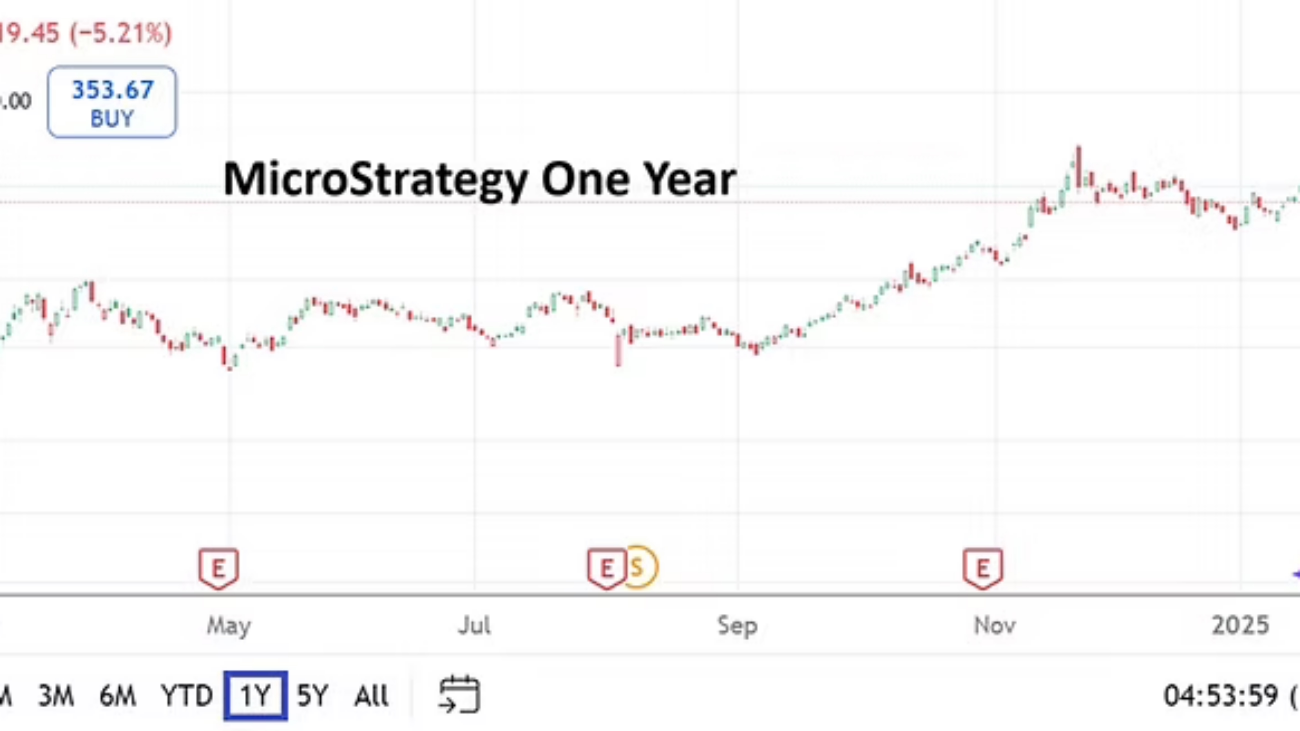
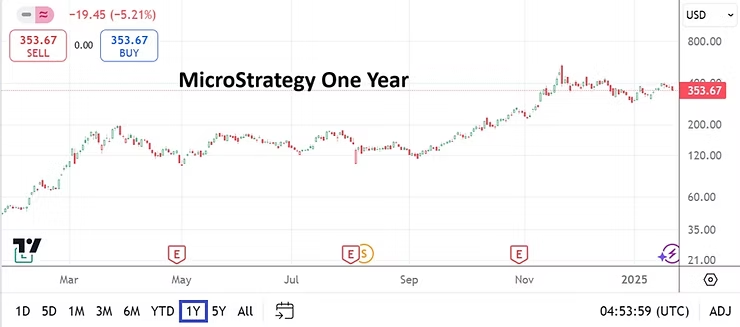
MicroStrategy One Year Chart as of 25th January 2025

MicroStrategy near 353.67 per yesterday’s close. Bitcoin around $104,625 this morning. Will the balloons keep inflating or become smithereens? The combo of MSTR and BTC/USD are combustible.

MarketWatch has published an excellent article on the borrowing via bonds that MicroStrategy is undertaking with investors. https://www.marketwatch.com/story/why-investors-are-lending-microstrategy-billions-of-dollars-at-0-interest-so-it-can-buy-bitcoin-03f7cacf The article highlights the red hot glow that some investors are pursuing via bets on MicroStrategy and Bitcoin.

MSTR has turned from a data driven company that produces revenue into a proxy bet on Bitcoin. Not everyone is a fan. As of late November 2024 Citron Capital has been reported to be ‘shorting’ MicroStrategy.

Students intrigued by the art of speculation, finance and business outlook have an active case study via MicroStrategy. This is a saga which will continue to grow in stature as investors and speculators seek profits. While the potential for disaster remains high, Michael Saylor of MicroStrategy and his cult like leadership capabilities has led his flock of believers into a golden land for now, but what storms await?

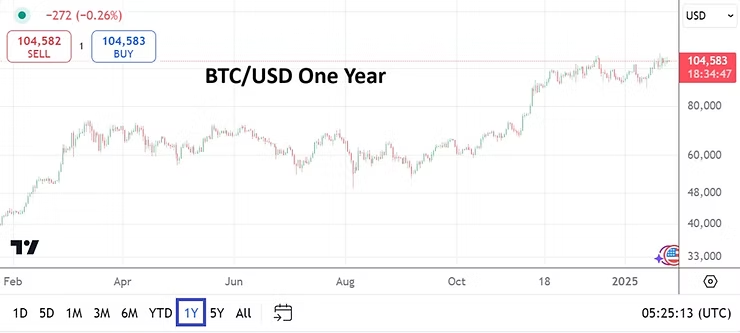
BTC/USD One Year Chart as of 25th January 2025

Naysayers of MicroStrategy’s foray into Bitcoin have thus far been proven wrong. Michael Saylor and his legions will continue singing praises about Bitcoin and its ability to turn into the modern version of gold, but perhaps it will turn into a digital asset nightmare. However, there is no denying the strength of the trend which has manifested the past year in both MSTR and BTC/USD. With the advent of President Trump and his seemingly pro digital asset stance being taken; and the growing desire by some crowds to turn fiat currencies which have been paper based into Central Bank Digital Currencies (CBDC) there are likely years left in this saga to unfold.

There has been a growing clamor for central banks to start holding some of their reserves in Bitcoin instead of gold, but for the moment this seems like too wild a thought and a purely speculative notion. Wagering on the confidence generated by digital hype with little intrinsic value, except the ability to create hot air via rhetoric and lofty visions of grandeur still appears to a step too far for most central bankers. Speculating on MicroStrategy and Bitcoin is one of the ultimate bets looking to take advantage of behavioral sentiment in the digital asset realm. MSTR and BTC/USD are highly volatile and have certainly created profits, but the combination could also turn into a horror if things go wrong.

post217

USD/JPY: Bank of Japan Actually Does its Job: Raises Rate

USD/JPY: Bank of Japan Actually Does its Job: Raises Rate

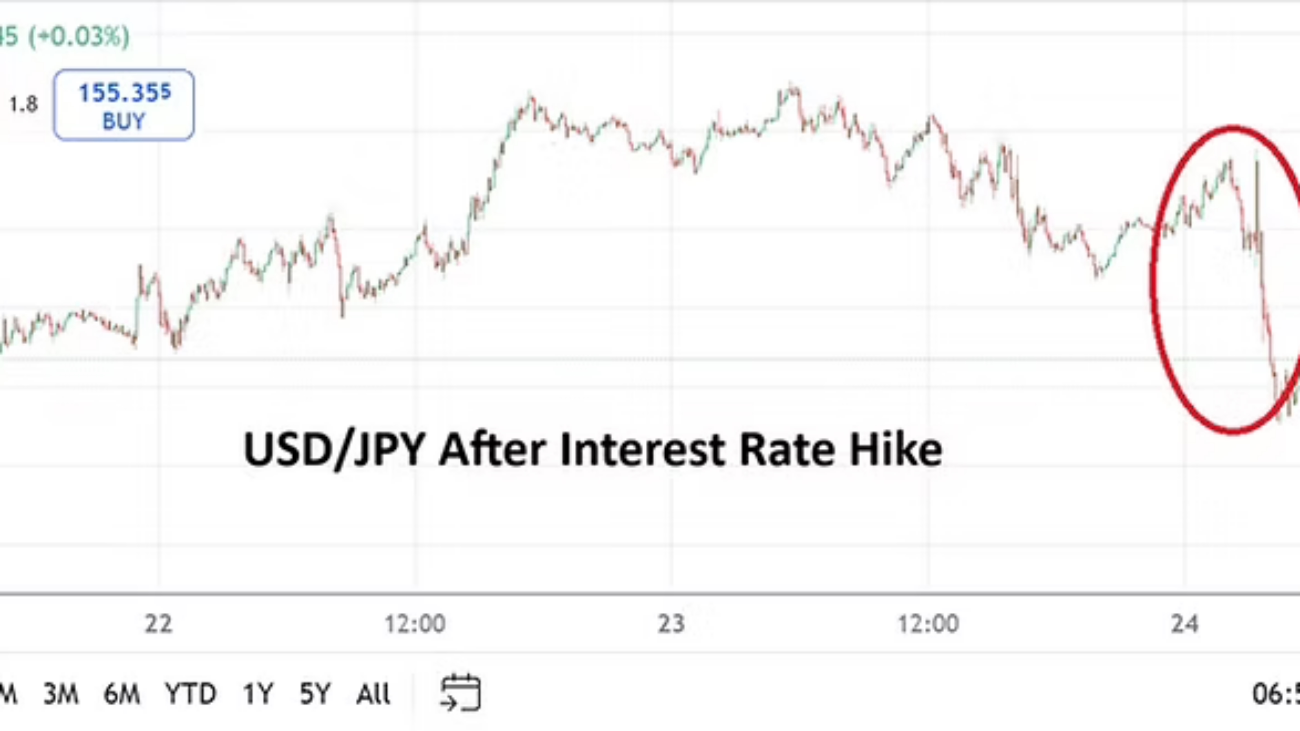
USD/JPY Five Day Chart as of 24th January 2025

The Bank of Japan actually raised its Policy Rate by 0.25 to 0.50% this morning. The move was done while the central bank stated the Japan economy is improving. The Bank of Japan also noted that the implications of U.S tariff policy are not completely known, thus it is acting on existing facts. The action by the BoJ created selling in the USD/JPY and is a healthy sign.

While the U.S Federal Reserve has taken on a cautious tone, President Trump has started to signal via rhetoric that he would like to see U.S interest rates lowered. The Fed and President Trump may find that they are in disagreement regarding mid-term policy and Forex traders shouldn’t be surprised if the debate escalates. The USD/JPY is trading near the 155.500 vicinity with fast price action at this moment. The ability to sustain values below the 156.000 level will be important technically if maintained. A fall below the 155.000 ratio may indicate more selling should be expected.

While financial institutions globally remain nervous about U.S economic policy regarding trade negotiations, Japan for the moment is out of the spotlight regarding tariff implications. The USD/JPY was trading near the 153.000 area on the 17th of December and it will be intriguing to see if large players use this level as a target in the coming days.

Retail traders should practice solid risk taking tactics and conservative leverage. The ability of the Bank of Japan to increase its interest rate, while the U.S Fed is in the midst of considering no changes to the Federal Funds Rate is a potentially solid sign for USD/JPY bearish attitudes.

Global Forex conditions remain choppy, but there has been some buying of the EUR/USD and GBP/USD produced recently. Next week talk of tariffs against China, Canada and Mexico will heighten, but traders need to understand the tough sounding talk from Trump is part of his negotiation tactics. While he certainly seems intent on carrying out his mandate, he will also be open to finding a way to create agreements.

Behavioral sentiment is in charge of Forex for the moment. Outlooks remain unclear, but USD centric strength may be traversing within the apex of its highs in many cases.

post216

Trump Bounce Potentially Coming This Week in Equity Indices

Trump Bounce Potentially Coming This Week in Equity Indices

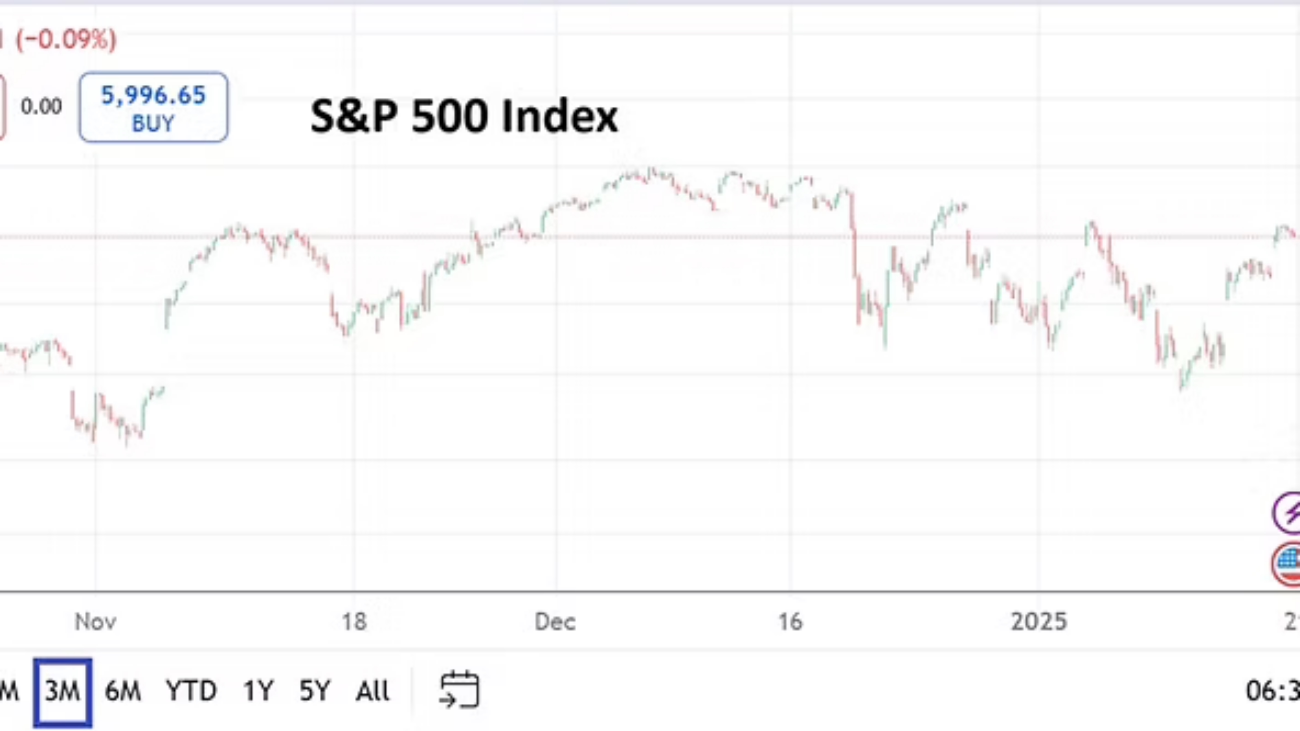
S&P 500 Three Month Chart as of 19th January 2025

Trump: U.S equity markets will be closed Monday for MLK Day. Upwards momentum developing this week as Trump White House takes power would not be surprising.

Retail traders need to know that U.S equity markets will be shuttered on the 20th of January because of the Martin Luther King Jr. holiday. Importantly tomorrow is also the United States Presidential Inauguration. Donald Trump will retake power of the Executive Branch of the U.S government at noon in Washington D.C as he is sworn in as the 47th President. U.S stock markets have produced choppy results the past few months but still remain in sight of highs. It would not be a shock to see optimistic momentum develop on Tuesday in the U.S stock markets near-term.

Yes, financial institutions have known Trump will be taking the White House for two and a half months and have had plenty of time to already react regarding their outlooks. However, from a behavioral sentiment standpoint it is easy to deduce that Trump’s coming inauguration speech tomorrow will deliver a confirmation of his economic policy intentions. Financial institutions near-term may produce optimistic upwards trajectory and they may have psychological targets which take into account late November and early December 2024 highs in the S&P 500.

The coming week will also be light on U.S economic data, except for the weekly Unemployment Claims on Thursday, Flash Manufacturing PMI and Existing Home Sales on Friday. Meaning the week will be driven largely on sentiment generated via President’s Trump’s actions in the coming days. Trump is expected to deliver a series of Executive Orders which will affect outlooks and likely be reflective of his campaign rhetoric spoken the past year.

Retail traders should not bet blindly on upside via CFDs for the S&P 500, Nasdaq and Dow 30. Near-term prices are not guaranteed to move higher, but there is reason to suspect buying might prove positive. An interesting barometer for price action will certainly be seen via future contracts early on Tuesday morning as financial institutions return to full volume and get set to return after a long holiday weekend. Risk taking tactics should include price targets that are realistic and not be leveraged wildly.

Forex conditions may prove volatile this week, and traders need to remain cautious about betting against the strength of the USD which has been ferocious the past three months. U.S Federal Reserve outlook remains murky and cautious, and nervousness regarding Trump’s intended foreign policy changes including trade negotiations still have to be fully demonstrated. USD centric risk bullishness likely still has ammunition which will be displayed in the coming days.

post213

Federal Reserve Expected to Sound Guardedly Cautious Tmrw

Federal Reserve Expected to Sound Guardedly Cautious Tmrw

EUR/USD Five Day Chart as of 17th December 2024

Large traders are clearly bracing for the Fed tmrw as Forex produces volatile tight ranges. A rate cut is expected, but cautious Fed rhetoric will likely follow.

Forex has been a dangerous wagering ground for retail traders since the end of September. Financial institutions which clearly were betting on a more dovish Federal Reserve starting in early summer becoming a central theme into 2025 have been proven half right, this as the Fed has cut interest rates and is expected to do so tomorrow. However, being half right leaves the door open to also being half wrong, and financial institutions have reacted to this by becoming aggressive buyers of the USD since late September as perspectives have changed. The strong USD trend the past two months plus has hit some speculators hard.

The election of Donald Trump added a strong dose of impetus for USD buyers, this as the President-elect’s tough rhetoric regarding tariffs caused reactions and fear of unknown consequences. In the past couple of weeks more tranquil Forex trading has emerged and the USD finally started to give back some of its gains, yet the USD versus most major currencies, like the EUR/USD, remains within the the stronger elements of it range. While the Fed is expected to lower its Federal Funds Rate tomorrow by 0.25 to 4.50% tomorrow, traders need to remember this has been priced into Forex already. Tranquil trading the past two weeks indicates financial institutions have readjusted their outlooks to the incoming White House administration.

Now it is time to see if the U.S Federal Reserve has started to adjust their outlooks to what a Trump Presidency means. And financial institutions are keen to better understand the outlook of the U.S central bank. Inflation numbers while traversing lower are still rather stubborn and this may will not help the Fed’s mid-term mindset regarding interest rate cuts. GDP in the U.S has remained steady, and there is the potential the economy in the States will improve under Trump. Unemployment numbers while showing signs of weakness have not been terrible either. So while the Fed’s current Federal Funds Rate is higher than normal taking into consideration the historic average the past ten years, they still may not feel they have enough ability to cut interest rates too much more without sparking inflation.

A January rate cut seems unlikely at this time. If the Fed does sound guardedly cautious tomorrow, retail traders may see the USD get initially weaker due to the Fed rate cut, but then see a storm emerge and USD centric strength reappear all in the same day – perhaps in the span of minutes. Speculators need to understand that financial institutions have already baked tomorrow’s interest rate cut into the cake. So it isn’t the rate cut tomorrow that is important if it happens (if it doesn’t then that’s another story); it is what the Fed says and traders should expect them to be very cautious – because per the recent trading of the USD and a barometer it appears financial institutions are bracing for a more vigilant Fed.

Just like he has with many folks he views as uncompromising before, Donald Trump may begin to feel Federal Reserve Chairman Jerome Powell is not on his side regarding interest rate policy. If the Federal Reserve chooses to sound hesitant to cut interest rates in early 2025, it will be rather intriguing to see President-elect Trump’s response. Could a confrontation between the White House and Federal Reserve be in the cards over the next six months?

post209

Forex: Trump Effect and Reasonable Trading Caution for All

Forex: Trump Effect and Reasonable Trading Caution for All

The Forex market the past two months has created a profoundly stronger USD against many major currencies. The combination of late September intrigue regarding U.S Federal Reserve outlook, then nervousness about the approaching U.S election, followed by the subsequent results have been a dumpster fire for many speculators looking for a sustained return to USD centric weakness. Hopefully risk taking tactics have included a solid dose of caution.

This week’s Non-Farm Employment Change numbers scheduled for Friday may give financial institutions a moment to focus on economic data instead of President-elect Donald Trump’s loud pronouncements, but the effect may prove to only be momentary. It isn’t data that is driving Forex for the moment it is nervousness and fear of the unknown.

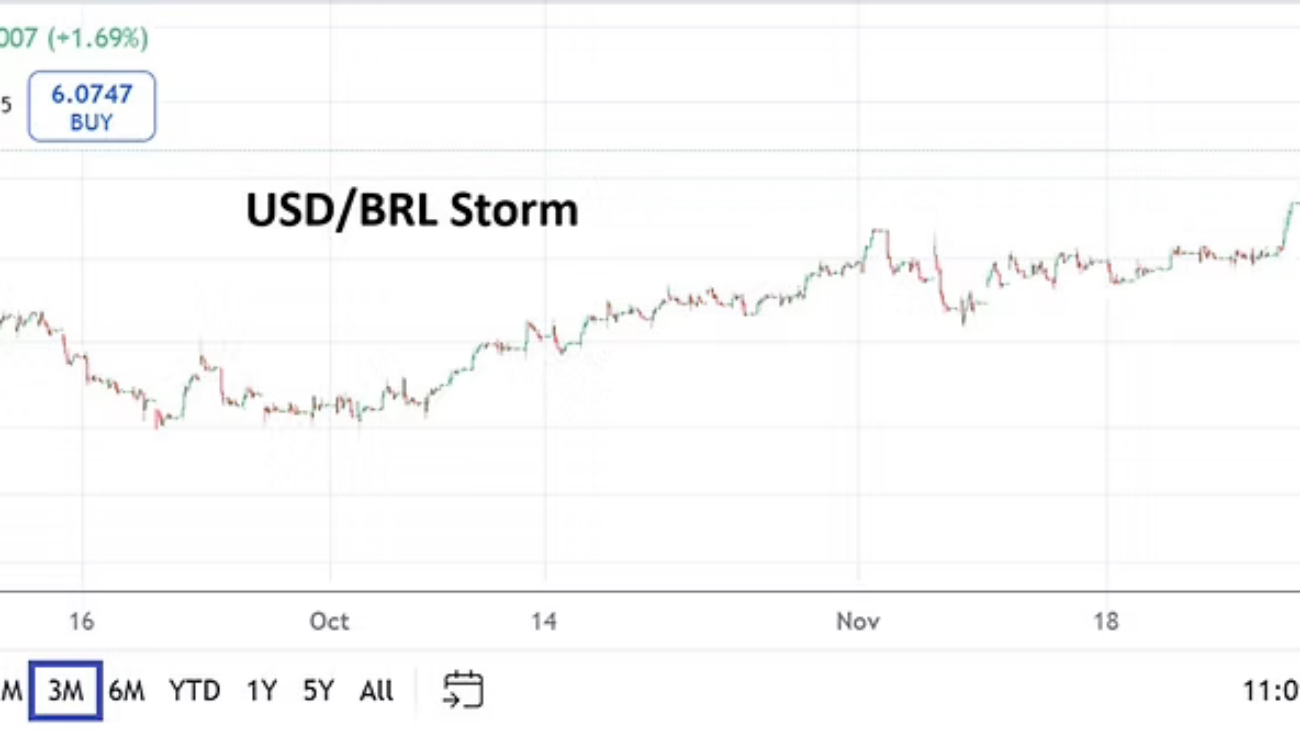
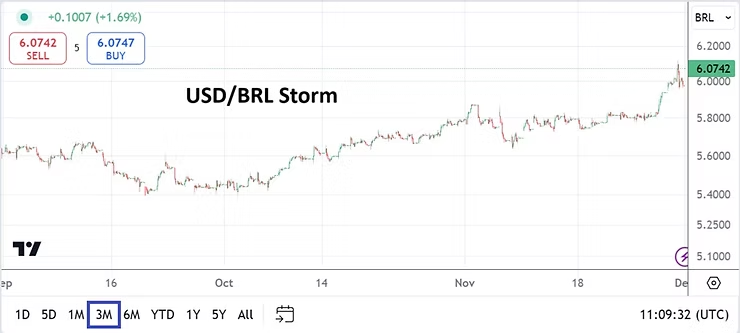
USD/BRL Three Month Chart as of 3rd December 2024

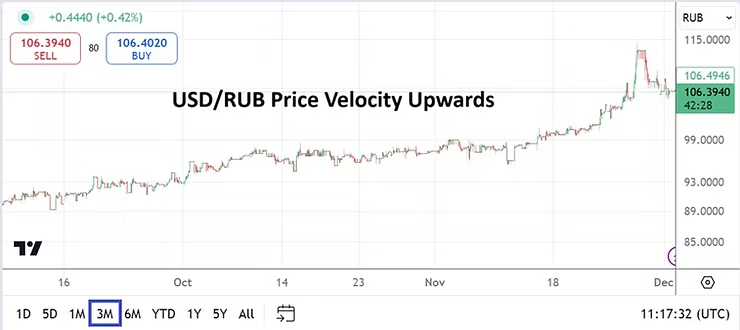
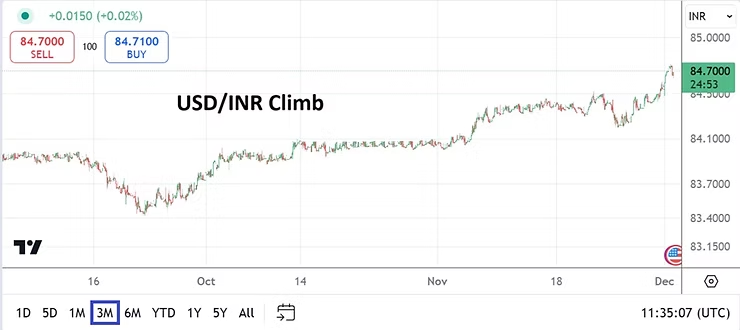
While many financial institutions and speculators trade only the major currency pairs, taking a look at the less obvious and more infrequently transacted major currencies may provide retail traders additional perspectives regarding the fragile nature of Forex. Many nations and large institutions are demonstrating concerns about possible sea changes to U.S foreign economic policy. Yes, the EUR/USD, GBP/USD and USD/JPY have all seen volatility via USD strength the past two months, but price velocity in the USD/BRL, USD/RUB, and USD/INR may be equally intriguing. And prove that mid-term forecasts (or lack of them) are causing bedlam for all.

USD/RUB Three Month Chart as of 3rd December 2024

While it is more than probable calmer heads will start to be seen in Forex and weakness eventually will return to the USD, trying to pick the exact moment this is going to happen remains a guessing game. Financial institutions via evidence in current Forex pricing remains rather cautious regarding their cash forward commercial enterprise. President-elect Donald Trump has certainly been dealt with before and his negotiation style is that of a businessman, it is not a coincidence that some global leaders who do not exactly see eye to eye with Trump are giving him respect because they understand he will act upon threats if not dealt with fairly.

Trump’s recent brief rhetoric regarding BRICS and the organization’s public consideration of creating a new currency to compete with the USD did not go unnoticed this weekend. Critics may want to proclaim Trump’s threats as belligerent, but BRICS is free to create a new currency still if they wish. While Trump cannot stop the birth of a BRICS currency, he can certainly try to initiate actions (via sanctions) against nations that attempt to create a new unified currency which tries to curtail the dominance of the USD. It would certainly help Trump’s bargaining position and the USD also, if better fiscal policy is practiced by the U.S Treasury and government.

USD/INR Three Month Chart as of 3rd December 2024

It needs to be pointed out that Trump’s warning to BRICS may not be needed. Even though the organization may be able to create a currency based on a commodities backbone, the lack of trust many financial institutions and nations would feel towards a non-transparent fiat currency powered by the fiscal monetary policies from the likes of Russia, China, Brazil and South Africa remains a difficult sell. Until many changes happen domestically within these nations via governance, creation of a BRICS currency remains wishful thinking.

Getting back to the big picture and the volatility recently seen in Forex. While the major currencies teamed against the USD have certainly faced hectic conditions, the fluctuations have not been unexpected. Day traders need to understand the month of December is likely going to remain choppy and see a test of technical support and resistance levels that are wide and full of fast reversals.

The question for the EUR, GBP, and JPY is if most of the negative inputs into these currencies has been factored into value. The suspicion may be yes, and that strength may rightfully appear in these big three sooner rather than later. However, the approaching holiday season and potential bluster from President-elect Trump will not make this a comfortable or easily wagered avenue.

Short-term retail traders looking to take advantage of the bloodbath created in Forex the past two months who seek opportunities should focus on perceived targets which aren’t overly ambitious. The coming U.S jobs data this Friday may allow the U.S Federal Reserve room to cut the Federal Funds rate on the 18th of December by another quarter of a point. As a point of attention, the European Central Bank will announce their Main Refinancing Rate on the 12th of December. The ECB’S actions may be a solid clue regarding the Fed’s approach to upcoming policy.

However, even if an interest rate cut were to take place via the Federal Reserve, it is likely the cut has already been factored into Forex. Which also highlights the high degree of nervousness that exists because of fears which permeate due to Donald Trump’s tough negotiation stances which have been made public. Meaning those who are looking for USD centric weakness to emerge still need to rely on a shift within behavioral sentiment to occur that is not generated because of the Federal Reserve. Nations need to show a willingness to amend existing trading agreements with the U.S, allowing for changes to internal policies regarding exuberant price duties they place on U.S goods in their own countries.

postR197.1

Return to Normal Market Conditions and a Trump Outlook

Return to Normal Market Conditions and a Trump Outlook

Retail speculators can now expect a return to calm and clear financial market outlooks, knowing that potential influences from new U.S policies will start to be considered. With the U.S elections in the rear view mirror and a Trump mandate delivered by many U.S voters, global financial institutions and traders will again be able to focus on a combination of technical perspectives, current behavioral sentiment and outlook.

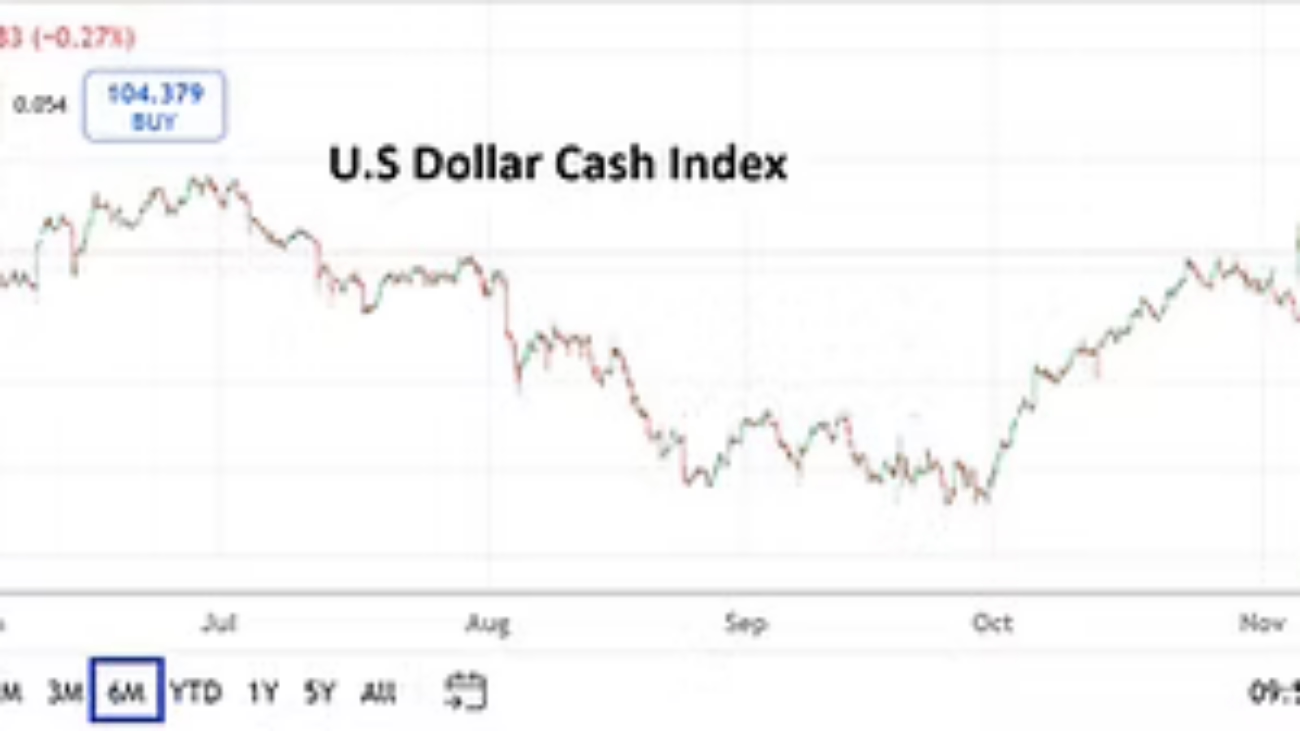
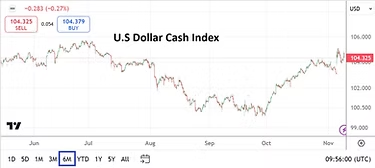
USD Cash Index Six Month Chart as of 10 November 2024

Some technical traders may believe behavioral sentiment has nothing to do with the long-term prospects of studying charts, but price action last week in FX and equities clearly showed why traders must be attuned to storms created by human emotions. Risk adverse trading has been prevalent since the end of September. A glance at the six month USD Cash Index demonstrates the extent of behavioral sentiment causing volatility the past handful of months. After believing the U.S Federal Reserve was going to become dovish which propelled the USD lower in many Forex pairs in early July, financial institutions expressed concerns about political outlook the past handful of weeks as a lack of clarity started to shroud their perspectives. USD centric positions have powered Forex.

And now that there is a Trump administration coming, and the U.S Fed has remained cautiously dovish this past Thursday, financial institutions may exhale with relief. The election on November the 5th has delivered a clear message regarding the potential for changes to U.S administration mandates regarding trade. Whether a stronger U.S economy is attained because of these hopes is not the question, it is the perception new policies will be initiated which try to deliver results which have been promised. Yes, promises can be broken.

However, the ability to believe changes are coming will affect behavioral sentiment. The Trump soundbites may prove to be rather weak in the future, but there is a chance he will also get things done regarding stronger trade agreements which protect U.S business enterprise and manufacturing. Folks can argue until they are blue in the face regarding the prospects of all things, but the U.S major equity indices rising like a rocket ride in the middle of last week is clear evidence that many believe the prospects for U.S corporations is better. No matter if it is only hopes about tax laws changing, less regulation, and better U.S trade agreements, investors are clearly betting on optimistic outlooks for the mid-term.

Dow Jones 30 One Month Chart as of 10 November 2024

Improved attitudes are great for the prospect of financial institutions, but traders still have to certainly protect their positions against volatility developing. Markets should start to return to tranquil conditions in the days ahead. U.S data will come this week which will be important via the CPI numbers on Wednesday and PPI figures this Thursday – the combination of these inflation reports will be important. Friday will see Retail Sales from the States.

The return to data as a guideline for financial institutions teamed with the Fed’s rate cut this past Thursday may be an ointment for retail traders who seek a return to normal conditions. Nervous behavioral sentiment could remain a factor in the coming days as people adjust their outlooks to a Trump White House, but the coming week should be relatively quiet regarding surprises.

It isn’t a question of liking or disliking the outcome of the U.S election, it is a question about how behavioral sentiment will now be affected. While some bring up potential tariffs as a major risk for the U.S and global economy, we have been down this road before with Trump. The risk of inflation if trade disagreements flourish should be taken seriously, but Trump has dealt with China in the past and both sides did find a way to do business in many respects. China is probably worried about Trump being in the White House again, but they likely have a gameplan for the tough business discussions ahead. The experience of having dealt with President Trump before allows China and others to know what they may face this time and empower them to be prepared.

It should be noted that Trump has shown in the past a tendency to enter negotiations with a difficult offer and permitting the other side to counter. Trump then might turn down a proposal, but often shows he is open to discussing things further and reaching a compromise. And that is the crucial word – compromise. It is about business and geopolitics. Financial institutions have dealt with a Trump White House before. This time around there is a hope Trump’s naming of a White House cabinet will not be as messy an affair as it was the first time.

The naming of Susie Wiles as the White House Chief of Staff last week looks like a good first step, also having strong Republican leadership in the Senate and House of Representatives may make things easier. While some are worried about a slew of loud rhetorical stances by Trump, perhaps pragmaticism will be practiced. And based on that rather optimistic viewpoint, retail traders may also feel businesslike conditions are ahead and that the financial markets will be a safer place to pursue speculative wagers again in the near and mid-term.

postR196

Top Ten Miscellaneous Slogans for the 21st of October

Top Ten Miscellaneous Slogans for the 21st of October

10. Evil Empires: The Yankees and Dodgers will square off in the World Series with their ultra expensive rosters competing for the championship. Maybe this is exactly what the U.S needs so people can take their minds off of U.S election concerns. A contest between Los Angeles and New York is a big selling card. TV ratings should soar as Shohei Ohtani, Juan Soto, Mookie Betts, and Aaron Judge battle for the supremacy of baseball.

9. Vision: SpaceX achieved magical results as a Falcon 9 rocket booster was caught by ‘chopsticks’ as planned for and engineered. Elon Musk proved again that his preposterous ramblings are frequently correct. SpaceX is in a solid position to provide logistics for outer space exploration and development, but to also create new business endeavors as it evolves. The implied value of SpaceX mid-2024 was estimated to be around 200 billion USD.

8. 2017: Bitcoin was around 1,000.00 USD in January of 2017. The price of the digital asset is now approximately 68,500. The perception and betting that a Trump victory may be putting a spring in the step of the cryptocurrency market is intriguing. Bitcoin trades based on behavioral sentiment and not intrinsic value. Trump has spoken about crypto favorably time to time. A more welcoming SEC and CFTC regarding crypto could help values. For those looking for further correlation to BTC/USD and Trump, when he left office in January of 2021, Bitcoin was near 31,000 USD.

7. Downturn: Environmental, social and governance investing has taken a hit compared to results from the past couple of years as outflows from investment vehicles led by the likes of BlackRock and others make noise. ESG has lost its luster as the race for superior profits has run into headwinds and analysts question values and revenues. What will happen over the next few years, particularly if ESG investing finds that it has fewer friends in the U.S halls of power?

6. Data: U.S economic statistics will be rather lacking this week, the highlight may be the Flash Manufacturing PMI numbers on Thursday. Some may try to make the weekly Unemployment Claims a spectacle too, particularly brokers who may be trying to entice day traders into Forex positions. However, the rather calm seas regarding data will turn tumultuous next week because U.S Advance GDP, Core Personal Consumption Expenditures, and the Non-Farm Employment Change results are all on the schedule.

5. Underwater: WTI Crude Oil started to flirt with the 70.00 USD mark last Tuesday, and after a few days of remaining within a rather tight range, support was proven vulnerable. As of this writing WTI is near 69.65. The lack of an attack on Iranian oil infrastructure by Israel has seemingly calmed the energy sector. Fearmongering and bombastic rhetoric have not caused WTI Crude Oil to sustain highs. The commodity is within the lower elements of its long-term price range technically.

4. 24 Carat: Record values in gold are being traversed. As of this writing the precious metal is near 2,734.00 per ounce. Gold was around 1,200.00 USD in January of 2017. Inflation, speculation and concerns about central banks are likely helping gold shine. Some may say the rise in value is a derivative of safe haven investing. Day traders may view the price as speculatively high and dangerous because of its intraday volatility, but long-term gold bugs know the historical track record of the precious metal and its ability to preserve wealth.

3. FX: Major currencies paired against the USD are finding increasingly choppy waters near-term. The USD/JPY is dangerously close to the 150.000 mark, the USD/MXN is within sight of 20.00000, and the GBP/USD is hovering above 1.30000. The EUR/USD is battling too and scuffling below the 1.09000 ratio. With no major data coming this week, but major risk events approaching on the horizon, now is the time for Forex traders to remain cautious and not get too ambitious. Forex may provide technical traders with the ability to wager on perceived support and resistance near-term. But soon, a huge wave of volatility is going to hit currency speculation and financial institutions are certainly getting prepared for the storm.

2. Tick Tock: The U.S election is only a bit more than two weeks away. This may be the last week for any huge surprises which could sway the decisions of voters. Harris and Trump and campaigning hard and receiving intense media coverage. Early voting is underway, but November the 5th is the date everyone is focused on. When the clock strikes November the 6th in the U.S, global investors will react.

1. Behavioral sentiment: Key market barometers will continue to get plenty of attention in the coming days. U.S indices serve as a heat check regarding the potential outcome of the U.S election. Equities are near highs and this seems to be a rather solid indication risk appetite remains the dominant feature. While some will not want to hear it, this likely means many folks in the investment world are starting to believe Donald Trump might win the U.S election.

postR196

AMT Top Ten Miscellaneous Salvos for the 29th of September

AMT Top Ten Miscellaneous Salvos for the 29th of September

10. Profit: OpenAI has announced plans to become a money making corporation. Founded in 2015 the artificial intelligence company had the stated goal of creating ‘safe and beneficial’ technologies via its foundation, and now will face the slings and arrows of investors and potential critics. The AI boom the past two years has produced many new competitors. Can Sam Altman, the CEO of OpenAI, sustain the momentum generated or will negative organizational impetus turn the company into an also-ran?

9. Softs: Cocoa, Coffee and Sugar all remain volatile and playgrounds for day traders who like casino experiences via CFDs. Cocoa is again over 9,000 USD, Sugar touched February highs this past week as it shows signs of extreme speculation, and Coffee Arabica surged to record prices on Thursday and Friday. Over exuberance however is not being created by day traders, it is the work of large institutional traders who are in control. While the ‘softs’ may look overbought it would be unwise to bet against trends while big players pursue bullish notions. Massive money is being made in these commodities, but losses are also being felt by those who wager incorrectly.

8. Escalation: Risks in the Middle East have become a focal point, this as the region appears to have generated more must watch television. The noise which the media seemingly craves is hard to escape. Market participants cannot be blamed for maintaining vigilance as sabers rattle, especially after Friday’s events in Beirut when Hassan Nasrallah, the Hezbollah leader, was eliminated by Israel. However, experienced traders who are also strategic analysts have seen this show before and may turn the channel knowing there will be reruns in the future.

7. WTI Crude Oil: Prices closed within the lower elements of the commodity’s long-term depths. Traders did have a chance to react to Friday’s developing news from Beirut, but the energy sector remained calm. The price of WTI was around 68.57 going into this weekend, after trading at highs earlier in the week. For all the talk about fear of escalation from the Middle East, the price of Crude Oil remains within a remarkable bearish stance as large traders appear to be more concerned about lackluster economic growth globally.

6. Apex Gold: The price of the precious metal flirted with 2,685.00 momentarily on Thursday. The price of gold going into this weekend finished near 2,658.00 USD. Sustained highs have certainly continued to catch the attention of short-term speculators, but they need to be aware the commodity does remain susceptible to sudden spikes. While alluring, gold remains dangerous for day traders.

5. Countdown: The U.S Presidential vote is slightly more than 5 weeks away. Interestingly, the Fed will announce their Federal Funds Rate decision only two days after the election results. Will the outcome of the vote change the Fed’s perspective on interest rates? Financial institutions will definitely brace for the outcome of the U.S vote. Cautious winds will start to prevail as the 5th of November draws closer.

4. China: A huge stimulus package from the Chinese government has been initiated, but talk regarding potential effects and outcomes are being debated. The notion that the Chinese economy is be driven too much with a top to down centralized approach is being vocalized by some worried ‘outside’ observers. The USD/CNY is trading near 7.0105. The Shanghai Composite is near 3,087, this after massive gains via a reversal upwards which was sparked from lows around 2,691 which were seen on the 18th of September.

3. Risk Appetite: U.S equity indices continue to challenge record values in the Dow 30 and S&P 500. Yes, the Nasdaq remains beneath its highs, but is still within sight of all-time heights. Trading this week will work under the shadow of the jobs numbers coming this Friday. Financial institutions have produced rather positive behavioral sentiment and do not seem like they are ready to back away from this stance. Are some large market participants starting to quietly bet on the possibility of a Trump victory which they believe would be good for U.S stocks?

2. Forex: USD centric notions remain the impetus in foreign exchange. The USD Cash Index is within the lower boundaries of its long-term values as it trades near July 2023 realms. If the USD Cash Index moves lower it would then start to technically be within price calculations not seen since the spring of 2022. Action in the USD/JPY and GBP/USD, and other major currency pairs have been volatile, choppy conditions should be expected this week for traders leading into Friday’s key data.

1. Jobs Numbers: Last week’s GDP statistics met expectations, while inflation numbers via the Core PCE Price Index came in slightly below estimates. The growth and inflation outcomes set the table for the Non-Farm Employment Change and Average Hourly Earnings which will be reported on the 4th of October. If the employment numbers continue to trend lower and there are additional negative revisions this coming Friday, this could propel USD selling. Financial institutions are trying to figure out if the Fed will cut by 0.25% or 0.50% in November. The Fed was aggressively dovish when they cut the Federal Funds Rate by 0.50% on the 18th of September, but the U.S central bank might want to be cautious in November following the election and wait for all the dust to settle and cut by only 0.25%. Thus allowing for another interest rate cut in early 2025 if needed. The broad markets are in a reflexive mode for the time being, this Friday’s data will be important and cause an immediate reaction that day traders will notice.

postR196

AMT Top Ten Miscellaneous ‘Just the Facts Jack’ on the 14th of Sept.

AMT Top Ten Miscellaneous 'Just the Facts Jack' on the 14th of Sept.

10. Word of the Day: Quaestuary, the usage of the word comes from William Manchester’s book A World lit only by Fire. The word is now considered obsolete. Manchester used the Latin word, quaestiarii, to describe profit making by the Roman Catholic Church during the Middle Ages and into the Renaissance. Church ‘officials’ would use their positions of power to raise money dubiously. Promising absolution to the naive via treacherous claims which included the charging of payments for potential sins committed in the future, and a more lenient purgatory for already deceased members of a family who were waiting to be allowed into heaven because of past transgressions.

9. Undecided: With less than two months before the U.S election for President, swing States are crucial battlegrounds for candidates Trump and Harris. Turning purple into red or blue is the prime task for the Republicans and Democrats. Economy, immigration, foreign policy, reproductive rights are among the talking points. Which side can receive the most votes via promises that will be hard to accomplish?

8. Artificial Intelligence: Early this week Oracle Corporation released revenue results and projections showing that profits are increasing due to demand for data centers as the use of AI expands. Cloud services provided by Oracle has become the corporation’s largest source of growth. Investments in big data centers are getting competitive. Data4 has recently announced they are going to invest approximately 300 million EUR into a data center facility in Paiana, Greece. Data4 led by Olivier Micheli, CEO, has announced that it plans on investing around 7 billion EUR into 2030 for expansion.

7. Crude Oil: WTI Crude Oil briefly went above the 70.00 USD mark on Friday, but went into the weekend near 69.33. U.S economic data this coming week (besides the U.S Fed on the 18th) will be limited to manufacturing readings and retail sales data. The notions that the U.S economy is struggling via weaker employment numbers and lackluster GDP, European data remaining murky, while China is not exactly robust is likely causing speculative demand in Crude Oil to remain low. Global energy supply is solid and the Middle East conflict remains somewhat muted.

6. Whipsaw Gains: Major U.S equity indices moved upwards as the Dow 30, S&P 500 and Nasdaq 100 all produced better weekly results. However, improved momentum mostly occurred as equities reversed from nervous lows on Wednesday. The Dow 30 and S&P 500 are within sight of apex values, while the Nasdaq isn’t far behind. U.S Treasury yields also dropped lower via their totals for the week with the 5, 7, and 10 Year Notes approaching yields last seen in the spring of 2023. The 30 Year Bonds are traversing lower too, but will have to penetrate early 2024 levels to then challenge depths from early 2023.

5. Inflation: Global central banks are having a large internal debate about their target inflation numbers. Trying to agree on what the neutral rate – mean average – over the next year should be is causing central banks to remain cautious about inflation projections. While it is clearly evident that Europe and the U.S are facing economic headwinds the ECB, Fed and BoE seemingly refuse to step on the gas pedal and become aggressively dovish. However, financial institutions who frequently use their mid-term outlooks as guidance continue to lean into their trading positions and seemingly wager on the central banks having to become more dovish. How much can each central bank cut by over the next 6 months? Why not cut by 0.50% to inject easier borrowing rates now? Because apparently it seems all the central banks remain nervous about inflation remaining stubborn. The word stagflation still comes to mind. The decline in Crude Oil prices seen the past few weeks may be a hopeful sign for lower costs.

4. USD/JPY: The currency pair finished trading near the 140.775 ratio on Friday. Trading in the USD/JPY appears to be driven by the notion that financial institutions believe the U.S Federal Reserve is going to have to cut the Federal Funds Rate by 0.75% over the next six months. Behavioral sentiment has a breathtaking history of producing strong trends in the USD/JPY. The Bank of Japan will announce their Monetary Policy Statement on the 20th of September. The USD/JPY was trading near 162.000 in July and its decline lower seems to have surprised some, but why? The BoJ is likely going to sound cautious this coming week, but sitting on their hands and allowing their global counterparts to become more dovish may be enough to keep the USD/JPY within its lower price realm.

3. China Data: Numbers published early this morning showed that New Home Prices continue to fall, Industrial Production has decreased, Retail Sales have dropped, and the Unemployment Rate has risen. China’s economy is suffering. The USD/CYN looks too low at the current rate of 7.0925. The Shanghai Composite (SSE) has fallen to nearly 2,704 and touching lows from early February of 2024. The SSE is down roughly -13.46% over the last year. The Chinese government’s desire to manage the economy with a tight grip continues to produce fractures and should be reconsidered.

2. Gold: The precious metal finished Friday’s trading near 2,577.00. Yesterday’s values hit all-time record prices for Gold versus the USD. The 2,586.00 vicinity was touched before reversing slightly lower. The ability to remain near apex highs going into the weekend highlights large traders likely still have a taste for gold and that long-term investors remain bullish. Is nervousness due to perceived global central bank ineptitude helping to create more gold buying? Short-term speculators need to remain careful within these heights.

1. FOMC Prediction: The European Central Bank’s decision to cut by only 0.25% this past Thursday is almost a sure sign the Federal Reserve will mirror the ECB on the 18th of September. Last week’s prediction by AMT that the ECB would only cut by 0.25% proved to be true, and our outlook for the FOMC’s Federal Fund Rate decision is also a cautious 0.25% cut. While the U.S Consumer Price Index and PPI info published this past Wednesday and Thursday showed inflation is under control, the data also shows a stubborn streak. However, an erosion of inflation is taking place and while the target ‘neutral’ rate is likely being debated behind closed doors, it is also apparent to most outside observers that the Fed is being too cautious and will be ‘forced’ to cut this coming week, November 2024, and early in 2025.

Content

postR196

AMT Top Ten Miscellaneous Notions for the 30th of August 2024

AMT Top Ten Miscellaneous Notions for the 30th of August 2024

10. Ellis Park, Johannesburg: The Springboks will face the All Blacks on Saturday in round three of the Rugby Championship. One of the greatest rivalries in sports will match South Africa who is looking to cement their current team’s legacy as one of the best rugby squads ever, versus New Zealand who is looking for revenge having lost to the Springboks in the World Cup Final in October 2023.

9. Labor Day: Short-term speculators should be mindful that today’s volumes may be thin due to U.S financial institutions allowing employees to leave early for a long weekend. While all the major U.S exchanges will be operating, transaction volumes will become lackluster as the day progresses with the last U.S summer holiday approaching.

8. Precious Future: Gold is traversing around 2,520.00 USD per ounce this morning, as Bitcoin is near 59,500 USD as of this writing. The precious metal was around 2,000.00 much of February, while Bitcoin began flirting with 59,000 and 60,000 in late February after starting that month near 43,000 USD. While influencers proclaim the future is digital with Bitcoin, Gold continues to shine and has a historical track record as a store of value.

7. Pavel Durov: The CEO of Telegram was released on Wednesday after posting 5 million EUR as bail, he must stay in France and faces a handful of charges. Russia, the UAE and high profile people, including Elon Musk, have publicly criticized France for Durov’s arrest last Saturday. Free speech advocates are largely against the arrest of Durov, while France contends Durov has not been forthcoming about data which has been shared on Telegram to conduct criminal enterprises. Julian Assange was arrested in 2019 in Britain and was only released in June of this year, promptly leaving for Australia.

6. Commodities: The price of WTI Crude Oil is near 76.00 USD and remains in a fairly stable range, Cocoa remains within sight of 9,000.00 as it trades around 8,950.00 this morning. And the prices for Coffee via Robusta and Arabica continue to flirt with apex highs. Day trading wagers on these commodities should be done carefully before the U.S holiday.

5. Art of Speaking: Kamala Harris is being criticized for her reliance on teleprompters as some pundits wonder loudly when she will sit for an unscripted interview. Donald Trump faces continued scrutiny for speaking extemporaneously, and everyone knows this characteristic is not going to change. The race for the White House appears tight. The televised debate between the candidates remains on the schedule for the 10th of September and its format may present the opportunity for verbal fireworks.

4. Eastern Europe: The Russian-Ukrainian war has been escalating the past few weeks as both sides appear to be working with the belief they need to create facts on the ground over the next few months. The potential of a victory by Donald Trump in the U.S may be pushing Russia and the Ukraine into a mode which hopes they can bolster their respective negotiating positions, this if the newly elected U.S President can get the warring sides to discuss an endgame.

3. China: The nation faces difficult economic circumstances and tries to maintain stability via Yuan and bonds interventions. Also, the foreign policy stance of China is growing tensions with the Philippines. The long standing disagreement about Taiwan’s sovereignty is well documented, but Chinese naval activity in the South China Sea is raising alarm bells among some political analysts. Manufacturing PMI results will be published by China early on Saturday. Economic data from the nation is being inspected by foreign investors carefully who are looking for long-term yields, but are troubled about transparency and the potential of sudden policy changes.

As an aside, APEC will conduct its annual meeting in November from the 10th until the 16th in Peru. Both Joe Biden and Xi Jinping will attend. Depending on Biden’s health and the outcome of the U.S Presidential Election on the 5th of November, this Asian-Pacific Economic Cooperation Forum will prove important.

2. U.S Data: Jerome Powell’s capitulation last Friday via his public statement that the Fed needs to cut interest rates fueled a weaker USD. Forex has seemingly priced in a combined 0.50% basis cut via the Fed for September and November. Yesterday’s stronger than anticipated U.S GDP growth and inflation reports however created headwinds, which caused outlook jitters. Today’s Core Personal Consumption Expenditures Price Index monthly gauge is expected to come in with a gain of 0.2%. If the inflation report can match the anticipated result this may calm Forex, equity indices, and Treasury yields before going into the long holiday weekend. Next Friday U.S Non-Farm Employment Change numbers will be published. Today’s trading may be muted because of thin volumes, but day traders should expect volatility to increase starting next Tuesday.

1. Competition: Nvidia was valued around 47.50 USD per share this time last year, as of today the price is near 117.60. Intel’s value was approximately 34.50 USD this time last year, as of today the price is about 20.13 per share. Intel appears to be valued as a commodity supply company nowadays by some investors, while Nvidia’s outlook remains within the auspices of a highly anticipated technological future. Where will both companies values be this time next year?

postR179

AMT Top Ten Miscellaneous Rays of Light for 23rd of August

AMT Top Ten Miscellaneous Rays of Light for 23rd of August

10. Word of the Day: Like crepuscular animals which are active during twilight, large market players are ruminating as their summer hiatus draws to an end over the next week and a half. Plans for coming hunts are being formulated as leisure concludes for financial institutions preparing to work in the shadows.

9. Scrolling Failures: Lack of solid results on search engines are becoming a growing annoyance. Is it just us? An abundance of poor information via defined searches on the internet and finding what is sought is becoming increasingly problematic. Is AI being allowed to do too much while still too dumb? AI doesn’t know when it is wrong. Competitors to Google and others are sought.

8. How Dare Us: The postponement of imposed dates regarding energy policy changes are multiplying. The end for the classical use of oil, coal and nuclear is not near. Efficient power is evolving, but this will have to include ‘antique’ generation and grids. The demand for electric vehicles are being confronted with declining sales via U.S consumers. Tangible technology needs precise planning, not apocalyptic rhetoric which tries to scare people.

7. Middle East Calm: The storm is being limited within a tea cup for the moment. The potential for a dangerous boiling painful mess still exists. ‘Serenity now’ remains a mantra for those who need to pay attention as chagrin and anxiousness mix.

6. Fed Retreat: The FOMC Meeting Minutes released this week showed some Fed members remained cautious, while others banged the drum louder regarding interest rate cuts. However, a Fed Funds Rate reduction is almost a 100% certainty for the 18th of September. The question now is what the Fed will do in November. Fed Chairman Powell and a slew of other renowned global central bankers will speak today and tomorrow at the Jackson Hole Symposium. Financial institutions largely believe they know what is going to be said, but comments from Bank of Japan and Brazilian leadership could prove to be informative and entertaining for central bank nerds. Monday could be volatile for USD/BRL traders.

5. VIX: The CBOE’s Volatility Index climbed to the 56 vicinity on the 5th of August as panic grew via widespread overreactions to hyperbole ripping through the markets. The fear gauge is near the 17.55 ratio as of this writing. Market calm has resumed across the board as financial institutions and day traders have been able to achieve a pleasant tone again. Traders who use the VIX as a template regarding the potential of risks suddenly cascading into assets should keep their eyes on the index, which went to a low around the 14.45 mark on Monday. Yet, the slight incremental climb the past few days could be coming from folks still speculating on volatility which may not develop near-term.

4. Barometers: Gold is lingering slightly below 2,500.00 for the moment, this after having achieved a record high on Tuesday when it touched the 2532.00 apex. WTI Crude Oil is near 74.00 USD per barrel and is maintaining a polite value range. Speculatively, Cocoa is again above 9,000 USD per ton and Bitcoin has fought its way above 61,000 this morning. Risk appetite remains stable for the moment.

3. Forex: USD/JPY, EUR/USD, even the USD/ZAR have been able to hold onto their recent trends as USD centric weakness remains viable. Traders who were looking for huge moves in FX this week have likely been disappointed. Retail speculators need to understand financial institutions have been positioning for a weaker USD since the tail end of July. Market players may be quite pleased regarding current Forex equilibrium, which may allow technical traders the ability to take advantage of existing behavioral sentiment, this as reversals flourish and the next big wave of impetus is awaited. Next Thursday’s U.S Preliminary GDP numbers may deliver some noise.

2. Cassandras: Market experts who proclaimed a long-term stock market crash in early August have crawled back into their caves to take cover and percolate their next fear mongering tactics. This after the latest round of predicted catastrophes have vanished. While the major U.S stock indices are not at record highs, they have recovered plenty of lost ground and appear ready for more days in the sun.

1. Political Winds: The curtain closed on the Democratic National Convention in Chicago last night without a serious hiccup. Kamala Harris and Donald Trump now enter a crucial phase of campaigning, and will get plenty of attention as they go into attack mode. The next big event for Harris and Trump will be their televised debate on the 10th of September. Will the outcome prove to be a devastating storm for one of the candidates?

postR196

AMT Top Ten Miscellaneous Remarks for the 14th of July 2024

AMT Top Ten Miscellaneous Remarks for the 14th of July 2024

10. Words of the Day: Political rhetoric is using platitudes and subterfuge camouflaging verbal nonsense, masking a vacuum of non-results and causing fatigue of populist promises.

9. Harris Prediction: After the NATO press conference in which Biden was more lucid but still made mistakes, it is beginning to feel like Kamala Harris is being given room to audition for the Presidency by the Democratic machine. If her polling numbers show improvement over the next couple of weeks, look for Harris to replace Biden at the DNC in Chicago, if her polling numbers are not good enough in the eyes of the elite power brokers, it is possible Biden may be asked to give up his delegates, allowing for an open convention.

8: Zombie Inflation: Data results via the U.S CPI caused a reaction in the broad markets, and volatility in Forex. While the broad monthly Consumer Price Index number on Thursday was minus -0.1%, the PPI numbers on Friday came in higher than expected causing some to feel that inflation remains a plague. However, if the Producer Price Index was interpreted as being higher because rising prices are coming via more expensive employee costs (which might see an end to the cycle sooner rather than later if jobs data continues to weaken) this is why there might not have been a violent Forex reversal on Friday. And Consumer Sentiment numbers from the University of Michigan came in below expectations again, and inflation expectations via the consumer survey showed some erosion.

7. Federal Fund Rates: Financial institutions have clearly begun to factor in the belief an interest rate cut will occur in September. The Fed which has been cautious consistently the past seven months may now have enough ammunition to consider becoming more dovish. A September interest rate cut has certainly been factored into Forex and Treasury yields, and there is a growing tide of sentiment which believes the weaker GDP numbers combined with the potential of less inflation could spark additional Federal Funds Rate cuts this calendar year. Outlook fueled by optimism regarding a more dovish Fed could be a factor in the markets the remainder of July.

6. Gold and Silver: Commodity prices are soaring as speculators pursue bullish trends. Gold finished this week above 2,410.00 USD. Silver is traversing above 30.00 USD per ounce for the first time since 2011 and 2012. These two metals are not always correlated, and day traders should remember Silver remains a rather easily mined commodity which sometimes influences downwards pressure because supply can be increased. Having said that, Gold and Silver have had solid bullish trends since February of this year.

5. Thaw: Bitcoin is near 60,000 as of this writing. The crypto winter has seemingly ended and many folks are standing in the sunlight and proclaiming long-term projections of Bitcoin as it maintains a higher price range. It should be remembered the most significant percentage of trading volumes within cryptos reside heavily within the top tier, and the ‘assets’ ranked lower remain in wagering cesspools. Cryptocurrency remains speculatively dangerous, and largely a place to move illicit cash with the perception the money can be kept ‘dark’.

4. USD/JPY: The Bank of Japan won last week’s game of fire. The U.S Consumer Price Index numbers dealt a blow to the blind fury of speculative buying in the USD/JPY, and there is also a belief among many that the BoJ added onto the selling momentum of the currency pair too with a well timed intervention. The currency pair which was near the 161.640 juncture suddenly dived to nearly 157.420. The USD/JPY has gone into this weekend near the 157.900 ratio. The USD/JPY saga is not finished yet, and froth via bullish endeavors remains dangerous. Day traders here have been warned.

3. China: Friday’s Trade Balance numbers were good, compared to the rather weak CPI results seen on the 10th of July which were negative. China’s Communist Central Committee begins a Plenary Session tomorrow until the 18th. Will they speak in platitudes? The USD/CNY has certainly seen a ‘soft’ devaluation since February of this year, but the currency pair did go into the weekend near the 7.2500 mark which is off the high of 7.2765 seen this past Thursday. China still must improve consumer sentiment domestically and this remains a difficult struggle as ramifications from the implosion in China housing values mires the landscape. GDP numbers will come from the nation on Monday.

2. Behavioral Sentiment: Equities and indices, Forex, and commodities are all experiencing risk appetite permutations. While it might be tempting for retail traders to bet on lower reversals of trends, sometimes its much easier to simply ride optimistic waves. Certainly there will be days when financial assets struggle, but the apex heights of the Dow Jones 30, S&P 500, Nasdaq 100 should be treated with respect. Treasury yields are at mid-term depths and appear ready to traverse lower.

1. Trump: The attempted assassination of Donald Trump on Saturday in Pennsylvania will galvanize his supporters and likely push many people towards voting for him November. The amount of vitriol Trump has endured from his political opponents including the highest echelons of the Democrats and many in the media needs to be contemplated and quieted. Opposition to political ideology is fine, but the use of hyperbolic musings has led the U.S to a dangerous place. It would be wise for pragmatic adults to rejoin political discourse. Traders should watch the financial markets early this week to see if the U.S political front causes a reaction.