Negotiation 20260415

Checkmate: Who is Afraid of Negotiations?

President Trump has Laid a Trap for Iran and China

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 15th of April via The Angry Demagogue.

Both the defeatist camp and the “victory now” group see the advent of negotiations between the United States and Iran as a defeat for the United States and Israel. The argument by the defeatists is that victory was supposed to be quick and now we are stuck and looking for a way out since no one saw Iranian use of the Straits of Hormuz coming. The defeatists claim that only negotiations can end the conflict and anyway, Iran never should have been considered an enemy so the United States and Israel have overemphasized Iranian danger. The defeatists do not want a military victory and assume defeat as the moral choice.
For the victory now group, negotiations are seen as a weakness by the United States and Israel since a further pummeling of Iranian military and civil assets is the only thing that will guarantee a non-nuclear Iran incapable of threatening their neighbors – and the Straits of Hormuz. If there is no regime change, this group says, then there is nothing left to do except continue fighting until the regime falls or until there is nothing left for them to fight with.

A third group sees tactical victory and strategic defeat – or at least strategic stalemate which has forced both sides to the negotiating table meaning for the United States and Israel it is at least a temporary defeat since a stalemate is not victory.

Which if any of these assessments are correct? Or is there a third explanation that says that the negotiations themselves are a victory even if the absolute goals of the war, removing Iran from the Chinese-Russian axis has yet to be accomplished. We won’t retread the arguments about how much punishment the Islamic Republic has endured nor will we agree that as long as they have one missile launcher and enough Kalashnikov’s to stay in power there is no victory.

However, we do agree as we argued in The Art of the (Middle Eastern) Deal, that negotiations done incorrectly will be a precursor to defeat. Each time there is a rumor of continued negotiations there is panic from the victory now crowd, assuming that this time, President Trump will cave into Iranian demands. The defeatists on the other hand assume that the fact of negotiations is a good thing since military defeat is assured. The Macron-Starmer wing of the defeatists are trying to pretend to be the grownups in the room, as they want to be part of the opening of Hormuz but not be on “either side”. Their attempt to insert themselves into the situation but not on “either side” puts them a step or two below Pakistan but maybe one level above Sanchez’s Spain in influence.

Back to the real world. While the negotiations are between two countries and hosted or mediated by a third, there are two other countries involved on the Iranian side – China and Russia, and four on the American side – Saudi Arabia, Qatar, UAE and Israel. Each has its own interests and in general most of those mesh with the main participants in the talks. American allies need a non-nuclear Iran that is weak enough that it can’t threaten those countries and America has the same interests. Although a non-Islamist regime would be the best guarantor of that, it is not something that can be done only from the outside.

Russia and China need an American defeat more than anything especially after the world has witnessed the poor performance of their weaponry. They will try to re-arm Iran in order to create a war of attrition with the United States that America will be forced to end. This is where the interests of Russia and China clash. Russia would love the damage if not the destruction of Persian Gulf oil fields and refineries but the subsequent rise in oil prices would further damage China’s increasingly fragile economy. If Putin’s Russia has a goal of survival, self-enrichment and embarrassing the west (one seems to go with the other for Putin) and China’s goal is to dominate the Indo-Pacific, then the survival of Iran is a nice to have for Russia but a need to have for China.

China does not have the will and/or ability to do what is necessary to defend their Iranian ally, so they are really in a no win situation without a nuclear Iran. The American insistence on a complete end to the Iranian nuclear program is a shot right at the Chinese global strategy. Without the Iranian nuclear umbrella, China will depend on the United States for the flow of oil to their country.

As for Iran, they have one goal in this war and that is to survive with enough firepower intact to continue their quest to destroy Israel, rid the middle east of the United States and eventually to bring the Sunni Arab states in the Gulf under their thumb. As opposed to a dictatorship that is “only” corrupt and can be bought, they also need their theological goals met – and that starts with the destruction of Israel and genocide of the Jews. That, like Hitler’s Germany is an aim greater than the goal of winning the war.

They have come to the negotiating table because they felt that a continued bombing attack by the U.S and Israel and possibly the Gulf states risks their goals more than negotiating. This is the same reason that Hamas agreed to release the hostages as they saw the needed respite from the IDF in order to retain control of at least part of Gaza. This could be seen as Iran’s last ditch effort to survive and are using the cease fire to reconstitute their industry, re-arm and most important – to dig out and reach their underground missile cities

So why has the United States come to the negotiating table? Is it a show of weakness? An attempt to re-arm and bring more troops to the region? Is there a regime change plan that needs time to take share?

As for the last of these, over that last two days there have been car bombs and shootings at Basij checkpoints and the commander of Basij forces of Teheran has been assassinated. There is clearly something going on inside of Teheran and the head of the Mossad, David Barnea stated yesterday that the Iran mission will not end until there is regime change. Not only are the IRGC using the cease fire to regroup, so, it seems, is the opposition.

In addition to continued operations in Iran, the blockade of the Straits of Hormuz, an act of war in itself, tells Iran not to see negotiations as a sign of weakness by the United States, but rather as an opportunity for the US to widen their attacks beyond bombs and missiles.

The move from bombing to negotiations have trapped both Iran and China in a place where neither can win unless the U.S, against all statements by the President, VP, Secretary of State and Secretary of War, decides to fold.

Iran is trapped in a place where if they starts to shoot they will have their economy in worse shape than it is now and they no longer are lords of the Straits of Hormuz – THE trump card (no pun intended) that the defeatists have been gloating about.

China is trapped in a place where they need the United States to guarantee their flow of oil and their ally is no longer able to sell it to them on the cheap.

Negotiations have taken away the two things that were pressuring America and its allies – Iran’s daily missile attacks and their veto over the Straits of Hormuz. While they are using the time to try and rebuild what has been destroyed, that will take so long that, assuming no surrender by the United States, will be irrelevant to this war and the next -if there is one.

President Trump and the United States have set a trap for Iran and China and there does not seem to be a good way out. That doesn’t mean Iran will recognize it and end their genocidal quests, but it does mean that their path to victory has been shut down.

Checkmate?

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

You can follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/
Copy and paste the text from AMT that you want to share

postN87

AMT Top Ten Miscellaneous Morsels for the 12th of April 2026

Optimistic Hopes Appear Ready to Fade into the Distance

10. B-ball: The NCAA Men’s Basketball Championship concluded early last week with a rather resounding outcome for the University of Michigan who won their 2nd Men’s trophy, the first one coming in 1989. Michigan dismantled the Arizona Wildcats and then handled the Connecticut Huskies. The NBA playoffs will start this coming week. The Oklahoma Thunder and the San Antonio Spurs are getting a lot of attention, and the Denver Nuggets might have something to offer.

9. Trump: A week of optimism now leads towards threats of additional noise. Peace talks held in Pakistan appear to have failed this weekend, and now another countdown has begun as the Iranian conflict appears ready to escalate. The U.S White House and President Trump will certainly make more noise in the coming days.

AMT Top 10 for the 12th of April 2026

8. Logistics Advertising: Kit Kat and Nutella have been rewarded with massive exposure. The Kit Kat truck heist of 12 tons of product (reportedly said to be in a special F1 designed candy bar theme) made headlines. Kit Kat’s owner, Nestle, was obviously content with the free publicity and proof of demand. And a jar of Nutella floated across the Artemis 2 spacecraft unexpectedly this week, gaining international attention and sparking smiles from fans of the Italian chocolate hazelnut spread.

7. Creator: Yet another candidate accused of being Satoshi Nakamoto has been produced. Blockstream’s CEO Adam Back has been named by the N.Y Times as a potential creator. In the meantime, the real question is whether anyone but Iran (as they run their illicit shadow economy), Michael Saylor of MSTR and a few big whales consisting of institutions and hedge funds are really paying any attention to BTC anymore. The BTC/USD price as of this morning is around $71,600.00. Bitcoin was traversing near $126,000.00 in the first week of October 2025.

6. Greenback: USD/JPY 159.240, EUR/USD 1.17225, USD/ZAR 16.38540, USD/INR 93.0480. USD centric strength may prove solid this coming week and other currencies may suffer a bit.

5. Sideways Shimmer: Gold finished the week near $4.745.00, roughly $100.00 above its starting point last Monday. U.S 10-Y Treasury yields went into this weekend around 4.34%. Shifting outlooks this coming week will likely ignite turbulence in both assets.

4. Blind Eyes: More than a handful of U.S politicians have been featured as big winners regarding their stock trading abilities. Their gains far exceed the winning percentages of the overall returns made by indexes (as a benchmark). Little has been done to stop what many view as insider trading. There are many forms of political corruption around the world. However, a variety of places and people, including Americans seem to accept this potential misconduct. The ‘Stop Insider Trading Act’ has been brought forth in the House of Representatives and Senate, but the legislation may simply meet a slow death and disappear.

3. Inflation: U.S interest rates via the Federal Reserve will be held in check at a minimum over the next few months. The higher costs of energy will certainly seep into prices for transportation, manufacturing and agriculture. Fed Chairman Jerome Powell may be quite content to leave his position May the 15th. The next Fed FOMC interest rate decision is due on the 29th of April.

2. Strait of Hormuz: WTI Crude Oil closed above $90.00 going into this weekend. When futures markets open early on Monday, the price of the commodity is likely to rise via increased anxiousness which will build into the mindsets of large players today because of the failure of peace talks in Pakistan. The price of Crude Oil remained high last week, only moving to a low of around $85.00 this past Tuesday, showing cautious attitudes remained. Prices above $100.00 will likely become a new target quickly for some who bet. Will an early spike upwards this week then start a counter reversal lower, or will a climb become sustained?

1.  Risk Off: The S&P 500 and Nasdaq 100 will get plenty of attention this coming week as behavioral sentiment remains fragile. Having skirted near its 200-days moving average lows in recent weeks, the indices have gained handsomely since the 31st of March. Will the upwards momentum come to an abrupt end this week, or have financial institutions been able to digest their nervousness and will they show a capability of remaining buyers?

Copy and paste the text from AMT that you want to share

Outflows 20250220a

India Insider: Macro Stress a Capital Flow Problem, Not a Trade One

India Insider: Macro Stress a Capital Flow Problem, Not a Trade One

Editor’s note: This article was originally written in January 2026. It has been updated to incorporate developments through February 2026, including the U.S – India interim trade agreement and subsequent capital flow data.

India is currently experiencing what can best be described as macro stress. By macro stress, we mean pressure across the broader economy that shows up simultaneously in the currency, financial markets, and capital flows, rather than a problem limited to one sector or company. In India’s case, this stress is visible in a weak rupee, persistent foreign investor outflows, and rising concerns about equity valuations.

This stress is often misinterpreted as a trade or export problem. In reality, the pressure on the Rupee and the growing fragility in equity markets stem primarily from the capital account, not from collapsing exports or remittances. Even as the U.S Dollar softens – helped by Federal Reserve rate cuts and renewed trade tensions under U.S President Donald Trump, India continues to struggle to attract foreign capital, exposing a deeper structural imbalance.

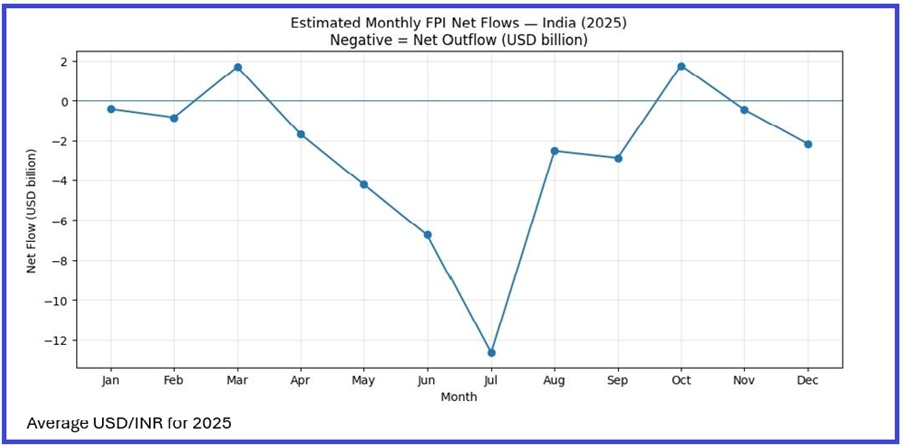
Source: NSDL (FPI Equity Flows): Reuters and author’s calculations.

Recent weakness in the USD would normally support emerging market currencies and risk assets. This time, however, the response across emerging markets has been uneven. Capital has flowed toward economies linked to artificial intelligence, semiconductors, and commodities, as well as toward markets where valuations have already adjusted. South Korea, Hong Kong, Chile, and South Africa have all benefited from this rotation. India has not.

The Rupee’s weakness reflects this divergence. USD/INR continues to trade around ₹91.5–91.6 despite the absence of a sharp deterioration in India’s trade fundamentals. Services exports, particularly IT services, remain resilient, and remittances continue to provide a steady source of foreign exchange. This brings us to the current account.

The current account represents a country’s net trade balance with the rest of the world, including goods, services, and remittances. India runs a current account deficit, meaning it imports more than it exports. While this deficit persists, it is manageable at present, supported by stable services exports and remittance inflows.

The real problem lies in the capital account, which tracks investment flows such as foreign investors buying or selling Indian equities and bonds. When foreign capital flows into the country, it helps finance the current account deficit. When it flows out, pressure builds quickly on the currency and financial markets.

Foreign capital is neither entering India in sufficient scale, nor remaining invested. Portfolio outflows have become persistent, and this has emerged as the dominant driver of currency pressure. In calendar year 2025, foreign portfolio investors sold approximately USD 19–20 billion worth of Indian equities, marking one of the largest annual equity outflow episodes in recent years. Importantly, this selling has been sustained rather than episodic, pointing to a structural reassessment of India’s growth outlook and valuation premium rather than a temporary risk off shock.

Crucially, this capital flight is not the result of a collapse in exports to the United States. Despite tariff concerns, the U.S remains India’s largest export destination. Between April and December 2025, Indian exports to the U.S rose to roughly $65–68 billion, compared with $60–63 billion during the same period last year. Trade flows, for now, are holding up better than sentiment suggests.

The effects of capital account stress are most visible in financial markets. Indian equities are failing to attract foreign inflows as growth momentum weakens. Market leadership has narrowed, with headline indices supported by a small group of large-cap stocks, while consumption-sensitive sectors such as FMCG remain under pressure.

This dynamic fits squarely within the balance of payments framework described by Professor Michael Pettis. He described, “a country cannot sustainably run a current account deficit without stable capital inflows. When capital inflows weaken, the adjustment shows up through a weaker currency, tighter financial conditions, and pressure on asset prices.”

Indian equities now trade at some of the highest valuation multiples globally, supported largely by domestic retail and mutual fund flows. However, domestic capital is structurally constrained, while global investors can freely reallocate. As Bloomberg’s Andy Mukherjee recently noted, Indian cement stocks now trade at higher valuations than Hong Kong Tech stocks showing the exuberance of Domestic equity capital chasing local themes.

At a deeper level, India’s vulnerability reflects a structural imbalance between savings and investment. Domestic savings are insufficient relative to the economy’s long term investment needs, and the financial system lacks the institutional capacity to consistently channel savings into productivity enhancing investment. As a result, growth has become increasingly dependent on mobile foreign capital – capital that is cyclical, return sensitive, and easily reversible. It is this dependence, more than any near term trade shock, that leaves the Indian rupee vulnerable when global capital flows turn cautious.

Update: The US–India Interim Trade Agreement (February 2026)

Since this article was first written, a significant development has reshaped the near-term outlook. In early February 2026, the United States and India reached an interim trade agreement. As part of the deal, the US lowered its reciprocal tariff on Indian goods from 25% to 18%. President Trump also signed a separate executive order removing an additional punitive 25% tariff that had been imposed as a penalty for India’s purchases of Russian oil, meaning the effective tariff burden on Indian exports had, at its peak, approached 50% before being brought down to 18%.

The announcement acted as an immediate sentiment catalyst. The rupee, which had been trading in the ₹91.5–92 range under stress conditions, strengthened on the news, touching ₹90.30 before settling near ₹90.70. Foreign portfolio investors, who had spent most of 2025 as relentless net sellers, turned net buyers in the first week of February 2026, purchasing approximately $897 million worth of Indian equities.

These are meaningful moves. After 18 months of persistent underperformance relative to other emerging markets, India’s excessive valuation premium has moderated toward historical averages, which may create better entry points for global capital going forward.

Copy and paste the text from AMT that you want to share

postN76.1

India Insider: Strategic Memory and Why Unilateral Power is Resisted

India Insider: Strategic Memory and Why Unilateral Power is Resisted

After Independence, India was often described as “tilting” toward the Soviet Union. In reality, this was the outcome of India’s pursuit of Non-Alignment at a time when the United States was actively backing perceived rogue actors in South Asia, most notably Pakistan. What appeared as ideological preference was, in fact, strategic necessity born of hard experience.

The Soviet Union supported India on core security concerns when few others would. The first major Soviet defense deal was not merely a weapons sale. It included licensed production in India through Hindustan Aeronautics Limited, full technology transfer, and made India the first non-Communist country to receive the MiG-21. This distinction mattered. India was treated as a sovereign partner capable of absorbing technology, not as a dependent client expected to align unquestioningly.

By contrast, Washington’s alignment with Pakistan was driven by Cold War geopolitics rather than South Asian stability. Despite repeated military coups, wars with India, and regional destabilization, the United States armed Pakistan, provided diplomatic cover during conflicts, and sustained the relationship through military rule and nuclear proliferation. These experiences deeply shaped India’s strategic culture and explain its enduring emphasis on autonomy, redundancy, and diversified partnerships rather than alliance dependency.

This history is one of the central reasons India resists Washington dictating regional dynamics. South Asia, in New Delhi’s view, is not a chessboard for external powers to reorder at will.

Democratic Republic of the Congo Example

The same pattern is visible beyond Asia. Take the Democratic Republic of Congo. After decades of horrific colonial exploitation, the Belgians realized by the mid-20th century that they could not hold on indefinitely and exited abruptly, having never prepared the country for self-rule. What they left behind was not independence, but a political vacuum. The United States and the United Nations intervened, but their actions were shaped less by concern for Congolese society than by geopolitical rivalry, ideological competition, and racial hierarchy.

The assassination of Patrice Lumumba destroyed the Republic of the Congo’s (as it was known then) only credible attempt at building a unified nationalist state at independence. The dictatorship of Mobutu Sese Seko that followed did not merely fail to develop institutions; it actively hollowed them out. Corruption became a governing principle, loyalty replaced competence, and the state turned into a vehicle for extraction. Today’s instability in the Democratic Republic of the Congo is not a governance failure in isolation—it is the predictable outcome of a political system designed to rule without building state capacity. For countries like India, this is not ancient history, it is a warning.

Washington’s unilateralism reinforces this mistrust:

The recent military operation to remove Venezuelan President Nicolás Maduro without U.S Congress authorization, international legal justification, or an imminent threat would have been unthinkable as recently as the first Trump administration. It became possible in 2026 only because of congressional capitulation, judicial immunity, and the transformation of an apolitical defense establishment into a politicized instrument of executive power. To much of the world, this signals that restraint is no longer embedded in American decision making.

Europe exposes another contradiction. The post war order was built on liberal democracy and collective security through NATO. When that order is weakened by unilateral action, trust erodes, even among allies expected to align automatically.

Even before Trump, the U.S – India relationship remained cordial rather than fully strategic. Before 9/11, India was the most natural regional ally against Al-Qaeda, yet Washington lacked patience and local understanding to navigate India’s complex democracy and nationalism. That failure was not tactical, it was conceptual.

India’s neutrality today is deliberate:

It prioritizes diplomacy over military actions that violate international law. India sees a multipolar world emerging, not as disorder, but as the end of unchecked unilateral supremacy. This is not ambiguity. It is a strategic memory.

post278

Behavioral Sentiment: False Narratives and Noisy Realities

Behavioral Sentiment: False Narratives and Noisy Realities

The past handful of months in Forex have provided day traders problems if they have been trying to pursue steady trends. Constant flashes of rhetoric and news pervading tariff implications, U.S Federal Reserve interpretations from various media and analytical corners, and mixed economic data has caused a rather mired reality for speculators trying to operate.

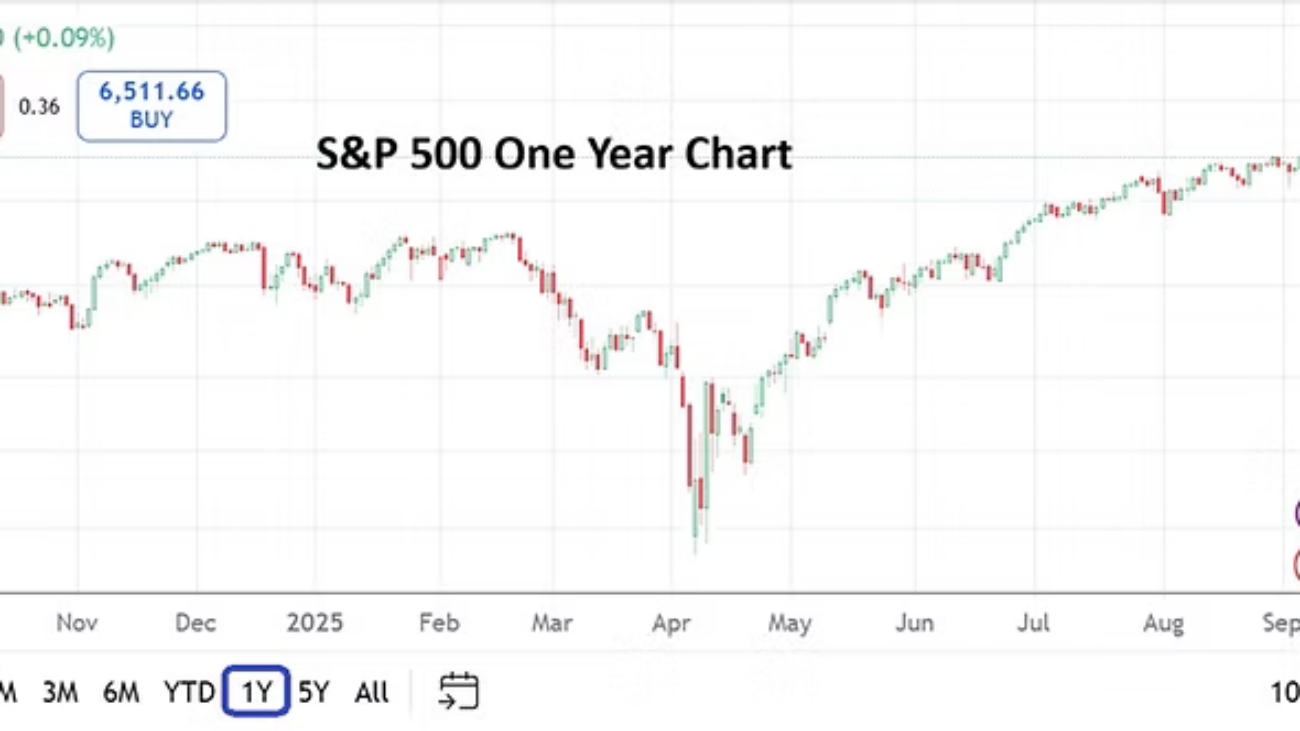
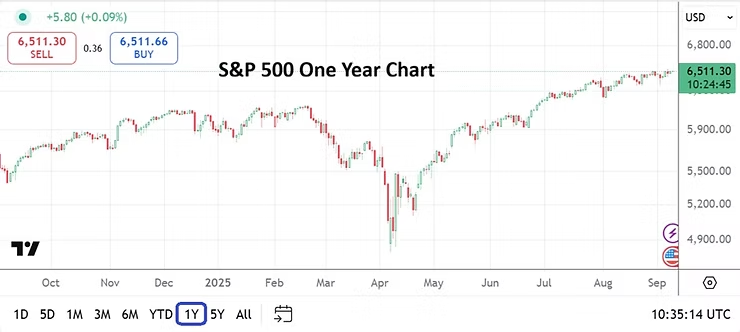
S&P 500 One Year Chart via Futures CFD Trading on the 9th of September 2025

However, if the noise is turned down by day traders and sometimes given less importance regarding potential influences, signals become visible and some perceptions can be looked upon as roadmaps. While many want to to throw their hands up and proclaim some sort of developing economic meltdown and a coming apocalypse, the major U.S indices are actually performing quite well as a barometer. The S&P 500 is continuing to challenge all-time values. Yes, the Nasdaq 100 and Dow Jones 30 are not marching in lockstep with the S&P 500 to new highs, but they are not far behind. The stock market has never guaranteed people an ability to constantly move upwards, but it does offer the potential to judge outlook and mid-term sentiment.

The USD has been extremely choppy since the start of this year, this as the Trump administration has taken over, but its trend towards weakness has been rather clear. The EUR/USD and GBP/USD have done reasonably well regarding mid-term strength. Yes, the USD/JPY has produced whipsaw movements and the Japanese Yen remains awkward, but this is a direct reflection of mitigating Japanese government policy (some may call it incompetence) regarding its ability to manage fiscal concerns, interest rates, and fight deflation and now inflation (which has been going on for a few decades).

Gold is traversing record heights and is showing signs of sustaining values above 3,600.00 as of yesterday. After languishing (albeit within elevated realms) near 3,350.00 the past handful of months with prevalent volatility, the precious metal has bolted out of its consolidation. And the likely reason for this is the anticipated Federal Reserve policy changes regarding interest rates. 10 Year U.S Treasury yields have also been pushed lower recently – this as financial institutions await a definite cut in interest rates by the Fed on the 17th of September. But folks who believe a 50 point basis reduction is coming late next week are likely wrong.

The Federal Reserve under Chairman Jerome Powell has been quite conservative, this will probably not change next Wednesday. It is more likely a cut of 25 basis points will take place on the 17th, and the FOMC Statement will offer the potential of another interest rate cut in October. Tomorrow’s PPI numbers and Thursday’s CPI results will influence the Fed’s coming meeting and mid-term outlook.

What we are left with is a broad market that is having a lot of noise applied to it by people with a variety of biases. Political bantering has reached a threshold in which it might be best to simply not pay attention to anything – but that is dangerous too. Yes, some people do talk sense, and some people do show signs of actually trying to engage in adult decision making regarding their insights, but it often feels like wanting to sound correct is more important than outcomes. Technical traders may be enjoying a quiet laugh at the expense of fundamental players right now.

However, economic data remains important. While rhetoric from the U.S White House and its opponents remains within a state of hyperbole, day traders should try to turn down the noise and pay attention to signals that long term investors continue to produce and take advantage of their sentiment. Stocks continue to be pursued and indices have done well, but volatility should be expected particularly into next week.
post261

Unpredictability of President Trump and the Markets

Unpredictability of President Trump and the Markets

Everyone wants to know what will happen in the future in the financial world. Most everyone also knows that this is impossible. However, clarity about the mid-term is a legitimate focal point that financial institutions strive. Risk managers define their considerations on assorted perspectives depending on their backgrounds.

While some may like him and others clearly are are not fans, President Trump has a reputation for wanting to get things done. His calling card for a long time has been an ability to make business deals. President Trump however has put himself in a rather difficult position and the next two weeks may prove to be an important milestone. One in which those who like the President and those who don’t will be given more credence to debate.

The Federal Reserve will announce their FOMC decision on the 30th of July. Tariff deadlines will supposedly come on the 1st of August. President Trump has made it clear he does not like the lack of aggressiveness which Fed Chairman Jerome Powell is displaying. Trump has called for the Federal Funds Rate to be cut and Powell has not acquiesced.

President Trump has openly spoken about trying to replace the Fed Chairman, but at this juncture the Trump White House knows this will be difficult unless they can prove Jerome Powell has done something maliciously. Not lowering the Federal Funds Rate because of a fear inflation will develop because of potential effects due to tariff fallout is a legitimate reason not to act. Even if the Fed Chairman is wrong, he appears to still be working on a basis which is based on an economic interpretation.

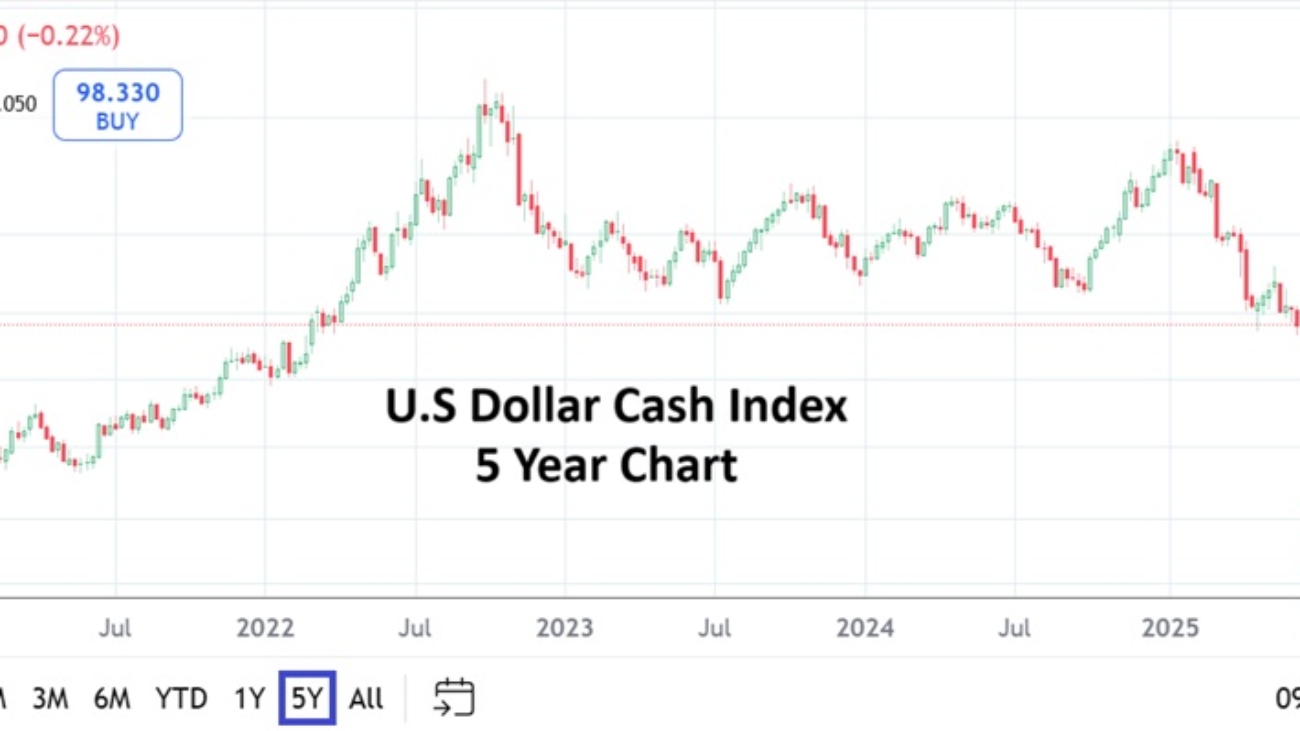
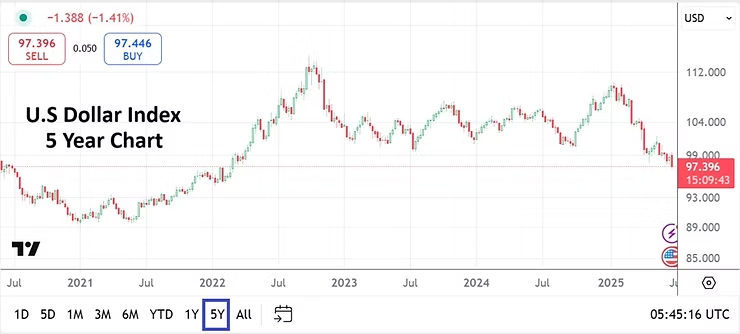
For the next two weeks the broad markets will hear about the Trump and Powell disagreement. It has been argued the Federal Reserve should have lowered the Federal Funds Rate a few months ago, clearly this was not done. However, the USD did trade with weaker sentiment in Forex from early April until the beginning of July. In the past few weeks the USD has garnered some strength, but remains within the lower part of its long-term realms via the U.S Dollar Cash Index. The weakness in the USD was likely due to financial institutions betting on rate cuts to come over the mid and long-term, and which they still believe will happen.

The upwards momentum generated recently by the USD has put the greenback in a position that seems to indicate financial institutions are transacting their cash forward orders cautiously for the moment, while waiting on the next round of impetus. And that is where Federal Reserve clarity and tariff threats now shadow mid-term outlooks.

U.S Dollar Cash Index Five Year Chart as of 21st July 2025

We have entered an unpredictable window and President Trump apparently doesn’t mind allowing a little danger into the mindsets of the financial markets. It is one thing to proclaim tremendous results and great, magnificent prospects, but how long will investors tolerate a lack of clarity regarding tariff agreements? President Trump has postponed the tariff deadlines several times and what should be considered is the potential that at some point he will have to take action to prove he means business. If the August 1st deadline is extended again this may not cause much of a shock, but it will not be met with optimism.

Instead, the main interpretation from financial institutions may be that Trump is struggling to get agreements done as he had promised. While that might lead to the idea that global commerce will continue on as is, this will certainly not help create the positive impetus which President Trump desired. At some juncture President Trump may begin to be perceived as the little boy that cried wolf. No one will pay attention and the markets will proceed without him. But President Trump will not likely let that happen, he does like attention.

The Nasdaq 100 and the S&P 500 are near record highs, so there isn’t a lot to complain about by index investors. The U.S economy has shown signs of green shoots regarding better retail sales and the recent Philly Fed Manufacturing Index. The grey area for many remains inflation, which has been coming in rather well behaved although the most recent report showed a slightly higher outcome with the yearly CPI reading. However, the Federal Reserve actually has evidence that inflation has been tame. Yes, there are questions regarding the coming influence of tariffs on the U.S economy, but for the moment inflation has not risen.

The lack of clarity and not having a mid-term comfort level which is unperturbed may be problematic for small U.S business owners that face tariff concerns on their imported goods. And the bigger picture remains unclear for large U.S corporations – but they certainly continue to try being optimistic. And this is where it gets more dangerous, plenty of perspectives are being driven (inspired) by analysts who have confirmation bias. For instance the downturn in the USD from April until early July was amplified by many who saw this as a sign the USD was being punished by foreign governments opposed to President Trump. This in fact was highly unlikely, traders need to remain alert to false narratives.

The next two weeks need to be treated carefully. There will be a running monologue among many analysts that changes daily as behavioral sentiment moves depending on what is being spoken about the Federal Reserve and tariffs. However, until there are actual answers the financial markets are likely to remain rather choppy. Self awareness will be crucial for speculators. Also, a large factor in the financial markets will be played by the U.S White House regarding how incoming results are presented. Until then day traders may want to watch technical charts and try to figure out where programmed trading lurks regarding support and resistance levels. Price velocity in Forex, bond yields and gold should be monitored.

post260

Risk Events Horizon, Fireworks and a Tranquil Marketplace

Risk Events Horizon, Fireworks and a Tranquil Marketplace

Financial narrative as always remains important and depends on who is sharing their viewpoints. As of today the U.S Senate is still discussing spending legislation which President Trump is selling as the Big Beautiful Bill. Even some Republicans don’t quite agree and it has caused political turmoil already, North Carolina Senator Thom Tillis has announced he will not seek reelection in 2026, but the markets remain stable. An agreement on the budget bill looks like it will take longer than hoped. However, day traders should remain calm.

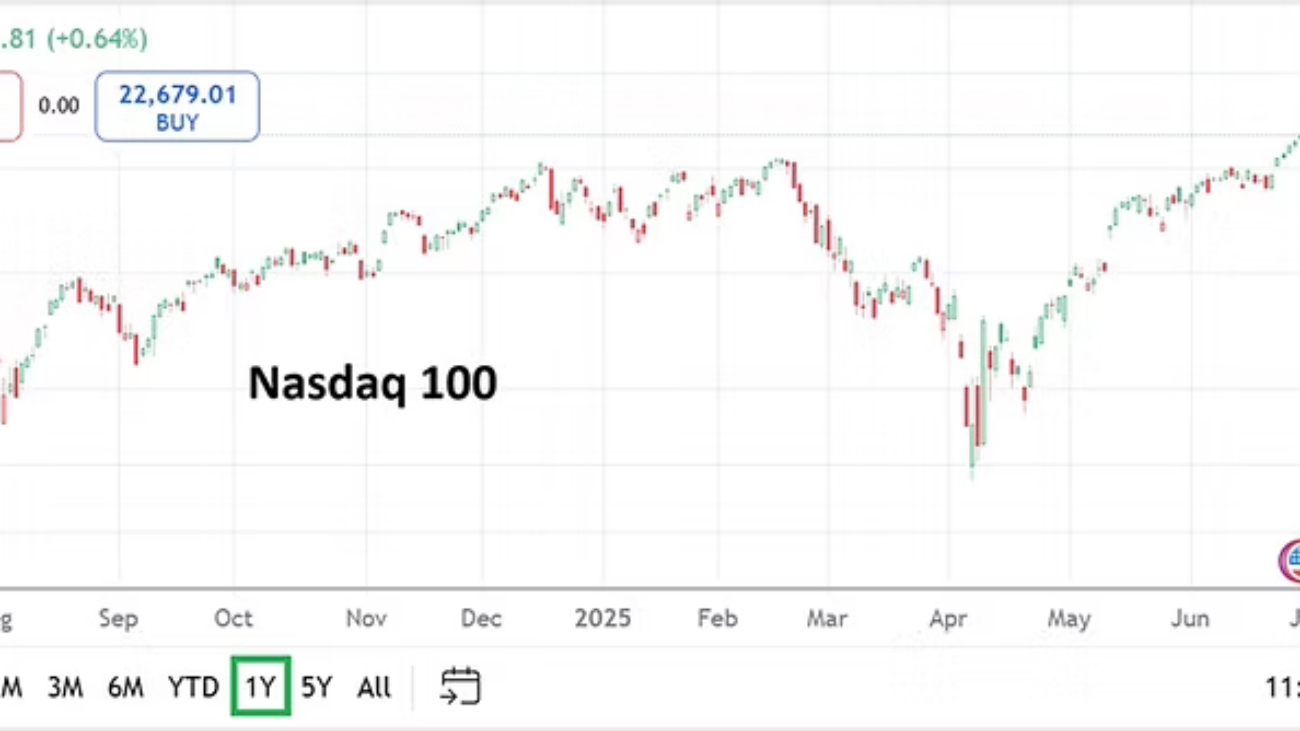
Nasdaq 100 One Year Chart as of 1st July 2025

The words scramble and race are being used by some in the media as the Senate tries to pass the legislation. If the Senate is able to approve a budget it will still have to be voted on by the House of Representatives. The deadline of July 4th is political theatre orchestrated by President Trump largely because of Independence Day symbolism. Early fireworks are ready to be sounded by some market analysts in Washington D.C if there is a legislative failure. There is a risk of irritating the White House and a danger of political backlash for certain politicians if hurdles are not jumped.

Elon Musk apparently hasn’t bought into the White House threats and has once again started to express criticism of the bill. But Musk’s condemnation seems to be falling on deaf ears the past couple of days as the work of market participants have achieved rather serene outcomes. Musk remains an important voice globally, but he has been sidelined rather effectively by President Trump in the past month. The media seemingly doesn’t have a taste for another round of Musk versus Trump recriminations and the public appears bored.

The coming Independence Day holiday means the Non Farm Employment Change numbers will be published this Thursday. The employment data may not get much fanfare if the U.S Senate is still dancing with the Big Beautiful Bill. The long holiday weekend could be made rather volatile if the legislation deadline is not met. If there is no conclusion to the Big Beautiful Bill going into the July 4th celebrations, financial institutions may preposition for the long weekend in a cautious manner, but panic doesn’t appear anticipated.

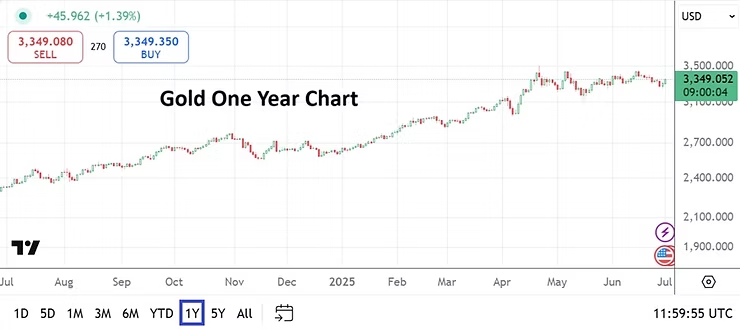
Gold One Year Chart as of 1st July 2025

Adding to the risk events horizon with dynamic ingredients are the 9th of July tariff negotiations and results which will be announced by the White House. Countries such as India are hoping for a positive outcome or at least a pronouncement of optimism that progress has been made. And this is possibly the most important role for the Big Beautiful Bill and the Tariff deadline, it is all self imposed dramatics by President Trump. The double feature for investors may be rather dull because many have seen this film before.

There is pressure on the U.S Senate to pass the spending bill, and on nations trying to negotiate new trading terms. However, many have the likely notion, that as long as the promise of solid developments are predictably claimed by the White House that global markets will stay calm.

Experienced traders in financial institutions have proven tranquil the past week, excluding the recently seen Middle East conflict – which also became a buying opportunity. The solid results seen recently might be evidence that players in equities, commodities, bonds and Forex may be viewing the anticipated fireworks with a lack of fear. While President Trump has a substantial amount of power, he also has shown the ability to take a step backwards and allow for extensions of dialogue.

The broad markets have learned to practice patience with President Trump over the past handful of months, and perhaps aren’t focused on short-term volatility, while continuing to be optimistic about mid-term harmony. The strong selling in U.S equity indices this past winter and into April has turned into bullish dreams and record values being challenged.

Yes, there will be bursts of noise from various corners that beg for attention, but financial institutions may simply go into the weekend unperturbed and feel as if they know the coming political and economic script. Day traders as always need to remain alert to risks, but keeping undisturbed if an uproar begins to reach fever pitch over the coming days may provide the best results. Market bedlam may stay rather muted much to the dismay of headlines proclaiming coming catastrophe.

post258

The Fed: Beating a Dead Horse as the Bulls want to Run

The Fed: Beating a Dead Horse as the Bulls want to Run

Yesterday’s lackluster and underperforming GDP results from the U.S highlights our often discussed doubts surrounding the Federal Reserve. While Jerome Powell definitely has a right to be ‘uncertain’ and express his concerns regarding sudden inflation emerging, he has also proven to be wrong. The Fed should have begun cutting the Federal Funds Rate three months ago.

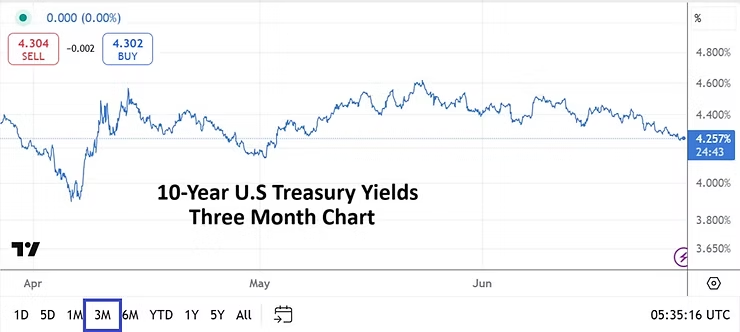
10-Year U.S Treasury Yields Three Month Chart as of 27th June 2025

Although Powell may not be a fan of President Trump, the Fed Chairman and the FOMC has the ability to be more nimble in this era. Instead of being passive about interest rates, the Fed could have lowered borrowing costs and helped spur on the U.S economy months ago instead of watching GDP numbers falter.

For all of the consternation regarding potential tariff pratfalls, the effect from President Trump’s policies have not caused massive inflation. The Fed can begin cutting rates even before the next FOMC meeting in late July, but they will not. In fact, the Fed should now cut the Federal Funds Rate by 0.50% in late July, but again they won’t. We will be lucky to get a 25 point basis cut.

The Federal Reserve remains too passive and acts as if it doesn’t have data technology which can be more proactive. Instead, Fed Chairman Powell chooses to act as if cutting the Fed Funds Rate is an academic exercise and can be done via a polite semester like manner akin to a report card. Dangerously, the U.S is paying an exorbitant amount of interest on long-term Treasuries and short-term Notes. Lower borrowing costs would also help U.S consumers. Jerome Powell doesn’t seem to care about these factors, which raises the consideration regarding his loyalties.

U.S Dollar Index Five Year Chart as of 27th June 2025

In recent weeks there have been at least two FOMC members who have suggested that interest rates need to be cut sooner rather than later. And there are some financial institutions who are clamoring for aggressive interest rate cuts throughout the calendar year and into 2026 in order to jumpstart the U.S economy, this includes Goldman Sachs and UBS. Signs of evidence that interest rate cuts will develop can be seen in the 10-Year Treasury yields which have been eroding recently. Some may claim this is a false narrative and that it is merely risk premium starting to be discounted. Nevertheless yields have lowered in the past month.

Yes, President Trump speaks loudly and delivers brawling negotiations. July 9th is another deadline for tariff agreements. However, financial institutions and many governments have learned to cope with President Trump’s backstreet tactics, which academics like Jerome Powell are not fond of particularly. U.S stock markets are hovering near highs, but still cautious because they are waiting on impetus from the Federal Reserve.

If the Fed fails to deliver an impactful FOMC Statement in late July this will not be greeted well by investors. Many believe the Fed needs to react, and it is quite apparent the S&P 500, Nasdaq 100 and even the Dow 30 are positioning for gates to be opened allowing for a bullish stampede. The USD has been weaker too the past few months as large commercial players anticipate lower U.S borrowing costs. The time for the Fed and Chairman Powell to act is now, making it clear that cuts to the Federal Funds Rate are coming.

post255

Quick Hits: Inflation, USD, China and U.S Trade and WTI

Quick Hits: Inflation, USD, China and U.S Trade and WTI

Yesterday’s weaker than anticipated CPI data from the U.S cements the realization that inflation is eroding in the States statistically in a rather consistent fashion. Today’s PPI numbers will be watched, but yesterday’s results clearly show the Federal Reserve has been far too cautious.

Media reported yesterday’s inflation results differently showing bias as some pointed out that inflation rose, compared to some outlets that showed it came in less than expected. Bottom line – inflation has been below expectations consistently and tariff concerns as of yet have not killed the U.S economy with higher prices. The Fed’s insistence on being cautious are comparable to the instincts of an overly protective parent. Day traders need to understand their perceptions are in danger of being affected by folks with confirmation bias.

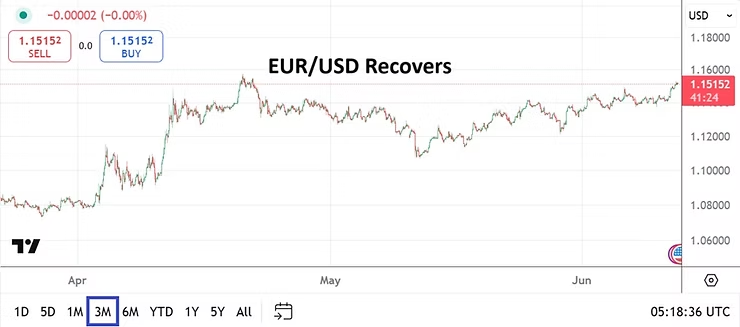
EUR/USD Three Month Chart as of 12th June 2025

The EUR/USD climbed above the 1.15000 level again yesterday confirming mid-term outlook for a weaker USD based on the notion the Federal Reserve will have to lower the Federal Funds Rate exists. While perhaps kicking and screaming against their desires to remain hawkish, the Fed will start feeling the heat to act. Next week’s FOMC meeting is unlikely to be the actual date. However, financial institutions have certainly been leaning into a weaker USD since April, and the upwards trajectory in values by major currencies against the USD may prove to be a solid baseline via support prices moving forward.

Certainly, day traders should consider the notion that larger traders have bet against the USD already, thus leaving the door open to the potential of reversals. Yet, mid-term price levels are what financial institutions are gearing their outlooks towards via cash forward transactions for commercial companies. If financial institutions believe the Fed will have to indicate the potential of a rate cut not only in July, but another one in September this could spur on additional USD weakness. Folks should also consider the notion that the White House won’t be against a somewhat weaker USD in order to help U.S manufacturers and producers export.

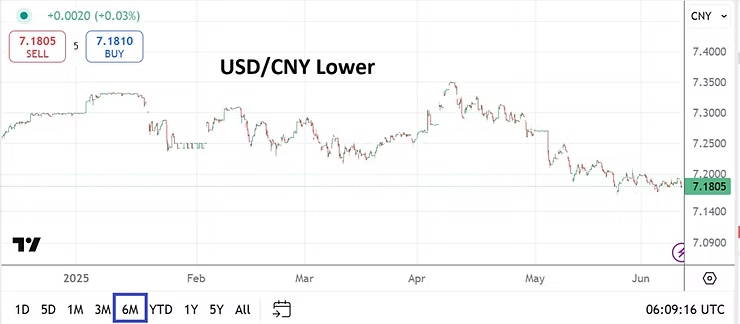
USD/CNY Six Month Chart as of 12th June 2025

U.S stock indices didn’t climb on the results of the China tariff news proclaiming a working agreement has been attained over the past two days. Perhaps markets are inclined to believe there will be more fireworks regarding rhetoric from the U.S and China over the coming months – which appears logical given the circumstances between the two nations.

While rare earth metals got the headlines, there appears to be plenty of line items in the tariff negotiations that still must be worked on. The announcement that the deadline has been pushed back again, this time until the 9th of August shows that talks are making progress – but slowly. Red lines keep getting erased.

Financial markets reacted rather passively to the U.S and China news, seemingly indicating larger players are now focused on other matters, and funds have played most of their cards regarding the China and U.S saga via their existing trading positions. Noteworthy, is the fact, the USD/CNY has reacted in a rather correlated fashion with the broad Forex market the past six months. For all the talk about a catastrophe for China and U.S trade, the USD/CYN has behaved quite well, showing the Chinese government is playing a long game against President Trump and doesn’t want to create a huge firefight via currency manipulation accusations.

WTI Crude Oil Five Day Chart as of 12 June 2025

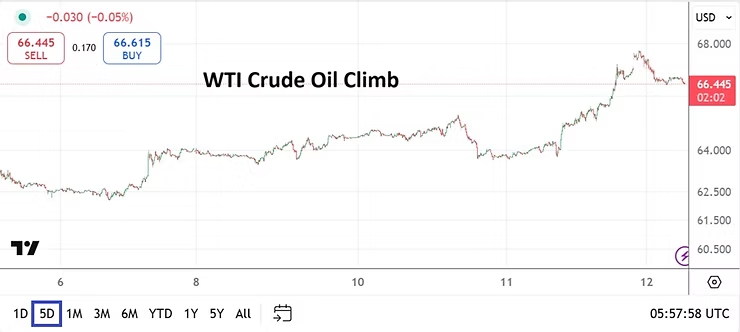
Middle East Escalation: WTI Crude Oil jumped late yesterday as news quickly filtered through social circles of embassy evacuations in various proximities within reach of Iran. The loud whispers certainly caused the price of the commodity to surge to almost $67.75 last night, but this morning’s values suggest some deep breaths have been taken as WTI trades near $66.45.

For options traders who want to buy cheap calls on WTI, they will likely have to look several months out and speculate on military escalation under rather speculative circumstances. If traders want an idea of what larger players are doing in options they can use CME (Chicago Mercantile Exchange) info to get some thoughts on positioning pattens in WTI Crude Oil calls and puts. The call options did get more expensive last night – meaning that some large traders are hedging against the threat of higher WTI Crude Oil prices because they are likely leaning into cheaper oil for the time being, or they are betting on the price of the commodity to rise if chaos breaks out in the Middle East.

post252

No Chance of a Nimble U.S Fed as Entitled Investors Served

No Chance of a Nimble U.S Fed as Entitled Investors Served

On Wednesday of this week Consumer Price Index numbers will be published, followed by Producer Price Index data on Thursday. Inflation statistics from the U.S for several months have been coming in rather tame and sometimes below forecasted results. Fed Chairman Powell and his team of FOMC members continue to plead uncertainty as the main reason for a lack of Federal Fund Rate cuts because of tariff concerns. The next meeting by the Fed finishes on Wednesday the 18th of June.

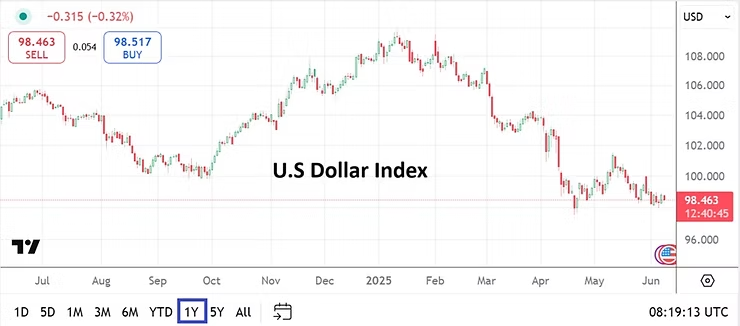
U.S Dollar Index One Year Chart as of 9th June 2025

Even if the inflation numbers come in as anticipated in the next few days, the Federal Reserve is unlikely to cut interest rates next week. President Trump and some in his cabinet have spoken about the need for rate cuts. Not only would it help consumers via mortgage rates, borrowing costs to buy autos and other high ticket items, but it would help the U.S government pay less on interest rate expenditures generated by inflamed Treasury yields.

The Fed continues to stay passive about its outlook, but if inflation data via the CPI and PPI are near forecasts this week, why would the U.S central bank continue to take such a stubborn stance? Interest rate decisions are not supposed to be political. The Fed has pointed to the potential of sudden inflation occurring due to tariff implications. This is a genuine concern. However, why can’t the Federal Reserve be more nimble? Inflation has not shown signs of immediate upwards pressure.

Perhaps it is because the Fed serves large U.S and foreign financial institutions, and has gotten into the habit of telling important folks not only what it anticipates, but handing out its interest rate plans on a silver platter so large players can position themselves beforehand like entitled elites. The Fed is very unlikely to cut interest rates the middle of next week, but it is probable they will open the door to a 25 basis point cut in July. However, July’s meeting is scheduled for the end of that month, in essence this is the middle of the summer, which is a long time to wait for action.

Day traders hoping to ride the trends that flow through the marketplace as they pursue speculative wagers remain in a difficult spot. Intraday volatility remains dangerous. Mid-term outlooks are certainly taking hold in Forex and equity indices, but sudden reversals for those using too much leverage continues to cause harm. Short-term speculators need to remain patient and vigilant, it is important to remember day traders are seen as second class citizens in the big scheme of the financial world, and this is not going to change for the moment.

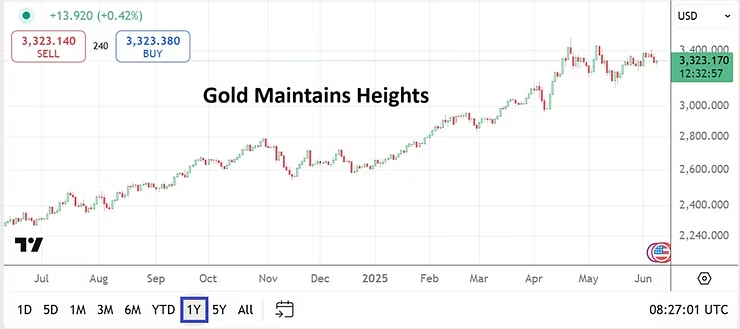
Gold One Year Chart as of 9th June 2025

A lack of clarity has spooked large players in the financial markets the past handful of months, but it does appear many institutions are becoming more comfortable. Though not at all-time highs, the major stock indices are within sight of important values. Behavioral sentiment seems to be leaning into a more positive outlook. Large investors appear to have concluded that while President Trump talks a tough game and often presents a strong stance, that ultimately he allows for tactical maneuvering to achieve deals. Trump is not big on being polite and this occasionally inflames markets. Bullish sentiment is growing on the hope President Trump’s characteristics are understood.

The Fed and the White House are likely to continue locking horns for the next few weeks. Perhaps if Jerome Powell tries to placate Donald Trump with a solid hint of an interest rate cut in July this will smooth things over. However, waiting for an interest rate cut in late July seems like a road too far, particularly when inflation levels the past couple of months avail the U.S economy to proactive actions from a Federal Reserve now.

Let’s remember, there is no law that says the Fed cannot cut or raise interest rates only during the conclusion of FOMC meetings. The U.S central bank has the ability to make changes to the Federal Funds Rate whenever it deems needed. Yet, the Fed refuses to be nimble in an age when technology allows data to be attained faster, this is a detriment.

The inability of the Fed to show it can be agile is another reason why investors are nervous about U.S policy regarding fiscal matters. The U.S government’s bureaucracy is too slow and bloated. The U.S is still a golden place to invest, but it is becoming problematic and this is leading to changes which effect long-term financial decisions.

post250

AMT Top Ten Miscellaneous Ruminations for the 31st of May

AMT Top Ten Miscellaneous Ruminations for the 31st of May

Western Cape, South Africa

10. Absence: Apologies for the truancy of AMT’s Top 10 the past handful of months. The staff has offered a myriad of poor excuses, but it accepts responsibility and has promised to try and meet the standards of our readers with timely publication once more. More coffee has been promised to the staff as a negotiation tactic by management, even though the price of the beverage is obscene.

9. Dim the Lights: President Cyril Ramaphosa, his staff and well known South African golfers attended a highly publicized meeting in the White House with President Trump. After surprisingly dimming the lights, a video mainly consisting of EFF radical Julius Malema’s threatening escapades was shown while Trump voiced concern about attacks on farmers. Not a lot is known about the outcome of talks which went on behind closed doors afterwards, but speculation abounds. The USD/ZAR is near 17.97000.

8. Anduril Industries: An aviation company, cofounded by Palmer Luckey who at a young age created Oculus VR, is receiving important attention. Anduril is a privately held company intent on building pilotless jet fighters, among other innovative technologies. Palmer Luckey is now 32 years old and appears ready to become a transformative tech entrepreneur perhaps in the vein of Elon Musk.

7. Bitcoin: Value of BTC/USD is near $103,600.00 at this moment. GameStop has announced it has purchased Bitcoin as a form of corporate treasury, apparently following the path of MicroStrategy’s foray as a Bitcoin proxy to the dismay of some and delight of others. The price of the world’s biggest digital asset was nearly $75,000 on the 7th of April 2025.

6. TACO: An acronym meaning ‘Trump always chickens out’, created by Robert Armstrong of the Financial Times, has caught the attention of many, including President Trump. While an amusing and pointed term, the context should be considered as a way to monitor the thinking of behavioral sentiment of anxious investors. Trump’s tough rhetoric and tendency to then issue a softer toned stance has been noted before by his backers as well as critics. As a means of accumulation while seeking value in assets perceived to be oversold, TACO may be a useful tool for those who agree with Armstrong’s thinking.

5. Values: Gold went into this weekend near $3,288.00. After achieving an apex around the vicinity of $3,500.00 on the 22nd of April, speculative fever has subsided a bit, but the commodity remains stubbornly in demand. Inflation in the U.S appears to be under control. Yesterday’s Core PCE Price Index met expectations with a monthly outcome of 0.1%. WTI Crude Oil’s spot price finished near $61.05 on Friday showing large traders remain convinced supply is strong.

4. Paralysis: The Fed remains steadfast and scared. While using the word ‘uncertainty’ repetitively – as if part of a rave song, Federal Reserve Chairman Jerome Powell must contend with official U.S inflation data which is starkly lower and a discontent Donald Trump, this while trying to explain the comatose behavior of the U.S central bank. The Fed should cut the Federal Funds Rate asap. And a 50 basis point cut by the end of this summer should be the discussed target.

3. Leviathan: The White House’s goal of reducing the deficit is running into tough political realities as budget cutting hopes clash with entrenched bureaucracy that swallows money like a hungry sea monster. U.S Treasuries yields remain elevated. The U.S has been cautioned again via rating services – highlighted by Moody’s recent downgrade of U.S bonds. To the chagrin of many fiscal conservatives, U.S government spending remains problematic.

2. Intimidation: Apocalyptic economic headlines attract viewers. Proclaiming global catastrophe creates attention and reactions in global financial markets. However, after the fierce selling seen in equities over the past few months, there has also been plenty of resilience and indices are now showing signs of coalescing as outlooks improve. Value and yields remain a prime motivator for experienced investors.

1. Pundits: Day traders have been battling volatile market storms since the election of Donald Trump, this as financial institutions have shown a tendency to shift outlooks as they react to pandemonium and cause whipsaw price action. Many speculators have experienced costly losses. Listening to self-anointed experts has not helped. Be wary of anyone who claims to be a market guru, and remember some call themselves gurus simply because spelling charlatan takes too long.

post249

Taco Trade Consideration: All about Accumulation Not Ego

Taco Trade Consideration: All about Accumulation Not Ego

Taco Friday is upon us. Fair or not the newly coined expression TACO – Trump always chickens out – is a rather savvy way of looking at current market perspectives. Day traders have run into a buzzsaw trying to speculate on daily gyrations, but investors who have the ability to accumulate based on valuations in equities, Forex and perhaps even commodities such as gold and WTI Crude Oil have likely enjoyed the choppy ride the past handful of months.

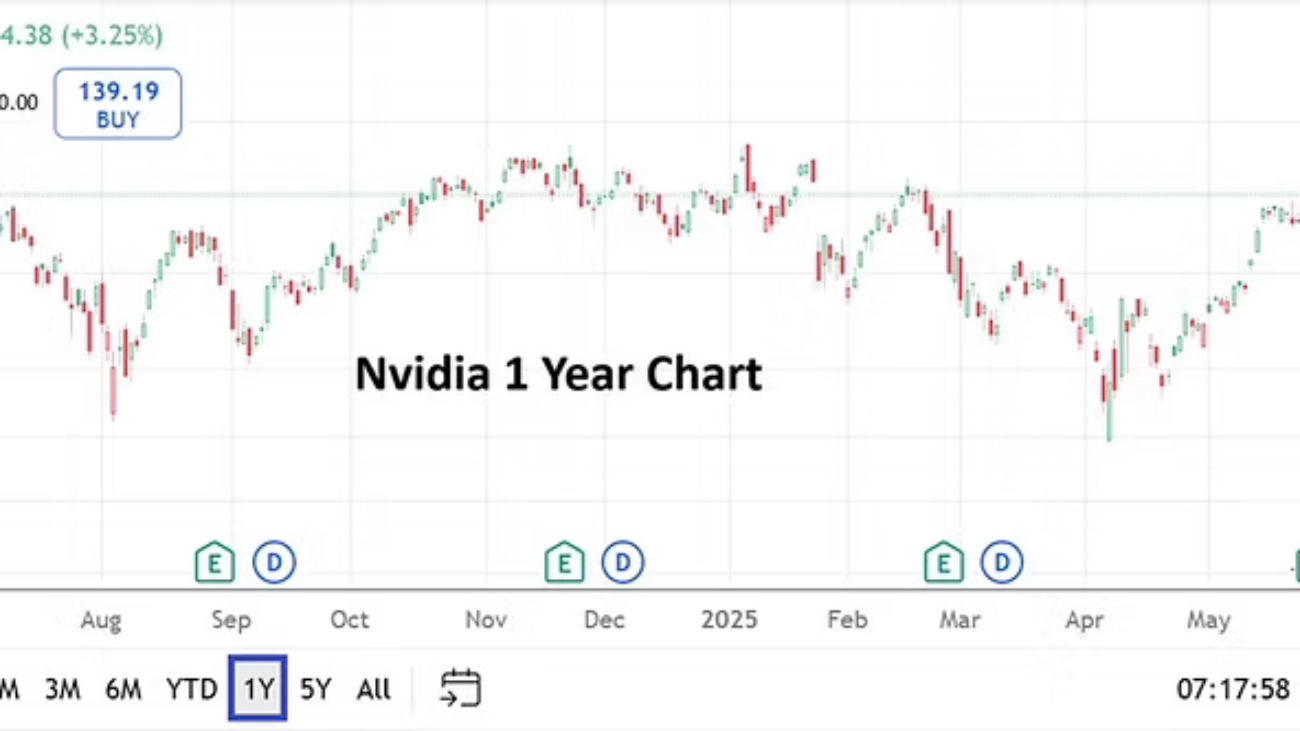
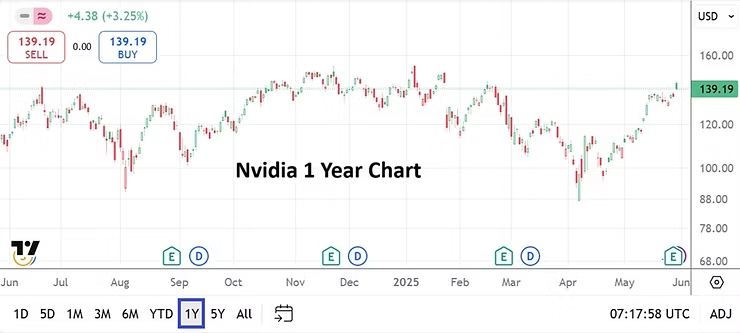
Nvidia One Year Chart as of 30th May 2025

Day traders who are betting on the daily whims of Forex or the stock markets have been participating in assets being stirred by a constant storm via behavioral sentiment shifts caused by White House rhetoric. President Trump has said the expression is mean. And in fact the Taco statement may be wrong all together, because what has gone down and back up, has also gone down again followed by additional reversals. But let’s put ego and wrong notions to the side for a moment. Because the important point about the Taco expression is actually about finding value.

Let’s consider that financial institutions have experience and skin in the game. The ability to buy stocks on lows and accumulate them based on a long-term mindset is likely going to prove correct. Consider Nvidia, it has suffered pratfalls, but continues to recover and pick itself off the floor and is now challenging highs again. Yes, the SP500, Nasdaq and Dow30 have all seen what can be described as whipsaw results. However, the optimistic notion that common sense rules and quality will prevail is a feature of investing. Blood on the streets as Warren Buffet has often said, is not a bad thing, it is an opportunity.

Nasdaq 100 One Year Chart as of 30th May 2025

Day traders attempting to time the markets have always experienced a great deal of pain when speculating on notions that ‘now is the time’. Patience often proves to be worthwhile in trading and investing. Anyone who claims they are constantly buying exactly on lows and selling on apex values should be treated suspiciously. Attempting to time highs and lows is a bit like gambling on sports without any inside knowledge, sometimes you win and sometimes you lose.

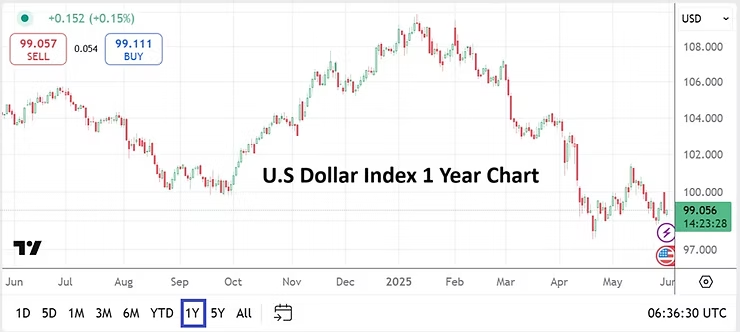
U.S Dollar Index as of 30th May 2025

In Forex the USD has been battered but continues to produce sudden violent price action. Today’s Core PCE Price Index from the U.S is expected to produce a 0.1% increase – which would be considered negligible by the markets. Fed Chairman Jerome Powell recently met with the President for the first time since Trump took control of the White House this term. The President is on the record as saying the Fed should cut interest rates now, this while Powell repeats the word ‘uncertainty’ repetitively.

Today’s inflation report is a vital statistical report for the Federal Reserve and will stir Forex. Perhaps, Jerome Powell should consider the Taco expression and understand that while talking tough Trump often is only expressing a strong stance to achieve a middle ground. If inflation numbers are near the forecasted outlook, the Fed should certainly cut interest rates sooner rather than later.

In the meantime, investors who have been accumulating stock on lower values and are playing a long game, may also be counting on ignition fuel being poured upon the markets to create a dynamic bullish run via positive impetus. Yet, even if profits are not achieved in the short-term, investors also understand they are being given an opportunity via the occasional outbursts from President Trump to take advantage of a rather delicious tactic.