post217

USD/JPY: Bank of Japan Actually Does its Job: Raises Rate

USD/JPY: Bank of Japan Actually Does its Job: Raises Rate

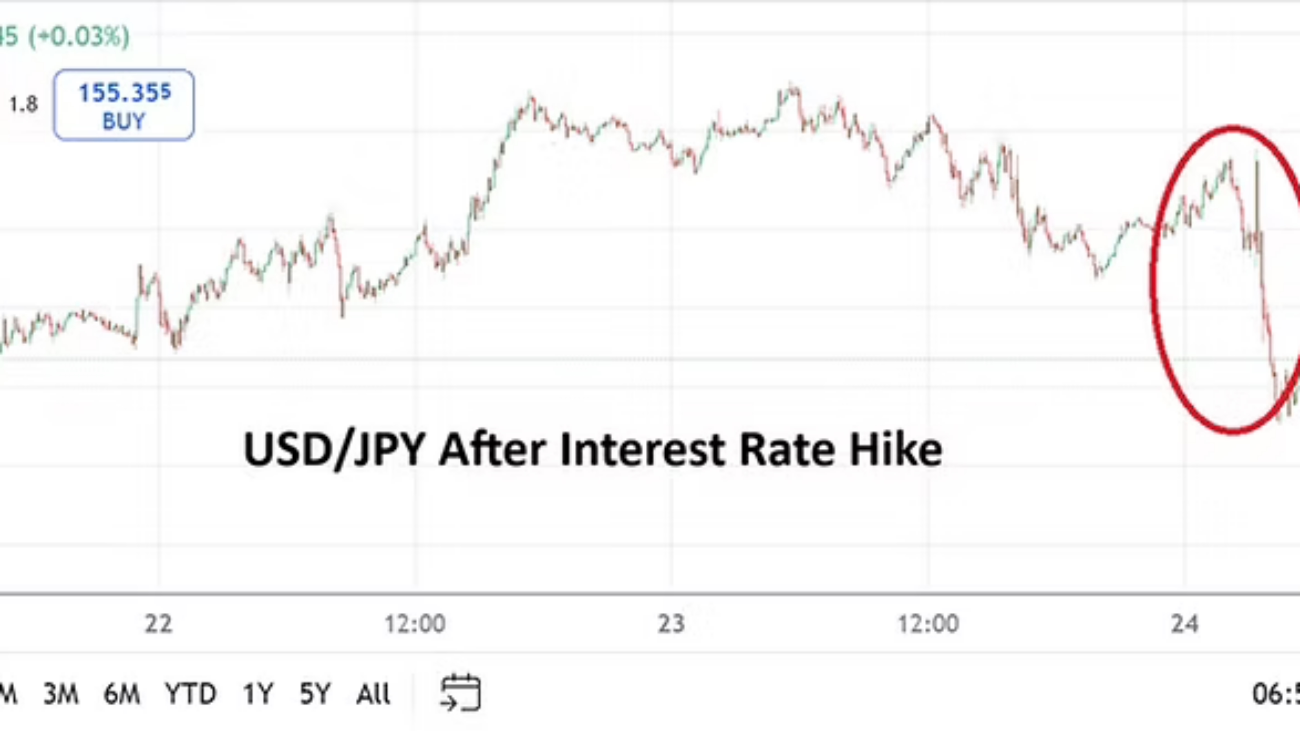
USD/JPY Five Day Chart as of 24th January 2025

The Bank of Japan actually raised its Policy Rate by 0.25 to 0.50% this morning. The move was done while the central bank stated the Japan economy is improving. The Bank of Japan also noted that the implications of U.S tariff policy are not completely known, thus it is acting on existing facts. The action by the BoJ created selling in the USD/JPY and is a healthy sign.

While the U.S Federal Reserve has taken on a cautious tone, President Trump has started to signal via rhetoric that he would like to see U.S interest rates lowered. The Fed and President Trump may find that they are in disagreement regarding mid-term policy and Forex traders shouldn’t be surprised if the debate escalates. The USD/JPY is trading near the 155.500 vicinity with fast price action at this moment. The ability to sustain values below the 156.000 level will be important technically if maintained. A fall below the 155.000 ratio may indicate more selling should be expected.

While financial institutions globally remain nervous about U.S economic policy regarding trade negotiations, Japan for the moment is out of the spotlight regarding tariff implications. The USD/JPY was trading near the 153.000 area on the 17th of December and it will be intriguing to see if large players use this level as a target in the coming days.

Retail traders should practice solid risk taking tactics and conservative leverage. The ability of the Bank of Japan to increase its interest rate, while the U.S Fed is in the midst of considering no changes to the Federal Funds Rate is a potentially solid sign for USD/JPY bearish attitudes.

Global Forex conditions remain choppy, but there has been some buying of the EUR/USD and GBP/USD produced recently. Next week talk of tariffs against China, Canada and Mexico will heighten, but traders need to understand the tough sounding talk from Trump is part of his negotiation tactics. While he certainly seems intent on carrying out his mandate, he will also be open to finding a way to create agreements.

Behavioral sentiment is in charge of Forex for the moment. Outlooks remain unclear, but USD centric strength may be traversing within the apex of its highs in many cases.

post216

Trump Bounce Potentially Coming This Week in Equity Indices

Trump Bounce Potentially Coming This Week in Equity Indices

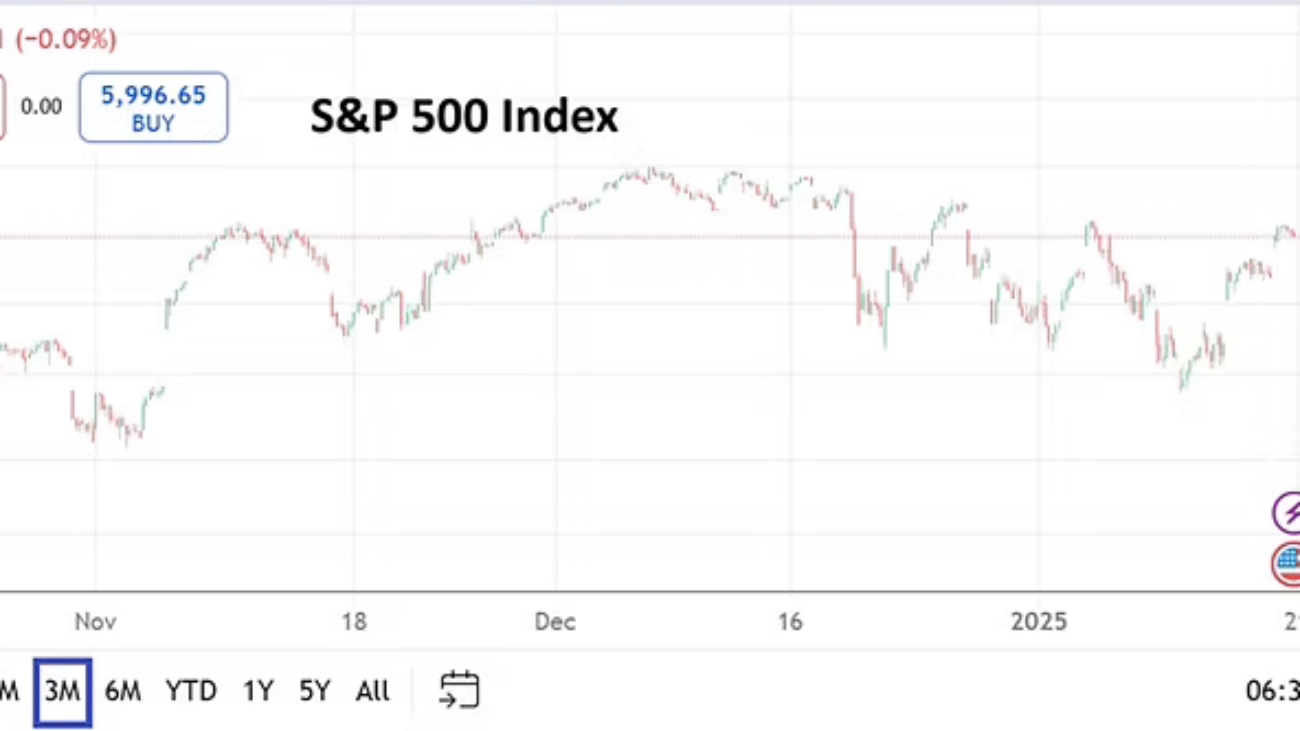
S&P 500 Three Month Chart as of 19th January 2025

Trump: U.S equity markets will be closed Monday for MLK Day. Upwards momentum developing this week as Trump White House takes power would not be surprising.

Retail traders need to know that U.S equity markets will be shuttered on the 20th of January because of the Martin Luther King Jr. holiday. Importantly tomorrow is also the United States Presidential Inauguration. Donald Trump will retake power of the Executive Branch of the U.S government at noon in Washington D.C as he is sworn in as the 47th President. U.S stock markets have produced choppy results the past few months but still remain in sight of highs. It would not be a shock to see optimistic momentum develop on Tuesday in the U.S stock markets near-term.

Yes, financial institutions have known Trump will be taking the White House for two and a half months and have had plenty of time to already react regarding their outlooks. However, from a behavioral sentiment standpoint it is easy to deduce that Trump’s coming inauguration speech tomorrow will deliver a confirmation of his economic policy intentions. Financial institutions near-term may produce optimistic upwards trajectory and they may have psychological targets which take into account late November and early December 2024 highs in the S&P 500.

The coming week will also be light on U.S economic data, except for the weekly Unemployment Claims on Thursday, Flash Manufacturing PMI and Existing Home Sales on Friday. Meaning the week will be driven largely on sentiment generated via President’s Trump’s actions in the coming days. Trump is expected to deliver a series of Executive Orders which will affect outlooks and likely be reflective of his campaign rhetoric spoken the past year.

Retail traders should not bet blindly on upside via CFDs for the S&P 500, Nasdaq and Dow 30. Near-term prices are not guaranteed to move higher, but there is reason to suspect buying might prove positive. An interesting barometer for price action will certainly be seen via future contracts early on Tuesday morning as financial institutions return to full volume and get set to return after a long holiday weekend. Risk taking tactics should include price targets that are realistic and not be leveraged wildly.

Forex conditions may prove volatile this week, and traders need to remain cautious about betting against the strength of the USD which has been ferocious the past three months. U.S Federal Reserve outlook remains murky and cautious, and nervousness regarding Trump’s intended foreign policy changes including trade negotiations still have to be fully demonstrated. USD centric risk bullishness likely still has ammunition which will be displayed in the coming days.

post214

Central Banks Noise: Holiday Trading Put on Hold For a Bit

Central Banks Noise: Holiday Trading Put on Hold For a Bit

As suspected the Federal Reserve sounded more cautious than many analysts expected yesterday. While the Fed did cut the Federal Funds Rate by 0.25 to 4.50%, they essentially opened the door to allowing the current borrowing rate to simmer over the mid-term. Yes, they did suggest they would like to lower interest rates, but it sounded more like wishful thinking. In response to the more aggressive rhetoric (hawkish) from the Federal Reserve financial markets became volatile in equities, Forex and bonds.

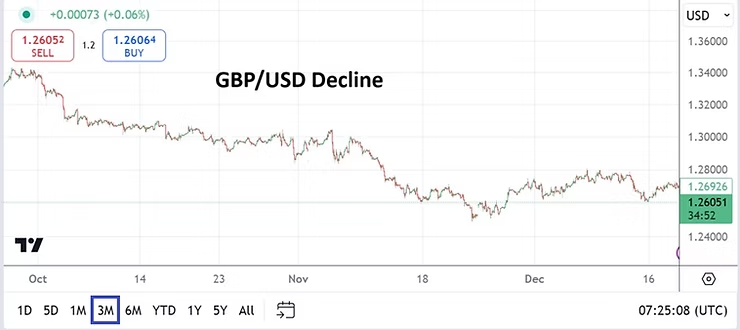
GBP/USD Three Month Chart as of 19th December 2024

The show is not over yet ladies and gentlemen, this morning the Bank of Japan repeated their typical historic stance of proving cautious, and later today the Bank of England will step onto centerstage with their Monetary Policy Summary and Official Bank Rate. And here is where things may get more odd, the BoE in many circles is not expected to cut its interest rate even though the U.K economy has been struggling and continues to publish lackluster statistics. The current borrowing rate via the Bank of England stands at 4.75%. Though the BoE should consider a rate cut of 0.25 certainly, and may even have enough reasons to decrease by 0.50, they may do absolutely nothing and that would be a mistake.

If the BoE decides to remain overtly guarded this will cause some bedlam with the GBP/USD. Large commercial players may choose to punish the GBP/USD as they consider their cash forward positions. Retail traders should be extremely careful if they choose to speculate on the British Pound in the coming hours. Not to say the GBP/USD is going to have a Liz Truss like moment from September 2022 today, but Forex traders have been selling the currency pair based on nervous outlooks over the past three months. If the Bank of England looks at the incoming headlights via the GBP/USD bearish trend and does not move, they might get run over by the truck.

Big and small traders certainly have the approaching holiday season on their minds and they might be getting things in order to take a break for the next couple of weeks, but financial markets because of the central banks actions yesterday and today will not allow for comfortable thoughts. And this is important, because some financial institutions are shuttering for the long holiday starting this Friday, they may be more prone to being quite cautious going into a period where trading volumes will light and assets will be exposed to the potential of sudden gyrations caused by large positions being placed in unbalanced markets. In other words, equities, Forex and bonds will be dangerous today and tomorrow. Behavioral sentiment will be the power.

post213

Federal Reserve Expected to Sound Guardedly Cautious Tmrw

Federal Reserve Expected to Sound Guardedly Cautious Tmrw

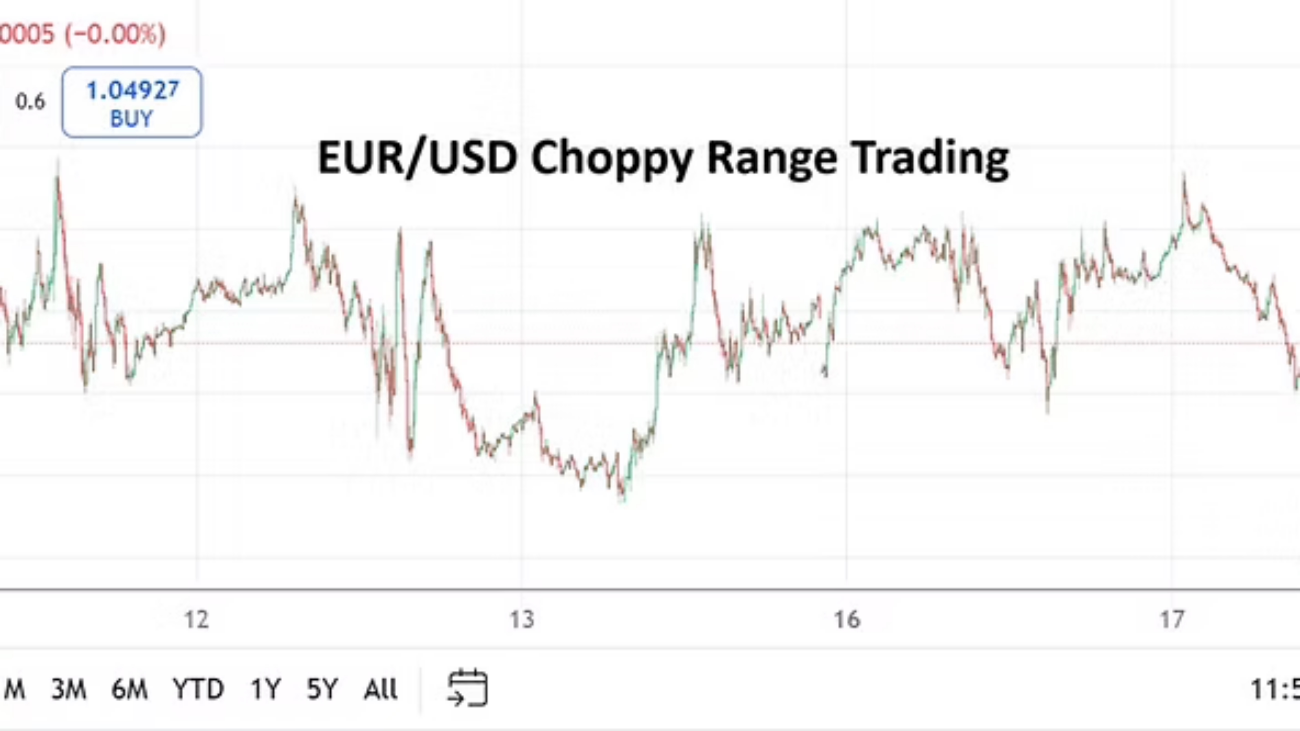
EUR/USD Five Day Chart as of 17th December 2024

Large traders are clearly bracing for the Fed tmrw as Forex produces volatile tight ranges. A rate cut is expected, but cautious Fed rhetoric will likely follow.

Forex has been a dangerous wagering ground for retail traders since the end of September. Financial institutions which clearly were betting on a more dovish Federal Reserve starting in early summer becoming a central theme into 2025 have been proven half right, this as the Fed has cut interest rates and is expected to do so tomorrow. However, being half right leaves the door open to also being half wrong, and financial institutions have reacted to this by becoming aggressive buyers of the USD since late September as perspectives have changed. The strong USD trend the past two months plus has hit some speculators hard.

The election of Donald Trump added a strong dose of impetus for USD buyers, this as the President-elect’s tough rhetoric regarding tariffs caused reactions and fear of unknown consequences. In the past couple of weeks more tranquil Forex trading has emerged and the USD finally started to give back some of its gains, yet the USD versus most major currencies, like the EUR/USD, remains within the the stronger elements of it range. While the Fed is expected to lower its Federal Funds Rate tomorrow by 0.25 to 4.50% tomorrow, traders need to remember this has been priced into Forex already. Tranquil trading the past two weeks indicates financial institutions have readjusted their outlooks to the incoming White House administration.

Now it is time to see if the U.S Federal Reserve has started to adjust their outlooks to what a Trump Presidency means. And financial institutions are keen to better understand the outlook of the U.S central bank. Inflation numbers while traversing lower are still rather stubborn and this may will not help the Fed’s mid-term mindset regarding interest rate cuts. GDP in the U.S has remained steady, and there is the potential the economy in the States will improve under Trump. Unemployment numbers while showing signs of weakness have not been terrible either. So while the Fed’s current Federal Funds Rate is higher than normal taking into consideration the historic average the past ten years, they still may not feel they have enough ability to cut interest rates too much more without sparking inflation.

A January rate cut seems unlikely at this time. If the Fed does sound guardedly cautious tomorrow, retail traders may see the USD get initially weaker due to the Fed rate cut, but then see a storm emerge and USD centric strength reappear all in the same day – perhaps in the span of minutes. Speculators need to understand that financial institutions have already baked tomorrow’s interest rate cut into the cake. So it isn’t the rate cut tomorrow that is important if it happens (if it doesn’t then that’s another story); it is what the Fed says and traders should expect them to be very cautious – because per the recent trading of the USD and a barometer it appears financial institutions are bracing for a more vigilant Fed.

Just like he has with many folks he views as uncompromising before, Donald Trump may begin to feel Federal Reserve Chairman Jerome Powell is not on his side regarding interest rate policy. If the Federal Reserve chooses to sound hesitant to cut interest rates in early 2025, it will be rather intriguing to see President-elect Trump’s response. Could a confrontation between the White House and Federal Reserve be in the cards over the next six months?

post211

AMT Top Ten Miscellaneous Reckonings for the 8th of December

AMT Top Ten Miscellaneous Reckonings for the 8th of December

10. France Falls: President Macron’s leadership is in peril after his anointed Prime Minister, Michael Bernier, suffered a no confidence vote outcome. French politics and finances are in shambles. Life for French citizens goes on as their politicians battle for their jobs, supremacy of voice and egos. With the restoration and presentation publicly of Notre Dame Cathedral yesterday, Macron now has to find something else to divert attention away from his misappropriation of power.

9. 100,000: Bitcoin came within sight of the 104,000 USD vicinity this Thursday, then sunk with a rapid pace and challenged 92,000. Once again traversing near 100 grand, large BTC whales and MicroStrategy’s Michael Saylor and his cult of followers are likely celebrating. However, if the wind changes direction what kind of damage will the low tides create this time for Bitcoin and speculative leveraged positions? The price of BTC/USD as of this writing is near 99,500.

8. Al-Assad: The Syrian regime is apparently coming to an end after 50 plus years in power. Bashar al-Assad’s whereabouts are unknown. Russia, Iran and Hezbollah appear for the moment to be big losers in this power play. The many factions will now have to see if they can create a semblance of government, but that remains doubtful. Syria will be a quagmire in the coming months as its cauldron stirs.

7. Martial Law: South Korean President Yoon Suk Yeol startled Asia and foreign investors by declaring martial law this past week, making one of the worst political miscalculations in recent memory. Yoon was quickly forced to rescind the decision. The USD/KRW spiked and KOSPI Composite sank via the instability. However, the South Korean National Assembly has shown the ability to provide leadership and display power of law prevails, this as they try to calm their citizens concerns and investor sentiment.

6. Roasted: Coffee Arabica has boiled again and commodity’s price is fighting within apex levels. Like Cocoa, both Arabica and Robusta Coffee have surged the past year as large players have created a strangulated grip which suggests the markets may be ‘cornered’. While some analysts are quick to point out weather conditions as a reason for the higher prices, the tenacity of Coffee and Cocoa to sustain upwards momentum is intriguing but also suspicious.

5. FX and Data: U.S jobs numbers this Friday were marginally better than anticipated and the Average Hourly Earnings came in slightly above expectations. Economists from different schools of thought are debating the potential of recession and inflation concerns, versus those who believe growth, greater transparency of U.S fiscal mandates and elimination of a bloated budget will be achieved when Trump’s economic policies takeover. Globally Forex conditions are showing signs of fragility because of the threat of tariffs and trade concessions by nations which may need to be made. Yet, it is quite possible the ‘bad news’ consisting of accusations of unfair trade agreements by Trump, and the reactions which have been cooked into the EUR, GBP, JPY, ZAR, MXN, CAD, NZD and others is overdone. While there could certainly be more weakness in major global currencies paired against the USD, upside potential mid-term may be more positive compared to near-term drawdowns. Retail traders still face difficult technical perceptions in the days ahead because financial institutions also remain shaky regarding their outlooks.

4. Pardon Me Joe: President Biden has forgiven his son, Hunter Biden, for crimes known and unknown for an eleven year period – that is not a round number ladies and gentlemen, with a Presidential Pardon. Why 11 years? Why not 10 or 15? There is conjecture that Joe Biden is also considering preemptive pardons for people his administration feels may face the wrath of the incoming Trump White House. However, if pardons are given to the likes of Anthony Fauci, won’t the pardons awarded to those who have not been charged with a crime yet look like an admission of guilt?

3. Central Banks: The ECB will deliver their interest rate decision on the 12th and the Federal Reserve will announce their Fed Funds Rate on the 18th. Behavioral sentiment however is seemingly more focused on the threat of potential storms that could suddenly appear due to the Trump effect. The ECB and Fed are both expected to cut their interest rates by a quarter of a point, while it appears many financial institutions no longer believe the Fed will cut again in January.

2. Chinese Gold: Tucked away in the quiet corners of the business news has been the discovery of a massive gold ore deposit in China. Some geologists claim the Wangu gold field could have up to 1,100 tons of the precious metal. If correct and the amount of gold meets or exceeds the expectations of the experts, the question about this becoming a deflationary event for gold is intriguing but likely wrong. Importantly, the gold will be a long-term benefit for China and potentially create a stronger national currency via the Renminbi (China Yuan). Perhaps also solidifying the idea of using the reserve as part of the backbone for a potential BRICS ‘Unit’ currency if and when that day ever arrives. Gold closed at nearly 2633.00 USD per ounce before going into this weekend.

1. Trump Effect: WTI Crude Oil is around 66.78 USD as the promise of easier energy production for U.S companies has created the conviction of steady and less expensive supply. The USD remains in the stronger elements of its long-term Forex range, and folks betting against the strength of the USD need to remain cautious. BRICS has been warned about not infringing on the USD by Donald Trump, and some member nations of the organization have affirmed they do not seek a BRICS currency (yet). Tariffs have been threatened, but China has responded by showing it has the ability to create potential hinderances this week via a tough negotiation stance by threatening to stop export of rare earth metals to the U.S. Mexico and Canada have felt the verbal wrath of the President-elect already and started to react. All of this while Donald Trump still has six full weeks before taking power.

post209

Forex: Trump Effect and Reasonable Trading Caution for All

Forex: Trump Effect and Reasonable Trading Caution for All

The Forex market the past two months has created a profoundly stronger USD against many major currencies. The combination of late September intrigue regarding U.S Federal Reserve outlook, then nervousness about the approaching U.S election, followed by the subsequent results have been a dumpster fire for many speculators looking for a sustained return to USD centric weakness. Hopefully risk taking tactics have included a solid dose of caution.

This week’s Non-Farm Employment Change numbers scheduled for Friday may give financial institutions a moment to focus on economic data instead of President-elect Donald Trump’s loud pronouncements, but the effect may prove to only be momentary. It isn’t data that is driving Forex for the moment it is nervousness and fear of the unknown.

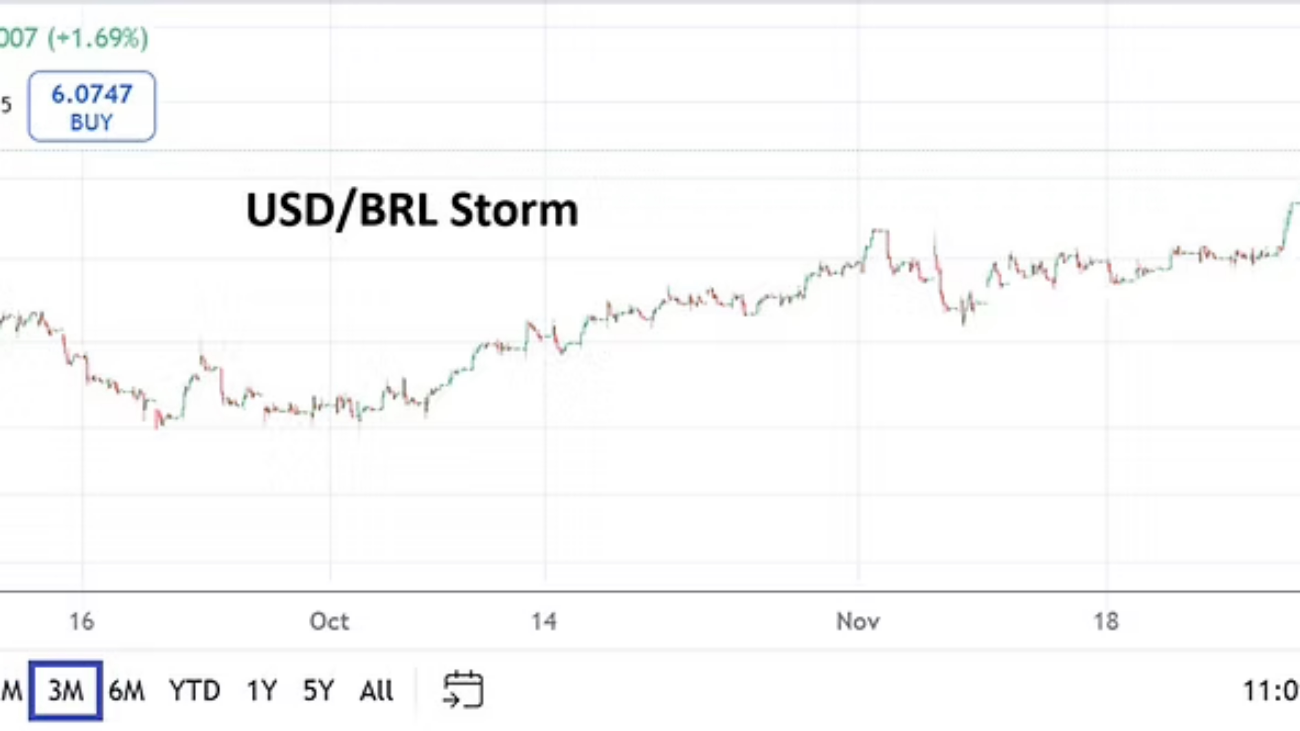
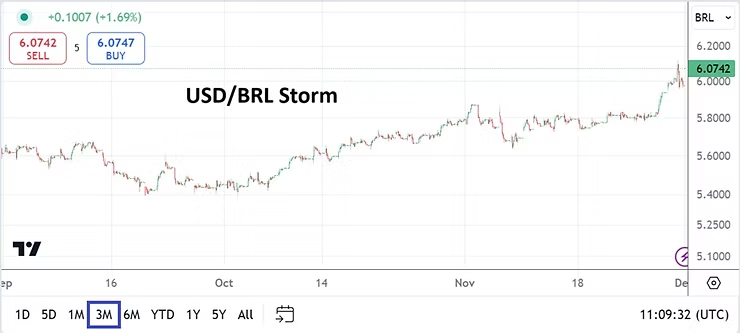
USD/BRL Three Month Chart as of 3rd December 2024

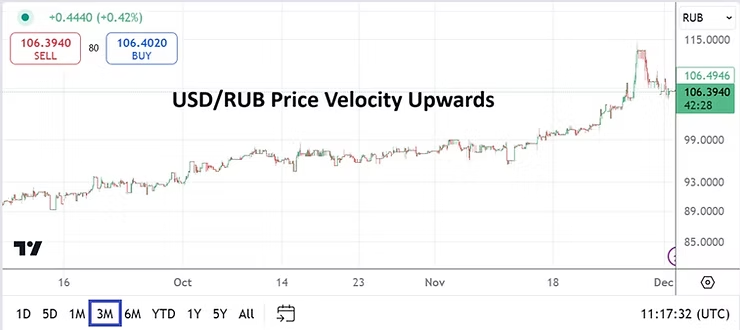
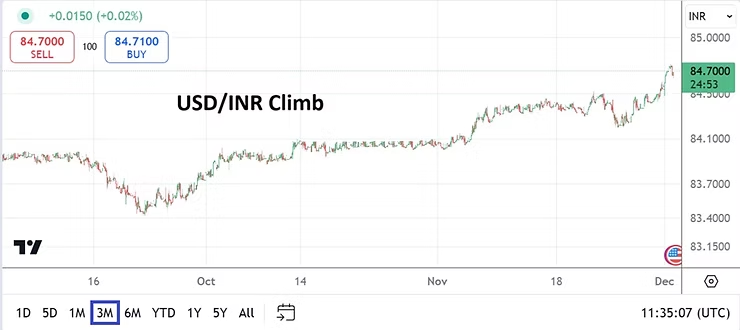
While many financial institutions and speculators trade only the major currency pairs, taking a look at the less obvious and more infrequently transacted major currencies may provide retail traders additional perspectives regarding the fragile nature of Forex. Many nations and large institutions are demonstrating concerns about possible sea changes to U.S foreign economic policy. Yes, the EUR/USD, GBP/USD and USD/JPY have all seen volatility via USD strength the past two months, but price velocity in the USD/BRL, USD/RUB, and USD/INR may be equally intriguing. And prove that mid-term forecasts (or lack of them) are causing bedlam for all.

USD/RUB Three Month Chart as of 3rd December 2024

While it is more than probable calmer heads will start to be seen in Forex and weakness eventually will return to the USD, trying to pick the exact moment this is going to happen remains a guessing game. Financial institutions via evidence in current Forex pricing remains rather cautious regarding their cash forward commercial enterprise. President-elect Donald Trump has certainly been dealt with before and his negotiation style is that of a businessman, it is not a coincidence that some global leaders who do not exactly see eye to eye with Trump are giving him respect because they understand he will act upon threats if not dealt with fairly.

Trump’s recent brief rhetoric regarding BRICS and the organization’s public consideration of creating a new currency to compete with the USD did not go unnoticed this weekend. Critics may want to proclaim Trump’s threats as belligerent, but BRICS is free to create a new currency still if they wish. While Trump cannot stop the birth of a BRICS currency, he can certainly try to initiate actions (via sanctions) against nations that attempt to create a new unified currency which tries to curtail the dominance of the USD. It would certainly help Trump’s bargaining position and the USD also, if better fiscal policy is practiced by the U.S Treasury and government.

USD/INR Three Month Chart as of 3rd December 2024

It needs to be pointed out that Trump’s warning to BRICS may not be needed. Even though the organization may be able to create a currency based on a commodities backbone, the lack of trust many financial institutions and nations would feel towards a non-transparent fiat currency powered by the fiscal monetary policies from the likes of Russia, China, Brazil and South Africa remains a difficult sell. Until many changes happen domestically within these nations via governance, creation of a BRICS currency remains wishful thinking.

Getting back to the big picture and the volatility recently seen in Forex. While the major currencies teamed against the USD have certainly faced hectic conditions, the fluctuations have not been unexpected. Day traders need to understand the month of December is likely going to remain choppy and see a test of technical support and resistance levels that are wide and full of fast reversals.

The question for the EUR, GBP, and JPY is if most of the negative inputs into these currencies has been factored into value. The suspicion may be yes, and that strength may rightfully appear in these big three sooner rather than later. However, the approaching holiday season and potential bluster from President-elect Trump will not make this a comfortable or easily wagered avenue.

Short-term retail traders looking to take advantage of the bloodbath created in Forex the past two months who seek opportunities should focus on perceived targets which aren’t overly ambitious. The coming U.S jobs data this Friday may allow the U.S Federal Reserve room to cut the Federal Funds rate on the 18th of December by another quarter of a point. As a point of attention, the European Central Bank will announce their Main Refinancing Rate on the 12th of December. The ECB’S actions may be a solid clue regarding the Fed’s approach to upcoming policy.

However, even if an interest rate cut were to take place via the Federal Reserve, it is likely the cut has already been factored into Forex. Which also highlights the high degree of nervousness that exists because of fears which permeate due to Donald Trump’s tough negotiation stances which have been made public. Meaning those who are looking for USD centric weakness to emerge still need to rely on a shift within behavioral sentiment to occur that is not generated because of the Federal Reserve. Nations need to show a willingness to amend existing trading agreements with the U.S, allowing for changes to internal policies regarding exuberant price duties they place on U.S goods in their own countries.

postR200

AMT Top Ten Miscellaneous Musings for the 18th of November

AMT Top Ten Miscellaneous Musings for the 18th of November

10. Election Results: The U.S election concluded almost two weeks ago and there is no discussion this time around of mischievous results, which we can all be thankful. However, there is still talk about results from the past, but perhaps these folks should be thankful for the prospect of a serendipitous outcome this time and get to work.

9. Conspirators: The Onion has tried to buy InfoWars via an auction which is now under review by a court to judge if the procedure was undertaken fairly. Alex Jones’s InfoWars and its sometimes other worldly offering of bizarre and misguided notions is in bankruptcy. The Onion wants to turn the tables on InfoWars and dedicate the ‘purchase’ of the site to ridiculing media and conspiracy folks who produce mindless gobbledygook.

8. From Beyond: The UAP, unidentified aerial phenomena, hearing before Congress last week led to a variety of questions and answers which rehashed known ‘unknowns’ while discussing orders of magnitudes of speed and g-forces that humans and machines can endure. The UAP (UFO) hearing didn’t disclose much in the way of developments regarding alien crafts visiting Earth, except to make it obvious to some that if ‘they’ are out there, we had better hope they are friendly. And if it is earthly corporations or nations testing and displaying new technologies, there seems to be little information publicly available about who may be playing in the skies and waters. Optical illusions?

7. Polymarket Raid: Many folks started pointing fingers when the CEO of Polymarket, Shayne Coplan, had his home raided on the 13th of November, claiming the FBI was politicizing Polymarket’s prediction that Donald Trump would win the U.S President race. But after further review, few have pointed out that Kalshi Inc., which also operates in the U.S and allows sentiment betting was not raided. The difference perhaps being that Kalshi is regulated via contract markets with the CFTC, and Polymarket is not and appears to be potentially operating in non-accordance to U.S laws.

6. Bitcoin & Coffee: BTC/USD continues to tread within the highest of tides and is slightly below 92,000 as of this writing. Coffee Arabica and Robusta are boiling within apex price ranges. Cocoa also remains rather impressively expensive. Which one of these speculative assets has no intrinsic value?

5. Buyer Remorse: At some juncture votes may start to feel a bit of angst per their recent voting decisions. We suggest to Polymarket and Kalshi to allow wagers on when this might be displayed in mass. However, in a very real way the U.S election in two years will be the key instrument to gauge the reaction to what is about to come from the new White House administration. Who will control the House of Representatives in two years time?

4. Forex: Foreign exchange should likely be placed in a number two or one AMT ranking, except to say we do not think retail traders should be enticed by being told no. Volatility that has pervaded the FX markets is not finished quite yet. While USD centric strength continues to cause upheavals against major currencies, and technical support and resistance levels are testing mid and long-term considerations, there still may be a week or so left in swirling whipsaw storms. Risk management has hopefully helped retail traders survive to wager again, but it shouldn’t be today.

3. Fed Donations: Federal law mandates employees of the U.S government, https://www.commerce.gov/sites/default/files/2023-08/political_activities-dos_and_donts-2022.pdf, must disclose their political donations. Recent studies indicate that approximately 90% of Federal Reserve employee donations to political candidates go to Democrats, https://www.yahoo.com/news/federal-employees-overwhelmingly-donate-democratic-175055289.html. This highlights the possibility that many current Fed employees have different perspectives regarding economics compared to those about to take positions of power in Washington D.C.

2. See No Data: U.S economic statistics have been rather tame recently, but financial institutions clearly are not paying much attention to near-term considerations about the potential influence of the Federal Reserve and interest rates. Instead behavioral sentiment appears anxiety laden. Retail traders and large speculators may be getting crushed together in a cyclone of certain assets, particularly if they are trying to fight short-term trends while infatuated with mid-term outlooks. The Fed may cut interest rates again in December.

1. The Clash: The highs in U.S Treasury yields and record territory of U.S stocks being traversed together indicates we will see a rather violent collision when one of these investment pursuits likely capitulates to market dynamics, allowing the other to take precedent. Some long-term investors may be nervous about President-elect Trump taking power in the third week of January, but it would be unwise to bet against him in the next six months. Meaning stocks may ultimately win this battle of attrition against bonds and prove they are more appealing.

postR199.1

Forex: The Art of Not Making Sense and Accepting Price Values

Forex: The Art of Not Making Sense and Accepting Price Values

Retail traders are likely learning the hard way that attempting to trade in Forex for the moment is more than dangerous, it is expensive. The U.S Consumer Price Index numbers yesterday met expectations, which essentially allows the Federal Reserve to remain in a cautious dovish stance. However, after an initial show of USD weakness upon the data in many FX pairs, USD centric strength quickly returned.

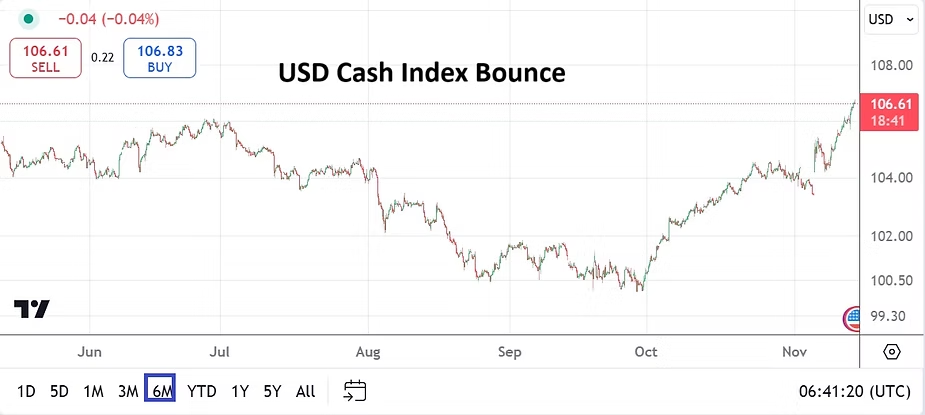
USD Cash Index Six Month Chart as of 14 November 2024

Short and near-term trading for speculators who do not have deep pockets and are suffering from whipsaw movements are creating the need to take a step back. As many major currencies have suffered losses against the USD since late September, the tendency is to likely think a reversal is going to develop sooner rather than later. However, until financial institutions become comfortable with the notion President-elect Trump’s policies aren’t going to harm economic prospects in a variety of nations regarding tougher trade agreements, risk adverse trading is going to remain a key in Forex.

Yes, at some point the USD will start to give back some value, but timing the moment this is going to start and become sustained for day traders is simply betting. Financial institutions are feeling anxious about their commercial forward positions in Forex too, which will continue to create volatility for all trying to predict where the USD will be mid-term. Federal Reserve policy may actually be able to deliver a 0.50 basis point total cut over the next few months, but this notion has had almost no impact on USD strength short-term. Perhaps financial institutions do not feel the Fed will be that dovish through February, but if inflation remains tame the Federal Funds Rate still has room to decrease.

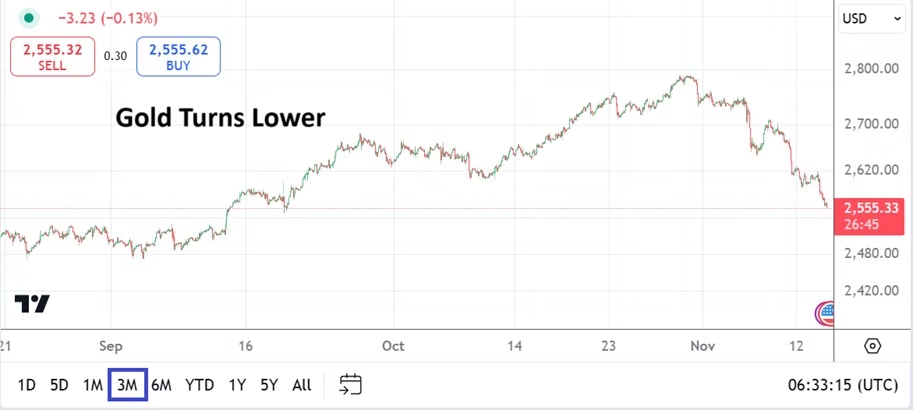
Gold Three Month Chart as of 14 November 2024

Today’s Producer Price Index inflation reports will be watched, but like yesterday the results are unlikely to be a key which will suddenly ignite strong reversals in Forex. In the meantime traders need to practice solid risk taking tactics and patience. Retail Sales figures will come from the U.S on Friday, but again day traders should expect financial institutions to remain risk adverse until there is an event which changes their cautious mindsets.

Gold is noteworthy because it has struggled since early November. There is the possibility the precious metal has turned lower because investors feel more sure about their long-term bets in the U.S equity markets for a moment, but that is likely wrong. It could also be argued speculators are cashing out winnings they have made the past handful of months. The point being that explanations for price movements are tenuous. False narratives abound. Fundamentals like behavioral sentiment are shifting because new economic policies from the U.S are going to develop and market participants want greater clarity.

Like the major currencies suffering significant declines versus the USD, the value of gold can be argued, but the market is telling us what participants are willing to pay for assets whether we agree or not. Let there be no doubt that the highs being produced in U.S Treasury yields which are near early summer values, the USD Cash Index reversing towards technical levels seen in early July, gold recently losing value, and U.S equity indices being near all-time highs makes it particularly difficult for predictions regarding what is next. Except to say the Trump victory in many ways has sparked a buy American parade for the moment. If you want to bet against the trends you are free to do so, but behavioral sentiment is proving once again the king of the hill.

While the broad markets may not feel like they are making much sense to some, as traders we need to be able to put our bias to the side and accept the markets as they are, not what we think they should be. There is a significant difference between near-term and long-term targets. Day traders need to understand they are wagering in markets that will remain dangerous for a while. Nothing is guaranteed, but the idea that U.S equities may continue to rally into the New Year is being wagered upon by larger players and they might be proven correct.

postR196

AMT Top Ten Miscellaneous Votes for the 4th of November

AMT Top Ten Miscellaneous Votes for the 4th of November

10. Priorities: Not to dismiss the execution of beloved Peanut the Squirrel by New York authorities recently, but lets reflect on the fact that this little fellow made international news while wars are raging, and nearly 300 people in the U.S are dying from drug overdoses per day. Social media is rather powerful.

9. NBC: Kamala Harris appeared on Saturday Night Live for roughly 90 seconds this weekend, this created criticism and questions about unfair airtime for the Vice President. SNL is lucky to get more than 5 million viewers per episode on average. To try and apologize for the potential trouble, NBC then gave Donald Trump free commercial airtime twice yesterday, once during a NASCAR race which on average attracts over 3 million viewers, and on a Sunday night NFL broadcast which averages sometimes up to 22 million viewers.

8. Saber-Rattling: There is a potential Iran is waiting on the outcome of the U.S vote for President before undertaking more military actions. Deciding if and how they are going to launch another attack on Israel, depending on who wins the U.S election because of the potential ramifications is likely part of their military strategy.

7. BTC/USD: Bitcoin as of this writing is trading near 68,500 USD. The digital asset continues to bounce around rather intriguing resistance. On Tuesday of last week Bitcoin traded near 73,500 momentarily, while the highs are certainly noteworthy, support for the speculative asset has been around 66,000 since the middle of October. There are reasons to suspect Bitcoin will display a large amount of volatility this week, particularly when the new U.S President is known.

6. Forex: As of this writing the USD/JPY is slightly below 152.000, the EUR/USD is around 1.09000, the GBP/USD is near 1.29650. The question is where these currency pairs and other major FX assets will be in three nights. Day traders dreaming of riding momentum via financial institutions need to understand the equilibrium of risk and reward. In other words, the same amount of money you can make, is likely the same amount of money you can lose. Risk management will be a life preserver for many speculators this week.

5. U.S. Data: This past Friday the Non-Farm Employment Change numbers came in wildly below the 106,000 jobs added estimate, the result of only 12,000 hired was rather shocking, but met with almost muted bewilderment. Also, the jobs numbers showed another revision lower from the previous month. Advanced GDP quarterly numbers, on Wednesday the 30th of October, also missed their estimate coming in with a 2.8% gain compared to anticipated growth of 3.0%. The U.S economy is still under stress.

4. Barometers: Risk adverse trading has been widespread the past handful of weeks. While gold has reached new highs and is slightly below the 2,750.00 mark for the moment, one month from now will be a telltale for gold and many assets. Since the end of September a number of narratives have been heard trying to explain the results seen across the board, but the simple answer is caution has entered the markets. U.S equity indices are still flirting with highs, even as they have suffered downturns in recent trading. WTI Crude Oil is near 71.50 USD per barrel. Gold, U.S equities and WTI Crude Oil will react to the outcome of the U.S election and serve as solid behavioral sentiment indicators in one month when compared to current prices.

3. Federal Reserve: If last week’s U.S economic data had been delivered without the fanfare of the U.S election approaching, Fed observers would likely be anticipating a dovish sounding FOMC Statement coming on the 7th of November. Instead, the USD has remained rather strong as risk adverse trading has been demonstrated in the broad markets. The Fed is certainly in a position to cut the Federal Funds Rate by another 0.25 basis points, some could even argue for another 0.50% cut. However, the Fed is likely to cut interest rates by a quarter of a point and sound rather cautious as they too read the landscape in the wake of the U.S voting results. Mid-term outlook from the Fed will be scrutinized this Thursday.

2: Nervousness: Day traders who decide to participate in the broad markets near-term may also enjoy walking outside and looking at approaching storms and dreaming about the fury about to come. Being anxious before and during large risk events when outcomes are unknown is a survival instinct. Speculators need to protect themselves over the next couple of days. Tranquil trading in all major assets may appear, but as tomorrow grows long assets will begin to percolate and by Wednesday almost all financial markets will be boiling. While this is certainly being hailed as the most important week of the year because of the U.S election and the Federal Reserve, it is also a very dangerous time to be trading. Those with limited funds may want to hunker down in a safe place and watch the markets create bedlam over the next 48 hours.

1. U.S Election: The vote is less than one day away when old standards are considered. However, more than 72 million votes have been cast early in the U.S already. That’s more than 45% of the total U.S vote during 2020, when 158,434,567 votes were counted. While the media bangs the drum regarding the incoming results tomorrow, it is important to note that many Americans and global observers are merely waiting for the final results to be announced. The end of the election campaign is nearly upon us, now financial institutions and traders await clarity. Wednesday the 6th of November is going to be an interesting day for the markets.

postR194.1

Forex: Dangerous Triggers Abound for Inexperienced Speculators

Forex: Dangerous Triggers Abound for Inexperienced Speculators

While the U.S jobs reports via the Non-Farm Employment Change and Average Hourly Earnings will grab attention today, and the Advance GDP this Wednesday and inflation numbers yesterday were important. Institutional trading focus in many respects will be elsewhere, behavioral sentiment and the potential reactions that lurk after the results from the U.S election are known are the biggest risk threat.

USD/SGD Three Month Chart as of 1st November 2024

Yesterday’s weaker than expected Employment Cost Index will help the U.S Federal Reserve to clip another 0.25% off of the Federal Funds Rate on the 7th of November. However, the winner of the U.S Presidency will be a talking point in the coming FOMC meeting, and also the halls of the U.S Treasury, influencing potential policies. Weaker than expected jobs numbers would fuel dovish perspectives from financial institutions today, but because of the coming U.S election on Tuesday results will fall on ears possibly tuned into other frequencies. And let’s remember last month’s job numbers were stronger than expected, and revisions downward in the back months remains a problem causing mixed sentiment.

Major currencies versus the USD continue to thread within cautious weaker values. USD centric strength has been persistent since the last week of September. If this had been a normal week of trading, the USD would have likely gotten weaker after the Advance GDP results came in slightly less than anticipated. Fuel might have been added to USD selling on yesterday’s lower than expected labor costs too, but this did not happen in many cases. This needs to be a consideration for day traders who are trying to interpret U.S economic data as the U.S election looms. Simply put, behavioral sentiment in the near-term is being more influenced by the race for the White House.

If a trader wants to bet on who they think the winner of the U.S vote will be they need to be careful too, not only because they could be wrong, but if their ‘winner’ takes the presidency, reactions may be more tumultuous than planned. Speculators need to understand that financial institutions too have likely been positioning their cash forward transactions based on who they think is going to win the U.S vote. Meaning wicked reversals and take profit orders could be triggered when the U.S election outcome is known. Forex trading volumes next week should be immense.

Gold Three Month Chart as of 1st November 2024

It is a dangerous time for inexperienced traders to participate in Forex. Brokers will certainly sell this alluring show and point out that there is a lot of opportunity to make money in the coming days, but the opposite is true too. Because if you can make a lot of money from volatility, you can also lose a lot of money. Folks without deep pockets who are using leverage will be vulnerable to price velocity.

Retail traders need to understand the risks that confront them are dangerous because their Forex positions cannot be held over a long-term because of too much carrying costs, too much volatility and frequently too much leverage. Large financial institutions who are the shakers in Forex play by a completely different set of rules. It may help a day trader immensely to understand they can really only feast on profits when they have been able to ride the technical momentum caused by the influence of financial institutions.

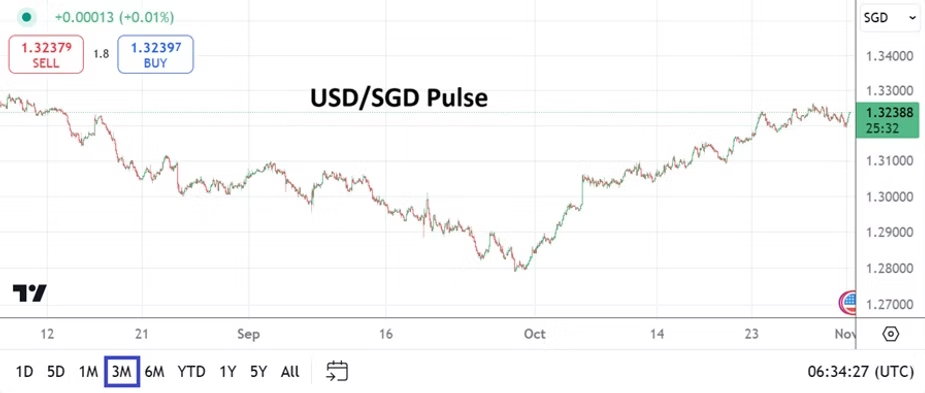
The cyclical nature of Forex has been on full display the past three months. Trading within the USD/SGD the past three months is a solid example of a major currency teamed against the USD and sustaining a strong bearish cycle on the expectation the U.S Fed would become dovish, and then the reversal higher since late September as financial institutions started to become risk adverse. While some analysts may argue this point, the coming results in the weeks ahead will tell us a lot as large players react to clarity via a new U.S President and the Federal Reserve’s monetary policy outlook. Traders large and small over the next five days in Forex will be treated to quite a carnival like experience.

postR192

Impolite Opinion: BRICS Long-Term Plans & Implications Part 1

Impolite Opinion: BRICS Long-Term Plans & Implications Part 1

The global Forex market is spastic and many major currencies are traversing within weaker whipsaw value ranges against the USD. The currency pairs are trading in price bands seen before the Fed cut its Federal Funds Rate by 0.50 basis points on the 18th of September. And there is still one and a half weeks of assured volatility that will be demonstrated. Crucial U.S data is on the schedule in the coming days via the Advance GDP and Non-Farm Employment Change statistics, and the U.S Presidential election is edging closer. Israel and Iran continue to play a game of cat and mouse in the Middle East, which thus far has led to a controlled chaos and not worldwide bedlam. Financial institutions have plenty of reasons to be apprehensive.

Expansion of BRICS Feels Inevitable

Now let’s turn our attention to a tectonic foundational shift building in global trade and geopolitics. Attention on short-term behavioral sentiment which is fragile and has a less than clear mid-term perspective, needs long-term considerations too. Investors are required to contemplate possible dangers that are hiding in open sight and will pose a problem in the future.

The BRICS 2024 Summit was conducted this week in Kazan, Russia. This included the new member nations of Egypt, Ethiopia, Iran and the United Arab Emirates. I am not here to give you a major recap on what took place behind closed doors. I wasn’t invited. But we should look at some of the results and statements made and what they imply strategically.

The BRICS attendees to this year’s conference included powerful dignitaries from approximately 36 nations. One major result of this BRICS conference was to award Partner State status to 13 countries including Algeria, Turkey, Malaysia, Indonesia, Vietnam, Thailand, Nigeria, Uganda, Kazakhstan, Uzbekistan, Belarus, Cuba and Bolivia. Saudi Arabia was invited last year and has not made their full participation official yet, but they attended this year’s conference as an invited guest. The trend appears clear, we are entering a new paradigm in which long-term thinking by the BRICS nations could out maneuver the short-term nonchalance of the West and this has implications for the USD long-term.

There were high level meetings between leaders of BRICS countries including China, India and Russia. Perhaps, more importantly was Vladimir Putin’s bold statement about BRICS desire to start its own grain exchange. Putin also advocated for the creation of a BRICS cartel in other commodities such as metals, including gold. Gemstones such as diamonds and emeralds could develop into a sizeable entity too. This needs to be taken seriously by the West.

Credence must be given because the BRICS nations already are among the largest producers of grains, legumes and oilseeds. The scope of commodity production and supply capabilities by BRICS could certainly turn into a painful thorn in the side of existing large trading companies. And a potentially coordinated energy sector via Iran, Saudi Arabia, Nigeria, Russia and others must be taken into account.

Russia and China as Friends of the Underdogs

Historical entanglements put Western nations like France and others in a vulnerable spot diplomatically as they try to maintain alliances with many BRICS nations. France serves as a good example of diminishing Western influence. France remains on the ground overtly in Africa while dealing with vestiges of a colonial past. But France’s influence in Africa is under stress and their ability to use the continent as a source of power and financial gain is being confronted. France still maintains the Presidential Council for Africa, but France is likely perceived by many of the participants as a wolf dressed in sheep’s clothing. Coups in French influenced African nations have a bloody and present history when political diplomacy does not go well.

Exploiters of the past in many African nations are looked upon with derision and scorn. Russia and China are often viewed as friendly countries who helped fight along the side of certain African nations who sought and achieved independence. The ability to create ascendancy in Africa by Russia and China needs to be looked at within a prism that suggests additional spheres of power will develop in BRICS. Many nations that dealt with colonial statuses in the past are rightfully intent on shaking off the notion of being considered laggards.

The West certainly knows in no uncertain terms it cannot return to colonialism. However, African governments should make sure they are not replacing old masters for new. While some might say it is wishful thinking – and I am still on the fence contemplating the notion – on the part of Russia and China to create powerful commodity cartels, if achieved this actually could prove to be an emphatic first step in attempting to secure a new and powerful currency by backing it with a foundation of intrinsic value. Brazil and South Africa would be a big part of this underpinning too. Russia and China’s foray into Africa via their military and money lending excursions, and the already created organizational and trade structures which exists within BRICS opens the door for the perceived underdogs to battle together against the power of Western riches.

A competition is certainly underway between the West and BRICS. What exactly is the U.S doing in Angola? The planed visit of Joe Biden in the first week of December, which was supposed to take place in mid-October was postponed due to the recent hurricanes. Will the U.S presidential visit be anything more than a sideshow, particularly if the Democrats do not win the election on November the 5th? Angola has a massive amount of Crude Oil and is an OPEC member. American energy companies and other Western corporations are active commercial participants in the African nation. However, China has a firm financial stake in Angola via infrastructure projects too. The political and financial implications between BRICS and the West is a growing dynamic, one that will be further discussed in Part 2.