postR162.1

USD Weakness: Wagers on Fed Outlook as Risk Appetite Surges

USD Weakness: Wagers on Fed Outlook as Risk Appetite Surges

Yesterday’s start for the week was slightly subdued as many nations in Europe enjoyed a long holiday weekend. In Forex the past few weeks the USD has taken on a weaker stance and this was reiterated by last Wednesday’s slightly lower U.S Consumer Price Index results. The outlook of investors and financial institutions has once again shifted and a more dovish U.S Federal Reserve is being anticipated for the moment.

However, while inflation data from the U.S did come in with lower marks via the CPI report last week, it should be remembered the PPI actually came in higher. While there is a natural instinct to always be optimistic, the prudent fact is that risk management remains important. A glance into the looking glass via the USD/JPY shows that all is not calm in the world of Forex.
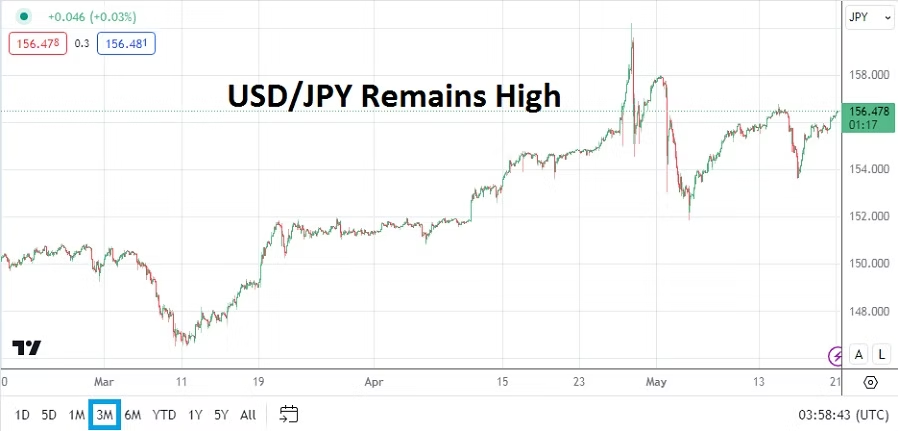
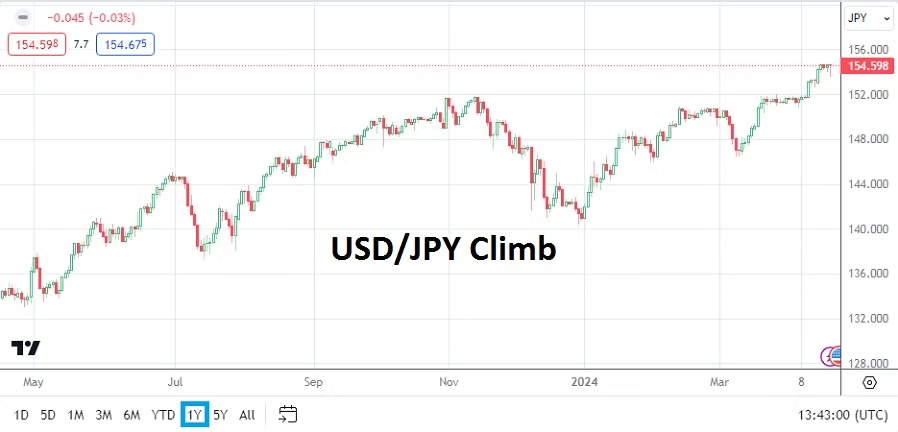
USD/JPY Three Month Chart on the 21st of May 2024

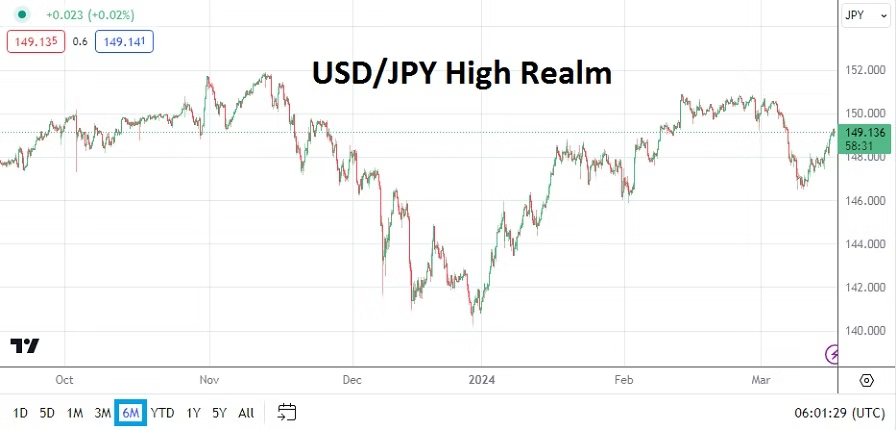
While many currencies have gained against the USD since late April, the price action in the USD/JPY represents anxiety regarding central bank policies from the Bank of Japan and Federal Reserve. The USD/JPY since experiencing two interventions from the BoJ has incrementally climbed again – meaning the Japanese Yen remains weak, this while other major currencies like the GBP and EUR have gained against the USD. Yesterday’s Tertiary Industrial Activity data from Japan came in negative, showing strains exist within the Japanese economy which underlies why the Bank of Japan may be staying cautious. The ability of the USD/JPY to not trade in a correlated manner to global Forex is proving difficult for some day traders. Volatility within the USD/JPY is not finished.
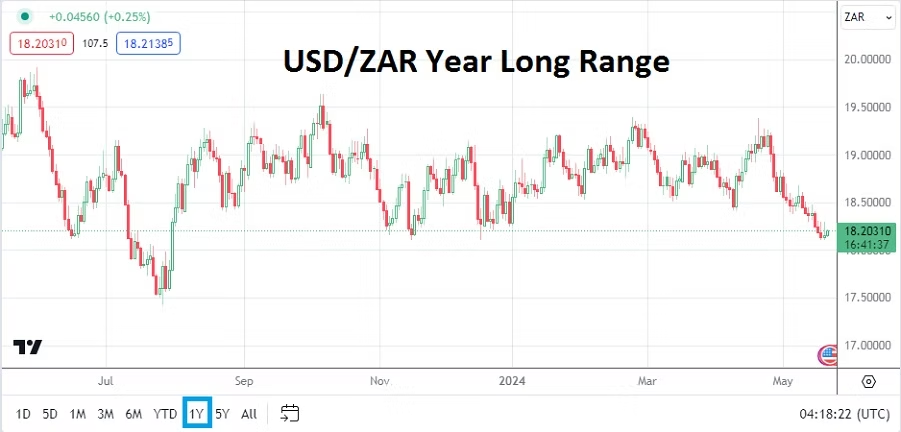
USD/ZAR 1 Year Chart on the 21st of May 2024

However, if people want to look at the knock-on positive influence of the weaker USD, they can glance at the USD/ZAR which is near important mid-term lows. South Africa will be conducting their national election next week on the 29th of May, which is likely to cause some nervousness for the currency pair. Even though South Africa continues to suffer from a struggling economy caused by questionable government policy and faltering infrastructure, the USD/ZAR is experiencing solid bearish behavior. However, risks certainly remain for the South African Rand and at its current values, some financial institutions may view the currency pair suspiciously.
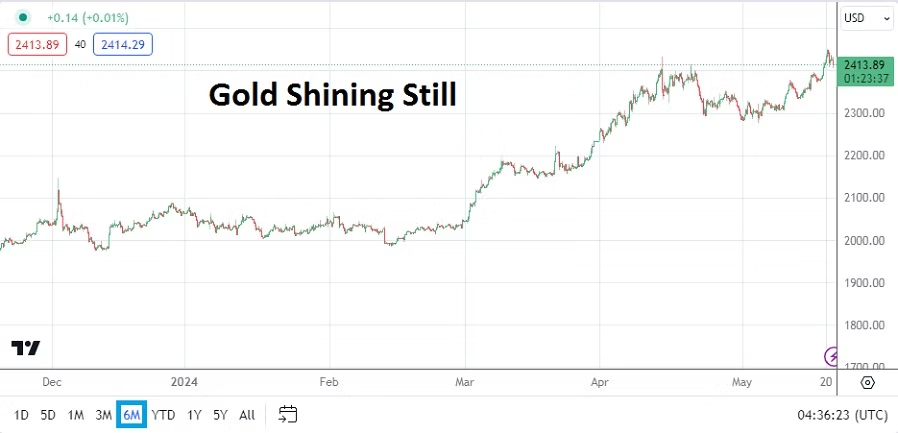
Gold Six Month Chart on the 21st of May

Gold remains within sight of record values achieved yesterday when the 2,440.00 USD plus levels were touched. The shift in behavioral sentiment towards risk appetite and a weaker USD centric attitude seemingly geared towards dovish Fed mid-term perspectives have helped the precious metal. Day traders should remain cautious with Gold and while the technical trend is enticing, it will be good to remember too much leverage coupled with blind betting can be dangerous. A clear warning sign that speculative zeal is high in Gold is that the current price of the commodity is 30.00 USD lower for the moment compared to yesterday’s highs. Price velocity can prove costly when a daily reversals goes against wished upon directions.

U.S equity indices and their ability to fight toward new highs is a clear sign risk appetite via outlooks within financial institutions and from investors remain strong. U.S Treasury yields should be monitored and if they continue to erode this will fuel optimism. One additional note for traders this coming week is that Memorial Day will be observed in the U.S next Monday, meaning there may be more impetus for some to buy U.S equity indices now instead of waiting out a long holiday weekend and coming back to markets which have gained. Yes, Fear of Missing Out could be a factor.
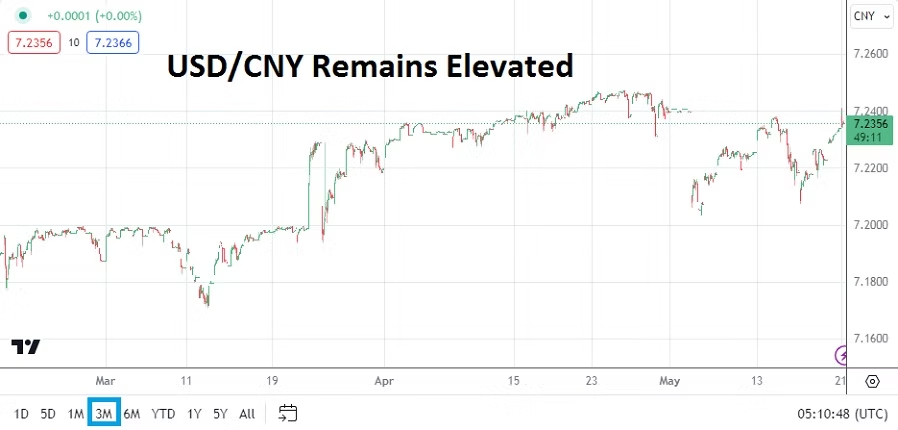
USD/CNY Three Month Chart on the 21st of May 2024

Monday, 20th of May, China Loan Rates – while banks kept their 1 and 5 year Prime Rates in place per the reports yesterday. Last Friday’s Retail Sales figures came in weaker than anticipated, and New Home Prices produced another decline. Industrial Production numbers were however stronger than expected before going into last weekend. China remains in a difficult position economically and the USD/CNY should remain observed because it is elevated.

Tuesday, 21st of May, Canada Consumer Price Index – inflation numbers from Canada will be watched carefully. The results will impact the USD/CAD certainly, but unless there is a surprise result which misses estimates wildly, the currency pair should return to a USD centric mode rather quickly.

Wednesday, 22nd of May, U.S Federal Reserve FOMC Meeting Minutes – while this report is not read by many people, and the Federal Reserve will have taken a cautious rhetorical tone, the report may offer some tidbits for consideration. However, the reality is that U.S economic data has been a mess for the past few months. GDP showed signs of decreasing last month, but the multi trillion dollar question is if inflation is now under control. Folks looking for answers will not find them in the Fed notes. They will have to wait like everyone else for more data in the weeks and months to come.

Thursday, 23rd of May, European Flash Manufacturing and Services PMI – the Purchasing Managers Index reports from European Union members and the U.K are anticipated to show signs of some improvement mostly. The U.S will also be publishing its reports, although the Services report from the States is expected to be slightly weaker. Investors will react to all of this data. Positive readings from E.U and U.K would likely have a positive influence on the EUR/USD and GBP/USD for bullish speculators.

Friday, 24th of May, U.K Retail Sales – consumer spending is anticipated to show a decline. However, the last Gross Domestic Product report from the U.K was stronger than anticipated. While the Retail Sales data is important for the GBP/USD, as long as the outcome meets expectations or comes in slightly stronger than estimated the currency pair could retain technical value.

Friday, 24th of May, U.S Revised Consumer Sentiment and Inflation Expectations – the University of Michigan numbers for sentiment came in weaker than expected last month. The anticipated outcome is slightly better for this report. However, the inflation numbers should be watched carefully via the U. of Michigan statistics. The tick higher in recent reports regarding where prices are expected to go by consumers is troubling for the prospects of the U.S economy.

If American consumers are not confident they will spend less. Yet, within the strange world of economic data and policy consisting of lagging and forward looking numbers, if consumers feel less optimistic this means the U.S Federal Reserve will be pushed to consider cutting the Federal Funds Rate, unless inflation actually does remain elevated. And again, traders should remember that a long U.S holiday weekend might add to the rather electric financial markets.
postR168

AMT Top Ten Miscellaneous Intrigues for the 17th of May 2024

AMT Top Ten Miscellaneous Intrigues for the 17th of May 2024

10. Georgia and Slovakia: It would we wise to pay attention to Tbilisi demonstrations, and also cast an eye on Bratislava after the assassination attempt of Prime Minister Fico. Russia is certainly paying attention.

9. Superconductivity: Origin Quantum Computing Technology of China is making solid advancements and has announced they are ready to domestically produce a 72 qubit capable microwave module known as ‘Origin Wukong’. The battle to create efficient quantum components and operating systems between China, the U.S and others is real.

8. Secretary of Music: Anthony Blinken’s naive decision to play guitar in a Kiev nightclub this week is comparable to Nero playing music while Rome burned. U.S foreign policy continues to raise concerned eyebrows from friends and foes alike.

7. South African Election: The coming vote on the 29th of May is less than two weeks away. USD/ZAR as of this writing is near 18.22000, where will it be on the 30th of May?

6. Biden and Trump: The potential for debates between the two presidential candidates is growing. One question observers may be wondering is if there is adequate supply of caffeine to keep Joe energetic and ample enough hairspray for Donald to look under control?

5. GameStop: Yet another market manipulation of GME is causing massive losses for day traders. The price for the stock finished near $27.67 yesterday, this after touching a high above $56.00 on the 14th of May. GME was close to $10.00 on the 15th of April. Buyers that get in too late to these betting schemes created by frenzied crowds tend to go bust as the early manipulators cash out their profits.

4. Commodities: Cocoa is near 7560.0 USD per metric ton, and Coffee Arabica is traversing slightly below 200.00 USD. Speculative forces remain powerful in both and while they are likely still overpriced, risk management is imperative for those pursuing lower values.

3. Federal Reserve: After the weaker than anticipated CPI numbers printed this Wednesday, and last week’s eroding GDP growth statistics, financial institutions are increasing their risk appetite as they watch U.S Treasury yields decline and consider a mid-term outlook which is allowing for the contemplation of actual Federal Funds Rate cuts.

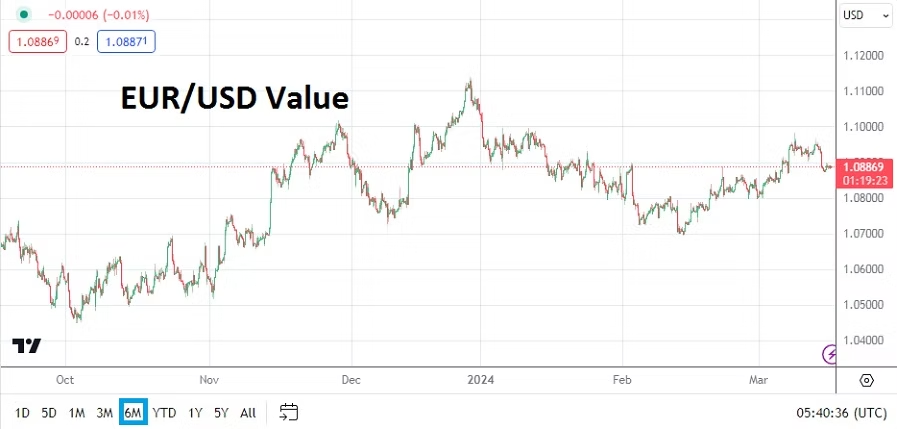
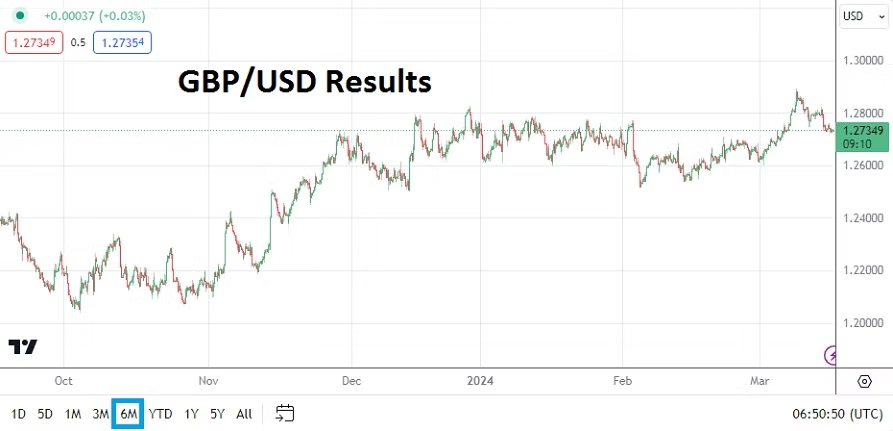
2. Forex: The EUR/USD is back above the 1.08000 level comfortably, and the GBP/USD has found sustainable trading beyond the 1.26000 ratio. While the major currencies versus the USD have pulled back slightly from near-term highs, large commercial traders are exhibiting risk appetite. A weaker USD centric notion is coming into vogue again.

1. Apex Equities: The three major U.S indices are all near record territories as solid earnings reports from corporations, amidst hopes the Federal Reserve will be able to cut rates a couple of times this year has combined to allow optimism to grow in the S&P 500, Dow 30 and Nasdaq 100. While the U.S public is starting to show they are losing confidence because of escalating consumer prices, financial institutions are wagering on solid returns via economic outlooks. Day traders looking to join the indices parade should make sure they limit their exposure, particularly if they are using CFDs and relying on short-term climbs which can suffer from sudden reversals lower.

post204

AMT Top Ten Miscellaneous Tastings for the 10th of May 2024

AMT Top Ten Miscellaneous Tastings for the 10th of May 2024

10. Word of the day: Ultracrepidarian is a person who speaks assertively about subjects that are beyond their level of knowledge. The world is full of many suspects ladies and gentlemen.

9. Steve Albini: The musician and production sound engineer passed away earlier this week in Chicago. Albini was a pioneer and leader in ‘alternative’ music and battled homogenized corporate music for nearly 40 years. Nirvana, Fugazi, Jimmy Page, the Pixies, P.J Harvey are some of the many that worked with Albini.

8. Bitcoin: BTC/USD continues to hover around the 63,000.00 realm per a three month technical chart perspective. Bitcoin’s higher values via one year results are being maintained. BNB/USD is lurking near 600.00 per a three month glance.

7. Commodities: Cocoa and Coffee prices remain elevated. After touching a low around the 7,250.00 USD mark last week per metric ton, Cocoa is now within sight of 9,000.00 USD again. Retail speculators who like to wager via CFDs on commodities need to remember their bets have no influence on the markets, which are in complete control by the largest players in the commodities sector.

6. Wayve Technologies: A U.K based company specializing in autonomous driving software has announced they have raised more than 1 billion USD in investments recently via the likes of Softbank, Nvidia and Microsoft. The U.K government has highlighted Wayve, proclaiming it shows Britain will be a major force in AI development. Wayve was established in 2017 and is still a privately held company.

5. U.S Foreign Policy: Election concerns appear to be a prime motivator for the U.S executive branch as its attempts to walk a fine line regarding diplomacy and saber-rattling in the Middle East. Polling from a variety of sources indicate Joe Biden is in jeopardy of not being reelected.

4. USD/CNY: China will release its Consumer Price Index and Producer Price Index numbers early on Saturday. The USD/CNY is trading around the 7.2245 mark as of this writing. Some analysts have expressed concerns about the China Yuan weakening via attempts by the Chinese government to boost exports. The USD/CNY certainly remains within the higher elements of its range, but is below marks seen in early September 2023 which were around the 7.3425 ratio.

3. Data Warning: While day traders may be inclined to look at the University of Michigan’s Consumer Sentiment reading today, they should remember to pay attention to the Inflation Expectations statistics. Last month’s inflation report produced a result of 3.2%, which delivered a solid dose of volatility to financial assets.

2. Forex: Behavioral sentiment appears to be leaning towards a weaker outlook for the USD as major currencies like the EUR, GBP (solid GDP numbers also helped this morning in Britain) and others have gained. However, its should be pointed out that the USD/JPY has seen an incremental climb since touching a low of nearly 151.880 last Friday. As of this writing the USD/JPY is around the 155.650 level.

1. Equity Indices: Bullish optimism has been seen in the S&P 500, Dow 30 and Nasdaq as all three major indices are ready to start the day near highs for the week. The burst of upwards momentum which started last Thursday, has ignited the major U.S indices within sight of their apex realms achieved in late March and early April.

postR160.1

Forex: Shifting Winds and Potential Optimism for Speculators

Forex: Shifting Winds and Potential Optimism for Speculators

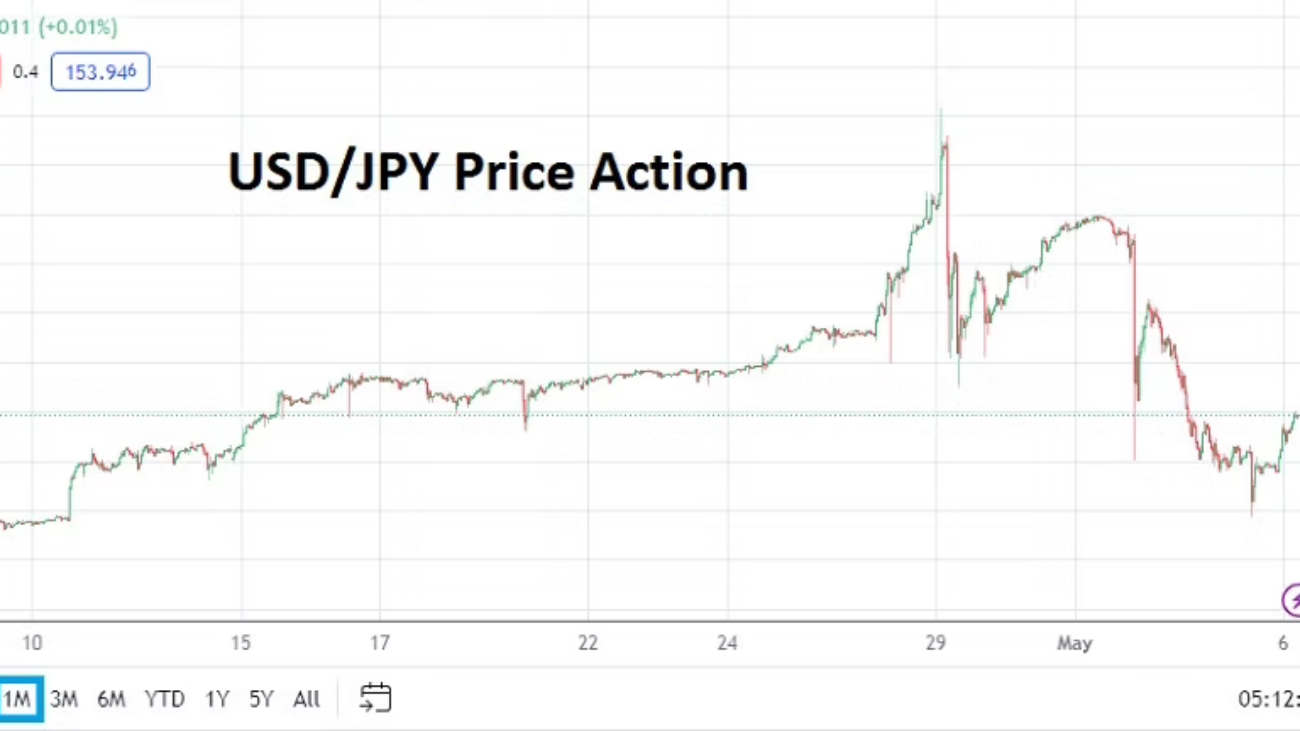
The BoJ intervened in Forex and propelled two fast selloffs of the USD/JPY last week. The actions by the Bank of Japan did not come as a surprise as the central bank seeks to maintain a dovish interest rate policy, a relatively weak Japanese Yen – but also a philosophy of not letting the JPY to suffer too much. Speculators and financial institutions got caught up in the price action which ensued as a clash developed between large traders and the BoJ as equilibrium was sought.

The BoJ clearly wants to keep the USD/JPY within the weaker realms of its long-term values to spur on the Japanese export sector with solid business results. However, domestically the Japanese government doesn’t want inflation within Japan to inflict too much pain for its citizens. BoJ interventions were carried out twice last week, once during a holiday in Japan, and the second when most global financial institutions were shuttered. At the time of this writing the USD/JPY is trading near the 153.720 mark.

Day traders always need to understand just how small they are within the larger speculative world. They need to judge economic intelligence and forecasts to get an understanding where behavioral sentiment could affect tides.

USD/JPY One Month Chart on 6th of May 2024

In the U.S, inflation and growth data caused investors to react nervously a week and a a half ago, additionally more anxious moments were fueled by the Federal Reserve’s FOMC Statement this past Wednesday when the Fed said it was uncertain about the timetable that inflation would return to their stated goal of two percent. Forex trading has been volatile the entire calendar year of 2024 for speculators.

Nearly ten days ago while inflation continued to prove it was stubborn via the U.S GDP Price Index on the 25th of April, Advance GDP data was much weaker than expected showing that economic growth was slowing. And last Friday’s Non-Farm Employment results were not only weaker regarding hiring, but also showed a slight drop in Average Hourly Earnings. This might have been enough to begin causing a shift in financial institution outlooks. This week of trading will prove interesting regarding risk appetite versus risk averse sentiment, particularly if large players believe economic data is finally catching up to the Fed’s rhetoric.

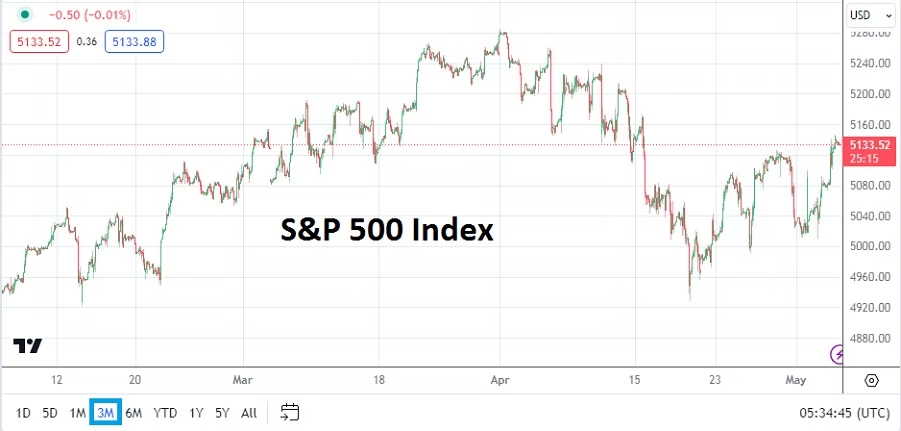
U.S equity indices which started last week with selling and battled lower depths in the middle of the week, began to see buying develop on Thursday, and finished Friday’s trading within their highs via weekly technical charts. While it is easy to report the past, it is the future speculators want to know. The ability of the U.S jobs numbers to produce results which were seen in a favorable light regarding the Fed’s ability to potentially cut the Federal Funds Rate certainly was an optimistic sign for financial institutions. If inflation can remain under control it would help the global economic picture. On that note, WTI Crude Oil is trading below 80.00 USD and should be monitored.

S&P 500 Index Three Month Chart on 6th of May 2024.

Monday, 6th of May, European Union Final Services PMI – Italy, France and Germany among other will present Purchasing Managers Index data. The broad numbers are mostly expected to replicate the previous month’s outcomes. Traders should note the U.K is observing a banking holiday today, which means lighter than normal Forex volumes will be seen.

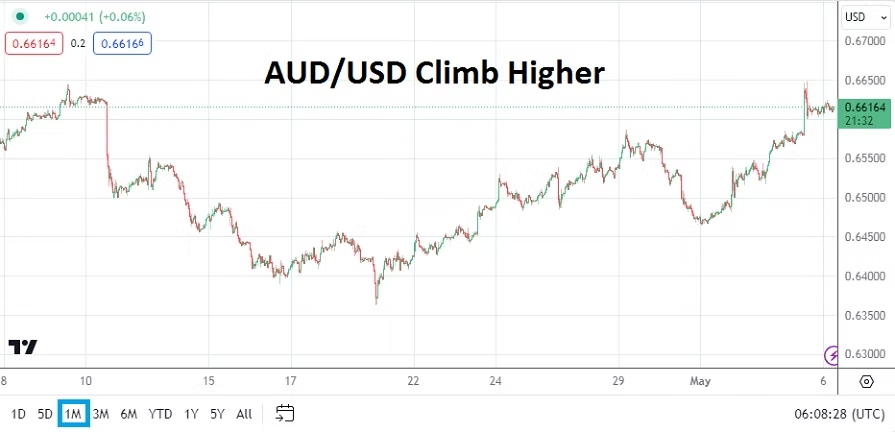
Tuesday, 7th of May, Reserve Bank of Australia Monetary Policy Statement – the central bank is not expected to change its interest rate. The AUD/USD has provided some upwards momentum the past week. The RBA is not expected to step out of line regarding global central bank policies. Expect talk about an optimistically cautious outlook by the RBA as they preach patience regarding an interest rate cut.

AUD/USD One Month Chart on 6th of May 2024

Wednesday, 8th of May, Bond Sales from Japan, the U.K and the U.S – while many European nations observe a holiday, Japan, Great Britain and the U.S will sell government debt. U.S Treasury yields should be watched and equity indices should have an eye kept on them. If behavioral sentiment remains optimistic as this day comes to a close it could set the table for more bullishness, particularly if the USD remains relatively tame or weaker.

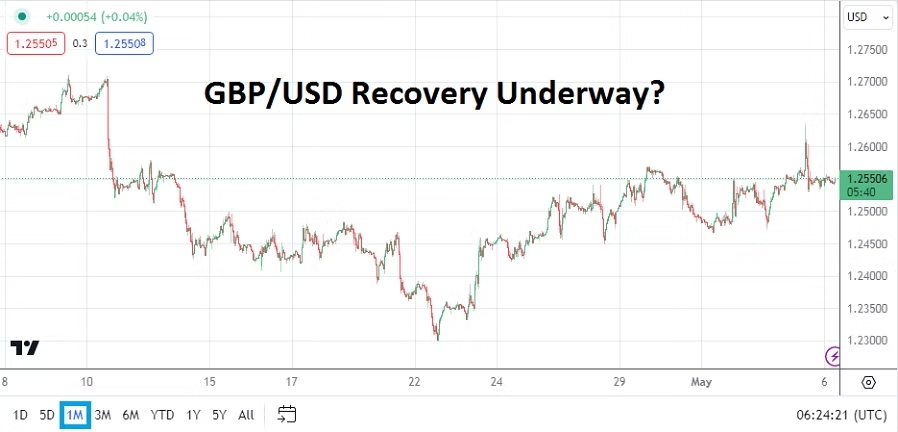
Thursday, 9th of May, Bank of England Monetary Policy Summary – the BoE is likely to mirror other central banks and keep its interest rate policy in place. No changes are expected to the Official Bank Rate. However, it would not be surprising to hear the BoE try to pose upbeat expectations, and if this occurs perhaps the GBP/USD will continue to find some momentum upwards.

GBP/USD One Month Chart on 6th of May 2024

Thursday, 9th of May, U.S Weekly Unemployment Claims – investors will keep their eyes on the jobs report. If the numbers come in around expectations this would allow risk appetite to remain strong in the near-term.

Friday, 10th of May, U.K Gross Domestic Product – an expected gain of 0.1% is forecast. GBP/USD traders who have bullish sentiment will be looking for the number to match expectations or beat the anticipated result. If the number is weaker, this could cause a reversal lower in the GBP/USD and an attempt to push back against gains made in the currency pair recently.

Friday, 10th of May, U.S Consumer Sentiment and Inflation Expectations via the University of Michigan – these readings will be watched by investors to see if consumers continue to show decreasing confidence in the U.S economy. While it sounds counter intuitive to want eroding sentiment regarding the ability to spend money, this would create more ammunition for the Federal Reserve to consider an interest rate cut. The Inflation Expectations could be the catalyst for traders going into the weekend regarding the USD.

postN2.1

Impact: Powell’s White Flag, Inflation Data, and the BoJ

Impact: Powell's White Flag, Inflation Data, and the BoJ

Federal Reserve Chairman Jerome Powell’s waving of the ‘white flag’ last Tuesday, when he admitted that inflation was producing stronger than anticipated data had been essentially wagered on since the second week of March by financial institutions. Powell’s speech acknowledging the Fed will find it difficult to cut the Federal Funds Rate in the mid-term (and probably at best not until late this summer) simply verified Forex positions which had already been taken by large players who could afford to make mid-term wagers.

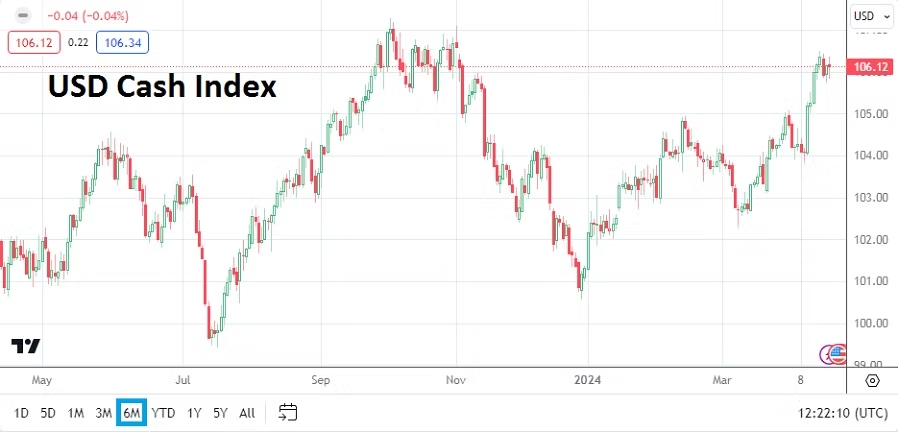
The USD Index has returned to early November 2023 values, and appears able to challenge late September and October prices if inflation data this week causes more volatility, which should put traders of major currencies like the GBP, EUR, JPY and others on full alert. After the USD spiked higher from the 10th to the 12th of April, Forex speculators have seen dynamic action incrementally flirting with stronger USD results the past week and a half.

USD Cash Index Six Month Chart as of 21st April 2024

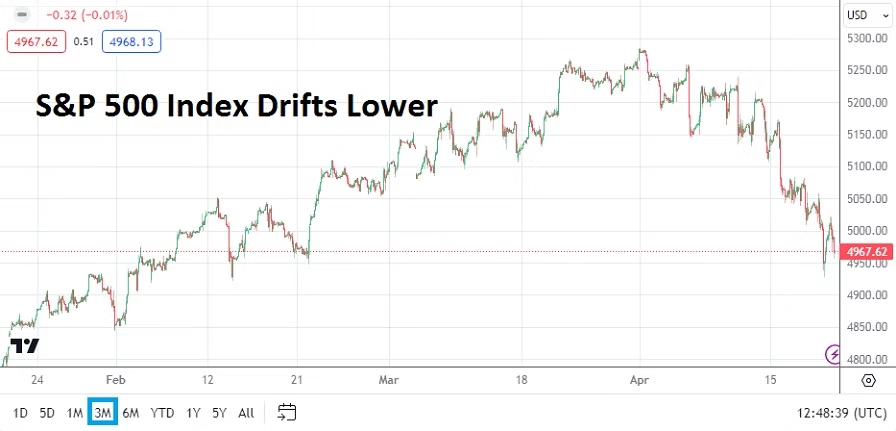
Nervous trading continues to be seen in U.S equity indices. The Dow 30 and the Nasdaq 100 are fighting near ratios they touched in the last week of January. And the S&P 500 is traversing ground from the first week of February.

S&P 500 Three Month Chart as of 21st April 2024

Content

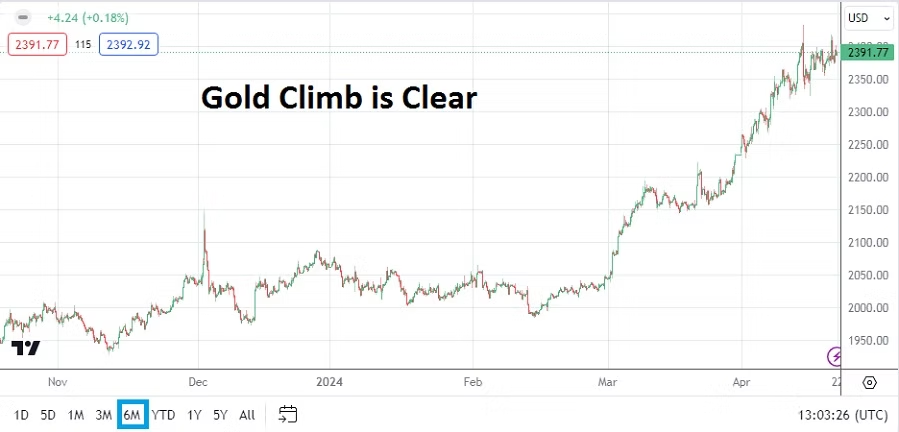
Gold Six Month Chart as of 21st April 2024

Gold remains speculatively high as its hovers near 2,400.00 USD per ounce. The price of the precious metal has not given back its gains made since the start of March and this is intriguing because of the ‘known’ USD inverse correlation, which had proven to work well with the precious metal over the past couple of years but has been stopped in its tracks for the moment. Technically Gold may look overbought, but geopolitical concerns and the prospect that some central banks may be strong buyers could be fueling the rather incremental gains. Retail traders of Gold need to be careful because price action is likely to produce more surprises.

Forex has been turbulent the past handful of months as shifting behavioral sentiment has created choppy conditions. This coming week contains large fundamental risk events via data releases traders should monitor. USD/JPY speculators will also have to contend with the Bank of Japan.

Monday, 22nd of April, China Loan Prime Rates – borrowing costs are anticipated to remain at the current benchmarks. China produced slightly better Gross Domestic Product results last week, but Industrial Production numbers were weaker. Consumers in China remain burdened by decreasing home values and concerns about the economy.

Tuesday, 23rd of April, European Union and U.K Manufacturing and Services PMI – E.U results via the PMI readings are expected to show slight improvements. However the readings from the United Kingdom are anticipated to come in flat. The EUR/USD and GBP/USD will be affected by the results, but the currency pairs will likely remain focused on U.S data later in the day.

Tuesday, 23rd of April, U.S Purchasing Managers Index – the Manufacturing and Services sectors are expected to produce slightly better readings than the previous month. These results will be interesting taking into consideration the Empire State Manufacturing Index numbers last week were bad. The PMI statistics will provide some impetus to the broad Forex market.

Wednesday, 24th of April, Australia Consumer Price Index – inflation data is anticipated to be higher than the previous month’s results. While stronger inflation is not something that will make consumers happy in Australia, stubborn price results may keep the AUD/USD slightly steadier. The currency pair is traversing values last seen in the second week of November 2023 as of this writing.

Thursday, 25th of April, U.S Advance Gross Domestic Product and Price Index – these numbers are certain to have an impact on all financial assets. A decline in growth is anticipated in the U.S compared to the previous month’s result, but the Price Index is expected to show an increase. Jerome Powell having come out last week and said inflation is causing uncertainty within the Federal Reserve, may have a bit of inside knowledge regarding this GDP inflation number and ‘tipped his hand’. If this inflation gauge is higher than anticipated it could pour fuel onto the already volatile USD. All Forex traders need to pay attention to these results and be prepared with solid risk management.

USD/JPY One Year Chart as of 21st April 2024

Friday, 26th of April, Bank of Japan – in what has already proven to be a couple of weeks filled with drama for the USD/JPY, the BoJ will step into the limelight. During their last central bank meeting the Bank of Japan increased the Policy Rate to 0.10%. It was the first time the BoJ hiked interest rates in 17 years. The USD/JPY is trading at values last seen in June of 1990. The Nikkei 225 has come off of recent record heights, but the famed Japanese stock index is also trading within territory seen in January of 1990. Business activity via the Core Machine Orders and the Tertiary Industry data last week were stronger than anticipated.

The Bank of Japan may want to maintain a weaker USD/JPY equilibrium to continue fostering domestic growth. However, many financial analysts have been calling on the BoJ to become more hawkish regarding monetary policy. The interest rate decision is certain to cause immediate volatility before and after the Policy Rate is made public. USD/JPY traders need to be prepared for fireworks. A slight raise of the interest rate seems to be needed, but after the March hike the BoJ may prove conservative again. The 34 year lows now being seen in the Japanese Yen are astonishing.

Friday, 26th of April, U.S Core PCE Price Index, and Inflation Expectations – the data from the government, and the reading from the University of Michigan will close the curtain on a big week of economic statistics for all traders. The USD will react to these outcomes. It should be noted the previous Inflation Expectations data from the University of Michigan caused a storm in Forex when it came with 3.1% gain.

post200

Retail Traders Caught Out by Shifting Sentiment as Data Hits

Retail Traders Caught Out by Shifting Sentiment as Data Hits

Forex speculators who relied heavily on technical data solely last week were likely punched in the gut by the rather surprising numbers from the Consumer Price Index results in the U.S last Wednesday, particularly if they were on the wrong side of trading trajectories. U.S inflation has shifted sentiment within many large investors with a rather seismic move regarding mid-term outlooks. Financial institutions which have been counting on cuts to the Federal Funds Rate have had to take a step backwards.

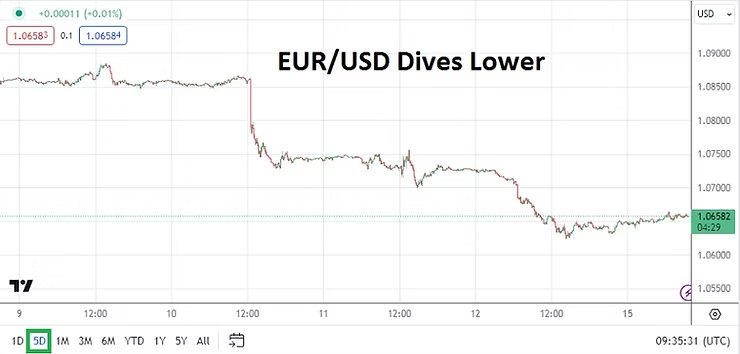
EUR/USD Five Day Chart as of 15th April 2024

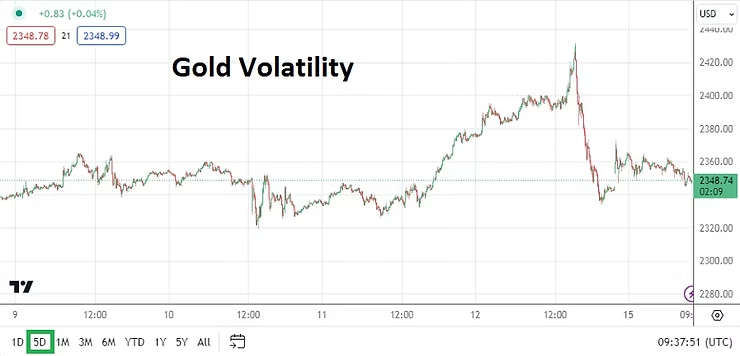
The dynamic momentum in Forex hit major currency pairs in the middle of last week and washed away support and resistance levels within a blink of the eye. Behavioral sentiment turned U.S Treasuries yields upwards and the major equity indices also experienced nervousness. Volatility also continued in Gold as new record values were produced, and then were followed by a rather strong reversal lower which likely hurt over-leveraged day traders.

Gold Five Day Chart as of 15th April 2024

Not only were U.S inflation numbers important last week, but geopolitical noise became heightened. Perhaps the climb in Gold before the weekend was helped by the anticipated conflict between Iran and Israel which did play out. The price of the precious metal and WTI Crude Oil have been more tranquil early today, which may be a signal for the moment that large market players are calm.

Monday, 15th of April, U.S Core Retail Sales – after last week’s larger than expected increase in the CPI results, the spending report today will get attention from financial institutions. Last Friday’s Preliminary Price Expectations reading from the University of Michigan did not allow investors to rest when it came in with a 3.1% elevated mark. If today’s Retail statistics are above expectations, this could make Forex roil again.

Tuesday, 16th of April, China Industrial Production and Gross Domestic Product – these economic reports will be watched closely by international investors. While there have been murmurs that China’s economy is improving, and media reports that the Biden administration is trying to engage diplomatically, the industrial and GDP results are expected to be weaker than the previous month’s outcomes. China will also release Retail Sales figures.

GBP/USD Five Day Chart as of 15th April 2024

Tuesday, 16th of April, U.K Claimant Count Change – last Friday’s GDP report from Britain did not produce any significant surprises. The U.K economy continues to struggle, but like most spheres inflation remains a problem. The GBP/USD sunk violently last week, while many speculators may believe it is currently oversold they may want to remain cautious.

Because of the U.S Federal Reserve’s own perilous fight against inflation, there are some who believe the Bank of England may need to cut interest rates before the U.S central bank. However, given the lack of proactive characteristics from the BoE and ECB which have been on full display as they dance in step with the Federal Reserve, this makes a BoE cut before the Fed a skeptical notion for the time being. The GBP/USD will stay largely USD centric even in the wake of this U.K employment report.

Tuesday, 16th of April, U.S FOMC Members – a parade of Federal Reserve voting policymakers will speak at various events, this includes Fed Chairman Jerome Powell. There will likely be little in the way of surprises from the Fed members as they likely all stick to ‘party’ lines and emphasize a cautious outlook.

Wednesday, 17th of April, U.K Consumer Price Index – the inflation report could prove to be catalyst for the GBP/USD. If the CPI number does come in weaker than expected it could spur on behavioral sentiment shifts regarding the potential for changes to BoE policy. Because the GBP/USD was so volatile the past week, day traders should be prepared for rather combustible price action from the currency pair which may look counter-intuitive. Smaller speculators should remember that ‘smart money’ from larger players may be positioned for the results of the U.K CPI data already.

Thursday, 18th of April, U.S Weekly Unemployment Claims – although not the most significant of reports usually, financial institutions are ‘waiting’ on a change of statistical direction via labor market evidence. If jobs numbers start to come in weaker than anticipated – meaning there are higher jobless claims – then the USD could react with some selling.

Friday, 19th of April, U.K Retail Sales – having endured a rather wild trading cycle, Great Britain will deliver one more important economic report to end this week. The GBP/USD will react to the consumer spending results.

postN77.1

Forex: Behind the Curtain as Speculative Deja Vu Strikes

Forex: Behind the Curtain as Speculative Deja Vu Strikes

Friday jobs reports came in stronger than anticipated on the surface, and this led to a roller coaster like ride for Forex traders as results were acted upon by financial institutions. However, a look behind the data shows ‘positive’ results were spurred on by part-time hiring and government influences leading to a notion that jobs numbers were not exactly a ray of sunshine regarding U.S economic health. The suspicious results cause a desire to look for ulterior motives, and to wonder if election year politics are playing a role in the U.S employment picture.

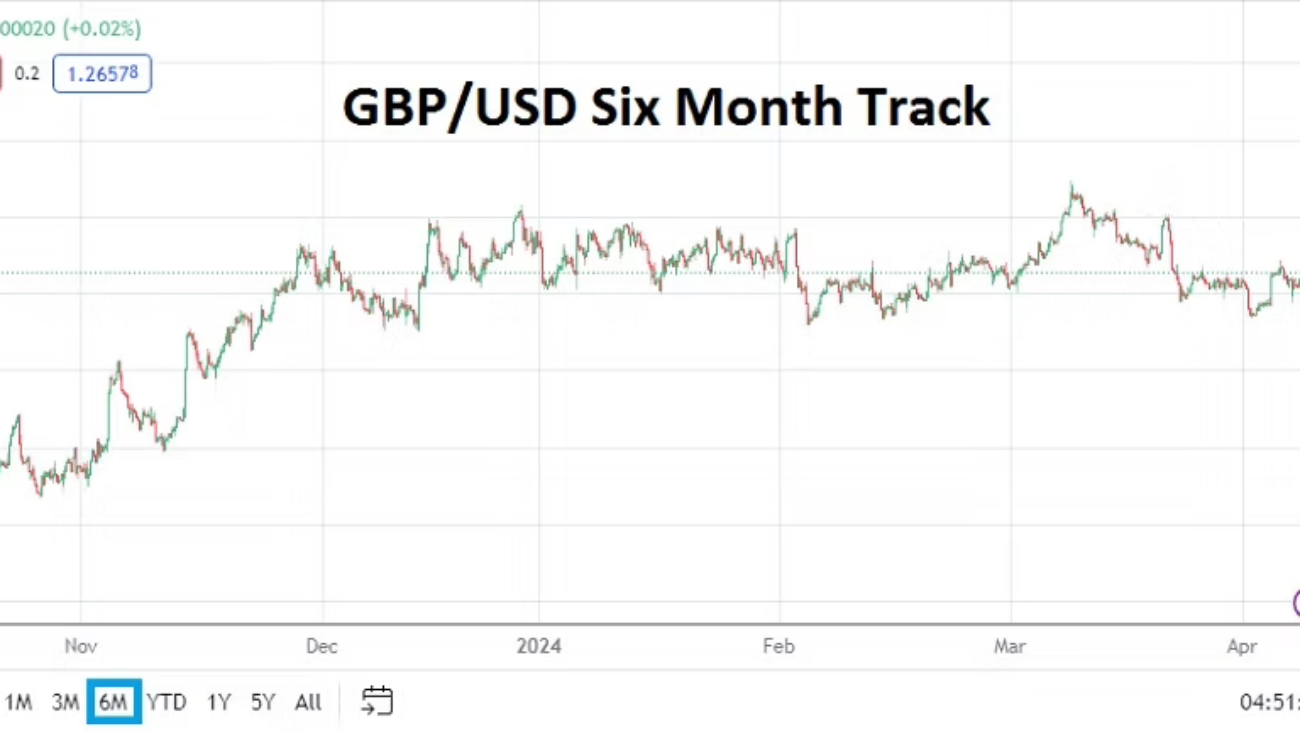
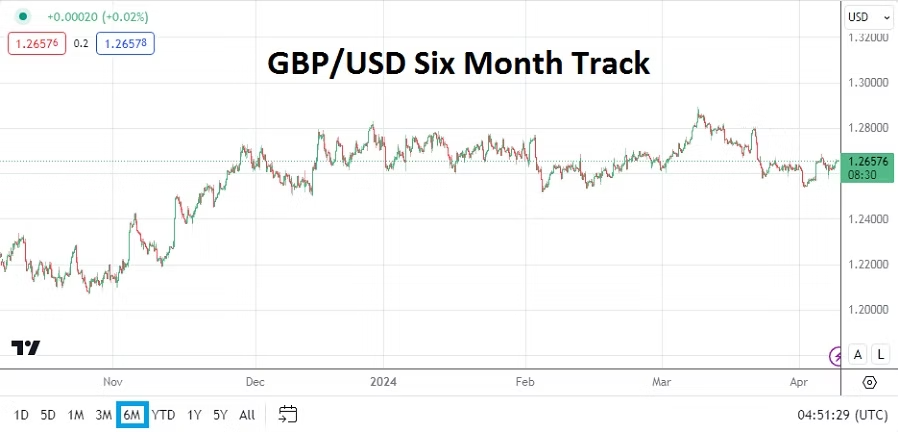
GBP/USD Six Month Chart as of 9th April 2024

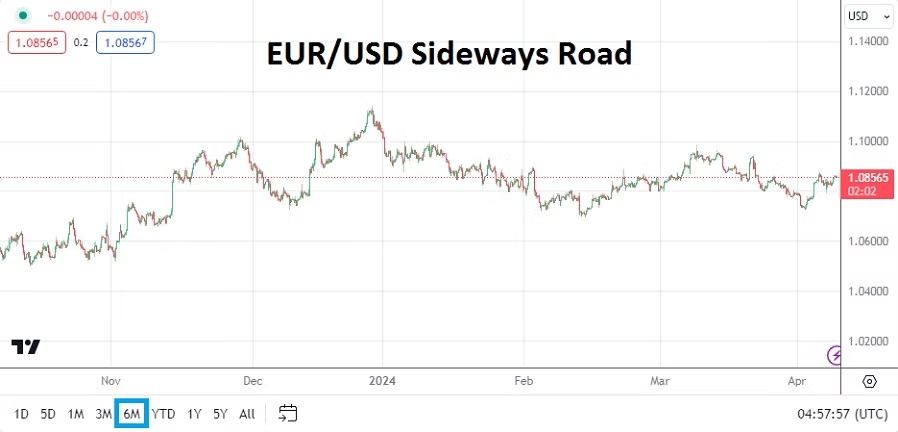
The GBP/USD and EUR/USD are rather insightful for technical and fundamental traders. The currency pairs are languishing as of today’s values near pricing that was seen in the second week of December. Since the ‘announcement’ from the U.S Federal Reserve on the 13th of December that a change in monetary policy would begin to occur in 2024, in actuality nothing has really happened, except government ‘speak’ trying to sound as if everything is understood and in control, while it is clearly not.

Economic data from the U.S and Europe has continued to be soiled by mixed results, and retail speculators looking for a trend to emerge have had to deal with choppy conditions. Financial institutions remain unclear about interest rate outlooks. The Fed while trying to ‘sound’ dovish rhetoric remains locked within a Google engine keyword mantra as they mutter the phrase ‘over time’ when trying to convince people that interest rates will ‘eventually’ be cut.

Last week leading up to the Non-Farm Employment Change numbers, many FOMC members were offering cautious tones about the Federal Funds Rate and warning it should not be changed yet. The implication of the Fed’s verbiage could lead some to suspect they have all practiced statements handed to them by their overlords who are concerned this is an election year and jobs are in jeopardy.

EUR/USD Six Month Chart as of 9th April 2024

Which leads us back to Forex and all financial assets, as investors try to swim waters which have left fundamental perspectives grasping at data which is not easy to decipher. U.S government policy is practicing fiscal spending that is causing massive debts, and perhaps influencing hiring data which may be more akin to putting lipstick on a pig. Many U.S voters seemingly lean towards electing officials who promise to hand out the biggest ‘social rewards’, while ignoring there will be a price to be paid down the road.

The Federal Reserve in the meantime tries to sound optimistic about inflation eroding, but concerns due to U.S government debt being accrued, and global geopolitical affairs combined with energy policy which is making it more expensive to maintain cheap transportation, efficient agriculture and manufacturing, shadow the Fed’s hopes. WTI Crude Oil remains over 86.00 USD per barrel. Gold is trading at record high values and above 2300.00 USD. Does anyone see the dangerous connections? Equity indices should be watched as a barometer this week.

USD/JPY Six Month Chart as of 9th April 2024

Monday, 8th of April, Japan Average Cash Earnings and Economic Watchers Sentiment – yesterday’s reports matched expectations regarding wages, but workers surveyed noted their concerns about incremental inflation which is being seen in Japan. The USD/JPY is challenging November higher values and the Bank of Japan has been widely criticized for not raising interest rates more aggressively. However, it is possible the BoJ wants the Japanese Yen to remain within its weaker price range to spark a stronger Japanese economy via exports.

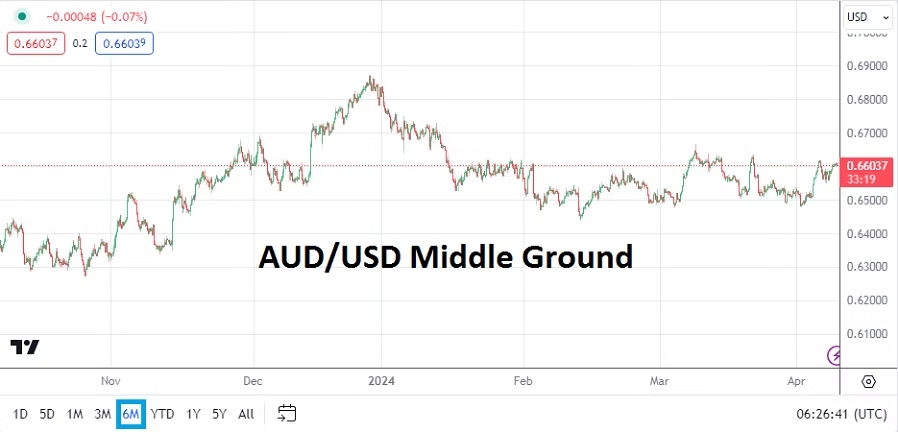
AUD/USD Six Month Chart as of 9th April 2024

Tuesday, 9th of April, Australia Westpac Consumer Sentiment – the results via the consumer reading came in negative. The AUD/USD like the GBP/USD and EUR/USD is traversing values tested in the second week of December 2023, leading to the feeling of deja vu.

Wednesday, 10th of April, U.S Consumer Price Index – you have heard this before, the inflation reports from the States are going to rattle the financial markets including Forex. The USD is certain to react. Data from the U.S has produced surprises aplenty in the past few months. The Consumer Price Index is important and day traders certainly need to pay attention.

Thursday, 11th of April, European Central Bank – the ECB is not expected to change its Main Refinancing Rate, but many analysts believe they should cut borrowing costs. However, the ECB will likely remain within the camp of choosing to ‘wait and see’. The ECB Press Conference with Christine Legarde has widely become regarded as an opportunity for political speech as much as an economic dialogue. Recent data from the European Union suggests the worst of the recessionary cycle is gone, but German Trade Balance numbers released on Monday were negative, highlighting hurdles remain. Inflation is a worry, and a cut to the interest rate might be able to help spur on economic activity while counting on lagging data to prove proactive policy should be implemented. But this likely is not going to happen and the EUR/USD will remain problematic.

Thursday, 11th of April, U.S Producer Price Index – these slew of reports should be watched carefully. If the data is stronger than expected it is likely a part of the residue caused by higher energy costs that have affected logistics and created more expensive raw materials which are needed to produce goods. It was the higher PPI reports last month that caused dramatic tidal shifts in Forex, speculators should brace for the potential of additional mayhem.

Friday, 12th of April, U.K Gross Domestic Product – last month’s GDP numbers from Great Britain came in slightly higher than expected with a 0.2% gain, this report is anticipating growth of only 0.1%. Traders should take a deeper look at the statistics upon publication and check for revisions to past months. The U.K economy has been struggling, the ‘growth’ results will affect the GBP/USD before going into the weekend.

postN80.2

Risky Outlooks: Central Banks and Inflation Colliding

Risky Outlooks: Central Banks and Inflation Colliding

Most traders and investors begin their pursuit of financial assets with an optimistic perspective. However, the markets and ability to speculate also allows those who have other outlooks to equally participate. The past week once again delivered U.S inflation data which was not anticipated. While last Tuesday’s CPI results came in slightly stronger than expected, it was Thursday’s PPI which provided surprises for many.

Producer Price Index Warning from AMT for the 14th of March 2024

Yet, some market participants may not have been utterly shocked by the results. Perhaps it was lucky to ‘guess’ the PPI numbers could cause volatility last Thursday, but the ability to be alert and attentive to the possibility of risk should not be ignored. Risk management is important for all traders.

This coming week will continue to be intriguing for day traders as they try to sail through speculative waters which are going to deliver shifting behavioral sentiment tides. A parade of central banks are ready to step into the limelight and they will focus on the word: inflation. Technical traders who wager on support and resistance levels in the coming days should not be scorned, because sideways and volatile trading results are likely.

U.S equity indices began to struggle the middle of last week, Gold has traded lower and Treasury yields have ticked upwards in recent market action, this as sentiment has again had to acknowledge economic outlooks remains problematic. Trading decisions this week will depend not only on what the central banks say and ‘do’, but also focus on the duration that a speculative position intends to be working.

Monday, 18th of March, China Industrial Production – a gain of 7.0% has beaten the expectation per the data already published this morning. Retail Sales numbers came in slightly below estimates, but Fixed Asset Investment numbers were better than anticipated. However, China’s data remains troublesome and the economic path ahead for the nation must overcome deflation and trust issues from international investors. A lack of confidence from the Chinese public about the value of Real Estate and the over abundance of available property is causing major headwinds economically.

EUR/USD Six Month Chart as of 18th March 2024

Monday, 18th of March, E.U Final Core Consumer Price Index – the European Union will release crucial inflation data. An expected gain of 3.1% is the estimate. While this data release is not considered vital by many investors, the inflation statistics should be watched. The EUR/USD has produced mixed results the past four months as shifting behavioral sentiment due to battling perceptions regarding central bank policy outlooks converge.

USD/JPY Six Month Chart as of 18th March 2024

Tuesday, 19th of March, Bank of Japan – the BoJ will deliver their Monetary Policy Statement and Policy Rate. While no numerical change is expected from the BoJ, signs for a change in rhetoric will be looked for as central bank observers try to read the tea leaves. The Japanese economy is within an intriguing spot, there have been signs of improvement, but the Bank of Japan is likely to remain on a conservative path regarding negative interest rates for the moment. The USD/JPY remains within the higher realms of its price range as the currency pair grapples with global inflation outlooks.

AUD/USD Six Month Chart as of 18th March 2023

Tuesday, 19th of March, Reserve Bank of Australia – the RBA is expected to parrot the pronouncements of the other central banks as they point to stubborn inflation and ‘improving yet lackluster’ economic outlook. Trading in the AUD/USD has been choppy and the volatility is likely to continue within the known price range.

Tuesday, 19th of March, Canada CPI – the Consumer Price Index data is anticipated to show inflation remains remains sticky in the ‘Northern Tundra’. The CPI report from Canada should be monitored because of the strong relationship between the U.S and Canadian economies. The USD/CAD will react to any surprises.

Wednesday, 20th of March, U.K Consumer Price Index – yet another important inflation report. Great Britain has been a ‘poster child’ regarding stagflation. The ugly word is not something central banks, nor governments want to discuss, but the simple truth is that problematic inflation and limited growth equal stagflation. The statistics from the U.K should be examined. The economic health of Great Britain is often a solid reflection of global conditions.

Wednesday, 20th of March, U.S Federal Reserve – the Federal Funds Rate, FOMC Statement and Fed Press Conference will be focal points for investors. Except importantly, not much is likely to be said be Jerome Powell that isn’t known already. Inflation reports from the U.S have highlighted stubborn higher prices. U.S economic numbers regarding manufacturing and consumer confidence have started to turn lower, but the Fed is not going to change its policy this week. Talk about ‘becoming’ dovish will be heard, but the U.S central bank still wants to see more proof that inflation can erode before they start to cut interest rates in the mid-term.

Thursday, 21st of March, E.U Manufacturing and Services PMI, readings will come from France, Germany and the U.K via the Purchasing Managers Index results. Most of the data will likely continue to point to lackluster outlooks, only the Services PMI from the U.K is expected to offer a glimmer of hope regarding ‘expansion’. If the Flash numbers come in worse than expected this could cast a shadow over behavioral sentiment for European investors.

GBP/USD Six Month Chart as of 18th March 2024

Thursday, 21st of March, Bank of England – the BoE is likely to keep its Official Bank Rate within place and their pronouncements via the Monetary Policy Summary may sound like a replica of the U.S Federal Reserve. Inflation and growth will be spoken about and the BoE will try its best to paint an optimistic picture. The GBP/USD will react to the gyrations, but the range of the currency pair will have already seen tests in the preceding days. The past four months have produced a value as of the 18th of March, that is hovering slightly above late November and early December 2023 prices.

Friday, 22nd of March, U.K Retail Sales – a negative result of minus -0.3% is expected. The retail data will certainly be watched, but following the massive week of central bank statements and data which have already been published, this number may prove to be rather anti-climatic unless there is a massive surprise.

Friday, 22nd of March, E.U ECB and U.S Fed – Officials from both central banks will engage in a variety of speeches in Europe and the U.S, but again after the week’s worth of central bank rhetoric which has been heard, investors are unlikely to react much to these soundbites from members of the European Central Bank and Federal Reserve. Existing behavioral sentiment which has been produced in the dynamic days beforehand should remain the central theme as investors go into the weekend.

post193

Inflation Encore: Forex Traders Gathering Important Evidence

Inflation Encore: Forex Traders Gathering Important Evidence

The USD has been weaker against many major currencies the past week and inflation numbers coming from the U.S will test short-term outlooks. It should be remembered that in February before the CPI numbers were published, some who were leaning towards a weaker USD were traumatized after the stronger than anticipated results. However recent U.S economic data has shown a rather polite and distinct downturn.

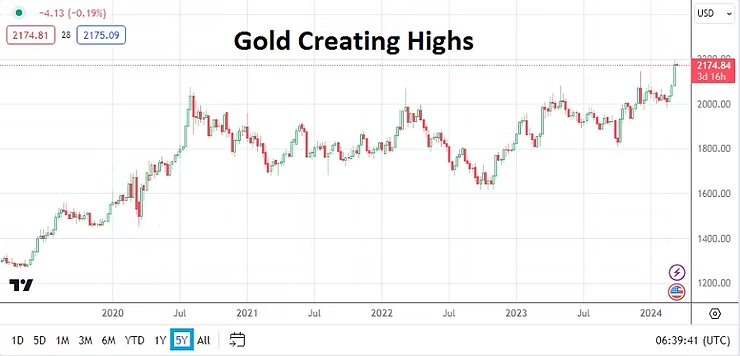
Day traders should brace for drama today and understand that financial institutions will lead the way, either catapulting trends or stopping them in their tracks. As Forex speculators get set, Gold continues to also flirt with highs, as of this writing the precious metal is near 2175.00 USD. Financial assets from equity indices to digital assets (yes, Bitcoin) are experiencing frothy returns as values seemingly attract more capital inflows. In other words, bullish behavioral sentiment is rather strong and traders are reminded to stay realistic with their goals.

Again, there is a difference between quick hitting speculators trying to take advantage of robust trends compared to long-term investing. Day traders still need to do their homework and not bet blindly.

Gold Five Year Chart as of 12th March 2024.

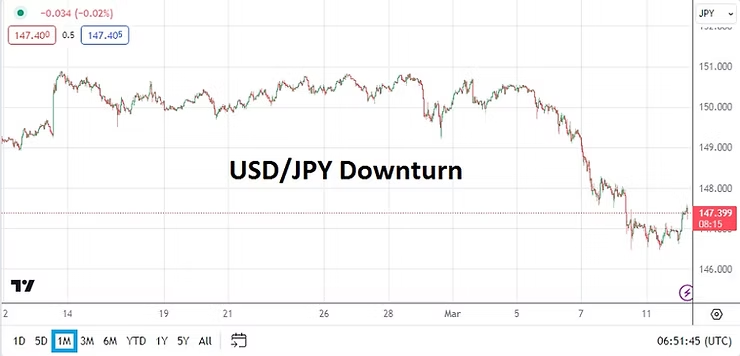
Monday, 11th of March, Japan GDP – Gross Domestic Product numbers yesterday came in with unexpected weaker results showing a gain of only 0.1% compared to an anticipated 0.3% gain. Yes, the USD/JPY held onto it downwards momentum, which it has established since last week. The trading results in the currency pair suggest financial institutions are placing their faith in mid-term outlooks.

USD/JPY One Month Chart as of 12th March 2024

Tuesday, 12th of March, U.S Consumer Price Index – the inflation reports will headline and drive market conditions near-term. Last month’s numbers provoked a strong reaction when prices remained stubborn. The monthly core report is expected to show a slight decline today, but the monthly broad number is actually anticipated to rise slightly. With mixed statistics forecast already, day traders need to be prepared for a lot of noise – which may prove rather misguided. The problem for the markets today will come from the interpretation of the numbers, if the CPI figures can simply come close to their expectations this might keep conditions from getting wild, but choppy trading should certainly be counted upon leading up to and following the publication. This month’s encore of the CPI inflation numbers will hopefully be less dramatic than February’s performance.

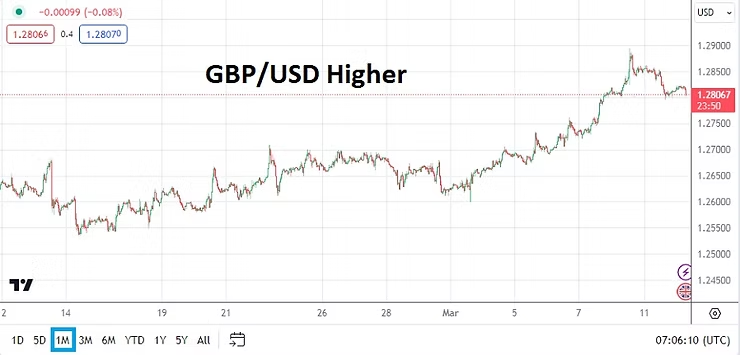
GBP/USD One Month Chart as of 12th March 2024

Wednesday, 13th of March, U.K Gross Domestic Product – a gain of 0.2% is expected via the growth number. Last month’s minus -0.1% outcome should serve as a reminder tough economic conditions remain evident. Yet, last month’s number actually beat a worse expectation. GBP/USD traders who have been patient with their bullish stances have been rewarded recently. A slight gain in the GDP number from the U.K could help bolster additional confidence regarding mid-term outlooks for the GBP/USD. The BoE, like the U.S Federal Reserve, will make their monetary policy pronouncements next week.

Thursday, 14th of March, U.S PPI and Retail Sales – the Producer Price Index and consumer spending numbers may produce the surprise for the week regarding market reactions. The Core PPI results are expected to be weaker, while Retail Spending is anticipated to grow. If the inflation results via the PPI data is weaker than anticipated this could allow for further weakness in the USD to develop.

Friday, 15th of March, China New Home Sales – real estate values in the nation remain a focal point for analysis. Another large decline in prices for homes would not be good news. The economy of China is suffering from deflation which hasn’t shown evidence of diminishing soon. China remains a vital part of the global economy. Industrial Production numbers will come from the nation on Monday.

postN100.1

Forex Volatility as Central Banks, GDP, U.S Equities Shadow

Forex Volatility as Central Banks, GDP, U.S Equities Shadow

Perhaps it is good that today will see a lack of important economic data which will affect the markets. It might give a chance for day traders to relax and to gauge the thinking of financial institutions and investors before Central Banks, and important growth and inflation numbers shift behavioral sentiment later this week. While Forex has remained a minefield, U.S equity indices have soared to record heights. More volatility will come.
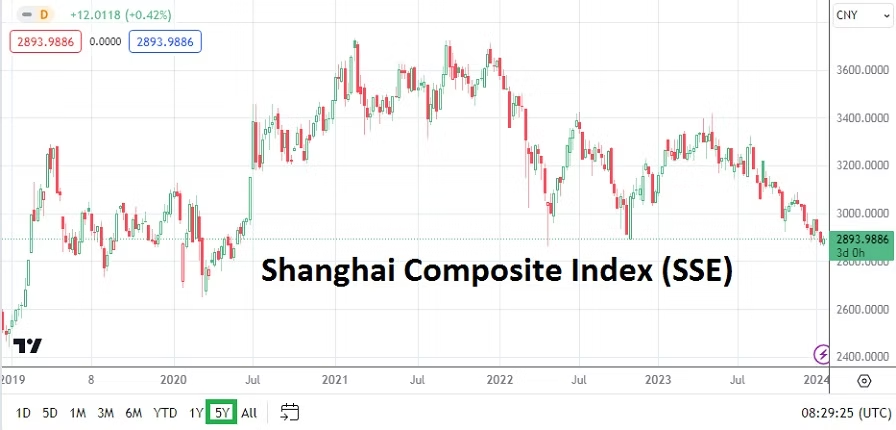
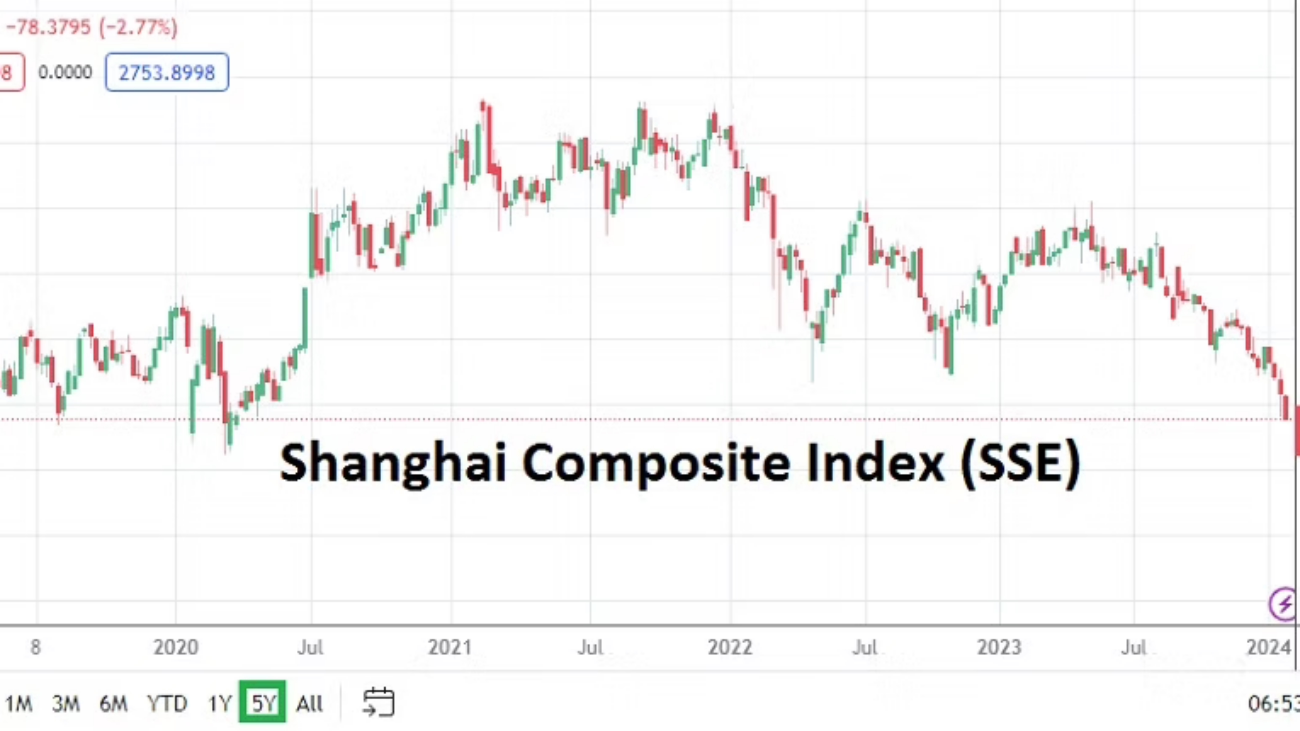
Shanghai Composite Index Five Year Chart as of 22nd January 2024

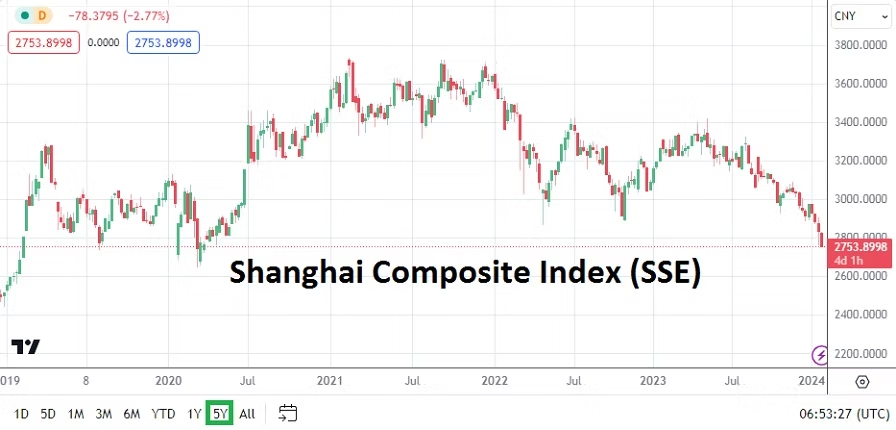
Risk assessment is always critical, it needs to be mentioned the Shanghai Composite Index is again facing severe selling pressure. This is a direct result of foreign investors losing faith in China’s economic policy and political maneuverings. The slump in Chinese equities is also hitting the Hang Seng Index in Hong Kong badly. Deflation is a legitimate fear in China. The dual consequences of a failing housing sector and crumbling equity values is harming Chinese citizens.

While the strong selloff in Chinese equities would have caused a massive amount of reaction in the global markets a few years ago, the ability to shift assets elsewhere by foreign investors who were active in China has likely reduced potential knock on effects in other global equity markets. It must also be pointed out that China continues to sit on a massive amount of USD holdings. China is a large investor in Africa and their attempt to steer influence there remains abundantly clear.
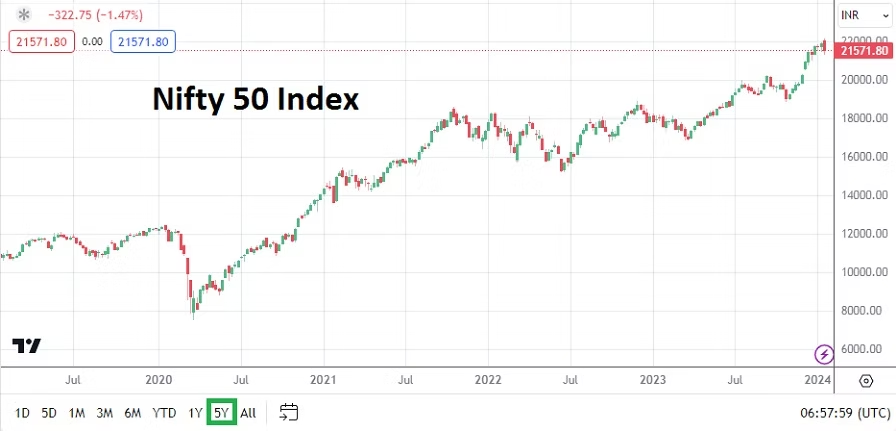
Nifty 50 Index Five Year Chart as of 22nd January 2024

India has directly benefited from the outflow of investments from China. A look at the Nifty 50 Index shows the upwards momentum India’s equity market has enjoyed as it has started to attract more direct foreign investment. The ability of the India stock market to go up while China struggles is a barometer worth studying. Outflow vs. inflow.

Monday, 22nd of January, U.S Conference Board’s Leading Index – the reading is not at the forefront of consideration for investors, they will be watching the results of U.S Treasury yields and stock indices more closely than this report.

Tuesday, 23rd of January, Bank of Japan Monetary Policy Statement and Outlook Report – no major change is expected from the BoJ quite yet. The USD/JPY has been volatile and provided a solid trend upwards since the start of January. Day traders looking for a reversal lower to develop should be extremely cautious. Data from Japan has been mixed and the BoJ is likely to remain conservative. The weaker JPY helps exports from Japan it must be remembered, but it also may factor into inflation creeping into the Japanese economy.

NZD/USD One Month Chart as of 22nd January 2024

Tuesday, 23rd of January, New Zealand Consumer Price Index – the inflation report is expecting a result of 0.5%, which would be below the previous result of 1.8%. The NZD/USD has taken a bearish dive since late December. Like all major currencies the New Zealand Dollar remains USD centric. Volatility in the NZD/USD may occur via the inflation numbers from New Zealand, but like the USD/JPY it may find its biggest impetus coming from afar – U.S data and the Federal Reserve outlook.

Wednesday, 24th of January, E.U and U.K Flash Manufacturing and Services PMI reports – Germany and France are anticipating slightly better Manufacturing Purchasing Managers’ Index numbers. Services numbers are expected to be slightly weaker from Germany. Solid results from these combined publications could help the EUR/USD create a bit of bullish momentum.

The U.K numbers via their Manufacturing PMI is expected to be slightly better than the previous outcome, but the Services number a bit worse. Economic data from Britain remains mixed to lackluster. Higher inflation numbers last week did the Bank of England no favors. The GBP/USD will be affected briefly by the results, but trading in the Forex pair is likely to remain geared towards thoughts about U.S data coming this Thursday and Friday.

Wednesday, 24th of January, Bank of Canada Rate Statement and Monetary Policy Report – the key lending rate from the BoC is expected to remain unchanged. However, Canadian economic numbers have been problematic, and while the BoC may want to wait for the U.S Federal Reserve to move first regarding interest rates, critics of the BoC are becoming louder. The USD/CAD will react to the Bank of Canada’s rhetoric, but unless there is a major surprise the currency pair will remain heavily USD centric.

Thursday, 25th of January, European Central Bank Main Refinancing Rate and Monetary Policy Statement – the ECB is expected to provide no major changes. The 4.50% interest rate is anticipated to stay in place. The ECB will likely ‘sound’ a calm tone and say while improvements are being seen in the E.U, that areas of difficulty remain but are understood and being managed.

Thursday, 25th of January, U.S Advance Gross Domestic Product – the key growth number from the U.S is anticipated to show a gain of 2.0%. This number will get a reaction in Forex, equities and bonds. The Federal Reserve’s FOMC meeting is next week and this GDP result will factor into their monetary policy rhetoric. Because it is an election year in the U.S, this number will also get an additional ‘sounding board’. Day traders should be careful before and after the noise caused by this growth report.

Friday, 26th of January, U.S Core Personal Consumption Expenditures – the vital inflation number carries an estimated gain of 0.2% before its release. As much as the Fed watches the GDP number, the inflation result via the Core PCE is a huge component of the U.S central bank’s thinking. The USD will react to this report and Forex traders should brace for a reaction from financial institutions. If the number is weaker than expected the USD could find selling momentum, if the number is stronger more USD strength could be seen. Folks looking at the GDP and Core PCE reports should also look for potential revisions to previous months results, which could cause another wave of volatility in the markets if they are significant.

postN98.1

Choppy Forex Conditions and the Trading Week Ahead

Choppy Forex Conditions and the Trading Week Ahead

Forex traders may be feeling a bit perplexed if they have blindly been looking for a weaker USD the past two weeks. While outlook for a bearish USD over the mid-term remains a theme from many analysts, day traders need to accept that intra-day results often create price fluctuations which make wagering on short and near-term perspectives dangerous. Trading conditions have been turbulent the past week and early this morning.

While analysis of monetary policies and economic data are vital, it is also important to remember there is a significant difference between the desires and needs of businesses functioning in global commerce, and the trading perspectives of speculators who are hoping to ride on the back of ‘insights’ provided by experts. It should also be considered that coming out of the holiday season many global corporations are now repositioning for 2024, and the financial institutions that work for these companies are also trying to get these outlooks aligned.

The USD has become stronger over the past day against many major currencies, but looking for a 100% reason to explain why this happened is likely misguided. Most U.S financial institutions were closed yesterday for the MLK holiday observance. While inflation data from the U.S Producer Price Index was weaker than anticipated last Friday and caused a brief spurt of USD bearishness, the greenback is lingering within the stronger realms of its near-term values against many currencies.

The idea that recent USD bullishness may simply be a sign that financial institutions believed the greenback had been oversold over the past couple of months may be correct, but this also opens the door for the potential of a reversal to develop and more USD selling as sentiment and economic data try to dance in a unified manner.

The week ahead may still prove to be choppy, but there are interesting bits of evidence that risk appetite lingers within the stomachs of many large investors. The slight rise in U.S Treasury yields recently may be worrying to some, but it should be acknowledged that the climb higher has been achieved while yields remain near mid-term lows. The same can be said for U.S equity indices which provided choppy conditions last week but certainly remain in highly valued realms.

Patience is a needed tool when trading, speculators looking for instantaneous results often lose money because they are being too aggressive. Risk taking tactics always have to be given importance.

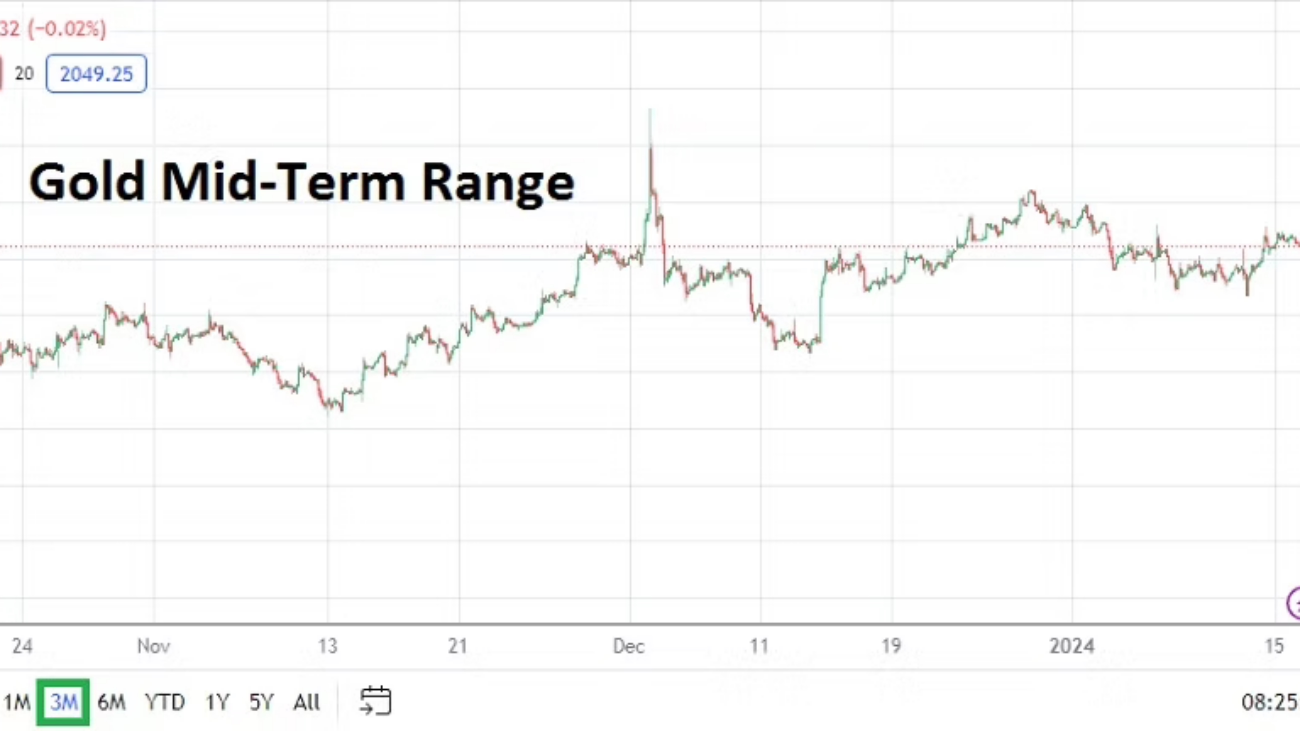
Gold Three Month Chart as of 16th January 2024

Gold remains rather comfortable above the 2000.00 USD level. As of this writing the spot price for the precious metal is near 2050.00 USD. This is fascinating because it underscores the notion that long-term gold buyers appear to believe the USD will remain within weaker territory. But again, short-term and mid-term outlooks for speculative wagers are two very different things.

Tuesday, 16th of January, Canada Consumer Price Index – the inflation numbers from the ‘North’ are expected to be lower than last month’s results.

Shanghai Composite Index Five Year Chart as of 16th January 2024

Wednesday, 17th of January, China Industrial Production and GDP – recent economic reports regarding the deflationary troubles the nation is facing have been loud. The industrial and growth numbers should be monitored. The Shanghai Composite Index (SSE) is trading near values last seen in May of 2020, this is not a good signal.

Wednesday, 17th of January, U.S Retail Sales – the consumer data will have an affect on sentiment in the broad markets. The results are anticipated to match the Core Retail Sales gains from last month, and the broad number is expected to be slightly higher. Traders should be alert in case a surprise outcome occurs. If the statistics are close to the estimates, this could create some calm in Forex and perhaps set the table for USD weakness to be seen for a moment.
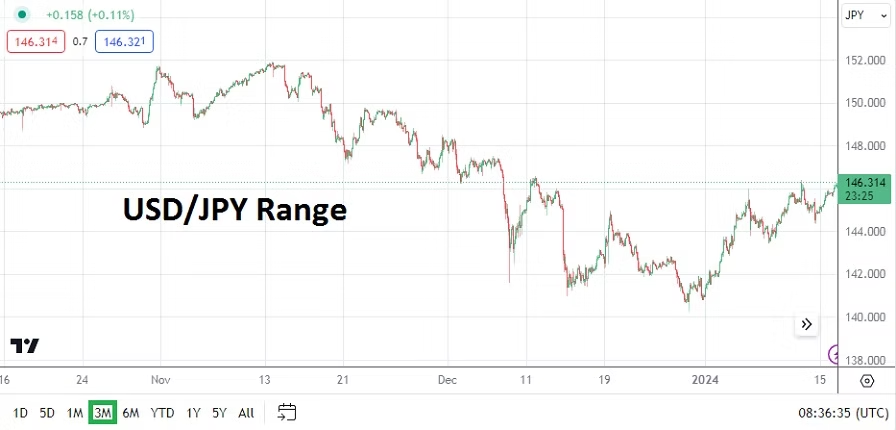
USD/JPY Three Month Chart as of 16th January 2024

Thursday, 18th of January, Japan Revised Industrial Production – while the report is not viewed as a major piece of financial impetus in the speculative world, the USD/JPY has been rather dangerous for short-term traders caught on the wrong side of recent bullishness. If the number comes in at minus -0.9% as expected, it will then likely take USD centric bearish sentiment to cause a reversal lower. The past two weeks in the USD/JPY have been difficult for traders looking for downside momentum. A stronger than expected industrial number from Japan would likely help USD/JPY bearish outlooks.

Friday, 19th of January, U.K Retail Sales – the British consumer spending numbers are expected to come in weaker. The GBP/USD is currently trading near early January values as choppy short-term conditions persists.

postN94.1

Thin Holiday Markets Await FX Speculators

Thin Holiday Markets Await FX Speculators

Traders who want to pursue speculative positions this week need to understand that market conditions will be extremely thin. While the USD has certainly taken on a ‘softer’ dimension and financial institutions are demonstrating solid risk appetite, this week’s trading could produce lackluster choppy conditions.

Economic data will be light this week due to the ongoing Christmas celebrations, and the New Year’s holiday which will come next Monday. Forex markets can produce trading opportunities in the near-term for folks who want to wager on changes of direction, but some of the trajectories may be dubious and reversals could loom. Entry orders are urged for participants because spreads between bids and asks will likely be wide.

Gold Three Month Chart as of 26th December 2023

Gold remains within its higher price boundaries as the USD produces weakness, but betting on the precious metal this week could also be dangerous. Gold has certainly been trending upwards, but short-term speculative positions by large players could make the commodity agitated the next handful of days if they try to take advantage of light volumes. Day traders without significant bankrolls should be careful.

While economic data will be released, it is doubtful how much impact the reports will have on the broad markets. Active traders should monitor the coming statistics, but they should stay ‘more’ alert for possible outside influences which could shake confidence and shadow the rather optimistic behavioral sentiment which is currently being demonstrated.
News via international shipping should be given attention as the Houthis and Iran rattle their swords. While experienced traders will not be flustered by noise, the potential for escalating violence should be given attention.

USD/JPY Three Month Chart as of 26th December 2023

Tuesday, 26th of December, Japan Core CPI via the BoJ – inflation data from Japan has been published today and the Consumer Price Index came in below expectations. The USD/JPY remains on a downwards trajectory and should be given consideration.

Wednesday, 27th of December, U.S Richmond Manufacturing Index – this report being ‘highlighted’ shows the minimal amount of data being published this week. A decline versus the previous month’s negative outcome is expected. The likelihood that significant trading will be ignited via the results of this publication is almost nil.

Thursday, 28th of December, U.S Pending Home Sales – the data is expected to show a gain of 1.1%. However, it is next month’s report which will get more attention, this as investors look to see if the Fed’s soft monetary policy stance which was heard in mid-December, helps boost the housing market in the coming weeks. This immediate report however is likely to be met with a rather quiet reaction.

Friday, 29th of December, U.K Nationwide Home Price Index – this economic report like yesterday’s U.S housing numbers is destined to have little influence on short-term trading results. The GBP/USD will not be affected by this report in any great manner.