
The Power of Intelligence
The most valuable piece of real estate in the world is a fab complex on the western edge of the Pacific, a short flight from the coast of a huge country that claims the ground it sits on. Taiwan Semiconductor Manufacturing Company, aka TSMC, prints the chips that every frontier AI model on earth depends on – and nearly all of them are currently made on that shore in Taiwan. This is simply a given; geography, unlike software, doesn’t scale, doesn’t copy, and doesn’t move.
For a decade the industry treated intelligence as something borderless, a global utility that would flow to wherever demand called for it. That framing is way past obsolete in a world that is split, lost along with the old dream of an uncensored Internet and free information exchange. Now, the crack is widening along a new axis. Forty years ago, the division ran through Berlin, and it was drawn by ideology. Today it runs through a supply chain, and it is drawn by who can make, buy, and run the machines that think. The AI chips are only the part of the split you can see and touch.
The Great Compression Part 4: Sovereignty Franchise
The Independence Chokepoint
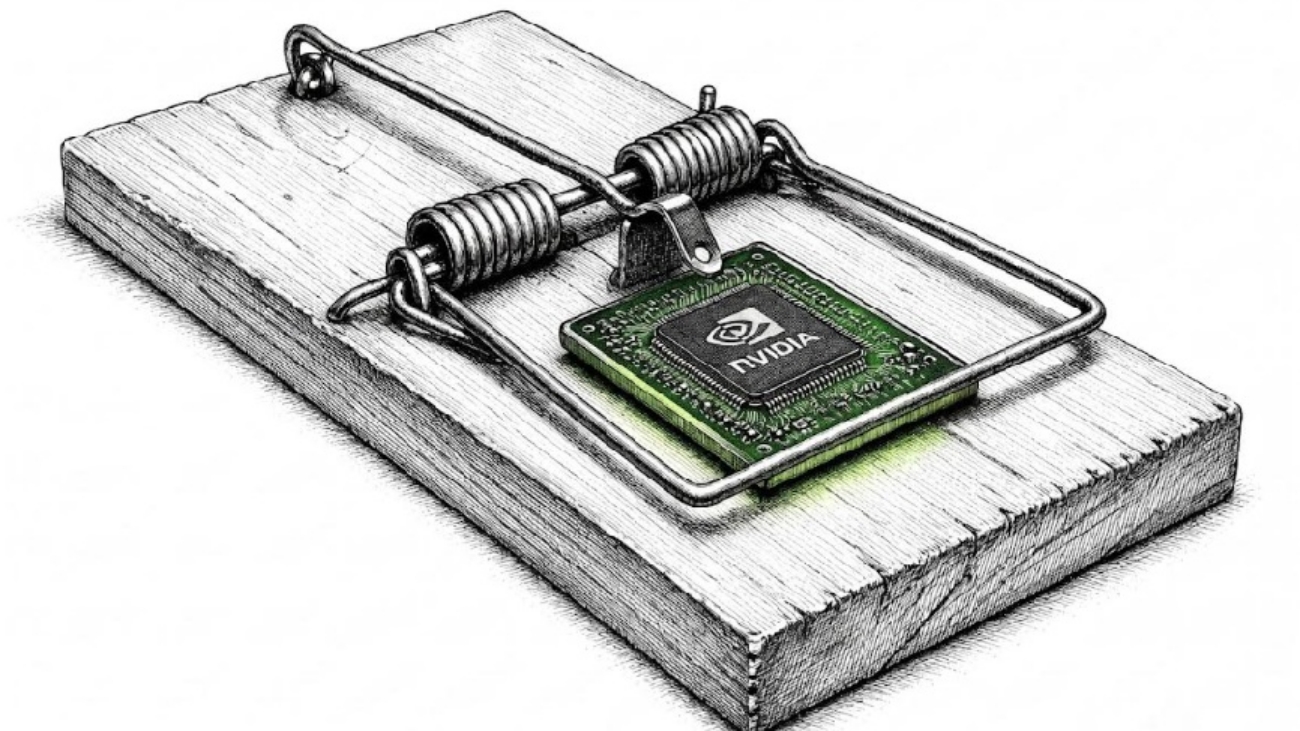
Compute has already left the free market and entered the permitted layer of the economy. Advanced NVIDIA processors are no longer something a buyer simply purchases; they are something a government allows a buyer to receive. Export licenses now stand between the most capable silicon and any customer headquartered on the wrong side of the line. Washington has spent three years building this wall chip by chip – and the reshoring push, the fabs rising in Arizona, the equipment and materials supply chains being pulled back onto home turf, is the same impulse cast in concrete: move the chokepoint onto ground you control.
The scale of the gap explains the urgency. The U.S. holds a lead in AI compute capacity measured not in percentages but in multiples. China’s domestic production of the highest-end accelerators runs at a small fraction of American-equivalent scale. Its most advanced labs still lean on Western silicon to train their best models, whether the chips arrive through smuggling networks or through the gray route of renting restricted hardware inside third-country data centers.
Even when it’s leaking, the chokehold does its work. The controls slow every Chinese frontier effort, force it onto inferior domestic silicon, and keep it a step behind the labs it is chasing. But compute is only the first roadblock to independence: the next ones – on the intelligence itself – are only going up now.
The Gate to Intelligence
A wall around compute would be contained if compute were the end of the story, but it isn’t. The same logic that gates the chip is now reaching for what runs on it.
In June 2026, the U.S. Commerce Department required an export license for any foreign national to access a frontier AI model made by Anthropic – including the developer’s own non-citizen staff. Unable to verify the nationality of its users, the company withdrew the model entirely, and for the first time in this cycle a publicly available AI capability moved backward by government order. The controls were contested, the legal basis was unsettled, and access was restored within weeks. But the precedent was set: the authority to license the export of chips had been stretched to license access to an intelligence provider, and the mechanism worked before anyone had settled whether it lawfully could.
Beijing read the same lesson and moved to mirror it, drafting a regime to fence its own leading model weights behind national-security law rather than let them diffuse into the world. Two capitals, the same month, reaching the same conclusion from opposite sides: an AI model is not a product to be sold freely but a strategic asset released on terms. Intelligence has crossed into the permitted layer, and it crossed at both ends of the divide at once.
The Chained Brains
All of that is behind us; the interesting part is ahead.
Every ally now starting up its own sovereign AI is building it on a stack it doesn’t own – because the models, the chips, and the cloud beneath them are all American. What the ally holds is the building, the flag over the door, and the electricity bill. But the intelligence itself answers to another country’s export regime. This is sovereignty in name and franchise in fact.
The precedent for this arrangement already flies. Allied air forces buy the F-35 – the most expensive piece of weaponry in history – but they don’t thereby own it. The U.S. controls the source code and the mission-data files, and the aircraft’s full capability remains under American authority no matter how large the check. The buyer flies a plane whose brain is licensed, not sold, because withholding the core is the entire instrument of leverage. You can’t buy your way to control over a capability whose value to the seller depends on never fully handing it over.
While the F-35’s licensed brain governs a single platform, a national AI stack governs the layer through which a modern state thinks: its analysis, its logistics, its intelligence fusion, its administration. The fighter is a product on a leash, while the intelligence layer is the nervous system on a leash.
The Thinking Franchise
And the company installing that nervous system is already doing it. Palantir’s value was never the model but the trust above it and the data structure beneath it – the ontology layer that ingests a government’s data and turns it into decisions. In mid-2026 it began offering sovereign customers what they most wanted to have: full ownership of their model weights, retrainable, air-gapped, sealed behind their own walls. Still, the weights are the airframe that a buyer can own – but they will still have to run on NVIDIA silicon, inside an operating layer a U.S. company builds and controls, under the same export regime that pulled a frontier model offline in June.
Canada shows how thin the sovereignty can wear. Ottawa named itself the anchor customer of its own national AI strategy in mid-2026 while already running tens of millions of dollars in undisclosed Palantir contracts inside its defense and policing systems. The strategy announced sovereignty, but the procurement had already outsourced it. And by late summer, the two were trading tariffs and hard words, the closest alliance on the continent gone frosty, with the most sensitive systems of one side still running on the other’s stack. Nobody had to threaten anything. The dependency simply sat there, the way it was always going to.
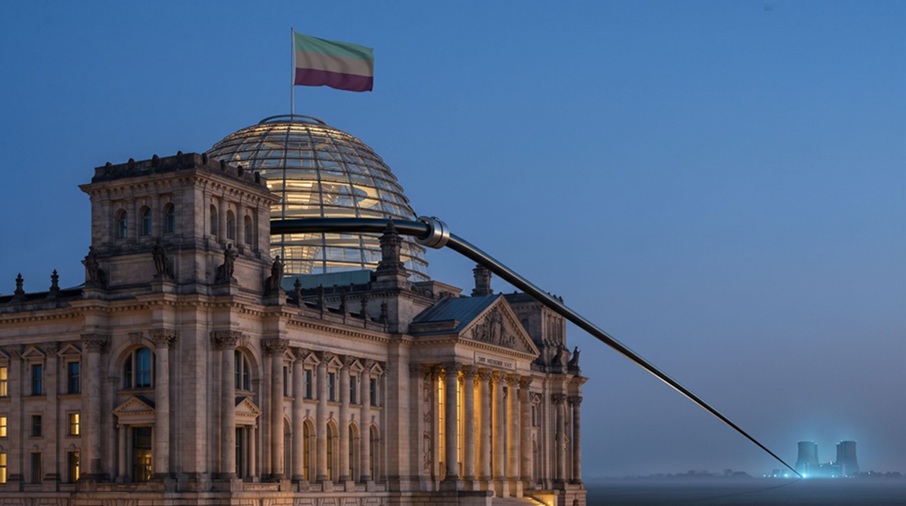
Right in front of our eyes, the forward base of the last century gives way to the forward stack of this one. Instead of a U.S. army base near a European capital, a data-orchestration system running on NVIDIA chips, wired into the host government’s own operations, doing quietly what the garrison once did loudly. Land, power, and data can belong to Berlin or Paris, on paper – but the intelligence stack that holds the dependency will be American. It’s a cheaper umbrella, a deeper one, and a far harder one to ask to leave.
The End of Sovereignty
The immovable object was supposed to be the safe end of this story. Land, power, fabs, the heavy and hard-to-replicate assets that no software cycle can compress, the bedrock beneath the cloud. All of that still holds. But immovable is not the same as owned – and anyway, even the owner isn’t sovereign, because sovereignty itself is what’s being compressed at the top of the stack.
Every chokepoint described above rests on a fact that holds only for now: advanced compute is scarce, and what it produces can be walled. Practical quantum advantage dissolves both, and it is a contest between the same two powers that have run through every layer of this story. Perhaps one arrives first. Perhaps, if less likely, two arrive together. It changes little for everyone else. The machine owner reads what others hide and shields what it keeps. The only defense is a new cryptography built to withstand it, and it takes the same frontier compute and talent that only those two powers command. Even the lock is provisioned by the vendor.
It doesn’t matter who owns the oil or holds the warheads if the secrets around them can be opened at will and the means to reseal them belongs to someone else. The world is already two powers and their satellites, although most of them still speak as though sovereignty were something they possessed. The quantum edge is the point where the pretense ends.