postN87

AMT Top Ten Miscellaneous Morsels for 5th of January 2024

AMT Top Ten Miscellaneous Morsels for 5th of January 2024

10. Book: Truth to Power – My Three Years Inside Eskom by Andre de Ruyter, an insider’s account about South Africa’s public energy company amidst corruption, mismanagement and scandal.

9. NBA: Last night’s Milwaukee and San Antonio game was the first ‘match’ of Giannis Antetokounmpo and Victor Wembanyama. Basketball is global and spectacular.

8. Noise: Clickbait media headlines about nervous results in financial markets this week have been exaggerated.

7. Horn of Africa: Ethiopia and Somalia are arguing about a port passage through ‘Somaliland’, astute eyes should be kept on the region and Egypt.

6. Diplomacy: U.S foreign policy has delivered poor statesmanship with India recently, allowing Russia to reinitiate its longstanding relationship with the nation.

5. Taiwan: Presidential election is on the 13th of January. President Tsai Ing-wen is not eligible to run again because she has now served two terms.

4. USD/JPY has ebbed higher and next week’s results promise to be rather insightful regarding the outlooks of financial institutions. Reversals coming?

3. China: Economic concerns in the Asian giant continue to mount as deflation threatens to become intractable and investors fret.

2. Data: U.S jobs numbers coming today, the results are anticipated to be slightly weaker. A reaction in the broad markets is certain, but it is full market volume next week which will set the tone.

1. Outlook: Anxious short-term trading results from the past two weeks are likely going to be confronted by optimism and risk appetite next week. Who will win?

postN19

Preventing WWIII: Part 2 – Reviving Western Deterrence

Preventing WWIII: Part 2 - Reviving Western Deterrence

Opinion: The following article is commentary and its views are solely those of the author.

Aggressive Western Action Can over-extend China and Revive Needed Deterrence.

Some cliches are just correct, in spite of their being cliches – “if you want peace, prepare for war” is one. But really it should be “if you want to avoid war, deter war”.

Therefore, it is not clear to me why there is opposition by some in the Republican party to fighting Russian aggression in Ukraine. For some, I guess it is a knee jerk reaction against Biden administration policy while for others it seems to be a general loathing of American involvement in the world. 

Each is understandable on its own but does not take into effect the appeasement of Russia will have on Western deterrence around the world – including in the Western hemisphere and the Indo-Pacific. While most Americans understand that Russian control of Ukraine threatens the main Western European countries, the key to Russian imperialism really is in the south. Historically, Russia has always tried to find a warm water port to call its own. For nearly four centuries Czarist Russia fought Ottoman Turkey so that Russia could expand its territory southward and have a warm water presence in the Mediterranean. Currently, a Ukrainian presence in the Black Sea denies Russia even the opportunity to pressure modern Turkey to abide its wishes.

A Russian victory in Ukraine would mean dominance of the Black Sea by the Russian Navy and directly challenge Turkey to appease Russian power by giving them free passage through the Dardanelles to the Mediterranean. That in itself would not be worth much to the Russians without a port in the Mediterranean, which they currently have. That they have one goes back to the disastrous decision by the Obama administration to invite Russia back into the Mideast in order to take care of Syrian chemical weapons. This came, we all remember, when the Syrians laughed at Obama and crossed his “red line” about using chemical weapons against its own people. We might also remember when then Secretary of State John Kerry (the one who was never right on a single foreign policy issue ever) who, first demanded that Syria turn over all chemical weapons in a week, then reassured them that even if we attack it will be “unbelievably small”.

In 1973-4, Henry Kissinger brilliantly took advantage of the Israeli-Arab War’s outcome with Israel’s surrounding the Egyptian 3rd Army in the south and controlling the road to Damascus in the north, by brokering a cease fire on both fronts. This led directly to the expulsion of Russia/Soviet Union from the Middle East. While Russia continued friendly ties with the murderous Assad family – first Hafez and then his son, Bashar, they did not have a military, air or naval presence there. Due to this longstanding relationship with Assad’s Syria, Obama and Kerry thought it a brilliant idea to have them come in and do the dirty work that they didn’t want to do – prevent Assad from gassing his own people. 

As Russia came in and established air and sea bases in Syria and introduced the infamous Wagner group to carry out its brutal ground operations, Russia slowly started to strengthen its position in the region. While slyly allowing Israel to attack Iranian arms shipments meant for Hezbollah while pretending to be its ally, Russia formed a close  relationship with Iran. Wagner, which fought hand in hand with Hezbollah in order to prop up the Assad regime (and attack American forces fighting ISIS) is now rumored to be training Hezbollah in the use of Russian anti-aircraft systems. 

In addition, reports last week that an Iranian Ilyushin 76 cargo jet has now landed in one of the Russian air-bases they established after Obama’s kind invitation to return to the Mideast. This plane, filled with Iranian arms destined for Hezbollah has been unable to land in regular Syrian airports or bases because Israel continuously puts them out of service. Knowing that Israel would never attack a Russian base – this is a safe haven that Russia gladly supplies. 

When free countries unite in warfare there is usually one joint goal  – that they are all united to defend freedom – that is why they fight together.  While autocratic and totalitarian regimes fight together it is usually a combination of a negative goal – disturbing or destroying the current world or regional order – as well as the goal for each power in itself. Currently, the joint goal in the Mideast (of Russia, China, Iran and North Korea) is to hurt the main ally of the US in the region – Israel, in order to weaken and embarrass the US. For Iranians, they also want Israel destroyed. For Russia, they want Israel weakened so they can replace the US as the power broker in the Mideast. For China, it is to dismantle America’s control of the flow of oil and, eventually, the replacement of the USD in the global economy with the Yuan.

Ukraine is important in this calculus because, as we said above it gives Russia complete control of the Black Sea and will pressure Turkey – whose NATO membership is uses only to its own advantage – to break permanently with the West. While the Chinese theory is that the two fronts the US is supplying arms to, Ukraine and the Mideast, are tying it down and expending its resources it would otherwise use in the Pacific, in truth, an aggressive strategy on both fronts would be to over-extend Russian and Chinese resources in order to keep China from moving on Tiawan. A credible threat of destruction or even marginalization of the Axis allies in the Mideast – including (besides the soon to be gone Hamas) Hezbollah, Shiite-Iranian proxies in Iraq and Syria, as well as Iran itself combined with a major offensive in Ukraine will tie down Axis resources and possibly prevent a Chinese blockade or attack on Taiwan.   If its two main allies need full supply and full readiness to be able to respond to credible and massive attacks by Ukraine, Israel and the US, China itself might have to expend resources to prop up its own allies. 

Add to that a major show of naval force in the Indo-Pacific by Japan, India, Australia and South Korea combined with US forces will give China the choice of destroying their own wavering economy by attacking or blockading Taiwan or in maintaining peaceful Pacific trade routes while trying to prevent the collapse of its Axis allies. 

An immediate and radical change in policy can restore Western deterrence quickly.   Re-arming Ukraine and leaving Israel to do its job without pressure to stop in Gaza and to respond forcefully in Lebanon will send a strong message. Biden brought two carrier groups to the Mideast and told Hezbollah, “don’t”. But they did.  

In spite  of that  US Secretary of Defense Austin told Israel that its response to Hezbollah aggression in the north is “provoking” them.  

And the US hesitates even against Iranian proxies. Just now, the NY Times has reported that Biden-Blinken have turned down a Pentagon plan to be more aggressive in response to Iranian attacks against US forces in Syria and Iraq for fear of “provoking Iran” (this seems to tell us that the Austin complaint from Austin to Israel is really from Blinken).  

Iran never seems to fear provoking the US.   

Israel fooled itself by thinking Hamas was deterred by its destruction of an arms factory or two (as the US is doing now in Iraq/Syria) when proper deterrence would have meant them knowing we can and will go into Gaza and destroy their underground city as Israel is doing now. Instead, media fear mongers, backed by Israeli ex-Generals on the payroll of the US progressive left (via cushy think-thank jobs) combined with policy directives by successive governments have told us and Hamas time and time again that Israel cannot destroy Hamas as the cost is too high. I don’t want to speak too early, but that seems to have been as wrong as their assurance that Hamas is deterred since they want to drink white wine in the evening overlooking the Mediterranean while watching their children play innocent video games.

It is time to stop calling for cease fires and repeating UN hypocrisy and to start being aggressive and provocative in the defense of freedom. 

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

You can follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/ 

postN19

Preventing WWIII: This is a 1936 Moment for the Middle East

Preventing WWIII: This is a 1936 Moment for the Middle East

Opinion: The following article is commentary and its views are solely those of the author.

The wonderful historian and public intellectual Niall Ferguson has aptly called the current US-China relationship a “Cold War II” and the current debate in the punditry is if the Israel-Hamas war lead to a WWIII. But what if we are already in WWIII? While Russia and the rest of the world did not expect the war in Ukraine to still be fought nearly three years later, the Russia-Ukraine war is now clearly a part of the fight of the West vs the new Axis – Russia/Iran/China/North Korea. But it was the Hamas attack of Israel on October 7 and the response of the Axis and its allies that have more clearly established the battle lines.

We have Russian and Iranian weaponry vs. American and Israeli weaponry. The Russians and the Iranians are using what we so quaintly call “proxies” for a plausible (un)deniability, sheltering them from retaliation. Iran has its various Shiite militias, with Hezbollah being the strongest and most lethal. Hamas and Palestinian Islamic Jihad (PIF) are the Sunni useful idiots helping the Shiite empire to destroy their Sunni cousins by dying for the cause. The Shiite militias formed and fighting in Iraq and Syria along with the Houthis in Yemen round out Iran’s ability to pretend it is not fighting while creating a genocide of Sunnis in Syria and Iraq and Jews in Israel. On the Russian side we have of course the infamous Wagner Group which in its racist undertaking is taking over and subjugating sub-Saharan Africa in its run to control minerals, gold and diamonds. They are now helping Hezbollah with weaponry and training by providing anti-aircraft weapons. The two groups fought hand in hand saving Bashir Assad, the leader and butcher of Syria, to stay in power so they already have close ties. Wagner is Russia and Russia is Wagner. Hezbollah is Iran and Iran is Hezbollah. The quicker we understand this the better off we will be.

We don’t have any details on Chinese or North Korean weaponry being used by Hamas or Hezbollah, but that might just be a timing issue. China has already decided not to report Hamas atrocities to its people in its official Chinese language news service and are eliminating Israel from its maps. It only reports Israeli’s response and has taken a clear stance supporting its ally, Iran. Will they learn from their Axis allies and also form proxies in Asia to destabilize countries like the Philippines or Vietnam while being immune to retaliation? They don’t need to conquer or even blockade Taiwan if they can destabilize their neighbors while still selling the West all that it wants to buy and inundate our youth via Tik-Tok propaganda.

Japan has realized what this war is about, and is supporting Israel like it never has. Being totally dependent upon the Mideast for its oil, Japan has never been a close friend of Israel. But they have now condemned the Hamas attack while refusing the criticize Israel’s massive response. The Japanese understand well that an Israeli defeat can lead to Chinese dominance in the Indo-Pacific.

Back to the Mideast – it seems we always go back to the Mideast.

Iranian backed Hamas and PIJ launched a brutal attack on Israel.

The Iranian backed Houthis in Yemen declared war on Israel and launched cruise missiles and drones in their opening attack.

Iranian backed and financed Shiite militias are moving to Syria and Lebanon hoping to open two new fronts against Israel.

Iranian backed and financed Hezbollah is attacking from the north in what, for some reason, we are not yet considering a war.

And Iran itself is feeling safe from attack from Israel or the US/West since “only” its proxies are fighting.

This is the remilitarization of the Rhineland of 1936 and a Western betrayal of Israel by hamstringing the IDF by allowing gasoline into Gaza or by a forced cease fire, will be the Munich, 1938.

Are we in WWIII yet? Not being an expert, I don’t know. But the main link tying the Axis together is Iran. They are the most experienced in exporting terror and supporting anti-Western regimes from the Mideast to Africa to America’s doorstep – Latin America. They support and are supported by the Castroite regimes in Cuba and Venezuela and have made deep inroads in Argentina, Brazil and now even Mexico. They are currently nearly as great a threat to the west as is China and probably a greater threat than Russia. A nuclear Iran would create three nuclear powers that could threaten the West as an Axis or independently. The Obama-Biden Iranian policy has been proven a total disaster and its seems that the Biden team is finally understanding this. But they can, in Margaret Thatcher’s famous warning to the first President Bush, “go wobbly” at any moment.

The only way to prevent a full fledged WWIII is Iranian regime change. This would bring the entire Persian Gulf (and its oil) into the Western sphere of influence as China does not yet have the naval power to challenge the US. Hezbollah would be instantly neutralized reducing the threat of war and denying the anti-Western powers another presence in the Eastern Mediterranean. Although the Syrian butcher, Bashir Assad would still have Russia to back him, it is not clear that Russian power alone could keep him in power. In Latin America, Iranian export of terror would stop instantly.

This does not mean that the US needs to invade Iran in order to defeat it. A majority of the Iranian people are sick of the Islamist regime and sick of paying the price for their being ruled by terrorists. The destruction of Iranian nuclear and missile facilities along with the destruction, by air and cruise missiles, of the main Revolutionary Guard bases will be enough. It is not an easy task -but one within the capabilities of the US Navy and Air Force. It is only the Revolutionary Guards that keep the terrorists in power in Iran – the regular Iranian armed forces can be left alone to decide if they want to help overthrow the regime or stay in their barracks. Once they see that the Guards are weakened it is a good bet they will take the side of the Iranian people and help topple the Islamist-terrorist regime.

Regime change in Iran in 2023 will change the global dynamic just as regime change in Nazi Germany in 1936 would have saved 70 million lives in WWII. A failure to act against the source of evil and to cut off the main link in the current Axis will just kick the can down the road – once again. We have appeased Iran enough and if the West and the US don’t act quickly it will have to act while simultaneously fighting off a Chinese attack in the Indo-Pacific – on its own or with its very own proxies – as well as terrorist attempts coming from Latin America and Russian nuclear blackmail in Europe.

And we haven’t even spoken of the West’s moral obligation to prevent a second holocaust, which will be the very first task of a nuclear Iranian regime.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.
You can follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

postN44.1

Dog Days of Summer and a Return of Calm as Storms Threaten

Dog Days of Summer and a Return of Calm as Storms Threaten

With essentially two full weeks of trading until the end of August and the unofficial end of summer in sight, perhaps this week may be a good time for retail traders to be observers if they do not have the stomach for potentially noisy speeches and markets.

However, speculators who can block out media hyperbole and microphone soundbites from folks standing on podiums may find conditions rather attractive. As always outlook depends on perspective, time frames and managing risk. Behavioral sentiment has been rather chaotic the past month and some traders may suspect we are approaching the end of the loud spectacles of nervous drama in the markets.

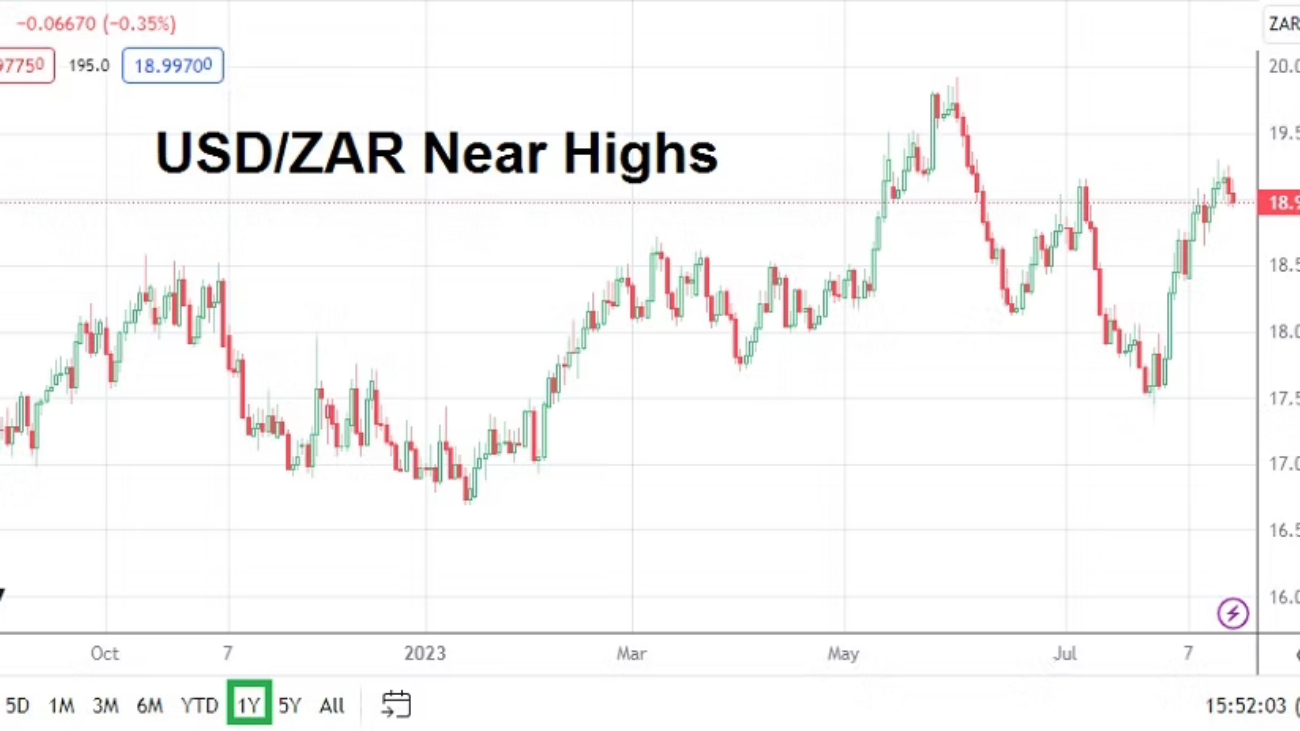
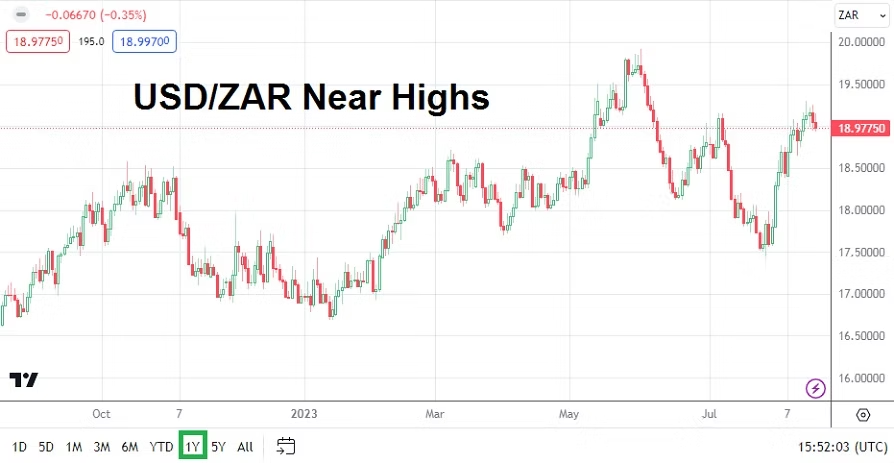
USD/ZAR One Year Chart as of 20th August 2023

The economic data this coming week should prove to be a rather mild schedule, but outside influences will certainly get publicity and get fanfare from talking heads who want 15 minutes of your attention. The BRICS Summit will get underway in Johannesburg, South Africa officially on the 22nd. Another big conference later this week will be the U.S Federal Reserve’s Jackson Hole Symposium. Both events will produce plenty of conversations about inflation, economic stability and a more cohesive global cooperation monetarily. This will also create many raised eyebrows among traders who are skeptical about these type of events.

While leaders of China, Russia, India, Brasil and South Africa get together in Johannesburg, it is likely we will hear talk about potential BRICS expansion and the pursuit of a new unified currency which doesn’t rely upon the USD. However, in the background there is likely to be plenty of distraction because of China’s faltering economic data and Russia’s Ruble which has been impacted severely in the past month. Plenty of large rugs will be needed to hide the dust which threatens to make this BRICS event rather memorable.

Add the ongoing saga of Niger and the absence of a political solution for the world’s fourth largest producer of uranium as a potential flash point standing on the side of the stage waiting to make an appearance regarding Africa news. Perhaps it is too cynical to wonder if coordinated military action within Niger will await the end of the BRICS Summit. This so China and Russia are not given an opportunity on the ‘world stage’ as a united voice to offer their opinions regarding an intervention.

The Jackson Hole get together of global central bankers from the Fed, BoE, ECB, BoJ and others will certainly grab headlines late this week, but the script is mostly known regarding the rhetoric to come from the Federal Reserve’s annual event. Forex may move based on comments from the central bank chiefs as they speak towards the end of this week, but it is unlikely anything surprising is going to be heard. U.S Treasuries will remain a topic because of the ability to lock in a solid return over the mid-term compared to betting on the outcomes of the stock market, but this scenario has been playing out the past month. Investors should prepare for a long line of speeches regarding economic outlooks from central bank officials all week. Day traders should also remember that the chatter starts to be ‘tuned out’ as the speeches grow longer.

Traders looking for other outside influences may want to look at the cryptocurrency market where major assets have shown signs of struggling. Bitcoin and Binance coin could remain in the headlines for all the wrong reasons, if their prices continue to challenge important support levels and become more vulnerable.

Monday, 21st August, China Prime Rates – economic data from the nation has caused concerns that real estate problems are spilling over into the domestic consumer market. The interest rates China lends money to consumers is expected to be lowered to try and spark spending. Recent economic reports from China have been bad, and readers who believe this is merely ‘Western’ bias being reported should be careful to look for other sources to confirm data. Investment within the second biggest economy of the world has become tentative, because there is a fear the ‘official’ China numbers may be worse than those being reported.

USD/JPY Six Months Chart as of 20th August 2023

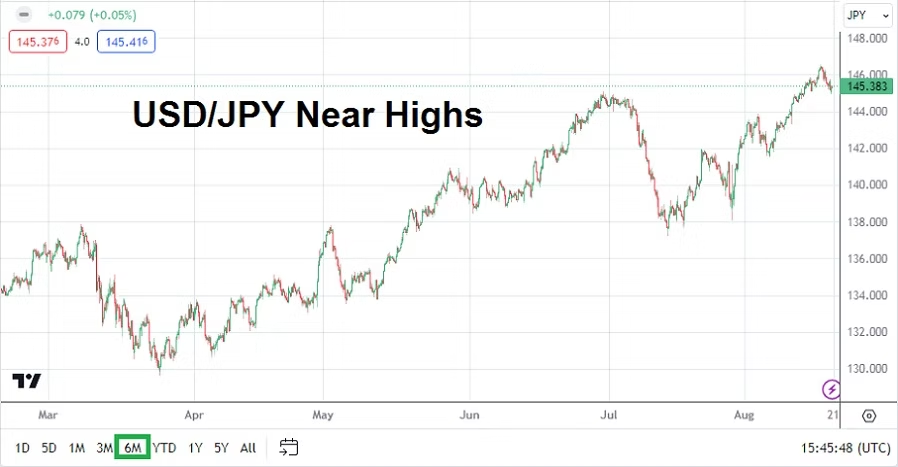
Tuesday, 22nd August, Japan Consumer Price Index – the Bank of Japan report is expected to show a slight decline to the inflation numbers. Last month’s outcome of 3.0% is expected to lower and produce a 2.9% result. The USD/JPY could react momentarily to the outcome, the currency pair is near highs it hasn’t touched since November 2022.

Tuesday, 22nd August, U.S Existing Home Sales – the data is expected to show a slight decline of purchases. Mortgage prices continue to climb in the U.S and homeowners are less likely to desire taking on a new higher mortgage, this if they already have a lower mortgage locked in from a few years ago within a dwelling they already live.

Wednesday, 23rd August, Flash European Manufacturing and Services PMI – the reports will come from the E.U and U.K. The German and British outcomes will stir the Forex markets. The manufacturing data from Germany and Britain are forecast to be slightly negative.

Wednesday, 23rd of August, U.S Flash Manufacturing and Services PMI – the U.S reports are expected to show a decline in the manufacturing sector. If a negative result materializes, this could actually spark a selloff of the USD – if the financial markets have returned to calm waters by the middle of this week. Weaker numbers might be interpreted as another reason for the U.S Federal Reserve to remain neutral and why they should consider becoming dovish over the mid-term.

Thursday, 24th of August, U.S Durable Goods Orders – the core and broad numbers are anticipated to show declines. If the Durable Goods Orders numbers are worse than expected this could spark more USD selling, particularly if financial institutions are already calm and feel the data is another step to ‘lowering’ the Fed’s hawkish interest rate rhetoric. However, for the USD to weaken the markets will likely have needed to be tranquil beforehand, without major surprises having happened earlier in the week that may have escalated nervous behavioral sentiment in the broad markets.

Friday, 25th of August, Germany Business Climate and GDP – the ifo Business Climate report comes from a composite of manufacturers, wholesalers, and other enterprises and is expected to be lower than last month’s outcome. The Gross Domestic Product results are anticipated to show no changes, which would mean Germany’s economy remains in the doldrums and is flirting with recessionary pressures.

Friday, 25th of August, U.S University of Michigan Consumer Sentiment – this revised reading is expected to show U.S consumers remain steady without significant changes compared to the previous outcome.

postN21

Risk Events and Questioning the Hyperbole of ‘Bad Actors’

Risk Events and Questioning the Hyperbole of 'Bad Actors'

The week in a way has already started for financial institutions and traders because of the developing news from Russia. Due to yesterday’s events surrounding the ‘noise’ caused by the Wagner Group’s leader Yevgeny Prigozhin, let there be no doubt that energy sector traders became nervous and fragile behavioral sentiment was being anticipated for Monday’s openings. However, like a well staged drama (perhaps this is giving too much credit to the actors) the Russian saga seems to have come to an odd conclusion. Leaving the possibility for a Part Two to develop. Stay tuned ladies and gentlemen.

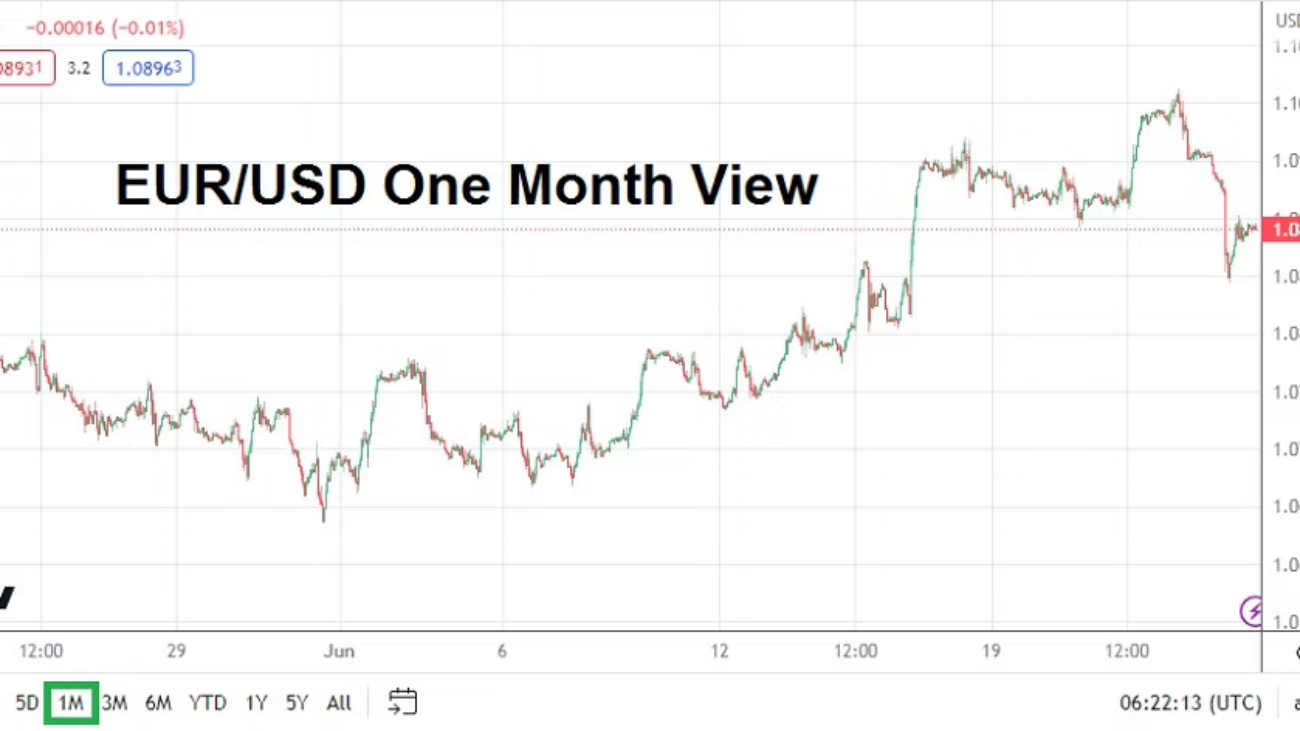
EUR/USD One Month Chart as of 25th June 2023

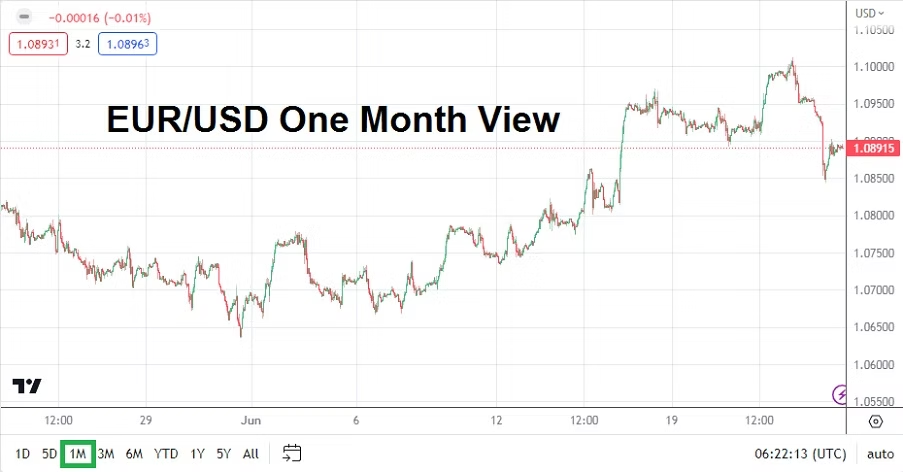
Monday, the 26th of June, Germany ifo Business Climate – the reading is forecast to come in worse than the previous month. Germany has turned in rather troubling economic data and the E.U as a whole is struggling under the weight of inflation and lackluster growth. The EUR/USD could be affected from the business climate survey.

Monday, the 26th of June, E.U ECB Forum on Central Banking – the annual event which is a bit like the Fed’s Jackson Hole Symposium will be attended by the leading central bank officials from around the globe. This year’s event in Sintra, Portugal will focus on inflation. ECB President Christine Legarde will kick off the event, which will end on Wednesday the 28th of June with speeches from Fed Chairman Jerome Powell, BoE Governor Andrew Bailey and others.

Tuesday, the 27th of June, Canada Consumer Price Index – a slew of inflation reports will be delivered. The forecast anticipates a slight drop in price pressure, but will that actually be the result? The USD/CAD could move based on the outcomes.

Tuesday, the 27th of June, U.S Consumer Confidence via the Conference Board – this survey is expected to show a slight improvement in the outlook of American consumers.

Wednesday, the 28th of June, E.U ECB Forum on Central Banking – the event will conclude with speeches from the heads of the ECB, Bank of Japan, Bank of England and Federal Reserve. The event is not supposed to stir up the dust, but Forex traders should monitor the rhetoric generated.

Thursday, the 28th of June, Germany Preliminary Consumer Price Index – the data is expected to show an increase in prices and underscore the ECB’s aggressive rhetoric regarding inflation.

Thursday, the 28th of June, U.S Final Gross Domestic Product – the growth numbers are projected to show a gain of 1.4% compared to last month’s 1.3%. The results will move the financial markets if they are surprising. Traders should be on the lookout for revisions to the previous month’s numbers.

Friday, the 29th of June, U.K Final Gross Domestic Product – an expected ‘growth’ number of 0.1% is anticipated, which would match last month’s lackluster outcome. The U.K is hovering under recessionary pressures and this GDP result will be watched by GBP/USD day traders.

postN19

Broader Alliances: Sustaining Economic and Political Power

Broader Alliances: Sustaining Economic and Political Power

The following article is commentary and its views are solely those of the author.

If the United States decides to abandon its role as the premier global superpower and shall only be a Pacific and Atlantic power, withdrawing as defender of free seas, free trade and freedom in general, its democratic allies will have to start looking elsewhere for broader military alliances. This large group of nations would have to defend their interests against a revanchist China tied to Iran, Russia, North Korea and many of the Latin American countries – possibly including Brazil, and South Africa who have questionable politics and outlooks.

Eastern Mediterranean Alliance: A Strong Sea Power

Here is a speculative, yet reasonable look at the future of the free world. Let’s start with the Eastern Mediterranean where the two major powers are Israel and Turkey. One cannot deny that both these countries outclass all others regarding military might in the region. Israel’s air force is second to none and its navy is becoming a strategic necessity as it needs to defend its natural gas fields miles offshore. It now has six submarines that are capable of projecting power anywhere in the Mediterranean and even into the Indian Ocean and Persian Gulf. Turkey is currently a NATO member, but it is not clear that this will outlast the first half of the 21st century.

There is currently an informal alliance among Israel, Greece and Cyprus (both NATO countries) via joint military exercises and intelligence sharing. The Israeli navy and air force train regularly with Greece and its special forces train in the Cyprian mountains with its army. It would be in all three countries interests to formalize a treaty – if not of mutual defense, at least of mutual aid during times of war. All three of these countries are democracies and all three have mutual economic interests.

A formalization of this alliance makes sense now and if there is a NATO collapse it turns into a necessity for Greece and Cyprus. Adding Egypt (although it would be the only non-democracy) to this group would only strengthen the alliance and keep Turkey at bay. A post-Erdogan Turkey that is comfortable with its Islamic character and its modern society could even join this grouping with Israel as a potential peacemaker between the historic Greek-Turkish rivalry.

This alliance without Turkey is a powerful force in the eastern Mediterranean, and this alliance with Turkey could neutralize a nuclear Iran. A Post-Hezbollah Lebanon which is in the interests of all of these alliance members (including Turkey and Egypt), could become a reality and another member.

A New Alignment: The United Border Nations

What about Eastern and Central Europe? Poland is rapidly becoming the major non-nuclear European military power. Within the next few years it will outshine Germany and the U.K and rival France. It is quite clear, nuclear weapons aside, Poland would probably defeat Russia in a number of weeks, if not days if a conflict were to ignite.

Whether the Russian-Ukrainian war ends in a Russian defeat or in some sort of face saving armistice, Russia will not lose its aggressive nature or nuclear capabilities and it will inevitably become aligned more closely with China and Iran because of its current political nature.

The important new alignment will be categorization of ‘countries bordering Russia’. A new alliance of Poland, Finland, Sweden, Norway and the Baltic states – Lithuania, Estonia and Latvia together would have the land, sea and air power necessary to deter and defeat, if necessary, any Russian imperialist expansion. Even with closer ties to China it would be difficult to imagine that, over the next 50 years, Russia would be a threat to this alliance. Adding Ukraine to this grouping would make a powerful force. Its joint population of over 100 million people, while not quite Russia’s 150 million – would be a formidable adversary, especially as the technological skills of these countries is first world and continuing to improve. Adding the other former Warsaw Pact countries like Czech, Slovakia, Romania, Moldova and Bulgaria can only increase its potency.

Unlike the Eastern Mediterranean alliance mentioned above, this would have to be based on a mutual defense treaty in order to properly deter any Russian-Chinese-Iranian attack. Linking up, informally with the ‘new’ Eastern Mediterranean Alliance would create a powerful grouping of free countries against any attempt by authoritarian adversaries. Adding an economic aspect to these border nations and an alliance with the Eastern Med group with free trade zones would create a strong challenge to any attempted Chinese hegemony.

Asian Border Nations Group: Potential Look Ahead at Potential

If we were to unite the Eastern Mediterranean and Border Alliances to an admittedly non-democratic Asian ‘stans nations, including Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan and Uzbekistan with a joint population of around 80 million, we are beginning to see the creation of a multi-cultural alliance that extends from the Arctic Ocean through Central Europe, Northern Africa and into Asia.

The Crucial Partner in Order to Balance Power: India

Which leads us to the Indian Ocean; a dominant India can help control the sea lanes from the Persian Gulf to the Bay of Bengal and down to Australia. An Indian-Australian alliance, along with Israel would create a democratic economic and military force that would keep China and Iran from dominating the region. This would require an Indian navy that is not only large, but effective also because it would hold a main responsibility for patrolling the seas from the Persian Gulf up to Australia strongholds.

As India also reaches its potential as a global manufacturing giant, it will be a force to be reckoned with. Including into this potent mix of nations, is the possibility of adding authoritarian countries like Saudi Arabia and the other Gulf states; along with Thailand, Myanmar, Malaysia and Indonesia who have strong ‘western’ economic interests and would create a formidable bulwark against China’s imperialist Belt and Road project.

Without the need to project naval power worldwide the Unites States could use it massive naval, air and ground forces to take better control of the Pacific Ocean along with Japan, South Korea and Australia.

If we add countries like the Philippines and Vietnam, then China would be deterred from further aggression. The only other region that would fall under American responsibility would be the Atlantic Ocean – the shipping lanes to Europe, West Africa and the Mediterranean. Along with the UK and France there would be no challenger to the control of the Atlantic. This could also lead to a revival of the old Monroe Doctrine and maybe free South America from the destructive influences of Iran, China and Russia.

The Global Economy and Free Trade Zones with a Stable USD as Reserve Currency

What does all this mean for the global economy? The free world along with its less than free allies who fear China, Russia and Iran could still maintain a U.S dollar based world. Free trade zones amongst and between the various alliances along with a revival of manufacturing led by a technology revolution using AI, quantum computing, renewable energy and space exploration could lead to a global resurgence of free countries that could stop the authoritarian appetites of Russia, China and Iran in its tracks. This can only happen with a stable reserve currency the ‘West’ can rely upon which is the USD.

Potentially a U.S freed from being the sole defender of freedom in the world, would help get America’s fiscal house in order and allow it to focus on being a dominant economic power. Is there a future for the ‘free world’ without a United States that projects power globally? Currently, a U.S withdrawal from global military assertion would certainly cause the end of freedom (economic and political) in the world for many nations. However, with the new alliances described above and a fiscally responsible United States, freedom could yet make a comeback.

Disclaimer: the views expressed in this article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.
post26.1

BRICS and a Potential New Currency Paradigm

BRICS and a Potential New Currency Paradigm

The BRICS nations are causing alarm in some ‘Western’ financial circles as they seek to strengthen their trading alliance reflecting their ability to be large producers and consumers. BRICS has a common goal of creating better trade and financial conditions for each other, and as a potential byproduct to possibly create an alternative to USD dominance.

While political crisis and global security concerns have grown the past few years and are causing uncertainty and instability, the strength of the USD has also caused inflationary problems for many nations including BRICS members. Cash reserve shortages of USD have become problematic and have been fueled measurably by decisions from the U.S government, Federal Reserve system and U.S Treasury. This has ignited many emerging market nations to seek dialogue about potential BRICS membership.

Alliance intrigue and concerns also shadow BRICS members often, the February 2023 naval exercise held between Russia, China and South Africa within waters near Cape Town raised anger in the United States and the European Union. The fact that the joint military exercise was held during the first anniversary of the Russian invasion of Ukraine did not go unnoticed. While no signed military alliance exists between these nations, it should be noted that Russia, China and South Africa also held a naval exercise in November 2019 also within proximity to Cape Town, South Africa.

USD/ZAR 1 Year Chart as of 28th April 2023

Formation and Agenda as Members Scoff at the ‘King Dollar.

The agenda of the BRICS nations often appears a desire to topple the dominance of the USD to those watching from outside, but is it realistic? Trading alliances are important certainly in order to create better economic stability. The BRICS potential effect on the USD is concerning, although not critically dangerous at this juncture the bloc needs to be monitored. In addition there are worries from some in the West that new military alliances could be formed, but historical and cultural differences within BRICS makes this rather questionable for the time being when contemplated in total.

BRIC was an acronym coined by then Goldman Sachs Chief Economist Jim O’Neill to identify potential opportunities for investors within emerging market nations. Members in this ‘bloc’ are countries that have begun to work in unison. About two months ago, Jim O’Neill reiterated the same refrain and alluded to the BRICS theme of suppressing USD strength and its reliance in global trade. BRIC (Brazil, Russia, India and China) was formed in 2009, and they added South Africa as a member in 2010 formally initiating BRICS. This coalition has met annually to discuss coordinated policies regarding trade, finance and investment opportunities. The next annual meeting will be held in August 2023 in South Africa. Vladimir Putin’s potential attendance at this year’s meeting is being monitored widely.

Plenty of discussions have already been articulated internationally about undermining USD dominance in global trade, but little effect has come to fruit in reality and the USD retains its moniker of ‘King Dollar’. However, countries being affected by the rise of inflation and the strength of the USD are becoming numerous and this has caused a diverse group of nations to seek conversations with BRICS leadership about being able to join the trading alliance. Iran, Algeria, Argentina, Mexico, Nigeria, Saudi Arabia, Indonesia, Pakistan, Egypt, Sudan, Syria, the United Arab Emirates, Bahrain, Turkey, Venezuela, Sri Lanka and Zimbabwe are some of the nations that have expressed interest in BRICS membership.

Impact of Sanctions on Russia and its Ability to Counter via BRICS

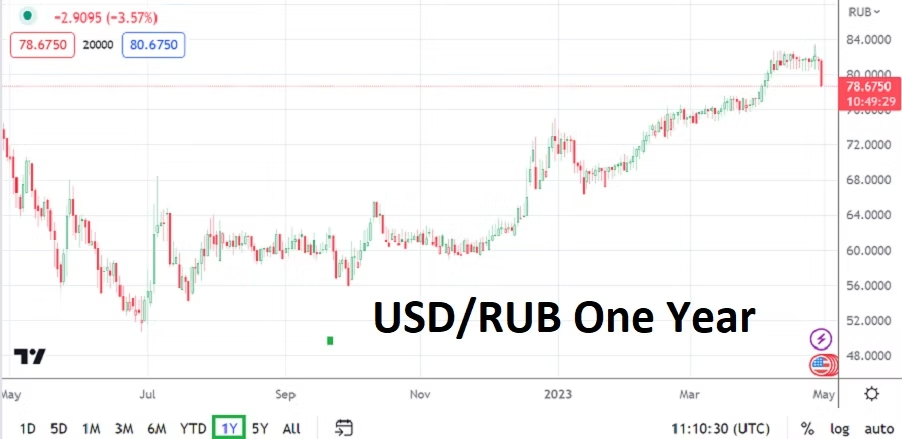
Russia has been waging a war with Ukraine for over a year and is currently under many Western sanctions. It’s been kicked out of the SWIFT banking system, which means it has limited opportunity to trade the RUB with Western countries. This in theory also limits the amount of USD that Russia can get its hands on.

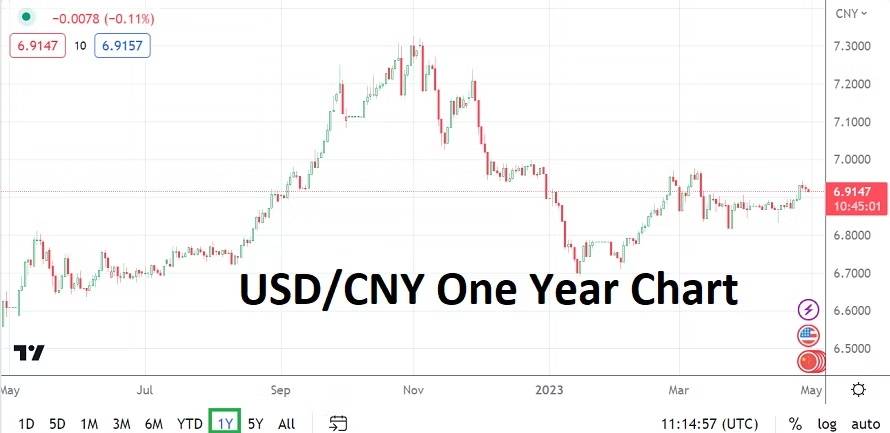
Russia last year asked to be paid in Rubles (RUB) for gas and other energy purchases when dealing with E.U countries, trying to play a game of chess which largely failed. This while China too, tries to make the Yuan (CNY), a more significant currency in order to suppress USD dominance. China certainly has plenty of political and economic reasons to have the CNY emerge as a global power.

Russia has supposedly wanted to get out of Western currencies and especially the USD, this to punish the West, but will it work out and is it pragmatic? No. Russia’s attempts are high on rhetoric, but low on quantified changes thus far. The USD is far too dominant within the global banking system, and while incremental challenges to the USD have been tested, chipping away at USD strength remains difficult at best. The Kremlin has tried to inoculate itself from the pain caused to its trade balance because of sanctions, and create problems respectively for countries that oppose its invasion of Ukraine by cutting off gas supplies which were used for heating and to generate power for industrial purposes. Threatening to not allow grain to flow from Ukraine has also been a rather constant noise made by Russia.

Prices were capped on Russian energy via the G7 beginning in 2022 as a retaliatory move to limit revenues for Russia, and alternative gas agreements were sought by many European nations creating a loss of momentum for the Kremlin’s chess game. The Nord Stream pipeline was also damaged via sabotage. Russia used to supply Europe with 50% of its energy until sometime in 2021, it now provides less than 20% after Western sanctions. Russia has moved its eye towards other nations hungry for energy, ones that are not obligated to make transactions in USD, which brings BRICS into focus.


USD/RUB 1 Year Chart as of 28th April 2023

Inflation and a Strong USD have Caused Harm Globally

Inflation has caused problems across the globe following the impact of the coronavirus epidemic. The Federal Reserve, BoE and ECB have raised rates to try and cool inflation in their respective economies. This has made the USD attractive against emerging market currencies and caused capital outflows. An economic nightmare has occurred in Sri Lanka which is suffering from staggering political and economic problems the past two years, and nations like Pakistan and Egypt have been hit hard too by inflation’s impact and debt. USD reserves dwindled in these nations and they found it difficult to service their USD denominated debt in 2022, and troubles persist in 2023. Import without any USD reserves is difficult and sometimes impossible.

Russia and China as Major Players in ‘Their’ Bipolar World with ‘Friends’

Global trade is still dominated by the “King Dollar”. Almost 88% of global trade happens with the USD. The USD accounted for more than 71% of currency reserves at central banks in 2000, but has now declined to slightly below 59%. Oil and gas exports are important for Russia as these revenues constitute nearly 45% of its Federal Budget and it’s already been in deficit since February 2023, because oil revenues have slumped by half. Russia has a growing dependence on BRICS and is actively trying to get other nations to join the trading coalition, this because it has few other places to turn, and there appears to be no end in sight regarding the war with Ukraine.

Trading with other nations and signing currency agreements which would not include USD transactions is a long term goal of Russia and China, this if monetary values via the other nations currencies can remain firm. And then there is a wished for and ‘feared’ long-term dream of creating an alternative ‘super’ currency to compete against the USD.

Even before the escalation of fighting in the Russia and Ukrainian War, Russia was strongly advocating an end to USD dominance in global trade via rhetoric, particularly during previous BRICS Summits. We need to understand the political implications and complexities within BRICS, when talk of a decoupling from USD dominance news flares up. The U.S certainly keeps an eye on BRICS and so do other Western nations. At this moment South Africa has a delegation in Washington, D.C regarding the questionable South African policy behavior, particularly in light of recent military exercises with Russia and China, to try and smooth its U.S relationship. South Africa membership in AGOA, the Africa Growth and Opportunity Act, which grants special trade benefits to the nation and other members is being questioned strongly by U.S politicians. Getting kicked out of AGOA would cost South Africa billions of dollars in aid.

China and Russia seemingly want to create a bipolar power sphere, one in which U.S dominance is not so easy. Chinese President Xi Jinping and Vladimir Putin have met several times recently and are certainly collaborating regarding trade and investments. The developing news regarding the potential of BRICS enlargement shows that China and Russia maybe preaching multi-polarities such as their involvement with South Africa, but may actually be working towards a bipolar constellation of forces in which they would lead a broad alliance of countries in countering the preponderance of Western economies and potentially military might.

USD/CNY 1 Year Chart as of 28th April 2023


By allowing membership of BRICS to expand, U.S influence and the dominance of the USD would be lessened incrementally. A long game seems to be in play and if that is the case, the game of chess being played by Russia and China together against the West is complex and the U.S and its allies will need to be ready with a response if they want to protect the USD.

From the China point of view, the internationalization of the CNY is a positive. It has recently brokered a peace deal between Saudi Arabia and Iran, long-term arch rivals which surprised many in the West and seemingly caught the U.S unaware. China has also lent close to 1 trillion in USD value to Ghana, Pakistan, Nigeria and other smaller African countries. China is wielding power via trade and investment leverage into these respective nations strategically, pushing its global trade agenda even as Washington quietly threatens to punish China for backing Russia in the war with Ukraine.

Changing Role of China on the World Stage and BRICS

China’s role today is very different than in 2009 when BRIC was founded, this as the nation has become more secure regarding its stature globally. In the initial stages of BRICS there were talks about challenging USD dominance in global trade by member countries, but China vehemently avoided discussing this proposition openly to avoid conflict. The game has changed significantly regarding rhetoric, this as U.S – China relations have worsened as global trade, military security and corporate surveillance issues become more troubling. Political tensions with Taiwan as China rattles swords is a drama that nations are also watching attentively.

For China, the developing alliance with Russia has been a complex and sometimes slowly evolving plan historically, but one that has grown amidst tensions with Washington since the Trump presidency. The Russia and Ukraine war has accelerated the desire to break U.S led global dominance, and that means trying to break the USD internationally when it is possible. It is a long game and BRICS is part of this equation.

China and Russia view themselves at the vanguard in the struggle against Western global predominance, and they are eager to bring others on board. At the last summit of BRICS in June 2022, both Chinese President Xi Jinping and Russian President Vladimir Putin argued in favor of expanding into BRICS Plus. Beijing has become particularly interested with developing BRICS as a counterweight to the G7. While it has been difficult to establish a consensus on expansion among the current BRICS members, it appears to be a certainty that expansion is coming and the summit in South Africa this August will provide insights.

China is promoting the CNY in exchange for getting oil from Russia. The CNY is now ranked fifth regarding global transactions according to many banking sources. From the Kremlin’s point of view accumulating CNY reserves is good for Putin in the short-term; this creates more buying power for goods from countries that are friendly to Russia and China collectively and creates strategic momentum.

Yes, there are long-term historical complexities between Russia and China which will likely prove difficult politically to solve, but for the moment money is helping grease their wheels of diplomacy. Differences of opinion between Russia and China cannot be ruled out in these kinds of power games. Putin is an astute politician and liable to act in a surprising manner, this while trying to help Russia and its place among nations. Russia is certainly not keen on becoming a puppet state of China.

Trust is Almost a Four Letter Word for Some Economically and Politically

In his acclaimed book ‘Trust: The Social Virtues and the Creation of Prosperity’, the political economist Francis Fukuyama illustrates how degrees of trust in a society and indeed in a company can be decisive for prosperity and the ability to compete. In “low-trust” societies such as China, Russia and Italy, you cannot assume that everyone is willing to follow the rules. Members of these societies must frequently renegotiate ‘asserted’ rules, and often have to go to court to decide on matters. Ironically, one can see that this also applies to trading of the CNY.

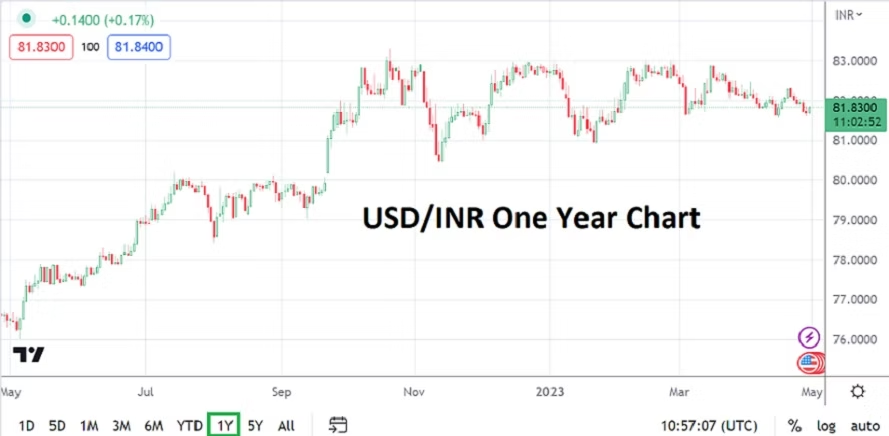
USD/INR 1 Year Chart as of 28th of April 2023

For instance, while China promotes the use of the CNY, countries like India are still using UAE Dirham (AED) for buying oil from Russia. BRICS still needs to sort out which currency they will use extensively for trade, this while many members try not to make enemies of other nations. South Africa exports are significantly more to the E.U, U.S and the U.K compared to Russia. Its share of exports to Russia are minuscule compared to the other three. Not only is South Africa risking free trade agreements with the U.S, E.U and U.K, but membership in key groups like AGOA as it tries to play on both sides of the fence politically is in jeopardy. Western observers are certainly watching South Africa and they will watch any other nation that joins BRICS. How long will the ANC led government of South Africa will be allowed to flirt with Russia and China militarily before it is stopped?

India has a Large Role in BRICS and is Growing in Stature

India is a vital member of BRICS, but also an important member of the QUAD alliance, the Quadrilateral Security Dialogue. Japan, Australia, the U.S and India are members and confer over trade and security. India is the largest democracy in Asia – and the world – and a Western advocate in South East Asia, even as China plays a dominant role in geopolitics. While BRICS wishes may be good for conducting bilateral trade among members, it is not necessarily good for global trade and political understandings. Complications from long-term political and historical disagreements between India and China cannot be discounted either.

Is the Indian Rupee (INR) or CNY more relevant for international trade? Use of the INR and the CNY needs coordination with other countries many times. Australia is a good example regarding the ability to trade INR internationally. If Australia and India agree to make their payments for exports and imports in their respective nation’s currencies, trade can be conducted rather well, but then Australia would have to find another nation for its ‘extra’ INR, because it would likely suffer due to trade imbalances. It would be important for another country outside of India to agree to take INR from Australia for other trades. Potentially some Gulf countries could be open to these types of INR transactions. A bigger group of BRICS nations would help India certainly.

Saudi Arabia has recently agreed to sell oil for CNY, but shoring up CNY in their coffers has long-term implications. This as Saudi Arabia wrangles politically with the U.S occasionally. Saudi Arabia has demonstrated a desire to take on a seemingly more neutral tone and perhaps wants to limit its exposure to the strength of the USD, particularly if the U.S tries to make a weapon of the USD via political policy. Thus, India as the most populated nation in the world and a growing economic sphere of importance, has to make careful considerations moving forward as it positions its economic stature for complexities that will develop. India and Saudi Arabia may have visions of becoming great ‘neutral’ economic powers moving into the next one hundred years.

The Indian Government has made economic deals with Egypt, Sri Lanka and Malaysia for bilateral INR trade, but still no pure INR trades of significance have materialized according to official banking data. There are multiple headwinds for BRICS nations to overcome USD dominance in international finance. Whenever exchanges of INR or CNY to other currencies for trade settlement are needed, they need to first change the base currency to USD to buy RUB or AED. Few exporting countries will accumulate CNY without a total need. Holders of these currencies would likely dump the INR and CNY for USD via Forex.

China Economic Transparency is Lacking and the Future of India in BRICS

China doesn’t make it easy for foreigners to own assets in their nation. The China government does not want massive trade deficits and free capital flows are restricted with force. Who would invest in China and risk having their money being stuck in the nation without guarantees? China continues to ramp up its oversight and aggressive tactics of supervision of foreign owned companies that have operations in the nation.

Now and into the foreseeable future, the Chinese government will control transactions of CNY with an iron fist. The United States will likely remain the predominant place for trade because of its huge economy, and as a nation that allows many other countries and foreign citizens to own and invest their assets within it boundaries. There is still something to be said for transparency. Any new nation or coalition trying to challenge U.S government debt instruments are likely to fail. The U.S continues to be a place where nations can hold ‘safe assets’ with a guaranteed return of interest for the long-term. No country equals the asset size and security of U.S Treasury Bonds. On that basis alone, there will be a no challenge to the USD in the near future.

Liquidity remains an issue for capital flows and convertibility within BRICS. A lot of hard work via transparent trade agreements will have to be signed to get these issues resolved. Plenty of questions exist regarding China’s economic data and its reliability because of a lack of oversight from ‘recognized’ outside agencies which are often forbidden.

India is still having border issues with China and these problems remain unresolved. India’s role of leadership in G20 is hard to ignore despite its alliance with BRICS. The Indian government has advised traders not to speculate in CNY. This shows that strained relationships between China and India remain and a lack of trust regarding clarity continues. In the U.S, New Delhi is considered an important partner, one that can be trusted regarding the growing rivalry between the U.S and China. Prime Minister Narendra Modi, said last year, “this is not an era for wars”, and this shows India wants stability and wants to play a global role in diplomacy.

There is a definite strategy for BRICS to grow with the nations of the Middle East and others. Using their currencies for mutual trade arrangements could eventually work out, but it will take a long time for this to change the dynamics of USD dependence and dominance.

However, we shouldn’t forget that almost 40% of the world’s population lives in Asia. Yet, even if oil producing nations will trade in a BRICS backed currency basket, which has been dreamed about for a long time, China’s leader Xi didn’t highlight this goal while in Moscow or in Saudi Arabia during recent summits. China is certainly playing a long game, but it also shows they remain cautious and vulnerable to the strength of the USD globally. If Xi wanted to cause the greatest pain to the United States, he would liberalize his financial sector and make the CNY a true competitor to the USD with complete economic transparency, but that would take him in the direction of free markets and levels of openness that are likely the opposite of China’s domestic ambitions. A strong due diligence of the Chinese economy, is something Chinese leadership likely wants to avoid for the foreseeable future.

BRICS: A Multi-Polar World and Avoiding Confrontation

Many developing countries will want to avoid a confrontation consisting of China and Russia on one side, and Western powers on the other side. India has overtaken China regarding population numbers, and will likely become the world’s third largest economy before the end of this decade. India will become a strong voice in favor of a multi-polar world. Arguably, ideas of a more multi-polar world are being worked towards in pragmatic ways, but the BRICS coalition will not develop their own asset backed common currency unless they can resolve issues regarding trade and monetary agreements with transparency. It is a matter of trust.

post9

Escalation of Rhetoric doesn’t create Calm Investors

Escalation of Rhetoric doesn't create Calm Investors

Putin and U.S Federal Reserve will Stir U.S Markets Today

An escalation of rhetoric via Russian President Vladimir Putin regarding his nation’s war with Ukraine took place this morning via a televised address to the Russian people. Putin has said Russia will call upon those with previous military training, and use a ‘limited’ call up of potential new troops. A claim of nearly 300,000 additional soldiers to be readied has been made by senior Russian officials shortly after Putin’s speech.

Making matters more intense, Putin said all military options are possible while Russia protects its sovereign territory. The land he was speaking about however, is not recognized Russian territory, it is Ukrainian soil. Putin’s ‘talk’ to Russia has firmly put him in a position which shows that results from the Ukrainian war have not had favorable results and that he is showing signs of frustration. An anxious Vladimir Putin is not about to calm down what are already nervous global markets.

China Urges a De-escalation in Ukraine while not naming Russia

China has already reacted to Putin’s speech by urging all sides active in the Ukrainian conflict to de-escalate the situation. China has its own economic worries presently and certainly doesn’t need another bad ingredient thrown into its midst as it deals with weaker demand for export products and a shaky real estate market as the global economy reacts to inflation and recessionary concerns.

International traders will hardly hear what China had to say today, not because it isn’t important, but because their attention will be on Putin and the U.S Federal Reserve. However, it is important to point out China did not condemn Russia, instead it asked that all sides involved in the Ukrainian sphere to lessen the dangers. China and its relationship with Russia remains an important aspect of global politics.

The U.S Federal Reserve will raise Interest Rates Today

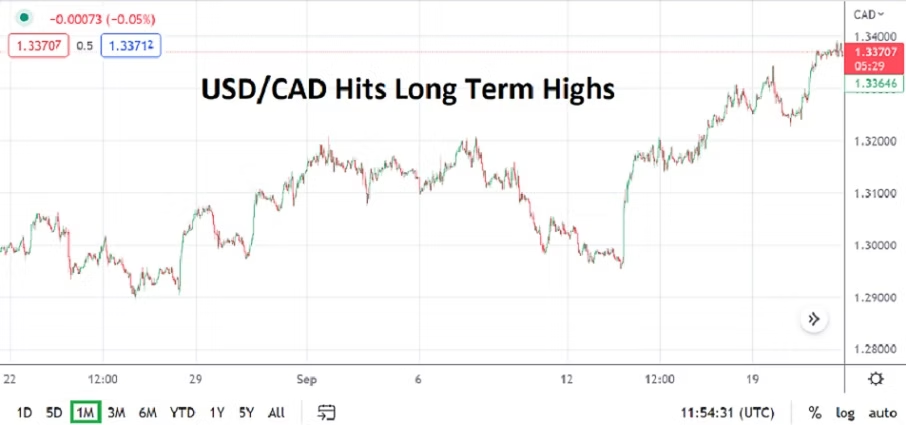
The U.S Fed will raise its interest rate by 0.75% today according to most financial houses which have already acted accordingly within Forex per interpreted price action. The USD has made new long term highs within the USD/ZAR and the USD/CAD. The EUR is below par as of this writing against the USD, and the JPY and GBP also continue to struggle near long term lows versus the USD.

USD/CAD One Month Chart

U.S equity indices which have been struggling are not showing a massive promise of a reversal upwards which will alleviate losses seen this year. Investors need to remain patient if they are invested in indices such as the S&P 500. Day traders looking to profit from the volatility ripping through the markets will continue to be challenged by choppy conditions, difficult perceptions of short term technical charts and a lack of positive behavioral sentiment among the larger players in the marketplace who actually drive the markets most of the time.

  • USD remains stronger against many major and emerging market currencies, day traders need to be very careful if they pursue Forex positions in the short term.

  • U.S equity indices traded lower yesterday, and if the Federal Reserve falters and doesn’t offer solid clarity regarding interest rates today, this could create more nervousness.

Optimism is not being heard far and wide. While it is always interesting to be a contrarian and sometimes the correct avenue to engage thinking, the notion that upwards trajectories will suddenly occur may be wishful thinking in the near and mid term. Many asset classes are under stress.

Today’s upcoming pronouncements from the Fed will be important for institutional investors as they try to gauge the U.S central bank’s outlook until early 2023. If the Fed gives clues they will remain hawkish into the winter and a Funds rate around 4.50 to 5.00%is a possibility, this could shake investors and cause more capitulation – meaning a stronger selloff via equity indices could ensue. Short term traders will need to be prepared for violent conditions if they are day traders of stocks or CFDs. The inverted U.S bond yields remains a sign investors are seeking short and mid-term safety via interest rates to preserve money.

The fact that most traders are typically buyers first, not sellers first makes trading in bear markets difficult. Psychologically humans want to be optimistic. Today’s speech by Vladimir Putin while it doesn’t change the conditions on the ground in the Ukraine immediately, will shake the confidence of some financial houses which may have become accustomed to a ‘polite war’ they could ‘forget’ about and make believe would not get loud again. Nervous behavior is likely to be seen later today as early risers in the States awake to the news of Putin’s speech and react.

In short global markets will be dynamic today and tomorrow, as financial houses position their portfolios according to their foresight regarding developments the next few months. Day traders are urged to be cautious, and the prospect of sitting on the sidelines and watching ‘the show’ may prove to be a solid choice.