AMT Top 10

AMT Top Ten Miscellaneous Insights on the 18th of May, 2026

Valuations and Drinking, Bad Storms and Politics Amidst the Resilient Nature of People

10. Resilience: The Western Cape of South Africa endured strong storm conditions last week. One of the hardest hit areas was the Cape Winelands District, but electricity and water have been widely restored. And a collective of people have proven working together can produce solid results when needed. 

9. Spencer Who: The Los Angeles mayor race is growing intriguing. A reality star turned social influencer threatens to become an influenza for his opponents. This as Spencer Pratt’s campaign gets noticed for its entertaining social media videos. This has caused many folks to ask what has happened to the state of politics and meaningful policy. But if NYC can elect a socialist, why can’t L.A elect an influencer and make some people feel sick?
AMT Top 10 Miscellaneous Insights for the 18th of May, 2026

8. Two Trillion: SpaceX early investors have agreed to allow a five for one stock split, meaning the company (and Elon Musk) are now aiming for a potential doubling of its worth when its IPO is initiated – on Nasdaq – in the second week of June. Some very serious accountants will be kept busy trying to show how SpaceX will produce enough revenue over the next twenty years in order to make a 2 trillion USD valuation palpable to future investors.

7. Drunk: Brown-Forman Corporation will begin its trading near $26.28 on the NYSE today. The company is the majority owner of Jack Daniels and other alcohol related enterprises. The value of Brown-Forman Inc. in June of 2021 was around 80.00 per share. The sobering phase of the public – particularly among young drinkers – to avoid bars and clubs, and instead stay on their mobile phones has hurt share values in many alcohol related companies. There are also concerns that too many drink companies now exists. Before Brown-Forman becomes the life of the party again, it appears some competition will have to go dry.

6. Deals: Prime Minister Modi visited Abu Dhabi a few days ago, and one of the results was an agreement to purchase and store energy reserves on a large scale in the United Arab Emirates. Modi also confirmed India’s strong connection to the UAE politically. While always trying to maintain a non-aligned stature, India appears to be moving closer to an increasingly important alliance with the UAE – which has also aligned with Israel strategically. The potential of these three nations acting together will ruffle feathers in a few noteworthy Middle Eastern and Asian countries.

5. Populists: President Trump’s tendency to say outlandish things and then suddenly turn around and show a willingness to negotiate terms has always been part of his art of the deal composite. However, saying what people want to hear and then turning on a dime and not delivering is also a symptom of populism. Trump isn’t the only politician suffering from this flaw. What do politicians really think, and how differently would they act if a they didn’t need votes for themselves or backers to remain in power?

4. Wall Street: After attaining apex highs early last week, the three major indices have taken a step backwards. Near-term concerns are effecting outlook as financial institutions balance risk averse tactics to long-term belief that sunnier days will prevail. While the Dow 30 didn’t set a record last week, the ability of the index to climb above 50,000 was noticeable. Equity markets appear tentative as this week begins and folks seemingly wait for more thunder and its potential effects.

3. Emirates: The UAE was attacked by drones yet again yesterday, this time at the Barakah nuclear facility. The hit has been downplayed, but highlights that military conflict with Iran remains very possible across the region. It is doubtful conversations are being conducted with polite undertones behind closed doors. The U.S, Israel and other nations are watching Iran – and Iran is watching them. The price of WTI Crude Oil remains a key barometer regarding the markets and concerns about the war igniting in full once more. Prices of oil remain sustained above $101.00 per barrel in the futures markets. The UAE might not want to be a focal point, but it isn’t backing down either.

2. Hawkish: The U.S Federal Reserve may have to actually consider raising interest rates before they can realistically discuss the notion of cutting borrowing costs, particularly if energy prices remain elevated and spark a sustained inflation threat over the mid-term. The USD started to show renewed strength the past few trading sessions in Forex, this as financial institutions compare their near-term anxiousness to growing concerns about mid-term ramifications regarding higher fuel costs.

1. Ego vs. Hubris: The U.S and China summit held largely in Beijing this past Thursday and Friday matched competing politicians and ideologies. In one corner U.S President Trump spoke with a rather inflated sense of himself while he detailed policy objectives and his perspectives. In the other corner Xi Jinping, the President of China, might have displayed some hubris as he warned the U.S about the Thucydides Trap. Xi expressed his belief that China is the emerging super power and that the U.S is a declining nation. However, China’s economy is known to be suffering because of a myriad of complex reasons, and could face more headwinds if energy prices and supplies remain hard-pressed.
Copy and paste the text from AMT that you want to share

WTI Crude Oil 20260428

Shift To Economic War Against Iran to Deprive Funds to Regime and IRGC

What If Everyone Is Looking At The Wrong Things About Iran?

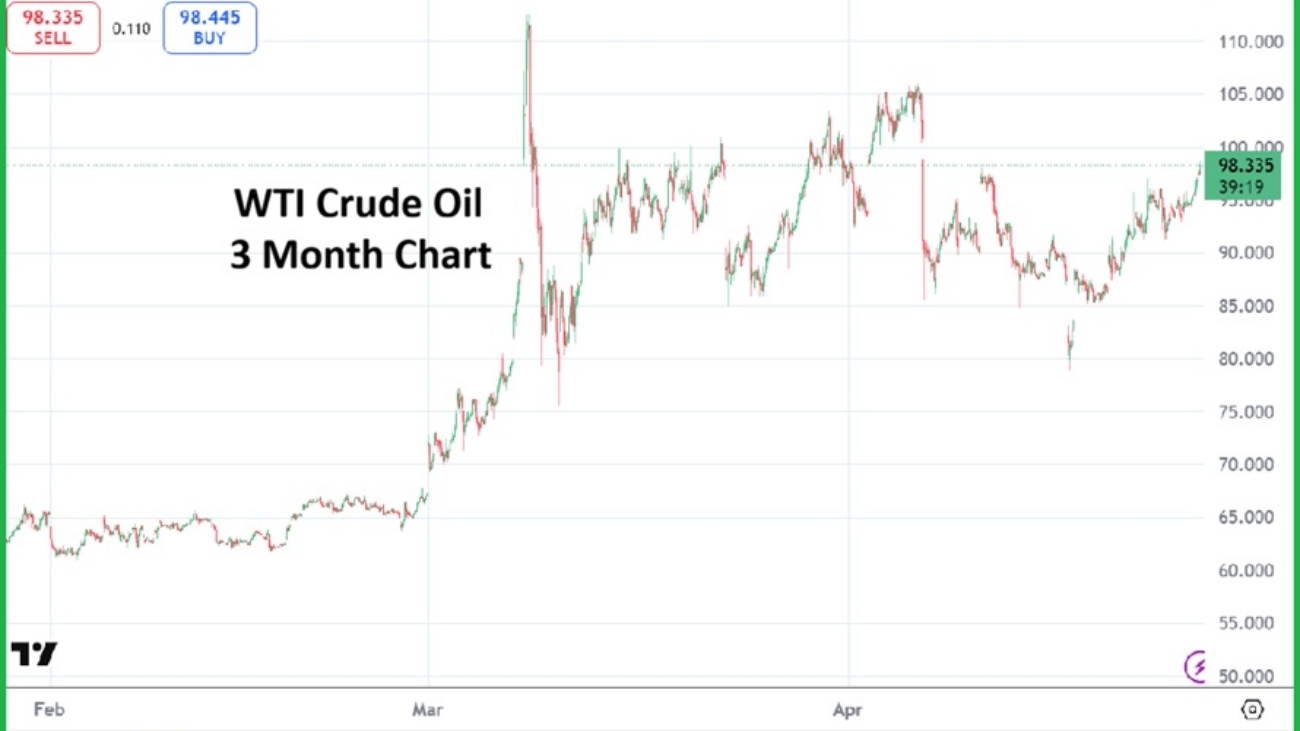
The current futures price for WTI Crude Oil is above $98.00. The cash price for the commodity is above $103.00. While many people continue to fret about what endgame strategy the U.S White House is conducting, what if we are seeing it play out in real time via the price of Crude Oil? Is it possible that President Trump has a coordinated plan to starve the Iranian regime and the IRGC of its much loved and needed money? It appears this is the case.

WTI Crude Oil Futures Three Months Chart on the 28th of April

Simply put, the Iranian Revolutionary Guard Corps is a mafia. They stay in power using the tool of fear brought upon by their ability to be ruthless to the Iranian citizens. They are a terrorist organization in the truest sense. If you disagree with that assessment, you are free to do so. However, facts when they are studied point to the conclusion Iran is a terrorist state led by its regime and the IRGC. 

Iran has made massive amounts of money via its energy products for decades. The shutdown of the Hormuz Strait, or at least the inability to export Crude Oil freely, is putting a strain on global energy prices, and it is causing a major fracture in the main financial export of Iran. 

The U.S has not only shut down easy navigation in the Hormuz Strait, but it is also going after Iran’s cryptocurrency operations. The ability to receive and transfer digital money by Iran is being strangled. What if President Trump is not only listening to the opinions of his military officers, and Secretary of State Rubio and Vice-President Vance, but also Treasury Secretary Scott Bessent who has an abundance of financial knowledge about how money flows internationally and how to create obstacles.

If the IRGC is not able to pay its own members, and other adherents to the Iranian regime are only slowly reimbursed, the apparatus of the IRGC will certainly lose its influence. The inability to pay allies that exists merely because they are employed or corrupted by the IRGC likely is starting to cause fractures regarding loyalties. 

China needs Iranian oil too. And evidence is starting to be speculated upon that China is facing tough decisions about acquiring Crude Oil from other sources. China will not be happy about having to pay higher costs, this because discounted Iranian oil that has abundantly been used is no longer available. 

Equities via the major U.S indices have done incredibly well since the end of March. The Nasdaq 100 has seemingly forgotten about AI overbought concerns, the S&P 500 is within apex territory and the VIX is acting as if sunny days are in the forecast. Forex has been volatile, but the value of the USD is within known realms.  However, the price of WTI Crude Oil is high and it has gotten higher since the 17th of April when futures prices briefly flirted with the $80.00 realm – this before going into a weekend. And this is a clue that something is afoot, beside larger players speculating on what their outlooks are for WTI Crude Oil in the mid-term.

The weekend of the 18th and 19th of April witnessed talk of an end to the Iranian war fall short; and heard President Trump essentially declare the ceasefire is still on but with the caveat that the U.S would create a blockade in the Hormuz Strait. While the semantics of a blockade can be debated, the U.S has caused shipping problems for tankers that were supposed to ship Iranian Crude Oil. The U.S clearly decided to create economic distress for Iran.

The Iranian regime still stands, but its leadership is rather shaken. The IRGC is controlling a lot of the decision making for the time being, and it appears the U.S White House is trying to make the IRGC weaker by ending their financial lifelines. It appears that it has been figured out that an economic war which includes starving Iran of cash is the most certain way to create revolts inside of the nation. When the influence of money is eroded, and temptations via other spheres of power suddenly sound tempting and can be joined, this is when shifts in authority and leadership can occur. 

While many analysts wonder about the lack of an obvious endgame being announced by the Trump administration, maybe it is already being played out. President Trump has a large ego and he is happy to extoll the virtues of his ‘tremendous’ policies frequently, but he also has shown the ability to remain quiet when it comes to plans of action and carrying them out. Yes, this can be argued into the late hours by pro-Trump and anti-Trump people. But maybe Trump is simply telling the truth when it comes to the U.S having time on its side regarding the Iranian ceasefire and the Strait of Hormuz. Maybe the clock is ticking on the eroding cash pile the Iranian regime and IRGC has within its grasp.

Copy and paste the text from AMT that you want to share

US Cash Index 20260424

Upcoming Weekend Nervousness: Does Anyone Know What is Going On?

Preaching Caution and Looking Like a Fool to Those Who Want to Profit

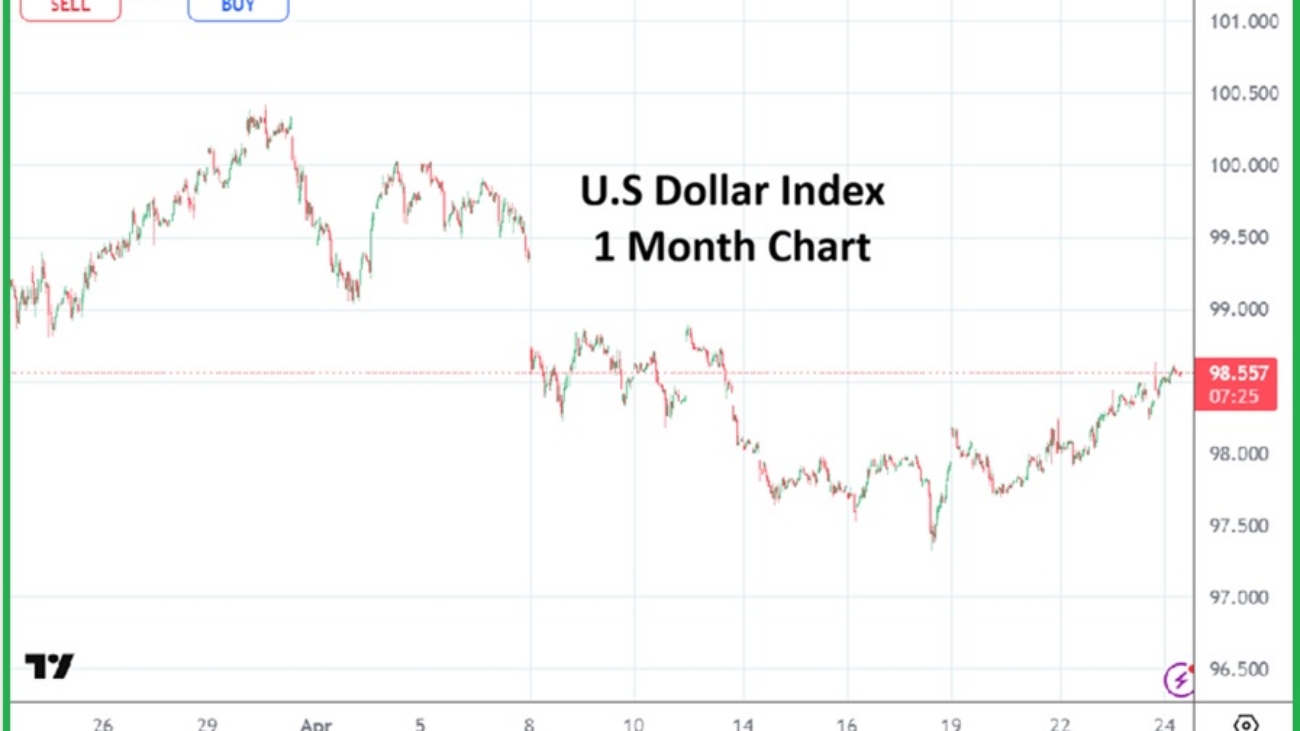
Can someone please tell the rest of us what is going on? Global markets via Forex this morning are demonstrating additional USD centric strength which developed yesterday. The price of WTI Crude Oil is above $94.00. Gold is languishing and around 4,675.00 USD. And although the 3 major U.S stock indices are all within their higher realms – one thing stands out – folks are uneasy.  But then again, the markets never move in one direction only, and perhaps current results can be interpreted as profit taking by those on winning sides.

U.S Dollar Index One Month Chart on the 24th April 2026

I would love to be the person to tell you what is going to happen, but as this weekend looms making short and near-term bets still appears a fool’s game. Yes, it is easy to make predictions, but being correct is more difficult. Retail traders are suffering more than most market participants, this as leverage and a lack of funds to remain in a position through violent reversals destroy plenty of trading accounts.

There is talk of manipulation via chat rooms regarding the price of WTI Crude Oil. The usual dialogues can be seen – largely based on conspiracies via large players trying to blow out smaller traders. However, these types of forum chatter are mostly wrong. Large players are getting hurt too in the energy markets. Anyone who is taking a position in order to speculate on a quick hitting foray in WTI is betting on their perceptions. 

The problem is that unless there is inside knowledge of what the next words out of President Trump’s mouth are going to be, or that from Iranian officials – any pursuit of WTI Crude Oil at this juncture is a ‘vibe’ trade. What is going to happen from Saturday and into Sunday is an unknown quantity. Folks holding positions into this weekend need to understand they are wagering. And some may find they are quite profitable afterwards, while others grimace and find themselves on the wrong side of the next surges higher or spikes downward. Intraday trading volatility in nothing new however.

The USD/JPY is near 159.600 as of this writing. The EUR/USD is close to 1.16820. While a tourist traversing foreign lands may not find the Forex incremental shifts in value mesmerizing or of interest, FX traders who do not have deep pockets are likely wondering why risk adverse conditions are prevailing suddenly. But as a risk analyst, I must say that conditions simply may have been perceived to have been oversold in the USD by financial institutions, this as the Fed looms on the horizon.

However, my task as a risk analyst the past two months has been like a carnival barker, because while it has been easy to say that a show is happening within the big tent of speculation, I have been hard pressed to predict short and near-term directions correctly. Perhaps I fret too much. The optimistic thunder claps upwards in the stock markets since the 31st of March have been astounding to many. Hopefully it has been prosperous for day traders, but the likelihood is that financial institutions are the ones who are profiting more via their pension funds purchases for institutional clients.

This coming week the U.S Federal Reserve will make their FOMC decision public. This will be Jerome Powell’s swan song at the Fed. The Chairman is being faded out by the U.S White House mid-May. And somewhere when he is all alone, Jerome Powell may be having a quiet laugh to himself. The Fed will not act this week. Rates will remain the same – unless there is some bizarre move in the global markets over the next handful of days. Yet, Powell’s remarks will be listened to for warnings. While it is not in Powell’s nature to issue a ‘I told you so’ quote, and he is likely content to walk away from the Federal Reserve quietly, it would be captivating if Powell looked into the cameras and pointed fingers. 

But because Jerome Powell like most others, likely has no clue what is going to happen next internationally he will remain mostly mute (cautious as always).

And here we meet again, wondering what the next 72 hours hold. Will the Iranian ceasefire remain observed? Is it even a ceasefire in reality? The Strait of Hormuz remains a linchpin for military action by the U.S Navy and Iranian Revolutionary Guards via a cascade of ship seizures. Maybe that continues to be the key, WTI Crude Oil prices remain a crucial barometer. USD centric prices via Forex action seems to be a reflection of fear or positive thinking in the energy sector depending on the prevailing tides.

Last week there was so much optimism folks were talking about WTI prices potentially hitting $75.00 and lower, now this hope seems to be wishful thinking. Global markets will remain fast and dangerous, that is easy to say and is right, but telling you which direction assets will move, that is a bit different.

And there is the old standard test I use when an opinion is definitely asked for: if someone were to put a gun theoretically to my head and ask me what I think, I would venture to say things will remain quiet and optimism will seep into the markets before the close this weekend. However, I don’t like to play fool’s games, so I will leave now and wish you luck via your own perspectives because the near-term remains more speculative than normal for day traders – even if strict risk management is used. 

Copy and paste the text from AMT that you want to share

postN87

AMT Top Ten Miscellaneous Bits of Clarity for the 19th of April 2026

In a World Filled with Bread and Circuses, Now a Dose of Transparency

10: The Risk Reward Show: Sommer and Petrucci will return to the airwaves this coming week, via sources like Spotify and YouTube, with their podcast starting after a long break (absence).

9. Hardball: Major League Baseball is back and the sport continues to attract more fans and growing attention with its quicker games, a new computerized strike zone, and maybe even more dislike of the Los Angeles Dodgers. Yes, Shohei Ohtani remains a dominant and positive force in the baseball world.

AMT Top 10 for the 19th of April 2026

8. Populism: Politicians on both sides of the Atlantic continue to display a wide display of nonsensical rhetoric and bold asinine actions equating into empty spectacles. An example from the Left is Zohran Mamdani the mayor of New York City with his socialist platform, which is certain to fail and equate into more people and companies leaving NYC for less expensive and friendlier tax environments. And from the Right Italian Prime Minister Giorgia Meloni who talks a tough game but consistently falls short of backing up her words when she senses she could lose control of her power base. The putrid smell of trying to please voters with rotting bread and circuses prevails.

7. Speculation: Gold finished Friday’s trading near $4,837.50, Silver around 80.78. Bitcoin is close to $75,570.00. 

6. AI: While the Artificial Intelligence hangover has been widely discussed for a handful of months, health continues to be seen via Nvidia which closed above $201.00 going into this weekend, and Anthropic PBC which appears to be aiming for an IPO in late 2026 or early 2027. At this moment Anthropic has an estimated valuation of 800+ billion USD. If Nasdaq is able to secure a listing with Anthropic it will immediately factor into the Nasdaq 100. Are some investors betting on upside now which they believe will be seen when Nasdaq reorganizes its index?

5. Optimism: India, South Africa, Brazil and other emerging markets have experienced Forex volatility like all nations the past month and half due to the Iranian war. However, in the past two weeks the Indian Rupee, South African Rand and Brazilian Real have performed better as global markets have calmed. The ZAR and BRL have actually outperformed major currencies over the past handful of months showcasing existing optimism within financial institutions dealing with these currencies.

4. Money for Something: Lefarge, a French company specializing in concrete, was found guilty this past week of paying ISIS (Daesh) and other terrorists groups money in the years from 2012 into 2014, this in order to maintain their business operations in Syria. While Lafarge claims they paid the money to keep their operating staff safe, a French court ruled Lafarge was buying not only safe passage to allow employees to work, but also paying for physical resources needed from quarries that were controlled by the terrorists. Critics of Lafarge point towards the company’s massive infrastructure investments leading up to 2012 and a decision to seek profits no matter the costs of dubious morality. Some Lafarge former senior executives involved have been sentenced to prison including Bruno Lafont and Christian Herrault. Lafarge and Holcim (a Swiss conglomerate) merged officially in July of 2015.

3. WTI Prices: The value of the world’s most famous Crude Oil went into the weekend near $83.30 via futures markets. The commodity is certain to open with volatility early on Monday, this as folks weigh in via their existing behavioral sentiment which will range from speculative perceptions to insights they hold to be true (but that could prove false). WTI Crude Oil challenged 79.00 USD momentarily on Friday, before sparking upwards as cautious attitudes likely ignited doubts about what would happen this weekend in the Middle East regarding potential developments. Wagering on WTI in the coming days for day traders may be akin to spins of the roulette wheel.

2. Apex Heights: The winning streak and surge upwards for the Nasdaq 100, S&P 500 and Dow 30 via gains have caught some investors by surprise and standing on the sidelines. Some large financial institutions may find they have to explain why they did not participate in the rally which has unfolded since late March. The S&P 500 has gone up around 9.5% during this time.

1. Straight Talk: The Hormuz and whether or not the strait is open for oil tankers will remain a catalyst for all global assets until clarity is gained. In the meantime a whirlwind of noise and threats from President Trump, the U.S White House and Iran will remain a menace for all traders – small and large. Is the Strait of Hormuz open or closed?

Copy and paste the text from AMT that you want to share

India Rupee 20260416

Progression Upwards for Indian Rupee and Catalysts

USD/INR Persistent Trajectory Remains in Force and Mid-Term Concerns

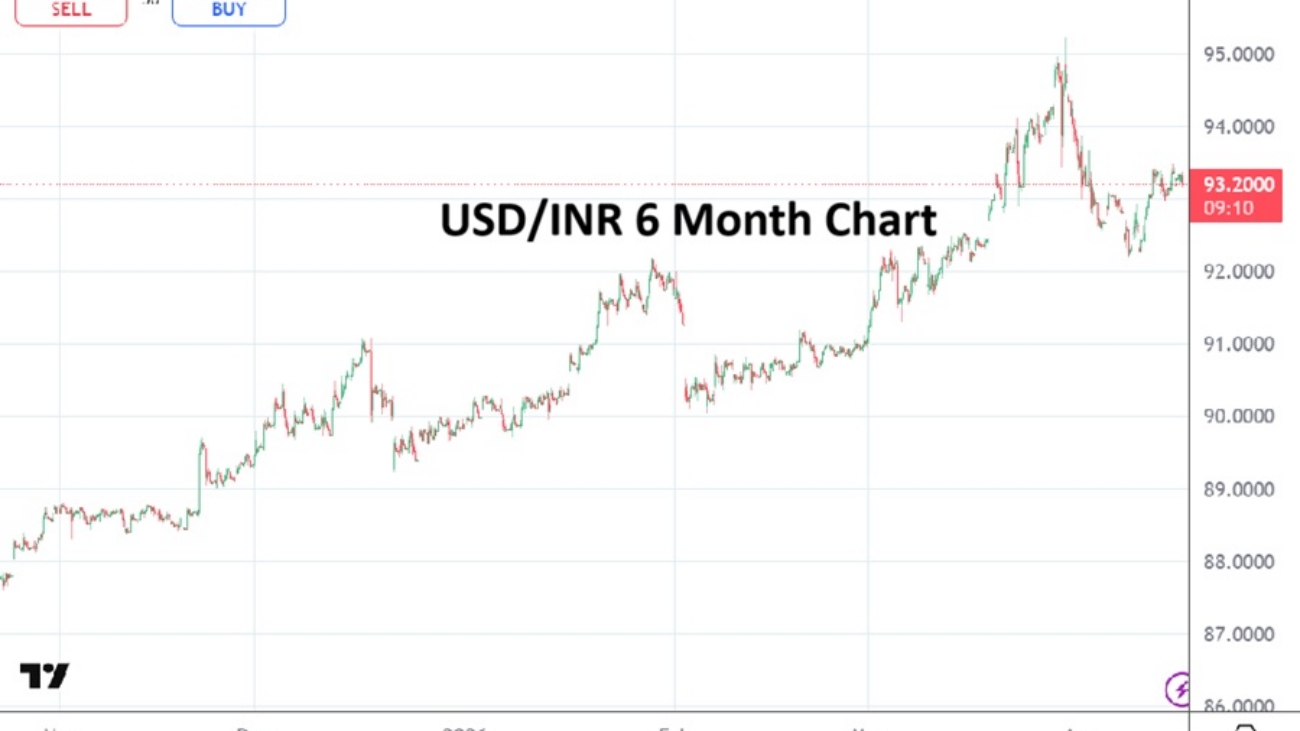
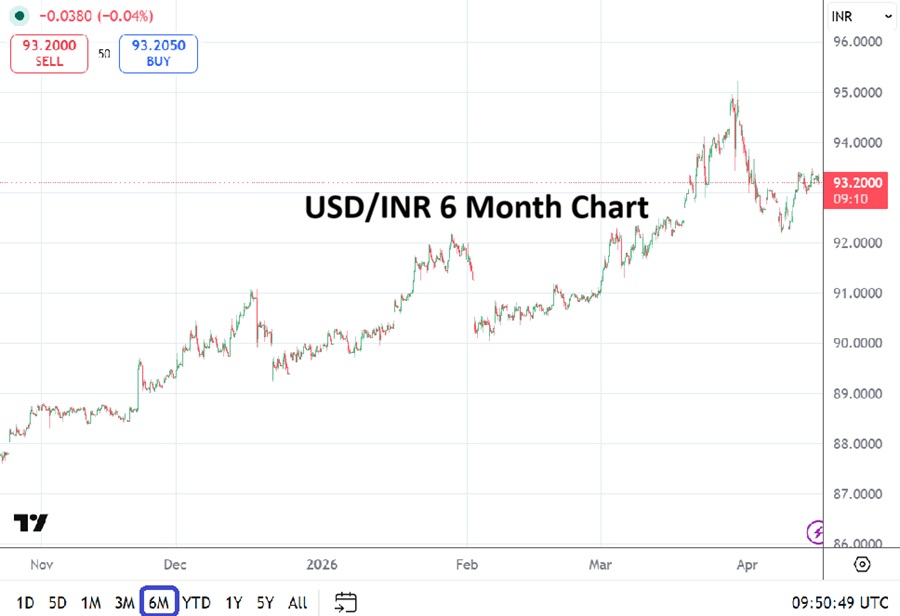
As of this writing the USD/INR is within the 93.2000 vicinity. The price of Gold is around $4,810.00 and Silver close to 79.50. Importantly, WTI Crude Oil is trading around $89.25. Global markets have turned in solid performances the past two weeks, this has been a two step progression for most investors. 

Indian financial institutions began to digest their worries regarding the Iranian war late in March – perhaps acknowledging the risks and ramifications, while adjusting outlooks. Then on Tuesday the 7th of April the establishment of a ceasefire was announced. However, after hitting a low of around the 92.2200 realm on the 8th of April, the USD/INR is back within higher ratios.

USD/INR Six Month Price Chart as of 16th April 2026

Yes, the USD/INR had been traversing above the 95.0000 ratio late in March, so it can be said the Indian Rupee has gotten stronger. Yet, there will not be many willing participants who will join a parade with the belief this lower trend can be sustained. The bullish trajectory of the USD/INR is not going to vanish.

On the 24th of October 2025, the USD/INR was near 87.7500. At this time last year the currency pair was close to 85.5000. A persistent and long-term move higher has been the theme in the USD/INR. Weakness in the Indian Rupee has been part of India’s economic story rather consistently for a handful of years. 

Narendra Modi has been in power since 2014, he is serving his third term as Prime Minister. His political party the BJP clearly has its chosen people within the Reserve Bank of India.

The government’s position of allowing the Indian Rupee to be weaker is not something they will want to state out loud as part of their mandate, but it is clearly not bothering them.

The pursuit of creating a stronger industrial and manufacturing base for India, including IT and software via good exchange rates for international clients is seen as a cornerstone to build demand. The quality of work and technology provided by the Indian workforce is good and this allows global clients to foster solid relationships with Indian companies.

However, the rise of the USD/INR to above the 95.0000 level in late March was a warning sign, that sometimes price velocity in Forex can become dangerous. And the Iranian war although enjoying a week and half of less noise, still could escalate into a problematic scenario for India that could cause additional concerns in Indian financial institutions who are trying to gauge their mid-term outlooks.

The USD/INR is an important part of this economic math and the prospect that higher energy costs, or in a worst case scenario – shortages incur hardship for Indian citizens and companies is an actual concern.

The current situation in the Hormuz Strait and availability of Crude Oil is significantly important for India. So is supply of LNG (liquefied natural gas) which Qatar, Oman and the UAE play a role. The supply of energy presents a glaring dark shadow for the prospects of the Indian economy should there be shortfalls. 

The 93.5000 resistance level has been durable since early April in the USD/INR. Stability of the exchange rate is crucial for a wide range of business in India, including banking and financial institutions active in the Bombay stock market – particularly since a weaker India Rupee opens the door to Forex concerns for foreign investors who do not have the ability to hedge if they are exposed via the INR too much. Foreign investors are needed in the Nifty indices to help values.

The near-term is likely going to remain a difficult path for the USD/INR and its outlook. The positive sentiment which has prevailed the past couple of weeks has been welcome and certainly stable conditions are hoped for so equilibrium can be kept. However, if the Iranian situation manifests into open military conflict again, or if there is a disruption of supply of energy that cannot be easily solved by India – then the USD/INR could once again face price velocity upwards that is uncomfortable.

While China may be getting the headlines regarding potential ramifications of its Crude Oil supply being threatened, India is estimated to have consumption that is ranked as the 3rd biggest globally. India’s ability to get a supply of energy from a diversified stable of sources is a key for the nation moving forward. 

The USD/INR will continue to move higher, the question is how fast? A slow steady rise in the currency pair – again, this will not be a spoken mandate by the Indian government – will continue. The fear of a rapid debasement is a concern. Financial institutions in India need steady emotions and are certainly hoping for the Iranian war to conclude with a sliver of optimism. 

Copy and paste the text from AMT that you want to share

postN87

AMT Top Ten Miscellaneous Morsels for the 12th of April 2026

Optimistic Hopes Appear Ready to Fade into the Distance

10. B-ball: The NCAA Men’s Basketball Championship concluded early last week with a rather resounding outcome for the University of Michigan who won their 2nd Men’s trophy, the first one coming in 1989. Michigan dismantled the Arizona Wildcats and then handled the Connecticut Huskies. The NBA playoffs will start this coming week. The Oklahoma Thunder and the San Antonio Spurs are getting a lot of attention, and the Denver Nuggets might have something to offer.

9. Trump: A week of optimism now leads towards threats of additional noise. Peace talks held in Pakistan appear to have failed this weekend, and now another countdown has begun as the Iranian conflict appears ready to escalate. The U.S White House and President Trump will certainly make more noise in the coming days.

AMT Top 10 for the 12th of April 2026

8. Logistics Advertising: Kit Kat and Nutella have been rewarded with massive exposure. The Kit Kat truck heist of 12 tons of product (reportedly said to be in a special F1 designed candy bar theme) made headlines. Kit Kat’s owner, Nestle, was obviously content with the free publicity and proof of demand. And a jar of Nutella floated across the Artemis 2 spacecraft unexpectedly this week, gaining international attention and sparking smiles from fans of the Italian chocolate hazelnut spread.

7. Creator: Yet another candidate accused of being Satoshi Nakamoto has been produced. Blockstream’s CEO Adam Back has been named by the N.Y Times as a potential creator. In the meantime, the real question is whether anyone but Iran (as they run their illicit shadow economy), Michael Saylor of MSTR and a few big whales consisting of institutions and hedge funds are really paying any attention to BTC anymore. The BTC/USD price as of this morning is around $71,600.00. Bitcoin was traversing near $126,000.00 in the first week of October 2025.

6. Greenback: USD/JPY 159.240, EUR/USD 1.17225, USD/ZAR 16.38540, USD/INR 93.0480. USD centric strength may prove solid this coming week and other currencies may suffer a bit.

5. Sideways Shimmer: Gold finished the week near $4.745.00, roughly $100.00 above its starting point last Monday. U.S 10-Y Treasury yields went into this weekend around 4.34%. Shifting outlooks this coming week will likely ignite turbulence in both assets.

4. Blind Eyes: More than a handful of U.S politicians have been featured as big winners regarding their stock trading abilities. Their gains far exceed the winning percentages of the overall returns made by indexes (as a benchmark). Little has been done to stop what many view as insider trading. There are many forms of political corruption around the world. However, a variety of places and people, including Americans seem to accept this potential misconduct. The ‘Stop Insider Trading Act’ has been brought forth in the House of Representatives and Senate, but the legislation may simply meet a slow death and disappear.

3. Inflation: U.S interest rates via the Federal Reserve will be held in check at a minimum over the next few months. The higher costs of energy will certainly seep into prices for transportation, manufacturing and agriculture. Fed Chairman Jerome Powell may be quite content to leave his position May the 15th. The next Fed FOMC interest rate decision is due on the 29th of April.

2. Strait of Hormuz: WTI Crude Oil closed above $90.00 going into this weekend. When futures markets open early on Monday, the price of the commodity is likely to rise via increased anxiousness which will build into the mindsets of large players today because of the failure of peace talks in Pakistan. The price of Crude Oil remained high last week, only moving to a low of around $85.00 this past Tuesday, showing cautious attitudes remained. Prices above $100.00 will likely become a new target quickly for some who bet. Will an early spike upwards this week then start a counter reversal lower, or will a climb become sustained?

1.  Risk Off: The S&P 500 and Nasdaq 100 will get plenty of attention this coming week as behavioral sentiment remains fragile. Having skirted near its 200-days moving average lows in recent weeks, the indices have gained handsomely since the 31st of March. Will the upwards momentum come to an abrupt end this week, or have financial institutions been able to digest their nervousness and will they show a capability of remaining buyers?

Copy and paste the text from AMT that you want to share

Gold 20260409

Intraday Blues as Trading Conditions Remain Perilous

Red Flags Persists for Day Traders and Hedge Funds as More Wild Surf Predicted

Risk on or risk off? Day traders and hedge funds, two groups who are known to speculate, have both suffered considerably the past handful of weeks due to the market turbulence. While falls of 4 to 5% the past handful of weeks for long-term investors can be digested with proper patience and accumulation ability, those who are using leverage or making monster sized bets on intraday speculation continue to suffer from widespread anxiousness within the marketplace.

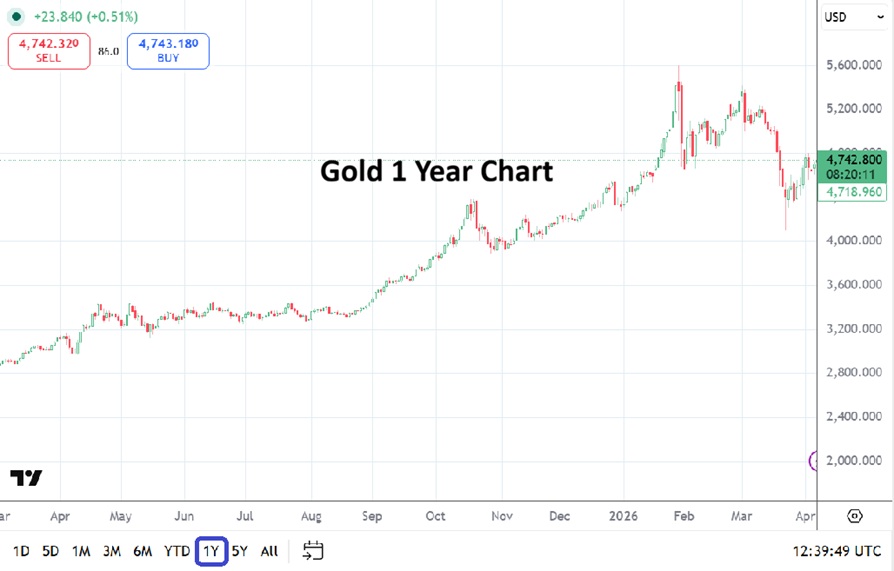
Gold One Year Chart as of 9th March 2026

WTI Crude Oil should have gone back down below $80.000 in many folks thinking – and they may have bet on this strike price via options –  due to ideas of an Iranian ceasefire, but the target has not been met. WTI did in fact challenge $88.000 early this week, but it is back around $93.000.

With the weekend quickly approaching and concerns about what will happen when the marketplace is largely shuttered, March mayhem has opened the door for April surprises. Gold is near $4,737.00, and this price remains mildly upsetting for many who believed it would act as a safe haven asset that would gain during the war, but hasn’t responded with buying fever. Gold was near $5,180.00 on the 27th of February. But in fact gold has performed rather well considering it was riding a long-term speculative buying spree and its current price still remains well above where is was last year around this time near $2920.00.

The point? The markets still exists and can still be bet on. The parameters may have changed, but let’s recall at this time last year global investors were dealing with the potential of Trump tariffs which was an entirely other set of hypersonic conditions caused by noise. If you don’t like loud markets you can cover your ears. You can try to take advantage of them too, but day trading the marketplace via Forex, commodities and stock indices has always been gambling. Perhaps this is what you are looking for – price action.

Again, the global markets are not concerned with your feelings. If you want to cry, grab a tissue and sit on the sidelines until the big show is over. However, know that the Iranian war is certain to have an encore from either a new round of potential fighting in the Middle East via stresses caused by the said openings/closings of the Hormuz Strait, or some other entirely new flashpoint elsewhere. 

The S&P 500 closed slightly below 6783.00 yesterday, last year the index was close to 5,745.00. Sometimes the best thing all traders and investors can do is take a deep breath and believe in better days.

Near-term price action will remain choppy. That is very easy to say and agree to, yet it tells you nothing. It doesn’t tell you what the markets are going to do today or tomorrow. And the reason for that is that intraday performance at this juncture is being driven by swiftly changing sentiment in which momentum is a swirling sea. Technical traders may claim they have a handle on the price skirmishes via their perceptions, but are likely suffering like everyone else as they try to surf the rather wild waves.

Copy and paste the text from AMT that you want to share

Markets Say 20260407

What Do the Markets Say?

Ambivalence Rules the Day

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 7th of April via The Angry Demagogue.

There is nothing we capitalists like saying more than “the markets say….”. What we mean is that the amorphous group of individuals and institutions that together form some sort of consensus as to the value of “things” taking everything known by the individuals involved into consideration. Since no one can know everything, the idea is that the market represents the sum of knowledge of everyone who has money to invest – or, as we like to say, “skin in the game”.

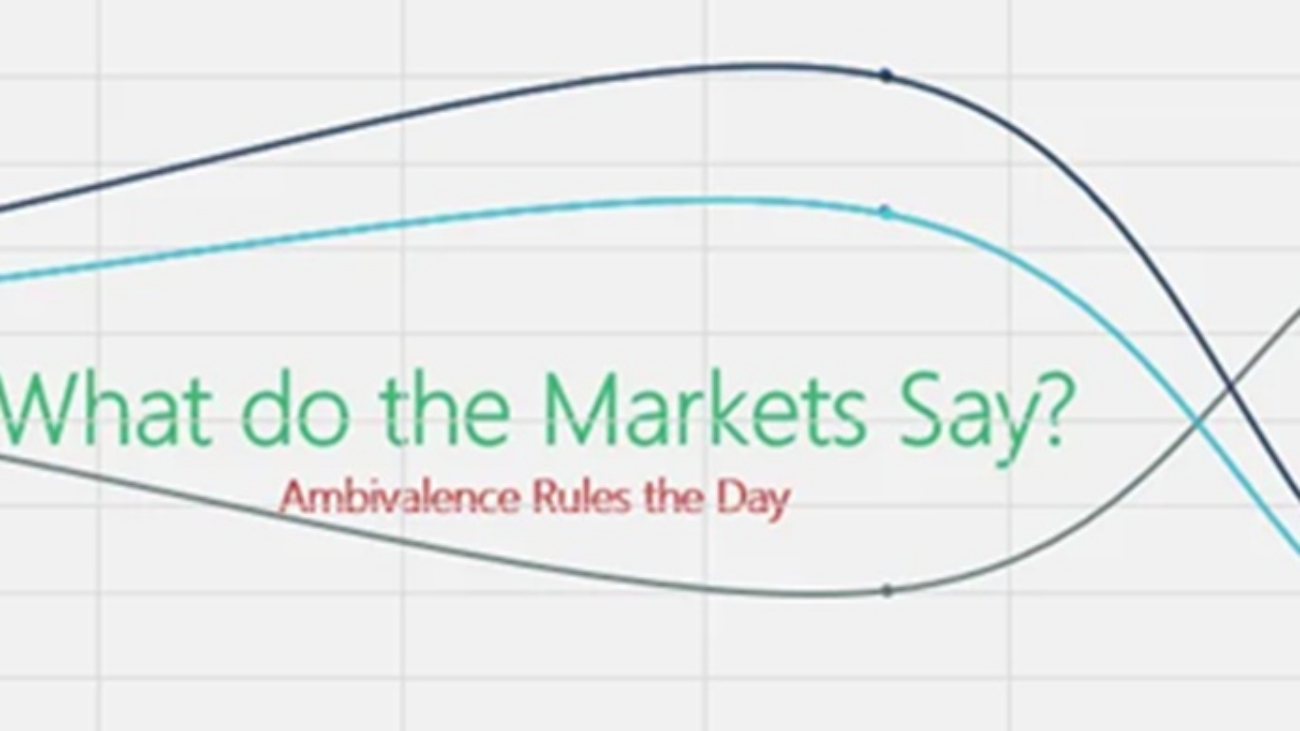
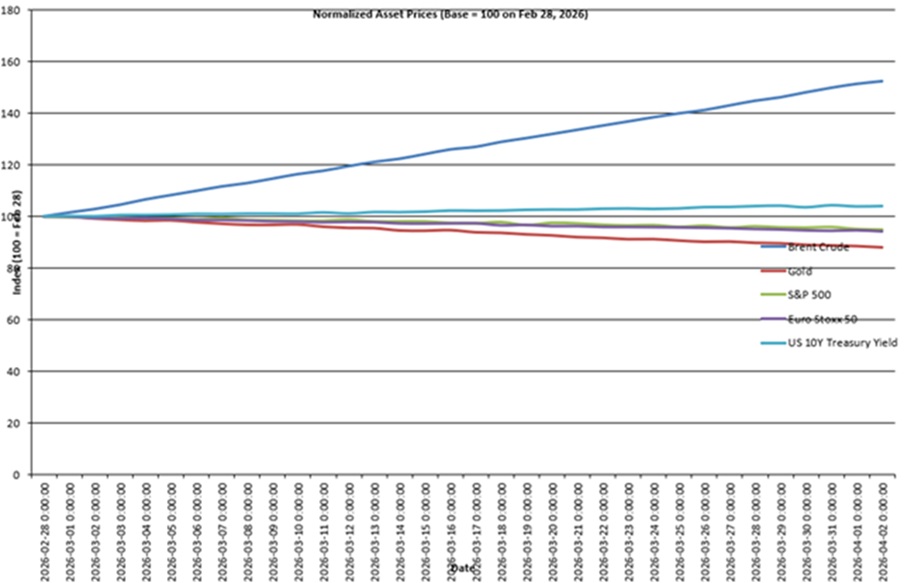
Below is a graph from the start of the war until April 2, of oil, gold, 10-Year U.S Treasury yields, American and European stocks. Each should tell us something and in general all together they should be saying the same thing. However – that is not the case here considering we are in the midst of a major Middle Eastern war, with China and Russia watching with interest and Western Europe squirming with unease.

Normalized at 100 via ChatGPT as source.

Those items that signify a flight to safety are the price of gold and the U.S Treasury yields, while those that signify a faith in the future of the economies are the index levels of the U.S and European stocks. A commodity that is directly affected, oil in this case, is expected to rise and it has, by over 50% since the start of the war.

While one would expect the price of U.S Treasuries to rise considerably as it is considered a “safe haven” by investors, it has risen just 4% as yields dropped from 4.31% to 4.13% (with bonds, prices and yields moving inversely. A rise in bond price is a decline is their yield – meaning they earn less for the bondholder). Gold, the other safe haven, though has dropped by nearly 12% since the start of the war. True enough, the price of gold has skyrocketed over the past year, but still while there is a reason why gold might underperform U.S Treasuries, it is odd that it has underperformed stocks on both sides of the Atlantic, in spite of the 50% increase in the price of oil – forcing up energy prices for industry. Stocks in the U.S have dropped by just 4.95% while in Europe the decline is just 5.8%. Neither number is one an investor wants to see in just six weeks, but all things considered the war has not caused a lack of confidence in the economies of the EU or the U.S.

People might claim that gold has lost its safe haven luster over the years, but that is not the belief of governments as India and China have been buyers of vast stores of gold and France decided to repatriate all of their gold reserves. They still see it as necessary.

So, what are the markets telling us about this war and the future of domestic and global economies? Regarding Iran, the supposed victors in this “quagmire”, the Iranian Rial has dropped 96.8% in 2026 and has moved from 0.00002378 to the dollar to an incredible 0.00000076 (that means that 1 million Iranian Rial equals 76 cents) the market speaks in one voice – no confidence.

Regarding the rest of the world the markets are not really telling us much of anything because there has not been a rush to safe havens as usually happens in wars and happened during Covid, nor has there been supreme confidence. The markets are, shall we say, ambivalent.

That volatility is high and that they move drastically on each Trumpian proclamation is more a sign that the algorithms that control the very short term market trends are mostly chasing the same thing. When X happens, sell Y is a race to the bottom by unthinking and unsophisticated (in spite of AI) analysis until that race causes the “when Y hits a certain price, buy it” or “when Z happens then buy A” algorithms kick in. After a few days or weeks, we can start to see trends as long as we ignore the record highs or lows. However, there is nothing other than “wait and see” ambivalence in the current market data.

While this does not necessarily mean that the “markets” are in support of the war, but neither does it see a debacle of any sort. The Libyan bombing campaign of 2011 lasted seven months with no real Western interests involved and the Kosovo ariel campaign of 1999 lasted around 3 months and involved humanitarian but not economic interests. The 6 weeks of this war, so far, is not at a level of “quagmire” for the markets.

If the markets are telling us anything now it is that while oil may stay high for awhile, the world is not heading south due to the war. This can change– for good or bad – but the markets themselves are not currently taking a stand either way. They are not telling us we are in for a rough ride. While we believe that this war will reshape global politics and alliances and create an economic boon for the victors, no one can be sure who will end up on top and who will suffer once the war winds down.

The defeatists around the western world could do worse than listen to what the markets are not telling us.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

You can follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

postN87

AMT Top Ten Miscellaneous Missiles and Missives for the 29th of March, 2026

The Iranian War Dominates our Lack of Humor

10. Final Four: The Men’s NCAA Basketball Championship will be set after today’s games. The Arizona Wildcats, our pick, advanced to the Final 4 by beating Purdue last night. Michigan is favored to beat Tennessee and the Duke vs. UConn game is anticipated to be close. The University of Illinois advanced by beating Iowa on Saturday and maybe the biggest underdog – if the Volunteers lose to the Wolverines today.

AMT Top Ten for the 29th of March 2026

9. Jobs Data: U.S Non-Farm Employment Change numbers will be published during a banking holiday on the 3rd of April, this as the Iranian war shadows investment sentiment. Will potential jobs numbers results create nervousness on Thursday, and side effects Monday the 6th of April? 

8. Private Equity: Outflows remain a problem for BlackRock and other firms as deal making comes under a bright light. Investors are questioning valuations, lack of exits and money that sits in ‘zombie’ funds. Imposed limits on redemptions by some firms have created nervous indicators. Is the private equity problem correlated to lackluster momentum on Wall Street, this as desire for the next big thing runs out of marketing hyperbole?

7. 10-Y Notes: U.S 10-Year Treasury yields finished the week near 4.43%, Friday’s price action saw an apex around the 4.48% vicinity, highlighting nervousness. On Friday the 27th of February 10-Y yields were close to 3.94%,

6. Forex: USD/JPY ended this past Friday around 160.250, making it cheaper for tourists to visit Japan as cherry blossom season starts this week and lasts into early May. However, the Bank of Japan and Japanese citizens are not amused by the weakening Yen. USD centric strength continues to resonate loudly. 

5. Fed: Potential drama surrounding the U.S central bank and the replacement of Fed Chairman Jerome Powell has taken a backseat to the Middle East conflict. Concerns about inflation are legitimate. The Federal Reserve will be hard pressed to defend an interest rate cut in the mid-term.

4. President Trump: Speaking from both sides of his mouth (and his opponents might say another area of the body) may be strategic genius from the White House regarding Iran or prove to be a lack of focus. However, it certainly keeps everyone guessing what is going to happen next in the Middle East.

3. $100.00: WTI Crude Oil prices have remained below the one-hundred level for the most part during the Iranian war, yes – there have been outliers above. Will we begin to see sustained prices above the century mark this week? Short-term reactions to the U.S military potentially seizing Iran’s Kharg island would certainly cause price chaos, but could it also soothe some large players in the energy sector via mid-term outlooks? 

2. Good Friday: The holiday at the end of this week will be effected by anxious behavioral sentiment. The potential of a long weekend with plenty of noisy chatter could make for nervous investors this coming Thursday as they position themselves ahead of possible escalating storms.

1. Fear: The S&P 500 and Nasdaq 100 have entered corrective depths. Who will be brave enough to start looking for bottoms as the Iranian war rages with no end in sight? Will a reversal upwards emerge this week?

Copy and paste the text from AMT that you want to share

postN87

AMT Top Ten Thoughts and Trepidations for the 22nd of March, 2026

The Return of AMT's Top 10 Illustrious 'Weekly' Salvos

First we must congratulate those who were willing to climb out from under their rocks (and bomb shelters) to offer musings. But let’s not digress….. to the AMT Top Ten List we go.

AMT Top Ten for the 22nd of March 2026

10. March Madness: The NCAA Men’s Basketball Championship is underway. Some of the more hated schools remain catalysts. Our pick, the University of Arizona Wildcats. 

9. Bitcoin: Traversing above 68,000.00 USD currently almost feels like an accomplishment considering BTC/USD was near 63,000.00 in early February and again in early March. But do not blink your eyes. BTW, MSTR (the much loathed MicroStrategy by some AMT folks) went into this weekend below $136.00 per share.

8. South Africa: The USD/ZAR finished Friday near 16.96800 depending on bids and asks. On the 29th of January the currency pair was close to 15.65000. The South African Rand has done well over the long-term, but it is correlating to the broad Forex market concerns. Day traders should not take things personally, and accept that risk adverse moves – particularly as a major war rages is part of speculation. Near-term viewpoints can differ with long-term prospects. 

7. Not Glimmering: Gold at the start of the Iranian war was around $5,260.00, it has fallen to a mark of $4,491.00 this weekend. Showing gold’s speculative momentum beforehand hand, outmatched current values. Where next?

6. Silver: Above 120.00 USD briefly towards the end of January, the commodity is below 68.00. Wild betting has caused a drop of more than 42%. Too much exuberance.

5. Risks: U.S 10-Year Treasury Yields were below 3.95% on the 27th of February, via Friday’s close rates are above 4.38%. Can you spell f.e.a.r?

4. Safe Haven: The U.S Dollar Index which had been showing solid downside is near 99.500, on the 27th of February it was around 97.850 – a rather legitimate rise. 100.000 may be a target by some large players.

3. Shrieking Hyperbole: WTI Crude Oil prices are certainly getting plenty of attention. However, voices expressing concern about WTI touching higher values starts to sound like an auction in order to get attention for the circus barkers. WTI remains near 100.00 USD and this mark is a barometer. The price is high and it can go higher, but expressed fear about $140.00 and $200.00 should be treated with disdain in the near-term.

2. Iran War: The conflict in the Middle East cannot be downplayed, but it can become fearmongering by Cassandras’. The U.A.E is still open for business and other nations in the Middle East are functioning. Yes, there is noise and the situation can grow more dangerous. But the potential of freedom for the people of Iran is a solid goal, though some may find this naive until it is proven. Can it become fact?

1. Coming Attractions: U.S stock markets are rightfully nervous. Friday’s close for the S&P 500 has brought it into terrain that challenges its 200 day moving average. The combination of weak technical attitudes and behavioral sentiment is a dangerous mix. Risk management may not be enough for day traders to survive current conditions, sitting on the sideline instead of betting on equity indices intraday may be more efficient and less lethal.

Copy and paste the text from AMT that you want to share

post273

China’s Economic Future: Speculation & Transparency Question

China's Economic Future: Speculation & Transparency Question

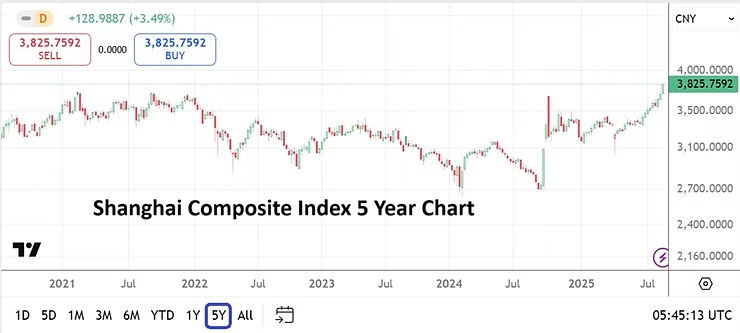
China’s economy has been underperforming for a handful of years. Growth has not only stagnated but has experienced a downturn, deflation has been experienced. Strong leadership from Xi Jinping has led to a firm approach regarding the management of China’s political and economic affairs. Until this year, Xi’s grip on power had grown significantly since he took office as the President and General Secretary of the Chinese Communist Party in 2012, but his control appears to be waning. Yet even as lackluster Chinese economic data has persisted, the Shanghai Composite Index (SSE 000001) has mirrored many global equity indices and done remarkably well since April of this year.

The SSE is near 3,826 currently. In early April the SSE was around 3,080, and in the middle of September 2024 the Shanghai Composite Index was close to 2,700, which was clearly within sight of long-term lows. The current heights of the SSE have not been seen since August of 2015. Yes, the Shanghai Composite Index was over 5,000 in April of 2015 and also in 2007. The point being that highs being traversed have not been seen in a long time. But is the positive speculation in the SSE a sign that economic conditions and political considerations in China are positive? Where is the transparency?

Shanghai Composite Index Five Year Chart as of 24th August 2025

China’s ability to create significant growth over the past four decades has transformed the nation into a global powerhouse economically and militarily. Yet, the past few years have begun to show cracks in the single handed approach to centralized decision making regarding the economy, government data presented has become suspicious. Rampant speculative forces in the SSE have been seen before. Is now the time to buy more Chinese equities or is it time to become cautious? Reliable statistics remain a troublesome aspect for investors.

China’s real estate market collapsed under the weight of too much building and speculative buying of apartments. Yes, inflated property and sudden deflation has been seen in capitalist countries in the past and will be witnessed again in the future. But the bubble in Chinese real estate and its crash also points out problems regarding a lack of transparency. While the Chinese government has tried to fix the fiscal problems caused by the real estate implosion, it has also created significant fractures within its banking system, which are confronting the Chinese government and public, and sometimes feels like a coverup trying to hide bad news. When will there be a recovery in the China real estate sector, is the worst of the crisis fixed?

Chinese political questions and some evidentiary circumstances point to intriguing considerations. There is evidence in China that a change of leadership is progressing. In the past couple of months small hints have been allowed to be published via China’s state media, the Xinhua News Agency. Rule changes have been made regarding decision making processes in the Chinese Communist Party, this was published by Xinhua in late June and republished by the South China Morning Post of Hong Kong in early July. While paraphrasing, both news entities expressed that rule changes meant Xi Jinping would officially have to delegate more decision making.

USD/CNY One Year Chart as of 24th August 2025

Speculation is growing beyond a mere whisper that the Chinese military has become a wildcard and a source of power that is potentially ready to help remove Xi Jinping. The military apparently is not supporting Xi and wants a more collective approach to decision making via the Chinese government. Yes admittedly, this information can be described as being from news services and podcasts that do not favor the Chinese government, but they seem to be singing in unison. It appears that China’s People’s Liberation Army have decided it is time for a change and is ready to play a role in the selection of new Chinese leadership.

The 80th Anniversary Victory Day Parade in Beijing will be held on the 3rd of September, what role will Xi Jinping play in the show of military force? Will it become apparent that Xi is merely a figurehead until an official decision is made on how the Chinese Communist Party will be led? Importantly, the 15th Five Year Planning Conclave for the Chinese Communist Party will be held in October and this is where a leadership change could take place including the official removal of Xi Jinping.

There appears to be – yes, via the dissident information heard, two factions within the Chinese Communist Party vying for power – hardliners and reformers. The army still hasn’t made it clear if they are backing the hardliners or the reformers. What is evident however via many publications, is that China’s PLA has decided along with other important leadership circles in China’s Communist Party that Xi had too much control and they want a more collective leadership.

Regarding the Chinese economy which has undergone a period of stagnation and lackluster results the past handful of years under Xi’s strong centralized approach, something big is about to happen which will have ramifications for the next five years. Who will lead China? The hardliners who are true believers in ideological communism or reformers who want China to move towards more of a market economy? This is a huge question. This type of political infighting has been seen in China during the past four decades and played a role in key leadership changes. It is not a conspiracy plot which is being sounded, it is the possibility of a transfer of power which happens cyclically in many nations when changes are warranted.

China’s Shanghai Index has done well recently. Perhaps this is a correlation reflecting optimism being sparked globally in equities in recent months. Or is it also possible that some folks in the know are betting on the reformists to take control of the Chinese government? Tariff concerns have seemingly been brushed to the side in China and something bigger is certainly at play. President Donald Trump is not the story here. Investors participating in China need to pay attention to the political changes that seem to be brewing. While speculation has certainly brought the Shanghai Composite Index to long-term highs, transparency from China is a concern economically and politically and there will be an impact if changes to leadership occur.

post203

AMT Top Ten Miscellaneous Picks for the 26th of April 2024

AMT Top Ten Miscellaneous Picks for the 26th of April 2024

10. Salk Institute: Work known as the Harnessing Plants Initiative is focused on optimizing the ability of plants to help combat climate change, sometimes via root systems in order to help reduce carbon dioxide. Problematically when plants die they do release carbon dioxide too. One key to the HPI project maybe altering the affects of Suberin. The Salk Institute received 50 million USD last year from the Hess Corporation to fight climate change.

9. Anticipation: Chicago is celebrating today after landing quarterback Caleb Williams and wide receiver Rome Odunze as hoped. However, as the August 2024 Democratic National Convention approaches, trepidation for the potential of nasty demonstrations is building.

8. Quantum Investing: Oak Ridge National Laboratory has announced a successful test using the H1-1 computer via Quantinuum to study the spread of disease via quantum mathematical models. Honeywell International Inc. owns a large stake in Quantinuum which is a stand alone company valued at approximately 5 billion USD.

7. Speculative: Gold is near 2348.00, the price is below values seen last week, but remains high via some perspectives as the USD creates havoc.

6. Forex: Whipsaw volatility has been seen in foreign exchange as financial institutions fight to get a proper gauge on their mid-term outlooks. Equilibrium will continue to be fought over today.

5. Fixed Income: U.S Treasury yields are battling within higher ground as investors look for guaranteed returns as behavioral sentiment remains fragile. And there is a likelihood the next four days of trading will continue to produce a whirlwind.

4. Equities: Major U.S indices continue to grapple with headwinds caused by a murky economic outlook. Retail traders speculating via CFD’s should remain careful. Patience is a key for the S&P 500, Nasdaq Composite, and Dow 30. Trying to ‘time’ the indices for short-term wagers is dangerous because technical trends are vulnerable.

3. Data: U.S Core Personal Consumption Expenditures Price Index statistics will be released today, inflation via the GDP Price Index came in higher than expected yesterday. Forex will react to the PCE results which is anticipated to have a gain of 0.3%. Financial institutions do not need another scare today. The Revised University of Michigan Inflation Expectations reading should also be given attention which will be published afterwards.

2. BoJ: The Bank of Japan is clearly playing a game of truth or dare with Forex. Having held interest rates at merely 0.10% earlier today, the USD/JPY climbed comfortably above 156.000 and is presently near the 156.540. The BoJ will remain in the news as the USD/JPY trades around a 34 year high. As financial institutions clamor for a higher interest rate, the BoJ apparently is more concerned with creating dynamic export demand and growing Japan’s economy, believing it can keep inflation under control. Speculators need to be on alert for an intervention from the Bank of Japan, but cannot count on one either.

1. Analysis Paralysis: The Federal Reserve was served an intriguing dose of results via the lower than expected growth numbers from the Gross Domestic Product yesterday, while digesting a higher GDP Price Index. Jerome Powell has stressed caution and patience. However, yesterday’s stubborn inflation numbers with waning growth creates the prospect for stagflation. This is an important political year because of the upcoming U.S elections in November. Next Wednesday the Fed’s FOMC Meeting pronouncements will be made. There will not be a change to the Federal Funds Rate on the 1st of May. It is the FOMC Statement’s vocabulary which will get attention. Today’s inflation reports will play a role in next week’s Fed meeting. Day traders may want to tune out political noise from pundits today which will certainly be sounded. The inflation numbers globally are tricky, and have created overthinking by investors and central banks which remain mostly reactive.