Nifty 50 20260708

India Insider: Foreign Investors and Their Selective Choices

Return of Global Investors into the Indian Marketplace

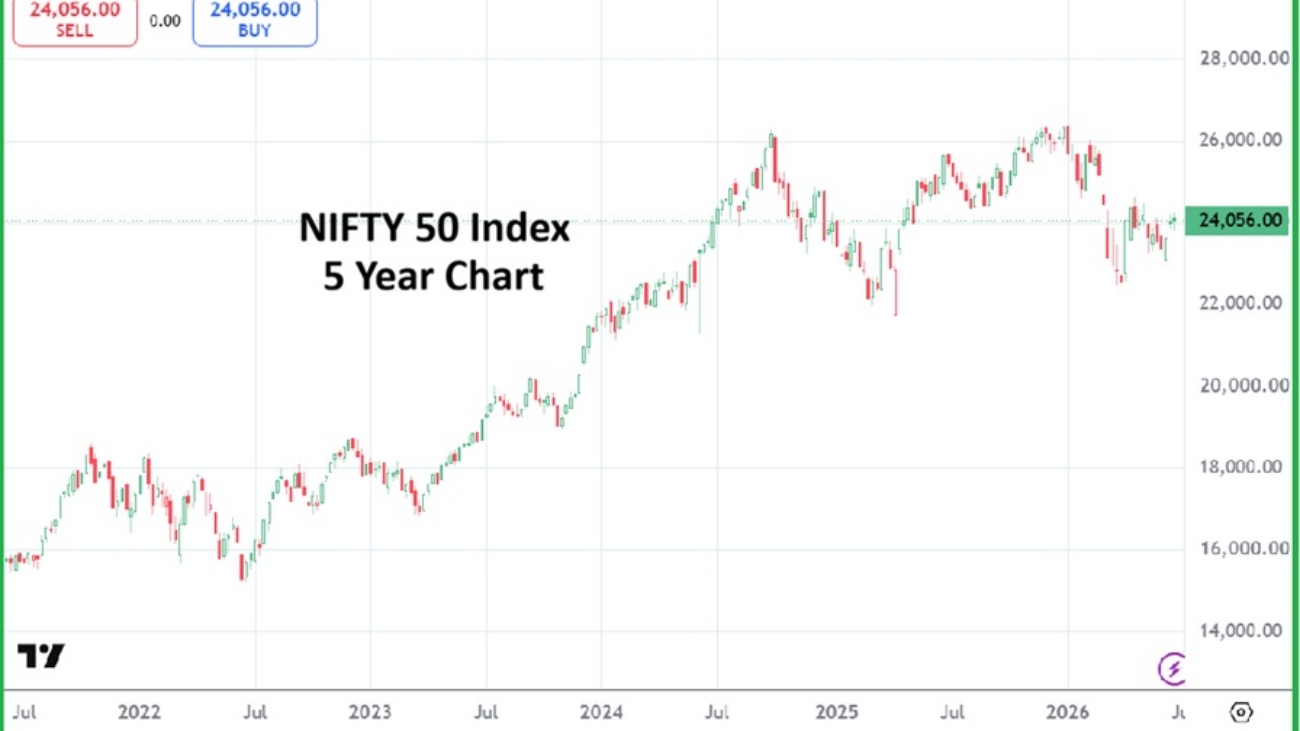
Global investors are gradually returning to Indian assets after months of persistent outflows as risk appetite sentiment has been ignited by an extended ceasefire between the U.S and Iran. Energy prices have moved in India’s favor, sparking favorable conditions. 

Despite recent flare ups in the Strait of Hormuz, Brent Crude has dropped about 30% in the past quarter, easing India’s fuel concerns as the world’s third largest Crude Oil buyer. AI trade rotation is gathering pace in Asia also, this as investors pull money from chipmakers that powered this year’s rally and hunt for cheaper ways to deploy their cash.
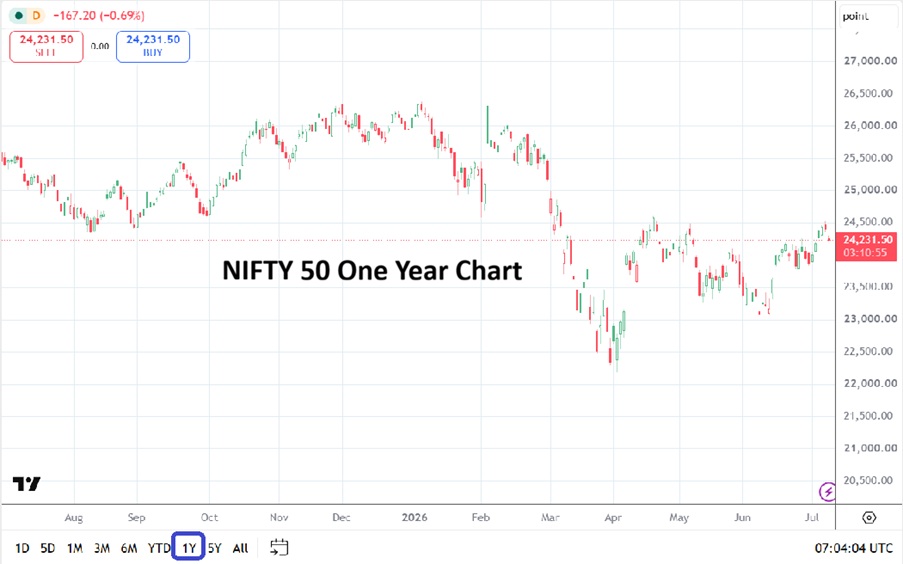
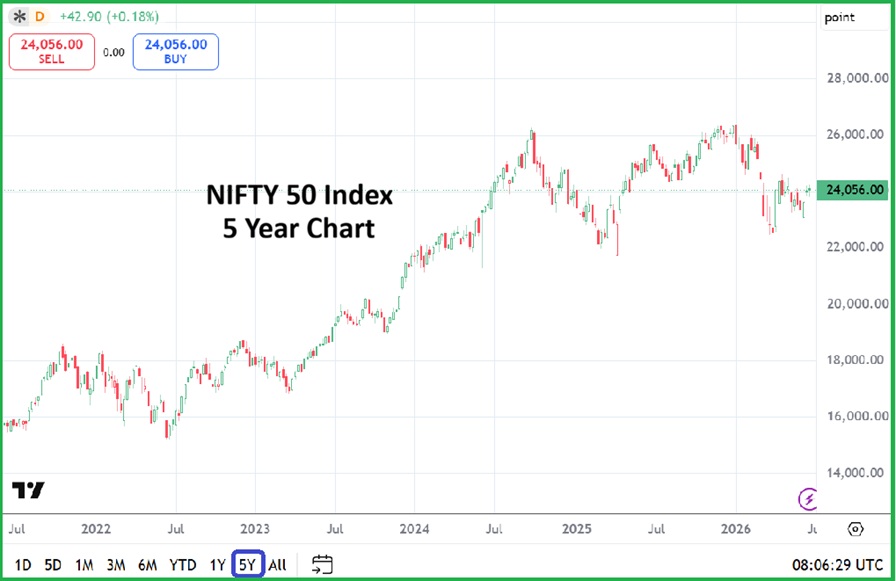
NIFTY 50 One Year Chart as of 8th of July 2026

Indian equities beat its emerging markets peers in June by its biggest margin in seven months. The Reserve Bank of India’s measures to attract foreign currency deposits and overseas capital have eased funding concerns for lenders, record foreign inflows into government bonds have helped stabilize the Rupee and improve liquidity conditions. According to Bloomberg, “Goldman Sachs favors 30-Year government bonds as lower oil prices allay inflation and fiscal risks”. 

Combined with resilient credit growth and improving asset quality, India’s banking sector is once again attracting global investors, this after trading at meaningful discounts to historical valuations for quite a while.

Second Opportunity May Be Information Technology

Indian IT companies have undergone a sharp valuation correction over the past two years. Unlike the post pandemic period, when large Indian technology firms traded at substantial premiums to global peers such as Accenture. These premiums have now narrowed considerably after earnings growth slowed, and enthusiasm surrounding Artificial Intelligence shifted investor attention towards US technology companies.

As highlighted in Business Line magazine, the sector is undergoing a healthy valuation reset, with investors increasingly questioning whether premium valuations remain justified without a corresponding acceleration in earnings growth.

However, the discussion extends beyond valuations. Artificial Intelligence is fundamentally reshaping the enterprise software industry. For decades, Software as a Service (SaaS) companies dominated enterprise technology by offering standardized cloud based solutions that were cheaper and easier than developing software in-house. That advantage is now beginning to erode.

Large AI companies such as OpenAI and Anthropic are building AI agents capable of operating across multiple enterprise applications through a single conversational interface. Rather than competing within individual software categories, these horizontal AI platforms could reduce the importance of stand alone enterprise applications by seamlessly connecting them. At the same time, AI native startups are targeting specialized business functions, while advances in generative AI are encouraging enterprises to revisit the traditional ‘build versus buy’ decision as they develop customized software internally at significantly lower costs.

For Indian IT services companies, this represents both a disruption and a new opportunity. Routine application development and maintenance may become increasingly automated, placing pressure on traditional outsourcing revenues. Yet demand for AI integration, cloud migration, cybersecurity, enterprise transformation, and customised AI deployment is likely to create an entirely new investment cycle. The winners will be firms that evolve from conventional software service providers into strategic AI implementation partners.

Risks ahead for Indian Markets

The near term outlook is not without risks for India. A weak monsoon could push food inflation higher. Elevated Crude Oil prices may widen India’s external balances. And a stronger USD with elevated U.S interest rate yields could moderate foreign capital inflows. The technology sector also faces a structural challenge as Artificial Intelligence reshapes the traditional software business model, requiring companies to adapt more quickly than in previous technology cycles.

Even so, the broader macro backdrop appears to be improving. Policy measures have eased liquidity conditions, corporate balance sheets remain healthy, and valuations across several sectors have become considerably more attractive after an extended correction. Rather than chasing expensive momentum trades elsewhere in emerging markets, global investors may increasingly look toward Indian sectors where fundamentals are strengthening while expectations remain relatively subdued.
Copy and paste the text from AMT that you want to share

Nasdaq100 20260707

Benefits of a Moderate Restoration While Threats of Growing Fissures are Heard

Sentiment: Financial Institutions and November Outlook Amidst Possible Gridlock

The Nasdaq 100 is clearly being driven by behavioral sentiment at this time. Few investors are paying attention to corporate data, instead many financial institutions are wagering on mid-term outlooks driven by a combination of algorithmic led coding mixed with wishful thinking and hoping they are not washed out to sea by dangerous tidal pools they know are out of their control.

On the 3rd of November 2026, the U.S mid-term elections will largely be held. President Trump’s hold on the House of Representatives looks as if it may come undone as a result of the coming vote if the Democrats take control as some polling suggests.

Perhaps that is exactly what investors are hoping for because historically when there is a divided Congress legislatively, stock market indices actually tend to gain. The reason for this is largely because a paralyzed Congress often finds it hard to pass measures which can hinder corporations and investors, because regulatory mandates are difficult to pass.

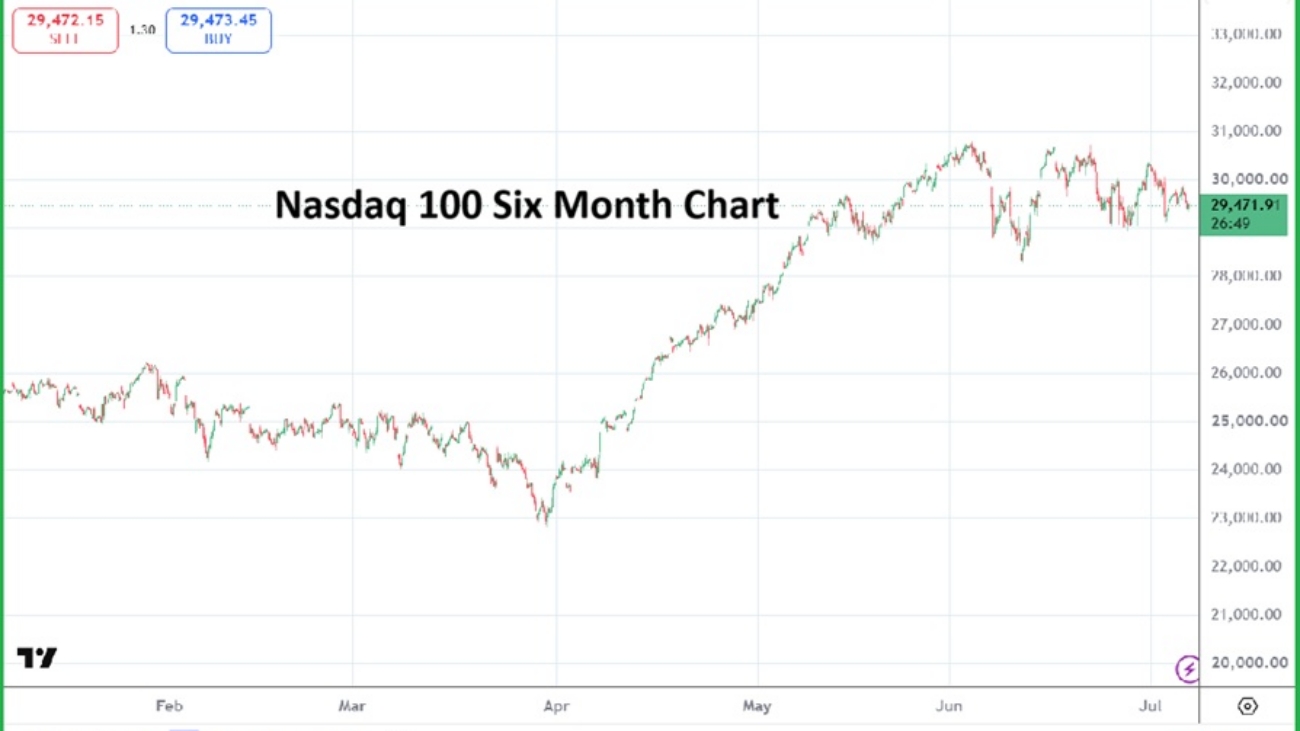
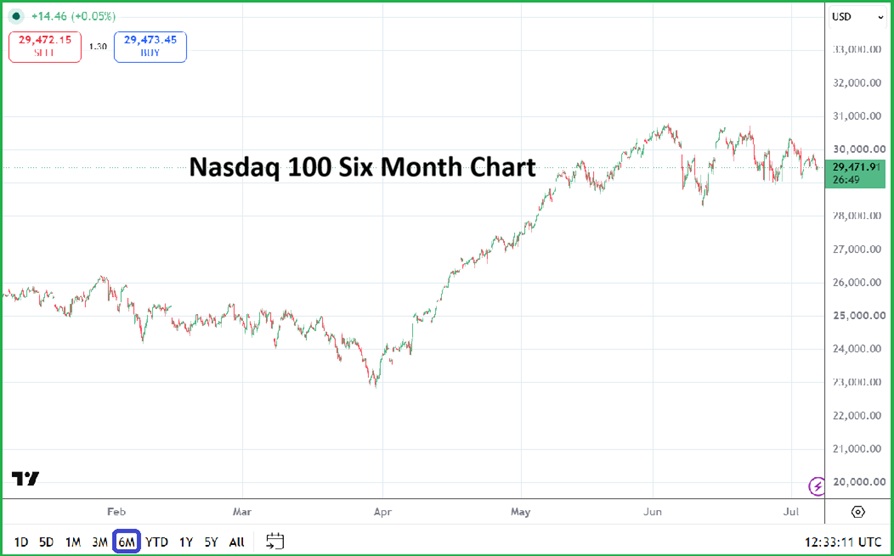
Nasdaq 100 Six Month Chart as of 7th of July 2026

If the Democrats win the House and President Trump is able to retain a Republican led Senate, this will lead to a deadlocked Congress which will make it hard to get work much done. Resulting in what may become one of the more memorable lame-duck Presidency’s of our time, one in which both sides of the U.S Congress openly disagrees with Trump’s ego driven rhetoric and instead turns to the backing of voters from their constituent state’s as a way to amplify their own policies.

While the Republicans appear potentially vulnerable in the November elections, the Democrats have problems of their own. An open fissure has been displayed as Socialists inspired candidates have won primaries in a handful of Democratic led Congressional districts and appear ready to splinter their political party regarding direction. What does any of this have to do with the economy and markets?

Perhaps this is exactly what crowds of investors in global markets, including Wall Street wants to happen at this point. Politicians forced to retreat to return their homes and become less vocal publicly may be a welcome remedy. Folks are starting to tire of political rabble, a crowded intersection of gridlock may be welcome at this point.

Unknowns: A Source of Concern for Investors

While it is certainly within the arsenal of the Trump Presidency to try and issue executive orders to try and get policies approved and acted upon. A split Congress, one in which Republicans can openly disagree with the White House without the fear of a political backlash may cause ruptures and positive outcomes for the GOP, if President Trump is weakened after the mid-term elections this November.

Democrats, particularly if they clash internally on their pronounced policies and have to spend more time trying to put out their own progressive internal fires may have to realign their thinking and walk more moderate lines. Activists on both sides of the political aisles may have to lessen their banter following election outcomes if they believe their voting public wants less noise.

A lame-duck President, could equate into a deadlocked Congress and debates simmering within each party which produce more moderate stances. However, if nothing is settled in November of this year this may lead to betrayals and revenge politically and potentially new leadership emerging which could be even more cynical, ignorant and insistent on false narratives.

Intriguingly, Wall Street will not be bothered by a deadlocked Congress and President who suddenly is limited by eroding power. In fact the conditions of withered post-revolutionary zeal and a slumber which could develop may allow corporations and investors to move freely about the ruptured political landscape with more liberty amidst the chaos. Investors will react to the sentiment that Washington D.C produces. A calm is wanted.

Within the ashes of Republican and Democratic turmoil a reconciliation may actually be able to take place. The question is if a restoration of moderate power will be finally be seen. Wall Street and most global investors would like a return of the centrists. No one is going to agree 100% of the time on policy, but a reality of transparent government without corruption would be a good start, one that many people actually would agree upon.

Copy and paste the text from AMT that you want to share

Nifty 50 20260626

India Insider: Systematic Investment Plan Boom

Liquidity, Valuations and the Limits of Domestic Capital

India’s equity market has surprised many investors over the past two years. Despite persistent foreign institutional investor selling, weak net foreign direct investment (FDI), subdued private capital expenditures and a depreciating Rupee, the broader markets have not fallen and proven remarkably resilient. But risks abound.

Many observers point to the rapid growth of Systematic Investment Plans (SIPs), which millions of retail investors invest regularly via mutual funds in India. Monthly SIP inflows into the Indian equity market has reached record highs at the tune of 32,087 Crore Rupees ($3.38 billion USD) in March, 2026 per AMFI (Association of Mutual Funds India) data. 

Nifty 50 Five Year Chart as of 26th June 2026

Before COVID-19, the stock market industry in India was a boring business. Accounts were opened via paperwork, and demat (the account in which the digital shares were held) in a bureaucratic manner with multiple paperwork requirements. Clients who liked to participate in the Initial Public Offerings (IPOs) had to go to their broker or issue a cheque to participate in the bidding process. As of 2019, the total demat accounts in India stood at 40 million. Sophisticated retail investors would go to their local branches of associated brokers and trade stocks, derivatives or commodities. They sometimes would use telephone or online orders.

All this changed during the Covid-19 pandemic, when equity market valuations became depressed and people were forced to stay at home. This ushered a wave of new retail traders who had time to master the game and wanted to capitalize on the falling valuations of many companies and take advantage of opportunities they believed in. Astonishingly, demat accounts opened between 2020-2026 totaled around 180 million, almost quadrupling pre-Covid levels. Due to digital penetration and the rise of discount brokers, young retail traders were able to quickly allocate substantial portions of their monthly income into SIPs.

SIPS have strengthened the financial market resilience of India, compared to the previous decade when it was the domestic institutional investors who helped market stability. Yet concerns are now arising whether domestic household savings are supporting fundamentally stronger companies, or are creating systematic inflows which help tenuous companies to have higher valuations?

For instance, a famous financial markets journalist recently argued that India’s SIP boom has fueled expensive stocks. Thus, enabling insiders and institutions to exit at favorable prices, reduced future return potential, has weakened the Rupee, and exposed the limitations of crowd-driven investing.

As the AMT India Insider columnist, I decided to investigate these considerations and talked with some people in the financial markets who offered different perspectives regarding the issue.

Mr. Mahalingam, an IIM alumnus noted, “it is difficult to generalize like that. Total SIP inflows should be viewed relative to the total market capitalization of listed companies, not in absolute terms. If the Nifty delivers around 12% returns, it roughly doubles every six years. SIP inflows must also increase over time, simply to purchase the same proportion of shares.”

Arguably, the SIP flows into the Nifty Index some 15 years back are not comparable to today. Considering the higher capitalization of Nifty listed companies (which means greater share values), and given the Nifty index has delivered 12% returns in the last few years, and that it took 6 years for it to double at this rate, it’s important that investors look at higher share prices values arising out of company earnings while considering their investment decisions.

Mr. Prasath, who taught economics and finance to students during his tenure at a private educational institution, argues, “I think there are many dimensions. In stock markets, everything comes down to valuations, the continuous SIP flows may diminish future returns if the earnings don’t grow. But comparing SIP flow with 2005 numbers exaggerates the issue. The Indian economy has grown bigger since 2005 and naturally inflows will also grow accordingly. India has one of the lowest public participation in the capital markets, even with current SIP numbers.”

Mr. Prasath continued, “currently the world is going through turbulent times with the Russia-Ukraine war, the Trump Presidency including tariff actions, the Iran situation and energy crisis, and supply chain disruptions, etc., which are effecting economic growth. The Indian government is also not taking some required steps. Indian companies also have low R&D and failed to participate in emerging themes like AI and semiconductor development. These turbulent times will continue for awhile and Indian markets will underperform its peers. So we have to wait for better times or for world leaders to come to their senses. I think we have to remain both optimistic/realistic and plan our investments accordingly”

If India grows at 7.7% during the 2025-2026 annual year, and foreign capital (especially foreign portfolio investment) is leaving, while private capital expenditures are weak and government capital expenditures are increasing, then what’s the point of higher stock prices for many of these companies? Is it due to steady retail SIP inflows? Does it really help institutions and insiders to cash out, and make retail investors vulnerable?  Foreign investors have sold $29 billion USD worth of equities so far this year, and the Rupee has taken a hit, yet we have not see drastic changes in companies’ share or indices values.

In 2022, when the U.S Federal Reserve was raising interest rates, the Nifty 50 Index lost around 3000 points, but this did not happen in 2026. The SIP retail crowd and domestic institutional investors have absorbed the foreign investors’ outflows and provided a cushion for share prices.

Even if some people in the financial markets argue that the foreign investors’ selloff off did not result in poor corporate performance or themes becoming weak, given that the growing market capitalization and the past earnings has justified the higher share prices, it’s significant to note that the Net FDI remains weak. Indian and foreign corporations are repatriating cash at a faster pace, and capital is flowing out of India. That’s ironically what hit the Rupee this year, along with higher oil prices due to the Iran war. In my opinion, private capital expenditures of listed corporations has to grow to justify higher earnings multiples.

Kotak Mahindra Bank director Paritosh Kashyap, while talking to Business Line said that private capital expenditures in India has been subdued for the last 10 years. Higher interest rates, expensive oil and lower equity valuations has dampened sentiment. India’s government Capex (capital expenditure strategy) remains the primary driver.

To summarize and conclude, weak foreign direct investment, subdued private investment, and inflated valuations of Indian assets along with a lack of AI related development is a large underlying issue and concern. For foreign investors to return with greater force again into Indian equities, either the Rupee has to depreciate or equity prices have to decline to generate investor confidence and create an appealing landscape. Retail investors may soon have to face drawdowns in their portfolios as returns dwindle and headwinds move against them.0

Copy and paste the text from AMT that you want to share

AI Aluminium 20260624

The Great Compression Part 2: The Intelligence Trap

AI Aluminum

On June 17th, the U.S. Air Force handed Anduril Industries a contract for its FQ-44 autonomous combat drone, making it the first new entrant to win a U.S. fighter aircraft program since the 1970s. The Silicon Valley startup beat Lockheed Martin, Northrop Grumman, and Boeing – companies that between them have defined American air power for generations – to the target. Anduril, a defense technology firm founded in 2017, did not win on relationship or on legacy: it won on AI-native architecture.

The shift this represents is psychological as much as commercial. Defense procurement is arguably the most bureaucratic, relationship-driven, clearance-protected industry on earth. If AI-native vertical integration can break this barrier, anything is now open for re-negotiation.

The Great Compression Part Two: The Intelligence Trap

The compression of the human intermediary layer across the economy – the subject of this series’ opening piece – raises a question that is both philosophical and financial: if the old middlemen are disappearing, and if the AI models replacing them are themselves becoming commodities, where does value go?

What made the Air Force announcement structurally significant was a detail that went largely unnoticed: the service deliberately separated the drone hardware from its AI software, specifying that the intelligence layer could be upgraded or replaced independently of the platform. By doing so, the Air Force drew a line that the market is still catching up to – and then immediately complicated it. The aircraft is the delivery vehicle. The intelligence tier is what matters, except that intelligence is also commoditizing fast.

The commoditization signal had already arrived earlier this month, when Google cut the price of its AI plan by nearly 40% overnight. OpenAI is reportedly considering steep token-price cuts as competition with Anthropic intensifies. The models themselves are beginning to resemble a capital-intensive utility more than a premium software business. As intelligence becomes cheaper, the investment question shifts to what models cannot easily access: proprietary data, regulated workflows, institutional trust, and the systems that turn AI output into real-world action.

The answer, in the most durable cases, is proprietary domain data combined with deep sector integration. Anduril is not a defense company that adopted technology: it’s a technology company that chose defense as its vertical. Palmer Luckey, who sold Oculus to Meta when he was just 21, founded Anduril alongside veterans of Palantir with a specific thesis: Silicon Valley had abandoned defense, leaving a widening gap between what the military needed and what the traditional primes could deliver.

Where Lockheed and Boeing run bid-led organizations optimized for cost-plus contracting cycles measured in decades, Anduril built a product-first company that moves at software speed, focused on cheap, autonomous, attritable systems designed to be deployed and lost without catastrophic cost. The competitive edge that results has nothing to do with which model runs underneath it. It is purpose-built architecture, mission-specific design, and the kind of deep operational embedding that no generalist technology company can shortcut and no traditional prime can easily imitate.

Palantir built the same competitive edge a decade earlier, at the intelligence level. Their forward-deployed engineers embedded themselves inside classified environments, building proprietary data structures around defense and intelligence that competitors cannot access, let alone replicate. The model is almost beside the point. What matters is the institutional trust above it and the data structure underneath it.

The same logic plays out in banking, and the psyche shift there is equally striking. JPMorgan Chase is not an obvious candidate for AI leadership – a 150-year-old Wall Street institution steeped in regulatory obligation and institutional conservatism. Yet it has become arguably the most digitally aggressive major bank outside the fintech world, spending north of $17 billion annually on technology and deploying AI across trading, risk, legal document review, and client services. JPMorgan’s AI advantage over any fintech competitor is not compute – it is 150 years of proprietary transaction data, credit history, and market intelligence, combined with the institutional will to deploy it at scale. Many large banks sit on comparable reserves; few have built the machine to turn them into a competitive weapon. The model commoditizes; the data does not – but only in the hands of someone with the commitment to exploit it.

The pattern across defense, banking, and every sector where this is playing out is consistent: the prize migrates to whoever owns the scarce position that generic models cannot substitute for. Right now the prize sits with domain data and deep sector integration. What’s forming above it is agentic orchestration – systems that coordinate networks of specialized AI agents across high-stakes workflows: routing battlefield targeting decisions, flagging fraud across millions of simultaneous transactions, managing the exception-handling that no single model can resolve alone. Palantir’s AIP platform is the most mature example of this emerging tier, and it is no coincidence that the same company that mastered domain-specific data is now positioning for that orchestration tier. Salesforce’s Agentforce is building toward the same position from the enterprise side. The race for this trophy is not yet decided, but the companies that already own those domain data advantages are the natural favorites to own the control plane above them.

The stack, in other words, keeps moving upward. Value migrates to the next bottleneck, then the next. And below all of it – the models, the sectors, the orchestration layer – something has to hold the weight. Every control plane needs a floor. What that floor looks like, who owns it, and why it may be the most durable investment thesis of the AI era is the subject of the next piece.

Copy and paste the text from AMT that you want to share

AMT Top 10

AMT Top Ten Miscellaneous Meditations for the 16th of June

Memorandum of Misunderstanding, the SPCX Rocket, the Knicks and Brazil as Jazz Plays in the Background

10. Legacy: Sonny Rollins passed away on the 25th of May at the age of 95. Rollins was a master jazz musician and saxophonist who will be listened to forever. His sound, cadence and imaginative ability to create while playing with bands, and often lead via his unique style make him an everlasting legend. If you haven’t listened to Sonny Rollins start out with his song St. Thomas via Saxophone Colossus.

AMT Top 10 Miscellaneous Meditations for the 16th of June, 2026

9. Surreal: The New York Knicks won their first NBA Championship in 53 years. Some Brazilian football fans returning to their hotels after their team’s 1-1 draw versus Morocco in their Group Stage World Cup match in New Jersey had to walk through throngs of Knick fans celebrating on the streets of Manhattan in bizarre looking circumstances as they worried about their national team. Walt Frazier and Pele both wore Puma and met in the 70’s.

8. Strategy: Michael Saylor continues to claim the wet and cold Bitcoin wind blowing back in investors’ faces is a refreshing mist that will invigorate the HODL crowd eventually. In the meantime MSTR is near $131.00 and BTC/USD around $66,300.00. Saylor sees Bitcoin above 1 million eventually and beyond, while some others see headwinds and more losses developing.

7. Bleeding Money: Political mismanagement shadows Chicago which appears ready to lose the Bears football team via a new stadium across state lines in Hammond, Indiana, this as team officials and ill-equipped Illinois leaders argue about property taxes and other business considerations (and maybe kickbacks). NYC is hurting for funds too, this as important companies make plans to place their corporate headquarters and employees elsewhere and avoid Mayor Mamdani’s nonsense. Apollo Global Management is the latest to decide to venture forth into Texas and make its New York presence less important. 

6. Commodities: Gold is near $4,330.00 this morning, Silver around $70.00 and WTI Crude Oil close to $78.00 via futures pricing.

5. Nasdaq 100: The index finished 3.06% higher yesterday and at a value of 30,543.92 per last night’s close. The Nasdaq 100 has been delivering a wild ride for speculators and investors. The index saw all-time highs in early June when it went above the 30,700.00 level. The S&P 500 concluded Monday’s trading at 7,554.28 and up by 1.65%, the index’s high was also in early June when it went above 7,600.00. For all the talk of doom and gloom over the past week and a half with fears about a sustained run downwards in the U.S indices, they are showing upwards momentum for now. 

4. BoJ: The USD/JPY remains within sight of the 160.000+ mark consistently. While other major currencies have gained a bit the past few days against the USD, the Japanese Yen remains sticky near its highs as the Bank of Japan is likely watching speculators wager on the higher realm. FX traders need to remember that the BoJ may act when it feels it has enough clarity regarding the Iran saga and inflation concerns. In other words, a warning shot may come soon threatening an intervention. Buyers beware.

3. SpaceX: Is it a bird or a plane? No, its a 2.1 trillion market cap valuation via a rocket like IPO on the Nasdaq 100. While some may want to bet against Elon Musk early, those type of decisions have proven costly mistakes for some short sellers in the past when dealing with Musk and Tesla. Some may argue for value of $115.00 and less per each SPCX share, but it might prove unwise to step in front of the upward trend for the moment. Case in point, Tesla is near $411.00 per share and causing chagrin within certain crowds as they point to weakening sales, but only see the company do better in value. Oh, and SpaceX ended Monday’s trading at $192.50.

2. Fed: Kevin Warsh leads the FOMC Committee as the Chairman for the first time as the Federal Funds Rate decision awaits this Wednesday. Some think the Fed will increase the interest rate by 0.25%, AMT does not based on the opinion Chairman Warsh likely wants to start off his job on friendly terms with the White House and Treasury, while also counting (hoping) on cheaper energy prices.

1. MoU: The Iran conflict awaits a signed agreement. The terms of the Memorandum of Understanding are being whispered, but transparency has not been delivered and won’t be until Friday supposedly when the U.S and Iran attend a ceremony in Switzerland. While financial institutions and global markets are ready to turn the page and engage in optimistic outlooks, it remains to be seen if negotiations will lead to tangible results as multiple questions and concerns linger. In the meantime a sizeable part of Iran’s population still lives under tyranny. Who won? Did President Trump make a quiet deal with China to guarantee oil flows from the Strait of Hormuz and receive something in return during his visit to Beijing from the 13th to the 15th of May? There appears to be room for plenty of misunderstanding.

Copy and paste the text from AMT that you want to share

USDINR 20260615

India Insider: Can We Become a Developed Economy on Low Wages?

The Brutal Nature of a Large and Cheap Workforce

Ms. Nithya (name changed) works in a private school in Tamil Nadu. She gets to school by 9 AM and leaves around 5 PM. The school she works for hasn’t paid a salary for two months and she has no contract. She gets $83.00 USD per month in a small city of Tamil Nadu State. While this may sound extraordinary to some readers, it is not an isolated case in countries like India. 

Salary surveys and labour market studies indicate that many private school teachers in smaller towns and rural areas earn between ₹5,000 and ₹15,000 per month, this despite possessing educational qualifications and working full-time schedules. Though private schools in India often collect exorbitant fees, they pay teachers less and it hasn’t changed for years. 

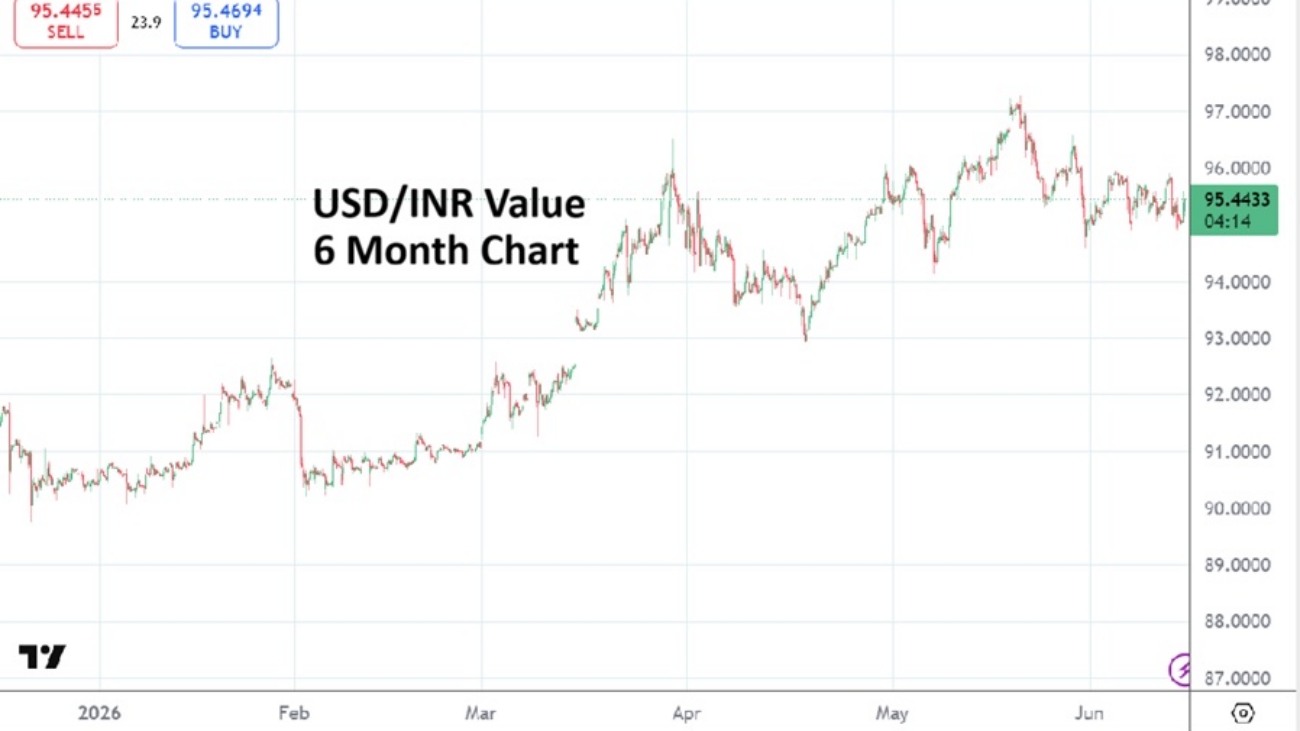
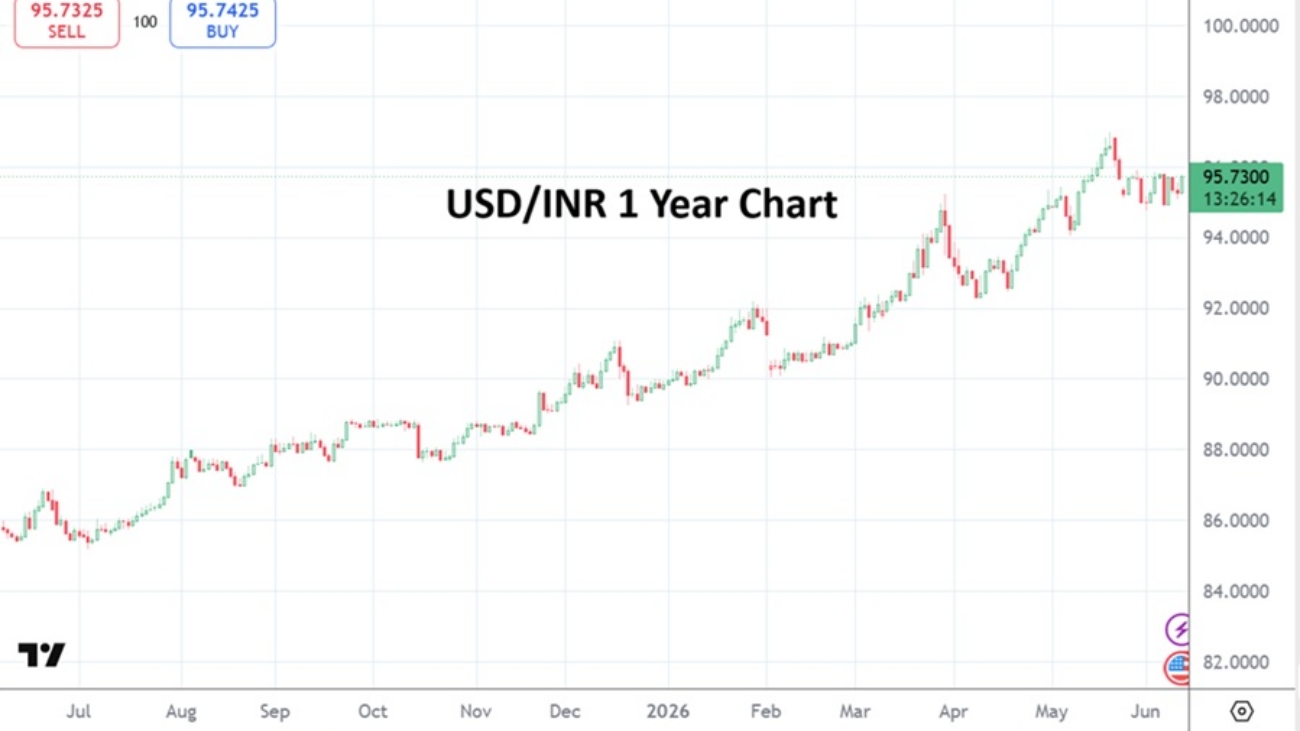
USD/INR Six Month Chart as of 15th June 2026

Indian nurses often are treated in the same manner. Those who prefer to work in government institutions or emigrate to foreign countries earn better wages. Attrition in the nursing industry is quite high in India. Why?

Because of the lower wages in most of the private hospitals in India, and the higher wages offered in Singapore or in the Middle East a career and lifestyle choice arises. That’s why many nurses work for a time in institutions closer to their towns. And then switch to more lucrative opportunities when salaries are more handsome in distant Indian cities or in a foreign country.

Male nurses from rural areas also leave and work in GCC countries. As long as wages remain lower and uncompetitive, attrition will prevail in India’s nursing sector.

Perspectives From The Employees Standpoint

India wants to become a 10 trillion USD economy by 2047. How will India increase its total output to achieve the above target? India has to create jobs and better compensation via salaries for its people.

Without sufficient income, how are people expected to pay for goods and services produced in the economy? And if people are not buying, who will buy the goods? Maybe the generous foreigners, but can India accomplish this goal? India’s service exports such as Information Technology are already facing questions of viability, this as AI confronts and makes strong and sufficient intrusions into existing business models of legacy companies.

Gig workers deliver parcels dictated by soulless algorithms. The algorithm doesn’t understand the burdens of hot summers and cold winters. It dictates rules and regulations according to its capital owners’ protocols. Employees who work in this profession have to work no matter whether they have fevers, cold ,body aches or anything else they might be an affliction.

Like feudal landlords who extracted labour without many concerns for the well being of those who worked under their authority, today’s digital platform economy often places efficiency and profits above human considerations. This is called “techno-feudalism” by some economists.

Though individual states in India have labour laws and regulations, India’s readiness and capability to enforce these laws in order to regulate the welfare of the labour market is still not up to standards elsewhere and difficult to enforce.

If your income remains low relative to the cost of living, how do you increase your consumption? A question that India’s ultra-wealthy should ask as their companies produce everything from cars to household goods and understand the importance of making money for themselves, is if they understand the other side of the balance sheet? Perhaps they would make investments that create jobs which in turn would help families spend their extra money on their companies goods and services.

India suffers from the availability of a high proportion of cheap and qualified labour that is easy to manipulate and allows a few to profit from the many. Given the tepid investments by private business in consideration for the other side of the balance sheet, the wages that most employees receive via basic economic models are insufficient.

Ironically and sadly, in some parts of India, especially in smaller towns or rural areas it is true that many private sector nurses, schoolteachers, and other service workers earn less than the international poverty line of $3 per day (around ₹285 at current exchange rates).

Education is certainly a tool for women empowerment, but it is often confronted by employers who take advantage of the educated and still pay poor salaries. This ‘accepted truth’ regarding education becomes questionable given the reluctance of institutions to pay a better salary for those who have spent money on improving their knowledge and skills. Those who work for meager pay, while not earning enough income to save money, nor participate in liquid investments or stock investments are caught in India’s labour market trap.

While writing this article, I witnessed a young married woman in her 30s, delivering parcels on behalf of Flipkart (owned by Walmart) in a vehicle which suffered from the brutality of the afternoon sun. Such is the nature of the labour market right now in India .

India shouldn’t allow people to work in a system that enriches techno-feudalists and business people by putting the welfare of their employees at risk. If India wants to be a developed economy, it should put people first. Economic development should not be measured solely by GDP growth, stock market indices, or the wealth of billionaires. It should also be judged by whether the ordinary workers can earn enough to live with dignity, support their families, and participate meaningfully in the prosperity they are helping create.

Note: 1 USD = 94.90 INR as of 12th June 2026

Copy and paste the text from AMT that you want to share

Indian Rupee 20260611

India Insider: Should the RBI Raise Interest Rates?

A Case for Higher Interest Rates In India

As the Rupee remains under pressure and oil prices continue to rise amid tensions in the Middle East, the debate has shifted towards what the Reserve Bank of India (RBI) should do next.

Economist Janak Raj has argued that raising interest rates to defend the Rupee comes with significant costs. Higher rates increase the cost of capital for businesses, reduce investment activity, and compress equity valuations. In theory, this could even accelerate foreign outflows from equities rather than attract fresh capital. Yet the RBI may soon find itself with limited options.

USD/INR One Year Chart as of 11th of June 2026

Foreign Portfolio Investors (FPIs) were net buyers of Indian equities for most of the period between 2004 and 2024, with only a few exceptions such as 2011, 2018 and 2022. However, the trend has changed. FPIs sold approximately $19 billion USD worth of Indian equities in 2025 and another $24 billion USD so far in 2026.

Question: Why are Foreign Investors Selling

One reason is that global investors today have alternatives. The growth of Artificial Intelligence related companies in the United States has created significant investment opportunities. At the same time, U.S Treasury yields hovering around 4.6% offer attractive risk-free returns in a strengthening dollar environment.

For many global investors, earning high returns in Dollar assets is preferable to taking exposure in emerging markets that face current account pressures from rising  Crude Oil prices and other energy costs.

Taxation is another factor. India taxes foreign investors at 20% on short-term capital gains and 12.5% on long-term gains. Meanwhile, competing financial centres such as Singapore, Hong Kong, Malaysia and Thailand generally do not tax foreign investors’ capital gains.

Some global funds have argued that India should move closer to international norms, where capital gains are usually taxed in the investor’s home jurisdiction rather than the country where the investment is made. Higher post-tax returns would undoubtedly make Indian assets more attractive.

A stable Rupee would also reduce hedging costs, lower currency-risk premiums and improve the overall risk-reward profile for overseas investors. However, tax cuts alone cannot solve India’s problem.

The Real Issue is Balance of Payments

As Business Line columnist Lokeshwari Mam has pointed out, a significant portion of equity outflows consists of short-term speculative capital. Long-term capital tends to remain invested. This is why the decline in net Foreign Direct Investment (FDI) should concern policymakers more than short-term fluctuations in portfolio flows.

Net FDI has fallen sharply from $28 billion in FY 2022-23 to just $7.7 billion in the year ended March 2026. This is a worrying trend because FDI is the most stable source of external financing. Unlike portfolio flows, it creates factories, jobs, exports and long-term productive capacity.

India therefore needs more than tax incentives. A genuine single window clearance system, reduced bureaucracy, easier business regulations and reforms in manufacturing remain essential. Attracting long-term capital should be a national priority.

The recent foreign buying of Indian bonds after tax cuts is encouraging. But relative to India’s current account financing requirements, it remains a small drop in the ocean.

For example, in FY 2025, the current account deficit was 0.6% of GDP. And in Q4, the current account became a surplus. Is it really that difficult to finance it’s small current account deficit?

India’s external vulnerability is determined not merely by a current account deficit, but by whether the capital account can be comfortably financed. A modest current account deficit still creates currency pressure if foreign capital inflows weaken (which we are seeing), while a larger deficit may be sustainable when capital inflows remain strong. The risk of sustained higher oil prices could widen the deficit, increasing India’s dependence on foreign capital at a time when global liquidity is tightening and U.S Treasury yields are rising.

Furthermore, hedging costs continue to erode much of the yield advantage that Indian bonds offer over U.S Treasuries. In that sense, active global money is likely to prefer Dollar assets over emerging-market debt or equities

India’s repo rate currently stands at 5.25%. The RBI’s decision to raise its inflation forecast to 5.1%, while lowering its GDP growth projection to 6.6% reveals where the shock from the Iran conflict is likely to be felt via higher inflation and weaker growth. For an economy that remains heavily dependent on imported oil, a depreciating Rupee only compounds the problem by increasing the cost of energy imports. 

In such an environment, the Monetary Policy Committee is unlikely to focus solely on growth. Currency stability, inflation expectations and the availability of foreign capital to finance India’s external requirements could become increasingly important considerations. If these pressures persist, the RBI should raise the repo rate, in the same manner other Asian central banks have done in recent weeks.

Copy and paste the text from AMT that you want to share

Celtics and the Middle East 20260609

Falling into the Middle Eastern Trap

When Talking Becomes an Obsession

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 9th of June via The Angry Demagogue.

The United States is falling into the Middle Eastern trap that Israel fell into thirty years ago. This trap fits nicely with the post cold-war progressive Western way of diplomacy in that its goal is “talking”. Perpetual talking rather than deal making is the key to understanding the Middle Eastern way of things and Israel has become a practitioner in the “way” that led directly to October 7. The idea of perpetual talking is to reach a situation where you can defeat your opponent without making concessions. In the Middle East, they suck you in to a point where just “talking” becomes an obsession. The United States is heading into the same where results are less important than the act of discussion itself.

Falling into the Middle Eastern Trap – When Talking Becomes an Obsession 9th of June 2026

This obsession, this being sucked into something against your best interests reminds me of a wonderful episode of Cheers, the sitcom that takes place in a Boston bar – a bar in which pints of beer plus inane discussions over anything that leads to nowhere is its reason for being. The episode that I am thinking of has Boston Celtics great Kevin McHale as a guest and the two main instigators of irrelevant and purposeless conversation, Norm and Cliff, (not so) innocently ask McHale how may bolts are in the famous parquet floor at the Boston Garden.

The waitress Carla, Boston working class par excellence, begs the basketball star to ignore them, knowing he will become obsessed and sucked into something that clearly will lead to a disaster for him and her beloved Celtics. Sure enough, the episode ends with McHale driving towards the basket with what ought to be the winning shot only to get distracted by trying to figure out how many bolts are in the floor of the Boston Garden.

That is exactly what is happening now in in the Middle East where President Trump is the basketball star being distracted by Iran and their attempt to suck him into endless discussions that are meant to lead to nothing productive. We don’t know if McHale ever figured out the number of bolts, but besides going back to Cheers with the answer, it is a useless endeavor that can only lead to defeat. So too, with the Trump Administration and the sacred talks with Iran where the end game might be something he can bring back to a press conference in DC or a rally in Pennsylvania but will be worth as much as knowing the number of bolts in the Boston Garden floor.

Israel fell into this trap with the Palestinian Authority of Yasser Arafat and when talks ended, the only goal was to start them up again. Just return to talking. The result didn’t matter. This trap picked up again after October 7 when the goal seemed to be to always be talking with Hamas via Qatar or Egypt even if everyone knew it would lead to nowhere. Ironically, it was President Trump who realized this and was able to do his dealmaking magic to free the hostages – but only after the IDF put Hamas in an untenable situation and Qatar wanted a “great deal” with the Trump administration. Talks never led anywhere.

So here we are, the Trump Administration is hell bent on continuing discussions for the sake of discussions no matter how many times Kuwait, UAE, Bahrain, Israel, or even the U.S military get shot at by Iran. When the goal is talking – when the obsession becomes talking – you have fallen into the Middle Eastern trap much as Keven McHale fell into the trap of inane bar talk for the sake of inane bar talk.

While the American President is a deal maker par-excellence, the Middle Eastern leaders, this time Iran’s, are the experts at making you think that talking is always the best outcome – because it is, for them. Eventually, their experience tells them, you will make a mistake. The Administration has allowed Iran to attack allies at will in the Gulf and in Israel, as Iran gains concession after concession due to the trap that is “talks at all costs”. The first concession was linking Lebanon to the talks and the next, done just yesterday was in putting Iran and Israel on the same level.

This is the mistake one would expect from the Obama-Biden crowd where they always believed that talks were the purpose – they didn’t have to fall into any trap as they were there already. However, the Trump Administration understood the fallacy of forever talks which is what makes it so painful to see them fall into the same Middle-Eastern and Western, progressive trap. Obsession to make a deal is good because results oriented; but an obsession that is just to “get back to talking” will lead only to results that you never wanted in the first place.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

Follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

Nasdaq 100 20260608

Nasdaq 100: Terrible Friday Being Confronted by Manic Monday

Fear of the Middle East Not the Main Motivator for the Nasdaq 100

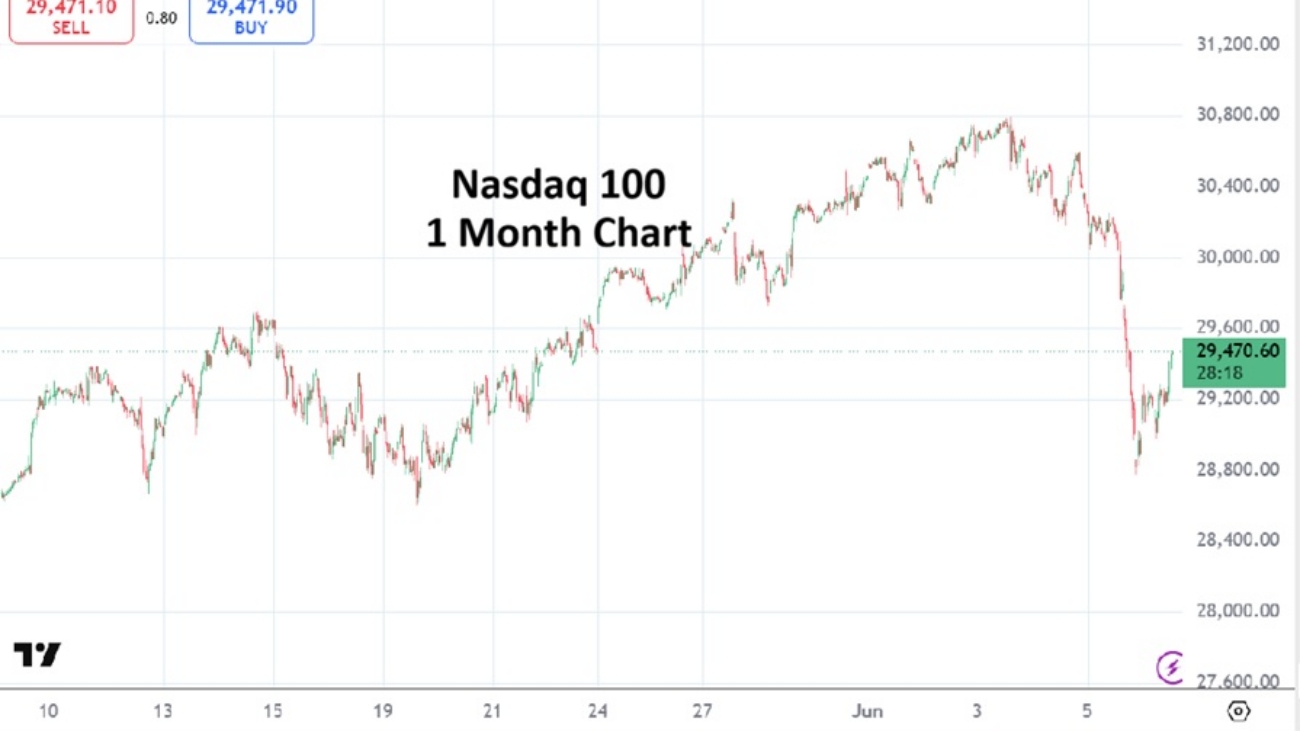
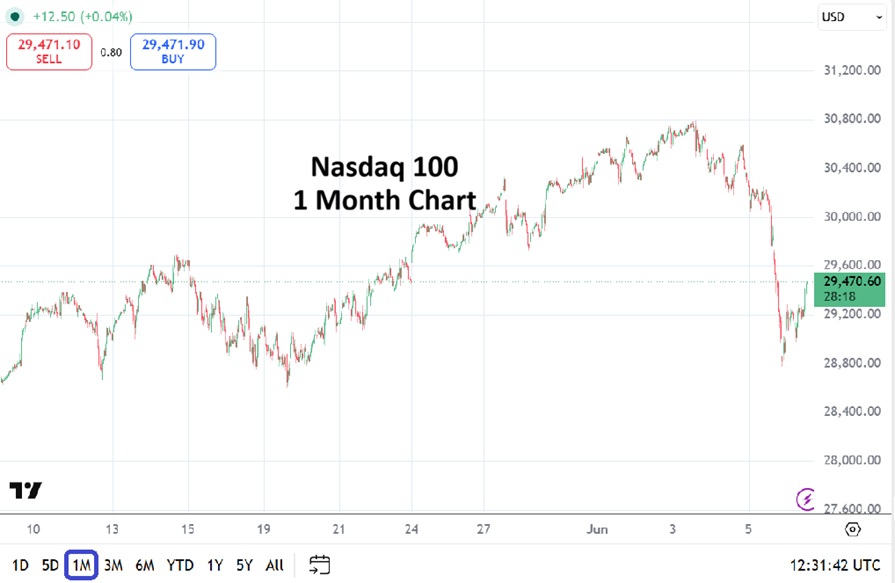
After Friday’s selling surge and a fall of -4.77% with a close of 28,957.60, the Nasdaq 100 futures trading this morning has actually seen an increase and is near the 29,479.00 mark as of this writing before the cash Nasdaq 100 market opens.

Friday’s selling nightmare for traders who found themselves stubbornly locked into what were to be short-term buying positions and saw the Nasdaq 100 plummet -4.77%, probably woke this morning believing ugly conditions may not stop. An escalation in military action via proclaimed retaliatory moves between Israel and Iran started today’s trading with a high degree of more anxiousness. USD centric strength in Forex was demonstrated early.

Nasdaq 100 Futures Value 1 Month Chart as of the 8th of June 2026

However, in the past couple of hours calmer heads have prevailed among financial institutions and USD centric buying in the broad Forex market has run out of steam – at least momentarily. For instance the USD/JPY is near 159.927 currently, opposed to earlier highs seen this morning which challenged the 160.400 vicinity. What does this have to do with the Nasdaq 100 and its current status? 

It appears via futures trading that large players may also have taken a sedative and looked at the index as having been oversold on Friday. The Nasdaq 100 has actually gained early today and signs that a de-escalation of military force between Israel and Iran is being reported. However, that still leaves day traders wondering what will happen as the cash market opens soon and volumes increase.

Let’s Say Quiet Prevails the Remainder of the Day

Not because of a utopian outlook, but a geopolitical perspective, let’s try to image Iran’s stated intentions of no more retaliatory strikes being launched towards Israel as true. The past couple of hours have been more tranquil as a signal in case you are wondering. Then investors and financial institutions will have to digest the Middle East concerns as they have done over the past couple of months in U.S equities, and decide to operate again on the Nasdaq 100 with near and mid-term outlooks.

Friday’s huge selling was blamed by some on the likelihood of a ‘potential’ U.S Federal Reserve interest rate taking place on the 17th of June. This because better than expected jobs numbers showed to some that the U.S economy was running hot once again. 

Additionally expressed fears, which are legitimate, about higher energy costs sparking sticky inflation have been discussed and worried about aloud. Yet, again let’s decide to say even if U.S inflation numbers via the Consumer Price Index come in higher than expected this Wednesday via the coming CPI data, that doesn’t shut the door on the possibility the new Fed Chair Kevin Warsh won’t fight against an interest rate hike during the FOMC meeting next week. In other words it still seems rather unlikely – to me – that the new Federal Reserve Chairman is going to want to initiate higher interest rates the first month on the job. So what if there was another reason for the steep selling on the Nasdaq 100?

Not Paradise but Purgatory

The Nasdaq 100 actually has other questions which have been raised as possible fodder for its large selling this past Friday. Was it spawned because of profit taking by those who took advantage of the index’s fabulous rise knowing that many institutions had been front running the IPO of SpaceX which is scheduled to happen on the 12th of June – this Friday? 

Did large players who rode the wave of frontrunning by financial institutions up in the Nasdaq 100 since late March, decide to cash in profits. There is plenty of nervousness surrounding what will take place with SpaceX in the coming months and long-term via outlooks because of its rather inflated valuation which looks like it will be around 1.7+ Trillion plus at share values of $135.00 per share this coming Friday. 

Questions surrounding SpaceX’s price per sales rhetoric, this instead of price per earnings (because SpaceX is not making a net profit) is just one example. While denying Elon Musk’s genius and ability to create clamor for his companies has proven to be a losing proposition for many, doubters still remain. 

Folks might have cashed out winnings on Friday and decided to now wait on the sidelines to see where behavioral sentiment takes the Nasdaq 100. After two full months of paradise for the Nasdaq 100, a few days of purgatory and seeing which direction U.S indices go may be the right decision by folks who rely on clarity; this as the Middle East gets untangled (or becomes more complicated), the Federal Reserve offers insights on the 17th of June, and large financial institutions lead the way regarding investment decisions.

Copy and paste the text from AMT that you want to share

Female Work Percents 20260605

India Insider: Growth Matters, Development Matters Even More

Participation of Women in the Workforce and Advancing Progress

There is more poverty in this world than many of us realize and would like to comprehend when confronted by the facts, and this is also true with India.

Recently, I visited several villages in Tiruvannamalai District in Tamil Nadu State on behalf of Angry Meta Traders to survey household capital formation, wage growth and labor market dynamics. To my astonishment, in many homes, people still use rice and palm oil purchased through ration shops. The important observation is their consumption basket appears narrow and heavily dependent on subsidized essentials. I saw simple aluminum utensils in kitchens, when higher income households often use silver-plated utensils. Things that many middle-class families consider normal like energy drinks, snacks, or packaged foods were often absent.

What struck me even more was the number of women managing families alone. In some households, the husbands had died due to excessive alcohol consumption. Children attended government schools and depended on nutritious meal schemes provided by the State.

Growing up, I have seen people wear torn uniforms in school because their family could not afford new uniform every year. Some did not wear shoes, and many students stood outside the class because the fees in private schools in India are several times higher than what government schools would charge and their families could not pay on time. Yet, through education and perseverance, many people have succeeded. 

However, the poverty I witnessed in Tiruvannamalai District is different. These observations reminded me of a study published in the Lancet Regional Health Center. Researchers followed 251 children in Vellore District (closer to Tiruvannamalai District) and found that poor children living in urban areas were often exposed to calorie-rich but nutrient poor food environments.

If such conditions exist in parts of Tamil Nadu State, one of India’s more developed states, then we should think carefully about the situation across the country.

Another Transformation is Taking Place

For generations, many women carried the burden of childcare, household work, elder care and agricultural labor simultaneously. In many families, they sacrificed their own aspirations for others. Are women born to carry everyone’s burden?

Interestingly, across the globe especially in Southeast Asia, education and economic opportunities have expanded women’s choices. Researchers such as Stanford University’s visiting Professor Alice Evans argue that many women choose marriage only when their partner’s own goals align with their own. If not, remaining single becomes a reasonable choice for them

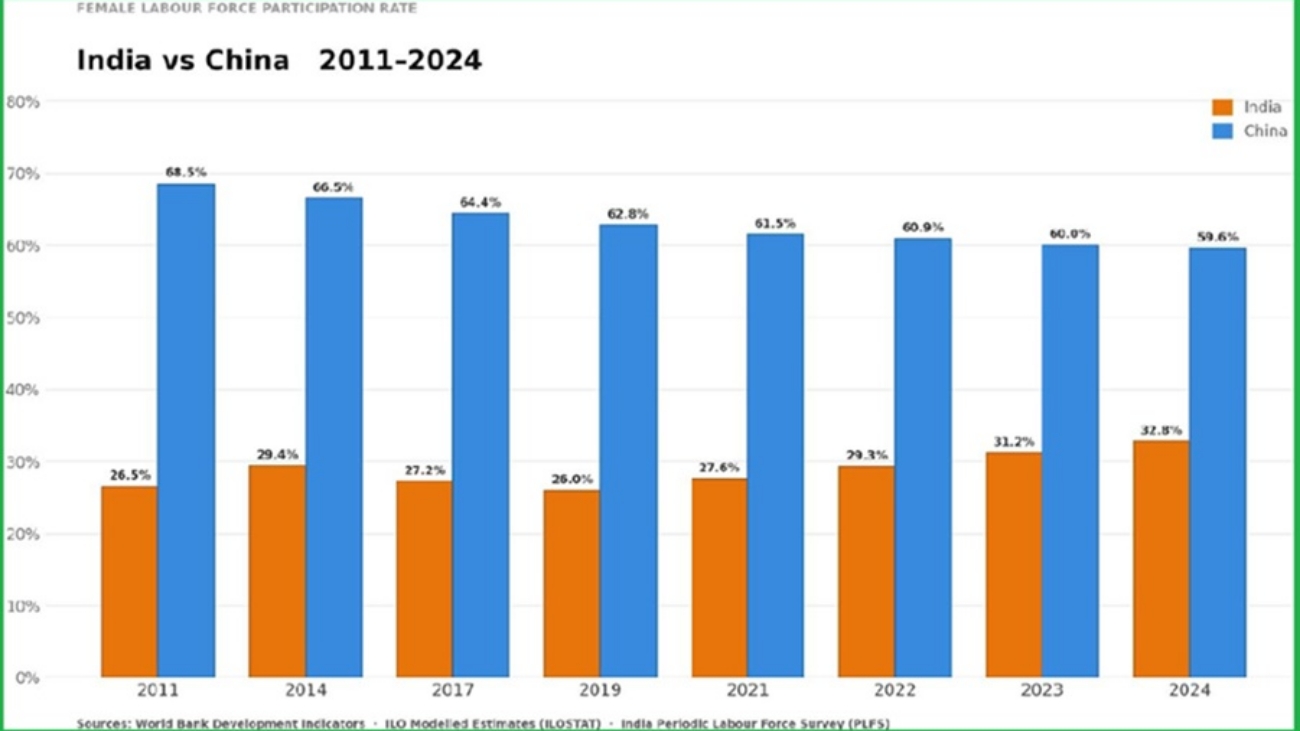
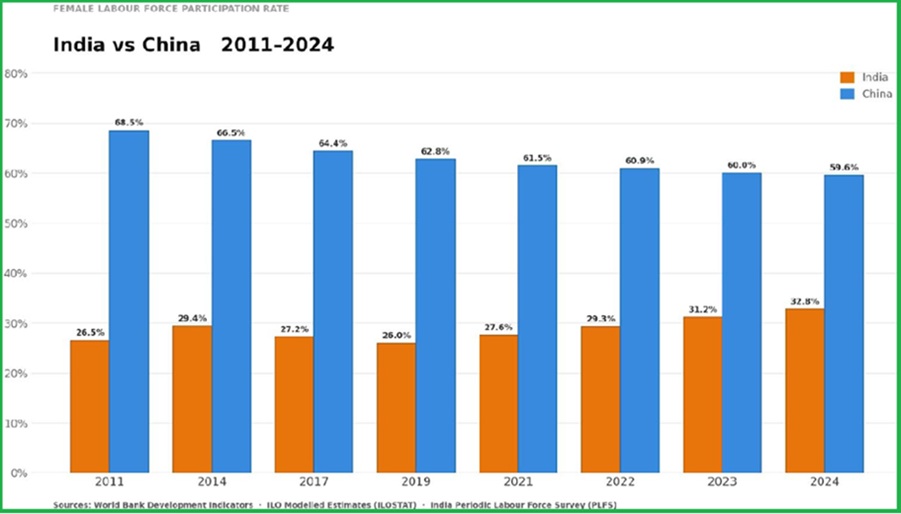
Female Labor Participation Rates Comparing India and China from 2011 to 2024

As shown in the above chart, India has certainly made progress, but female participation in the workforce remains below that of many East Asian economies. A society that fully allows women to participate in economic life is likely to become more prosperous and productive.

Economic realities are also shaping family decisions. Housing is expensive. Job markets are uncertain. Inflation remains a challenge. Asset prices have risen significantly.

Yesterday, a college friend called me. He recently built a new house in his town. He is 33 years old, unmarried, and works in Oman. Years of overseas employment and remittances have helped him to achieve his goals. I sometimes wonder whether the same outcome would have been possible had he stayed and earned entirely in India, especially outside the software and technology sectors.

India still has demographic advantages, but a demographic does not bear fruit automatically. It requires healthy, educated and economically secure citizens.

We often speak about India becoming a developed nation. However, the real question is whether growth can and will improve the lives of ordinary people, especially women, children and underprivileged. Growth matters, development matters even more.

Copy and paste the text from AMT that you want to share

Perception Over Fact 20260603

Perception Over Fact: Iran as the Savior of Beirut

Trump Policy and The Art of a Middle Eastern Deal: Israel, Iran and Lebanon

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 2nd of June via The Angry Demagogue.

Although it is difficult to see where the negotiations between Iran and the United States are going – if anywhere – over the last 24 hours the United States has made Iran the “savior” of Beirut. Against American policy of creating a civil and unified Lebanon at peace with its neighbors, the Trump Administration has told the Lebanese government and people that Iran still controls what happens in Lebanon.

Perception over Fact: Iran as the Savior of Beirut

Even if this was not the case, in the art of the Middle Eastern deal, perception is more important than fact. Whether the Trump Administration actually twisted Israel’s arm due to Iran’s demands or not, the fact that Israel has agreed not to bomb the Dahiya section of Beirut after announcing that they would gives a message to the Lebanese people and government that Iran still calls the shots in Lebanon and not to rush to support those who wish to disarm or dismantle Hezbollah since you will be on the losing side.

Lebanon has been embroiled in civil wars since its inception. Beirut, the “Paris of the Middle East” has never known quiet times although that did not stop the partying (sort of like Paris itself today) and Iran’s involvement, much like Syria’s and the PLO’s before has not helped. Before the PLO inspired civil war in the mid 1970’s, after King Hussein threw them out of Jordan, the civil wars were about Lebanon itself. The French thought they created a formula for the creation of a semi-western state by dividing up the power centers amongst the religious and ethnic groups – Maronite-Christians got the Presidency, the Sunnis the Prime Minister-ship, the Shiites the speaker of the Parliament. The Druze historically were appointed Chief of the General Staff of the army.

This formula was, as can be imagined, not one for the free exchange of ideas but caused a rush to create power centers and led to conflict, civil and military. But it was all internal. Once the PLO and Yassir Arafat came, Israel became a factor in the civil war since Israel had to cross the border to stop the PLO from its numerous cross border terrorist attacks. After the First Lebanon War and the forced exit of the PLO, Iran created Hezbollah with the sole aim of using it, in the future, to destroy Israel. Therefore, from the late 1970’s until today, the Lebanese state has been embroiled, often against its will, in the Israeli-Palestinian conflict.

The goal of the Trump Administration’s negotiations in Washington between Israel and the Lebanese government is to break Iran’s stranglehold over Lebanese internal and external policy and allow it to either establish diplomatic relations with Israel or at least to put the two countries in the situation they were in before the late 1970’s – and that was a quiet, irrelevant border for both countries.

The real or even perceived notion that Beirut was “saved” from Israeli bombing by Iran’s demands has set back that goal and given Hezbollah and hence Iran, veto power over Lebanese government policy. The correct answer to Iran after their demands were made tying Lebanon to the cease fire was that Lebanon is none of your business and if your proxy decided to join your war then they will have to take responsibility for it. The time for “protecting” Lebanon was when you ordered Hezbollah to come to your aid and attack Israel’s north. The result of that – the administration needs to tell both Iran and the Lebanese government and people, is the loss of Lebanese sovereign territory to Israel and the destruction of Shiite villages in the south of the country. A further price is the destruction of the Beirut neighborhood in which Hezbollah has command and control facilities as well as underground arms depots.

Iran cannot be seen to be the savior of Beirut and Lebanon but the cause of its troubles. No amount of rhetoric to the contrary will prove to the Lebanese government and people what they see on the ground now – only Iran has the power to stop Israel’s bombing of their country. The Administration has set back its goals in Lebanon without aiding its war effort in Iran. The constant Iranian threat to make the war regional is coming true since the Administration is not taking seriously Iranian deal-making methods.

As we wrote two months ago in The Art of the (Middle Eastern) Deal” – “Each ‘concession’ by Iran will have to be paid for twice or three times – once upon agreement and then again before numerous times before implementation”. Iran agreed to open the Straits and then reneged and the US is negotiation for that again – AFTER Iran received the much needed cease fire.

Now, after the administration denied linkage to Lebanon, Iran is again demanding that linkage – not in order to open the Straits, but just to continue negotiations. This pushes both American interests to the back burner – the opening of the Straits of Hormuz and the normalization of Lebanon as a country free from Iranian influence. And the “concession” that Iran is giving for this is just a continuation of the negotiations that have been going on for over two months. In other words, like most negotiations in the middle east that are supposed to lead to “peace” – this too is moving backwards.

President Trump has asked for patience and has insisted that the United States will never accept a bad deal – and I am willing to be patient and believe that. But what if the goal of the Iranian government is not a deal at all but the ability to re-set their genocidal triad or missiles, proxies and nuclear weapons? These negotiations have given them time to dig out their underground missile cities, to keep their enriched uranium hidden and now to revive their flailing major proxy – Hezbollah. In the end, as the President said, it will be good, but by allowing Iran to take the initiative he is making it harder to get to that “good”.

What we have now is a continuation of American-Iranian negotiations where a concession was given to Iran and they are no closer to reaching an agreement. Iran is now perceived as the power to be reckoned with in Lebanon and Israel is put on a level with Hezbollah. Iran and the United States are now equals in this negotiation, something that was not the case when they started. While it might in fact end well, the journey is now a longer and more difficult one. The perception given by the last 24 hours that Iran controls Lebanon, is now the “fact” that the Middle East “knows”.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

Follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/

Copy and paste the text from AMT that you want to share

Fear of Russia 20260529

Fear of Russia in Europe

Time for the Baltic+ Alliance

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 28th of May via The Angry Demagogue.

The Wall Street Journal had a thoughtful piece the other day (Europe is Starting to Think Putin will Expand the War Beyond Ukraine) on Europe fearing that Russia will look to expand their war beyond Ukraine. This has been a fear since Russia’s ill-fated invasion four years ago and is the reason why Europe is supporting Ukraine (not due to any love or respect for the people of Ukraine).

The gist of the article though is America’s possible unwillingness to come to the rescue of Europe and honor their NATO commitments. These fears are not unfounded, but sitting and worrying about American will or overextension will not deter Putin from yet another attempt to divert attention to the deteriorating nature of his country’s military, economy and general health.

Rather than whine and wonder, those front line countries that will be most affected by Russian adventures need to form a new or sub-alignment and make moves that Russia can judge only as threatening to any new venture. Rather than not provoke, this new alliance needs to show Russia that they have the power and more importantly the will to defend the Baltic States and others that border Russia and are most at risk.

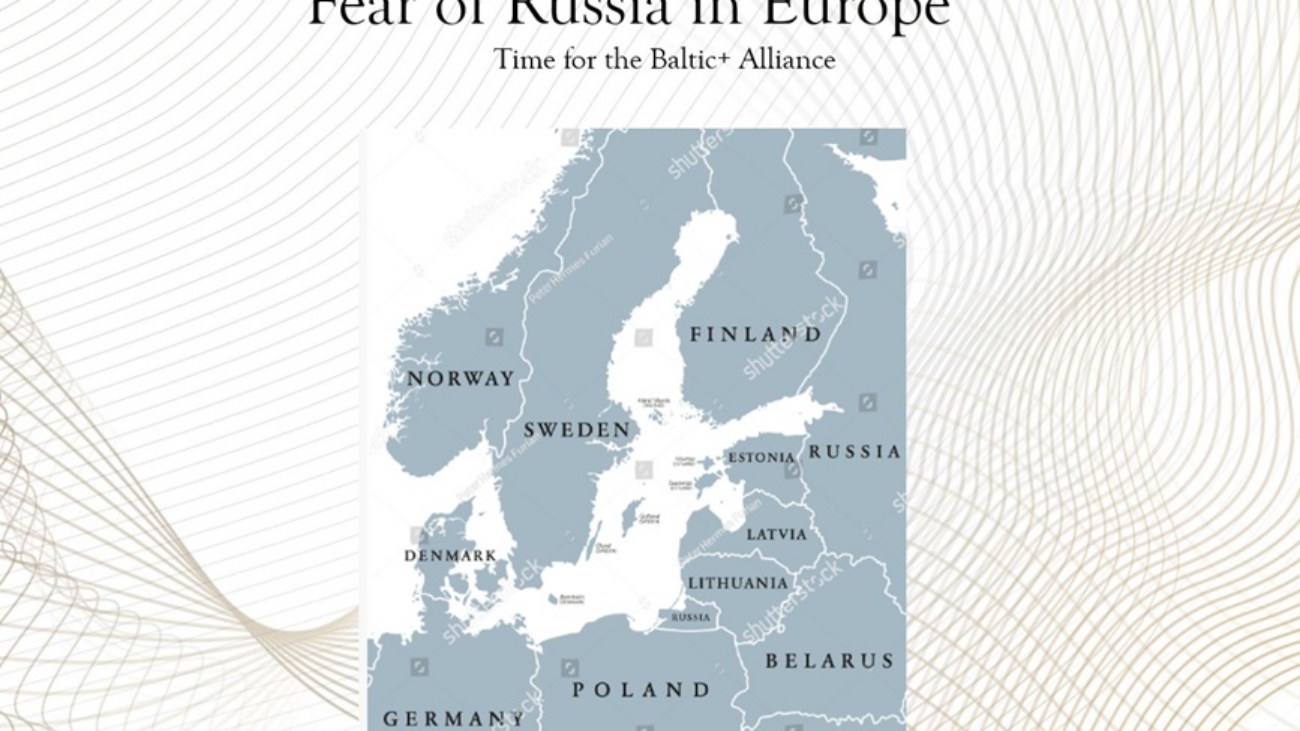
As we have written in the past (National Security Strategy, part 2: Regional Alliances-Europe), only countries with “skin in the game” have the will and the opportunity to successfully fight any Russian invasion. This Baltic+ alliance of Poland, Germany, Sweden, Finland, Norway, Denmark, Latvia, Lithuania and Estonia have a joint population of nearly 160 million people to Russia’s 145 million. Further, these countries have nearly 500 advanced jet fighters and a navy that can control the Baltic Sea. They have around 1,500 battle tanks combined and over 300,000 infantry soldiers.

Neither the United States, nor for that matter the UK, France, Italy or Spain (not to speak of the weak Benelux countries) have the will to defend the Baltic countries but, as they usually do, will offer diplomatic and other “help” in case of crisis. These 9 Baltic+ countries alone have the wherewithal and power to defeat Russia in case of attack. Joint air and naval maneuvers in and near the Baltic countries, naval buildups in the Baltic and the movement of tanks and infantry closer to the border including a “tripwire” in the Baltic countries themselves should be enough to deter and if necessary, defeat Russia in a new Putin venture.

However, this needs to be made operational and not just discussed. They cannot show the cowardice they usually show when facing military challenges like they have done in the Persian Gulf. Diplomatic solutions can work when backed up by superior military force and a clear will to use that force.

While the U.S sending 9,000 troops to Poland is a good thing, Sweden’s increasing its naval and air presence close to the Baltic States, combined with Polish and German tanks and infantry in those states and Finland moving troops close to its border with Russia will be taken by Russia with a sense of seriousness. There should be no fear of “provoking” Russia since Russia responds to perceived weakness and not strength. Russia would love to depend on America’s “overextension” and lack of will but this strong new alliance will compensate for any American hesitation. More than that, it will be taken more seriously than a few American brigades on Polish soil.

The creation of alliances does not need years of study and position papers, but bold moves by leaders that are sworn to protect their countries. If Europe seriously fears a Russian expansion of their war beyond Ukraine, then leadership of a kind Europe has been missing since Adenauer, De Gaulle and Thatcher left the scene, needs to come to the fore. Only then will it make sense for America to use its formidable power.

America does have a deep national interest in containing Russia and protecting Central Europe but, like when it faced its Iranian enemy it needs allies that are willing and able to take a central role in combat and not only half hearted support at the UN.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

You can follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/ 

Copy and paste the text from AMT that you want to share