postR163.1

Caution as GDP and Reactive Sentiment the Key for the Week

Caution as GDP and Reactive Sentiment the Key for the Week

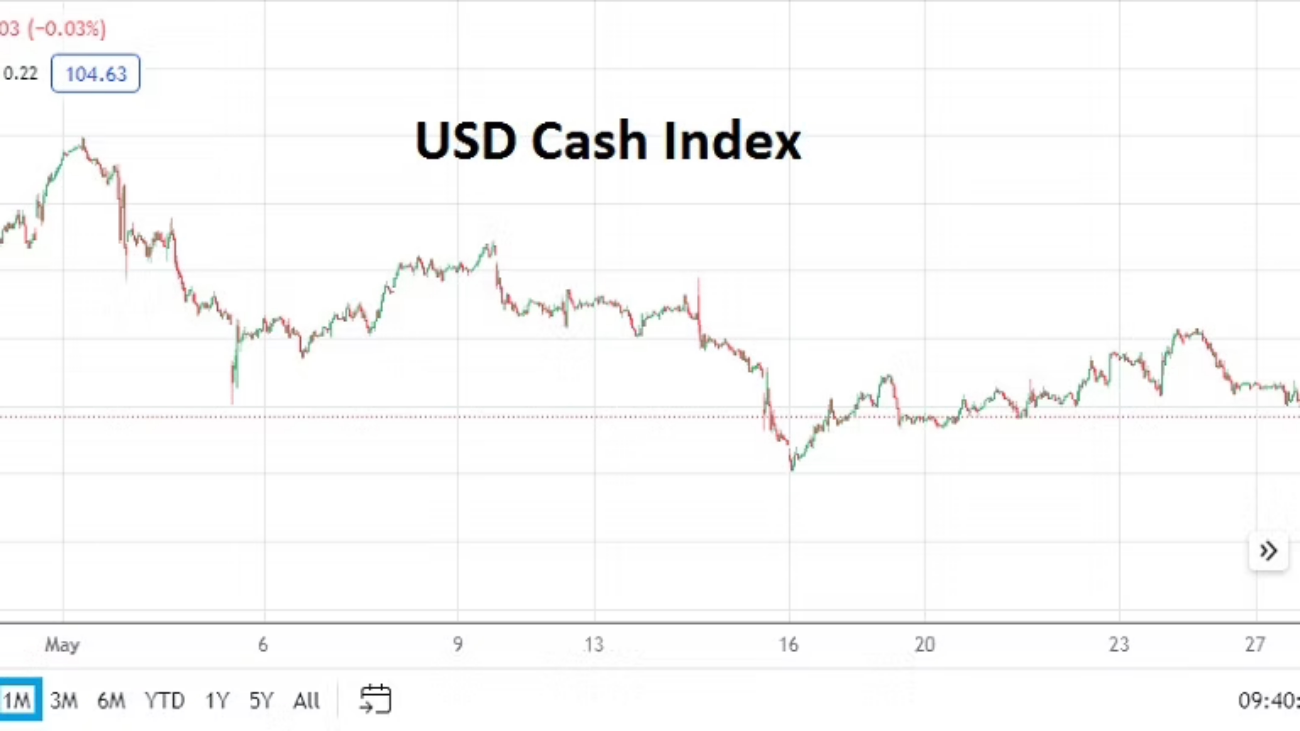
Forex markets have seen plenty of sideways action with the USD Cash Index lingering within the weaker parts of one and three month ranges. Yes, financial institutions appear to be leaning towards a belief the Federal Reserve will have to become more dovish over the mid-term, but last week’s price action before the onset of the long holiday weekend which has just passed did start to produce headwinds.

Risk appetite although high has climbed down from its peaks for the moment. Yet, financial institutions, investors and day traders likely still are aiming for more optimistic results. Speculative inclinations may believe more weakness is about to come from the USD, and major currencies are within sight of important technical barometers which could fuel more bets on a weaker USD to develop.

USD Cash Index One Month Chart on the 28th of May 2024

A taste for speculative buying in the equity indices while running out of some power last week remains within sight of highs. The Dow 30 and S&P 500 might have come off their records along with the Nasdaq, but the slight declines may be viewed as a buying opportunity by day traders.

However, before retail speculators dip their toes in the water they should understand that the Gross Domestic Product numbers this week will factor into existing behavioral sentiment. Again, taking a position for a short-term wager is different than buying an equity index as a long haul investment vehicle. The two are not the same and the daily fluctuations, even the weekly movements of the equity indices, do not bother investors who are gearing their outlooks for the long-term, while short-term moves can wipe out a person using too much leverage if they are pursing a casino like belief in direction without solid risk management.

Dow 30 Index One Month Chart on the 28th of May 2024

Yesterday’s holidays in the U.S and U.K have likely given financial institutions a chance to reflect on events and outlooks which will be unfolding and affecting sentiment. The announcement on Wednesday of last week that Britain will have a national election on the 4th of July will certainly start to create concerns for the GBP/USD.
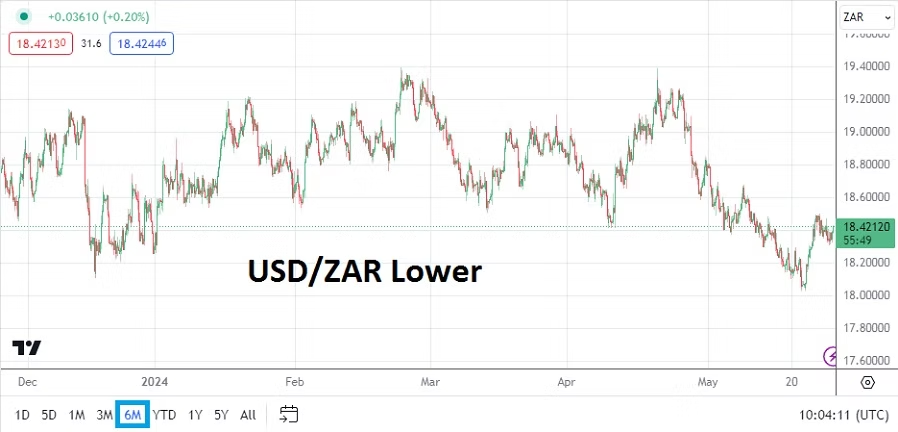
USD/ZAR Six Month Chart on the 28th of May 2024

Tomorrow the South Africa election will be held. While not an event which will get the attention of all investors, the implications of the vote in South Africa and the potential for a coalition should be watched. If the African National Congress is forced to form a coalition, investment managers will be hoping that the political maneuvering doesn’t bring about a ‘hard-left’ ruling government. Again while the investment stakes may not be felt by everyone around the globe concerning the results in the South Africa election, its impact on geopolitics long-term could be substantial.

International mining companies with large amounts of infrastructure and investment in the nation will certainly be keeping their eyes on events. There is a high level of suspicion within South Africa that load-shedding (rolling electrical blackouts) which has largely disappeared the past few months could reappear after the election, which highlights some of the distrust citizens have regarding the current leadership. The ANC has been in power for 30 years and tomorrow’s election marks one of the first times their leadership may prove vulnerable.
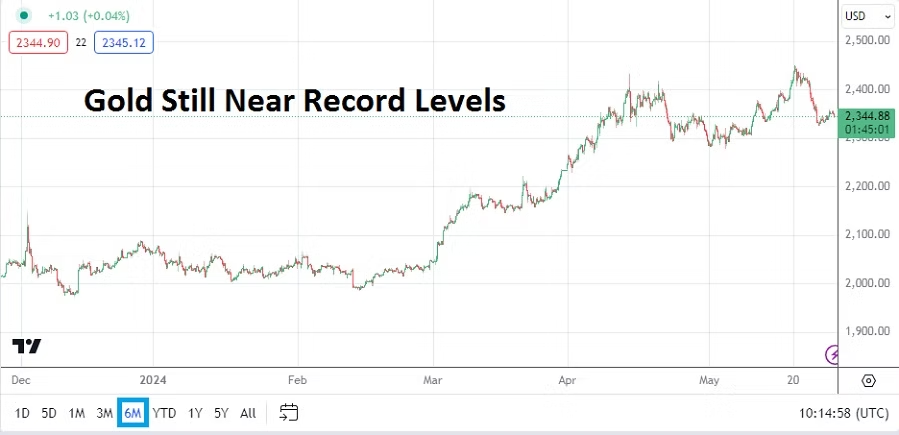
Gold Six Month Chart on the 28th of May 2024

As a clue for speculators and the level of complexity being seen in the financial markets near-term is that the price of gold remains elevated. Although not at its apex values, the price is certainly within sight of highs. What is interesting is that the record levels have taken place as USD centric attitudes have turned weaker the past month, showing that their is likely a large speculative presence within the gold market.

Certainly governments via central banks and other investors could be buying gold. The apex values in gold coupled with weaker USD sentiment which has developed the past month shows that nervousness still lingers. Again, long-term players in gold have much less to fear than short-term day traders who are betting on intraday price changes. Gold is a remarkably strong inflation hedge historically, but retail wagers on the price of the precious metal is a constant battleground. If the USD stays weaker over the mid-term it will prove very interesting to see where gold starts to display a durable support level – if in fact it is tested. There are gold bugs who certainly believe the price of the commodity should be much higher in relation to the unreliability of paper money in many spheres.

For traders who are looking ahead to the economic data risk events, the price of WTI Crude Oil needs to be given attention too. The price of the energy source remains under 80.00 USD per barrel which is important. If the costs of WTI Crude Oil remains stable this may cool some inflation fears. It should be noted that OPEC will begin conducting a conference to discuss Crude Oil production on the 2nd of June.

Tuesday, 28th of May, U.S Consumer Confidence via the Conference Board – the University of Michigan Consumer Sentiment numbers came in slightly better than expected last week. However, today’s reading is expected to be slightly lower than the previous result. Weaker than anticipated data could actually help the USD remain within its bearish technical range in Forex.

Wednesday, 29th of May, Germany Preliminary Consumer Price Index – this CPI result will impact the EUR/USD. The expectation is for a weaker result of 0.2% compared to previous outcome of 0.5%. If this number matches the expectation, this could put the European Central Bank into a collision course with financial institutions who want the ECB to take on a proactive dovish policy and begin cutting interest rates.

Thursday, 30th of May, U.S Preliminary Gross Domestic Product – the growth and Price Index numbers via the GDP reports will be significant and cause a large impact in the financial markets. Forex, commodities and equity indices (and Treasuries) will all be affected. The growth number is expected to be weaker than last month’s. Having produced lower results last month, if this GDP statistic is below the anticipated level of 1.3% it could set off fireworks. The GDP Price Index will have many eyes upon it too, and it carries a expected gain of 3.1%. Inflation remains a chief catalyst for the Fed and in Forex. The combination of the growth and price numbers is certain to cause volatility.

Friday, 31st of May, China Manufacturing PMI – economic data from China has been mixed recently, but foreign investment is still weak and the nation is looking for positive outcomes. Traders should keep their eyes on these numbers and also remember that economic results from China are not exactly the most transparent. Consumer numbers via retail spending domestically in China are still struggling. China is hoping to attain better trade relationships in Europe, but its intentions are running into a more competitive export landscape and political complications which are making the chances for a quick fix for its economy elusive.

Friday, 31st of May, U.S Core PCE Price Index – this report should be watched by Forex traders because it is highly regarded by the Federal Reserve as an inflation gauge. An outcome of 0.2% is the expectation for this report and if met, the USD could turn weaker going into the weekend.
postR160.1

Forex: Shifting Winds and Potential Optimism for Speculators

Forex: Shifting Winds and Potential Optimism for Speculators

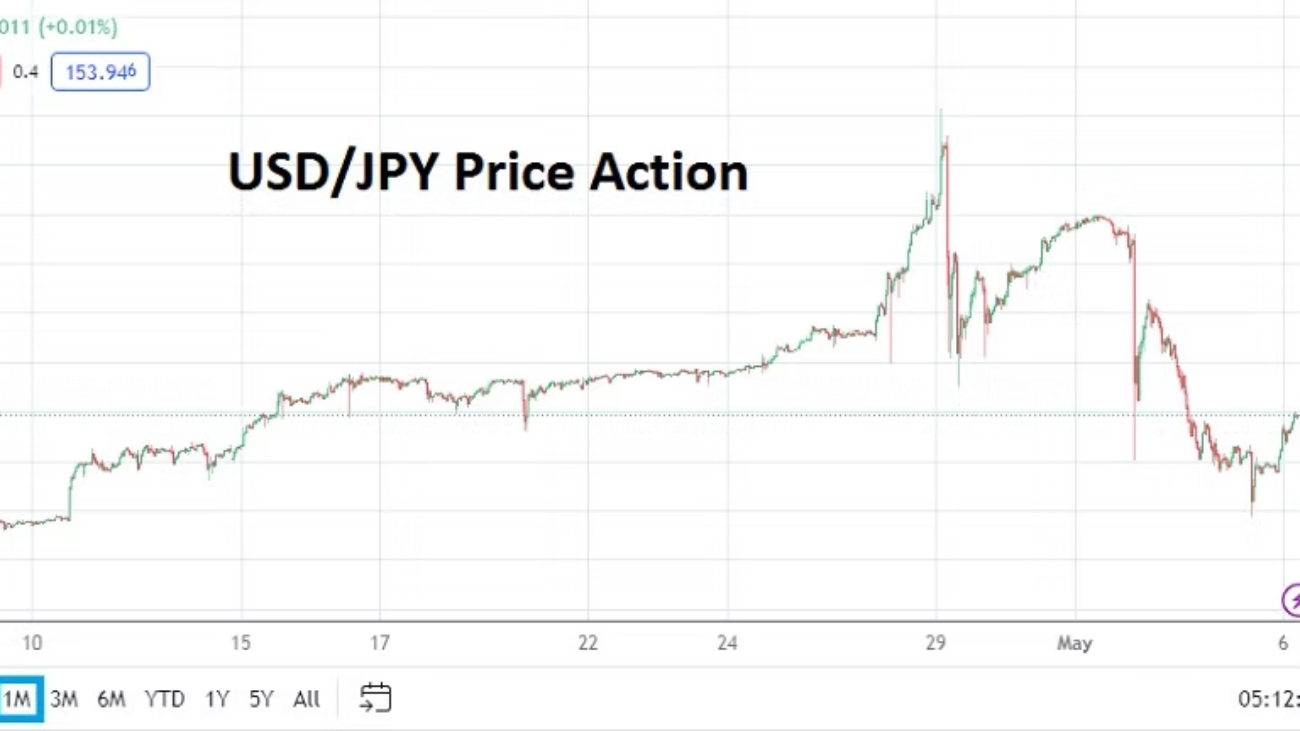
The BoJ intervened in Forex and propelled two fast selloffs of the USD/JPY last week. The actions by the Bank of Japan did not come as a surprise as the central bank seeks to maintain a dovish interest rate policy, a relatively weak Japanese Yen – but also a philosophy of not letting the JPY to suffer too much. Speculators and financial institutions got caught up in the price action which ensued as a clash developed between large traders and the BoJ as equilibrium was sought.

The BoJ clearly wants to keep the USD/JPY within the weaker realms of its long-term values to spur on the Japanese export sector with solid business results. However, domestically the Japanese government doesn’t want inflation within Japan to inflict too much pain for its citizens. BoJ interventions were carried out twice last week, once during a holiday in Japan, and the second when most global financial institutions were shuttered. At the time of this writing the USD/JPY is trading near the 153.720 mark.

Day traders always need to understand just how small they are within the larger speculative world. They need to judge economic intelligence and forecasts to get an understanding where behavioral sentiment could affect tides.

USD/JPY One Month Chart on 6th of May 2024

In the U.S, inflation and growth data caused investors to react nervously a week and a a half ago, additionally more anxious moments were fueled by the Federal Reserve’s FOMC Statement this past Wednesday when the Fed said it was uncertain about the timetable that inflation would return to their stated goal of two percent. Forex trading has been volatile the entire calendar year of 2024 for speculators.

Nearly ten days ago while inflation continued to prove it was stubborn via the U.S GDP Price Index on the 25th of April, Advance GDP data was much weaker than expected showing that economic growth was slowing. And last Friday’s Non-Farm Employment results were not only weaker regarding hiring, but also showed a slight drop in Average Hourly Earnings. This might have been enough to begin causing a shift in financial institution outlooks. This week of trading will prove interesting regarding risk appetite versus risk averse sentiment, particularly if large players believe economic data is finally catching up to the Fed’s rhetoric.

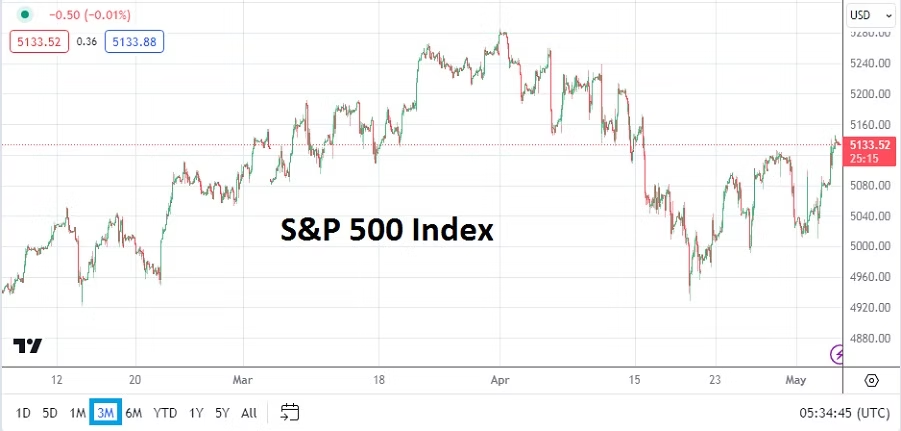
U.S equity indices which started last week with selling and battled lower depths in the middle of the week, began to see buying develop on Thursday, and finished Friday’s trading within their highs via weekly technical charts. While it is easy to report the past, it is the future speculators want to know. The ability of the U.S jobs numbers to produce results which were seen in a favorable light regarding the Fed’s ability to potentially cut the Federal Funds Rate certainly was an optimistic sign for financial institutions. If inflation can remain under control it would help the global economic picture. On that note, WTI Crude Oil is trading below 80.00 USD and should be monitored.

S&P 500 Index Three Month Chart on 6th of May 2024.

Monday, 6th of May, European Union Final Services PMI – Italy, France and Germany among other will present Purchasing Managers Index data. The broad numbers are mostly expected to replicate the previous month’s outcomes. Traders should note the U.K is observing a banking holiday today, which means lighter than normal Forex volumes will be seen.

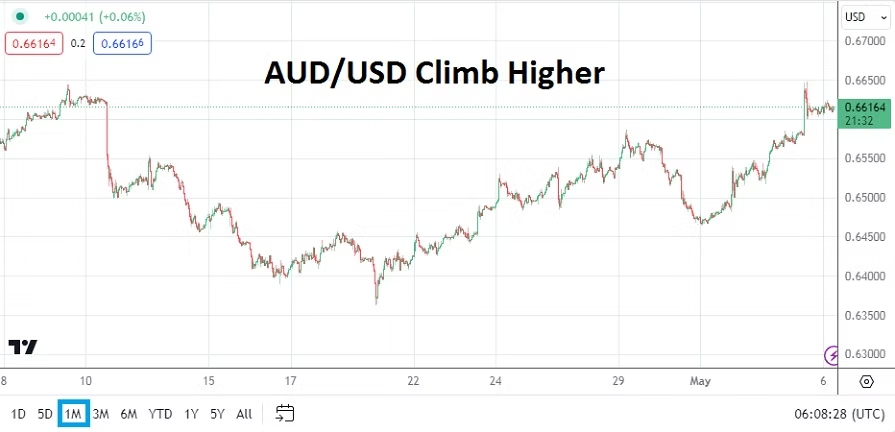
Tuesday, 7th of May, Reserve Bank of Australia Monetary Policy Statement – the central bank is not expected to change its interest rate. The AUD/USD has provided some upwards momentum the past week. The RBA is not expected to step out of line regarding global central bank policies. Expect talk about an optimistically cautious outlook by the RBA as they preach patience regarding an interest rate cut.

AUD/USD One Month Chart on 6th of May 2024

Wednesday, 8th of May, Bond Sales from Japan, the U.K and the U.S – while many European nations observe a holiday, Japan, Great Britain and the U.S will sell government debt. U.S Treasury yields should be watched and equity indices should have an eye kept on them. If behavioral sentiment remains optimistic as this day comes to a close it could set the table for more bullishness, particularly if the USD remains relatively tame or weaker.

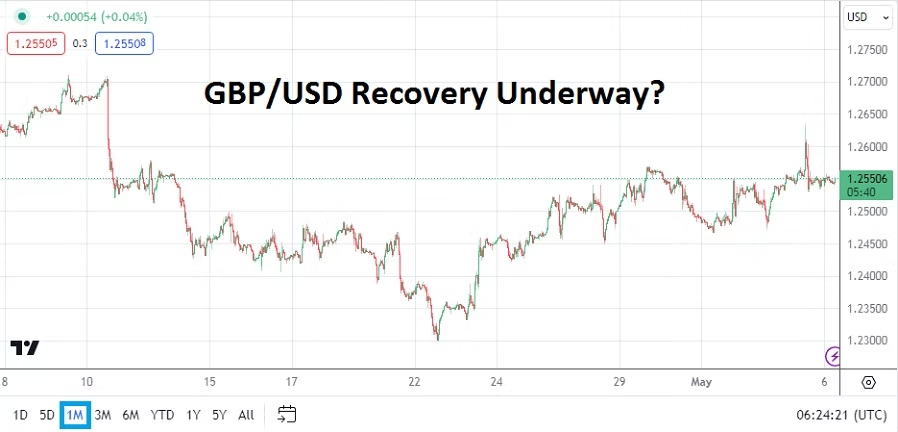
Thursday, 9th of May, Bank of England Monetary Policy Summary – the BoE is likely to mirror other central banks and keep its interest rate policy in place. No changes are expected to the Official Bank Rate. However, it would not be surprising to hear the BoE try to pose upbeat expectations, and if this occurs perhaps the GBP/USD will continue to find some momentum upwards.

GBP/USD One Month Chart on 6th of May 2024

Thursday, 9th of May, U.S Weekly Unemployment Claims – investors will keep their eyes on the jobs report. If the numbers come in around expectations this would allow risk appetite to remain strong in the near-term.

Friday, 10th of May, U.K Gross Domestic Product – an expected gain of 0.1% is forecast. GBP/USD traders who have bullish sentiment will be looking for the number to match expectations or beat the anticipated result. If the number is weaker, this could cause a reversal lower in the GBP/USD and an attempt to push back against gains made in the currency pair recently.

Friday, 10th of May, U.S Consumer Sentiment and Inflation Expectations via the University of Michigan – these readings will be watched by investors to see if consumers continue to show decreasing confidence in the U.S economy. While it sounds counter intuitive to want eroding sentiment regarding the ability to spend money, this would create more ammunition for the Federal Reserve to consider an interest rate cut. The Inflation Expectations could be the catalyst for traders going into the weekend regarding the USD.

post203

AMT Top Ten Miscellaneous Picks for the 26th of April 2024

AMT Top Ten Miscellaneous Picks for the 26th of April 2024

10. Salk Institute: Work known as the Harnessing Plants Initiative is focused on optimizing the ability of plants to help combat climate change, sometimes via root systems in order to help reduce carbon dioxide. Problematically when plants die they do release carbon dioxide too. One key to the HPI project maybe altering the affects of Suberin. The Salk Institute received 50 million USD last year from the Hess Corporation to fight climate change.

9. Anticipation: Chicago is celebrating today after landing quarterback Caleb Williams and wide receiver Rome Odunze as hoped. However, as the August 2024 Democratic National Convention approaches, trepidation for the potential of nasty demonstrations is building.

8. Quantum Investing: Oak Ridge National Laboratory has announced a successful test using the H1-1 computer via Quantinuum to study the spread of disease via quantum mathematical models. Honeywell International Inc. owns a large stake in Quantinuum which is a stand alone company valued at approximately 5 billion USD.

7. Speculative: Gold is near 2348.00, the price is below values seen last week, but remains high via some perspectives as the USD creates havoc.

6. Forex: Whipsaw volatility has been seen in foreign exchange as financial institutions fight to get a proper gauge on their mid-term outlooks. Equilibrium will continue to be fought over today.

5. Fixed Income: U.S Treasury yields are battling within higher ground as investors look for guaranteed returns as behavioral sentiment remains fragile. And there is a likelihood the next four days of trading will continue to produce a whirlwind.

4. Equities: Major U.S indices continue to grapple with headwinds caused by a murky economic outlook. Retail traders speculating via CFD’s should remain careful. Patience is a key for the S&P 500, Nasdaq Composite, and Dow 30. Trying to ‘time’ the indices for short-term wagers is dangerous because technical trends are vulnerable.

3. Data: U.S Core Personal Consumption Expenditures Price Index statistics will be released today, inflation via the GDP Price Index came in higher than expected yesterday. Forex will react to the PCE results which is anticipated to have a gain of 0.3%. Financial institutions do not need another scare today. The Revised University of Michigan Inflation Expectations reading should also be given attention which will be published afterwards.

2. BoJ: The Bank of Japan is clearly playing a game of truth or dare with Forex. Having held interest rates at merely 0.10% earlier today, the USD/JPY climbed comfortably above 156.000 and is presently near the 156.540. The BoJ will remain in the news as the USD/JPY trades around a 34 year high. As financial institutions clamor for a higher interest rate, the BoJ apparently is more concerned with creating dynamic export demand and growing Japan’s economy, believing it can keep inflation under control. Speculators need to be on alert for an intervention from the Bank of Japan, but cannot count on one either.

1. Analysis Paralysis: The Federal Reserve was served an intriguing dose of results via the lower than expected growth numbers from the Gross Domestic Product yesterday, while digesting a higher GDP Price Index. Jerome Powell has stressed caution and patience. However, yesterday’s stubborn inflation numbers with waning growth creates the prospect for stagflation. This is an important political year because of the upcoming U.S elections in November. Next Wednesday the Fed’s FOMC Meeting pronouncements will be made. There will not be a change to the Federal Funds Rate on the 1st of May. It is the FOMC Statement’s vocabulary which will get attention. Today’s inflation reports will play a role in next week’s Fed meeting. Day traders may want to tune out political noise from pundits today which will certainly be sounded. The inflation numbers globally are tricky, and have created overthinking by investors and central banks which remain mostly reactive.

post203

AMT Top Ten Miscellaneous Missiles for the 19th of April 2024

AMT Top Ten Miscellaneous Missiles for the 19th of April 2024

10. Fusion: The U.S Senate presented legislation yesterday which creates guidelines allowing the Nuclear Regulatory Commission to authorize commercial investment and research of fusion energy. Significant strides are being made in the technology and the U.S government is preparing for the newest developments.

9. Cup of Joe: Your cafe is going to get more expensive. Robusta and Arabica coffee both remain at higher values having hit apex prices respectively this Wednesday and Thursday. And Cocoa remains ‘comfortably’ above 11,000.00 USD per metric ton this morning.

8. United Arab Emirates: The UAE has been hit by heavy weather, suffering its biggest rainfall in 75 years. It was reported that over 14 centimeters of rain fell this Tuesday in Dubai, which is the equivalent to one and a half year’s worth of typical accumulation in the city.

7. India Elections: The vote in the world’s biggest democracy has begun as millions decide on the the Lok Sabha. The election process will take place for nearly a month and a half with the results formally being presented on 4th of June. The Bharatiya Janata Party is expected to win a majority in the House of the People, thus likely re-electing Narendra Modi as the country’s Prime Minister.

6. Gold: The precious metal remains within sight of record values with the price around 2,388.00 USD per ounce. Today’s earlier ratios touched the 2,420.00 vicinity.

5. Cone of Silence: Israel and Iran have remained mum on military counterstrike action scuttlebutt, which was heard this morning throughout global media. The silence from the two nations did not stop the Nikkei 225 Index from dropping over 1000 points upon the news.

4. Bitcoin Halving: A coding change is anticipated to occur soon in Bitcoin which will affect ‘mining’ parameters for the digital asset. The code change will double the amount processing needed to create one BTC, making it twice as expensive for Bitcoin operators. Day traders tempted to wager on BTC/USD over the next couple of days need to be careful. BTC/USD is near 64,560.00 at the moment of this report.

3. Fear Factor: Price of WTI Crude Oil is near 82.70 USD per barrel. Large energy traders continue to show they are experienced in geopolitics, remaining relatively calm as Middle East concerns are being brandished.

2. While Flag: U.S Fed Chairman Jerome Powell conceded that inflation remains stubborn earlier this week. Stagflation is not being discussed openly by the Fed, but it is likely raising concerns among global central bankers. The USD has returned to very strong levels as financial institutions brace for the possibility of U.S interest rates remaining high into the late summer.

1. Behavioral Sentiment: Equity indices, Treasury yields and Forex are within the midst of nervous seas as central banks and geopolitical concerns create storms. Speculators should make sure they pay attention to the waters they traverse with their bets, which could prove dangerous to navigate in the near-term.

postN51

AMT Top Ten Miscellaneous Postings for the 5th of April 2024

AMT Top Ten Miscellaneous Postings for the 5th of April 2024

10. Petrichor: The pleasant smell after a rain has fallen following a long dry spell which elicits earth’s fragrance. The Fed is likely hoping for this sensation via ‘weaker’ Non-Farm Employment Change numbers today. In December the Federal Reserve spoke about data signals needed in order to cut interest rates. If jobs statistics are stronger than anticipated, there will be no ‘petrichor’ for the Fed.

9. Underreported: Five engineers from China on their way to work for the Dasu dam project they participated, were killed in a ‘suicide’ terrorist attack in Pakistan on the 26th of March. Terror attacks in Pakistan on Chinese involved with infrastructure ‘Economic Corridor’ work have been increasing.

8. Qubits: Microsoft and Quantinuum recently announced they have made breakthroughs regarding quantum computing research reliability. Results have shown 14,000 ‘test routines’ without errors. The emergence of quantum technology approaches.

7. Intrinsic Value: Cocoa is near 9640.0 USD per metric ton as of this morning and remains speculatively energetic. Bitcoin is slightly below 67,000 USD and continues to ‘beat’ the notion that intrinsic value is important.

6. Precious: Gold prices have ‘fallen’ below 2300.00 USD per ounce, and is near 2289.00 for the moment, but the metal is shining as crowds admire its ability to create a safe haven.

5. WTI Crude Oil: Middle East news is rumbling and hyperbole is resonating, the price of the commodity is over 86.40 USD per this writing. A calm weekend, and peaceful end to Ramadan this coming Tuesday might help calm nerves. Higher oil prices will not help global inflation.

4. Forex: The USD/JPY has started to experience waves of volatility and has recently challenged long-term highs. Bottom line is the notion that large players are positioning for today’s U.S data which will affect all financial assets as USD centric power resounds.

3. Equities: The U.S major stock indices are beginning their day near lows not seen since the 15th of March for the Dow 30, and the 19th of March for the S&P 500 and Nasdaq Composite. Nervous?

2. Bonds Watch: U.S Treasuries need to be monitored as the 5, 7, and 10-Years Notes respond to nervous investors and fears of a new ‘inversion’. Having come off of high yields a couple of days ago, doesn’t mean all is well as values languish near late September 2023 technical realms.

1. Data: Recent chatter from many Fed FOMC members have created anxious investors. Vivid reactions will occur after the Non-Farm Employment Change and Average Hourly Earnings. Bluntly, today’s jobs reports are crucial and the Fed would like the results to be weaker than anticipated in order to consider cutting interest rates. However, if hiring comes in stronger, it would be a sign of a resilient U.S economy and would ignite more USD strength. The first half hour following the jobs numbers may look counter-intuitive regarding price action as financial institutions adjust their trading positions.

postN78.1

USD and the Fed: Parade of Jobs Data Ready to Make Noise

USD and the Fed: Parade of Jobs Data Ready to Make Noise

U.S data last week created landmines for Forex speculators and the Federal Reserve. Global financial markets return to full action today following the long holiday weekend. Growth and inflation numbers from the States last week provided more unsettling results for financial institutions. While Forex has proven difficult for many traders, the major equity indexes are flirting with highs but also running into some intermittent headwinds.

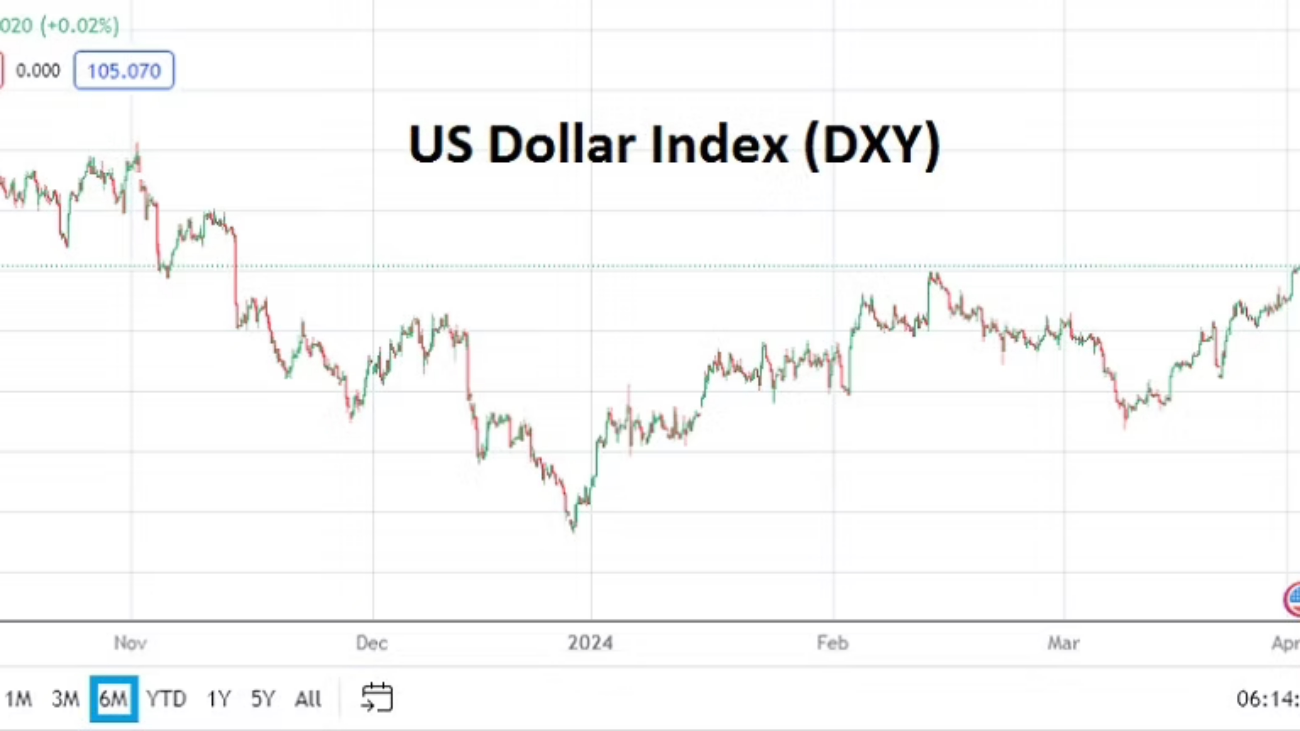
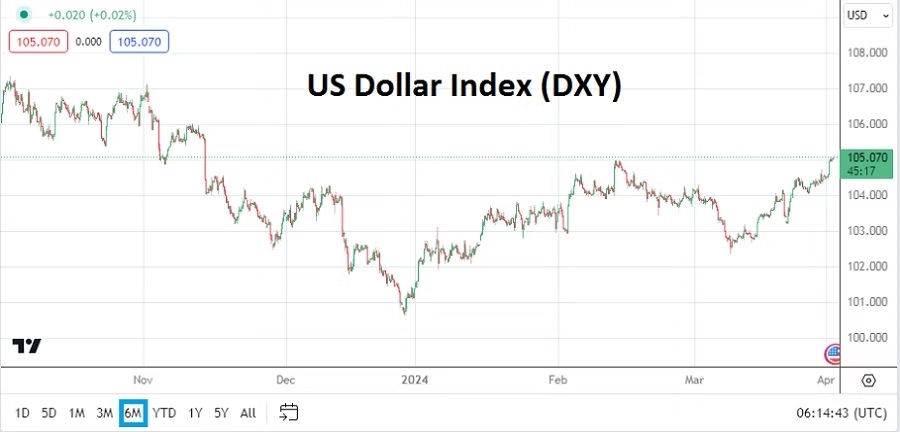
US Dollar Index Six Month Chart as of 2nd April 204

In December of 2023 the Fed was interpreted as having confirmed it would be able to cut the Federal Funds Rate during the 2024 calendar year rather consistently. Dovish policy had been anticipated by financial institutions which began to sell the USD aggressively in November. But by the end of the Christmas week the USD had essentially hit lows in many major currency pairs, and as January started reversals intensified.

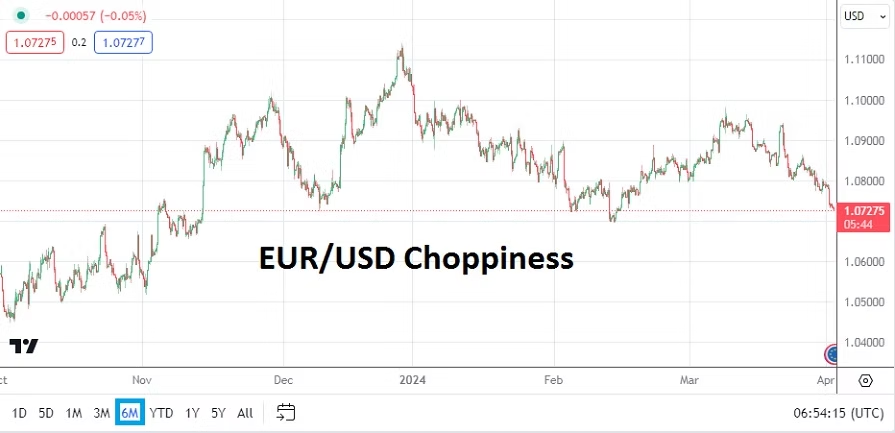
The last three months of trading has produced choppy conditions in Forex, but one thing is clear – financial institutions no longer believe the Federal Reserve will be able to aggressively cut the Federal Funds Rate. The Fed has now begun to show signs that it is nervous regarding U.S economic data, this as growth via GDP numbers has remained firm, inflation sticky, and consumers resilient. Clouds shadow Forex and day traders have been hampered by a lack of solid trends.

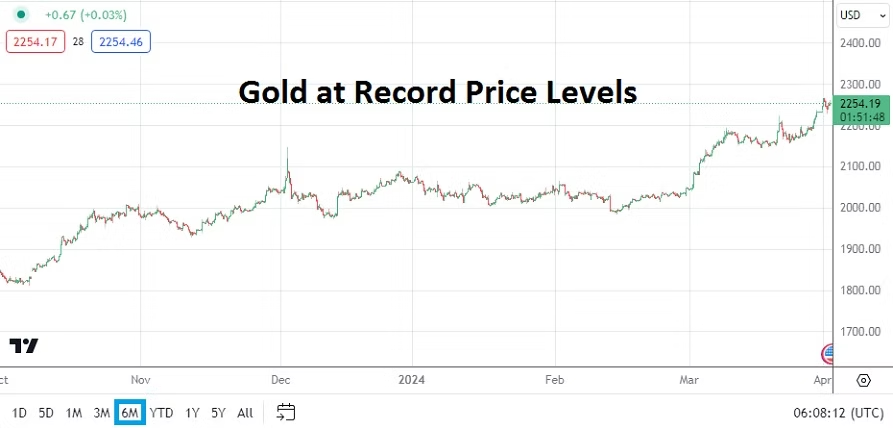
Gold Six Month Chart as of 2nd April 2024

Gold is trading near record price levels. The fact that the precious metal is touching all-time values as the USD has been strong has flustered some speculators. But traders need to remember Gold is affected by large players, including nations, that may be hedging USD bets and preparing for political instability. The price of Gold may underscore belief the U.S Fed will have to cut rates at least a couple of times this year no matter the economic facts on the ground, because this is an election year and if the central bank doesn’t deliver on its ‘promise’ jobs at the Fed may be at stake.

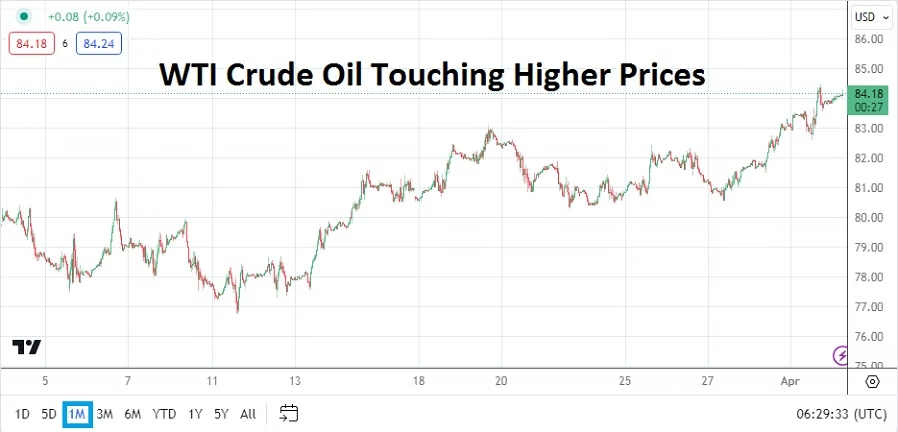
WTI Crude Oil One Month Chart as of 2nd April 2024

Not making anything easier for Federal Reserve policy is the higher price of WTI Crude Oil which has reached the 84.00 USD per barrel price. If energy costs go higher this will not help the fight against inflation. OPEC will be conducting a meeting this week. As an aside the price of Cocoa per metric ton is now over 10,000.00 USD, which is more expensive than Copper. While the price of Cocoa is not a game changer for global financial markets, the higher price will make chocolate more expensive, which some traders may find disagreeable as they try to relax and watch their speculative wagers while trying to nibble on their favorite snack.

Monday, 1st of April, U.S ISM Manufacturing – both the Purchasing Managers Index reading and the Price numbers came in higher than expected. The stronger results show the U.S economy remains better than anticipated by the Federal Reserve, which has been counting on its higher interest rate to slow down growth and inflation.

EUR/USD Six Month Chart as of 2nd April 2024

Tuesday, 2nd of April, European Manufacturing PMI – the European Union and Great Britain will release their business readings today. The results will demonstrate insights regarding sentiment. Financial institutions are worried the European Central Bank and Bank of England may have to consider lowering their interest rates before the Federal Reserve. The EUR/USD and GBP/USD will react to the results.

Tuesday, 2nd of April, U.S Federal Reserve FOMC Members – there will be appearances throughout the day in the U.S from various Federal Reserve members who will make the case for their monetary policy outlooks. It should be noted that Jerome Powell will be speaking on Wednesday. The JOLTS Job Openings will come out before the FOMC members speak. While the JOLTS report will not cause earth shattering reactions, the jobs data is the beginning of the parade regarding employment statistics for this week.

Wednesday, 3rd of April, U.S ISM Services PMI – taking into account the Manufacturing report came in stronger than expected on Monday, the Services data will be watched by financial institutions. If this report is better than anticipated, USD sellers will not rest easy. The ADP Non-Farm Employment Change data will also be released on this day.

Thursday, 4th of April, U.S Weekly Unemployment Claims – the Federal Reserve has been counting on employment strength to erode based on their notion that higher interest rates would create ‘lagging’ reactions in the jobs sector. Jerome Powell has said the Fed is anticipating weaker employment data. The results from the weekly report will not be as significant Friday’s data, but should be given attention by day traders in Forex.

Friday, 5th of April, U.S Non-Farm Employment Change and Average Hourly Earnings – the climax for speculators this week will be these jobs numbers from the States. If the numbers produce less hiring than expected this would help USD bearish momentum. Wages will also prove crucial regarding behavioral sentiment for financial institutions. Simply put, the Federal Reserve is anticipating that weaker employment numbers are going to be seen, if this doesn’t happen it might cause major volatility in Forex going into the weekend.
postN51

AMT Top Ten Miscellaneous Musings for the 29th of March 2024

AMT Top Ten Miscellaneous Musings for the 29th of March 2024

10. Holidays: We wish everyone a peaceful long weekend. Hopefully the price of your chocolate eggs have not emptied your wallets.

9. Superconductivity: Nuclear fusion and magnets have a future together. Efficient electricity produced via compact generation is being worked on by the Massachusetts Institute of Technology and the Jet Propulsion Laboratory of NASA.

8. TMTG: The Trump Media and Technology Group listed as DJT on Nasdaq ended yesterday’s trading within sight of 62.00 USD. The price is overbought taking into consideration its lack of revenues. However, because of its limited available shares, ‘shorting’ DJT is dangerous and a potentially expensive mistake.

7. Silly Season: U.S elections are growing closer and louder. However, fiscal and foreign policy clarity doesn’t get much airtime. Bread and circus for the masses.

6. Crypto ‘Insanity’: FTX Founder Sam Bankman-Fried was sentenced to 25 years in prison yesterday for his crimes. In the meantime, Bitcoin is over 70,000.00 USD this morning. Binance Coin is valued above 600.00 USD.

5. Frothy: Gold is near 2,230.00 USD per ounce, even as the USD grows in strength. Cocoa closed yesterday around 9,792.00 USD per metric ton, meaning it is more expensive than Copper, and the reason why your chocolate may be getting costly.

4. ‘Quiet’ Data: Core Personal Consumption Expenditures Price Index data will be released today in the U.S, this as the financial markets are largely absent. Yesterday’s GDP and Consumer Sentiment numbers were stronger than expected. The inflation statistics may not get much fanfare today, but paying attention to the results could prove worthwhile for speculators.

3. Risk Warning: The return of large trading volumes next week are likely to cause volatility as financial institutions reopen and are reactive.

2. Bias: Many major currencies are struggling against the USD. Traders who believe their chosen currencies have been oversold should contemplate their perspectives and potential bias. Just because you believe something, doesn’t mean it is true. Forex is expressing nervous behavioral sentiment.

1. Fed Watch: Many analysts are starting to believe the Federal Reserve may not be able to cut interest rates this year, but traders should remember politics will be crucial as the U.S Presidential Election approaches. The Fed may be ‘independent’ but they are not deaf. If inflation remains stubborn, the Fed will need weak jobs numbers. But weekly Unemployment Claims came in below expectations yesterday. Financial institutions understand the U.S central bank is in a difficult place.

postN79.1

Forex Volatility and Coming Data Attractions for this Week

Forex Volatility and Coming Data Attractions for this Week

Nervous trading results have hurt many day traders and likely financial institutions too, as behavioral sentiment in Forex gets blindsided by rather mixed U.S data and the Federal Reserve not giving a definitive answer regarding monetary policy. The violent trading in the USD last week was expected, but the turbulence that many Forex pairs experienced on Thursday and Friday of last week was rather vicious. For all the perceived sophistication of Forex markets via financial institutions, the trading results last week point to a definite fear of the unknown.

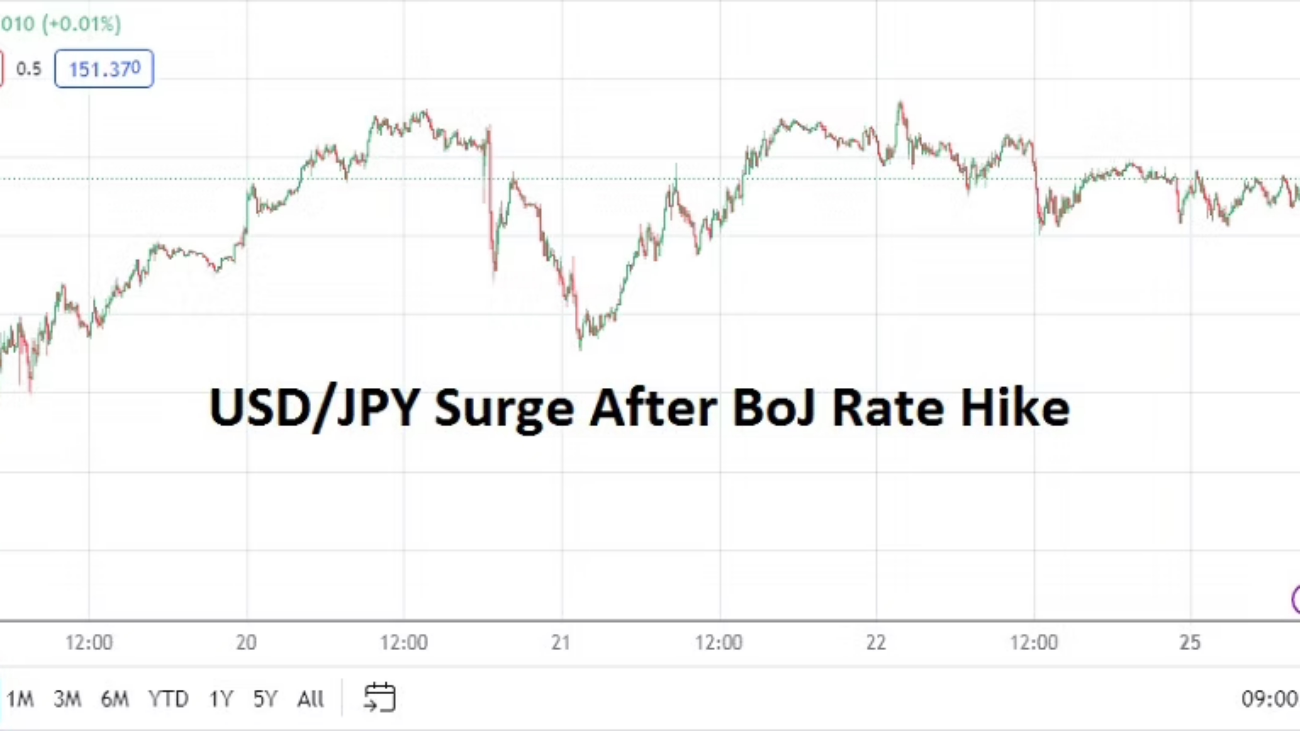
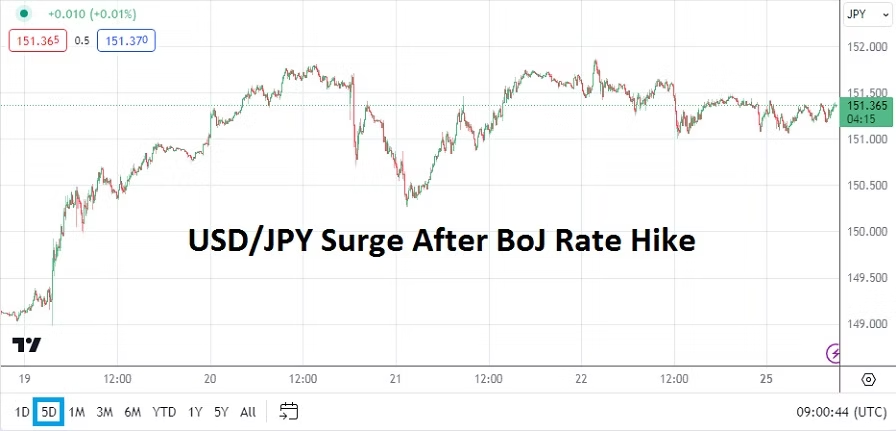
USD/JPY Five Day Chart as of 25th March 2024

While the Bank of Japan finally changed its interest rate policy and moved to a Policy Rate of 0.10% early last week, this did not create selling momentum in the USD/JPY. The Federal Reserve’s dangling of potential interest rates to come this year caused temporary weakness in the USD, but as financial institutions and their clients looked at the prospects for a more dovish Fed they apparently became unimpressed as the days passed.

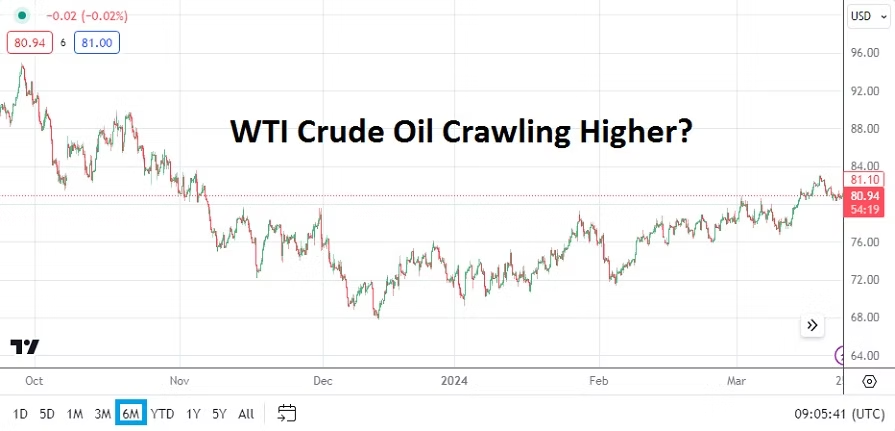
WTI Crude Oil Six Month Chart as of 25th March 2024

The Fed seems to be betting on weaker jobs numbers developing, and there has been data which points to part-time jobs increasing, and full-time jobs becoming harder to find in the States. Jerome Powell said last week that if jobs numbers start to show weakness that the Fed would be willing to begin cutting interest rates even if inflation remains sticky. Lagging economic data correlations have not eased the Fed’s problems.

The Fed has also admitted inflation in housing, transportation and food remains problematic. WTI Crude Oil spent much of last week above 80.00 USD per barrel as its price has begun to show signs of rising incrementally again; and there is little the Fed can do about more expensive energy costs should they be seen. Higher costs for logistics will not make anything cheaper. Pricier mortgages, more expensive rent and insurance rates for cars and gasoline is creating serious knock on effects.

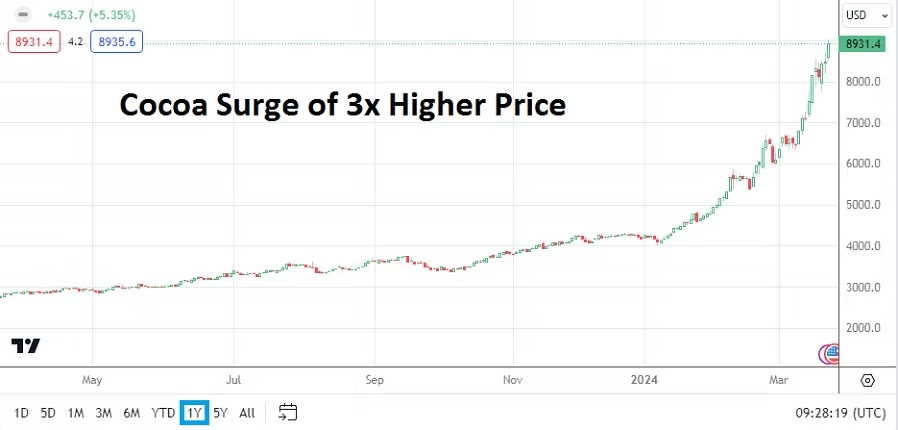
And for the sake of acknowledging the screaming prices in Cocoa, please have a look at the chart below which should explain why your chocolate products are going to be more expensive in the coming months. The price of the most delicious commodity in the world has tripled in less than a year’s time and is around 8931.0 USD per metric ton as of this writing.

Cocoa One Year Chart as of 25th March 2024

Gold turned in a violent week of trading too as it reached 2224.00 last Wednesday, only to fall back to a known value around 2165.00. Day traders are dealing with violent cycles in Forex because sustained trends have been nearly impossible to find. While U.S equity indices are fighting upwards, speculators who are afraid of heights are likely being cautious if they are betting merely on the daily results from the S&P 500, Nasdaq 100 and Dow Jones 30 instead of investing for the long-term.

This week’s coming data from the U.S is important, financial institutions are already dealing with plenty of noise, and they will have to be careful regarding their interpretations regarding the coming economic statistics. Meaning day traders who are speculating in all financial assets should use risk taking tactics that are planned significantly in advance.

Monday, 25th of March, U.S New Home Sales – a slight gain is expected, but mortgage rates continue to shadow the housing sector and cause concerns.

Tuesday, 26th of March, U.S Consumer Confidence via the Conference Board – the reading is anticipating a slight increase. Consumer numbers from the U.S have come in mixed recently. A stronger result than estimated might not be welcomed by traders with bearish sentiment regarding the USD. The Fed wants its cake and to eat it too, they would like to see weaker consumer numbers and a soft economic downturn. If U.S shoppers remain confident this could help sustain inflation. It should be noted too, that Core Durable Goods Orders data will be released one and a half hours before the Consumer Confidence numbers.

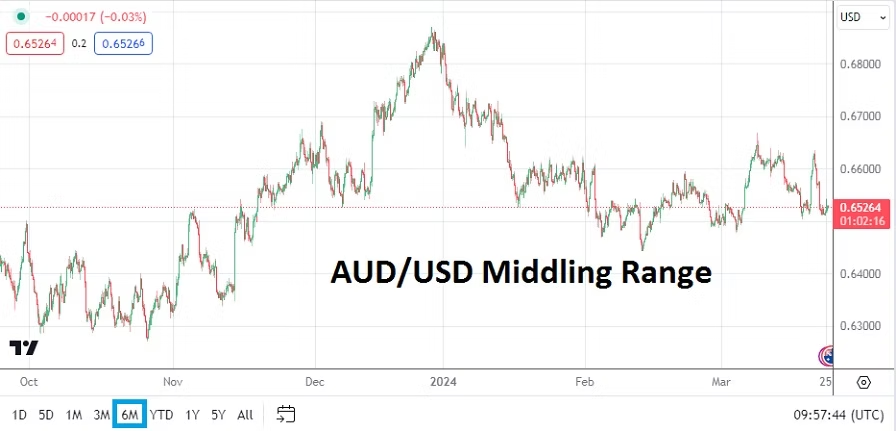
AUD/USD Six Month Chart as of 25th March 2024.

Wednesday, 27th of March, Australia Consumer Price Index – inflation numbers are expected to come in slightly higher than the previous results. Like most other central banks, except for the BoJ, the Reserve Bank of Australia would enjoy seeing inflation erode. The AUD/USD will react to the results certainly, but the price action might prove complicated because of USD centric notions.

Thursday, 28th of March, U.S GDP, Weekly Unemployment Claims, Pending Home Sales, and Revised Consumer Sentiment from the University of Michigan – put bluntly day traders will have to be well prepared for the combination of data from the States. Spectators who do not have large trading accounts and cannot take on a great amount of risk, should seriously consider sitting on the sidelines until most of the data is published. The GDP numbers will be watched carefully, while they are expected to match last month’s total, any surprises will affect the USD immediately in Forex. Weaker growth numbers might cause USD sellers to ignite positions.

However, before traders react too much to the Gross Domestic Product numbers, the Weekly Unemployment data will also impact the financial market. Financial institutions are anticipating a higher amount of unemployment claims this week. Also, at the same time as the growth and jobs numbers, the Final GDP Price Index numbers will be brought forth. The mixture from these reports could cause speculative whiplash.

The housing sector numbers and consumer numbers which come one and a half hours later will finish off a very big day for traders and institutional investors. The wide array of data could make this coming Thursday rather loud, and again rather dangerous for retail traders to participate.

Friday, 29th of March, Japan’s Tokyo Core Consumer Price Index – the inflation numbers are expecting to show a slight decrease to 2.4%. The result should certainly be watched by USD/JPY and GBP/JPY traders. If the number were to come in higher than expected, this could cause additional volatility for the Japanese Yen. Financial institutions seemed to indicate last week they would like to see the BoJ become more aggressive with their Policy Rate.

Friday, 29th of March, U.S Core Personal Consumption Expenditures Price Index – the reading is expected to be below the previous month’s total. Traders should be on the lookout for revisions to past results. Financial institutions know this inflation number is important for the Federal Reserve, but they are concerned the U.S central bank doesn’t have the ability to combat inflation which is not part of the Core number. Energy and food costs which are hurting U.S consumers are not part of this report and likely making the Federal Reserve gun shy regarding monetary policy – which has caused a large part of the USD whipsaw trading results that Forex has experienced.

postN51

AMT Top Ten Miscellaneous Entries for the 22nd of March 2024

AMT Top Ten Miscellaneous Entries for the 22nd of March 2024

10: Jefferson: Jon Meacham’s Thomas Jefferson The Art of Power provides well written historical and psychological insights concerning one of the U.S Founding Fathers.

9. Shohei Ohtani: Major League Baseball has a gambling scandal. Claims that Ohtani’s interpreter ‘stole’ over 4 million USD from the player to pay off gambling debts beg for questions.

8. Saudi Arabia: The nation has announced it plans on investing 40 billion USD into Artificial Intelligence sector companies via its Public Investment Fund (sovereign wealth fund) and potential business partners.

7. Steve Jobs: Apple’s innovation and tech leadership appears to be weakening as the absence of its deceased leader fades into memory, and competitors grow.

6. Bank of Japan: Monetary policy was finally shifted on Tuesday, an interest rate of 0.10% was instituted, today’s National Core CPI data came in at 2.8%. USD/JPY is currently around 151.400 suggesting financial institutions believe the BoJ Policy Rate may have to be raised again.

5. Gold & Forex: The precious metal challenged 2223.00 USD on Wednesday after the Fed’s FOMC rhetoric but is trading near 2165.00 as of this morning, this as the USD has gotten stronger again producing FX volatility.

4. Hot Chocolate: Cocoa finished yesterday at 8477.0 USD per metric ton, the commodity cost 2880.0 USD one year ago. What and who are manipulating the market?

3. China: Official Foreign Direct Investment statistics are supposed to be released soon. China argues that the fall of foreign investment capital is being reported with bias and not taking into consideration the impact of coronavirus, global monetary policy changes, and cyclical investment fluctuations. However, the FDI numbers remain troublesome and should be watched.

2. Risk Appetite: Major U.S equity indices including the S&P 500, Nasdaq Composite, and Dow Jones 30 are challenging record highs as behavioral sentiment remains exuberant, along with Japan’s Nikkei 225.

1. Interest Rates: The Federal Reserve has hinted three interest rate cuts ‘could’ happen this year, this while inflation in housing, transportation and food remain significant for U.S consumers. The Fed seems to be indicating it believes U.S jobs data will get worse. Political shadows hover over the central bank as the presidential election draws closer. The Fed only has 6 FOMC meetings left and appears to be playing with fire.

postN80.2

Risky Outlooks: Central Banks and Inflation Colliding

Risky Outlooks: Central Banks and Inflation Colliding

Most traders and investors begin their pursuit of financial assets with an optimistic perspective. However, the markets and ability to speculate also allows those who have other outlooks to equally participate. The past week once again delivered U.S inflation data which was not anticipated. While last Tuesday’s CPI results came in slightly stronger than expected, it was Thursday’s PPI which provided surprises for many.

Producer Price Index Warning from AMT for the 14th of March 2024

Yet, some market participants may not have been utterly shocked by the results. Perhaps it was lucky to ‘guess’ the PPI numbers could cause volatility last Thursday, but the ability to be alert and attentive to the possibility of risk should not be ignored. Risk management is important for all traders.

This coming week will continue to be intriguing for day traders as they try to sail through speculative waters which are going to deliver shifting behavioral sentiment tides. A parade of central banks are ready to step into the limelight and they will focus on the word: inflation. Technical traders who wager on support and resistance levels in the coming days should not be scorned, because sideways and volatile trading results are likely.

U.S equity indices began to struggle the middle of last week, Gold has traded lower and Treasury yields have ticked upwards in recent market action, this as sentiment has again had to acknowledge economic outlooks remains problematic. Trading decisions this week will depend not only on what the central banks say and ‘do’, but also focus on the duration that a speculative position intends to be working.

Monday, 18th of March, China Industrial Production – a gain of 7.0% has beaten the expectation per the data already published this morning. Retail Sales numbers came in slightly below estimates, but Fixed Asset Investment numbers were better than anticipated. However, China’s data remains troublesome and the economic path ahead for the nation must overcome deflation and trust issues from international investors. A lack of confidence from the Chinese public about the value of Real Estate and the over abundance of available property is causing major headwinds economically.

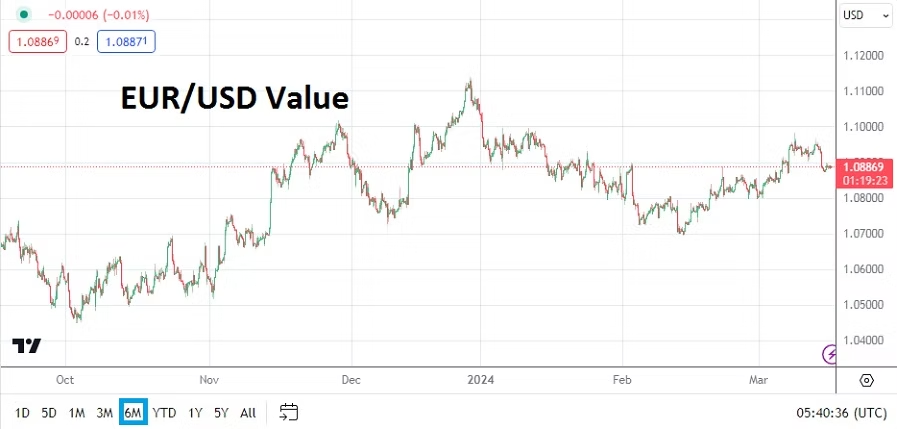
EUR/USD Six Month Chart as of 18th March 2024

Monday, 18th of March, E.U Final Core Consumer Price Index – the European Union will release crucial inflation data. An expected gain of 3.1% is the estimate. While this data release is not considered vital by many investors, the inflation statistics should be watched. The EUR/USD has produced mixed results the past four months as shifting behavioral sentiment due to battling perceptions regarding central bank policy outlooks converge.

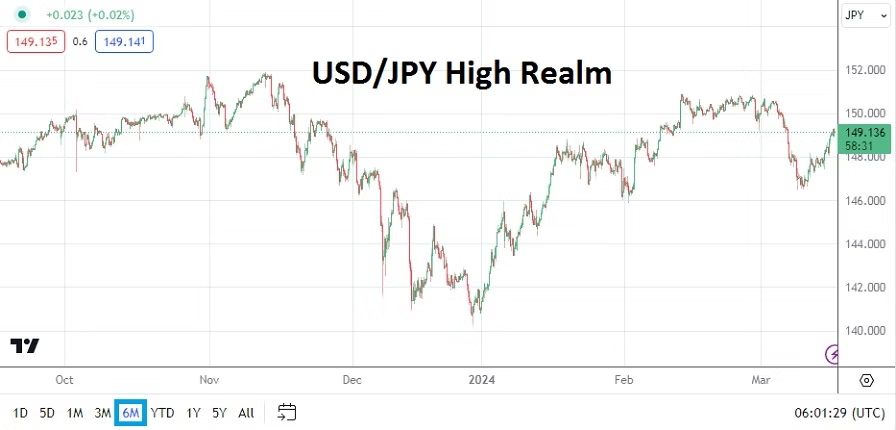
USD/JPY Six Month Chart as of 18th March 2024

Tuesday, 19th of March, Bank of Japan – the BoJ will deliver their Monetary Policy Statement and Policy Rate. While no numerical change is expected from the BoJ, signs for a change in rhetoric will be looked for as central bank observers try to read the tea leaves. The Japanese economy is within an intriguing spot, there have been signs of improvement, but the Bank of Japan is likely to remain on a conservative path regarding negative interest rates for the moment. The USD/JPY remains within the higher realms of its price range as the currency pair grapples with global inflation outlooks.

AUD/USD Six Month Chart as of 18th March 2023

Tuesday, 19th of March, Reserve Bank of Australia – the RBA is expected to parrot the pronouncements of the other central banks as they point to stubborn inflation and ‘improving yet lackluster’ economic outlook. Trading in the AUD/USD has been choppy and the volatility is likely to continue within the known price range.

Tuesday, 19th of March, Canada CPI – the Consumer Price Index data is anticipated to show inflation remains remains sticky in the ‘Northern Tundra’. The CPI report from Canada should be monitored because of the strong relationship between the U.S and Canadian economies. The USD/CAD will react to any surprises.

Wednesday, 20th of March, U.K Consumer Price Index – yet another important inflation report. Great Britain has been a ‘poster child’ regarding stagflation. The ugly word is not something central banks, nor governments want to discuss, but the simple truth is that problematic inflation and limited growth equal stagflation. The statistics from the U.K should be examined. The economic health of Great Britain is often a solid reflection of global conditions.

Wednesday, 20th of March, U.S Federal Reserve – the Federal Funds Rate, FOMC Statement and Fed Press Conference will be focal points for investors. Except importantly, not much is likely to be said be Jerome Powell that isn’t known already. Inflation reports from the U.S have highlighted stubborn higher prices. U.S economic numbers regarding manufacturing and consumer confidence have started to turn lower, but the Fed is not going to change its policy this week. Talk about ‘becoming’ dovish will be heard, but the U.S central bank still wants to see more proof that inflation can erode before they start to cut interest rates in the mid-term.

Thursday, 21st of March, E.U Manufacturing and Services PMI, readings will come from France, Germany and the U.K via the Purchasing Managers Index results. Most of the data will likely continue to point to lackluster outlooks, only the Services PMI from the U.K is expected to offer a glimmer of hope regarding ‘expansion’. If the Flash numbers come in worse than expected this could cast a shadow over behavioral sentiment for European investors.

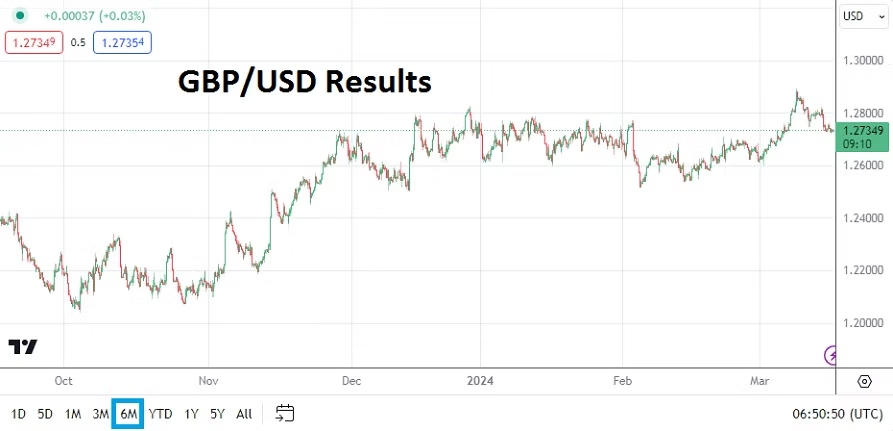
GBP/USD Six Month Chart as of 18th March 2024

Thursday, 21st of March, Bank of England – the BoE is likely to keep its Official Bank Rate within place and their pronouncements via the Monetary Policy Summary may sound like a replica of the U.S Federal Reserve. Inflation and growth will be spoken about and the BoE will try its best to paint an optimistic picture. The GBP/USD will react to the gyrations, but the range of the currency pair will have already seen tests in the preceding days. The past four months have produced a value as of the 18th of March, that is hovering slightly above late November and early December 2023 prices.

Friday, 22nd of March, U.K Retail Sales – a negative result of minus -0.3% is expected. The retail data will certainly be watched, but following the massive week of central bank statements and data which have already been published, this number may prove to be rather anti-climatic unless there is a massive surprise.

Friday, 22nd of March, E.U ECB and U.S Fed – Officials from both central banks will engage in a variety of speeches in Europe and the U.S, but again after the week’s worth of central bank rhetoric which has been heard, investors are unlikely to react much to these soundbites from members of the European Central Bank and Federal Reserve. Existing behavioral sentiment which has been produced in the dynamic days beforehand should remain the central theme as investors go into the weekend.
postN51

AMT Top Ten Miscellaneous Spiders for the 1st of March 2024

AMT Top Ten Miscellaneous Spiders for the 1st of March 2024

10. Palystes: Huntsman spiders known in South Africa as ‘rain spiders’ are nocturnal and visit indoors, sometimes causing horror for those stumbling through hallways in the middle of the night. But it is better than a baboon entering the house.

9. Victor Wembanyama: Last night’s stat line included 28 points, 13 rebounds, 5 blocks, 5 3pts made, 7 assists, 2 steals in less than 33 minutes played. The rookie is already one of the best NBA players. Btw, the Spurs beat the Thunder also.

8. Tech: Chinese cars are now in the crosshairs of U.S politicians who are worried the ‘smart’ vehicles can collect sensitive data from Americans.

7. Crypto: Bitcoin above 61,000.00 USD, Ethereum over 3,300.00, and Binance Coin testing 400.00 even as the company remains under U.S legal shadows. How much air can the balloons withstand?

6. Putin’s Nuclear Threats: In a world with escalating geo-political tension, the Russian leader remains determined and energetic while playing ‘war poker’ against Europe.

5. U.S Data: Core PCE Index numbers yesterday met expectations, but the previous month’s outcome was revised downwards. Today a Consumer Sentiment reading comes from the University of Michigan. This week’s U.S data has mostly been pleasantly ‘weaker’.

4. Central Banks: Fed ‘watchers’ are likely feeling more comfortable this morning regarding the possibility of a late spring ‘thaw’ in U.S interest rates. Jerome Powell will testify in front of the Senate next Thursday. The ECB will release their Monetary Policy Statement on the 7th of March also. Next FOMC pronouncements will be on the 20th of March.

3. Gold: The precious metal is near 2050.00 USD, this after yesterday’s U.S inflation report, gold could remain volatile today. Some speculators may be looking for additional value to develop.

2. Forex: FX has been a constant battle the past two months, but patient traders with mid-term perspectives may be anticipating their weaker USD targets to trend more steadily.

1. Equities: Many global stock indices are achieving record levels as bullish behavioral sentiment creates upwards momentum. S&P 500, Nasdaq 100 and the Composite, Dow 30, Nikkei 225 and the DAX Index are flirting with higher values.

postN87

AMT Top Ten Miscellaneous Raindrops for the 2nd of February

AMT Top Ten Miscellaneous Raindrops for the 2nd of February

10. Risk Appetite: WTI Crude Oil almost serene around 74.00 USD, as bombastic rhetoric remains loud involving the Middle East.

9. South Africa: President Cyril Ramaphosa expected to announce the country’s election date when delivering the State of the Nation Address on 8th of February.

8. Tesla: Negative media coverage and an always defiant Elon Musk gravitate towards each other, share price is around 188.88 USD.

7. China: Shanghai Composite Index (SSE) hovering near 2,730 as of this moment.

6. Gold: After near-term lows a challenge of highs as USD has gotten slightly weaker.

5. Central Banks: All bark and no bite yet, as financial institutions desire interest rate cuts from Federal Reserve, European Central Bank and Bank of England.

4. India: Nifty 50 Index near 21,865 as of this writing, it has gained more than 101% over the last five years – yes, plus one-hundred and one percent.

3. Forex Reactions: Recent short-term volatility and reversals seen as expected, patience still needed as USD mid-term outlook remains weaker.

2. U.S Equities: S&P 500, Nasdaq 100 and Dow Jones 30 have produced nervous results but still near record highs, as U.S Treasury yields have edged lower this week.

1. Data: U.S Non Farm Employment Change and Average Hourly Earnings today, this as some major corporations shed employees but labor market remains rather tight. Broad markets will react to the outcomes.