postR197.1

Return to Normal Market Conditions and a Trump Outlook

Return to Normal Market Conditions and a Trump Outlook

Retail speculators can now expect a return to calm and clear financial market outlooks, knowing that potential influences from new U.S policies will start to be considered. With the U.S elections in the rear view mirror and a Trump mandate delivered by many U.S voters, global financial institutions and traders will again be able to focus on a combination of technical perspectives, current behavioral sentiment and outlook.
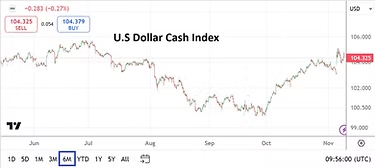
USD Cash Index Six Month Chart as of 10 November 2024

Some technical traders may believe behavioral sentiment has nothing to do with the long-term prospects of studying charts, but price action last week in FX and equities clearly showed why traders must be attuned to storms created by human emotions. Risk adverse trading has been prevalent since the end of September. A glance at the six month USD Cash Index demonstrates the extent of behavioral sentiment causing volatility the past handful of months. After believing the U.S Federal Reserve was going to become dovish which propelled the USD lower in many Forex pairs in early July, financial institutions expressed concerns about political outlook the past handful of weeks as a lack of clarity started to shroud their perspectives. USD centric positions have powered Forex.

And now that there is a Trump administration coming, and the U.S Fed has remained cautiously dovish this past Thursday, financial institutions may exhale with relief. The election on November the 5th has delivered a clear message regarding the potential for changes to U.S administration mandates regarding trade. Whether a stronger U.S economy is attained because of these hopes is not the question, it is the perception new policies will be initiated which try to deliver results which have been promised. Yes, promises can be broken.

However, the ability to believe changes are coming will affect behavioral sentiment. The Trump soundbites may prove to be rather weak in the future, but there is a chance he will also get things done regarding stronger trade agreements which protect U.S business enterprise and manufacturing. Folks can argue until they are blue in the face regarding the prospects of all things, but the U.S major equity indices rising like a rocket ride in the middle of last week is clear evidence that many believe the prospects for U.S corporations is better. No matter if it is only hopes about tax laws changing, less regulation, and better U.S trade agreements, investors are clearly betting on optimistic outlooks for the mid-term.

Dow Jones 30 One Month Chart as of 10 November 2024

Improved attitudes are great for the prospect of financial institutions, but traders still have to certainly protect their positions against volatility developing. Markets should start to return to tranquil conditions in the days ahead. U.S data will come this week which will be important via the CPI numbers on Wednesday and PPI figures this Thursday – the combination of these inflation reports will be important. Friday will see Retail Sales from the States.

The return to data as a guideline for financial institutions teamed with the Fed’s rate cut this past Thursday may be an ointment for retail traders who seek a return to normal conditions. Nervous behavioral sentiment could remain a factor in the coming days as people adjust their outlooks to a Trump White House, but the coming week should be relatively quiet regarding surprises.

It isn’t a question of liking or disliking the outcome of the U.S election, it is a question about how behavioral sentiment will now be affected. While some bring up potential tariffs as a major risk for the U.S and global economy, we have been down this road before with Trump. The risk of inflation if trade disagreements flourish should be taken seriously, but Trump has dealt with China in the past and both sides did find a way to do business in many respects. China is probably worried about Trump being in the White House again, but they likely have a gameplan for the tough business discussions ahead. The experience of having dealt with President Trump before allows China and others to know what they may face this time and empower them to be prepared.

It should be noted that Trump has shown in the past a tendency to enter negotiations with a difficult offer and permitting the other side to counter. Trump then might turn down a proposal, but often shows he is open to discussing things further and reaching a compromise. And that is the crucial word – compromise. It is about business and geopolitics. Financial institutions have dealt with a Trump White House before. This time around there is a hope Trump’s naming of a White House cabinet will not be as messy an affair as it was the first time.

The naming of Susie Wiles as the White House Chief of Staff last week looks like a good first step, also having strong Republican leadership in the Senate and House of Representatives may make things easier. While some are worried about a slew of loud rhetorical stances by Trump, perhaps pragmaticism will be practiced. And based on that rather optimistic viewpoint, retail traders may also feel businesslike conditions are ahead and that the financial markets will be a safer place to pursue speculative wagers again in the near and mid-term.
postR196

AMT Top Ten Miscellaneous Votes for the 4th of November

AMT Top Ten Miscellaneous Votes for the 4th of November

10. Priorities: Not to dismiss the execution of beloved Peanut the Squirrel by New York authorities recently, but lets reflect on the fact that this little fellow made international news while wars are raging, and nearly 300 people in the U.S are dying from drug overdoses per day. Social media is rather powerful.

9. NBC: Kamala Harris appeared on Saturday Night Live for roughly 90 seconds this weekend, this created criticism and questions about unfair airtime for the Vice President. SNL is lucky to get more than 5 million viewers per episode on average. To try and apologize for the potential trouble, NBC then gave Donald Trump free commercial airtime twice yesterday, once during a NASCAR race which on average attracts over 3 million viewers, and on a Sunday night NFL broadcast which averages sometimes up to 22 million viewers.

8. Saber-Rattling: There is a potential Iran is waiting on the outcome of the U.S vote for President before undertaking more military actions. Deciding if and how they are going to launch another attack on Israel, depending on who wins the U.S election because of the potential ramifications is likely part of their military strategy.

7. BTC/USD: Bitcoin as of this writing is trading near 68,500 USD. The digital asset continues to bounce around rather intriguing resistance. On Tuesday of last week Bitcoin traded near 73,500 momentarily, while the highs are certainly noteworthy, support for the speculative asset has been around 66,000 since the middle of October. There are reasons to suspect Bitcoin will display a large amount of volatility this week, particularly when the new U.S President is known.

6. Forex: As of this writing the USD/JPY is slightly below 152.000, the EUR/USD is around 1.09000, the GBP/USD is near 1.29650. The question is where these currency pairs and other major FX assets will be in three nights. Day traders dreaming of riding momentum via financial institutions need to understand the equilibrium of risk and reward. In other words, the same amount of money you can make, is likely the same amount of money you can lose. Risk management will be a life preserver for many speculators this week.

5. U.S. Data: This past Friday the Non-Farm Employment Change numbers came in wildly below the 106,000 jobs added estimate, the result of only 12,000 hired was rather shocking, but met with almost muted bewilderment. Also, the jobs numbers showed another revision lower from the previous month. Advanced GDP quarterly numbers, on Wednesday the 30th of October, also missed their estimate coming in with a 2.8% gain compared to anticipated growth of 3.0%. The U.S economy is still under stress.

4. Barometers: Risk adverse trading has been widespread the past handful of weeks. While gold has reached new highs and is slightly below the 2,750.00 mark for the moment, one month from now will be a telltale for gold and many assets. Since the end of September a number of narratives have been heard trying to explain the results seen across the board, but the simple answer is caution has entered the markets. U.S equity indices are still flirting with highs, even as they have suffered downturns in recent trading. WTI Crude Oil is near 71.50 USD per barrel. Gold, U.S equities and WTI Crude Oil will react to the outcome of the U.S election and serve as solid behavioral sentiment indicators in one month when compared to current prices.

3. Federal Reserve: If last week’s U.S economic data had been delivered without the fanfare of the U.S election approaching, Fed observers would likely be anticipating a dovish sounding FOMC Statement coming on the 7th of November. Instead, the USD has remained rather strong as risk adverse trading has been demonstrated in the broad markets. The Fed is certainly in a position to cut the Federal Funds Rate by another 0.25 basis points, some could even argue for another 0.50% cut. However, the Fed is likely to cut interest rates by a quarter of a point and sound rather cautious as they too read the landscape in the wake of the U.S voting results. Mid-term outlook from the Fed will be scrutinized this Thursday.

2: Nervousness: Day traders who decide to participate in the broad markets near-term may also enjoy walking outside and looking at approaching storms and dreaming about the fury about to come. Being anxious before and during large risk events when outcomes are unknown is a survival instinct. Speculators need to protect themselves over the next couple of days. Tranquil trading in all major assets may appear, but as tomorrow grows long assets will begin to percolate and by Wednesday almost all financial markets will be boiling. While this is certainly being hailed as the most important week of the year because of the U.S election and the Federal Reserve, it is also a very dangerous time to be trading. Those with limited funds may want to hunker down in a safe place and watch the markets create bedlam over the next 48 hours.

1. U.S Election: The vote is less than one day away when old standards are considered. However, more than 72 million votes have been cast early in the U.S already. That’s more than 45% of the total U.S vote during 2020, when 158,434,567 votes were counted. While the media bangs the drum regarding the incoming results tomorrow, it is important to note that many Americans and global observers are merely waiting for the final results to be announced. The end of the election campaign is nearly upon us, now financial institutions and traders await clarity. Wednesday the 6th of November is going to be an interesting day for the markets.

postR196

AMT Top Ten Miscellaneous Frights for the 28th of October

AMT Top Ten Miscellaneous Frights for the 28th of October

10. MLB Concern: Baseball executives are hoping the Yankees can start to make the World Series more competitive this evening. The Los Angeles Dodgers have won the first two games of the championship battle. Significant hopes for a drama filled, seven game World Series would be dampened badly if the Yankees do not win tonight. Television ratings which were expected to be high could suffer appreciably if the Yankees go down three games to none. A non-competitive championship would mean a loss of revenue.

9. Israel and Iran: The Middle East saga is at number nine, and hopefully doesn’t become number one. A dangerous game of poker is being played by the participants. If Iran decides to up the ante once again, it would be a dangerous decision, because it appears Israel has positioned itself via this weekend’s retaliation to be more aggressive if need be.

8. WTI Crude Oil: The ability of the energy to move below 70.00 USD upon this morning’s trading is a sign the Middle East conflict remains tranquil in the minds of large participants in the oil sector. However, if Iran decides to test Israel again directly, Iran may find that its oil infrastructure is vulnerable. As the price hovers below 68.00 USD during this writing, it appears buyers who bought speculative positions the past few weeks might be capitulating.

7. BRICS: The inclusion of 13 additional nations as Partner States to the international organization led by Russia, China and India shows the entity sees itself as a growing alternative geo-political force and trading sphere with real power. The West should be paying attention, but often seems like it is not concerned about the potential strength of BRICS, and instead makes believe the group is a fallacy and much ado about nothing – this is a mistake by the West.

6. North Korea: The potential of North Korean combat troops entering the Ukraine – Russia war is a dangerous notion. However, it opens the door for Ukraine and South Korea to offer surrendering deserters the possibility of being allowed into South Korea, if soldiers can prove they are not spies. Unfortunately, the temptation of desertion by enemy troops could prove to be wishful thinking because North Korean soldiers will have intense supervision at all times; the threat of being shot as a liable traitor is a likely constant menace.

5. Gold: Record values continue to be seen, the price of the precious metal as of this writing is near 2,732.00. Noted as a store of value, gold is also seen as a safe haven by its buyers. Now may be the time to consider behavioral sentiment as a main driver because of anxiousness in the global marketplace. Speculative forces are certainly involved in the move higher too. With so many risk events shadowing, it may be very unwise for day traders to bet against the rise of gold near-term.

4. U.S Data and the Fed: Advance GDP numbers will be published this Wednesday, the Core Personal Consumption Expenditures Price Index will be seen this Thursday, and on Friday the Non-Farm Employment Change statistics will be presented. Fireworks should be anticipated by day traders. The combination of these reports, the approaching U.S election, and the Federal Reserve’s FOMC Meeting decision on the 7th of November will be enough to make most analysts hearts beat faster.

3. USD/JPY: Japan’s election results today now require a coalition government because the ruling Liberal Democratic Party has lost its majority. The Bank of Japan has a meeting this Thursday and is expected to hold its BoJ Policy Rate in place. The Japanese Yen has returned to values above the 153.000 level as of this writing. While many major currencies have lost value against the USD since the end of September, the USD/JPY needs to be watched as a dynamic combination of risks abound. Political gridlock, inflation, and lackluster economic data in Japan are not ingredients which will provide financial institutions with optimism in the near-term. The historically cautious attitude of the Bank of Japan will be severely tested in the coming weeks.

2. U.S Election: There is a little more than one week to go before the Presidential vote begins. While many folks are focused on the White House, the race for the Senate looks to be a stiff competition too. Republicans are hoping to regain the majority in the Senate and retain their power in the House of Representatives. Financial institutions are apprehensive about the outcomes for Congress, which will have an important role in fiscal and regulatory management. The Democrats appear to be nervous. Noise from the campaign trail and media will become heightened over the next seven days. Top bureaucrats in offices like the SEC, CFTC, FCC and other agencies know their jobs are on the line.

1. Market Volatility: U.S economic data, the coming election, and the Fed means the next week and a half of trading in the global markets are going to be packed with violent firework displays. Day traders who do not have experience should watch from afar, because the coming price action can cause fast losses for those caught on the wrong side. Trading sentiment is fragile, this is evident via the choppy results seen in equities, Forex, many commodities, and rising U.S Treasury yields. Over stating the obvious for the moment about risk management is a public service.

postR196

AMT Top Ten Miscellaneous Interpretations on the 13th of Oct

AMT Top Ten Miscellaneous Interpretations on the 13th of Oct

10. Language: The French word histoirie includes both history and story via its English interpretation. The French usage conveys the acknowledgement that history is often subjective and a story written with an opinion which may or may not be the correct narrative.

9. Subway Series: New York baseball fans will be in an uproar this coming week as the Mets play the Los Angeles Dodgers, and the Yankees face the Cleveland Guardians. The potential of a crosstown World Series will have NYC holding its collective breath. New York fans shouldn’t celebrate too soon, because the Dodgers are dangerous and the Guardians will be competitive.

8. Free Press: CBS News in the U.S has been widely condemned this past week. Video released shows ’60 Minutes’ explicitly edited an interview with Kamala Harris. Also, a recorded and ‘leaked’ staff meeting from CBS management has come to light in which Tony Dokoupil, a news anchor, is reprimanded for asking critical questions to writer Ta-Nehisi Coates.

7. Barometers: Gold went into this weekend near 2,656.00, WTI Crude Oil closed around 75.45 on Friday, and U.S Treasury yields increased this week and are now challenging values last seen in the third week of August. Intriguingly, the major U.S equity indices continue to flirt with highs. Broad market results appear to be walking a tightrope as financial institutions seem to be waiting for November and U.S election outcomes. However, long-term investors who are diversified maybe cynical of this thought, and believe buy and hold remains the best policy.

6. Buy or Sell: Negativity surrounding Boeing via workers who are on strike, layoffs, a potential corporate bonds downgrade, production delays, and court decisions are still shadowing. In December of 2023, Boeing was near 265.00 USD per share value. Prices were near 158.00 this time last year, and as of this weekend Boeing is close to 151.00. The bad news surrounding Boeing has been a thorn in the side of investors. Boeing is a major corporation in the U.S and relied upon militarily and for global public aviation. What is the downside potential for Boeing the next year compared to upside capabilities long-term?

5. Crypto: The SEC has filed charges against Cumberland DRW LLC, claiming the crypto exchange has been acting as an unregistered dealer. https://www.sec.gov/enforcement-litigation/litigation-releases/lr-26151 It appears the SEC is growing more aggressive via confrontations with U.S based cryptocurrency exchanges. The U.S election result will play a role in the future leadership and direction of the SEC, and could have an affect on cryptocurrency values. BTC/USD is near 62,700.00, ETH/USD around 2,465.00, BNB/USD about 575.00 at the time of this writing.

4. Tranquility: Stronger USD centric price action continues to create some downwards motion for other major currencies, but price velocity was not as violent last week compared to previous days since the end of September. Fragile sentiment in financial institutions is still stirring. The ECB rate decision this week will come Thursday and a 0.25 basis point cut is expected. Traders need to remember that a change to the European Central Bank’s Main Refinancing Rate has likely been priced into the EUR/USD. What needs to be heard now is ECB rhetoric and that is likely to remain guarded. Price velocity in Forex remains a danger for retail traders this coming week.

3. U.S Election: There are only three weeks left until the U.S vote. Day traders need to understand financial institutions will grow more cautious as the election approaches. Speculators may want to try and wager on the outcome of the election, but unless a definitive result is predictable beforehand, it will be hard to take advantage of political winds which are swirling. It will be nearly impossible for day traders to hold onto a position over the next few weeks unless they have deep pockets, use no leverage, and have the patience of a saint.

2. Make or Break: China will release important economic data this week. Trade Balance and Foreign Direct Investment numbers are tentatively scheduled to be released on Monday, along with New Loans reporting. This coming Friday New Homes Sales, GDP, and Retail Sales figures will be released. China is trying to stimulate the economy with billions of cash, but critics suggests this will not work. The Shanghai Composite Index is near the 3,217 mark, on the 30th of September the SSE was near 3,675. Before the China stimulus was released the Shanghai Composite was near 2,755. Bullish SSE momentum has run into headwinds since the beginning of October, China may be pressured to try and create more stimulus, but will it produce a lasting positive result? Traders caught up in the buying frenzy in late September are likely getting more nervous about declines. The USD/CNY is near 7.066. Chinese economic data should be monitored this week.

1. Interest Rates: The Federal Reserve via the CPI and PPI inflation reports still appears able to cut another 0.25 basis point from the Federal Funds Rate on the 7th of November. While the Consumer Price Index data showed a slight tick up in a few categories, Friday’s Producer Price Index met expectations via the core monthly report and the broad monthly outcome came in less than anticipated. The November interest rate decision is important regarding consistency per the Fed’s messaging the past two months, and mid-term behavioral sentiment outlook among financial institutions. U.S Retail Sales and Housing numbers will be published this week.

postR189.1

Hurricanes, Wars, U.S Election and Inflation Reports Noise

Hurricanes, Wars, U.S Election and Inflation Reports Noise

Between hurricanes, wars, the coming U.S election what could possibly go wrong for day traders? Oh wait, the U.S will also issue their Consumer Price Index reports today to throw some fuel onto the Federal Reserve outlooks of financial institutions. As the loud headlines get attention and try to scare us, it should be noted that markets have actually behaved rather calmly this week. Perhaps volatility was already traded heavily into assets the past week and a half, and tranquility is returning. However, there is the possibility that experienced smart money has simply positioned investments and speculative endeavors, and now await outcomes via objectives in order to react.

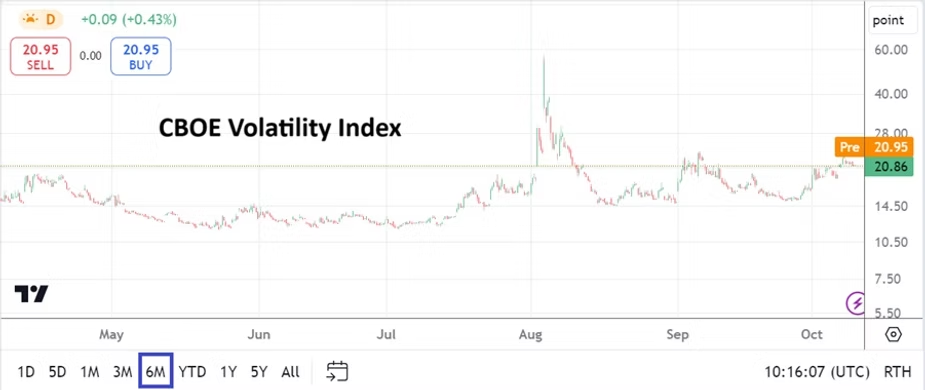
CBOE Volatility Index Six Month Chart on the 10th of October 2024

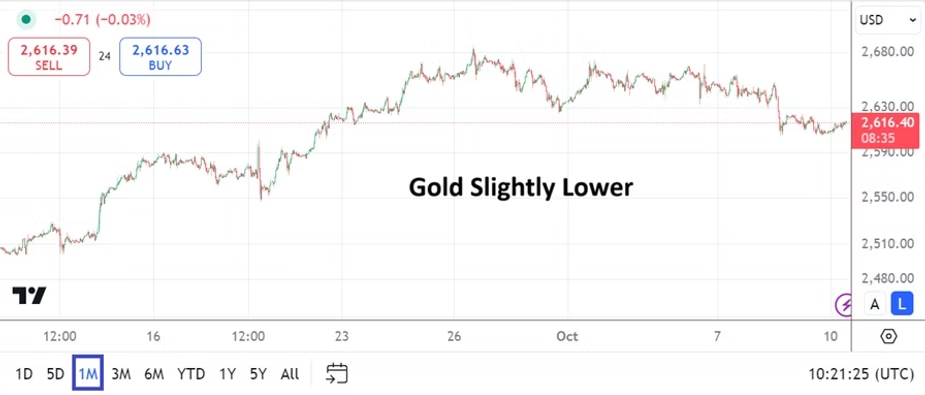
The Chicago Board Options Exchange’s Volatility Index (VIX) has risen since the last week of September, but remains within known realms. Gold while definitely within the higher levels of its long-term price range has ebbed lower during the same timeframes. And WTI Crude Oil while flirting with short-term highs today, actually remains within the known realms of its six month range. In other words while short-term day traders potentially get caught up in fearmongering rants and tremble, financial institutions continue to trade with an outlook that remains rather tame mid-term.

Gold One Month Chart on the 10th of October 2024

Financial institutions were dealt a perplexing blow last Friday when the U.S Non-Farm Employment Change hiring numbers came in stronger than anticipated. However, what is not getting enough attention is another revision downwards to the previous month’s totals did happen. Today’s Consumer Price Index statistics and tomorrow’s U.S Producer Price Index results are expected to show that inflation remains under control. If the coming data meets estimates or can show a slight decrease this could ease the fear of some financial institutions regarding what’s coming next from the Federal Reserve. If higher inflation numbers are displayed this would spark more volatility.

WTI Crude Oil Six Month Chart on the 10th of October 2024

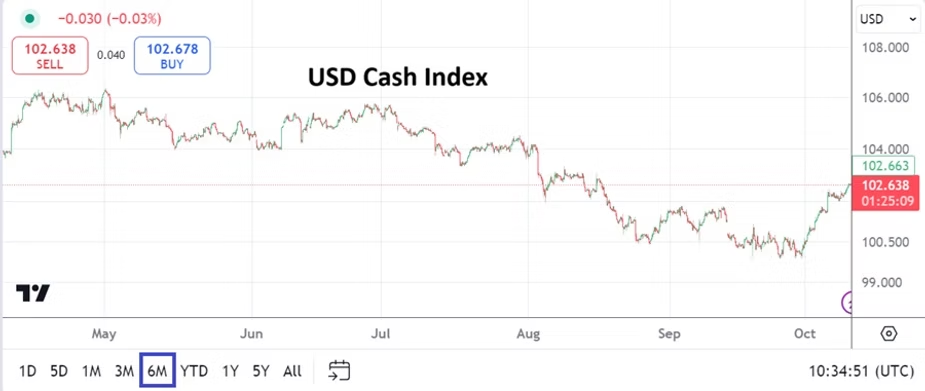
Certainly, USD selling got ahead of itself by the end of September. Day traders need to understand there are seldom one way avenues in Forex. Intraday reversals aside, when equilibrium and outlooks do not mesh via the insights of financial institutions, volatility occurs. The buying of the USD since September’s end has been noteworthy, but it was not entirely unexpected. The CPI and PPI reports from the U.S on the calendar will provide impetus. Let’s see if the markets remain calm as a swirl of other risk events linger in the air. Risk adverse tendencies have caused caution in the broad markets.

USD Cash Index Six Month Chart on the 10th of October 2024

Traders need to know there will be one more jobs report from the U.S on the 1st of November. There are some people around us that no doubt believe the U.S government is showing better than expected jobs numbers to try and ramp up support for certain political candidates. However, if analysts do their jobs well enough and point to the revisions downwards that have been consistently seen, this could help alleviate fear of conspiracies.

The Fed is still in a position to cut the Federal Funds Rate by another 0.25 on the 7th of November. Yes, the FOMC Statement is coming only two days after the U.S election, so the Fed’s decision which will be garnered during meetings on the 6th and 7th will carry some significance depending on who has been elected U.S President. While U.S economic data has been mixed via a combination of jobs numbers which had been faltering until last week, and consumers suddenly showing greater confidence and manufacturing sentiment in important sectors with improved optimism, interest rates are still high. The Federal Reserve has a dilemma and likely will want to try continuing to incrementally cut borrowing costs when they have the opportunity.

Day traders should not be too concerned with what will happen a few weeks away, particularly when they are interested in the results of trades consisting of a few minutes, half hour, and other limited durations. But they should always understand their positions in Forex, equity indices, commodities, and elsewhere have little to no effect on the real marketplace. Day traders need to be able to catch onto the technical trends and behavioral sentiment being created by larger players and financial institutions.

postR196

AMT Top Ten Miscellaneous Salvos for the 29th of September

AMT Top Ten Miscellaneous Salvos for the 29th of September

10. Profit: OpenAI has announced plans to become a money making corporation. Founded in 2015 the artificial intelligence company had the stated goal of creating ‘safe and beneficial’ technologies via its foundation, and now will face the slings and arrows of investors and potential critics. The AI boom the past two years has produced many new competitors. Can Sam Altman, the CEO of OpenAI, sustain the momentum generated or will negative organizational impetus turn the company into an also-ran?

9. Softs: Cocoa, Coffee and Sugar all remain volatile and playgrounds for day traders who like casino experiences via CFDs. Cocoa is again over 9,000 USD, Sugar touched February highs this past week as it shows signs of extreme speculation, and Coffee Arabica surged to record prices on Thursday and Friday. Over exuberance however is not being created by day traders, it is the work of large institutional traders who are in control. While the ‘softs’ may look overbought it would be unwise to bet against trends while big players pursue bullish notions. Massive money is being made in these commodities, but losses are also being felt by those who wager incorrectly.

8. Escalation: Risks in the Middle East have become a focal point, this as the region appears to have generated more must watch television. The noise which the media seemingly craves is hard to escape. Market participants cannot be blamed for maintaining vigilance as sabers rattle, especially after Friday’s events in Beirut when Hassan Nasrallah, the Hezbollah leader, was eliminated by Israel. However, experienced traders who are also strategic analysts have seen this show before and may turn the channel knowing there will be reruns in the future.

7. WTI Crude Oil: Prices closed within the lower elements of the commodity’s long-term depths. Traders did have a chance to react to Friday’s developing news from Beirut, but the energy sector remained calm. The price of WTI was around 68.57 going into this weekend, after trading at highs earlier in the week. For all the talk about fear of escalation from the Middle East, the price of Crude Oil remains within a remarkable bearish stance as large traders appear to be more concerned about lackluster economic growth globally.

6. Apex Gold: The price of the precious metal flirted with 2,685.00 momentarily on Thursday. The price of gold going into this weekend finished near 2,658.00 USD. Sustained highs have certainly continued to catch the attention of short-term speculators, but they need to be aware the commodity does remain susceptible to sudden spikes. While alluring, gold remains dangerous for day traders.

5. Countdown: The U.S Presidential vote is slightly more than 5 weeks away. Interestingly, the Fed will announce their Federal Funds Rate decision only two days after the election results. Will the outcome of the vote change the Fed’s perspective on interest rates? Financial institutions will definitely brace for the outcome of the U.S vote. Cautious winds will start to prevail as the 5th of November draws closer.

4. China: A huge stimulus package from the Chinese government has been initiated, but talk regarding potential effects and outcomes are being debated. The notion that the Chinese economy is be driven too much with a top to down centralized approach is being vocalized by some worried ‘outside’ observers. The USD/CNY is trading near 7.0105. The Shanghai Composite is near 3,087, this after massive gains via a reversal upwards which was sparked from lows around 2,691 which were seen on the 18th of September.

3. Risk Appetite: U.S equity indices continue to challenge record values in the Dow 30 and S&P 500. Yes, the Nasdaq remains beneath its highs, but is still within sight of all-time heights. Trading this week will work under the shadow of the jobs numbers coming this Friday. Financial institutions have produced rather positive behavioral sentiment and do not seem like they are ready to back away from this stance. Are some large market participants starting to quietly bet on the possibility of a Trump victory which they believe would be good for U.S stocks?

2. Forex: USD centric notions remain the impetus in foreign exchange. The USD Cash Index is within the lower boundaries of its long-term values as it trades near July 2023 realms. If the USD Cash Index moves lower it would then start to technically be within price calculations not seen since the spring of 2022. Action in the USD/JPY and GBP/USD, and other major currency pairs have been volatile, choppy conditions should be expected this week for traders leading into Friday’s key data.

1. Jobs Numbers: Last week’s GDP statistics met expectations, while inflation numbers via the Core PCE Price Index came in slightly below estimates. The growth and inflation outcomes set the table for the Non-Farm Employment Change and Average Hourly Earnings which will be reported on the 4th of October. If the employment numbers continue to trend lower and there are additional negative revisions this coming Friday, this could propel USD selling. Financial institutions are trying to figure out if the Fed will cut by 0.25% or 0.50% in November. The Fed was aggressively dovish when they cut the Federal Funds Rate by 0.50% on the 18th of September, but the U.S central bank might want to be cautious in November following the election and wait for all the dust to settle and cut by only 0.25%. Thus allowing for another interest rate cut in early 2025 if needed. The broad markets are in a reflexive mode for the time being, this Friday’s data will be important and cause an immediate reaction that day traders will notice.

postR186.1

Risk Appetite: Forex and Equities and Cautious Optimism

Risk Appetite: Forex and Equities and Cautious Optimism

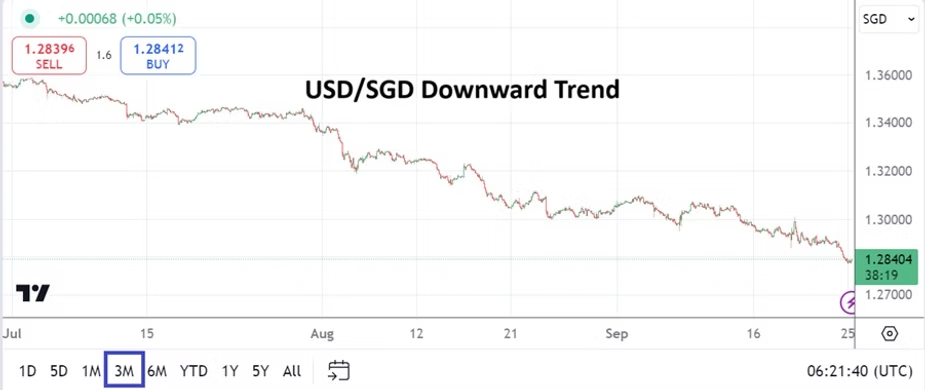
Day traders can clearly see that risk appetite has taken hold of behavioral sentiment early this week. USD centric price action has created highs for the British Pound, South African Rand, Singapore Dollar and a host of other major currencies paired against the USD. Yesterday’s poor showing via the CB Consumer Confidence reading in the U.S poured additional fire onto the notion the U.S economy is not doing as well as Fed Chairman Jerome Powell expressed last week, which means caution should be used when looking at the broad markets. Speculators who only make short-term wagers cannot let blind optimism be the guiding light.

USD/SGD Three Month Chart as of 25th Sept. 2024

While today will be thin with economic data, Thursday’s Gross Domestic Product results could prove to be another ignition switch for market impetus. The quarterly Final GDP result is widely expected by analysts to produce a gain of 3.0%. The Final GDP Price Index statistics are anticipated to show a 2.5% ratio. If the growth and inflation numbers miss their marks this could set off a momentary storm in the markets. A good example of trading that has already been baked into the cake regarding values and mid-term outlook is the USD/JPY, which while maintaining its bearish stance has clearly found a price realm financial institutions are now maneuvering carefully within as equilibrium is battled.

GBP/USD Three Month Chart as of 25th Sept. 2024

Yet, many financial institutions have clearly leaned further into their optimistic stances particularly via the U.S major equity indices and day traders are likely trying to follow the momentum being generated. Yes, New Home Sales will be published in the U.S today, but these numbers carry a lot of complex considerations which analysts tend to dissect in a myriad of ways, meaning that while they will get some attention, the largest players will stay focused on tomorrow’s growth and inflation data coming via the U.S GDP outcomes.

USD/ZAR Three Month Chart as of 25th Sept. 2024

Forex traders should keep an eye on U.S Treasury yields, yesterday’s slight climbs early in they day were mostly met by reversals lower later on. There is also the knowledge that the yields are traversing long-term depths and there is an assumption they don’t appear ready to see a large shift in momentum. The Federal Reserve is widely expected to cut the Federal Funds Rate again in November by another 0.25%. Numbers via reports like tomorrow’s GDP statistics, and Friday’s Core Personal Consumption Expenditures Price Index will shake existing behavioral sentiment and the Fed’s outlook. The Core PCE number has an estimate of 0.2% per its monthly reading, the last three reports have met expectations.

USD/JPY Three Month Chart as of 25th Sept. 2024

Fed Chairman Jerome Powell will speak tomorrow at the U.S Treasury Markets Conference in New York, but his remarks will have been pre-recorded and presented via video. Treasury Secretary Janet Yellen will also speak afterwards at the meeting. However, their thinking is widely known and they are expected to sound rather tame. It also needs to be added that both Powell and Yellen are fully aware the U.S Presidential election is approaching. Neither one of them is going to risk saying something that can be interpreted as economically defiant.

Traders should expect the potential of volatility developing tomorrow as financial institutions and larger market participants position for the GDP reports, but if the numbers are within sight of expectations, it is likely current price equilibriums will continue to reflect current risk appetite dynamics. Proper risk management and the use of conservative leverage should be fully practiced. Retail traders should also begin to start considering that Non-Farm Employment Change data that will come from the U.S on Friday, October the 4th. The jobs numbers next week could pose a significant threat.

The Fed last week made it clear they believe there was reason to lower the Federal Funds Rate (while playing catch up) and there is the potential to enact further dovish actions in the months ahead. However, Jerome Powell also insisted – paraphrasing – the U.S economy is rather strong and added this is being reflected in solid growth statistics and a jobs market which may be weaker but remains stable.

Given the Fed’s propensity for a conservative approach, they have crawled out a rather precarious limb regarding their rather positive attitude. The coming economic data will certainly be noteworthy tomorrow and Friday, and via next week’s job numbers. Will optimistic equilibrium in Forex prevail over the next week? The major currency pairs will certainly be tested.

postR196

AMT Top Ten Miscellaneous Items on the 21st September 2024

AMT Top Ten Miscellaneous Items on the 21st September 2024

10. Shohei Ohtani: The slugger hit another home run last night bringing his total to 52 for the season. There is more than a week of regular season action remaining. Incredibly, if Ohtani pitches next season while also hitting, his current statistics could be outshined. The Dodgers pitching staff is in tatters as the MLB playoffs approach, and it has been opined that Ohtani could pitch in the postseason. However, this option is highly unlikely. Ohtani is an outstanding athlete and has surpassed many expectations.

9. Beep, Beep: The purchasing of technology, including their production and logistics sources are likely coming into question in many diverse places around the globe. The detonation of pagers and walkie talkies used by the terrorist group Hezbollah which is largely based in Lebanon has certainly created panic about vulnerabilities. Contemplation in many nations regarding the buying of equipment that could be prone to spyware and other harmful acts is a reality.

8. Michael J. Saylor: MicroStrategy led by its Executive Chairman has added to their Bitcoin holdings. MicroStrategy is reported to have around 252,220 Bitcoins. The current value of BTC/USD is around 63,000 as of this writing. Part of Saylor’s love for Bitcoin rests in his belief that value is due to scarcity, and secure durability as a store of value technologically. However, each Bitcoin holds 100 million Satoshis, the units each Bitcoin is divided by digitally as source code. Even if conservatively there are only 15 million Bitcoin in circulation in ten years time, 15 million times 100 million is 1.5e + 15, meaning more than a quadrillion Satoshis in circulation. That is not scarcity, particularly when quantum computers could create lightning quick digital trading via coding sources. The premise and concern for a major devaluation in Bitcoin is legitimate. Do you disagree?

7: Equity: Intel has apparently been made a sales offer by Qualcomm. Intel’s market cap is 93.19 billion USD, and Qualcomm’s is 188.18 billion USD. The biggest shareholders of Intel are Vanguard, Blackrock and State Street, interestingly enough Qualcomm’s three biggest shareholders are identical. So if the largest shareholders are practically alike, it comes down to a management question, can Qualcomm run Intel better?

6. Closer: The U.S election will be in a little over six weeks times. The race for the White House according to many polls is very close and the outcome will depend on important swing States. There is still enough time for Harris and Trump to pick up votes, but also enough time for each to unwittingly make an error which can cost votes. Not only is the White House up for grabs, but the House and Senate are at stake too for the Democrats and Republicans.

5. Europe’s ability to put on blinders as the Ukraine and Russia battle in a not so distant land, and bickering between E.U nations while finding no solutions for the conflict have many historical comparisons within the continent. The ability to look the other way as chaos grows and inflicts harm on neighbors has a long tradition in Europe. Since the Middle Ages into the present Europe has a significant track record of negotiating harmony and procuring tenuous treaties, which eventually lead to additional discord.

4. USD/JPY: The currency pair closed at nearly 143.850 yesterday. Analysts are trying to create narratives regarding the climb higher the past handful of days, this after the USD/JPY touched the 139.600 level approximately last Monday. Here’s the thing: financial institutions that trade the Japanese Yen had positioned for a more dovish Federal Reserve and more hawkish BoJ. The Fed delivered their end of the bargain on Wednesday, confirming actions which had already been factored into the currency pair. The USD/JPY ‘correction’ higher is within equilibrium that financial institutions have to recalibrate as they make their new mid-term outlooks and decide how to shift their cash forward positions incrementally. The move higher has not been massive and is a natural reaction as large players rearrange their commercial paper. Incremental is the key word.

3. Energy Calm: WTI Crude Oil and Brent Oil continue to trade slightly above their lower price realms, which saw long-term values in the second week of September tested. Current ratios are still flirting with technical considerations seen in the late spring of 2023. While hyperbole is communicated far and wide regarding potential Black Swan events in the Middle East which could cause Crude Oil to increase rapidly, the energy resources remain rather tranquil and seemingly transfixed on concerns about mid-term demand globally due to recessionary pressures.

2. All-Time Highs: Gold created new record values going into this weekend near 2,622.00. In September of 2022, gold was trading near 1,600.00 USD per ounce. The move higher in the precious metal has come on the heels of global inflation. Some also correctly point to a distrust of global central banks and fiscal concerns regarding the world’s largest economies. The bullish run upwards in gold has been significant and the commodity will remain an important store of value for investors. Speculatively, some short and mid-term traders are wondering about gold’s ability to maintain a trajectory skywards and if sideways price action and possible downturns will ensue for a while. Long-term investors remain serene.

1. Applause: The Federal Reserve issued an aggressive interest rate cut of 0.50%. The Fed seemingly is acting as if they are trying to please financial institutions because of past incompetence. The U.S central bank now needs economic data to behave according to their prescribed outlooks. What could go wrong? Another Federal Funds Rate cut is likely in November, after that a lot will depend on behavioral sentiment and data which may be affected by as of yet unknown leadership from the White House starting in early 2025. Fed Chairman Jerome Powell sounded almost too optimistic about the U.S economy during his Press Conference this past Wednesday. The U.S Final GDP numbers coming this Thursday will prove interesting, the growth numbers carry an expected gain of 2.9%.

postR185.1

Fed Plays Catch Up and Sets a Calm Table for Day Traders

Fed Plays Catch Up and Sets a Calm Table for Day Traders

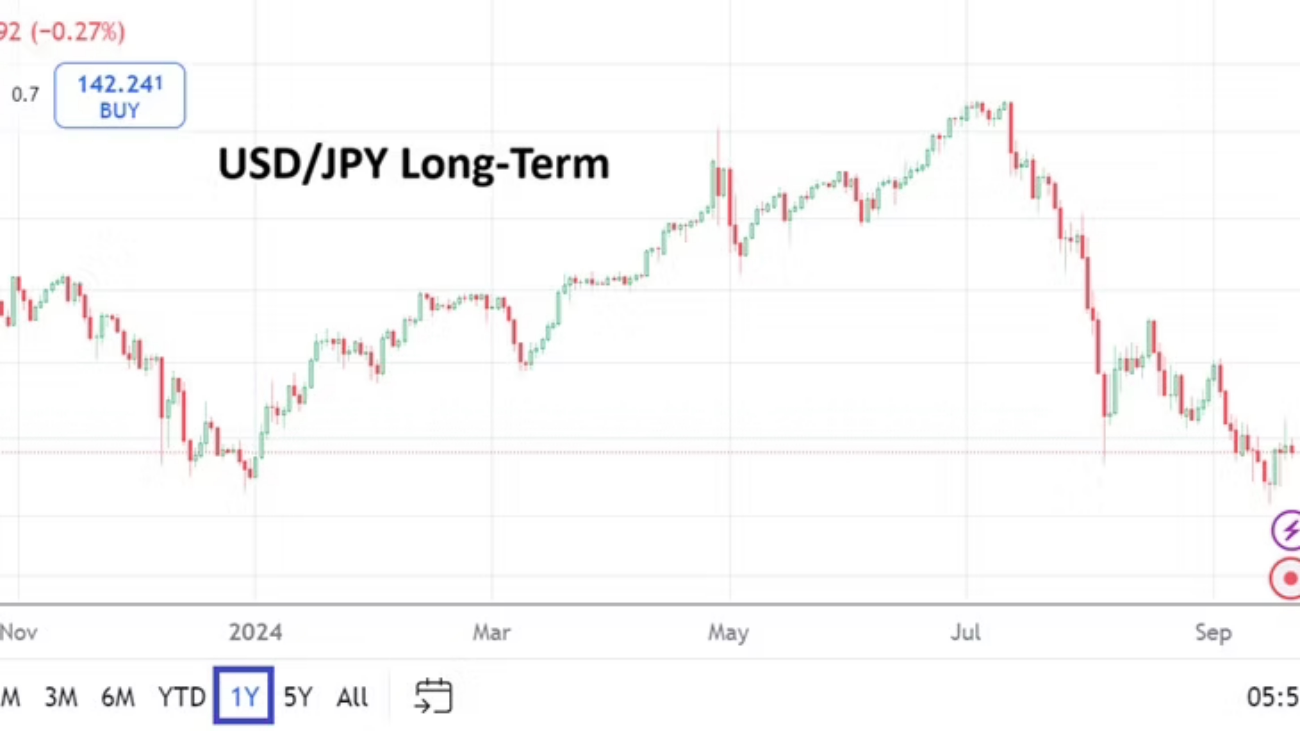
The Fed essentially played a game of catch up on Wednesday when they cut the Federal Funds Rate by 0.50%. The interest rate cut was bigger than AMT expected because of the Fed’s rather cautious stance the past handful of years. However, the move by the FOMC was certainly justified and welcomed, and now financial institutions have been given what most thought was bound to happen, a roadmap to at least a 0.75% Federal Funds Rate cut over the next six months. Longer term many believe the Fed will continue to be aggressively dovish if U.S economic conditions cooperate.

USD/JPY One Year Chart on the 20th of Sept. 2024

Traders certainly seem to be leaning into the notion another 0.25% will be trimmed by the Federal Reserve in November. And this sets the table for day traders to now face potentially calmer market conditions that react solely to economic data, geopolitical events and the occasional flashes of news. The U.S presidential election will certainly be a big event on the 5th of November. Long-term investors are likely feeling rather tranquil and have not been surprised. Behavioral sentiment over the next month should be easier to gauge.

USD Cash Index One Year Chart on the 20th of Sept. 2024

So what happens near-term? The Bank of Japan today, like the BoE yesterday, stood in place. The USD/JPY is trading near 142.300 as of this writing. The GBP/USD is near 1.32890. Gold is hovering near 2,600.00 and WTI Crude Oil is approximately 72.00 USD. Perhaps short-term traders should keep one eye on the Middle East this weekend, but for the moment it doesn’t appear a major escalation is about to ignite in the region. Yes, there is saber rattling, but composure may actually prevail. Those looking for a sudden emergence of a strong USD trend may find that headwinds keep the greenback within the lower realms of the USD Cash Index.

Gold One Year Chart on the 20th of Sept. 2024

Next week’s U.S GDP numbers on Thursday the 26th, and the Core PCE Price Index results on Friday the 27th will get plenty of attention. What the Fed and financial institutions would like to see are stable economic numbers which do not spark fears of a recession. The almighty ‘soft landing’ being pursued by the Federal Reserve is likely being hoped for too by financial institutions via their mid-term outlooks.

The Federal Reserve is supposed to be an independent entity not associated with the Executive Branch of the U.S government regarding oversight. There has been some bantering about the potential that the Fed cut by 0.50% before the U.S elections and Powell proclaimed the U.S economy is doing well to help the Democrats, but this is unlikely. Conspiracy thinking aside, the broad markets are now going to be a barometer regarding economic outlook based on data such as growth, jobs numbers and inflation; clarity regarding a more dovish Fed has been delivered in many respects, data has to justify their decision moving forward.

Day traders may have the ability to follow their technical charts and gather behavioral sentiment perspectives over the next month serenely by watching barometers like gold and U.S Treasury yields. As the U.S election draws closer financial institutions may start to position for potential outcomes, but with polls indicating a tight race currently they would be foolish to bet on one particular outcome. Meaning the broad markets including equity indices, Forex, U.S Treasury yields and even commodities may be moving within fairly priced equilibriums for the moment.

As the Dow 30 and S&P 500 move within record heights, the Nasdaq 100 is slightly below its all-time highs. Yet, it should be remembered the Nasdaq 100 still has done remarkably well the past year and although not at an apex level has the potential to scale upwards quickly. Optimism for the moment seems to be driving the financial markets and day traders should keep this in mind. However, speculators should remember risk management is essential, not over leveraging ideal, and keeping realistic price targets remains always important.

postR184.1

Trading Dangers: Profit Seeking and Federal Reserve Dynamics

Trading Dangers: Profit Seeking and Federal Reserve Dynamics

A 0.25% or 0.50% interest rate cut is the talking point for speculators and financial institutions now, as the U.S Federal Reserve readies its FOMC Statement and prepares to present its Federal Funds Rate this Wednesday. While day traders will certainly listen to plenty of noise being created by pundits and wager, and financial institutions actively operate within the market place and seek profits, long-term investors are likely not very nervous, nor concerned with the monthly Federal Reserve announcements about to be delivered. Perhaps day traders should learn from this long-term insight.

Long-term investors understand the Federal Reserve will be cutting the Federal Funds Rate back to its mean average eventually. While the Fed may only cut by 0.25% this week, over the next six months the U.S central bank is likely to cut by 0.75% or so. Investors who are comfortable with their portfolio positions believe they know what the Fed will be doing and they are not concerned with daily gyrations in the marketplace. Yes, long-term investors will rebalance their positions occasionally, but they do not overtrade.

However, speculators need to be braced for the price velocity which will develop over the next few days. Small price movements in Forex, U.S equity indices and commodities creates havoc for folks who are using leverage and short-term timeframes to bet on outcomes. Nervous sentiment has created velocity, reversals, and unreliable trends recently which will be tested again the next few days.

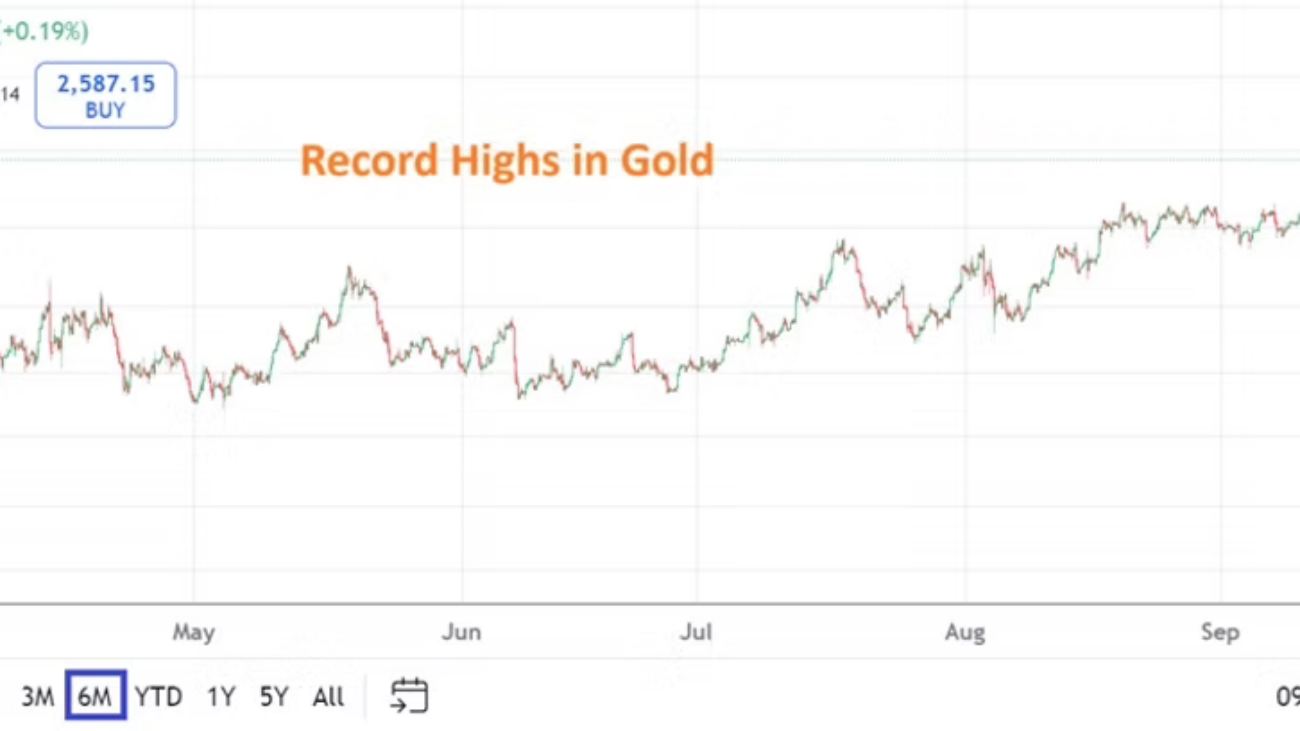
Gold Six Month Chart as of 16th Sept. 2024

Financial institutions are part of this turbulent landscape as they use algos geared towards working models like trend, mean revision (statistical arbitrage) and other dynamics which create huge amounts of volume and move the markets. Let there be no doubt that the broad markets will react violently on Wednesday in the wake of the Federal Reserve’s actions and rhetoric. Last week’s trading produced new highs in gold, and buying in the U.S major equity indices increased starting on Wednesday and pushed towards highs once again.

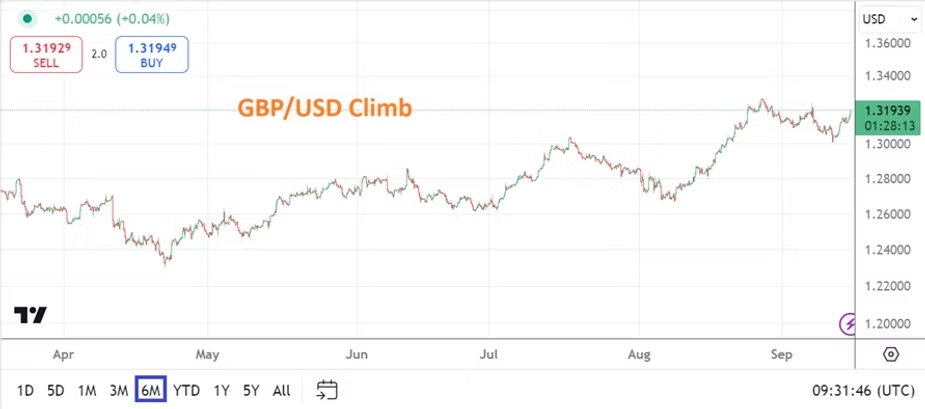
GBP/USD Six Month Chart as of 16th Sept. 2024.

The question every one has is what is the Fed going to do this week? I believe the Fed is going to cut by 0.25%, and say that if current economic conditions via the jobs numbers and growth remains lackluster that another interest rate cut will be possible in November. Based on the knowledge that central banks remain wary of stubborn inflation and appear to be debating what the inflation rate will be over the mid-term, it would be surprising to see the Federal Reserve suddenly turn aggressive given their history the past handful of years.

Having seen the ECB stay cautious last Thursday even though economic data shows recession is still being battled across Europe is a strong indicator regarding what the Fed’s likely thinking. The U.K will release important inflation numbers this Wednesday, but the BoE is probably going to remain rather mute on Thursday because they cut interest rates already in August. Again, central banks remain in turtle mode, they are not rabbits.

A dangerous consideration is how will the large financial institutions react to this quagmire being caused by cautious central banks? As said, many long term investors believe the Fed will have to be dovish over the mid-term. Lackluster economic data from China, Europe and the U.S feed into a belief interest rates cuts will continue to be delivered. Day traders live and die via the price action created by financial institutions.

Potential Black Swan events aside, behavioral sentiment generated by short and mid-term results will likely be geared towards the notion that financial institutions also believe global central banks will have to be dovish over the mid-term. This doesn’t include the Bank of Japan which is its own animal and has delivered a rather admirable bearish trend the past two months. The BoJ will release its Policy Rate this Friday and are likely to remain standing in place.

USD/JPY Six Month Chart as of 16th Sept. 2024

So what can day traders who are nervous that volatility will cause great harm over the next few days do? They can always decide to sit on the sidelines and not bet. Long-term investors who plan on holding their assets over the span of a few years are not so concerned about what the central banks are doing short-term – except to say investors are obviously hoping that solid fiscal and monetary policy are being practiced.

Financial institutions engaged in their funds trying to create profitable returns are the folks that need to be kept an eye on, their behavioral sentiment will drive markets in the short and mid-term. Speculators who are trying to take advantage of the dynamics caused by large trading houses this week need to practice solid risk management. While it might be fun to have wagers on potential sudden moves in the coming days, the Federal Reserve’s FOMC Statement and Jerome Powell’s press conference will cause short-term pandemonium.

postR196

AMT Top Ten Miscellaneous ‘Just the Facts Jack’ on the 14th of Sept.

AMT Top Ten Miscellaneous 'Just the Facts Jack' on the 14th of Sept.

10. Word of the Day: Quaestuary, the usage of the word comes from William Manchester’s book A World lit only by Fire. The word is now considered obsolete. Manchester used the Latin word, quaestiarii, to describe profit making by the Roman Catholic Church during the Middle Ages and into the Renaissance. Church ‘officials’ would use their positions of power to raise money dubiously. Promising absolution to the naive via treacherous claims which included the charging of payments for potential sins committed in the future, and a more lenient purgatory for already deceased members of a family who were waiting to be allowed into heaven because of past transgressions.

9. Undecided: With less than two months before the U.S election for President, swing States are crucial battlegrounds for candidates Trump and Harris. Turning purple into red or blue is the prime task for the Republicans and Democrats. Economy, immigration, foreign policy, reproductive rights are among the talking points. Which side can receive the most votes via promises that will be hard to accomplish?

8. Artificial Intelligence: Early this week Oracle Corporation released revenue results and projections showing that profits are increasing due to demand for data centers as the use of AI expands. Cloud services provided by Oracle has become the corporation’s largest source of growth. Investments in big data centers are getting competitive. Data4 has recently announced they are going to invest approximately 300 million EUR into a data center facility in Paiana, Greece. Data4 led by Olivier Micheli, CEO, has announced that it plans on investing around 7 billion EUR into 2030 for expansion.

7. Crude Oil: WTI Crude Oil briefly went above the 70.00 USD mark on Friday, but went into the weekend near 69.33. U.S economic data this coming week (besides the U.S Fed on the 18th) will be limited to manufacturing readings and retail sales data. The notions that the U.S economy is struggling via weaker employment numbers and lackluster GDP, European data remaining murky, while China is not exactly robust is likely causing speculative demand in Crude Oil to remain low. Global energy supply is solid and the Middle East conflict remains somewhat muted.

6. Whipsaw Gains: Major U.S equity indices moved upwards as the Dow 30, S&P 500 and Nasdaq 100 all produced better weekly results. However, improved momentum mostly occurred as equities reversed from nervous lows on Wednesday. The Dow 30 and S&P 500 are within sight of apex values, while the Nasdaq isn’t far behind. U.S Treasury yields also dropped lower via their totals for the week with the 5, 7, and 10 Year Notes approaching yields last seen in the spring of 2023. The 30 Year Bonds are traversing lower too, but will have to penetrate early 2024 levels to then challenge depths from early 2023.

5. Inflation: Global central banks are having a large internal debate about their target inflation numbers. Trying to agree on what the neutral rate – mean average – over the next year should be is causing central banks to remain cautious about inflation projections. While it is clearly evident that Europe and the U.S are facing economic headwinds the ECB, Fed and BoE seemingly refuse to step on the gas pedal and become aggressively dovish. However, financial institutions who frequently use their mid-term outlooks as guidance continue to lean into their trading positions and seemingly wager on the central banks having to become more dovish. How much can each central bank cut by over the next 6 months? Why not cut by 0.50% to inject easier borrowing rates now? Because apparently it seems all the central banks remain nervous about inflation remaining stubborn. The word stagflation still comes to mind. The decline in Crude Oil prices seen the past few weeks may be a hopeful sign for lower costs.

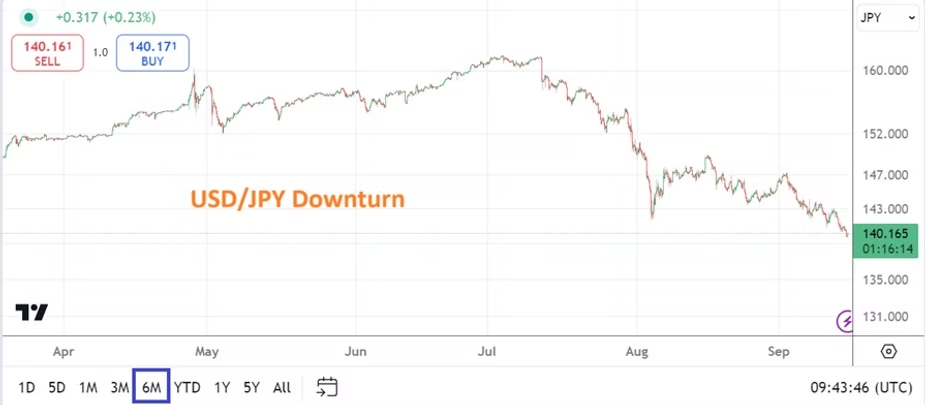
4. USD/JPY: The currency pair finished trading near the 140.775 ratio on Friday. Trading in the USD/JPY appears to be driven by the notion that financial institutions believe the U.S Federal Reserve is going to have to cut the Federal Funds Rate by 0.75% over the next six months. Behavioral sentiment has a breathtaking history of producing strong trends in the USD/JPY. The Bank of Japan will announce their Monetary Policy Statement on the 20th of September. The USD/JPY was trading near 162.000 in July and its decline lower seems to have surprised some, but why? The BoJ is likely going to sound cautious this coming week, but sitting on their hands and allowing their global counterparts to become more dovish may be enough to keep the USD/JPY within its lower price realm.

3. China Data: Numbers published early this morning showed that New Home Prices continue to fall, Industrial Production has decreased, Retail Sales have dropped, and the Unemployment Rate has risen. China’s economy is suffering. The USD/CYN looks too low at the current rate of 7.0925. The Shanghai Composite (SSE) has fallen to nearly 2,704 and touching lows from early February of 2024. The SSE is down roughly -13.46% over the last year. The Chinese government’s desire to manage the economy with a tight grip continues to produce fractures and should be reconsidered.

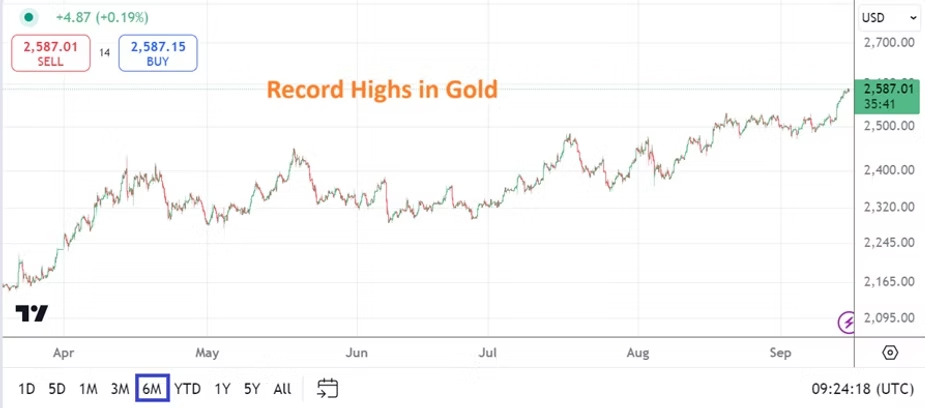
2. Gold: The precious metal finished Friday’s trading near 2,577.00. Yesterday’s values hit all-time record prices for Gold versus the USD. The 2,586.00 vicinity was touched before reversing slightly lower. The ability to remain near apex highs going into the weekend highlights large traders likely still have a taste for gold and that long-term investors remain bullish. Is nervousness due to perceived global central bank ineptitude helping to create more gold buying? Short-term speculators need to remain careful within these heights.

1. FOMC Prediction: The European Central Bank’s decision to cut by only 0.25% this past Thursday is almost a sure sign the Federal Reserve will mirror the ECB on the 18th of September. Last week’s prediction by AMT that the ECB would only cut by 0.25% proved to be true, and our outlook for the FOMC’s Federal Fund Rate decision is also a cautious 0.25% cut. While the U.S Consumer Price Index and PPI info published this past Wednesday and Thursday showed inflation is under control, the data also shows a stubborn streak. However, an erosion of inflation is taking place and while the target ‘neutral’ rate is likely being debated behind closed doors, it is also apparent to most outside observers that the Fed is being too cautious and will be ‘forced’ to cut this coming week, November 2024, and early in 2025.

Content

postR183.1

Nervous? Central Banks Cautious, FX and Asset Equilibrium

Nervous? Central Banks Cautious, FX and Asset Equilibrium

Sometimes when looking for ideas regarding a risk analysis article it is difficult to find a timely subject. Exaggeration is often used to grab attention. This week and next will not be one of those times. Equities, Forex and commodities have produced nervous results since last Monday. The broad markets appear to be in search of equilibrium, but price velocity while higher than normal hasn’t produced a volcanic surge of pain. Financial institutions were presented less than inspiring jobs data this past Friday and day traders hopefully had their risk management working. Everyone will need to be paying attention this week too.

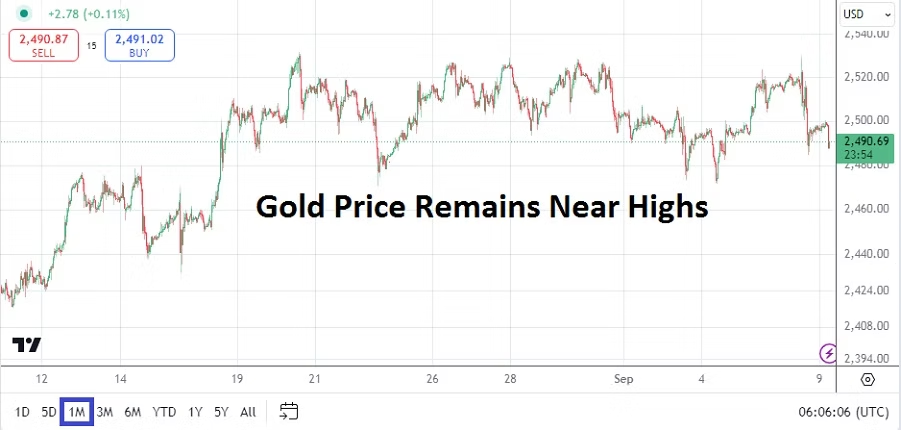
Gold One Month Chart as of 9th Sept. 2024

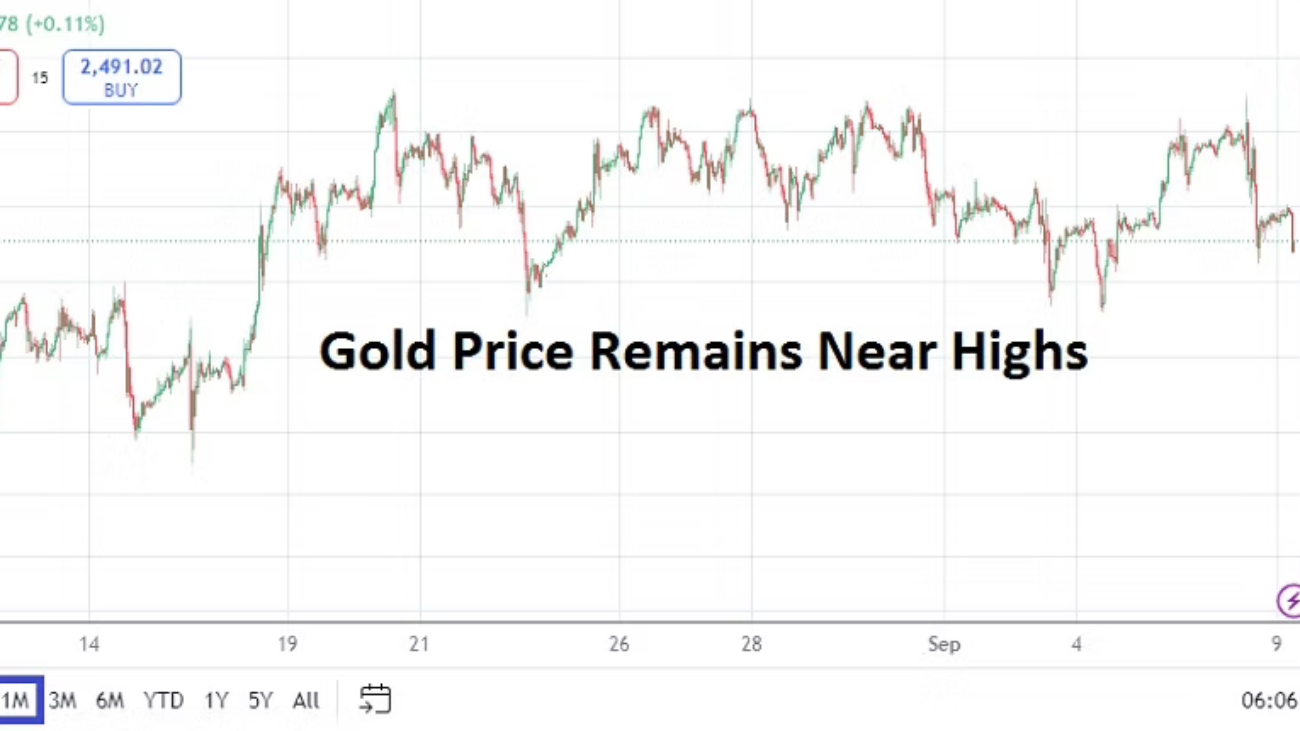
Gold has hovered around the 2,500.00 level and while it certainly is a short-term speculative asset for day traders, the precious metal also serves as distinct barometer of behavioral sentiment and long-term guidance regarding inflation. Recent economic data has created concerns in financial institutions about the potential for a stronger than anticipated U.S downturn. The volatility and sell off in equity indices last week is a clear sign investors would like the Federal Reserve to be more aggressively dovish.

This coming week is packed with a variety of risk events which will keep all market participants engaged. Long-term investors may feel calm as they rely on their outlooks which extend over a handful of years, but anyone who needs a firm grasp on short and mid-term viewpoints might not be comfortable. It is important not to cry wolf too often, but based on the trading results seen the past week it is worthwhile to point to the turbulent outcomes and issue a warning that more volatility could develop.

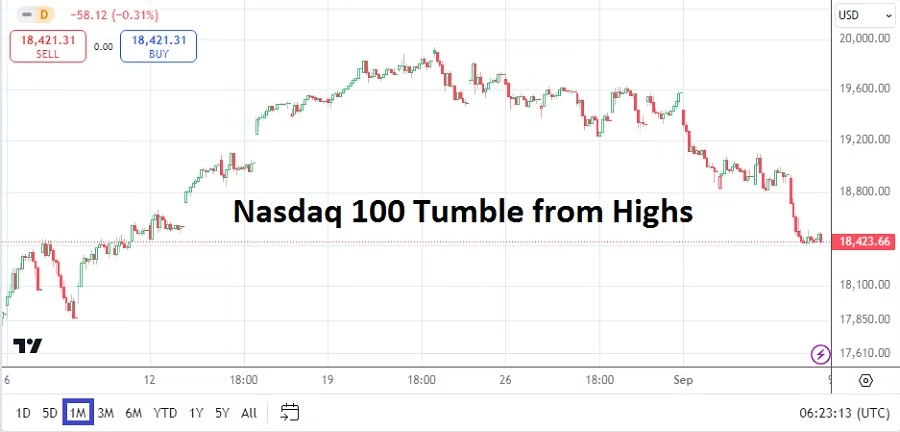
Nasdaq 100 One Month Chart as of 9th of Sept. 2024

Some analysts may apply the thought that what we have seen was profit taking, and this can certainly be debated. The coming two weeks have plenty of noteworthy events on the calendar. Besides the listed risk highlights noted below, the Fed will release its FOMC Statement on Wednesday the 18th, the BoE will follow on the 19th and not to be outdone the Bank of Japan will step onto center stage on Friday the 20th of September.

While long-term investors likely believe all variables will return to known price realms and that central banks sooner or later will fall into their proper places regarding monetary policy, day traders who are gambling on short-term momentum must try to figure out where behavioral sentiment is leaning. One of the ways speculators without deep pockets can put the odds in their favor concerning potential profits, is to make sure they are practicing rock solid risk management and not stepping into Forex trades, equity indices via CFDs wagers, and commodities bets when they are displaying rough conditions without being prepared.

Monday, 9th of Sept., China Consumer and Producer Price Index – the inflation reports from China both came in below their estimates earlier today. While some may believe that less inflation than predicted is a good thing, it isn’t when the economy is suffering from deflationary pressures. Lackluster spending from consumers in China continues to highlight negative sentiment about prospects for growth. The USD/CNY is near the 7.1125 ratio as of this writing.

Tuesday, 10th of Sept., U.S Presidential Debate – while not an economic data event, investors might want to pay attention to the answers given by Vice President Kamala Harris and former President Donald Trump. The race for the White House appears to be close according to various polling. It could prove interesting for financial institutions if Harris is questioned about her ideas regarding taxing unrealized capital gains.

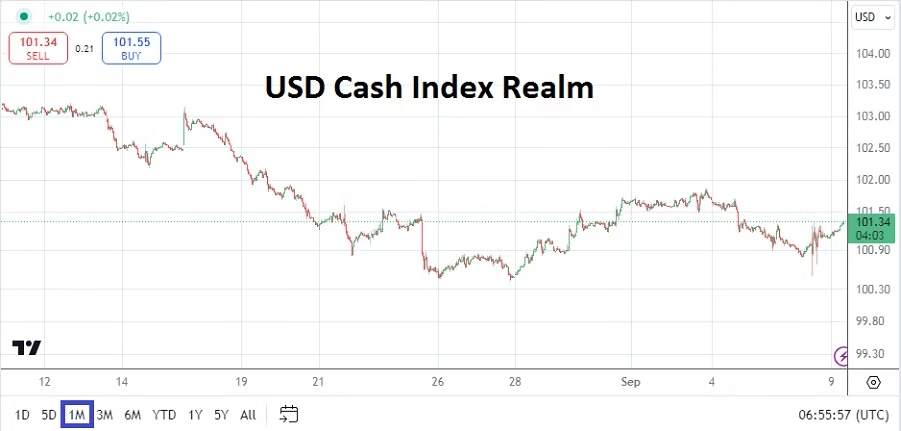
USD Cash Index One Month Chart as of 9th Sept. 2024

Wednesday, 11th of Sept., U.S Consumer Price Index data – the inflation reports will certainly get the attention of financial institutions. If the annual CPI report comes in weaker than the previous outcome, this could spark more USD centric weakness in Forex. All asset classes will react to the inflation numbers because they are likely to play a major part in the Fed’s FOMC decision in one week’s time. The USD Cash Index is still lingering near lows, but for it too resume a more bearish trajectory, financial institutions will need to believe the Federal Reserve is going to become increasingly dovish.

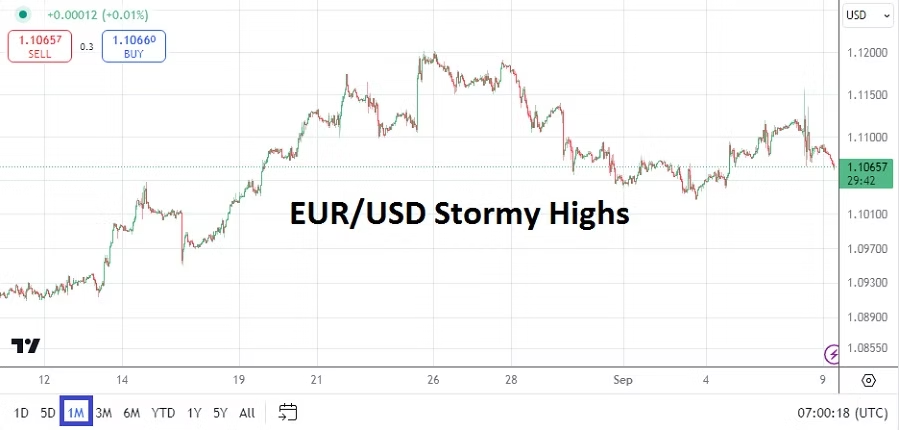
EUR/USD One Month Chart as of 9th Sept. 2024

Thursday, 12th of Sept., European Central Bank Main Refinancing Rate – The ECB is definitely going to cut its prime borrowing interest rate, the question is how much of a haircut they are going to provide. A 0.25% cut has certainly been traded into the EUR/USD, but many financial institutions believe there is a possibility to see a 0.50% basis cut. Can the ECB and Christine Legarde be aggressive? The European Union remains under recessionary pressures and inflation data is starting to show signs of erosion. The amount of the interest rate cut from the ECB will also be a telltale sign regarding what will happen via the Federal Reserve on the 18th of September. The EUR/USD will react to the European Central Bank’s decision, and global assets in far off places may react too because behavioral sentiment among investors may shift according to the rhetoric provided. Prediction: The ECB will stay cautious and cut by 0.25%, while saying a November rate cut is likely if economic data remains under pressure. Having said the above, the ECB should cut by 0.50% this Thursday, if they do not – financial institutions will not be pleased unless ECB President Legarde sounds very dovish during her Press Conference.

Thursday, 12th of Sept., U.S Producer Price Index – more inflation data from the U.S will provide investors an other opportunity to glance into the Fed’s looking glass. But if these PPI numbers meet or are near the anticipated results, financial institutions may be reacting to the ECB’s rate decision more because they might believe it is a better clue regarding the Fed’s Federal Funds Rate decision which will come in a handful of days.

USD/JPY One Month Chart as of 9th Sept. 2024

Friday, 13th of Sept., Japan Revised Industrial Production – this number may not get much attention, but because the Bank of Japan will release its Policy Rate on the 20th, the outcome could impact existing sentiment in the USD/JPY. The Japanese Yen has continued its bearish trajectory and traders who are wagering on more downside should not bet blindly on selling positions because intraday trading remains very choppy. The USD/JPY is now touching values last seen in a sustained manner in early January of 2024, lower values were seen in December 2023, and lower ratios that traversed the 138.000 realm and proved choppy occurred in the spring of 2023.

Saturday, 14th of Sept., China New Home Prices, Retail Sales, Industrial Production – this parade of data from the nation will be important. Foreign investors remain concerned about China’s economic prospects. The deflationary winds that have been blowing in the Asian giant have been well documented. The results from these three reports are expected to be lackluster.