post265

Trading Thud Ending Last Week and Early August Insights

Trading Thud Ending Last Week and Early August Insights

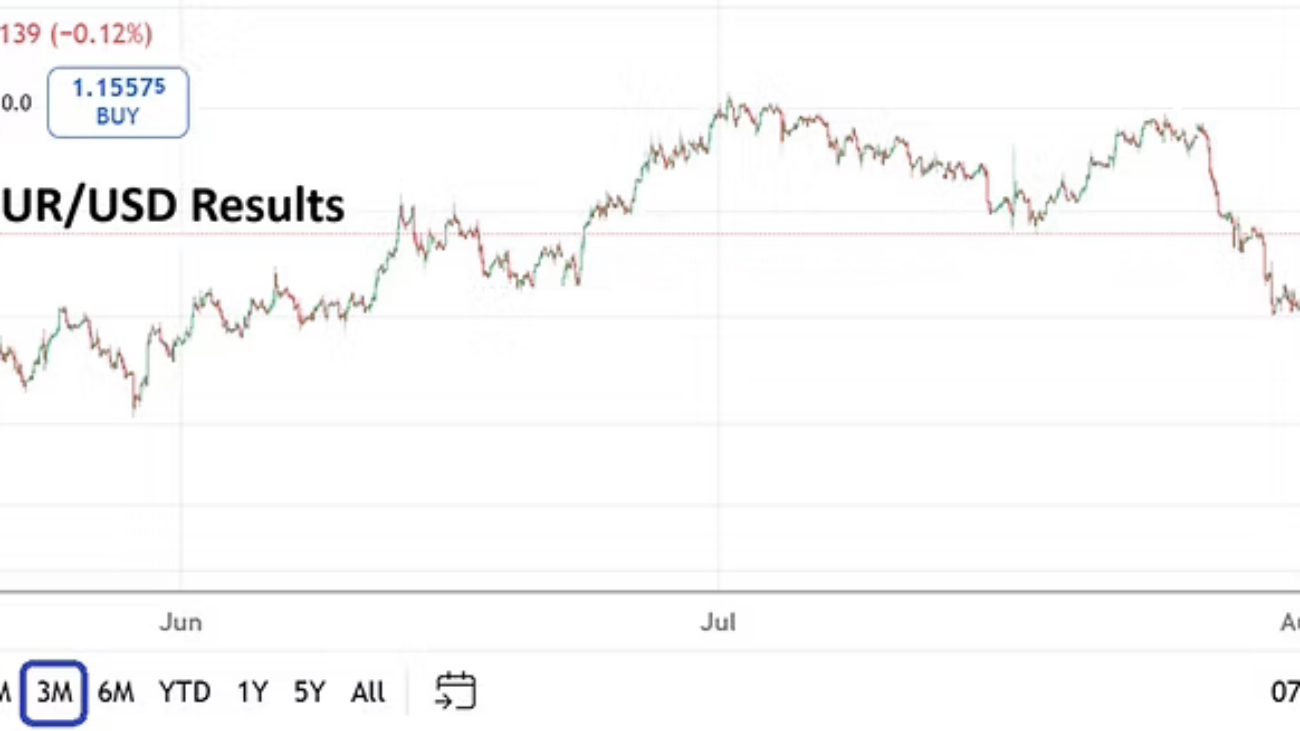
The EUR/USD is near 1.15650 early this morning. The USD/JPY around 147.850. Forex has provided fast reversals and most major currency pairs are within well established known realms, but caution prevails. Friday’s U.S jobs numbers before going into weekend provided additional mud to filter through for those seeking clear outlooks. Were the employment numbers rigged by the Bureau of Labor Statistics?
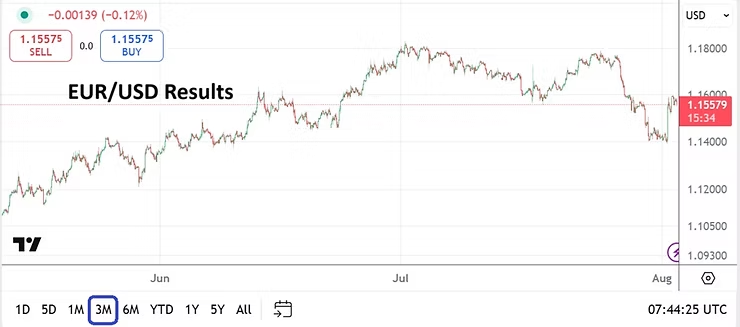
EUR/USD Three Month Chart as of 4th August 2025

Questionable economic statistics have become an open sore spot for some analysts in the U.S, this has been a problem since the financial crisis of 2007/08 and ensuing years when politically expedient numbers were rumored to be in use so the Federal Reserve and U.S Treasury could work in a more comfortable manner. Let’s just say there are actual reasons why and how economic statistics could be used to hurt and help policies. For some evidence take a look at the art of revisions that has been practiced with key economic data the past handful of years. Financial institutions now need to consider the possibility that numbers cannot be trusted, interpret reports, try to decipher reality and consider impact.

Effect on the Federal Reserve is a big question. Fed Chairman Jerome Powell continues to preach uncertainty and say a wait and see approach is needed because of implications regarding tariffs. However, conspiracy theories are also somewhat blown out of the water regarding the recent jobs numbers, because the lackluster results will actually put pressure on the Fed to cut rates in September in order to help spur on a better jobs market. So in other words, financial institutions, big investors and day traders are back to square one.

The ISM Services Purchasing Managers Index stats will be published tomorrow for the U.S, but this report is likely to be a mere ingredient that affects the marketplace. Behavioral sentiment will remain the cornerstone in Forex, equity indices, Treasuries and commodities. August is typically a rather calm month of trading taking into consideration that holidays are being taken by many market participants, but as the S&P 500, Nasdaq 100 and the Dow 30 remain elevated and capable of achieving new record highs, the USD creates chaos regarding outlook influenced by a Federal Reserve that is now in a difficult spot, and tariff implications are contemplated it would be wise to keep an eye on all near-term outcomes.

Technical trading and computer generated algos will factor into conditions as psychological levels are challenged and perceptions are debated. Has the global marketplace grown comfortable to the tactics used by President Trump? While it is easy to say yes, there are still plenty of reasons to remain concerned, this because White House policy seemingly has the ability to shift without notice.

Which has helped produce what may be the golden rule that develops under the current circumstances. Stay alert, stay optimistic but practice caution. Financial institutions have always practiced the art of realpolitik behind closed doors to chase profits, but they must remain vigilant to fast reactions caused from the potential sudden fear of shifting doctrine. President Trump’s rather swirling mix of laissez faire enterprise, and his stark ability to express anger at those who stand in his way or disagree with him do make for a new trading reality. Cautious optimism is likely to rule the world of investment and speculation going forward.
post261

Unpredictability of President Trump and the Markets

Unpredictability of President Trump and the Markets

Everyone wants to know what will happen in the future in the financial world. Most everyone also knows that this is impossible. However, clarity about the mid-term is a legitimate focal point that financial institutions strive. Risk managers define their considerations on assorted perspectives depending on their backgrounds.

While some may like him and others clearly are are not fans, President Trump has a reputation for wanting to get things done. His calling card for a long time has been an ability to make business deals. President Trump however has put himself in a rather difficult position and the next two weeks may prove to be an important milestone. One in which those who like the President and those who don’t will be given more credence to debate.

The Federal Reserve will announce their FOMC decision on the 30th of July. Tariff deadlines will supposedly come on the 1st of August. President Trump has made it clear he does not like the lack of aggressiveness which Fed Chairman Jerome Powell is displaying. Trump has called for the Federal Funds Rate to be cut and Powell has not acquiesced.

President Trump has openly spoken about trying to replace the Fed Chairman, but at this juncture the Trump White House knows this will be difficult unless they can prove Jerome Powell has done something maliciously. Not lowering the Federal Funds Rate because of a fear inflation will develop because of potential effects due to tariff fallout is a legitimate reason not to act. Even if the Fed Chairman is wrong, he appears to still be working on a basis which is based on an economic interpretation.

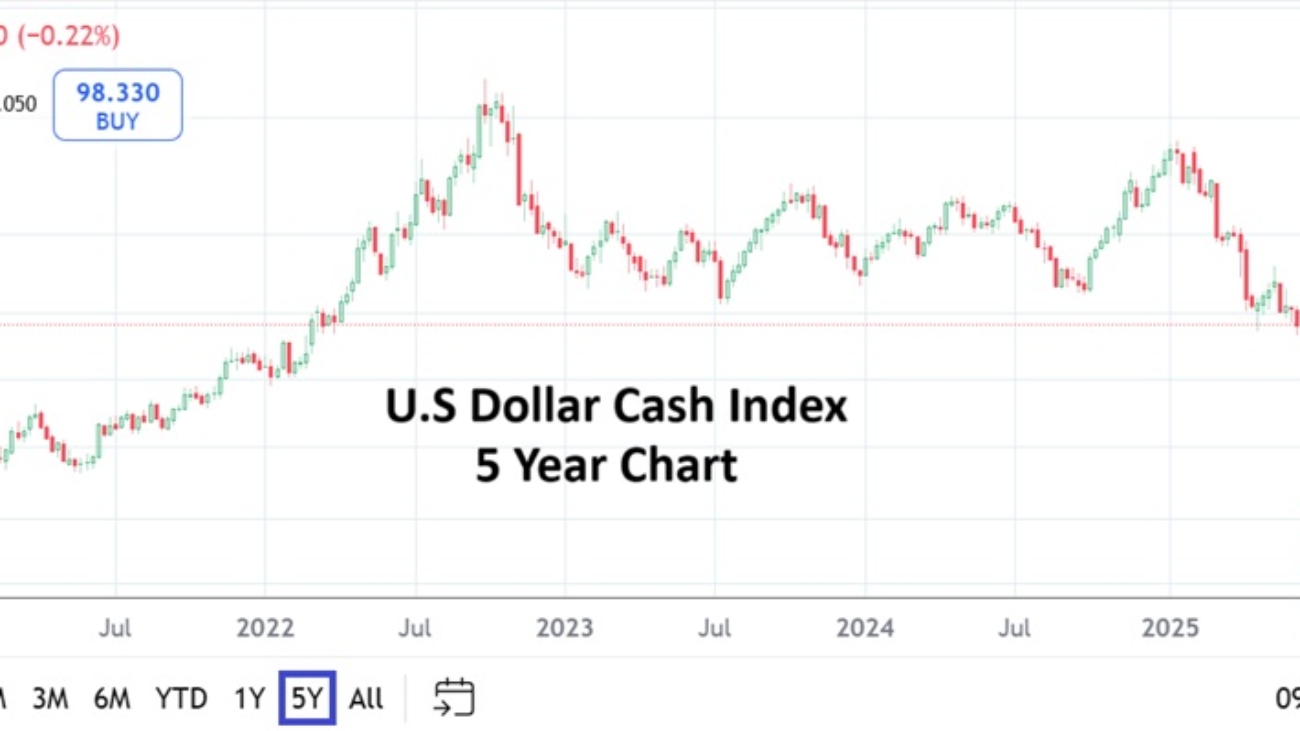
For the next two weeks the broad markets will hear about the Trump and Powell disagreement. It has been argued the Federal Reserve should have lowered the Federal Funds Rate a few months ago, clearly this was not done. However, the USD did trade with weaker sentiment in Forex from early April until the beginning of July. In the past few weeks the USD has garnered some strength, but remains within the lower part of its long-term realms via the U.S Dollar Cash Index. The weakness in the USD was likely due to financial institutions betting on rate cuts to come over the mid and long-term, and which they still believe will happen.

The upwards momentum generated recently by the USD has put the greenback in a position that seems to indicate financial institutions are transacting their cash forward orders cautiously for the moment, while waiting on the next round of impetus. And that is where Federal Reserve clarity and tariff threats now shadow mid-term outlooks.

U.S Dollar Cash Index Five Year Chart as of 21st July 2025

We have entered an unpredictable window and President Trump apparently doesn’t mind allowing a little danger into the mindsets of the financial markets. It is one thing to proclaim tremendous results and great, magnificent prospects, but how long will investors tolerate a lack of clarity regarding tariff agreements? President Trump has postponed the tariff deadlines several times and what should be considered is the potential that at some point he will have to take action to prove he means business. If the August 1st deadline is extended again this may not cause much of a shock, but it will not be met with optimism.

Instead, the main interpretation from financial institutions may be that Trump is struggling to get agreements done as he had promised. While that might lead to the idea that global commerce will continue on as is, this will certainly not help create the positive impetus which President Trump desired. At some juncture President Trump may begin to be perceived as the little boy that cried wolf. No one will pay attention and the markets will proceed without him. But President Trump will not likely let that happen, he does like attention.

The Nasdaq 100 and the S&P 500 are near record highs, so there isn’t a lot to complain about by index investors. The U.S economy has shown signs of green shoots regarding better retail sales and the recent Philly Fed Manufacturing Index. The grey area for many remains inflation, which has been coming in rather well behaved although the most recent report showed a slightly higher outcome with the yearly CPI reading. However, the Federal Reserve actually has evidence that inflation has been tame. Yes, there are questions regarding the coming influence of tariffs on the U.S economy, but for the moment inflation has not risen.

The lack of clarity and not having a mid-term comfort level which is unperturbed may be problematic for small U.S business owners that face tariff concerns on their imported goods. And the bigger picture remains unclear for large U.S corporations – but they certainly continue to try being optimistic. And this is where it gets more dangerous, plenty of perspectives are being driven (inspired) by analysts who have confirmation bias. For instance the downturn in the USD from April until early July was amplified by many who saw this as a sign the USD was being punished by foreign governments opposed to President Trump. This in fact was highly unlikely, traders need to remain alert to false narratives.

The next two weeks need to be treated carefully. There will be a running monologue among many analysts that changes daily as behavioral sentiment moves depending on what is being spoken about the Federal Reserve and tariffs. However, until there are actual answers the financial markets are likely to remain rather choppy. Self awareness will be crucial for speculators. Also, a large factor in the financial markets will be played by the U.S White House regarding how incoming results are presented. Until then day traders may want to watch technical charts and try to figure out where programmed trading lurks regarding support and resistance levels. Price velocity in Forex, bond yields and gold should be monitored.

post252

No Chance of a Nimble U.S Fed as Entitled Investors Served

No Chance of a Nimble U.S Fed as Entitled Investors Served

On Wednesday of this week Consumer Price Index numbers will be published, followed by Producer Price Index data on Thursday. Inflation statistics from the U.S for several months have been coming in rather tame and sometimes below forecasted results. Fed Chairman Powell and his team of FOMC members continue to plead uncertainty as the main reason for a lack of Federal Fund Rate cuts because of tariff concerns. The next meeting by the Fed finishes on Wednesday the 18th of June.

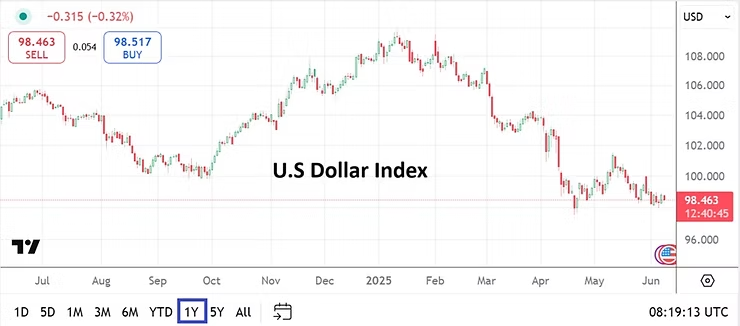
U.S Dollar Index One Year Chart as of 9th June 2025

Even if the inflation numbers come in as anticipated in the next few days, the Federal Reserve is unlikely to cut interest rates next week. President Trump and some in his cabinet have spoken about the need for rate cuts. Not only would it help consumers via mortgage rates, borrowing costs to buy autos and other high ticket items, but it would help the U.S government pay less on interest rate expenditures generated by inflamed Treasury yields.

The Fed continues to stay passive about its outlook, but if inflation data via the CPI and PPI are near forecasts this week, why would the U.S central bank continue to take such a stubborn stance? Interest rate decisions are not supposed to be political. The Fed has pointed to the potential of sudden inflation occurring due to tariff implications. This is a genuine concern. However, why can’t the Federal Reserve be more nimble? Inflation has not shown signs of immediate upwards pressure.

Perhaps it is because the Fed serves large U.S and foreign financial institutions, and has gotten into the habit of telling important folks not only what it anticipates, but handing out its interest rate plans on a silver platter so large players can position themselves beforehand like entitled elites. The Fed is very unlikely to cut interest rates the middle of next week, but it is probable they will open the door to a 25 basis point cut in July. However, July’s meeting is scheduled for the end of that month, in essence this is the middle of the summer, which is a long time to wait for action.

Day traders hoping to ride the trends that flow through the marketplace as they pursue speculative wagers remain in a difficult spot. Intraday volatility remains dangerous. Mid-term outlooks are certainly taking hold in Forex and equity indices, but sudden reversals for those using too much leverage continues to cause harm. Short-term speculators need to remain patient and vigilant, it is important to remember day traders are seen as second class citizens in the big scheme of the financial world, and this is not going to change for the moment.

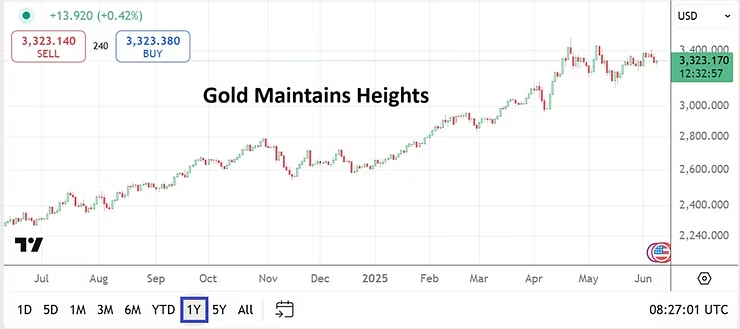
Gold One Year Chart as of 9th June 2025

A lack of clarity has spooked large players in the financial markets the past handful of months, but it does appear many institutions are becoming more comfortable. Though not at all-time highs, the major stock indices are within sight of important values. Behavioral sentiment seems to be leaning into a more positive outlook. Large investors appear to have concluded that while President Trump talks a tough game and often presents a strong stance, that ultimately he allows for tactical maneuvering to achieve deals. Trump is not big on being polite and this occasionally inflames markets. Bullish sentiment is growing on the hope President Trump’s characteristics are understood.

The Fed and the White House are likely to continue locking horns for the next few weeks. Perhaps if Jerome Powell tries to placate Donald Trump with a solid hint of an interest rate cut in July this will smooth things over. However, waiting for an interest rate cut in late July seems like a road too far, particularly when inflation levels the past couple of months avail the U.S economy to proactive actions from a Federal Reserve now.

Let’s remember, there is no law that says the Fed cannot cut or raise interest rates only during the conclusion of FOMC meetings. The U.S central bank has the ability to make changes to the Federal Funds Rate whenever it deems needed. Yet, the Fed refuses to be nimble in an age when technology allows data to be attained faster, this is a detriment.

The inability of the Fed to show it can be agile is another reason why investors are nervous about U.S policy regarding fiscal matters. The U.S government’s bureaucracy is too slow and bloated. The U.S is still a golden place to invest, but it is becoming problematic and this is leading to changes which effect long-term financial decisions.

post240

Market Volatility Shelf Life Doesn’t Have an Expiration Date

Market Volatility Shelf Life Doesn't Have an Expiration Date

Updated: Apr 11

An associate in the financial world just wrote to me that “all bets are off”. Perhaps that is a solid way to think about the present speculative and investment situation. The tumultuous wave of hysteria in equity indices, Forex, commodities and U.S Treasuries are evident to everyone. President Trump’s tariff policies released last week lacked precision via perspectives for many investment institutions who suddenly had their mirage of calm destroyed. The realization that President Trump was undertaking what he had promised caught many by surprise who thought he was bluffing. Trump’s ‘Art of the Deal’ tactics are now being confronted by middlegame chess strategies from opponents.

While the broad markets have boiled and folks look for calm to return, the prospect that current volatility has the potential to carry a long shelf life with no expiration date has to be considered. Yes, the financial world will become serene again. The return of semi-tranquil trading has been seen in the Nasdaq, S&P 500 and Dow 30 the past couple of days – only because the losses and gains depending on the index have been moderate compared to last Thursday’s and Friday’s results.

Yet the shadow of more violent trading remains crystal clear. China and the U.S are now exchanging loud threats which include higher tariffs and retaliatory measures. The USD/CNY is under scrutiny as devaluation by China appears an evident threat. And U.S Treasuries are being watched as some contemplate that China is undertaking a selloff of U.S bonds. Higher U.S yields on long-term Treasuries will create pressure via the amount of debt the U.S will be obligated to pay.

Vice President J.D Vance’s peasant comments about China were not helpful on Tuesday. Why must a hornets nest must be stirred up? China has now been hit with a 104% tariff from the U.S, this while China has vowed to ‘fight till the end’ in its media. Asian markets are selling off cautiously this morning as tensions reignite. Forex pairs such as the USD/SGD, USD/ZAR and USD/BRL should be watched as a barometer not only by currency traders, but by those who want metrics regarding how global economic sentiment and credibility of policies are being contemplated. Risk adverse trading in emerging markets will cause harm and has the earmarks of looking like a stiff penalty for nations trying to develop and raise their standards of living.

While the start of this week has been smoother in relative terms compared to last week, the lack of a comprehensive end game is still missing. There is merit to treat current circumstances with cautious respect. The mid-term outlook remains highly questionable as President Trump and his negotiation gambits are tested publicly.

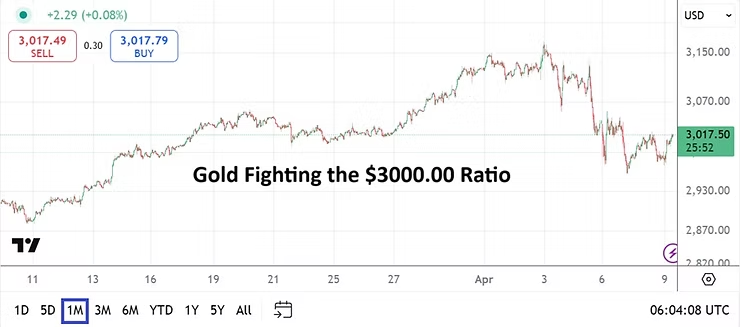
Gold One Month Chart as of 9th April 2025

Gold has stumbled back to the 3000.00 USD level, WTI Crude Oil is down and these two commodities are intriguing as a looking glass into the hearts of large players. Are people selling gold short-term because they believe inflation will lessen because of a recession which some are forecasting, or is it merely a speculative move? Gold certainly carries an important risk adverse power and its lower move showed be looked upon skeptically.

WTI Crude Oil One Month Chart as of 9th April 2025

Is WTI Crude Oil selling off because there is a belief there will be less demand due to fear tariff policies will influence a stumbling global economy? This viewpoint is plausible, the price of the commodity falling below 60.00 USD is a warning that large players are not comfortable with their outlooks and view downside risks as legitimate. The energy selloff in the past couple of hours is a negative barometer for what potentially is in store the remainder of the day in the broad markets.

The lack of finesse exhibited during these tariff negotiations is not palatable, the taste in the mouths of financial institutions has them worried. And outlooks via talking heads and analysts must be treated carefully by traders, this as they try to digest the onslaught of information and complex economic scenarios. Importantly, day traders should avoid getting caught up in the deleveraging talks surrounding the notion that large financial institutions will now pull money out of their U.S based investments in companies via stocks and Treasuries. Traders need to consider the bias of the people they are listening to and reading, and consider the scope and might of the U.S economy mid and long-term. There will be value found after the massive selloffs.

As a side note Warren Buffett has let it be known for a while he is sitting on a large amount of cash via Berkshire Hathaway. And folks should note that the annual meeting for Berkshire Hathaway is on Saturday the 3rd of May, which means people should get ready for insights from Buffett and his legions of admirers in the coming weeks. Certainly, Buffett’s comments and potential actions will be watched carefully.

The U.S Federal Reserve has taken a wait and see approach to the Trump tariff implications. Calls for an immediate cut of the Federal Funds Rate have not caused Fed Chairman Jerome Powell to shift his cautious stance yet. The coming days could bring a different attitude from the Fed if equity markets and U.S Treasuries perform badly. In the meantime some central banks have said they might become more proactive – the Reserve Bank of New Zealand cut its interest rate by 25 basis points this morning to 3.50% and said it will continue to cut their Official Cash Rate if tariff policies create more negativity.

The consideration by financial institutions regarding the beginning of a paradigm shift of the global economy is justified. However, the ramifications of the Trump tariff policies have a long way to go before these present days will be able to be pointed to as the moment the world decided that it no longer wants to participate in the U.S marketplace. That notion seems farfetched. The USD remains the world’s reserve currency, its corporations remain extraordinarily large and valuable, and U.S Treasuries as they absorb current volatility and see yields moving higher in the 30 Year bonds cannot be viewed as an economic apocalypse – yet. Yes, the warning signs are meaningful and the Trump White House will need to respond diligently.

Again, the past week of trading has seen vast disarray, but we have been here before. It is important to recognize that current circumstances however do remain dangerous, this because we are still in the midst of the crisis. At some point, egos will have to be put to the side. The Trump White House will have to negotiate with China. China may be vulnerable, but so is the U.S. Why be belligerent and show no respect to each other? The remainder of this week’s trading will produce more whipsaw results. Selling looks to be in vogue once again this morning. Behavioral sentiment and understanding its power need to be contemplated as folks await sunnier days.

post235

Predicting the Federal Reserve and President Trump’s Rhetoric

Predicting the Federal Reserve and President Trump's Rhetoric

Financial institutions have grown accustomed to the rather fierce rhetoric from President Trump in the early days of his second term. Financial institutions have also become quite used to the recent overly cautious statements from the Federal Reserve. This Wednesday the Fed’s FOMC Statement will be delivered and there will be no change to the Federal Funds Rate. The current ‘main’ borrowing rate offered by the Fed is 4.50%.

US Dollar Index Five Year Chart as of 18th March 2025

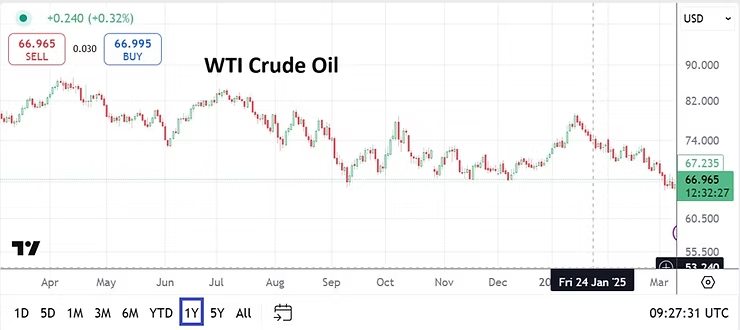
This Wednesday Fed Chairman Jerome Powell will speak about the recent CPI and PPI numbers which came in below expectations. This typically would be a good signal regarding weaker inflation. And Powell might also mention that energy prices in the U.S have started to erode. WTI Crude Oil is now trading in a sustained manner below the 70.00 USD threshold, and this will influence the potential of less inflation. It is a good development for the U.S and Federal Reserve.

However, Powell is unlikely to express the unease and anxiousness the Federal Reserve has regarding President Trump, this because the Fed certainly doesn’t want to get into an open confrontation with the White House.

The U.S Treasury is now being run Scott Bessent who was selected by President Trump. Bessent ran the Key Square Group and is well respected in financial circles, which includes vast experience in top financial institutions. Powell though perceived as pragmatic by many analysts, may not be within President Trump’s trusted inner circle like Bessent and Commerce Secretary Howard Lutnick, the former Chairman and CEO of Cantor Fitzgerald. Lutnick is perceived as a workhorse who get things done and is smart.

The Fed’s likely cautious FOMC Statement will not be enough to appease President Trump this week. While some may think Trump’s attention will be elsewhere, those who have come to understand Trump know his capability to react quickly to events should be taken seriously.

What will Bessent and Lutnick think about the Fed’s FOMC Statement and stance? Powell is not a trained economist, do Bessent and Lutnick trust Powell? One thing for certain is that Janet Yellen who served as the Fed Chairwoman before Powell, and the Treasury Secretary before Bessent is not part of the inner circle in the White House.

Powell’s loyalties may be questioned, and eyes should be kept on Trump later this week to see how the President responds to the rather cautious Federal Reserve. The Fed will certainly not want to say aloud it is waiting like everyone else regarding the effects of tariff negotiations and their implications. Powell wants to keep his job. Trump certainly wants lower interest rates. Bessent and Lutnick certainly want lower interest rates too, but like Powell these two may prove pragmatic and know inflation needs to erode further. The Treasury and Commerce secretaries may want to test chicken and egg questions. Will these two gentlemen push Trump to proactively push for lower interest rates in a louder fashion?

Day traders will have to wait to see how financial institutions react to tomorrow’s FOMC Statement – which has already been accepted as being a ‘no interest rate cut event’. And it is probably being discussed in the White House that the Fed may want to wait until early this summer – June? – to consider another interest rate cut. Which means the Fed may not be cutting interest rates mid-term, while the ECB and BoE may have to be more dovish and remain active via interest rate cuts if their economies continue to show recessionary trends.

Meaning that risk premium which was factored into the stronger USD centric buying since the Trump election on the 5th of November until the peaks in mid-January and early February, and have now reversed lower – needs to be watched technically and weighed in combination with behavioral sentiment.

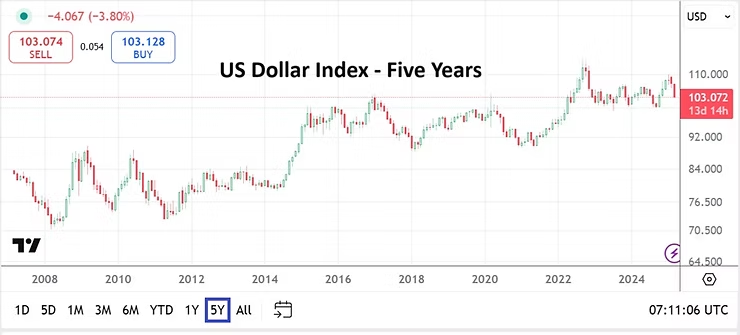
Intriguingly the US Dollar Index is around levels it stood at on the 5th of November (Election Day 2024). It is also near values seen on the 15th of October. (Did financial institutions start to bet on a stronger USD around this time because of a more cautious Fed outlook and the potential Trump was going to win the election?) Raising the question, if financial institutions envision the USD can technically be weaker and attain values seen in late September and early October when the US Dollar Index was testing support levels which have held since April of 2022. The US Cash Index which stands around the 103.070 level now, was trading near 90.00 in the spring of 2021.

Trump wants lower interest rates, the Fed wants to wait on cutting the Federal Funds Rate until they have clarity regarding the results of tariff negotiations. There will be a collision between Jerome Powell and Donald Trump, the only question is when it will happen. The US Dollar Index has been lower historically. Trump, Bessent and Lutnick may not want to say it out loud, but a weaker USD in the global economy would help U.S exporters. A weaker USD may not convey the strong populist rhetoric of MAGA, but it may be economic hardware the Trump administration actually seeks. To sustain a weaker USD, inflation levels will have to erode, and interest rates will have to be lower (and another myriad of complex events have to happen), until then rhetoric and risk premium will factor into USD Forex trading for financial institutions and speculators.

post233

Stock Market Narrative and Looking for a Trump Silver Lining

Stock Market Narrative and Looking for a Trump Silver Lining

S&P 500 One Year Chart as of 14th March 2025

U.S stock markets have been hit on the nose in recent weeks, the major indices have put in rather consistent declines since the 19th of February, and the selling frenzy and particularly noise have grown worse since the start of March. Narrative regarding tariffs and a lack of clarity have certainly had a negative effect. The notion that there is a part of the media that wants to see a downturn in the markets and blame President Trump could also be factoring into concerns and fragile sentiment among indices participants. I am not blaming the media for the downturn, just pointing out that there are some entities which are not unhappy about the recent selling in the stock markets, this because it fits comfortably into their narratives.

While the bearish decline on the S&P 500, Nasdaq 100, and Dow 30 have all been easy to see, defining the dynamics of the downturn, and reactions from day traders and investors are complicated. The stock markets are not guaranteed to always go higher. This may sound naive, but people have gotten so used to the notion that U.S indices always go up that they forget about the potential for downturns. Yes, the stock markets have turned negative, but a one month decline is not uncommon historically. And some of the folks rooting against Donald Trump may want to take that into consideration.

Risk premium has certainly been factored into the markets which has influenced equities, but has created forceful moves in Forex too. Risk adverse tension because of persistent rhetoric about tariffs and their impact on behavioral sentiment cannot be discounted. However, the stock markets are still higher over the past year.

The Trump Effect is certainly being pointed at by many as the cause for the sudden downturn, but it should be remembered that all-time highs occurred after Trump won the election. Yes, the selloff has definitely happened too, and stock markets are now traversing values seen before the election. And support levels are being looked at with caution and more selling could lead to a test of psychological ratios which pressure market confidence further. Yet, it should also be remembered the S&P 500 at this time last year was around the 5,150 ratio compared to its current mark near 5,565.

Day traders have been hard pressed to find momentum with solid wagering opportunities, particularly if they have been in search of a bullish trend in recent weeks. The belief that U.S indices always go up eventually is a solid reference, but in the short-term can cause expensive losses for stubborn betters. Investors certainly have an easier time with stock indices if they practice the long-game and do not worry about the daily and monthly gyrations when their money is parked in indices. The use of leverage when betting on the daily results of stock markets can become ultra expensive for speculators, particularly when upside bias is being counted upon.

WTI Crude Oil One Year Chart as of 14th March 2015

Data this week from the U.S has actually been positive regarding lower inflation, both the CPI and PPI reports released the past two days has shown a slow down in costs. Yet, these results have little to do with President Trump, since he has only been in power less than two months. However, the lower WTI Crude Oil prices being achieved at this moment will start to factor into weaker inflation and will benefit the U.S economy.

The U.S Federal Reserve will have to be watched, because Fed officials seemingly continue to be among the crowd worried about tariff knock-on repercussions. But it should be remembered during Trump’s first term in office, there were tariff concerns too and inflation was tame. It will take a few months to still see results via inflation under this Trump administration, but if energy prices remain stable and low, this can mitigate circumstances while the tariff winds blow and their effects are waited upon. Interest rates from the Federal Reserve, U.S taxes on the public will continue to come under scrutiny. The likelihood of Trump and the Federal Reserve locking horns regarding interest rates seems to be a certainty in the coming months.

U.S stock markets have proven dangerous for bullish perspectives the past handful of weeks, but the viewpoint that markets have been too discounted will certainly start getting the attention of large players. U.S Treasury yields remain a barometer, but short-term results do not always correlate. Speculators without deep pockets may want to continue to watch from the sidelines.

Traders should also remember there is the ability to short U.S indices, but this brings up the healthy question about when will price support start to become a factor. It is nearly impossible to pick the precise moment financial assets will stage a turnaround for day traders, but history does indicate that bullish sentiment will start to be seen. Betting on a continued downturn could prove more expensive in the end, compared to speculating on upside.

Trading is not easy. It takes a lot of stamina to endure price movements that do not go according to plans. The financial markets are proving difficult for many. We are likely not out of the woods yet because clarity remains problematic, investors who have longer timeframes are likely anxious too. Price velocity needs to be given attention, markets can certainly go lower. However, at some juncture equities will start to look cheap to important long-term players. Behavioral sentiment among investors will likely also start to acclimate to the Trump Effect.

post229

EUR/USD: Volatility is Visiting Again upon the Trump Effect

EUR/USD: Volatility is Visiting Again upon the Trump Effect

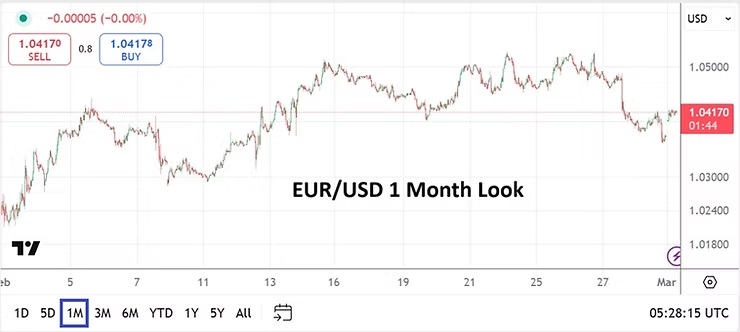
EUR/USD One Month Chart as of 3rd of March 2025

The EUR/USD bounced slightly higher in early trading this morning, this after Friday’s burst lower when nervousness was ignited by the loud outcome (and lack of a resolution) via the Zelensky and Trump meeting. However, after achieving some buying impetus to start today, the EUR/USD is running into nervous headwinds as concerns remain evident.

This Thursday the ECB is expected to cut another 0.25 from its Main Refinancing Rate. The difference between borrowing rates from the ECB and Fed will be significant if the ECB does lower costs. E.U economic data warrants the dovish policy, while concerns about stubborn U.S inflation persists. And President Trump will have something to say about the Federal Reserve’s policy too. Trump wants the Fed to lower the Federal Funds Rate.

The U.S will issue its Non-Farm Employment Change numbers this Friday. And many Fed members will be speaking at various engagements this coming Thursday and Friday which is certain to get attention. Financial institutions will certainly be listening for clues regarding the potential of shifting viewpoints regarding the Fed’s current stance which is cautious from FOMC officials.

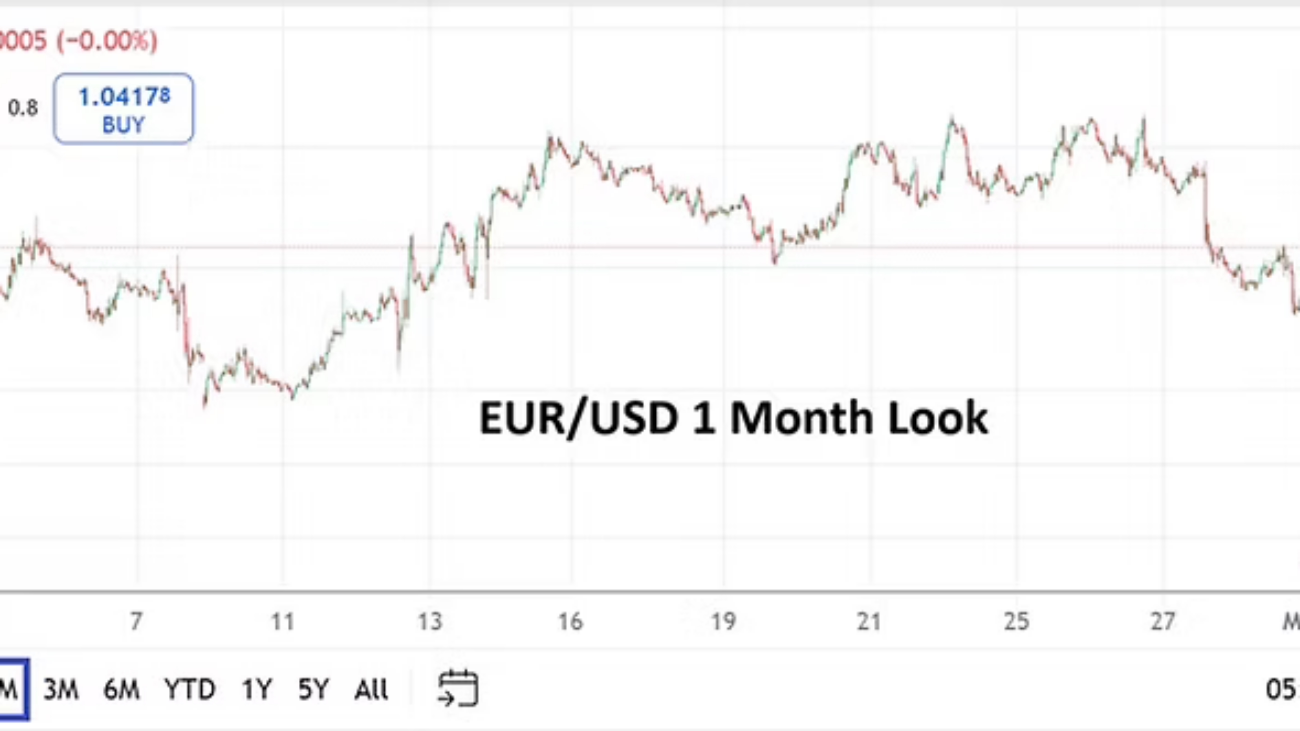
Which brings us back to the current value of the EUR/USD and behavioral sentiment which is being generated by a deep sea which is not clear. The EUR/USD into early last week was showing signs of bullishness, this as folks piled into the notion the currency pair was in oversold territory. The ability of the EUR/USD to remain above 1.04000 today should be watched. While there has been upside early this morning, European traders and full market action will begin to kick off in about one hour.

Day traders need to know the potential rate cut cut from the ECB this coming Thursday has been anticipated and factored into the EUR/USD already. Leaving the currency pair ready to be influenced by USD centric perspectives, and Ukraine concerns which are unresolved. The U.S equity indices should be watched too via their less than inspiring results the past week. While many financial institutions believe the EUR/USD should be valued higher, this may be based on instinctive bias instead of fundamental reasons.

Economists are great for insights, but it is skittish sentiment which is driving the markets. Volatility is likely and the price range of the EUR/USD could prove tactically challenging and wide. If cautious attitudes in financial institutions create calm, the EUR/USD could produce durable support levels, which could be used for upside wagers. Speculators will have opportunities in the currency pair this week, but risk management will be essential to protect against sudden gusts caused by swirling Trump rhetoric.

post221

A More Aggressive Sounding ECB Could be Wishful Thinking

A More Aggressive Sounding ECB Could be Wishful Thinking

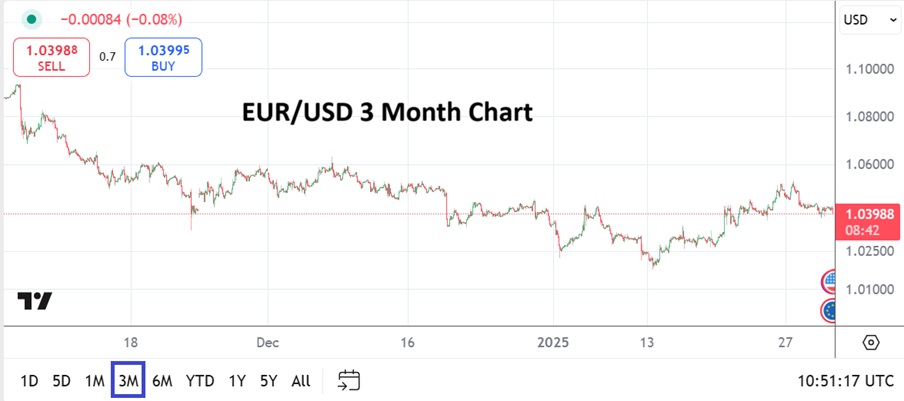
EUR/USD Three Month Chart as of 30th January 2025

Will an interest rate cut by the ECB spark near-term buying in EUR/USD today? Financial institutions want news they have anticipated, day traders need to understand this dynamic.

The Federal Reserve stood in place yesterday almost acting as if it is afraid of its own shadow. No one was surprised the Fed did not cut the Federal Funds Rate. The Fed insisted inflation remains slightly elevated, it also said it thinks most of the worst employment data has been seen. What it did not say was that it remains in a quandary regarding the potential affects of President Trump’s policy on the U.S economy. The Fed wants to stay away from this debate. They also likely understand Donald Trump will bring up the subject himself. Trump wants the Fed to cut U.S interest rates more.

On the other side of the coin today stands the European Central Bank, which is anticipated to cut their Main Refinancing Rate by another 0.25, this to the 2.90% level. Financial institutions have certainly factored an interest rate cut from the ECB into the EUR/USD already. If there is no cut, this would cause an immediate reaction and likely a bad one against the EUR.

However, if the ECB acts as expected and cuts their rate this might actually spur on some near-term positive thoughts about the EUR and create some buying momentum. But for the move to be sustained and stronger, as outlandish as it might seem, what financial institutions will want to hear is that the ECB understands the E.U faces ongoing tough economic conditions and will remain dovish.

The problem with an overly aggressive attitude by the ECB today is that this is not anticipated. Yes, the rate cut of 0.25 is being counted upon, but the ECB and Fed are not exactly bastions of pro-active policy change. The ability of the EUR/USD climbing above the 1.05000 ratio last Friday and into Monday of this week was a signal financial institutions believe the EUR/USD is oversold, but they want to see more concrete steps taken. Doubts about what the ECB will say today has likely led to the 1.04000 level again being tested.

It may seem counterintuitive to believe that interest rate cuts from the ECB and a overly cautious Fed will help the EUR/USD achieve a bullish footing, but behavioral sentiment regarding mid-term outlook is crucial. Carry trade folks may say that if the ECB were to promise another cut today after their actions taken now, that this would create too large a difference between the ECB and Fed borrowing rates. This may be correct, but pro-active policy is something financial institutions would like to see. Day traders should be very careful today.

The EUR/USD hovering near 1.04000 is a signal that financial institutions will certainly react, there will be volatility in the coming hours. A rate cut from the ECB today will be the first ray of hope regarding a stronger EUR. However, unless the European Central Bank sounds like they will remain vigilant and are considering another potential cut sooner rather than later, the EUR/USD could quickly start to become choppy again.

The EUR/USD is essentially occupying a price range right now that it traded one month ago. Sentiment remains jittery. And President Trump will be watching and his comments which could come at anytime regarding the Fed, interest rates, potential tariffs and sanctions will create vulnerabilities for Forex and financial institutions in the days ahead.

post217

USD/JPY: Bank of Japan Actually Does its Job: Raises Rate

USD/JPY: Bank of Japan Actually Does its Job: Raises Rate

USD/JPY Five Day Chart as of 24th January 2025

The Bank of Japan actually raised its Policy Rate by 0.25 to 0.50% this morning. The move was done while the central bank stated the Japan economy is improving. The Bank of Japan also noted that the implications of U.S tariff policy are not completely known, thus it is acting on existing facts. The action by the BoJ created selling in the USD/JPY and is a healthy sign.

While the U.S Federal Reserve has taken on a cautious tone, President Trump has started to signal via rhetoric that he would like to see U.S interest rates lowered. The Fed and President Trump may find that they are in disagreement regarding mid-term policy and Forex traders shouldn’t be surprised if the debate escalates. The USD/JPY is trading near the 155.500 vicinity with fast price action at this moment. The ability to sustain values below the 156.000 level will be important technically if maintained. A fall below the 155.000 ratio may indicate more selling should be expected.

While financial institutions globally remain nervous about U.S economic policy regarding trade negotiations, Japan for the moment is out of the spotlight regarding tariff implications. The USD/JPY was trading near the 153.000 area on the 17th of December and it will be intriguing to see if large players use this level as a target in the coming days.

Retail traders should practice solid risk taking tactics and conservative leverage. The ability of the Bank of Japan to increase its interest rate, while the U.S Fed is in the midst of considering no changes to the Federal Funds Rate is a potentially solid sign for USD/JPY bearish attitudes.

Global Forex conditions remain choppy, but there has been some buying of the EUR/USD and GBP/USD produced recently. Next week talk of tariffs against China, Canada and Mexico will heighten, but traders need to understand the tough sounding talk from Trump is part of his negotiation tactics. While he certainly seems intent on carrying out his mandate, he will also be open to finding a way to create agreements.

Behavioral sentiment is in charge of Forex for the moment. Outlooks remain unclear, but USD centric strength may be traversing within the apex of its highs in many cases.

post213

Federal Reserve Expected to Sound Guardedly Cautious Tmrw

Federal Reserve Expected to Sound Guardedly Cautious Tmrw

EUR/USD Five Day Chart as of 17th December 2024

Large traders are clearly bracing for the Fed tmrw as Forex produces volatile tight ranges. A rate cut is expected, but cautious Fed rhetoric will likely follow.

Forex has been a dangerous wagering ground for retail traders since the end of September. Financial institutions which clearly were betting on a more dovish Federal Reserve starting in early summer becoming a central theme into 2025 have been proven half right, this as the Fed has cut interest rates and is expected to do so tomorrow. However, being half right leaves the door open to also being half wrong, and financial institutions have reacted to this by becoming aggressive buyers of the USD since late September as perspectives have changed. The strong USD trend the past two months plus has hit some speculators hard.

The election of Donald Trump added a strong dose of impetus for USD buyers, this as the President-elect’s tough rhetoric regarding tariffs caused reactions and fear of unknown consequences. In the past couple of weeks more tranquil Forex trading has emerged and the USD finally started to give back some of its gains, yet the USD versus most major currencies, like the EUR/USD, remains within the the stronger elements of it range. While the Fed is expected to lower its Federal Funds Rate tomorrow by 0.25 to 4.50% tomorrow, traders need to remember this has been priced into Forex already. Tranquil trading the past two weeks indicates financial institutions have readjusted their outlooks to the incoming White House administration.

Now it is time to see if the U.S Federal Reserve has started to adjust their outlooks to what a Trump Presidency means. And financial institutions are keen to better understand the outlook of the U.S central bank. Inflation numbers while traversing lower are still rather stubborn and this may will not help the Fed’s mid-term mindset regarding interest rate cuts. GDP in the U.S has remained steady, and there is the potential the economy in the States will improve under Trump. Unemployment numbers while showing signs of weakness have not been terrible either. So while the Fed’s current Federal Funds Rate is higher than normal taking into consideration the historic average the past ten years, they still may not feel they have enough ability to cut interest rates too much more without sparking inflation.

A January rate cut seems unlikely at this time. If the Fed does sound guardedly cautious tomorrow, retail traders may see the USD get initially weaker due to the Fed rate cut, but then see a storm emerge and USD centric strength reappear all in the same day – perhaps in the span of minutes. Speculators need to understand that financial institutions have already baked tomorrow’s interest rate cut into the cake. So it isn’t the rate cut tomorrow that is important if it happens (if it doesn’t then that’s another story); it is what the Fed says and traders should expect them to be very cautious – because per the recent trading of the USD and a barometer it appears financial institutions are bracing for a more vigilant Fed.

Just like he has with many folks he views as uncompromising before, Donald Trump may begin to feel Federal Reserve Chairman Jerome Powell is not on his side regarding interest rate policy. If the Federal Reserve chooses to sound hesitant to cut interest rates in early 2025, it will be rather intriguing to see President-elect Trump’s response. Could a confrontation between the White House and Federal Reserve be in the cards over the next six months?

post209

Forex: Trump Effect and Reasonable Trading Caution for All

Forex: Trump Effect and Reasonable Trading Caution for All

The Forex market the past two months has created a profoundly stronger USD against many major currencies. The combination of late September intrigue regarding U.S Federal Reserve outlook, then nervousness about the approaching U.S election, followed by the subsequent results have been a dumpster fire for many speculators looking for a sustained return to USD centric weakness. Hopefully risk taking tactics have included a solid dose of caution.

This week’s Non-Farm Employment Change numbers scheduled for Friday may give financial institutions a moment to focus on economic data instead of President-elect Donald Trump’s loud pronouncements, but the effect may prove to only be momentary. It isn’t data that is driving Forex for the moment it is nervousness and fear of the unknown.

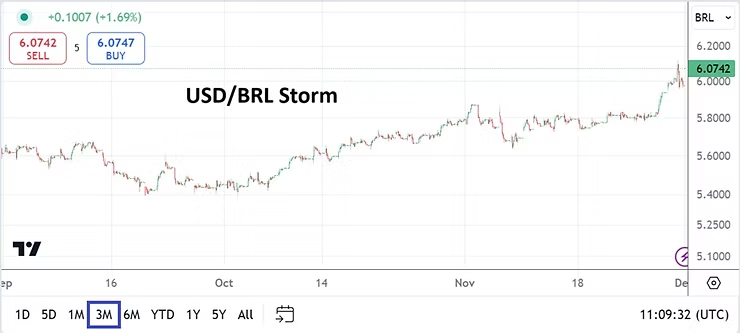
USD/BRL Three Month Chart as of 3rd December 2024

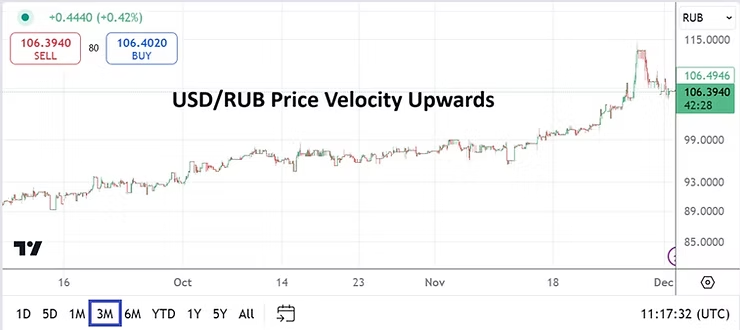
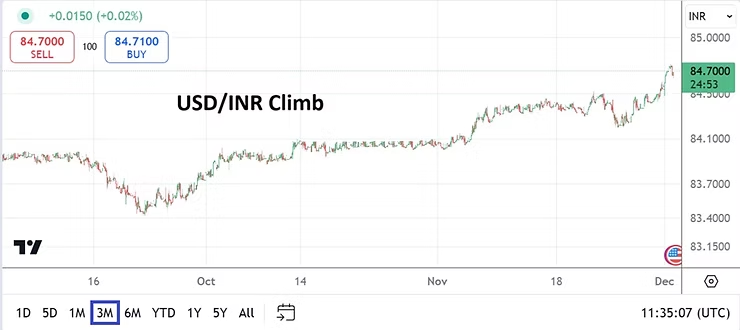
While many financial institutions and speculators trade only the major currency pairs, taking a look at the less obvious and more infrequently transacted major currencies may provide retail traders additional perspectives regarding the fragile nature of Forex. Many nations and large institutions are demonstrating concerns about possible sea changes to U.S foreign economic policy. Yes, the EUR/USD, GBP/USD and USD/JPY have all seen volatility via USD strength the past two months, but price velocity in the USD/BRL, USD/RUB, and USD/INR may be equally intriguing. And prove that mid-term forecasts (or lack of them) are causing bedlam for all.

USD/RUB Three Month Chart as of 3rd December 2024

While it is more than probable calmer heads will start to be seen in Forex and weakness eventually will return to the USD, trying to pick the exact moment this is going to happen remains a guessing game. Financial institutions via evidence in current Forex pricing remains rather cautious regarding their cash forward commercial enterprise. President-elect Donald Trump has certainly been dealt with before and his negotiation style is that of a businessman, it is not a coincidence that some global leaders who do not exactly see eye to eye with Trump are giving him respect because they understand he will act upon threats if not dealt with fairly.

Trump’s recent brief rhetoric regarding BRICS and the organization’s public consideration of creating a new currency to compete with the USD did not go unnoticed this weekend. Critics may want to proclaim Trump’s threats as belligerent, but BRICS is free to create a new currency still if they wish. While Trump cannot stop the birth of a BRICS currency, he can certainly try to initiate actions (via sanctions) against nations that attempt to create a new unified currency which tries to curtail the dominance of the USD. It would certainly help Trump’s bargaining position and the USD also, if better fiscal policy is practiced by the U.S Treasury and government.

USD/INR Three Month Chart as of 3rd December 2024

It needs to be pointed out that Trump’s warning to BRICS may not be needed. Even though the organization may be able to create a currency based on a commodities backbone, the lack of trust many financial institutions and nations would feel towards a non-transparent fiat currency powered by the fiscal monetary policies from the likes of Russia, China, Brazil and South Africa remains a difficult sell. Until many changes happen domestically within these nations via governance, creation of a BRICS currency remains wishful thinking.

Getting back to the big picture and the volatility recently seen in Forex. While the major currencies teamed against the USD have certainly faced hectic conditions, the fluctuations have not been unexpected. Day traders need to understand the month of December is likely going to remain choppy and see a test of technical support and resistance levels that are wide and full of fast reversals.

The question for the EUR, GBP, and JPY is if most of the negative inputs into these currencies has been factored into value. The suspicion may be yes, and that strength may rightfully appear in these big three sooner rather than later. However, the approaching holiday season and potential bluster from President-elect Trump will not make this a comfortable or easily wagered avenue.

Short-term retail traders looking to take advantage of the bloodbath created in Forex the past two months who seek opportunities should focus on perceived targets which aren’t overly ambitious. The coming U.S jobs data this Friday may allow the U.S Federal Reserve room to cut the Federal Funds rate on the 18th of December by another quarter of a point. As a point of attention, the European Central Bank will announce their Main Refinancing Rate on the 12th of December. The ECB’S actions may be a solid clue regarding the Fed’s approach to upcoming policy.

However, even if an interest rate cut were to take place via the Federal Reserve, it is likely the cut has already been factored into Forex. Which also highlights the high degree of nervousness that exists because of fears which permeate due to Donald Trump’s tough negotiation stances which have been made public. Meaning those who are looking for USD centric weakness to emerge still need to rely on a shift within behavioral sentiment to occur that is not generated because of the Federal Reserve. Nations need to show a willingness to amend existing trading agreements with the U.S, allowing for changes to internal policies regarding exuberant price duties they place on U.S goods in their own countries.

postR199.1

Forex: The Art of Not Making Sense and Accepting Price Values

Forex: The Art of Not Making Sense and Accepting Price Values

Retail traders are likely learning the hard way that attempting to trade in Forex for the moment is more than dangerous, it is expensive. The U.S Consumer Price Index numbers yesterday met expectations, which essentially allows the Federal Reserve to remain in a cautious dovish stance. However, after an initial show of USD weakness upon the data in many FX pairs, USD centric strength quickly returned.

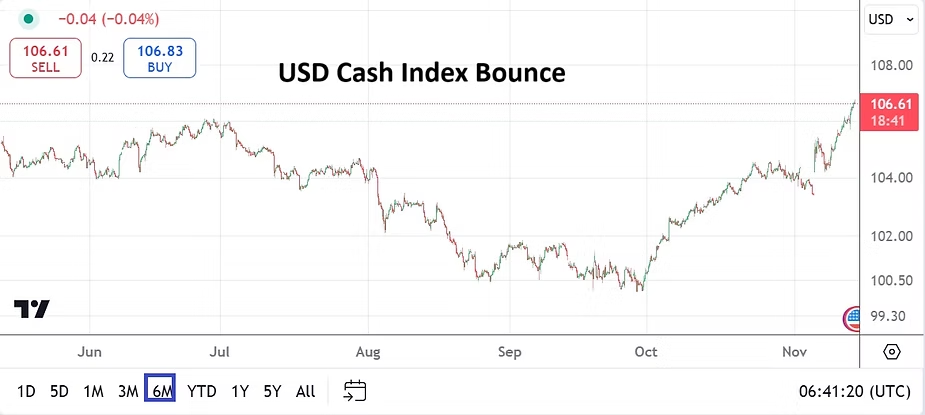
USD Cash Index Six Month Chart as of 14 November 2024

Short and near-term trading for speculators who do not have deep pockets and are suffering from whipsaw movements are creating the need to take a step back. As many major currencies have suffered losses against the USD since late September, the tendency is to likely think a reversal is going to develop sooner rather than later. However, until financial institutions become comfortable with the notion President-elect Trump’s policies aren’t going to harm economic prospects in a variety of nations regarding tougher trade agreements, risk adverse trading is going to remain a key in Forex.

Yes, at some point the USD will start to give back some value, but timing the moment this is going to start and become sustained for day traders is simply betting. Financial institutions are feeling anxious about their commercial forward positions in Forex too, which will continue to create volatility for all trying to predict where the USD will be mid-term. Federal Reserve policy may actually be able to deliver a 0.50 basis point total cut over the next few months, but this notion has had almost no impact on USD strength short-term. Perhaps financial institutions do not feel the Fed will be that dovish through February, but if inflation remains tame the Federal Funds Rate still has room to decrease.

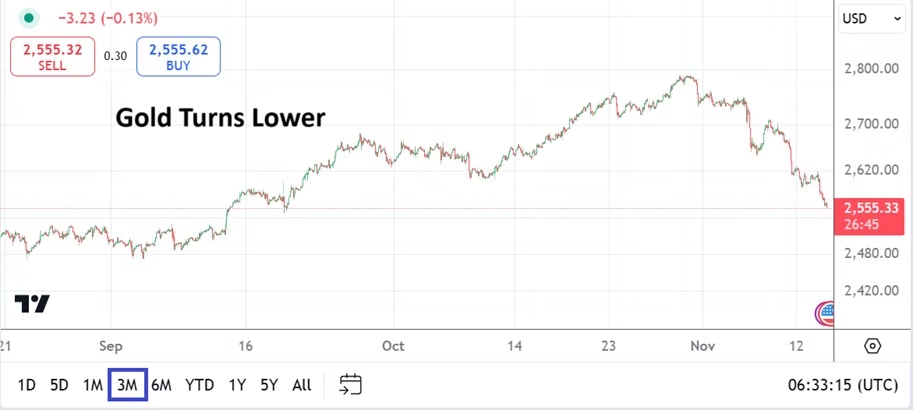
Gold Three Month Chart as of 14 November 2024

Today’s Producer Price Index inflation reports will be watched, but like yesterday the results are unlikely to be a key which will suddenly ignite strong reversals in Forex. In the meantime traders need to practice solid risk taking tactics and patience. Retail Sales figures will come from the U.S on Friday, but again day traders should expect financial institutions to remain risk adverse until there is an event which changes their cautious mindsets.

Gold is noteworthy because it has struggled since early November. There is the possibility the precious metal has turned lower because investors feel more sure about their long-term bets in the U.S equity markets for a moment, but that is likely wrong. It could also be argued speculators are cashing out winnings they have made the past handful of months. The point being that explanations for price movements are tenuous. False narratives abound. Fundamentals like behavioral sentiment are shifting because new economic policies from the U.S are going to develop and market participants want greater clarity.

Like the major currencies suffering significant declines versus the USD, the value of gold can be argued, but the market is telling us what participants are willing to pay for assets whether we agree or not. Let there be no doubt that the highs being produced in U.S Treasury yields which are near early summer values, the USD Cash Index reversing towards technical levels seen in early July, gold recently losing value, and U.S equity indices being near all-time highs makes it particularly difficult for predictions regarding what is next. Except to say the Trump victory in many ways has sparked a buy American parade for the moment. If you want to bet against the trends you are free to do so, but behavioral sentiment is proving once again the king of the hill.

While the broad markets may not feel like they are making much sense to some, as traders we need to be able to put our bias to the side and accept the markets as they are, not what we think they should be. There is a significant difference between near-term and long-term targets. Day traders need to understand they are wagering in markets that will remain dangerous for a while. Nothing is guaranteed, but the idea that U.S equities may continue to rally into the New Year is being wagered upon by larger players and they might be proven correct.