postN30.1

Summertime Behavioral Sentiment Game: Who Do You Trust?

Summertime Behavioral Sentiment Game: Who Do You Trust?

Have we started to reach a polite equilibrium within Forex, gold, equities and bonds for a moment? U.S CPI data just came in below expectations, the decrease of inflation pressures in the U.S will be welcomed. Price ranges are starting to show signs of polite trends in Forex and equities – there seems to be a recognition of basic ideas which are perhaps serving as factors that are ‘accepted’ in the broad markets. Please do not close your eyes for long, because conditions can change in a moments notice, but for the moment the USD is weaker.
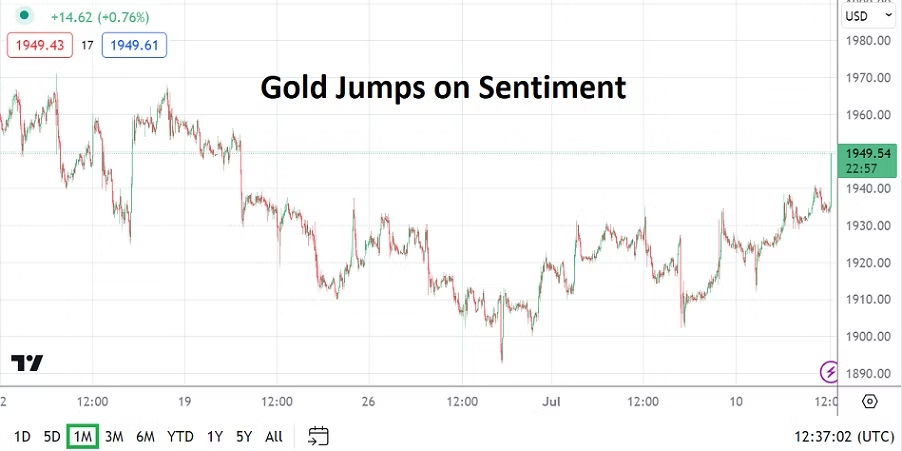
Gold One Month Chart as of 12th July 2023

The Federal Reserve could still raise its Federal Funds Rate at the end of July, though today’s CPI data outcome will create headwinds against that notion. There has been a wide voice given by folks who say the Fed shouldn’t raise rates again, and that real inflation will start to come down and that it is doing so now. The CPI has shown a decrease in U.S inflation – a larger drop than anticipated, which will certainly spur on USD weakness today. This confirms – momentarily – many analysts inflation outlooks who work in financial institutions not related to the U.S Federal Reserve and have been saying price pressures will recede. Yet, inflation is not dead yet and may still be heard. Stagflation is a genuine concern.

Tomorrow’s U.S Producer Price Index will be another opportunity to stir sentiment. Remember folks, outlooks are often adjusted according to facts. But what are facts? Can we really trust them. What are leading indicators, what is data that looks forward instead of backwards – numbers are often offered as evidence but randomness often rules interpretations of data. How do acceptable outlooks really develop when data management and outlooks can change within split seconds depending on the team looking over the quantified math. Humans are naturally optimistic, even when the data is negative, this can lead to bias.

We are in an age when trading software is doing a majority of the large volume transactions, and has been coded by algos processed by quant teams in financial institutions. Do retail traders even have a chance in this type of environment? Yes, retail traders can still manage to find opportunities, but they need to combine technical perceptions with fundamental knowledge of data, and combine the two into a behavioral sentiment outlook depending on their time horizons.

Market dynamics and situations change a lot in the broad markets. Assets move depending on the bias of incoming data. Preconceived notions being acted on and then changing according to need can be done in microseconds because of existing trading technology that financial institutions use. Larger players have an advantage and they are not about to give this up. Timeframes are also different for big trading houses compared to small speculators. It is also important to stress institutional traders could care less about day traders in Forex.
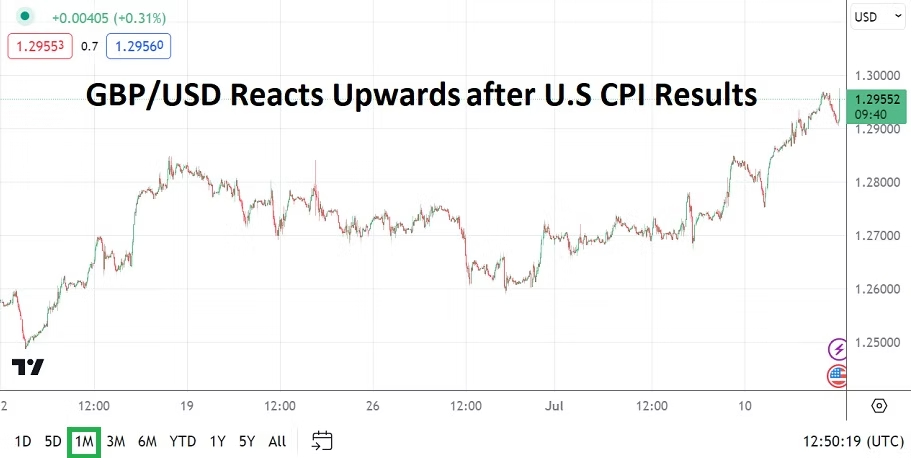
GBP/USD One Month Chart as of 12th July 2023

We have finished nearly a month of summer trading and seem to be confronted by a question of who do we trust? Do we trust the U.S Federal Reserve and its decisions and outlooks? In my opinion, you shouldn’t. But you should also remember the old adage, do not fight the Fed. The U.S central bank is bigger than you and I.

Central banks work together and often coordinate their combined outlooks, while shadows cast from the ‘oversight’ of political leaders rhetoric are frequently given consideration by the Fed, BoE, ECB and BoJ officials even if they claim they are not listening. Inflation is not welcomed by central banks, but because they are largely reactive and not proactive the Fed and others sometimes look uncaring and like fools, while the public sometimes suffer.

Thus we sit and wait for central bank pronouncements, but for the moment we seem to have a good grasp regarding what they will say. And perhaps – for the moment, maybe that is why Forex, gold and equities are trading rather politely. We seem to think we know what is going to be said moving forward for the next few weeks and remainder of the summer – more of the same warnings and interest rate correlations sprinkled in via central bank diatribes.
postN27.1

Risk Friday: Fear is a Terrible Thing to Waste

Risk Friday: Fear is a Terrible Thing to Waste

Behavioral sentiment in the broad markets took a turn for the worse yesterday among many major equity indices. This as financial institutions seemingly came to the short-term conclusion the Federal Reserve may actually have to raise interest rates again on the 26th of July, and possibly beyond. Meaning, the Fed might actually back up what it has been saying.

Yes, investors have been warned many times already by some analysts that the handwriting was on the wall regarding additional increases to the Federal Funds Rate, but it seems a fear of losing out has kept many market participants actively running forward with blinders on not cognizant of the Fed’s rhetoric.

Day traders should always be mindful of their emotions. While it is not good to trade based on emotions when involved in an active position, intuition and gut instinct sometimes can save you money when you decide to simply sit on the sidelines and watch the market action instead of participating. In other words, if you are nervous and your instinct is bothering you – do not attempt to enter the trade.

U.S Data Remains Rather Strong even as Inflation Boils

Yesterday’s better than expected jobs report via ADP helped create sparks early regarding U.S economic data continuing to show it is robust, but the ISM Services PMI threw gasoline onto the fire with a much better result of 53.9 compared to the estimated reading of only 51.3. While inflation simmers in the U.S, signs of limited growth abound too making stagflation a real danger.

Investors can now attain a yield around 4.995% on 2-year U.S government Treasuries. A gain of nearly 5% that is almost assured with very little costs regarding commission rates needing to be spent, looks like a solid short-term investment to many. Equity markets have a reason to feel spooked. If the U.S Fed raises the Federal Funds Rate which is now 5.25% to 5.50% at the end of July, and at the same time continues to speak in an aggressive manner about other potential hikes later this year, summer may lose its sense of tranquility for financial institutions.

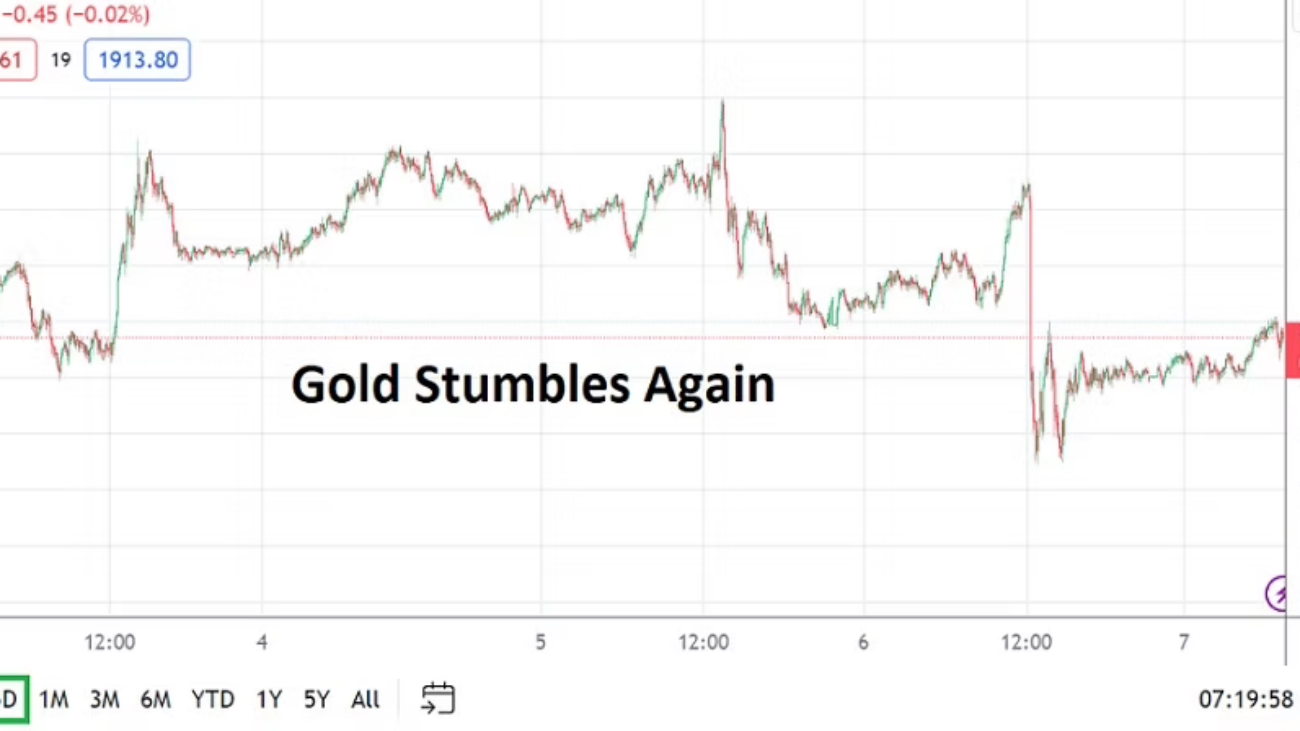
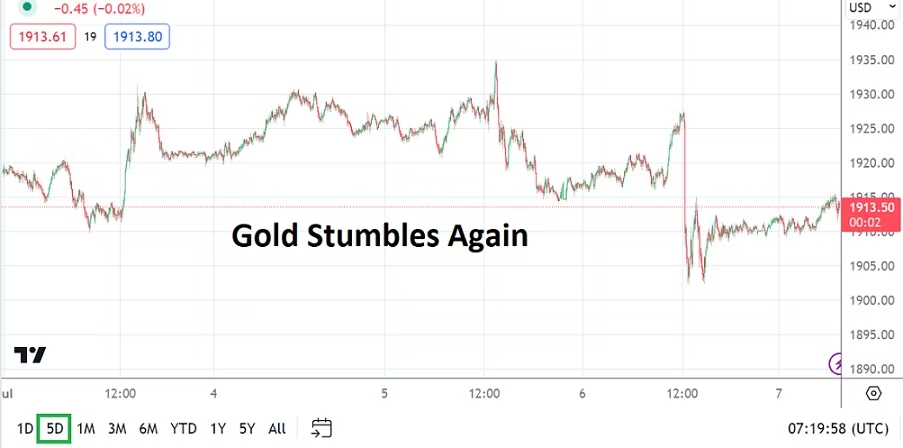
Gold Five Day Chart as of 7th July 2023

Gold which was trading at nearly 1925.00 USD yesterday, suddenly fell to around the 1900.00 briefly in the wake of the better U.S economic data, showing investors are worried the USD has some additional strength to display potentially. Again, the results of intraday gyrations may not mean a lot to mid and long-term investors, but day traders speculating on the outcome of quick hitting results frequently get hurt by the bursts of volatile storms.

U.S Official Jobs Numbers Today and Anticipation

Adding another dose of intrigue to the day are the upcoming official jobs numbers from the U.S, including the Non-Farm Employment Change and the Average Hourly Earnings reports. The inflation data via the earnings statistics are anticipated to show a gain of 0.3%, if for some reason it comes in stronger than expected this could create more fireworks. Having said that, the Wall Street Journal reported yesterday that Americans appear to have stopped quitting their jobs in order to switch to similar competitive positions as much as they had been the past couple of years. Perhaps this signals wages are starting to cool or least will in the near-term.

Let’s also remember that yesterday’s selloff in equities may have been anticipating better Non-Farm Employment Change results today based on the ADP outcome Thursday, and other solid U.S data before like last week’s GDP gains. Day traders betting on quick hitting CFDs via their brokerage platforms should be careful today and listen to news regarding the U.S bonds market. Inexperienced speculators should try to understand the adage – buy the rumor and sell the fact. Meaning ‘smart money’ often acts before others and takes advantage of their outlooks regarding data.

Quick Warning on Binance and Cryptocurrencies for Gamblers

BNB/USD Three Month Chart as of 7th July 202

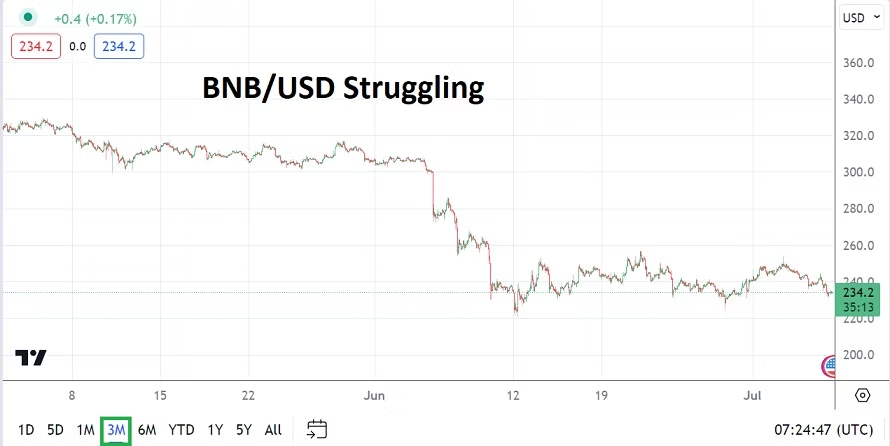
In a non-related subject, cryptocurrency traders seem to remain rather steady but should be nervous – if anyone is actually really trying to speculate in this endeavor besides Larry Fink of BlackRock currently, news regarding Binance remains troubling on the surface as legal clouds grow. Folks involved with the BNB coin should be careful. As one of the most ‘important’ crypto exchanges Binance’s legal problems moving forward could affect the prices of cryptocurrencies significantly. As of this writing BNB/USD is at nearly 233.00, and it should be noted Tether’s USDT appears to remain rather solid for the moment at 1.00. A look at the current three month chart of BNB/USD highlights its latest value struggles.

postN20.1

Friday Barometer Regarding the BoE Decision and Gold Prices

Friday Barometer Regarding the BoE Decision and Gold Prices

The Bank of England’s rate hike of 0.50% cements the notion that global central banks remain steadfastly locked on inflation, and understand politically the implications on the public regarding higher consumer prices which are being experienced. The Bank of England ‘met’ before its Official Bank Rate announcement with corporate bank executives it was whispered, to discuss their concerns regarding the knock on affects of higher mortgage rates to come. However, this did not stop the BoE from being aggressive.

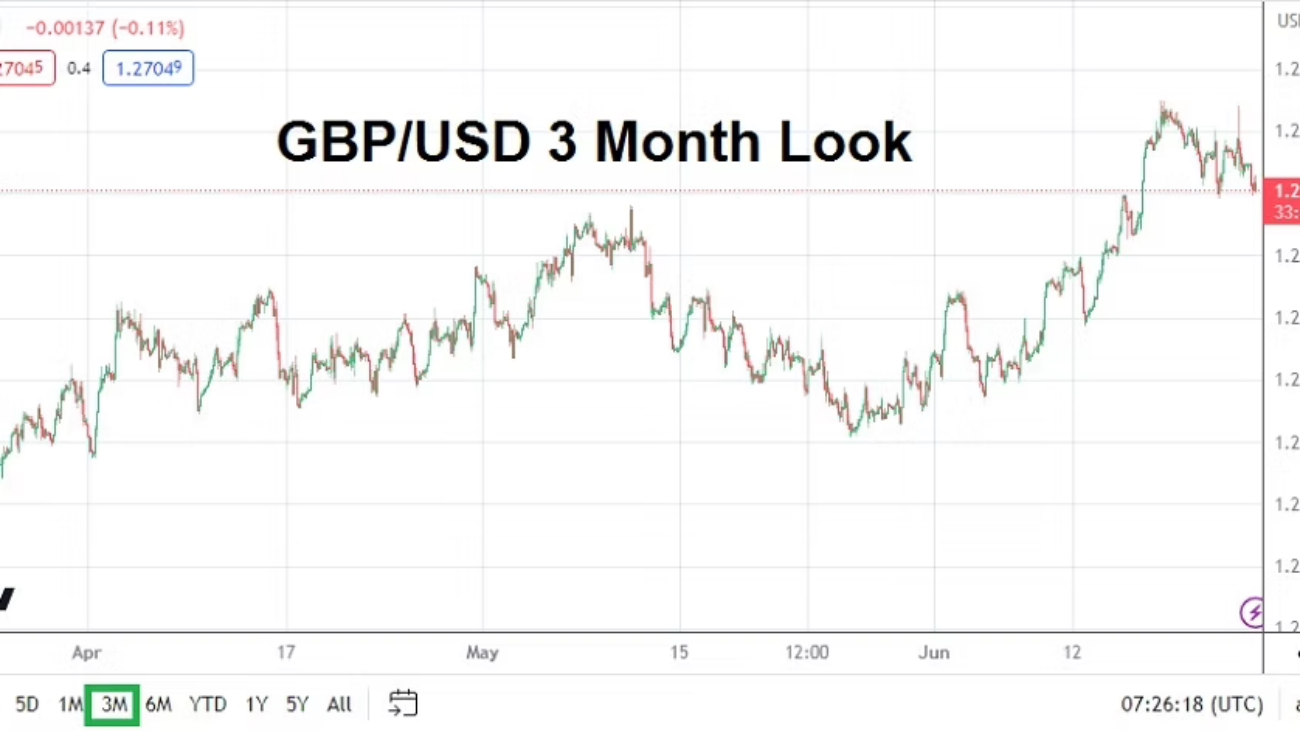
GBP/USD Three Month Chart as of 23rd June 2023

Is the BoE Move a Sign Regarding the Fed’s Next Decision?

The move by the BoE also is intriguing because the larger than expected hike puts into play the notion the U.S Fed may be raising the Federal Funds Rate in July. The reasoning is based on the idea the Bank of England wants to protect the British Pound from another interest rate hike from the Fed, thus ‘securing’ the value of GBP/USD Forex mechanics.

The U.S Federal Reserve, the BoE and ECB finally seem to have a grasp on import inflation implications. Although higher costs and dynamic pressures on exporting countries like China, India and others that face the gauntlet of these challenges remains critical, because these nations need to raise the costs of manufactured goods internationally when they sell.

Smart Money and the Value of Gold

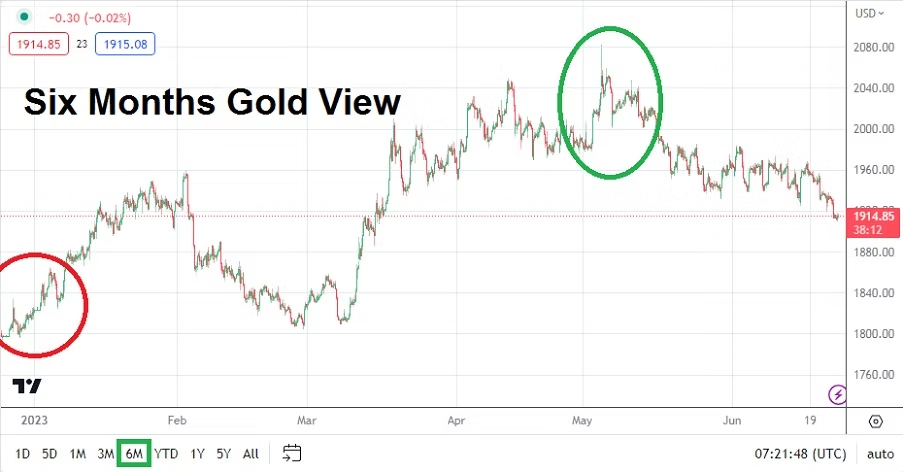
Let’s talk about ‘smart money’ for a moment surrounding Gold – and please try to hold down your laughter – but the price of the precious metal is interesting and should be monitored even by folks who do not trade the commodity. Gold as of this morning is near the 1915.00 USD ratio.

Gold Six Month Chart as of 23rd June 2022

On the 4th of May the price of the precious metal momentarily challenged the 2080.00 level. On the 1st of June the price of the commodity was near 1985.00. Do you see a trend here? Please note, Gold isn’t going to zero.

The point to be made is that the build up in the price of the precious metal from the 22nd of November 2022 when Gold was around the 1625.00 USD per ounce level, until early May anticipated the U.S Federal Reserve was going to become more dovish regarding their interest rate polkicy. For consideration look at the price of the USD during this time too, against many major currencies – the value of the USD also started to come down.

‘Smart money’ is showing signs of nervousness certainly since the start of June that more hikes are feared from the Federal Reserve. However, the price of Gold and the USD are not correlating well at this moment. This is a potential sign that Gold and the USD are both within speculative trading zones in which financial institutions are seeking ‘true’ equilibrium and are not comfortable. Fragility in the financial marketplace is likely to be seen until the Federal Reserve Federal Funds Rate announcement late in July. Expect financial institutions to price in their outlooks respectively depending on their outlooks.

Gold and U.S Treasuries: Inverted Interest Rate Implications

Gold definitely fluctuates within daily trading conditions, it is a speculative commodity, but it is also a solid barometer of risk management among the elite. If financial institutions are in favor of buying items like U.S bonds because of their guaranteed short term interest payments (look at the fact U.S Treasuries are mostly inverted – meaning shorter term bond interest rates are paying higher returns compared to longer term bonds) instead of buying Gold as an investment tool.

The Gold and USD Forex dynamics tells us that investment institutions are still very nervous about the Fed potentially raising interest rates a couple of more times this year. July and late this year appear to be reasonable bets. This Fed consideration and concern remains legitimate while looking forward as long as inflation remains elevated in the U.S. However, the Federal Reserve must also feel comfortable they will not kill mid and small sized banks, which by now should have shifted their business practices allowing for slightly higher interest rates to be delivered.

postN16.1

Week Ahead: Summer Begins with Questions Lurking for Traders

Week Ahead: Summer Begins with Questions Lurking for Traders

Monday, the 19th of June, China Foreign Direct Investment – data from China has been lackluster and last week’s announcement of a stimulus program from the government underscores economic concerns regarding growth.

Monday, the 19th of June, U.S banking holiday – for commemoration of Juneteenth.

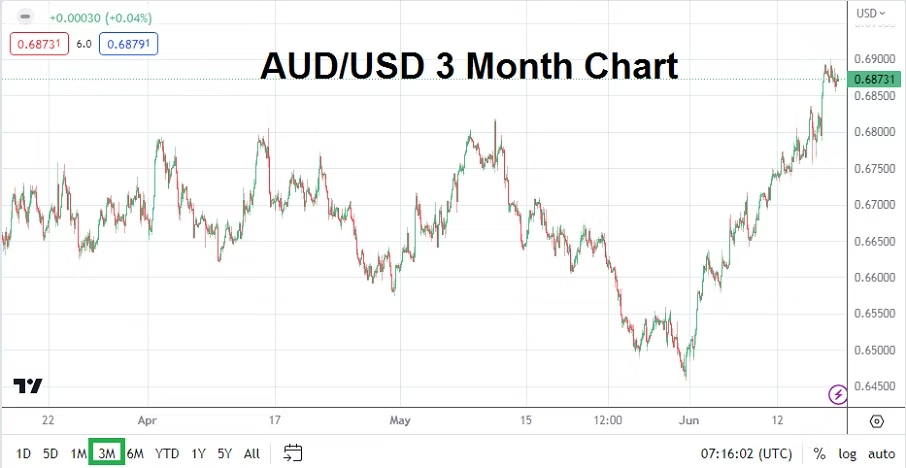
AUD/USD Three Month Chart as of 18th June 2023

Tuesday, the 20th of June, Australia Monetary Policy Meeting Minutes – report from the Reserve Bank of Australia will interest AUD traders and those with an interest in Asian Pacific economics.

Tuesday, the 20th of June, U.S FOMC member John Willliams – as the President of the New York Federal Reserve, Williams, is a key member regarding policy. Taking into consideration last week’s pause, traders may want to pay attention to the New York Fed Presidents’s remarks to see if the pause in Federal Funds Rates seen last week is looked upon as a halt or a ‘skip’ by Williams. The difference between a pause and a skip may appear to be semantics, but a skip would mean an interest rate hike is coming in July. Williams is not going to say what is going to happen at the next Federal Reserve meeting, but he may give a hint regarding his opinion on what should be done.

GBP/USD Three Month Chart as of 18th June 2023

Wednesday, the 21st of June, U.K Consumer Price Index – the data will be important regarding inflation insights for Britain. The Bank of England is expected to raise their Official Bank Rate on Thursday by 0.25%. Another report showing stubborn inflation could set the table for a rather hawkish Monetary Policy Statement from the BoE.

Wednesday, the 21st of June, U.S Federal Reserve Chairman Powell testimony – the Fed Chairman will begin two days of speaking and taking questions. The first day will be before the House of Representatives and the second day in front of the Senate. Because a major election is coming in the U.S in 2024, this will be an opportunity for politicians from both sides of the aisle to get airtime and take a ‘stance’ while bludgeoning Jerome Powell. The Fed Chairman’s remarks could stir the markets slightly, but Powell will be as careful as possible not to put a scare into the financial sector.

Thursday, the 22nd of June, U.K Bank of England – the Official Bank Rate, Monetary Policy Summary and vote count from the Monetary Policy Committee will be released. A hike has been widely expected by GBP traders and has been factored into the British Pound already.

Thursday, the 22nd of June, U.S Existing Home Sales – the housing report will cause a few murmurs in the marketplace because it is seen as an extension of consumer health and interest rate policy in the U.S regarding behavioral sentiment. Existing home sales numbers have been dropping as people with homes have decided to stay put in their current residences. ‘Locked in’ interest rates are more attractive, instead of taking on a higher rate via a new purchase due to costlier mortgages because of more expensive borrowing fees.

Friday, the 23rd of June, E.U Manufacturing and Services PMI – the flash reports from the likes of Germany, France and the U.K should be watched. Manufacturing readings have been producing recessionary readings while Services data is expected to show incremental decreases too.

Friday, the 23rd of June, U.S Manufacturing and Services PMI – the flash reports via the Purchasing Managers Index data need to be monitored too from the States. The readings give a rather good insight regarding outlook of U.S business sentiment.

postN14.1

Anticipated Federal Reserve Shop Talk to be Delivered Today

Anticipated Federal Reserve Shop Talk to be Delivered Today

For what it’s worth, here is my prediction regarding what the Federal Reserve will do today. The Federal Funds Rate will remain unchanged in my opinion. The FOMC Statement may show that the vote actually was debated and not unanimous. The statement is likely to warn that inflation remains stubborn and potentially problematic, meaning the Federal Reserve continues to believe it may have to raise the Federal Funds Rate over the mid-term and again before the end of 2023.

The Forex market has seen the USD get weaker against many major currencies since late May. While financial institutions have seemingly positioned for no increase from the Federal Reserve today, this move has also likely been priced into Forex. Day traders need to understand institutional traders will not be betting on what took place the last three weeks, but are trying to anticipate what will happen into early July and beyond regarding their Forex positions.

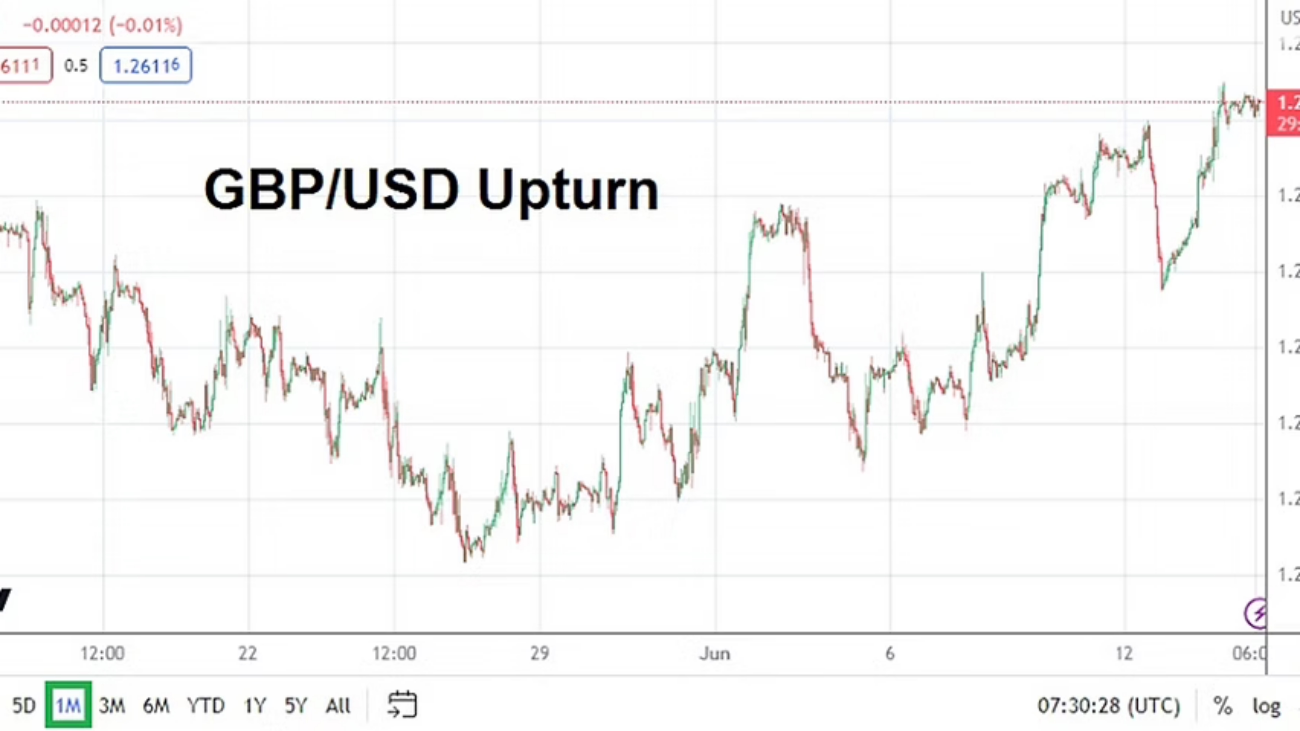
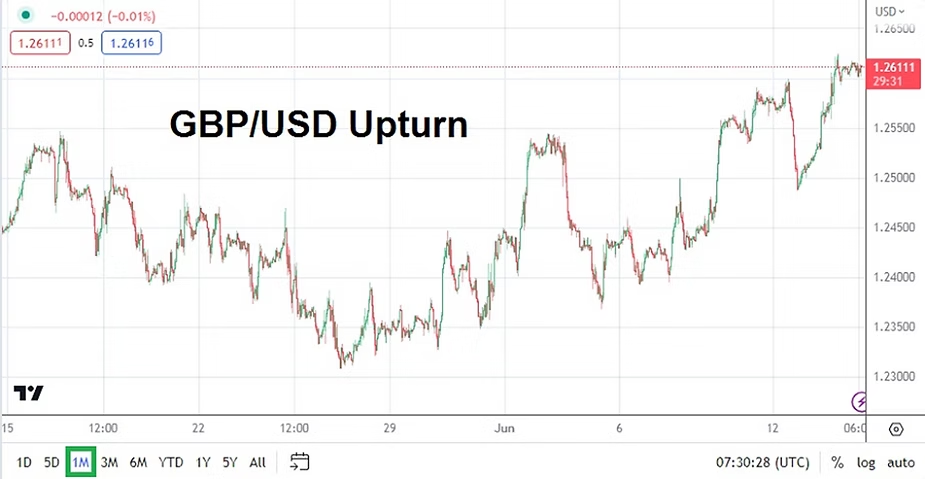
GBP/USD One Month Chart as of the 14th June 2023

Many financial institutions may still be betting the Fed will remain more dovish than the U.S central bank wants to admit, but this is a dangerous perception and could prove costly. Financial institutions are concerned about the Fed because they know the central bank has painted itself into a corner it may not be able to maneuver freely within. The battle to conquer inflation while trying to fuel economic growth is not an easy one. Mixed sentiment abounds regarding the U.S economy depending on who is asked.

Talk of a soft landing and a small recession continues to be heard, this while some analysts warn about a hard drop and darker days ahead. Folks, it is all about timelines and their interpretations, experts warning about brighter or darker days ahead have a tendency to be vague regarding exact moments in time. Everyone has an opinion, and people often have more than one.

In my opinion – my one opinion, the Fed is likely to say that it is not going to raise rates today, but may have to do so in the mid-term. If these were normal times and economic conditions were not suffering from huge spending running amok in Washington and the corporate banking sector wasn’t fragile, the Fed may actually have raised the Federal Funds Rate today to continue to battle inflation deliberately. However, a pause for the moment seems like the logical choice, this while ‘hoping’ inflation continues to diminish. And hope is a key word here. Everyone seems to be hoping. The question financial houses and traders need to decide after the FOMC Statement takes place today is how seriously do they consider the Fed’s remarks.

If they believe the Fed will have to continue to remain neutral regarding its mid and long-term interest rate policy, the USD may soften and incremental selling might be demonstrated. Human instinct tends to be optimistic, which means financial institutions and maybe even the Fed wants to believe inflation will ebb lower. If this happens the USD would weaken further. However, the Fed may have to sound more aggressive than people want, but that would damper the mood of financial institutions – so look for optimistic interpretations to abound with rose colored glasses, even if they are wrong in the long-term.

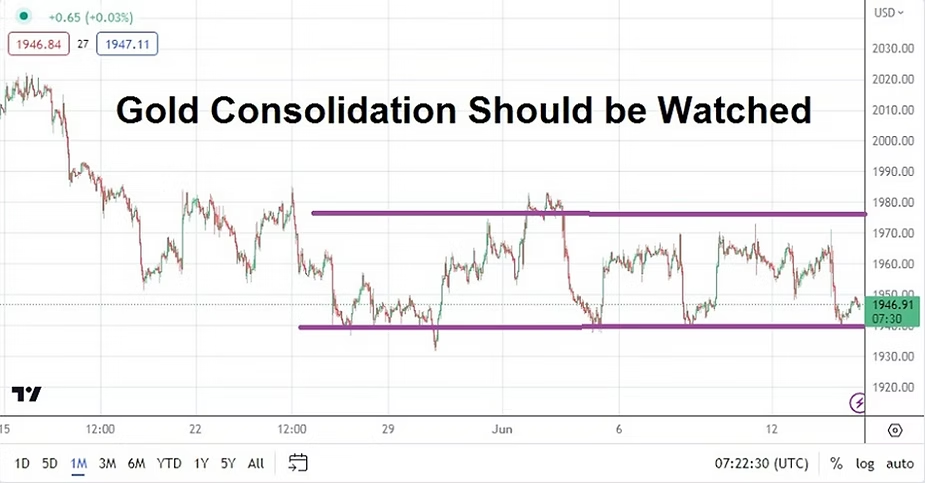
Gold One Month Chart as of the 14th June 2023

For evidence of outside barometers, traders may want to look at Gold which has essentially traded between 1940.00 and 1975.00 with a few outliers since the last week in May. The price of Gold has seemingly situated within a consolidated framework the past few weeks. The precious metal may produce a strong move if the Fed shows more dovish behavior today, particularly if financial institutions show more optimism via behavioral sentiment in Forex – meaning if a weaker USD trend continues momentarily Gold could traverse higher.

My prediction and $1.00 USD may get you on a bus. As always caution will be needed if you are trading immediately before and after the U.S Federal Reserve’s rate decision. I advise using a seat belt today consisting of entry price, stop loss and take profit orders via solid risk management, but then again these cautious attitudes should always be practiced by day traders.

post38

FOMC Meeting Minutes and Key Growth Data Coming this Week

FOMC Meeting Minutes and Key Growth Data Coming this Week

Monday the 22nd of May, Japan Core Machinery Orders – which will likely have very little impact on the markets – not even the USD/JPY should react too much. Although it should be noted last month’s figure was negative and this month’s result is expecting a better outcome.

Monday the 22nd of May, E.U Consumer Confidence – forecast to produce a negative number, but this statistic doesn’t usually get much of a response in the financial markets unless there is a shocking result.

Tuesday the 23rd of May, E.U French and German Manufacturing and Services PMI, along with the broad E.U results – the manufacturing statistics from France and Germany are expected to come in slightly better than last month’s results but remain in negative territory.

Tuesday the 23rd of May, U.K Manufacturing and Services PMI – traders will watch these results after the bad GDP numbers from Britain almost two weeks ago.

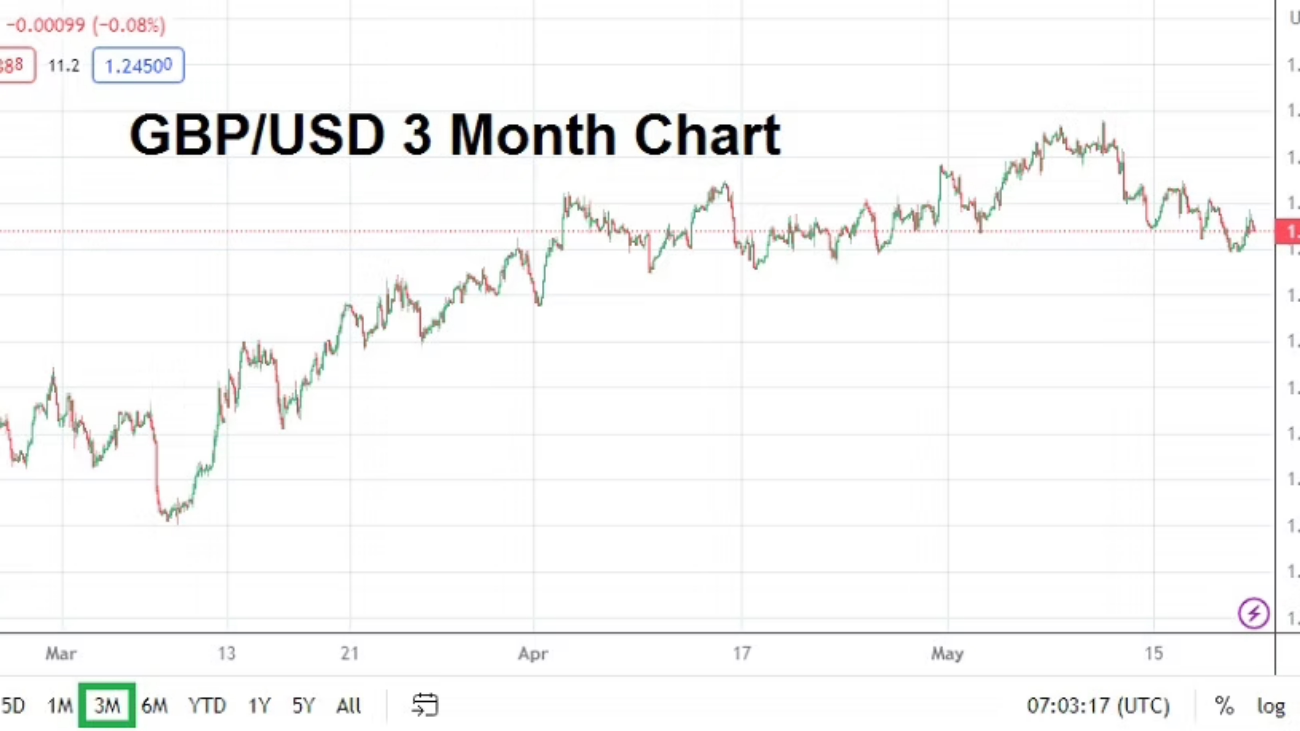
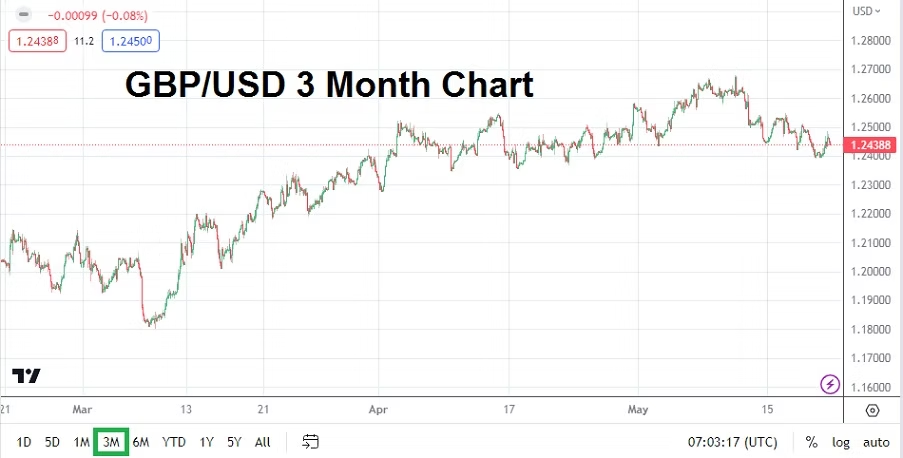
GBP/USD Three Month Chart as of 21st of May 2023

Tuesday the 23rd of May, U.S Flash Manufacturing and Services PMI – the reports could prove of interest and cause a bit of a tremor in the market, but unless there is a big surprise investors will remain cautious as they anticipate the next day’s potentially big risk events.

Wednesday the 24th of May, U.K Bank of England Governor Bailey – will be speaking at two events and could stir the GBP/USD with his comments on the British economy and inflation.

Wednesday the 24th of May, U.S Treasury Secretary Janet Yellen – will be speaking at a Wall Street Journal event, where she will be listened to for any comments on the ‘U.S debt ceiling” crisis. Yellen is a ‘trained’ speaker and she will try not to scare financial institutions who will have some leaders in attendance.

Wednesday the 24th of May, U.S FOMC Meeting Minutes – the report which will outline the U.S Federal Reserve’s thinking regarding its recent interest rate hike and what it might be considering regarding June could impact the marketplace. The report is published late in the day, but financial institutions will certainly wait for the publication and react. While the FOMC paper is sometimes considered ‘noise’, this report will be important because of the nervous sentiment which exists in markets like Forex and equity indices as they deal with a lack of clarity.

Thursday the 25th of May, U.S Preliminary Gross Domestic Product – the growth (or lack of growth) numbers from the States will be watched intently. A muted projected gain of 1.1% is anticipated by some analysts.

Thursday the 25th of May, U.S Preliminary GDP Price Index – this report will deliver insights regarding inflation in the U.S and should be given some attention by traders.

Friday the 26th of May, Core PCE Price Index – the inflation numbers should be watched. Any surprise above the anticipated 0.3% forecast could cause an affect in the financial markets.