WTI CrudeOila 20260902

Bad Timing for President Trump May Equal Good Trading Opportunities

You Don't Have to be a Buyer in the Current Marketplace in Order to Profit

There are moments when the markets are calm and then there are these times. It is beginning to look like increasingly bad timing for President Trump and his administration’s hope to keep WTI Crude Oil prices in check and silence the chatter about inflation. 

Instead of a de-escalation based on tranquil conditions in the Middle East, investors were smacked in the face again last night. However, while this may be a bad time to be an investor unless they are looking for value plays, traders may actually have more opportunities in the current market circumstances as long as they manage their risks appropriately.

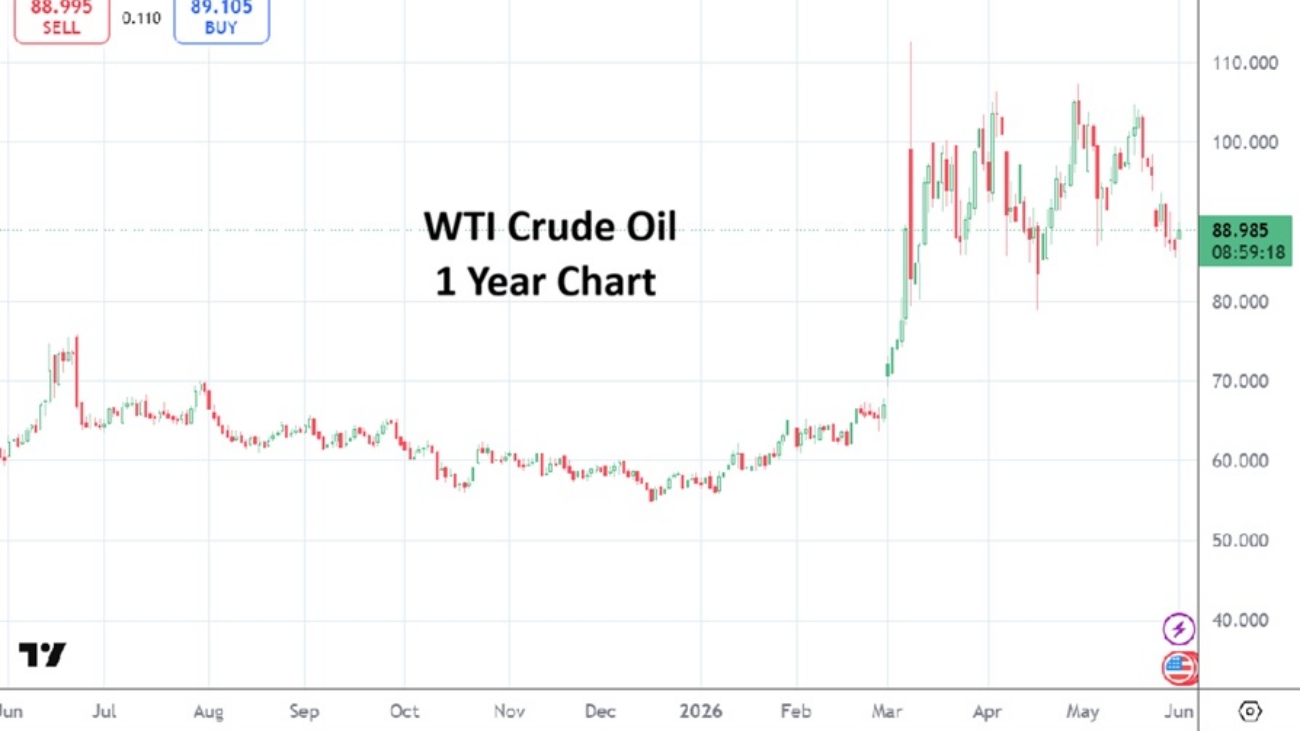
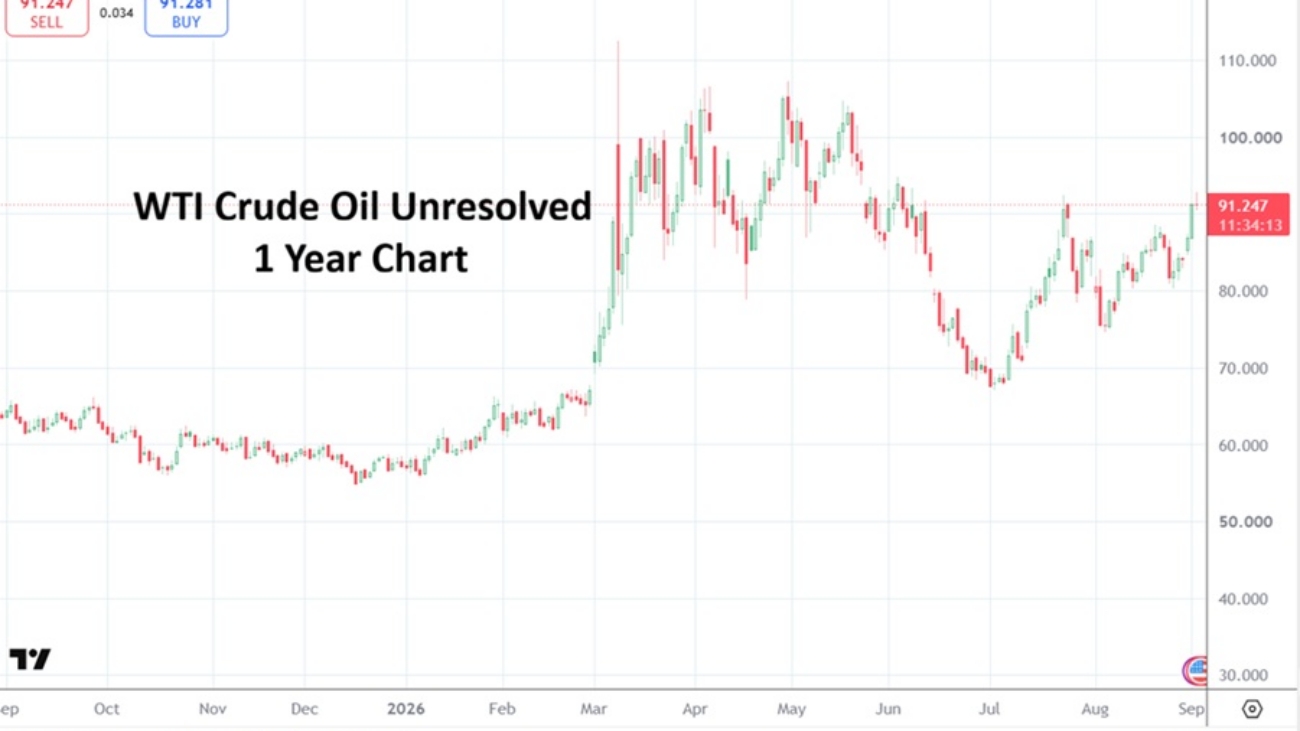
WTI Crude Oil jumped higher last night and while the commodity has outdone itself since late February regarding price velocity, last night’s performance likely felt volatile even for experienced large players who have solid intel on the ground regarding Middle East shipping and supplies. The energy sector has been more akin to the soft commodities regarding reversals the past handful of months, Coffee, Cocoa and Crude Oil have offered colorful price ranges. But that is not how WTI Crude Oil is supposed to work.
WTI Crude Oil 1 Year Chart as of 2 September 2026

Inflation concerns will not go away quietly as long as WTI Crude Oil remains highly valued. Fed Chairman Kevin Warsh may in fact be putting on a show for the public – that he is his own man and can express his concerns regarding inflation no matter what President Trump thinks – when in fact he may simply be laying a framework to work in tandem with Treasury Secretary Scott Bessent and lower interest rates in order to create less pressure on Treasury yields. However, this planned (or conspiratorial) thinking may be hard to actually produce in reality on the 16th of September when the Fed’s FOMC has to show its cards once again. As long as WTI Crude Oil remains above $90.00, “Houston we have a problem,” murmurs may be heard loud and clear.

If Treasury yields remain tilted upwards because investors are refusing to buy them at cheaper rates, it will start to infect the Nasdaq 100, S&P 500 and the Dow 30 more and create cautionary skirmishes which may produce deeper downsides in stock markets.

Iran wouldn’t want to cause President Trump problems, correct? Why would Iran want higher Crude Oil prices to ensnarl President Trump into a morass of political battles in the U.S and make life difficult for the Republicans during the mid-term elections? Does the IRGC have folks who understand the dynamics of U.S politics? Yes they do and it is a 100% certainty they would like to be a pain in President’s Trump’s aspirations.

We are left to deal with the ever-changing events that seem to be quite good at repeating themselves. Financial institutions are not only nervous about their mid-term outlooks, they are wary about the near-term too. Forex, commodities, bond yields, Wall Street and other global stock markets will struggle to make solid gains until clarity develops.

What will clarity look like? It will be optimistic banter in which rhetoric from different mouths and geographies is actually believed by the adoring crowds. Results do not have to be good, but outcomes need to be able to be forecasted and planned, allowing investors to seek their cash preservation and fortunes in a variety of assets (and show their overseers that they used adequate risk management in case things go wrong). 

Gold has done well recently, although it seems to have hit some resistance lately. However, if inflation tranquility is not achieved and if President Trump’s circumstances grow more dire, the precious metal will continue to offer speculative plays upwards. 

Investors are restless. Making 6 to 8% profits a year looks rather boring after plenty of solid years of upwards traction. Folks aren’t used to powerful financial storms and they forget about lingering troubled periods in which simple profits can prove comforting as broad markets struggle. 

Day trading is dangerous. However, those with solid risk taking tactics and those who aren’t married to the notion that markets only go up, but are willing to bet that markets (assets of many classes) can go lower too – now have an opportunity to test their technical perspectives and understanding of behavioral sentiment. 

Realistic targets using take profits and making sure stop loss protection still allows for a trade to move until goals are met is important when volatility is ripping price realms to shreds. Forex instability appears to be increasing as USD centric attitudes remain convoluted. Does Fed Chair Kevin Warsh have enough power to fight against an interest rate hike on the 16th of September, will the price of WTI Crude Oil cooperate, will President Trump’s wishful thinking about Iran come true? Results may not match what is wanted by the guardians of the marketplace. Contrarians may see the current market and global political situation as a time to seek value and help inflate markets, but they might be spitting into the wind. 

Maybe the AI concerns about infrastructure costs and corporate cash needs are baseless. Perhaps the deficit being created by the U.S and many other nations is simply idle chatter by risk analysts who are too nervous. Maybe there is a secret pill for all of us to become optimistic about all things.

It is a good time for traders to remain realistic and target exaggerated price movements in assets that offer opportunities in distressed offerings. You do not have to buy the marketplace to profit ladies and gentlemen.
Copy and paste the text from AMT that you want to share

Share:
30Y Treausry Yields 20260826

How Warsh Can Solve the US Debt Crisis With Just a Few Words at Jackson Hole!

A Roadmap for Fed Chairman Kevin Warsh to Rescue U.S Debt

Many think the market decides interest rates.

Wrong!

The Fed – and only the Fed – has full control over interest rates, all over the curve!

We just need to have the right person on board.

During the European crisis in 2011, speculators all around the world were betting that the Eurozone would explode and that the EUR would collapse under the weight of government debt that had started with Greece and spread to other countries that were shamelessly labelled “PIGS,” adding insult to the speculative attack.

Trichet, at that time chair of the ECB, seemed totally clueless, afraid to take any “unconventional” step, even at the risk of seeing the entire European financial system go bust.

The crisis seemed unstoppable… until Mario Draghi stepped in, replacing Trichet.

With just one magical statement (“the ECB will do whatever it takes to save the Euro. And believe me, it will be enough”) Draghi implied that he was ready to buy government bonds from European countries, even though such action was considered at the time to be “against the ECB’s statutes” and outside its mandate.

By going against the prevailing market narrative, and knowing very well the economic strength of the Eurozone, Draghi forced the market to follow him.

The speculation against the Eurozone stopped almost instantly, and European government bond prices recovered without the ECB even being forced to intervene!

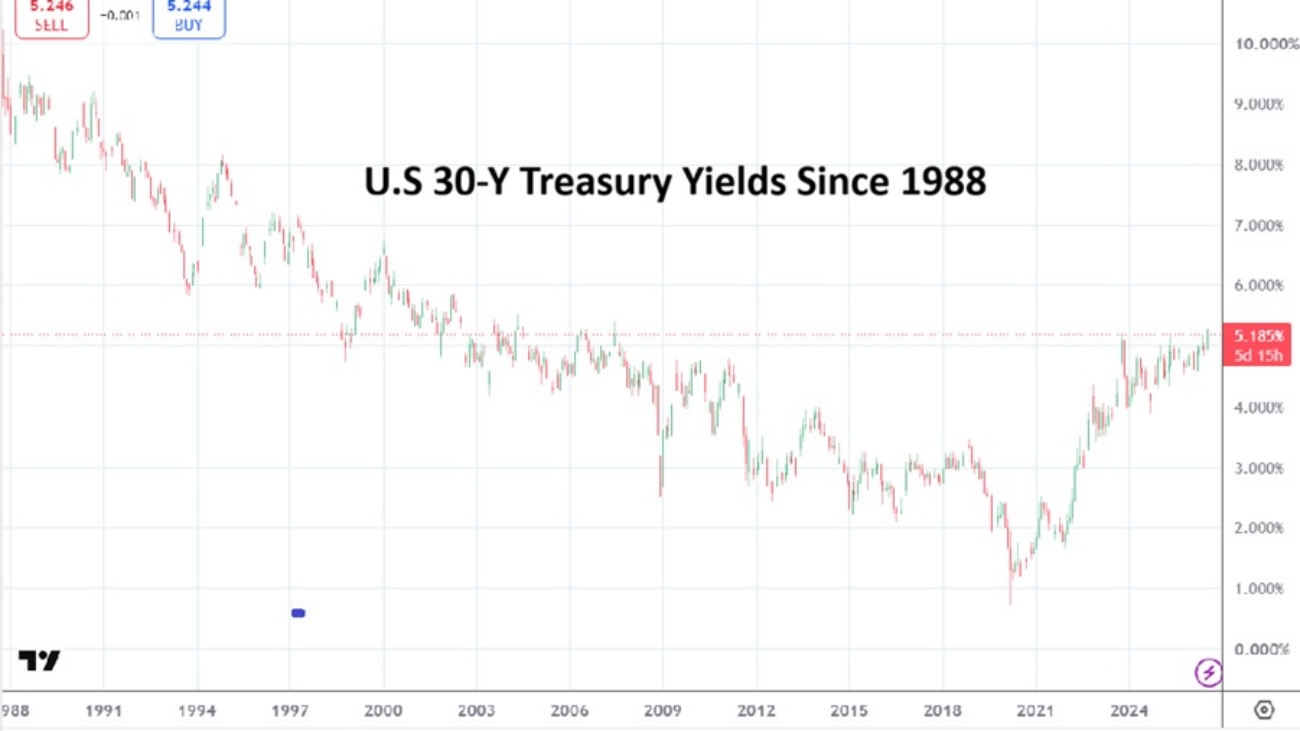
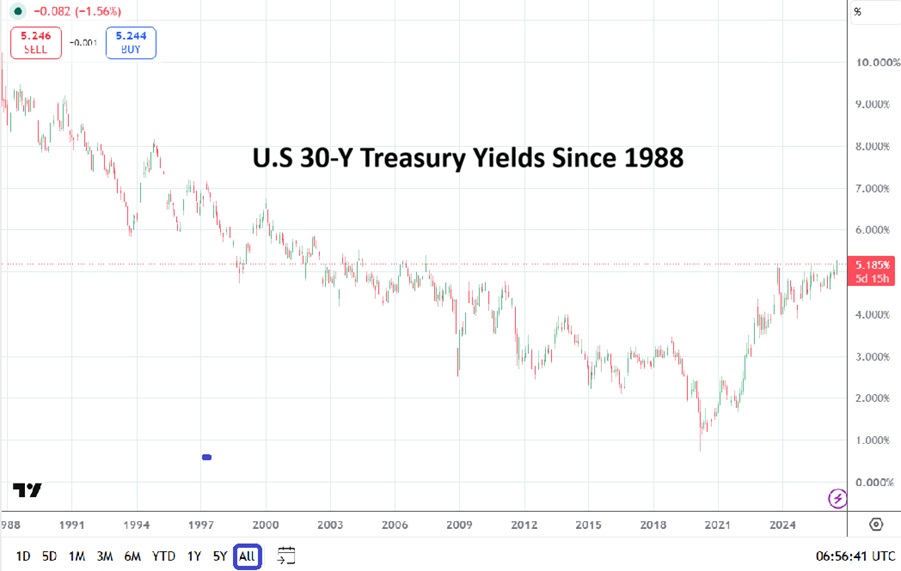
U.S 30-Year Treasury Yields Chart From 1988 until 26 August 2026

Today, the U.S is in exactly the same position!

A massive speculative attack is being waged against U.S debt (probably led in part by the crypto industry in an attempt to justify the “value” of its virtual tokens), with “inflation” suddenly becoming the ultimate beast.

Like Trichet at the time, the weak Powell got driven into the trap of raising rates abruptly on his own government, forcing it to pay more than $1 trillion in yearly interest, a massive and unnecessary injection of liquidity that is itself… inflationary!

In today’s world, driven by massive debt, raising interest rates on governments is INFLATIONARY!

Now that Powell is almost gone, all hopes lie on Warsh’s shoulders.

He can save the U.S from the current debt crisis with just a few words, exactly as Draghi did for Europe.

Warsh completely missed his first intervention a month ago. Instead of showing the market who’s boss, he showed total febrility.

Fearing being labelled a “Trump puppet,” he insisted on the 2% inflation target – an absurd threshold that nobody really knows where it came from – and claimed that “the economy is robust”… while we all know it is not!

Then he totally capitulated to the market by saying that he would “listen to the market” to determine where rates should go. The worst thing any Governor could ever say!

That’s how long-term yields exploded to levels not seen since 2007, and forcing Bessent to intervene to limit the damage.

We are now just one day away from the Jackson Hole Symposium.

Warsh can now either save the U.S or send it into Armageddon!

Every word he says could change the entire picture.

He simply has to focus on the right narrative:

  • Current inflation is geopolitical and driven by supply shocks. Raising interest rates has zero impact on such inflation.
  • The 2% inflation target is NOT an absolute figure. A 3% inflation rate should be acceptable when the economy is at risk.
  • Signs of recession are looming, with the labor market under pressure, rising bankruptcies, and record rates of defaults on credit cards and car loans.
  • Forcing the government to inject more than $1 trillion through interest payments is itself inflationary. Raising interest rates to fight inflation is counterproductive at such a high level of government debt.

If Warsh is capable of highlighting these arguments, yields will drop instantly without any intervention from Bessent.

Then the Fed can start decreasing interest rates gradually, with the market accepting whatever rate it sets.

What if Warsh deliberately gave a disastrous speech a month ago, taking a tough position against what Trump appointed him to do and allowing the market to drive rates to extreme levels… only to radically change his position following the recommendations of the task force he appointed?

This way, he would have absolved himself from being labelled Trump’s puppet while executing exactly the plan of reducing interest rates.

We can therefore suspect that he will take the opportunity at Jackson Hole to present the first findings of this task force, which could include, among other things:

  • A questioning of the 2% inflation threshold, especially when the economy is at risk of entering a deep recession.
  • Stressing that inflation comes mainly from geopolitical issues and supply shock. Fighting such inflation with high interest rates is totally inefficient.
  • A highlight of the absurdity of raising interest rates on the U.S government and forcing it to inject $1 trillion in interest payments – an unnecessary injection of liquidity that is itself inflationary.
  • The necessity of coordinating with the Treasury Department to fight inflation where it hurts the most, through subsidies, tax relief, and other targeted measures, while primarily fighting “greedflation” through higher profit taxes on specific industries.
  • A warning about the increasing risk of recession, with record numbers of corporate bankruptcies, credit-card defaults, and a deteriorating job market.

Warsh has a unique chance to prove that he is the right person for the job by rescuing the U.S from the massive speculation against its debt, exactly like “Super Mario” did when he saved Europe from collapse in 2012.

Copy and paste the text from AMT that you want to share

Share:
AMT Top 10

AMT Top Ten Miscellaneous Interjections on the 3rd of August

Narrative Storms, Complaints and Observations

10. Mo’ Money: The Los Angeles Dodgers surprised nobody when they acquired Detroit Tiger’s pitcher Tarik Skubol in an effort to solidify their chances of a World Series three-peat. Don’t blame the LA Dodgers for playing by the rules, even if many don’t like the results. Expect a MLB strike in the coming year when owners try to change the salary structure in baseball.

9. Staggered: SpaceX is below $110.00 as trading gets set to begin today. Financial institutions are likely bracing for the open window that begins the 6th of August via a large amount of unblocked initial equity from pre-IPO shareholding that will soon be given freedom to sell. 

AMT Top 10 Miscellaneous Interjections on the 3rd of August 2026

8. Fidel Castro: Mayor Mamdani and a gang of other U.S utopian (and sometimes bigoted) politicians continue to make headway. Authoritarian failures like Venezuela and Cuba are prime examples of the paradise offered to U.S voters who lean left for the coming mid-term elections.

7. Takeover: Citadel’s takeover of Situational Awareness – which seems to have proven it had none – this past week in the wake of multi-billion dollars of losses has put Leopold Aschenbrenner’s smirk on hold for the moment. Have no fear fans, Aschenbrenner is likely to land on his feet and extol his methods once again to those who love leveraged speculative ventures while embracing unproven hedge fund saints.

6. Fragile: The VIX Index appears asleep as it remains a hair under 16 as it measures the volatility of  the S&P 500 Index’s options. 10-Year U.S Treasury yields are around 4.68% and within sight of apex highs. The Nasdaq 100 futures are higher as of this writing as the cash market and a full week of trading awaits, having finished Friday’s session at 28,274. 

5. Anthony Fauci: Takes the Fifth and now hopes his pardon covers contempt.

4. Bitcoin: BTC/USD is near $62,850 in the wake of confirmed cold storage hacks via a generated random prediction onslaught using AI against Coldcard hardware. In other bad news Strategy’s MSTR value is around $93.35. And, yes, Michael Saylor has reportedly whispered he is thinking about buying more BTC soon. The ship appears to be sinking folks.

3. $80.00: WTI Crude Oil has shown price velocity lower today again, this after another flip-flop in behavioral sentiment was sparked by the announcement this weekend of a ‘rough framework’ agreed upon by Iran and the U.S. The Strait of Hormuz is seemingly quiet for the moment. At this point WTI Crude Oil price reversals are beginning to look like a well practiced dance routine. What will the next steps look like?

2. Forex Freakout: USD/JPY traders are listening to a myriad of narratives regarding the BoJ’s intervention. All experienced large players in the USD/JPY had to know an intervention was coming. While folks are pointing to the N.Y Fed and U.S Treasury selling of positions to bolster the JPY last week, they apparently need to be reminded the Treasury had the N.Y Fed start preparing the groundwork for such maneuvers earlier this year with steps including the ability to check on and counter USD/JPY Forex rates in January. 

While folks are accusing the Fed/Treasury of hurting the USD, they should note the move is to counter weaker JPY which Treasury Secretary Scott Bessent likely had been pressed by ‘higher ups’ to manage in order to make sure Japanese products didn’t become too cheap in the States. There had been at least two other interventions in the past handful of months from the BoJ, as of this writing the USD/JPY is near 156.600.

1. Unilateral: President Trump’s decision making has become bewildering entertainment as he practices a comedic like opera trying to convince people about his opinions which he seems to change relentlessly. President Trump should learn the Art of Sparse Talking. Will the Republicans harness the President after the mid-term elections?

Copy and paste the text from AMT that you want to share

Share:
10Y US Treasury Yield 20260716

Why the U.S Fed Should Lower Interest Rates Closer to 2%

Fighting Inflation with Higher Interest Rates is Totally Counterproductive

For nearly a century, central banks have relied on one dominant prescription to fight inflation: raise interest rates. The theory is straightforward. Higher borrowing costs discourage spending and investment, reducing demand and eventually slowing price increases.

While this approach may have worked reasonably well in the past, today’s economy is fundamentally different. Applying the same monetary formula developed in the past century by Irving Fisher is obviously creating more problems than it solves. In many cases, raising interest rates has become a counterproductive way to fight inflation.

  • The first and most obvious consequence is the impact on government finances. As interest rates rise, the U.S. Treasury must refinance its enormous public debt at increasingly expensive rates. The result is an explosion in annual interest payments, which now exceed $1 trillion. Those payments are in fact a direct injection of additional liquidity into the economy while simultaneously widening the federal deficit.

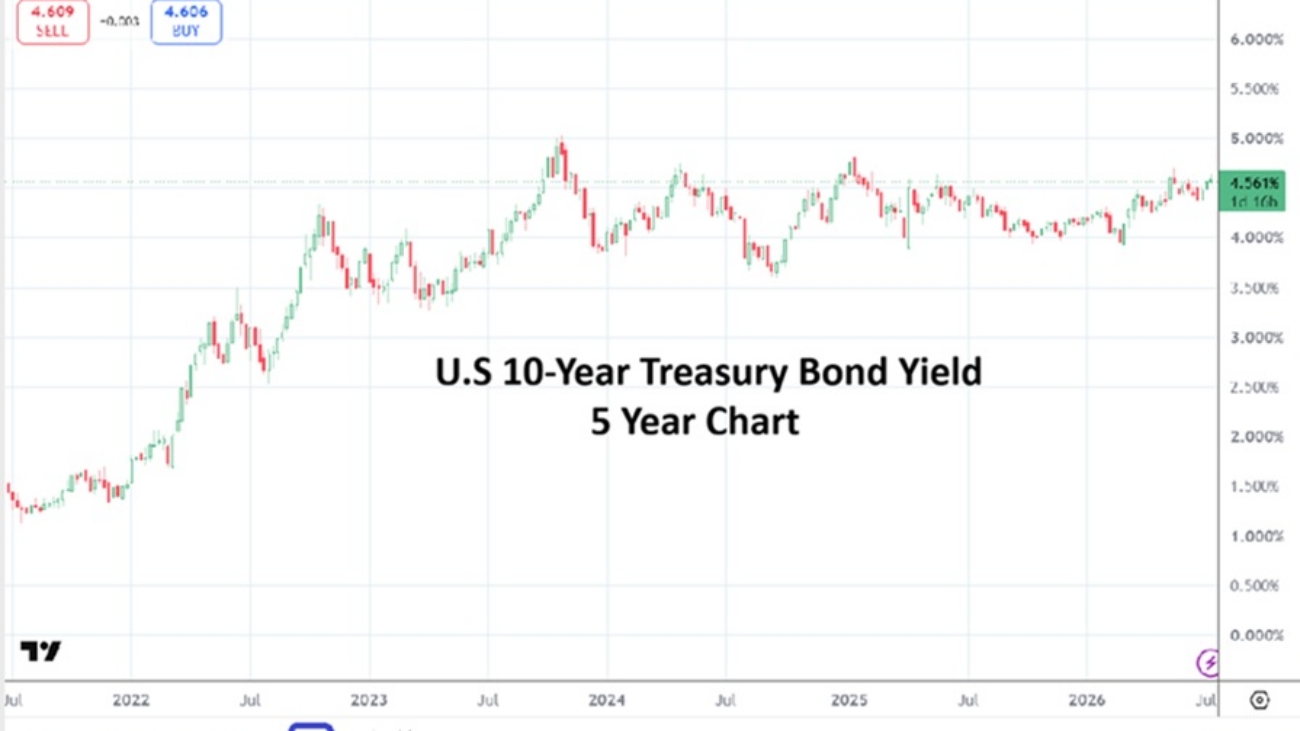
U.S 10-Y Treasury Yields Five Year Chart as of 16th of July 2026

Ironically, a policy designed to reduce inflation is contributing to larger government spending through higher debt-servicing costs. Instead of easing inflationary pressures, excessively high interest rates may actually reinforce them through this fiscal channel.

  • Consumers also bear a heavy burden. Modern households depend far more on credit than previous generations. Credit cards, auto loans, and consumer financing have become an integral part of everyday life. When the Federal Reserve raises interest rates, millions of Americans see the interest on their credit card balances climb to 20% or more.

Many families attribute their declining purchasing power entirely to inflation, when in reality a significant portion of the financial pressure comes from soaring interest payments.

  • Businesses suffer as well. Higher interest rates increase the cost of financing, while the same capital could be dedicated to investment, expansion, innovation, and research. Every additional dollar spent on interest is a dollar that cannot be invested in productive activity.

A recent example is SpaceX, which issued debt carrying a yield of approximately 6.65%. Given the company’s negative cash flow, investors naturally require a risk premium. However, if the Federal Reserve’s policy rate were closer to 2% rather than current levels, the company’s borrowing costs would be at least half their current level. The extra interest payments would instead be directed toward research, development, hiring, that would strengthen long-term economic growth.

In the current race for AI, that requires heavy investments, the Fed should lower the financing burden on U.S companies. Every additional percentage point of interest represents billions of dollars transferred from productive investment to debt servicing. Money that could finance AI chips, data centers, engineers, research laboratories or new factories instead goes to creditors.

The U.S cannot simultaneously declare China its principal strategic competitor while maintaining a monetary policy that systematically makes capital more expensive for American businesses than for their Chinese rivals, that benefit from much lower rates. The Fed may intend to fight inflation, but it is also making it more costly for American companies to invest in the industries that will determine economic leadership over the decade. The Fed may believe it is fighting inflation, but it is simultaneously increasing the cost of winning the AI race.

Perhaps the greatest weakness of relying on high interest rates is that much of today’s inflation originates from supply-side shocks that monetary policy simply cannot fix.

How does raising interest rates reduce the price of oil when energy prices are driven by geopolitical tensions such as the war with Iran?

How does raising interest rates lower egg prices when shortages stem from productivity issues in the poultry industry?

How does raising interest rates lower the prices of wheat, corn, or cocoa when inflation is due to droughts, floods, or other climate-related events?

How does it reduce insurance premiums that are rising because natural disasters have become more frequent and more costly?

In each of these cases, higher interest rates are totally inefficient to address the underlying cause of inflation. Instead, they merely increase financing costs across the economy while leaving supply constraints largely unchanged.

A more effective strategy would be to fight inflation where it actually originates. Governments possess fiscal tools that can be deployed with much greater precision than broad monetary tightening. Temporary subsidies, targeted tax relief, incentives for increased production, strategic investment in critical industries, and, in exceptional circumstances, carefully designed price controls can address specific inflationary pressures without unnecessarily slowing the entire economy.

For example, if geopolitical tensions cause oil prices to spike, temporarily subsidizing fuel or reducing fuel taxes is likely to be a far more direct and effective response than raising interest rates across the entire economy. Similarly, boosting domestic agricultural production is a better solution to food inflation than making mortgages, business loans, and credit cards more expensive.

The Fed should therefore focus on reducing the financing burden on both the federal government and the private sector. Maintaining interest rates closer to 2% would significantly lower debt-servicing costs, support productive investment, and allow fiscal authorities to intervene more effectively with targeted measures when inflation arises from specific sectors.

The doctrine of fighting inflation through higher interest rates was developed by Irving Fisher nearly a century ago, in an era with very different financial institutions, consumer behavior, and sources of inflation. Credit cards did not exist. Household debt was far lower. Global supply chains, geopolitical energy shocks, and climate-related disruptions were not defining features of inflation.

The modern economy requires modern solutions. Rather than relying almost exclusively on higher interest rates, policymakers should recognize that today’s inflation often demands targeted fiscal responses. Persisting with an outdated monetary framework risks imposing unnecessary costs on governments, businesses, and households while failing to address the real drivers of rising prices.

Supporters of high interest rates often argue that they are unavoidable whenever inflation rises. Yet international experience suggests otherwise.

Switzerland has repeatedly maintained policy interest rates close to 1%, or even below zero in previous years, despite being exposed to many of the same global shocks affecting other economies. Switzerland imports energy, is affected by fluctuations in oil prices, and faces the same geopolitical uncertainties. Yet the Swiss National Bank has generally preferred to tolerate modest inflation rather than impose unnecessarily high financing costs on households, businesses, and the government.

This illustrates an important principle: not every inflation shock requires an aggressive monetary response. When inflation is primarily imported through energy prices or supply-chain disruptions, forcing the entire economy to pay dramatically higher borrowing costs creates more economic damage than the inflation itself.

Copy and paste the text from AMT that you want to share

WTI Crude Oil 20260701

What Am I Missing About USD Centric Strength?

Being Wrong About USD Direction and Betting Against the Trend

Help me out here folks, I am perplexed. I seem to be missing something about the USD centric strength, it looks very overbought to me. Where is all the buying sentiment coming from? The FOMC meeting outcome on the 17th of June has certainly sparked USD centric buying stamina as financial institutions seem to have fallen into a strict line and priced in a Federal Reserve interest rate hike this year.

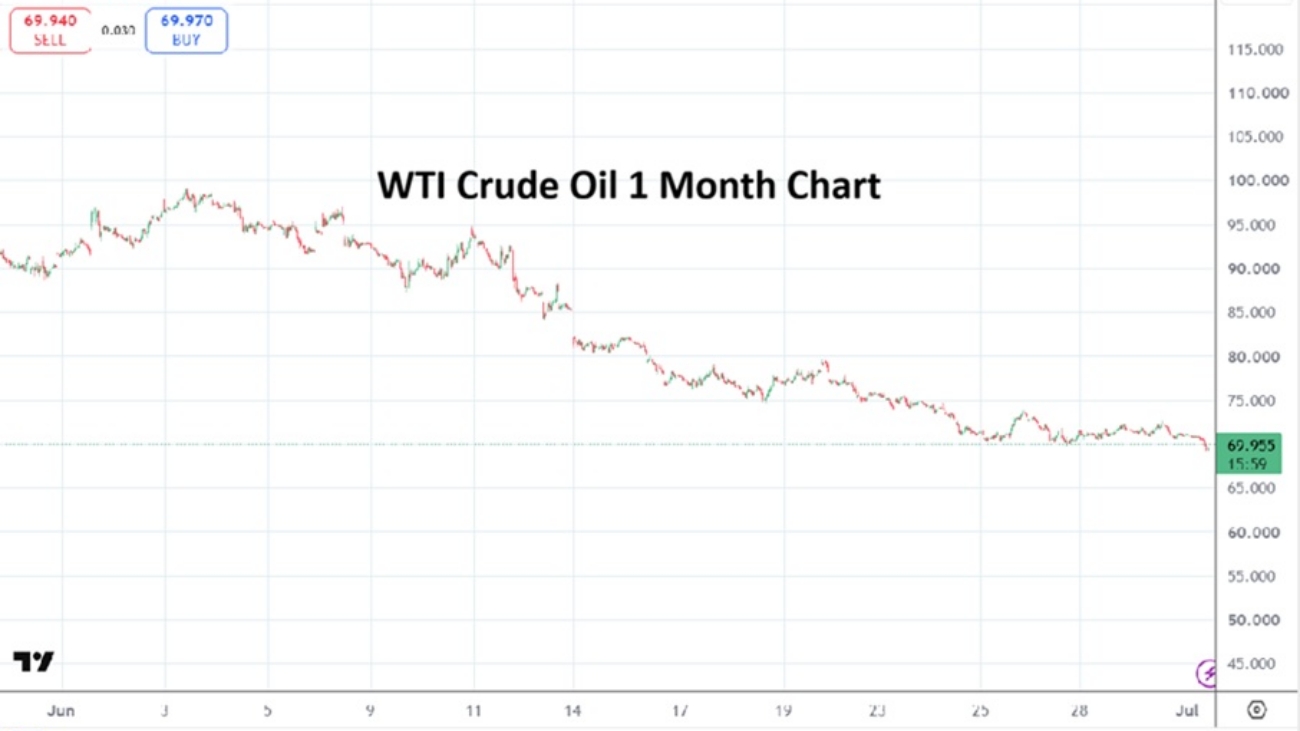
However, the price of WTI Crude Oil was near $80.00 on the 17th of June. And on the 3rd of June the price of WTI Crude Oil was within sight of $100.00. Meaning that we have seen the price of energy trend lower. The agreement between the U.S and Iran, although fragile, has held and the current price of WTI Crude Oil is close to $69.70.

WTI Crude Oil One Month Chart as of 1st July 2026

While concerns about inflation certainly remain, costs should actually start to erode for logistics, fertilizers for agriculture, and manufacturing. Job numbers are solid, growth has been rather steady and shown signs of improvement. If inflation starts to behave and financial institutions change their thinking about interest rates to come, perhaps they will ease off on their borrowing costs.

Also, let’s note that as expected the new Fed Chairman Kevin Warsh has made it clear he will take a more proactive stance regarding interest rates. Evidence for this comes via Warsh’s decision not to participate in the dot forecast that FOMC members use, his absence from the Fed’s ‘prediction market’ game was notable, but many analysts seem to have missed the importance.

In my opinion, Warsh’s decision not to participate in the Fed’s dot plot quarterly signal chart shows the new Chairman wants to create the capability of changing his mind regarding the Federal Funds Rate as needed. The decision not to ‘anonymously’ show what his beliefs are looking forward will allow him to steer the Federal Reserve per forward looking economic data points instead of being held accountable – and possibly blamed – for changing his mind if a shift of opinion is needed.

So again, why is the USD so strong across the Forex board? The USD/JPY is trading well above 162.660+, the EUR/USD is near 1.13900, the GBP/USD around 1.13247 and the USD/SGD is sustaining value at mid-term highs close to 1.29660. While financial institutions appear to have priced in an interest rate, and may also be nervous about volatility in U.S equity indices, the cautious approach has created in my opinion an overbought USD.

As the Independence Day holiday approaches, Forex traders should be careful. If ever there was a time for the Bank of Japan to intervene and cause chaos it might be when USD Forex volume is minimal. Large USD traders may start vanishing in the coming days before the long holiday weekend, and the absence of U.S banks this coming Monday will also factor into the markets.

Selling the USD looks like a speculative bet certainly, particularly because its trend has proven rather strong the past few weeks. Let’s see what happens, but I suspect some downside pressure via USD centric price action is going to be generated.

Copy and paste the text from AMT that you want to share

US Cash Index 20260617

Forex and the Fed Chair: Kevin Warsh in the Spotlight Later Today

New Federal Reserve Chairman will Cause a Reaction in Forex Today

I offer readers a ‘what if’ proposition ahead. These are my opinions and I am simply trying to give my perspective on what may happen in the Forex market in the coming hours.

The Fed Press Conference later today will be must watch television for Forex traders, including retail speculators, large players and financial institutions. Federal Reserve Chairman Kevin Warsh will make his first appearance after a FOMC rate decision. Dynamic conditions in the broad Forex market should be anticipated – that doesn’t tell day traders much I know, keep reading, please. 

U.S inflation has sparked higher this as energy prices have ignited upwards and caused logistics, manufacturing and agriculture to become more expensive. The Bank of Japan raised its interest rate by a quarter of a point yesterday to 1.00%. However, these two bits of evidence doesn’t mean the Federal Reserve will increase its interest rate today. 

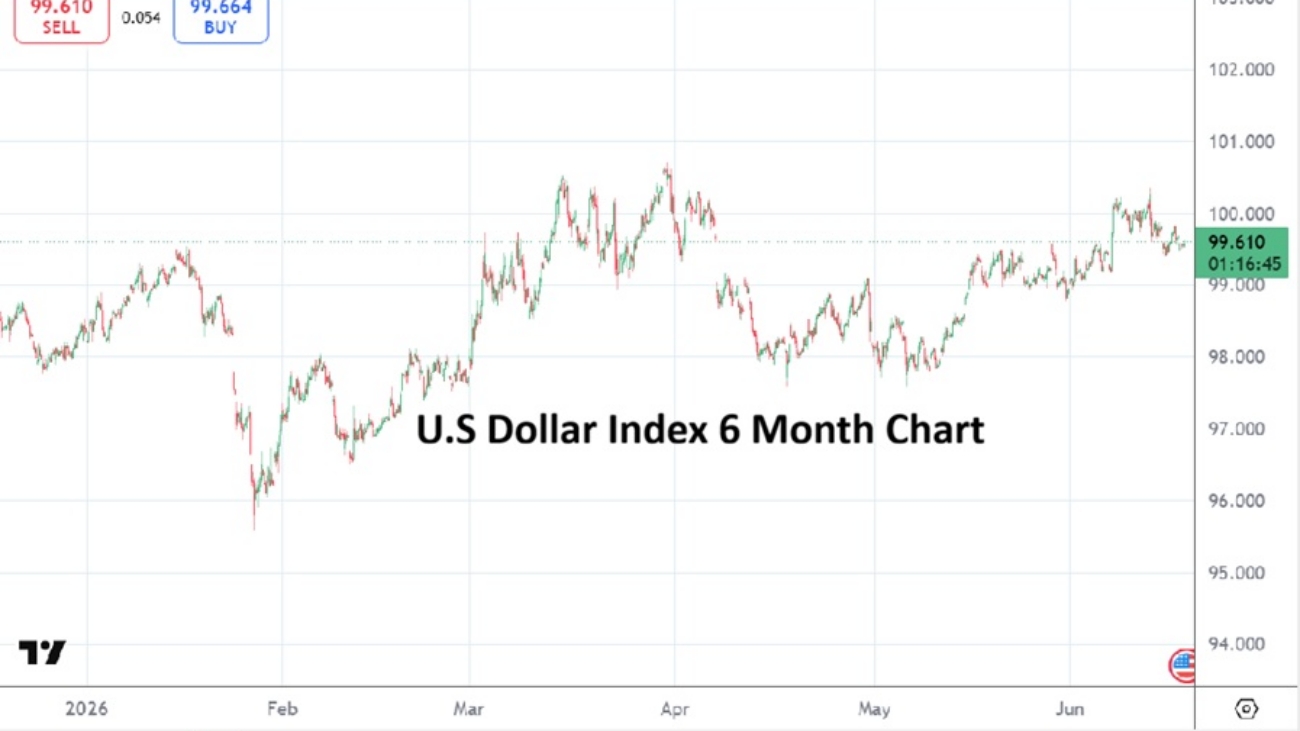
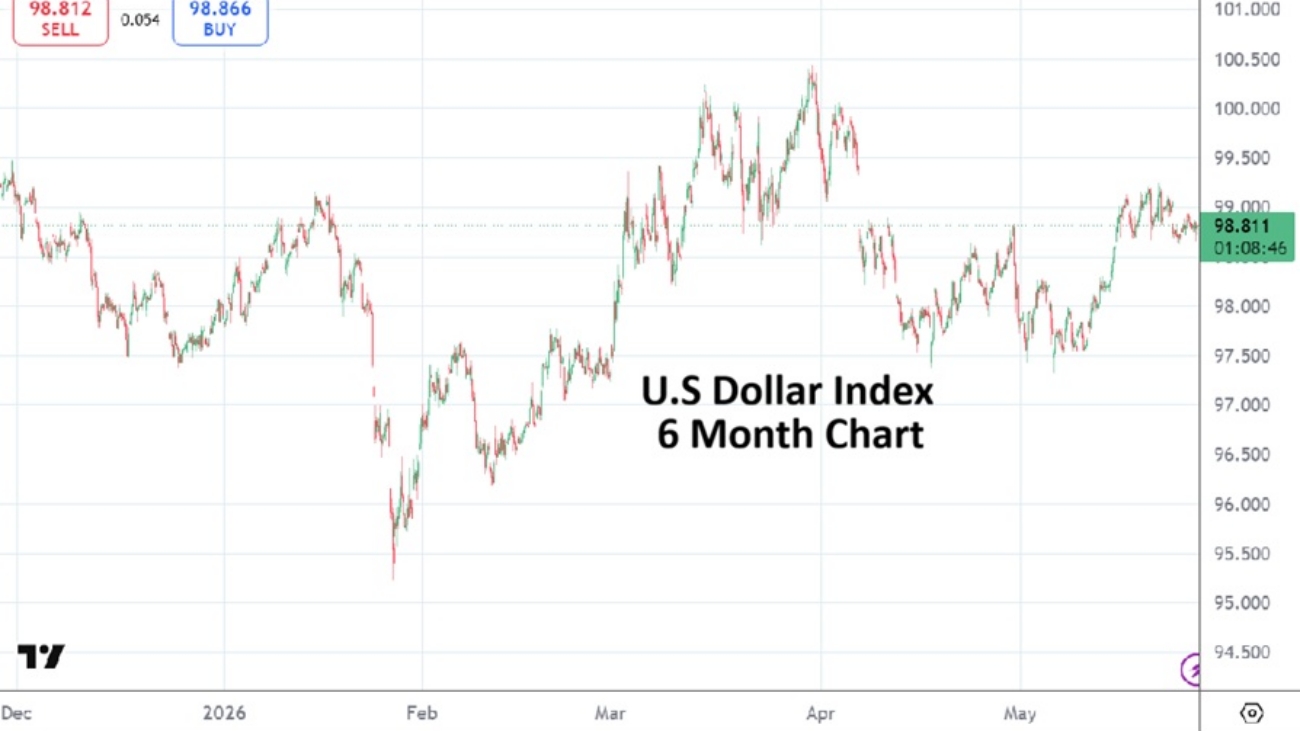
The U.S Dollar Index is trading near relative highs. The broad FX market is certainly cautious, but financial institutions may be leaning into the notion of USD centric weakness. Yes, the USD/JPY remains above 160.000+ for the moment, but the USD/SGD is flirting with its lower range and came within sight of the 1.28000 mark on Monday. So why is this important? Because folks are acting cautious before a potential storm.

U.S Dollar Index Six Month Chart as of 17th of June, 2026

Perhaps this will go down as an infamous egg on the face situation for me personally, but does Fed Chair Kevin Warsh really want to raise interest rates during his first FOMC meeting at the helm? Yes, Jerome Powell is still around as a voting Governor, but Warsh may find he has enough votes (and influence) to get a majority of other FOMC voting members to allow today’s decision to be a test case in favor of patience. 

If the Fed holds the Fed Funds Rate in place and announces it will use the near and mid-term as a trial period regarding their belief inflation will lessen, because it believes energy prices over the mid-term will erode rapidly, that may be enough to cause USD centric selling later today. The Fed will not use the word transitory I suspect, but an argument can certainly be made that now is the time to actually elucidate on the subject of transitory inflation.

Monday’s trading in the broad Forex markets showed that financial institutions bought into the optimism of an anticipated U.S and Iranian agreement and what it could deliver – a glut of Crude Oil, including lower costs for its ancillary products. Financial institutions were also relieved that U.S equity markets survived the launch of the SpaceX IPO certainly. While yesterday’s broad market trading turned cautious and demonstrated sideways action in Forex, many major currencies are traversing near curious values. Equities also went sideways for the most part on Tuesday.

The U.S Dollar Index is swimming within its higher terrain via a six month chart (per a look above), yet financial institutions – if they hear dovish sentiment from the new Fed Chair today could spring into action and sell the USD quickly. Day traders need to understand even if this occurs that it will still be ultra-dangerous to bet ahead of the Fed rate announcement and Press Conference. This because volatility leading up to and following the FOMC Federal Funds Rate decision will create large spreads in Forex and choppiness that small retail accounts cannot handle most of the time – particularly when too much leverage creates wildfires.

While the before and after of the Fed interest rate announcement will garner the headline news, and create a reaction on Wall Street for the S&P 500 and Nasdaq 100 immediately; it will be wise to pay attention to Fed Chairman Kevin Warsh a half hour later when he steps into the spotlight for the first time. There has been chatter that Warsh is not keen on trying to give too many signals regarding the Fed’s thinking regarding every move it is contemplating. 

This coincides with thoughts that Kevin Warsh and Scott Bessent believe in a more high-tech and pro-active approach to interest rate and monetary policy based on forward looking data. The consideration of a more dynamic approach to interest rates has not been widely considered by financial institutions quite yet. If the new Fed Chair surprises reporters and onlookers at the Press Conference today with a new philosophy on the way the Fed will work, this will set the stage for potentially large behavioral sentiment shifts that were not wagered on quite yet. In other words mid-term outlooks regarding U.S interest rate policy may change in a handful of hours more than many people think. 

Maybe I am wrong, maybe I am interpreting the political and financial landscape incorrectly, but these are my thoughts as a risk analyst – one who thinks the U.S White House would not mind seeing a weaker USD, a Fed that likely wants a different approach to interest rates – as they both hope for energy prices to lower (and may get their wishes fulfilled).

Copy and paste the text from AMT that you want to share

WTI Crude Oil 20260601

Clues and Insults: Forex and Equity Indices During the Iran Saga

Profits: Optimistic Wagers and Preserving Self as the Party Rages

New Federal Reserve Chairman Kevin Warsh certainly doesn’t want to have problems with President Trump. On the 17th of June the FOMC meeting via the Fed will make their interest rate decision known. Who really believes that during the first month on the job at the helm of the U.S central bank that Warsh is not going to fight to keep interest rates in place?

Those who are expecting an interest rate hike in June of a quarter of a point (0.25%) are most likely wrong. Yes, the price of WTI Crude Oil is high and the situation in Iran via narrative varies from one moment to the next per the reported incidents on the Strait of Hormuz.

However, just like the Fed there is a certain amount of reality that must be dealt with regarding human nature and behavioral sentiment regarding Iran and how it is dealt with via market participants. From the department of no news is good news: financial institutions and investors would like the noise to be kept to a minimum so they can continue doing their jobs and not be criticized themselves for potentially wrong outlooks. The art of making sure disclaimers are up to date is important for everyone who wants to stay employed.

WTI Crude Oil 1 Year Chart as of 1st June 2026

USD centric weakness was seen late last week in many currency pairs, but a quick glance at the majors: EUR/USD, GBP/USD and USD/JPY actually show the pairs traversing rather cautious values. The EUR has gained slightly for instance, but at its current levels around 1.16410 some may believe it is a safe equilibrium. (One that may be able to be taken advantage of by those with the ability to bet on mid-term higher trajectories).

Central Banks globally also want to keep the noise down in their various locations. Inflation concerns persists worldwide depending on the amount of knock-on effects that higher energy costs have on national economies.

Also adding additional intrigue to the storyline of wanting to keep quiet while volatility threatens the gates, is that many people with comfortable jobs in various government institutions do not want to step out of line and sacrifice their careers for the sake of being proven right. They would rather be proven wrong, but would like to do this quietly without facing consequences.

The fact that we are now in a situation in which we are afraid to undertake critical thinking aloud is going to cause problems down the road, but for the moment most will simply go on with their various duties and pretend all is well.

U.S equity indices have been having a massive upwards party since the end of March as record heights are attained. Certainly some long-term investors are simply throwing money into indices as a way to get positioned before the SpaceX IPO which is coming soon. There will also be the Anthropic IPO which is reportedly set for late 2026.

The SPCX which seems to be aiming for the 12th of June will create a valuation well above 1 Trillion USD for SpaceX. The perceived value of Anthropic is becoming a loud talking point among analysts in the tech sectors and they are keen to have the company join the 1 Trillion USD party. The cost of admission for bragging rights is getting more expensive.

There was a time when things like PE (price and earnings) ratios mattered on Wall Street. Some brave folks still whisper about such things in meetings and bars late at night, but many do not want to be insulted or possibly worse get marketing folks selling these high priced products angry. The reason for speaking softly about actual earnings regarding SpaceX is because the company is actually working via an earnings loss, and instead price to sales estimates are being offered as some type of guideline. Having said the above, it would be foolhardy to bet against SpaceX and Elon Musk. And it might be equally unwise to bet against Anthropic in a handful of months. And thus, the rush into equity indices because there is a genuine fear of missing out does exist. Afterall, we all want to be part of the party.

And that brings us back to Fed Chairman Kevin Warsh who has the backing of President Trump and Treasury Secretary Scott Bessent, he doesn’t want to insult these men either. Warsh may be quite good at what he does, he might be an expert and have real world business experience, and that might be a real clue for Forex traders who think higher interest rates are coming. Warsh will likely want to keep his first months on the job at the Fed on good terms with the White House and the Treasury. Kevin Warsh might be a free-thinker and know legally he is an independent leader of the Federal Reserve, but he also knows he was hired with a stated mission. There is a pro-business, free enterprise administration in power at the White House. Bessent, Warsh and Trump are on the same team.

So again, while some traders may believe the Fed will raise interest rates in June because of concerns of higher inflation, it most likely will not happen. While the Iranian war continues to make headlines in the financial world and dealt with via sentiment decisions, actual economic U.S data will start being watched in the coming days and weeks and might even influence perspectives. Investors will get bored of the Iranian saga as long as its narrative stays somewhat tepid. Meaning investors will start looking at CPI and PPI numbers coming from the U.S next week and talking about higher interest rates that will likely not be delivered in the upcoming FOMC meeting. 

The price of WTI Crude Oil as boring as it is to say remains a strong sentiment gauge for traders intraday. Large players involved in Forex might believe this will involve higher interest rates, but on the 17th of June it is more likely that Kevin Warsh will say that for the moment the Fed chooses to watch energy sector costs with the belief prices will decline in the coming months. The Fed will not use the term ‘transitory’ which was used infamously during the Covid crisis and turned into a poison pill with inflation that was not effectively fought. What the Fed will likely do is say they want more info to be gathered and more clarity regarding the Iranian situation and its overall effect on oil prices for a little while longer. Some patience will be asked for and it might be granted by investors who want the party to continue via equities.

Day traders should expect cautious markets to prevail in Forex with choppy results as financial institutions weigh their behavioral sentiment and try to make believe they are not too worried about near-term inflation. The CPI and PPI readings next week will prove of interest, but the results may be brushed aside by market pundits.

In the meantime, the celebrations on Wall Street continue as folks march merrily into the frenzy. Retail speculators who want to pursue short or near-term profits on the Nasdaq 100, S&P 500 or Dow 30 indices need to be careful and might want to stay away from daily bets and instead engage in conservative positions that allow for a full week of results. The gains made since the end of March have been outlandish and likely will not be repeated anytime soon, but why try standing in front of a trend that can crush you.

Near-term considerations in these markets should be done carefully. The mid-term may be very different from where we stand today and our current outlooks. One thing that may bother some risk analysts is that it may prove wrong to bet against the current parade of optimists who insists on participating in dangerous conditions and profit, while they (the risks mavens) stand in place.

Copy and paste the text from AMT that you want to share

US Dollar Index 20260627

The USD and The Art of Not Knowing

Being Mature Enough to Know You Don't Know as You Watch the Marketplace

Ask anyone that typically knows how they gauge the state of the global marketplace for the near-term and you are likely to either get a solid, “I have no idea” now. Or a bunch of thoughts on what might happen, which might lead to being more confused. Simply put at this point, it is easier to admit that potential conclusions regarding the world’s current affairs taking place and effecting the global marketplace are out of most peoples’ hands. 

Even those who have duties within the higher paid grades likely are just as confused about the potential unintended consequences not wanted, and results they hope will be achieved. And what am I speaking about exactly, regarding the world and its state of affairs, is that even qualifying the particular topics are difficult to put a finger on. Ramblings certainly include the Iran saga, but Cuba, the Ukraine, the NATO pact, shifting world alliances and future ones are creating a whirlwind. Besides the rather noisy political landscape of the USA. Not to mention China and Russia and other nations with aspirations.

Yet, the global markets continue to trade, albeit within a confused haze it sometimes appears. But do not be despondent day traders, brokers and their platforms will offer you the opportunity to wager on results of the USD in Forex, and CFDs certainly contain opportunities in major equity indices the world over, various big singular companies, commodities and yes cryptocurrencies (apologies to Bitcoin fans – who insist it is called a digital currency).

U.S Dollar Index Six Month Chart as of 27th May 2026

Iran War and Unclear Results

The U.S Dollar Index for the moment is near the 98.880 ratio, which it should be pointed out is near the values it swam upon the April 8th announcement of a ceasefire between Iran and the States, this after dropping from its 99.800 threshold on the 7th when investors were more troubled. The ceasefire is still in effect and now there seems to be a resolution which is being hoped for by the U.S White House – although when pressed about what negotiations between Iran and the U.S will result in delivers a few different versions of ideas. 

Perhaps that is to be expected via the fog of war, but what should not be expected is an easy path to a genuine resolution. And even if there is a pact of some type, what objectives will have been genuinely fulfilled? But alas, that is a question for those in the future, because the facts on the ground do not bode well for ordinary Iranians who have yearned for freedom. 

The Fed Has a Problem

But again, let’s not dwell on things like the individual rights of people, money is at stake…..(that is humor folks, others can call it sarcasm). The price of WTI Crude Oil has dropped this week on the idea that a resolution will actually be accomplished between Iran and the U.S – one at least that allows tankers to navigate the Hormuz Strait. 

The price of WTI via futures at this moment are around the $90.00 mark again, this after moving within sight of 88.00 USD earlier today. At the end of last week the $96.00 mark was in sight for WTI. And the price of energy continues to cast a shadow that is moving over the U.S Federal Reserve and has large implications for the new Fed Chairman Kevin Warsh. 

The mid-term versus the long-term in financial institutions as they judge their interest rate perspectives are likely making for rather entertaining dialogue. And let’s not forget ladies and gentlemen, the U.S mid-term elections are approaching in November of this year and are resulting in primary elections that are punishing Republicans who voiced criticism towards President Trump. The question about who will hold power in the U.S House of Representatives is a big riddle. Even the U.S Senate leadership may be fragile. Why is that important, because if President Trump were to become what is known as a lame-duck President during his last two years in office, this would produce different outlooks among investors. Stay focused on the money people. 

Our Forex Friend: The BoJ

The USD/JPY is now traversing its 159.490 vicinity again, and perhaps that is a bell weather for soothsayers to criticize again. The Bank of Japan is watching the Japanese Yen as its trades within sight of its weakest values, and yes, the BoJ can be expected to issue another warning to speculators once again about being run over by an intervention. The BoJ’s broken record about interventions have produced solid results for folks who are able to trade the USD/JPY with positions that can be held for a few weeks at a time – namely hedge funds, large players and some financial institutions. Retail traders trying to take advantage of the USD/JPY are likely suffering trauma via anxiety if their wagers have gone in the wrong direction.

SpaceX and Scams in the Cryptoworld

And as a bonus, let’s not forget about rumblings regarding SpaceX and another topic within the I do not know category. Elon Musk has set the table for an attempt at a 2 trillion USD market cap after the IPO for the corporation is launched in the second week of June. The value of SpaceX can be and will be argued for the next few years as admirers and critics lineup to be heard and spread sheets are compared regarding revenues against one of the greatest marketing giants of our time. Intriguingly, however, are hints that there has been a lot of cryptocurrency fiddling regarding how the corporation is going to allow investors to participate. Apparently there have been tokens issued in the cryptocurrency world that have promised some type of participation in SpaceX and most are being exposed as scams and have nothing to do with the company or Musk. Buyer beware folks.

Copy and paste the text from AMT that you want to share

AMT Top 10

AMT Top Ten Miscellaneous Early May Reflections

May Day Parades and Wishing on Santa Claus

10. NBA Playoffs: Basketball has now entered its serious season, one in which rest days are no longer done in order to gain better draft day lottery odds, nor appease star players who feel the need to take a day off. There have been a couple of upsets already during these playoffs with Houston, Denver and Boston all of whom were favored to win their first round competitions going down in flames. Semi-conference championship contests will begin tonight. Basketball fans are now getting the NBA product they want.

9. May Day: Parades and protests were seen throughout the United States this past Friday. The once treated contemptuous flag of communists was held aloft and portrayed as a viable ideology at many demonstrations. Protestors marched and chanted their displeasure about free enterprise. A lack of historical knowledge about the massacres ignited by Joseph Stalin, Mao Zedong and Pol Pot while paying homage to iconic Che Guevara images was evident. However, their longing for a Santa Claus like figure to come bearing free gifts did not appear. 

AMT Top 10 Miscellaneous Early May Reflections on the 4th of May 2026

8. $80,000.00: Bitcoin has been traversing higher and continues to flirt with the eighty thousand USD realm in its sights. Strategy (MSTR) finished last week above the $177.00 ratio. Are the new higher avenues a sign momentum will continue to endure for these two highly flammable speculative wagers, or will profit taking douse them again when suspicious caution reemerges?

7. NYC: Mayor Mamdani has made it known the city is not going to be able to meet his budget requirements and has postponed the publication of New York City expenditures until the second week of May. Mamdani has called on the State of New York to change is financial arrangements with NYC in order to facilitate his wishes. In the meantime, the Mayor has decided to pick a battle with hedge fund manager Ken Griffin, the primary owner of Citadel, which if unresolved is likely to cost NYC vital jobs and income. Charm and ignorance are likely to get Mayor Zohran Mamdani only so far.

6. Warning: USD/JPY is traversing near 156.900 as if this writing. Last week the USD/JPY was over the 160.000 ratio and sustaining values. But official murmurs from the Bank of Japan proclaiming readiness to intervene sent the Forex pair tumbling. Japanese Yen speculators betting against the BoJ should remain alert and understand that quick profits and escaping before an actual intervention strikes is a very dangerous game to play. The USD/JPY is the domain of large players and financial institutions. Yields on Japanese bonds have escalated, which is a sign that belief in Japanese fiscal policy remains lukewarm, but participating in the USD/JPY via wagers needs to be done with extreme care.

5. Hormuz Strait: WTI Crude Oil values continues to effect behavioral sentiment amongst investors and speculators. The price for spot Crude Oil is above $106.00, while futures are challenging the $100.00 realm. Inflation concerns are turning from whispers into fact. Airlines are being impacted, and logistics for large companies like Unilever are becoming higher costs for global consumers.

4. Reality Shock: Escalating electricity costs for the giant data centers that Artificial Intelligence infrastructure needs are starting to not only be realized, but causing investors to understand genuine profits for the mega-sized ambitions of many companies may prove fleeting. Hyper-scaling companies seeking to build bigger electrical capacity include Microsoft, Alphabet, Meta, Amazon Web Services and Equinix and it will not be easy. Potential and real electricity shortages are causing some nations, states and cities to plead for help due to too much demand on their overwhelmed power grids.

3. Voting: Jerome Powell has decided that he will remain as one of the seven Federal Reserve Governors, which allows him to vote fully on interest rate (FOMC) policy. Powell’s action is highly irregular and one that certainly doesn’t please the Trump administration. Treasury Secretary Scott Bessent has expressed his exasperation regarding Powell’s non-departure from the FOMC. Powell will step down as the Chairman of the Fed on the 15th of May, but his position as Governor doesn’t end until the close of January 2028. Because the Fed is an independent entity in theory, President Trump and those aligned with Trump’s economic outlooks will have to deal with Powell who will clearly not bend to White House desires. 

2. Apex Peaks: The official start to the Middle East conflict – this time – began on the 28th of February. Since deciding the Nasdaq 100 and S&P 500 were vastly oversold in late March, a parade upwards bearing gifts has developed and both indices attained record heights this past week. The Dow Jones 30 is still below its all-time levels produced in the second week of February when it scorched above the 50,000 level, but the granddaddy of U.S indices also did remarkably well in April. 

1. Exit West: The decision to officially leave OPEC by the United Arab Emirates is a clear sign that the Iranian war has turned into a philosophical realism regarding existential outlook. The UAE’s has aligned itself with the West and has said no to radicalization. The United Arab Emirates desire to become a Singapore like model in the Middle East that practices free enterprise and provides a worldwide hub for commerce is clear. Many people are not connecting the dots regarding the UAE’s choice, a realignment of the Middle East is underway and it will have a profound economic effect globally.

Copy and paste the text from AMT that you want to share

US Cash Index 20260424

Upcoming Weekend Nervousness: Does Anyone Know What is Going On?

Preaching Caution and Looking Like a Fool to Those Who Want to Profit

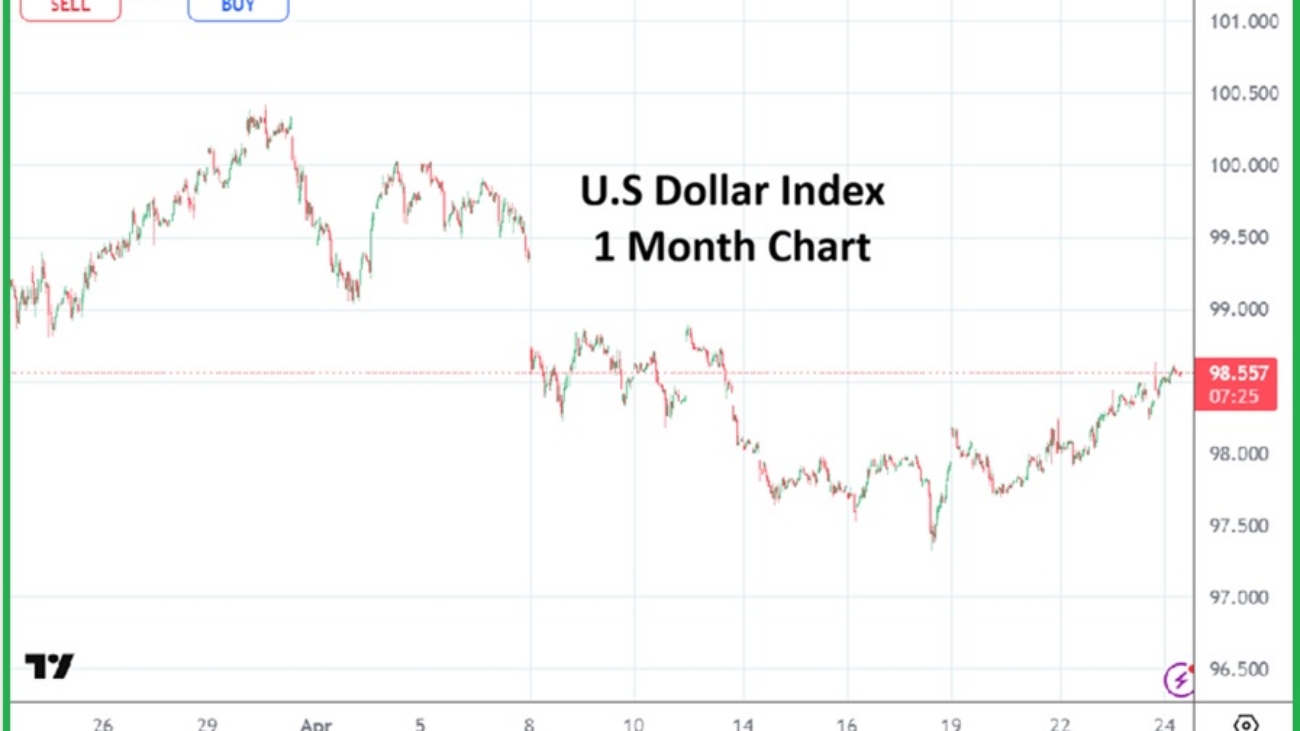
Can someone please tell the rest of us what is going on? Global markets via Forex this morning are demonstrating additional USD centric strength which developed yesterday. The price of WTI Crude Oil is above $94.00. Gold is languishing and around 4,675.00 USD. And although the 3 major U.S stock indices are all within their higher realms – one thing stands out – folks are uneasy.  But then again, the markets never move in one direction only, and perhaps current results can be interpreted as profit taking by those on winning sides.

U.S Dollar Index One Month Chart on the 24th April 2026

I would love to be the person to tell you what is going to happen, but as this weekend looms making short and near-term bets still appears a fool’s game. Yes, it is easy to make predictions, but being correct is more difficult. Retail traders are suffering more than most market participants, this as leverage and a lack of funds to remain in a position through violent reversals destroy plenty of trading accounts.

There is talk of manipulation via chat rooms regarding the price of WTI Crude Oil. The usual dialogues can be seen – largely based on conspiracies via large players trying to blow out smaller traders. However, these types of forum chatter are mostly wrong. Large players are getting hurt too in the energy markets. Anyone who is taking a position in order to speculate on a quick hitting foray in WTI is betting on their perceptions. 

The problem is that unless there is inside knowledge of what the next words out of President Trump’s mouth are going to be, or that from Iranian officials – any pursuit of WTI Crude Oil at this juncture is a ‘vibe’ trade. What is going to happen from Saturday and into Sunday is an unknown quantity. Folks holding positions into this weekend need to understand they are wagering. And some may find they are quite profitable afterwards, while others grimace and find themselves on the wrong side of the next surges higher or spikes downward. Intraday trading volatility in nothing new however.

The USD/JPY is near 159.600 as of this writing. The EUR/USD is close to 1.16820. While a tourist traversing foreign lands may not find the Forex incremental shifts in value mesmerizing or of interest, FX traders who do not have deep pockets are likely wondering why risk adverse conditions are prevailing suddenly. But as a risk analyst, I must say that conditions simply may have been perceived to have been oversold in the USD by financial institutions, this as the Fed looms on the horizon.

However, my task as a risk analyst the past two months has been like a carnival barker, because while it has been easy to say that a show is happening within the big tent of speculation, I have been hard pressed to predict short and near-term directions correctly. Perhaps I fret too much. The optimistic thunder claps upwards in the stock markets since the 31st of March have been astounding to many. Hopefully it has been prosperous for day traders, but the likelihood is that financial institutions are the ones who are profiting more via their pension funds purchases for institutional clients.

This coming week the U.S Federal Reserve will make their FOMC decision public. This will be Jerome Powell’s swan song at the Fed. The Chairman is being faded out by the U.S White House mid-May. And somewhere when he is all alone, Jerome Powell may be having a quiet laugh to himself. The Fed will not act this week. Rates will remain the same – unless there is some bizarre move in the global markets over the next handful of days. Yet, Powell’s remarks will be listened to for warnings. While it is not in Powell’s nature to issue a ‘I told you so’ quote, and he is likely content to walk away from the Federal Reserve quietly, it would be captivating if Powell looked into the cameras and pointed fingers. 

But because Jerome Powell like most others, likely has no clue what is going to happen next internationally he will remain mostly mute (cautious as always).

And here we meet again, wondering what the next 72 hours hold. Will the Iranian ceasefire remain observed? Is it even a ceasefire in reality? The Strait of Hormuz remains a linchpin for military action by the U.S Navy and Iranian Revolutionary Guards via a cascade of ship seizures. Maybe that continues to be the key, WTI Crude Oil prices remain a crucial barometer. USD centric prices via Forex action seems to be a reflection of fear or positive thinking in the energy sector depending on the prevailing tides.

Last week there was so much optimism folks were talking about WTI prices potentially hitting $75.00 and lower, now this hope seems to be wishful thinking. Global markets will remain fast and dangerous, that is easy to say and is right, but telling you which direction assets will move, that is a bit different.

And there is the old standard test I use when an opinion is definitely asked for: if someone were to put a gun theoretically to my head and ask me what I think, I would venture to say things will remain quiet and optimism will seep into the markets before the close this weekend. However, I don’t like to play fool’s games, so I will leave now and wish you luck via your own perspectives because the near-term remains more speculative than normal for day traders – even if strict risk management is used. 

Copy and paste the text from AMT that you want to share

Outflows 20250220a

India Insider: Macro Stress a Capital Flow Problem, Not a Trade One

India Insider: Macro Stress a Capital Flow Problem, Not a Trade One

Editor’s note: This article was originally written in January 2026. It has been updated to incorporate developments through February 2026, including the U.S – India interim trade agreement and subsequent capital flow data.

India is currently experiencing what can best be described as macro stress. By macro stress, we mean pressure across the broader economy that shows up simultaneously in the currency, financial markets, and capital flows, rather than a problem limited to one sector or company. In India’s case, this stress is visible in a weak rupee, persistent foreign investor outflows, and rising concerns about equity valuations.

This stress is often misinterpreted as a trade or export problem. In reality, the pressure on the Rupee and the growing fragility in equity markets stem primarily from the capital account, not from collapsing exports or remittances. Even as the U.S Dollar softens – helped by Federal Reserve rate cuts and renewed trade tensions under U.S President Donald Trump, India continues to struggle to attract foreign capital, exposing a deeper structural imbalance.

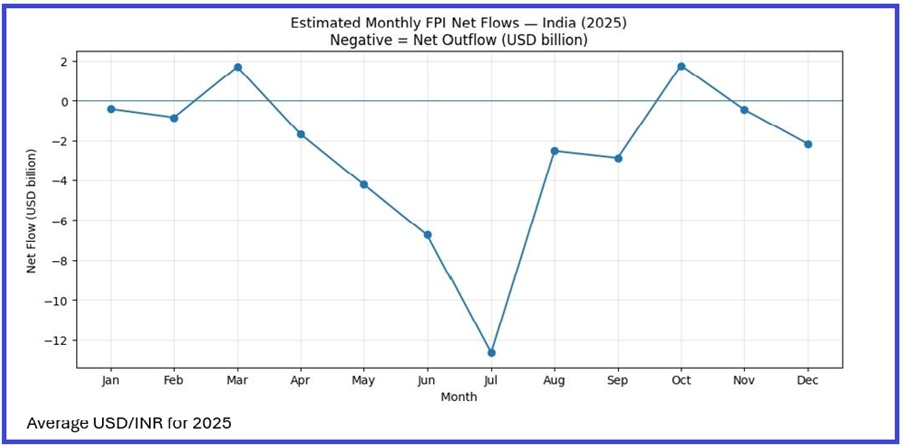
Source: NSDL (FPI Equity Flows): Reuters and author’s calculations.

Recent weakness in the USD would normally support emerging market currencies and risk assets. This time, however, the response across emerging markets has been uneven. Capital has flowed toward economies linked to artificial intelligence, semiconductors, and commodities, as well as toward markets where valuations have already adjusted. South Korea, Hong Kong, Chile, and South Africa have all benefited from this rotation. India has not.

The Rupee’s weakness reflects this divergence. USD/INR continues to trade around ₹91.5–91.6 despite the absence of a sharp deterioration in India’s trade fundamentals. Services exports, particularly IT services, remain resilient, and remittances continue to provide a steady source of foreign exchange. This brings us to the current account.

The current account represents a country’s net trade balance with the rest of the world, including goods, services, and remittances. India runs a current account deficit, meaning it imports more than it exports. While this deficit persists, it is manageable at present, supported by stable services exports and remittance inflows.

The real problem lies in the capital account, which tracks investment flows such as foreign investors buying or selling Indian equities and bonds. When foreign capital flows into the country, it helps finance the current account deficit. When it flows out, pressure builds quickly on the currency and financial markets.

Foreign capital is neither entering India in sufficient scale, nor remaining invested. Portfolio outflows have become persistent, and this has emerged as the dominant driver of currency pressure. In calendar year 2025, foreign portfolio investors sold approximately USD 19–20 billion worth of Indian equities, marking one of the largest annual equity outflow episodes in recent years. Importantly, this selling has been sustained rather than episodic, pointing to a structural reassessment of India’s growth outlook and valuation premium rather than a temporary risk off shock.

Crucially, this capital flight is not the result of a collapse in exports to the United States. Despite tariff concerns, the U.S remains India’s largest export destination. Between April and December 2025, Indian exports to the U.S rose to roughly $65–68 billion, compared with $60–63 billion during the same period last year. Trade flows, for now, are holding up better than sentiment suggests.

The effects of capital account stress are most visible in financial markets. Indian equities are failing to attract foreign inflows as growth momentum weakens. Market leadership has narrowed, with headline indices supported by a small group of large-cap stocks, while consumption-sensitive sectors such as FMCG remain under pressure.

This dynamic fits squarely within the balance of payments framework described by Professor Michael Pettis. He described, “a country cannot sustainably run a current account deficit without stable capital inflows. When capital inflows weaken, the adjustment shows up through a weaker currency, tighter financial conditions, and pressure on asset prices.”

Indian equities now trade at some of the highest valuation multiples globally, supported largely by domestic retail and mutual fund flows. However, domestic capital is structurally constrained, while global investors can freely reallocate. As Bloomberg’s Andy Mukherjee recently noted, Indian cement stocks now trade at higher valuations than Hong Kong Tech stocks showing the exuberance of Domestic equity capital chasing local themes.

At a deeper level, India’s vulnerability reflects a structural imbalance between savings and investment. Domestic savings are insufficient relative to the economy’s long term investment needs, and the financial system lacks the institutional capacity to consistently channel savings into productivity enhancing investment. As a result, growth has become increasingly dependent on mobile foreign capital – capital that is cyclical, return sensitive, and easily reversible. It is this dependence, more than any near term trade shock, that leaves the Indian rupee vulnerable when global capital flows turn cautious.

Update: The US–India Interim Trade Agreement (February 2026)

Since this article was first written, a significant development has reshaped the near-term outlook. In early February 2026, the United States and India reached an interim trade agreement. As part of the deal, the US lowered its reciprocal tariff on Indian goods from 25% to 18%. President Trump also signed a separate executive order removing an additional punitive 25% tariff that had been imposed as a penalty for India’s purchases of Russian oil, meaning the effective tariff burden on Indian exports had, at its peak, approached 50% before being brought down to 18%.

The announcement acted as an immediate sentiment catalyst. The rupee, which had been trading in the ₹91.5–92 range under stress conditions, strengthened on the news, touching ₹90.30 before settling near ₹90.70. Foreign portfolio investors, who had spent most of 2025 as relentless net sellers, turned net buyers in the first week of February 2026, purchasing approximately $897 million worth of Indian equities.

These are meaningful moves. After 18 months of persistent underperformance relative to other emerging markets, India’s excessive valuation premium has moderated toward historical averages, which may create better entry points for global capital going forward.

Copy and paste the text from AMT that you want to share

Confused Markets 20260217

Market Volatility: Structure, Geo-Politics and Culture

Why the (Free) World is so Confused and Depressed

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 16th of February via The Angry Demagogue.

Having been involved in the capital markets for the better part of the last four decades, I wouldn’t go so far as to say that I have not seen this amount of volatility and uncertainty in the markets, but I will say that this uncertainty and this volatility is different. The differences are important and have to do with the current structure of the markets as well as the geopolitical goals of the various powers and would-be powers. The trading world has changed radically over the last two decades with the advent of algorithmic trading and how they respond to global events as well as the type of money that is coming to dominate the markets.

The “type” of money has changed from those who invest in “things” – be they long term value investors like Warren Buffet and Peter Lynch, to those who chase income and dividends and to those who like to follow trends and industries. These investors, different in their own methods and goals had one thing in common – they invested in companies they felt had a future, or in the case of short-sellers (as legitimate as buyers) who thought it didn’t. The few hedge funds that were around four or five decades ago did what the name of the type of fund said – it “hedged” positions and gave up some potential upside in order to cushion losses when markets went south. That changed sometime at the end of the last century when George Soros nearly ended the United Kingdom by mercilessly shorting the Pound.

We are being very general of course and have not spoken about those who invested in bonds of “fixed income” products, corporate, federal or municipal as well as the basic speculator in all sorts of investment products. Nor have we spoken of the crooks who populate any era. We don’t want to give the impression that all was wonderful “then” – this is not a nostalgic look at the recent past but an attempt to understand what people were doing and how they did it, and how things have changed.

We are seeing now a sea change in the way the markets are responding to news and the way money is being invested. We still have the value and income investors; we have the large and small investors doing their best to pick the right stocks and bonds, and some of these investors also use options and futures to enhance and hedge their investments. Investing has become more sophisticated- read more mathematical – and the “basic” investor, large or small has been able to use this sophistication. However, the current hedge fund environment is based on much more than picking the right stocks or bonds and all that goes with it. The current hedge fund system is a group of funds, many of multiple hundreds of millions or even billions of dollars that don’t make investments per se as they try to beat their competitors by the microsecond in order to profit a very small amount on a a large but extremely short term investment (we will speak of the money of unfree countries, below).

As an example, there are dozens of hedge funds who work their “algos” to respond to market news and announcements only to get out of the position within minutes or even seconds. Each algo basically says the same thing – if X happens then buy and if Y happens, sell. The only difference is who will buy or sell quicker and then reverse what they have done. There have always been those with fingers on the button ready to buy or sell but the amounts were smaller and the effect less. Today, the reaction time is so quick that the large firms have their servers in the stock exchange buildings, close to the exchange computers so that they will get their orders in first. Remember, these are electronic so they are going at the speed of light. The difference between 100 feet way and 100 miles should not matter – but it does. We are talking the difference between 0.0000001 seconds for 100 feet and 0.000537 seconds for 100 miles – a time difference that people cannot discern.

This of course is not necessarily a bad thing if the algos themselves were correct for the long or even medium term (or what used to be called the short term – a quarter of a year). But they are programmed for the shortest of short term – what will happen over the next 30 or 40 seconds or maybe a day or two or a week. We see incredible volatility and panic where we should find none. A good or bad jobs report, inflation release or even a Federal Reserve rate cut or hike might have long term consequences but these trades that cause this radical volatility are not concerned with that. The market dropping two or three percent in a matter of minutes does not provide the comfort that investors usually seek. People jump on the bandwagon fearing the worst –when it was just the algos responses to the news rather than intelligent judgement on the news that drove the prices.

We will stop with the details and summarize – a large part of the uncertainty of the markets is structural as technology and the sheer amount of money being traded has surpassed what the markets, as currently structured can stand. As an example, as an employee of the Nasdaq Stock Market in the early 1990’s we were told to prepare for a 1 billion share day. During those days, there were very few shares that traded above $100 as the companies wanted more investors and there were many stock splits (more rare these days). The 1 billion share day in 1995 would have totaled around $40 billion. Today, daily trading activity has passed 15 billion shares and the total money is above $1 trillion.

It is not clear what structural changes need to be made in order to take all of this into consideration, but we do have some ideas (which we won’t bore you with now).

The second major issue that is the cause of the volatility and uncertainty in the markets has to do with what news is “good” and what news is “bad”. Not in the moral sense but in the economic and geo-political sense. What we mean by this is that there does not seem to be a unified view in the Western world where it should be going and because of this, it is not clear what news is in fact good and what is not. Economically it might be easier to figure out but even that has been hard since so many major American cities and so many young people are voting socialist and so much foreign money from non-free countries is flooding the market. News may say one thing for a free market economy and something entirely else for a planned socialist economy. It might mean one thing for investors in New York or Cleveland and something entirely different in China or Qatar.

Therefore, geo-politically the uncertainty is confusing. During the cold war of course we basically understood what moves were positive and which were negative. That is not to say there were no policy arguments but for the most part, the ends were agreed upon. Selling grain to the Soviets may or may not have bettered the Western world but both those like Henry Kissinger who supported it and Senator Scoop Jackson who opposed it argued based on the same goal – what was better for the free world.

This goes beyond who is considered the “enemies of the West” to what is considered the West – or even if it exists! We have always tried to write here from the perspective of what is good for free countries even if many free countries seem to think that Israel, for example, is not a member of that community. The same goes for those who doubt the cause that Ukraine is fighting for, as they support the Putin tyranny in the name of balance or alleged Christian values or whatnot. Interestingly, both sides – the right in the Russia-Ukraine war (and the Tuckeronian Right regarding Israel, too) and the left in the Israel-Islamist war – are willing to forgo freedom for some amorphous, form of justice or truth.

Iran is the perfect example. In every measure of Western values since WWII the Islamic Republic of Iran is an evil country. It denies freedom to its citizens, massacres them, executes women for immodesty and homosexuals for being homosexual. We don’t have to go on regarding the evils of the Islamic Republic of Iran but even with that, there are those in the West who support it. We are not talking about the legitimate policy debate regarding a war with Iran – morally as well as politically – but rather the fact that many just don’t consider that Iran is on the wrong side. Israel as we said is another example, but we can go on and on. Venezuela, Cuba and even China come to mind.

True enough, there were always people in the West that thought the Soviet Union or Maoist China was morally “better” than the United States or Europe, but never did they influence the politics, culture and businesses as the current naysayers do. The markets “understood’ that the Soviet Union was bad and reacted accordingly. The geo-political goals were mostly in sync.

The global markets reflect the geo-politics of the day and “vote” on it in a daily basis. The fact that there is a vast sum of money that influences the markets that are actively opposed to the freedom project – China, Qatar and Russia come to mind – does not help the situation. It is not the “foreign” money that disturbs the markets but rather which foreign money. There is a difference between an investor who is looking for the good company or the safe bond, and one who is looking to use their investment to further a radical Islamist or Chinese Communist agenda. President Trump’s trillion dollars of investments from Qatar and Saudi Arabia and others comes with a price tag he does not usually deal with – the price tag of undermining the market economy that has made him so successful. The proof of “goodwill” in the investments in the United States ought to be shown before that money flows into the economy. They have already contributed to ruining the universities (not that they needed the help) – there is no reason to permit them to ruin America’s great corporations, too.

The markets are crazy due to its structural issues and due to the “uncertainty” that is today’s world. Sadly, that uncertainty is not just uncertainty about what will happen, but uncertainty about what is good or bad (news). This goes beyond unity and “can’t we just get along?” and gets to the heart of why we are living today in the same culture. We say culture instead of country or city since that culture is the one that “got us here” as basketball or football coaches like to say.

The lack of agreement as to what matters most has affected the markets more than we think, and it all has contributed to the depression that so many in the free world are feeling at the moment.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

You can follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/ 


Copy and paste the text from AMT that you want to share