Impact: Powell's White Flag, Inflation Data, and the BoJ
Federal Reserve Chairman Jerome Powell’s waving of the ‘white flag’ last Tuesday, when he admitted that inflation was producing stronger than anticipated data had been essentially wagered on since the second week of March by financial institutions. Powell’s speech acknowledging the Fed will find it difficult to cut the Federal Funds Rate in the mid-term (and probably at best not until late this summer) simply verified Forex positions which had already been taken by large players who could afford to make mid-term wagers.
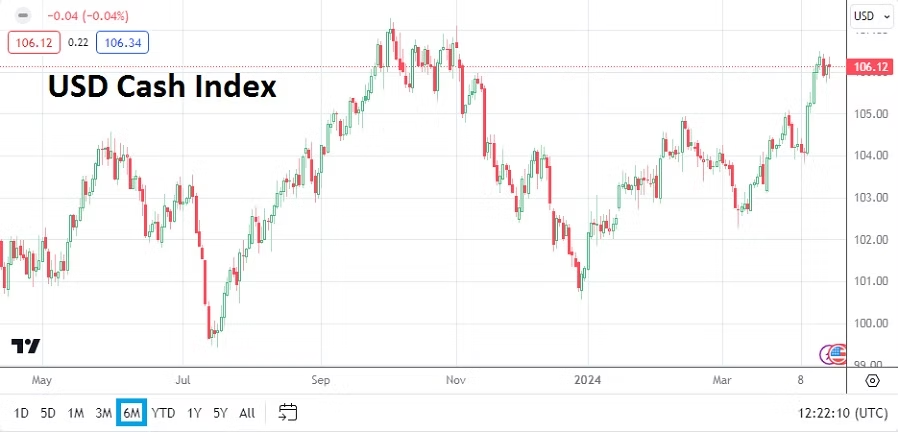
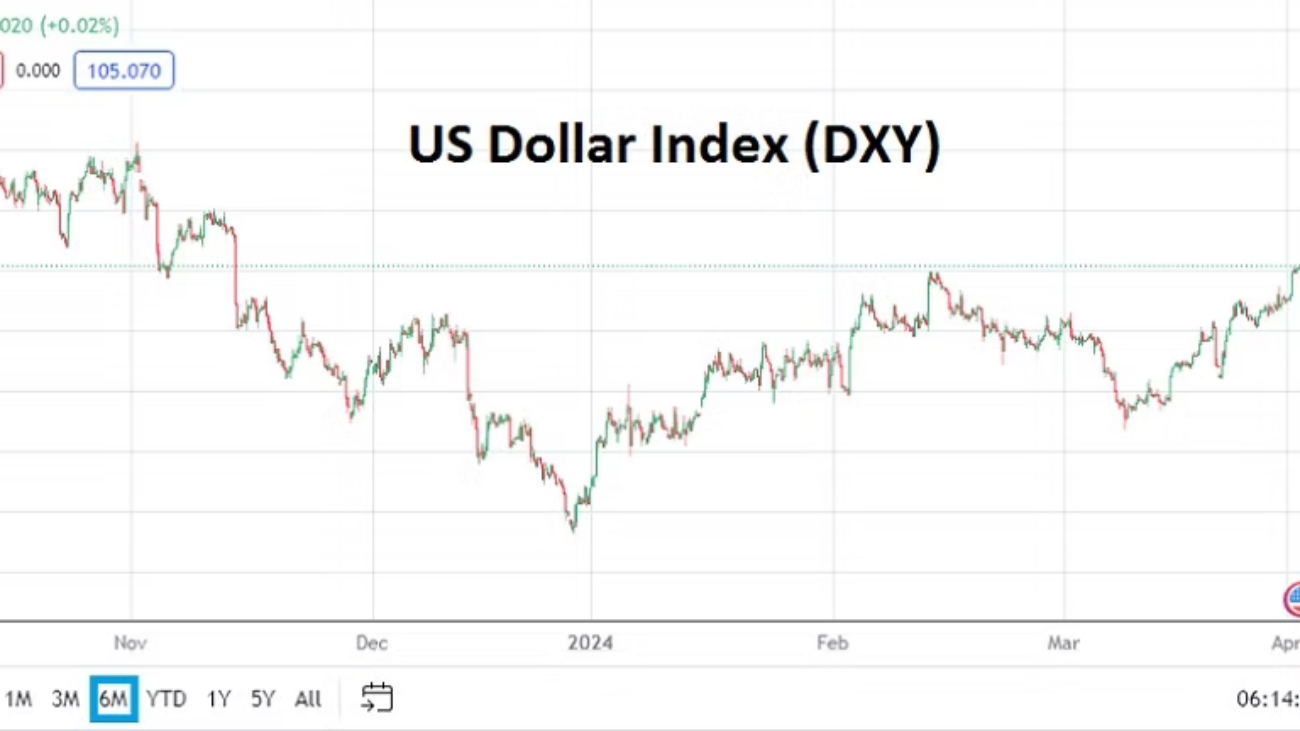
The USD Index has returned to early November 2023 values, and appears able to challenge late September and October prices if inflation data this week causes more volatility, which should put traders of major currencies like the GBP, EUR, JPY and others on full alert. After the USD spiked higher from the 10th to the 12th of April, Forex speculators have seen dynamic action incrementally flirting with stronger USD results the past week and a half.
USD Cash Index Six Month Chart as of 21st April 2024
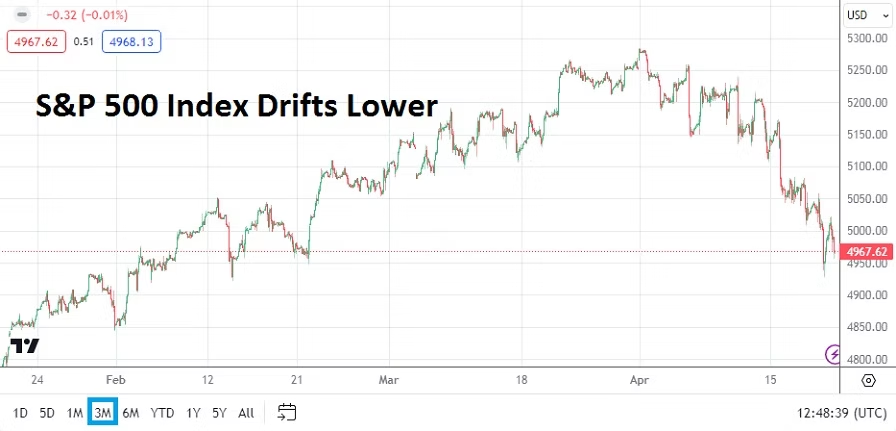
Nervous trading continues to be seen in U.S equity indices. The Dow 30 and the Nasdaq 100 are fighting near ratios they touched in the last week of January. And the S&P 500 is traversing ground from the first week of February.
S&P 500 Three Month Chart as of 21st April 2024
Content
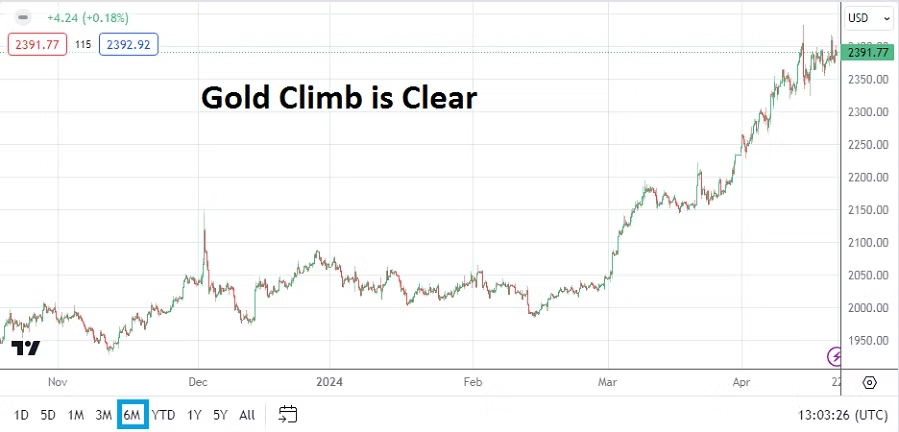
Gold Six Month Chart as of 21st April 2024
Gold remains speculatively high as its hovers near 2,400.00 USD per ounce. The price of the precious metal has not given back its gains made since the start of March and this is intriguing because of the ‘known’ USD inverse correlation, which had proven to work well with the precious metal over the past couple of years but has been stopped in its tracks for the moment. Technically Gold may look overbought, but geopolitical concerns and the prospect that some central banks may be strong buyers could be fueling the rather incremental gains. Retail traders of Gold need to be careful because price action is likely to produce more surprises.
Forex has been turbulent the past handful of months as shifting behavioral sentiment has created choppy conditions. This coming week contains large fundamental risk events via data releases traders should monitor. USD/JPY speculators will also have to contend with the Bank of Japan.
Monday, 22nd of April, China Loan Prime Rates – borrowing costs are anticipated to remain at the current benchmarks. China produced slightly better Gross Domestic Product results last week, but Industrial Production numbers were weaker. Consumers in China remain burdened by decreasing home values and concerns about the economy.
Tuesday, 23rd of April, European Union and U.K Manufacturing and Services PMI – E.U results via the PMI readings are expected to show slight improvements. However the readings from the United Kingdom are anticipated to come in flat. The EUR/USD and GBP/USD will be affected by the results, but the currency pairs will likely remain focused on U.S data later in the day.
Tuesday, 23rd of April, U.S Purchasing Managers Index – the Manufacturing and Services sectors are expected to produce slightly better readings than the previous month. These results will be interesting taking into consideration the Empire State Manufacturing Index numbers last week were bad. The PMI statistics will provide some impetus to the broad Forex market.
Wednesday, 24th of April, Australia Consumer Price Index – inflation data is anticipated to be higher than the previous month’s results. While stronger inflation is not something that will make consumers happy in Australia, stubborn price results may keep the AUD/USD slightly steadier. The currency pair is traversing values last seen in the second week of November 2023 as of this writing.
Thursday, 25th of April, U.S Advance Gross Domestic Product and Price Index – these numbers are certain to have an impact on all financial assets. A decline in growth is anticipated in the U.S compared to the previous month’s result, but the Price Index is expected to show an increase. Jerome Powell having come out last week and said inflation is causing uncertainty within the Federal Reserve, may have a bit of inside knowledge regarding this GDP inflation number and ‘tipped his hand’. If this inflation gauge is higher than anticipated it could pour fuel onto the already volatile USD. All Forex traders need to pay attention to these results and be prepared with solid risk management.
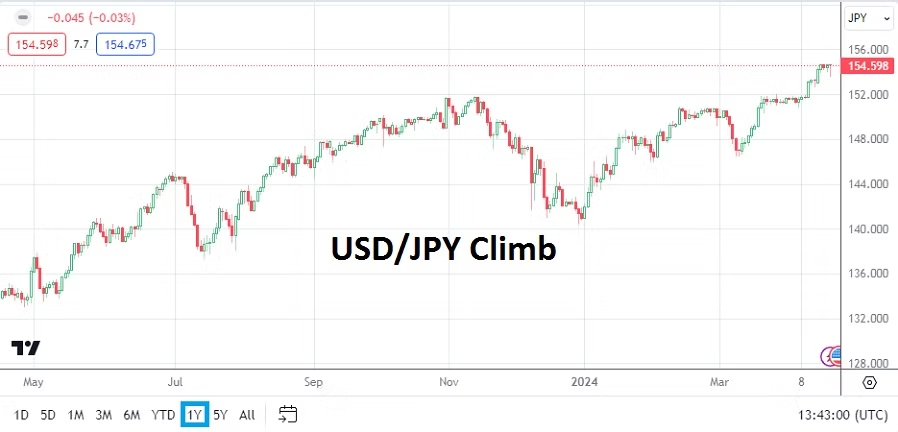
USD/JPY One Year Chart as of 21st April 2024
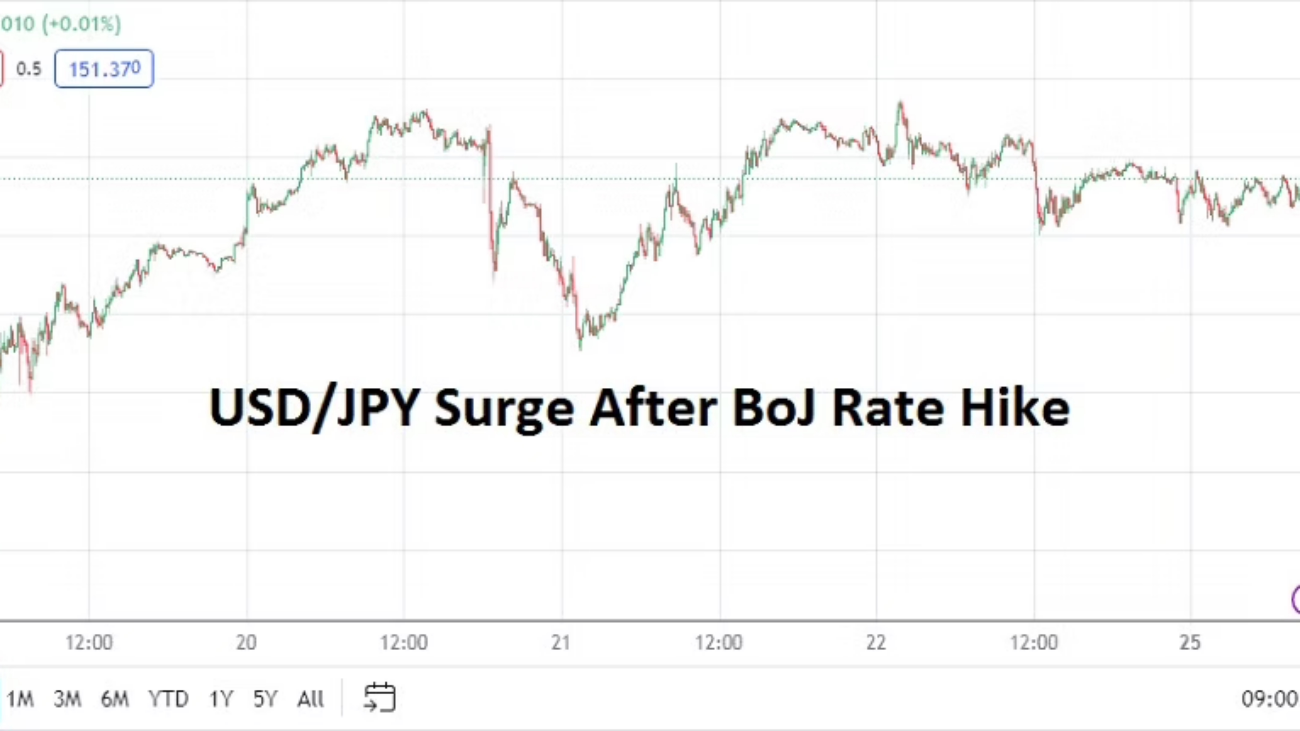
Friday, 26th of April, Bank of Japan – in what has already proven to be a couple of weeks filled with drama for the USD/JPY, the BoJ will step into the limelight. During their last central bank meeting the Bank of Japan increased the Policy Rate to 0.10%. It was the first time the BoJ hiked interest rates in 17 years. The USD/JPY is trading at values last seen in June of 1990. The Nikkei 225 has come off of recent record heights, but the famed Japanese stock index is also trading within territory seen in January of 1990. Business activity via the Core Machine Orders and the Tertiary Industry data last week were stronger than anticipated.
The Bank of Japan may want to maintain a weaker USD/JPY equilibrium to continue fostering domestic growth. However, many financial analysts have been calling on the BoJ to become more hawkish regarding monetary policy. The interest rate decision is certain to cause immediate volatility before and after the Policy Rate is made public. USD/JPY traders need to be prepared for fireworks. A slight raise of the interest rate seems to be needed, but after the March hike the BoJ may prove conservative again. The 34 year lows now being seen in the Japanese Yen are astonishing.
Friday, 26th of April, U.S Core PCE Price Index, and Inflation Expectations – the data from the government, and the reading from the University of Michigan will close the curtain on a big week of economic statistics for all traders. The USD will react to these outcomes. It should be noted the previous Inflation Expectations data from the University of Michigan caused a storm in Forex when it came with 3.1% gain.
Retail Traders Caught Out by Shifting Sentiment as Data Hits
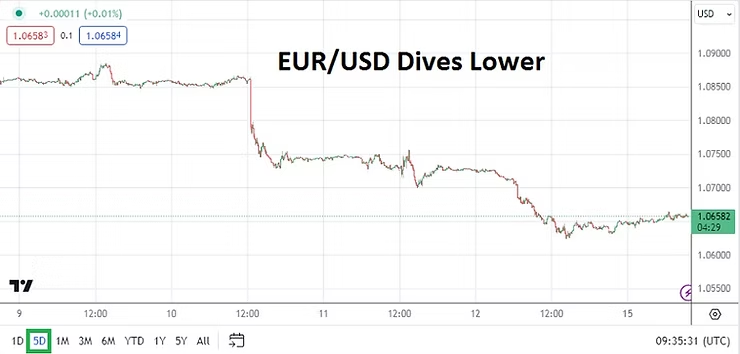
Forex speculators who relied heavily on technical data solely last week were likely punched in the gut by the rather surprising numbers from the Consumer Price Index results in the U.S last Wednesday, particularly if they were on the wrong side of trading trajectories. U.S inflation has shifted sentiment within many large investors with a rather seismic move regarding mid-term outlooks. Financial institutions which have been counting on cuts to the Federal Funds Rate have had to take a step backwards.
EUR/USD Five Day Chart as of 15th April 2024
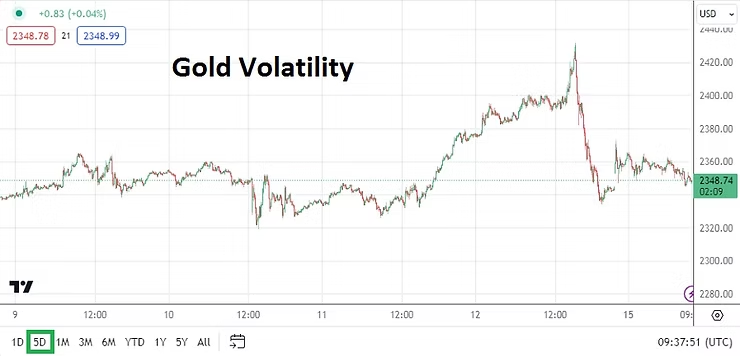
The dynamic momentum in Forex hit major currency pairs in the middle of last week and washed away support and resistance levels within a blink of the eye. Behavioral sentiment turned U.S Treasuries yields upwards and the major equity indices also experienced nervousness. Volatility also continued in Gold as new record values were produced, and then were followed by a rather strong reversal lower which likely hurt over-leveraged day traders.
Gold Five Day Chart as of 15th April 2024
Not only were U.S inflation numbers important last week, but geopolitical noise became heightened. Perhaps the climb in Gold before the weekend was helped by the anticipated conflict between Iran and Israel which did play out. The price of the precious metal and WTI Crude Oil have been more tranquil early today, which may be a signal for the moment that large market players are calm.
Monday, 15th of April, U.S Core Retail Sales – after last week’s larger than expected increase in the CPI results, the spending report today will get attention from financial institutions. Last Friday’s Preliminary Price Expectations reading from the University of Michigan did not allow investors to rest when it came in with a 3.1% elevated mark. If today’s Retail statistics are above expectations, this could make Forex roil again.
Tuesday, 16th of April, China Industrial Production and Gross Domestic Product – these economic reports will be watched closely by international investors. While there have been murmurs that China’s economy is improving, and media reports that the Biden administration is trying to engage diplomatically, the industrial and GDP results are expected to be weaker than the previous month’s outcomes. China will also release Retail Sales figures.
GBP/USD Five Day Chart as of 15th April 2024
Tuesday, 16th of April, U.K Claimant Count Change – last Friday’s GDP report from Britain did not produce any significant surprises. The U.K economy continues to struggle, but like most spheres inflation remains a problem. The GBP/USD sunk violently last week, while many speculators may believe it is currently oversold they may want to remain cautious.
Because of the U.S Federal Reserve’s own perilous fight against inflation, there are some who believe the Bank of England may need to cut interest rates before the U.S central bank. However, given the lack of proactive characteristics from the BoE and ECB which have been on full display as they dance in step with the Federal Reserve, this makes a BoE cut before the Fed a skeptical notion for the time being. The GBP/USD will stay largely USD centric even in the wake of this U.K employment report.
Tuesday, 16th of April, U.S FOMC Members – a parade of Federal Reserve voting policymakers will speak at various events, this includes Fed Chairman Jerome Powell. There will likely be little in the way of surprises from the Fed members as they likely all stick to ‘party’ lines and emphasize a cautious outlook.
Wednesday, 17th of April, U.K Consumer Price Index – the inflation report could prove to be catalyst for the GBP/USD. If the CPI number does come in weaker than expected it could spur on behavioral sentiment shifts regarding the potential for changes to BoE policy. Because the GBP/USD was so volatile the past week, day traders should be prepared for rather combustible price action from the currency pair which may look counter-intuitive. Smaller speculators should remember that ‘smart money’ from larger players may be positioned for the results of the U.K CPI data already.
Thursday, 18th of April, U.S Weekly Unemployment Claims – although not the most significant of reports usually, financial institutions are ‘waiting’ on a change of statistical direction via labor market evidence. If jobs numbers start to come in weaker than anticipated – meaning there are higher jobless claims – then the USD could react with some selling.
Friday, 19th of April, U.K Retail Sales – having endured a rather wild trading cycle, Great Britain will deliver one more important economic report to end this week. The GBP/USD will react to the consumer spending results.
AMT Top Ten Miscellaneous Wonders for the 12th of April 2024
10. Free Press: Brazil and the Lula de Silva government are cracking down on dissent in social media. ‘X’ – formerly Twitter – led by Elon Musk is fighting back and refusing to cooperate as Brazilian ‘leadership’ attempts to intimidate the ‘loyal opposition’ in the legislature.
9. GROOT: Nvidia is working on ‘humanoid’ robotics. Project GROOT was presented by Jensen Huang at the GTC Conference. The synergy between machine learning, semiconductors and robotics is an evolution taking place before our eyes. Tesla is involved in similar research as it works on Optimus.
8. Hot Chocolate: Speculation in Cocoa has brought the commodity above 10,400.00 USD per metric ton as of this writing. Questions about gravity and hypersonic speculative values are logical at this juncture.
7. Seclusion: Do humans still need each other? People are relying on their mobile devices for social interactions. Robotics with AI capabilities will make our existence potentially more lonely. Open source software DOBB-E will be part of this future as household chores are taken care of by ‘machines’.
6. Iran: Those with holiday excursion plans which include Teheran this weekend may need to check on ticket availability due to the possibility of flight cancellations.
5. Fed Liberty: President Joe Biden this week spoke about an interest rate cut coming from the Federal Reserve this year, yet Consumer Price Index statistics are demonstrating escalating expenses. Current U.S government leaders may want to spend less on ‘vote buying’ via student loan forgiveness and think about conservative fiscal practices. Why should Americans who choose not to attend universities pay for those who did via higher taxes? Are Fed and Treasury officials still independent?
4. Risk Averse: Gold is within sight of 2,400.00 USD this morning. In the meantime U.S bond yields have inverted completely except for the 30-Year issue. Financial institutions are showing nervous behavioral sentiment.
3. USD Centric: Forex has seen reactive trading this week as financial institutions begin to conclude the U.S Federal Reserve’s monetary policy ‘over time’ will remain disturbingly difficult and full of doublespeak.
2. Caution: Mixed results are flourishing in the major U.S stock indices as the Nasdaq 100 and S&P 500 touch late March values, and the Dow Jones 30 has returned to February levels. Higher than anticipated interest rates are causing turbulence.
1. Energy Illusions: As the prices of food, transportation and housing escalates isn’t it time governments start to question their ‘green’ policies which are making the costs of energy production more expensive? We all want a clean planet, but logical strategies must be applied to create efficient use of resources.
USD/ZAR Celebratory Parade Should be Put on Hold Awhile
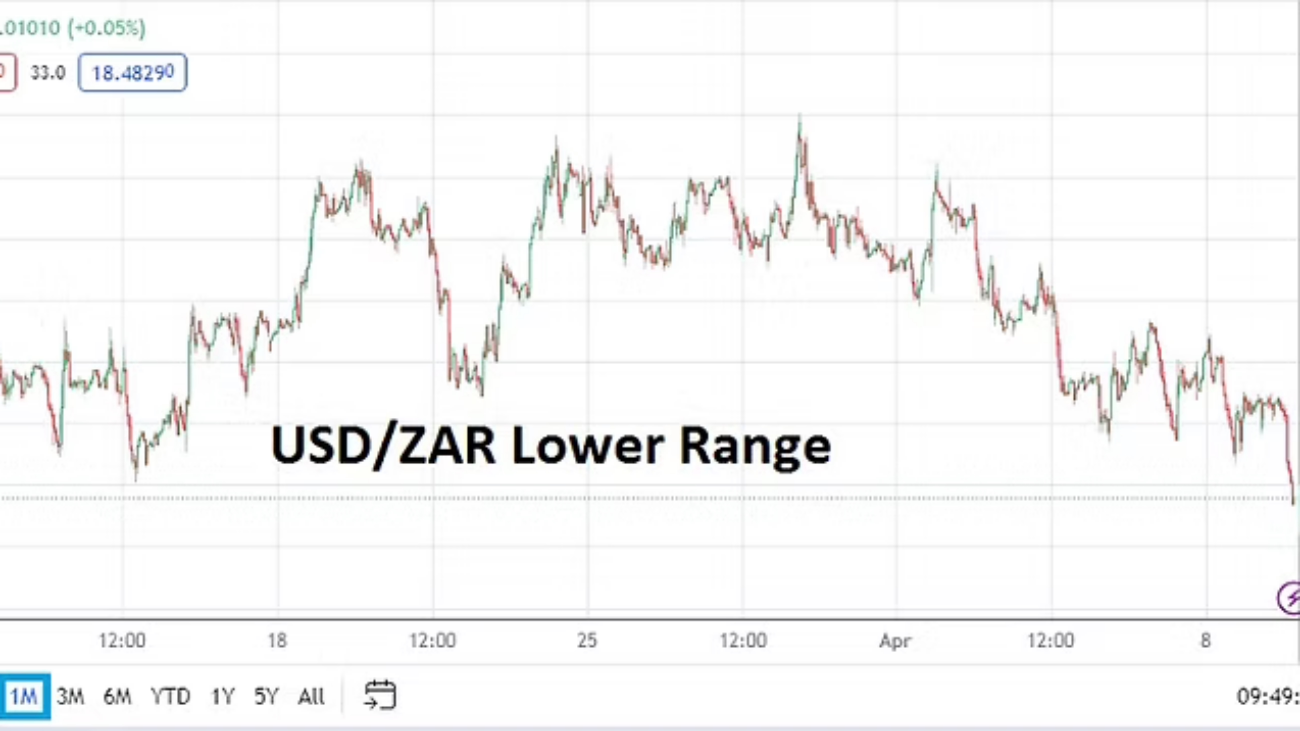
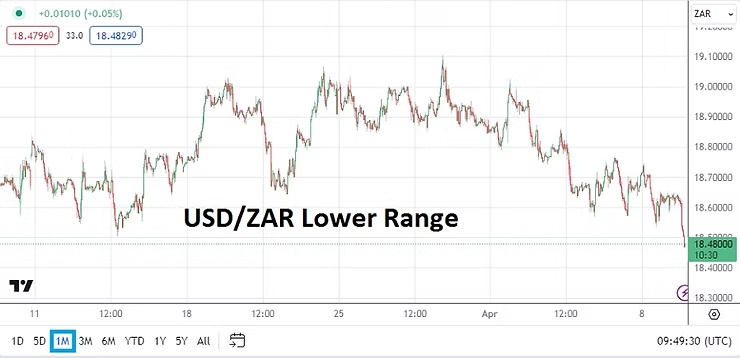
The USD/ZAR has produced a solid downward turn since the 1st of April when the currency pair was trading above 19.00000.
The value of the USD/ZAR as of this writing is near the 18.48000 mark as the currency pair fluctuates within Forex. The currency pair has produced a solid downturn since the start of April when it was above the 19.00000 level. The ability of the USD/ZAR to suddenly create a streak of bearish trading and make support levels look vulnerable is intriguing, particularly considering USD centric sentiment against many other major currencies the past week and a half has produced very choppy results in the broad Forex market.
The USD/ZAR is now trading at its monthly low via a technical perspective and the currency pair is testing values last seen at the start of January. The ability of the USD/ZAR to suddenly spark selling may be able to be explained because of the higher value of Gold which is trading at record prices while traversing near 2,360.00 USD currently. Mining makes up roughly 8% of the Gross Domestic Product value for South Africa.
USD/ZAR One Month Chart as of 9th April 2024
However, before a party is launched to start celebrating the reemergence of the South Africa Rand, traders should note the USD/ZAR was trading within its current value range on the 14th of December. Thus the South African Rand is simply taking up residence like many other major currencies including the GBP and EUR within known prices they were valued, when the U.S Federal Reserve ‘changed’ its monetary policy stance on the 13th of December to a more dovish outlook.
The choppiness within the USD/ZAR has been rather extreme over the past few months. On the 28th of December the USD/ZAR was trading near the 18.26000 ratio briefly, on the 23rd of February the currency pair was near the 19.40000 mark and testing values which had been last seen in October of 2023. While the price of Gold is at record values now, the worth of the precious metal might be a false correlation to the USD/ZAR, and technical traders may want to watch the currency pair’s support levels below as a place that reversals higher could be sparked.
U.S Data and Concerns in South Africa Regarding the Election
The U.S will release important inflation data on Wednesday and Thursday. Last month’s Producer Price Index numbers from the States sparked a wave of volatility in Forex and the USD/ZAR was not immune. The bearish cycle in the USD/ZAR has been noteworthy, but fundamental doubt exists regarding its ability to sustain lower price momentum. The U.S Federal Reserve does not appear any closer to cutting its Federal Funds Rate.
There is also a political shadow regarding South Africa elections. The nation’s vote will take place on the 29th of May. The results potentially could create instability and the need for a coalition government which may be difficult to attain without signing off on more costly social policies which the South African government cannot easily afford fiscally.
USD/ZAR Short Term Thoughts:
· The 18.46000/18.47000 support levels in the short-term may cause reactions if challenged.
· Traders are urged not to be overly ambitious, particularly if they still want to pursue downside in the USD/ZAR, the use of take profit and stop loss orders is appropriate.
· Current price levels may spark volatility if financial institutions feel the price of the USD/ZAR has become unbalanced.
Forex: Behind the Curtain as Speculative Deja Vu Strikes
Friday jobs reports came in stronger than anticipated on the surface, and this led to a roller coaster like ride for Forex traders as results were acted upon by financial institutions. However, a look behind the data shows ‘positive’ results were spurred on by part-time hiring and government influences leading to a notion that jobs numbers were not exactly a ray of sunshine regarding U.S economic health. The suspicious results cause a desire to look for ulterior motives, and to wonder if election year politics are playing a role in the U.S employment picture.
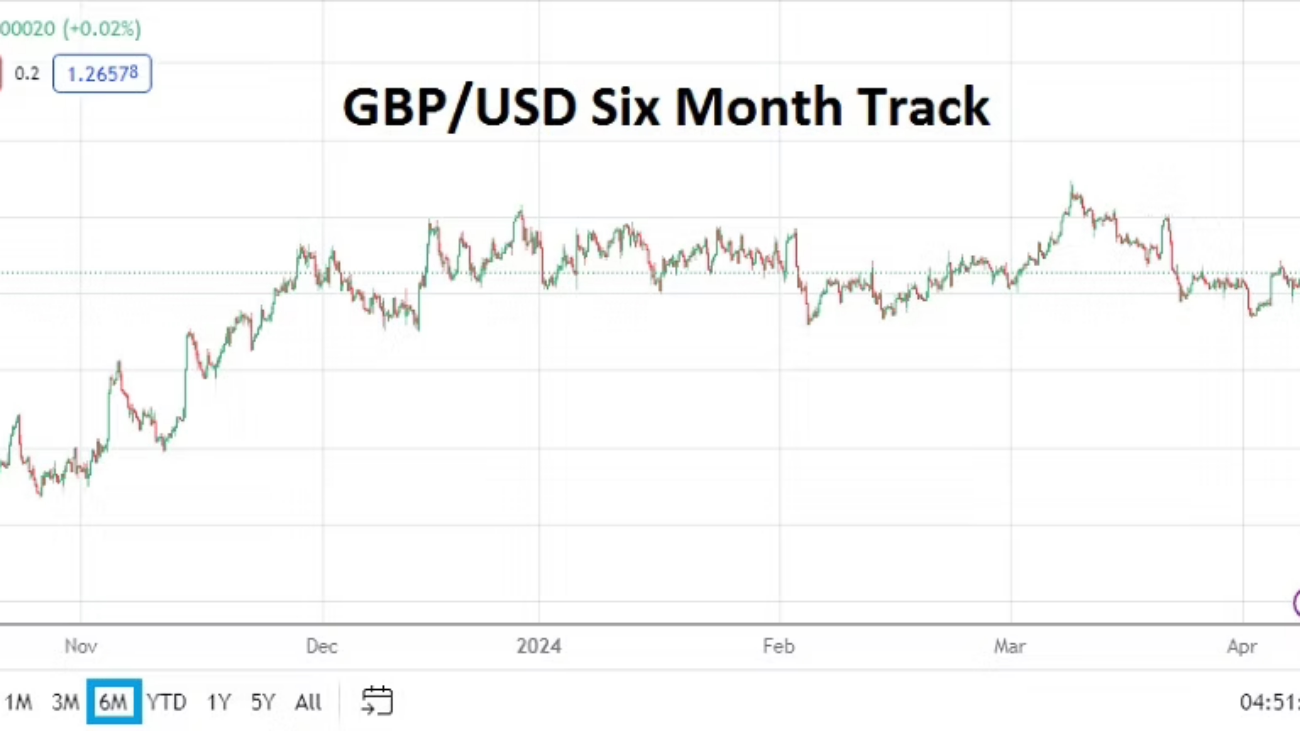
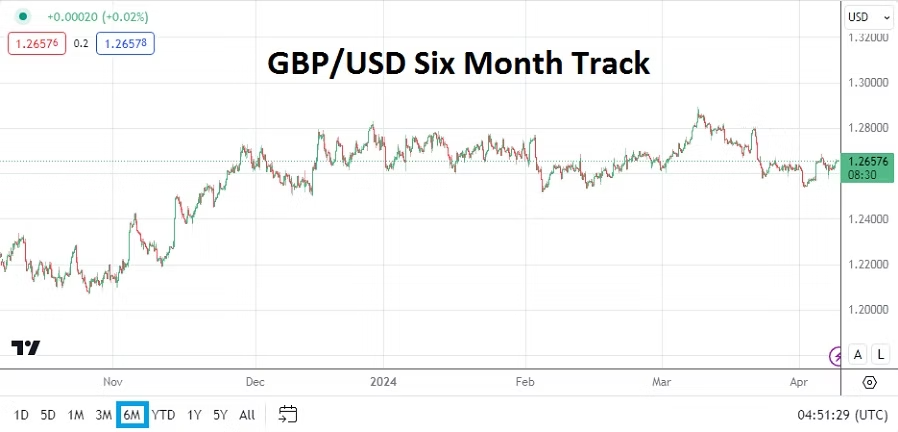
GBP/USD Six Month Chart as of 9th April 2024
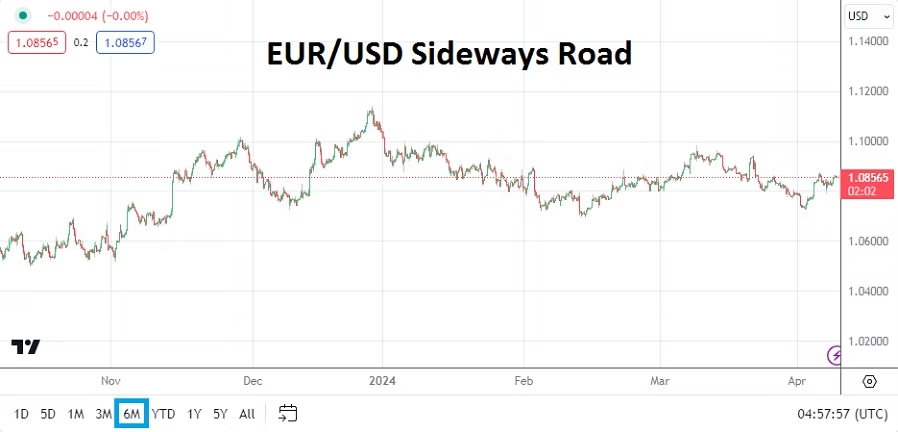
The GBP/USD and EUR/USD are rather insightful for technical and fundamental traders. The currency pairs are languishing as of today’s values near pricing that was seen in the second week of December. Since the ‘announcement’ from the U.S Federal Reserve on the 13th of December that a change in monetary policy would begin to occur in 2024, in actuality nothing has really happened, except government ‘speak’ trying to sound as if everything is understood and in control, while it is clearly not.
Economic data from the U.S and Europe has continued to be soiled by mixed results, and retail speculators looking for a trend to emerge have had to deal with choppy conditions. Financial institutions remain unclear about interest rate outlooks. The Fed while trying to ‘sound’ dovish rhetoric remains locked within a Google engine keyword mantra as they mutter the phrase ‘over time’ when trying to convince people that interest rates will ‘eventually’ be cut.
Last week leading up to the Non-Farm Employment Change numbers, many FOMC members were offering cautious tones about the Federal Funds Rate and warning it should not be changed yet. The implication of the Fed’s verbiage could lead some to suspect they have all practiced statements handed to them by their overlords who are concerned this is an election year and jobs are in jeopardy.
EUR/USD Six Month Chart as of 9th April 2024
Which leads us back to Forex and all financial assets, as investors try to swim waters which have left fundamental perspectives grasping at data which is not easy to decipher. U.S government policy is practicing fiscal spending that is causing massive debts, and perhaps influencing hiring data which may be more akin to putting lipstick on a pig. Many U.S voters seemingly lean towards electing officials who promise to hand out the biggest ‘social rewards’, while ignoring there will be a price to be paid down the road.
The Federal Reserve in the meantime tries to sound optimistic about inflation eroding, but concerns due to U.S government debt being accrued, and global geopolitical affairs combined with energy policy which is making it more expensive to maintain cheap transportation, efficient agriculture and manufacturing, shadow the Fed’s hopes. WTI Crude Oil remains over 86.00 USD per barrel. Gold is trading at record high values and above 2300.00 USD. Does anyone see the dangerous connections? Equity indices should be watched as a barometer this week.
USD/JPY Six Month Chart as of 9th April 2024
Monday, 8th of April, Japan Average Cash Earnings and Economic Watchers Sentiment – yesterday’s reports matched expectations regarding wages, but workers surveyed noted their concerns about incremental inflation which is being seen in Japan. The USD/JPY is challenging November higher values and the Bank of Japan has been widely criticized for not raising interest rates more aggressively. However, it is possible the BoJ wants the Japanese Yen to remain within its weaker price range to spark a stronger Japanese economy via exports.
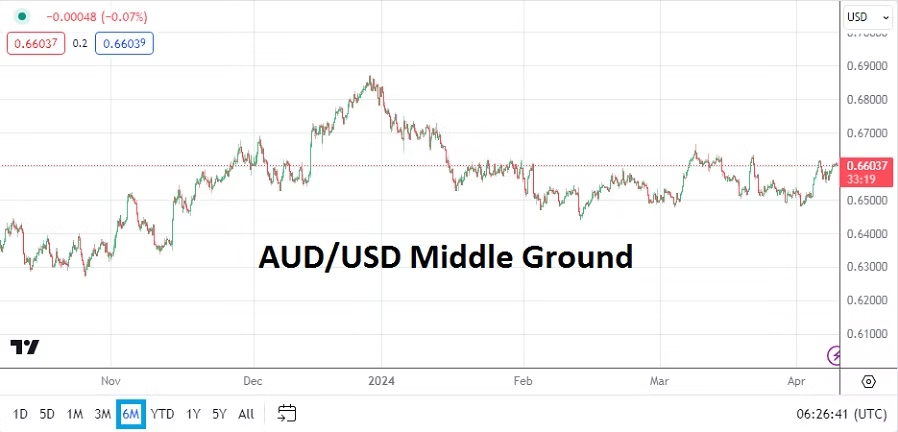
AUD/USD Six Month Chart as of 9th April 2024
Tuesday, 9th of April, Australia Westpac Consumer Sentiment – the results via the consumer reading came in negative. The AUD/USD like the GBP/USD and EUR/USD is traversing values tested in the second week of December 2023, leading to the feeling of deja vu.
Wednesday, 10th of April, U.S Consumer Price Index – you have heard this before, the inflation reports from the States are going to rattle the financial markets including Forex. The USD is certain to react. Data from the U.S has produced surprises aplenty in the past few months. The Consumer Price Index is important and day traders certainly need to pay attention.
Thursday, 11th of April, European Central Bank – the ECB is not expected to change its Main Refinancing Rate, but many analysts believe they should cut borrowing costs. However, the ECB will likely remain within the camp of choosing to ‘wait and see’. The ECB Press Conference with Christine Legarde has widely become regarded as an opportunity for political speech as much as an economic dialogue. Recent data from the European Union suggests the worst of the recessionary cycle is gone, but German Trade Balance numbers released on Monday were negative, highlighting hurdles remain. Inflation is a worry, and a cut to the interest rate might be able to help spur on economic activity while counting on lagging data to prove proactive policy should be implemented. But this likely is not going to happen and the EUR/USD will remain problematic.
Thursday, 11th of April, U.S Producer Price Index – these slew of reports should be watched carefully. If the data is stronger than expected it is likely a part of the residue caused by higher energy costs that have affected logistics and created more expensive raw materials which are needed to produce goods. It was the higher PPI reports last month that caused dramatic tidal shifts in Forex, speculators should brace for the potential of additional mayhem.
Friday, 12th of April, U.K Gross Domestic Product – last month’s GDP numbers from Great Britain came in slightly higher than expected with a 0.2% gain, this report is anticipating growth of only 0.1%. Traders should take a deeper look at the statistics upon publication and check for revisions to past months. The U.K economy has been struggling, the ‘growth’ results will affect the GBP/USD before going into the weekend.
AMT Top Ten Miscellaneous Postings for the 5th of April 2024
10. Petrichor: The pleasant smell after a rain has fallen following a long dry spell which elicits earth’s fragrance. The Fed is likely hoping for this sensation via ‘weaker’ Non-Farm Employment Change numbers today. In December the Federal Reserve spoke about data signals needed in order to cut interest rates. If jobs statistics are stronger than anticipated, there will be no ‘petrichor’ for the Fed.
9. Underreported: Five engineers from China on their way to work for the Dasu dam project they participated, were killed in a ‘suicide’ terrorist attack in Pakistan on the 26th of March. Terror attacks in Pakistan on Chinese involved with infrastructure ‘Economic Corridor’ work have been increasing.
8. Qubits: Microsoft and Quantinuum recently announced they have made breakthroughs regarding quantum computing research reliability. Results have shown 14,000 ‘test routines’ without errors. The emergence of quantum technology approaches.
7. Intrinsic Value: Cocoa is near 9640.0 USD per metric ton as of this morning and remains speculatively energetic. Bitcoin is slightly below 67,000 USD and continues to ‘beat’ the notion that intrinsic value is important.
6. Precious: Gold prices have ‘fallen’ below 2300.00 USD per ounce, and is near 2289.00 for the moment, but the metal is shining as crowds admire its ability to create a safe haven.
5. WTI Crude Oil: Middle East news is rumbling and hyperbole is resonating, the price of the commodity is over 86.40 USD per this writing. A calm weekend, and peaceful end to Ramadan this coming Tuesday might help calm nerves. Higher oil prices will not help global inflation.
4. Forex: The USD/JPY has started to experience waves of volatility and has recently challenged long-term highs. Bottom line is the notion that large players are positioning for today’s U.S data which will affect all financial assets as USD centric power resounds.
3. Equities: The U.S major stock indices are beginning their day near lows not seen since the 15th of March for the Dow 30, and the 19th of March for the S&P 500 and Nasdaq Composite. Nervous?
2. Bonds Watch: U.S Treasuries need to be monitored as the 5, 7, and 10-Years Notes respond to nervous investors and fears of a new ‘inversion’. Having come off of high yields a couple of days ago, doesn’t mean all is well as values languish near late September 2023 technical realms.
1. Data: Recent chatter from many Fed FOMC members have created anxious investors. Vivid reactions will occur after the Non-Farm Employment Change and Average Hourly Earnings. Bluntly, today’s jobs reports are crucial and the Fed would like the results to be weaker than anticipated in order to consider cutting interest rates. However, if hiring comes in stronger, it would be a sign of a resilient U.S economy and would ignite more USD strength. The first half hour following the jobs numbers may look counter-intuitive regarding price action as financial institutions adjust their trading positions.
USD and the Fed: Parade of Jobs Data Ready to Make Noise
U.S data last week created landmines for Forex speculators and the Federal Reserve. Global financial markets return to full action today following the long holiday weekend. Growth and inflation numbers from the States last week provided more unsettling results for financial institutions. While Forex has proven difficult for many traders, the major equity indexes are flirting with highs but also running into some intermittent headwinds.
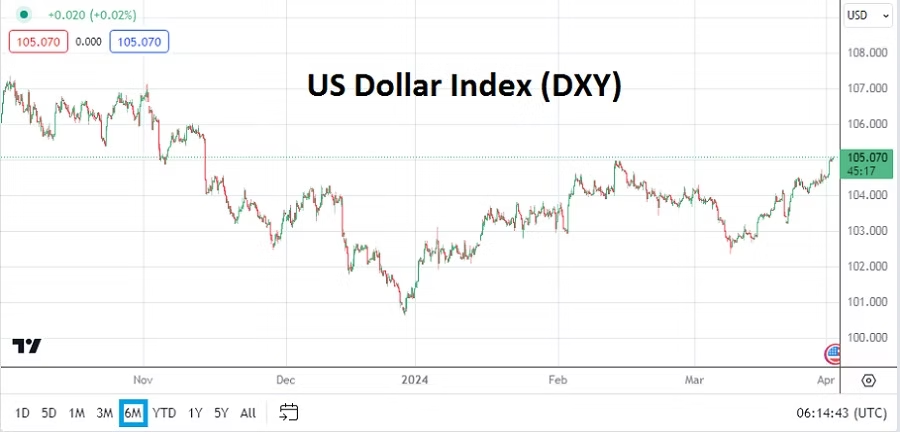
US Dollar Index Six Month Chart as of 2nd April 204
In December of 2023 the Fed was interpreted as having confirmed it would be able to cut the Federal Funds Rate during the 2024 calendar year rather consistently. Dovish policy had been anticipated by financial institutions which began to sell the USD aggressively in November. But by the end of the Christmas week the USD had essentially hit lows in many major currency pairs, and as January started reversals intensified.
The last three months of trading has produced choppy conditions in Forex, but one thing is clear – financial institutions no longer believe the Federal Reserve will be able to aggressively cut the Federal Funds Rate. The Fed has now begun to show signs that it is nervous regarding U.S economic data, this as growth via GDP numbers has remained firm, inflation sticky, and consumers resilient. Clouds shadow Forex and day traders have been hampered by a lack of solid trends.
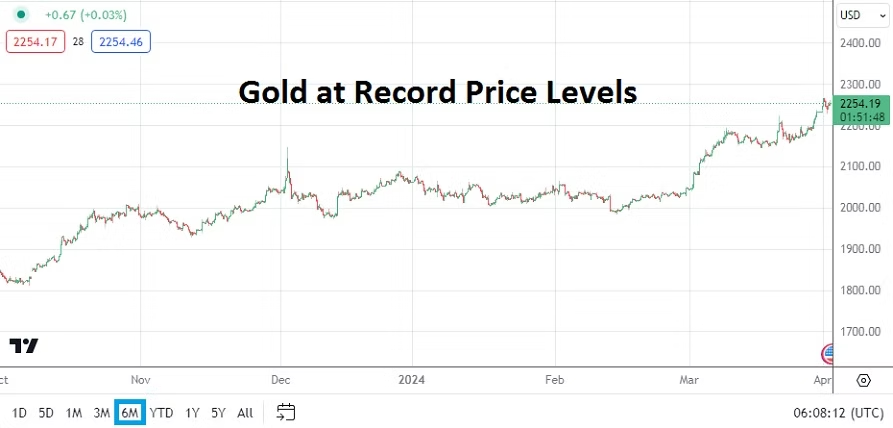
Gold Six Month Chart as of 2nd April 2024
Gold is trading near record price levels. The fact that the precious metal is touching all-time values as the USD has been strong has flustered some speculators. But traders need to remember Gold is affected by large players, including nations, that may be hedging USD bets and preparing for political instability. The price of Gold may underscore belief the U.S Fed will have to cut rates at least a couple of times this year no matter the economic facts on the ground, because this is an election year and if the central bank doesn’t deliver on its ‘promise’ jobs at the Fed may be at stake.
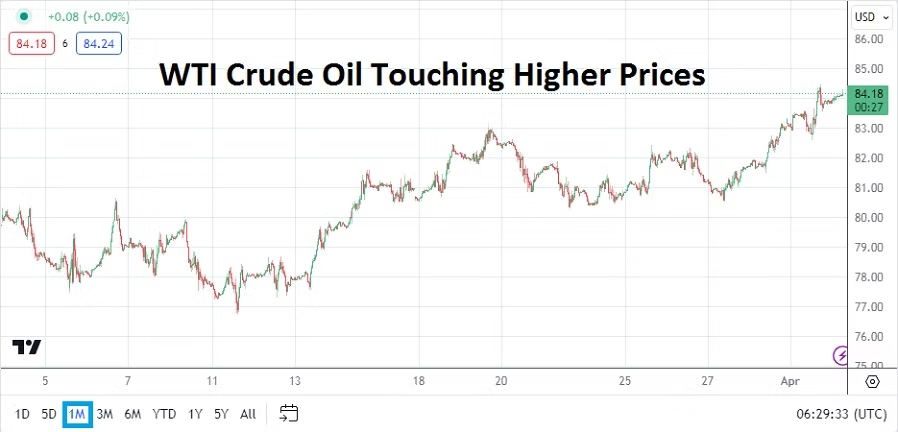
WTI Crude Oil One Month Chart as of 2nd April 2024
Not making anything easier for Federal Reserve policy is the higher price of WTI Crude Oil which has reached the 84.00 USD per barrel price. If energy costs go higher this will not help the fight against inflation. OPEC will be conducting a meeting this week. As an aside the price of Cocoa per metric ton is now over 10,000.00 USD, which is more expensive than Copper. While the price of Cocoa is not a game changer for global financial markets, the higher price will make chocolate more expensive, which some traders may find disagreeable as they try to relax and watch their speculative wagers while trying to nibble on their favorite snack.
Monday, 1st of April, U.S ISM Manufacturing – both the Purchasing Managers Index reading and the Price numbers came in higher than expected. The stronger results show the U.S economy remains better than anticipated by the Federal Reserve, which has been counting on its higher interest rate to slow down growth and inflation.
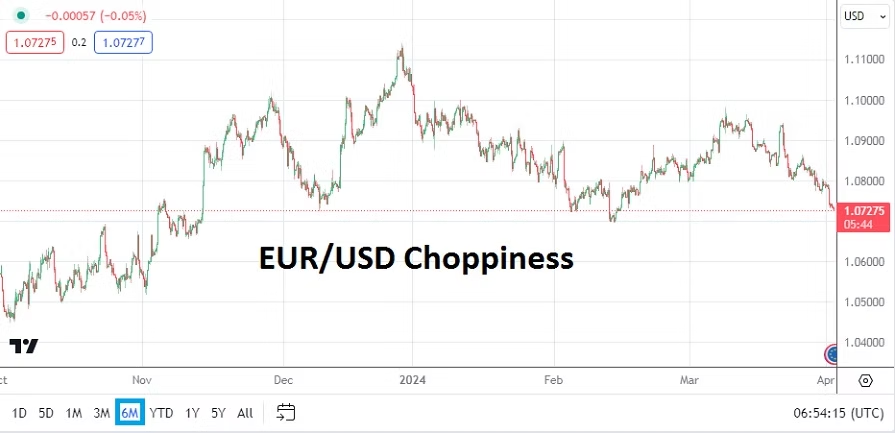
EUR/USD Six Month Chart as of 2nd April 2024
Tuesday, 2nd of April, European Manufacturing PMI – the European Union and Great Britain will release their business readings today. The results will demonstrate insights regarding sentiment. Financial institutions are worried the European Central Bank and Bank of England may have to consider lowering their interest rates before the Federal Reserve. The EUR/USD and GBP/USD will react to the results.
Tuesday, 2nd of April, U.S Federal Reserve FOMC Members – there will be appearances throughout the day in the U.S from various Federal Reserve members who will make the case for their monetary policy outlooks. It should be noted that Jerome Powell will be speaking on Wednesday. The JOLTS Job Openings will come out before the FOMC members speak. While the JOLTS report will not cause earth shattering reactions, the jobs data is the beginning of the parade regarding employment statistics for this week.
Wednesday, 3rd of April, U.S ISM Services PMI – taking into account the Manufacturing report came in stronger than expected on Monday, the Services data will be watched by financial institutions. If this report is better than anticipated, USD sellers will not rest easy. The ADP Non-Farm Employment Change data will also be released on this day.
Thursday, 4th of April, U.S Weekly Unemployment Claims – the Federal Reserve has been counting on employment strength to erode based on their notion that higher interest rates would create ‘lagging’ reactions in the jobs sector. Jerome Powell has said the Fed is anticipating weaker employment data. The results from the weekly report will not be as significant Friday’s data, but should be given attention by day traders in Forex.
Friday, 5th of April, U.S Non-Farm Employment Change and Average Hourly Earnings – the climax for speculators this week will be these jobs numbers from the States. If the numbers produce less hiring than expected this would help USD bearish momentum. Wages will also prove crucial regarding behavioral sentiment for financial institutions. Simply put, the Federal Reserve is anticipating that weaker employment numbers are going to be seen, if this doesn’t happen it might cause major volatility in Forex going into the weekend.
AMT Top Ten Miscellaneous Musings for the 29th of March 2024
10. Holidays: We wish everyone a peaceful long weekend. Hopefully the price of your chocolate eggs have not emptied your wallets.
9. Superconductivity: Nuclear fusion and magnets have a future together. Efficient electricity produced via compact generation is being worked on by the Massachusetts Institute of Technology and the Jet Propulsion Laboratory of NASA.
8. TMTG: The Trump Media and Technology Group listed as DJT on Nasdaq ended yesterday’s trading within sight of 62.00 USD. The price is overbought taking into consideration its lack of revenues. However, because of its limited available shares, ‘shorting’ DJT is dangerous and a potentially expensive mistake.
7. Silly Season: U.S elections are growing closer and louder. However, fiscal and foreign policy clarity doesn’t get much airtime. Bread and circus for the masses.
6. Crypto ‘Insanity’: FTX Founder Sam Bankman-Fried was sentenced to 25 years in prison yesterday for his crimes. In the meantime, Bitcoin is over 70,000.00 USD this morning. Binance Coin is valued above 600.00 USD.
5. Frothy: Gold is near 2,230.00 USD per ounce, even as the USD grows in strength. Cocoa closed yesterday around 9,792.00 USD per metric ton, meaning it is more expensive than Copper, and the reason why your chocolate may be getting costly.
4. ‘Quiet’ Data: Core Personal Consumption Expenditures Price Index data will be released today in the U.S, this as the financial markets are largely absent. Yesterday’s GDP and Consumer Sentiment numbers were stronger than expected. The inflation statistics may not get much fanfare today, but paying attention to the results could prove worthwhile for speculators.
3. Risk Warning: The return of large trading volumes next week are likely to cause volatility as financial institutions reopen and are reactive.
2. Bias: Many major currencies are struggling against the USD. Traders who believe their chosen currencies have been oversold should contemplate their perspectives and potential bias. Just because you believe something, doesn’t mean it is true. Forex is expressing nervous behavioral sentiment.
1. Fed Watch: Many analysts are starting to believe the Federal Reserve may not be able to cut interest rates this year, but traders should remember politics will be crucial as the U.S Presidential Election approaches. The Fed may be ‘independent’ but they are not deaf. If inflation remains stubborn, the Fed will need weak jobs numbers. But weekly Unemployment Claims came in below expectations yesterday. Financial institutions understand the U.S central bank is in a difficult place.
Forex Volatility and Coming Data Attractions for this Week
Nervous trading results have hurt many day traders and likely financial institutions too, as behavioral sentiment in Forex gets blindsided by rather mixed U.S data and the Federal Reserve not giving a definitive answer regarding monetary policy. The violent trading in the USD last week was expected, but the turbulence that many Forex pairs experienced on Thursday and Friday of last week was rather vicious. For all the perceived sophistication of Forex markets via financial institutions, the trading results last week point to a definite fear of the unknown.
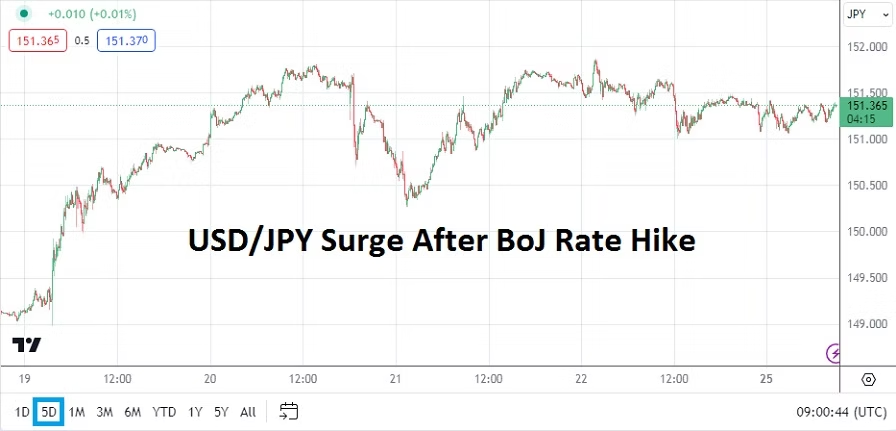
USD/JPY Five Day Chart as of 25th March 2024
While the Bank of Japan finally changed its interest rate policy and moved to a Policy Rate of 0.10% early last week, this did not create selling momentum in the USD/JPY. The Federal Reserve’s dangling of potential interest rates to come this year caused temporary weakness in the USD, but as financial institutions and their clients looked at the prospects for a more dovish Fed they apparently became unimpressed as the days passed.
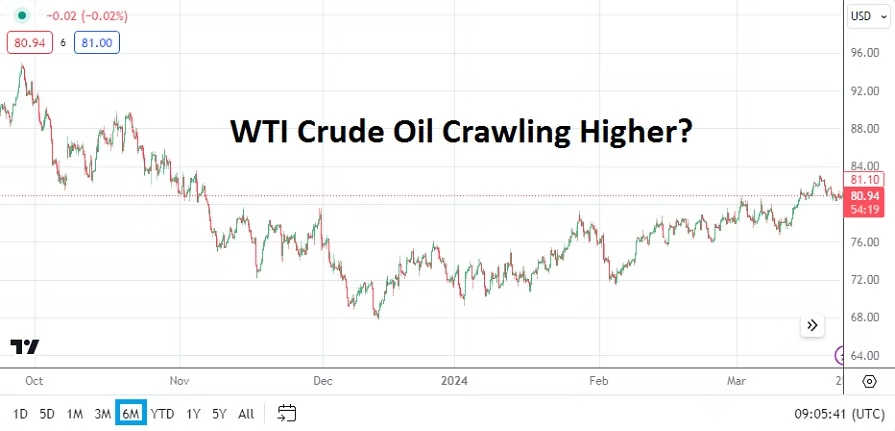
WTI Crude Oil Six Month Chart as of 25th March 2024
The Fed seems to be betting on weaker jobs numbers developing, and there has been data which points to part-time jobs increasing, and full-time jobs becoming harder to find in the States. Jerome Powell said last week that if jobs numbers start to show weakness that the Fed would be willing to begin cutting interest rates even if inflation remains sticky. Lagging economic data correlations have not eased the Fed’s problems.
The Fed has also admitted inflation in housing, transportation and food remains problematic. WTI Crude Oil spent much of last week above 80.00 USD per barrel as its price has begun to show signs of rising incrementally again; and there is little the Fed can do about more expensive energy costs should they be seen. Higher costs for logistics will not make anything cheaper. Pricier mortgages, more expensive rent and insurance rates for cars and gasoline is creating serious knock on effects.
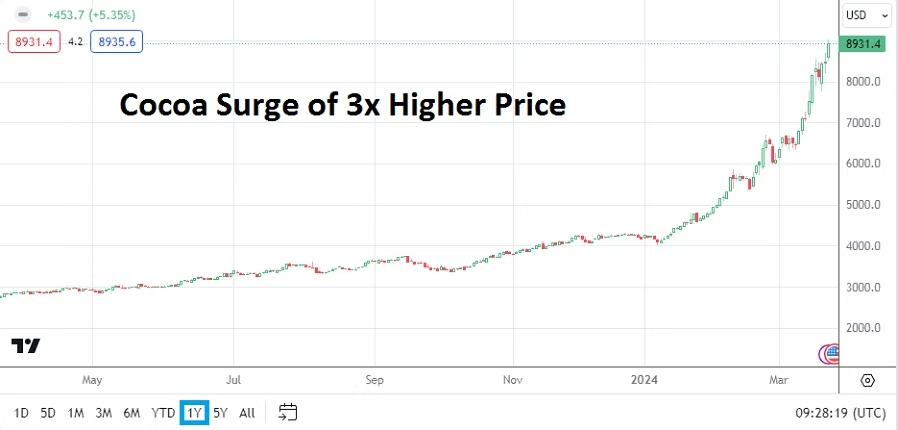
And for the sake of acknowledging the screaming prices in Cocoa, please have a look at the chart below which should explain why your chocolate products are going to be more expensive in the coming months. The price of the most delicious commodity in the world has tripled in less than a year’s time and is around 8931.0 USD per metric ton as of this writing.
Cocoa One Year Chart as of 25th March 2024
Gold turned in a violent week of trading too as it reached 2224.00 last Wednesday, only to fall back to a known value around 2165.00. Day traders are dealing with violent cycles in Forex because sustained trends have been nearly impossible to find. While U.S equity indices are fighting upwards, speculators who are afraid of heights are likely being cautious if they are betting merely on the daily results from the S&P 500, Nasdaq 100 and Dow Jones 30 instead of investing for the long-term.
This week’s coming data from the U.S is important, financial institutions are already dealing with plenty of noise, and they will have to be careful regarding their interpretations regarding the coming economic statistics. Meaning day traders who are speculating in all financial assets should use risk taking tactics that are planned significantly in advance.
Monday, 25th of March, U.S New Home Sales – a slight gain is expected, but mortgage rates continue to shadow the housing sector and cause concerns.
Tuesday, 26th of March, U.S Consumer Confidence via the Conference Board – the reading is anticipating a slight increase. Consumer numbers from the U.S have come in mixed recently. A stronger result than estimated might not be welcomed by traders with bearish sentiment regarding the USD. The Fed wants its cake and to eat it too, they would like to see weaker consumer numbers and a soft economic downturn. If U.S shoppers remain confident this could help sustain inflation. It should be noted too, that Core Durable Goods Orders data will be released one and a half hours before the Consumer Confidence numbers.
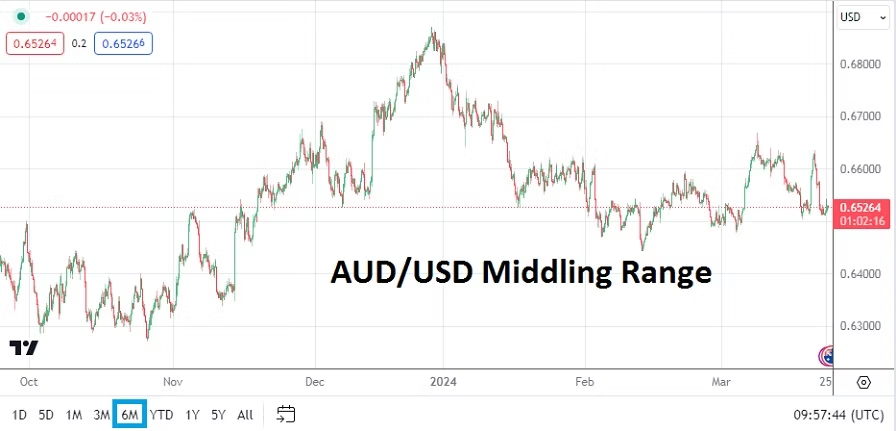
AUD/USD Six Month Chart as of 25th March 2024.
Wednesday, 27th of March, Australia Consumer Price Index – inflation numbers are expected to come in slightly higher than the previous results. Like most other central banks, except for the BoJ, the Reserve Bank of Australia would enjoy seeing inflation erode. The AUD/USD will react to the results certainly, but the price action might prove complicated because of USD centric notions.
Thursday, 28th of March, U.S GDP, Weekly Unemployment Claims, Pending Home Sales, and Revised Consumer Sentiment from the University of Michigan – put bluntly day traders will have to be well prepared for the combination of data from the States. Spectators who do not have large trading accounts and cannot take on a great amount of risk, should seriously consider sitting on the sidelines until most of the data is published. The GDP numbers will be watched carefully, while they are expected to match last month’s total, any surprises will affect the USD immediately in Forex. Weaker growth numbers might cause USD sellers to ignite positions.
However, before traders react too much to the Gross Domestic Product numbers, the Weekly Unemployment data will also impact the financial market. Financial institutions are anticipating a higher amount of unemployment claims this week. Also, at the same time as the growth and jobs numbers, the Final GDP Price Index numbers will be brought forth. The mixture from these reports could cause speculative whiplash.
The housing sector numbers and consumer numbers which come one and a half hours later will finish off a very big day for traders and institutional investors. The wide array of data could make this coming Thursday rather loud, and again rather dangerous for retail traders to participate.
Friday, 29th of March, Japan’s Tokyo Core Consumer Price Index – the inflation numbers are expecting to show a slight decrease to 2.4%. The result should certainly be watched by USD/JPY and GBP/JPY traders. If the number were to come in higher than expected, this could cause additional volatility for the Japanese Yen. Financial institutions seemed to indicate last week they would like to see the BoJ become more aggressive with their Policy Rate.
Friday, 29th of March, U.S Core Personal Consumption Expenditures Price Index – the reading is expected to be below the previous month’s total. Traders should be on the lookout for revisions to past results. Financial institutions know this inflation number is important for the Federal Reserve, but they are concerned the U.S central bank doesn’t have the ability to combat inflation which is not part of the Core number. Energy and food costs which are hurting U.S consumers are not part of this report and likely making the Federal Reserve gun shy regarding monetary policy – which has caused a large part of the USD whipsaw trading results that Forex has experienced.
AMT Top Ten Miscellaneous Entries for the 22nd of March 2024
10: Jefferson: Jon Meacham’s Thomas Jefferson The Art of Power provides well written historical and psychological insights concerning one of the U.S Founding Fathers.
9. Shohei Ohtani: Major League Baseball has a gambling scandal. Claims that Ohtani’s interpreter ‘stole’ over 4 million USD from the player to pay off gambling debts beg for questions.
8. Saudi Arabia: The nation has announced it plans on investing 40 billion USD into Artificial Intelligence sector companies via its Public Investment Fund (sovereign wealth fund) and potential business partners.
7. Steve Jobs: Apple’s innovation and tech leadership appears to be weakening as the absence of its deceased leader fades into memory, and competitors grow.
6. Bank of Japan: Monetary policy was finally shifted on Tuesday, an interest rate of 0.10% was instituted, today’s National Core CPI data came in at 2.8%. USD/JPY is currently around 151.400 suggesting financial institutions believe the BoJ Policy Rate may have to be raised again.
5. Gold & Forex: The precious metal challenged 2223.00 USD on Wednesday after the Fed’s FOMC rhetoric but is trading near 2165.00 as of this morning, this as the USD has gotten stronger again producing FX volatility.
4. Hot Chocolate: Cocoa finished yesterday at 8477.0 USD per metric ton, the commodity cost 2880.0 USD one year ago. What and who are manipulating the market?
3. China: Official Foreign Direct Investment statistics are supposed to be released soon. China argues that the fall of foreign investment capital is being reported with bias and not taking into consideration the impact of coronavirus, global monetary policy changes, and cyclical investment fluctuations. However, the FDI numbers remain troublesome and should be watched.
2. Risk Appetite: Major U.S equity indices including the S&P 500, Nasdaq Composite, and Dow Jones 30 are challenging record highs as behavioral sentiment remains exuberant, along with Japan’s Nikkei 225.
1. Interest Rates: The Federal Reserve has hinted three interest rate cuts ‘could’ happen this year, this while inflation in housing, transportation and food remain significant for U.S consumers. The Fed seems to be indicating it believes U.S jobs data will get worse. Political shadows hover over the central bank as the presidential election draws closer. The Fed only has 6 FOMC meetings left and appears to be playing with fire.
Risky Outlooks: Central Banks and Inflation Colliding
Most traders and investors begin their pursuit of financial assets with an optimistic perspective. However, the markets and ability to speculate also allows those who have other outlooks to equally participate. The past week once again delivered U.S inflation data which was not anticipated. While last Tuesday’s CPI results came in slightly stronger than expected, it was Thursday’s PPI which provided surprises for many.
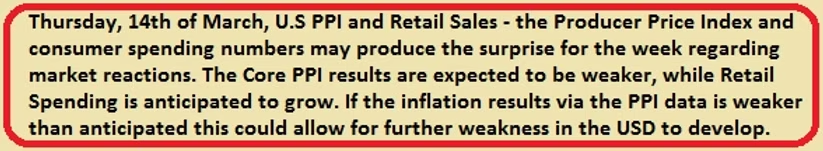
Producer Price Index Warning from AMT for the 14th of March 2024
Yet, some market participants may not have been utterly shocked by the results. Perhaps it was lucky to ‘guess’ the PPI numbers could cause volatility last Thursday, but the ability to be alert and attentive to the possibility of risk should not be ignored. Risk management is important for all traders.
This coming week will continue to be intriguing for day traders as they try to sail through speculative waters which are going to deliver shifting behavioral sentiment tides. A parade of central banks are ready to step into the limelight and they will focus on the word: inflation. Technical traders who wager on support and resistance levels in the coming days should not be scorned, because sideways and volatile trading results are likely.
U.S equity indices began to struggle the middle of last week, Gold has traded lower and Treasury yields have ticked upwards in recent market action, this as sentiment has again had to acknowledge economic outlooks remains problematic. Trading decisions this week will depend not only on what the central banks say and ‘do’, but also focus on the duration that a speculative position intends to be working.
Monday, 18th of March, China Industrial Production – a gain of 7.0% has beaten the expectation per the data already published this morning. Retail Sales numbers came in slightly below estimates, but Fixed Asset Investment numbers were better than anticipated. However, China’s data remains troublesome and the economic path ahead for the nation must overcome deflation and trust issues from international investors. A lack of confidence from the Chinese public about the value of Real Estate and the over abundance of available property is causing major headwinds economically.
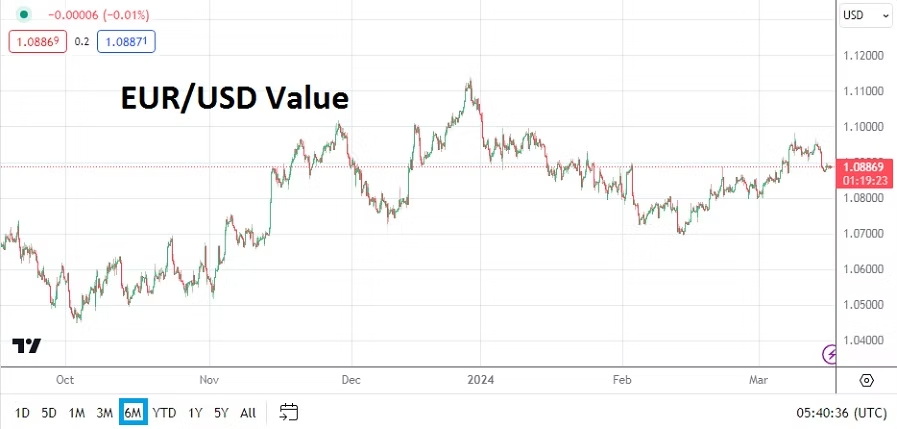
EUR/USD Six Month Chart as of 18th March 2024
Monday, 18th of March, E.U Final Core Consumer Price Index – the European Union will release crucial inflation data. An expected gain of 3.1% is the estimate. While this data release is not considered vital by many investors, the inflation statistics should be watched. The EUR/USD has produced mixed results the past four months as shifting behavioral sentiment due to battling perceptions regarding central bank policy outlooks converge.
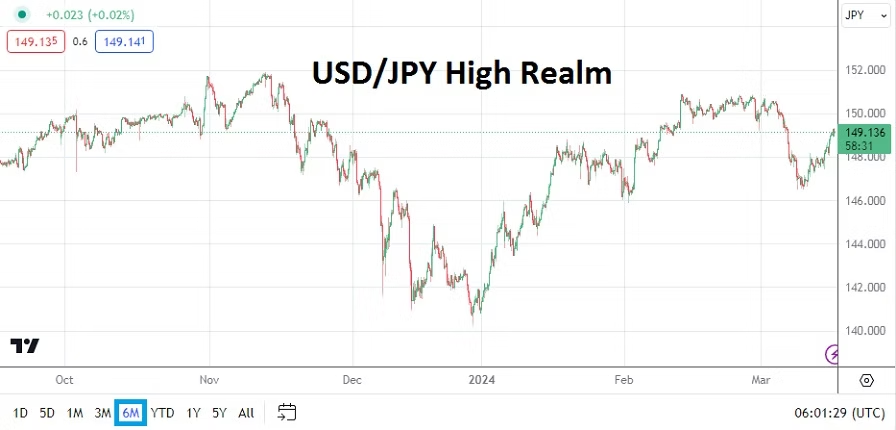
USD/JPY Six Month Chart as of 18th March 2024
Tuesday, 19th of March, Bank of Japan – the BoJ will deliver their Monetary Policy Statement and Policy Rate. While no numerical change is expected from the BoJ, signs for a change in rhetoric will be looked for as central bank observers try to read the tea leaves. The Japanese economy is within an intriguing spot, there have been signs of improvement, but the Bank of Japan is likely to remain on a conservative path regarding negative interest rates for the moment. The USD/JPY remains within the higher realms of its price range as the currency pair grapples with global inflation outlooks.
AUD/USD Six Month Chart as of 18th March 2023
Tuesday, 19th of March, Reserve Bank of Australia – the RBA is expected to parrot the pronouncements of the other central banks as they point to stubborn inflation and ‘improving yet lackluster’ economic outlook. Trading in the AUD/USD has been choppy and the volatility is likely to continue within the known price range.
Tuesday, 19th of March, Canada CPI – the Consumer Price Index data is anticipated to show inflation remains remains sticky in the ‘Northern Tundra’. The CPI report from Canada should be monitored because of the strong relationship between the U.S and Canadian economies. The USD/CAD will react to any surprises.
Wednesday, 20th of March, U.K Consumer Price Index – yet another important inflation report. Great Britain has been a ‘poster child’ regarding stagflation. The ugly word is not something central banks, nor governments want to discuss, but the simple truth is that problematic inflation and limited growth equal stagflation. The statistics from the U.K should be examined. The economic health of Great Britain is often a solid reflection of global conditions.
Wednesday, 20th of March, U.S Federal Reserve – the Federal Funds Rate, FOMC Statement and Fed Press Conference will be focal points for investors. Except importantly, not much is likely to be said be Jerome Powell that isn’t known already. Inflation reports from the U.S have highlighted stubborn higher prices. U.S economic numbers regarding manufacturing and consumer confidence have started to turn lower, but the Fed is not going to change its policy this week. Talk about ‘becoming’ dovish will be heard, but the U.S central bank still wants to see more proof that inflation can erode before they start to cut interest rates in the mid-term.
Thursday, 21st of March, E.U Manufacturing and Services PMI, readings will come from France, Germany and the U.K via the Purchasing Managers Index results. Most of the data will likely continue to point to lackluster outlooks, only the Services PMI from the U.K is expected to offer a glimmer of hope regarding ‘expansion’. If the Flash numbers come in worse than expected this could cast a shadow over behavioral sentiment for European investors.
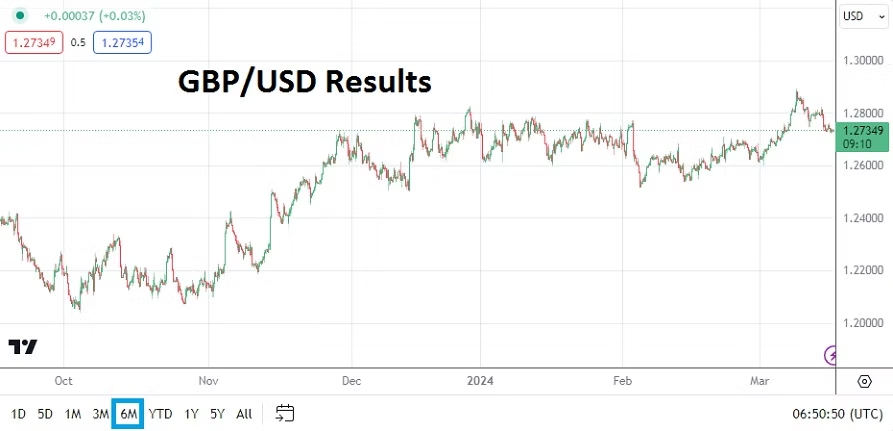
GBP/USD Six Month Chart as of 18th March 2024
Thursday, 21st of March, Bank of England – the BoE is likely to keep its Official Bank Rate within place and their pronouncements via the Monetary Policy Summary may sound like a replica of the U.S Federal Reserve. Inflation and growth will be spoken about and the BoE will try its best to paint an optimistic picture. The GBP/USD will react to the gyrations, but the range of the currency pair will have already seen tests in the preceding days. The past four months have produced a value as of the 18th of March, that is hovering slightly above late November and early December 2023 prices.
Friday, 22nd of March, U.K Retail Sales – a negative result of minus -0.3% is expected. The retail data will certainly be watched, but following the massive week of central bank statements and data which have already been published, this number may prove to be rather anti-climatic unless there is a massive surprise.
Friday, 22nd of March, E.U ECB and U.S Fed – Officials from both central banks will engage in a variety of speeches in Europe and the U.S, but again after the week’s worth of central bank rhetoric which has been heard, investors are unlikely to react much to these soundbites from members of the European Central Bank and Federal Reserve. Existing behavioral sentiment which has been produced in the dynamic days beforehand should remain the central theme as investors go into the weekend.
AMT Top Ten Miscellaneous Rays for the 15th of March 2024
10. Argentina: President Javier Milei is practicing fiscal sanity. The health of the Argentine Peso has improved, and monthly inflation data has begun to show signs of erosion.
9. Copper: The commodity has shown a steady increase since the 9th of February and is challenging values last seen in April of 2023. Demand could signal better global economic outlooks emerging.
8. Gold: The precious metal is near 2167.00 USD which appears high momentarily, this as questions about USD near-term direction lurks and Forex remains choppy.
7. Aramco: Profits for the energy producer were an approximately 121 billion USD for 2023, this as Saudi Arabia is propelling the nation’s infrastructure towards an elite future.
6. Bubble Watch: Binance Coin is around 580.00 USD as of this writing. BNB/USD was near 200.00 in the middle of October 2023.
5. Centrists: Will the adults be allowed back into the political arena to govern and brush away populists?
4. Inflation: Consumer prices are causing pain and household arrears are growing. Total U.S credit card debt is estimated over 1 trillion USD by the Reserve Bank of New York.
3. China: New Home Prices are still losing value via data released today. And the Shanghai Composite Index is near 3050.00 which looks suspiciously like a member of the ‘too expensive club’.
2. Data: U.S Producer Price Index stats were sharply higher yesterday, while Retail Sales came in below estimates. University of Michigan Consumer Sentiment readings will be published today. The U.S economic outlook remains murky.
1. Prediction: Fed’s FOMC meeting next week will provide financial institutions cautious ‘vanilla’ remarks about monetary policy from Jerome Powell, meaning market conditions will likely continue to move sideways.