post291

India Insider: Why is Gold Frequently Accumulated by Indians?

India Insider: Why is Gold Frequently Accumulated by Indians?

In a society like India in which I live gold hoarding is a fact of life. According to a recent report by the World Gold Council, Indian households are believed to hold around 25,000 tonnes of gold with a combined value of around $3 trillion USD.
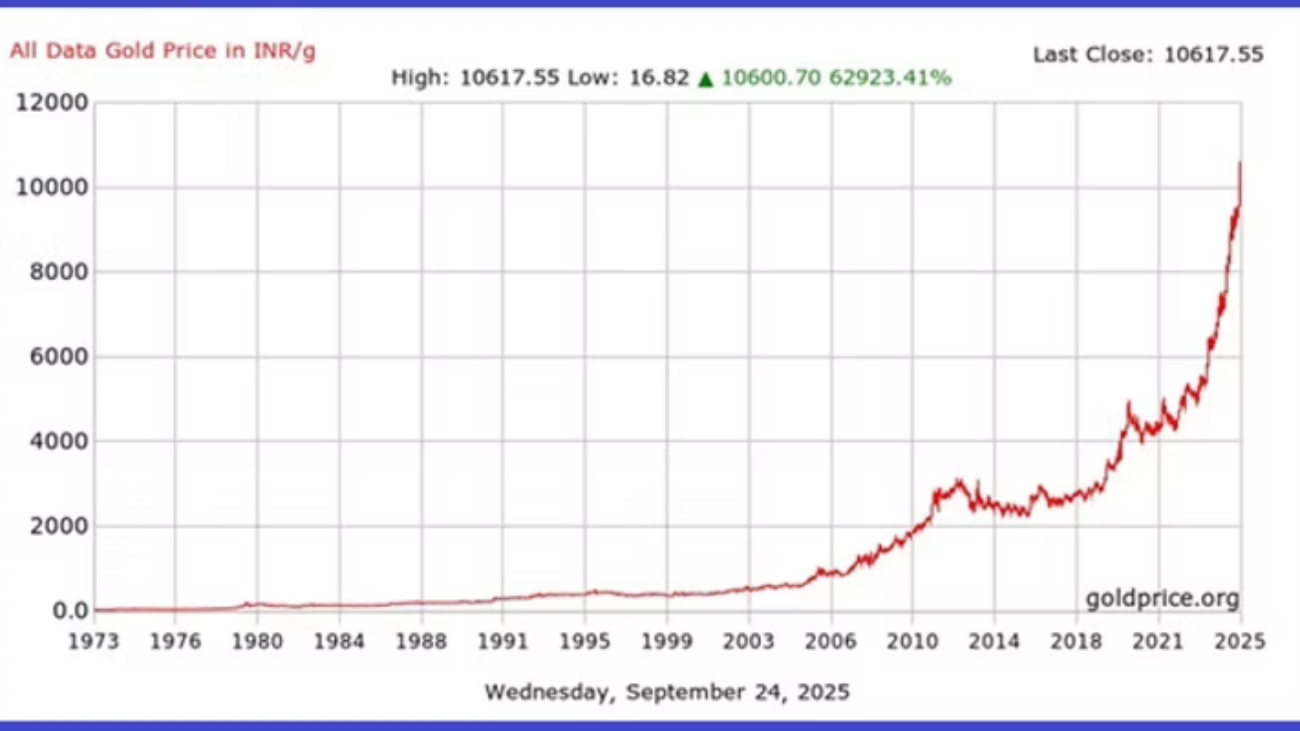
Billionaire banker Uday Kotak applauded Indian women when he said they are ”the smartest fund managers in the world”. The precious metal has gained 42% in 2025 alone, and returned 700% in the last 20 years in Indian Rupee terms. In India consumers have a habit of monitoring daily gold prices. There is a gold festival in India called Aksayatritiyai, when gold is bought frequently in small grams but often also includes large purchases for religious sentiments. In Northern India, gold is bought during festival times like Dhanteras and believed to bring prosperity and good fortune.

It’s almost unthinkable for marriages to occur in India without gold. Many marriages have been postponed and even stopped if the requisite dowry is not given by a girl’s family. And there was a time in India when some families didn’t want to have a baby girl due to the excessive gold dowry they would be responsible for and have to give a boy’s family at the time of marriage. 

Adam Smith’s Case Against Gold:

Smith lashed out at gold for its lack of productiveness. He wrote in the The Wealth of Nations, “labour was the first price, the original purchase-money that was paid for all things. It was not by gold or by silver, but by labour, that all the wealth of the world was originally purchased; and its value, to those who possess it, and who want to exchange it for some few productions, is precisely equal to the quantity of labour which it can enable them to purchase or command.”

The act of hoarding, whether it is money or gold, depresses economic activity, as demonstrated by John Maynard Keynes in his ‘paradox of thrift’. Indeed, it was the Europeans by spending all the precious metals taken from the Americas which boosted economic activity, and ultimately sparked the rise of modern capitalism whereas Asians by hoarding ended up falling behind.

Ancient China Example:

In the past, China’s reliance on silver gave short-term stability but stunted long term growth. With no domestic silver, it depended on inflows from Spain and Japan, making its money supply hostage to global trade. Wars or disruptions cut silver inflows, draining liquidity while crippling tax collection. Unlike Europe, China clung to silver as ‘real’ money, while neglecting credit, banking and bonds. This rigid system weakened the nation’s fiscal capacity, leaving China unable to mobilize resources or industrialize effectively. In the end, silver ensured stability, but strangled flexibility and growth. Indian growth has been strangled too often because of an over-obsession towards gold.

Why Gold Prices are Moving Up?

The price of gold was relatively stable until the 2008 financial crisis and it’s been rising steadily ever since, doubling in 3 years from 2009 to 2012. After some broad consolidation, gold has been in a higher value band if you scrupulously study charts. Arguably, it is an influence due to lower interest rates that have helped gold prices move up for 15 years as inflation has been attempted to be camouflaged by Central Banks.
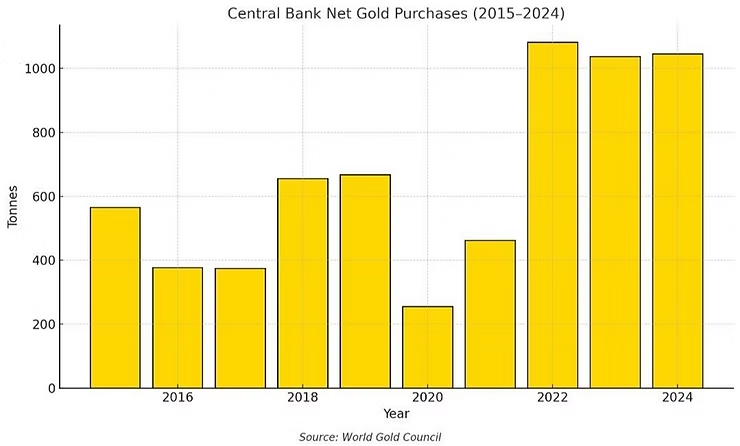
Accumulation of Central Bank Holding of Gold into 2024

Central Banks also accumulate gold for many reasons. One reason for this are rising bond yields that make existing fiscal obligations underperform for governments. Central Banks buy gold to diversify and hedge against risk. As the Official Monetary and Financial Institutions Forum – an independent body – noted recently, many European national bank systems endure massive losses because of quantitative easing. When the institutions try to undertake quantitative tightening, they are forced to sell at market prices, which deepen their balance sheets losses. Thus, Central Banks diversify into gold as a sacrosanct hedge against losses incurred and allows them to offset many liabilities. Gold has a long historical track record of working as a safeguard against inflation.

It’s also true that gold is often accumulated by Central Banks when hedging against geopolitical uncertainty. The Russia and Ukraine war offers intrigue regarding the nation of Kyrgyzstan, which China uses as a route for its exports to Russia, this due to Kyrgyzstan’s inherent ability to conduct trade via accessible routes. There is high plausibility that Kyrgyzstan might be converting Russian Ruble surpluses into gold.

Monetary Policy Matters for Gold:

Gold will remain vital for many years to come as a store of value and a safe haven. Buying the precious metal delivers investors and businesses a needed hedge against inflation. Protections against the lose of purchasing power within their own fiat currencies remains important for all people.

The Indian public and other societies need to remember, the value of gold within their own currencies often lies within the interest rate valuations sparked by Central Banks mechanisms which sometimes amount to magic shows and influence demand. While public buying of gold is important, it sometimes equates into mere speculation and does not always help economic activity.
post289

India Insider: Speculation, IPO Mania, and Capital Erosion

India Insider: Speculation, IPO Mania, and Capital Erosion

A speculative frenzy is reflected nowadays via India social media around quarterly results and IPOs. Animated talk about investment potential in India can be compared in some respects to the Dot-com bubble in the U.S which grew in stature into the late 1990’s and peaked in March of 2020 before imploding. Retail speculators in India rush into untested technology stocks hoping for quick profits, often without understanding the businesses. Avoiding a Dot-com like crash is important.

Hedge funds and institutions with their superior supply of capital often speculate across stocks, bonds, Forex and commodities as part of their strategies. However, retail investors should only purchase individual corporate stocks like pieces of businesses which they want to own when they have the ability. Market fluctuations lower can be used to buy quality companies when intrinsic value has been discounted allowing investors with limited funds to take advantage of stock volatility.

Charlie Munger, the right hand man of Warren Buffett, when asked what the secret of running Berkshire Hathaway Inc. was replied, “Warren likes to say, just tell us the bad news, the good news can wait. So people trust us in that (decision making process), and that helps prevent mistakes from escalating into disasters. When you’re not managing for quarterly earnings and you’re managing only for the long pull, you don’t give a damn what the next quarter’s earnings look like.” And this has proven to be advice that all investors can learn from.

Lessons from Yes Bank and Ola Electric:

Many speculative investors rely on technical charts using support and resistance patterns for trading decisions. This frequent buying and selling enriches brokers but rarely investors. Technical trading entices because it often is easier to look at a chart and feel that by glancing at past results you are able to predict the future, but this frequently proves to be incorrect. Fundamentals should always be a large part of investment decisions.

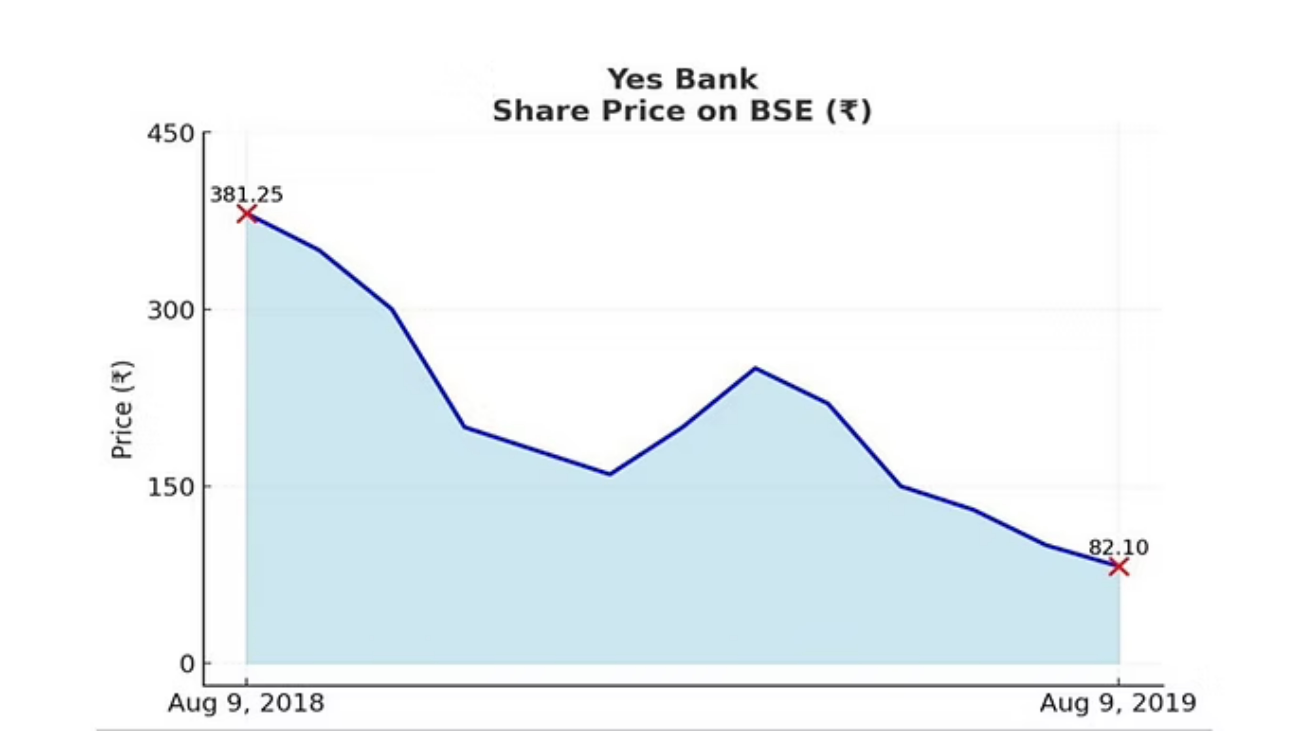
Yes Bank is a classic example. Investors assumed strong fundamentals in 2018, but allegations against founder Rana Kapoor revealed critical issues which proved to be damaging. The Reserve Bank of India stepped into the mess, forcing a consortium of banks to inject equity. Small investors who bought the dips blindly learned the cost of ignoring fundamentals and were hurt financially.
Yes Bank Share Value from 9th of August 2018 to 9th of August 2019 in India Rupees

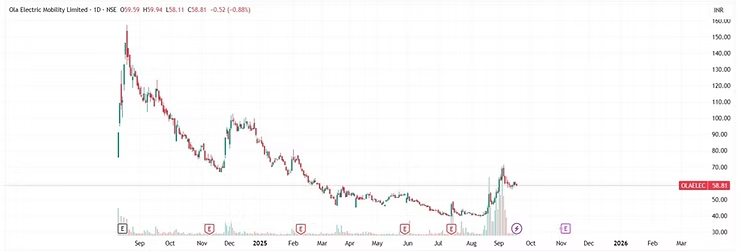
Another example unfortunately is Ola Electric Mobility Ltd which highlights a similar trap. Ola’s 2024 IPO raised 75 billion Indian Rupees ($900 million USD) at a value of 76 INR per share. It was hailed as a ‘BYD of India’, and despite high valuation warnings, investors pushed share value towards 160 INR. Predictably as cash burn mounted and with no operating profitability, Ola Electrical Mobility value soon fell below the IPO price and speculators who dreamed big soon began to feel like they had lost. The Yes Bank and Ola Electric Mobility cases demonstrate the dangers of investing outside one’s circle of competence.

Ola Electric Mobility One Year Chart as of 17th September 2025

Valuations and Investor Behavior:

From October 2022 to October 2024, Indian markets moved significantly higher, stretching valuations beyond earnings. Even after U.S. Liberation Day tariffs triggered a pullback in India, investors continued pouring money into mutual funds through SIPs (Systematic Investment Plans), ignoring glaring fundamental problems. This raises concerns and creates doubts about whether SIP passive investing is wise without understanding individual businesses.

Investment becomes more intelligent when it is done with a business like approach. As Warren Buffett said, “the stock market is a device for transferring money from the impatient to the patient.” But patience should not mean overpaying for growth stories. Predicting future earnings is difficult, and paying lofty prices for stocks in the EV, battery, and micro-processing chip sectors based only on expectations can be dangerous.

When competition or innovation shifts, stock prices collapse as Ola Electric Mobility has shown. True investing is businesslike. It requires understanding, discipline, and buying below intrinsic values. Chasing hype, speculation, and every new IPO can lead to erosion of capital. Smaller investors can do better and they should desire to study fundamentals in order to make good decisions.

post287

Forex: Tomorrow is Known, October and Beyond are Uncertain

Forex: Tomorrow is Known, October and Beyond are Uncertain

The U.S Federal Reserve will cut its Federal Funds Rate by 25 basis points tomorrow. The big question all financial institutions would like some clarity about is whether the U.S Central Bank will strongly suggest that another cut of 25 basis points will need to take place in late October during the next FOMC meeting.

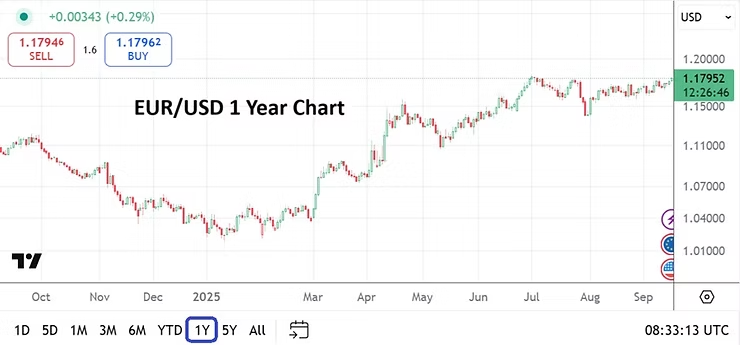
EUR/USD One Year Chart as of 16th September 2025

Forex has certainly seen the USD weaken because a definitive interest rate cut has already been factored into mid-term outlooks. Those who are betting on a 50 basis point cut tomorrow are spitting into the wind and most likely wrong. The Fed under Jerome Powell has proven time and again that it is cautious. The word uncertainly is likely to be heard on Wednesday, even as the Fed Chairman admits conditions warrant cutting interest rates further.

And this is where it will get tricky for day traders betting on conditions beyond tomorrow. Since the quarter of a point cut has been factored into Forex already, and the EUR/USD, GBP/USD and even the USD/JPY are bouncing up against technical inflection ratios for the time being, powerful reactions and dangers will ignite based on the perceptions generated about late October outlook. It is likely some large financial institutions have already priced a rate cut of 25 basis points into the USD already for their October outlooks, meaning some big houses have accounted for a 50 basis point cut mid-term.

It is probable some larger firms have remained conservative, and have not leaned into overly confident cash forward contracts for their corporate clients. This because they want to be certain the Fed is definitely setting the table for another interest rate cut in October.

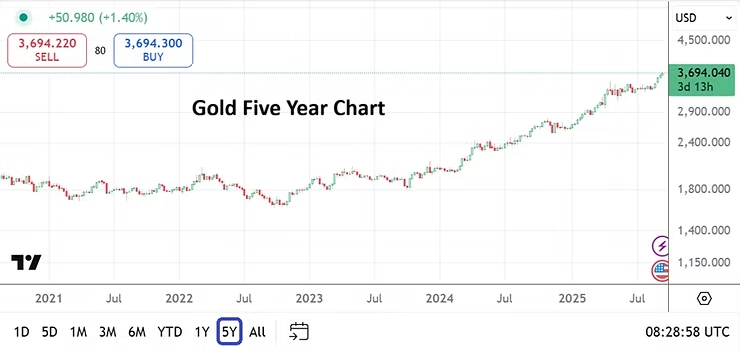
Gold Five Year Chart as of 16th of September 2025

Nothing is guaranteed and Fed Chairman Powell is likely to state this obvious point tomorrow. However, he may have to admit the jobs market looks weak. And he may have to also acknowledge, that although he and other FOMC members remain concerned about the threat of inflation, that for the moment it remains somewhat tame. This is where a secret ingredient in Forex trading tomorrow may fuel volatility. Inflation fears telltale signal is being seen in the current price of Gold which is within record territory and sight of $3,700.00 as of this writing, this even as the 10-Year U.S Treasury yields have decreased.

As a critic of the Federal Reserve’s conservative approach to cutting interest rates the past half year, I have to acknowledge that it is important that the Fed remains nimble, they cannot simply give into pressures from political circles. However and unfortunately, the Fed has been anything but nimble the past six months. The Fed should have cut interest rates by 50 basis points in total in the late spring and early summer, they did not. Now they are once again behind the proverbial curve and in a position in which they are being forced to be reactive instead of proactive.


Again the Fed has at its disposal high tech quantified data via its distinct Fed Districts to know the economic landscape and react at a quicker pace. It chooses not to do this efficiently, this was a feature of the Fed’s inability to accept that inflation was a danger almost four years ago and its snail like reaction which caused economic harm. Now the Fed finds itself in a position in which it should be admitting that it should have been cutting interest rates six months ago, while also knowing logically storm clouds are on the horizon regarding murky economic outlooks due to the threat of inflation actually increasing in the mid-term. Justification for a nimble Federal Reserve remains a pragmatic desire.

Here’s the thing, the Federal Reserve is going to cut the Funds Rate by 25 basis points tomorrow and say they are considering another cut in October. The Fed will probably also say after another cut in October, that they anticipate taking a way and see approach into the end of this calendar year.

Regarding the potential reactions of the EUR/USD, GBP/USD and USD/JPY tomorrow and into Thursday, volatility needs to be expected. The consolidation we have seen develop the past few days near important levels that seemingly are holding back large value moves will vanish for day traders. Small retail speculators in Forex need to understand what they view as massive moves are often considered simple small mathematical gyrations by financial institutions which are not only participating in the cash forward business via FX rates, but also taking part in hedging via futures trading through the likes of the Chicago Mercantile Exchange and other venues.

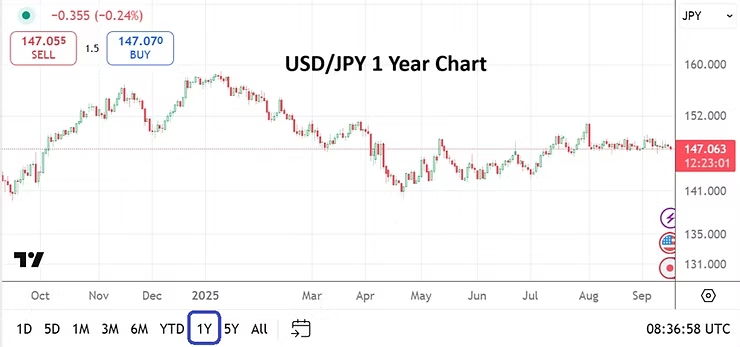
USD/JPY One Year Chart as of 16th September 2025

It needs to be noted the Bank of England will release its Official Bank Rate on Thursday along with its Monetary Policy Summary. And the Bank of Japan will issue its Policy Rate and Monetary Policy Statement on Friday. The BoE is not expected to change its borrowing rates on Thursday, and the Bank of Japan is expected to stand in place too. It should be pointed out that the Bank of Japan does have room to increase its borrowing costs, but the government of Japan appears to be married to maintaining a weaker Japanese Yen, much to the chagrin of some economists.

If the Fed admits they need to likely cut interest rates again in October this might spur on some USD weakness and create volatile conditions tomorrow and Thursday. However, if the Fed offers the phrase that they will take a wait and see approach after October, until further economic data can be accessed in November and December, then the USD may start to show signs of firming. The Fed’s interest rate is 4.50% today, by the end of Wednesday it should be at 4.25% with signs that by the end of October it will be 4.00%. Looking for more than those clues is speculative, financial institutions want answers like everyone else.

postN3.1

India Insider: Working with the West as it Deals with Others

India Insider: Working with the West as it Deals with Others

India’s Prime Minister Narendra Modi visited Tianjin, China for the 2025 Shanghai Cooperation Organization Summit in early September, which was attended by over twenty nations. Before India visited the conference in August, Washington D.C had already imposed a 50% punitive tariff on India’s exports. The initial tariff was a 25% duty, but included another 25% penalty because India purchases a large amount of Russian Oil, which the U.S seeks to reduce. An uneasy trade dilemma looms for India.

Many Western analysts quickly concluded that Prime Minister Modi was tilting India towards a stronger relationship with the Russian and Chinese camps, by potentially embracing warmer associations with Presidents Vladimir Putin and Xi Jinping, and defying Washington’s previous warnings.

Yet, the trade composition and the underlying reality highlights a different story. Despite India being positioned in the global South politically, the nation recognizes its higher value exports – which include textiles, gems and jewelry, apparel, and pharmaceuticals are primarily sold to the West. The United States clearly remains India’s biggest consumer. In essence President Trump holds a trump card.

In contrast, China’s total exports to the global South (excluding Western Europe, Australia, New Zealand, and North America) has doubled since 2015. Chinese exports to the U.S were $525 billion USD in 2024, but to the global South, China’s exports grew to nearly $1.3 trillion USD.

As Professor Michael Pettis accurately points out, “countries with expanding trade surpluses with the U.S, use their higher revenues to fund deficits with the rest of the world.”

India Exports More to the West:

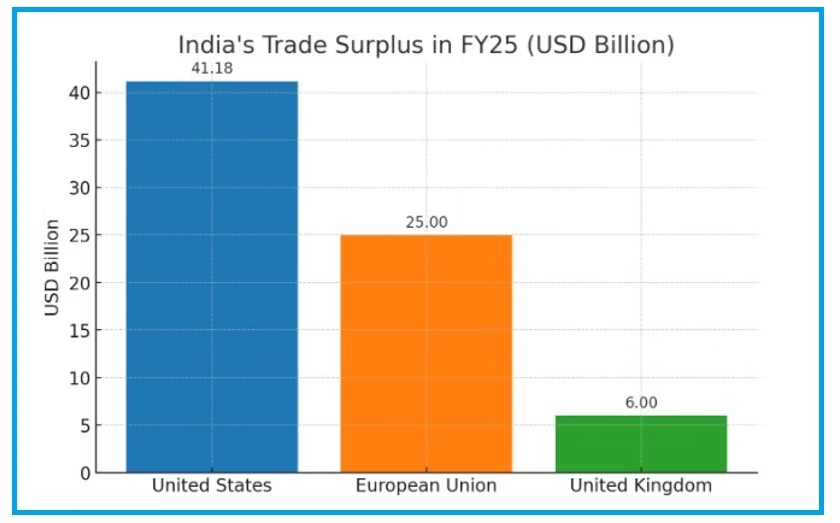
India’s trade surplus with United States, the European Union and U.K stands at $72.18 billion USD. If India wants to be competitive with China in terms of manufacturing, it should affiliate more astutely with the Western camp.

Dependence on Anti-Western Countries Hurts India’s Trade Balance:

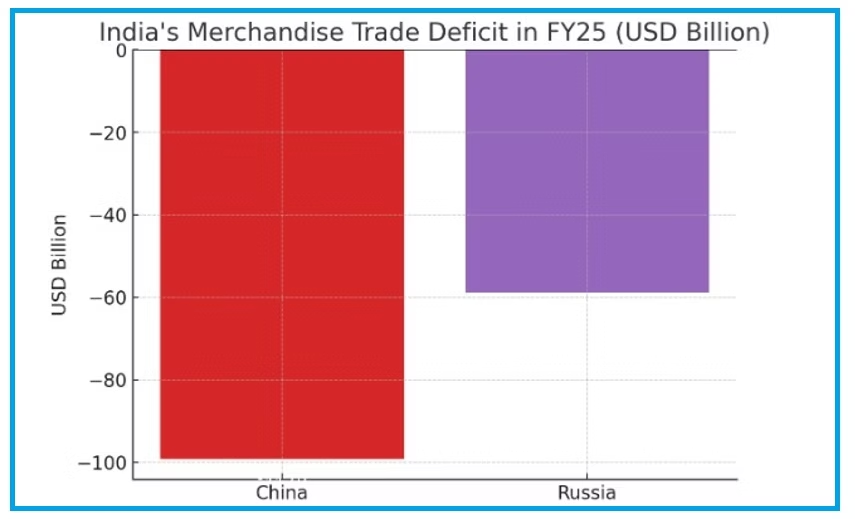
India’s combined trade deficit with Russia and China is approximately $158 billion USD, which demonstrates how much less India exports to these two countries. India’s overall merchandise trade deficit is $282 billion USD, with a deficit of almost 56% in total attributed to Russia and China.

Service Exports a Crucial Metric in India’s Balance of Payments:

India’s services exports stood at $383 billion USD in financial year 2025, earned primarily from the U.S and other Western countries. Washington has imposed tariffs on India’s tradable goods sector, while the nation’s non-tradable sector has been operating without much stress.

India’s overall trade deficit stood at minus $94.26 billion USD in financial year 2025. Without service exports (predominately from the software services sector), India’s current account deficit would be much larger and the Indian Rupee would face greater depreciation pressures.

India’s economic stability is precarious, equilibrium needs to be found. Solid domestic outcomes for manufacturing and a stable Rupee, including exchange rates, could be achieved with a well-defined calibration that looks West but does not weaken India’s stance as a non-aligned nation. New Delhi should focus on maintaining neutrality and strategic autonomy.

While India may shake hands with Presidents Vladimir Putin and Xi Jinping, an important economic lifeline runs firmly through Washington, Brussels, and London. Crucial negotiations are said to be taking place between Prime Minister Narendra Modi’s team and President Trump’s White House behind closed doors. New Delhi could become vulnerable if it does not find adequate solutions. President Trump has recently reiterated his friendship with the Prime Minister Modi, perhaps an agreement can be produced in the mid-term.

post278

Behavioral Sentiment: False Narratives and Noisy Realities

Behavioral Sentiment: False Narratives and Noisy Realities

The past handful of months in Forex have provided day traders problems if they have been trying to pursue steady trends. Constant flashes of rhetoric and news pervading tariff implications, U.S Federal Reserve interpretations from various media and analytical corners, and mixed economic data has caused a rather mired reality for speculators trying to operate.

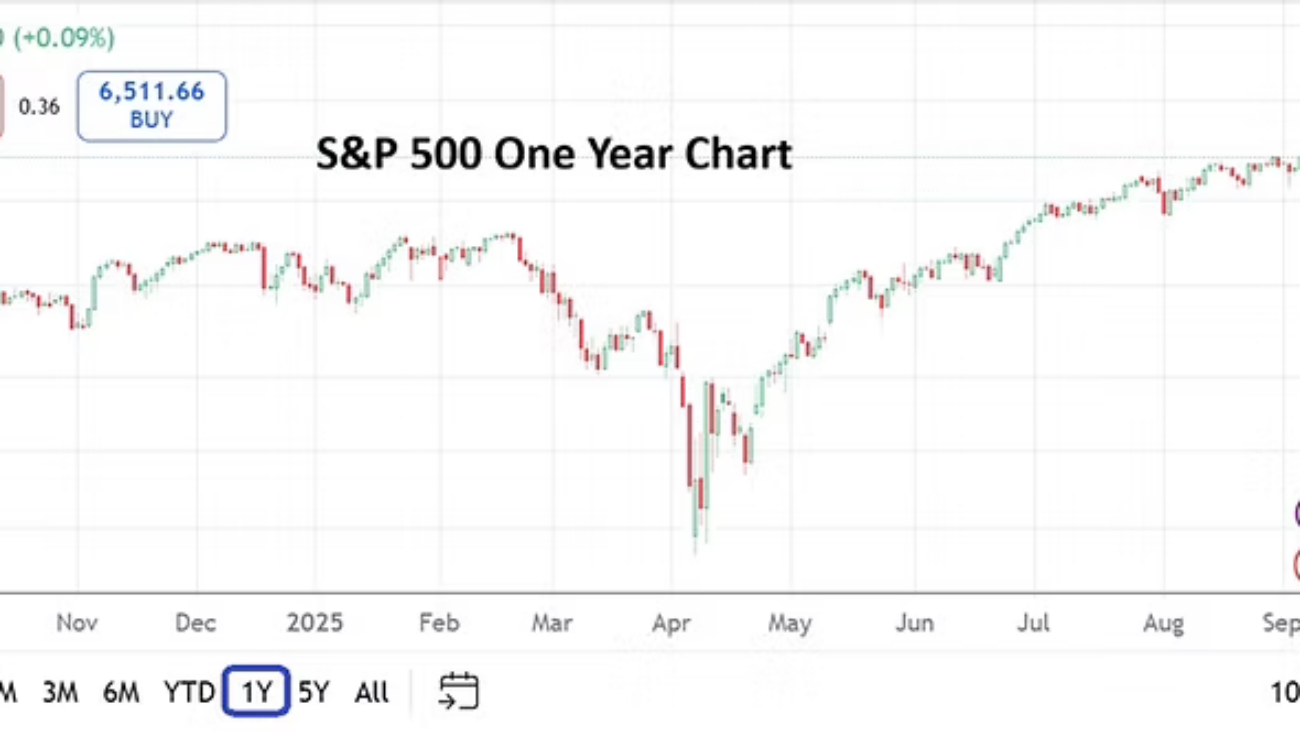
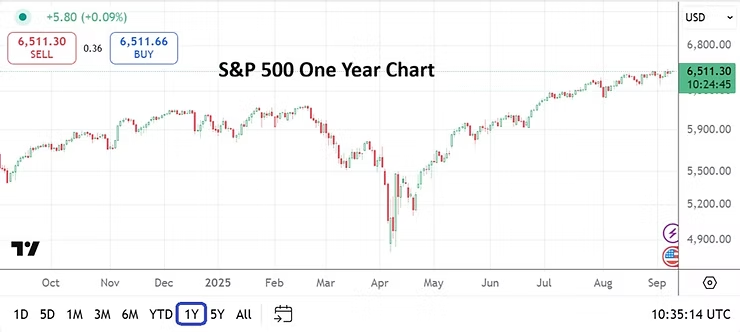
S&P 500 One Year Chart via Futures CFD Trading on the 9th of September 2025

However, if the noise is turned down by day traders and sometimes given less importance regarding potential influences, signals become visible and some perceptions can be looked upon as roadmaps. While many want to to throw their hands up and proclaim some sort of developing economic meltdown and a coming apocalypse, the major U.S indices are actually performing quite well as a barometer. The S&P 500 is continuing to challenge all-time values. Yes, the Nasdaq 100 and Dow Jones 30 are not marching in lockstep with the S&P 500 to new highs, but they are not far behind. The stock market has never guaranteed people an ability to constantly move upwards, but it does offer the potential to judge outlook and mid-term sentiment.

The USD has been extremely choppy since the start of this year, this as the Trump administration has taken over, but its trend towards weakness has been rather clear. The EUR/USD and GBP/USD have done reasonably well regarding mid-term strength. Yes, the USD/JPY has produced whipsaw movements and the Japanese Yen remains awkward, but this is a direct reflection of mitigating Japanese government policy (some may call it incompetence) regarding its ability to manage fiscal concerns, interest rates, and fight deflation and now inflation (which has been going on for a few decades).

Gold is traversing record heights and is showing signs of sustaining values above 3,600.00 as of yesterday. After languishing (albeit within elevated realms) near 3,350.00 the past handful of months with prevalent volatility, the precious metal has bolted out of its consolidation. And the likely reason for this is the anticipated Federal Reserve policy changes regarding interest rates. 10 Year U.S Treasury yields have also been pushed lower recently – this as financial institutions await a definite cut in interest rates by the Fed on the 17th of September. But folks who believe a 50 point basis reduction is coming late next week are likely wrong.

The Federal Reserve under Chairman Jerome Powell has been quite conservative, this will probably not change next Wednesday. It is more likely a cut of 25 basis points will take place on the 17th, and the FOMC Statement will offer the potential of another interest rate cut in October. Tomorrow’s PPI numbers and Thursday’s CPI results will influence the Fed’s coming meeting and mid-term outlook.

What we are left with is a broad market that is having a lot of noise applied to it by people with a variety of biases. Political bantering has reached a threshold in which it might be best to simply not pay attention to anything – but that is dangerous too. Yes, some people do talk sense, and some people do show signs of actually trying to engage in adult decision making regarding their insights, but it often feels like wanting to sound correct is more important than outcomes. Technical traders may be enjoying a quiet laugh at the expense of fundamental players right now.

However, economic data remains important. While rhetoric from the U.S White House and its opponents remains within a state of hyperbole, day traders should try to turn down the noise and pay attention to signals that long term investors continue to produce and take advantage of their sentiment. Stocks continue to be pursued and indices have done well, but volatility should be expected particularly into next week.
post275

Nvidia: Short-Term Speculative Reactions Versus Investing

Nvidia: Short-Term Speculative Reactions Versus Investing

Nvidia is near 181.60 as of this writing, this after the company issued a quarterly report that beat expectations, but also pointed out that mid-term concerns may slow down the pace of some of its data driven business, and that China enterprise complications remain murky.

Nvidia Five Day Chart Early Morning as of 28th August 2025

Day traders should be certain they acknowledge the difference between a short and near-term wager on Nvidia compared to mid and long-term outlooks. Speculators who want to venture forth and gamble on Nvidia based on last night’s quarterly earnings report are free to do so. However, there is a distinct difference between betting on what today and tomorrow’s reactions in Nvidia will be compared to folks who are investing long-term in the company and believe that over the long haul it will remain a solidly profitable company that adds value to bottom lines.

In early August Nvidia was challenging the 185.00 ratio. As of this morning the stock is near the 181.60 mark. Nvidia faces headwinds currently in after hours markets because the company had the gumption to say it outperformed expectations in the last quarter, but put up a cautionary sign saying its data business may face some obstacles regarding growth, and outlooks for its China enterprise remains solid but could face some complications.

Reacting to Short-Term Temptations and Speculating:

For those who want to sell Nvidia based on the above ‘warnings’ today, they are free to try their luck. However, selling positions could quickly turn into buying opportunities. Nvidia like most equities is about considering reactions due to behavioral sentiment, short-term nervousness could rapidly shift to bullish perspectives in the eyes of investors, programmed trading software, and – yes – day traders.

Lower support for Nvidia technically when a five day chart is looked at may be 170.00 if someone is overly cautious. A look at a one month chart for day traders who have a bit more of an aggressive manner, may believe technical chart evidence suggests a lower move can be taken advantage of at 177.00, this if they are keen on waiting for a downturn to look for an opportunity to buy at lows.

Yes, perhaps some short sellers may target the mentioned values as places to cash out positions while speculating. But there is a chance Nvidia will not touch those lows. Perhaps bearish reactions – if they even happen – will fade quickly and additional bullish sentiment will continue to seep into Nvidia. Does anyone really think Nvidia is about to face a steep selling curve?

Tech Stock Consideration and Looking for a Barometer:

·       Some folks are talking about AI and its potential status as a bubble.

·       However, this is Nvidia we are talking about, even if there is a bubble in the AI sector, Nvidia long-term is a solid stock that will likely do well for years to come.

·       Short-term reactions seen the remainder of this week and perhaps over the next few weeks may be choppy, but this would include reversals in both directions.

·       Betting on a big downside in Nvidia looks to be wrongheaded.

·       Traders who are conservative and believe Nvidia is a good buy short-term after some selling happens, while looking for momentum higher – at least back to known resistance levels – may be making a solid wager.

Nvidia is one of the most important equities in the stock market. Some may justifiably say it is the most important at this moment. As a big driver of the Nasdaq 100, Nvidia has in many respects traded sideways since late July. This has been one of the reasons the Nasdaq 100 has faced headwinds too. The broader S&P 500 has been doing better than the Nasdaq 100 the past few weeks, this because tech stocks like Nvidia are facing some skepticism regarding just how high they can go. However, Nvidia as a stand alone company has excellent long-term prospects.

post274

India Insider: K-Shaped Economy via Growth and Inequality

India Insider: K-Shaped Economy via Growth and Inequality

ndia’s growth story remains inspiring, supported by the National Democratic Alliance (NDA) government’s policies that attract foreign capital into infrastructure projects. The last decade has seen improvements in railways, ports, bridges and highways. In Financial Year 2025 (1st April 2024 to 31st March 2025), gross Foreign Direct Investment inflows reached USD 81.04 billion, a 14% rise from the previous year, reflecting global investor confidence under the China+ strategy. However, net FDI shrank to just USD 353 million, its lowest on record, as significant divestments and profit repatriations offset the inflows.

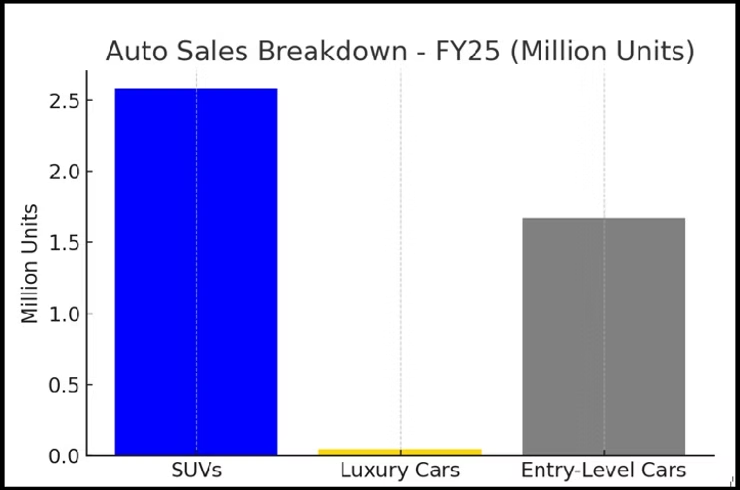
Auto Sales in India from 1st of April 2024 to the 31st of March 2025

India’s stock market has rallied recently, driven by strong corporate performance despite tariff-related jitters. Corporate capital expenditures by listed non-financial companies rose over 20% year-on-year to exceed 11 lakh crore ($125 billion USD) in FY25, surpassing the government’s capital expenditures of 10.5 lakh crore ($120 billion USD). This signals robust investment by large firms.

In contrast, the unlisted corporate sector, contributing two-thirds of corporate value added and holding most corporate debt, remains weak with falling profits and tax payments. The divergence comes from the markets they serve: listed firms cater to higher-income households, while unlisted firms rely on low and middle income consumers, where progress and recovery is slower. Corporate tax receipts remain healthy, but are largely driven by listed firms. Collections in FY25 reached 12.72 lakh crore ($145 billion USD), while net direct tax collections climbed to 22.26 lakh crore ($254.97 billion USD).

Consumer trends mirror this imbalance. Passenger vehicle sales hit a record 4.3 million units, led by SUVs and luxury cars, while entry level cars and two-wheelers saw subdued demand. The aspirational middle class, especially tech professionals in their late 20s and 30s, drives premium demand, leaving the mass market segments of the population behind.

Nearly half of the nation’s workforce remains in low productivity sectors contributing only a fifth of national income. Wage growth is stagnant in several States. Micro, medium and small enterprises struggle with credit, policy bottlenecks, and institutional constraints. This is India’s K-shaped economy as large corporates and affluent consumers thrive, while smaller businesses and lower-income groups lag. India’s booming economy hasn’t delivered progress for all quite yet.

The country remains the fastest-growing major economy in the world, above 6%. A crucial question is whether this astonishing growth will create mass employment and better equality. Unfortunately, without updated consumer expenditures data since 2011–12 due to the lack of a recent census, policymakers rely on capital expenditure and earnings trends to gauge consumption patterns which deliver incomplete insights. The next census for India is scheduled to be conducted in 2027. More transparency is needed statistically to help alleviate the K-shaped results via the Indian economy.

post271

Hard Truth: No Secret Sauce, A Possibly Unfriendly Reminder

Hard Truth: No Secret Sauce, A Possibly Unfriendly Reminder

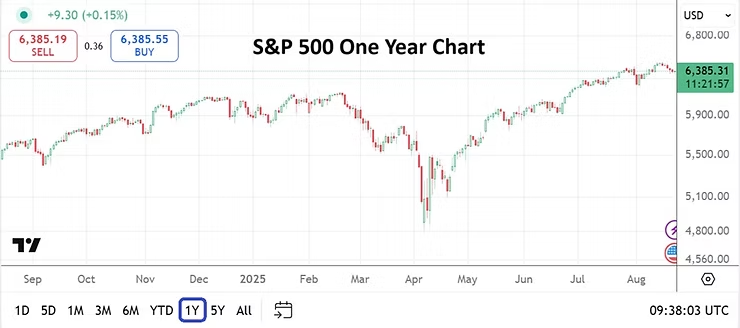
Day traders face constant battles. Choppy conditions in markets lead many salespeople within brokerage firms to proclaim the ability to take advantage of technical shifts to their clients, but it is much easier to demonstrate what has taken place before compared to what is going to happen next. Technical trading via charts often looks good for those offering its charms until reality bites.

Day traders also have the disadvantage of fighting large market institutional forces that have completely different timeframes, deeper pockets, and perhaps even a fair amount of analyses they can use to validate their reasons for taking a position – not necessarily a correct position – but enough to provide insurance regarding their decision making.

S&P 500 One Year Chart as of 22nd August 2025

Institutional traders can fall back on the analyses they have at their disposal and point to it as the reason why they made a trade. Literally giving them an excuse to explain why things went wrong, so they can tell inquiring management when needed, this in order to protect their miscues. Institutional players do not get fired easily from their positions, they usually just wait a few years and shift to another company when too many bad trades have been made – that is a dirty little secret in the trading world.

Comparatively, day traders simply blow out their own accounts while losing money. Yes, sometimes they have to explain to their romantic partner why they can’t go on the trip they had been planning because there is a sudden lack of funds. Hopefully they didn’t wipe out too much money that they may have borrowed from family or friends, this via ambitions and proclamations that a coming trade was a once in a lifetime opportunity.

But wait, yes, there are speculators and large traders who do make money. These are the folks many allude to who are – in many peoples’ minds – sitting on a yacht in a lovely ocean locale and enjoying the fruits of their labors. They do exists and we should acknowledge this, even if we sometimes think they are merely lucky and one day will face a losing streak.

However, many of these anointed winners do not exists either. Beware of experts ladies and gentlemen. Influencers are often selling a dream they know a day trader desires. Commissions drive the brokerage business. Unfortunately, it is seldom profits made by an emerging victorious crowd via newly minted speculators that make brokerages money.

I am frequently warned that this is not what day traders want to read. They do not want to be reminded that 90% of their group usually loses most of their money, or at a minimum walks away with less money than they started. The U.S Fed’s Jackson Hole Symposium is now underway in Wyoming. Yet, most day traders will only be able to take advantage of this event by trying to ride on the sentiment tides created by large institutional traders in Forex. The headline: Fed Rhetoric and Jackson Hole, will be the talking point of the media today.

However wait a moment please, the retail brokerage business in the States must be pointed out as a reason for some positive momentum in the major U.S indices the past handful of years and needs to be watched regarding its sentiment. Reddit, X, Instagram, Quora and other social media sites can be monitored to gather this info. Behavioral sentiment is becoming important in the markets. While some institutional investors are showing caution via inquiries (polling) and actual market positions, some public cash appears to be supporting the S&P 500, Nasdaq 100 and Dow Jones 30 via purchases through reputable brokers who do buy the actual asset.

That is a contradiction of sorts compared to what has been written in previous paragraphs, but then again this is trading (and investing) we are discussing, so there are no straight lines, and often complexity rules. Perhaps you noticed that I didn’t say, institutional players are smarter than day traders. In many cases institutions and their managers merely have more money to wager with, and can do this without too much leverage and over much longer timeframes – giving them the ability to ride out financial storms and survive.

Under the current market circumstances the Fed is expected to cut interest rates in September by 25 basis points. But the U.S central bank is going to face a possible battle via murky data that will have to be factored into October, November and decisions beyond, meaning caution prevails. Trading choppiness in Forex will continue in the near term. The possibility that financial institutions may believe current pricing represents fair value is legitimate.

Let’s remember that the movements in Forex, stocks and indices, commodities, bonds and other assets always appear more volatile for smaller traders, because intraday price action and the absurd amount of leverage being used by many folks often leads to dangerous speculative circumstances.

Traders need patience, shouldn’t use too much leverage and allow for the ability to walk away from a losing trade with limited losses. Leaving enough cash in your account to participate again later can lead to other opportunities. There are no guarantees in trading. Good trading discipline is essential.

post270

India Insider: Strategic Balancing Act Comes with Risks

India Insider: Strategic Balancing Act Comes with Risks

On the 15th of August, India’s Independence Day, Prime Minister Narendra Modi announced a large reduction on Goods and Services Tax rates to boost domestic consumption. The Indian economy is certainly slowing, this as lackluster domestic consumption has prompted the Reserve Bank of India to cut the repo rates from 6.5% to 5.5% in 2025.

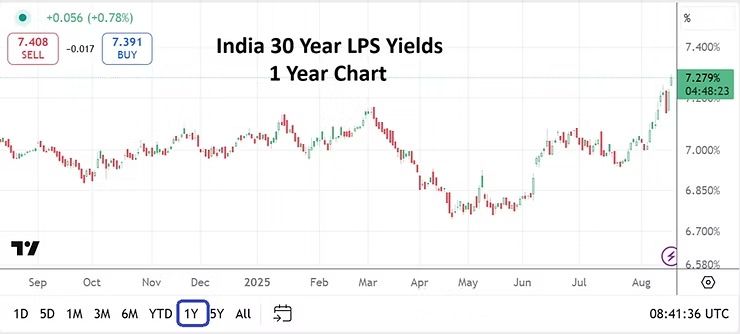
Indian Bonds 30 Year LPS Yields One Year Chart as of 19th August 2025

As trade deal discussions with Washington flounder, New Delhi is being forced to shift economic considerations towards China. The diplomatic relationship between India and China has grown colder, particularly since they clashed on the eastern border region in 2020.

Relying on China also comes with challenges for New Delhi. Since 2021, the trade deficit with China has expanded from $73.3 billion to $99.27 billion USD, showing that India still depends increasingly on China for significant importing needs.

According to Bloomberg, India’s major conglomerates have already established excellent relationships with Chinese suppliers of lithium ion batteries and EV components, although they try to discreetly tread under the radar in order to avoid the wrath of New Delhi government.

The fact is India can sustain its economy and maintain its geopolitical posture of non-alignment by practicing a multi-polar stance with Washington and Beijing. But despite clinching trade deals with the U.K and reviving trade negotiations with the E.U, New Zealand & Australia, and its deepening bilateral relationships with many central Asian nations and within BRICS, New Delhi’s major trading partner for exports remains the United States. Around 18% of India’s exports go towards the U.S, while 15% of imported goods come from China. The numbers do demonstrate an intriguing balance.

While India’s negotiations with the U.S have stalled and appear postponed indefinitely, other Southeast Asian countries, including Vietnam, Indonesia and the Philippines have secured lower tariffs with the Trump administration making them more competitive in the U.S. market. These nations are using the U.S for economic and military security, but they also rely on China for manufacturing and logistical needs.

India Faces Additional Challenges with Washington and Beijing:

Indian IT companies derive nearly 57% of their export revenues from U.S clients, making them heavily dependent on that market. And rapid advances in AI and the erosion of legacy outsourcing models are putting India’s traditional profit engines under pressure.

Meanwhile, China is not keen on helping India achieve expertise and manufacturing competitiveness which would threaten its own business model. China wants to make inroads by selling goods to the world’s largest consumer market, rather than technology transfers which would allow India to attain manufacturing supremacy.

Some economists warn that India’s own plans for mitigation of its current circumstances will likely be disinflationary. India’s bond results via yields clearly express concern about potential fiscal costs and difficulties. New Delhi’s focus has shifted towards appeasing domestic consumers, while trying to deal with uncertain foreign partners. Government capital expenditures have been declining since last year, signaling that both corporate and public investment confidence remains weak.

India’s neutrality is welcomed. It’s not anti-Western or pro-Western, and attempts to balance between the U.S and China while trying to forge new trade agreements and ties are a constant high-stakes game capable of creating strains economically and politically. The path forward with the U.S and China will remain complex and it must be worked on with precision in order to help achieve success.

post265

Trading Thud Ending Last Week and Early August Insights

Trading Thud Ending Last Week and Early August Insights

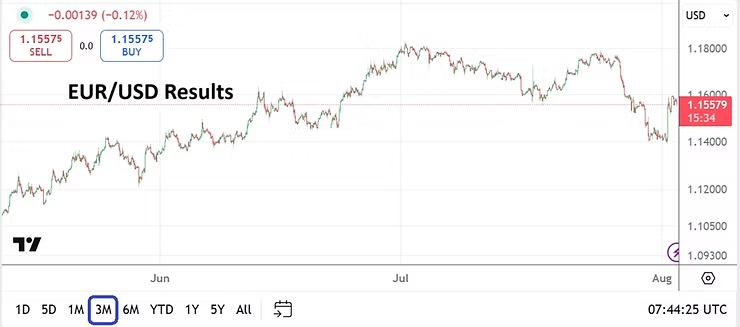
The EUR/USD is near 1.15650 early this morning. The USD/JPY around 147.850. Forex has provided fast reversals and most major currency pairs are within well established known realms, but caution prevails. Friday’s U.S jobs numbers before going into weekend provided additional mud to filter through for those seeking clear outlooks. Were the employment numbers rigged by the Bureau of Labor Statistics?

EUR/USD Three Month Chart as of 4th August 2025

Questionable economic statistics have become an open sore spot for some analysts in the U.S, this has been a problem since the financial crisis of 2007/08 and ensuing years when politically expedient numbers were rumored to be in use so the Federal Reserve and U.S Treasury could work in a more comfortable manner. Let’s just say there are actual reasons why and how economic statistics could be used to hurt and help policies. For some evidence take a look at the art of revisions that has been practiced with key economic data the past handful of years. Financial institutions now need to consider the possibility that numbers cannot be trusted, interpret reports, try to decipher reality and consider impact.

Effect on the Federal Reserve is a big question. Fed Chairman Jerome Powell continues to preach uncertainty and say a wait and see approach is needed because of implications regarding tariffs. However, conspiracy theories are also somewhat blown out of the water regarding the recent jobs numbers, because the lackluster results will actually put pressure on the Fed to cut rates in September in order to help spur on a better jobs market. So in other words, financial institutions, big investors and day traders are back to square one.

The ISM Services Purchasing Managers Index stats will be published tomorrow for the U.S, but this report is likely to be a mere ingredient that affects the marketplace. Behavioral sentiment will remain the cornerstone in Forex, equity indices, Treasuries and commodities. August is typically a rather calm month of trading taking into consideration that holidays are being taken by many market participants, but as the S&P 500, Nasdaq 100 and the Dow 30 remain elevated and capable of achieving new record highs, the USD creates chaos regarding outlook influenced by a Federal Reserve that is now in a difficult spot, and tariff implications are contemplated it would be wise to keep an eye on all near-term outcomes.

Technical trading and computer generated algos will factor into conditions as psychological levels are challenged and perceptions are debated. Has the global marketplace grown comfortable to the tactics used by President Trump? While it is easy to say yes, there are still plenty of reasons to remain concerned, this because White House policy seemingly has the ability to shift without notice.

Which has helped produce what may be the golden rule that develops under the current circumstances. Stay alert, stay optimistic but practice caution. Financial institutions have always practiced the art of realpolitik behind closed doors to chase profits, but they must remain vigilant to fast reactions caused from the potential sudden fear of shifting doctrine. President Trump’s rather swirling mix of laissez faire enterprise, and his stark ability to express anger at those who stand in his way or disagree with him do make for a new trading reality. Cautious optimism is likely to rule the world of investment and speculation going forward.

post262

India Insider: Booming GDP & Fragile Foundations of Growth

India Insider: Booming GDP & Fragile Foundations of Growth

India’s economic footprint on the global stage is expanding significantly each year. As the world’s largest democracy, the nation achieved a remarkable 7.4% GDP growth rate January to March of this fiscal year. Yet, beneath this impressive headline, job creation remains tepid, overshadowed by slowing foreign direct investments (FDI) and lower corporate investments from India’s domestic market.

Despite Prime Minister Narendra Modi’s initiative to attract manufacturing into India and boost jobs, the manufacturing share of GDP has stubbornly clung to 16% for the last decade. While India’s services sector accounts around 55% of GDP, the IT and allied services sectors contributes a mere 3-4% of total employment. Even after the last two decades in which India’s Asian neighbors have shifted labor force out of agriculture and into high scale manufacturing, 45% of India’s workforce still are employed in agriculture and aligned services constituting only 15-17% of GDP.

Speculative Capital, Excessive Credit and Rising Financial Risk

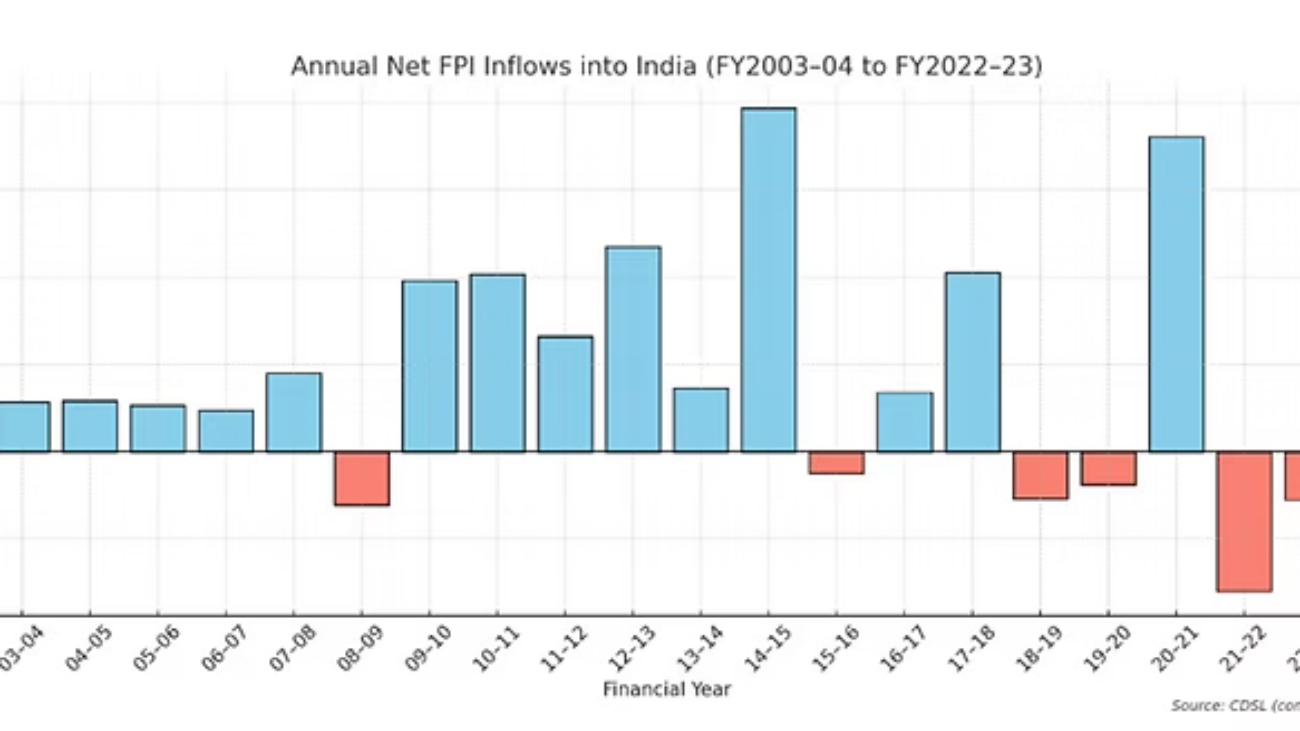
Between 2003 and 2023, India attracted approximately $275 Billion USD from foreign capital inflows, encompassing mostly equity and debt foreign portfolio investments. These capital injections are speculative in nature, primarily chasing returns in financial markets, rather than being directly invested into long-term productive infrastructure like manufacturing and export oriented industries.

Foreign Portfolio Investment into India 2003 to 2023

Interestingly, India’s public sector banks especially between 2008 and 2015 aggressively lent to infrastructure, real estate and capital intensive projects. The state owned banks tried to fill the gap left behind by private investors. A substantial share of these loans later turned into non-performing loans, exacerbating a duel crisis as corporate and bank balance sheets came under severe stress within a few years. The government of India stepped in and injected 3.1 lakh crore Rupees ($45 Billion USD) to recapitalize the struggling banks, and also orchestrated mergers of weaker banks with stronger banks. India’s citizens helped cover these costs via higher taxes and hidden banking charges.

Reserve Bank of India: FX Reserves and Liquidity Dynamics 

As of financial year 2025, the RBI’S Foreign Exchange Reserves stand at around $696 billion USD. While a stronger reserve buffer is crucial for maintaining external stability, the Reserve Bank of India’s purchase of foreign currency to build reserves leads to problems with domestic Rupee liquidity and creates liabilities for the RBI’s balance sheet. Unless it’s not fully absorbed via Open Market operations, it will end up as excess liquidity in the banking system.

Post 2020 and the Covid19 pandemic, loose monetary policy and excess liquidity within the banking system has culminated with more reckless lending. Unsecured retail credit particularly in personal loans, credit cards and consumer finance is troubling. Non-banking financial companies (shadow banking) and fintech enterprises also expanded rapidly into this segment and now pose risks.

India Falling into Debt Trap 

Per a recent survey conducted by the RBI,  household financial savings have sharply declined to a five decade low of 5.1% of GDP in FY2023, down from 11.5% in 2021. Concurrently, household liabilities have risen, particularly in the unsecured credit segment.

Delinquencies in small ticket personal loans and “Buy Now, Pay Later“ programs are on the rise, prompting the RBI to intervene recently with tightening of personal loan norms in late 2023. This dynamic suggests that excessive credit creation, unaccompanied by productive or real income growth, is fueling a fragile boom in consumption backed predominately by debt especially among middle and lower income groups.

Lower Net Foreign Direct Investment amid Higher Repatriation

Even with coordinated efforts from the likes of Apple, Foxconn (Hon Hai Technology Group) and other electronics companies setting up facilities, and the assembly of manufactured goods like iPhones as part of the “China Plus“ strategy, a more comprehensive method of doing business and improved proactive FDI policy is needed. Overall results are still falling short. Evidence shows many companies continue to choose Vietnam and Mexico over India, which is clearly reflected in the lower net FDI figures in India’s Balance of Payments. In financial year 2024-25, net FDI fell 96% to $353 million USD, caused by a surge of money being repatriated out of India led by foreign companies, and also increased foreign investments by Indian companies to other nations, per the Hindu magazine.

The irony is that India needs foreign capital to finance its current accounts deficit, long-term capital investment would boost jobs and increase wages. As the central Indian government practices an austerity drive and its corporations show an unwillingness to invest, India needs higher foreign capital at this crucial juncture. How will India achieve this task? Without better employment and raising wages, India’s celebrated growth faces risks from underlying cracks.

post261

Unpredictability of President Trump and the Markets

Unpredictability of President Trump and the Markets

Everyone wants to know what will happen in the future in the financial world. Most everyone also knows that this is impossible. However, clarity about the mid-term is a legitimate focal point that financial institutions strive. Risk managers define their considerations on assorted perspectives depending on their backgrounds.

While some may like him and others clearly are are not fans, President Trump has a reputation for wanting to get things done. His calling card for a long time has been an ability to make business deals. President Trump however has put himself in a rather difficult position and the next two weeks may prove to be an important milestone. One in which those who like the President and those who don’t will be given more credence to debate.

The Federal Reserve will announce their FOMC decision on the 30th of July. Tariff deadlines will supposedly come on the 1st of August. President Trump has made it clear he does not like the lack of aggressiveness which Fed Chairman Jerome Powell is displaying. Trump has called for the Federal Funds Rate to be cut and Powell has not acquiesced.

President Trump has openly spoken about trying to replace the Fed Chairman, but at this juncture the Trump White House knows this will be difficult unless they can prove Jerome Powell has done something maliciously. Not lowering the Federal Funds Rate because of a fear inflation will develop because of potential effects due to tariff fallout is a legitimate reason not to act. Even if the Fed Chairman is wrong, he appears to still be working on a basis which is based on an economic interpretation.

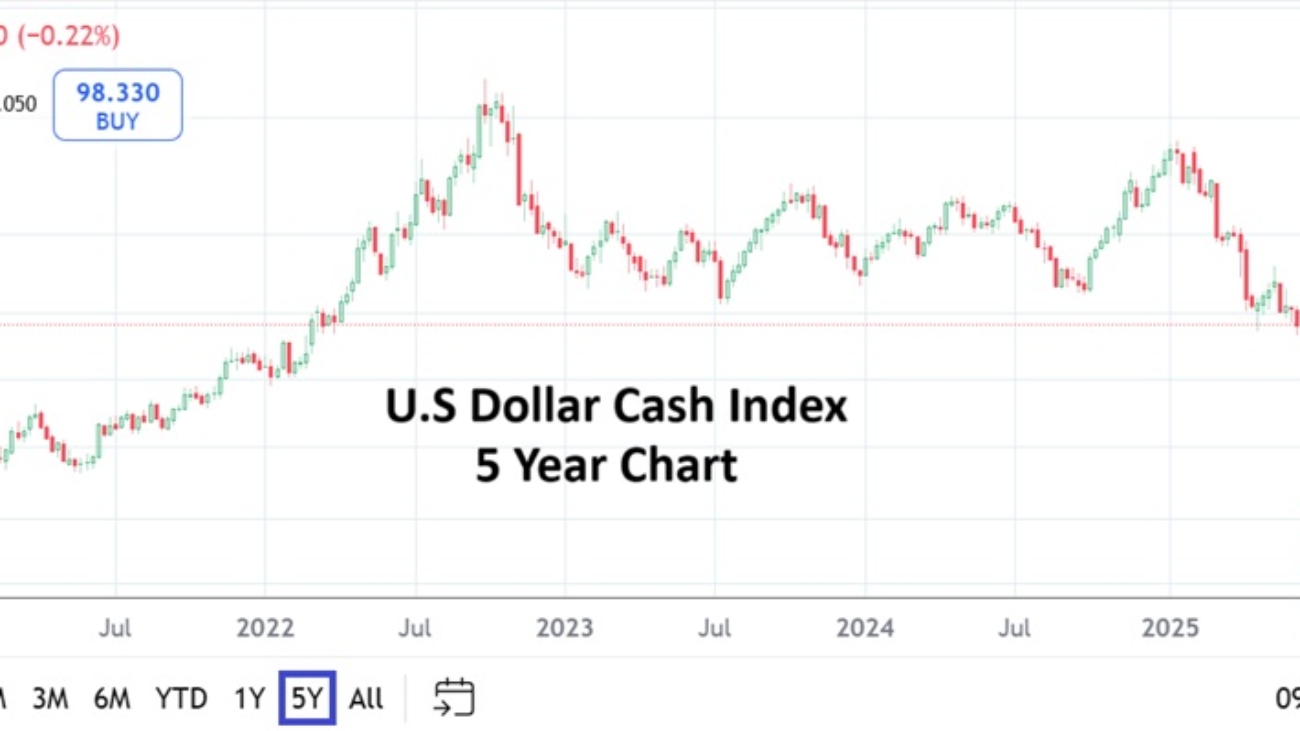
For the next two weeks the broad markets will hear about the Trump and Powell disagreement. It has been argued the Federal Reserve should have lowered the Federal Funds Rate a few months ago, clearly this was not done. However, the USD did trade with weaker sentiment in Forex from early April until the beginning of July. In the past few weeks the USD has garnered some strength, but remains within the lower part of its long-term realms via the U.S Dollar Cash Index. The weakness in the USD was likely due to financial institutions betting on rate cuts to come over the mid and long-term, and which they still believe will happen.

The upwards momentum generated recently by the USD has put the greenback in a position that seems to indicate financial institutions are transacting their cash forward orders cautiously for the moment, while waiting on the next round of impetus. And that is where Federal Reserve clarity and tariff threats now shadow mid-term outlooks.

U.S Dollar Cash Index Five Year Chart as of 21st July 2025

We have entered an unpredictable window and President Trump apparently doesn’t mind allowing a little danger into the mindsets of the financial markets. It is one thing to proclaim tremendous results and great, magnificent prospects, but how long will investors tolerate a lack of clarity regarding tariff agreements? President Trump has postponed the tariff deadlines several times and what should be considered is the potential that at some point he will have to take action to prove he means business. If the August 1st deadline is extended again this may not cause much of a shock, but it will not be met with optimism.

Instead, the main interpretation from financial institutions may be that Trump is struggling to get agreements done as he had promised. While that might lead to the idea that global commerce will continue on as is, this will certainly not help create the positive impetus which President Trump desired. At some juncture President Trump may begin to be perceived as the little boy that cried wolf. No one will pay attention and the markets will proceed without him. But President Trump will not likely let that happen, he does like attention.

The Nasdaq 100 and the S&P 500 are near record highs, so there isn’t a lot to complain about by index investors. The U.S economy has shown signs of green shoots regarding better retail sales and the recent Philly Fed Manufacturing Index. The grey area for many remains inflation, which has been coming in rather well behaved although the most recent report showed a slightly higher outcome with the yearly CPI reading. However, the Federal Reserve actually has evidence that inflation has been tame. Yes, there are questions regarding the coming influence of tariffs on the U.S economy, but for the moment inflation has not risen.

The lack of clarity and not having a mid-term comfort level which is unperturbed may be problematic for small U.S business owners that face tariff concerns on their imported goods. And the bigger picture remains unclear for large U.S corporations – but they certainly continue to try being optimistic. And this is where it gets more dangerous, plenty of perspectives are being driven (inspired) by analysts who have confirmation bias. For instance the downturn in the USD from April until early July was amplified by many who saw this as a sign the USD was being punished by foreign governments opposed to President Trump. This in fact was highly unlikely, traders need to remain alert to false narratives.

The next two weeks need to be treated carefully. There will be a running monologue among many analysts that changes daily as behavioral sentiment moves depending on what is being spoken about the Federal Reserve and tariffs. However, until there are actual answers the financial markets are likely to remain rather choppy. Self awareness will be crucial for speculators. Also, a large factor in the financial markets will be played by the U.S White House regarding how incoming results are presented. Until then day traders may want to watch technical charts and try to figure out where programmed trading lurks regarding support and resistance levels. Price velocity in Forex, bond yields and gold should be monitored.