India Vote 20260507

India Insider: How a Film Star is Reshaping Politics in Tamil Nadu

Vijay: A Stunning Victory by an Actor Turned Politician in India

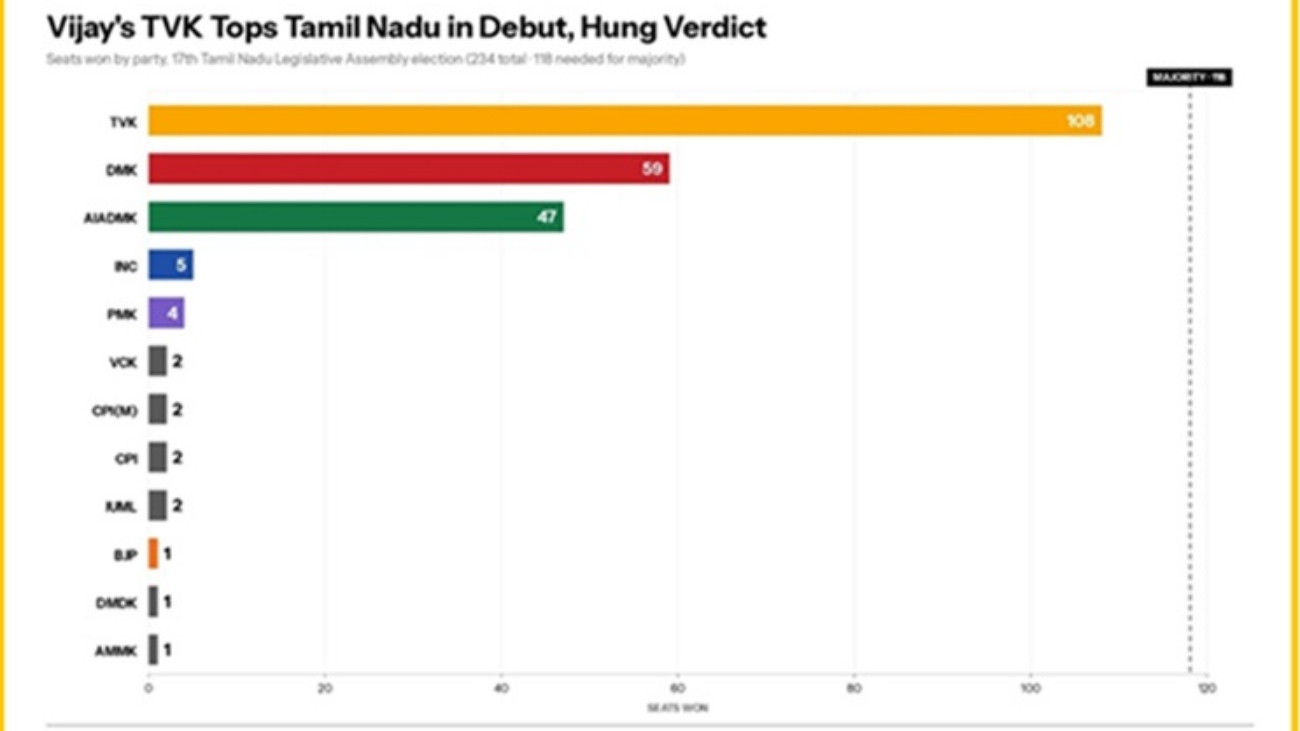
When the Tamil Nadu state election results were announced this Monday, many people were stunned that a party with barely two years of political existence had managed to unseat parties that had dominated the state for more than 75 and 50 years respectively.

TVK (Tamizhaga Vetri Kazhagam), founded by actor turned politician Vijay, used his charismatic presence in Tamil cinema along with the power of social media to attract Gen Z voters and women.

This came despite the incumbent DMK (Dravida Munnetra Kazhagam) government under Chief Minister M.K. Stalin being widely credited for stable governance and helping Tamil Nadu remain one of India’s fastest growing state economies, with a GSDP( Gross State Domestic Product) growth rate of 11.9%.

Voting Results in Tamil Nadu and TVK Topping the Results

The two major Dravidian parties – DMK and AIADMK (All India Anna Dravida Munnetra Kalagam) were originally built on the foundations of social justice, welfare, and development. For decades, they shaped Tamil Nadu’s political identity and succeeded in winning the trust of the people.

However, despite the DMK government’s governance record, allegations of corruption, nepotism, and cash for votes politics continued to surround both DMK and ADMK. These criticisms have become deeply embedded in public perception over the years.

Today’s Gen Z voters appear to want change. Many were looking for a fresh political face capable of reshaping Tamil Nadu’s political landscape.

Vijay’s party reportedly secured around 1.67 crore votes, or approximately 34.3% of the total vote share, one of the strongest performances ever recorded by a newly formed political party contesting its first major election.

India’s political landscape has also been evolving rapidly in recent years. Prime Minister Narendra Modi and the BJP have successfully consolidated much of North India politically and are now working aggressively to expand their influence in southern states such as Telangana, Karnataka, and Tamil Nadu.

For Modi, strong regional opposition leaders such as M.K. Stalin in Tamil Nadu and Mamata Banerjee in West Bengal have remained major political challenges. Any significant political shifts in states like Tamil Nadu and West Bengal could reshape India’s national political dynamics in the years ahead.

While corruption, nepotism, and vote buying are important issues to consider, it is also necessary to distinguish between political allegations and governance outcomes.

In many ways, the DMK government performed better during the last five years than several previous ADMK and DMK administrations. Social indicators are impressive while Tamil Nadu State has attracted billions of USD investment for iPhone and automobile manufacturing.

During the election results, I was driving through Tiruvannamalai in northern Tamil Nadu and noticed that the streets were unusually silent. There were hardly any people celebrating openly.

If another traditional Dravidian party had won, the roads would likely have been filled with supporters distributing sweets and celebrating publicly.

For the first time, it felt as though a major electoral victory had been shaped more by social media influence and public perception than by traditional ground level welfare based political desires.

On my way back home on Monday, I saw an elderly man sitting at a bus stop equipped with fans that helped ease the intense summer heat.

That moment made me wonder: in the next five years, will political change alone truly improve the lives of ordinary people?

Or will charisma and digital influence matter more than governance, infrastructure, and social-welfare in the long run?

Copy and paste the text from AMT that you want to share

Water India Graph 20260430

India Insider: Water Crisis Has Turned From Severe to Critical

India Needs Sustainable Water Security With Improved Infrastructure

India’s population has been expanding at a rapid pace and stands at 1.4 billion. Due to the urbanization process, industrialization in cities like Chennai, Mumbai and Delhi must continue to emphasize improving public infrastructures in order to maintain vital growth.

The growing population and urbanization adds noteworthy stress to the nation’s water bodies. With more people living in increasingly congested areas and pumping large amounts of water via borewells, groundwater levels are rapidly diminishing.

For instance, India consumes roughly 761 billion cubic meters of water per year, making it the largest water consumer in the world, ahead of China and the United States. 85% of rural India is dependent on ground water for agriculture and consumption, this because lake and pond water are not accessible. Rural India suffers from a lack of maintenance and sewage water that often contaminates these important sources.

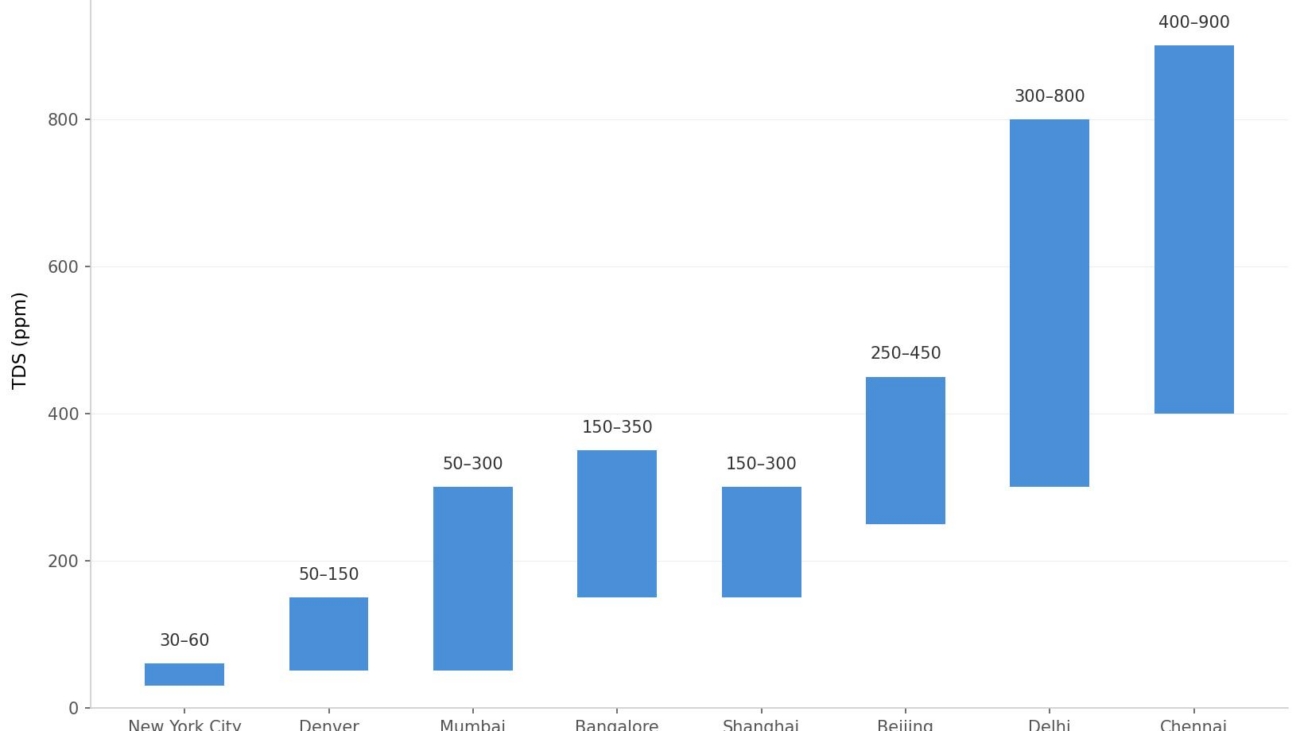
Tap Water via Total Dissolved Solids Comparison in Various Cities Worldwide 

Only a few years ago, water facilities provided by municipalities and urban systems were relatively accessible in India. Low and middle income households relied on pipelines, wells and tap water for their daily usage. However, with sharp rises in population, government capital expenditures on water pipelines and sanitation has not kept pace and often fails to meet needs.

For example, rainfall in Chennai City always ends up staying on roads and platforms in the last few years, this despite the city’s infrastructure which has expanded multifold. In many parts of Chennai, water contamination has become severe with high levels of iron, hardness, turbidity and nitrate levels visible. The government has been inefficient when addressing the contamination. As I witnessed in 2019, many parts of Chennai cannot use ground water due to inadequate rainfall, storage and lack of proper municipal supplies.

And due to excessive extraction of ground water and an inability to channel rain water into the ground, many parts of Tamil Nadu now report total dissolved solids (TDS) ranging from 500 to 1000 parts per million, reaching extreme levels of 3000–5000 ppm in some areas. The World Health Organization recommends much lower levels for safe and palatable drinking water.

Water treatment for households using reverse osmosis plants, which were not normal a few years back have become essential for people seeking safe drinking water. Despite being a coastal region , cities like Chennai cannot rely solely on seawater desalination to meet their drinking water needs. While desalination plants contribute to supply, they account for only a fraction of total demand.

Desalination is an energy intensive and expensive process, making it difficult to scale for universal, affordable access. More importantly, producing water is only one part of the solution and delivering it efficiently remains a major challenge.

India endures 3 to 4 crore (30–40 million) waterborne disease cases every year, mostly from contaminated drinking water. As borewells go deeper, they draw water containing high concentrations of fluoride, arsenic, nitrates, and heavy metals. This creates significant health risks, especially for low income households that cannot afford advanced purification systems. The depletion crisis and contamination crisis are increasingly converging.

Due to rapid urbanization and high population with inefficient audits, many water bodies such as lakes and ponds have been encroached upon by the real estate sector or contaminated by waste disposal by surrounding settlements. This is quite visible in Chennai.

Experts claim that many water officials do not have a clear understanding of how pipeline networks are laid out across cities. As Frontline magazine columnist Vedaant Lakhera wrote in April 2026, India’s water crisis stems less from hydrological scarcity and more from a failure of governance.

The absence of water sensitive designs have allowed cities to expand unchecked, almost freely, contaminating local water sources such as lakes and ponds. This has led to a significant depletion of groundwater availability, which were supposed to act as reserve water reserves.

Addressing this crisis requires a multi-dimensional approach. Rainwater harvesting must be scaled to improve groundwater recharge and long-term availability, while modern purification systems remain essential to ensure safe consumption in the short term. At the same time, systemic reforms such as regular pipeline audits, mandatory replacement of ageing infrastructure, and better urban water management are critical to prevent contamination at its source.

Without such integrated efforts, cities will continue to face a paradox of water scarcity amid abundance. Sustainable water security in India does not depend only on how much water is available, but on how effectively it is managed, protected and delivered.

Copy and paste the text from AMT that you want to share

Hospitalization Costs 20260421

India Insider: Rising Hospitalization Costs a Growing Concern

Indian Households Face Rising Expenditures for Hospitalization and Critical Care

Many households in India face unexpected hospital expenses that have become almost routine in today’s environment. Rapid urbanization, unclean drinking water, poor air quality due to carbon emissions and industrialization have hit low and middle income homes harder than upper income families. These households are increasingly exposed to diseases that require critical treatment, but the government institutions are ill-equipped to handle the growing patient loads. As a result, many Indians are forced to seek treatment in private hospitals, where costs are significantly higher.

Consider that a middle income household in Madurai earns roughly between 15,000 to 20,000 Rupees per month per person. This per the Periodic Labor Force Survey 2023-2024 Annual Report. So if two people are working in a family, it means empirically, we can estimate the income between 35,000 to 40,000 per month. We need to compute the family’s expenditures – if one member is hospitalized for critical illness or gets hospitalized treatment in private and public hospital.

Even if the income range for this family is better than median estimates, their capacity to absorb medical shocks are limited due to high baseline consumption and minimal household savings.

In the case of hospitalization in a government facility, out of pocket expenditures such as medicines, diagnostics, transport, and wage loss can amount to 12,000 to 40,000, effectively deducting one to two months of household income.

In other words, families need to spend out of pocket by borrowing to finance these gaps for consumption and medical expenses.

However, if a family is forced to take treatment in a private hospital, they would be spending 100,000 to 500,000 Rupees in critical cases, their total spending as a higher percentage of net income and is close to 1,250% in extreme cases.

The Role of Savings and Informal Safety Nets

As observed during Covid-19 and other crises, Gold has often acted as a financial buffer for Indian households.

Families that save during stable periods are able to pledge or sell gold in times of distress, helping them to manage medical expenses without relying entirely on high cost borrowing.

In contrast households without many buffers, often turn to informal lenders or personal loans, where interest rates can range between 36 to 60% compounding the financial distress.

Looking at Government Data for Clues

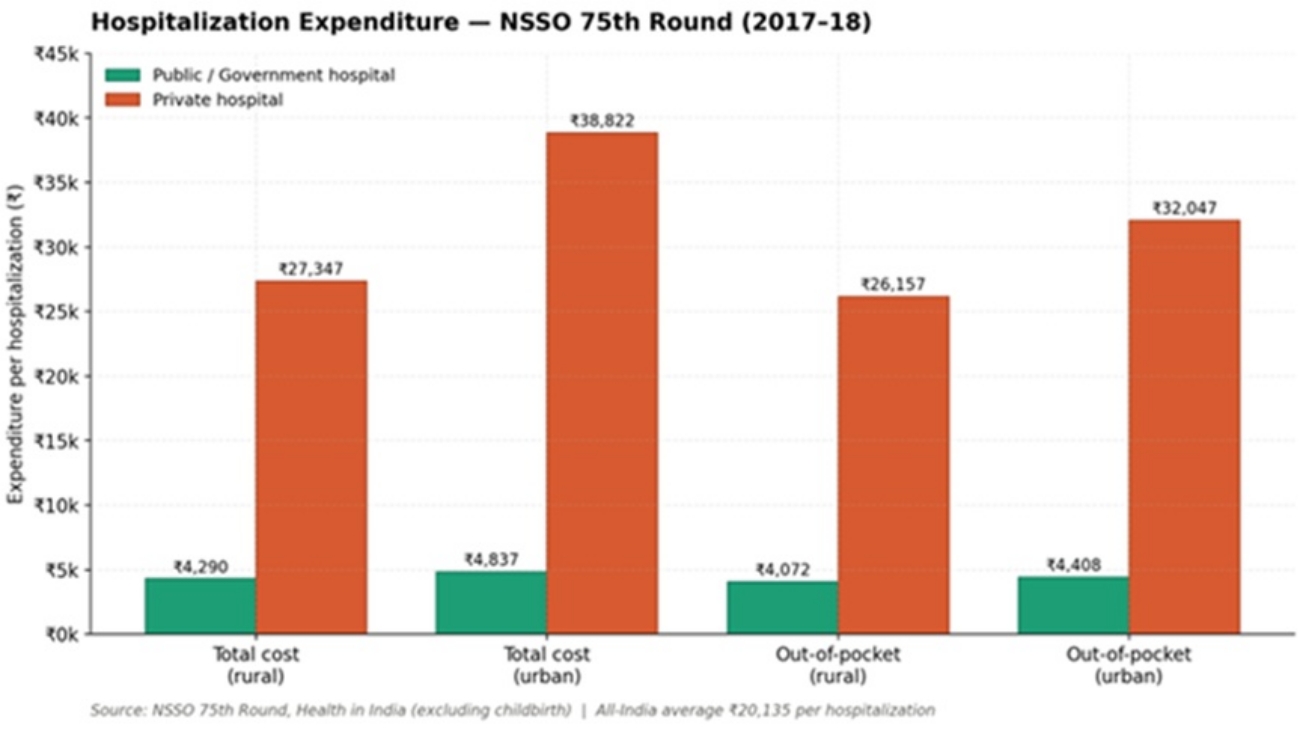
The most authoritative survey on household expenditures on hospitalization comes from National Sample Survey Office’s (NSSO) “Health in India” (2017-2018), and it showed the costs for those hospitalized in private facilities were eight times costlier than government facilitys.

An average hospitalization (excluding child birth) cost 4,290 Rupees in a rural government hospital, and 4,837 in an urban government hospital. The same scenario in a private hospital cost 27,347 in rural India and 38,822 in urban India. Out of pocket expenditures – the amount families pay themselves, follows the same pattern with families having to pay out about 4,000 Rupees in government hospitals, versus 26,000 – 32,000 Rupees in private ones.

Hospitalization Expenditure by Hospital Type and Sector, NSSO 75th Round (2017-2018). Source: MoSPI, Ministry of Statistics.

These were already catastrophic figures for a typical household in 2017-2018. A single private hospital admission cost more than a month’s wages for most Indian families, and it is getting worse.

Seven Years of 12-14% Medical Inflation

Since 2018, the cost of being hospitalized in India has risen at a pace that outstrips almost every other category of spending: Millman’s 2025 medical inflation report pegged the rate at 12% in 2024, more than triple the general CPI inflation of 4.2%.

An urban private hospital admission that cost 38,822 Rupees in 2017-2018 now is in a 76,000 – 91,000 price range, this while real wages are stagnant and not growing. Recent RBI Household surveys conclude that Indians absorb higher debt in order to manage their household expenses.

Critical Illness Can Wipe Out a Household’s Future

Critical illness like heart attacks, a cancer diagnosis, renal failure, kidney transplants costs even more in India – and the problems grow unbearable for Indian families after they are forced to take on more debt. For example, a heart angioplasty with stent that costs 100,000 in 2018 now costs between 200,000 – 300,000 Rupees in private hospitals.  A kidney transplant which costs 400,000 – 600,000 a decade ago now costs 1 million to 1.5 million Rupees. A full course of chemotherapy ranges from 250,000 for early stage diseases to 2.5 million Rupees for advanced cases requiring targeted biologics.

Cost ranges for major critical illness in India, 2024-2025, green bars show public hospital costs, orange bars show private hospital costs. Sources: ACKO India Health Report 2024, HCG Oncology, Hospital Quote Data from Apollo, CARE and others.

Where the Indian Household Stands

As per periodic labor force surveys, the median Indian worker earns 10,000 Rupees a month. The Economic Survey in 2024-2025 recorded average monthly earnings of 13,279 for self-employed workers, 20,702 for salaried workers, and 12,750 for casual laborers. Crucially, only the top 22% of the India’s labor force earns more than 15,000 Rupees per month.

Monthly household income distribution, rural vs urban India (2023-2024). Sources: Periodic Labor Force Surveys, Azim Premji University Income Distribution Study 2019-2024.

Statistically, the household we have taken for the reference is not a poor household by national standards. It is comfortably above the rural and urban median, sitting in the top fifth of the country, and this is what makes the rest of the story so troubling. If this household cannot afford a critical illness, almost no household outside the urban upper middle class can afford rising hospitalization costs.

The Insurance Gap

The government of India has expanded insurance schemes for low income households since 2018 via the Ayushman Bharat PM-JAY with 500,000 Rupees coverage. But the scheme which was set many years ago, does not match the current medical costs scenarios. Income eligibility is an another problem where a majority of people who earn in the middle, slip out of the government insurance schemes and have to take private insurance to cover their health risks. Health insurance penetration in India is low at 3.7% of GDP, well below global statistical standards of 7%.

Across much of India, a single critical illness can effectively destroy years of household income accumulation and trigger debt dependence. In the absence of stronger public healthcare delivery, and without deeper insurance penetration at affordable costs providing better claims services, and lacking robust risk sharing mechanisms – escalating medical costs could act as a drag on India’s economic growth trajectory by weakening household balance sheets.

Notes: 1 USD = 93.24 INR

Copy and paste the text from AMT that you want to share

India Insider GDP Savings and Investment 20260408

India Insider: Education, GDP and Personalized Growth a Difficult Balancing Act

Is India Still 'The Country of the Future'?

In 1991, when India’s foreign exchange reserves had dwindled to barely three weeks of import cover, the government pledged its gold to the Bank of England. It was a moment of humiliation and, paradoxically, of liberation as the crisis forced an opening that three decades of socialist planning had resisted. Fast forward into 2025: India is a $4.1 trillion USD economy, the world’s most populous nation, with a moon rover, a thriving startup ecosystem, and a digital payments infrastructure the developed world now studies with envy.

This article asks if India is still ‘the country of the future’ using the same growth determinants framework applied by Professor Manoel Bittencourt to Brazil, and argues that the answer lies not primarily in corruption (though it matters), not in policy failure (though that matters too), but in two structural features that resist easy reform: the vast informality of the Indian economy, and the depth of its inequality.

Does Growth Matter? The 70/g Rule Applied to India

Before diagnosing India’s problems, we must appreciate what it has already achieved. Using the 70/g rule which tells us how many years it takes for income per capita to double at a given growth rate – India’s average GDP growth of roughly 6.5% since 1991 implies a doubling of income every 11 years. That is extraordinary by historical standards.

But averages mask distributions. If growth accrues predominantly to the formal sector – the top 10% of earners who hold formal employment, own financial assets, and participate in the organized economy, then the 70/g rule tells a story of elite enrichment, not a broad based development. This is India’s core dilemma.

The Eight Growth Determinants: India in the Data

Bittencourt’s framework identifies eight standard growth determinants: savings, fertility, rule of law, government consumption, trade openness, education and health investment, inflation, and finance. Let us examine some of each through Indian data, with Brazil as our comparator.

Savings & Investment

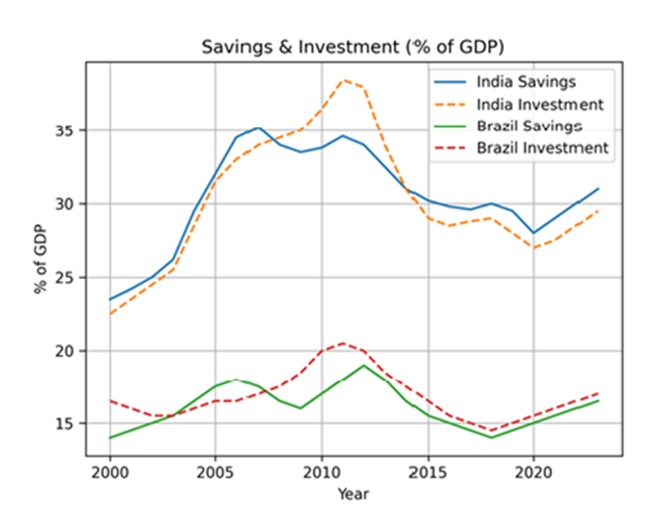
India’s gross savings rate has historically been a strength hovering around 30–32% of GDP through the 2000s and 2010s. But the investment picture is more troubled. Fixed capital formation has declined since its peak around 2011–12, driven by a stressed banking sector, weak private investment appetite, and an infrastructure gap. Brazil shows a similar pattern of savings-investment divergence  but India’s gap has widened more sharply in recent years.

Gross Domestic Savings and Fixed Capital Formation. India vs Brazil. 2000-2023

Education & Health Spending

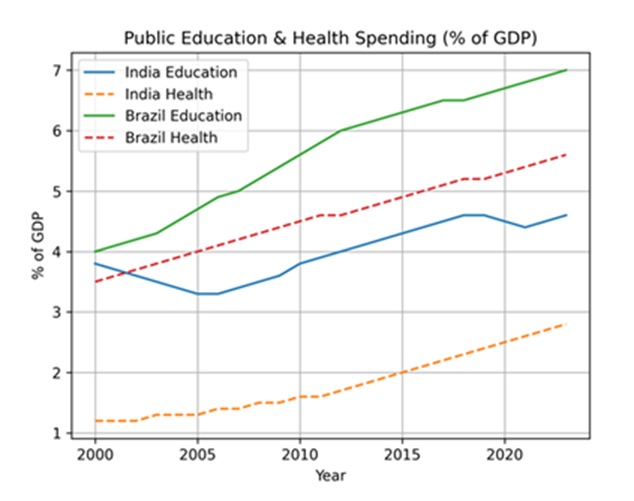
Perhaps nowhere is India’s “policy-delivery gap” more apparent than in social spending. India spends approximately 4.5% of GDP on education and just over 3% on health, and both figures are well below what comparable middle income countries invest. Brazil, despite its own fiscal struggles, consistently outspends India on health as a share of GDP. The consequences are visible in learning outcomes: the Annual Status of Education Report (ASER) consistently finds that a significant share of Indian schoolchildren cannot read a simple paragraph or perform basic arithmetic.

This matters enormously for growth. An economy hoping to absorb millions of workers into formal, productive employment each year needs those workers to arrive with usable skills. When they do not, informal low productivity employment becomes the default  and cycles of informality perpetuate.

Government Spending on Human Capital. India vs Brazil. 2000-2023

The Thesis: Informality as Structural Trap

Bittencourt identified corruption as the growth killer in Brazil. For India, the more precise diagnosis is informality and the inequality it both reflects and reinforces.

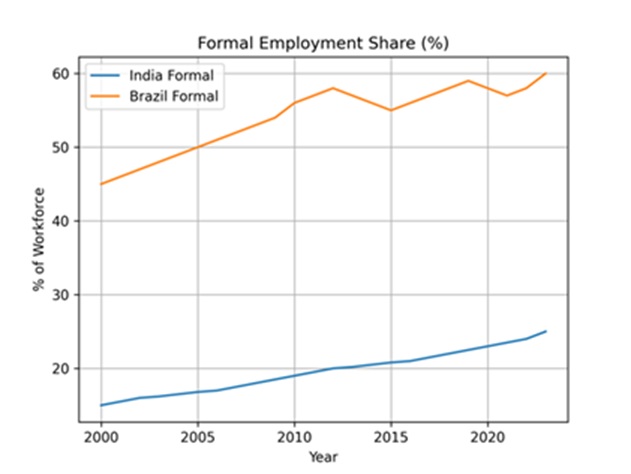
Consider the arithmetic: approximately 80% of India’s workforce is informally employed who are working without contracts, without social protection, without access to formal credit, and largely invisible to the tax system. This informal mass produces perhaps 50% of GDP. The productivity gap between the formal and informal sectors is staggering, and it does not shrink naturally with overall growth.

Share of Workforce in Formal Employment. India vs Brazil. 2000-2023

Brazil is itself a country with significant informality, but its formal sector share has grown meaningfully since the early 2000s, driven by the expansion of the Bolsa Família program, minimum wage policies, and labor formalization drives. India, by contrast, saw its already small formal sector shrink as a share of total employment after demonetization in 2016 and the disruptions of COVID-19. The gap between the two countries on this metric is instructive.

Inequality: When Growth Passes People By

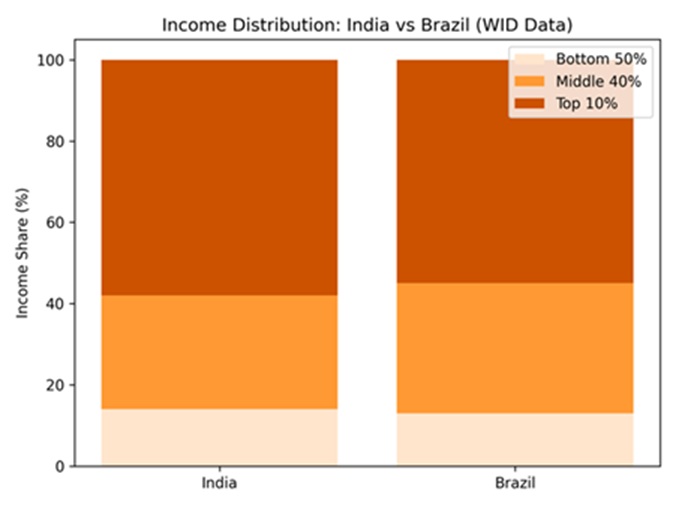
India’s Gini coefficient – a standard measure of income inequality – has risen over the reform era even as aggregate poverty has fallen.  It shows the signature of unequal growth. The bottom quartile has seen real income gains, but the top decile has captured a disproportionate share of the growth dividend. Recent estimates suggest that India’s top 1% now hold a larger share of national income than at any point since Independence.

Income Distribution India vs. Brazil.

Compare this to Brazil, which, despite its own severe inequality, pursued deliberate redistributive policies through the 2000s with Bolsa Família reaching 14 million families at its peak and a concerted minimum wage policy. India’s equivalents – the MNREGA rural employment guarantee, PM-Kisan farm payments are larger in coverage but smaller in benefit size at this stage, and reach informal workers imperfectly.

The Structural Complications

A purely data driven analysis, as Bittencourt himself acknowledged for Brazil, understates the depth of the challenge. India’s informality is not simply a policy failure, it is rooted in structures that predate modern economics.

The caste system, legally prohibited but still socially persistent, has historically sorted populations into occupational roles and those at the bottom of the hierarchy were systematically excluded from property ownership, formal education, and credit. Colonial de-industrialization destroyed the artisan economy that might otherwise have been a pathway to formal employment. The fragmentation of the federal system with 28 states running effectively different labor markets, land acquisition regimes, and social programs means that a policy that works in Tamil Nadu may fail in Uttar Pradesh.

These are not excuses. They are explanatory variables that any honest growth analysis must include.

What Does Growth Theory Tell Us to Do?

The prescription is not mysterious. If informality is the barrier, then the priority is to make formal employment more accessible through labor law simplification, portable social insurance that follows the worker rather than the employer, and a genuine skill based learning infrastructure that reaches the rural poor.

If inequality is the barrier, then the priority is redistribution that enhances human capital at the bottom – not cash transfers alone, but the quality of the school your child attends and the clinic your mother can access. India has the architecture of such systems; it does not yet have substantive results.

The demonstrators on India’s streets – whether farmers in 2020-21, or youth protesting paper leaks, or contract workers demanding permanence – know this intuitively. They are not asking for charity. They are asking to be absorbed into the formal economy that has prospered around them.

Conclusion: Is India Still the ‘Country of the Future’?

The answer to the question is Yes, and it is both an achievement and an indictment. India has built a moon program and yet cannot reliably staff a primary school. It has produced the world’s most used digital payments system and left 200 million people without bank accounts until recently. It exports software engineers to Silicon Valley, while its domestic labor market cannot absorb graduates at scale.

Brazil, our comparison, has struggled with its own version of this duality longer. But Brazil’s welfare state, however fiscally stressed has created a floor. India’s floor is thinner, and the drop beneath it steeper.

Informality is not the destiny for any developing economy. South Korea was deeply informal in the 1960s, China was an overwhelmingly rural agrarian nation in 1980. Both made transitions through deliberate, state led investment in human capital and formal employment creation. The path is known. The question for India in 2026 is whether the political will exists to progress via focused programs, or whether fifty years from now someone else will write another article illuminating the same structural problems.

Article Notes:

Data sources include the World Bank World Development Indicators, ILO Labour Statistics, Transparency International Corruption Perceptions Index, ASER Centre (India), UNESCO Institute for Statistics, and IMF World Economic Outlook. Growth determinant categories follow Barro (2008) as synthesized by Bittencourt.

Copy and paste the text from AMT that you want to share

Indian Diaspora 20260325

India Insider: Why the Gulf Remains a Vital Economic Lifeboat

Indian Expat Labour and Recalibration Realities

The skyline of Dubai, once a symbol of untouchable prosperity, now sits under a shadow of regional recalibration. As Reuters recently noted, Dubai has successfully transitioned to a non-oil economy, with oil accounting for less than 2% of its GDP. It is now a powerhouse of trade, high-end real estate, and financial services. 

However, its “backyard” – the Strait of Hormuz – remains a strategic bottleneck. With 20% of global seaborne crude passing through this narrow vein, the recent tensions in March 2026 have forced a shift in perception: the Gulf is no longer an insulated sanctuary, including Dubai where millions of Indians work and earn for their families in India.

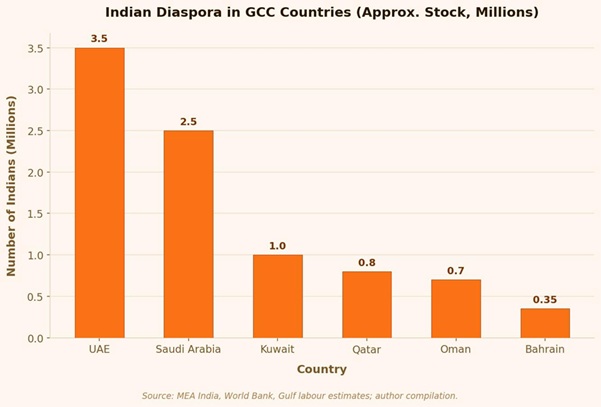
Indian Diaspora Gulf Representation

The scale of this “labour export” is enormous. As of early 2026, approximately 9.5 to 10 million Indians live and work across the GCC (Gulf Cooperation Council) countries. To put that in perspective, that is nearly the entire population of a country like the UAE, made up solely of Indian expats.

A Remittance Driven Economy

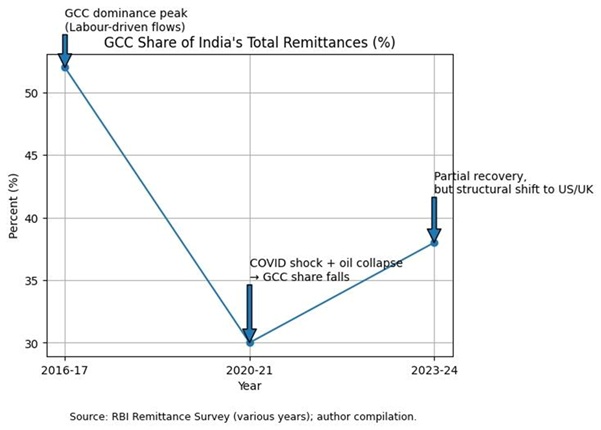
As per Government data sources, India remains the world’s top remittance recipient, with total inflows hitting a record $135.4 billion in the last fiscal year. And despite a rise in high-skilled migration to the US and UK, the GCC remains a juggernaut, contributing roughly 38% of India’s total remittances.

For states like Tamil Nadu, Kerala, and Maharashtra, which receive nearly 50% of these total inflows, it is a macroeconomic stabilizer that funds the current account deficit and keeps the Rupee from a freefall.

India’s Labour Market Paradox

But here is the real question, if people return to India due to the crisis in the Middle East, are there any “good quality” jobs waiting for them in India? The honest answer is no.

Youth unemployment remains elevated, particularly among graduates. Engineers in mechanical and construction fields face limited opportunities. Outside IT, and to some extent automobiles, there are not enough stable, high-paying jobs.

So people adjust. You will find postgraduates working in delivery jobs and informal sectors. I have personally spoken to Amazon delivery workers who told me they hold M.A degrees, or that they had worked in Dubai or Singapore before Covid and are now trying to leave again. This is becoming norm nowadays.

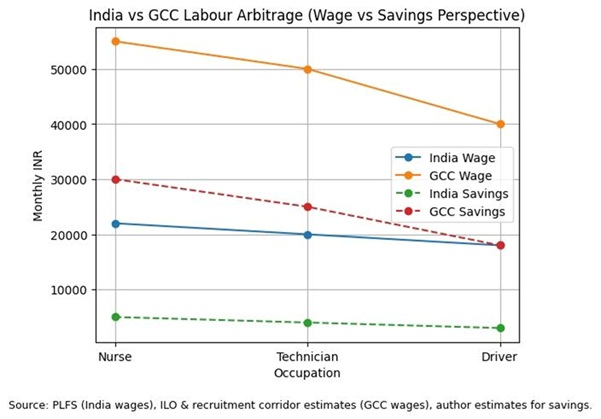
Indian National Wages and Savings Compared to Expat GCC Averages

In many towns in India, migration itself has become an economic model. People move to Singapore, Malaysia, or the Gulf, and the money they send back drives real estate, consumption, and local business activity. In many such regions, the labour market feels tight, not because jobs are available, but because the workforce has already left.

The wage gap explains everything. A nurse or lab technician in India may earn ₹15,000–₹20,000 per month. The same person can earn close to ₹80,000 in the Gulf. A private school teacher in Villupuram city in Tamil Nadu state earns around ₹8,000.

While nominal wages are  2–2.5x higher in GCC, the true driver of migration is savings arbitrage , which can be 5–6x higher.

This reflects structural differences in labour productivity and capital intensity.

India has a large pool of educated labour. But instead of becoming an advantage, it has turned into a wage suppressing force. There is always someone willing to work for less. As a result, wages remain low and bargaining power stays weak.

Percent of India’s Remittances From The GCC

At the same time, we are told growth is strong. Yes, the labour force participation is rising, but inequality is also increasing. A large share of employment remains informal and unstable. Inflation continues to erode purchasing power, and disposable incomes remain under pressure.

Right now, for many Indians, prosperous conditions are easier to find outside the country. Yes, the Gulf has risks. However, geopolitical tensions will come and go, and these are short-term disruptions.

Structurally, GCC economies will stabilize and grow again, and when they do, the flow of Indian labour will continue to pursue these opportunities. Because until India creates enough high-quality jobs at scale, migration will not slow down.

Copy and paste the text from AMT that you want to share

Outflows 20250220a

India Insider: Macro Stress a Capital Flow Problem, Not a Trade One

India Insider: Macro Stress a Capital Flow Problem, Not a Trade One

Editor’s note: This article was originally written in January 2026. It has been updated to incorporate developments through February 2026, including the U.S – India interim trade agreement and subsequent capital flow data.

India is currently experiencing what can best be described as macro stress. By macro stress, we mean pressure across the broader economy that shows up simultaneously in the currency, financial markets, and capital flows, rather than a problem limited to one sector or company. In India’s case, this stress is visible in a weak rupee, persistent foreign investor outflows, and rising concerns about equity valuations.

This stress is often misinterpreted as a trade or export problem. In reality, the pressure on the Rupee and the growing fragility in equity markets stem primarily from the capital account, not from collapsing exports or remittances. Even as the U.S Dollar softens – helped by Federal Reserve rate cuts and renewed trade tensions under U.S President Donald Trump, India continues to struggle to attract foreign capital, exposing a deeper structural imbalance.

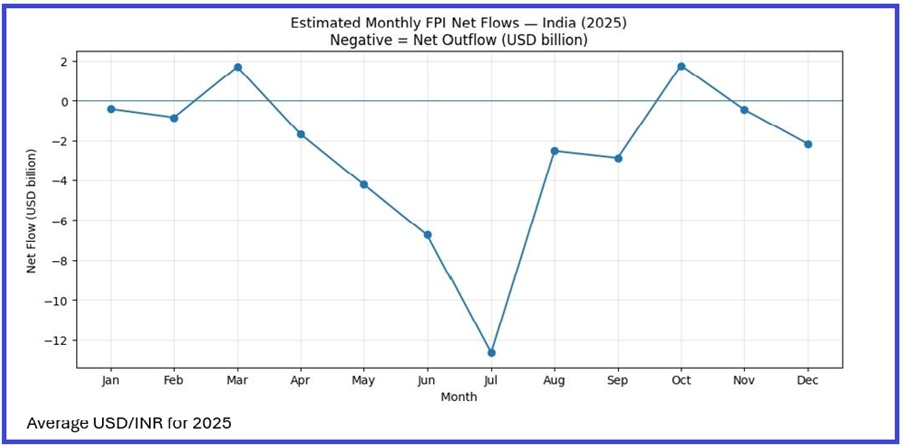
Source: NSDL (FPI Equity Flows): Reuters and author’s calculations.

Recent weakness in the USD would normally support emerging market currencies and risk assets. This time, however, the response across emerging markets has been uneven. Capital has flowed toward economies linked to artificial intelligence, semiconductors, and commodities, as well as toward markets where valuations have already adjusted. South Korea, Hong Kong, Chile, and South Africa have all benefited from this rotation. India has not.

The Rupee’s weakness reflects this divergence. USD/INR continues to trade around ₹91.5–91.6 despite the absence of a sharp deterioration in India’s trade fundamentals. Services exports, particularly IT services, remain resilient, and remittances continue to provide a steady source of foreign exchange. This brings us to the current account.

The current account represents a country’s net trade balance with the rest of the world, including goods, services, and remittances. India runs a current account deficit, meaning it imports more than it exports. While this deficit persists, it is manageable at present, supported by stable services exports and remittance inflows.

The real problem lies in the capital account, which tracks investment flows such as foreign investors buying or selling Indian equities and bonds. When foreign capital flows into the country, it helps finance the current account deficit. When it flows out, pressure builds quickly on the currency and financial markets.

Foreign capital is neither entering India in sufficient scale, nor remaining invested. Portfolio outflows have become persistent, and this has emerged as the dominant driver of currency pressure. In calendar year 2025, foreign portfolio investors sold approximately USD 19–20 billion worth of Indian equities, marking one of the largest annual equity outflow episodes in recent years. Importantly, this selling has been sustained rather than episodic, pointing to a structural reassessment of India’s growth outlook and valuation premium rather than a temporary risk off shock.

Crucially, this capital flight is not the result of a collapse in exports to the United States. Despite tariff concerns, the U.S remains India’s largest export destination. Between April and December 2025, Indian exports to the U.S rose to roughly $65–68 billion, compared with $60–63 billion during the same period last year. Trade flows, for now, are holding up better than sentiment suggests.

The effects of capital account stress are most visible in financial markets. Indian equities are failing to attract foreign inflows as growth momentum weakens. Market leadership has narrowed, with headline indices supported by a small group of large-cap stocks, while consumption-sensitive sectors such as FMCG remain under pressure.

This dynamic fits squarely within the balance of payments framework described by Professor Michael Pettis. He described, “a country cannot sustainably run a current account deficit without stable capital inflows. When capital inflows weaken, the adjustment shows up through a weaker currency, tighter financial conditions, and pressure on asset prices.”

Indian equities now trade at some of the highest valuation multiples globally, supported largely by domestic retail and mutual fund flows. However, domestic capital is structurally constrained, while global investors can freely reallocate. As Bloomberg’s Andy Mukherjee recently noted, Indian cement stocks now trade at higher valuations than Hong Kong Tech stocks showing the exuberance of Domestic equity capital chasing local themes.

At a deeper level, India’s vulnerability reflects a structural imbalance between savings and investment. Domestic savings are insufficient relative to the economy’s long term investment needs, and the financial system lacks the institutional capacity to consistently channel savings into productivity enhancing investment. As a result, growth has become increasingly dependent on mobile foreign capital – capital that is cyclical, return sensitive, and easily reversible. It is this dependence, more than any near term trade shock, that leaves the Indian rupee vulnerable when global capital flows turn cautious.

Update: The US–India Interim Trade Agreement (February 2026)

Since this article was first written, a significant development has reshaped the near-term outlook. In early February 2026, the United States and India reached an interim trade agreement. As part of the deal, the US lowered its reciprocal tariff on Indian goods from 25% to 18%. President Trump also signed a separate executive order removing an additional punitive 25% tariff that had been imposed as a penalty for India’s purchases of Russian oil, meaning the effective tariff burden on Indian exports had, at its peak, approached 50% before being brought down to 18%.

The announcement acted as an immediate sentiment catalyst. The rupee, which had been trading in the ₹91.5–92 range under stress conditions, strengthened on the news, touching ₹90.30 before settling near ₹90.70. Foreign portfolio investors, who had spent most of 2025 as relentless net sellers, turned net buyers in the first week of February 2026, purchasing approximately $897 million worth of Indian equities.

These are meaningful moves. After 18 months of persistent underperformance relative to other emerging markets, India’s excessive valuation premium has moderated toward historical averages, which may create better entry points for global capital going forward.

Copy and paste the text from AMT that you want to share

postN105.1

India Insider: Agriculture Still Traps Nation’s Workforce

India Insider: Agriculture Still Traps Nation's Workforce

A Field Survey in South India’s Agricultural Towns

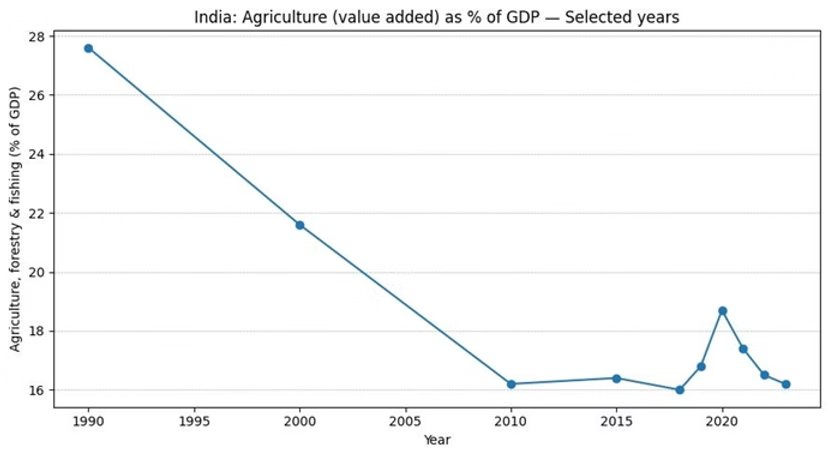
India’s growth story is usually told through noteworthy headline numbers. Yet beneath these aggregates lies a persistent imbalance, agriculture continues to employ a large share of the workforce, while contributing a much smaller share of output. This gap shapes income stability, consumption patterns, and the complicated experience of growth across much of the country for many people.

This essay uses field observations comparing two major agricultural towns in Tamil Nadu State in India, Tiruvannamalai and Kallakurichi. After analyzing their respective data and examining how this imbalance plays out on the ground, I offer my perspective.

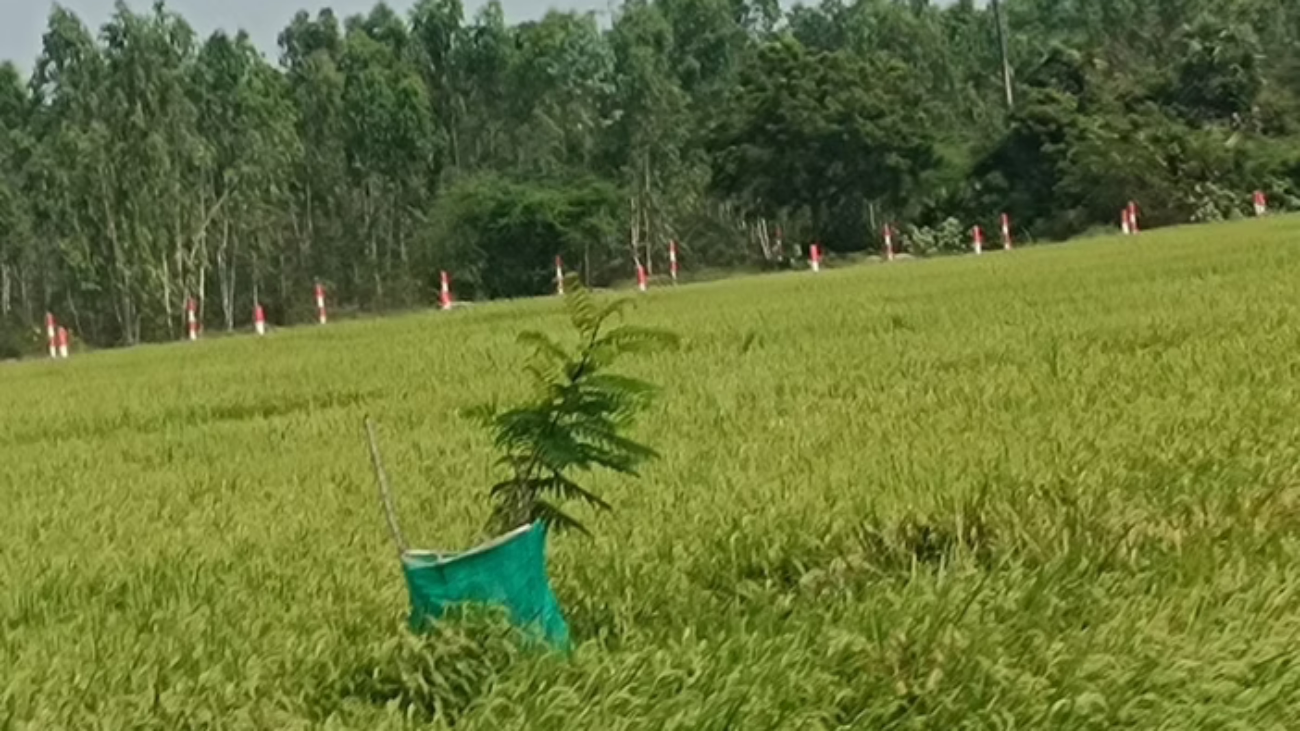
Typical Agricultural Field in Southern India

Tiruvannamalai: Growth Without Employment Transformation

In Tiruvannamalai district, I visited several areas where housing conditions were poor and informal settlements were widespread. I have visited many households here since 2023. These conditions are now changing, but not in a way that fundamentally transforms employment.

Capital inflows from the neighboring State of Andhra Pradesh have fueled a real estate boom and expanded services such as lodging, restaurants, and transport. While this has altered the physical landscape and raised asset values, it has not created stable non-farm jobs at scale. Employment remains largely informal, seasonal, and low-paid, leaving the underlying agricultural labor trap intact.

Although Tiruvannamalai exhibits a relatively high services share in district GDP, the income generated by this sector accrues from a narrow group of asset owners, intermediaries, and rent-seekers. As a result, per capita income figures overstate the extent of broad-based welfare. A large share of the workforce remains engaged in low-wage service activities with limited income security.

Kallakurichi: Agricultural Dependence, Weaker Services

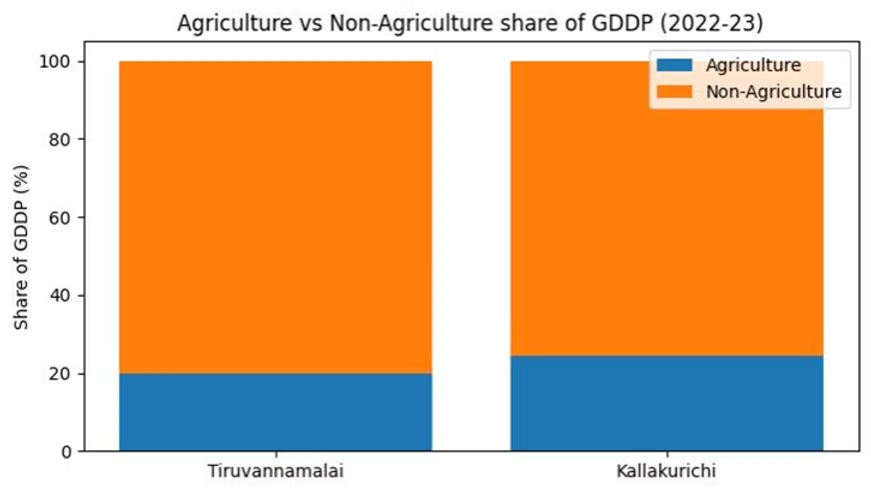
In Kallakurichi district, the structural imbalance is even more pronounced. Agriculture accounts for a noticeably larger share of district GDP than in Tiruvannamalai, while the services share is correspondingly lower. District level GDDP and sectoral composition data from the Department of Economics and Statistics, Government of Tamil Nadu (2022–23 provisional, current prices), show that agriculture contributes roughly one-fifth of district output, even as a disproportionately large share of the workforce continues to depend on this type of work for income.

This high dependence on agriculture results in extremely low output per worker, widespread disguised unemployment, and chronically weak incomes. Growth exists, but it is concentrated in activities that do not absorb labor effectively.

Gross Domestic District Product Comparison of Agriculture versus Non-Agriculture

Core Problem: Growth Composition, Not Growth Absence

The core structural problem in districts like Tiruvannamalai and Kallakurichi is therefore not the absence of growth, but its composition. Too many workers remain tied to a sector that generates relatively little value. Services and industry have expanded, but not in a manner that absorbs surplus rural labor at scale.

As long as labor remains trapped in low productivity farming, while non-farm sectors fail to provide stable employment opportunities, headline income measures will continue to overstate actual welfare.

Consumption Consequences of Agricultural Dependence

This imbalance has direct consequences for consumption. Towns that depend heavily on agriculture tend to exhibit weak and uneven consumption patterns. Farm incomes are inherently volatile, driven by fluctuations in commodity prices, weather conditions, and market access. In many cases, farmers are forced to sell produce at a discount, incur outright losses, or delay sales under distressing conditions. Only intermittently do they realize meaningful profits.

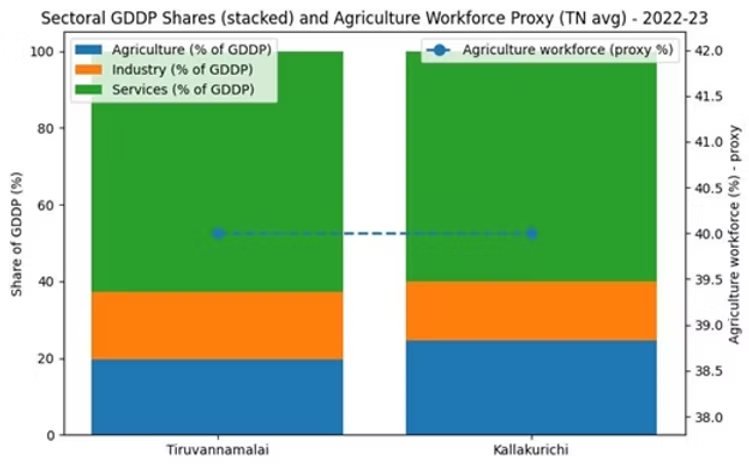
Chart Comparing Towns of Tiruvannamalai and Kallakurichi in Tamil Nadu

This volatility translates into cautious spending behavior. Consumption rises in short bursts following a good season, but thereafter contracts sharply. This pattern is clearly visible in districts such as Tiruvannamalai and Kallakurichi, where agricultural dependence suppresses steady consumption despite occasional income windfalls.

The same dynamic is visible at State level. Across Tamil Nadu, agriculture employs over 40 percent of the labor force, while contributing a far smaller share of output. The statistics exhibited at the district level are therefore not an isolated phenomenon, but a systemic one.

National Structural Imbalance

Zooming out further, what is visible in Tiruvannamalai and Kallakurichi mirrors India’s broader structural imbalance. Nationally, agriculture employs close to half the workforce, but contributes less than a fifth of GDP. This gap suppresses incomes, weakens consumption, and reflects India’s limited success in industrializing at scale.

India Agriculture as Percent of GDP from 1990s into 2020s

Services have grown rapidly, but they remain reliant on capital and skill intensive, and unable to absorb surplus rural labor in large numbers. As a result, economic growth continues without broad based prosperity. Headline GDP numbers improve, but the underlying structure remains fragile.

India’s central economic scrouge is growth without labor mobility. Until workers move out of low productivity agriculture jobs and into stable non-farm employment at scale, income volatility and weak consumption will remain defining features of the economy. Regardless of how strong the headline growth numbers appear, a national challenge remains.

Copy and paste the text from AMT that you want to share

postN104

India Insider: Weakening the MNREGA Employment Guarantees

India Insider: Weakening the MNREGA Employment Guarantees

When the Mahatma Gandhi National Rural Employment Guarantee Act was enacted in 2005, it was conceived as more than a poverty-alleviation program. It was a direct intervention in India’s rural labor market. By guaranteeing employment on demand at a statutory wage, MNREGA established what the agrarian economy had long lacked – a credible wage floor.

For India, where nearly half the workforce remains trapped in agriculture and align activities often involuntarily, this mattered enormously. Rural labor markets are structurally weak in India. They are seasonal, informal, and dominated by excess labor. In such conditions, wages do not rise organically. MNREGA altered that balance by providing an outside option. A worker who could demand public employment could also refuse exploitative private wages. That is why rural real wages rose meaningfully during the first decade of MNREGA’s implementation.

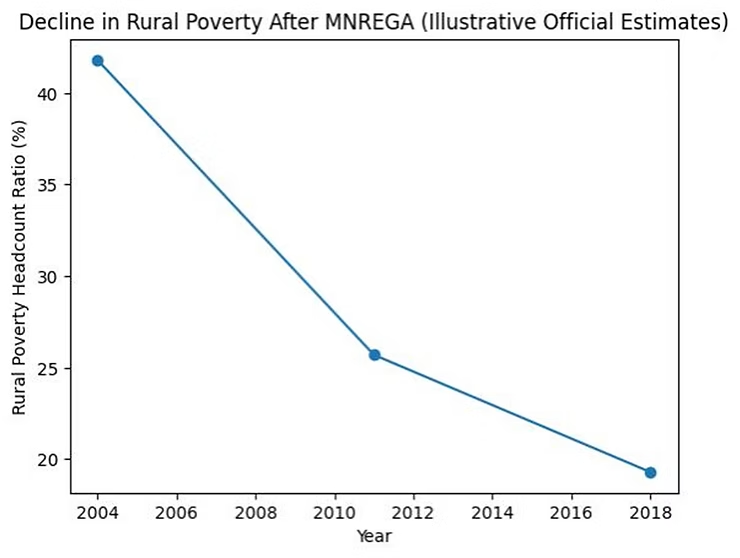
MNREGA Rural Poverty Data from 2005 to 2018

The figure above illustrates the broader context in which MNREGA operated. Rural poverty declined sharply after 2005, falling from over 40 per cent in the mid 2000s to below 20 per cent by the late 2010s. While this decline reflects multiple forces like overall growth, structural change, and social programs, micro-level studies consistently find that districts and households with higher exposure to MNREGA experienced significantly larger gains in consumption and poverty reduction compared to areas where the program was weakly implemented.

The scheme also acted as a counter cyclical stabilizer. During droughts, agrarian distress, or macro slowdowns, MNREGA expanded automatically, injecting purchasing power into rural areas. This supported consumption, reduced distress migration, and softened downturns. In macroeconomic terms, MNREGA transferred income to households with the highest marginal propensity to consume, precisely where fiscal multipliers are strongest.

Despite its strong design, MNREGA has long suffered from implementation weaknesses. Chronic delays in wage payments undermined its credibility as a reliable source of income. Corruption has generated fake muster rolls, ghost workers, inflated material bills, and substandard asset creation. Social audits which meant to be the backbone of accountability were uneven across states while effective in some.

Technological reforms such as Aadhaar linked payments, and digital attendance reduced certain leakages but introduced new problems, including worker exclusion, authentication failures, and further payment delays. The result was not only fiscal leakage, but a weakening of MNREGA’s core economic function which had promised a dependable wage floor.

Yet instead of fixing these implementation failures, a new policy chose to change the promise itself. In December 2025, this shift became explicit with the passage of the VB-G RAM G Act, 2025 in Parliament, replacing the Mahatma Gandhi National Rural Employment Guarantee Act with a redesigned rural jobs framework.

Under MNREGA, employment was a legal right, if work was demanded, it had to be provided. The new framework reverses this logic altogether. Employment now depends on budget limits, administrative approvals, and notifications from the center, not on demand. What was once automatic is now conditional.

This change also quietly shifts risk onto States. With limited revenue powers and tight borrowing limits, States responded by rationing work and delaying payments. As a result, the employment guarantee weakens, rural workers lose bargaining power, and wages come under pressure. What appears as fiscal control for the central government to rein on capital expenditures on paper thus becomes wage suppression in practice for rural workers.

Almost half of India’s workforce, around 46 per cent, still depends on agriculture and allied rural activities for employment, even though agriculture produces a much smaller share of the country’s total output. This gap between employment and output signals very low productivity in rural work and a large pool of surplus labor. For most of these workers, moving out of agriculture is difficult. They face barriers because of a lack of skills, weak urban job absorption, high migration costs, and social constraints. As a result, the ability to bargain for higher wages is structurally limited.

In such an economy, rural labor markets tend not to be competitive. Employers often face many workers competing for few jobs, while workers have few alternative sources of income. This creates conditions close to monopsony, where employers have disproportionate power in setting wages. In the absence of an institutional counterweight, wages tend to settle near subsistence levels rather than reflecting productivity or broader economic growth.

The consequences are visible in wage outcomes. Daily wages in rural areas stagnate or decline in real terms, failing to keep pace with inflation. Over time, this suppresses labor incomes relative to profits and rents, leading to a further decline in labor’s share of national income. In effect, weakening the employment guarantee shifts income distribution away from workers and back toward employers, reinforcing existing structural inequalities in the economy.

Copy and paste the text from AMT that you want to share

postN76.1

India Insider: Strategic Memory and Why Unilateral Power is Resisted

India Insider: Strategic Memory and Why Unilateral Power is Resisted

After Independence, India was often described as “tilting” toward the Soviet Union. In reality, this was the outcome of India’s pursuit of Non-Alignment at a time when the United States was actively backing perceived rogue actors in South Asia, most notably Pakistan. What appeared as ideological preference was, in fact, strategic necessity born of hard experience.

The Soviet Union supported India on core security concerns when few others would. The first major Soviet defense deal was not merely a weapons sale. It included licensed production in India through Hindustan Aeronautics Limited, full technology transfer, and made India the first non-Communist country to receive the MiG-21. This distinction mattered. India was treated as a sovereign partner capable of absorbing technology, not as a dependent client expected to align unquestioningly.

By contrast, Washington’s alignment with Pakistan was driven by Cold War geopolitics rather than South Asian stability. Despite repeated military coups, wars with India, and regional destabilization, the United States armed Pakistan, provided diplomatic cover during conflicts, and sustained the relationship through military rule and nuclear proliferation. These experiences deeply shaped India’s strategic culture and explain its enduring emphasis on autonomy, redundancy, and diversified partnerships rather than alliance dependency.

This history is one of the central reasons India resists Washington dictating regional dynamics. South Asia, in New Delhi’s view, is not a chessboard for external powers to reorder at will.

Democratic Republic of the Congo Example

The same pattern is visible beyond Asia. Take the Democratic Republic of Congo. After decades of horrific colonial exploitation, the Belgians realized by the mid-20th century that they could not hold on indefinitely and exited abruptly, having never prepared the country for self-rule. What they left behind was not independence, but a political vacuum. The United States and the United Nations intervened, but their actions were shaped less by concern for Congolese society than by geopolitical rivalry, ideological competition, and racial hierarchy.

The assassination of Patrice Lumumba destroyed the Republic of the Congo’s (as it was known then) only credible attempt at building a unified nationalist state at independence. The dictatorship of Mobutu Sese Seko that followed did not merely fail to develop institutions; it actively hollowed them out. Corruption became a governing principle, loyalty replaced competence, and the state turned into a vehicle for extraction. Today’s instability in the Democratic Republic of the Congo is not a governance failure in isolation—it is the predictable outcome of a political system designed to rule without building state capacity. For countries like India, this is not ancient history, it is a warning.

Washington’s unilateralism reinforces this mistrust:

The recent military operation to remove Venezuelan President Nicolás Maduro without U.S Congress authorization, international legal justification, or an imminent threat would have been unthinkable as recently as the first Trump administration. It became possible in 2026 only because of congressional capitulation, judicial immunity, and the transformation of an apolitical defense establishment into a politicized instrument of executive power. To much of the world, this signals that restraint is no longer embedded in American decision making.

Europe exposes another contradiction. The post war order was built on liberal democracy and collective security through NATO. When that order is weakened by unilateral action, trust erodes, even among allies expected to align automatically.

Even before Trump, the U.S – India relationship remained cordial rather than fully strategic. Before 9/11, India was the most natural regional ally against Al-Qaeda, yet Washington lacked patience and local understanding to navigate India’s complex democracy and nationalism. That failure was not tactical, it was conceptual.

India’s neutrality today is deliberate:

It prioritizes diplomacy over military actions that violate international law. India sees a multipolar world emerging, not as disorder, but as the end of unchecked unilateral supremacy. This is not ambiguity. It is a strategic memory.

postN74

India Insider: Growth Without Development an Inequality Trap

India Insider: Growth Without Development an Inequality Trap

An India and Latin America Comparison

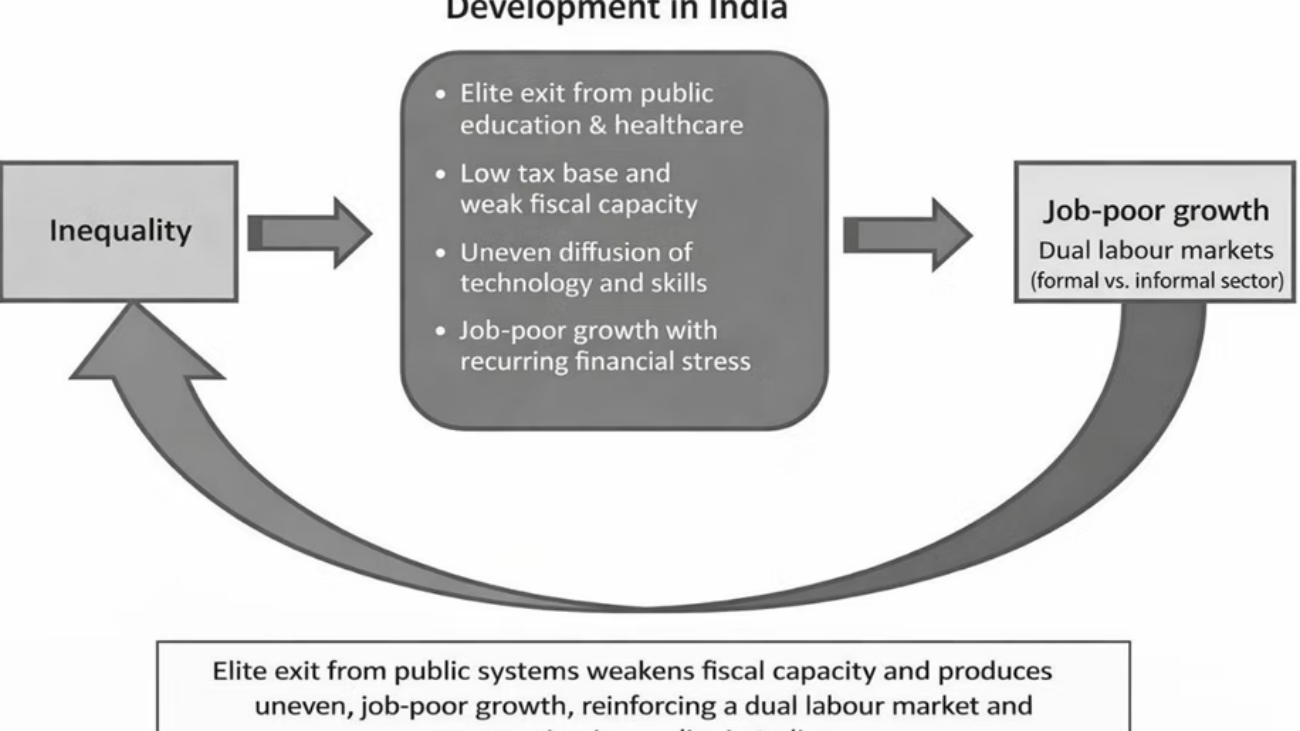
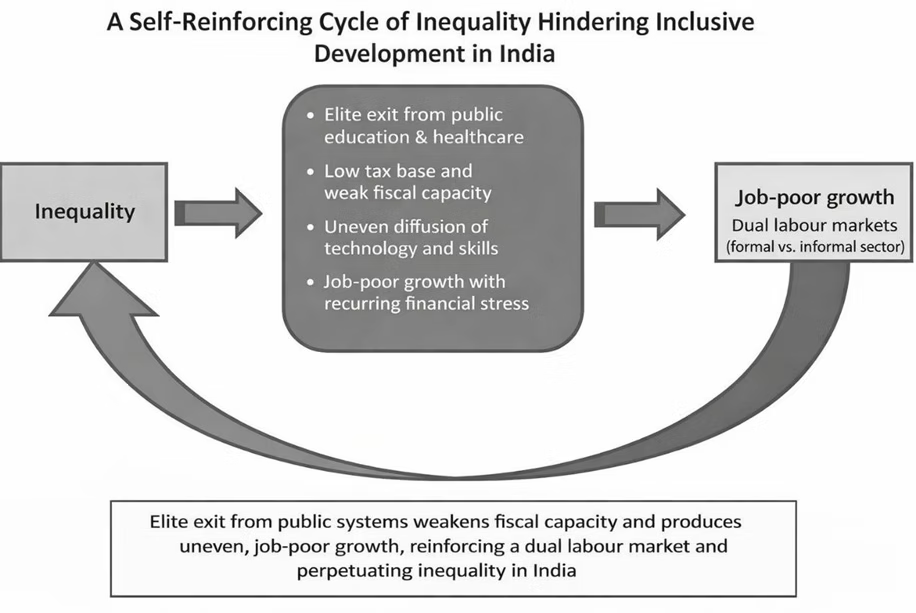
India’s strong headline growth reflects a rapid expansion of aggregate output. Yet this growth often coexists with weak job creation, uneven human capital formation, and persistent inequality. This coexistence is not a temporary anomaly. It reflects a deeper political & economic structure in which inequality itself constrains development, rather than merely emerging as a byproduct of slow growth.

This mechanism is similar to Latin America. In unequal political economies, rising income concentration encourages elites to exit from public systems like education, healthcare, transport, and social insurance. Once affluent groups no longer depend on public provision, political incentives to strengthen these systems weaken fiscal capacity erodes, public services deteriorate, and inequality becomes self-reinforcing.

Latin America’s experience illustrates this dynamic clearly. Despite periods of high growth driven by industrialization, commodity booms, or financial liberalization, many countries failed to build universal public systems. Elites relied on private schools, private healthcare, and offshore financial arrangements, while the majority depended on chronically underfunded public institutions. The result was a narrow tax base, weak state capacity, and growth that was volatile and socially shallow.

Figure concept adapted from book, “The cost of Inequality in Latin America” by Diego Sanchez-Ancochea

India increasingly shows signs of a similar trajectory. Public spending on health remains around 1.2 – 1.4 percent of GDP. Government expenditures on education is around 3 percent of GDP, which is low not just by OECD standards, but comparative to many middle income Latin American economies. Out of pocket healthcare costs account for roughly 45 – 50 percent of total health spending in India, among the highest shares globally. These figures point to a systematic private substitution over public provisions, a hallmark of elite exit.

Implications of Elite Leaving Public Systems

Withdrawal from public systems has direct implications for growth quality. When education and healthcare remain uneven, the diffusion of skills and productivity across the workforce is limited. Growth then concentrates in capital intensive or skill intensive enclaves, while large segments of the labor force remain trapped in low productivity informal employment. India’s employment elasticity of growth has remained structurally low, estimated at below 0.2 in recent decades, meaning that even high output growth generates relatively few jobs.

This structural weakness is reinforced by the nature of Indian capitalism. Like much of Latin America, India’s growth model rewards scale, access, and regulatory navigation more than technological risk taking. Firms that can manage land acquisition, compliance complexity, market concentration, and political connections earn higher returns than those that invest in frontier innovation. Private investment in research and development remains modest: total R&D spending in India is around 0.6 – 0.7 percent of GDP, with a particularly weak contribution from the private sector. By contrast, East Asian economies that achieved solid employment growth invested 2.0 – 4.0 percent of GDP in R&D during their catch up phases.

This outcome produces poor job growth and entrenched dual labor markets, which is also another Latin American hallmark. A relatively small formal sector benefits from capital strengthening and productivity gains, but the majority of workers remain in informal employment with stagnant wages and weak social protection. Gradually this weakens domestic demand and increases reliance on credit, exports, or asset inflation to sustain growth. Latin America’s history also shows that such growth patterns are inherently fragile.

India Vulnerability and Structural Risks

Narrow tax bases limit counter-cyclical policies. High inequality constrains mass consumption. Credit expansion often substitutes for income growth, increasing financial vulnerability. India has thus far avoided repeated balance of payments or sovereign debt crises, but the underlying structural risks look similar to Latin America. Growth looks strong on paper, yet remains vulnerable to shocks and has been slow to translate into broad based societal gains.

India differs from economies that have escaped their inequality traps, like East Asia and Northern Europe, because of poor development sequencing. These successful regional giants expanded universal public education, healthcare, and social insurance early, before inequality became politically entrenched. Elite dependence on public systems sustained fiscal capacity and productivity diffusion, allowing growth to create gainful employment.

India’s Social and Economic Dualism

India’s economic liberalization grew before consolidating universal public provisions. As growth has accelerated, inequality has widened and the exit of elites has deepened from public centers. An opportunity to create inclusive institutions during this early growth phase is missing for parts of the society.

The implication is clear. High growth alone does not guarantee development. When inequality weakens public systems and limits fiscal capacity, this discourages technological risk taking and produces inadequate job growth. Output expansion becomes narrow and periodically fragile. Latin America’s experience is a warning. Without building strong public institutions and reshaping incentives toward broad based innovation, India risks portraying impressive headline growth while vast disparity persists.

postN72

U.S National Security: USD Reserve Currency Importance

U.S National Security: USD Reserve Currency Importance

Opinion: The following article is commentary and its views are solely those of the author. This article was first published the 23rd of December via The Angry Demagogue.

We would like to start going through the U.S administration’s National Security Strategy released last month. There is a lot in there – much of it the same as in past administrations and much of it different. The tone of course is full Trump and while the introductory parts try to make it into a revolutionary document it does in fact build upon much of what has been American foreign policy for decades. One thing it most certainly gets right is that American foreign policy since the end of the Cold War has not found its compass. From a unitary world to one dependent upon global organizations, from a sharing of goals with western Europe to a pivot to Asia, from the war on terror and the middle east to Russia-Ukraine, the United States has struggled to find its way in the post-Cold War world.

We however will concentrate today on one aspect of the strategy, the third bullet in part III – “What Are America’s Available Means to Get What We Want?”. The third bullet point speaks of America having “The world’s leading financial system and capital markets, including the Dollar’s global reserve currency status” – a point that no one with any knowledge of global capital markets can not accept. The end of the bullet point – the Dollar’s global reserve currency status – is the most important because it underscores America’s leadership and essentially allows the United States of America to finance its military and its welfare state. The U.S Dollar as the “reserve currency” means that nearly all the world’s goods are quoted and therefore sold in Dollars.

Why is that important to the United States? Because the U.S government depends on its ability to issue Treasury bonds and bills at will – something no other government can do. It can do this because for another country to buy oil or copper or titanium or corn or soybeans from a country that is not their own– they need access to Dollars. Saudi Arabia and the other gulf states quote the price of oil in U.S Dollars and demand payment in U.S Dollars. The Saudis can deposit those Dollars in American banks or in what is called Eurodollar deposits in foreign banks (there are some 13 trillion Dollars in Eurodollar accounts globally). The Eurodollar accounts are essentially promises by the bank to give U.S Dollars to the holder when he makes a withdrawal. This strengthens the U.S capital markets and allows investors to have better and more investment choices. It is not only America’s often superior companies that bring profits to 401k’s and pension funds but the liquidity and vastness of America’s capital markets that can list domestic and foreign corporations. The reserve currency leading to the advanced capital markets allows the world – and America – to do this.

The U.S Treasury market is so liquid because every country needs Dollars in order to trade. They need to have enough dollar reserves since no one actually wants their own currency. In Israel, for example, local gas companies cannot buy oil with Israeli Shekels, since what will Azerbaijan, for example, do with them? There are only so many products that Israel can sell them. They need Dollars so that they are free to buy other commodities or other products.

The U.S Dollar as a reserve currency also is a break on inflation since the price of oil and other commodities is always in U.S Dollars. A weak or strong U.S Dollar influences the inflation rate in non-USD countries. A weak Israeli Shekel, South African Rand or Chinese Yuan does not influence the price of gasoline in the United States.

In short – as the Trump Administration understands well, the dollar as a reserve currency is a luxury the U.S cannot give up. The lack of the USD as a reserve currency could cause the Dollar to collapse and along with it the price of U.S Treasuries. As UST prices drop, their yields will rise and the cost of financing the U.S government will make interest payments on debt to rise well beyond its already absurd figure of over 4% of GDP – while debt itself is 120% of GDP. The U.S government currently pays over $1 trillion in debt service (interest payments on its bonds and bills). By contrast, the U.S defense budget for 2024 was $836 billion (about 3.3% of GDP).

We need to ask ourselves what can challenge the USD as the reserve currency and what could happen that would encourage the world to change? While the E.U had dreams of making the Euro an alternative reserve currency, the lack of growth in the E.U’s economy and population have put that dream to rest. The only other country that could theoretically replace the United States as the global economic go to country could be China. While in the long run, China’s lack of openness would probably mean that the Yuan would not last long as the reserve currency, that does not mean that they couldn’t jolt the global economy just enough to force it to use the Yuan to buy oil and other commodities.

China is already cornering the market on rare earth minerals and it making inroads in Africa where it mines all sorts of commodities from gold to copper to platinum and so many others (Africa has about 30% of global mineral reserves). That in itself is not enough to rock the global markets and cause a change in how the world does business.

Oil though, is that one thing that could allow China to challenge the USD as the reserve currency, even if it just presents the Yuan as an alternative.

How could that happen?

A Chinese takeover of Taiwan, by whatever means it uses would give the Chinese Communist Party control not only of the South China Sea but also allow its noisier and inferior (to America’s) submarine fleet to enter the Pacific and patrol it freely. The Chinese Navy, with a base on the “other” side of Taiwan would give it control of the north-south sea lanes that Japan and South Korea are dependent upon. Essentially, Chinese control of Taiwan would put Japan, South Korea, Vietnam and the Philippines at the mercy of the Chinese Navy. China could blockade these countries but that would be an act of war and then involve the navies of those countries and possibly the United States. It would affect the global economy negatively but it would not cause a change in world’s reserve currency. But, what if China works out a deal with Saudi Arabia to quote and sell their oil in Yuan (or the Chinese Petro-Yuan it wants to create) and then tells these countries, especially industrial powerhouses and energy poor Japan and South Korea that it will allow the passage of oil as long as they purchase the oil in Yuan?

Russia is already trying to get India to pay it for its oil in Yuan, to some success. Adding economies the size of Japan and South Korea would mean that any country that wants to buy oil could buy it in Yuan instead of Dollars. Once in Yuan, these countries would need to use the Yuan to buy Chinese products, deposit cash there and buy Chinese treasury bills. If China were to combine that with demands that all chips made in Taiwan also be sold in Yuan, the U.S Dollar would suddenly and forcefully no longer be the only reserve currency in the world.

Obviously, the way to stop this from happening is by stating outright that the United States will not tolerate a Chinese takeover of Taiwan. It is true, that the Strategy claims that the US “will also maintain our longstanding declaratory policy on Taiwan, meaning that the United States does not support any unilateral change to the status quo in the Taiwan Strait” but in practice the administration has criticized Japan’s tough talk on China instead of leaving it be. A strong silence on Prime Minister Takaichi’s remarks on China would have served the purpose of keeping the status quo more than telling her to tone down her rhetoric. There is a strong “no intervention ever” strain in the country and the President must make the case that that is not an option if the United States wants to maintain its leadership position, way of life and general prosperity.

In short, the threat to the Dollar as the reserve currency heads right through Taiwan. For those who think that the investment the U.S makes in keeping the Dollar where it is, is too expensive, just think of going on vacation and having the change to Yuan before you leave the country, wondering how much to change because of currency fluctuation and how much fun it is to return with hundreds of dollars in banknotes that you can’t use. Imagine your credit card bill on such travels and wondering how you went 15% over budget but didn’t get anything extra for it. Now imagine the national economy working that way.

Disclaimer: the views expressed in this opinion article are solely those of the author, and not necessarily the opinions reflected by angrymetatraders.com or its associated parties.

You can follow Ira Slomowitz via The Angry Demagogue on Substack https://iraslomowitz.substack.com/ 

postN71

India Insider: The 8.2% Growth Mirage Needs a Reality Check

India Insider: The 8.2% Growth Mirage Needs a Reality Check

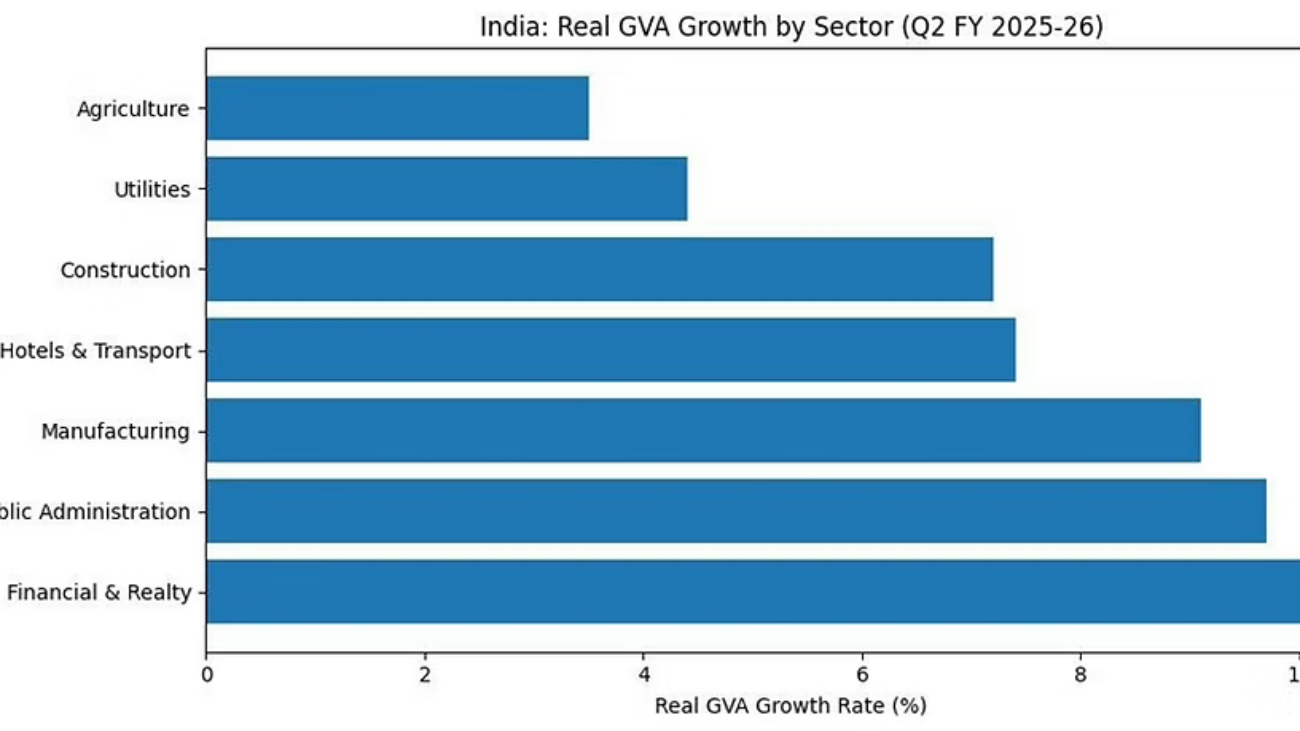
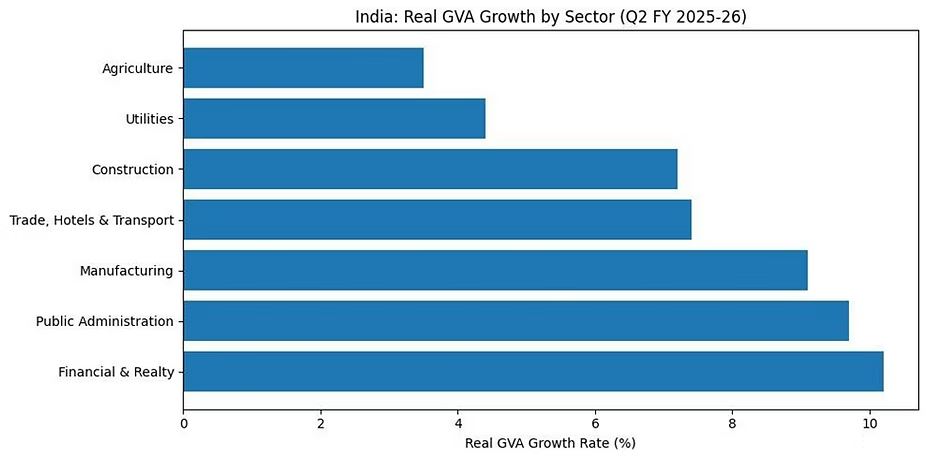
India is celebrating the 8.2% real GDP growth result for Q2 FY26, as if it has entered a new economic orbit. Politicians are claiming victory and media is packaging optimism. The narrative is simple: India cannot be stopped. But once we move beyond the headline, the number loses credibility. It rests on a broken deflator, a statistical gap that no one can trace, and data architecture that doesn’t consider half the economy. This is not a story of unstoppable growth. This is a story of statistical convenience.

The Production–Expenditure Divide

On the production side, the numbers look heroic. Manufacturing allegedly grew 9.1%, and financial and professional services posted more than 10% growth. Corporate India looks like it is flying. But when the same activity is measured from the expenditure side – who actually spends this income – the story weakens.

Private consumption at 7.9% is respectable, not outstanding. The real shock is government consumption, which contracted by 2.7%. A shrinking government should normally mute growth, not accelerate it. Yet the GDP shoots up. How does that make sense? It doesn’t unless the number is being propped up somewhere else – and this is the case.

₹1.63 Lakh Crore of ‘Unknown Growth’

GDP includes a category called ‘discrepancy’. It exists because the two methods – production and expenditure – never perfectly align. The discrepancy stands at ₹1.63 lakh crore ($18.2 Billion USD) which equates into roughly 3.3% of real GDP. That means a chunk of this 8.2% growth has no identifiable spender: No households. No firms. No government.

It is income without absorption. A statistical plug. When a number this large is called ‘discrepancy’, the headline becomes unreliable – suspicious. You cannot claim world beating growth when your own data admits it cannot explain where that growth came from.

Chart via the National Statistical Office

The Deflator Illusion

The next distortion is the nominal vs real GDP gap. Nominal GDP is growing at 8.7% and real GDP at 8.2%. A gap of 0.5 percentage points implies inflation has almost vanished. Every Indian knows this is not true. Costs did not collapse. Food inflation has not disappeared.

The explanation is mechanical: India still uses the Wholesale Price Index (WPI) to deflate nominal output. Global commodity prices fell, WPI softened sharply, and that flattening pushed up the real number. In other words, GDP grew because the denominator fell, not because production surged.

This creates a fiscal problem. The Union Budget assumed 10.1% nominal growth. At 8.7%, tax buoyancy will weaken, deficit targets become more difficult, and next year’s fiscal capability shrinks. Real GDP does not pay the bills, Nominal GDP does.

The Informal Blind Spot

India still cannot measure its informal economy accurately. Nearly half of GDP and employment sits outside the formal system, yet the NSO uses formal sector proxies such as corporate balance sheets, GST data, and financial flows to estimate the rest of the economy. If a small business collapses and a corporate giant expands, the data shows a net gain, erasing distress at the bottom which means real economic circumstances are not portrayed accurately for Indian citizens.

Agriculture grew at 3.5%, but it still supports 46% of India’s workforce. That means growth is concentrated in capital intensive and balance-sheet heavy sectors, not into areas that put cash into rural hands. A booming Nifty Index via the stock market does not translate into household prosperity.

An Economy Measured with Old Tools

India continues to measure GDP using a 2011–12 base year, an era before UPI (Unified Payments Interface), before fintech credit, before e-commerce, before gig workforces, before the pandemic rewired supply chains and consumption patterns. India is living in a digital economy, but measuring activity with analog instruments.

A shift to a 2022–23 base year, plus replacing WPI with a Producer Price Index, may finally align the numbers realistically. But until then, headlines are running ahead of bona-fide measurements.

India’s 8.2% print is impressive, but growth estimates that don’t reflect grounded realities produce illusionary optics rather than useful insights. For India to strengthen fiscal and economic credibility, measurements must capture households, labor markets, and productivity, not solely corporate outputs. Policy cannot be shaped by statistical ambiguity, it requires transparency and trusted data.