AMT Top 10

AMT Top Ten Miscellaneous Insights, Mischief and Concerns for the 22nd of September

Trump's Saga, Market Conditions, Saudi Arabia, Investor Outlooks and More

10. Naima: John Coltrane’s classic composition from the late 1950’s should be listened to intently with eyes closed as his harmony and provocative ability to create a devotional hymn enchants. What do you hear? Instead of playing music for mere mortals, it sounds as if Coltrane is orchestrating for gods – take a moment to listen.

9. Upwards: Bitcoin, cough, cough is again making some look foolish as it traverses higher. As of this moment, BTC/USD is at $86,000 and making doubters – among them some AMT staff – shake their heads in disbelief (disdain). Michael Saylor’s Strategy/MicroStrategy entities have MSTR share prices around $168.00 per yesterday’s close. This is occurring as AI concerns because of its ability to challenge cybersecurity and coding of crypto remains relevant. Additionally, higher energy costs are causing miners to wince, running out of folks who are willing to speculate in the domain remains a danger (because of Ponzi suspicions), notions about government supervision getting stronger instead of becoming more lax, quantum technology, and known rogue nations keeping Bitcoin and other cryptos vibrant to hide illicit money shadow. But this is nothing to worry about it appears for Bitcoin believers and influencers.
AMT Top 10 Miscellaneous Insights, Mischief and Concerns for the 22nd of September

8. Unheralded Victories: While many were looking away purposely and likely do not want to give President Trump applause, Denmark extended the U.S administration not only an olive branch regarding Greenland, but perhaps a signal that they have acquiesced by expanding U.S security jurisdiction. From a foreign policy perspective the Trump administration has changed the Venezuela leadership, secured greater military capabilities in Greenland, and remains focused on bringing Cuba’s leadership to their knees as the island nation suffers from extended electrical outages.

7. Berkshire Hathaway: Warren Buffet stepped away from his job as Chairman on the 18th of September and named his son as successor. Share values via BRK.A were above $800,000 in April and March of 2025. This August BRK was again over $800,000. Yesterday’s close was near $752,000. Warren Buffet’s brand and era is coming to a close and the new leadership will be hard pressed to fill the confidence void. Berkshire Hathaway investors however, are some of the most loyal constituents in the marketplace. They will want to see a steady ship run by Howard Buffet and CEO Greg Abel.

6. New School: What will the Fed do now that they have raised the Federal Funds Rate by a quarter of a basis point on the 16th of September? Kevin Warsh has proven he is not exactly in the coat pocket of President Trump. After the Fed’s unanimous vote last week to raise rates, what happens on the 28th of October? Via Forex it appears financial institutions have braced their outlooks for another hike sometime later this year, but are they correct? Old theories via central banking to attack inflation with higher interest rates is a standard practice, but the escalating costs via higher energy prices has nothing to do with a sudden emergence of pent up demand, it is a supply shock that has caused more expensive WTI Crude Oil – not one driven by an increase in desire. Will Warsh prove he is new-school and proactively fight for lower interest rates sooner rather than later? Higher interest rates will not stop the Middle East saga from remaining an economic influence and spectacle.

5. Bank of Japan: Like the Fed the BoJ is not in a particularly safe space. After following in the footsteps of the Federal Reserve last week, the interest rate hike of 0.25% by the BoJ was viewed as a rather lackluster move from financial institutions and Forex players who seemingly wanted an increase of at least 0.50%. The USD/JPY remains a volatile speculative wager and is above 156.850 – give or take the tantrums and punishment inflicted from the FX market. The Bank of Japan has only had 3+ decades of questionable policy, here’s to another decade worth of doubts and consistent critical observations from outsiders.

4. Hear No Trump: The U.S President is entering a dangerous political phase for his legacy and risks losing his grip on power. Mid-term elections are rapidly drawing closer and the White House could lose its Republican led majority of the House. The President is starting to be viewed as a lame-duck by some observers. Trump who is known for his ability to change his rhetorical stances and policies quickly is still at the epi-center of global affairs. The question is if other policy makers and nations are listening. The Republican party is entering a dangerous phase and its leadership is likely going to endure a rather loud fight for control as factions take sides. The Vance and Rubio camps are likely to grow louder and divergent.

3. Saudi Arabia: Ask a friend to point to Yemen on a map, can they do this correctly? The Houthis of Yemen and Saudi Arabia may feel like a world away from known geographies, but what is happening in the wake of attacks on port areas and islands in the Red Sea (and even Riyadh) is significant. Crude Oil production and shipping problems suffered because of pipeline vulnerability is a vital concern for energy supply to Europe and Asia. While large investors may feel like they have digested the dangers, Iran and its proxies – including the Houthis may have additional theater to present. WTI Crude Oil has come down in price since yesterday but remains volatile and is around $93.00. Will optimistic banter continue?

2. FOMO: The Nasdaq 100, S&P 500, Dow 30 and their global counterparts are within their higher apexes as traders and financial institutions keep placing their money into these known asset spheres. The bond market is still producing high yields and folks are seemingly letting their casino like bets ride on a wheel they hope propels solid momentum for as long as possible. But alas, number 1, should make people pause:

1. Bandages: Perhaps our circle of contacts is too small, but behavioral sentiment is not exactly robust regarding positive market outlooks via mid-term queries. Concerns about equity indices, bond yields, inflation (because of sticky energy costs) and the general malaise that is hovering over the broad markets is not appealing. It feels as if sutures are keeping wounds from becoming infected in a haphazard manner. Investors are cautious and appear ready for the Band-Aid to be ripped off. The late ’90s and early 2000s dot.com bubble bursting, the 2006 bank and housing whispers and rumors flotilla which turned into the catastrophe of 2007-08 feel oddly similar. Perhaps it is a good time for accumulation if nothing seriously bad takes place in the markets. Circumstances feel as if a wave of blind market powers may harm those who seek never ending profits with a tsunami of losses. Perhaps it is a good time to be a speculator.
Copy and paste the text from AMT that you want to share

Share:
WTI CrudeOila 20260902

Bad Timing for President Trump May Equal Good Trading Opportunities

You Don't Have to be a Buyer in the Current Marketplace in Order to Profit

There are moments when the markets are calm and then there are these times. It is beginning to look like increasingly bad timing for President Trump and his administration’s hope to keep WTI Crude Oil prices in check and silence the chatter about inflation. 

Instead of a de-escalation based on tranquil conditions in the Middle East, investors were smacked in the face again last night. However, while this may be a bad time to be an investor unless they are looking for value plays, traders may actually have more opportunities in the current market circumstances as long as they manage their risks appropriately.

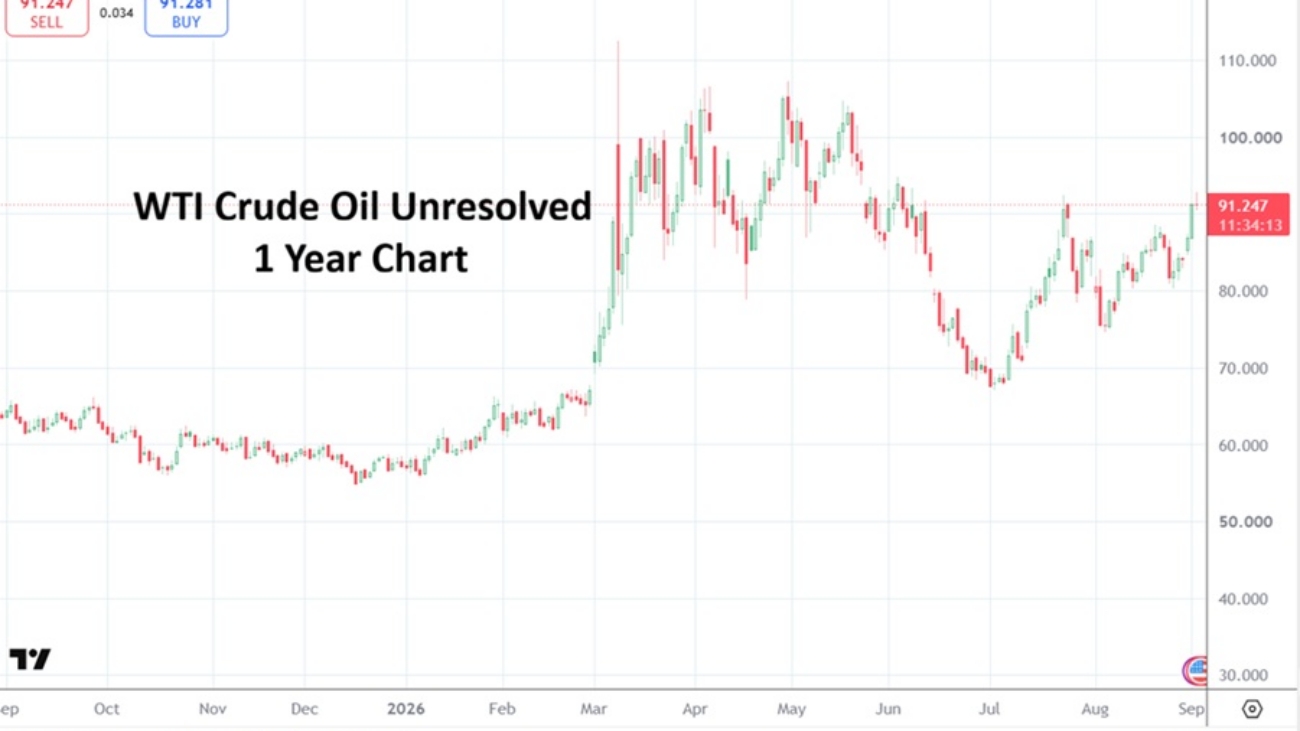
WTI Crude Oil jumped higher last night and while the commodity has outdone itself since late February regarding price velocity, last night’s performance likely felt volatile even for experienced large players who have solid intel on the ground regarding Middle East shipping and supplies. The energy sector has been more akin to the soft commodities regarding reversals the past handful of months, Coffee, Cocoa and Crude Oil have offered colorful price ranges. But that is not how WTI Crude Oil is supposed to work.

WTI Crude Oil 1 Year Chart as of 2 September 2026

Inflation concerns will not go away quietly as long as WTI Crude Oil remains highly valued. Fed Chairman Kevin Warsh may in fact be putting on a show for the public – that he is his own man and can express his concerns regarding inflation no matter what President Trump thinks – when in fact he may simply be laying a framework to work in tandem with Treasury Secretary Scott Bessent and lower interest rates in order to create less pressure on Treasury yields. However, this planned (or conspiratorial) thinking may be hard to actually produce in reality on the 16th of September when the Fed’s FOMC has to show its cards once again. As long as WTI Crude Oil remains above $90.00, “Houston we have a problem,” murmurs may be heard loud and clear.

If Treasury yields remain tilted upwards because investors are refusing to buy them at cheaper rates, it will start to infect the Nasdaq 100, S&P 500 and the Dow 30 more and create cautionary skirmishes which may produce deeper downsides in stock markets.

Iran wouldn’t want to cause President Trump problems, correct? Why would Iran want higher Crude Oil prices to ensnarl President Trump into a morass of political battles in the U.S and make life difficult for the Republicans during the mid-term elections? Does the IRGC have folks who understand the dynamics of U.S politics? Yes they do and it is a 100% certainty they would like to be a pain in President’s Trump’s aspirations.

We are left to deal with the ever-changing events that seem to be quite good at repeating themselves. Financial institutions are not only nervous about their mid-term outlooks, they are wary about the near-term too. Forex, commodities, bond yields, Wall Street and other global stock markets will struggle to make solid gains until clarity develops.

What will clarity look like? It will be optimistic banter in which rhetoric from different mouths and geographies is actually believed by the adoring crowds. Results do not have to be good, but outcomes need to be able to be forecasted and planned, allowing investors to seek their cash preservation and fortunes in a variety of assets (and show their overseers that they used adequate risk management in case things go wrong). 

Gold has done well recently, although it seems to have hit some resistance lately. However, if inflation tranquility is not achieved and if President Trump’s circumstances grow more dire, the precious metal will continue to offer speculative plays upwards. 

Investors are restless. Making 6 to 8% profits a year looks rather boring after plenty of solid years of upwards traction. Folks aren’t used to powerful financial storms and they forget about lingering troubled periods in which simple profits can prove comforting as broad markets struggle. 

Day trading is dangerous. However, those with solid risk taking tactics and those who aren’t married to the notion that markets only go up, but are willing to bet that markets (assets of many classes) can go lower too – now have an opportunity to test their technical perspectives and understanding of behavioral sentiment. 

Realistic targets using take profits and making sure stop loss protection still allows for a trade to move until goals are met is important when volatility is ripping price realms to shreds. Forex instability appears to be increasing as USD centric attitudes remain convoluted. Does Fed Chair Kevin Warsh have enough power to fight against an interest rate hike on the 16th of September, will the price of WTI Crude Oil cooperate, will President Trump’s wishful thinking about Iran come true? Results may not match what is wanted by the guardians of the marketplace. Contrarians may see the current market and global political situation as a time to seek value and help inflate markets, but they might be spitting into the wind. 

Maybe the AI concerns about infrastructure costs and corporate cash needs are baseless. Perhaps the deficit being created by the U.S and many other nations is simply idle chatter by risk analysts who are too nervous. Maybe there is a secret pill for all of us to become optimistic about all things.

It is a good time for traders to remain realistic and target exaggerated price movements in assets that offer opportunities in distressed offerings. You do not have to buy the marketplace to profit ladies and gentlemen.

Copy and paste the text from AMT that you want to share

Share:
postN87

AMT Top Ten Miscellaneous Bits of Clarity for the 19th of April 2026

In a World Filled with Bread and Circuses, Now a Dose of Transparency

10: The Risk Reward Show: Sommer and Petrucci will return to the airwaves this coming week, via sources like Spotify and YouTube, with their podcast starting after a long break (absence).

9. Hardball: Major League Baseball is back and the sport continues to attract more fans and growing attention with its quicker games, a new computerized strike zone, and maybe even more dislike of the Los Angeles Dodgers. Yes, Shohei Ohtani remains a dominant and positive force in the baseball world.

AMT Top 10 for the 19th of April 2026

8. Populism: Politicians on both sides of the Atlantic continue to display a wide display of nonsensical rhetoric and bold asinine actions equating into empty spectacles. An example from the Left is Zohran Mamdani the mayor of New York City with his socialist platform, which is certain to fail and equate into more people and companies leaving NYC for less expensive and friendlier tax environments. And from the Right Italian Prime Minister Giorgia Meloni who talks a tough game but consistently falls short of backing up her words when she senses she could lose control of her power base. The putrid smell of trying to please voters with rotting bread and circuses prevails.

7. Speculation: Gold finished Friday’s trading near $4,837.50, Silver around 80.78. Bitcoin is close to $75,570.00. 

6. AI: While the Artificial Intelligence hangover has been widely discussed for a handful of months, health continues to be seen via Nvidia which closed above $201.00 going into this weekend, and Anthropic PBC which appears to be aiming for an IPO in late 2026 or early 2027. At this moment Anthropic has an estimated valuation of 800+ billion USD. If Nasdaq is able to secure a listing with Anthropic it will immediately factor into the Nasdaq 100. Are some investors betting on upside now which they believe will be seen when Nasdaq reorganizes its index?

5. Optimism: India, South Africa, Brazil and other emerging markets have experienced Forex volatility like all nations the past month and half due to the Iranian war. However, in the past two weeks the Indian Rupee, South African Rand and Brazilian Real have performed better as global markets have calmed. The ZAR and BRL have actually outperformed major currencies over the past handful of months showcasing existing optimism within financial institutions dealing with these currencies.

4. Money for Something: Lefarge, a French company specializing in concrete, was found guilty this past week of paying ISIS (Daesh) and other terrorists groups money in the years from 2012 into 2014, this in order to maintain their business operations in Syria. While Lafarge claims they paid the money to keep their operating staff safe, a French court ruled Lafarge was buying not only safe passage to allow employees to work, but also paying for physical resources needed from quarries that were controlled by the terrorists. Critics of Lafarge point towards the company’s massive infrastructure investments leading up to 2012 and a decision to seek profits no matter the costs of dubious morality. Some Lafarge former senior executives involved have been sentenced to prison including Bruno Lafont and Christian Herrault. Lafarge and Holcim (a Swiss conglomerate) merged officially in July of 2015.

3. WTI Prices: The value of the world’s most famous Crude Oil went into the weekend near $83.30 via futures markets. The commodity is certain to open with volatility early on Monday, this as folks weigh in via their existing behavioral sentiment which will range from speculative perceptions to insights they hold to be true (but that could prove false). WTI Crude Oil challenged 79.00 USD momentarily on Friday, before sparking upwards as cautious attitudes likely ignited doubts about what would happen this weekend in the Middle East regarding potential developments. Wagering on WTI in the coming days for day traders may be akin to spins of the roulette wheel.

2. Apex Heights: The winning streak and surge upwards for the Nasdaq 100, S&P 500 and Dow 30 via gains have caught some investors by surprise and standing on the sidelines. Some large financial institutions may find they have to explain why they did not participate in the rally which has unfolded since late March. The S&P 500 has gone up around 9.5% during this time.

1. Straight Talk: The Hormuz and whether or not the strait is open for oil tankers will remain a catalyst for all global assets until clarity is gained. In the meantime a whirlwind of noise and threats from President Trump, the U.S White House and Iran will remain a menace for all traders – small and large. Is the Strait of Hormuz open or closed?

Copy and paste the text from AMT that you want to share

postN87

AMT Top Ten Thoughts and Trepidations for the 22nd of March, 2026

The Return of AMT's Top 10 Illustrious 'Weekly' Salvos

First we must congratulate those who were willing to climb out from under their rocks (and bomb shelters) to offer musings. But let’s not digress….. to the AMT Top Ten List we go.

AMT Top Ten for the 22nd of March 2026

10. March Madness: The NCAA Men’s Basketball Championship is underway. Some of the more hated schools remain catalysts. Our pick, the University of Arizona Wildcats. 

9. Bitcoin: Traversing above 68,000.00 USD currently almost feels like an accomplishment considering BTC/USD was near 63,000.00 in early February and again in early March. But do not blink your eyes. BTW, MSTR (the much loathed MicroStrategy by some AMT folks) went into this weekend below $136.00 per share.

8. South Africa: The USD/ZAR finished Friday near 16.96800 depending on bids and asks. On the 29th of January the currency pair was close to 15.65000. The South African Rand has done well over the long-term, but it is correlating to the broad Forex market concerns. Day traders should not take things personally, and accept that risk adverse moves – particularly as a major war rages is part of speculation. Near-term viewpoints can differ with long-term prospects. 

7. Not Glimmering: Gold at the start of the Iranian war was around $5,260.00, it has fallen to a mark of $4,491.00 this weekend. Showing gold’s speculative momentum beforehand hand, outmatched current values. Where next?

6. Silver: Above 120.00 USD briefly towards the end of January, the commodity is below 68.00. Wild betting has caused a drop of more than 42%. Too much exuberance.

5. Risks: U.S 10-Year Treasury Yields were below 3.95% on the 27th of February, via Friday’s close rates are above 4.38%. Can you spell f.e.a.r?

4. Safe Haven: The U.S Dollar Index which had been showing solid downside is near 99.500, on the 27th of February it was around 97.850 – a rather legitimate rise. 100.000 may be a target by some large players.

3. Shrieking Hyperbole: WTI Crude Oil prices are certainly getting plenty of attention. However, voices expressing concern about WTI touching higher values starts to sound like an auction in order to get attention for the circus barkers. WTI remains near 100.00 USD and this mark is a barometer. The price is high and it can go higher, but expressed fear about $140.00 and $200.00 should be treated with disdain in the near-term.

2. Iran War: The conflict in the Middle East cannot be downplayed, but it can become fearmongering by Cassandras’. The U.A.E is still open for business and other nations in the Middle East are functioning. Yes, there is noise and the situation can grow more dangerous. But the potential of freedom for the people of Iran is a solid goal, though some may find this naive until it is proven. Can it become fact?

1. Coming Attractions: U.S stock markets are rightfully nervous. Friday’s close for the S&P 500 has brought it into terrain that challenges its 200 day moving average. The combination of weak technical attitudes and behavioral sentiment is a dangerous mix. Risk management may not be enough for day traders to survive current conditions, sitting on the sideline instead of betting on equity indices intraday may be more efficient and less lethal.

Copy and paste the text from AMT that you want to share