post203

AMT Top Ten Miscellaneous Picks for the 26th of April 2024

AMT Top Ten Miscellaneous Picks for the 26th of April 2024

10. Salk Institute: Work known as the Harnessing Plants Initiative is focused on optimizing the ability of plants to help combat climate change, sometimes via root systems in order to help reduce carbon dioxide. Problematically when plants die they do release carbon dioxide too. One key to the HPI project maybe altering the affects of Suberin. The Salk Institute received 50 million USD last year from the Hess Corporation to fight climate change.

9. Anticipation: Chicago is celebrating today after landing quarterback Caleb Williams and wide receiver Rome Odunze as hoped. However, as the August 2024 Democratic National Convention approaches, trepidation for the potential of nasty demonstrations is building.

8. Quantum Investing: Oak Ridge National Laboratory has announced a successful test using the H1-1 computer via Quantinuum to study the spread of disease via quantum mathematical models. Honeywell International Inc. owns a large stake in Quantinuum which is a stand alone company valued at approximately 5 billion USD.

7. Speculative: Gold is near 2348.00, the price is below values seen last week, but remains high via some perspectives as the USD creates havoc.

6. Forex: Whipsaw volatility has been seen in foreign exchange as financial institutions fight to get a proper gauge on their mid-term outlooks. Equilibrium will continue to be fought over today.

5. Fixed Income: U.S Treasury yields are battling within higher ground as investors look for guaranteed returns as behavioral sentiment remains fragile. And there is a likelihood the next four days of trading will continue to produce a whirlwind.

4. Equities: Major U.S indices continue to grapple with headwinds caused by a murky economic outlook. Retail traders speculating via CFD’s should remain careful. Patience is a key for the S&P 500, Nasdaq Composite, and Dow 30. Trying to ‘time’ the indices for short-term wagers is dangerous because technical trends are vulnerable.

3. Data: U.S Core Personal Consumption Expenditures Price Index statistics will be released today, inflation via the GDP Price Index came in higher than expected yesterday. Forex will react to the PCE results which is anticipated to have a gain of 0.3%. Financial institutions do not need another scare today. The Revised University of Michigan Inflation Expectations reading should also be given attention which will be published afterwards.

2. BoJ: The Bank of Japan is clearly playing a game of truth or dare with Forex. Having held interest rates at merely 0.10% earlier today, the USD/JPY climbed comfortably above 156.000 and is presently near the 156.540. The BoJ will remain in the news as the USD/JPY trades around a 34 year high. As financial institutions clamor for a higher interest rate, the BoJ apparently is more concerned with creating dynamic export demand and growing Japan’s economy, believing it can keep inflation under control. Speculators need to be on alert for an intervention from the Bank of Japan, but cannot count on one either.

1. Analysis Paralysis: The Federal Reserve was served an intriguing dose of results via the lower than expected growth numbers from the Gross Domestic Product yesterday, while digesting a higher GDP Price Index. Jerome Powell has stressed caution and patience. However, yesterday’s stubborn inflation numbers with waning growth creates the prospect for stagflation. This is an important political year because of the upcoming U.S elections in November. Next Wednesday the Fed’s FOMC Meeting pronouncements will be made. There will not be a change to the Federal Funds Rate on the 1st of May. It is the FOMC Statement’s vocabulary which will get attention. Today’s inflation reports will play a role in next week’s Fed meeting. Day traders may want to tune out political noise from pundits today which will certainly be sounded. The inflation numbers globally are tricky, and have created overthinking by investors and central banks which remain mostly reactive.

postN2.1

Impact: Powell’s White Flag, Inflation Data, and the BoJ

Impact: Powell's White Flag, Inflation Data, and the BoJ

Federal Reserve Chairman Jerome Powell’s waving of the ‘white flag’ last Tuesday, when he admitted that inflation was producing stronger than anticipated data had been essentially wagered on since the second week of March by financial institutions. Powell’s speech acknowledging the Fed will find it difficult to cut the Federal Funds Rate in the mid-term (and probably at best not until late this summer) simply verified Forex positions which had already been taken by large players who could afford to make mid-term wagers.

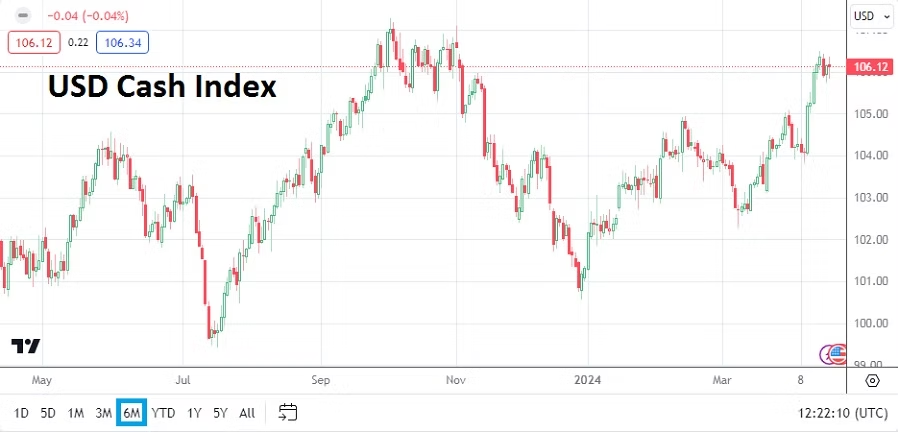
The USD Index has returned to early November 2023 values, and appears able to challenge late September and October prices if inflation data this week causes more volatility, which should put traders of major currencies like the GBP, EUR, JPY and others on full alert. After the USD spiked higher from the 10th to the 12th of April, Forex speculators have seen dynamic action incrementally flirting with stronger USD results the past week and a half.

USD Cash Index Six Month Chart as of 21st April 2024

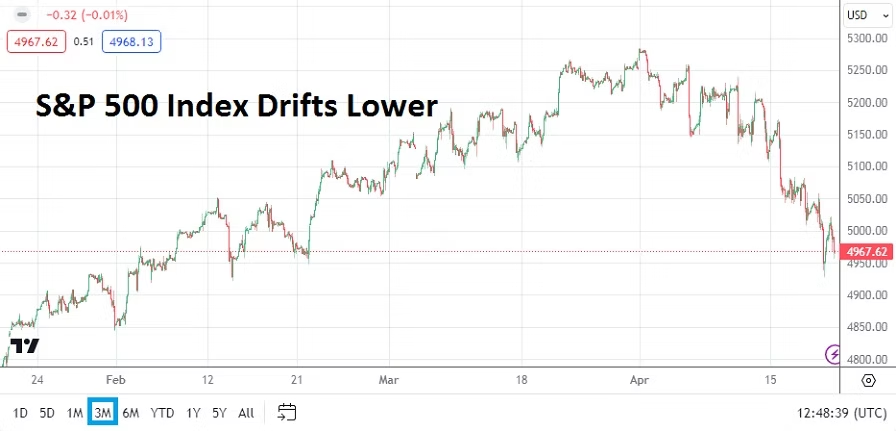
Nervous trading continues to be seen in U.S equity indices. The Dow 30 and the Nasdaq 100 are fighting near ratios they touched in the last week of January. And the S&P 500 is traversing ground from the first week of February.

S&P 500 Three Month Chart as of 21st April 2024

Content

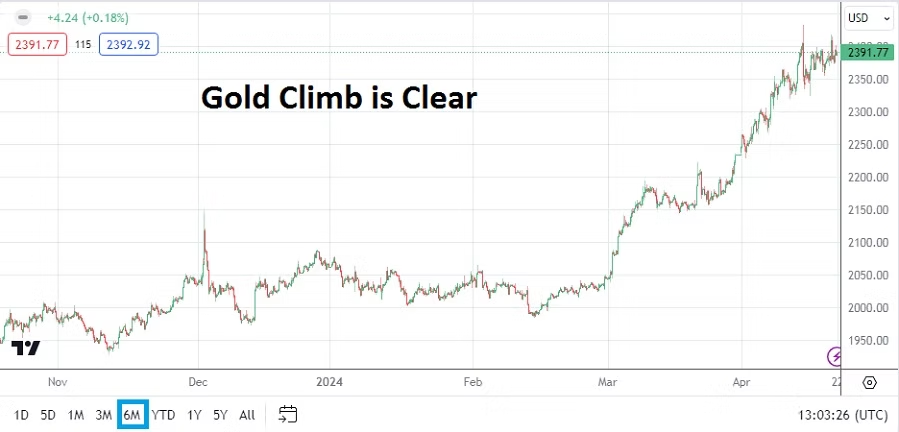
Gold Six Month Chart as of 21st April 2024

Gold remains speculatively high as its hovers near 2,400.00 USD per ounce. The price of the precious metal has not given back its gains made since the start of March and this is intriguing because of the ‘known’ USD inverse correlation, which had proven to work well with the precious metal over the past couple of years but has been stopped in its tracks for the moment. Technically Gold may look overbought, but geopolitical concerns and the prospect that some central banks may be strong buyers could be fueling the rather incremental gains. Retail traders of Gold need to be careful because price action is likely to produce more surprises.

Forex has been turbulent the past handful of months as shifting behavioral sentiment has created choppy conditions. This coming week contains large fundamental risk events via data releases traders should monitor. USD/JPY speculators will also have to contend with the Bank of Japan.

Monday, 22nd of April, China Loan Prime Rates – borrowing costs are anticipated to remain at the current benchmarks. China produced slightly better Gross Domestic Product results last week, but Industrial Production numbers were weaker. Consumers in China remain burdened by decreasing home values and concerns about the economy.

Tuesday, 23rd of April, European Union and U.K Manufacturing and Services PMI – E.U results via the PMI readings are expected to show slight improvements. However the readings from the United Kingdom are anticipated to come in flat. The EUR/USD and GBP/USD will be affected by the results, but the currency pairs will likely remain focused on U.S data later in the day.

Tuesday, 23rd of April, U.S Purchasing Managers Index – the Manufacturing and Services sectors are expected to produce slightly better readings than the previous month. These results will be interesting taking into consideration the Empire State Manufacturing Index numbers last week were bad. The PMI statistics will provide some impetus to the broad Forex market.

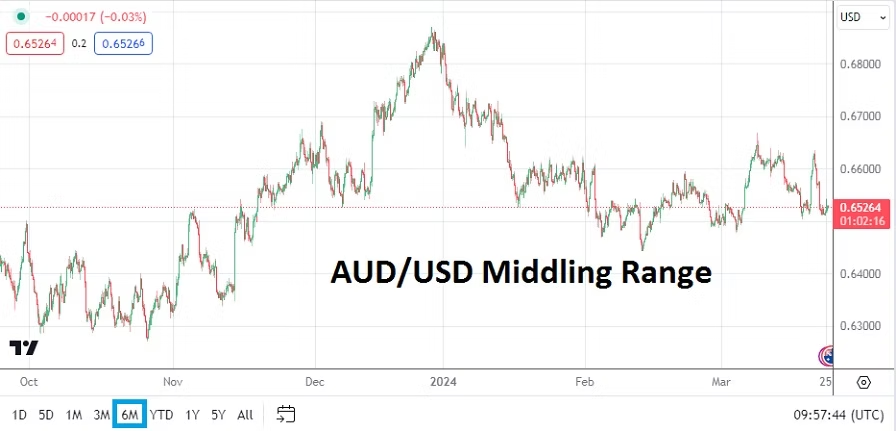
Wednesday, 24th of April, Australia Consumer Price Index – inflation data is anticipated to be higher than the previous month’s results. While stronger inflation is not something that will make consumers happy in Australia, stubborn price results may keep the AUD/USD slightly steadier. The currency pair is traversing values last seen in the second week of November 2023 as of this writing.

Thursday, 25th of April, U.S Advance Gross Domestic Product and Price Index – these numbers are certain to have an impact on all financial assets. A decline in growth is anticipated in the U.S compared to the previous month’s result, but the Price Index is expected to show an increase. Jerome Powell having come out last week and said inflation is causing uncertainty within the Federal Reserve, may have a bit of inside knowledge regarding this GDP inflation number and ‘tipped his hand’. If this inflation gauge is higher than anticipated it could pour fuel onto the already volatile USD. All Forex traders need to pay attention to these results and be prepared with solid risk management.

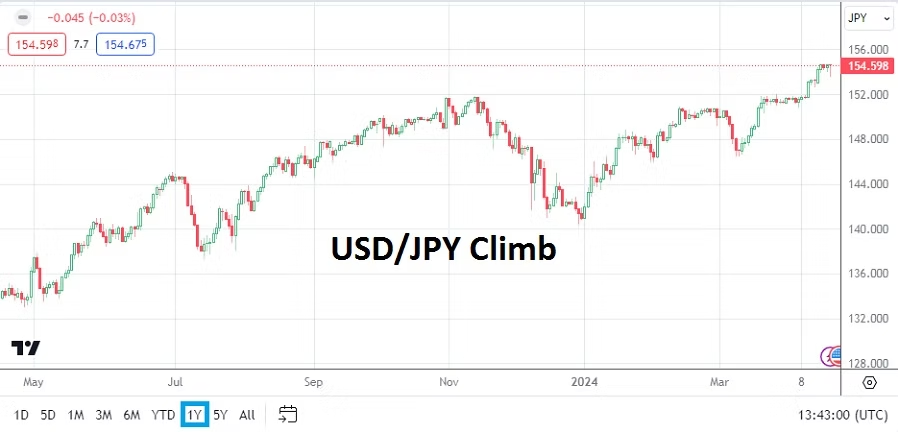
USD/JPY One Year Chart as of 21st April 2024

Friday, 26th of April, Bank of Japan – in what has already proven to be a couple of weeks filled with drama for the USD/JPY, the BoJ will step into the limelight. During their last central bank meeting the Bank of Japan increased the Policy Rate to 0.10%. It was the first time the BoJ hiked interest rates in 17 years. The USD/JPY is trading at values last seen in June of 1990. The Nikkei 225 has come off of recent record heights, but the famed Japanese stock index is also trading within territory seen in January of 1990. Business activity via the Core Machine Orders and the Tertiary Industry data last week were stronger than anticipated.

The Bank of Japan may want to maintain a weaker USD/JPY equilibrium to continue fostering domestic growth. However, many financial analysts have been calling on the BoJ to become more hawkish regarding monetary policy. The interest rate decision is certain to cause immediate volatility before and after the Policy Rate is made public. USD/JPY traders need to be prepared for fireworks. A slight raise of the interest rate seems to be needed, but after the March hike the BoJ may prove conservative again. The 34 year lows now being seen in the Japanese Yen are astonishing.

Friday, 26th of April, U.S Core PCE Price Index, and Inflation Expectations – the data from the government, and the reading from the University of Michigan will close the curtain on a big week of economic statistics for all traders. The USD will react to these outcomes. It should be noted the previous Inflation Expectations data from the University of Michigan caused a storm in Forex when it came with 3.1% gain.

postN77.1

Forex: Behind the Curtain as Speculative Deja Vu Strikes

Forex: Behind the Curtain as Speculative Deja Vu Strikes

Friday jobs reports came in stronger than anticipated on the surface, and this led to a roller coaster like ride for Forex traders as results were acted upon by financial institutions. However, a look behind the data shows ‘positive’ results were spurred on by part-time hiring and government influences leading to a notion that jobs numbers were not exactly a ray of sunshine regarding U.S economic health. The suspicious results cause a desire to look for ulterior motives, and to wonder if election year politics are playing a role in the U.S employment picture.

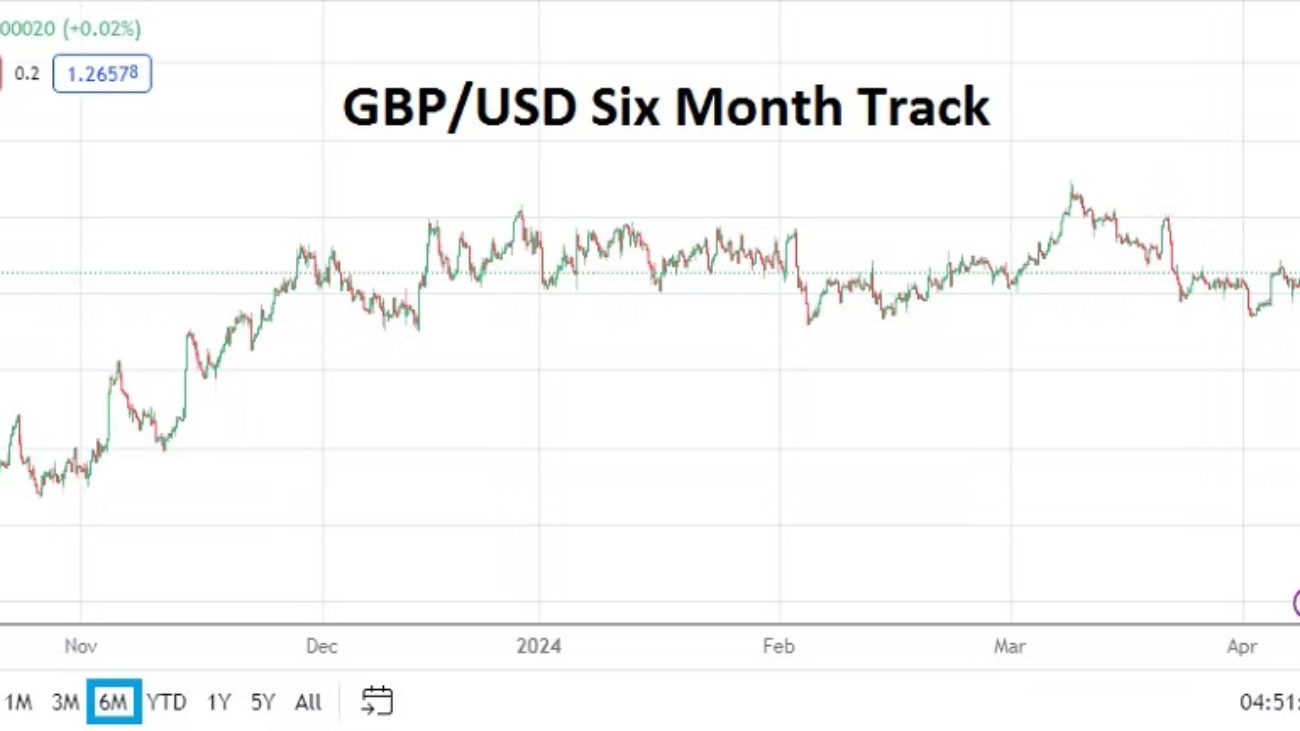
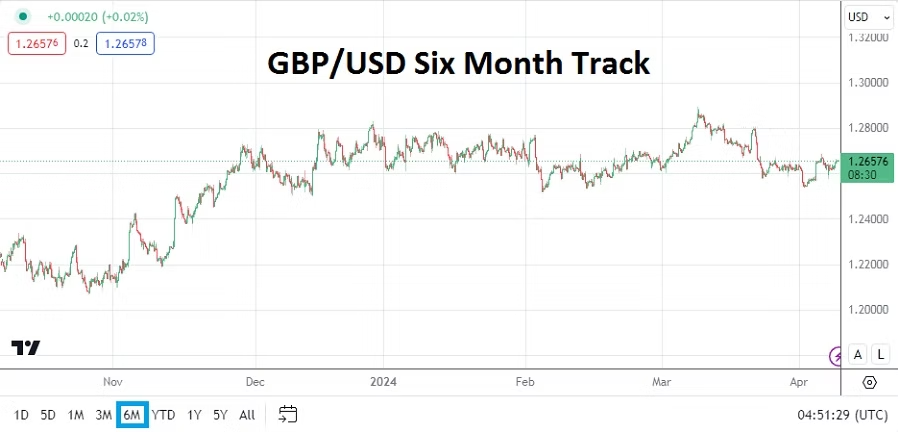
GBP/USD Six Month Chart as of 9th April 2024

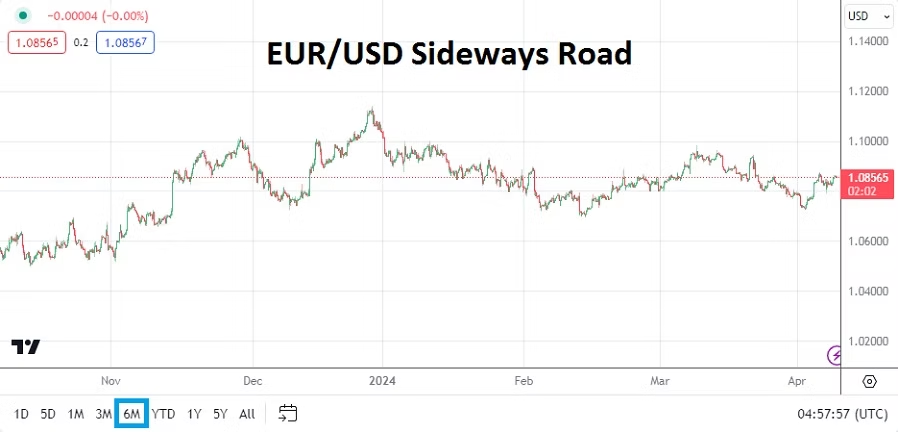
The GBP/USD and EUR/USD are rather insightful for technical and fundamental traders. The currency pairs are languishing as of today’s values near pricing that was seen in the second week of December. Since the ‘announcement’ from the U.S Federal Reserve on the 13th of December that a change in monetary policy would begin to occur in 2024, in actuality nothing has really happened, except government ‘speak’ trying to sound as if everything is understood and in control, while it is clearly not.

Economic data from the U.S and Europe has continued to be soiled by mixed results, and retail speculators looking for a trend to emerge have had to deal with choppy conditions. Financial institutions remain unclear about interest rate outlooks. The Fed while trying to ‘sound’ dovish rhetoric remains locked within a Google engine keyword mantra as they mutter the phrase ‘over time’ when trying to convince people that interest rates will ‘eventually’ be cut.

Last week leading up to the Non-Farm Employment Change numbers, many FOMC members were offering cautious tones about the Federal Funds Rate and warning it should not be changed yet. The implication of the Fed’s verbiage could lead some to suspect they have all practiced statements handed to them by their overlords who are concerned this is an election year and jobs are in jeopardy.

EUR/USD Six Month Chart as of 9th April 2024

Which leads us back to Forex and all financial assets, as investors try to swim waters which have left fundamental perspectives grasping at data which is not easy to decipher. U.S government policy is practicing fiscal spending that is causing massive debts, and perhaps influencing hiring data which may be more akin to putting lipstick on a pig. Many U.S voters seemingly lean towards electing officials who promise to hand out the biggest ‘social rewards’, while ignoring there will be a price to be paid down the road.

The Federal Reserve in the meantime tries to sound optimistic about inflation eroding, but concerns due to U.S government debt being accrued, and global geopolitical affairs combined with energy policy which is making it more expensive to maintain cheap transportation, efficient agriculture and manufacturing, shadow the Fed’s hopes. WTI Crude Oil remains over 86.00 USD per barrel. Gold is trading at record high values and above 2300.00 USD. Does anyone see the dangerous connections? Equity indices should be watched as a barometer this week.

USD/JPY Six Month Chart as of 9th April 2024

Monday, 8th of April, Japan Average Cash Earnings and Economic Watchers Sentiment – yesterday’s reports matched expectations regarding wages, but workers surveyed noted their concerns about incremental inflation which is being seen in Japan. The USD/JPY is challenging November higher values and the Bank of Japan has been widely criticized for not raising interest rates more aggressively. However, it is possible the BoJ wants the Japanese Yen to remain within its weaker price range to spark a stronger Japanese economy via exports.

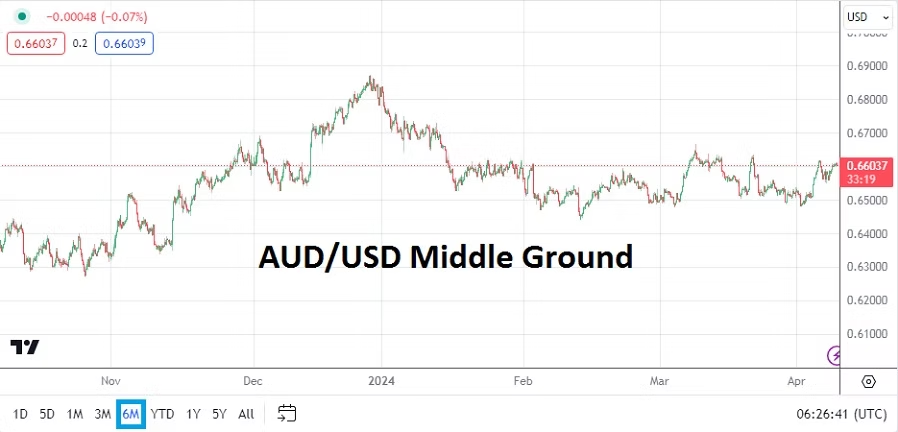
AUD/USD Six Month Chart as of 9th April 2024

Tuesday, 9th of April, Australia Westpac Consumer Sentiment – the results via the consumer reading came in negative. The AUD/USD like the GBP/USD and EUR/USD is traversing values tested in the second week of December 2023, leading to the feeling of deja vu.
Wednesday, 10th of April, U.S Consumer Price Index – you have heard this before, the inflation reports from the States are going to rattle the financial markets including Forex. The USD is certain to react. Data from the U.S has produced surprises aplenty in the past few months. The Consumer Price Index is important and day traders certainly need to pay attention.

Thursday, 11th of April, European Central Bank – the ECB is not expected to change its Main Refinancing Rate, but many analysts believe they should cut borrowing costs. However, the ECB will likely remain within the camp of choosing to ‘wait and see’. The ECB Press Conference with Christine Legarde has widely become regarded as an opportunity for political speech as much as an economic dialogue. Recent data from the European Union suggests the worst of the recessionary cycle is gone, but German Trade Balance numbers released on Monday were negative, highlighting hurdles remain. Inflation is a worry, and a cut to the interest rate might be able to help spur on economic activity while counting on lagging data to prove proactive policy should be implemented. But this likely is not going to happen and the EUR/USD will remain problematic.

Thursday, 11th of April, U.S Producer Price Index – these slew of reports should be watched carefully. If the data is stronger than expected it is likely a part of the residue caused by higher energy costs that have affected logistics and created more expensive raw materials which are needed to produce goods. It was the higher PPI reports last month that caused dramatic tidal shifts in Forex, speculators should brace for the potential of additional mayhem.

Friday, 12th of April, U.K Gross Domestic Product – last month’s GDP numbers from Great Britain came in slightly higher than expected with a 0.2% gain, this report is anticipating growth of only 0.1%. Traders should take a deeper look at the statistics upon publication and check for revisions to past months. The U.K economy has been struggling, the ‘growth’ results will affect the GBP/USD before going into the weekend.

postN51

AMT Top Ten Miscellaneous Postings for the 5th of April 2024

AMT Top Ten Miscellaneous Postings for the 5th of April 2024

10. Petrichor: The pleasant smell after a rain has fallen following a long dry spell which elicits earth’s fragrance. The Fed is likely hoping for this sensation via ‘weaker’ Non-Farm Employment Change numbers today. In December the Federal Reserve spoke about data signals needed in order to cut interest rates. If jobs statistics are stronger than anticipated, there will be no ‘petrichor’ for the Fed.

9. Underreported: Five engineers from China on their way to work for the Dasu dam project they participated, were killed in a ‘suicide’ terrorist attack in Pakistan on the 26th of March. Terror attacks in Pakistan on Chinese involved with infrastructure ‘Economic Corridor’ work have been increasing.

8. Qubits: Microsoft and Quantinuum recently announced they have made breakthroughs regarding quantum computing research reliability. Results have shown 14,000 ‘test routines’ without errors. The emergence of quantum technology approaches.

7. Intrinsic Value: Cocoa is near 9640.0 USD per metric ton as of this morning and remains speculatively energetic. Bitcoin is slightly below 67,000 USD and continues to ‘beat’ the notion that intrinsic value is important.

6. Precious: Gold prices have ‘fallen’ below 2300.00 USD per ounce, and is near 2289.00 for the moment, but the metal is shining as crowds admire its ability to create a safe haven.

5. WTI Crude Oil: Middle East news is rumbling and hyperbole is resonating, the price of the commodity is over 86.40 USD per this writing. A calm weekend, and peaceful end to Ramadan this coming Tuesday might help calm nerves. Higher oil prices will not help global inflation.

4. Forex: The USD/JPY has started to experience waves of volatility and has recently challenged long-term highs. Bottom line is the notion that large players are positioning for today’s U.S data which will affect all financial assets as USD centric power resounds.

3. Equities: The U.S major stock indices are beginning their day near lows not seen since the 15th of March for the Dow 30, and the 19th of March for the S&P 500 and Nasdaq Composite. Nervous?

2. Bonds Watch: U.S Treasuries need to be monitored as the 5, 7, and 10-Years Notes respond to nervous investors and fears of a new ‘inversion’. Having come off of high yields a couple of days ago, doesn’t mean all is well as values languish near late September 2023 technical realms.

1. Data: Recent chatter from many Fed FOMC members have created anxious investors. Vivid reactions will occur after the Non-Farm Employment Change and Average Hourly Earnings. Bluntly, today’s jobs reports are crucial and the Fed would like the results to be weaker than anticipated in order to consider cutting interest rates. However, if hiring comes in stronger, it would be a sign of a resilient U.S economy and would ignite more USD strength. The first half hour following the jobs numbers may look counter-intuitive regarding price action as financial institutions adjust their trading positions.

postN79.1

Forex Volatility and Coming Data Attractions for this Week

Forex Volatility and Coming Data Attractions for this Week

Nervous trading results have hurt many day traders and likely financial institutions too, as behavioral sentiment in Forex gets blindsided by rather mixed U.S data and the Federal Reserve not giving a definitive answer regarding monetary policy. The violent trading in the USD last week was expected, but the turbulence that many Forex pairs experienced on Thursday and Friday of last week was rather vicious. For all the perceived sophistication of Forex markets via financial institutions, the trading results last week point to a definite fear of the unknown.

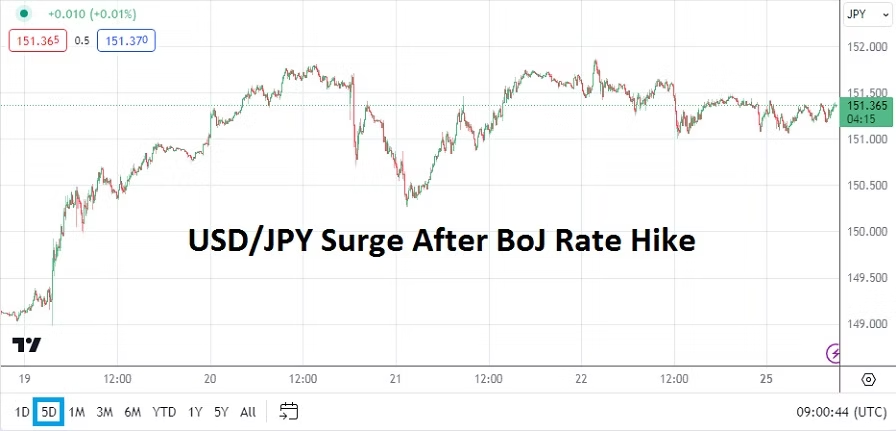
USD/JPY Five Day Chart as of 25th March 2024

While the Bank of Japan finally changed its interest rate policy and moved to a Policy Rate of 0.10% early last week, this did not create selling momentum in the USD/JPY. The Federal Reserve’s dangling of potential interest rates to come this year caused temporary weakness in the USD, but as financial institutions and their clients looked at the prospects for a more dovish Fed they apparently became unimpressed as the days passed.

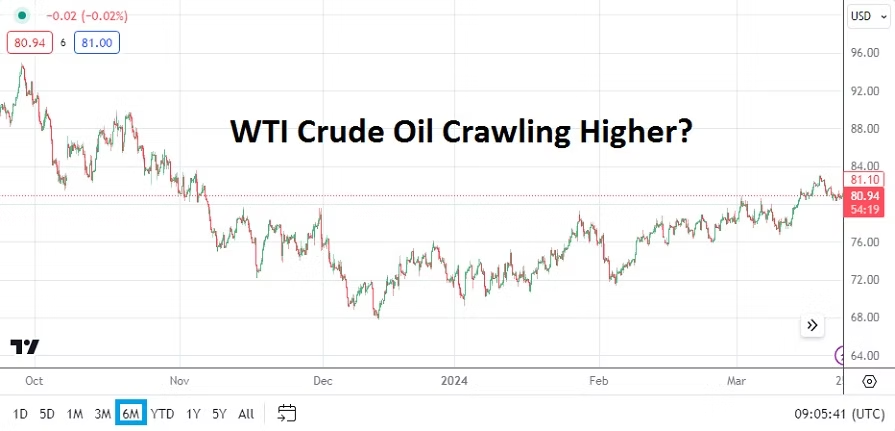
WTI Crude Oil Six Month Chart as of 25th March 2024

The Fed seems to be betting on weaker jobs numbers developing, and there has been data which points to part-time jobs increasing, and full-time jobs becoming harder to find in the States. Jerome Powell said last week that if jobs numbers start to show weakness that the Fed would be willing to begin cutting interest rates even if inflation remains sticky. Lagging economic data correlations have not eased the Fed’s problems.

The Fed has also admitted inflation in housing, transportation and food remains problematic. WTI Crude Oil spent much of last week above 80.00 USD per barrel as its price has begun to show signs of rising incrementally again; and there is little the Fed can do about more expensive energy costs should they be seen. Higher costs for logistics will not make anything cheaper. Pricier mortgages, more expensive rent and insurance rates for cars and gasoline is creating serious knock on effects.

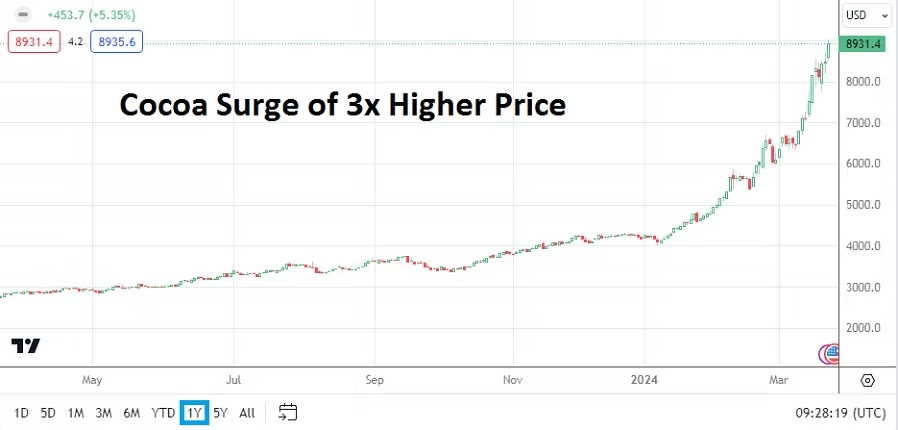
And for the sake of acknowledging the screaming prices in Cocoa, please have a look at the chart below which should explain why your chocolate products are going to be more expensive in the coming months. The price of the most delicious commodity in the world has tripled in less than a year’s time and is around 8931.0 USD per metric ton as of this writing.

Cocoa One Year Chart as of 25th March 2024

Gold turned in a violent week of trading too as it reached 2224.00 last Wednesday, only to fall back to a known value around 2165.00. Day traders are dealing with violent cycles in Forex because sustained trends have been nearly impossible to find. While U.S equity indices are fighting upwards, speculators who are afraid of heights are likely being cautious if they are betting merely on the daily results from the S&P 500, Nasdaq 100 and Dow Jones 30 instead of investing for the long-term.

This week’s coming data from the U.S is important, financial institutions are already dealing with plenty of noise, and they will have to be careful regarding their interpretations regarding the coming economic statistics. Meaning day traders who are speculating in all financial assets should use risk taking tactics that are planned significantly in advance.

Monday, 25th of March, U.S New Home Sales – a slight gain is expected, but mortgage rates continue to shadow the housing sector and cause concerns.

Tuesday, 26th of March, U.S Consumer Confidence via the Conference Board – the reading is anticipating a slight increase. Consumer numbers from the U.S have come in mixed recently. A stronger result than estimated might not be welcomed by traders with bearish sentiment regarding the USD. The Fed wants its cake and to eat it too, they would like to see weaker consumer numbers and a soft economic downturn. If U.S shoppers remain confident this could help sustain inflation. It should be noted too, that Core Durable Goods Orders data will be released one and a half hours before the Consumer Confidence numbers.

AUD/USD Six Month Chart as of 25th March 2024.

Wednesday, 27th of March, Australia Consumer Price Index – inflation numbers are expected to come in slightly higher than the previous results. Like most other central banks, except for the BoJ, the Reserve Bank of Australia would enjoy seeing inflation erode. The AUD/USD will react to the results certainly, but the price action might prove complicated because of USD centric notions.

Thursday, 28th of March, U.S GDP, Weekly Unemployment Claims, Pending Home Sales, and Revised Consumer Sentiment from the University of Michigan – put bluntly day traders will have to be well prepared for the combination of data from the States. Spectators who do not have large trading accounts and cannot take on a great amount of risk, should seriously consider sitting on the sidelines until most of the data is published. The GDP numbers will be watched carefully, while they are expected to match last month’s total, any surprises will affect the USD immediately in Forex. Weaker growth numbers might cause USD sellers to ignite positions.

However, before traders react too much to the Gross Domestic Product numbers, the Weekly Unemployment data will also impact the financial market. Financial institutions are anticipating a higher amount of unemployment claims this week. Also, at the same time as the growth and jobs numbers, the Final GDP Price Index numbers will be brought forth. The mixture from these reports could cause speculative whiplash.

The housing sector numbers and consumer numbers which come one and a half hours later will finish off a very big day for traders and institutional investors. The wide array of data could make this coming Thursday rather loud, and again rather dangerous for retail traders to participate.

Friday, 29th of March, Japan’s Tokyo Core Consumer Price Index – the inflation numbers are expecting to show a slight decrease to 2.4%. The result should certainly be watched by USD/JPY and GBP/JPY traders. If the number were to come in higher than expected, this could cause additional volatility for the Japanese Yen. Financial institutions seemed to indicate last week they would like to see the BoJ become more aggressive with their Policy Rate.

Friday, 29th of March, U.S Core Personal Consumption Expenditures Price Index – the reading is expected to be below the previous month’s total. Traders should be on the lookout for revisions to past results. Financial institutions know this inflation number is important for the Federal Reserve, but they are concerned the U.S central bank doesn’t have the ability to combat inflation which is not part of the Core number. Energy and food costs which are hurting U.S consumers are not part of this report and likely making the Federal Reserve gun shy regarding monetary policy – which has caused a large part of the USD whipsaw trading results that Forex has experienced.

postN51

AMT Top Ten Miscellaneous Entries for the 22nd of March 2024

AMT Top Ten Miscellaneous Entries for the 22nd of March 2024

10: Jefferson: Jon Meacham’s Thomas Jefferson The Art of Power provides well written historical and psychological insights concerning one of the U.S Founding Fathers.

9. Shohei Ohtani: Major League Baseball has a gambling scandal. Claims that Ohtani’s interpreter ‘stole’ over 4 million USD from the player to pay off gambling debts beg for questions.

8. Saudi Arabia: The nation has announced it plans on investing 40 billion USD into Artificial Intelligence sector companies via its Public Investment Fund (sovereign wealth fund) and potential business partners.

7. Steve Jobs: Apple’s innovation and tech leadership appears to be weakening as the absence of its deceased leader fades into memory, and competitors grow.

6. Bank of Japan: Monetary policy was finally shifted on Tuesday, an interest rate of 0.10% was instituted, today’s National Core CPI data came in at 2.8%. USD/JPY is currently around 151.400 suggesting financial institutions believe the BoJ Policy Rate may have to be raised again.

5. Gold & Forex: The precious metal challenged 2223.00 USD on Wednesday after the Fed’s FOMC rhetoric but is trading near 2165.00 as of this morning, this as the USD has gotten stronger again producing FX volatility.

4. Hot Chocolate: Cocoa finished yesterday at 8477.0 USD per metric ton, the commodity cost 2880.0 USD one year ago. What and who are manipulating the market?

3. China: Official Foreign Direct Investment statistics are supposed to be released soon. China argues that the fall of foreign investment capital is being reported with bias and not taking into consideration the impact of coronavirus, global monetary policy changes, and cyclical investment fluctuations. However, the FDI numbers remain troublesome and should be watched.

2. Risk Appetite: Major U.S equity indices including the S&P 500, Nasdaq Composite, and Dow Jones 30 are challenging record highs as behavioral sentiment remains exuberant, along with Japan’s Nikkei 225.

1. Interest Rates: The Federal Reserve has hinted three interest rate cuts ‘could’ happen this year, this while inflation in housing, transportation and food remain significant for U.S consumers. The Fed seems to be indicating it believes U.S jobs data will get worse. Political shadows hover over the central bank as the presidential election draws closer. The Fed only has 6 FOMC meetings left and appears to be playing with fire.

post193

Inflation Encore: Forex Traders Gathering Important Evidence

Inflation Encore: Forex Traders Gathering Important Evidence

The USD has been weaker against many major currencies the past week and inflation numbers coming from the U.S will test short-term outlooks. It should be remembered that in February before the CPI numbers were published, some who were leaning towards a weaker USD were traumatized after the stronger than anticipated results. However recent U.S economic data has shown a rather polite and distinct downturn.

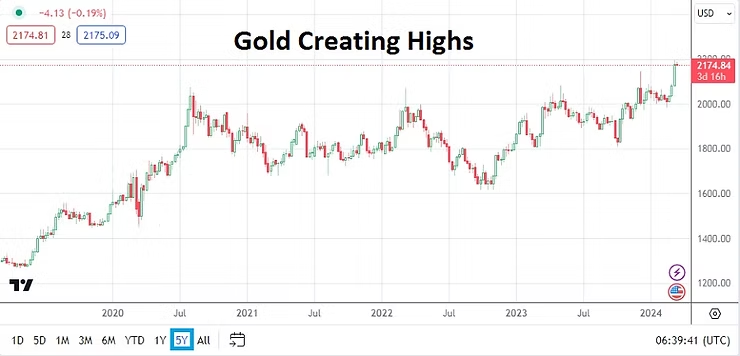
Day traders should brace for drama today and understand that financial institutions will lead the way, either catapulting trends or stopping them in their tracks. As Forex speculators get set, Gold continues to also flirt with highs, as of this writing the precious metal is near 2175.00 USD. Financial assets from equity indices to digital assets (yes, Bitcoin) are experiencing frothy returns as values seemingly attract more capital inflows. In other words, bullish behavioral sentiment is rather strong and traders are reminded to stay realistic with their goals.

Again, there is a difference between quick hitting speculators trying to take advantage of robust trends compared to long-term investing. Day traders still need to do their homework and not bet blindly.

Gold Five Year Chart as of 12th March 2024.

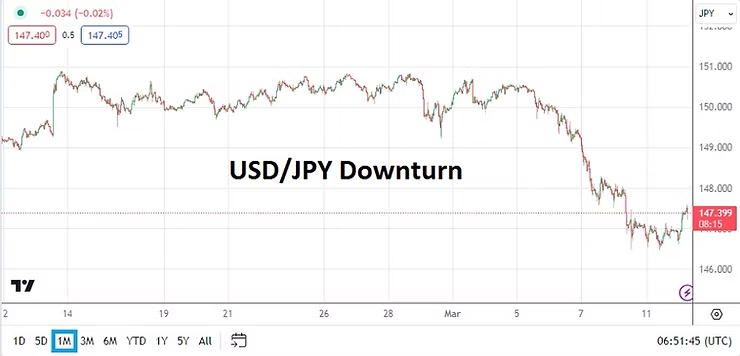
Monday, 11th of March, Japan GDP – Gross Domestic Product numbers yesterday came in with unexpected weaker results showing a gain of only 0.1% compared to an anticipated 0.3% gain. Yes, the USD/JPY held onto it downwards momentum, which it has established since last week. The trading results in the currency pair suggest financial institutions are placing their faith in mid-term outlooks.

USD/JPY One Month Chart as of 12th March 2024

Tuesday, 12th of March, U.S Consumer Price Index – the inflation reports will headline and drive market conditions near-term. Last month’s numbers provoked a strong reaction when prices remained stubborn. The monthly core report is expected to show a slight decline today, but the monthly broad number is actually anticipated to rise slightly. With mixed statistics forecast already, day traders need to be prepared for a lot of noise – which may prove rather misguided. The problem for the markets today will come from the interpretation of the numbers, if the CPI figures can simply come close to their expectations this might keep conditions from getting wild, but choppy trading should certainly be counted upon leading up to and following the publication. This month’s encore of the CPI inflation numbers will hopefully be less dramatic than February’s performance.

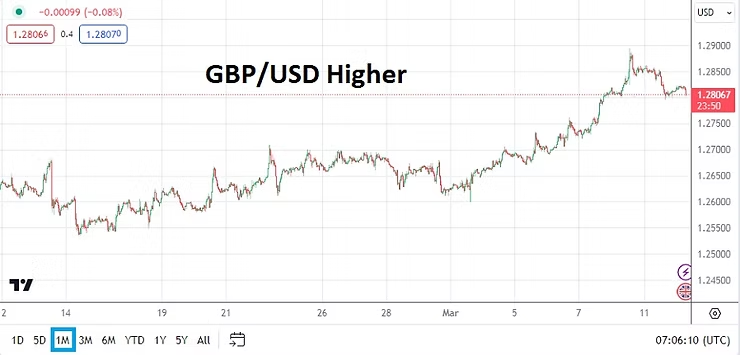
GBP/USD One Month Chart as of 12th March 2024

Wednesday, 13th of March, U.K Gross Domestic Product – a gain of 0.2% is expected via the growth number. Last month’s minus -0.1% outcome should serve as a reminder tough economic conditions remain evident. Yet, last month’s number actually beat a worse expectation. GBP/USD traders who have been patient with their bullish stances have been rewarded recently. A slight gain in the GDP number from the U.K could help bolster additional confidence regarding mid-term outlooks for the GBP/USD. The BoE, like the U.S Federal Reserve, will make their monetary policy pronouncements next week.

Thursday, 14th of March, U.S PPI and Retail Sales – the Producer Price Index and consumer spending numbers may produce the surprise for the week regarding market reactions. The Core PPI results are expected to be weaker, while Retail Spending is anticipated to grow. If the inflation results via the PPI data is weaker than anticipated this could allow for further weakness in the USD to develop.

Friday, 15th of March, China New Home Sales – real estate values in the nation remain a focal point for analysis. Another large decline in prices for homes would not be good news. The economy of China is suffering from deflation which hasn’t shown evidence of diminishing soon. China remains a vital part of the global economy. Industrial Production numbers will come from the nation on Monday.

postN89.1

Forex: Powell, ECB and U.S Jobs Numbers as Gold and Oil Run

Forex: Powell, ECB and U.S Jobs Numbers as Gold and Oil Run

Day traders and investors received a dose of optimistic ‘news’ last week as U.S economic data came in weaker than expected. While Forex certainly proved choppy as anticipated, the USD has shown signs of stability and perhaps has created a durable resistance level up above regarding its potential value looking into the mid-term.

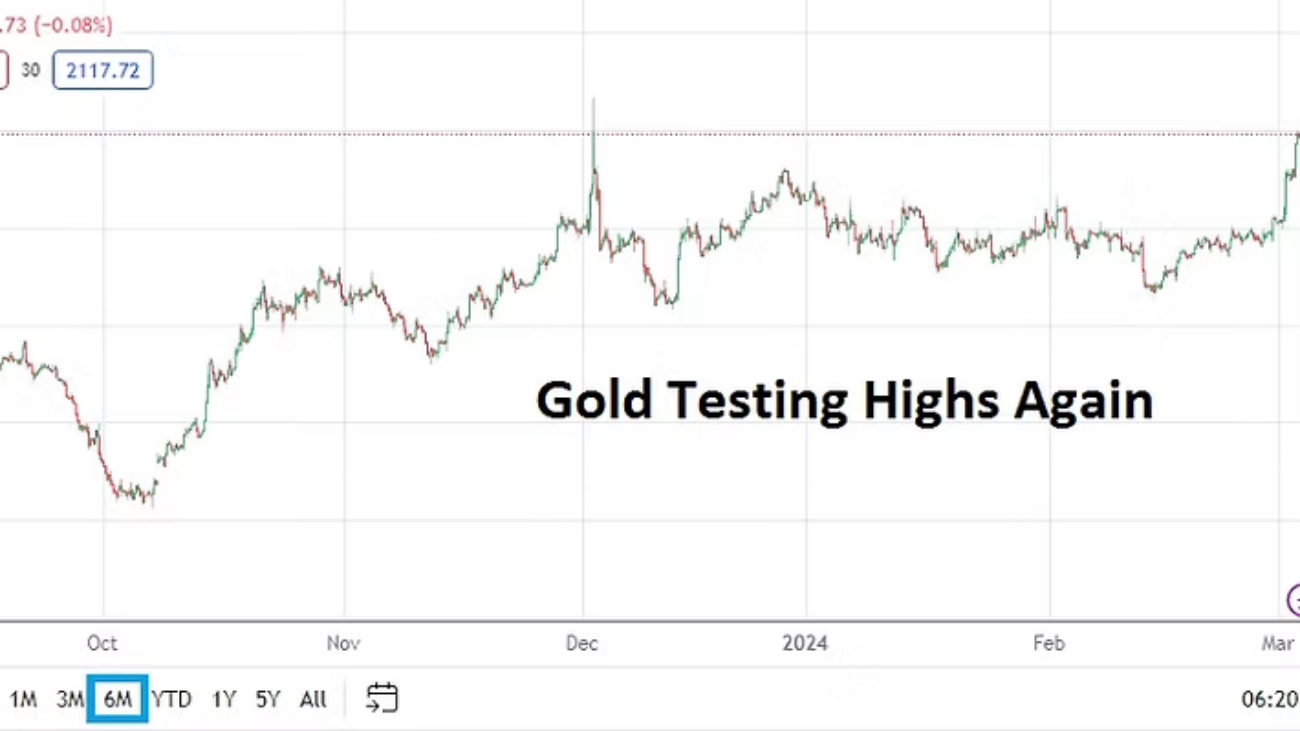
Gold Six Month Chart as of 5th March 2024

A potential telltale sign regarding the USD in Forex is the current price of Gold which is testing highs and as of this writing is near 2115.00 USD. While below the speculative heights of early December, the precious metal is above prices seen in late December when the USD was being sold heavily. The value of Gold is a rather solid barometer regarding outlook for behavioral sentiment in Forex. A weaker USD translates into a higher Gold price in many cases.

U.S Treasury yields have also decreased slightly over the past handful of days. And while U.S equity indices are within sight of record values, traders should monitor developing news regarding U.S regional banks and concerns about New York Community Bancorp (NYBC). For the moment it appears investors have not turned too nervous when considering the bigger picture of stock markets. Perhaps last year’s regional bank crisis has made investors in equity indices feel immune to fears of contagion stemming from bad commercial real estate lending. Or perhaps many folks are marching along merrily and refuse to pay attention for fear of missing out when their associates continue to parade into the indices.

The cryptocurrency market has come out of its deep freeze and sunshine is pervading the mindsets of speculative gamblers in crypto assets. U.S run ETFs are raising a lot of money. Folks have driven the market sky high again in the digital asset Bitcoin and its fellow travelers like Ethereum, Binance Coin, and there have been signs of pure casino like wagering in Dogecoin and Shibu Inu. Be carefu if you are considering dipping your toes into this ‘market’. Volatility and changes of sentiment can happen in the flick of an eye.

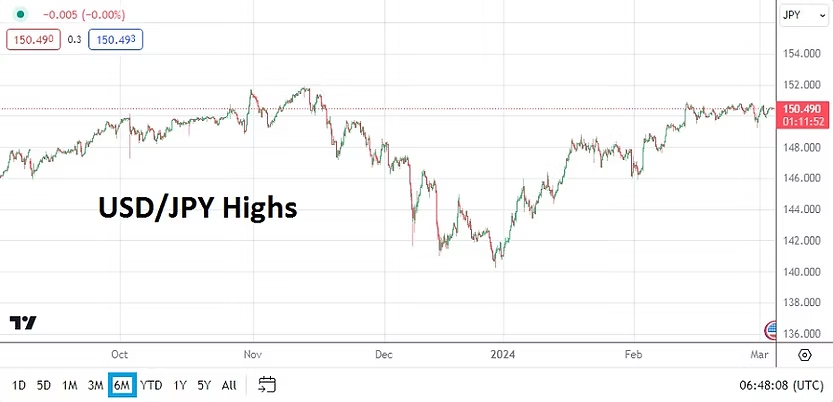
USD/JPY Six Month Chart as of 5th March 2024

Monday, 4th of March, Japan Capital Spending – a huge jump of 16.4% was reported yesterday. This points to better economic sentiment. The Bank of Japan has been getting a lot of attention the past handful of months because some financial institutions expect the BoJ’s monetary policy to begin changing. The USD/JPY remains near important resistance levels, but below the highs of last October and November 2023 values. Mid-term speculators may be leaning towards bearish sentiment in the currency pair, but a trend lower has not been established yet.

Tuesday, 5th of March, U.S Service PMI via ISM – last week’s growth and inflation data from the U.S was less than expected. While the U.S economy has shown rather stubborn growth, the American economy may be showing signs of slowing. Today’s reading is expected to come in below the previous month’s outcome.

Wednesday, 6th of March, U.S Federal Reserve Chairman Powell – the Fed chief will testify before the Senate via the Semi-Annual Monetary Report over a two day span. Because it is an election year a rather aggressive amount of questions will be asked. However, Powell is a skilled speaker and it unlikely he will be rattled by political rhetoric. Of interest will be any comments regarding inflation, this as the Fed Chairman is asked for insights regarding the Federal Funds Rate outlook. While this testimony in Washington D.C is usually a polite get together, the notion that some politicians may try to score points will make this a potentially important calendar event for investors to pay attention regarding financial market gyrations. Powell is expected to remain cautious regarding his answers.

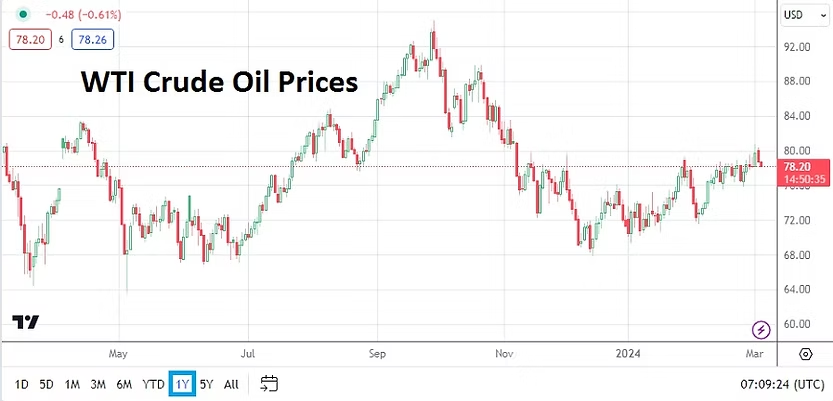
WTI Crude Oil One Year Chart as of 5th March 2024

Wednesday, 6th of March, U.S Crude Oil Inventories – last week’s U.S supply report posted increased results, yet the price of WTI Crude Oil jumped the end of last week. The value of the commodity remains within the lower part of its one year range and should be watched. Recent speculative action has shown some buying momentum. The price of energy is a big component within global inflation and should be watched as the 80.00 USD Crude Oil level is challenged.

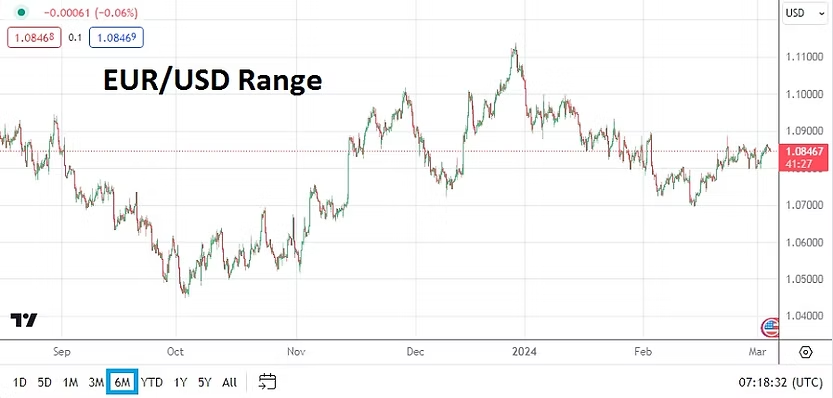
EUR/USD Six Month Chart as of 5th March 2024

Thursday, 7th of March, European Central Bank Main Refinancing Rate – once again the ECB is expected to not act. The question is if financial institutions may try to send the European Central Bank a message because of its ‘inaction’ as inflation remains stubborn in Europe and growth hard to achieve. The EUR/USD has returned to value above the 1.08000 mark again, but visions of a stronger EUR have been hard to attain. The combination of the ECB Monetary Policy Statement and Press Conference, as Fed Chairman Jerome Powell is addressing politicians in Washington D.C could make for an interesting day of volatility in Forex.

Thursday, 7th of March, U.S State of the Union – President Joe Biden will deliver his address to Congress.

Friday, 8th of March, U.S Non-Farm Employment Change and Average Hourly Earnings – weaker jobs numbers and diminishing wage escalation are expected. U.S economic data last week came in below estimates. This report will be a solid barometer for financial institutions. While the work force numbers in the U.S are said to be tight – meaning there is full employment – layoffs have certainly been taking place in some sectors. Also worth paying attention to in the ‘back pages’ of the report, will be the amount of average hours worked by employees which have seen a statistical decline emerge.

postN100.1

Forex Volatility as Central Banks, GDP, U.S Equities Shadow

Forex Volatility as Central Banks, GDP, U.S Equities Shadow

Perhaps it is good that today will see a lack of important economic data which will affect the markets. It might give a chance for day traders to relax and to gauge the thinking of financial institutions and investors before Central Banks, and important growth and inflation numbers shift behavioral sentiment later this week. While Forex has remained a minefield, U.S equity indices have soared to record heights. More volatility will come.

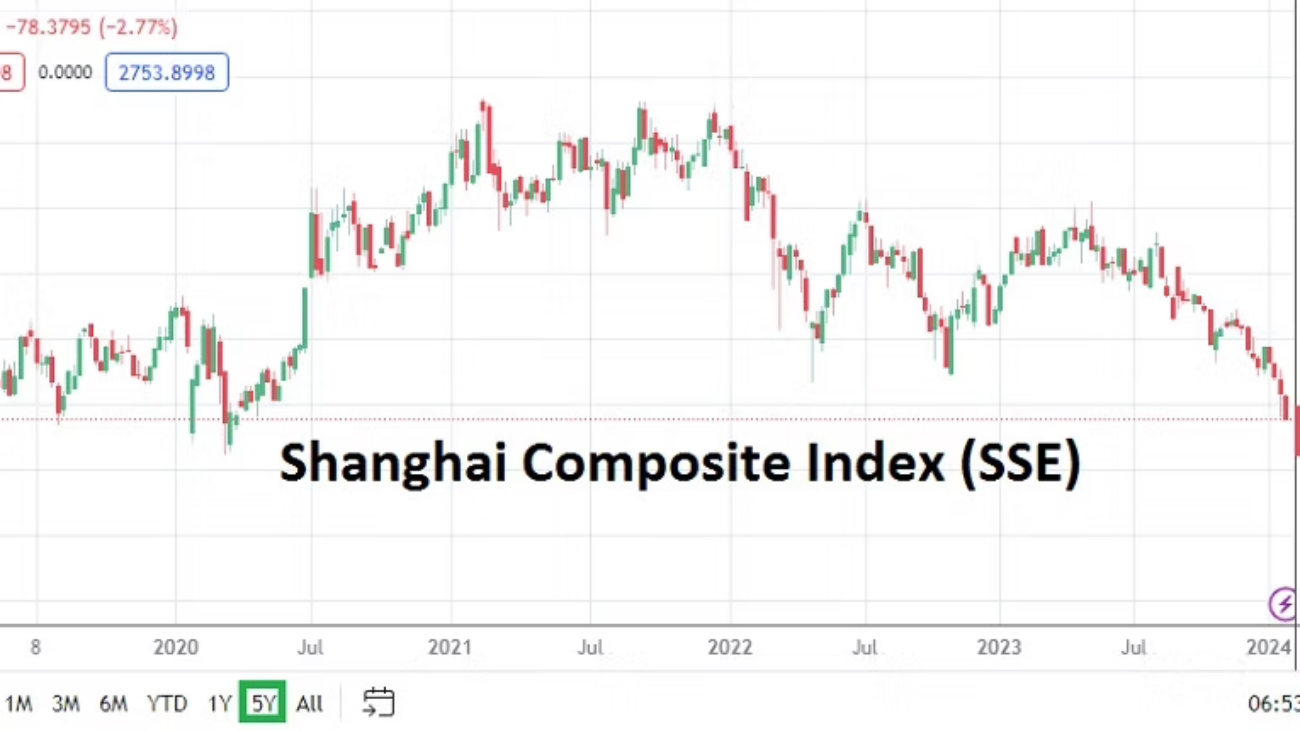
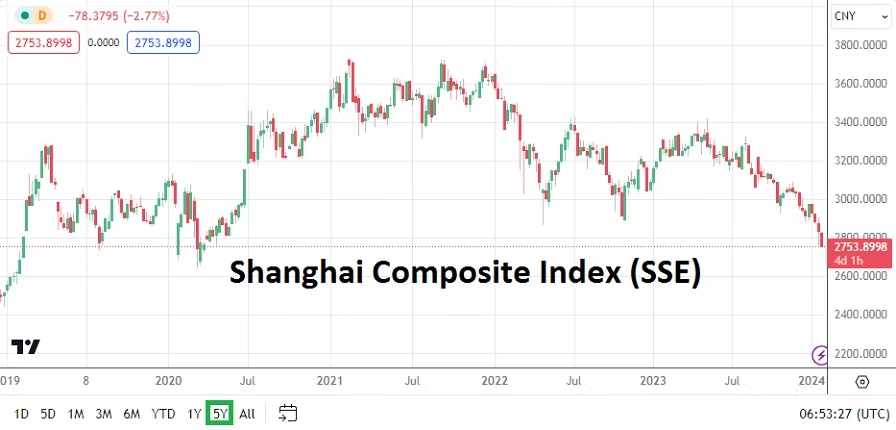
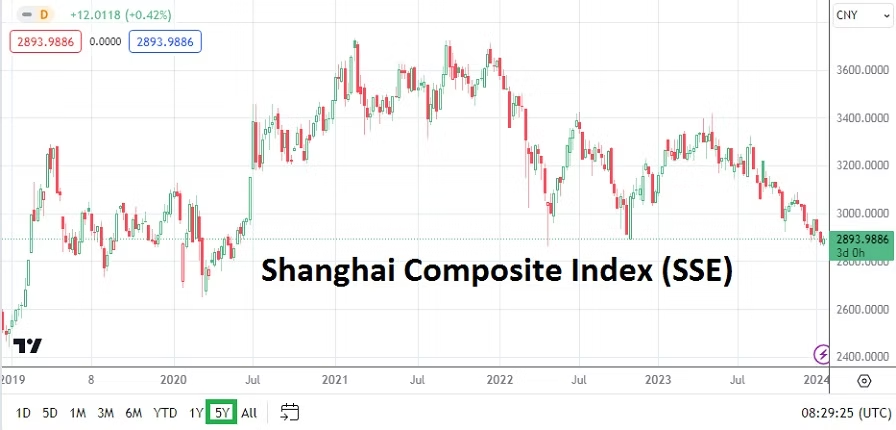
Shanghai Composite Index Five Year Chart as of 22nd January 2024

Risk assessment is always critical, it needs to be mentioned the Shanghai Composite Index is again facing severe selling pressure. This is a direct result of foreign investors losing faith in China’s economic policy and political maneuverings. The slump in Chinese equities is also hitting the Hang Seng Index in Hong Kong badly. Deflation is a legitimate fear in China. The dual consequences of a failing housing sector and crumbling equity values is harming Chinese citizens.

While the strong selloff in Chinese equities would have caused a massive amount of reaction in the global markets a few years ago, the ability to shift assets elsewhere by foreign investors who were active in China has likely reduced potential knock on effects in other global equity markets. It must also be pointed out that China continues to sit on a massive amount of USD holdings. China is a large investor in Africa and their attempt to steer influence there remains abundantly clear.

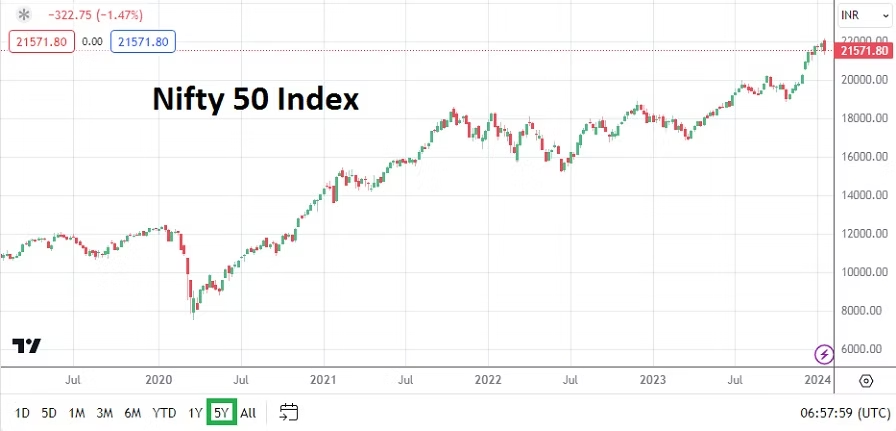
Nifty 50 Index Five Year Chart as of 22nd January 2024

India has directly benefited from the outflow of investments from China. A look at the Nifty 50 Index shows the upwards momentum India’s equity market has enjoyed as it has started to attract more direct foreign investment. The ability of the India stock market to go up while China struggles is a barometer worth studying. Outflow vs. inflow.

Monday, 22nd of January, U.S Conference Board’s Leading Index – the reading is not at the forefront of consideration for investors, they will be watching the results of U.S Treasury yields and stock indices more closely than this report.

Tuesday, 23rd of January, Bank of Japan Monetary Policy Statement and Outlook Report – no major change is expected from the BoJ quite yet. The USD/JPY has been volatile and provided a solid trend upwards since the start of January. Day traders looking for a reversal lower to develop should be extremely cautious. Data from Japan has been mixed and the BoJ is likely to remain conservative. The weaker JPY helps exports from Japan it must be remembered, but it also may factor into inflation creeping into the Japanese economy.
NZD/USD One Month Chart as of 22nd January 2024

Tuesday, 23rd of January, New Zealand Consumer Price Index – the inflation report is expecting a result of 0.5%, which would be below the previous result of 1.8%. The NZD/USD has taken a bearish dive since late December. Like all major currencies the New Zealand Dollar remains USD centric. Volatility in the NZD/USD may occur via the inflation numbers from New Zealand, but like the USD/JPY it may find its biggest impetus coming from afar – U.S data and the Federal Reserve outlook.

Wednesday, 24th of January, E.U and U.K Flash Manufacturing and Services PMI reports – Germany and France are anticipating slightly better Manufacturing Purchasing Managers’ Index numbers. Services numbers are expected to be slightly weaker from Germany. Solid results from these combined publications could help the EUR/USD create a bit of bullish momentum.

The U.K numbers via their Manufacturing PMI is expected to be slightly better than the previous outcome, but the Services number a bit worse. Economic data from Britain remains mixed to lackluster. Higher inflation numbers last week did the Bank of England no favors. The GBP/USD will be affected briefly by the results, but trading in the Forex pair is likely to remain geared towards thoughts about U.S data coming this Thursday and Friday.

Wednesday, 24th of January, Bank of Canada Rate Statement and Monetary Policy Report – the key lending rate from the BoC is expected to remain unchanged. However, Canadian economic numbers have been problematic, and while the BoC may want to wait for the U.S Federal Reserve to move first regarding interest rates, critics of the BoC are becoming louder. The USD/CAD will react to the Bank of Canada’s rhetoric, but unless there is a major surprise the currency pair will remain heavily USD centric.

Thursday, 25th of January, European Central Bank Main Refinancing Rate and Monetary Policy Statement – the ECB is expected to provide no major changes. The 4.50% interest rate is anticipated to stay in place. The ECB will likely ‘sound’ a calm tone and say while improvements are being seen in the E.U, that areas of difficulty remain but are understood and being managed.

Thursday, 25th of January, U.S Advance Gross Domestic Product – the key growth number from the U.S is anticipated to show a gain of 2.0%. This number will get a reaction in Forex, equities and bonds. The Federal Reserve’s FOMC meeting is next week and this GDP result will factor into their monetary policy rhetoric. Because it is an election year in the U.S, this number will also get an additional ‘sounding board’. Day traders should be careful before and after the noise caused by this growth report.

Friday, 26th of January, U.S Core Personal Consumption Expenditures – the vital inflation number carries an estimated gain of 0.2% before its release. As much as the Fed watches the GDP number, the inflation result via the Core PCE is a huge component of the U.S central bank’s thinking. The USD will react to this report and Forex traders should brace for a reaction from financial institutions. If the number is weaker than expected the USD could find selling momentum, if the number is stronger more USD strength could be seen. Folks looking at the GDP and Core PCE reports should also look for potential revisions to previous months results, which could cause another wave of volatility in the markets if they are significant.

postN98.1

Choppy Forex Conditions and the Trading Week Ahead

Choppy Forex Conditions and the Trading Week Ahead

Forex traders may be feeling a bit perplexed if they have blindly been looking for a weaker USD the past two weeks. While outlook for a bearish USD over the mid-term remains a theme from many analysts, day traders need to accept that intra-day results often create price fluctuations which make wagering on short and near-term perspectives dangerous. Trading conditions have been turbulent the past week and early this morning.

While analysis of monetary policies and economic data are vital, it is also important to remember there is a significant difference between the desires and needs of businesses functioning in global commerce, and the trading perspectives of speculators who are hoping to ride on the back of ‘insights’ provided by experts. It should also be considered that coming out of the holiday season many global corporations are now repositioning for 2024, and the financial institutions that work for these companies are also trying to get these outlooks aligned.

The USD has become stronger over the past day against many major currencies, but looking for a 100% reason to explain why this happened is likely misguided. Most U.S financial institutions were closed yesterday for the MLK holiday observance. While inflation data from the U.S Producer Price Index was weaker than anticipated last Friday and caused a brief spurt of USD bearishness, the greenback is lingering within the stronger realms of its near-term values against many currencies.

The idea that recent USD bullishness may simply be a sign that financial institutions believed the greenback had been oversold over the past couple of months may be correct, but this also opens the door for the potential of a reversal to develop and more USD selling as sentiment and economic data try to dance in a unified manner.

The week ahead may still prove to be choppy, but there are interesting bits of evidence that risk appetite lingers within the stomachs of many large investors. The slight rise in U.S Treasury yields recently may be worrying to some, but it should be acknowledged that the climb higher has been achieved while yields remain near mid-term lows. The same can be said for U.S equity indices which provided choppy conditions last week but certainly remain in highly valued realms.

Patience is a needed tool when trading, speculators looking for instantaneous results often lose money because they are being too aggressive. Risk taking tactics always have to be given importance.
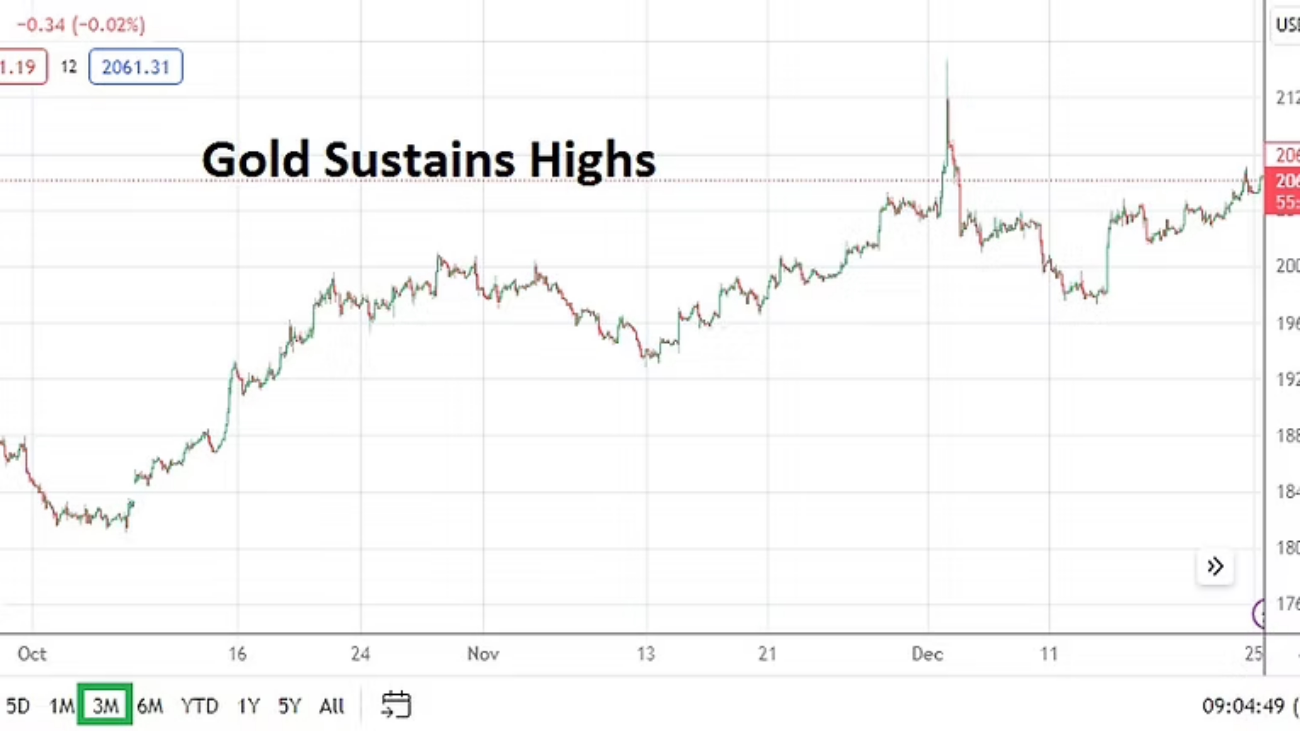
Gold Three Month Chart as of 16th January 2024

Gold remains rather comfortable above the 2000.00 USD level. As of this writing the spot price for the precious metal is near 2050.00 USD. This is fascinating because it underscores the notion that long-term gold buyers appear to believe the USD will remain within weaker territory. But again, short-term and mid-term outlooks for speculative wagers are two very different things.
Tuesday, 16th of January, Canada Consumer Price Index – the inflation numbers from the ‘North’ are expected to be lower than last month’s results.

Shanghai Composite Index Five Year Chart as of 16th January 2024

Wednesday, 17th of January, China Industrial Production and GDP – recent economic reports regarding the deflationary troubles the nation is facing have been loud. The industrial and growth numbers should be monitored. The Shanghai Composite Index (SSE) is trading near values last seen in May of 2020, this is not a good signal.

Wednesday, 17th of January, U.S Retail Sales – the consumer data will have an affect on sentiment in the broad markets. The results are anticipated to match the Core Retail Sales gains from last month, and the broad number is expected to be slightly higher. Traders should be alert in case a surprise outcome occurs. If the statistics are close to the estimates, this could create some calm in Forex and perhaps set the table for USD weakness to be seen for a moment.

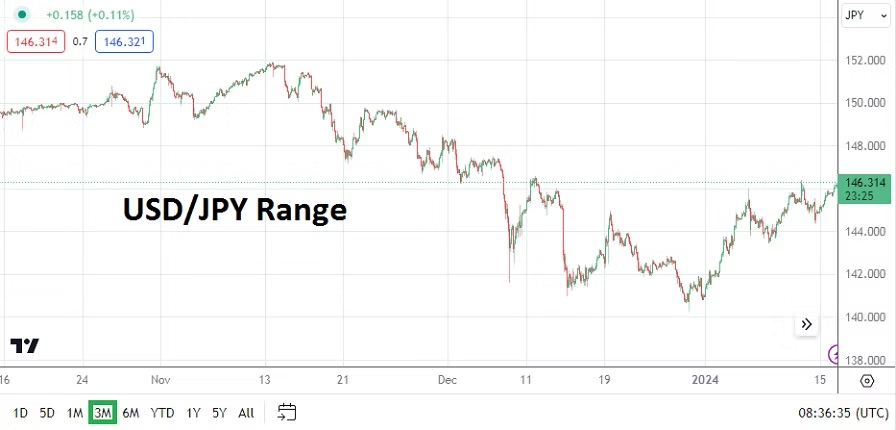
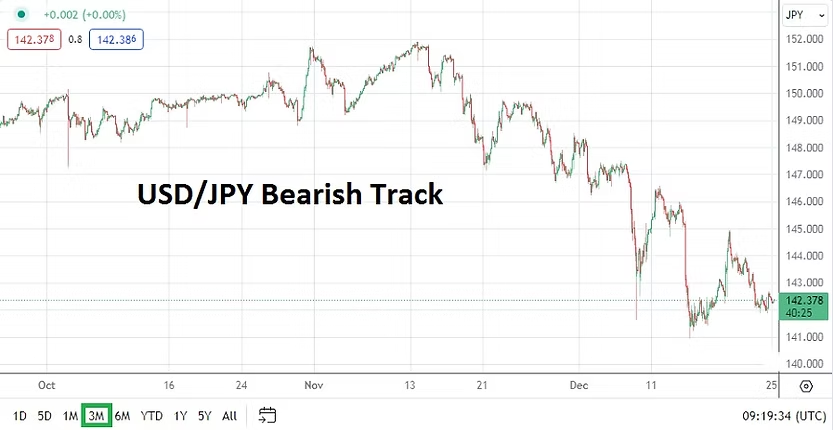
USD/JPY Three Month Chart as of 16th January 2024

Thursday, 18th of January, Japan Revised Industrial Production – while the report is not viewed as a major piece of financial impetus in the speculative world, the USD/JPY has been rather dangerous for short-term traders caught on the wrong side of recent bullishness. If the number comes in at minus -0.9% as expected, it will then likely take USD centric bearish sentiment to cause a reversal lower. The past two weeks in the USD/JPY have been difficult for traders looking for downside momentum. A stronger than expected industrial number from Japan would likely help USD/JPY bearish outlooks.

Friday, 19th of January, U.K Retail Sales – the British consumer spending numbers are expected to come in weaker. The GBP/USD is currently trading near early January values as choppy short-term conditions persists.

postN87

AMT Top Ten Miscellaneous Morsels for 5th of January 2024

AMT Top Ten Miscellaneous Morsels for 5th of January 2024

10. Book: Truth to Power – My Three Years Inside Eskom by Andre de Ruyter, an insider’s account about South Africa’s public energy company amidst corruption, mismanagement and scandal.

9. NBA: Last night’s Milwaukee and San Antonio game was the first ‘match’ of Giannis Antetokounmpo and Victor Wembanyama. Basketball is global and spectacular.

8. Noise: Clickbait media headlines about nervous results in financial markets this week have been exaggerated.

7. Horn of Africa: Ethiopia and Somalia are arguing about a port passage through ‘Somaliland’, astute eyes should be kept on the region and Egypt.

6. Diplomacy: U.S foreign policy has delivered poor statesmanship with India recently, allowing Russia to reinitiate its longstanding relationship with the nation.

5. Taiwan: Presidential election is on the 13th of January. President Tsai Ing-wen is not eligible to run again because she has now served two terms.

4. USD/JPY has ebbed higher and next week’s results promise to be rather insightful regarding the outlooks of financial institutions. Reversals coming?

3. China: Economic concerns in the Asian giant continue to mount as deflation threatens to become intractable and investors fret.

2. Data: U.S jobs numbers coming today, the results are anticipated to be slightly weaker. A reaction in the broad markets is certain, but it is full market volume next week which will set the tone.

1. Outlook: Anxious short-term trading results from the past two weeks are likely going to be confronted by optimism and risk appetite next week. Who will win?

postN94.1

Thin Holiday Markets Await FX Speculators

Thin Holiday Markets Await FX Speculators

Traders who want to pursue speculative positions this week need to understand that market conditions will be extremely thin. While the USD has certainly taken on a ‘softer’ dimension and financial institutions are demonstrating solid risk appetite, this week’s trading could produce lackluster choppy conditions.

Economic data will be light this week due to the ongoing Christmas celebrations, and the New Year’s holiday which will come next Monday. Forex markets can produce trading opportunities in the near-term for folks who want to wager on changes of direction, but some of the trajectories may be dubious and reversals could loom. Entry orders are urged for participants because spreads between bids and asks will likely be wide.

Gold Three Month Chart as of 26th December 2023

Gold remains within its higher price boundaries as the USD produces weakness, but betting on the precious metal this week could also be dangerous. Gold has certainly been trending upwards, but short-term speculative positions by large players could make the commodity agitated the next handful of days if they try to take advantage of light volumes. Day traders without significant bankrolls should be careful.

While economic data will be released, it is doubtful how much impact the reports will have on the broad markets. Active traders should monitor the coming statistics, but they should stay ‘more’ alert for possible outside influences which could shake confidence and shadow the rather optimistic behavioral sentiment which is currently being demonstrated.

News via international shipping should be given attention as the Houthis and Iran rattle their swords. While experienced traders will not be flustered by noise, the potential for escalating violence should be given attention.

USD/JPY Three Month Chart as of 26th December 2023

Tuesday, 26th of December, Japan Core CPI via the BoJ – inflation data from Japan has been published today and the Consumer Price Index came in below expectations. The USD/JPY remains on a downwards trajectory and should be given consideration.

Wednesday, 27th of December, U.S Richmond Manufacturing Index – this report being ‘highlighted’ shows the minimal amount of data being published this week. A decline versus the previous month’s negative outcome is expected. The likelihood that significant trading will be ignited via the results of this publication is almost nil.

Thursday, 28th of December, U.S Pending Home Sales – the data is expected to show a gain of 1.1%. However, it is next month’s report which will get more attention, this as investors look to see if the Fed’s soft monetary policy stance which was heard in mid-December, helps boost the housing market in the coming weeks. This immediate report however is likely to be met with a rather quiet reaction.

Friday, 29th of December, U.K Nationwide Home Price Index – this economic report like yesterday’s U.S housing numbers is destined to have little influence on short-term trading results. The GBP/USD will not be affected by this report in any great manner.