postR169.1

Forex Debate and Coming Impetus this Week for Speculators

Forex Debate and Coming Impetus this Week for Speculators

In many respects the broad markets feel as if they are waiting for big news and this may not be delivered as wanted. Yes, the debate between Biden and Trump this Thursday will get attention, but unless there is a major television moment the outcome is not likely going to give a final affirmation regarding the U.S election results in November. Some people may be counting on Biden to literally misstep, and for Trump to say something incredibly outlandish, but it is also possible the debate disappoints even as entertainment. Perhaps the Presidential debate will deliver sideways action like the broad markets have the past week, leaving us with a desire for more.

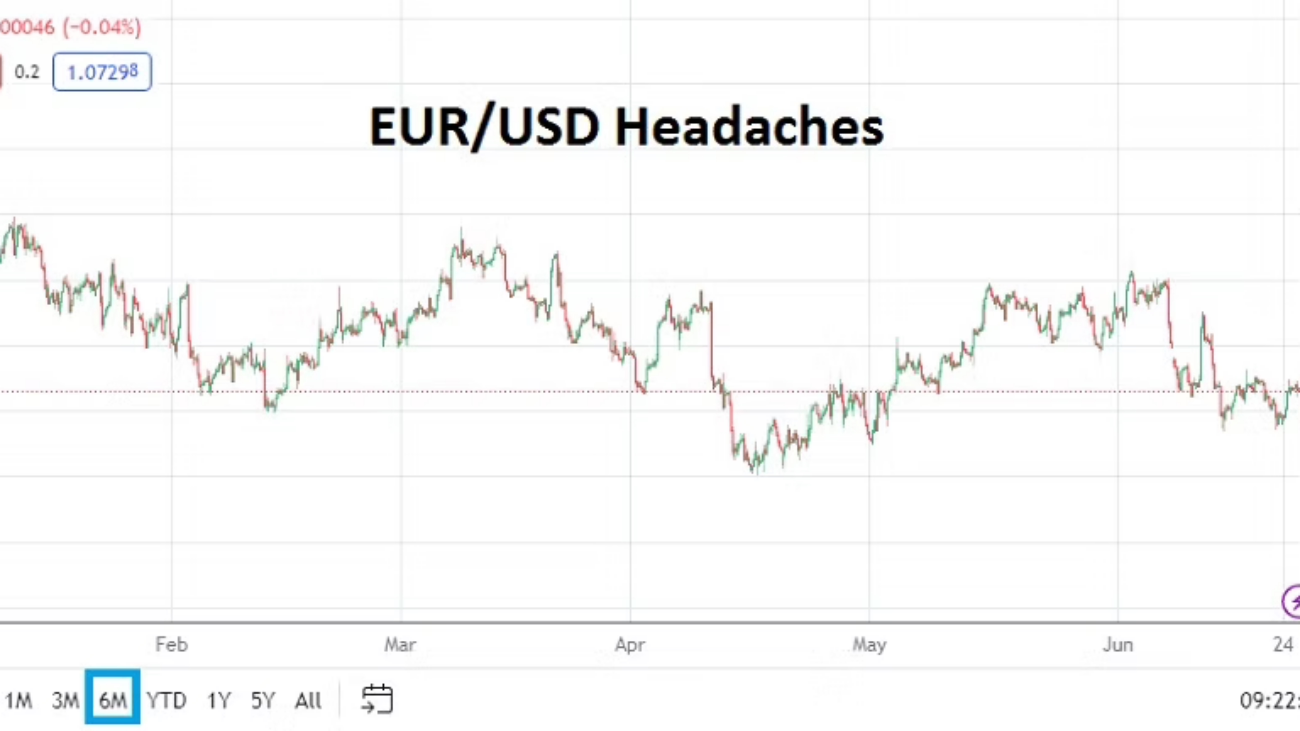
Financial institutions will look at U.S growth numbers this coming Thursday certainly, and also keep their eyes on the upcoming Sunday vote in France on the 30th which might prove rather remarkable. The EUR/USD is certainly back within its lower depths when a six month chart is inspected, and traders will react to France’s election this weekend, but it should be remembered the second and vital round of voting will not occur until the 7th of July. Until then, reactionary and precautionary results in the EUR/USD may produce headaches. The EUR does look oversold, but timeframes and the ability to hold a position may prove tough for short-term traders hoping for a wave of optimism to suddenly take hold and create a strong trend.
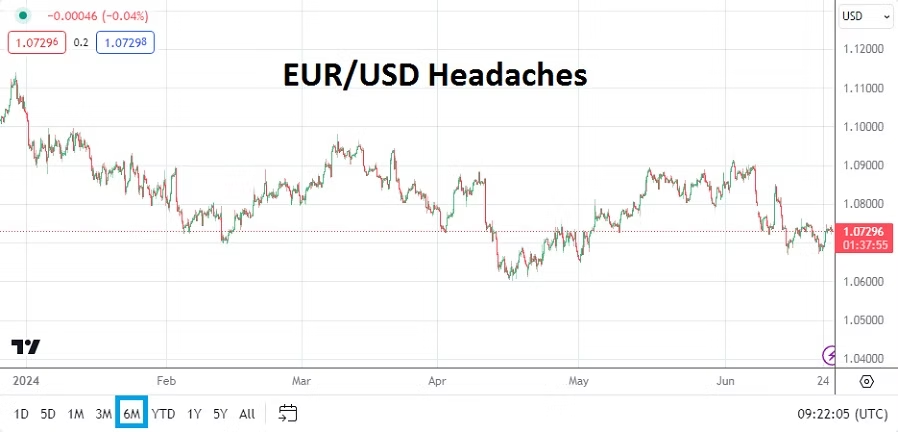
EUR/USD Six Month Chart on the 25th of June 2024

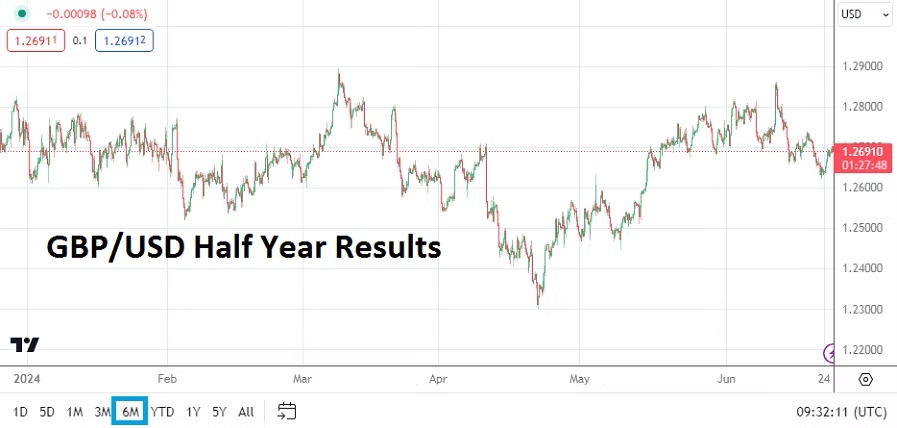
Not to be outdone the U.K is gaining plenty of attention because of its election on the 4th of July, but in this case it seems more like a coronation for the Labour Party and only a question about how devastating the carnage will be for the Tories. Financial institutions may have already factored in their perceived outlooks regarding the U.K vote into the GBP/USD. The currency pair will certainly react to the British election results, but financial institutions may have less to fear regarding sudden volatility of the British Pound, compared to the EUR/USD which could still have days ahead when it doesn’t trade in a USD correlated manner due to E.U political unknowns.
Monday, 24th of June, Germany Ifo Business Climate – the reading produced a drop to 88.6, missing the estimate of 89.4. Germany economic pressures remain negative and this may keep the idea alive that the ECB should be considering another interest rate cut. However, because the European Central Bank cut its Main Refinancing Rate recently and the U.S Fed continues to look rather neutral, it seems unlikely the ECB will decide to suddenly become the only proactive central bank around over the mid-term. Meaning, the ECB may stay conservative and want to wait on others to join the interest rate cut party, this before they create more unbalanced carry trade opportunities which could lower the value of the EUR/USD too much.

Tuesday, 25th of June, U.S CB Consumer Confidence – the reading will certainly be watched by investors, but will it create bedlam if there is surprise for equities or Forex? The likely answer is no. Behavioral sentiment has become flustered and shifted over the past handful of months, and this will create some caution no matter what today’s consumer reading says. Large financial institutions will probably stay geared to other upcoming data which will be considered more important.

Wednesday, 26th of June, U.S New Home Sales – a slight uptick in the amount of housing sales is expected. However, because of higher interest rates in the U.S via the cost of mortgages this number is likely to remain rather muted. For interested traders a look at the previous revisions of the New Home Sales data will prove interesting. The outcome of this reading should be treated with a bit of skepticism because it may be changed down the road. Unless there is a huge surprise the impact of this report may be rather calm, no matter what media narrative dictates.

Thursday, 27th of June, U.K Bank of England Governor – Andrew Bailey will speak about the Financial Stability Report. Bailey is certain to add some insights regarding the BoE’s neutral policy stance taken last week regarding interest rates, but more hints regarding potential cuts later this summer and possibly late this year again may be given. Economic data from the U.K remains troubling. The Bank of England may want to remain cautious because of inflation concerns, but financial institutions would like to see a more proactive dovish stance. Bailey might also talk about the potential affects from the U.K election, but he will have to be careful to make sure it doesn’t sound like he is taking a political side.

Thursday, 27th of June, U.S Gross Domestic Product and GDP Price Index – these two reports will impact the financial markets. The growth and inflation data will be examined by all financial institutions and generate trading reactions. The GDP growth number is expected to come at 1.4%, which is slightly higher than the previous report which posted a 1.3% result. Any number below 2.0% growth will be considered as lackluster by most financial analysts. Traders will then turn their attention to the inflation results which are supposed to match the 3.0% gain from the last Price Index report. If this number can somehow come in below expectations, this could propel some weakness in the USD. However, traders should be careful and remember U.S economic data the past handful of months has produced surprises which have created dangerous and choppy Forex conditions.
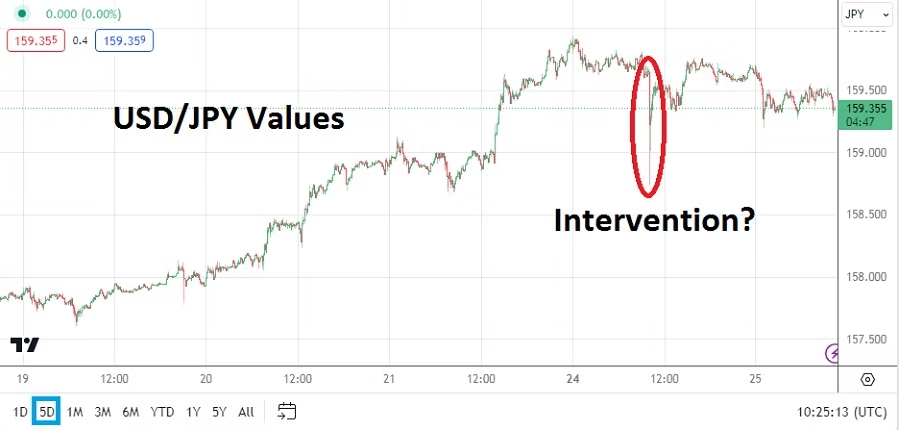
USD/JPY Five Day Chart on the 25th of June 2024

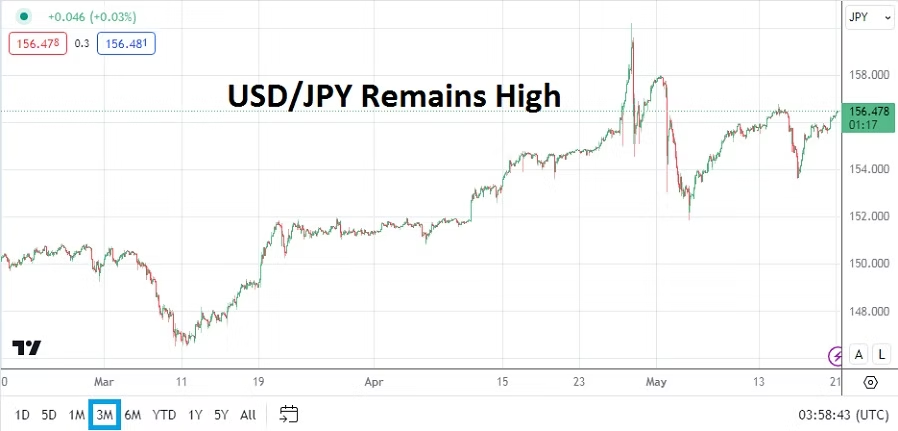
Friday, 28th of June, Japan Tokyo Core CPI – a gain of 2.0% is anticipated. The USD/JPY should be watched carefully. Early this Monday the BoJ likely tried an intervention in the Japanese Yen, but the USD/JPY only had a momentary swift selloff. As of this writing (Tuesday the 25th of June) the USD/JPY is trading near the 159.345 ratio which is very high when historical comparisons are considered. If the inflation number comes in with a 2.0% result or higher this could set off fireworks in the USD/JPY. Financial institutions clearly believe the BoJ should raise their interest rate by at least 0.25%, but the Japanese government appears keen on trying to keep the Japanese Yen weak to help GDP via exports from the nation. The Bank of Japan needs to be given attention. Speculators and the BoJ are battling against each other.

Friday, 28th of June, U.S Core PCE Price Index – the Personal Consumer Expenditures inflation report is forecasted to produce a gain of only 0.1% compared to the previous result of 0.2%. If the PCE Price Index does turn in the anticipated result, and the GDP Price Index from Thursday met expectations or came in lower, this could cause more speculative selling of the USD. However, if the inflation results come in stronger than expected Forex traders could see bullish USD buying which again challenges sellers abruptly.
postR196

AMT Top Ten Miscellaneous Complexities for the 14th of June

AMT Top Ten Miscellaneous Complexities for the 14th of June

10. International Tech Research: Universities and institutions around the world are developing innovative systems to deliver a quantum future. Cal-Berkeley, MIT, Cambridge, the Barcelona Supercomputing Center, the Institut Polytechnique de Paris, and the Cleveland Clinic are only a few of the places in the ‘West’ that investors should monitor for developments, Asia is also very focused on high speed computing.

9. Musk Schedule: The tech mogul has had a busy week. His Tesla stock option compensation package was approved by shareholders yesterday. In 2018 Musk negotiated a package with Tesla that included a massive compensation agreement via stock options if he met valuation targets over a 10 year period. He achieved the valuation goals within only a few years. Musk also formally dropped his lawsuit against OpenAI and Sam Altman in recent days, this after the enterprise released emails showing Musk backed OpenAI’s pursuit of profits in the past. Around 2015 Musk invested about 45 million USD into OpenAI.

8. Muted Data: The U.S Consumer Sentiment and Inflation Expectations numbers will be released today via the University of Michigan. However these numbers are likely not going to impact financial assets in the U.S. The Fed and CPI results from the States published this past Wednesday will dominate the investing narrative. Searching for meaning regarding why assets move in a particular direction is the media’s job, but perceived realities always remain open to complex interpretations as real time prices are exhibited. Day traders need to be cautious of revisionist history.

7. Petrol Dollar: Saudi Arabia has not reconfirmed its commitment to transact Crude Oil exports with USD. The formal agreement reached in 1974 has expired. Forex traders should not panic about this development yet. Speculators should note that Saudi Arabia is likely to still demand most of their payments in USD since they can count on the valuation of the currency to remain relatively tranquil compared to other instruments like China’s Yuan. What the absence of an agreement between the U.S and Saudi Arabia does indicate unfortunately, is that U.S foreign policy continues to look vulnerable.

6. Optimism: A South Africa government coalition agreement could be formalized soon and create a better economic outlook for the nation. While geo-political concerns remain, and the ANC is not a 100% friendly philosophical match with the Democratic Alliance and some of the other political parties which will be involved, it appears a working agreement can be reached. The question in South Africa is if transparent fiscal and anti-corruption mandates can be accomplished while diverse political outlooks will be heard and demanded from different factions. For the moment, financial institutions seem to like what they are hearing and the USD/ZAR has edged lower in the past week.

5. Highly Valued: Gold is over 2300.00, BTC/USD is near 67,000, and Cocoa is within sight of 11,000. Speculative large players remain active, and traders looking to take advantage of short and near-term fluctuations in these commodities need to remain vigilant. Cocoa, while extremely dangerous to trade, has outperformed gold and Bitcoin recently. Investors in gold think long-term, and Bitcoin influencers preach ‘hold on for dear life’ as non-believers shake their heads in disagreement. However, daily gyrations influenced by large players can still wreck havoc on those looking for short-term wagering opportunities.

4. Zombie Fed: Cautiously optimistic undertones were served from Jerome Powell as expected this past Wednesday, but intriguingly Powell admitted some government data remains open for interpretation, particularly the suspiciously strong headline jobs numbers which are being questioned. The Fed now says its outlook is for one interest rate cut this year. Financial institutions likely believe the Fed remains too reactive. The U.S GDP has shown signs of struggling, and CPI numbers have begun to erode. Crude Oil prices remain under 80.00 USD. However, the Fed seems intent on still pumping the brakes in order to kill off inflation via the high Federal Funds Rate. It would help if the U.S govt stopped spending cash recklessly, and the U.S Treasury stopped printing money.

3. Equities: U.S political concerns as the election approaches will create more analysis paralysis than normal. Short-term behavioral sentiment may sound nervous, but a bullish trend and risk appetite remain evident. Day traders may be able to take advantage of technical trading via support and resistance in CFDs, but fundamentally financial institutions appear inclined to count on equity indices achieving record highs.

2. 157.000 – 158.000: Today’s BoJ decision to remain stuck in the mud has created more financial institutional dismay in some quarters, and the the Japanese Yen will be punished occasionally against the USD. But the folks at the BoJ are not stupid and likely anticipated the USD/JPY move higher which ensued. The BoJ is obviously preserving its ‘soft devaluation’ of the JPY in order to maintain an export advantage for the U.S and European consumer markets. The question is if and when the BoJ will buy billions worth of JPY in order to punish bullish USD/JPY Forex speculators occasionally.

1. Volatile Near-Term: EUR/USD and GBP/USD price action has been boiling. France and the U.K have crucial elections in the coming weeks, after policies in both nations have led to a lack of confidence in the ruling governments. The ruckus outcome from the E.U Parliament voting have created an intriguing complication. Oddly enough, the U.K may be the left’s torch bearer in the coming year, while other European nations drift towards the right. Can centrists create a middle ground? Volatility and the search for equilibrium via financial institutions may create a lot of opportunities for Forex day traders in the coming weeks in the EUR/USD and GBP/USD as reversals and trends are sought.

postR196

AMT Top Ten Miscellaneous Politicos for the 7th of June 2024

AMT Top Ten Miscellaneous Politicos for the 7th of June 2024

10. Three P’s: Pragmatic and populist politicians are clashing in a world that seeks to try and sell utopian visions from all sides, instead of admitting realities that should be understood and defined, thus creating a more dangerous world. It would be funny if it weren’t so serious.

9. Investment: Pasqal, a quantum tech company located in France founded in 2019, and IBM have announced a collaboration to integrate efforts on creating quantum centric supercomputing architecture. The quest for fully functioning applications appears to be years away as theories such as neutral atoms are studied and applied, and cooling systems are pressed to their limits. However, a transition into working research continues to build momentum. Accelerated investment paths for those seeking the quantum golden goose are flourishing.

8. Three C’s: Cocoa, Coffee and Copper are creating speculative storms for traders as volatility has seen apex values, then dramatic drops, followed by violent reversals higher in the commodities. Cocoa is back above 10,100 USD per metric ton as of this writing, and Coffee Arabica and Copper have been delivering huge profits and staggering losses for large players and day traders who continue to wager.

7. India: Narendra Modi has retained power after a hard fought voting outcome has diminished some of his power. However, fears that turned the Nifty 50 index sharply lower earlier this week, also created a market discount for long-term investors. Foreign investors continue to have a positive economic outlook for the nation. It will not be a surprise to see the Nifty 50 back to pre-election levels and challenging record highs soon, yet again delivering a lesson for day traders who are speculating on the short-term instead of being patient.

6. South Africa: Coalition government discussions are ongoing and will grow in noise in the coming days as a deadline to conclude an agreement approaches. The ANC is said to be talking seriously with the Democratic Alliance, but the Congress of South African Trade Unions which is strongly aligned with the ANC is against the move. It has recently been reported that South Africa’s ports are among the least dependable in the world by the Container Port Performance Index. Poor infrastructure, corruption and a lack of transparency are hurting South Africa. The ANC decision in the coming week regarding a coalition is vitally important. Either it will decide to make concessions and bring the DA in as a working government partner and hopefully build a bridge towards a better South Africa, or the ANC will decide on a hard-left coalition which could potentially bring it to a Venezuela or Zimbabwe type of outcome. The USD/ZAR will react.

5. Conservatives: The U.K election is less than one month a way, and Labour appears set to take power and control Parliament with a large majority. The failure of the Tories to create the perception of successful economic, foreign, and social polices that resonated with the public, appears to be easing the way for a ruling Labour government which has not been seen since since 2010.

4. Carry Trade: The EUR/USD will become an interesting test ground for carry trade fundamentals in the coming weeks and months. The ECB cut its Main Refinancing Rate as anticipated yesterday by 0.25%, but said it is neutral about more cuts. The ECB explained it was able to cut interest rates yesterday, because current inflation levels have dropped enough that a modification of interest rates was needed, but that it remains cautious about inflation in the future. This statement and policy could potentially allow for the Federal Reserve to become the more dovish central bank over the mid-term and lead to a stronger EUR/USD. How much will financial institutions wager on this notion in the near-term?

3. USD/JPY: Serenity now should be the new mantra for the BoJ. The Bank of Japan seems to be waiting on the Fed to sound more dovish, which could stop the need for the BoJ to intervene again. The USD/JPY remains high and is currently testing the 155.000 to 156.000 range in a fairly steady manner. The Bank of Japan will release its Monetary Policy Statement on the 14th of June. While Forex tranquility has been demonstrated the past couple of days, conditions may change rapidly later today and day traders should brace for price velocity.

2. U.S Indices: Equity values have recovered in the Nasdaq and S&P indices, and while the Dow 30 is below apex highs it is still within sight of the 40,000 level touched on the 20th of May. Treasury yields have traded slightly lower this week which has ignited risk appetite again. Gold is trading below the 2,400.00 USD ratio, but still comfortably above 2,300.00 for the moment. If Treasury yields continue to experience a downturn, institutional investors are likely to funnel cash into the stock market.

1. Data: U.S jobs numbers via the Non-Farm Employment Change and Average Hourly Earnings figures will be published today. The result will certainly set the path for the Federal Reserve’s June 12th FOMC meeting. Yesterday’s weekly Unemployment Claims came in weaker (more claims filed) than expected and other jobs data was weaker the past few days via JOLTS and the ADP statistics. All financial assets will react to the U.S data today. Weaker jobs numbers would create more confidence among institutional investors that the Fed will have to sound dovish rhetoric regarding potential cuts to the Federal Funds Rate in the coming months. Fast trading conditions are coming today.

postR196

AMT Top Ten Miscellaneous Blossoms for the 31st of May 2024

AMT Top Ten Miscellaneous Blossoms for the 31st of May 2024

10. European Supremacy: The NBA Championship between Boston and Dallas is set to begin on the 6th of June. If the Dallas Mavericks win, it will mean Giannis Antetokounmpo in 2021, Nikola Jokic in 2023, and Luka Doncic in 2024 were victors, and are cementing the terrain as the best players.

9. Brisk Breeze: The need for ‘chill’ among AI and server companies isn’t only about attitude. The advent of quantum computing will add to the wintry demands. Vertiv, Asia Vital Components, and Auras Technology are a few of the enterprises in the industrial environment sector helping deliver precision cooling for the technologies to work efficiently.

8. Glitches: Stalled data within the S&P 500 and Dow Jones 30 for their index calculations took place yesterday for nearly one hour, but individual trading within companies via stock prices appears to have been unaffected. Futures trading for the two indices weren’t affected. On Monday the 18th of March, Nasdaq suffered a tech problem that stopped pre-market trading for a couple of hours.

7. OPEC: The cartel will conduct a one day online meeting this coming Sunday. Production levels will be discussed, among other issues. The price of WTI Crude Oil as of this writing is below 78.00 USD per barrel. While news remains stuck in hyperbole from the Middle East, the price of Crude Oil has declined since the first week of April.

6. Conviction: Donald Trump was found guilty in a NYC courtroom yesterday, but the verdict is certain to be appealed. The law of unintended consequences could come into play from the U.S as reactions generate. The perceived notion that ineffectual and non-credible leadership is mounting in the U.S, lends credence to some people around the globe regarding dwindling American exceptionalism.

5. Results: South Africa voting counts will be finalized sometime this weekend, India’s election count will be known on the 4th of June. The unknown outcomes are affecting the USD/ZAR and USD/INR, and more volatility in the currency pairs should be expected early next week.

4. Coincident: GDP results came in around their expectations yesterday. Growth numbers produced a gain of 1.3%, while the GDP Price Index showed a 3.0% climb. The data produced does show the U.S economy is slowing and is another ripple to be considered by analysts and traders.

3. USD/JPY: The Bank of Japan appears to be betting on weaker U.S data to continue, and potential dovish Fed rhetoric on the 12th of June to propel the USD/JPY lower, thus helping the BoJ to remain on the sideline and avoid an intervention for the moment. The BoJ will release their Policy Rate decision on the 14th of June and many eyes will be on the central bank’s Monetary Policy Statement.

2. Inflation: The Core PCE Price Index report outcome today is anticipated to be around the 0.3% ratio. The Federal Reserve pays plenty of attention to this publication and if the number meets the expectation or comes in below it, this could cause a repeat of the Fed’s dovish December 2023 FOMC Statement. Financial institutions have already begun wagering that the Federal Funds Rate could be cut this summer and later again this year. Many assets will react to today’s inflation report.

1. Behavioral Sentiment: Nervous price action has been seen in the equity indices and Forex this week. Investors may have felt they got a little ahead of their risk appetite curve and now appear to be waiting on more solid impetus to reconfirm their outlooks. Choppy price action has certainly been fueled by U.S Treasury yields which increased earlier this week. Losses in the S&P 500, Dow 30 and Nasdaq the past handful of days are now waiting for buyers to reemerge. The question day traders may want to consider is if financial institutions and large investors believe assets will cost less next week, or if prices have now hit worthwhile support levels which will spur on buying today?

postR196

AMT Top Ten Miscellaneous Tastings for the 10th of May 2024

AMT Top Ten Miscellaneous Tastings for the 10th of May 2024

10. Word of the day: Ultracrepidarian is a person who speaks assertively about subjects that are beyond their level of knowledge. The world is full of many suspects ladies and gentlemen.

9. Steve Albini: The musician and production sound engineer passed away earlier this week in Chicago. Albini was a pioneer and leader in ‘alternative’ music and battled homogenized corporate music for nearly 40 years. Nirvana, Fugazi, Jimmy Page, the Pixies, P.J Harvey are some of the many that worked with Albini.

8. Bitcoin: BTC/USD continues to hover around the 63,000.00 realm per a three month technical chart perspective. Bitcoin’s higher values via one year results are being maintained. BNB/USD is lurking near 600.00 per a three month glance.

7. Commodities: Cocoa and Coffee prices remain elevated. After touching a low around the 7,250.00 USD mark last week per metric ton, Cocoa is now within sight of 9,000.00 USD again. Retail speculators who like to wager via CFDs on commodities need to remember their bets have no influence on the markets, which are in complete control by the largest players in the commodities sector.

6. Wayve Technologies: A U.K based company specializing in autonomous driving software has announced they have raised more than 1 billion USD in investments recently via the likes of Softbank, Nvidia and Microsoft. The U.K government has highlighted Wayve, proclaiming it shows Britain will be a major force in AI development. Wayve was established in 2017 and is still a privately held company.

5. U.S Foreign Policy: Election concerns appear to be a prime motivator for the U.S executive branch as its attempts to walk a fine line regarding diplomacy and saber-rattling in the Middle East. Polling from a variety of sources indicate Joe Biden is in jeopardy of not being reelected.

4. USD/CNY: China will release its Consumer Price Index and Producer Price Index numbers early on Saturday. The USD/CNY is trading around the 7.2245 mark as of this writing. Some analysts have expressed concerns about the China Yuan weakening via attempts by the Chinese government to boost exports. The USD/CNY certainly remains within the higher elements of its range, but is below marks seen in early September 2023 which were around the 7.3425 ratio.

3. Data Warning: While day traders may be inclined to look at the University of Michigan’s Consumer Sentiment reading today, they should remember to pay attention to the Inflation Expectations statistics. Last month’s inflation report produced a result of 3.2%, which delivered a solid dose of volatility to financial assets.
2. Forex: Behavioral sentiment appears to be leaning towards a weaker outlook for the USD as major currencies like the EUR, GBP (solid GDP numbers also helped this morning in Britain) and others have gained. However, its should be pointed out that the USD/JPY has seen an incremental climb since touching a low of nearly 151.880 last Friday. As of this writing the USD/JPY is around the 155.650 level.

1. Equity Indices: Bullish optimism has been seen in the S&P 500, Dow 30 and Nasdaq as all three major indices are ready to start the day near highs for the week. The burst of upwards momentum which started last Thursday, has ignited the major U.S indices within sight of their apex realms achieved in late March and early April.

postR196

AMT Top Ten Miscellaneous Fragments for the 24th of May 2024

AMT Top Ten Miscellaneous Fragments for the 24th of May 2024

10. IP vs. AI: OpenAI has agreed to pay News Corp., the mass media company, for the rights to ‘farm’ data and written content from publications like the Wall Street Journal and other notable brands. OpenAI will compensate the media giant around 250 million USD over the next five years. Question, does this legally imply that all Artificial Intelligence companies will eventually have to pay for ‘scraping’ Intellectual Property from all resources they take information?

9. Memorial Day: The U.S will observe its commemoration for fallen soldiers this coming Monday. The long holiday weekend will affect financial markets later today with lighter than normal trading, and volumes will be very thin in Forex and many commodities early next week.

8. India: The 6th phase of India’s national election will be held tomorrow. The 7th and final polling date is the 1st of June. There are murmurs that Prime Minister Narendra Modi’s Bharatiya Janata Party is losing some ground and will not be able to attain a super majority in the Lok Sabha.

7. Moment of Lunacy: The United Nations observed a moment of silence for Iran’s deceased President and Foreign Minister who died earlier this week in a helicopter crash, while failing to mention the majority of citizens in Iran who live unwillingly under the Iranian Islamic Republic’s oppression.

6. 29th of May: The South Africa election will be held next Wednesday. After governing the nation since 1994, the African National Congress appears to have a fight on its hands to sustain power without having to use a coalition. Dangers abound regarding potential political alliances which might have to be formed. The USD/ZAR will certainly endure volatility in the days ahead, and geopolitical influences should be monitored in the weeks to come. Can a tranquil compromise be attained?

5. FOMC Meeting Minutes: Wednesday’s publication of the Federal Reserve’s decision making process rumpled some feathers in financial institutions regarding the central bank’s laser focus on inflation. However, traders should not have been surprised. While the outlook for the Federal Funds Rate has seemingly shifted within financial institutions to hopes of a more dovish policy, equity indices and Forex will continue to amplify a battle between short and mid-term speculative and investment positions that gyrate on power generated from fundamental economic reports and technical perspectives.

4. Gold: The precious metal is near 2,340.00 USD as of this writing, this after attaining an all-time record value around $2,450.00 per ounce this past Monday. Risk appetite is certainly high in the financial markets. Day traders need to understand large speculative forces can move commodities and other assets with lightning speed when big volumes and changes to behavioral sentiment collide.

3. Data and the G7: Today’s Consumer Sentiment and Inflation Expectations readings should be watched from the University of Michigan. Weaker than anticipated results could solidify a bearish trend for the USD. However, traders should also keep in mind the G7 meetings taking place as they monitor global events, they should also remember to eliminate the hyperbole that may come from some politicians today and tomorrow in Italy as pronouncements come from the conference.

2. U.S Debt Burden: As the U.S election draws closer, investors are likely to hear more about the growing U.S debt which is certainly increasing too rapidly. 34 trillion USD in public debt is owed by the U.S government. It is a monumental number and growing larger on a daily basis. The U.S must start to get its fiscal house in order. The ratio of 124.7% of U.S debt to Gross Domestic Product is eye catching, it is still less than many major countries but still troubling. Japan’s ratio is about 263%. However, the U.K’s ratio is less and standing at 85.4%.

1. Devaluation: USD/JPY as of this writing is hovering near 157.000. There has been talk among financial institutions regarding the belief that China is quietly devaluing the USD/CNY to gain an advantage in export ability. But little mention has been made of Japan’s devaluation of the Japanese Yen to accomplish the same goal. The USD/JPY remains in remarkably high territory and the currency pair needs to be treated carefully by day traders as the Bank of Japan maneuvers policy to accomplish economic goals.

postR162.1

USD Weakness: Wagers on Fed Outlook as Risk Appetite Surges

USD Weakness: Wagers on Fed Outlook as Risk Appetite Surges

Yesterday’s start for the week was slightly subdued as many nations in Europe enjoyed a long holiday weekend. In Forex the past few weeks the USD has taken on a weaker stance and this was reiterated by last Wednesday’s slightly lower U.S Consumer Price Index results. The outlook of investors and financial institutions has once again shifted and a more dovish U.S Federal Reserve is being anticipated for the moment.

However, while inflation data from the U.S did come in with lower marks via the CPI report last week, it should be remembered the PPI actually came in higher. While there is a natural instinct to always be optimistic, the prudent fact is that risk management remains important. A glance into the looking glass via the USD/JPY shows that all is not calm in the world of Forex.

USD/JPY Three Month Chart on the 21st of May 2024

While many currencies have gained against the USD since late April, the price action in the USD/JPY represents anxiety regarding central bank policies from the Bank of Japan and Federal Reserve. The USD/JPY since experiencing two interventions from the BoJ has incrementally climbed again – meaning the Japanese Yen remains weak, this while other major currencies like the GBP and EUR have gained against the USD. Yesterday’s Tertiary Industrial Activity data from Japan came in negative, showing strains exist within the Japanese economy which underlies why the Bank of Japan may be staying cautious. The ability of the USD/JPY to not trade in a correlated manner to global Forex is proving difficult for some day traders. Volatility within the USD/JPY is not finished.

USD/ZAR 1 Year Chart on the 21st of May 2024

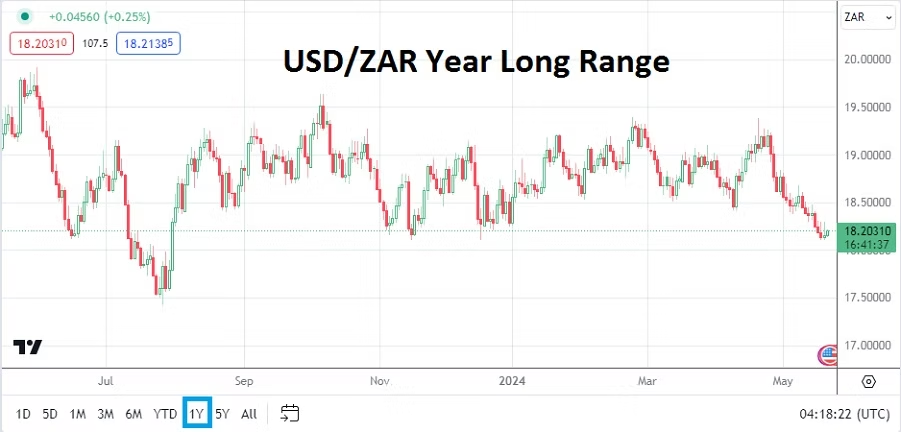
However, if people want to look at the knock-on positive influence of the weaker USD, they can glance at the USD/ZAR which is near important mid-term lows. South Africa will be conducting their national election next week on the 29th of May, which is likely to cause some nervousness for the currency pair. Even though South Africa continues to suffer from a struggling economy caused by questionable government policy and faltering infrastructure, the USD/ZAR is experiencing solid bearish behavior. However, risks certainly remain for the South African Rand and at its current values, some financial institutions may view the currency pair suspiciously.

Gold Six Month Chart on the 21st of May

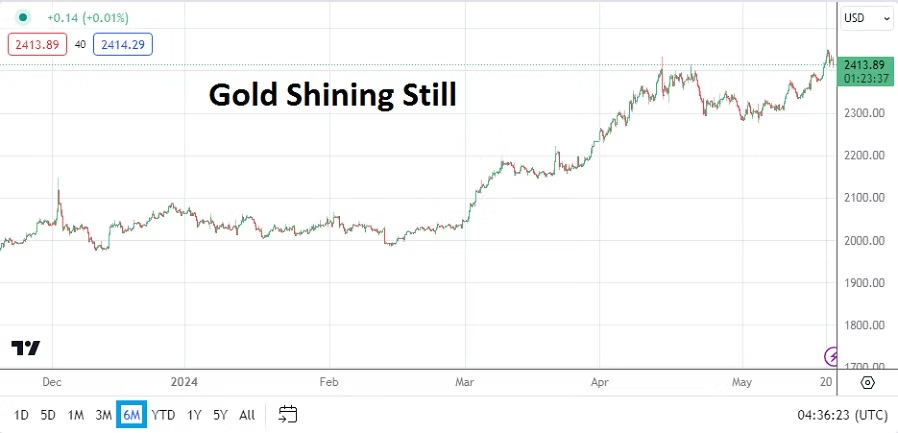
Gold remains within sight of record values achieved yesterday when the 2,440.00 USD plus levels were touched. The shift in behavioral sentiment towards risk appetite and a weaker USD centric attitude seemingly geared towards dovish Fed mid-term perspectives have helped the precious metal. Day traders should remain cautious with Gold and while the technical trend is enticing, it will be good to remember too much leverage coupled with blind betting can be dangerous. A clear warning sign that speculative zeal is high in Gold is that the current price of the commodity is 30.00 USD lower for the moment compared to yesterday’s highs. Price velocity can prove costly when a daily reversals goes against wished upon directions.

U.S equity indices and their ability to fight toward new highs is a clear sign risk appetite via outlooks within financial institutions and from investors remain strong. U.S Treasury yields should be monitored and if they continue to erode this will fuel optimism. One additional note for traders this coming week is that Memorial Day will be observed in the U.S next Monday, meaning there may be more impetus for some to buy U.S equity indices now instead of waiting out a long holiday weekend and coming back to markets which have gained. Yes, Fear of Missing Out could be a factor.

USD/CNY Three Month Chart on the 21st of May 2024

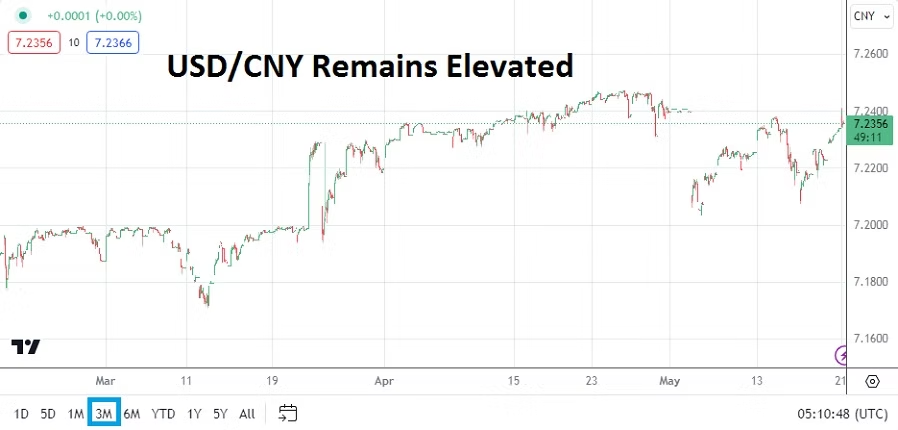
Monday, 20th of May, China Loan Rates – while banks kept their 1 and 5 year Prime Rates in place per the reports yesterday. Last Friday’s Retail Sales figures came in weaker than anticipated, and New Home Prices produced another decline. Industrial Production numbers were however stronger than expected before going into last weekend. China remains in a difficult position economically and the USD/CNY should remain observed because it is elevated.

Tuesday, 21st of May, Canada Consumer Price Index – inflation numbers from Canada will be watched carefully. The results will impact the USD/CAD certainly, but unless there is a surprise result which misses estimates wildly, the currency pair should return to a USD centric mode rather quickly.

Wednesday, 22nd of May, U.S Federal Reserve FOMC Meeting Minutes – while this report is not read by many people, and the Federal Reserve will have taken a cautious rhetorical tone, the report may offer some tidbits for consideration. However, the reality is that U.S economic data has been a mess for the past few months. GDP showed signs of decreasing last month, but the multi trillion dollar question is if inflation is now under control. Folks looking for answers will not find them in the Fed notes. They will have to wait like everyone else for more data in the weeks and months to come.

Thursday, 23rd of May, European Flash Manufacturing and Services PMI – the Purchasing Managers Index reports from European Union members and the U.K are anticipated to show signs of some improvement mostly. The U.S will also be publishing its reports, although the Services report from the States is expected to be slightly weaker. Investors will react to all of this data. Positive readings from E.U and U.K would likely have a positive influence on the EUR/USD and GBP/USD for bullish speculators.

Friday, 24th of May, U.K Retail Sales – consumer spending is anticipated to show a decline. However, the last Gross Domestic Product report from the U.K was stronger than anticipated. While the Retail Sales data is important for the GBP/USD, as long as the outcome meets expectations or comes in slightly stronger than estimated the currency pair could retain technical value.

Friday, 24th of May, U.S Revised Consumer Sentiment and Inflation Expectations – the University of Michigan numbers for sentiment came in weaker than expected last month. The anticipated outcome is slightly better for this report. However, the inflation numbers should be watched carefully via the U. of Michigan statistics. The tick higher in recent reports regarding where prices are expected to go by consumers is troubling for the prospects of the U.S economy.

If American consumers are not confident they will spend less. Yet, within the strange world of economic data and policy consisting of lagging and forward looking numbers, if consumers feel less optimistic this means the U.S Federal Reserve will be pushed to consider cutting the Federal Funds Rate, unless inflation actually does remain elevated. And again, traders should remember that a long U.S holiday weekend might add to the rather electric financial markets.

postR161.1

Market Trading Risks: Speculative, Anxious Impatient Results

Market Trading Risks: Speculative, Anxious Impatient Results

Monday’s trading provided a solid oversight for day traders to observe market conditions in commodities, Forex and equities. Financial institutions appear to be leaning towards a belief the U.S Federal Reserve will have to become more dovish, but financial institutions and other large players are worried about shadows being caused by inflation concerns and timeframes which are likely sparking nervous wagers.

Via the commodities, results saw Gold come down from highs on Friday which approached the 2,380.00 USD perch, and drop to lows around 2333.00 yesterday. The precious metal remains within sight of record values, this as questions persist about USD direction, and speculative forces bet. WTI Crude Oil meanwhile climbed from a selloff late Friday and into yesterday’s opening while challenging the 77.75 USD vicinity, and as of early Tuesday is now over the 79.00 mark again.

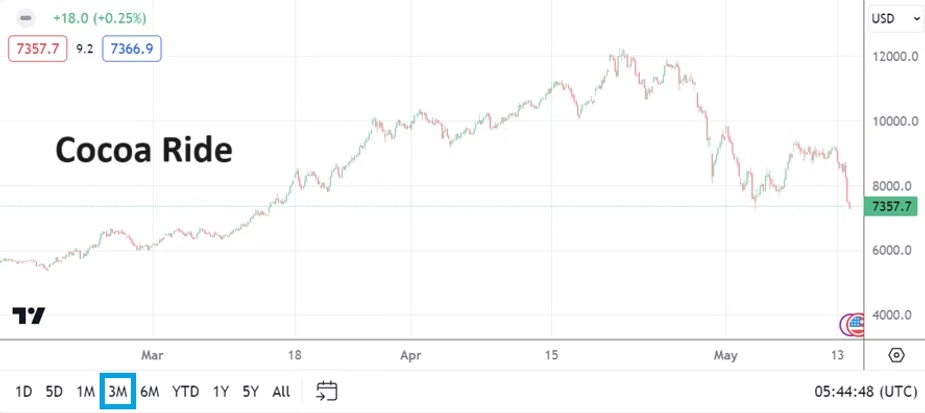
Also within the volatile world of commodities it needs to be mentioned that Cocoa which regained a portion of its higher price values last week and finished Friday above 9,000.0 USD per metric ton, fell swiftly in yesterday’s trading session and is now traversing 7,357.0 USD. Cocoa has enjoyed a spectacularly wide ride of maneuvering via market forces. The commodity is still valued within loftier heights when compared to its historical averages, and demonstrates the speed and danger (and opportunity) of price velocity.

Cocoa Three Month Chart on the 14th of May 2024

Further signs of risk appetite and fragile notions are being exhibited via U.S equity indices, which produced sideways price action yesterday as important economic data awaits and will certainly churn short-term and mid-term perspectives. The S&P 500 is again within sight of record levels, while investors of it and the Dow Jones 30 and Nasdaq 100 all brace for this week’s data which will affect their risk outlooks.

S&P 500 Index Three Month Chart on the 14th of May 2024

Monday, 13th of May, New Zealand Inflation Expectations – yesterday’s quarterly result came in slightly below the previous report. The decrease of inflation concerns likely helped the NZD/USD spark Monday’s climb above 0.60300 briefly. This morning’s early trading is seeing sideways action as U.S inflation reports are anticipated and the currency pair ebbs around 0.60180.

GBP/USD Three Month Chart on the 14th of May 2024

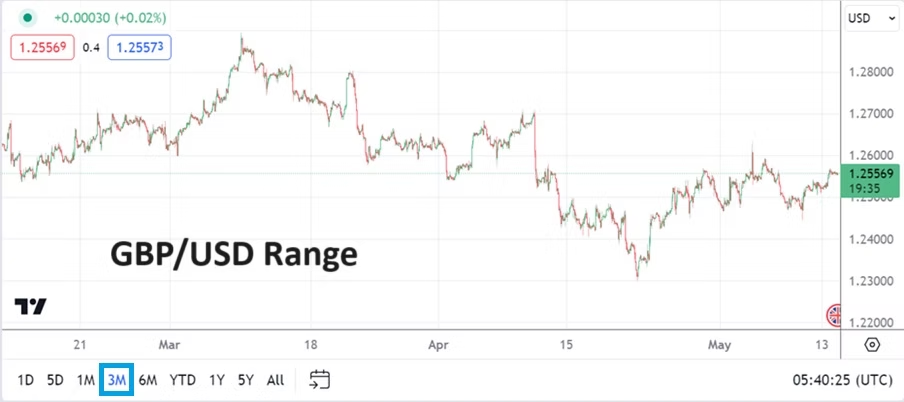
Tuesday, 14th of May, U.K Average Earnings Index, a gain of 5.7% has just been posted. This result will make GBP/USD traders nervous because it highlights that inflation remains sticky in Britain. While last week’s GDP numbers from the U.K showed an improvement, the growth certainly was not spectacular. The range of the GBP/USD remains choppy and bullish day traders targeting higher ratios on the belief the currency pair remains in oversold territory need to consider their timeframes and bias. While the 1.26000 may look like a logical target, it will take weaker U.S inflation and USD centric price action to get there.

Tuesday, 14th of May, U.S Core Producer Price Index – last month’s core report matched expectations. However, the PPI numbers occasionally spell trouble in Forex. Higher inflation results from the U.S would certainly kickstart volatility for all major currency pairs today.

Wednesday, 15th of May, U.S Consumer Price Index – this reading could prove to be the prime mover for financial assets this week because of its potential affect on behavioral sentiment. The Federal Reserve watches this number because of the influence it has on the American public. Forex will react to this report and if it is weaker than anticipated this would create weaker USD centric price action. The U.S will also report Retail Sales and the Empire State Manufacturing Index statistics on Wednesday.

USD/JPY Three Month Chart on the 14th of May 2024

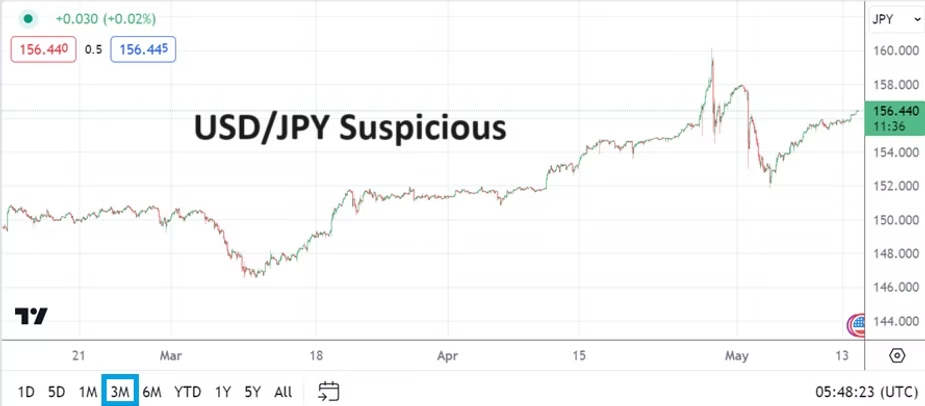
Thursday, 16th of May, Japan Preliminary Gross Domestic Product – last month’s report came in with a gain of 0.1%. This GDP data carries an expectation of minus -0.4%. Traders who like fundamentals should pay attention to revisions within the statistical pages. The Bank of Japan remains in a curious and suspicious predicament. After two interventions, the USD/JPY has climbed incrementally once again. The BoJ is certainly keeping their eyes on the USD/JPY and know financial institutions are still wagering against the Japanese Yen.

Day traders should be extremely cautious with the USD/JPY because the BoJ has the ability to strike with a massive blow when not expected. Risk management is essential for speculators wagering on this currency pair. Evidence of speculative interest in the USD/JPY correlates to the notion that while the USD has been weaker against many major currencies recently, the Japanese Yen remains within a weaker and elevated price range.

Friday, 17th of May, China Industrial Production and Retail Sales – economic dark clouds continue to cascade on Asia’s largest economy. The industrial numbers will be watched by investors certainly, but the overall health of Chinese consumers will likely be the focal point. The USD/CNY remains within bullish terrain, but the Shanghai Stock Exchange’s SSE Index has done well since its lows in the first week of February.
post204

AMT Top Ten Miscellaneous Tastings for the 10th of May 2024

AMT Top Ten Miscellaneous Tastings for the 10th of May 2024

10. Word of the day: Ultracrepidarian is a person who speaks assertively about subjects that are beyond their level of knowledge. The world is full of many suspects ladies and gentlemen.

9. Steve Albini: The musician and production sound engineer passed away earlier this week in Chicago. Albini was a pioneer and leader in ‘alternative’ music and battled homogenized corporate music for nearly 40 years. Nirvana, Fugazi, Jimmy Page, the Pixies, P.J Harvey are some of the many that worked with Albini.

8. Bitcoin: BTC/USD continues to hover around the 63,000.00 realm per a three month technical chart perspective. Bitcoin’s higher values via one year results are being maintained. BNB/USD is lurking near 600.00 per a three month glance.

7. Commodities: Cocoa and Coffee prices remain elevated. After touching a low around the 7,250.00 USD mark last week per metric ton, Cocoa is now within sight of 9,000.00 USD again. Retail speculators who like to wager via CFDs on commodities need to remember their bets have no influence on the markets, which are in complete control by the largest players in the commodities sector.

6. Wayve Technologies: A U.K based company specializing in autonomous driving software has announced they have raised more than 1 billion USD in investments recently via the likes of Softbank, Nvidia and Microsoft. The U.K government has highlighted Wayve, proclaiming it shows Britain will be a major force in AI development. Wayve was established in 2017 and is still a privately held company.

5. U.S Foreign Policy: Election concerns appear to be a prime motivator for the U.S executive branch as its attempts to walk a fine line regarding diplomacy and saber-rattling in the Middle East. Polling from a variety of sources indicate Joe Biden is in jeopardy of not being reelected.

4. USD/CNY: China will release its Consumer Price Index and Producer Price Index numbers early on Saturday. The USD/CNY is trading around the 7.2245 mark as of this writing. Some analysts have expressed concerns about the China Yuan weakening via attempts by the Chinese government to boost exports. The USD/CNY certainly remains within the higher elements of its range, but is below marks seen in early September 2023 which were around the 7.3425 ratio.

3. Data Warning: While day traders may be inclined to look at the University of Michigan’s Consumer Sentiment reading today, they should remember to pay attention to the Inflation Expectations statistics. Last month’s inflation report produced a result of 3.2%, which delivered a solid dose of volatility to financial assets.

2. Forex: Behavioral sentiment appears to be leaning towards a weaker outlook for the USD as major currencies like the EUR, GBP (solid GDP numbers also helped this morning in Britain) and others have gained. However, its should be pointed out that the USD/JPY has seen an incremental climb since touching a low of nearly 151.880 last Friday. As of this writing the USD/JPY is around the 155.650 level.

1. Equity Indices: Bullish optimism has been seen in the S&P 500, Dow 30 and Nasdaq as all three major indices are ready to start the day near highs for the week. The burst of upwards momentum which started last Thursday, has ignited the major U.S indices within sight of their apex realms achieved in late March and early April.

postR160.1

Forex: Shifting Winds and Potential Optimism for Speculators

Forex: Shifting Winds and Potential Optimism for Speculators

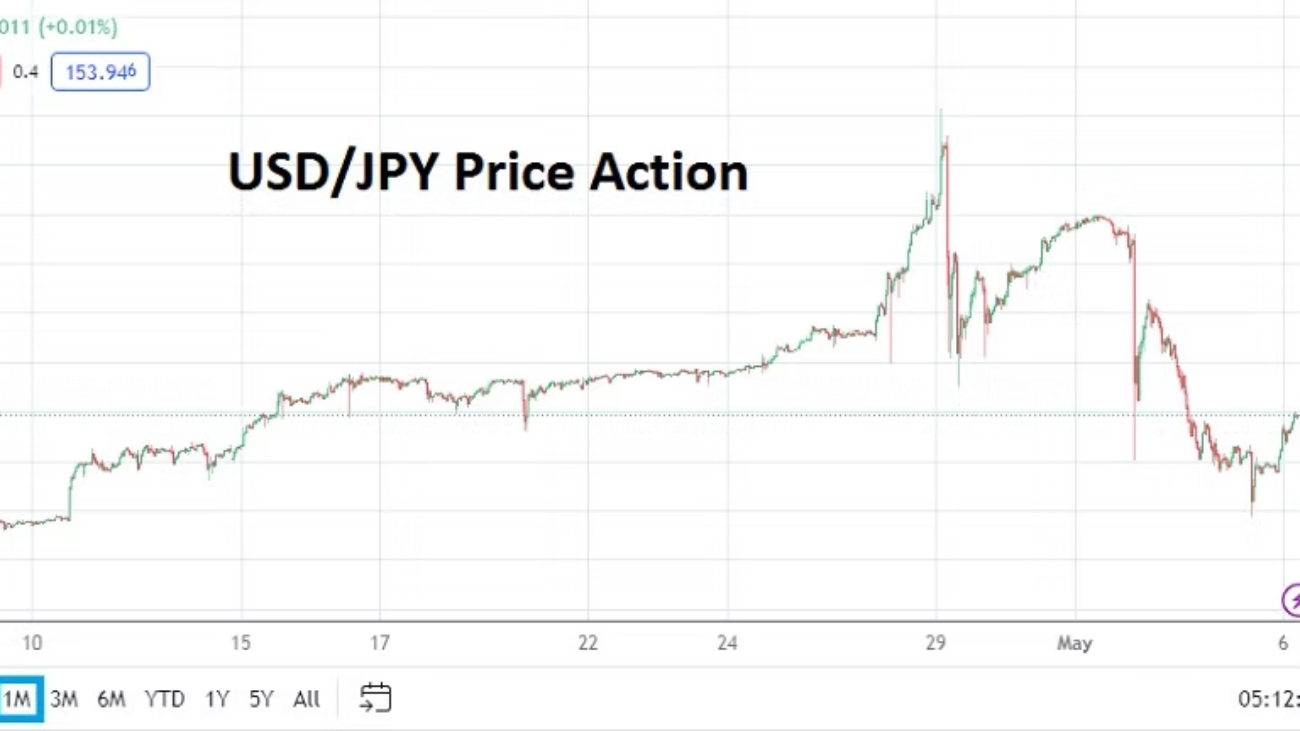
The BoJ intervened in Forex and propelled two fast selloffs of the USD/JPY last week. The actions by the Bank of Japan did not come as a surprise as the central bank seeks to maintain a dovish interest rate policy, a relatively weak Japanese Yen – but also a philosophy of not letting the JPY to suffer too much. Speculators and financial institutions got caught up in the price action which ensued as a clash developed between large traders and the BoJ as equilibrium was sought.

The BoJ clearly wants to keep the USD/JPY within the weaker realms of its long-term values to spur on the Japanese export sector with solid business results. However, domestically the Japanese government doesn’t want inflation within Japan to inflict too much pain for its citizens. BoJ interventions were carried out twice last week, once during a holiday in Japan, and the second when most global financial institutions were shuttered. At the time of this writing the USD/JPY is trading near the 153.720 mark.

Day traders always need to understand just how small they are within the larger speculative world. They need to judge economic intelligence and forecasts to get an understanding where behavioral sentiment could affect tides.

USD/JPY One Month Chart on 6th of May 2024

In the U.S, inflation and growth data caused investors to react nervously a week and a a half ago, additionally more anxious moments were fueled by the Federal Reserve’s FOMC Statement this past Wednesday when the Fed said it was uncertain about the timetable that inflation would return to their stated goal of two percent. Forex trading has been volatile the entire calendar year of 2024 for speculators.

Nearly ten days ago while inflation continued to prove it was stubborn via the U.S GDP Price Index on the 25th of April, Advance GDP data was much weaker than expected showing that economic growth was slowing. And last Friday’s Non-Farm Employment results were not only weaker regarding hiring, but also showed a slight drop in Average Hourly Earnings. This might have been enough to begin causing a shift in financial institution outlooks. This week of trading will prove interesting regarding risk appetite versus risk averse sentiment, particularly if large players believe economic data is finally catching up to the Fed’s rhetoric.

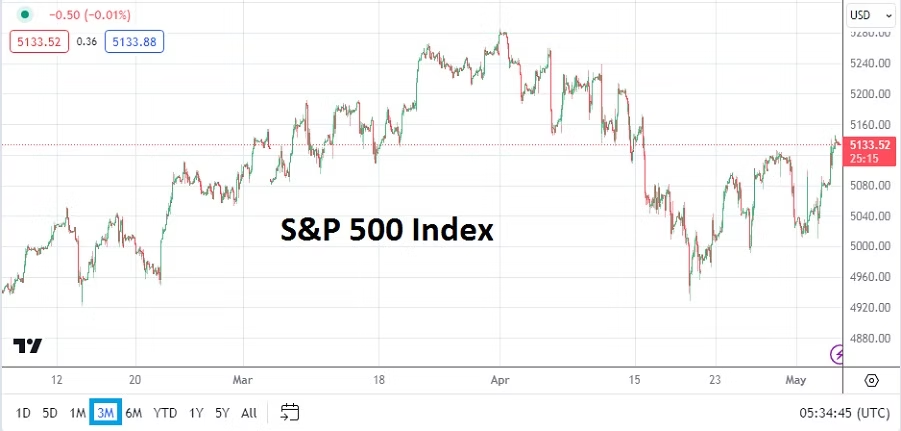
U.S equity indices which started last week with selling and battled lower depths in the middle of the week, began to see buying develop on Thursday, and finished Friday’s trading within their highs via weekly technical charts. While it is easy to report the past, it is the future speculators want to know. The ability of the U.S jobs numbers to produce results which were seen in a favorable light regarding the Fed’s ability to potentially cut the Federal Funds Rate certainly was an optimistic sign for financial institutions. If inflation can remain under control it would help the global economic picture. On that note, WTI Crude Oil is trading below 80.00 USD and should be monitored.

S&P 500 Index Three Month Chart on 6th of May 2024.

Monday, 6th of May, European Union Final Services PMI – Italy, France and Germany among other will present Purchasing Managers Index data. The broad numbers are mostly expected to replicate the previous month’s outcomes. Traders should note the U.K is observing a banking holiday today, which means lighter than normal Forex volumes will be seen.

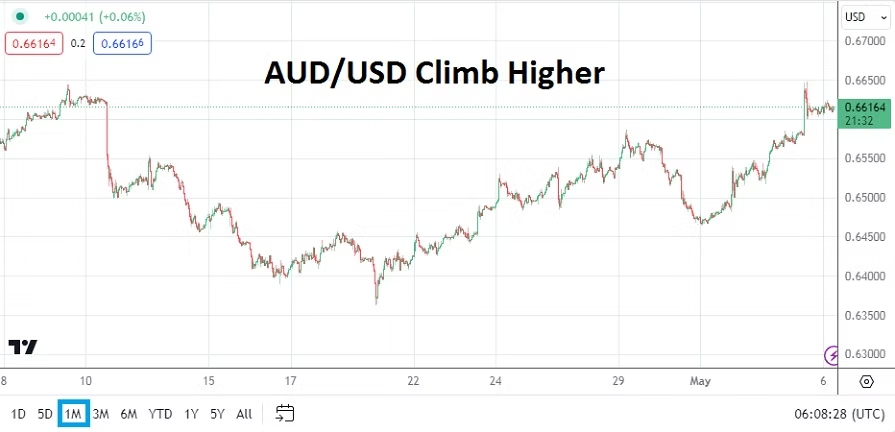
Tuesday, 7th of May, Reserve Bank of Australia Monetary Policy Statement – the central bank is not expected to change its interest rate. The AUD/USD has provided some upwards momentum the past week. The RBA is not expected to step out of line regarding global central bank policies. Expect talk about an optimistically cautious outlook by the RBA as they preach patience regarding an interest rate cut.

AUD/USD One Month Chart on 6th of May 2024

Wednesday, 8th of May, Bond Sales from Japan, the U.K and the U.S – while many European nations observe a holiday, Japan, Great Britain and the U.S will sell government debt. U.S Treasury yields should be watched and equity indices should have an eye kept on them. If behavioral sentiment remains optimistic as this day comes to a close it could set the table for more bullishness, particularly if the USD remains relatively tame or weaker.

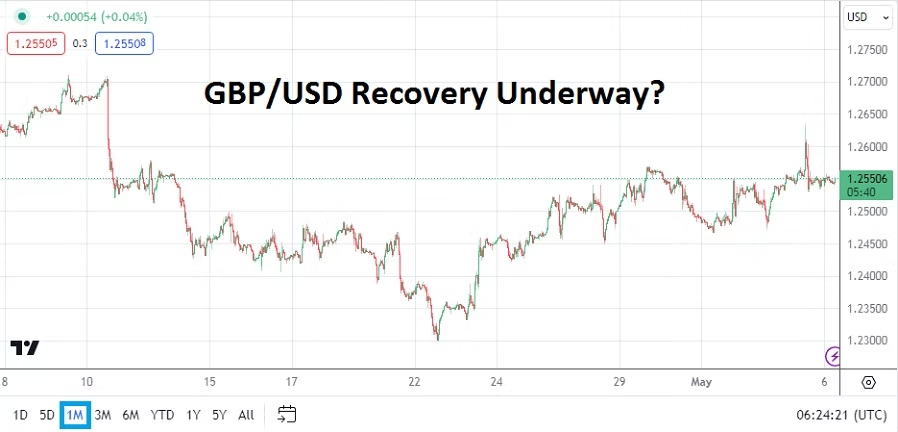
Thursday, 9th of May, Bank of England Monetary Policy Summary – the BoE is likely to mirror other central banks and keep its interest rate policy in place. No changes are expected to the Official Bank Rate. However, it would not be surprising to hear the BoE try to pose upbeat expectations, and if this occurs perhaps the GBP/USD will continue to find some momentum upwards.

GBP/USD One Month Chart on 6th of May 2024

Thursday, 9th of May, U.S Weekly Unemployment Claims – investors will keep their eyes on the jobs report. If the numbers come in around expectations this would allow risk appetite to remain strong in the near-term.

Friday, 10th of May, U.K Gross Domestic Product – an expected gain of 0.1% is forecast. GBP/USD traders who have bullish sentiment will be looking for the number to match expectations or beat the anticipated result. If the number is weaker, this could cause a reversal lower in the GBP/USD and an attempt to push back against gains made in the currency pair recently.

Friday, 10th of May, U.S Consumer Sentiment and Inflation Expectations via the University of Michigan – these readings will be watched by investors to see if consumers continue to show decreasing confidence in the U.S economy. While it sounds counter intuitive to want eroding sentiment regarding the ability to spend money, this would create more ammunition for the Federal Reserve to consider an interest rate cut. The Inflation Expectations could be the catalyst for traders going into the weekend regarding the USD.

post203

AMT Top Ten Miscellaneous Observations for 3rd of May 2024

AMT Top Ten Miscellaneous Observations for 3rd of May 2024

10. Formula One: The Miami Grand Prix race will be held on Sunday. Whispers have been heard that Red Bull driver Max Verstappen has been approached by Mercedes bidding an annual contract over 150 million USD, but that he has not accepted the offer. However, Adrian Newey, engineer and CTO of Red Bull Racing, has confirmed he is leaving the team after 19 years of leadership. F1 certainly needs more competitive racing, a shake up at Red Bull could deliver this for the sport.

9. De-movements: Desire for decolonization, decarbonization, depopulation, turned into delusion and dehydration for Columbia University protestors and the need for a glass of water per the request of a student leader. Perhaps de-escalation is next.

8. Geopolitics: The nation of Georgia is dealing with demonstrations as some citizens show disdain regarding feared political influence from Russia. Georgia has an approximate population of 3.7 million. The East European and West Asian country has seen civil disobedience on the streets of Tbilisi increase this week.

7. Lower Values: Cocoa is near 7,658.00 USD per metric ton as of this morning, on the 19th of April it traded above 12,000.00 briefly. BTC/USD is around 59,250 after having faced headwinds this week.

6. Gold: The precious metal has sold off this week and is hovering near 2,300.00 per ounce as concerns build about USD outlook remaining strong over the mid-term. A low of nearly 2,282.00 was seen on Wednesday. Today’s publication of U.S economic data will push the price of Gold around.

5. Mixed Trading: Equity indices have produced uneven results this week as investors try to find equilibrium. Optimism almost always is the eventual emotion long-term institutional market participants lean towards. The S&P 500, Dow 30, and Nasdaq Composite all gained yesterday, but remain below highs from earlier in the week. Behavioral sentiment appears fragile and many Fed observers are disgruntled.

4. Uncertainty: The Federal Reserve has admitted it is unsure about future economic progress this calendar year. When questioned about the potential of stagflation Fed Chairman Jerome Powell said he see no signs of this – while forgetting to add that politically saying such a thing would likely cost him his job. And lets remember, the Fed claimed they thought inflation was transitory in July of 2021.

3. Bank of Japan: A battle is underway with the USD/JPY as the BoJ has staged two interventions this week. Intent on trying to create economic growth via stronger exports, while allowing import inflation to be seen, the BoJ interest rate policy remains dovish. The USD/JPY is near 153.230 now, but it is unlikely to go into the weekend with this price. An apex on the 29th of April approached the 159.610 ratio. Financial institutions and Japanese Yen traders must remain alert.

2. High Anxiety: Day traders in Forex, equity indices and commodities have certainly seen heightened volatility and the choppiness is going to persist. Retail brokers will welcome speculators with open arms and point to opportunities, but traders need to understand the ‘casino’ often is making money via losses incurred because of leveraged wagers which turn into losing bets when price velocity hits.

1. Jobs Data: Yet another opportunity for inflation to be seen today via the Average Hourly Earnings numbers. A cautionary road sign was seen this Tuesday when the U.S Employment Cost Index came in with a stronger than anticipated quarterly gain of 1.2%. The USD will remain a lynchpin in many financial assets, and Treasury yields should be watched after the employment statistics have been printed.

postN1

BoJ and Fed are today’s Forex Bogeymen, and Job Numbers Lurk

BoJ and Fed are today's Forex Bogeymen, and Job Numbers Lurk

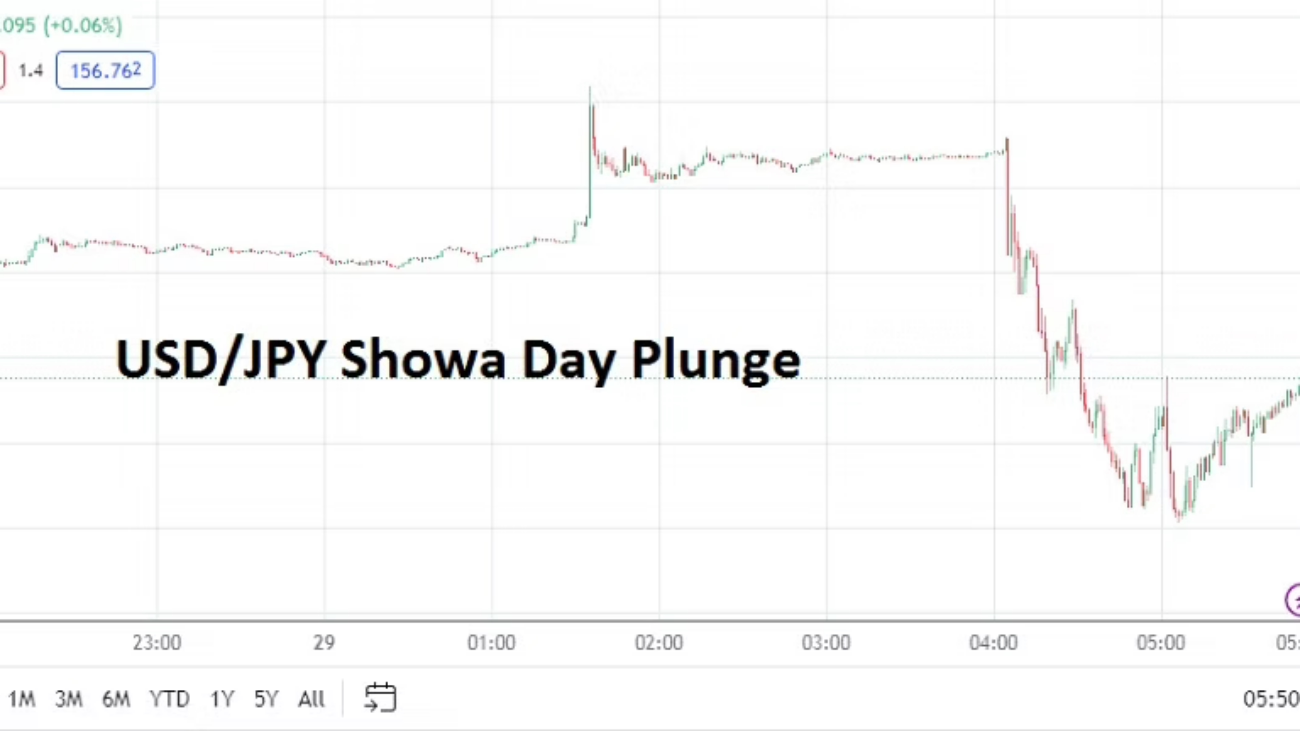
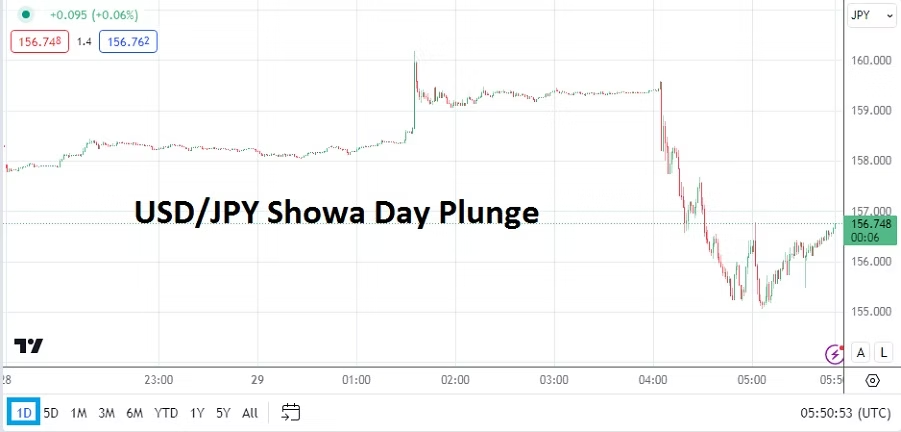
While the Showa holiday is being observed in Japan, the BoJ has apparently reacted with an intervention after seeing the USD/JPY race to new highs in the wake of the central bank’s decision to hold its Policy Rate at 0.10% on Friday. If in fact the Bank of Japan has acted when most Japanese financial institutions are celebrating a long holiday weekend, the reaction to the intervention will be noteworthy when Japanese currency traders return to their desks tomorrow. The question obviously becomes whether large players in the JPY will continue to wager against the Bank of Japan’s current monetary policy or if the apparent intervention will make them cautious.

USD/JPY One Day Chart as of 29th April 2024

U.S data this past Thursday turned in rather clumsy statistics starting with the Advance Gross Domestic Product growth results which showed the American economy is slowing. However, the GDP Price Index came in slightly higher than anticipated. This caused some tremors in Forex. Friday was followed by additionally troublesome readings when the University of Michigan’s Consumer Sentiment outcome was weaker than expected, but the U of M Inflation Expectations gauge was higher than the previous month’s report.

USD Cash Index Five Day Chart as of 29th April 2024

The USD began to show signs of weakness in many major currency pairs last week. Perhaps the expectation that the worst of Federal Reserve outlook has now been absorbed is playing into the Forex results. However, the past four months of trading have produced a continuous choppy wagering landscape for speculators and clarity still does not exist.

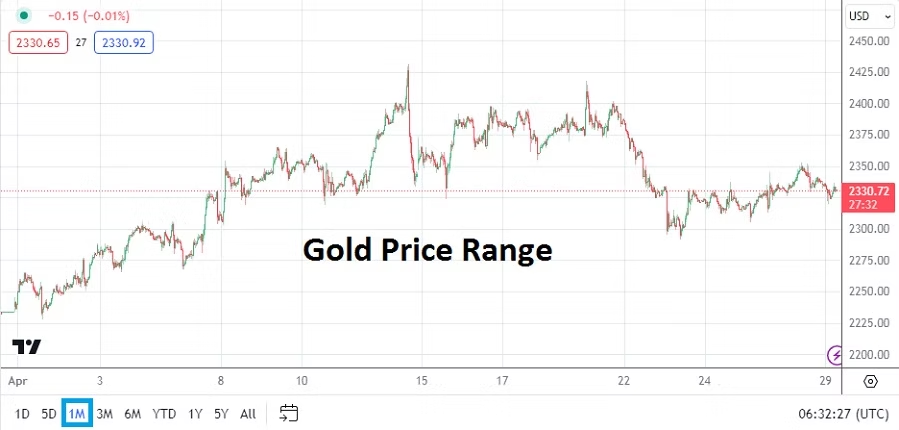
Gold One Month Chart as of 29th April 2024

Suspicion of the Bank of Japan’s intervention this morning and the creeping shadow from the U.S Federal Reserve which is scheduled to deliver their FOMC Statement this Wednesday have created trading bogeymen in many financial assets. The strains in the major equity indices, Treasuries and Forex are prime examples. While day traders try to find fair market value technically and financial institutions seek equilibrium, most observers likely have nervous behavioral sentiment as they consider mid-term prospects. The past month of speculative trading in Gold has produced record highs, but ran into resistance the past week as questions arise about USD inverse correlations not being technically efficient recently.

Monday, 29th April, Germany – Consumer Price Index – the inflation results from Germany should be given attention. The number will certainly affect sentiment surrounding the ECB and the EUR/USD, however the report should not cause an earthquake.

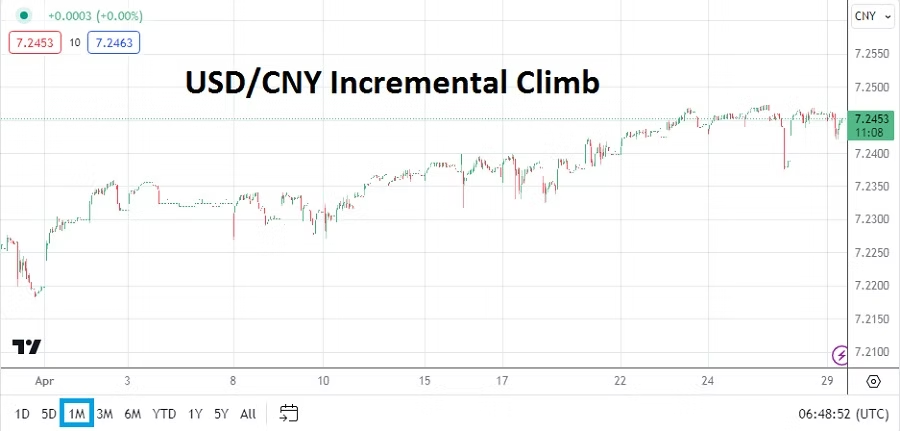
USD/CNY One Month Chart as of 29th April 2024

Tuesday, 30th April, China Manufacturing PMI – the nation has been making claims via government officials the economy is showing signs of a rebound. Yet, disturbing consumer data continues to be seen. The manufacturing statistics from China though will also reflect demand in what is generally accepted as a recessionary period for many global spheres. Traders of the USD/CNY should pay attention to the outcome, the currency pair has incrementally climbed and there are rampant whispers about China undertaking a policy to weaken the Chinese Yuan to spur economic growth.

Wednesday, 1st May, U.S Federal Reserve Funds Rate and FOMC Statement – the Fed will not change its interest rate this week. What will be noteworthy is how Fed Chairman Powell presents this month’s FOMC Statement rhetorically as he is asked questions during his Press Conference. We are certain to hear words mentioned like ‘lagging data and positive signs regarding the potential of weakening inflation’. The question financial institutions want to know is how long will they have to wait for a change to the Federal Funds Rate. The Fed is likely to try sounding cautiously optimistic, but will it be believed? Forex will react to the Fed’s policy meeting pronouncements, but no major surprises should be expected. Some observers may find interesting evidence regarding the future for Fed’s policy via the price of WTI Crude Oil which is hovering near 83.00 USD per barrel as of this writing, because stable energy prices are a key factor regarding inflation.

Thursday, 2nd May, U.S Weekly Unemployment Claims – the jobs data which will start to be delivered late this week will get attention. Forex traders however will be swimming within the riptides already created by the Federal Reserve’s policy.

Friday, 3rd May, U.S Non-Farm Employment Change Numbers and Average Hourly Earnings – these reports will cause a reaction. What financial institutions will be on the hunt for is weaker than anticipated hiring. The inflation numbers from the wages report will be a factor too. The USD traded with a slight decline in Forex last week, those who believe the greenback has been too strong and are inclined to remain sellers should pay attention to the U.S jobs numbers. If the headline hiring number is stronger than anticipated, analysts will rush to the back pages of the statistics to see if part-time hiring is still outpacing full-time employment.