postR196

AMT Top Ten Miscellaneous Items on the 21st September 2024
AMT Top Ten Miscellaneous Items on the 21st September 2024

10. Shohei Ohtani: The slugger hit another home run last night bringing his total to 52 for the season. There is more than a week of regular season action remaining. Incredibly, if Ohtani pitches next season while also hitting, his current statistics could be outshined. The Dodgers pitching staff is in tatters as the MLB playoffs approach, and it has been opined that Ohtani could pitch in the postseason. However, this option is highly unlikely. Ohtani is an outstanding athlete and has surpassed many expectations.

9. Beep, Beep: The purchasing of technology, including their production and logistics sources are likely coming into question in many diverse places around the globe. The detonation of pagers and walkie talkies used by the terrorist group Hezbollah which is largely based in Lebanon has certainly created panic about vulnerabilities. Contemplation in many nations regarding the buying of equipment that could be prone to spyware and other harmful acts is a reality.

8. Michael J. Saylor: MicroStrategy led by its Executive Chairman has added to their Bitcoin holdings. MicroStrategy is reported to have around 252,220 Bitcoins. The current value of BTC/USD is around 63,000 as of this writing. Part of Saylor’s love for Bitcoin rests in his belief that value is due to scarcity, and secure durability as a store of value technologically. However, each Bitcoin holds 100 million Satoshis, the units each Bitcoin is divided by digitally as source code. Even if conservatively there are only 15 million Bitcoin in circulation in ten years time, 15 million times 100 million is 1.5e + 15, meaning more than a quadrillion Satoshis in circulation. That is not scarcity, particularly when quantum computers could create lightning quick digital trading via coding sources. The premise and concern for a major devaluation in Bitcoin is legitimate. Do you disagree?

7: Equity: Intel has apparently been made a sales offer by Qualcomm. Intel’s market cap is 93.19 billion USD, and Qualcomm’s is 188.18 billion USD. The biggest shareholders of Intel are Vanguard, Blackrock and State Street, interestingly enough Qualcomm’s three biggest shareholders are identical. So if the largest shareholders are practically alike, it comes down to a management question, can Qualcomm run Intel better?

6. Closer: The U.S election will be in a little over six weeks times. The race for the White House according to many polls is very close and the outcome will depend on important swing States. There is still enough time for Harris and Trump to pick up votes, but also enough time for each to unwittingly make an error which can cost votes. Not only is the White House up for grabs, but the House and Senate are at stake too for the Democrats and Republicans.

5. Europe’s ability to put on blinders as the Ukraine and Russia battle in a not so distant land, and bickering between E.U nations while finding no solutions for the conflict have many historical comparisons within the continent. The ability to look the other way as chaos grows and inflicts harm on neighbors has a long tradition in Europe. Since the Middle Ages into the present Europe has a significant track record of negotiating harmony and procuring tenuous treaties, which eventually lead to additional discord.

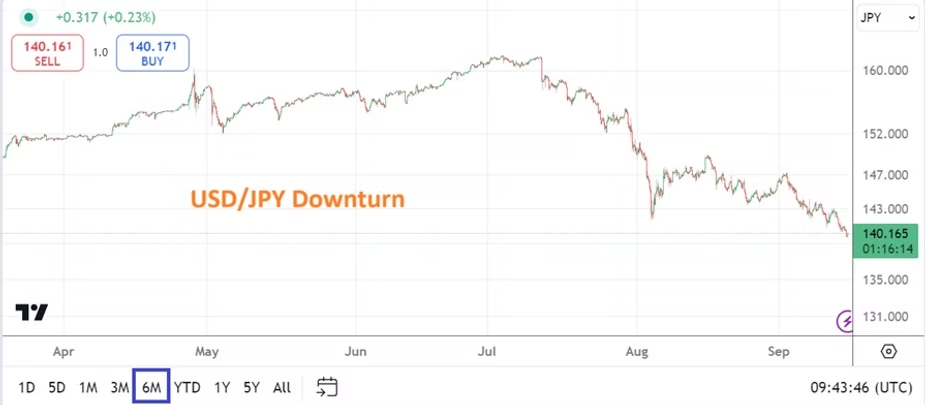
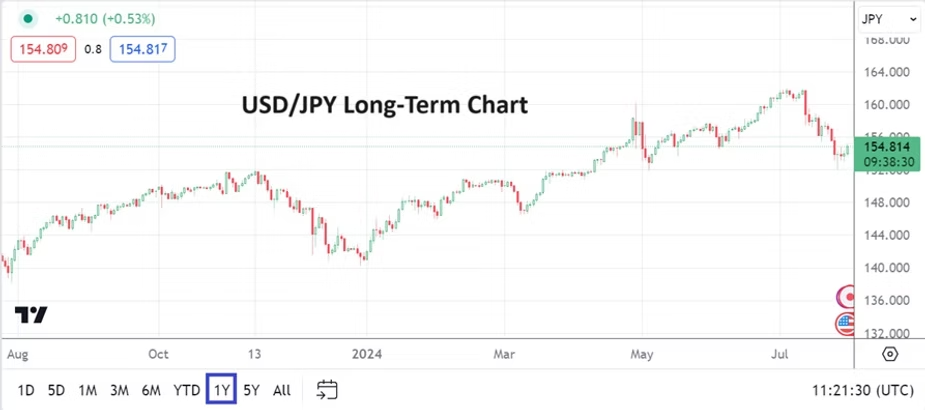
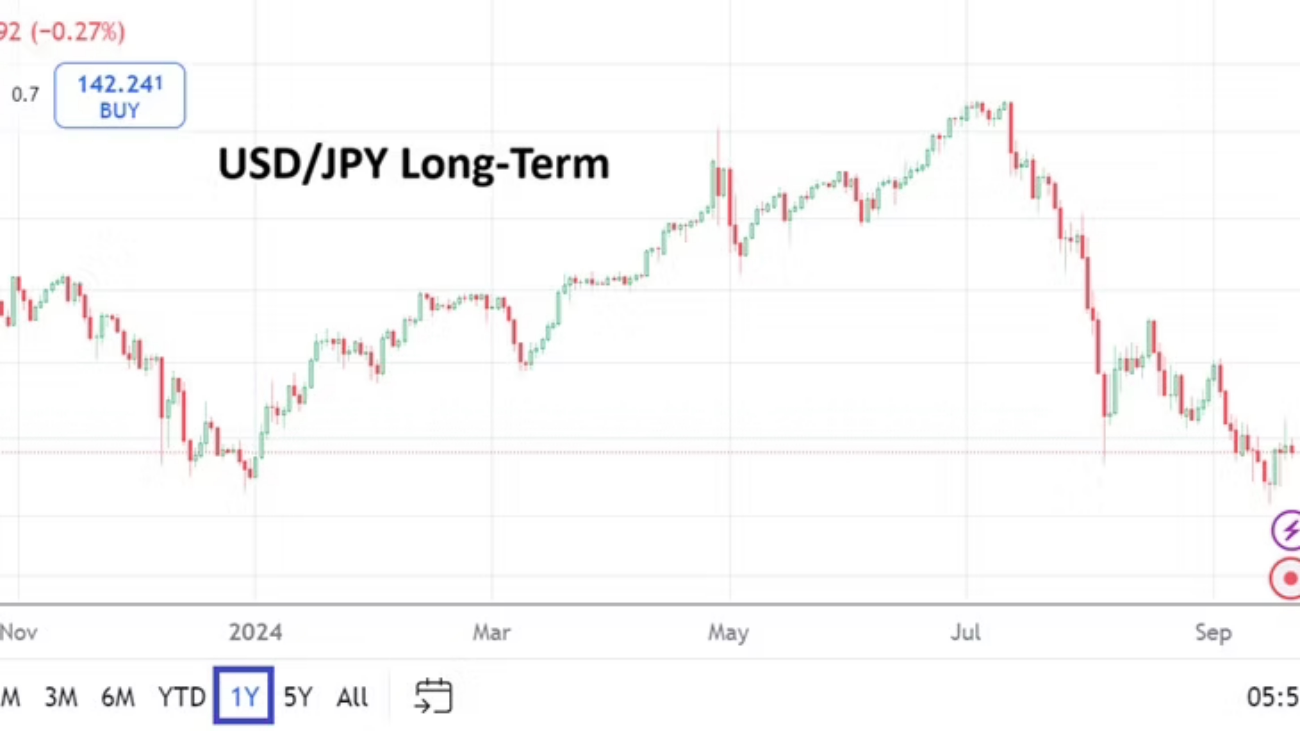
4. USD/JPY: The currency pair closed at nearly 143.850 yesterday. Analysts are trying to create narratives regarding the climb higher the past handful of days, this after the USD/JPY touched the 139.600 level approximately last Monday. Here’s the thing: financial institutions that trade the Japanese Yen had positioned for a more dovish Federal Reserve and more hawkish BoJ. The Fed delivered their end of the bargain on Wednesday, confirming actions which had already been factored into the currency pair. The USD/JPY ‘correction’ higher is within equilibrium that financial institutions have to recalibrate as they make their new mid-term outlooks and decide how to shift their cash forward positions incrementally. The move higher has not been massive and is a natural reaction as large players rearrange their commercial paper. Incremental is the key word.

3. Energy Calm: WTI Crude Oil and Brent Oil continue to trade slightly above their lower price realms, which saw long-term values in the second week of September tested. Current ratios are still flirting with technical considerations seen in the late spring of 2023. While hyperbole is communicated far and wide regarding potential Black Swan events in the Middle East which could cause Crude Oil to increase rapidly, the energy resources remain rather tranquil and seemingly transfixed on concerns about mid-term demand globally due to recessionary pressures.

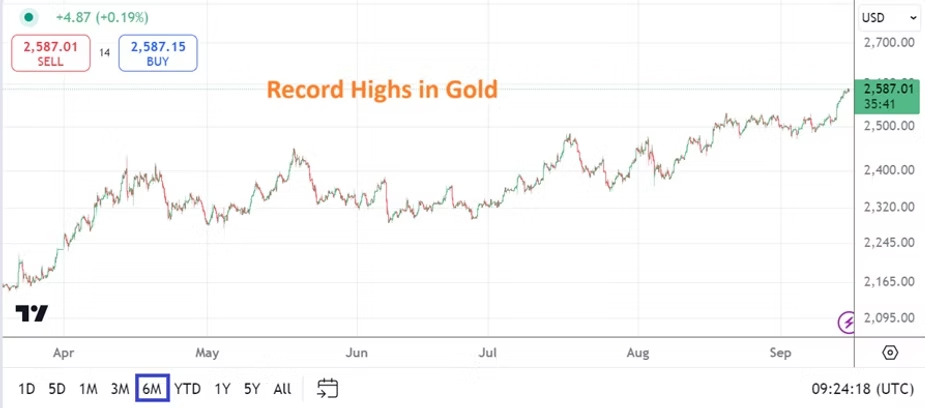
2. All-Time Highs: Gold created new record values going into this weekend near 2,622.00. In September of 2022, gold was trading near 1,600.00 USD per ounce. The move higher in the precious metal has come on the heels of global inflation. Some also correctly point to a distrust of global central banks and fiscal concerns regarding the world’s largest economies. The bullish run upwards in gold has been significant and the commodity will remain an important store of value for investors. Speculatively, some short and mid-term traders are wondering about gold’s ability to maintain a trajectory skywards and if sideways price action and possible downturns will ensue for a while. Long-term investors remain serene.

1. Applause: The Federal Reserve issued an aggressive interest rate cut of 0.50%. The Fed seemingly is acting as if they are trying to please financial institutions because of past incompetence. The U.S central bank now needs economic data to behave according to their prescribed outlooks. What could go wrong? Another Federal Funds Rate cut is likely in November, after that a lot will depend on behavioral sentiment and data which may be affected by as of yet unknown leadership from the White House starting in early 2025. Fed Chairman Jerome Powell sounded almost too optimistic about the U.S economy during his Press Conference this past Wednesday. The U.S Final GDP numbers coming this Thursday will prove interesting, the growth numbers carry an expected gain of 2.9%.
postR185.1

Fed Plays Catch Up and Sets a Calm Table for Day Traders

Fed Plays Catch Up and Sets a Calm Table for Day Traders

The Fed essentially played a game of catch up on Wednesday when they cut the Federal Funds Rate by 0.50%. The interest rate cut was bigger than AMT expected because of the Fed’s rather cautious stance the past handful of years. However, the move by the FOMC was certainly justified and welcomed, and now financial institutions have been given what most thought was bound to happen, a roadmap to at least a 0.75% Federal Funds Rate cut over the next six months. Longer term many believe the Fed will continue to be aggressively dovish if U.S economic conditions cooperate.

USD/JPY One Year Chart on the 20th of Sept. 2024

Traders certainly seem to be leaning into the notion another 0.25% will be trimmed by the Federal Reserve in November. And this sets the table for day traders to now face potentially calmer market conditions that react solely to economic data, geopolitical events and the occasional flashes of news. The U.S presidential election will certainly be a big event on the 5th of November. Long-term investors are likely feeling rather tranquil and have not been surprised. Behavioral sentiment over the next month should be easier to gauge.

USD Cash Index One Year Chart on the 20th of Sept. 2024

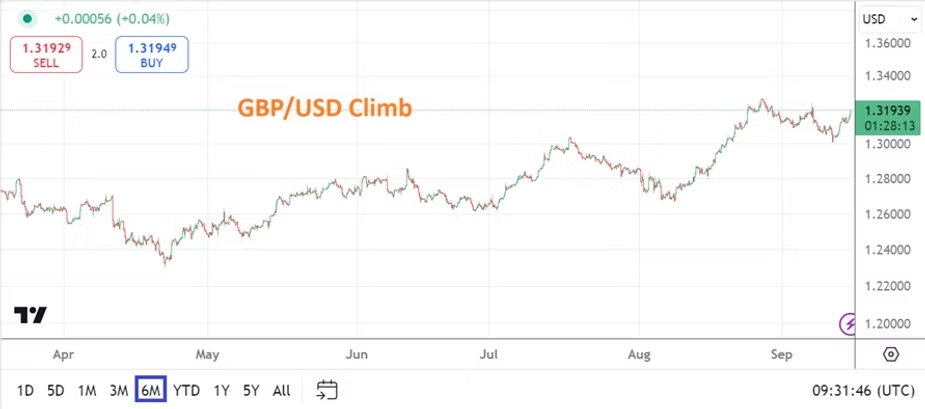
So what happens near-term? The Bank of Japan today, like the BoE yesterday, stood in place. The USD/JPY is trading near 142.300 as of this writing. The GBP/USD is near 1.32890. Gold is hovering near 2,600.00 and WTI Crude Oil is approximately 72.00 USD. Perhaps short-term traders should keep one eye on the Middle East this weekend, but for the moment it doesn’t appear a major escalation is about to ignite in the region. Yes, there is saber rattling, but composure may actually prevail. Those looking for a sudden emergence of a strong USD trend may find that headwinds keep the greenback within the lower realms of the USD Cash Index.

Gold One Year Chart on the 20th of Sept. 2024

Next week’s U.S GDP numbers on Thursday the 26th, and the Core PCE Price Index results on Friday the 27th will get plenty of attention. What the Fed and financial institutions would like to see are stable economic numbers which do not spark fears of a recession. The almighty ‘soft landing’ being pursued by the Federal Reserve is likely being hoped for too by financial institutions via their mid-term outlooks.

The Federal Reserve is supposed to be an independent entity not associated with the Executive Branch of the U.S government regarding oversight. There has been some bantering about the potential that the Fed cut by 0.50% before the U.S elections and Powell proclaimed the U.S economy is doing well to help the Democrats, but this is unlikely. Conspiracy thinking aside, the broad markets are now going to be a barometer regarding economic outlook based on data such as growth, jobs numbers and inflation; clarity regarding a more dovish Fed has been delivered in many respects, data has to justify their decision moving forward.

Day traders may have the ability to follow their technical charts and gather behavioral sentiment perspectives over the next month serenely by watching barometers like gold and U.S Treasury yields. As the U.S election draws closer financial institutions may start to position for potential outcomes, but with polls indicating a tight race currently they would be foolish to bet on one particular outcome. Meaning the broad markets including equity indices, Forex, U.S Treasury yields and even commodities may be moving within fairly priced equilibriums for the moment.

As the Dow 30 and S&P 500 move within record heights, the Nasdaq 100 is slightly below its all-time highs. Yet, it should be remembered the Nasdaq 100 still has done remarkably well the past year and although not at an apex level has the potential to scale upwards quickly. Optimism for the moment seems to be driving the financial markets and day traders should keep this in mind. However, speculators should remember risk management is essential, not over leveraging ideal, and keeping realistic price targets remains always important.

postR184.1

Trading Dangers: Profit Seeking and Federal Reserve Dynamics

Trading Dangers: Profit Seeking and Federal Reserve Dynamics

A 0.25% or 0.50% interest rate cut is the talking point for speculators and financial institutions now, as the U.S Federal Reserve readies its FOMC Statement and prepares to present its Federal Funds Rate this Wednesday. While day traders will certainly listen to plenty of noise being created by pundits and wager, and financial institutions actively operate within the market place and seek profits, long-term investors are likely not very nervous, nor concerned with the monthly Federal Reserve announcements about to be delivered. Perhaps day traders should learn from this long-term insight.

Long-term investors understand the Federal Reserve will be cutting the Federal Funds Rate back to its mean average eventually. While the Fed may only cut by 0.25% this week, over the next six months the U.S central bank is likely to cut by 0.75% or so. Investors who are comfortable with their portfolio positions believe they know what the Fed will be doing and they are not concerned with daily gyrations in the marketplace. Yes, long-term investors will rebalance their positions occasionally, but they do not overtrade.

However, speculators need to be braced for the price velocity which will develop over the next few days. Small price movements in Forex, U.S equity indices and commodities creates havoc for folks who are using leverage and short-term timeframes to bet on outcomes. Nervous sentiment has created velocity, reversals, and unreliable trends recently which will be tested again the next few days.

Gold Six Month Chart as of 16th Sept. 2024

Financial institutions are part of this turbulent landscape as they use algos geared towards working models like trend, mean revision (statistical arbitrage) and other dynamics which create huge amounts of volume and move the markets. Let there be no doubt that the broad markets will react violently on Wednesday in the wake of the Federal Reserve’s actions and rhetoric. Last week’s trading produced new highs in gold, and buying in the U.S major equity indices increased starting on Wednesday and pushed towards highs once again.

GBP/USD Six Month Chart as of 16th Sept. 2024.

The question every one has is what is the Fed going to do this week? I believe the Fed is going to cut by 0.25%, and say that if current economic conditions via the jobs numbers and growth remains lackluster that another interest rate cut will be possible in November. Based on the knowledge that central banks remain wary of stubborn inflation and appear to be debating what the inflation rate will be over the mid-term, it would be surprising to see the Federal Reserve suddenly turn aggressive given their history the past handful of years.

Having seen the ECB stay cautious last Thursday even though economic data shows recession is still being battled across Europe is a strong indicator regarding what the Fed’s likely thinking. The U.K will release important inflation numbers this Wednesday, but the BoE is probably going to remain rather mute on Thursday because they cut interest rates already in August. Again, central banks remain in turtle mode, they are not rabbits.

A dangerous consideration is how will the large financial institutions react to this quagmire being caused by cautious central banks? As said, many long term investors believe the Fed will have to be dovish over the mid-term. Lackluster economic data from China, Europe and the U.S feed into a belief interest rates cuts will continue to be delivered. Day traders live and die via the price action created by financial institutions.

Potential Black Swan events aside, behavioral sentiment generated by short and mid-term results will likely be geared towards the notion that financial institutions also believe global central banks will have to be dovish over the mid-term. This doesn’t include the Bank of Japan which is its own animal and has delivered a rather admirable bearish trend the past two months. The BoJ will release its Policy Rate this Friday and are likely to remain standing in place.

USD/JPY Six Month Chart as of 16th Sept. 2024

So what can day traders who are nervous that volatility will cause great harm over the next few days do? They can always decide to sit on the sidelines and not bet. Long-term investors who plan on holding their assets over the span of a few years are not so concerned about what the central banks are doing short-term – except to say investors are obviously hoping that solid fiscal and monetary policy are being practiced.

Financial institutions engaged in their funds trying to create profitable returns are the folks that need to be kept an eye on, their behavioral sentiment will drive markets in the short and mid-term. Speculators who are trying to take advantage of the dynamics caused by large trading houses this week need to practice solid risk management. While it might be fun to have wagers on potential sudden moves in the coming days, the Federal Reserve’s FOMC Statement and Jerome Powell’s press conference will cause short-term pandemonium.

postR196

AMT Top Ten Miscellaneous ‘Just the Facts Jack’ on the 14th of Sept.

AMT Top Ten Miscellaneous 'Just the Facts Jack' on the 14th of Sept.

10. Word of the Day: Quaestuary, the usage of the word comes from William Manchester’s book A World lit only by Fire. The word is now considered obsolete. Manchester used the Latin word, quaestiarii, to describe profit making by the Roman Catholic Church during the Middle Ages and into the Renaissance. Church ‘officials’ would use their positions of power to raise money dubiously. Promising absolution to the naive via treacherous claims which included the charging of payments for potential sins committed in the future, and a more lenient purgatory for already deceased members of a family who were waiting to be allowed into heaven because of past transgressions.

9. Undecided: With less than two months before the U.S election for President, swing States are crucial battlegrounds for candidates Trump and Harris. Turning purple into red or blue is the prime task for the Republicans and Democrats. Economy, immigration, foreign policy, reproductive rights are among the talking points. Which side can receive the most votes via promises that will be hard to accomplish?

8. Artificial Intelligence: Early this week Oracle Corporation released revenue results and projections showing that profits are increasing due to demand for data centers as the use of AI expands. Cloud services provided by Oracle has become the corporation’s largest source of growth. Investments in big data centers are getting competitive. Data4 has recently announced they are going to invest approximately 300 million EUR into a data center facility in Paiana, Greece. Data4 led by Olivier Micheli, CEO, has announced that it plans on investing around 7 billion EUR into 2030 for expansion.

7. Crude Oil: WTI Crude Oil briefly went above the 70.00 USD mark on Friday, but went into the weekend near 69.33. U.S economic data this coming week (besides the U.S Fed on the 18th) will be limited to manufacturing readings and retail sales data. The notions that the U.S economy is struggling via weaker employment numbers and lackluster GDP, European data remaining murky, while China is not exactly robust is likely causing speculative demand in Crude Oil to remain low. Global energy supply is solid and the Middle East conflict remains somewhat muted.

6. Whipsaw Gains: Major U.S equity indices moved upwards as the Dow 30, S&P 500 and Nasdaq 100 all produced better weekly results. However, improved momentum mostly occurred as equities reversed from nervous lows on Wednesday. The Dow 30 and S&P 500 are within sight of apex values, while the Nasdaq isn’t far behind. U.S Treasury yields also dropped lower via their totals for the week with the 5, 7, and 10 Year Notes approaching yields last seen in the spring of 2023. The 30 Year Bonds are traversing lower too, but will have to penetrate early 2024 levels to then challenge depths from early 2023.

5. Inflation: Global central banks are having a large internal debate about their target inflation numbers. Trying to agree on what the neutral rate – mean average – over the next year should be is causing central banks to remain cautious about inflation projections. While it is clearly evident that Europe and the U.S are facing economic headwinds the ECB, Fed and BoE seemingly refuse to step on the gas pedal and become aggressively dovish. However, financial institutions who frequently use their mid-term outlooks as guidance continue to lean into their trading positions and seemingly wager on the central banks having to become more dovish. How much can each central bank cut by over the next 6 months? Why not cut by 0.50% to inject easier borrowing rates now? Because apparently it seems all the central banks remain nervous about inflation remaining stubborn. The word stagflation still comes to mind. The decline in Crude Oil prices seen the past few weeks may be a hopeful sign for lower costs.

4. USD/JPY: The currency pair finished trading near the 140.775 ratio on Friday. Trading in the USD/JPY appears to be driven by the notion that financial institutions believe the U.S Federal Reserve is going to have to cut the Federal Funds Rate by 0.75% over the next six months. Behavioral sentiment has a breathtaking history of producing strong trends in the USD/JPY. The Bank of Japan will announce their Monetary Policy Statement on the 20th of September. The USD/JPY was trading near 162.000 in July and its decline lower seems to have surprised some, but why? The BoJ is likely going to sound cautious this coming week, but sitting on their hands and allowing their global counterparts to become more dovish may be enough to keep the USD/JPY within its lower price realm.

3. China Data: Numbers published early this morning showed that New Home Prices continue to fall, Industrial Production has decreased, Retail Sales have dropped, and the Unemployment Rate has risen. China’s economy is suffering. The USD/CYN looks too low at the current rate of 7.0925. The Shanghai Composite (SSE) has fallen to nearly 2,704 and touching lows from early February of 2024. The SSE is down roughly -13.46% over the last year. The Chinese government’s desire to manage the economy with a tight grip continues to produce fractures and should be reconsidered.

2. Gold: The precious metal finished Friday’s trading near 2,577.00. Yesterday’s values hit all-time record prices for Gold versus the USD. The 2,586.00 vicinity was touched before reversing slightly lower. The ability to remain near apex highs going into the weekend highlights large traders likely still have a taste for gold and that long-term investors remain bullish. Is nervousness due to perceived global central bank ineptitude helping to create more gold buying? Short-term speculators need to remain careful within these heights.

1. FOMC Prediction: The European Central Bank’s decision to cut by only 0.25% this past Thursday is almost a sure sign the Federal Reserve will mirror the ECB on the 18th of September. Last week’s prediction by AMT that the ECB would only cut by 0.25% proved to be true, and our outlook for the FOMC’s Federal Fund Rate decision is also a cautious 0.25% cut. While the U.S Consumer Price Index and PPI info published this past Wednesday and Thursday showed inflation is under control, the data also shows a stubborn streak. However, an erosion of inflation is taking place and while the target ‘neutral’ rate is likely being debated behind closed doors, it is also apparent to most outside observers that the Fed is being too cautious and will be ‘forced’ to cut this coming week, November 2024, and early in 2025.

Content

postR183.1

Nervous? Central Banks Cautious, FX and Asset Equilibrium

Nervous? Central Banks Cautious, FX and Asset Equilibrium

Sometimes when looking for ideas regarding a risk analysis article it is difficult to find a timely subject. Exaggeration is often used to grab attention. This week and next will not be one of those times. Equities, Forex and commodities have produced nervous results since last Monday. The broad markets appear to be in search of equilibrium, but price velocity while higher than normal hasn’t produced a volcanic surge of pain. Financial institutions were presented less than inspiring jobs data this past Friday and day traders hopefully had their risk management working. Everyone will need to be paying attention this week too.

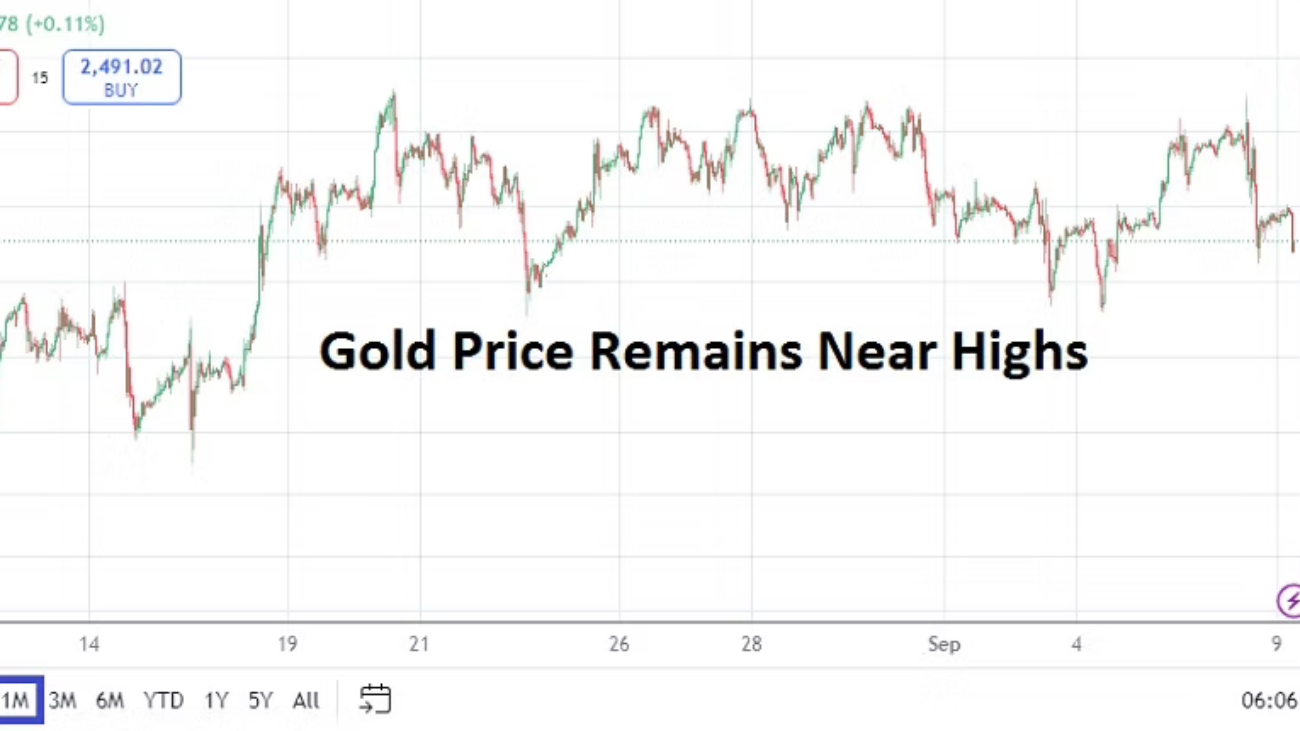
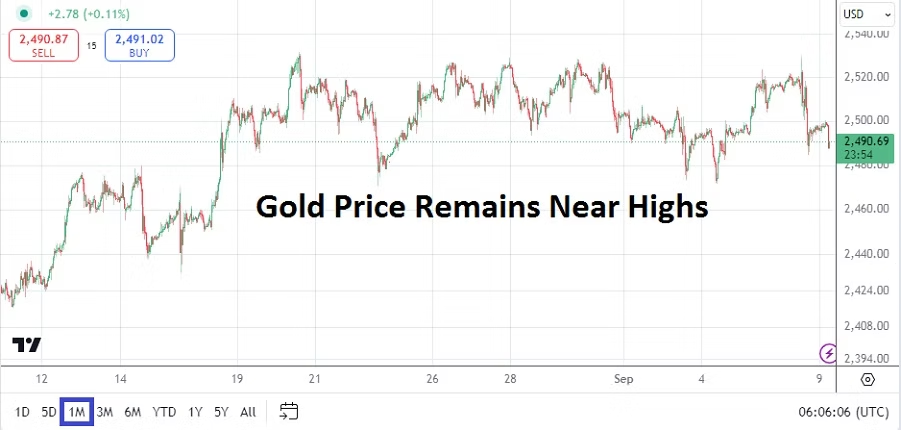
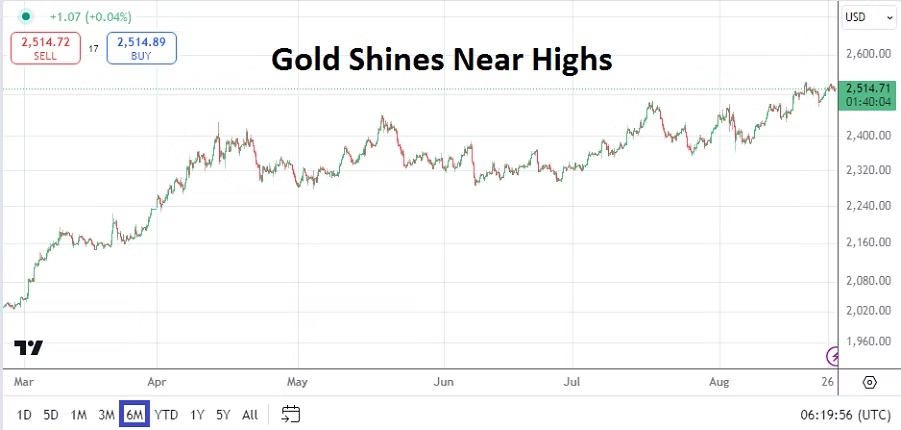
Gold One Month Chart as of 9th Sept. 2024

Gold has hovered around the 2,500.00 level and while it certainly is a short-term speculative asset for day traders, the precious metal also serves as distinct barometer of behavioral sentiment and long-term guidance regarding inflation. Recent economic data has created concerns in financial institutions about the potential for a stronger than anticipated U.S downturn. The volatility and sell off in equity indices last week is a clear sign investors would like the Federal Reserve to be more aggressively dovish.

This coming week is packed with a variety of risk events which will keep all market participants engaged. Long-term investors may feel calm as they rely on their outlooks which extend over a handful of years, but anyone who needs a firm grasp on short and mid-term viewpoints might not be comfortable. It is important not to cry wolf too often, but based on the trading results seen the past week it is worthwhile to point to the turbulent outcomes and issue a warning that more volatility could develop.

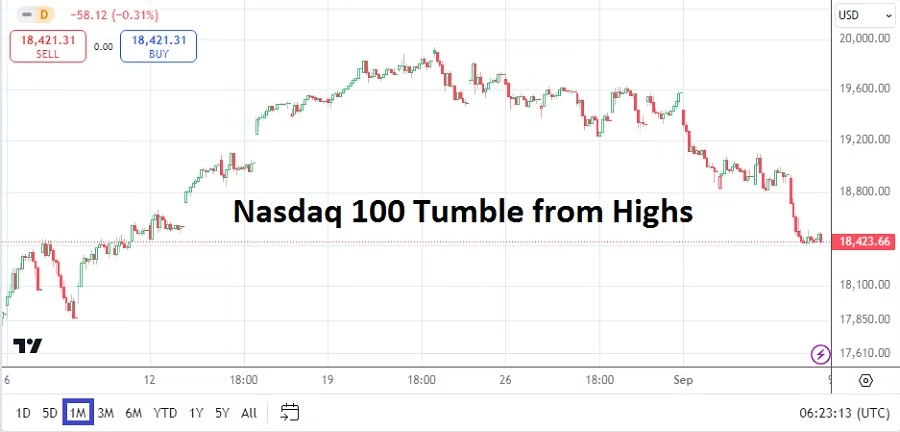
Nasdaq 100 One Month Chart as of 9th of Sept. 2024

Some analysts may apply the thought that what we have seen was profit taking, and this can certainly be debated. The coming two weeks have plenty of noteworthy events on the calendar. Besides the listed risk highlights noted below, the Fed will release its FOMC Statement on Wednesday the 18th, the BoE will follow on the 19th and not to be outdone the Bank of Japan will step onto center stage on Friday the 20th of September.

While long-term investors likely believe all variables will return to known price realms and that central banks sooner or later will fall into their proper places regarding monetary policy, day traders who are gambling on short-term momentum must try to figure out where behavioral sentiment is leaning. One of the ways speculators without deep pockets can put the odds in their favor concerning potential profits, is to make sure they are practicing rock solid risk management and not stepping into Forex trades, equity indices via CFDs wagers, and commodities bets when they are displaying rough conditions without being prepared.

Monday, 9th of Sept., China Consumer and Producer Price Index – the inflation reports from China both came in below their estimates earlier today. While some may believe that less inflation than predicted is a good thing, it isn’t when the economy is suffering from deflationary pressures. Lackluster spending from consumers in China continues to highlight negative sentiment about prospects for growth. The USD/CNY is near the 7.1125 ratio as of this writing.

Tuesday, 10th of Sept., U.S Presidential Debate – while not an economic data event, investors might want to pay attention to the answers given by Vice President Kamala Harris and former President Donald Trump. The race for the White House appears to be close according to various polling. It could prove interesting for financial institutions if Harris is questioned about her ideas regarding taxing unrealized capital gains.

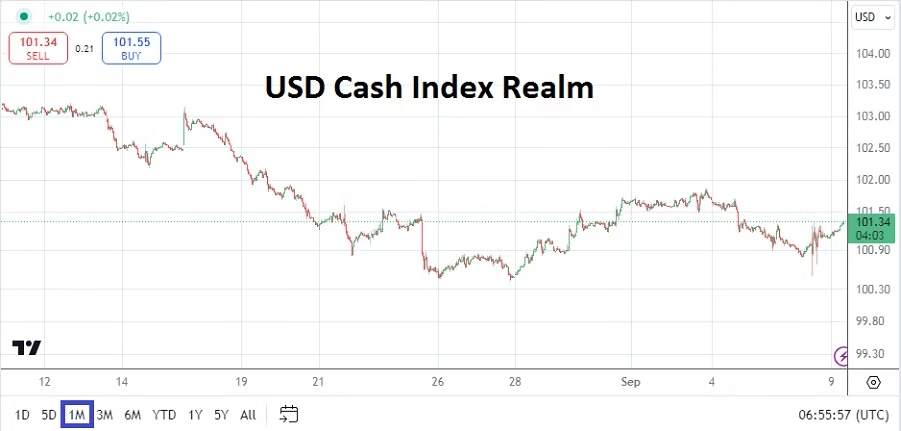
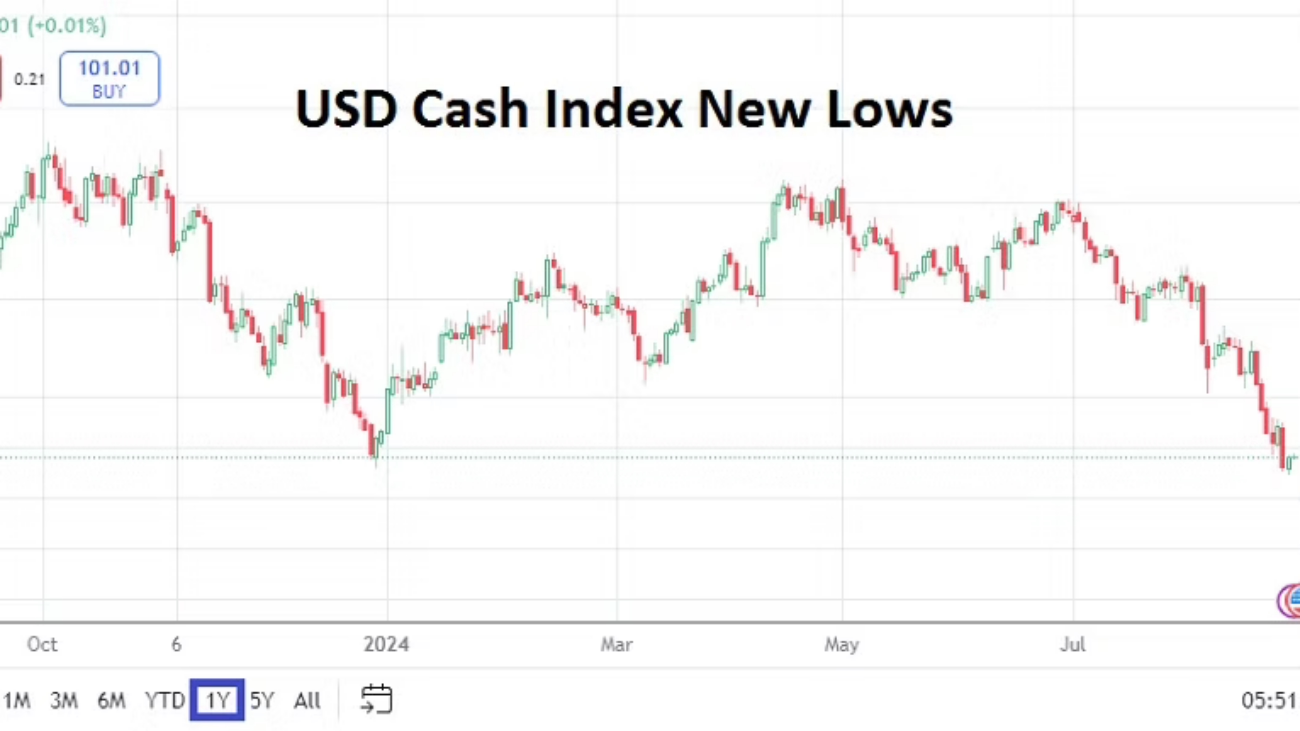
USD Cash Index One Month Chart as of 9th Sept. 2024

Wednesday, 11th of Sept., U.S Consumer Price Index data – the inflation reports will certainly get the attention of financial institutions. If the annual CPI report comes in weaker than the previous outcome, this could spark more USD centric weakness in Forex. All asset classes will react to the inflation numbers because they are likely to play a major part in the Fed’s FOMC decision in one week’s time. The USD Cash Index is still lingering near lows, but for it too resume a more bearish trajectory, financial institutions will need to believe the Federal Reserve is going to become increasingly dovish.

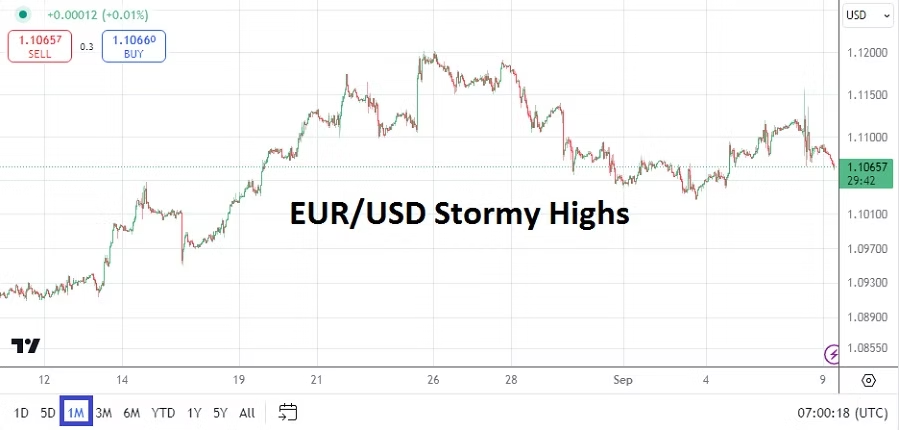
EUR/USD One Month Chart as of 9th Sept. 2024

Thursday, 12th of Sept., European Central Bank Main Refinancing Rate – The ECB is definitely going to cut its prime borrowing interest rate, the question is how much of a haircut they are going to provide. A 0.25% cut has certainly been traded into the EUR/USD, but many financial institutions believe there is a possibility to see a 0.50% basis cut. Can the ECB and Christine Legarde be aggressive? The European Union remains under recessionary pressures and inflation data is starting to show signs of erosion. The amount of the interest rate cut from the ECB will also be a telltale sign regarding what will happen via the Federal Reserve on the 18th of September. The EUR/USD will react to the European Central Bank’s decision, and global assets in far off places may react too because behavioral sentiment among investors may shift according to the rhetoric provided. Prediction: The ECB will stay cautious and cut by 0.25%, while saying a November rate cut is likely if economic data remains under pressure. Having said the above, the ECB should cut by 0.50% this Thursday, if they do not – financial institutions will not be pleased unless ECB President Legarde sounds very dovish during her Press Conference.

Thursday, 12th of Sept., U.S Producer Price Index – more inflation data from the U.S will provide investors an other opportunity to glance into the Fed’s looking glass. But if these PPI numbers meet or are near the anticipated results, financial institutions may be reacting to the ECB’s rate decision more because they might believe it is a better clue regarding the Fed’s Federal Funds Rate decision which will come in a handful of days.

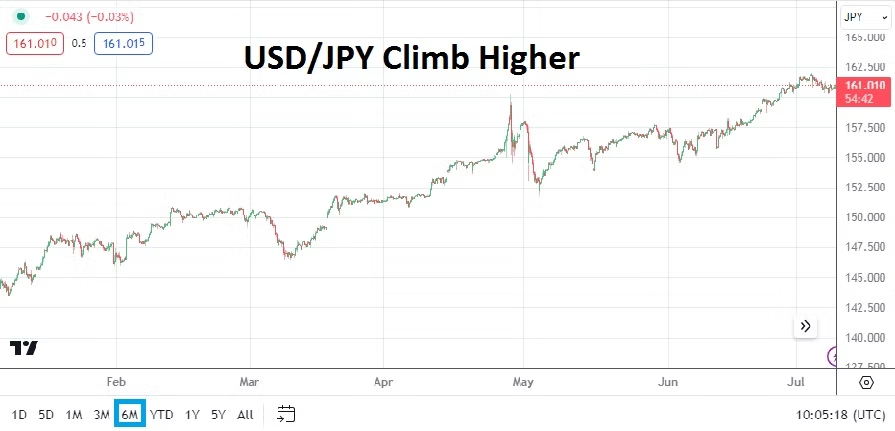
USD/JPY One Month Chart as of 9th Sept. 2024

Friday, 13th of Sept., Japan Revised Industrial Production – this number may not get much attention, but because the Bank of Japan will release its Policy Rate on the 20th, the outcome could impact existing sentiment in the USD/JPY. The Japanese Yen has continued its bearish trajectory and traders who are wagering on more downside should not bet blindly on selling positions because intraday trading remains very choppy. The USD/JPY is now touching values last seen in a sustained manner in early January of 2024, lower values were seen in December 2023, and lower ratios that traversed the 138.000 realm and proved choppy occurred in the spring of 2023.

Saturday, 14th of Sept., China New Home Prices, Retail Sales, Industrial Production – this parade of data from the nation will be important. Foreign investors remain concerned about China’s economic prospects. The deflationary winds that have been blowing in the Asian giant have been well documented. The results from these three reports are expected to be lackluster.

postR180.1

Summer Optimism as Forex and Equities Focus on Fall Outlooks

Summer Optimism as Forex and Equities Focus on Fall Outlooks

Fed Chairman Jerome Powell admitted the obvious at the Kansas City’s Fed’s Jackson Hole Symposium last Friday. The realization the U.S Federal Reserve is going to cut interest rates confirmed what many financial institutions had positioned their trading desks for via forward cash Forex contracts over the past month.

USD Cash Index One Year Chart on the 27th August 2024

The USD has been expected to grow weaker by many people because most knew the Fed would have to state a September rate cut would be delivered. The question that was also somewhat answered is the notion if the Fed will also cut in November. Though Powell certainly did not say a rate cut would happen in November, his rhetoric made it clear the Federal Reserve is considering a dovish perspective which could translate into additional cuts down the road.

The Fed has been criticized for being too passive and while Powell can be congratulated for his rather unemotional Federal Reserve leadership, he and the Fed can certainly be faulted for not reacting quickly enough to ‘transitory’ inflation and then not responding until this past weekend to the need for cutting interest rates with dovish rhetoric. Let’s also remember the U.S Treasury (government) is on the line to pay exorbitant costs for debt repayments because of bad U.S fiscal policy.

As an interesting related side note, the head of the Brazilian Central Bank, Roberto Campos Neto, made a strong appeal for governments to be fiscally responsible while speaking at the Jackson Hole Symposium this past weekend. While he could have been talking to any number of nations regarding spending, his points were obviously meant to highlight his disagreements with the Brazilian government led by Lula da Silva and the Workers Party. Roberto Campos-Neto stated that approximately 50,000,000 (yes, million) people in Brazil receive government allowances, while only about 43,000,000 people are earning money via employment and business enterprises. Traders who want to keep an eye on the USD/BRL this week may be entertained by the potential volatility within the currency pair which is trading a hair below 5.5000 before it opens today. The USD/BRL has certainly not been correlating to broad Forex USD centric weakness, and demonstrates the internal domestic fight between Lula da Silva and the Brazilian Central Bank regarding fiscal policy.

Jobs data from the U.S has continued to turn negative, particularly via revised reports which are being published rather ‘quietly’ as election season approaches. Yet, financial institutions have been aware of the weaker jobs numbers. While the poor jobs numbers combined with eroding inflation is good for USD centric weakness due to the knowledge the Fed will have to reverse from its rather high interest rates, the question becomes how much per the financial institutions selling of the USD has been acted upon in Forex. Is the USD oversold for the time being? It depends on trading timeframes certainly.

Weaker USD centric positions will need more impetus for further bearish trajectories to be seen near-term. Financial institutions may believe equilibrium is being approached, this because it appears interest rate cuts equaling a 0.50% decline seem to have been factored into Forex. Will the Federal Reserve be put into a position in which they will be able to cut by a full basis point (-1.00%) over the next six months?

Gold Six Month Chart on the 27th of August 2024

Gold is trading near 2,500.00 plus at the time of this writing. Gold has touched higher levels in the past week and is getting a round of applause from its throngs of believers who proclaim the precious metal the ultimate safe haven against inflation and erosion fears via fiat currencies – including the USD. As a reminder, Bitcoin is highly speculative and doesn’t have the historical (thousands of years) track record that gold has acquired.

GBP/USD Five Year Chart on the 27th of August 2024

The EUR and GBP are traversing higher territories not seen in a while. The EUR/USD is near the 1.11700 level, which was last traded in July of 2023, and it has been since 2022 that sustained prices above this current realm have been traded. The GBP/USD is near 1.32000 and is within a value ratio last seen in March of 2022. Central banks will remain in focus as summer ends and the fall trading season gets underway. The ECB will release their Main Refinancing Rate on the 12th of September, the Fed will present the Federal Funds Rate on the 18th, and the BoE will follow suit with the Official Bank Rate on the 19th.

However, those September dates are still a few weeks away and financial institutions do have data this week which could stir Forex, equity indices and U.S Treasuries in the near-term. Day traders often do not have the ability to rely upon mid and long-term outlooks, and instead have to be content with trying to ride the momentum trends being caused by larger players. While the USD weaker outlook is tempting to rely upon, speculators who are looking for quick hitting wagers need to judge technical charts and try to grasp existing behavioral sentiment which can shift rapidly depending on lengths of time.

Traders should remember the U.S will celebrate its Labor Day holiday next Monday, which sets the stage for potential sudden volatility to flourish before big financial institutions in the States leave for their long weekend. The last week of August should be rather tranquil. Certainly most long-term investors feel as if they have more clarity regarding interest rates and will be able to relax. The hope is that the current calm is not the quiet before the storm due to lingering political issues in the U.S, France and elsewhere. And that escalation of the Ukrainian and Russia war, and the Middle East conflict do not cause sudden surges of bedlam.

Economic data events the remainder of this week that should be given consideration includes the U.S CB Consumer Sentiment reading today. Yesterday’s U.S Durable Goods Orders came in with mixed results as the Core number fell by minus -0.2%, but the broad number came in with a substantial gain of 9.9%.

USD/JPY Three Month Chart on the 27th of August 2024

The Bank of Japan has published their Core CPI data today and the outcome came in below expectations with a gain of 1.8% compared to the estimate of 2.1%. The USD/JPY is trading near 144.790 at the time of this writing as it continues to show bearish tendencies. The Bank of Japan which was heavily criticized in many circles may actually be achieving what they have planned, this as they have tried to stimulate stronger export and confront inflation. Their battle is not over yet.

Australian CPI data will be published on Wednesday. And on Thursday, German Preliminary Consumer Price Index numbers will be released. The EUR/USD could react to this report, but the European Single Currency remains highly USD centric. Which sets the table for the U.S Prelim Gross Domestic Product report also on Thursday. The growth number from the U.S could diminish selling considerations for the USD if the report comes in stronger than expected. However, the GDP Price Index and weekly Unemployment Claims from the U.S could also impact short-term behavioral sentiment and cause a bit of turbulence if negative results are published.

Friday will see more CPI numbers from Japan, CPI and GDP numbers from France, and GDP data from Canada. But before going into the long holiday weekend the U.S will present one more major report with its Core PCE Price Index and the monthly statistic is expected to show a slight gain of 0.2%.

China watchers will get Manufacturing PMI numbers early on Saturday. Recent China data continues to show signs of economic stress regarding foreign investment, domestic consumer spending, and deflationary results. Buyers beware.

postR179

AMT Top Ten Miscellaneous Rays of Light for 23rd of August

AMT Top Ten Miscellaneous Rays of Light for 23rd of August

10. Word of the Day: Like crepuscular animals which are active during twilight, large market players are ruminating as their summer hiatus draws to an end over the next week and a half. Plans for coming hunts are being formulated as leisure concludes for financial institutions preparing to work in the shadows.

9. Scrolling Failures: Lack of solid results on search engines are becoming a growing annoyance. Is it just us? An abundance of poor information via defined searches on the internet and finding what is sought is becoming increasingly problematic. Is AI being allowed to do too much while still too dumb? AI doesn’t know when it is wrong. Competitors to Google and others are sought.

8. How Dare Us: The postponement of imposed dates regarding energy policy changes are multiplying. The end for the classical use of oil, coal and nuclear is not near. Efficient power is evolving, but this will have to include ‘antique’ generation and grids. The demand for electric vehicles are being confronted with declining sales via U.S consumers. Tangible technology needs precise planning, not apocalyptic rhetoric which tries to scare people.

7. Middle East Calm: The storm is being limited within a tea cup for the moment. The potential for a dangerous boiling painful mess still exists. ‘Serenity now’ remains a mantra for those who need to pay attention as chagrin and anxiousness mix.

6. Fed Retreat: The FOMC Meeting Minutes released this week showed some Fed members remained cautious, while others banged the drum louder regarding interest rate cuts. However, a Fed Funds Rate reduction is almost a 100% certainty for the 18th of September. The question now is what the Fed will do in November. Fed Chairman Powell and a slew of other renowned global central bankers will speak today and tomorrow at the Jackson Hole Symposium. Financial institutions largely believe they know what is going to be said, but comments from Bank of Japan and Brazilian leadership could prove to be informative and entertaining for central bank nerds. Monday could be volatile for USD/BRL traders.

5. VIX: The CBOE’s Volatility Index climbed to the 56 vicinity on the 5th of August as panic grew via widespread overreactions to hyperbole ripping through the markets. The fear gauge is near the 17.55 ratio as of this writing. Market calm has resumed across the board as financial institutions and day traders have been able to achieve a pleasant tone again. Traders who use the VIX as a template regarding the potential of risks suddenly cascading into assets should keep their eyes on the index, which went to a low around the 14.45 mark on Monday. Yet, the slight incremental climb the past few days could be coming from folks still speculating on volatility which may not develop near-term.

4. Barometers: Gold is lingering slightly below 2,500.00 for the moment, this after having achieved a record high on Tuesday when it touched the 2532.00 apex. WTI Crude Oil is near 74.00 USD per barrel and is maintaining a polite value range. Speculatively, Cocoa is again above 9,000 USD per ton and Bitcoin has fought its way above 61,000 this morning. Risk appetite remains stable for the moment.

3. Forex: USD/JPY, EUR/USD, even the USD/ZAR have been able to hold onto their recent trends as USD centric weakness remains viable. Traders who were looking for huge moves in FX this week have likely been disappointed. Retail speculators need to understand financial institutions have been positioning for a weaker USD since the tail end of July. Market players may be quite pleased regarding current Forex equilibrium, which may allow technical traders the ability to take advantage of existing behavioral sentiment, this as reversals flourish and the next big wave of impetus is awaited. Next Thursday’s U.S Preliminary GDP numbers may deliver some noise.

2. Cassandras: Market experts who proclaimed a long-term stock market crash in early August have crawled back into their caves to take cover and percolate their next fear mongering tactics. This after the latest round of predicted catastrophes have vanished. While the major U.S stock indices are not at record highs, they have recovered plenty of lost ground and appear ready for more days in the sun.

1. Political Winds: The curtain closed on the Democratic National Convention in Chicago last night without a serious hiccup. Kamala Harris and Donald Trump now enter a crucial phase of campaigning, and will get plenty of attention as they go into attack mode. The next big event for Harris and Trump will be their televised debate on the 10th of September. Will the outcome prove to be a devastating storm for one of the candidates?

postR178.1

Tranquility: Forex, Equities and Treasury Yields Drama-Free

Tranquility: Forex, Equities and Treasury Yields Drama-Free

Sometimes no news is welcome. The markets though not devoid of drama, have been relatively tranquil. It is obviously summer in the northern hemisphere which helps bring about quiet, this since many ‘active’ market participants are off vacationing having been allowed to go on holiday. The implosion in the markets on the 5th of August after the dangerous riptides created by the combination of the Federal Reserve and Bank of Japan have certainly eased and evidence of the chaos is fading. Retail traders who are always looking at charts and for opportunities may have even been able to rest too the past week and a half.

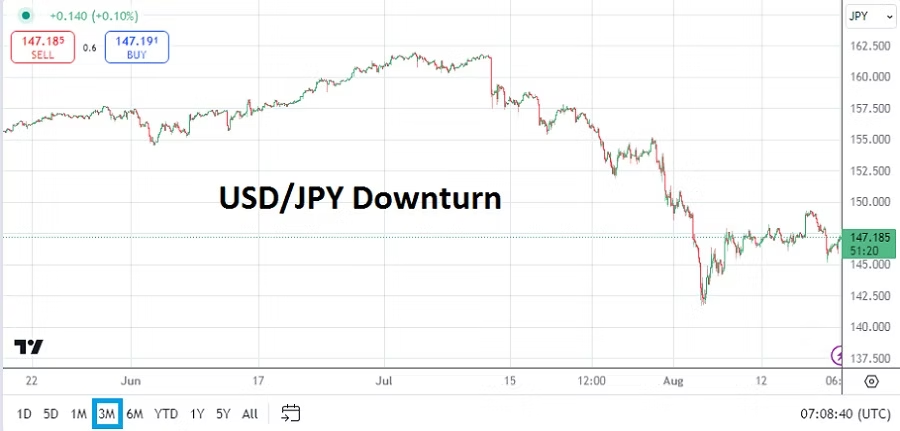
USD/JPY Three Month Chart as of 20th August 2024

The USD/JPY as of this moment is near 147.185. The Nikkei 225 has recovered lost ground from over-reactive selling on the 5th of August. The value of the Japanese equity index is within extremely intriguing territory as financial institutions are clearly taking a wait and see approach regarding more BoJ and Fed rhetoric, combined with fundamental analysis of Japan’s economy and their companies in consideration. It is a healthy market dynamic, particularly via a notion the Nikkei 225 having reached an early August equilibrium is a solid result, this if you have a long-term viewpoint.

Nikkei 225 Three Month Chart as of 20th August 2024

The GBP/USD, EUR/USD, USD/SGD have all seen better results for traders who have been wagering on USD centric weakness. Even the USD/ZAR has produced a solid trajectory. U.S Treasuries yields are falling.

Gold Six Month Chart as of 20th August 2024

Yes, day traders definitely have different approaches compared to long-term investors, but if a speculator who is accustomed to quick trades synthesizes an outlook using the behavioral sentiment of long-term institutional players, they might find it helps build some foundations which help perceptions when deciding what to pursue. The use of barometers is always good too, this often gives a trader insights regarding market mood even if it is not an asset class they want to pursue. Gold is within record territory as it hovers around 2,500.00 USD per ounce.

Investors can argue all day and night about interpretations regarding results. The trading within gold the past six months, even since November of 2022 opens doors to a vast amount of complex explanations and narratives. They are too numerous to argue here, but the ability of the precious metal to march higher should continue to be watched. The recent surge higher since the end of June suggests – but it is again, only an explanation after the results have been seen – that gold traders believed the Federal Reserve would have to eventually capitulate and stop behaving hawkish about interest rates.

And this brings us squarely to this weeks events. Yes, the DNC is underway in Chicago and hopefully it provides a rather calm atmosphere free of political chaos via unwanted demonstrators. If investors can focus on the Fed’s FOMC Meeting Minutes report which will be published on Wednesday this would be good.

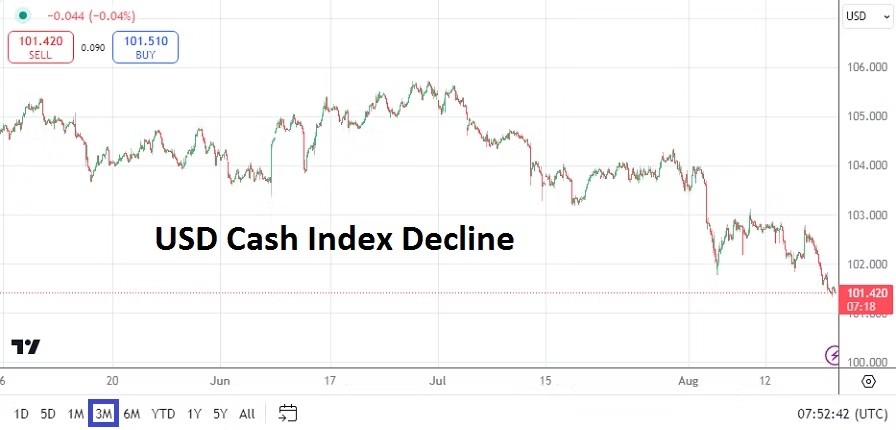
Because the Fed refused to sound dovish in their last FOMC Statement this created the potential for massive retaliation by institutional traders, and when coupled with the BoJ hike and their rhetoric, market turmoil in Japan and globally promptly ensued for a few days. However, because of recent inflation data again highlighting U.S prices via Producer Price Index are stable and decreasing in some sectors, and CPI has continued to come in below anticipated results, investors again firmly believe the Federal Reserve will definitely cut the Fed Funds Rate by at least 0.25% in September, and may be in a position to cut in November. Thus, the weakness and volatility of the USD which is clear to see via the USD Cash Index results.

USD Cash Index Three Month Chart as of 20th August 2024

Yet and potentially amusing tomorrow, the Fed’s FOMC Meeting Minutes may simply restate the cautious and very passive rhetoric from the last FOMC Statement. This because the Meeting Minutes are a reflection on thoughts shared at the Fed meeting, and we know what that outcome was already. Meaning tomorrow’s publication may scare some investors, but it shouldn’t. Tomorrow’s Fed paper may prove to be a non-event.

This sets the table for the Jackson Hole Symposium in Wyoming which starts on Thursday to produce a myriad of central banker statements led by Jerome Powell and his counterparts from the European Central Bank, Bank of Japan and Bank of England. The event is likely going to be important, but much of the talk which occurs in closed meetings is unlikely going to be made public.

postR177.1

Central Banks and Summer Storms for Traders as Actors Change

Central Banks and Summer Storms for Traders as Actors Change

Yesterday’s rather quiet start to the week regarding economic data allowed for traders to look over the financial markets before the onslaught of central bank mayhem hits on Wednesday. The Forex market has seen rather interesting results the past few weeks as behavioral sentiment has clearly shifted (for seemingly the tenth or so time) towards a more dovish outlook regarding the U.S Federal Reserve. Expect stormy waters this week in currency markets.

The usual lazy summer of the markets has had to deal with political winds in June and July as Britain, France and the U.S have delivered rather intriguing mischief via election results and changes of leadership. However, the world has survived and this is a lesson new day traders need to understand quickly. While tomorrow may not be known, experienced market players have seen these dramas before, they might be new episodes with different actors, but the theme remains the same for veterans of the markets.

Although powers shift, a focus on outlooks is often what matters. People and institutions are in pursuit of profit. This week central banks will be heard from and the rhetoric delivered will affect assets.

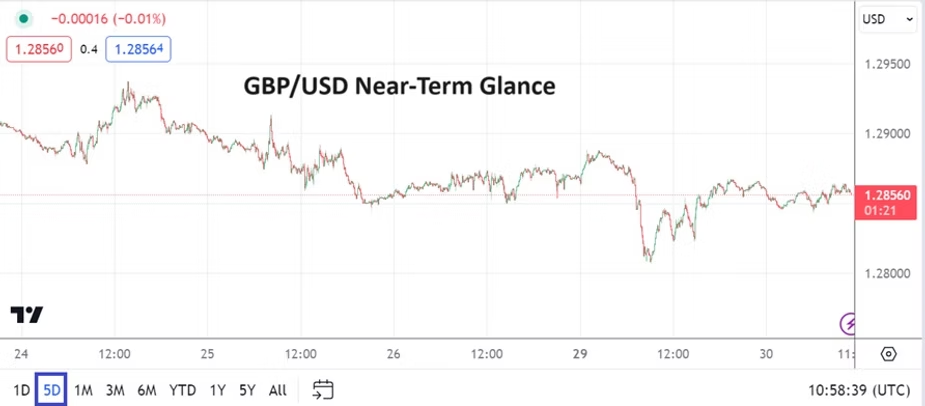
GBP/USD Five Day Chart on the 30th of July 2024

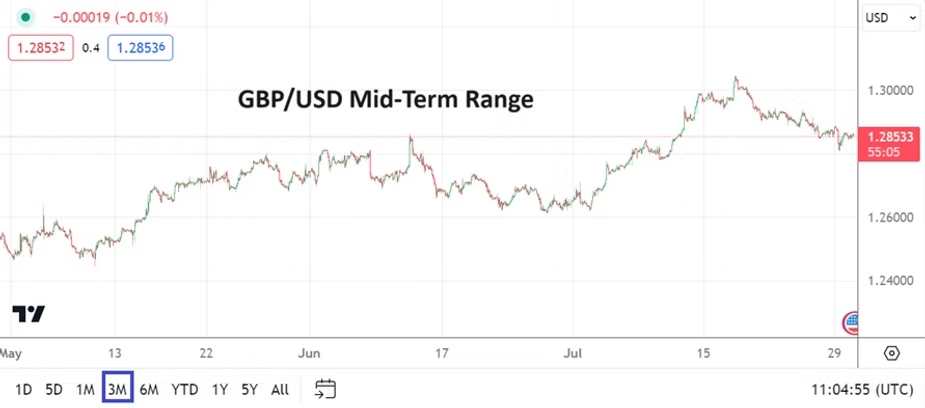
Monday, 29th July, U.K assorted data – Mortgage Approvals, Net Lending to Individuals and M4 Money Supply data was released to various fanfare yesterday and did not shake the GBP/USD dramatically. However, making more important news perhaps was the public statement by Rachel Reeves, who is the new Chancellor of the Exchequer, saying there is an existing 22 GBP billion ‘black hole’ within the U.K government finances that was not accounted for by the Conservatives. In other words the blame game between the new Labour bosses and now banished Tories has begun. While the GBP/USD dropped a bit on this development, it did not crush the currency pair as it returned to the lower depths of its higher three month technical chart.

GBP/USD Three Month Chart on the 30th of July 2024

Tuesday, 30th July, E.U Gross Domestic Product – a variety of GDP reports came from across the continent this morning, including France which recorded a slight gain of 0.3% and the German numbers which recorded a minus -0.1% result. The numbers show the E.U remains in trouble for the larger economic nations. Spain did show an improvement, but it is nothing that should start parades of celebration.

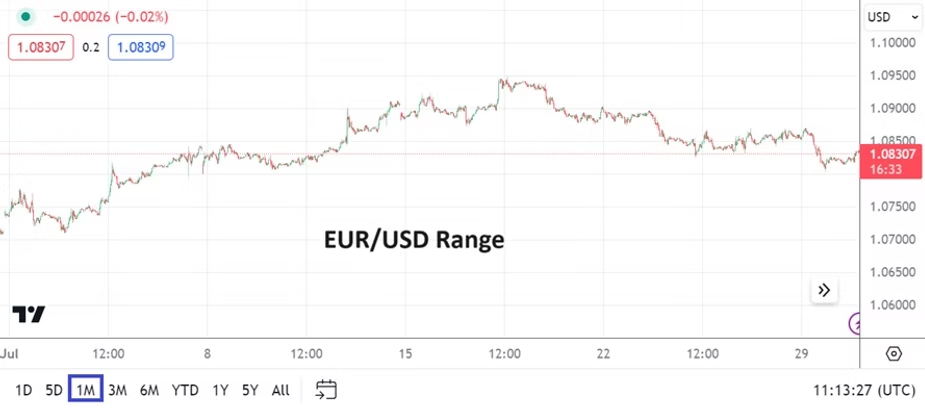
EUR/USD One Month Chart on the 30th of July 2024

Tuesday, 30th July, U.S CB Consumer Confidence – this sentiment report for the U.S consumers will get some notice today, but financial institutions are largely braced for tomorrow’s U.S Fed rhetoric. The trading of Forex, gold, equities and their indices will likely remain choppy today as folks take on cautious tones.

Wednesday, 31st July, Bank of Japan Policy Rate – and here we go ladies and gentlemen. The BoJ can never be counted on to do what is logical in the eyes of many analysts outside of the central bank’s inner circle. Japan has pursued a soft devaluation of the Yen this year. The Bank of Japan should consider an interest rate hike to the 0.20% level from the 0.10% ratio, but will they? Speculators need to be extra careful with the USD/JPY over the next 30 hours. If the BoJ somehow decides to raise and the U.S Fed makes it known they will consider more than one interest rate cut this calendar year, the USD/JPY could see swift price velocity lower. Perhaps the BoJ will stay muted and cautious, allowing for the currency pair to go higher again. However, there have been some signs large players suspect a slight interest rate hike could come tomorrow from the Bank of Japan. Day traders are advised to be extraordinarily careful.

Wednesday, 31st July, U.S Federal Reserve FOMC Statement – the Fed is not going to lower their Federal Funds Rate during this meeting. But what they are expected to do via their FOMC policy rhetoric is to say a cut is likely in September considering the current economic data, and that if inflation continues to show signs of erosion another cut will be considered in November. Recent economic data in the U.S has been mixed. GDP numbers jumped higher, but importantly the GDP Price Index was lower than anticipated last Thursday, and the PCE Price Index on last Friday matched expectations (and importantly didn’t rise). If the Fed sounds optimistic about an interest rate cut in September this will match the expectations of many financial institutions. If they sound cautious about a possible second rate cut later this year, this could cause a hiccup for those with weaker USD centric outlooks over the mid-term.

Thursday, 1st August, U.K Bank of England Official Bank Rate – the BoE is expected to lower the borrowing rate by 0.25% to 5.00%. The GBP/USD has been trading higher in July based on a cocktail of a weaker USD stance. There is plenty of reason to believe the less than sterling economic data from the U.K will help deliver the lower interest rate from the BoE this week. The BoE is likely to have spoken with the Fed and ECB to correlate a gameplan. The Bank of England Monetary Policy Summary should be given attention. GBP/USD traders will have responded to the Fed’s outlook from Wednesday, opening the door to plenty of volatility after the BoE speaks. Meaning that Forex speculators should be extremely cautious if they are pursuing short-term wagers which will be akin to surfing a violent storm.

Friday, 2nd August, U.S Non-Farm Employment Change and Average Hourly Earnings – this data will be anti-climatic. The results from Wednesday through Thursday from the central banks will take a lot of the bang out of these reports. The earnings report should be given some attention, but the financial markets will likely be trading on behavioral sentiment generated over the prior days.

postR196

AMT Top Ten Miscellaneous Remarks for the 14th of July 2024

AMT Top Ten Miscellaneous Remarks for the 14th of July 2024

10. Words of the Day: Political rhetoric is using platitudes and subterfuge camouflaging verbal nonsense, masking a vacuum of non-results and causing fatigue of populist promises.

9. Harris Prediction: After the NATO press conference in which Biden was more lucid but still made mistakes, it is beginning to feel like Kamala Harris is being given room to audition for the Presidency by the Democratic machine. If her polling numbers show improvement over the next couple of weeks, look for Harris to replace Biden at the DNC in Chicago, if her polling numbers are not good enough in the eyes of the elite power brokers, it is possible Biden may be asked to give up his delegates, allowing for an open convention.

8: Zombie Inflation: Data results via the U.S CPI caused a reaction in the broad markets, and volatility in Forex. While the broad monthly Consumer Price Index number on Thursday was minus -0.1%, the PPI numbers on Friday came in higher than expected causing some to feel that inflation remains a plague. However, if the Producer Price Index was interpreted as being higher because rising prices are coming via more expensive employee costs (which might see an end to the cycle sooner rather than later if jobs data continues to weaken) this is why there might not have been a violent Forex reversal on Friday. And Consumer Sentiment numbers from the University of Michigan came in below expectations again, and inflation expectations via the consumer survey showed some erosion.

7. Federal Fund Rates: Financial institutions have clearly begun to factor in the belief an interest rate cut will occur in September. The Fed which has been cautious consistently the past seven months may now have enough ammunition to consider becoming more dovish. A September interest rate cut has certainly been factored into Forex and Treasury yields, and there is a growing tide of sentiment which believes the weaker GDP numbers combined with the potential of less inflation could spark additional Federal Funds Rate cuts this calendar year. Outlook fueled by optimism regarding a more dovish Fed could be a factor in the markets the remainder of July.

6. Gold and Silver: Commodity prices are soaring as speculators pursue bullish trends. Gold finished this week above 2,410.00 USD. Silver is traversing above 30.00 USD per ounce for the first time since 2011 and 2012. These two metals are not always correlated, and day traders should remember Silver remains a rather easily mined commodity which sometimes influences downwards pressure because supply can be increased. Having said that, Gold and Silver have had solid bullish trends since February of this year.

5. Thaw: Bitcoin is near 60,000 as of this writing. The crypto winter has seemingly ended and many folks are standing in the sunlight and proclaiming long-term projections of Bitcoin as it maintains a higher price range. It should be remembered the most significant percentage of trading volumes within cryptos reside heavily within the top tier, and the ‘assets’ ranked lower remain in wagering cesspools. Cryptocurrency remains speculatively dangerous, and largely a place to move illicit cash with the perception the money can be kept ‘dark’.

4. USD/JPY: The Bank of Japan won last week’s game of fire. The U.S Consumer Price Index numbers dealt a blow to the blind fury of speculative buying in the USD/JPY, and there is also a belief among many that the BoJ added onto the selling momentum of the currency pair too with a well timed intervention. The currency pair which was near the 161.640 juncture suddenly dived to nearly 157.420. The USD/JPY has gone into this weekend near the 157.900 ratio. The USD/JPY saga is not finished yet, and froth via bullish endeavors remains dangerous. Day traders here have been warned.

3. China: Friday’s Trade Balance numbers were good, compared to the rather weak CPI results seen on the 10th of July which were negative. China’s Communist Central Committee begins a Plenary Session tomorrow until the 18th. Will they speak in platitudes? The USD/CNY has certainly seen a ‘soft’ devaluation since February of this year, but the currency pair did go into the weekend near the 7.2500 mark which is off the high of 7.2765 seen this past Thursday. China still must improve consumer sentiment domestically and this remains a difficult struggle as ramifications from the implosion in China housing values mires the landscape. GDP numbers will come from the nation on Monday.

2. Behavioral Sentiment: Equities and indices, Forex, and commodities are all experiencing risk appetite permutations. While it might be tempting for retail traders to bet on lower reversals of trends, sometimes its much easier to simply ride optimistic waves. Certainly there will be days when financial assets struggle, but the apex heights of the Dow Jones 30, S&P 500, Nasdaq 100 should be treated with respect. Treasury yields are at mid-term depths and appear ready to traverse lower.

1. Trump: The attempted assassination of Donald Trump on Saturday in Pennsylvania will galvanize his supporters and likely push many people towards voting for him November. The amount of vitriol Trump has endured from his political opponents including the highest echelons of the Democrats and many in the media needs to be contemplated and quieted. Opposition to political ideology is fine, but the use of hyperbolic musings has led the U.S to a dangerous place. It would be wise for pragmatic adults to rejoin political discourse. Traders should watch the financial markets early this week to see if the U.S political front causes a reaction.

postR192

AMT Top Ten Miscellaneous Fireworks for the 5th of July 2024

AMT Top Ten Miscellaneous Fireworks for the 5th of July 2024

10. Grudge: Ireland and the Springboks begin their rugby two match competition this Saturday in Loftus Stadium, Pretoria. Anticipation is palpable in South Africa. The weather is forecast to be good and the game is expected to be better. The battle between the Green Machines is real. The second game will be played on the 13th of July in Durban.

9. Digital Jitters: Bitcoin is trading near 54,300.00 USD as of this writing. As analysis filters in to explain this particular downturn which essentially began on the 7th of June, the fact is that BTC/USD has become a playground for institutional gamblers while many in the public remain dubious. Excuses such as the U.S election potential outcome and Fed monetary policy are all likely false narratives. Speculation is your answer.

8. Correlations: The USD/ZAR is near the 18.20500 mark, and the USD/MXN is around 18.06000 as of this morning. The South African Rand and Mexican Peso are not correlated, except as currencies that are witnessing a strong amount of political sentiment generate trading behavior in financial institutions which are trying to judge their long-term outlooks. The coalition National Unity Government of South Africa, and the Morena political party of Mexico are in the spotlights and are being watched by anxious investors.

7. National Security: The race for quantum supremacy is real as nations issue significant controls over the export of computing mechanisms to unfriendly competitors as reported by the New Scientist website recently. And the smuggling of semiconductors which are ‘forbidden’ to China who are using organized underground operations in order that Nvidia AI processors can be obtained, was reported on by the Wall Street Journal two days ago.

6. Commodities: WTI Crude Oil is trading above 84.00 USD, the energy has sustained prices above $80.00 since the 17th of June and is approaching mid-term highs, the slight rise in price earlier this week may have been because of hurricane concerns, but buyers have remained strong this morning. Cocoa is still traversing around 8,456.00 USD per metric ton, as it bounces along mid-term technical support levels. In early January of this year Cocoa was trading at half its current value.

5. Jobs Numbers: One of the favorite tools used by salespeople to get day traders geared towards speculating blindly are the monthly U.S Non-Farm Employment Change numbers which will be published today. But because of the U.S Independence Day yesterday, many financial institutions are celebrating a long holiday weekend and will be mostly inactive. Data has become increasingly lackluster from the U.S the past two months with rather pessimistic GDP, PMI manufacturing and services outcomes. Traders considering a dip of their toes into the markets today should be aware that volumes are going to be low which opens the door for volatility. Who will be paying attention to the Average Hourly Earnings report?

4. Markets: U.S Treasury yields are within sight of three month lows, this as the major stock indices via the S&P 500 and Nasdaq 100 make noise at record highs. The Dow 30 is not at a high but within a healthy territory as bullish behavioral sentiment remains rather abundant. When full trading volumes return next week, there is reason to believe the summer rally may continue.

3. Bank of Japan: The USD/JPY is trading below the 161.000 level. Some analysts suspect the BoJ engaged in a limited intervention earlier this week when the currency pair approached the 162.000 vicinity. The Bank of Japan is playing a dangerous game with speculators. The next BoJ Outlook Report is not due until the 31st of July. Until then the USD/JPY apparently is going to traverse in a higher price range with the threat of a potentially engaged Bank of Japan lurking which can punish speculators if they get too comfortable betting on the bullish trend. The price of Gold should be watched as it traverses around 2,365.00 USD, which remains in sight of record highs that touched the 2,425.00 vicinity on the 20th of May. Retail purchasing of gold in Asia is strong as citizens of some nations try to hedge against inflation.

2. Fallout: The Presidency of Joe Biden remains vulnerable as media pundits who have long supported him lurch towards public criticism, and question Biden’s inability to handle unscripted situations. Talk of replacing Biden with another candidate to face Donald Trump remains fever pitched, but there are strong obstacles which will not allow an easy path to unseat the current President. Biden owns his delegates won via Primary voting. He would have to officially relinquish his delegates at the Democratic National Convention in order to allow for a new candidate. The Democratic political party also knows that Vice President Kamala Harris is not particularly well liked, but if Biden were pushed to the side it would open the door for a potentially messy challenge by Harris who would certainly want the Presidency. Getting her to bow out of the race could be another potential disaster for the Democrats, and help create a level of disdain which could trigger a huge landslide for the Republicans in November.

1. Trouncing: Political incompetence is not only a stronghold in the U.S, this as the U.K and France are proving. The GBP/USD is near 1.27685 as of this writing, the EUR/USD is around 1.08230. Both currency pairs have gained this week. The massive defeat of the Conservatives in the U.K last night, and Macron’s political weakness which may increase after the 2nd round of voting this coming Sunday in France has been digested by financial institutions. The GBP/USD and EUR/USD were punished over the past few weeks due to knowledge that the Tories in Britain would suffer a resounding humiliation, and the belief that Macron opened the door for a loss of clout. Financial institutions have proven they are keen observers of politics and are accustomed to shifts of direction via new forces. Some may also say that financial institutions are comfortable as long as they know where power resides in the ‘deep state’ bureaucracies of every nation.

postR196

AMT Top Ten Miscellaneous Punches for the 28th of June 2024

AMT Top Ten Miscellaneous Punches for the 28th of June 2024

10. Cricket: The ICC T20 World Cup Championship will feature South Africa vs. India. The two teams are familiar with each other competitively and the final match will be held at the Kensington Oval in Bridgetown, Barbados on Saturday.

9. Selling Pressure: Lows are being challenged in Bitcoin as it hovers above 61,000.00 USD. Cocoa has stumbled dramatically this week and is below 8,000.00 per metric ton. Who will be courageous and wager on reversals higher? Speculators should remain cautious and understand price velocity that looks tantalizing can also prove costly to trading accounts.

8. Grounded: Boeing’s Starliner remains docked to the International Space Station. Problems have plagued The Boeing Company the past handful of months, and their ambitions of becoming a power within NASA’s explorations are also underachieving. SpaceX and Airbus are certainly paying attention to Boeing’s ineffectiveness.

7. Teetering: The African National Congress and Democratic Alliance political parties in South Africa are feuding about how coalition power will be shared within the National Unity Government. The USD/ZAR has become volatile and is near 18.21000 as tensions mount and reversals hit. Financial institutions are waiting for an optimistic resolution, while also fearing the possibility of an abandonment to positive visions.

6. Inflation: Core Personal Consumer Expenditures Price Index statistics will be released today from the U.S. Yesterday’s GDP Price Index came in slightly higher than anticipated which kept USD centric bullish positions relatively strong. However, other American statistics have weakened significantly and the mid-term looks troubling for the U.S economically. Stagflation remains a concern. The Federal Reserve is likely hoping to see today’s PCE numbers come in weaker than expected, which would allow the central bank to hint towards Federal Fund Rate cuts later this year.

5. Ennui: President Macron could find his political power further eclipsed after France’s first round voting results this coming Sunday. French voters appear ready to deliver a resounding message of dissatisfaction to the listless ruling government. Election turnout statistics should be watched. The second round of voting will be on the 7th of July. Financial institutions have braced for a shift of power already, but the EUR/USD will still produce volatility in the days ahead.

4. Geopolitical Risks: Russia, China and their allies are likely considering how they will prepare for a potential change in the U.S White House. Foreign policy following last night’s debate between Biden and Trump must be planned. The fact that Trump is viewed as a rather flamboyant personality and not bound by cautious diplomatic attitudes creates a calculus that U.S adversaries will have to consider. While the potential exists that some nations may try to be more aggressive now, they also know that a Trump victory in November would change the international political landscape long-term.

3. Bank of Japan: The Core Tokyo Consumer Price Index produced a gain of 2.1%, which was above the forecasted amount of 2.0% earlier today. The BoJ continues to remain far too dovish regarding interest rate policy and financial institutions are buying the USD/JPY in massive waves. The USD/JPY is around 160.750 as of this writing and did traverse above 161.000 earlier, these are Forex levels not seen since the late 1980’s for the USD/JPY. Japan’s attempt to stimulate the economy with a weaker Japanese Yen may work, but the U.S and others may start to look at the BoJ’s soft devaluation in a very negative light. Speculators of the currency pair need to be extremely careful, because the BoJ has the ability to intervene violently and cause momentary spikes which could prove deadly for day traders trying to take advantage of the outlandish bullish trend.

2. Behavioral Sentiment: Markets will be a looking glass into the future today, this as trading houses react to the realization that Donald Trump is likely going to be the next U.S President. While there are no guarantees regarding the U.S election outcome yet, the broad markets will certainly feel a shift of momentum in the coming days as large players adjust from a cautious approach to more aggressive postures regarding a Trump presidency. U.S equity indices remain near record highs, and the potential of a more business friendly White House which doesn’t threaten tax hikes on U.S corporations will likely affect speculative outlooks.

1. Power: The resounding defeat of Joe Biden last night in the Presidential debate will spark a heated battle among Democratic power brokers. Biden will certainly be asked to step aside after last night’s poor performance. However, Biden is stubborn, and Dem leaders like Nancy Pelosi and Barak Obama among others will have a difficult task to try and convince Biden for the sake of the nation that he must do the honorable thing and release his political delegates at the August Democratic National Convention in Chicago. If this doesn’t happen, the Republicans may be able to achieve a landslide victory by taking control of not only the White House but the Senate too, along with maintaining power in the House of Representatives. All the camouflage in the world last night, including the liberal media, couldn’t mask the inability of Joe Biden to be coherent.